

Overview
As custodians, your role is crucial in ensuring that the funds in a UTMA account are used solely for the direct benefit of the minor, such as for educational or health expenses. It’s essential to understand the specific legal and documentation requirements that come with this responsibility. Imagine if you could make a significant difference in your child’s life by wisely managing these funds.
Understanding state regulations and the proper withdrawal processes is vital. This knowledge not only helps you use the funds responsibly but also reinforces your commitment to your child’s welfare. Remember, custodians have a legal obligation to prioritize the child’s needs while managing these accounts.
Together, we can navigate this journey of financial planning with care and understanding, ensuring that every decision made is in the best interest of your child. We’re here for you, guiding you through this important responsibility with empathy and support.
Key Highlights:
- UTMA accounts allow asset transfers to minors without needing a trust, managed by a custodian until the child reaches the age of majority.
- Custodians can withdraw funds for the direct benefit of the child, covering expenses like education and health, but not for personal use.
- Kiddie Tax rules for 2025 state that the first $1,350 of unearned income is nontaxable, the next $1,350 is taxed at the child’s rate, and amounts over $2,700 are taxed at the parents’ rate.
- Custodians must be aware of state-specific regulations regarding withdrawals to avoid legal complications.
- Withdrawals from UTMA accounts are typically not taxed at the time, but earnings are taxed based on the child’s income level.
- A structured process for withdrawals includes determining the purpose, gathering documentation, contacting the financial institution, submitting requests, and maintaining records.
- Custodians have legal obligations to transfer custodial property to the minor upon reaching 21 or upon the minor’s death, emphasizing responsible fund usage.
- Bright Advisers offers tailored solutions and low fund fees to assist custodians in managing UTMA accounts effectively.
Introduction
In the landscape of financial planning for minors, UTMA accounts emerge as a nurturing tool that simplifies the process of transferring assets while promoting responsible management. Imagine being able to facilitate gifts of cash or property to your young beneficiaries—these accounts empower custodians to oversee funds until the child reaches adulthood.
However, it’s important to understand that navigating the complexities of UTMA accounts requires clarity regarding their purpose, regulations, and withdrawal procedures. As families strive to optimize their financial strategies, the significance of strategic planning, awareness of tax implications, and compliance with legal obligations cannot be overstated.
This article explores the essentials of UTMA accounts, offering insights into their management, the withdrawal process, and common challenges custodians may face. Together, we can navigate this journey towards securing a brighter financial future for your children.
Understand UTMA Accounts and Their Purpose
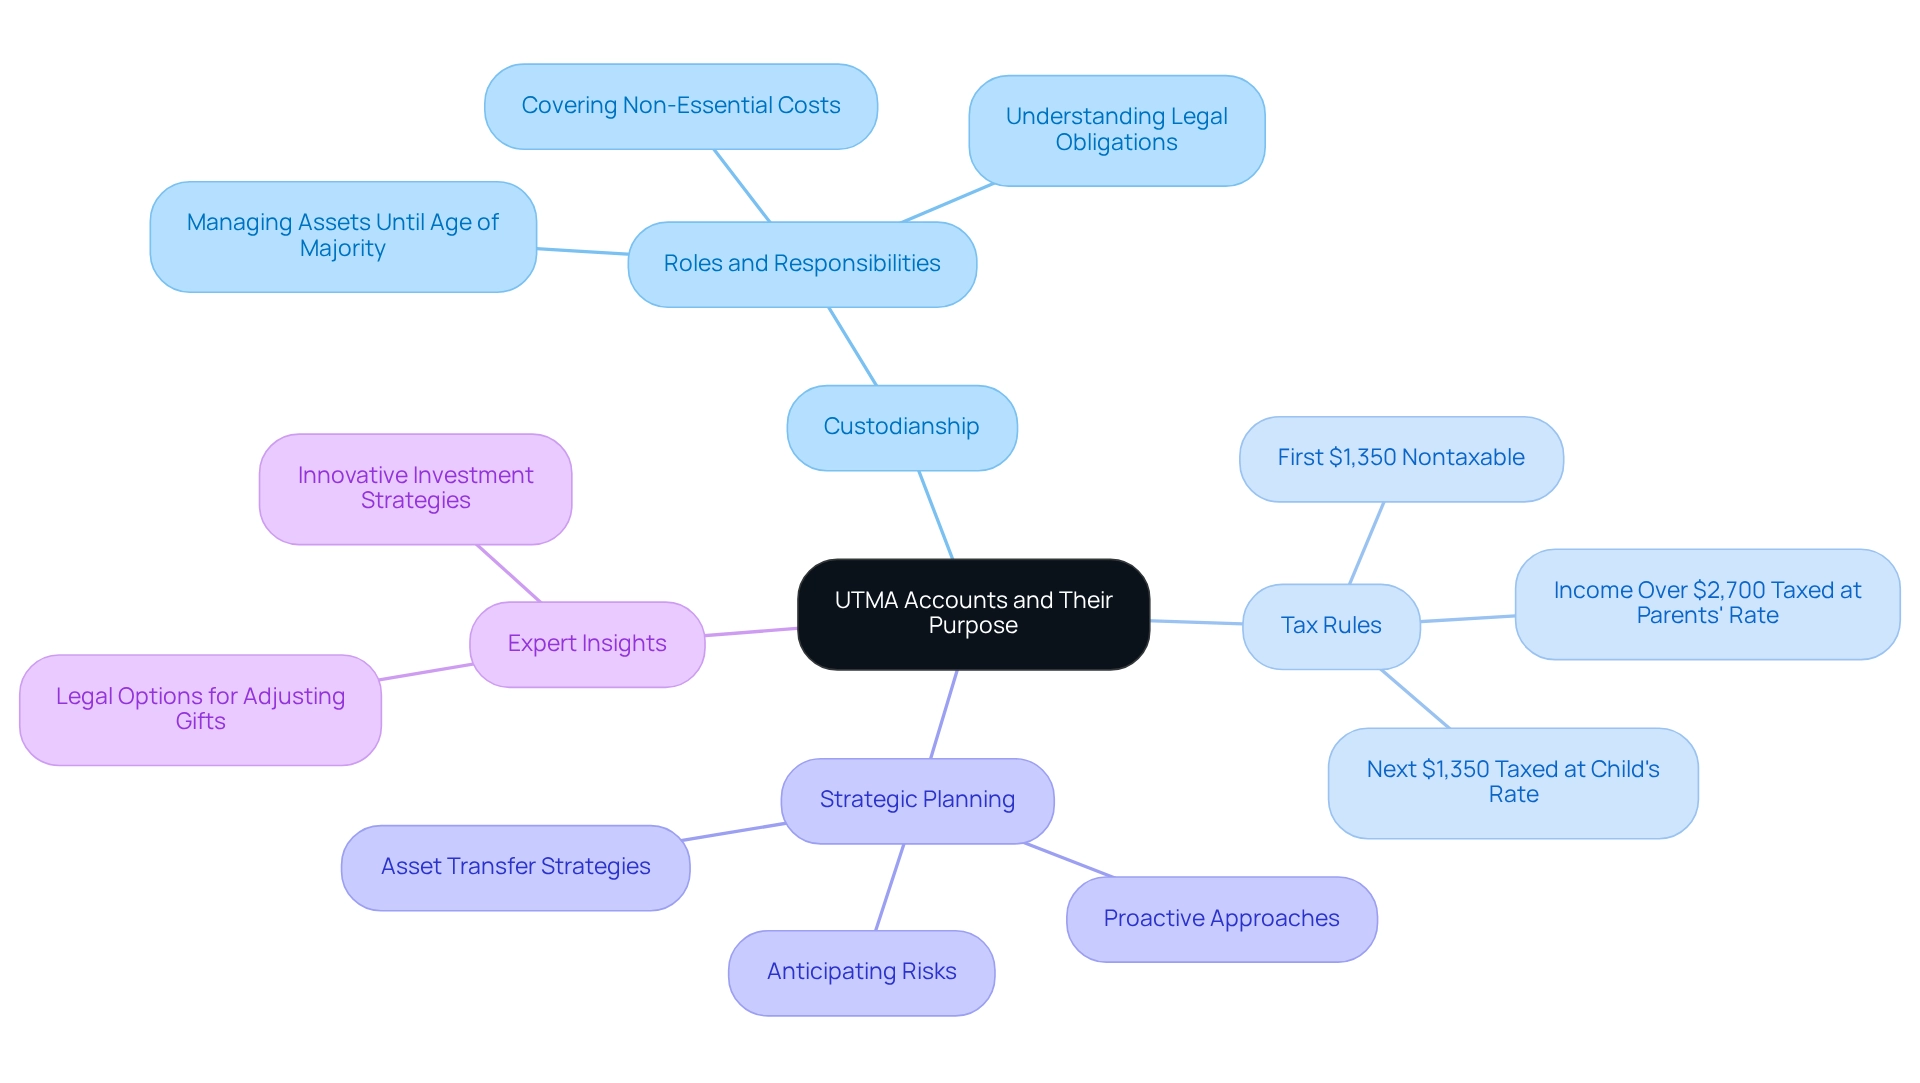
The Uniform Transfers to Minors Act offers a compassionate solution for transferring assets to young individuals without the complexities of establishing a trust. Imagine having a custodian who manages these assets until your child reaches the age of majority, and you might wonder, can a custodian withdraw from an UTMA account at that point, typically 18 or 21 years old, depending on your state. This arrangement is designed to allow young individuals to receive gifts, such as money or assets, while ensuring responsible oversight until they are ready to take charge.
Key characteristics of custodial arrangements include the ability to cover non-essential costs for your child, which can help alleviate some of the financial burdens parents face beyond basic support. As we look ahead to 2025, the Kiddie Tax rules indicate that:
- The first $1,350 of unearned income is nontaxable.
- The next $1,350 is taxed at your child’s rate.
- Any income exceeding $2,700 is taxed at the parents’ rate.
This framework underscores the importance of strategic planning in managing custodial accounts, especially for young families dedicated to enhancing their financial well-being, and highlights a key question: can a custodian withdraw from an UTMA account? As custodians, it’s crucial to understand your legal responsibilities and potential liabilities, as these factors significantly influence the management of custodial accounts. Proactive planning is essential, particularly as your children approach adulthood. This allows you to reassess your asset transfer strategies to align with your family’s goals. By anticipating risks and exploring flexible savings options, custodians can facilitate a smoother transition of assets, ultimately supporting the financial security of youth and empowering families to achieve their long-term aspirations.
Expert insights remind us that examining legal options to modify or restructure gifts can help manage the amount a child will be entitled to upon reaching the applicable age. This thoughtful approach ensures that custodians fulfill their obligations while maximizing the benefits of custodial funds for young individuals. Furthermore, Bright Advisers’ commitment to low fund fees and innovative investment strategies can enhance the management of custodial funds, equipping custodians with advanced tools and resources to optimize asset allocation and financial outcomes. Together, we can navigate this journey toward a secure future for your family.
Review Withdrawal Rules and Regulations for UTMA Accounts
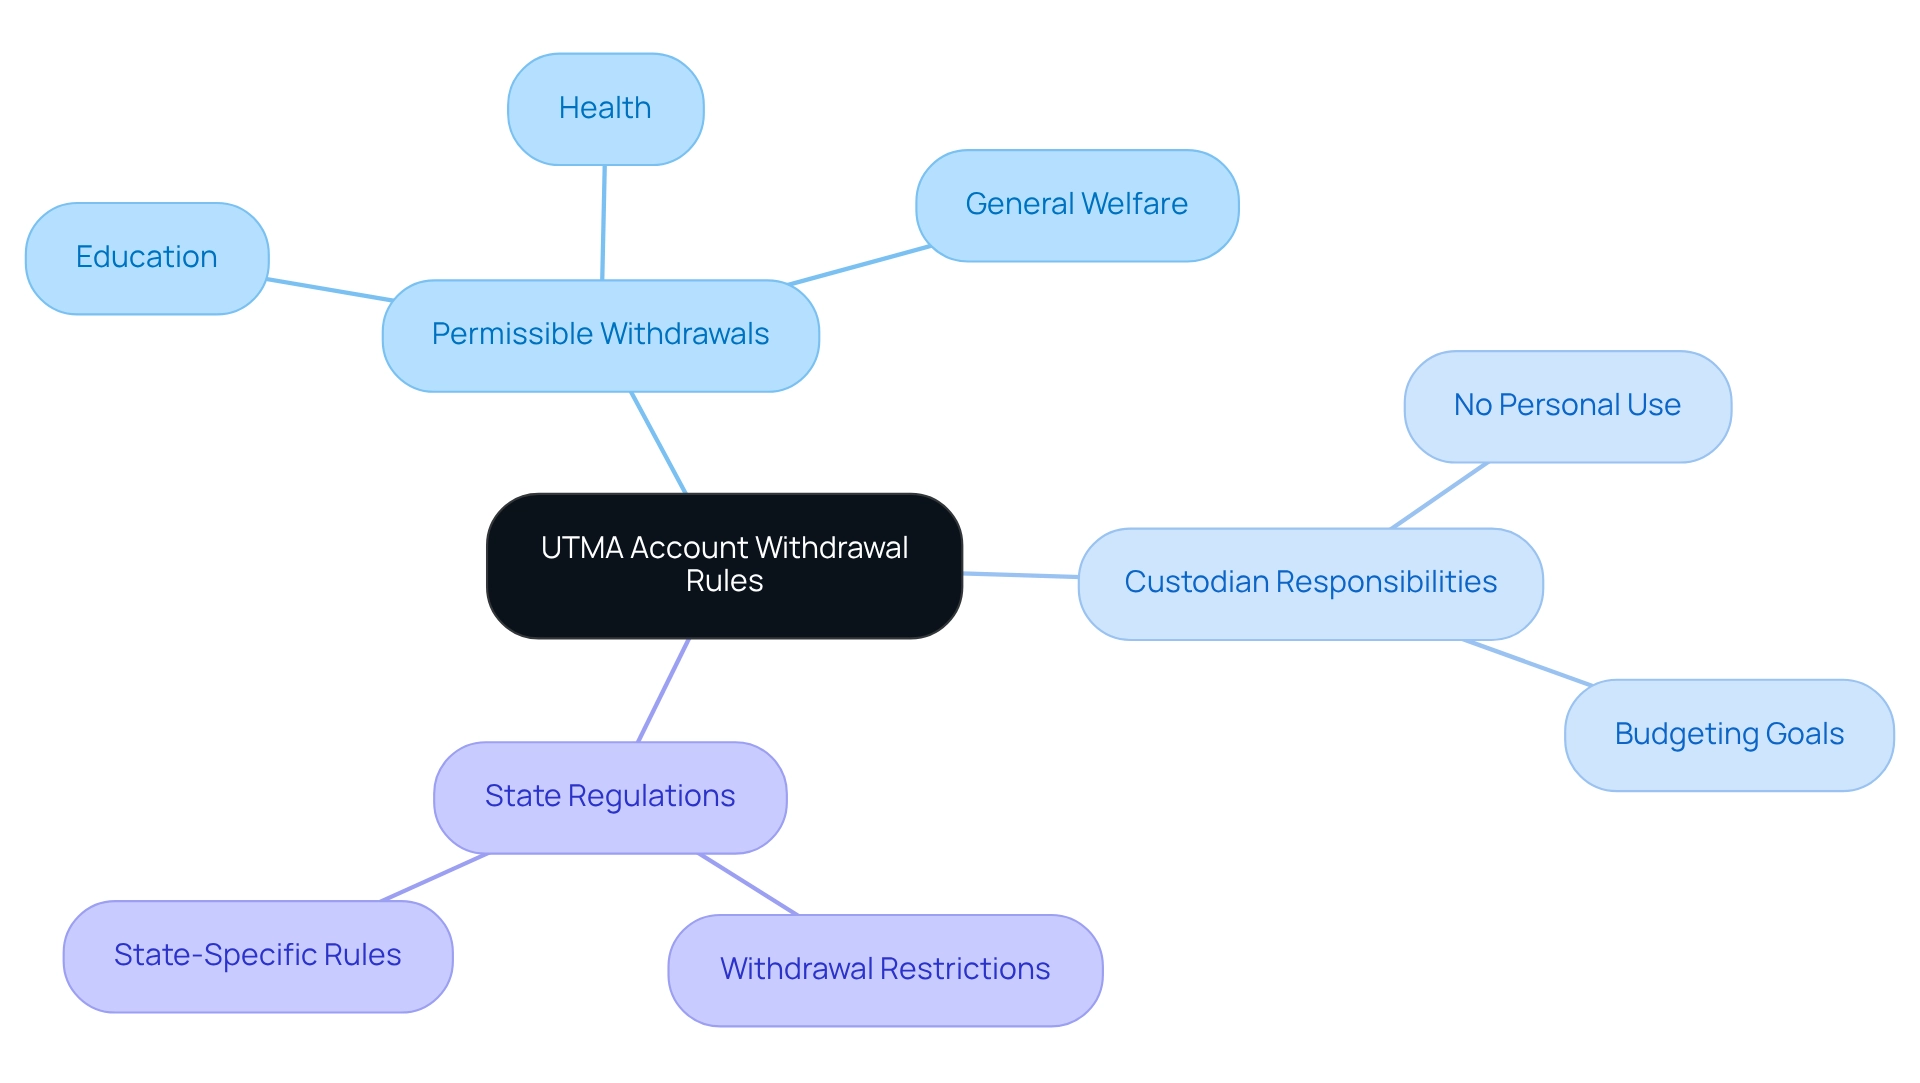
The question of whether a custodian can withdraw from an UTMA account arises, as withdrawals can only be made for the direct benefit of the minor. This is especially important for young families who are looking to ease their financial worries and secure a brighter future for their children. Custodians must ensure that the funds are used for expenses that support the child’s education, health, or general welfare, and they may wonder, can a custodian withdraw from an UTMA account? By carefully distributing these resources, we not only meet the immediate needs of the child but also align with long-term budgeting goals. It’s important to know that when considering what a custodian can withdraw from an UTMA account, they cannot use the funds for personal use or to meet their own financial obligations.
Additionally, custodians should be aware of state-specific regulations that may dictate when and how a custodian can withdraw from an UTMA account, as these may impose further restrictions on withdrawals. Familiarizing yourself with these rules is essential to avoid any legal complications. By ensuring that the funds are used appropriately, we empower young families to navigate their financial planning challenges effectively.
Imagine having a clear path to support your child’s future while also managing your family’s finances with confidence. We’re here for you, guiding you through these important decisions every step of the way.
Follow Steps to Withdraw Funds from a UTMA Account
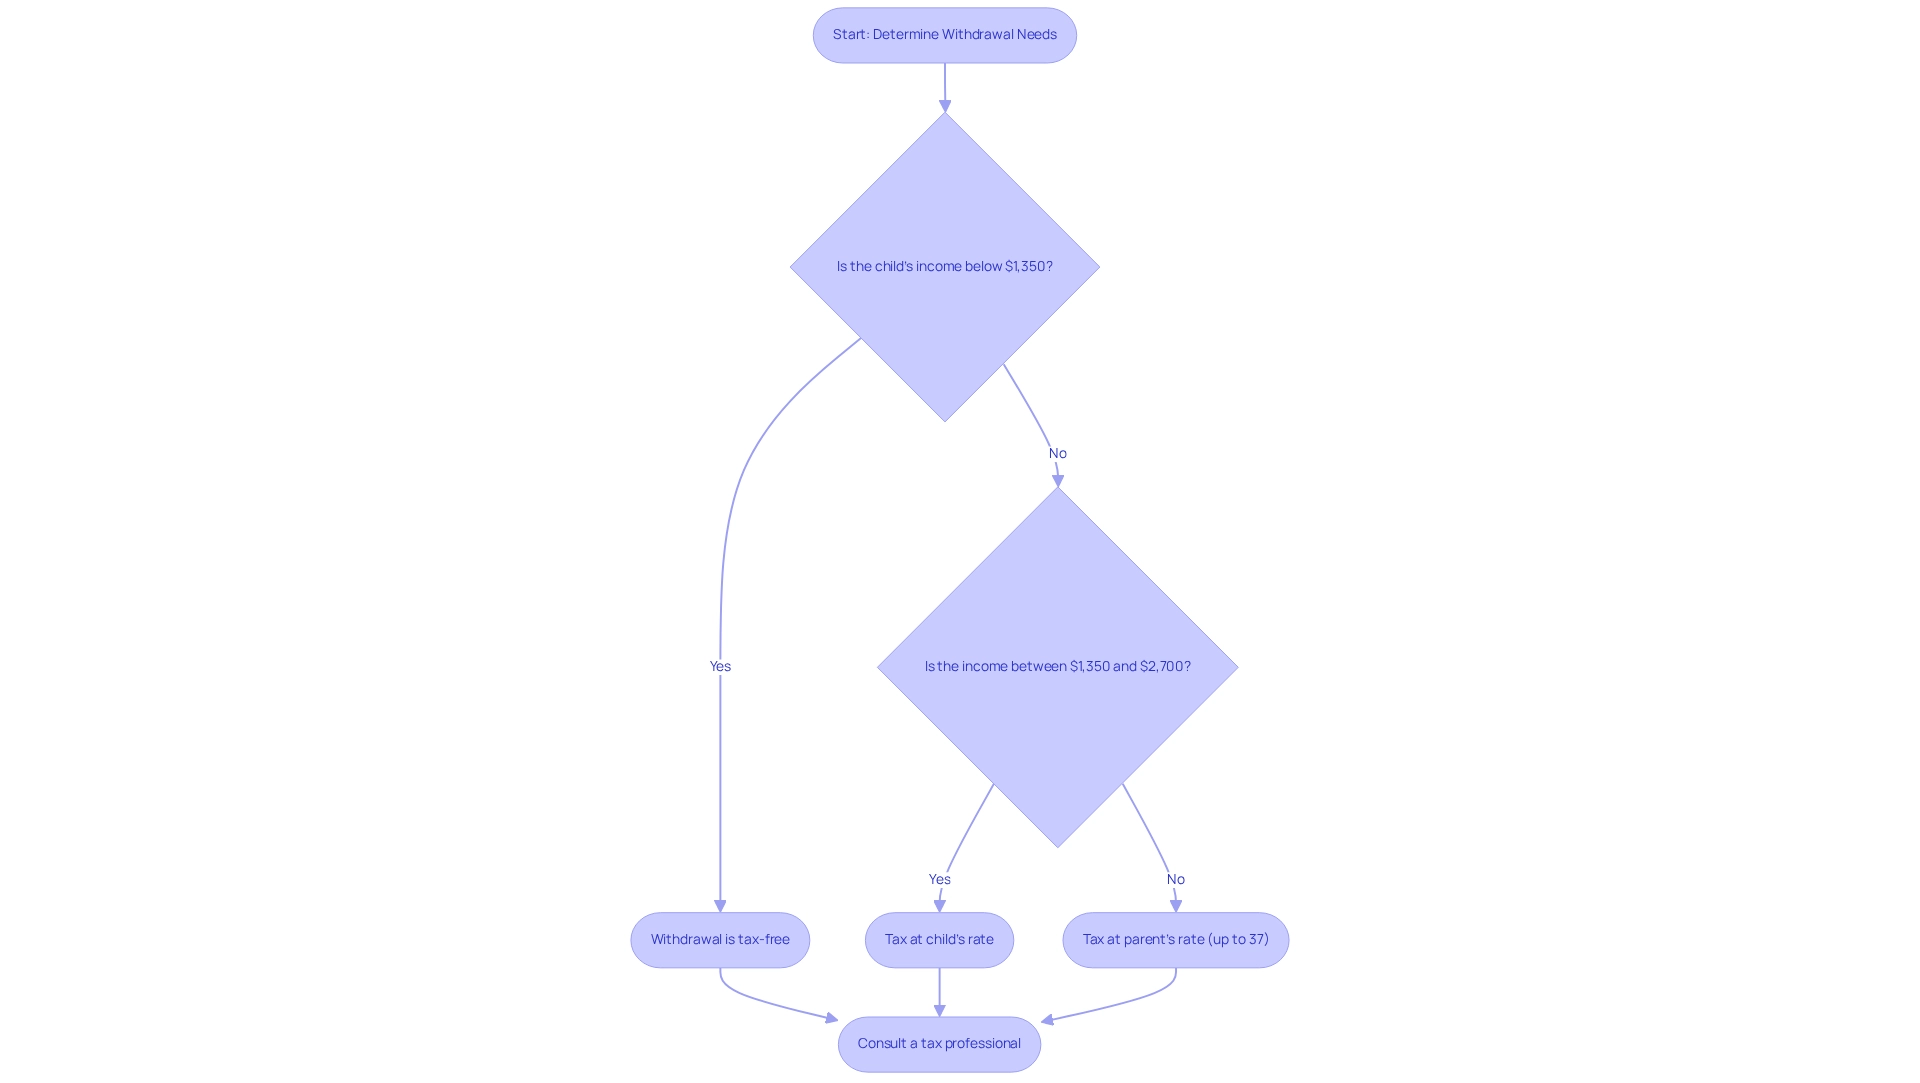
When it comes to withdrawals from a UTMA fund, it’s important to know that these are typically not taxed at the time of withdrawal, as contributions are made with after-tax dollars. However, the earnings generated within the fund are subject to taxation based on the child’s income level. For 2025, the tax structure for unearned income is designed to be fair:
- The first $1,350 is tax-free.
- The next $1,350 is taxed at the child’s rate.
- If the income exceeds this threshold, it is taxed at the parent’s rate, which can reach up to 37% for income above $751,600 for married couples filing jointly.
It is important for custodians to know if they can withdraw from a UTMA account while keeping meticulous records of all withdrawals. Consulting with a tax professional can help clarify how these actions impact both your tax situation and that of the child.
The Kiddie Tax is in place to ensure that children’s unearned income is taxed appropriately, preventing potential tax evasion strategies. For instance, consider how 1099 forms for custodial funds are issued in the child’s name, reinforcing their legal ownership of the assets. This practice ensures accurate tax reporting for any earnings generated, which is crucial for custodians to manage effectively, particularly when exploring the question of how much can a custodian withdraw from an UTMA account based on the child’s income level.
As custodians navigate these complexities, it’s vital to understand how the ability to answer whether a custodian can withdraw from an UTMA account can influence overall tax liabilities and future financial planning. Imagine if you could make informed decisions that align with your financial goals, while also laying a solid foundation for your child’s financial future. By being proactive and informed, you can truly make a difference.
Together, we can navigate this journey, ensuring that you feel supported every step of the way. We’re here for you as you work towards creating a brighter financial outlook for your family.
Identify Common Challenges and Solutions in UTMA Withdrawals
Withdrawing from a custodial fund raises the question: can a custodian withdraw from an UTMA account, which can be a significant step for your family? Here’s how to navigate this process with care:
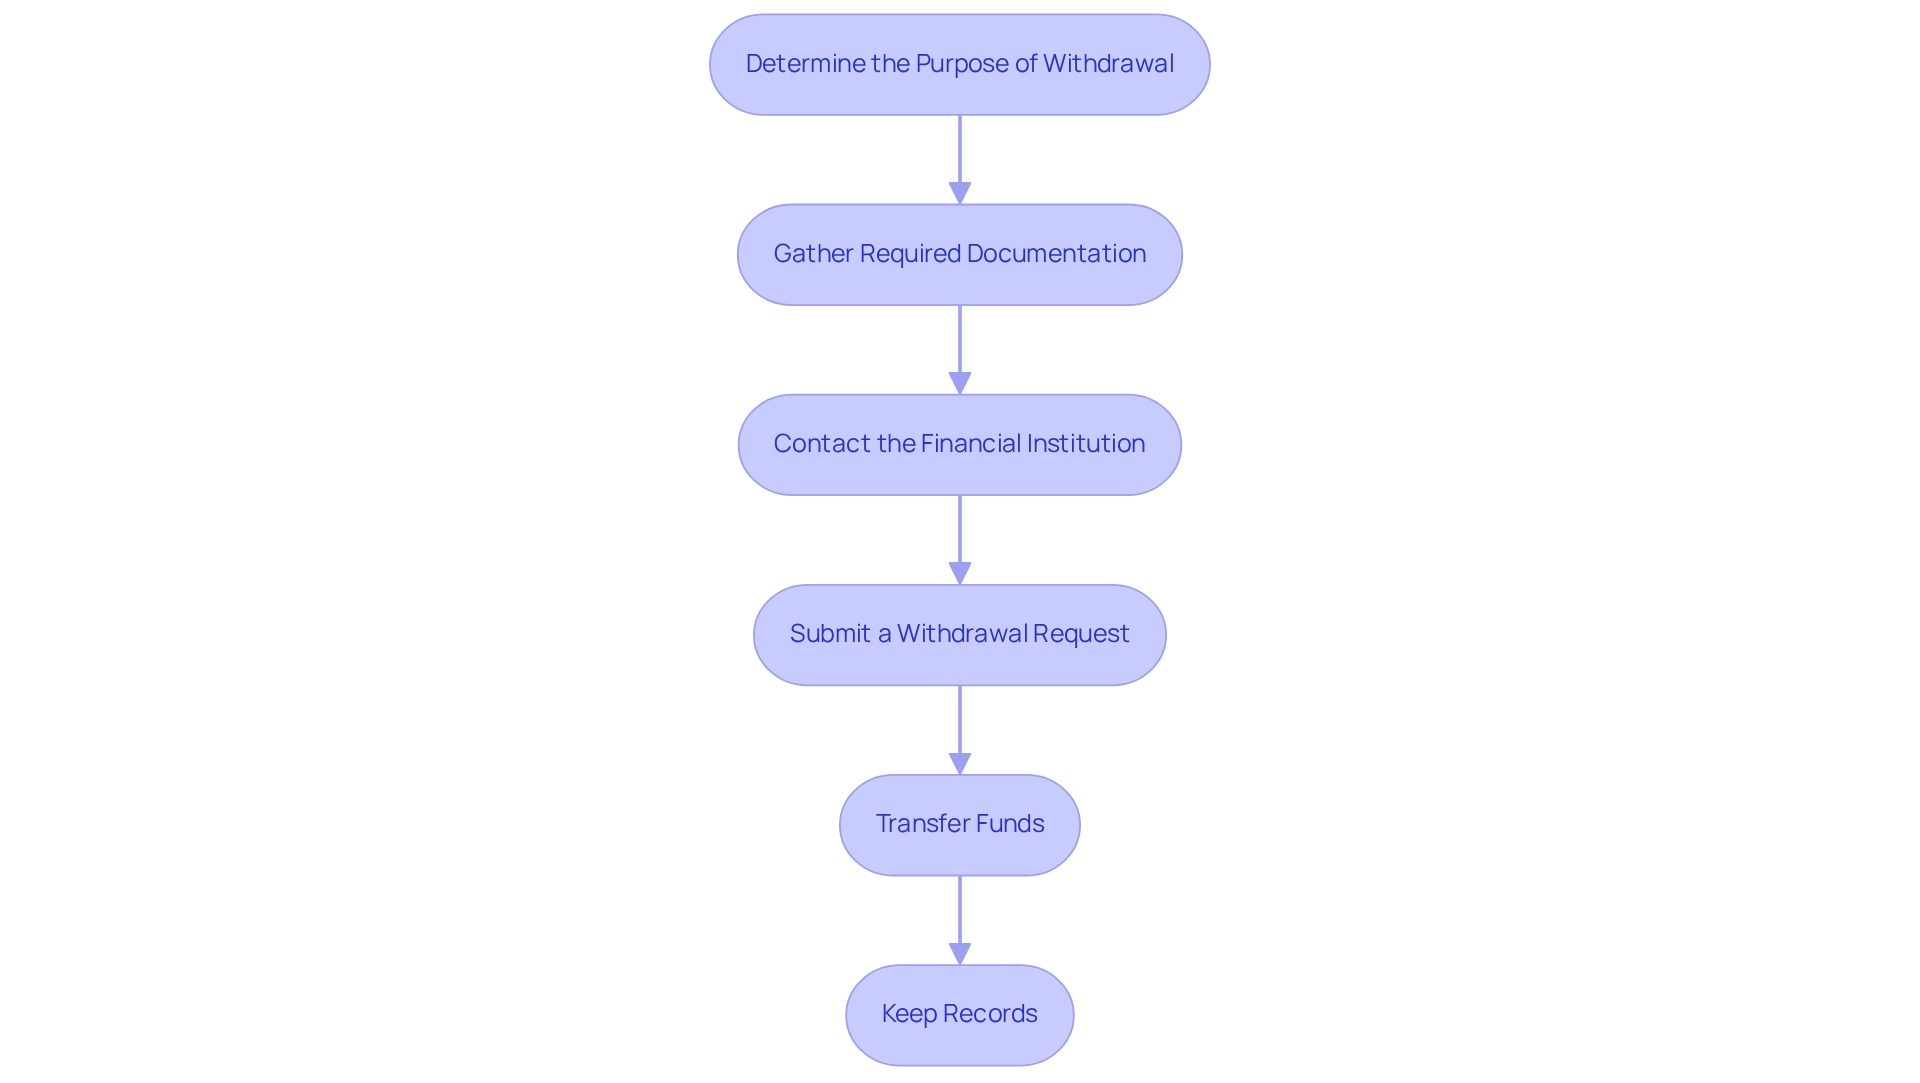
- Determine the Purpose of Withdrawal: Ensure that the funds will be used for the direct benefit of your child, such as educational expenses or medical bills.
- Gather Required Documentation: Collect necessary documents that justify the withdrawal, such as invoices or receipts for expenses.
- Contact the Financial Institution: Reach out to the bank or brokerage overseeing the UTMA fund. You can typically do this online, by phone, or in person.
- Submit a Withdrawal Request: Complete any required forms provided by the financial institution, and be prepared to explain the purpose of the withdrawal.
- Transfer Funds: Once approved, the funds can be sent to your deposit or directly to the service provider for your child’s benefit.
- Keep Records: Maintain thorough documentation of the withdrawal and how the funds were utilized. This ensures adherence to regulations and provides you with a reference for the future.
It’s important to note that, according to Section 20 of the act, custodians must transfer custodial property to the minor upon reaching 21 years of age or upon the minor’s death. This highlights the importance of using the funds appropriately during the custodial period.
At Bright Advisers, we understand the challenges families face. Our commitment to minimizing fund fees makes wealth management more accessible for you. Reduced fees allow for more resources to be allocated for your child’s necessities. Many custodians find themselves asking, can a custodian withdraw from an UTMA account for educational purposes, showcasing the adaptability of UTMA arrangements in customizing financial strategies to meet children’s future needs. Additionally, Bright Advisers offers tailored solutions to assist custodians in navigating the withdrawal process effectively. Alternatives to custodial accounts, such as 529 College Savings Plans and trusts, may present different withdrawal rules and tax implications, providing you with various options for saving for your child’s future. Remember, we’re here for you every step of the way, and together, we can navigate this journey.
Conclusion
Exploring UTMA accounts reveals their essential role in helping families transfer assets to minors, ensuring responsible management until they reach adulthood. As custodians navigate the complexities of these accounts, understanding their purpose, withdrawal regulations, and tax implications becomes crucial. By planning strategically and adhering to legal obligations, families can optimize their financial strategies, securing a brighter future for their children.
The withdrawal process, while straightforward, requires careful consideration of the funds’ intended use. It’s important to ensure that withdrawals support the minor’s education, health, or general welfare. This is not just a legal requirement; it’s a vital part of effective financial planning. By keeping meticulous records and consulting with tax professionals, custodians can prevent complications and align their actions with long-term financial goals.
Ultimately, managing UTMA accounts is an opportunity for custodians to empower young beneficiaries while fostering responsible financial habits. Imagine anticipating challenges and leveraging available resources—families can navigate this journey with confidence, ensuring that the assets entrusted to them serve their intended purpose. With the right knowledge and proactive strategies, UTMA accounts can be a powerful tool in building a secure financial foundation for the next generation. Together, we can navigate this journey with compassion and care.
Frequently Asked Questions
What is the purpose of UTMA accounts?
UTMA accounts allow parents to transfer assets to minors without the complexities of setting up a trust, enabling custodians to manage these assets until the child reaches the age of majority, typically 18 or 21 years old depending on the state.
Can a custodian withdraw from an UTMA account?
Yes, custodians can withdraw from an UTMA account to manage and utilize the funds for the benefit of the minor, but they must understand their legal responsibilities and potential liabilities in doing so.
What kind of expenses can custodial funds cover?
Custodial funds can cover non-essential expenses for the child, helping parents manage obligations that go beyond basic support.
What are the Kiddie Tax rules as they relate to UTMA accounts?
Under the Kiddie Tax rules, the first $1,350 of unearned income is nontaxable, the next $1,350 is taxed at the child’s rate, and any income exceeding $2,700 is taxed at the parents’ rate.
Why is strategic planning important for custodians managing UTMA accounts?
Strategic planning is crucial to ensure the child’s financial future is secure, allowing custodians to anticipate risks and explore flexible savings options as children approach adulthood.
How can custodians enhance the benefits of UTMA accounts for minors?
Custodians can explore legal avenues to modify or reorganize gifts, which can influence the amount a child will receive upon reaching the applicable age, maximizing the benefits of these financial arrangements.
List of Sources
- Understand UTMA Accounts and Their Purpose
- Gifts To Minors: Adjusting UTMA, 529 Plans, And Trusts (https://kitces.com/blog/david-haughton-utma-529-trust-parent-gifts-minors-regret-uniform-transfers-to-minors-actutma-529-trust-restructure-estate-planning)
- Custodial Accounts UTMA (https://pnc.com/en/personal-banking/investments-and-retirement/education-accounts/custodial-accounts-utma.html)
- What are the benefits and drawbacks of an UGMA / UTMA? (https://aboveboardfinancial.com/blog/what-are-the-benefits-and-drawbacks-of-ugma-utma-accounts)
- 77 Financial Advisor Quotes to Send to Clients (https://billgoodmarketing.com/resources/financial-advisor-quotes)
- Review Withdrawal Rules and Regulations for UTMA Accounts
- Custodial Accounts UTMA (https://pnc.com/en/personal-banking/investments-and-retirement/education-accounts/custodial-accounts-utma.html)
- Top 50 Financial Planning Quotes [2025] (https://digitaldefynd.com/IQ/financial-planning-quotes)
- 77 Financial Advisor Quotes to Send to Clients (https://billgoodmarketing.com/resources/financial-advisor-quotes)
- Everything You Need to Know About UTMA Account Rules (https://getearlybird.io/blog/utma-account-rules)
- Follow Steps to Withdraw Funds from a UTMA Account
- What is the Kiddie Tax? (https://savingforcollege.com/article/what-is-the-kiddie-tax)
- UTMA Tax Rules 2023 & 2024 – Greatest Gift (https://greatestgiftapp.com/blog/utma-tax-rules)
- Custodial Accounts UTMA (https://pnc.com/en/personal-banking/investments-and-retirement/education-accounts/custodial-accounts-utma.html)
- FAQs on UTMA Accounts (https://searcyfinancial.com/blog/faqs-on-utma-accounts)
- Identify Common Challenges and Solutions in UTMA Withdrawals
- Custodial Account | Plan For A Child’s Future | Fidelity Investments (https://fidelity.com/open-account/custodial-account)
- UTMA Tax Rules 2023 & 2024 – Greatest Gift (https://greatestgiftapp.com/blog/utma-tax-rules)
- Regulatory Notice 20-07 | FINRA.org (https://finra.org/rules-guidance/notices/20-07)
- Custodial Account Withdrawals: Rules and Best Practices – FasterCapital (https://fastercapital.com/content/Custodial-Account-Withdrawals–Rules-and-Best-Practices.html)
- Everything You Need to Know About UTMA Account Rules (https://getearlybird.io/blog/utma-account-rules)
- Understanding UTMA Accounts and Their Role in Estate Planning . (https://legacycarelaw.com/blog/estate-planning-2/understanding-utma-accounts-and-their-role-in-estate-planning)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Age Five Wealth Education for high-income W-2 families at Bright Advisers.
Keep reading