

Overview
Navigating the world of investment management fees can feel overwhelming, especially for young parents. It’s vital to understand the fee structures that affect your family’s financial future. By evaluating these fees, you can make informed decisions that align with your family’s values.
Imagine if you could uncover the hidden costs that might be eating into your returns. Recognizing the various types of fees is the first step towards ensuring that your investments work as hard as you do. Transparency in these costs can empower you to negotiate better terms, leading to more significant savings for your family.
Engaging with a trusted advisor is crucial. They can help you assess total costs and guide you through the complexities of investment fees. Remember, you’re not alone in this journey. We’re here for you, ready to support you in making the best financial choices for your family’s future.
Together, we can navigate this journey, ensuring that your investments reflect your family’s priorities and goals. Let’s take that first step towards financial clarity and security.
Key Highlights:
- Investment management fees significantly affect financial returns, typically ranging from 0.01% to over 2% of assets under management (AUM).
- Bright Advisers aims to keep fund costs low, benefiting families, especially young parents seeking better investment returns.
- Robo-advisors generally offer lower AUM fees (0.25% to 0.50%) compared to traditional advisors, making them appealing for cost-conscious families.
- Understanding fee structures, such as flat fees, percentage of AUM, tiered charges, and performance-based fees, is crucial for aligning financial goals.
- Families that engage with advisors about fee structures feel more empowered and confident in their financial decisions.
- Transparency in fee communication fosters trust between clients and advisors, with 85% of clients feeling more confident when costs are disclosed.
- Families should assess their investment goals, analyze portfolio size, and consider the services offered when selecting a fee structure.
- Hidden fees, such as transaction fees and fund expense ratios, can significantly reduce overall returns, making it essential to request a comprehensive cost breakdown.
- Negotiating fees can be beneficial, especially for those with substantial portfolios, to secure favorable arrangements.
Introduction
In the intricate world of investment management, understanding the fees associated with portfolio management is essential for families aiming to secure their financial futures. Imagine navigating this landscape, where investment management fees—ranging widely depending on the services provided—play a pivotal role in your overall returns.
As you embark on this financial journey, grasping the nuances of various fee structures, from flat fees to performance-based models, becomes crucial. It’s important to understand that with the rise of robo-advisors and a growing focus on transparency, the landscape is evolving, presenting both challenges and opportunities.
This article delves into the significance of investment management fees, explores common fee structures, and offers guidance on selecting the right approach tailored to your individual needs. Together, we can navigate this journey, ensuring your family is well-equipped to make informed financial decisions.
Understand Investment Management Fees
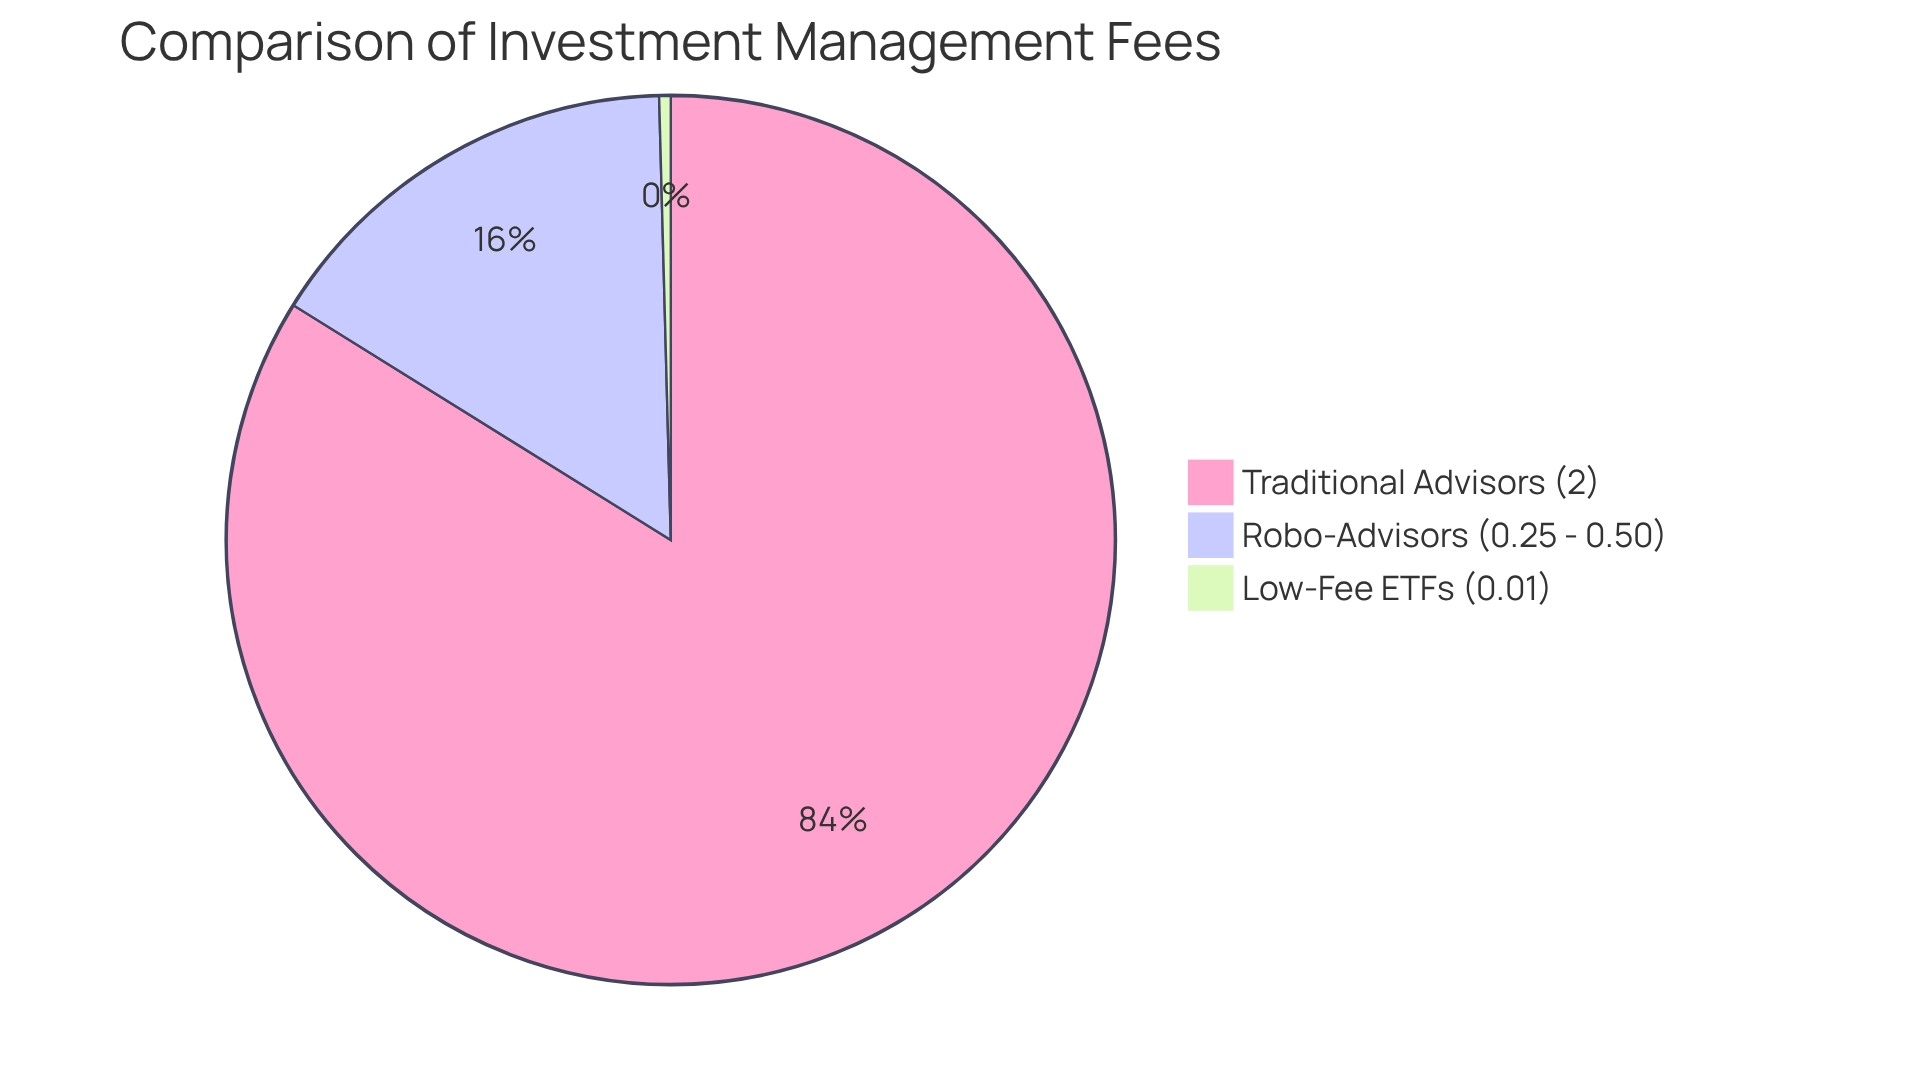
Understanding the fee for investment management is essential for families navigating their financial journeys. These expenses, which include the fee for investment management and are incurred for professional oversight of portfolios, can vary significantly based on the services provided and the firm’s pricing structure. Typically represented as a percentage of assets under management (AUM), the fee for investment management can range from as low as 0.01% to over 2%. Comprehending the fee for investment management is crucial, as it can significantly influence your returns over time. Imagine a 1% fee for investment management on a $100,000 contribution—this can lead to a substantial decrease in overall returns compared to a lower fee for investment management structure.
At Bright Advisers, we are dedicated to keeping fund costs low across most of our models, making wealth management more accessible for families. Some clients may hold legacy fee-bearing mutual funds and ETFs, which can incur higher costs, while others might choose low-fee ETFs to gain exposure to fixed income or alternative asset classes like precious metals and cryptocurrencies. This commitment to minimal charges is particularly beneficial for young parents looking to enhance their investment returns.
Recent trends show that robo-advisors typically offer reduced AUM fees, generally ranging from 0.25% to 0.50%, compared to traditional advisors. This makes them an appealing choice for cost-conscious families. However, the financial advisory market encompasses a spectrum of services, from low-cost options to more personalized services that include a fee for investment management. It’s important to assess what services are included in the fee for investment management to ensure you receive adequate value.
Practical examples illustrate how families have benefited from understanding investment management costs. Families that actively engaged with their advisors about fee structures reported feeling more empowered in their financial decisions, leading to better alignment with their long-term goals. A case study on transparency in advisory services highlights that consultants who clearly communicate their charges foster trust and comfort among clients. Indeed, research revealed that 85% of clients felt more confident in their financial choices when their advisors were open about costs, which is vital for a thriving advisory partnership.
Current expert opinions emphasize that understanding the fee for investment management costs is more important than ever, especially as global economic conditions evolve. As high-quality growth stocks may become scarce, families must be mindful of how costs affect their portfolio returns. As Warren Buffett wisely stated, “The best way to predict the future is to create it.” In 2025, the fee for investment management will remain a critical factor, as it can greatly impact net returns. Ultimately, being aware of the fee for investment management and its implications is a key step toward securing a strong financial future for families. Together, we can navigate this journey and ensure your family’s financial well-being.
Explore Common Fee Structures
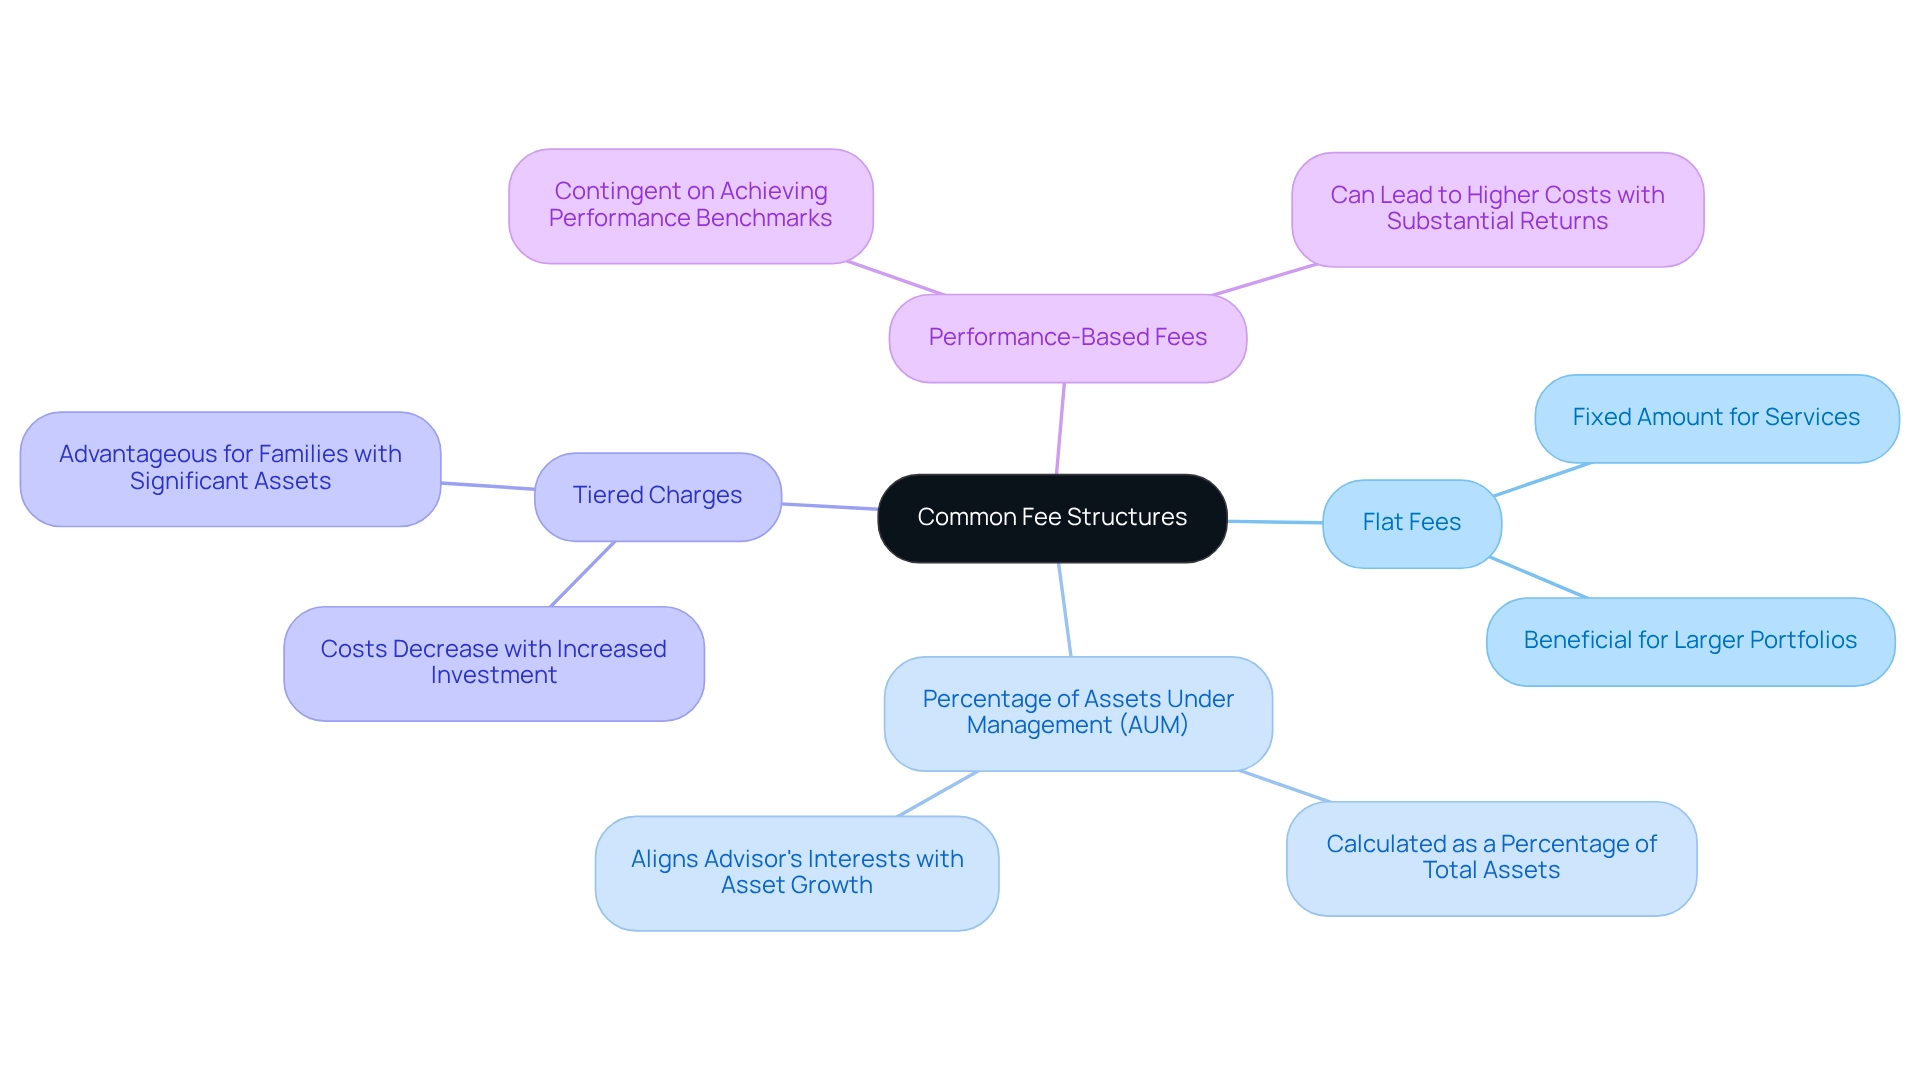
Investment management often involves various arrangements for fee for investment management that can significantly impact your financial planning. Understanding these options can empower you to make informed decisions that align with your family’s financial goals.
- Flat Fees: Imagine a fee structure where you pay a fixed amount for services, regardless of your capital size. This can be especially beneficial for larger portfolios, as the fee remains steady no matter how much you have invested.
- Percentage of Assets Under Management (AUM): This is the most prevalent arrangement, where fees are calculated as a percentage of your total assets managed. For example, if you have $1 million under management with a 1% fee, your annual cost would be $10,000. This model aligns the advisor’s interests with your asset growth, making it appealing for families focused on building wealth.
- Tiered Charges: In this structure, costs decrease as your investment amount increases. For instance, the first $500,000 might incur a 1% fee, while amounts beyond that could be charged at a lower rate, such as 0.75%. This can be advantageous for families with significant assets, as it reduces costs for larger portfolios.
- Performance-Based Fees: These fees are contingent on the investment manager achieving specific performance benchmarks. While they can motivate managers to excel, they may also lead to higher costs if substantial returns are realized.
As we look ahead to 2025, families are increasingly mindful of these fee structures amidst economic complexities. Take, for example, young professionals Emily and Mark. With the support of Bright Advisers, they prioritized their long-term financial objectives while balancing their careers and family life. Collaborating with Bright Advisers provided them with tailored guidance that not only refined their financial strategies but also aligned with their aspirations for financial independence.
When evaluating pricing structures, it’s essential for families to weigh the pros and cons of the fee for investment management against percentage-based fees. Flat fees offer consistency and can be more economical for larger portfolios, while percentage fees might suit those just starting their financial journey. As financial expert Andrea Coombes wisely notes, “Thankfully, just as there is wide variance in how much a financial advisor costs, there are plenty of options to choose from.” This diversity is crucial for families when selecting a fund manager.
Moreover, it’s vital to recognize that legacy fee-bearing mutual funds and ETFs can impact overall expense levels, affecting around 60 million participants managing $3 trillion in assets. By understanding these typical charge frameworks, families can choose the right asset manager, ensuring their financial plans resonate with their values and long-term aspirations. Together, we can navigate this journey toward a secure financial future.
Evaluate the Right Fee Structure for Your Needs
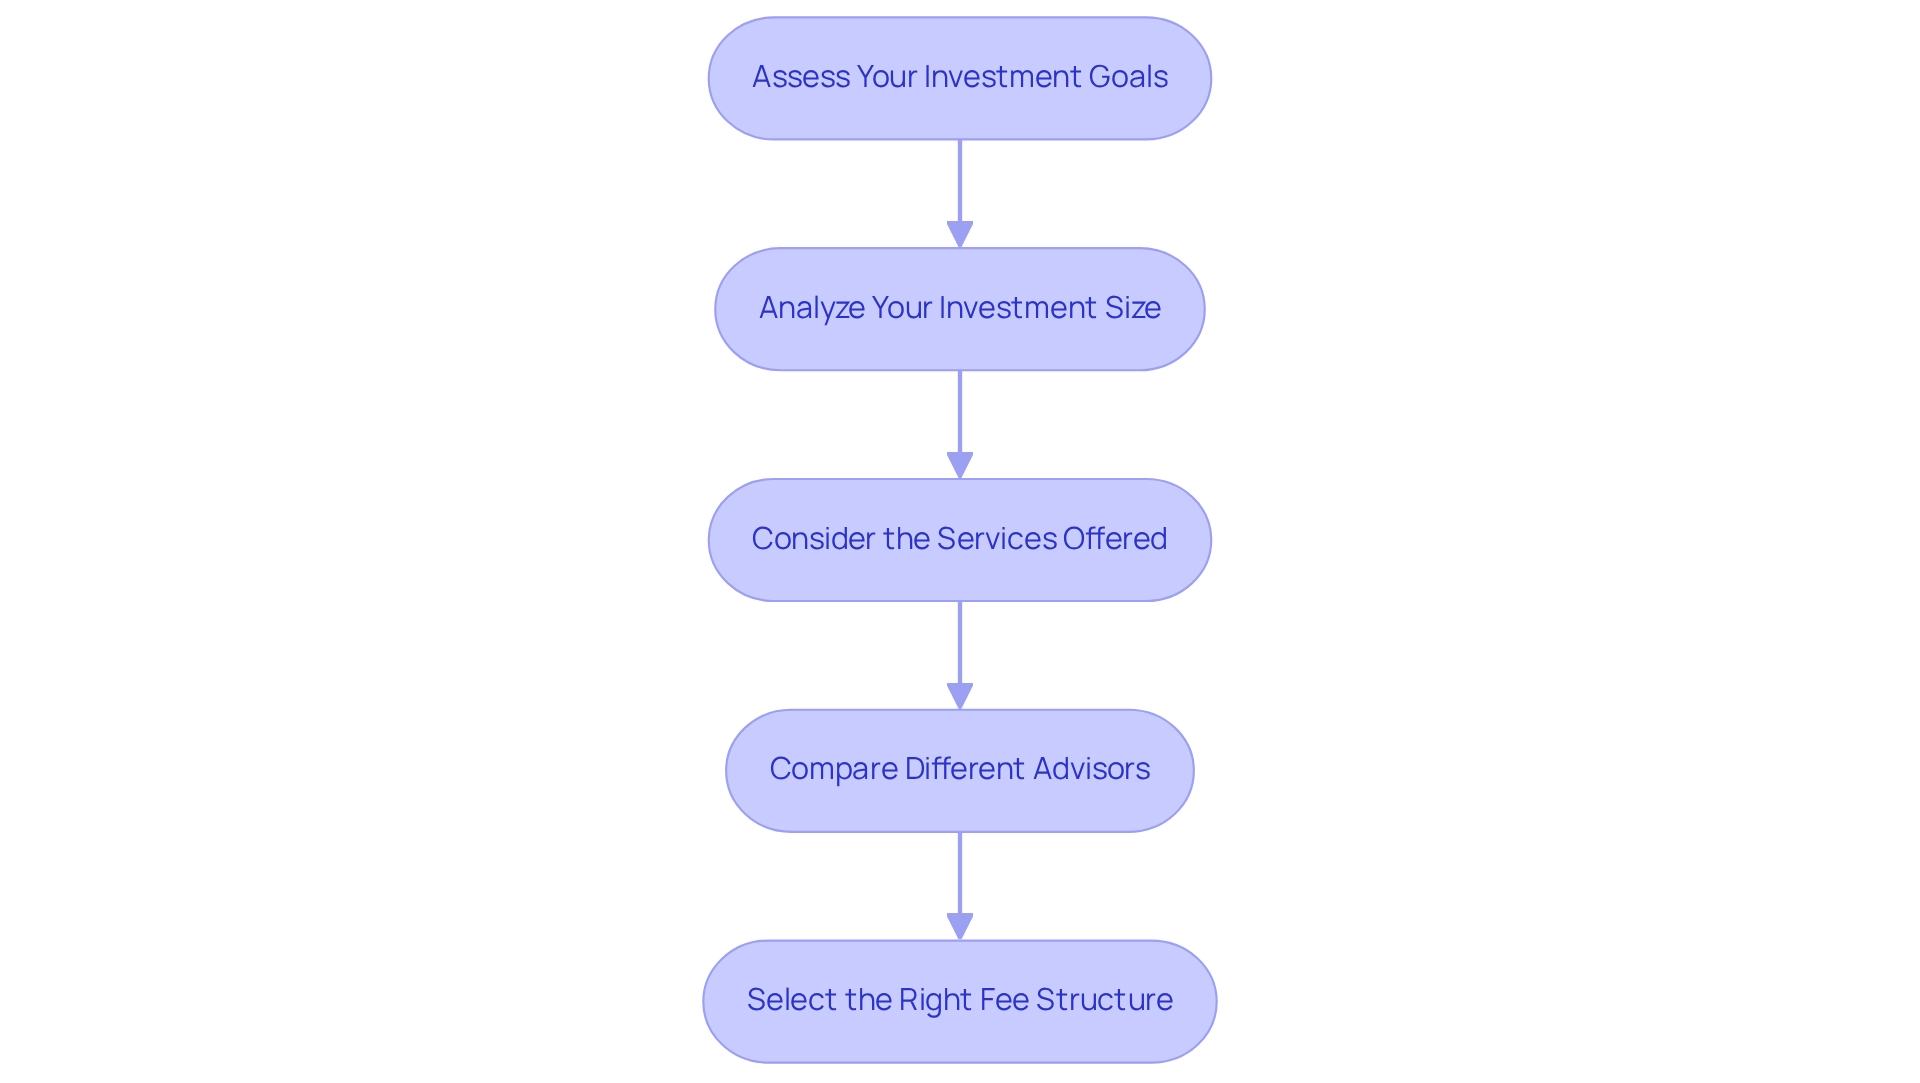
To find the right fee structure for your investment management needs, let’s take a thoughtful approach together:
- Assess Your Investment Goals: Start by clearly defining what you hope to achieve. Are you aiming for aggressive growth, or is capital preservation more important for your family? Understanding your objectives will guide you in selecting the right fee for investment management. As retirement and investing expert Ben Geier wisely points out, “Even before you go to an advisor, you should know how much money you’ll need for retirement and how close you are to being on track.”
- Analyze Your Investment Size: Consider how the size of your portfolio can influence the fee arrangement. Larger portfolios often benefit from flat or tiered fees, which can help lower overall costs. On the other hand, smaller portfolios might find percentage-based fees easier to manage and understand.
- Consider the Services Offered: It’s essential that the fee structure aligns with the services you truly need. If your requirements extend beyond just investment management to include comprehensive planning, a flat fee for investment management might provide greater value than a percentage-based charge focused solely on investments. At Bright Advisers, our onboarding process is designed to support you, including data gathering, strategy sessions, and personalized financial planning. We’re here to guide you through each step, helping you document your family strategy and develop a sound financial plan.
- Compare Different Advisors: Take the time to explore and compare the fee structures of various advisors. Seek clarity on how charges are determined and what services are included. The case study titled ‘Differentiating Through Clear Communication’ emphasizes the importance of advisors effectively conveying their unique value propositions regarding charges and services. This careful assessment empowers you to select a pricing model that maximizes your financial potential while minimizing unnecessary expenses, such as the fee for investment management.
Additionally, keep in mind that Bright Advisers offers a free initial consultation to potential clients. This is a wonderful opportunity to explore your options without any upfront commitment. Our commitment to minimal fund charges enhances wealth management accessibility for families, allowing you to focus on your economic security and freedom.
By following these gentle steps, families can thoughtfully evaluate their financial objectives and choose the most suitable fee for investment management, laying a strong economic foundation for the future.
Assess Total Costs and Hidden Fees
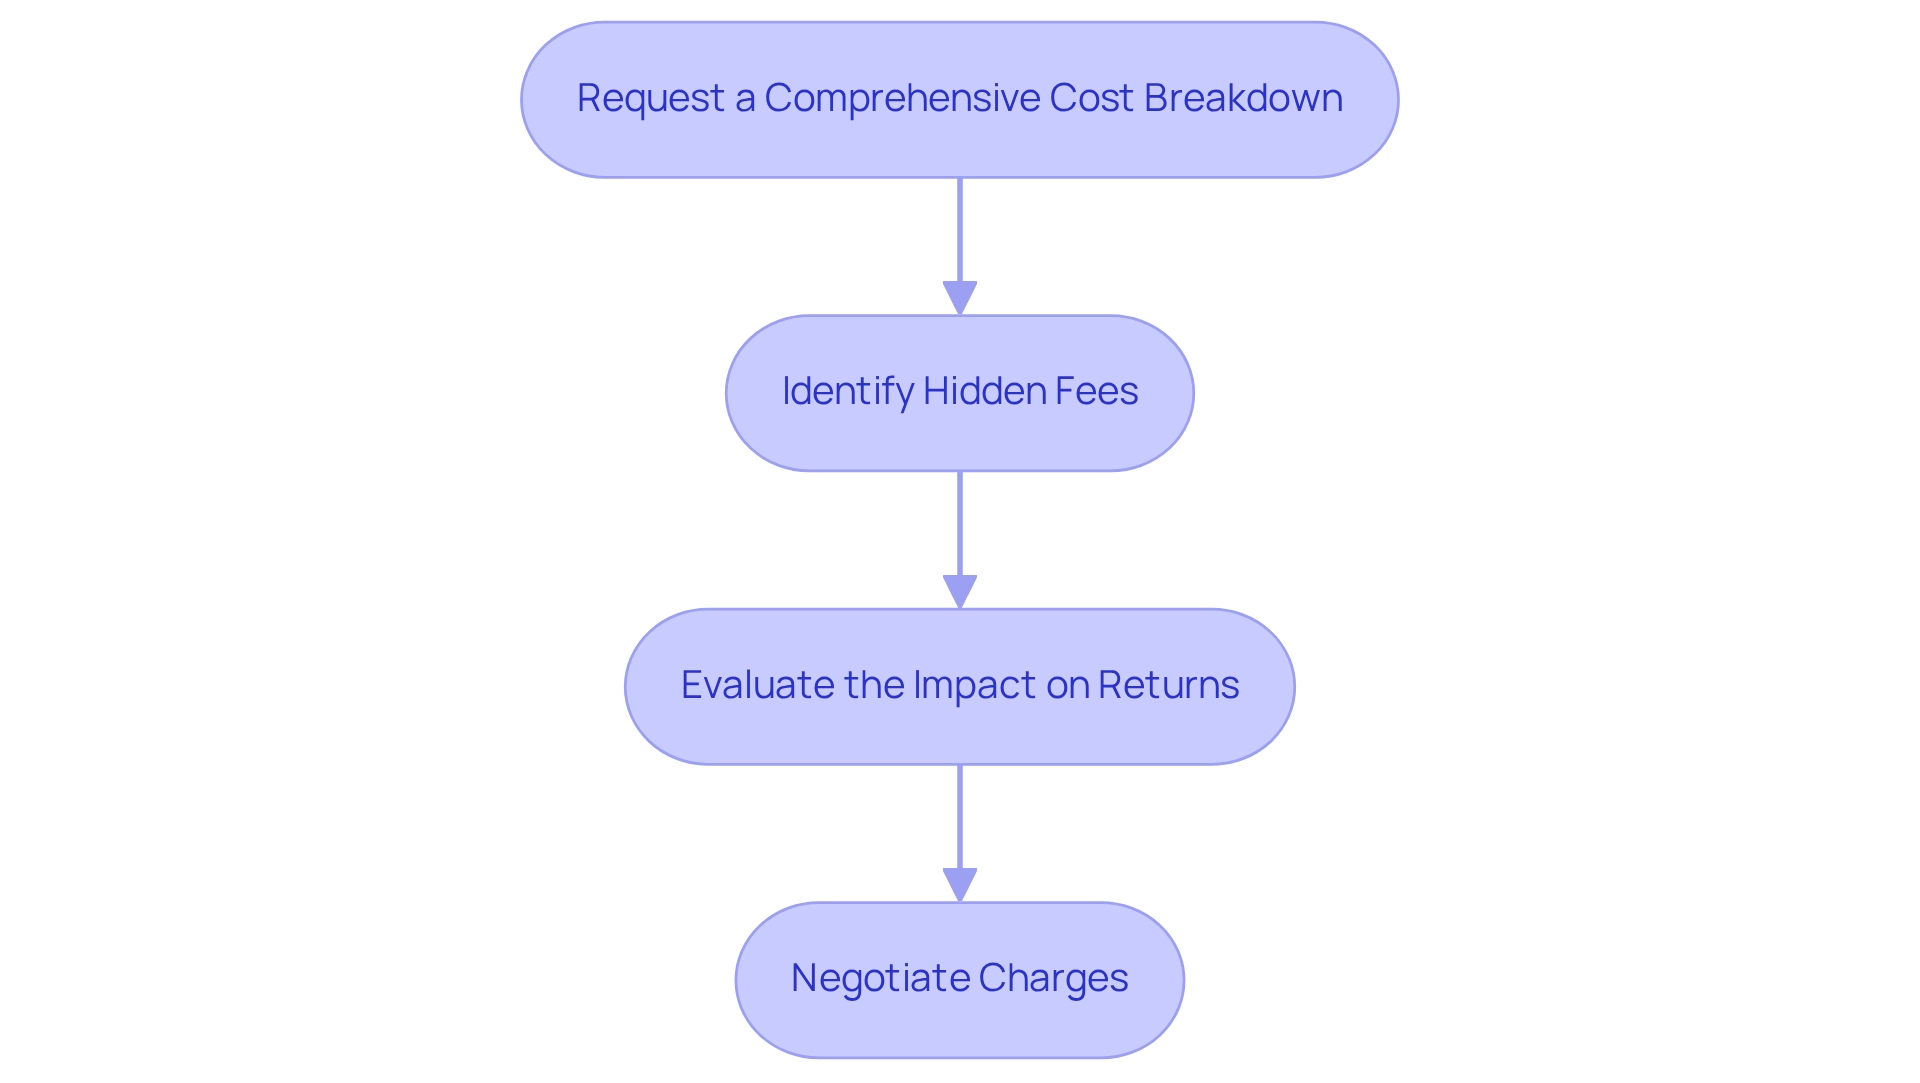
To effectively assess total costs and the fee for investment management, consider these gentle steps:
-
Request a Comprehensive Cost Breakdown: Start a conversation with your asset manager about all the charges associated with your account. This includes management costs, trading expenses, and any additional fee for investment management that may apply. At Bright Advisers, we prioritize transparency, ensuring our clients fully understand the minimal fund charges related to their assets.
-
Identify Hidden Fees: Stay alert for fees that might not be immediately apparent, such as transaction fees, fund expense ratios, and performance fees. Imagine if hidden costs accumulated and significantly reduced your overall returns—sometimes by as much as 2% each year. Over time, this can lead to considerable losses, which is why it’s essential to be informed.
-
Evaluate the Impact on Returns: Utilize financial tools or calculators to envision how different fee structures could impact your long-term investment outcomes. Even minor differences in charges can lead to significant losses over time, underscoring the importance of this evaluation. It’s vital to focus on key financial decisions, such as understanding costs.
-
Negotiate Charges: Don’t hesitate to discuss your fees with your investment manager. If you have a substantial portfolio, you may have the leverage to secure a more favorable fee arrangement. A case study titled ‘Choosing the Right Advisors’ highlights the importance of selecting knowledgeable and experienced consultants. This choice can be crucial in maintaining clarity regarding the fee for investment management. By diligently assessing total expenses and hidden charges, families can make informed decisions that align with their financial goals. This proactive approach not only enhances transparency but also empowers families to optimize their investment strategies for better financial health. Remember, at Bright Advisers, we’re here for you, committed to making wealth management accessible and supportive as you navigate this journey together.
Conclusion
Understanding investment management fees is essential for families who wish to secure their financial futures. These fees, which can vary widely depending on the service model, play a crucial role in determining overall investment returns. By exploring different fee structures—such as flat fees, percentage-based fees, tiered fees, and performance-based fees—families can make informed decisions that align with their financial goals and investment strategies.
It’s important to recognize the significance of transparency in this process. Engaging in open discussions with advisors about fee structures and hidden costs fosters trust and empowers families to make sound financial decisions. Families that actively assess their investment goals, analyze their portfolio sizes, and compare different advisors are better equipped to select the most suitable fee structures tailored to their unique needs.
Ultimately, navigating the complexities of investment management fees is a key step towards building a strong financial foundation. By being informed and proactive, families can minimize unnecessary costs and maximize their investment potential, ensuring a more secure and prosperous future. As the financial landscape continues to evolve, understanding these fees remains a cornerstone of effective investment management. Remember, together, we can navigate this journey toward a brighter financial future.
Frequently Asked Questions
Why is understanding the fee for investment management important for families?
Understanding the fee for investment management is essential because these expenses can significantly influence investment returns over time. Knowing the fee structure helps families navigate their financial journeys more effectively.
How are investment management fees typically represented?
Investment management fees are usually represented as a percentage of assets under management (AUM) and can range from as low as 0.01% to over 2%.
What impact does a 1% fee for investment management have on a $100,000 investment?
A 1% fee on a $100,000 contribution can lead to a substantial decrease in overall returns compared to a lower fee structure.
How does Bright Advisers approach fund costs?
Bright Advisers is dedicated to keeping fund costs low across most of their models, making wealth management more accessible for families.
What types of investment vehicles can incur higher costs?
Legacy fee-bearing mutual funds and ETFs can incur higher costs, while low-fee ETFs are available for those seeking exposure to fixed income or alternative asset classes.
How do robo-advisors compare to traditional advisors in terms of fees?
Robo-advisors typically offer reduced AUM fees, generally ranging from 0.25% to 0.50%, making them an appealing choice for cost-conscious families.
What should families consider when evaluating investment management fees?
Families should assess what services are included in the fee for investment management to ensure they receive adequate value for the costs incurred.
How can understanding investment management costs empower families?
Families that actively engage with their advisors about fee structures report feeling more empowered in their financial decisions, leading to better alignment with their long-term goals.
What does research indicate about transparency in advisory services?
Research shows that 85% of clients felt more confident in their financial choices when their advisors were open about costs, which fosters trust and comfort in the advisory partnership.
Why is it crucial to understand investment management fees in the current economic climate?
As global economic conditions evolve and high-quality growth stocks may become scarce, families must be mindful of how costs affect their portfolio returns, making it more important than ever to understand investment management fees.
List of Sources
- Understand Investment Management Fees
- 90 Warren Buffett Quotes on Investing, Business, and Life (https://sarwa.co/blog/warren-buffett-quotes)
- What to Know About Financial Advisor Fees & Costs (https://money.usnews.com/financial-advisors/articles/what-to-know-about-financial-advisor-fees-and-costs)
- How Much Does a Financial Advisor Cost in 2025? – NerdWallet (https://nerdwallet.com/article/investing/how-much-does-a-financial-advisor-cost)
- How Much Do Financial Advisors Charge? Your Updated Guide for 2025 (https://moneylogue.com/blog/how-much-do-financial-advisors-charge-your-updated-guide-for-2025)
- Explore Common Fee Structures
- What to Know About Financial Advisor Fees & Costs (https://money.usnews.com/financial-advisors/articles/what-to-know-about-financial-advisor-fees-and-costs)
- How Much Does a Financial Advisor Cost in 2025? – NerdWallet (https://nerdwallet.com/article/investing/how-much-does-a-financial-advisor-cost)
- What Is a Management Fee? Definition, Average Cost, and Example (https://investopedia.com/terms/m/managementfee.asp)
- Evaluate the Right Fee Structure for Your Needs
- Fee-Only vs. Fee-Based Financial Advisors (https://smartasset.com/financial-advisor/fee-based-vs-fee-only-financial-advisor)
- highlandplanning.com (https://highlandplanning.com/learning-center-1/decoding-financial-advisor-fees-your-guide-to-transparent-costs)
- Discussing Fees And The Value Of Financial Planning (https://kitces.com/blog/fees-value-financial-advice-client-communication-cost-anchoring)
- Assess Total Costs and Hidden Fees
- 90 Warren Buffett Quotes on Investing, Business, and Life (https://sarwa.co/blog/warren-buffett-quotes)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Investment & Risk Management for high-income W-2 families at Bright Advisers.
Keep reading