

Overview
Withdrawing money from a custodial account is a thoughtful process designed to ensure that funds are used solely for the benefit of your child, particularly for important needs like education or healthcare expenses. Imagine if you could navigate this process with ease and confidence, knowing that every step you take is in the best interest of your family.
This article gently outlines the key steps in the withdrawal process. It begins with reviewing the account terms, which is essential for understanding your options. Next, consider the purpose of the withdrawal—what specific needs does your child have that this money can support? Gathering the necessary documentation is also crucial, as it helps to streamline the process.
It’s important to remember that aligning your withdrawals with the account’s intended purpose is vital. This alignment not only supports your child’s needs but also helps to avoid any potential legal issues down the road.
We’re here for you, guiding you through each step of this journey. Together, we can ensure that your financial decisions reflect your family’s values and priorities. By approaching this process thoughtfully, you can provide the support your child deserves.
Key Highlights:
- Custodial accounts are established by adults for the benefit of minors, promoting savings and economic literacy.
- Funds in custodial accounts can be used for essential child-related expenses like education and healthcare.
- Withdrawals should primarily benefit the minor and align with the account’s intended purpose to avoid legal issues.
- The withdrawal process involves reviewing terms, determining the purpose, gathering documentation, and submitting requests to financial institutions.
- Common withdrawal issues include denied requests, documentation problems, and processing delays, which can be resolved through clear communication with the institution.
- Tax implications may arise from withdrawals, and parents should consult experts to navigate these effectively.
- Understanding the rules and regulations surrounding custodial accounts is crucial for informed financial decisions.
Introduction
Navigating the world of custodial accounts can be a pivotal step for parents seeking to secure their children’s financial futures. Imagine if you could provide a means to save and invest for your child’s benefit while also fostering essential financial literacy. These specialized accounts not only serve that purpose but are becoming increasingly popular among families.
It’s important to understand the intricacies of custodial accounts—including their purpose, withdrawal rules, and effective management strategies. By doing so, families can optimize their financial planning.
As you embark on this journey, remember that custodial accounts can unlock the potential to support education and other critical needs. Together, we can instill vital money management skills in your children, ensuring a brighter future for them.
Understand Custodial Accounts and Their Purpose
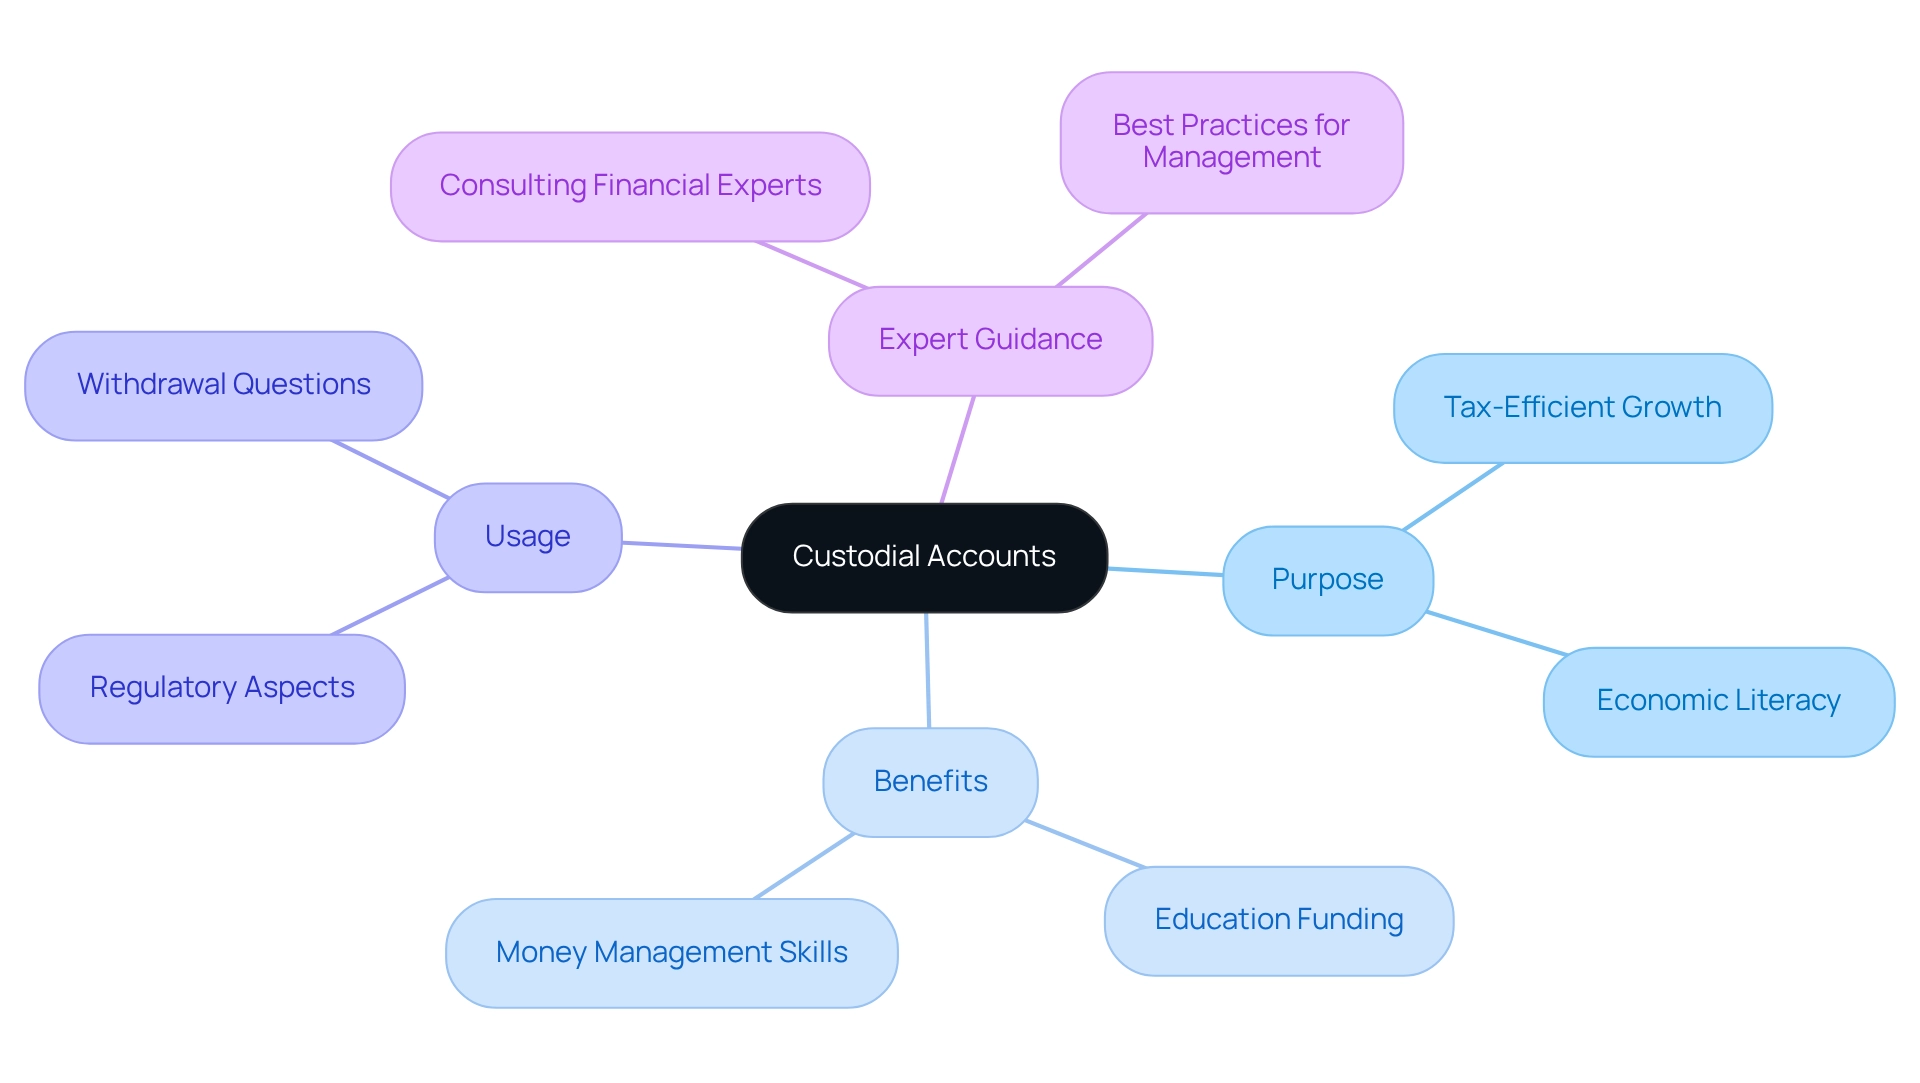
Custodial arrangements are valuable financial tools established by a caring adult, known as the custodian, for the benefit of a minor. These funds provide a means for parents or guardians to save and invest money for their children, fostering tax-efficient growth and promoting economic literacy. The primary goal of guardianship funds is to manage assets until the child reaches the age of majority, typically ranging from 18 to 21 years, depending on state regulations.
Imagine being able to support your child’s journey through education and life. Resources within guardianship funds can be utilized for various essential expenses that directly benefit the child, such as education, healthcare, and other vital needs. Recent statistics indicate that a significant number of parents are leveraging guardianship funds to help their children achieve educational aspirations, which raises the question: can you withdraw money from a custodial account? This highlights their growing popularity as a strategic planning resource and emphasizes the importance of understanding the rules and regulations surrounding custodial accounts to make informed decisions about withdrawals and appropriate use of resources. For instance, under the previous federal tax system, children under 19 could earn up to $1,050 in unearned income without facing taxes, making guardianship funds an attractive option for tax-efficient savings.
Real-world stories illustrate the positive impact of guardianship funds on education. Many families have successfully utilized these funds to cover tuition and other educational expenses, ensuring their children have access to quality learning opportunities. Furthermore, expert insights reveal that guardianship funds not only serve as a savings mechanism but also play a significant role in teaching children about money management and financial responsibility.
As custodial arrangements continue to gain traction among families, it is essential for parents to stay informed about their benefits and the best practices for effectively managing these funds. By seeking guidance from financial experts, like those at Bright Advisers, families can tailor their strategies for managed funds, incorporating innovative investment methods and minimizing fees to enhance their financial outcomes. Together, we can navigate this journey, empowering parents to make the best decisions for their children’s future.
Review Withdrawal Rules and Regulations
Navigating the process of removing funds from a managed fund can feel daunting, but we’re here to guide you through it step by step.
-
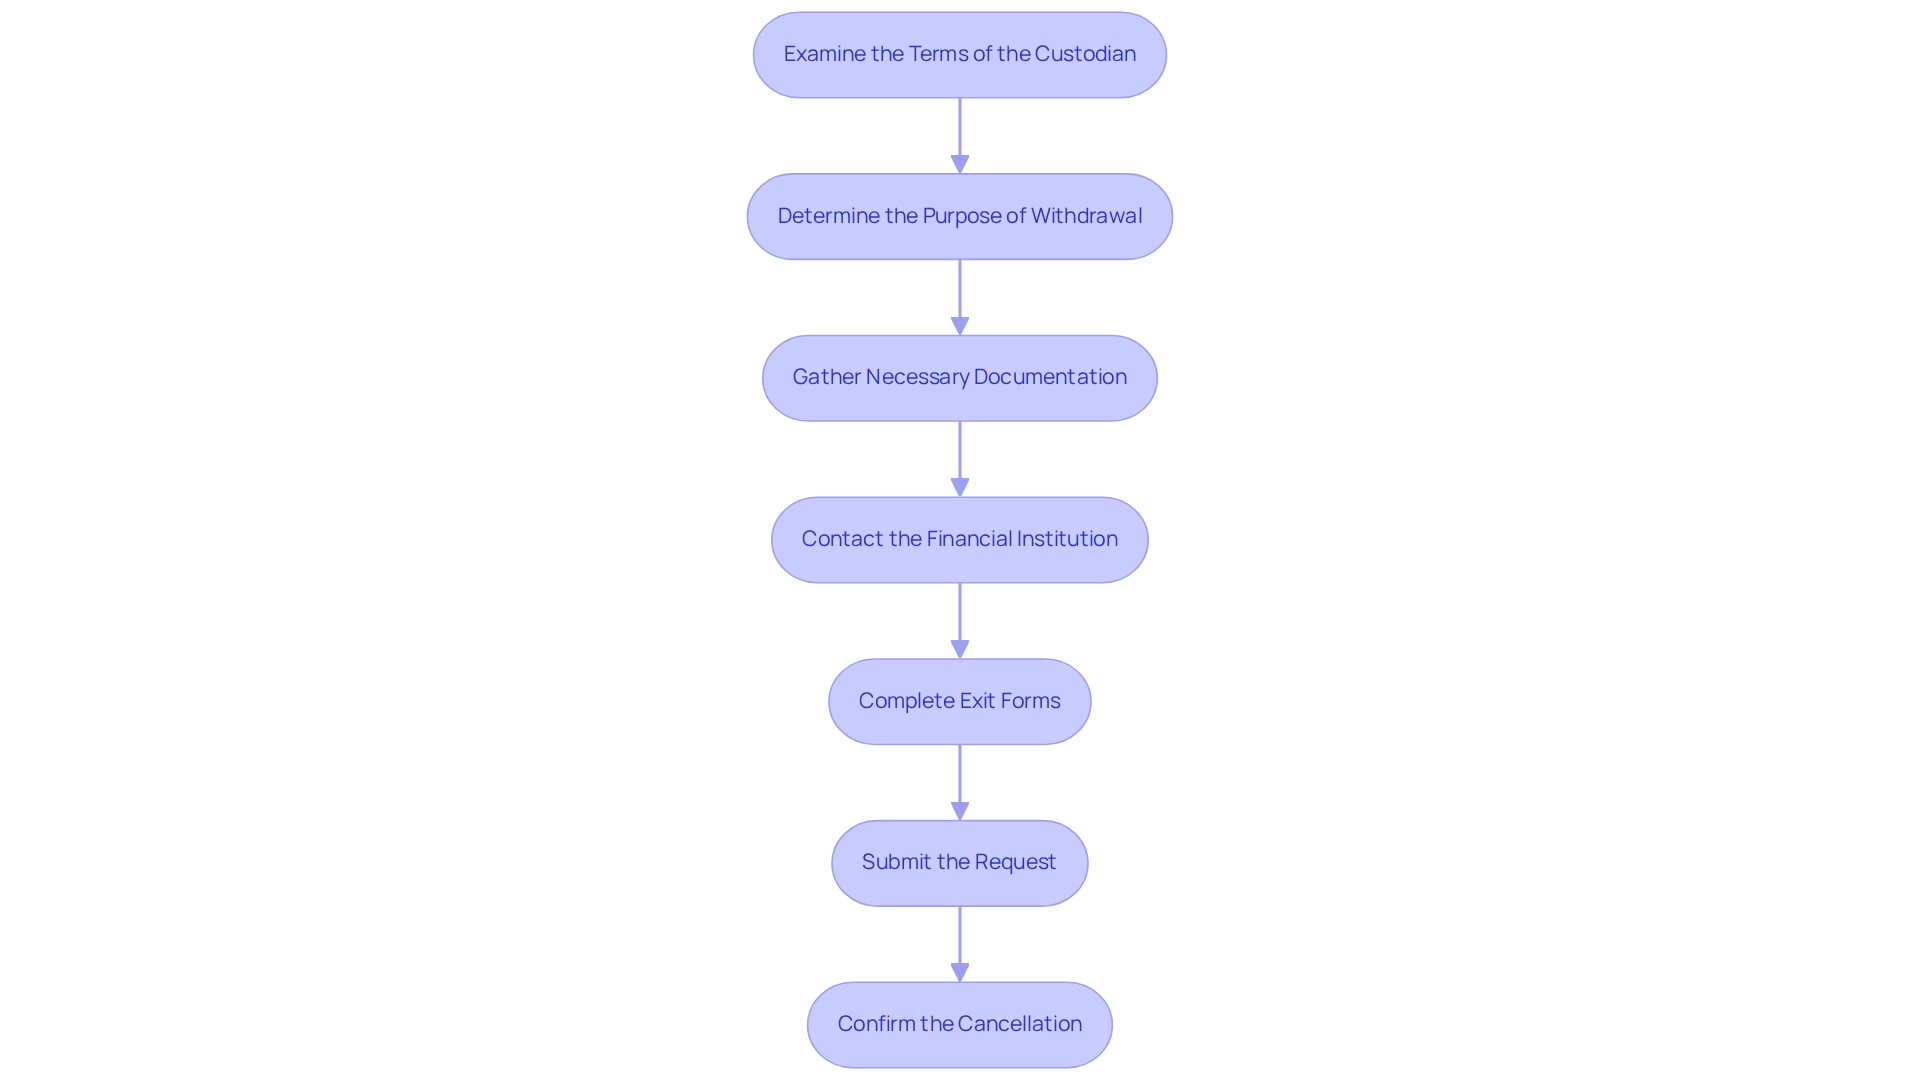
Examine the Terms of the Custodian: Before you begin, take a moment to review the conditions of the managed fund. Understanding any restrictions or requirements is essential, especially in light of Bright Advisers’ commitment to keeping fund fees minimal. This approach helps make wealth management accessible for families like yours.
-
Determine the Purpose of Withdrawal: It’s important to clarify why you need to withdraw funds. Ideally, these funds should support the needs of your minor, such as educational expenses, aligning with Bright Advisers’ mission to empower young families through tailored wealth management solutions.
-
Gather Necessary Documentation: Collect the required documents, including identification for both the custodian and the minor, along with any receipts or proof of expenses if relevant.
-
Contact the Financial Institution: Reach out to the bank or financial institution managing the custodial account. You may be wondering, can you withdraw money from a custodial account, and often this can be done via phone or online banking, making it convenient for you.
-
Complete Exit Forms: Take your time to fill out any exit forms provided by the institution. Ensuring all information is accurate will help avoid unnecessary delays.
-
Submit the Request: Once everything is in order, submit your request to withdraw along with the necessary documentation. Remember to keep a copy for your records.
-
Confirm the Cancellation: After submitting, it’s important to verify with the institution that your cancellation has been processed. Keep an eye on the records to ensure the funds are moved as expected, and remember that if you are wondering, can you withdraw money from a custodial account, the time it takes to handle such withdrawals can vary by institution, typically ranging from several days to a few weeks. It’s also worth noting that custodial arrangements may not be allowed in certain regions, such as South Carolina and Guam. Once the beneficiary reaches adulthood, they will need to submit a tax return for any earnings from the fund. Understanding these details can help ensure a smooth exit process, allowing your family to make informed financial choices together.
Initiate the Withdrawal Process
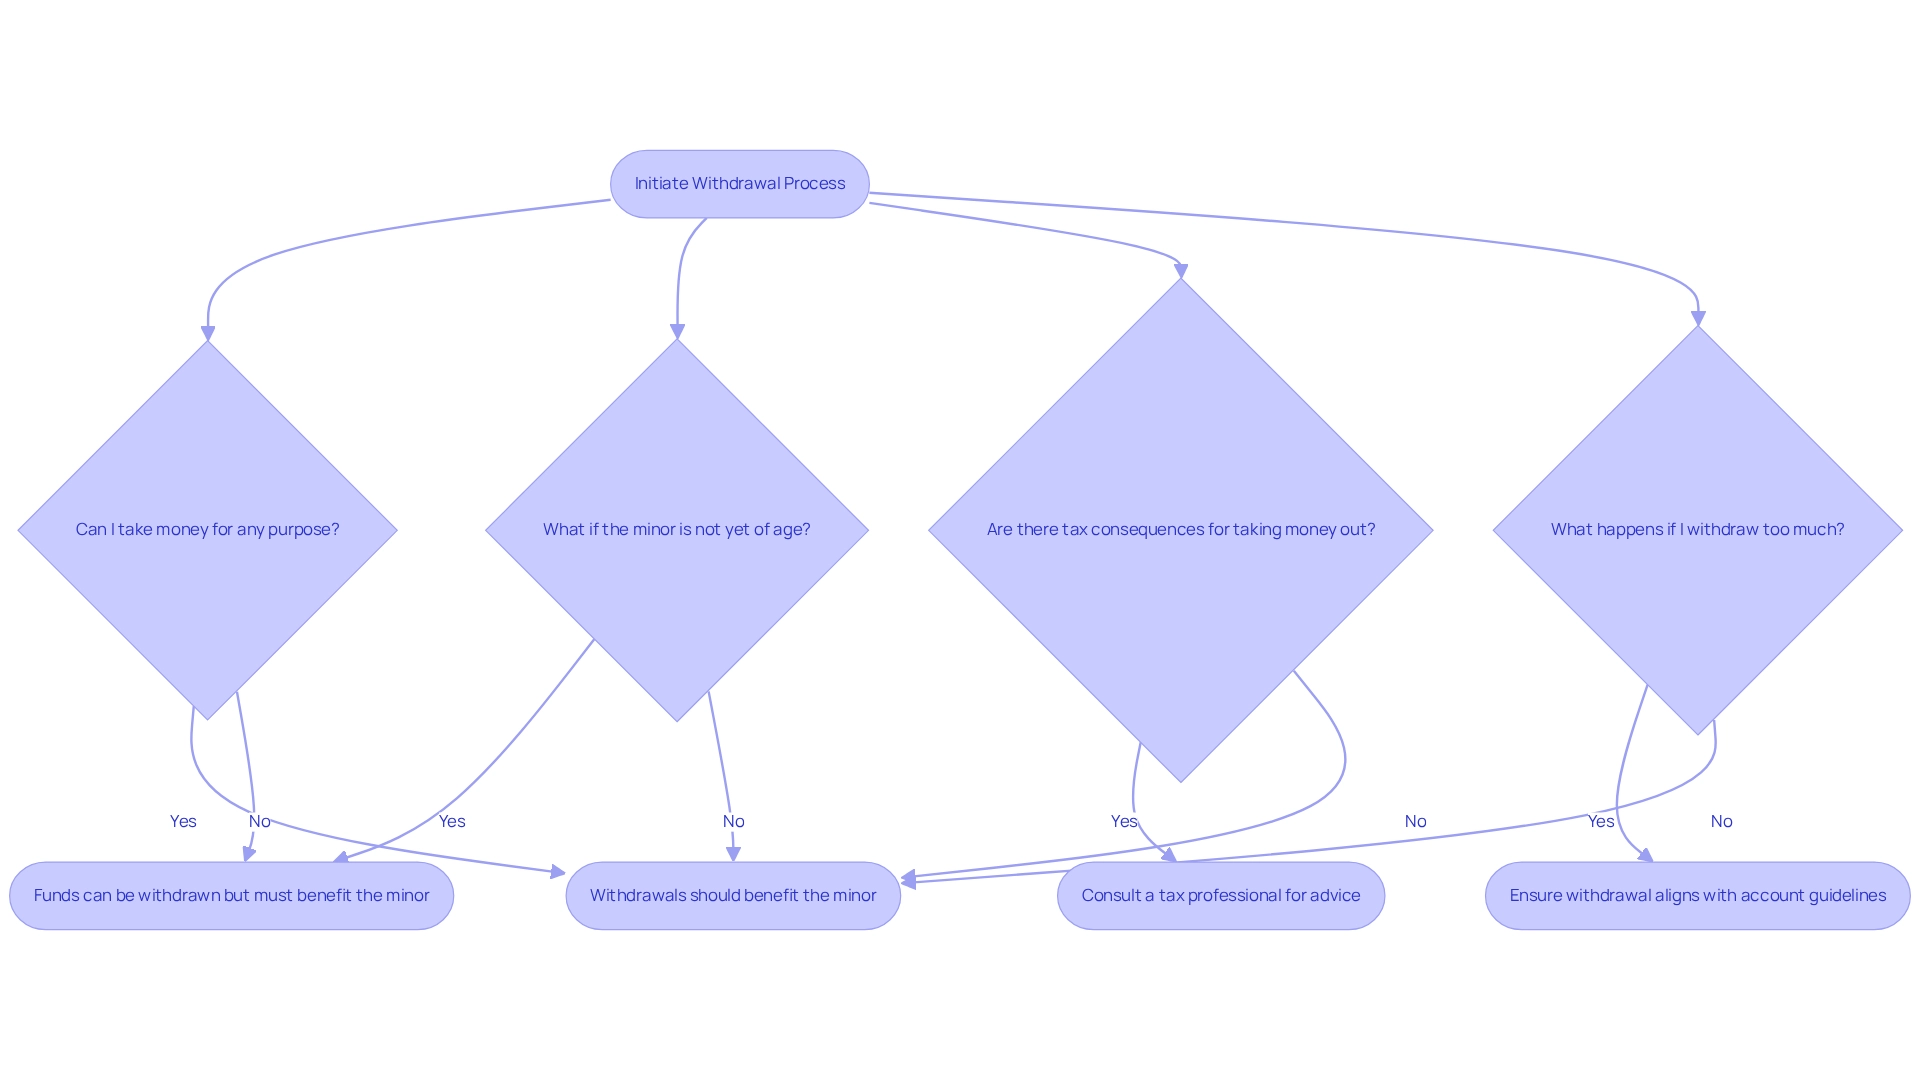
Here are some common questions and concerns about accessing funds from custodial holdings:
- Can I take money for any purpose?
Withdrawals should be made with the minor’s best interests in mind. Using these funds for personal expenses unrelated to the child’s needs may not align with the fund’s purpose, and could lead to legal complications. - What if the minor is not yet of age?
You can still withdraw funds, but they must benefit the minor. Once they reach adulthood, they will have complete control over the funds, allowing them to make independent financial decisions. - Are there tax consequences for taking money out?
Generally, withdrawals from custodial accounts are not taxable for the custodian; however, any earnings could be subject to taxes. For instance, while distributions for qualified education expenses from a Coverdell ESA are tax-exempt, other withdrawals might incur a 10 percent tax penalty along with income taxes on gains. It’s wise to consult a tax professional for personalized advice. - What happens if I withdraw too much?
Withdrawing more than allowed can result in penalties or restrictions on the account. It’s essential to ensure that the amount withdrawn aligns with its intended purpose and follows account guidelines, especially when considering if you can withdraw money from a custodial account, as some may limit withdrawals to one per month depending on the type or institution.
As your child grows, having conversations about financial literacy is vital. Teaching them about budgeting and saving can help them understand the value of money and responsible spending, preparing them for future financial responsibilities. A case study shows that informed decision-making regarding custodial funds, including choosing between UGMA and UTMA options, can lead to better financial outcomes for children, enhancing their ability to save.
Troubleshoot Common Withdrawal Issues
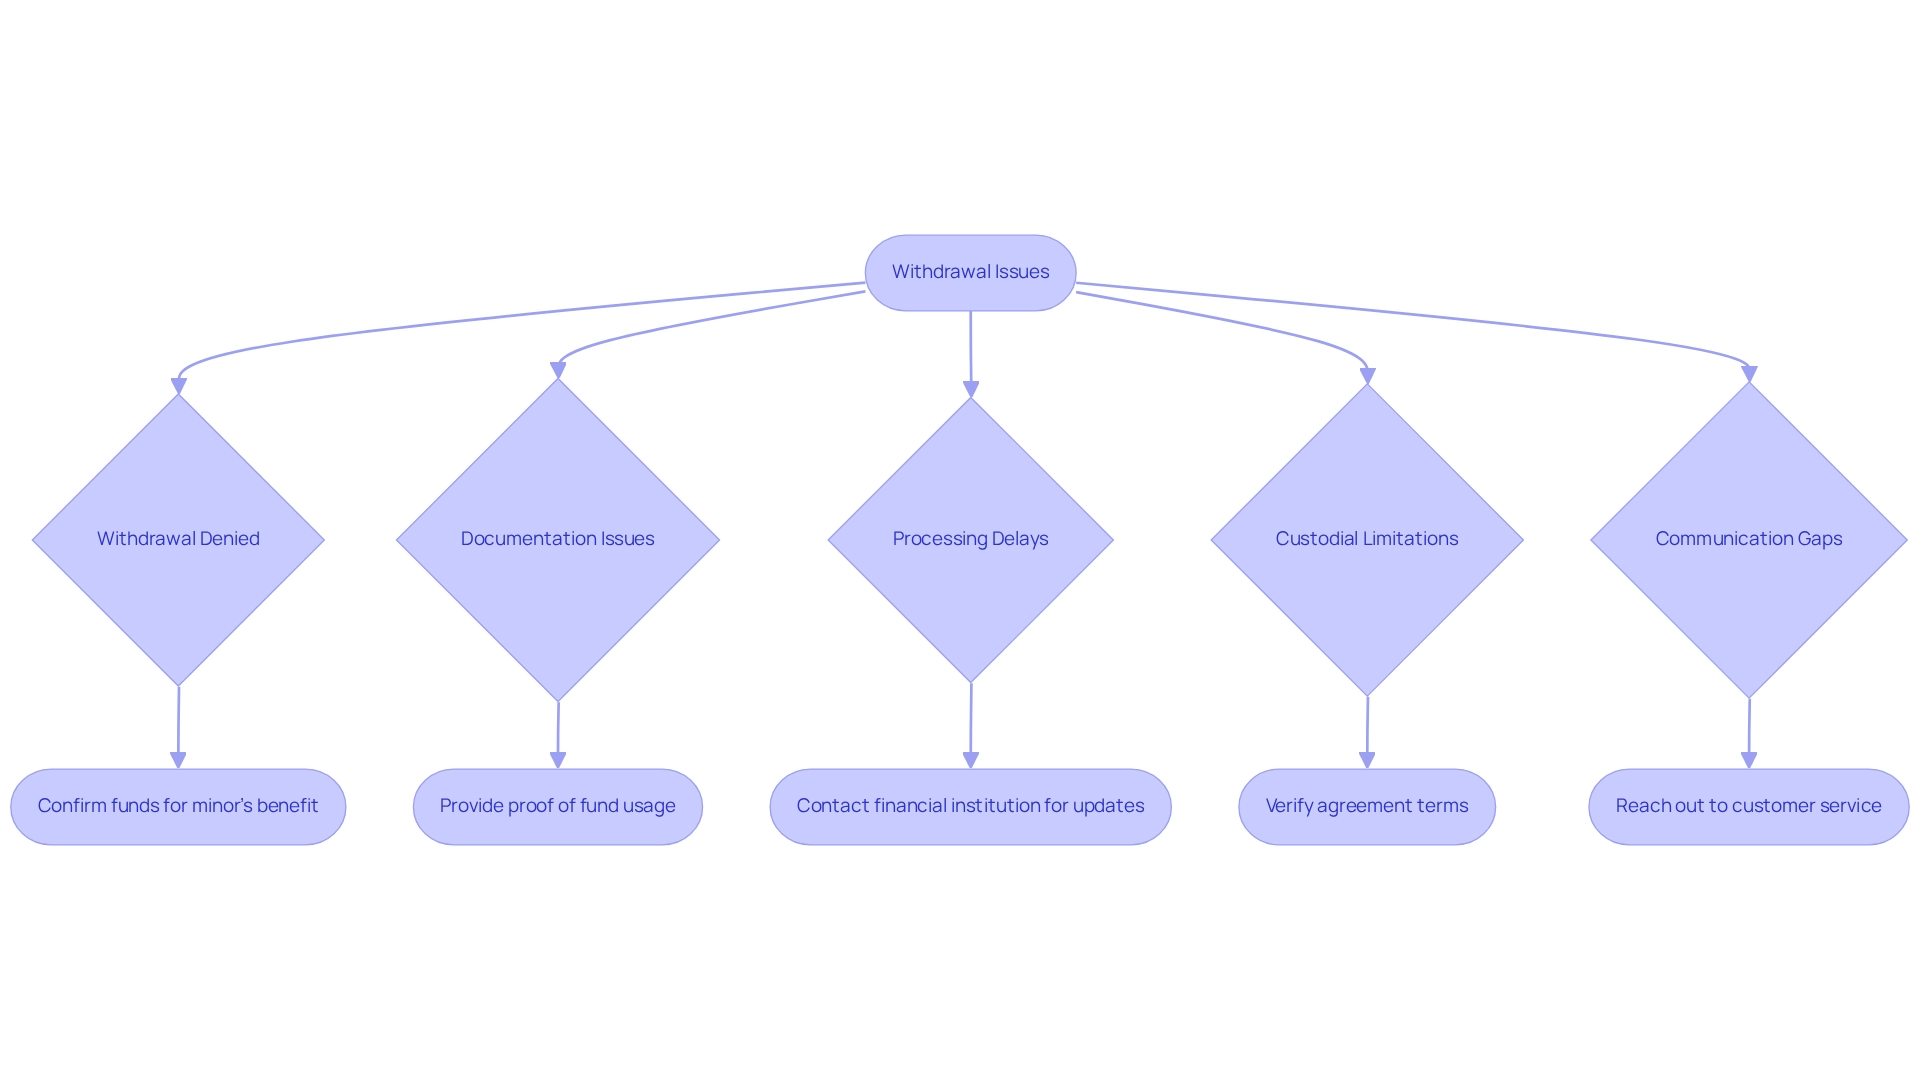
Can you withdraw money from a custodial account? It can be a straightforward process, yet various issues may arise. Here are some common challenges and effective troubleshooting strategies to help you navigate this journey:
- Withdrawal Denied: If your withdrawal request is denied, it’s crucial to confirm that the funds are being requested for the minor’s benefit. Take a moment to examine the organization’s policies to ensure adherence to their requirements.
- Documentation Issues: Should the institution request additional documentation, be prepared to provide proof of how the funds will be utilized for your child’s benefit. This may include receipts or invoices for educational or medical expenses that truly matter.
- Processing Delays: In the event of processing delays, don’t hesitate to reach out to the financial institution for updates. They can provide insights into any issues affecting the timeline, helping you feel more in control.
- Custodial Limitations: Some custodial funds enforce limitations on withdrawals until the child reaches a designated age. It’s important to verify the agreement’s terms to understand any limitations that may apply, ensuring you’re fully informed.
- Communication Gaps: If you have uncertainties about the withdrawal process, remember that customer service is there to help. Clear communication can often resolve misunderstandings swiftly, providing peace of mind.
In a relevant case study titled “Empowering Economic Freedom for Young Families – Emily and Mark’s Journey with Bright Advisers,” we see how customized monetary planning can alleviate concerns surrounding custodial accounts. Emily and Mark faced difficulties in managing their resources while striving for economic independence. By collaborating with Bright Advisers, they obtained tailored strategies that not only enhanced their economic well-being but also offered them the flexibility to make informed choices regarding their children’s financial futures.
Additionally, statistics indicate that if interest and dividend income is less than $13,500 in 2025, parents can include that income on their tax return. This information may affect withdrawal strategies, as understanding tax implications can help families make informed decisions. By recognizing these common issues and solutions, families can better understand if they can withdraw money from a custodial account, navigating withdrawals more effectively and ensuring they are maximizing their financial potential through informed planning and support. Together, we can navigate this journey with confidence.
Conclusion
Custodial accounts offer a wonderful opportunity for parents to secure their children’s financial futures while nurturing essential financial literacy. By understanding the purpose of these accounts, families can effectively save and invest for their children’s needs, especially in education and healthcare. Managing these accounts until the child reaches adulthood enables a structured approach to wealth accumulation and responsible money management.
Navigating the withdrawal rules and regulations associated with custodial accounts is crucial for ensuring that funds are used appropriately for the benefit of the minor. By following the necessary steps and being aware of potential challenges, parents can facilitate a smooth withdrawal process. This empowers families to make informed financial decisions and reinforces the importance of using these funds wisely.
Ultimately, custodial accounts are more than just a financial tool; they lay the groundwork for teaching children about money management. As families embrace the benefits of these accounts, they invest not only in their children’s immediate needs but also equip them with the skills to navigate their financial futures. By staying informed and seeking professional guidance, parents can maximize the potential of custodial accounts, paving the way for a brighter financial outlook for their children. Together, we can navigate this journey toward a secure future.
Frequently Asked Questions
What are custodial accounts and their purpose?
Custodial accounts are financial instruments established by a custodian for the benefit of a minor, allowing parents or guardians to save and invest for their children while promoting tax-efficient growth and financial literacy.
Who manages the assets in a custodial account?
The assets in a custodial account are managed by a custodian, typically a parent or guardian, until the minor reaches adulthood, which is usually between 18 to 21 years, depending on state regulations.
What expenses can custodial funds be used for?
Custodial funds can be allocated for various essential expenses, including education, healthcare, and other vital requirements for the child.
Can you withdraw money from a custodial account?
Yes, parents can withdraw money from a custodial account, but it is important to understand the appropriate uses of the funds and the regulations surrounding withdrawals.
What are the tax benefits of custodial accounts?
Under the previous federal tax framework, minors under 19 could earn up to $1,050 in unearned income without incurring taxes, making custodial accounts an attractive option for tax-efficient savings.
How do custodial accounts help with children’s education?
Many families use custodial funds to cover tuition and other educational expenses, ensuring their children have access to quality learning opportunities.
Do custodial accounts help teach children about money management?
Yes, custodial accounts not only serve as a savings method but also play a vital role in teaching children about money management and financial responsibility.
How can parents receive guidance on managing custodial accounts?
Parents can consult with experienced financial advisors, such as those at Bright Advisers, for tailored wealth management solutions and guidance on custodial funds.
List of Sources
- Understand Custodial Accounts and Their Purpose
- Are Custodial Accounts a Good Option for Parents Saving for College? (https://savingforcollege.com/article/are-custodial-accounts-a-good-option-for-parents-saving-for-college)
- Child Support Statistics in the United States (https://aecf.org/blog/child-support-statistics)
- Child Custody By The Numbers: Stats Every Parent Should Know (https://modernfamilylaw.com/resources/child-custody-by-the-numbers-stats-every-parent-should-know)
- 35 Quotes for Financial Advisors on a Tough Day | Don Connelly & Associates (https://donconnelly.com/35-quotes-for-financial-advisors)
- Review Withdrawal Rules and Regulations
- pnc.com (https://pnc.com/en/personal-banking/investments-and-retirement/education-accounts/custodial-accounts-utma.html)
- Permitted withdrawals from custodial account: Overview, definition, and example (https://cobrief.app/resources/legal-glossary/permitted-withdrawals-from-custodial-account-overview-definition-and-example)
- Everything You Need to Know About UTMA Account Rules (https://getearlybird.io/blog/utma-account-rules)
- fastercapital.com (https://fastercapital.com/content/Custodial-Account-Withdrawals–Rules-and-Best-Practices.html)
- Custodial Account | Plan For A Child’s Future | Fidelity Investments (https://fidelity.com/open-account/custodial-account)
- Initiate the Withdrawal Process
- Custodial Accounts: What You Should Know | Bankrate (https://bankrate.com/investing/custodial-account)
- fastercapital.com (https://fastercapital.com/content/Custodial-Account-Withdrawals–Rules-and-Best-Practices.html)
- Everything You Need to Know About UTMA Account Rules (https://getearlybird.io/blog/utma-account-rules)
- 14 Quotes From Our Favorite Money Saving Experts (https://chime.com/blog/quotes-from-money-saving-experts)
- Troubleshoot Common Withdrawal Issues
- UGMA & UTMA accounts | Tips for custodial accounts | Fidelity (https://fidelity.com/learning-center/personal-finance/custodial-account-for-kids)
- 35 Quotes for Financial Advisors on a Tough Day | Don Connelly & Associates (https://donconnelly.com/35-quotes-for-financial-advisors)
- 77 Financial Advisor Quotes to Send to Clients (https://billgoodmarketing.com/resources/financial-advisor-quotes)
- UTMA Accounts Explained: Rules, Custodial Brokerages and More (https://kiplinger.com/personal-finance/603545/hey-parents-caution-is-critical-with-utma-custodial-accounts)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Age Five Wealth Education for high-income W-2 families at Bright Advisers.
Keep reading