

Overview
Effective time horizon investing for families means categorizing investments into short, medium, and long-term strategies that align with your specific financial goals. Imagine if you could create a secure future for your loved ones. Regularly reviewing your goals can make a significant difference. Remember, diversification is key, and consulting with financial advisors can provide the support you need. Families with written plans are significantly more likely to save adequately for retirement and achieve their financial objectives. Together, we can navigate this journey and ensure your family’s financial well-being.
Key Highlights:
- Investment time horizon refers to the duration before accessing invested funds, categorised as short-term (less than 3 years), medium-term (3 to 10 years), and long-term (over 10 years).
- Short-term strategies prioritise capital preservation, while medium-term investments may include a mix of stocks and bonds for significant family goals.
- Long-term investments often involve higher equity allocations, allowing recovery from market fluctuations and benefiting from compounding growth.
- Statistics show a growing trend in families saving for education, with 16.8 million 529 college savings accounts in the U.S., averaging $30,295 per account.
- Regularly reviewing and adjusting financial goals is essential for successful time horizon investing, as households with written plans are more likely to save adequately for retirement.
- Diversification across asset types mitigates risk and enhances potential returns, while staying informed about market trends aids in making timely investment adjustments.
- Consulting with financial advisors can provide tailored guidance to align investment strategies with specific family goals.
Introduction
Understanding the nuances of time horizon investing is crucial for families like yours, who are striving to achieve their financial goals. Imagine how empowering it would feel to define exactly how long your investments will be held before you need access to those funds. By doing so, you can strategically align your assets with your unique objectives—whether it’s saving for your child’s education, planning that long-awaited family vacation, or preparing for a secure retirement.
However, many families grapple with the challenge of matching their investment strategies to their evolving needs and risk tolerances. It’s important to understand that you’re not alone in this journey. How can families effectively navigate this complex landscape to ensure their financial future remains secure? Together, we can explore the options available to you, helping you make informed decisions that align with your family’s values and aspirations.
Define Investment Time Horizon
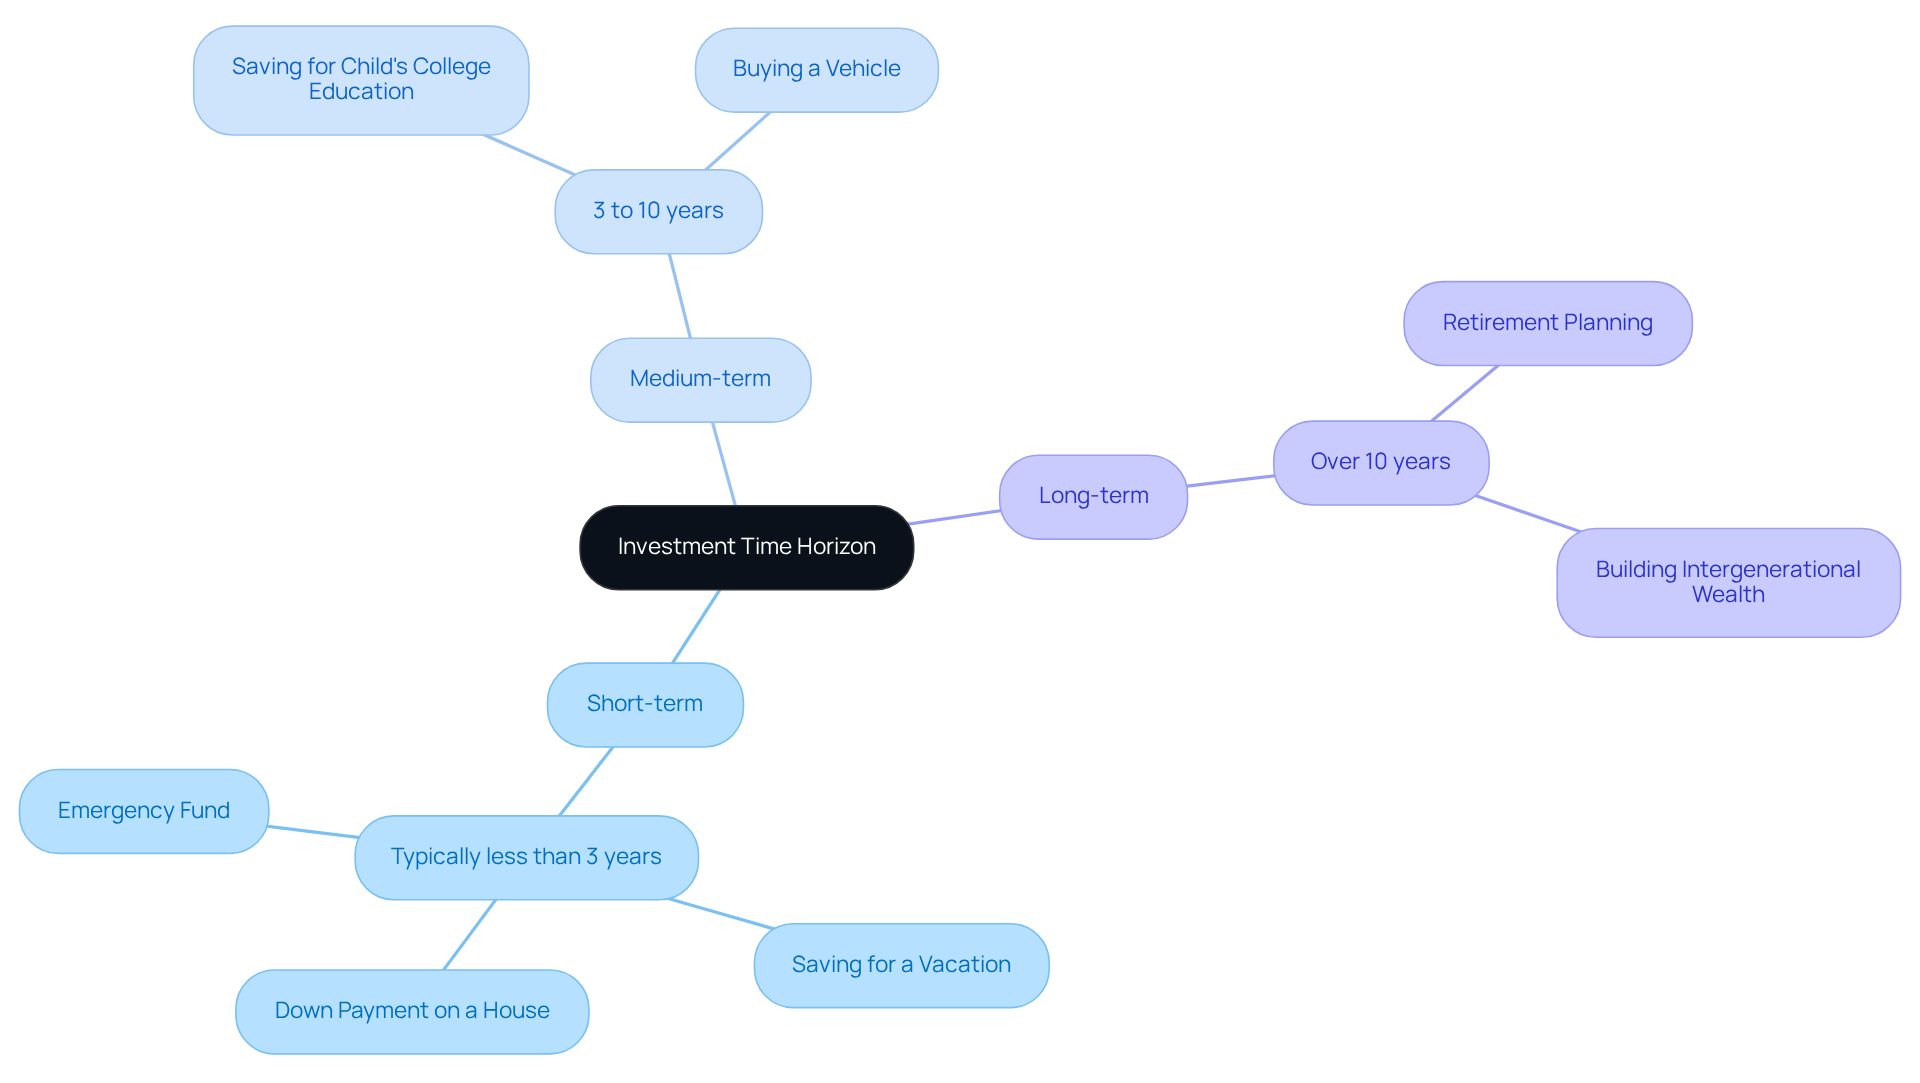
Understanding time horizon investing for assets is essential for your family’s financial journey. It refers to how long you plan to keep an investment before you need to access those funds. This concept is vital in determining which types of assets align with your family’s financial goals, particularly in the context of time horizon investing. Investment time horizon investing can be categorized as:
- Short-term (typically less than three years)
- Medium-term (three to ten years)
- Long-term (over ten years)
Imagine you are saving for your child’s college education in ten years. This goal will require a different strategy compared to someone planning a vacation next year. Recognizing these differences helps families make informed financial decisions through time horizon investing that match their needs and risk tolerance. It ensures you are prepared for upcoming expenses without jeopardizing your family’s financial stability.
It’s important to consistently review and adjust your financial strategies as your personal circumstances evolve. Not aligning your resources with the appropriate time horizon investing can expose your family to unnecessary risks. Remember, as Warren Buffett wisely stated, ‘Time is the friend of the wonderful company, the enemy of the mediocre.’ This highlights the importance of a thoughtful approach to your financial planning.
Together, we can navigate this journey, ensuring your family’s future is secure and bright.
Explore Types of Time Horizons: Short, Medium, and Long-Term
Understanding time horizon investing is crucial for families, as investments can be categorized into three main types:
- Short-term (less than 3 years)
- Medium-term (3 to 10 years)
- Long-term (10 years or more)
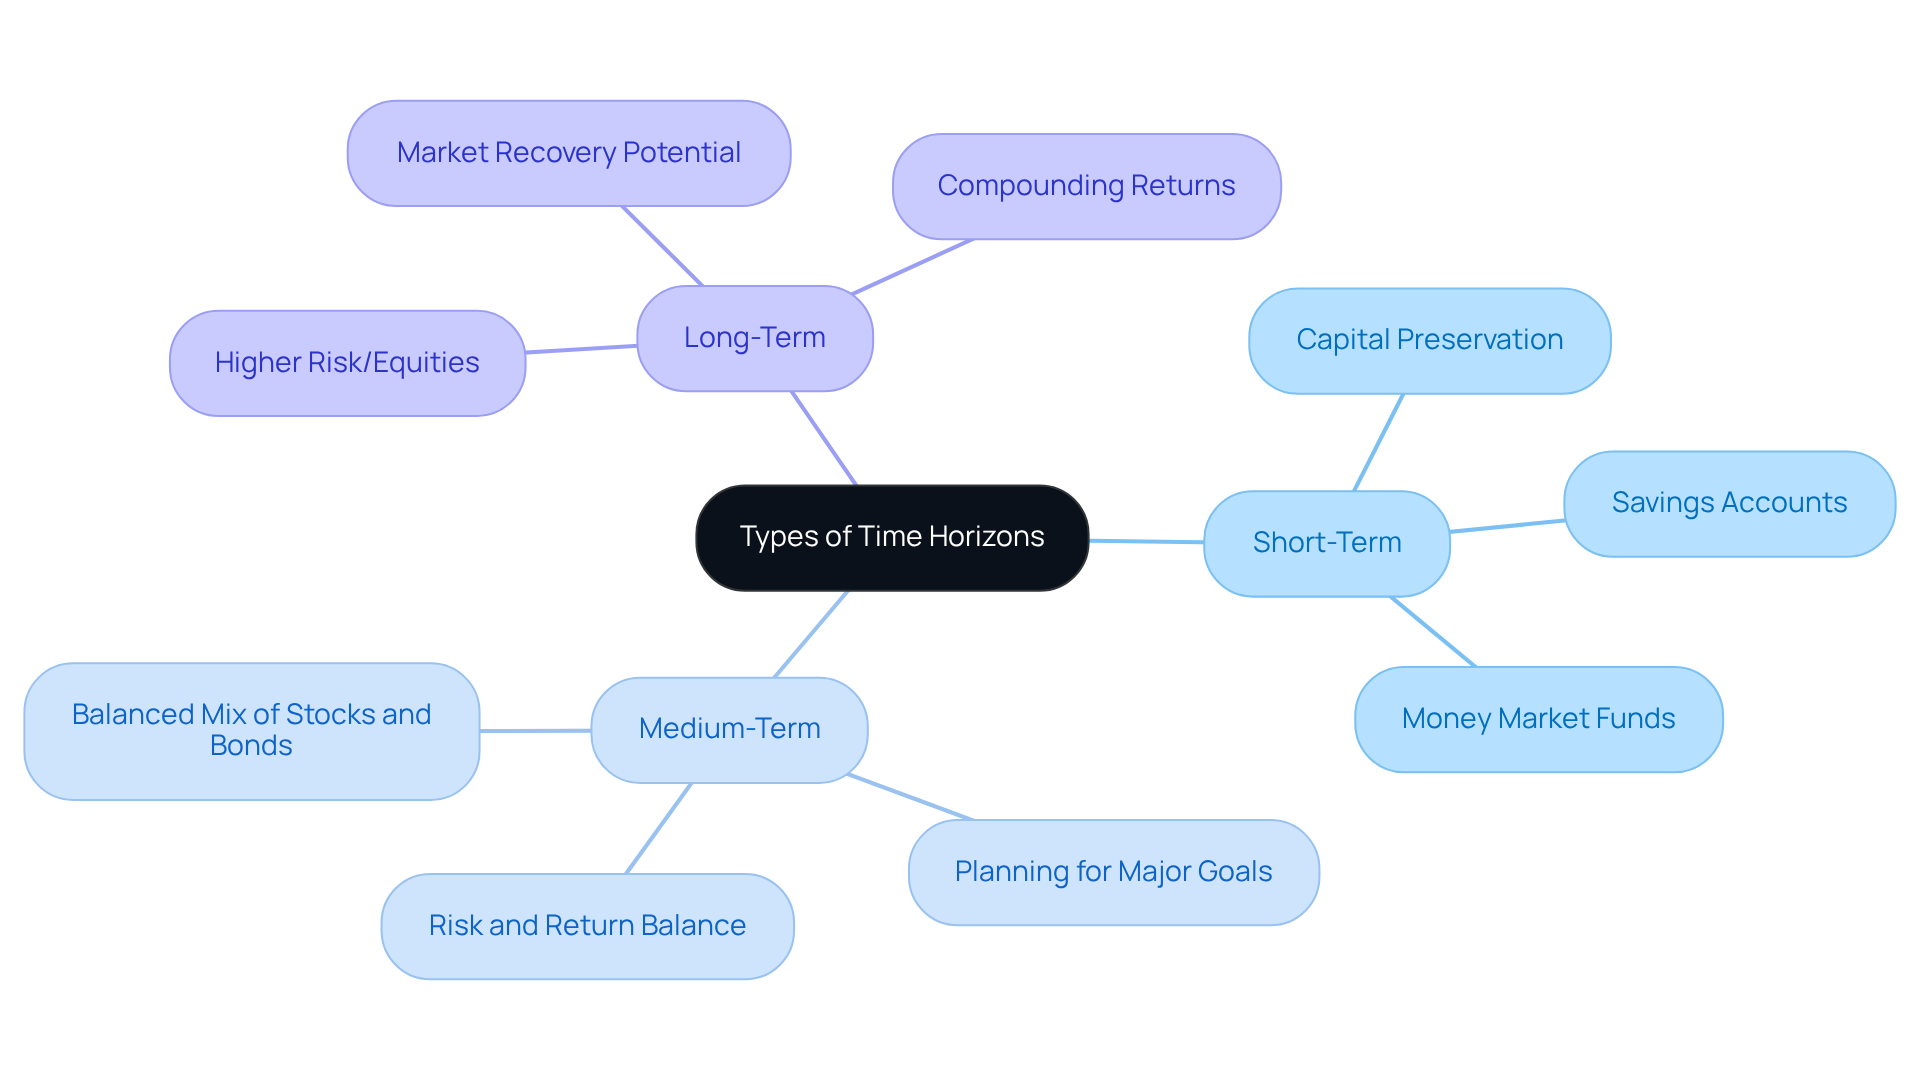
Short-term financial strategies focus on preserving your capital, often involving options like savings accounts or money market funds.
Imagine you’re planning for a significant family goal, such as purchasing a home or funding your child’s education. In these cases, medium-term assets typically include a balanced mix of stocks and bonds, helping you work towards those important milestones.
On the other hand, long-term investments can embrace a bit more risk. They often feature a higher allocation to equities, allowing your investments to recover from market fluctuations over time. This understanding of investment categories empowers families to align their financial choices with their broader objectives through time horizon investing, ultimately enhancing financial stability and growth potential.
Current trends indicate a growing focus on medium-term strategies. Families are looking to balance risk and return while preparing for significant life events. For instance, consider this: if you had invested $10,000 continuously in the market over the past 20 years, it would have grown to $63,636. This highlights the remarkable benefits of long-term investing.
However, it’s essential to be cautious of common pitfalls, such as attempting to time the market. This approach can lead to missed opportunities and potential losses. At Bright Advisers, we cultivate a nurturing atmosphere, assisting families in navigating these complexities and aligning their financial goals effectively. Remember, together, we can navigate this journey toward financial well-being.
Align Investment Strategies with Family Goals and Needs
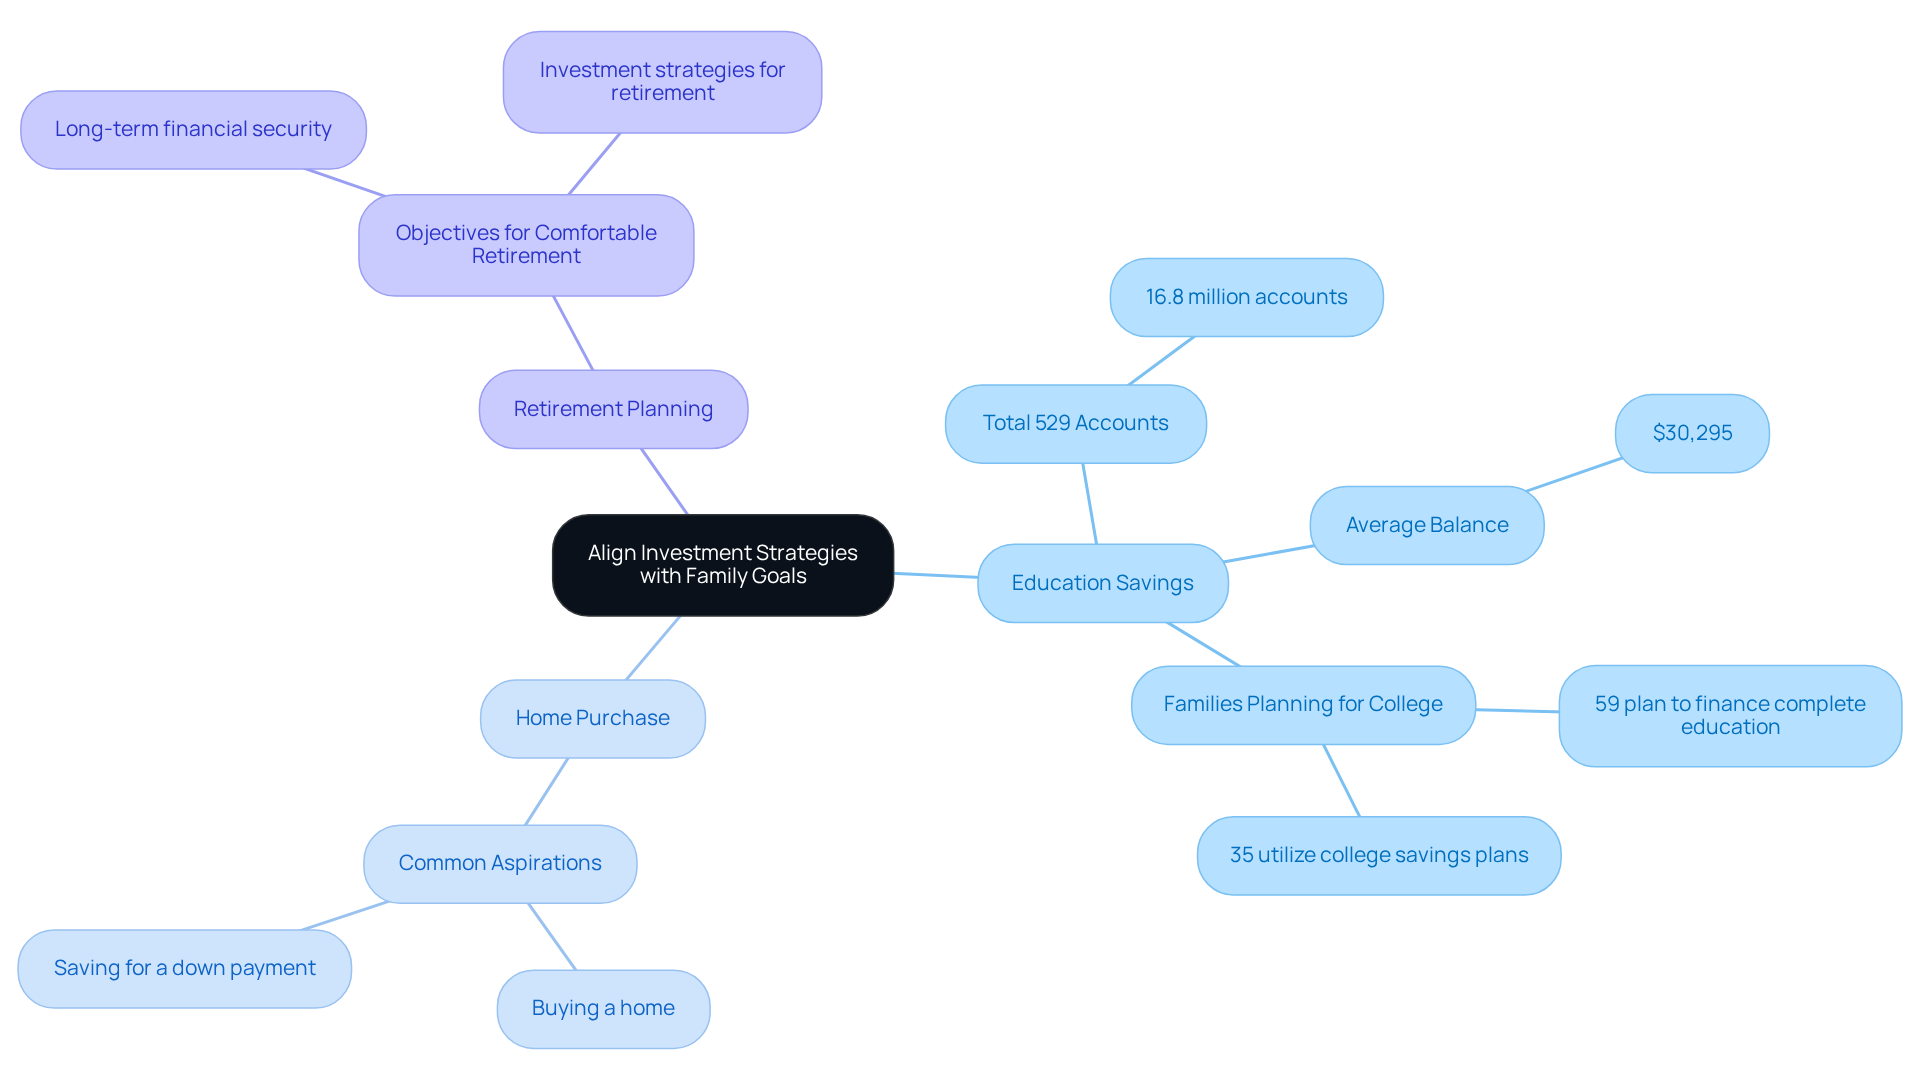
To effectively align your financial strategies with your family’s objectives, it’s essential to start with open discussions about your goals. Imagine gathering around the table to explore your aspirations—saving for your child’s education, purchasing a home, or planning for a comfortable retirement. Once you’ve established these objectives, you can tailor your investment strategies to meet them. For instance, if your family aims to save for a child’s college education in the next 10 years, you might consider a balanced portfolio that combines stocks for growth and bonds for stability. This thoughtful alignment not only enhances your chances of reaching financial goals but also fosters unity and purpose within your household.
Statistics show that as of June 2024, there were 16.8 million 529 college savings accounts in the U.S., with an average balance of $30,295 and a total of $508 billion saved across these plans. This highlights a growing trend of households proactively saving for education. Furthermore, a survey revealed that:
- 59% of families intended to finance their child’s complete college education before enrollment.
- 35% utilized college savings plans.
Yet, only 2.5% of households are currently using 529 college savings accounts, illustrating a significant gap between intention and action. Additionally, the typical amount saved in a 529 account for children aged 0-6 is $9,196, showcasing how families are planning for educational costs.
Financial advisors emphasize that setting household monetary objectives is a fundamental step in time horizon investing for successful outcomes. As Robert Kiyosaki wisely states, “It’s not how much money you make, but how much money you keep, how hard it works for you, and how many generations you keep it for.” By prioritizing these conversations, families can develop a plan that not only guides their financial choices but also strengthens their shared commitment to achieving common monetary goals. Together, we can navigate this journey, ensuring that your family’s financial future is bright and secure.
Implement Best Practices for Time Horizon Investing
To effectively implement best practices for time horizon investing, households can take heart in these supportive steps:
-
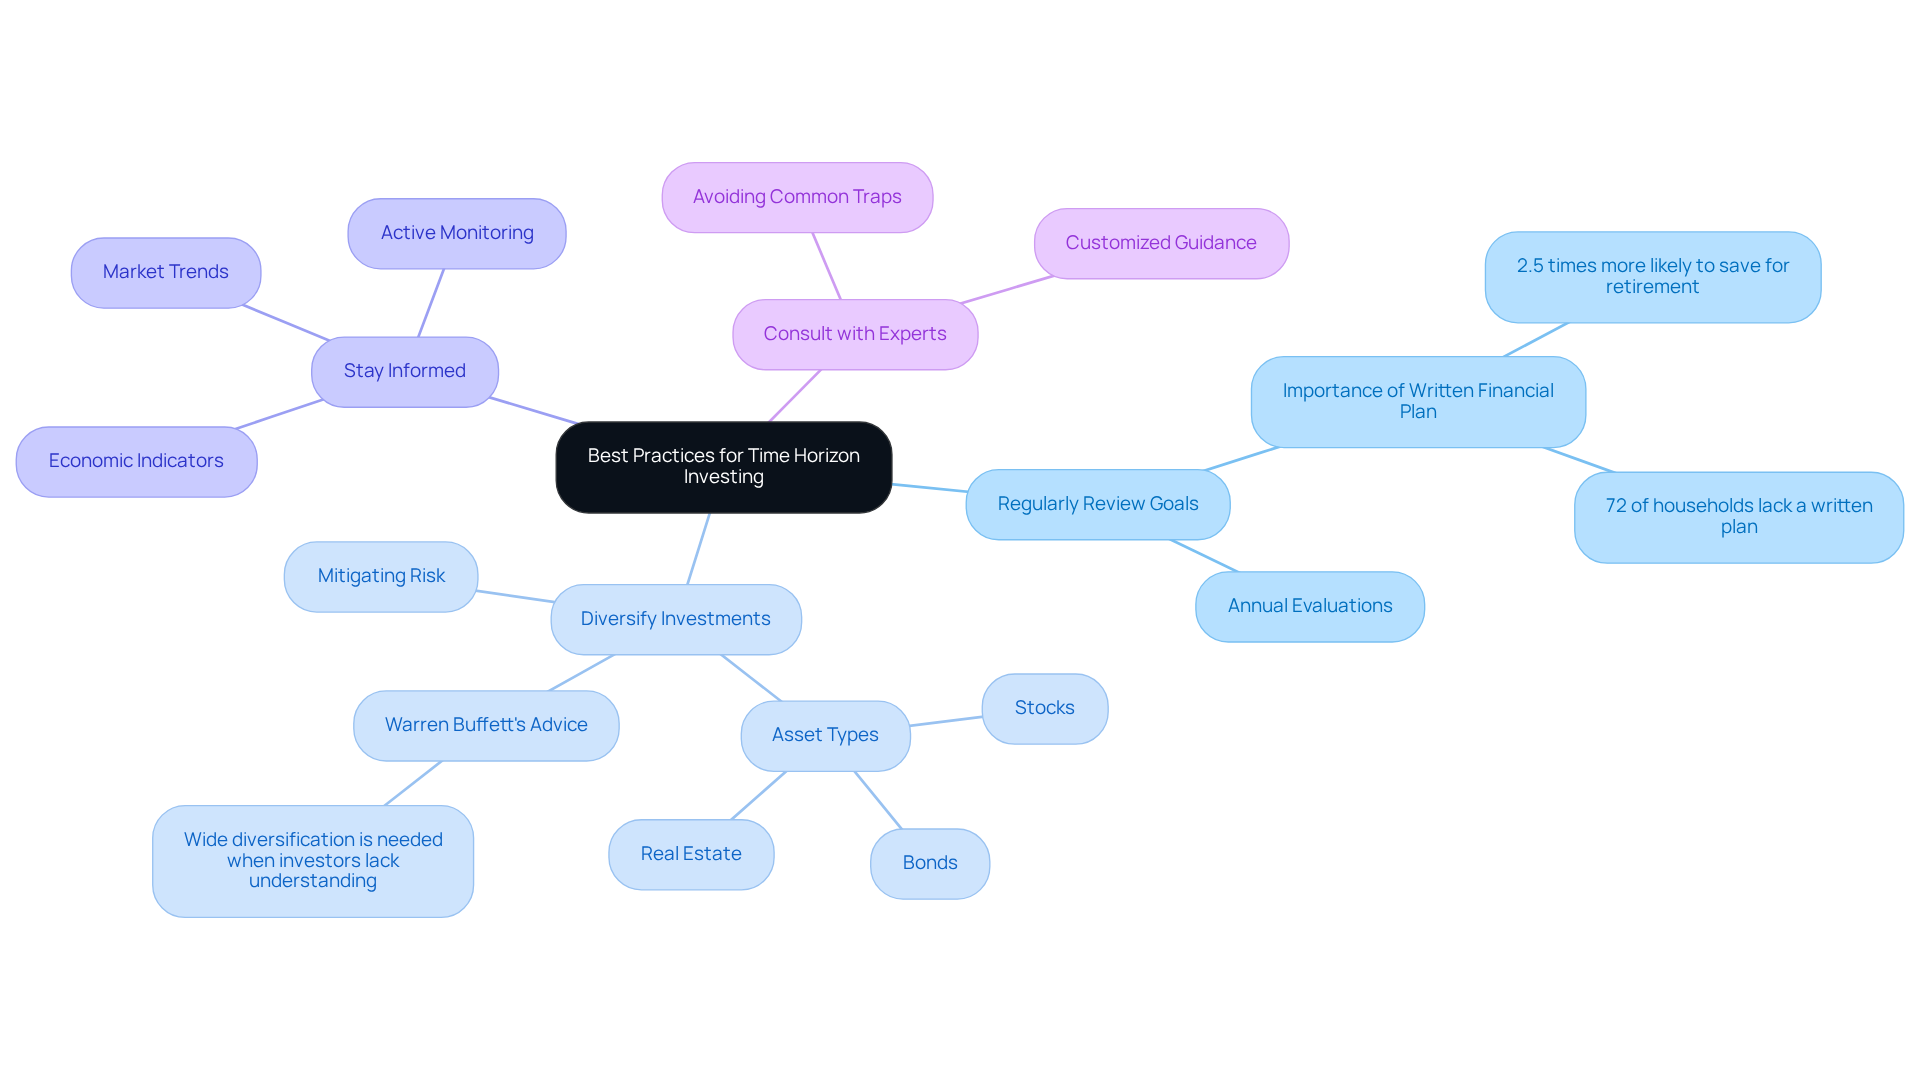
Regularly Review Goals: Financial goals are not static; they evolve over time. Imagine if you could adjust your plans as your family’s needs change. Regular evaluations—preferably at least annually—enable families to modify their financial strategies in response to shifting circumstances. Research indicates that households with a written financial plan are 2.5 times more likely to save adequately for retirement. With 72% of households lacking a written financial plan, this practice becomes even more critical.
-
Diversify Investments: Diversification is a key strategy for mitigating risk. It’s important to understand that families should diversify their holdings across different asset types, such as stocks, bonds, and real estate, to safeguard against market fluctuations. As Warren Buffett wisely notes, “wide diversification is only required when investors do not understand what they are doing.” This thoughtful approach not only enhances potential returns but also provides a buffer during economic downturns.
-
Stay Informed: Keeping abreast of market trends and economic indicators is crucial for making timely adjustments to asset portfolios. Picture this: families that actively monitor their investments are better positioned to capitalize on opportunities and navigate challenges.
-
Consult with experts: Collaborating with monetary advisors can provide households with customized guidance that corresponds with their particular time horizon investing and objectives. Expert advice can assist households in applying effective tactics and steering clear of typical traps.
By following these best practices, families can improve their investment results and ensure a more stable economic future. Additionally, it’s worth noting that 83% of people who set financial goals feel better about their finances after just one year, reinforcing the importance of regular reviews. Remember, together, we can navigate this journey toward financial well-being.
Conclusion
Understanding the intricacies of time horizon investing is essential for families aiming to secure their financial future. By categorizing investments into short, medium, and long-term horizons, families can make informed choices that align with their specific goals and risk tolerances. This strategic approach not only helps in preparing for significant life events but also reinforces financial stability and growth potential.
Imagine if you could regularly review your financial goals, diversify your investments, and stay informed about market trends. These strategies play a crucial role in navigating the complexities of investment planning while ensuring that family objectives are met. Moreover, the statistics presented highlight a growing awareness among families regarding the need for proactive financial planning, particularly in areas such as education savings.
Ultimately, the journey of time horizon investing is not just about numbers; it is about fostering unity and purpose within a family. By engaging in open discussions about financial aspirations and implementing best practices, families can cultivate a robust financial future. It’s important to take action now—evaluate your goals, diversify your investments, and seek guidance—to ensure that the financial dreams of today become the realities of tomorrow. Together, we can navigate this journey, ensuring that your family’s financial well-being is a priority.
Frequently Asked Questions
What is investment time horizon?
Investment time horizon refers to how long you plan to keep an investment before needing to access those funds. It is crucial for determining which types of assets align with your family’s financial goals.
What are the categories of investment time horizons?
Investment time horizons can be categorized as short-term (typically less than three years), medium-term (three to ten years), and long-term (over ten years).
How does investment time horizon affect financial strategies?
Different financial goals require different strategies based on the investment time horizon. For example, saving for a child’s college education in ten years involves a different approach than planning for a vacation next year.
Why is it important to review and adjust financial strategies?
It is important to consistently review and adjust financial strategies as personal circumstances evolve to ensure alignment with the appropriate investment time horizon and to avoid exposing the family to unnecessary risks.
What can happen if resources are not aligned with the appropriate time horizon?
Not aligning resources with the appropriate time horizon can expose a family to unnecessary risks, potentially jeopardizing their financial stability.
List of Sources
- Define Investment Time Horizon
- Investment Time Horizon: What It Is And Why It Matters | Bankrate (https://bankrate.com/investing/what-is-time-horizon)
- 102 Warren Buffett Quotes on Life, Success, & More (https://ruleoneinvesting.com/blog/how-to-invest/warren-buffett-quotes-on-investing-success)
- Investment Time Horizon | Definition, Types, & Impact on Goals (https://financestrategists.com/wealth-management/investment-risk/time-horizon)
- Importance of Time Horizons For Investing (https://sofi.com/learn/content/time-horizons-for-investing)
- Quotes on Time Horizon • Novel Investor (https://novelinvestor.com/quote-category/time-horizon)
- Explore Types of Time Horizons: Short, Medium, and Long-Term
- The Top 25 Investing Quotes of All Time (https://investopedia.com/financial-edge/0511/the-top-17-investing-quotes-of-all-time.aspx)
- Top 150 Financial Planning Quotes [2025] (https://digitaldefynd.com/IQ/financial-planning-quotes)
- 90 Warren Buffett Quotes on Investing, Business, and Life (https://sarwa.co/blog/warren-buffett-quotes)
- Wisdom of Great Investors – Quotes | Davis ETFs (https://davisetfs.com/investor_education/quotes)
- Align Investment Strategies with Family Goals and Needs
- Top 150 Financial Planning Quotes [2025] (https://digitaldefynd.com/IQ/financial-planning-quotes)
- 529 College Savings Plan Statistics | BestColleges (https://bestcolleges.com/research/529-college-savings-plan-statistics)
- College Saving Statistics [2025]: Average Savings & 529 Balance (https://educationdata.org/college-savings-statistics)
- 10 Great Investing Quotes to Consider (https://smartasset.com/investing/top-10-investing-quotes-of-all-time)
- 13 Important Personal Finance Stats You Need to Know – Savology (https://savology.com/13-financial-statistics-you-need-to-know)
- Implement Best Practices for Time Horizon Investing
- 13 Important Personal Finance Stats You Need to Know – Savology (https://savology.com/13-financial-statistics-you-need-to-know)
- The 200 best investing quotes of all time – Equito (https://equito.co/the-best-investing-quotes)
- 102 Warren Buffett Quotes on Life, Success, & More (https://ruleoneinvesting.com/blog/how-to-invest/warren-buffett-quotes-on-investing-success)
- The Importance of Regularly Reviewing and Adjusting Your Financial Goals (https://nasdaq.com/articles/importance-regularly-reviewing-and-adjusting-your-financial-goals)
- Key Financial Literacy Statistics in 2023 (https://annuity.org/financial-literacy/financial-literacy-statistics)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Investment & Risk Management for high-income W-2 families at Bright Advisers.
Keep reading