

Overview
Understanding the differences between 401(k) fees and IRA fees is crucial for young families planning for the future. 401(k) accounts typically offer higher contribution limits and may include employer matching, which can be a significant advantage. On the other hand, IRAs provide greater investment flexibility, though they come with lower contribution limits.
Imagine if you could make informed choices that align with your family’s financial goals. The distinct fee structures and benefits of each account type can play a pivotal role in shaping your long-term savings strategy. It’s important to understand these differences, as they can greatly influence your retirement planning.
By recognizing the unique features of 401(k)s and IRAs, you can better navigate your financial journey. Together, we can explore these options and find the best fit for your family’s needs. Remember, we’re here for you every step of the way.
Key Highlights:
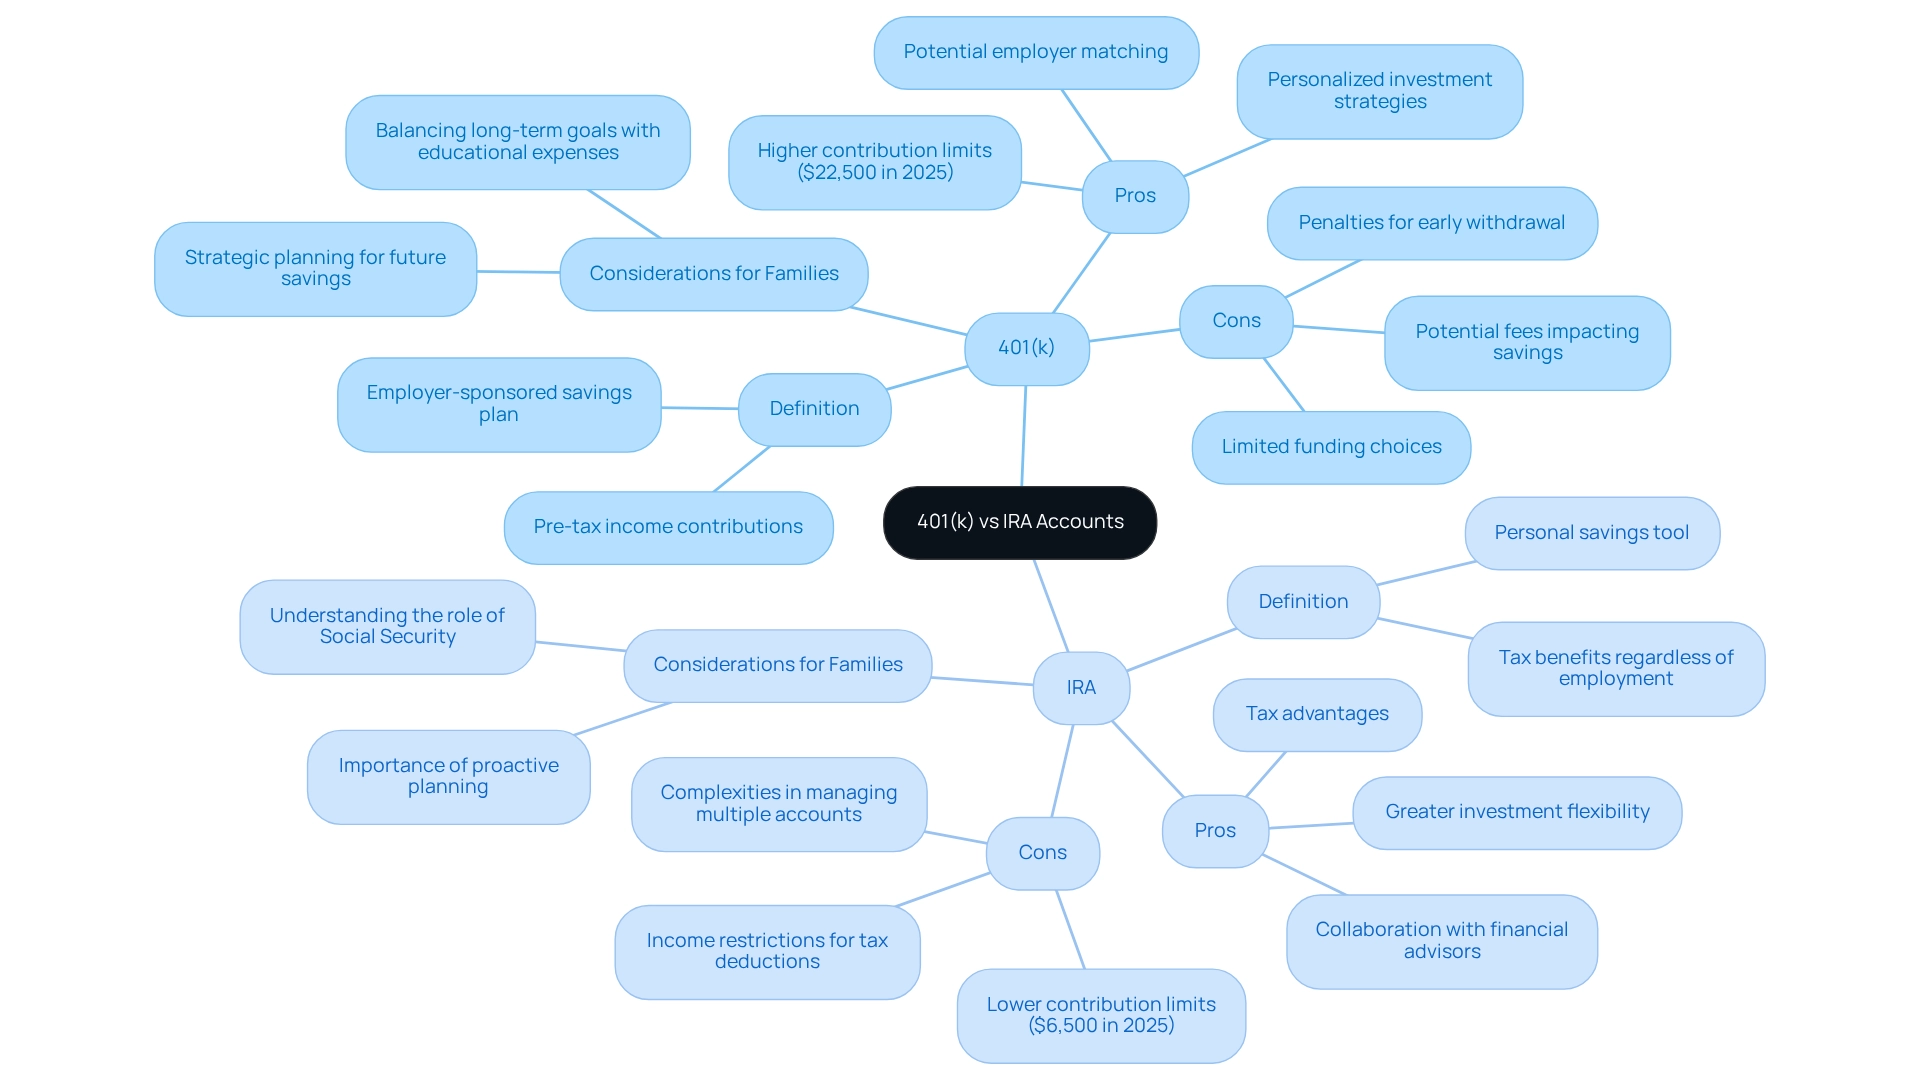
- A 401(k) is an employer-sponsored plan allowing pre-tax income contributions, often with employer matching, while an IRA is a personal savings tool providing tax benefits regardless of employment.
- In 2025, the contribution limit for a 401(k) is $22,500, compared to $6,500 for an IRA, making 401(k) accounts more suitable for higher contributions.
- Understanding the differences in contribution limits, tax implications, and withdrawal rules is crucial for families managing future savings and educational expenses.
- Statistics indicate that 57% of retirement income is expected to come from sources beyond personal savings, emphasizing the need for proactive planning.
- Many families lack a savings strategy, with half relying solely on Social Security, highlighting the importance of 401(k) and IRA accounts for financial stability.
- 401(k) plans typically have higher administrative fees but offer employer matching, while IRAs often have lower costs and greater investment flexibility.
- Fees associated with both account types can significantly impact long-term savings; even a small percentage fee can reduce savings substantially over time.
- Families should evaluate their financial goals and the fee structures of both accounts to make informed retirement planning decisions.
Introduction
Navigating the complex landscape of retirement savings can feel overwhelming, especially for young families eager to secure their financial futures. Imagine if you could confidently choose the right path for your family. With options like 401(k) plans and Individual Retirement Accounts (IRAs) available, understanding the nuances between these two popular vehicles is essential.
Each account offers unique benefits—think of the employer matching contributions in 401(k)s and the investment flexibility of IRAs. It’s important to assess your specific needs and goals as a family. As financial experts emphasize the importance of proactive planning, we’re here for you.
This article delves into the key differences, fees, and strategic considerations that can empower families to maximize their retirement savings and ensure a stable financial future. Together, we can navigate this journey.
Understanding 401(k) and IRA Accounts
A 401(k) is an employer-sponsored savings plan that allows employees to contribute a portion of their pre-tax income, often with employer matching, which can significantly enhance savings for the future. In contrast, an Individual Retirement Account (IRA) serves as a personal savings tool that provides tax benefits regardless of employment status. This flexibility empowers individuals to manage their investments more freely, aligning with their unique financial goals.
Both accounts are designed to foster future savings, yet they present notable differences in contribution limits, tax implications, and withdrawal rules—factors that are particularly crucial for families like Jay and Emma, who are navigating their financial futures while addressing their children’s educational needs. For instance, in 2025, the contribution limit for a 401(k) is $22,500, whereas the limit for an IRA is $6,500. This makes the 401(k) a more robust option for those looking to contribute more.
Understanding these differences is vital for young families. As Mike Shamrell, Vice President of Thought Leadership at Fidelity, wisely notes, “Saving for the future is a marathon, not a sprint.” This perspective underscores the importance of strategic planning in saving for later life, especially for families striving to balance long-term goals with immediate educational expenses. Current statistics reveal that 57% of income after retirement is expected to come from sources beyond personal savings, such as Social Security and pensions, highlighting the need for proactive future planning.
Moreover, recent data indicates that many working families lack a savings strategy for their later years, with half relying solely on Social Security. This trend emphasizes the increasing importance of 401(k) plans and IRAs in securing financial stability for generations to come. Bright Advisers can assist families like Jay and Emma by providing tailored financial planning and innovative asset management strategies that resonate with their specific objectives. Real-life examples illustrate how families leverage both accounts to maximize their retirement savings, ensuring they can maintain their desired lifestyle in retirement.
Pros and Cons Summary:
401(k):
- Pros: Higher contribution limits, potential employer matching, and personalized investment strategies from Bright Advisers.
- Cons: Limited funding choices, penalties for early withdrawal, and potential fees that may impact overall savings.
IRA: - Pros: Greater investment flexibility, tax advantages, and the ability to collaborate with Bright Advisers for customized investment strategies.
- Cons: Lower contribution limits, income restrictions for tax deductions, and potential complexities in managing multiple accounts.
In summary, while both 401(k) and IRA accounts serve the essential purpose of future savings, understanding 401k fees vs ira fees highlights their distinct features and benefits that cater to different financial strategies. Families like Jay and Emma should thoughtfully consider their options to optimize their retirement planning and alleviate financial anxiety, knowing that Bright Advisers is here to help them navigate these important financial decisions together.
Examining 401(k) Fees
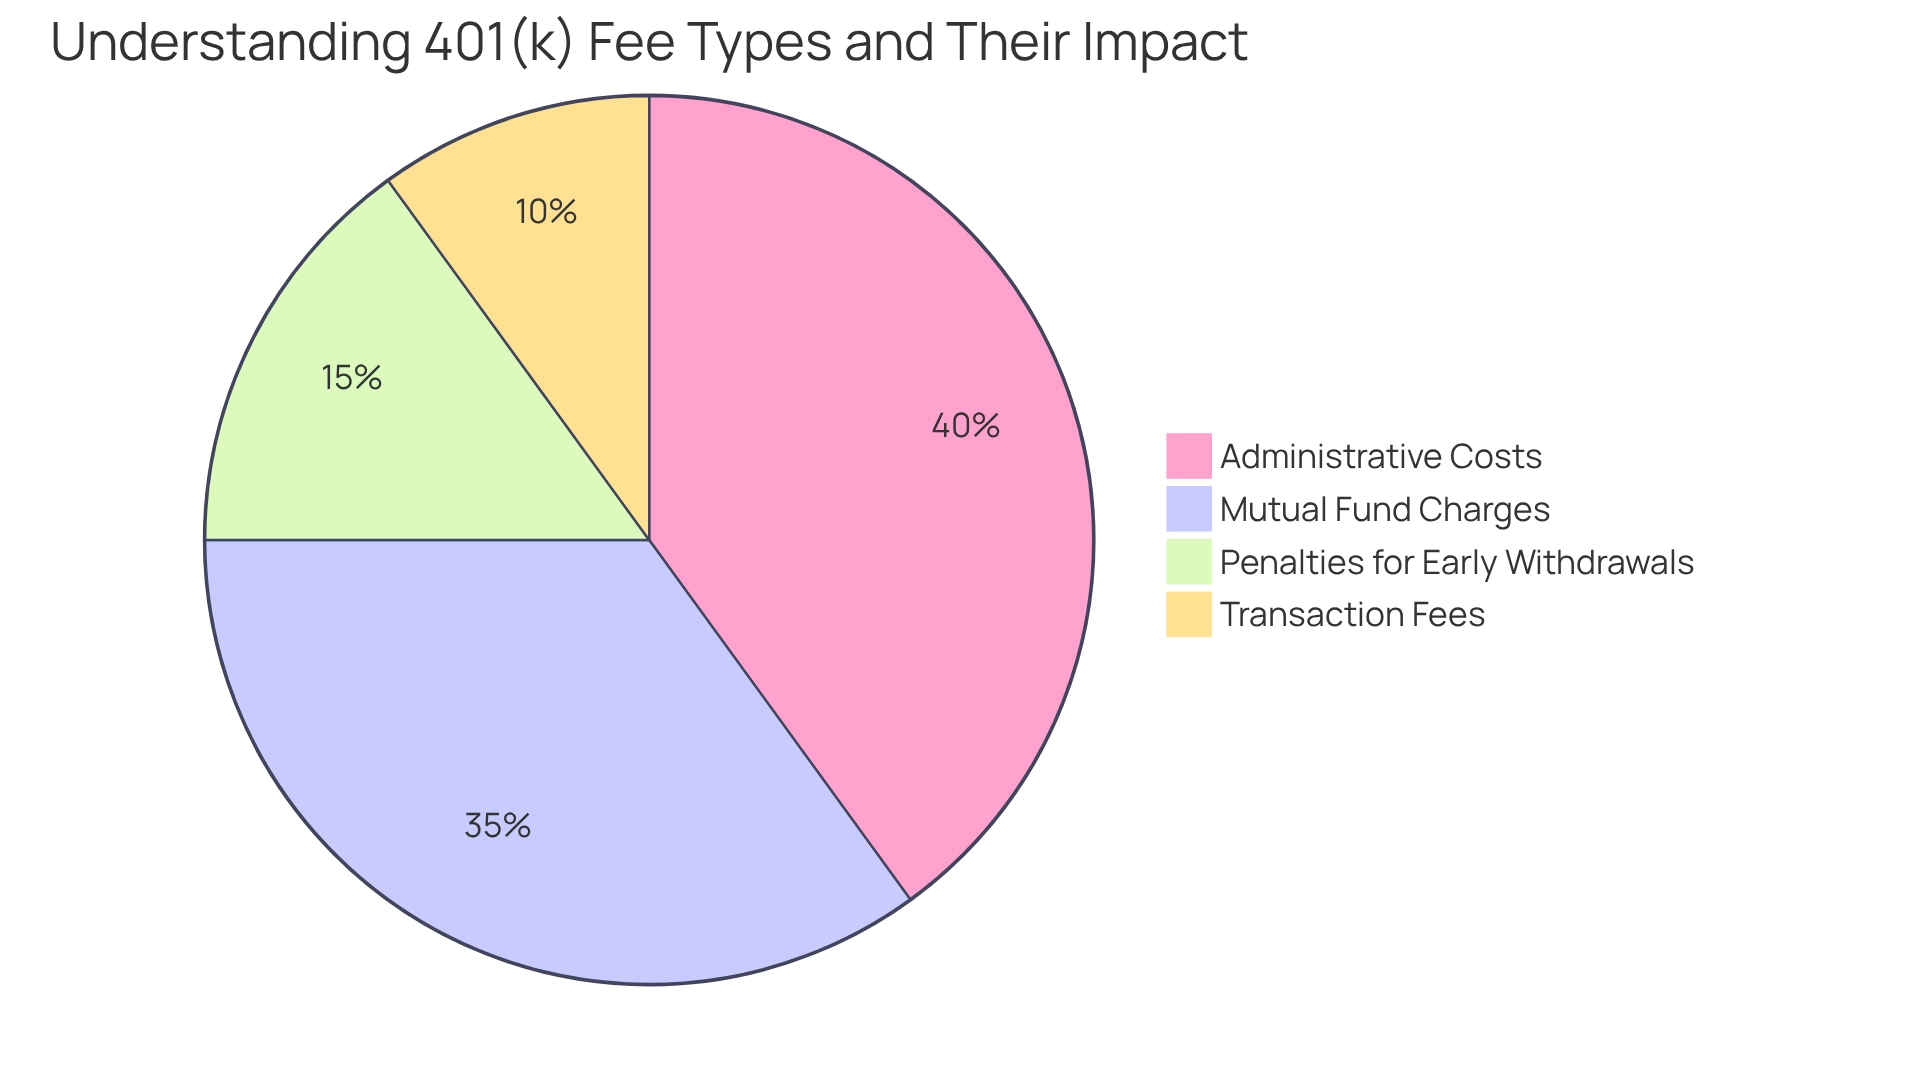
Understanding 401k fees vs ira fees can feel overwhelming, but it’s essential for your family’s financial future. These charges can vary widely, especially when comparing 401k fees vs ira fees, depending on the plan provider and the options you choose. Typically, you’ll encounter administrative costs, which cover the expenses of managing the plan, alongside charges related to mutual funds or other financial products included in the plan.
Imagine this: statistics reveal that 89% of small-cap funds have underperformed over a long 10-year period. This highlights how crucial it is to select the right investment options within your 401(k) plan. Additionally, some plans might impose penalties for early withdrawals or loans taken against your account, which adds another layer of complexity when considering the 401k fees vs ira fees. It’s important to take the time to examine your 401(k) plan documents. Understanding the differences in 401k fees vs ira fees can significantly impact your long-term savings.
For instance, when analyzing 401k fees vs ira fees, a seemingly small 1% fee might not appear significant at first glance, but over 30 years, it could reduce your future savings by approximately 30% due to compounding effects. This could potentially cost your family tens of thousands of dollars, highlighting the significance of understanding 401k fees vs ira fees, as financial experts like Eric Phillips, CFA, stress the importance of enhancing your financial wellness. They advise participants to carefully review their fund’s prospectus for detailed fee information. In contrast, Bright Advisers is committed to maintaining low fund charges, making wealth management more accessible for families like yours.
By taking the time to examine these charges and considering advisory services that prioritize low expenses, you can make informed decisions that greatly enhance your retirement outcomes. Remember, together, we can navigate this journey towards a secure financial future for your family.
Analyzing IRA Fees
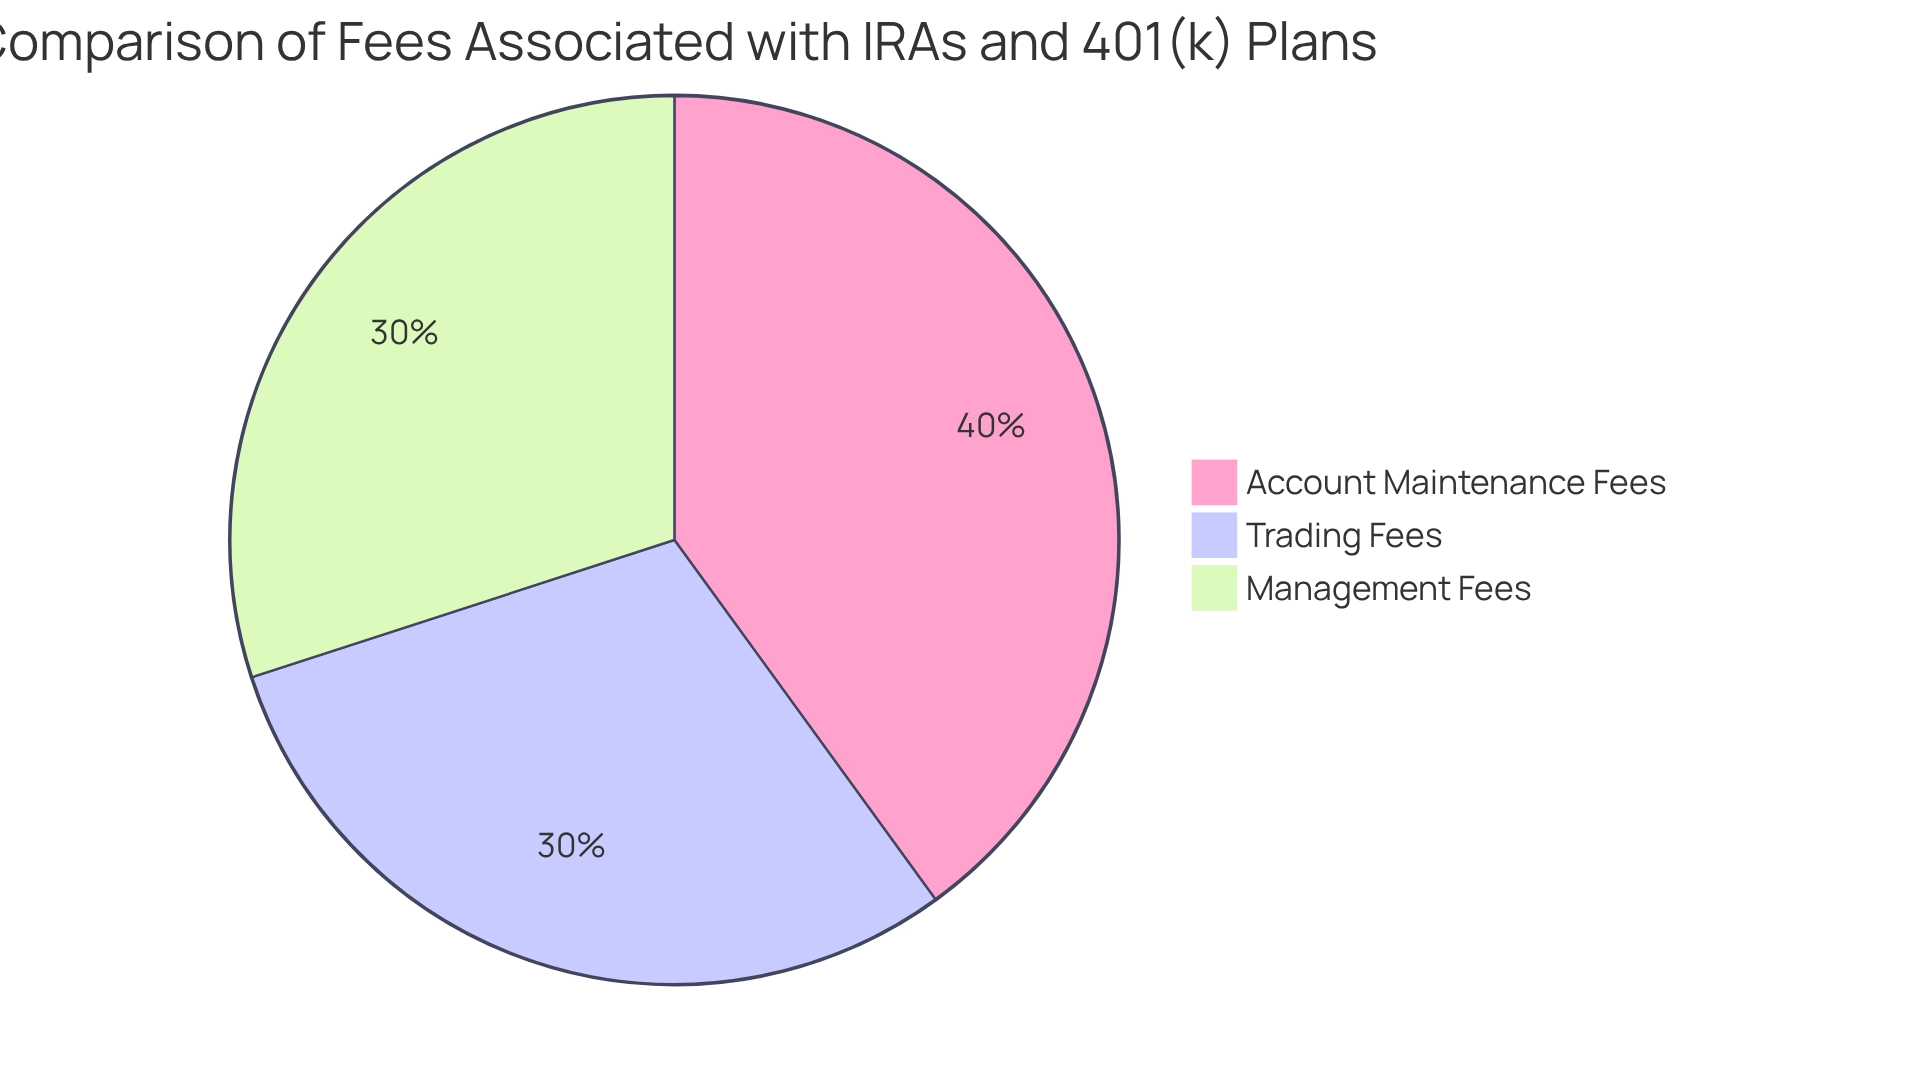
Understanding the costs associated with an IRA can feel overwhelming, especially for young families trying to plan for a secure future. IRA costs can vary significantly, typically including yearly account maintenance fees from certain providers, as well as expenses that are often compared with 401k fees vs ira fees found in 401(k) plans. Imagine if you could navigate these fees with ease, knowing exactly how they impact your savings.
It’s important to recognize that there may also be trading or management fees tied to the assets within your IRA. Unlike 401(k) plans, IRAs offer greater flexibility in investment options, which can lead to different fee structures. Families must remain vigilant about these charges, as 401k fees vs ira fees can greatly influence the growth of your savings over the years, with a traditional IRA often presenting lower costs compared to a 401(k), particularly if the latter incurs high administrative fees. This makes it a more appealing choice for some families. Understanding these fee dynamics is crucial for optimizing your retirement savings and ensuring a financially secure future for your loved ones.
Together, we can navigate this journey, ensuring that you make informed decisions that align with your family’s values and goals. We’re here for you, ready to support you in achieving the financial peace of mind you deserve.
Comparative Analysis of Costs and Benefits
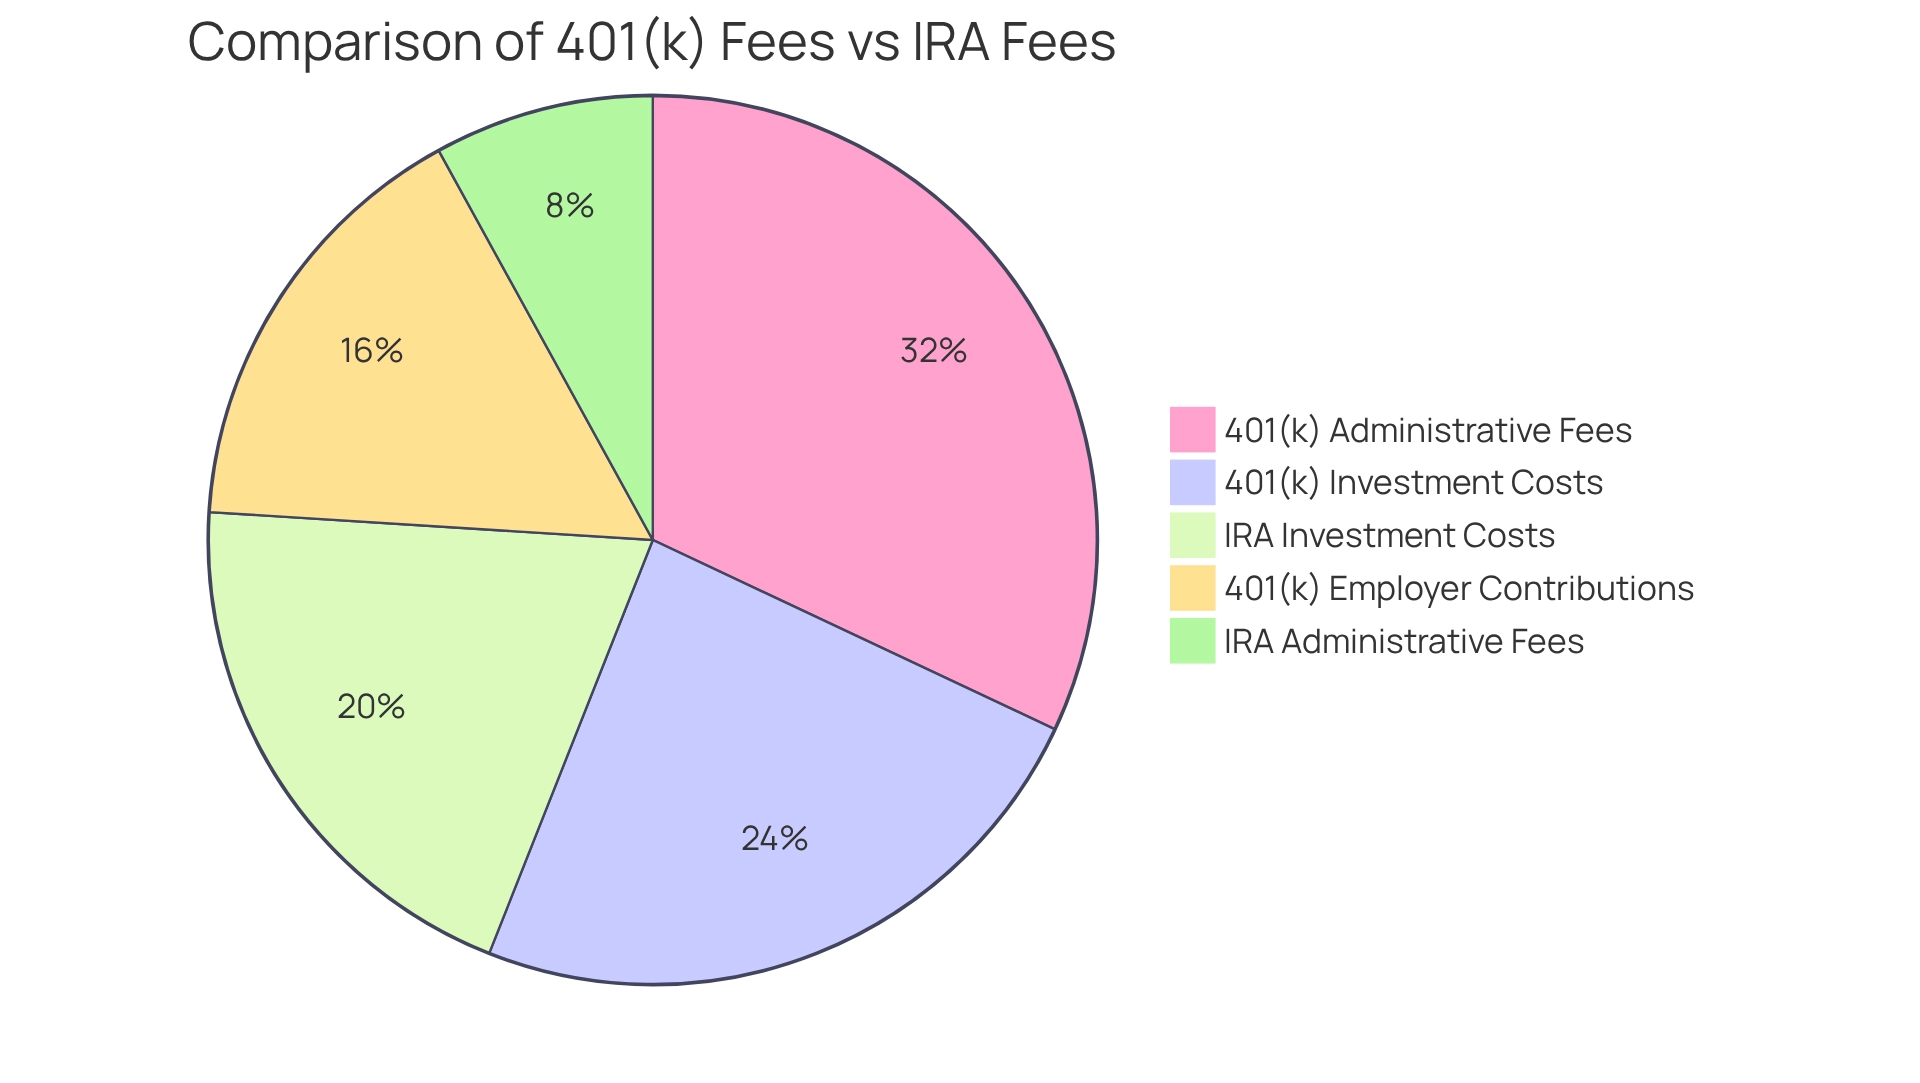
Understanding the differences in 401k fees vs ira fees is crucial for your family’s financial journey. Typically, when discussing 401k fees vs ira fees, 401(k) plans come with higher administrative expenses due to employer involvement, while IRAs often have lower maintenance costs. However, the potential for employer matching contributions in 401(k) plans can significantly offset these costs, ultimately boosting your savings. On the other hand, IRAs offer greater flexibility in investment choices, which can lead to lower investment costs when managed wisely.
As we look ahead to 2025, the contribution limit for 401(k) plans has increased to $23,500, making them an attractive option for families eager to enhance their savings. While 401(k) plans are becoming more popular, it’s vital for families to carefully evaluate the 401k fees vs ira fees associated with both options. In fact, statistics reveal that 31% of employers cite cost concerns as a reason for not offering a 401(k) plan, underscoring the need to understand the financial implications of each choice.
Consider real-life scenarios that illustrate how families navigate these decisions based on costs. For example, families might choose a 401(k) if their employer provides generous matching contributions, significantly boosting their retirement savings. Conversely, those who value investment flexibility may prefer an IRA, especially if they can effectively manage the associated fees.
Ultimately, the choice between a 401(k) and an IRA should reflect your unique circumstances, including employer offerings, investment preferences, and long-term financial aspirations. By thoughtfully assessing the 401k fees vs ira fees and the potential advantages of each option, you can make informed decisions that align with your family’s financial strategies. Remember, we’re here for you, ready to support you in navigating this journey toward financial security and freedom.
Conclusion
Understanding the nuances between 401(k) plans and Individual Retirement Accounts (IRAs) is essential for young families striving to secure their financial futures. Each option presents distinct advantages—401(k) plans often feature higher contribution limits and employer matching, while IRAs offer greater investment flexibility and potential for lower fees. Imagine if you could assess your specific needs, such as educational expenses and long-term financial goals, to determine the most suitable retirement savings strategy for your family.
It’s important to recognize that fees associated with these accounts can significantly impact overall savings. Even a seemingly minor fee can lead to substantial losses over time due to compounding effects. Families must remain vigilant in reviewing the fee structures of both 401(k) plans and IRAs to ensure they are making the most informed decisions possible. Remember, we’re here for you in this journey.
Ultimately, the decision between a 401(k) and an IRA should be guided by individual circumstances, including employer offerings and personal investment preferences. By leveraging expert financial planning and taking a proactive approach to retirement savings, families can navigate the complexities of these options and lay the groundwork for a secure and stable financial future. Prioritizing retirement planning today is a powerful step towards achieving lasting financial well-being for generations to come. Together, we can navigate this journey and ensure a brighter future for your family.
Frequently Asked Questions
What is a 401(k) account?
A 401(k) is an employer-sponsored savings plan that allows employees to contribute a portion of their pre-tax income, often with employer matching, which can significantly boost savings for the future.
What is an IRA account?
An Individual Retirement Account (IRA) is a personal savings tool that offers tax benefits and operates independently of employment status, allowing individuals to manage their investments more freely.
What are the contribution limits for 401(k) and IRA accounts in 2025?
In 2025, the contribution limit for a 401(k) is $22,500, while the limit for an IRA is $6,500.
Why is understanding the differences between 401(k) and IRA accounts important for families?
Understanding the differences is crucial for families as it helps them strategize their financial futures, especially when balancing long-term savings goals with current educational costs for their children.
What percentage of income after work is expected to come from sources beyond personal savings?
Current statistics indicate that 57% of income after work is anticipated to come from sources beyond personal savings, such as Social Security and pensions.
What challenges do working families face regarding savings for later years?
Many working families lack a savings strategy for later years, with half relying solely on Social Security, highlighting the need for proactive financial planning.
What are the pros and cons of 401(k) accounts?
Pros of 401(k) accounts include higher contribution limits and potential employer matching. Cons include limited investment options and penalties for early withdrawal.
What are the pros and cons of IRA accounts?
Pros of IRA accounts include more investment flexibility and tax advantages. Cons include lower contribution limits and income restrictions for tax deductions.
How can families optimize their retirement planning?
Families can optimize their retirement planning by consulting with financial planning services like Bright Advisers, which can help them develop customized strategies that align with their unique financial circumstances and goals.
What is a Roth IRA and its advantage?
A Roth IRA allows for tax-free withdrawals in later years, offering an additional avenue for tax-efficient savings compared to traditional retirement accounts.
List of Sources
- Understanding 401(k) and IRA Accounts
- Average retirement savings by age | Fidelity (https://fidelity.com/learning-center/personal-finance/average-retirement-savings)
- Retirement Statistics You Should Know (https://depositaccounts.com/blog/retirement-statistics.html)
- 401(k)/IRA Holdings in 2022: An Update from the SCF – Center for Retirement Research (https://crr.bc.edu/401k-ira-holdings-in-2022-an-update-from-the-scf)
- IRAs Play a Key Role in US Households’ Retirement Planning (https://ici.org/news-release/24-news-ira-retirement-plan)
- New Data Reveal Inequality in Retirement Account Ownership (https://census.gov/library/stories/2022/08/who-has-retirement-accounts.html)
- Have State Auto-IRAs and Fintech Shifted Who Contributes to IRAs? – Center for Retirement Research (https://crr.bc.edu/have-state-auto-iras-and-fintech-shifted-who-contributes-to-iras)
- Examining 401(k) Fees
- How A 1% Investment Fee Can Wreck Your Retirement (https://forbes.com/sites/robertberger/2021/02/05/how-a-1-investment-fee-can-wreck-your-retirement)
- Average 401(k) Fees | Recordkeeping & Management Fees | Human Interest (https://humaninterest.com/learn/articles/average-401k-fees)
- 401(k) Plan Fees Decline (Again) (https://asppa-net.org/news/2023/2/401k-plan-fees-decline-again)
- Understanding plan participant 401(k) fees | Human Interest (https://humaninterest.com/learn/articles/401k-fees-too-high)
- Low Fee Financial Advisor | Fee-only Financial Advisor | Index Funds (https://onedayinjuly.com/low-fees-matter)
- Analyzing IRA Fees
- IRA rollovers often come with higher investment fees, Pew finds: Here’s how much money that costs retirement savers (https://cnbc.com/2022/06/30/rollover-iras-cost-consumers-45point5-billion-in-fees-earnings-study.html)
- The Top 25 Investing Quotes of All Time (https://investopedia.com/financial-edge/0511/the-top-17-investing-quotes-of-all-time.aspx)
- 7 Key Quotes From Investor Bill Ackman That Could Make You Wealthier | Bankrate (https://bankrate.com/investing/quotes-from-investor-bill-ackman-that-could-make-you-wealthier)
- Comparative Analysis of Costs and Benefits
- 50+ Important 401k Statistics for Companies and Employees in 2025 | Shortlister (https://myshortlister.com/insights/401k-statistics)
- Retirement Account Statistics 2024 – NerdWallet (https://nerdwallet.com/article/investing/retirement-statistics)
- Understanding plan participant 401(k) fees | Human Interest (https://humaninterest.com/learn/articles/401k-fees-too-high)
- 401(k) limit increases to $23,500 for 2025, IRA limit remains $7,000 | Internal Revenue Service (https://irs.gov/newsroom/401k-limit-increases-to-23500-for-2025-ira-limit-remains-7000)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Retirement & Employee Benefits for high-income W-2 families at Bright Advisers.
Keep reading