

Key Highlights:
- Understanding credit scores is crucial for improving financial health, particularly for young families.
- Credit scores range from 300 to 850; higher scores indicate better creditworthiness.
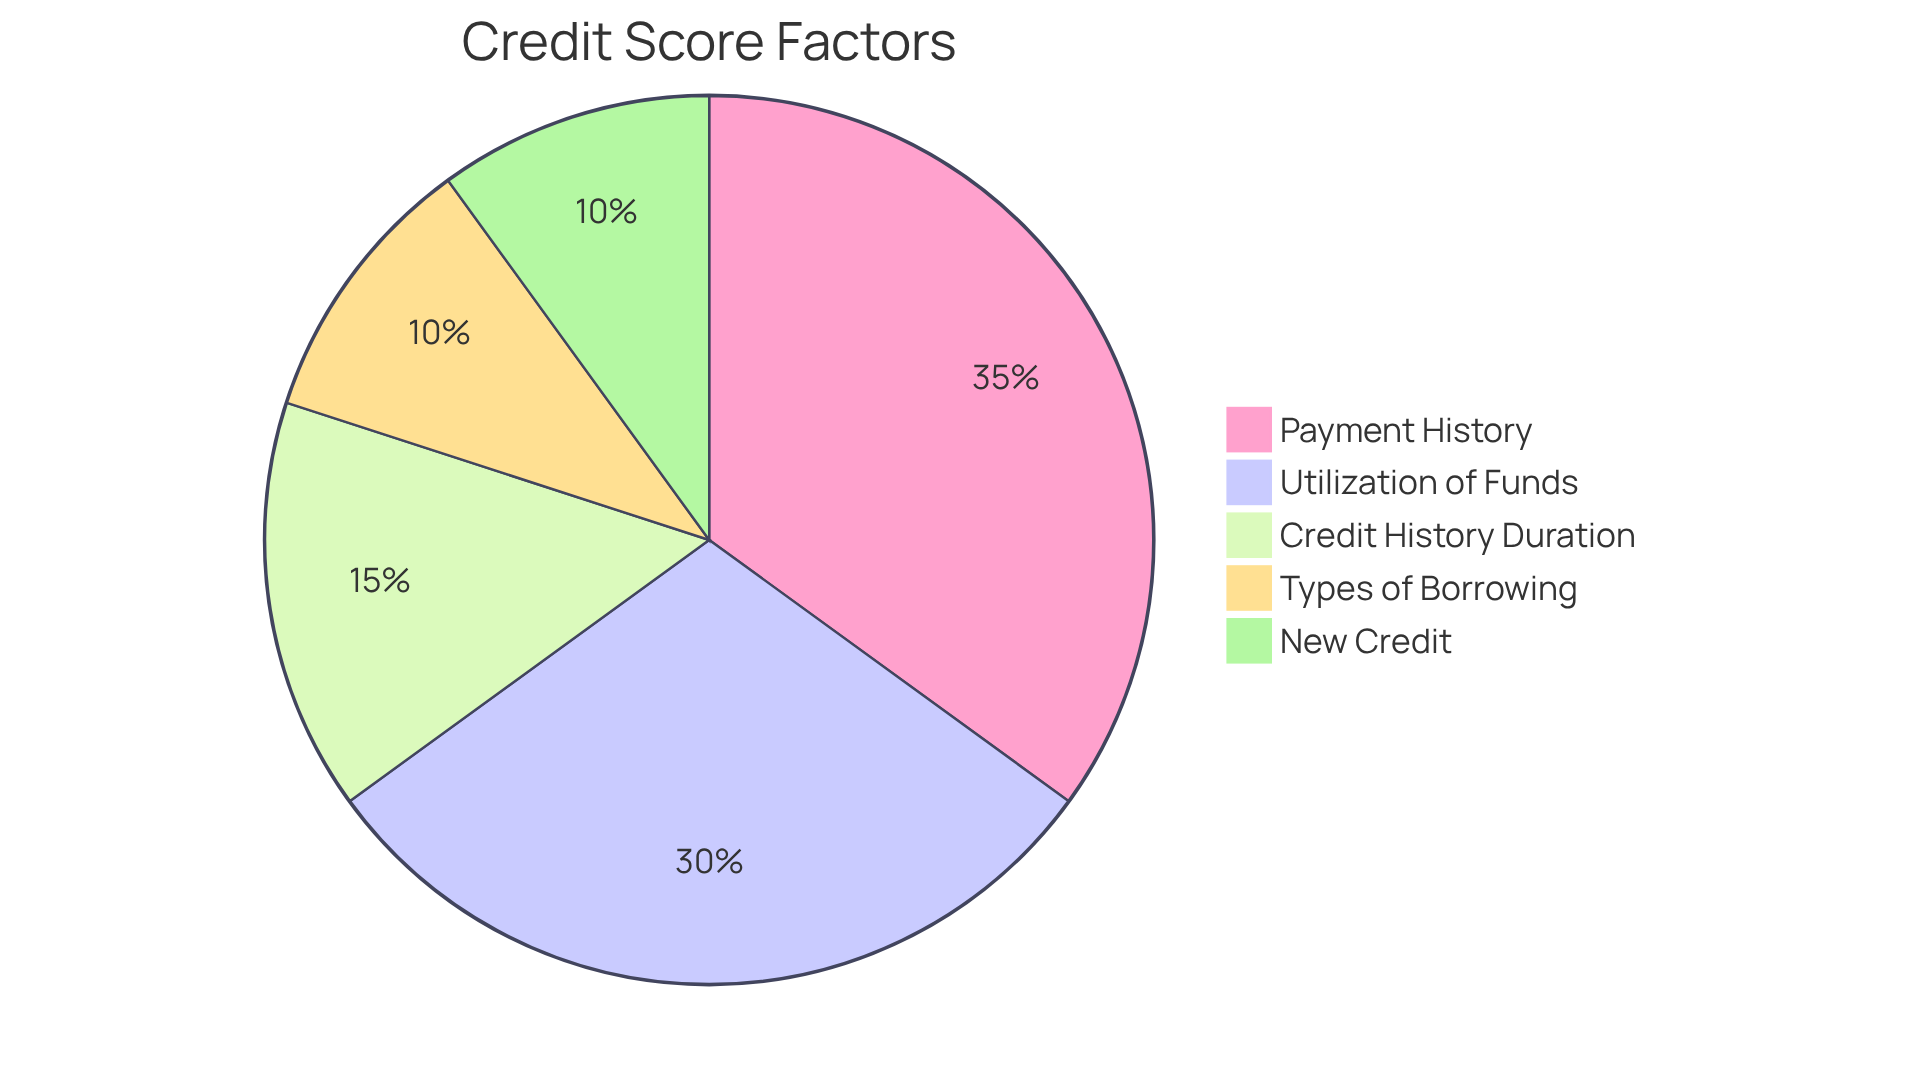
- Key factors influencing credit scores include payment history (35%), utilisation of available funds (30%), duration of credit history (15%), types of borrowing (10%), and new credit (10%).
- Timely payments significantly enhance credit scores; strategies include setting up automatic payments, creating reminders, budgeting wisely, and communicating with creditors.
- Maintaining a credit utilisation ratio below 30% is recommended for optimal financial health.
- Regularly review credit reports for errors, dispute inaccuracies, and ensure accurate reporting to enhance credit scores.
- Using a secured credit card can help rebuild bad credit by demonstrating responsible borrowing practises.
- Restoring credit ratings requires patience and consistency; setting realistic goals and tracking progress are essential for motivation.
Introduction
Understanding credit can feel overwhelming, especially for young parents who are striving to create a stable financial future for their families. Rebuilding bad credit isn’t just about numbers; it’s a journey that opens doors to better loan terms and financial opportunities. Imagine if you could transform your credit score and secure a brighter future for your loved ones.
This guide presents five essential steps that empower parents to take control of their financial health. Together, we can navigate this journey, ensuring you can thrive in an increasingly challenging economic environment. It’s important to understand that you’re not alone in this process; we’re here for you, ready to support you every step of the way.
Understand Your Credit Score and Its Impact
Understanding your credit rating is a vital step in learning how to and improve your financial health, especially for young families navigating the complexities of budgeting and loans. A credit rating typically ranges from 300 to 850, with higher scores indicating greater creditworthiness. Let’s explore the key factors that influence your score:
- Payment History (35%): Timely payments are crucial. They can significantly boost your score, while late payments can hurt it. Remember, your payment history accounts for a substantial 35% of your FICO Score.
- Utilization of Available Funds (30%): This ratio compares your current card balances to your limits. Keeping this ratio below 30% is ideal for maintaining a healthy score.
- Duration of Credit History (15%): A longer financial history can positively impact your rating, showcasing your experience in managing debt.
- Types of Borrowing (10%): Having a mix of borrowing types, like charge cards and loans, can be beneficial for your score.
- New Credit (10%): Opening several new accounts in a short time can negatively affect your rating.
By understanding these elements, you can learn how to rebuild bad credit and take practical steps toward improving your financial rating. Imagine if you consistently tracked your payment history and kept your utilization ratio low; many families have seen remarkable improvements in their scores by doing just that.
As financial experts emphasize, a strong credit rating is more than just a number; it opens doors to better loan terms and financial opportunities. Chris Horymski notes, “Going into 2025, the average rating was 715, remaining unchanged from 2023,” shedding light on the current landscape of financial assessments. It’s encouraging to know that nearly three-quarters of consumers (71.2%) have a good or better rating (670 or higher), inspiring young families to strive for similar success.
Jim Bander adds, “If there’s one thing I’ve learned from the data about the American consumer, it’s that they are incredibly resilient.” This reinforces a positive message for families managing their finances. Remember, we’re here for you, and together, we can navigate this journey toward financial stability.
Make Timely Payments on All Bills
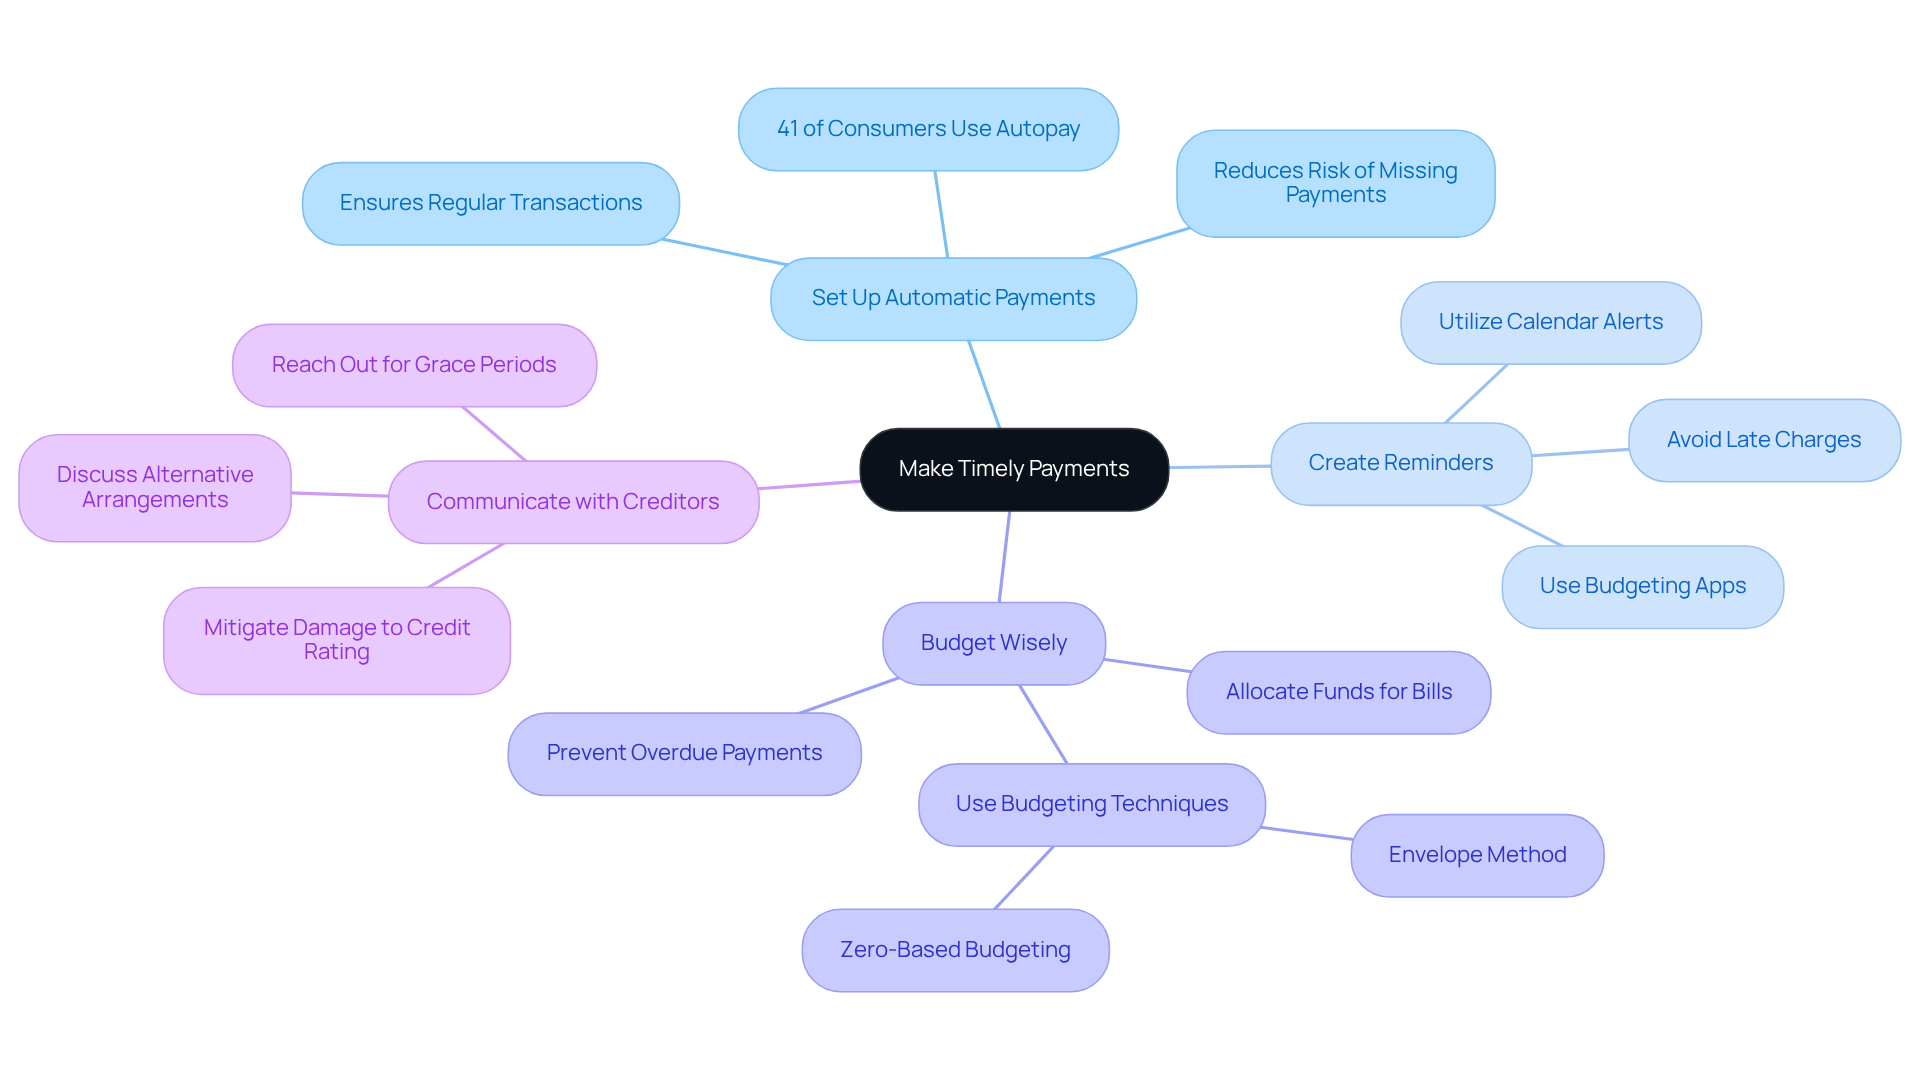
To improve your score, making on-time contributions is crucial. Here are some effective strategies to help you stay on track:
- Set Up Automatic Payments: Imagine never having to worry about missing a due date again! Automating your bill payments can significantly reduce that risk. Did you know that 41% of consumers use autopay for their bills? This approach ensures that vital transactions happen regularly, which is so important for maintaining a positive financial record.
- Create Reminders: It’s easy to forget due dates amidst the hustle and bustle of family life. Utilize calendar alerts or to remind you of upcoming dues. This proactive method can help you avoid late charges and the negative impact on your credit rating that comes with missed payments.
- Budget Wisely: Think of your budget as a roadmap for your family’s financial journey. Allocate specific funds for bills within your monthly budget. By prioritizing these costs, you can steer clear of deficits that might lead to overdue payments. Many households have found success with budgeting techniques like the envelope method or zero-based budgeting, helping them manage their finances effectively and ensure timely payments.
- Communicate with Creditors: Life can be unpredictable, and if you anticipate a delay in settling your debt, reach out to your creditor as soon as possible. Many lenders are open to discussing options like grace periods or alternative arrangements, which can help you avoid further damage to your credit rating.
By consistently making prompt contributions, you can gradually improve your rating and learn how to rebuild bad credit while building a strong financial history. This is key in assessing creditworthiness. Financial specialists emphasize that knowing how to rebuild bad credit is crucial, as payment history is one of the most important factors in your financial rating, affecting your long-term economic well-being. Remember, we’re here for you, and together, we can navigate this journey!
Reduce Your Credit Utilization Ratio
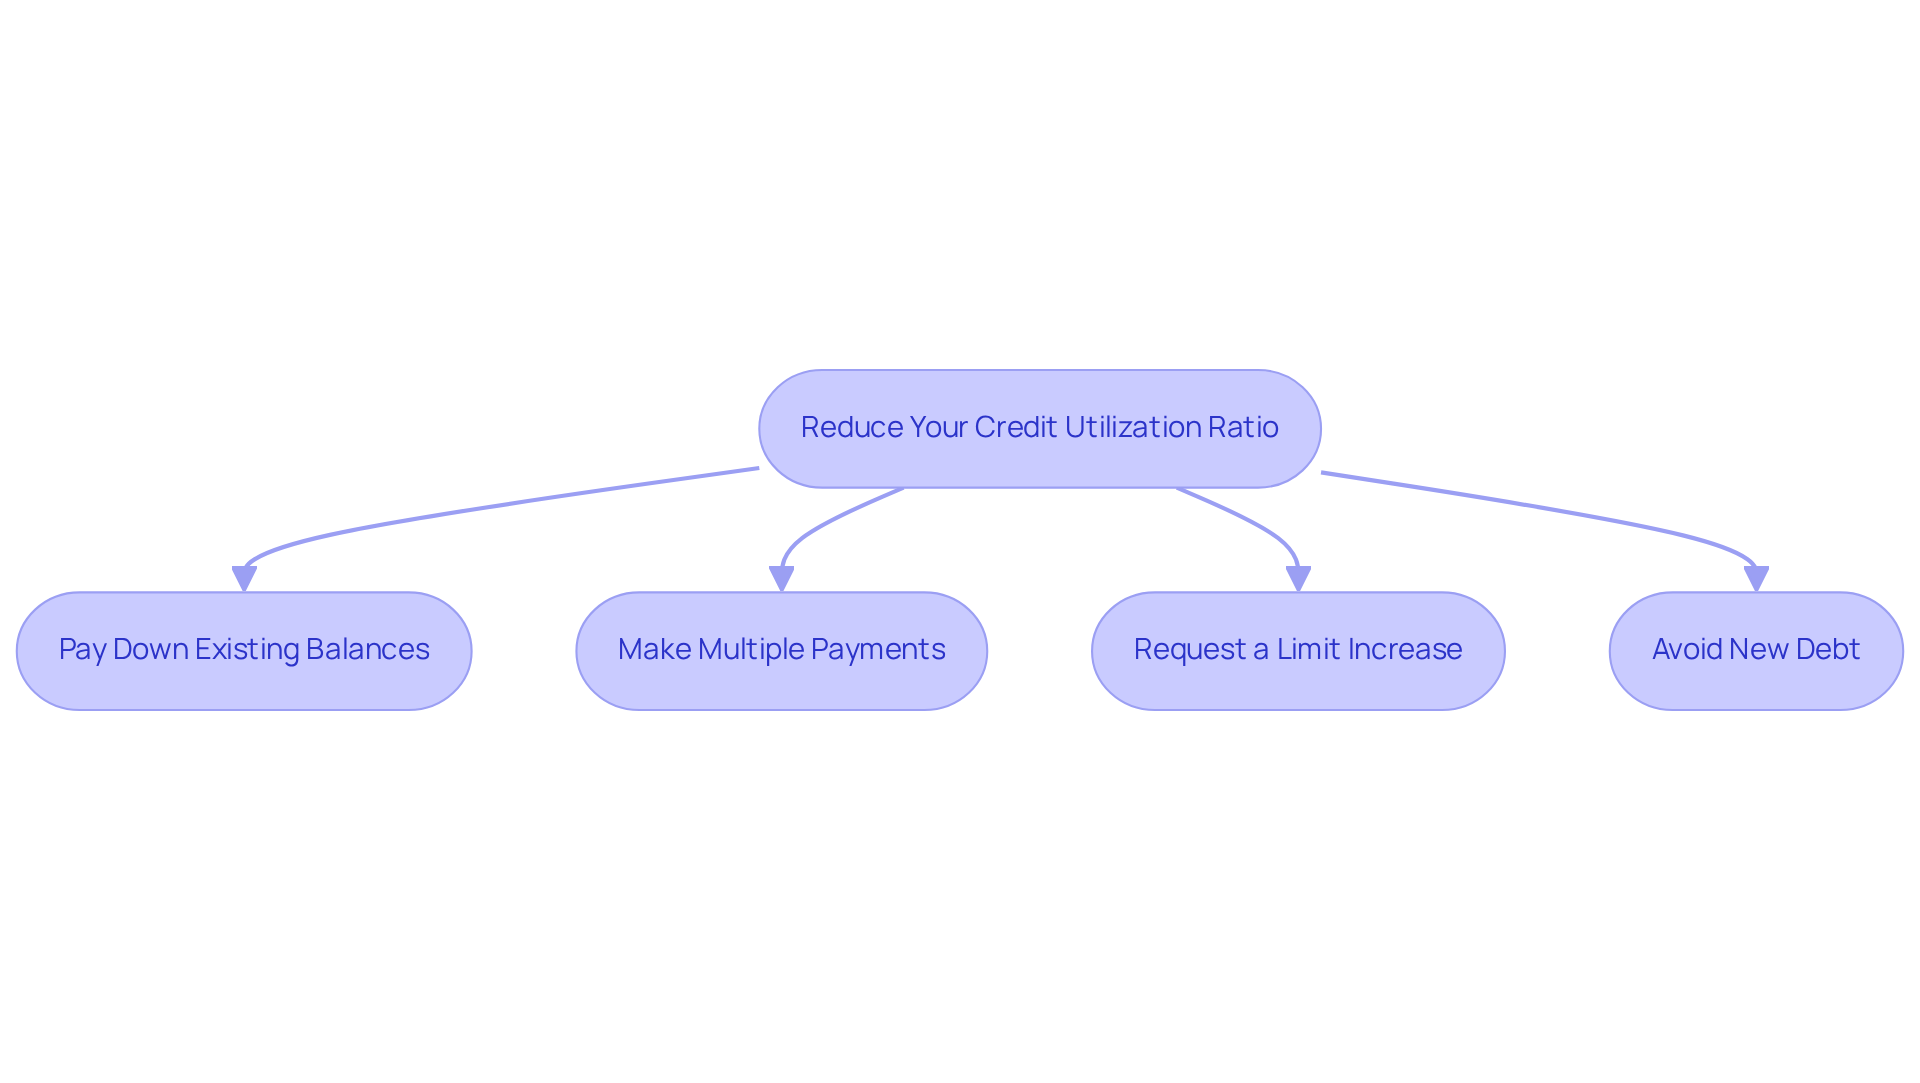
To effectively reduce your credit utilization ratio, consider these caring strategies:
- Pay Down Existing Balances: Start by prioritizing high credit card balances. Paying these off first can significantly lower your utilization ratio in no time, giving your credit score a boost.
- Make Multiple Payments: Instead of waiting for the due date, think about making payments throughout the month. This habit keeps your balances low and shows that you’re managing your finances responsibly.
- Request a Limit Increase: If your situation allows, consider asking your card issuer for a higher limit. This can lower your utilization ratio without changing your spending habits, providing a cushion that positively impacts your credit rating.
- Avoid New Debt: While you’re working to improve your score, it’s important to resist the temptation to take on more debt. This discipline is key to maintaining a healthy financial profile.
By actively managing your resources, you can enhance your trustworthiness and improve your overall financial well-being. Imagine this: in 2025, the average card balance in the U.S. is projected to be $6,580, with many families successfully managing their utilization to boost their scores. Financial coaches emphasize that keeping your utilization rate below 30% is vital for optimal financial health. As FICO suggests, “Keeping your overall utilization rate below 30% can be a helpful rule of thumb – but the lower, the better.” With 46% of households , these strategies can truly make a difference in achieving financial stability.
Together, we can navigate this journey toward a healthier financial future.
Review and Dispute Errors on Your Credit Report
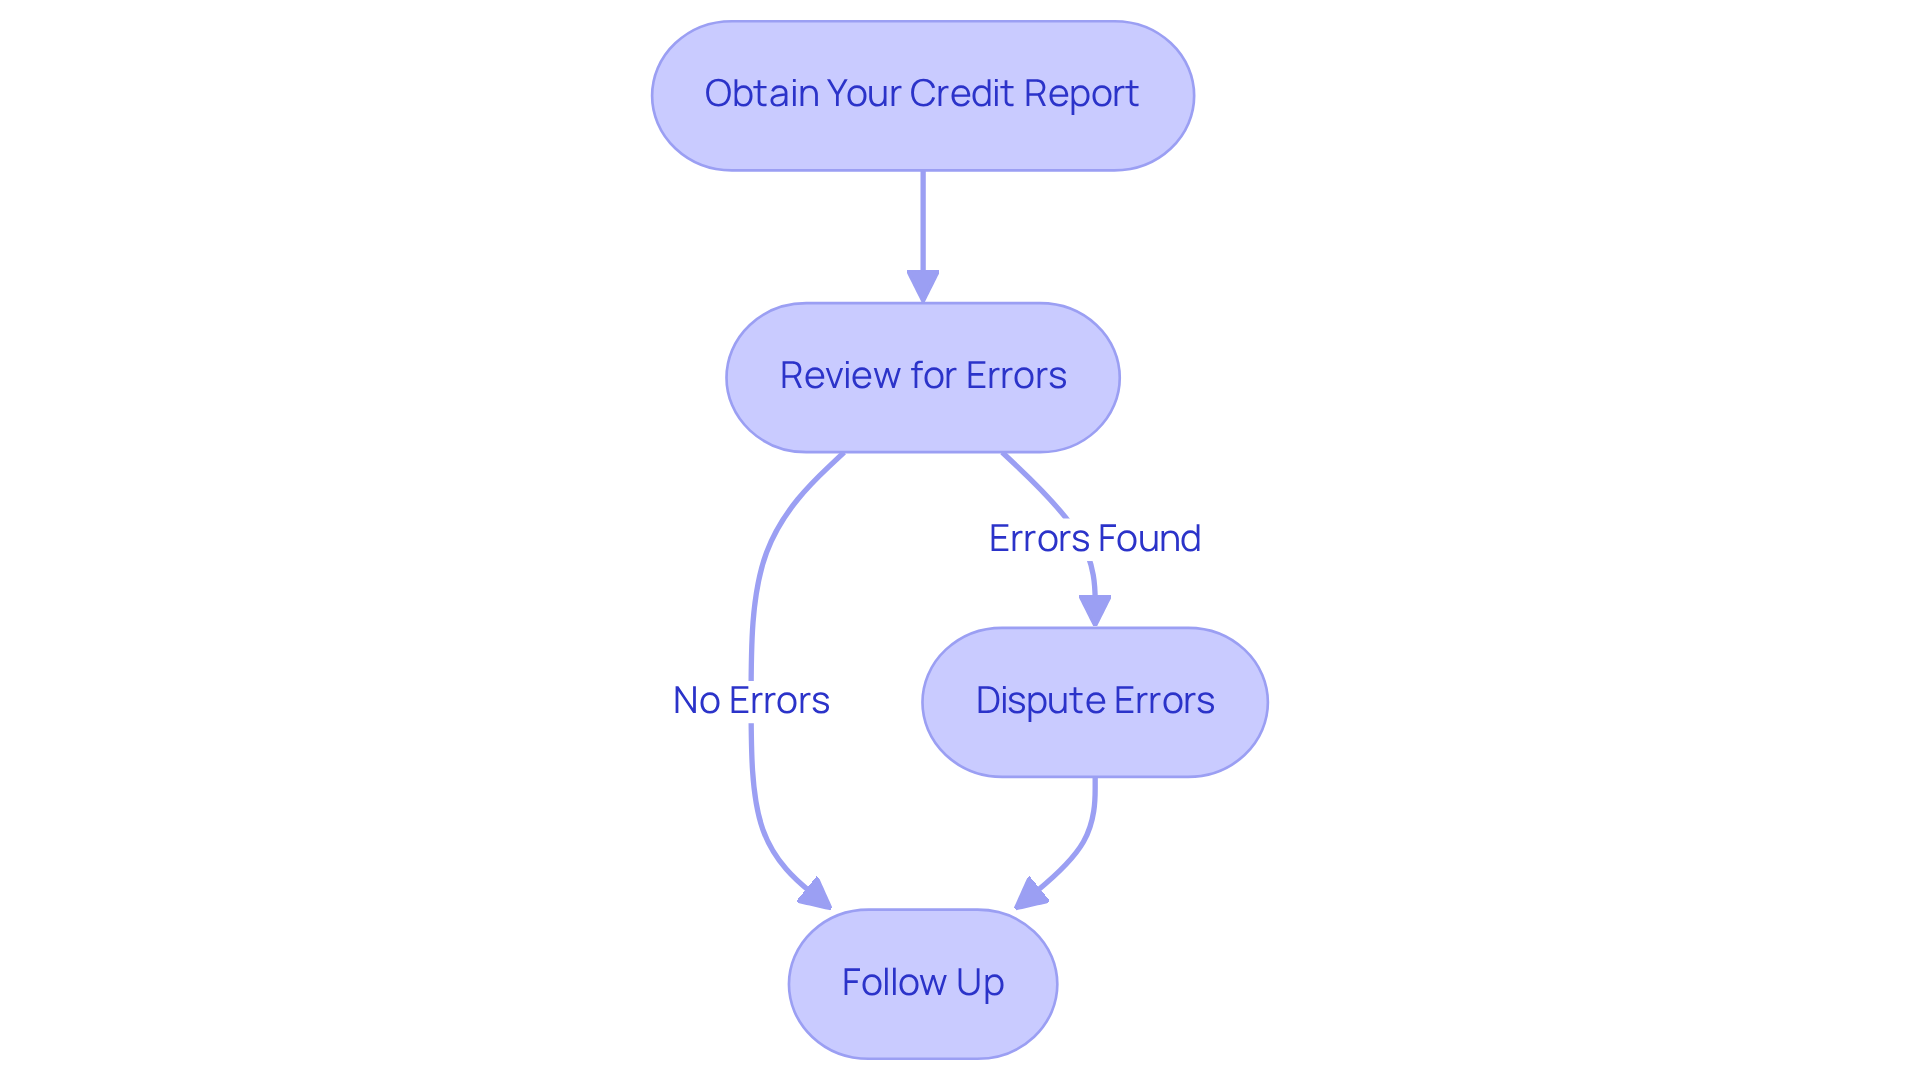
To ensure your credit report is accurate, follow these essential steps:
- Obtain Your Credit Report: You deserve to know where you stand financially. Each year, you can access one free credit report from each of the three major credit bureaus: Equifax, Experian, and TransUnion. Just visit AnnualCreditReport.com to get started.
- Review for Errors: Take a moment to carefully examine your reports. Look for inaccuracies like incorrect account details, late payments that were actually paid on time, or accounts that don’t belong to you. Research shows that 34% of consumers [[find mistakes related to personal information](https://advocacy.consumerreports.org/press_release/almost-half-of-participants-in-credit-checkup-study-find-errors-on-credit-reports-more-than-a-quarter-find-serious-mistakes)](https://advocacy.consumerreports.org/press_release/almost-half-of-participants-in-credit-checkup-study-find-errors-on-credit-reports-more-than-a-quarter-find-serious-mistakes) in their reports, and 5% face significant [[errors that could lead to higher costs for loans and insurance](https://debt.org/blog/study-suggests-you-check-credit-reports-for-inaccuracies)](https://certifiedcredit.com/scary-stats-about-your-mortgage-applicants-credit-reports-and-how-to-fix-them). Imagine the peace of mind you’ll feel when you know your report is accurate.
- Dispute Errors: If you spot a mistake, don’t hesitate to act. Swiftly [[submit a dispute to the appropriate bureau](https://mccarthylawyer.com/2023/05/10/how-common-are-credit-report-errors)](https://mccarthylawyer.com/2023/05/10/how-common-are-credit-report-errors), providing any supporting documentation to back up your claim. The process is usually straightforward and can often be done online, making it easier for you to take control of your financial health.
- Follow Up: After submitting your dispute, keep an eye on your financial report to ensure the error has been corrected. The financial bureau is required to investigate and respond within 30 days, but it may take 30-45 days for the correction to show up on your report. Remember, staying proactive is key to maintaining your [financial well-being](https://brightadvisers.com/?p=10250).
As Charles Harwood, interim director of the FTC’s Bureau of Consumer Protection, remarked, “Precise reports are essential for consumers’ economic well-being.” By actively overseeing your financial report, you can eliminate inaccuracies that may be negatively impacting your score, which is essential for understanding how to [[[rebuild bad credit](https://brightadvisers.com/?p=10134)](https://brightadvisers.com/?p=10134)](https://brightadvisers.com/?p=10134). Together, we can toward [financial stability](https://brightadvisers.com/?p=11328). Remember, [[[accurate financial reports](https://brightadvisers.com/?p=11078)](https://brightadvisers.com/?p=12663)](https://brightadvisers.com/?p=11328) are crucial for securing favorable loan terms and opportunities, especially for young families looking to build a bright future.
Consider Using a Secured Credit Card
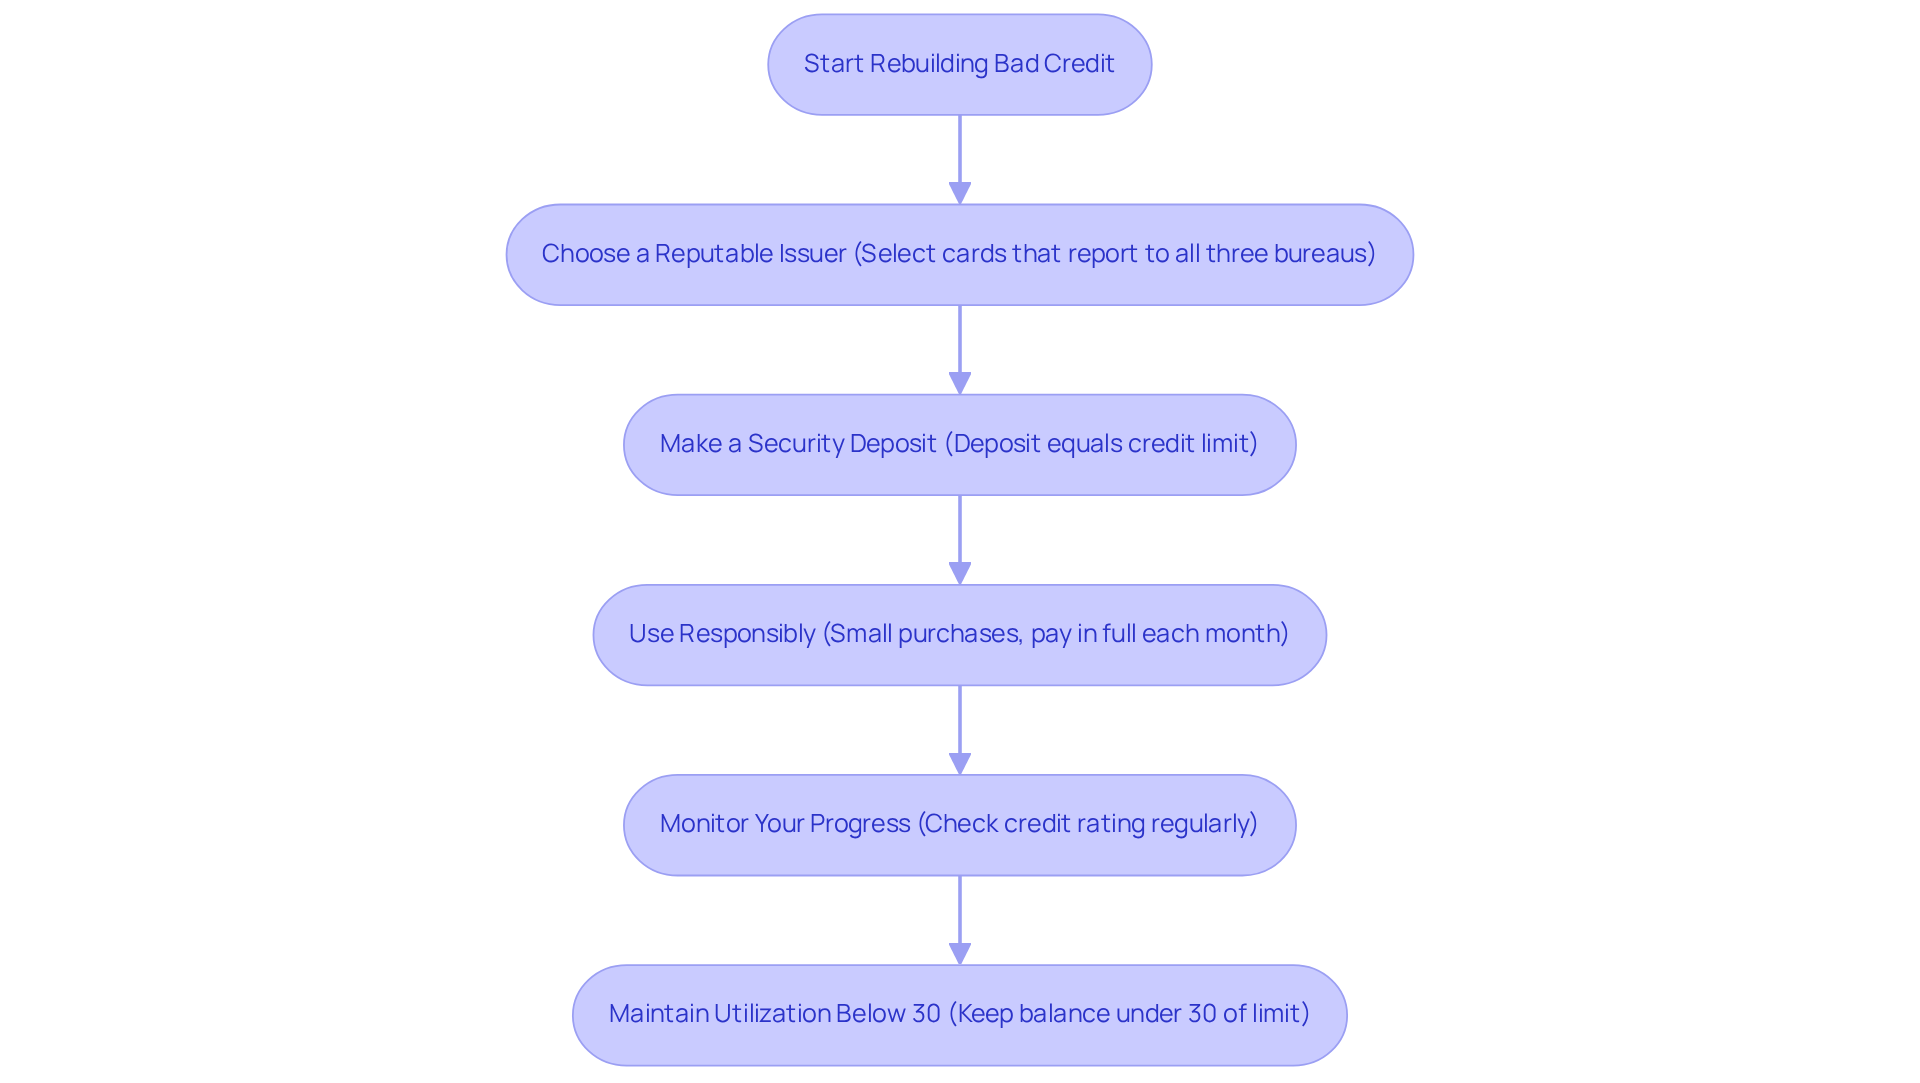
A secured charge card can be a vital resource for understanding how to rebuild bad credit. Imagine if you could take steps today on [[how to rebuild bad credit](https://bankrate.com/credit-cards/building-credit/how-to-use-secured-credit-card-to-rebuild-credit)](https://lexingtonlaw.com/blog/credit-cards/how-much-will-a-secured-credit-card-raise-my-credit-score.html) to improve your credit score and secure a brighter financial future for your family. Here’s how to maximize its benefits:
- Choose a Reputable Issuer: Select [secured credit cards](https://bankrate.com/credit-cards/building-credit/how-to-use-secured-credit-card-to-rebuild-credit) that report to all three major credit bureaus. This ensures that your [responsible usage](https://brightadvisers.com/understanding-the-cost-of-a-financial-planner-for-families) is reflected in your report, which is essential for enhancing your score.
- [[Make a Security Deposit](https://lexingtonlaw.com/blog/credit-cards/how-much-will-a-secured-credit-card-raise-my-credit-score.html)](https://lexingtonlaw.com/blog/credit-cards/how-much-will-a-secured-credit-card-raise-my-credit-score.html): Your deposit usually corresponds to your limit. For example, a $200 deposit sets a $200 borrowing limit, offering a practical way to begin developing creditworthiness.
- Use Responsibly: Engage in small purchases and pay off the balance in full each month. This practice not only helps you avoid interest fees but also establishes a favorable payment record, which is the most crucial element in assessing your financial rating. Plus, consider asking for limit increases after demonstrating responsible usage, as this can further enhance your utilization rate.
- [Monitor Your Progress](https://federalreserve.gov/econres/notes/feds-notes/an-overview-of-credit-building-products-20241206.html): Regularly check your rating to track the effect of your secured card usage. Improvement may take time, but [[[understanding how to rebuild bad credit](https://brightadvisers.com/?p=10262) through consistent responsible behavior](https://federalreserve.gov/econres/notes/feds-notes/an-overview-of-credit-building-products-20241206.html)](https://federalreserve.gov/econres/notes/feds-notes/an-overview-of-credit-building-products-20241206.html) can lead to significant gains. Remember, maintaining a utilization ratio of 30% or below is advised for optimal rating enhancement.
Using a secured payment card wisely can show you how to rebuild bad credit while [[demonstrating responsible borrowing practices](https://brightadvisers.com/?p=11100)](https://brightadvisers.com/?p=11120) and gradually improving your score. Families like Jessica Clark’s, who effectively restored their standing after financial difficulties while keeping their utilization below 30%, illustrate how to rebuild bad credit by using secured cards to promote economic recovery. Together, we can navigate this journey toward improved financial standing, starting with knowledgeable and proactive measures. We’re here for you .
Practice Patience and Consistency in Your Efforts
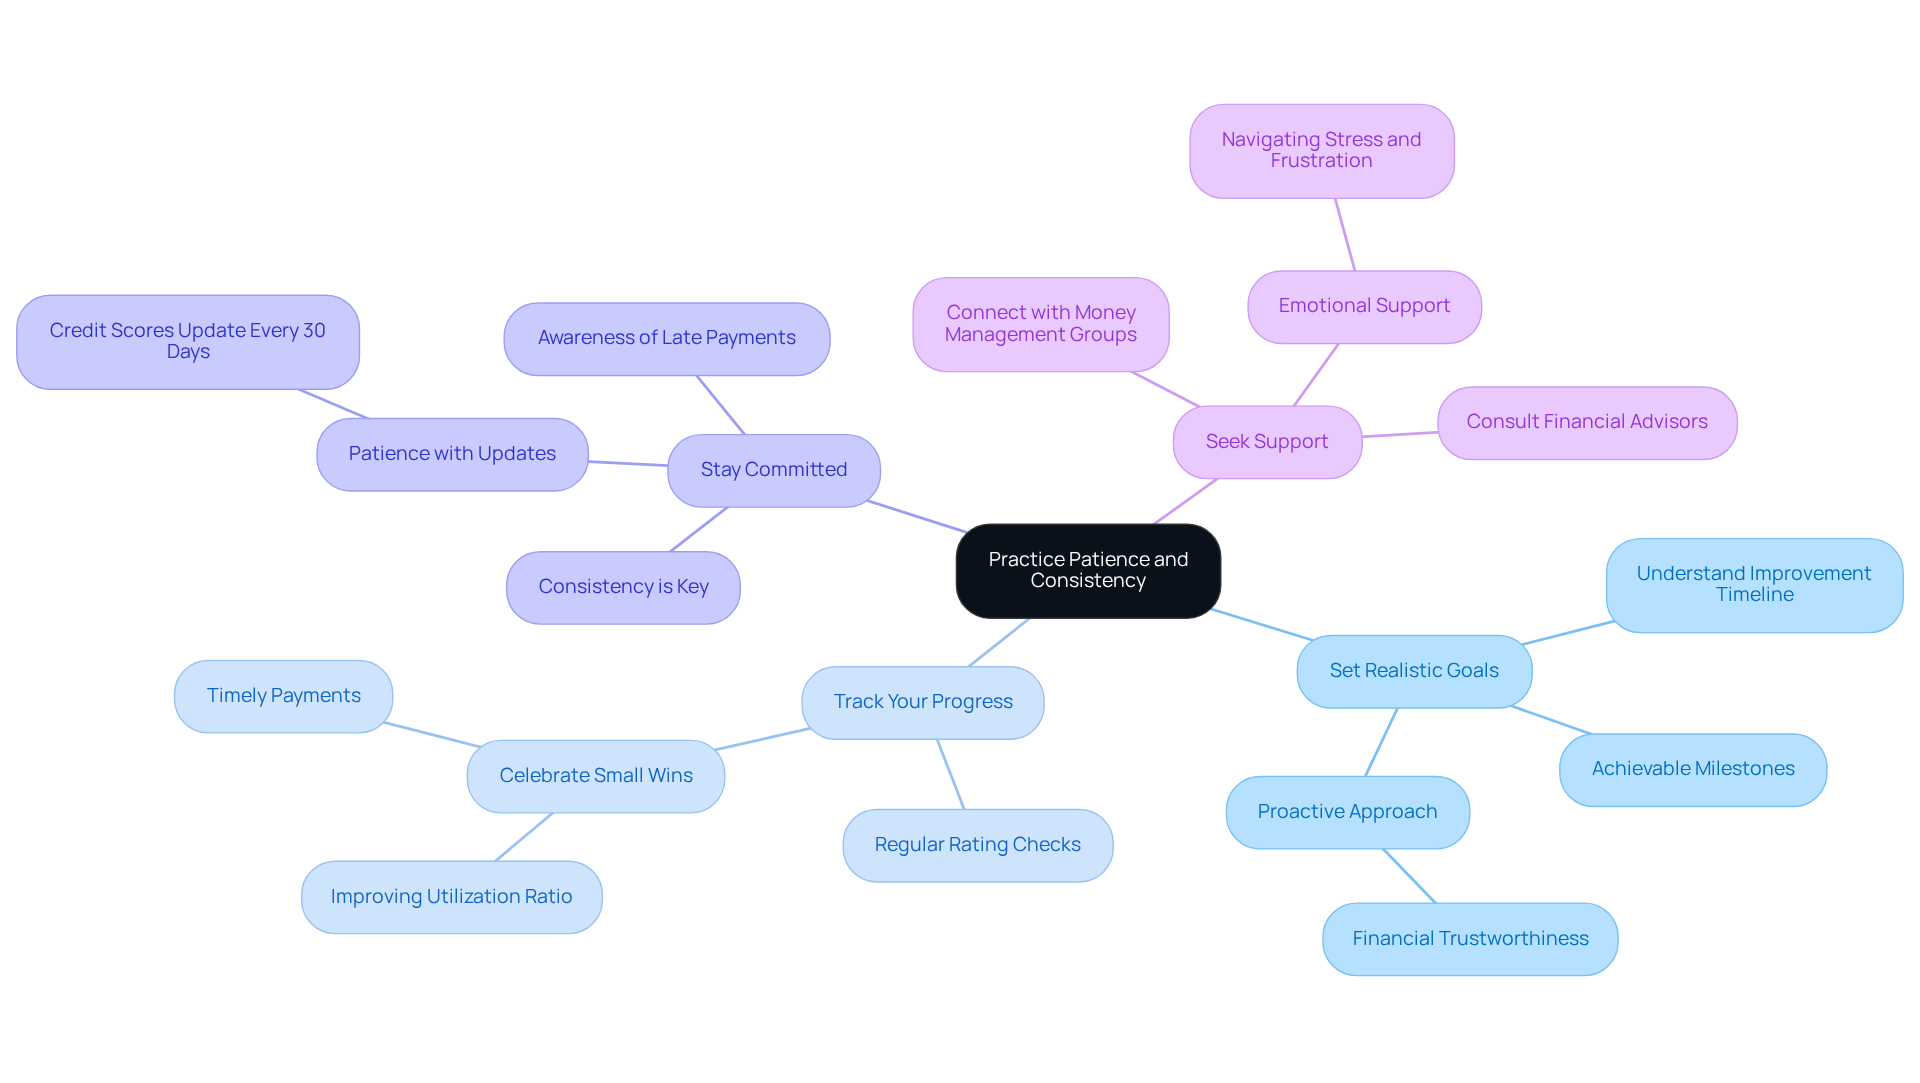
Restoring your rating is a gradual journey that requires commitment and a thoughtful plan. Here are some [effective strategies](https://brightadvisers.com/?p=11100) to keep your motivation alive along the way:
- Set Realistic Goals: Understand that meaningful improvements can take time-months or even years, depending on where you start. For families, [setting achievable milestones](https://lendingtree.com/credit-repair/how-long-does-it-take-to-improve-your-credit) can help you stay focused and reduce frustration. As Joey Robinson wisely notes, “A [proactive approach](https://creditonebank.com/articles/10-famous-quotes-about-finances-credit) is the best way to establish financial trustworthiness responsibly.”
- [Track Your Progress](https://bankrate.com/credit-cards/bad-credit/how-long-does-it-take-to-get-a-credit-score-up): Keep an eye on your rating. Studies show that about 30% of people regularly check their ratings. [Celebrating small wins](https://brightadvisers.com/?p=10995), like improving your utilization ratio or making timely payments, can boost your spirits and reinforce positive habits.
- [Stay Committed](https://brightadvisers.com/?p=10972): Consistency is crucial. Stick to the , even when it feels like progress is slow. Remember, credit scores typically update every 30 days, so patience is key. Knowing that late payments can stay on your report for years can motivate you to stay on track.
- Seek Support: Connect with [money management](https://brightadvisers.com/comparing-personal-investment-management-companies-for-families) groups or consult a [financial advisor](https://brightadvisers.com/10-essential-questions-to-ask-a-new-financial-advisor). Having a support system can provide accountability and encouragement, making the journey feel less overwhelming. Recognizing the emotional hurdles of rebuilding finances, like stress and frustration, can help you navigate this process more effectively.
By embracing patience and consistency, you can discover how to [rebuild bad credit](https://lifelock.norton.com/learn/credit-finance/how-long-does-it-take-to-rebuild-credit?srsltid=AfmBOor2sHdwZFgmGeJtt7okg9GrM8s6ankIx8kF2_9MZX7PHS2E-xsI), paving the way for a more secure [[financial future](https://brightadvisers.com/9-end-of-year-tax-strategies-for-young-families-to-save-big)](https://brightadvisers.com/avoid-rmd-penalties-essential-steps-for-young-families) for your family. Together, we can navigate this journey.
Conclusion
Understanding how to rebuild bad credit is essential for young parents striving for financial stability. Imagine if you could enhance your credit score and open doors to better financial opportunities for your family. It may seem daunting, but with the right strategies and a commitment to improvement, it’s entirely achievable.
Key insights from this guide highlight the importance of:
- Grasping credit scores
- Making timely payments
- Reducing credit utilization
- Regularly reviewing credit reports for errors
Utilizing tools like secured credit cards can also pave the way to effectively rebuild credit. Each of these steps plays a crucial role in establishing a solid financial foundation, allowing families to navigate their financial responsibilities with confidence.
Ultimately, patience and consistency are paramount in this process. As you embark on your journey to improve your credit scores, remember that meaningful change takes time. By embracing these strategies and maintaining a positive outlook, you can look forward to a brighter financial future, equipped with the knowledge and tools necessary to succeed. Taking action today can lead to lasting benefits for both you and your children. Together, we can navigate this journey.
Frequently Asked Questions
What is a credit score and what does it indicate?
A credit score is a numerical representation of your creditworthiness, typically ranging from 300 to 850, with higher scores indicating greater creditworthiness.
What are the key factors that influence a credit score?
The key factors influencing a credit score include:
- Payment History (35%): Timely payments boost your score, while late payments can hurt it.
- Utilization of Available Funds (30%): Keeping your credit utilization ratio below 30% is ideal.
- Duration of Credit History (15%): A longer credit history positively impacts your score.
- Types of Borrowing (10%): A mix of borrowing types can be beneficial.
- New Credit (10%): Opening several new accounts in a short time can negatively affect your score.
How can timely payments affect my credit score?
Making on-time payments is crucial as it significantly influences your credit score. Consistently paying on time can lead to improvements in your credit rating.
What strategies can I use to ensure I make timely payments?
Effective strategies include:
- Setting up automatic payments to avoid missing due dates.
- Creating reminders using calendar alerts or budgeting apps.
- Budgeting wisely by allocating specific funds for bills.
- Communicating with creditors if you anticipate a delay in payments.
What is the average credit rating currently, and how does it reflect consumer behavior?
The average credit rating is 715, which has remained unchanged from 2023. Nearly 71.2% of consumers have a good or better rating (670 or higher), indicating resilience among American consumers.
Why is understanding and improving your credit score important?
A strong credit rating opens doors to better loan terms and financial opportunities, making it essential for long-term financial health and stability.
List of Sources
- Understand Your Credit Score and Its Impact
- 10 Quotes About Finance & Credit (https://creditonebank.com/articles/10-famous-quotes-about-finances-credit)
- What’s the average credit score? (https://cnbc.com/select/the-average-credit-score-in-the-us-in-2025)
- What Is the Average Credit Score in the US? (https://experian.com/blogs/ask-experian/what-is-the-average-credit-score-in-the-u-s)
- Average Credit Score Statistics 2025 (https://wallethub.com/edu/cs/average-credit-scores/25578)
- 18 Statistics Proving Buyer-credit Score Volatility Post-pandemic (https://resolvepay.com/blog/statistics-proving-buyer-credit-score-volatility-post-pandemic)
- Make Timely Payments on All Bills
- Average U.S. FICO® Score stays at 717 even as consumers are faced with economic uncertainty (https://fico.com/blogs/average-u-s-fico-score-stays-717-even-consumers-are-faced-economic-uncertainty)
- Scary Stats About Your Mortgage Applicants’ Credit Reports and How to Fix Them (https://certifiedcredit.com/scary-stats-about-your-mortgage-applicants-credit-reports-and-how-to-fix-them)
- Nearly 60% of Americans Shun Automatic Bill Payments, Study Reveals | PYMNTS.com (https://pymnts.com/news/payment-methods/2025/nearly-60percent-of-americans-shun-automatic-bill-payments-study-reveals)
- 8 Perfect Dave Ramsey Quotes About Credit Cards (https://247wallst.com/banking-finance-and-taxes/2024/06/14/8-perfect-dave-ramsey-quotes-about-credit-cards)
- 9 Real Ways to Improve Your Credit Fast – NerdWallet (https://nerdwallet.com/finance/learn/raise-credit-score-fast)
- Reduce Your Credit Utilization Ratio
- 14 Quotes From Our Favorite Money Saving Experts (https://chime.com/blog/quotes-from-money-saving-experts)
- 10 Quotes About Finance & Credit (https://creditonebank.com/articles/10-famous-quotes-about-finances-credit)
- What is credit utilization? (and how to improve it) (https://lendingclub.com/resource-center/personal-finance/what-is-credit-utilization-and-how-to-improve-it)
- How to Pay Off Credit Card Debt (https://money.com/how-to-pay-off-credit-card-debt)
- How Many Credit Cards Are in the USA in 2025 and Other Statistics? (https://clearlypayments.com/blog/how-many-credit-cards-are-in-the-usa-in-2025-and-other-statistics)
- Review and Dispute Errors on Your Credit Report
- How Common are Credit Report Errors? | McCarthy Law PLC (https://mccarthylawyer.com/2023/05/10/how-common-are-credit-report-errors)
- Study: 10 Million Americans Face Costly Credit Report Errors (https://debt.org/blog/study-suggests-you-check-credit-reports-for-inaccuracies)
- In FTC Study, Five Percent of Consumers Had Errors on Their Credit Reports That Could Result in Less Favorable Terms for Loans (https://ftc.gov/news-events/news/press-releases/2013/02/ftc-study-five-percent-consumers-had-errors-their-credit-reports-could-result-less-favorable-terms)
- Scary Stats About Your Mortgage Applicants’ Credit Reports and How to Fix Them (https://certifiedcredit.com/scary-stats-about-your-mortgage-applicants-credit-reports-and-how-to-fix-them)
- Almost half of participants in Credit Checkup study find errors on credit reports; more than a quarter find serious mistakes – CR Advocacy (https://advocacy.consumerreports.org/press_release/almost-half-of-participants-in-credit-checkup-study-find-errors-on-credit-reports-more-than-a-quarter-find-serious-mistakes)
- Consider Using a Secured Credit Card
- How much will a secured credit card raise my credit score? (https://lexingtonlaw.com/blog/credit-cards/how-much-will-a-secured-credit-card-raise-my-credit-score.html)
- 10 Quotes About Finance & Credit (https://creditonebank.com/articles/10-famous-quotes-about-finances-credit)
- Consumer demand is strong for secured credit cards (https://emarketer.com/content/strong-demand-secured-credit-cards-issuers)
- Cardholders Who Used Secured Credit Cards To Rebuild Credit | Bankrate (https://bankrate.com/credit-cards/building-credit/how-to-use-secured-credit-card-to-rebuild-credit)
- An Overview of Credit-Building Products (https://federalreserve.gov/econres/notes/feds-notes/an-overview-of-credit-building-products-20241206.html)
- Practice Patience and Consistency in Your Efforts
- How Long Does It Take To Increase Your Credit Score? | Bankrate (https://bankrate.com/credit-cards/bad-credit/how-long-does-it-take-to-get-a-credit-score-up)
- How Long it Takes to Improve Your Credit Score (https://lendingtree.com/credit-repair/how-long-does-it-take-to-improve-your-credit)
- 10 Quotes About Finance & Credit (https://creditonebank.com/articles/10-famous-quotes-about-finances-credit)
- How long does it take to rebuild credit? (https://lifelock.norton.com/learn/credit-finance/how-long-does-it-take-to-rebuild-credit?srsltid=AfmBOor2sHdwZFgmGeJtt7okg9GrM8s6ankIx8kF2_9MZX7PHS2E-xsI)
- Quotes About Credit Scores (https://pinterest.com/ideas/quotes-about-credit-scores/956203319670)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About Kevin