

Key Highlights:
- Setting up savings accounts for children fosters financial understanding and responsibility from a young age.
- Savings accounts teach essential skills like budgeting, investing, and the value of money.
- Bright Advisers offers personalised investment portfolios tailored to family financial goals.
- Gather essential documents, including Social Security number and birth certificate, to open a child’s investment account.
- Custodial accounts (UGMA/UTMA) manage assets until adulthood but may affect financial aid eligibility.
- 529 College Savings Plans provide tax advantages for education savings, with funds growing tax-deferred.
- Roth IRAs for kids allow tax-free growth for children with earned income, teaching long-term saving.
- Youth brokerage options provide hands-on investing experience for minors through reputable firms.
- Steps to open an investment account include choosing a brokerage, filling out an application, and funding the account.
- Educating children about investing involves explaining basic concepts, using real-life examples, and encouraging questions.
Introduction
Opening an investment account for your child is a wonderful step towards nurturing their financial literacy and responsibility from an early age. Imagine empowering them with essential skills that will serve them well into adulthood. By introducing children to the world of investing, families can create a foundation for a secure financial future.
However, we understand that the process can feel overwhelming. With various account types and required documentation to navigate, it’s easy to feel lost. It’s important to understand that you’re not alone in this journey. Many parents share similar concerns, and together, we can explore the best strategies to make this experience not only beneficial but also enriching.
Think about the lasting impact this can have on your child’s understanding of money management. By taking this step, you’re not just securing their financial future; you’re instilling values that will guide them throughout their lives. We’re here for you, ready to support you in making informed decisions that align with your family’s goals.
Let’s embark on this journey together, ensuring that your child grows up with a strong grasp of financial principles. Together, we can navigate the complexities of investing, making it a rewarding experience for both you and your child.
Understand the Importance of Investment Accounts for Children
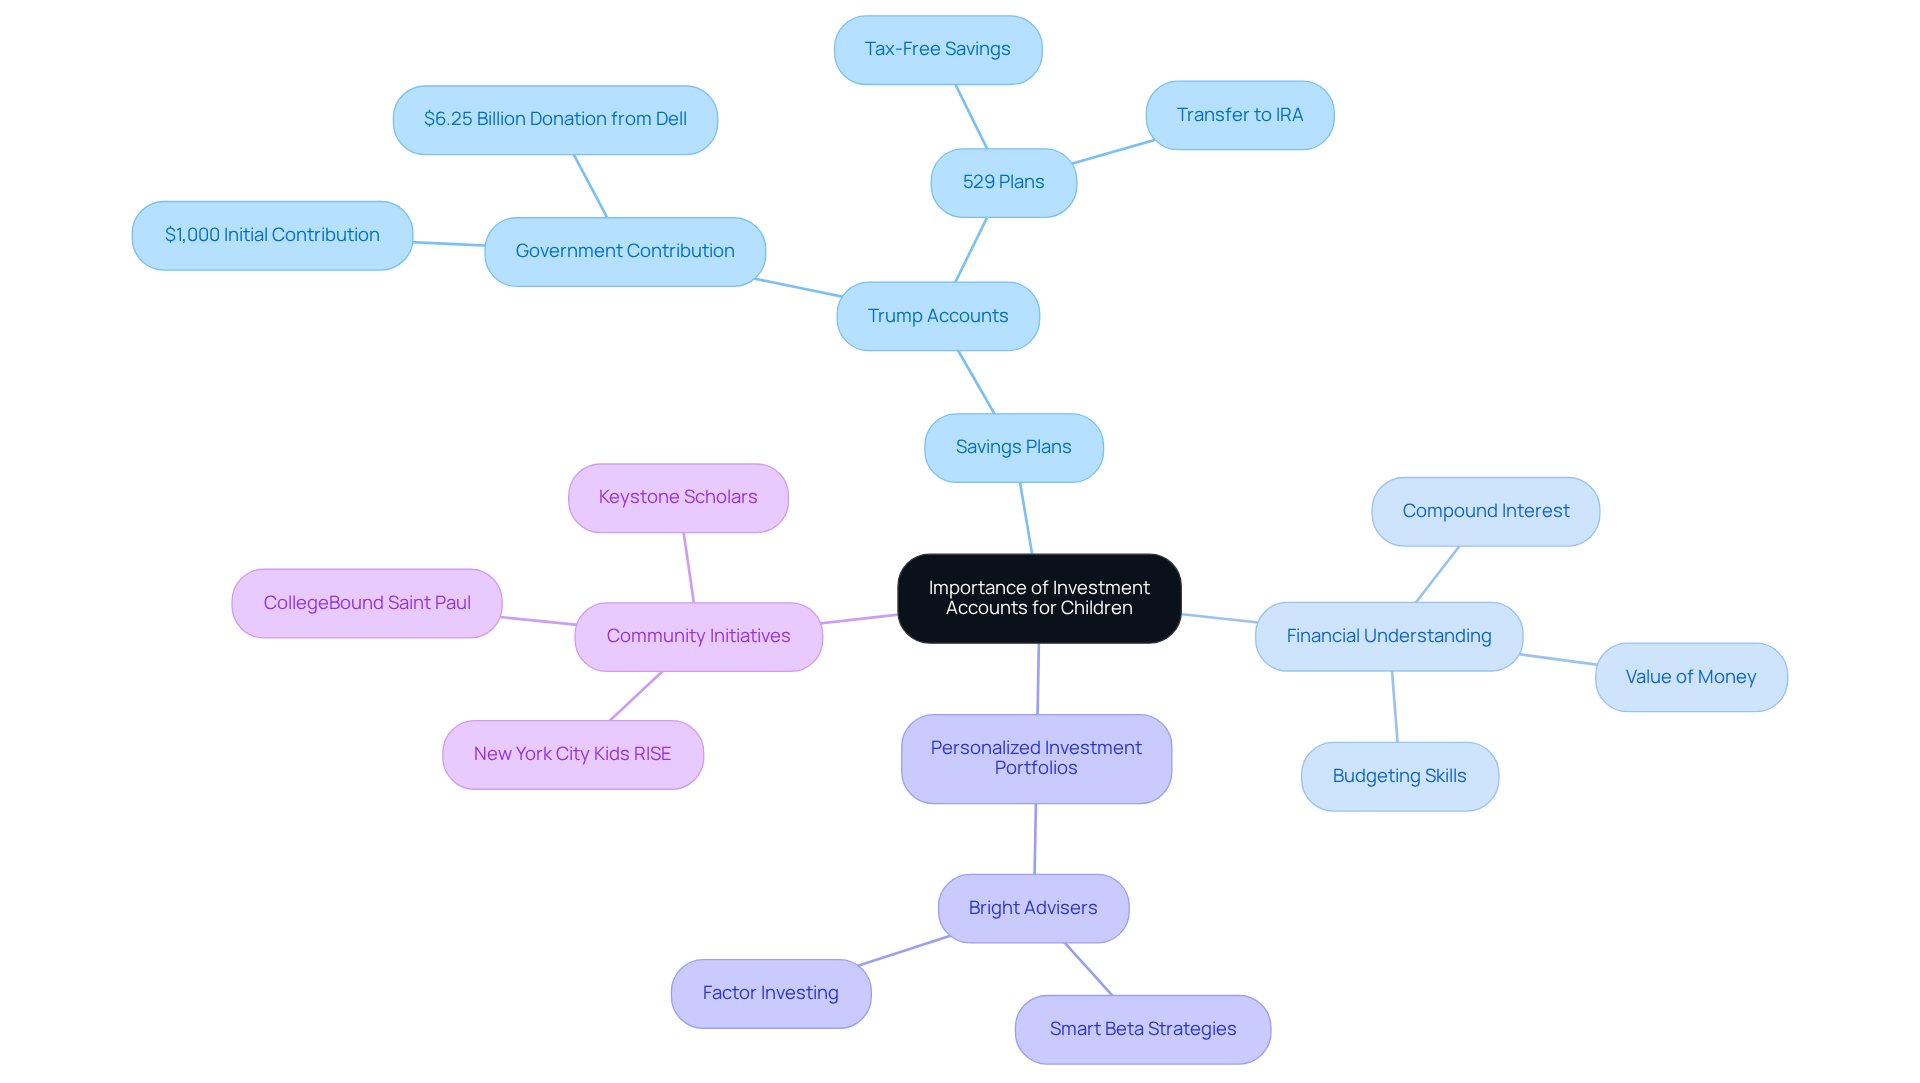
Setting up a savings plan for your children is more than just putting money aside; it lays the groundwork for their financial understanding and responsibility from a young age. Imagine your little ones grasping concepts like compound interest and the importance of saving for big milestones, like college or their first home. By starting this journey early, families can seize the right moments in the market, significantly boosting the growth potential of their savings.
Savings accounts can be wonderful tools for teaching kids essential money management skills, such as budgeting, investing, and appreciating the value of money. Bright Advisers takes this a step further by offering personalized investment portfolios that align with your family’s financial goals. Using advanced technology and strategies like smart beta and factor investing, they create tailored just for you.
Consider initiatives like Keystone Scholars and CollegeBound Saint Paul, which have successfully raised awareness and engagement in saving for education among families. These organized savings programs show how we can promote financial literacy together. By involving young people in these financial practices and leveraging Bright Advisers’ innovative strategies, you can help ensure a secure financial future for your children, equipping them with the knowledge and skills they need to navigate their financial journeys with confidence.
We’re here for you, ready to support you every step of the way. Together, we can navigate this journey toward financial security for your family.
Gather Required Information and Documentation
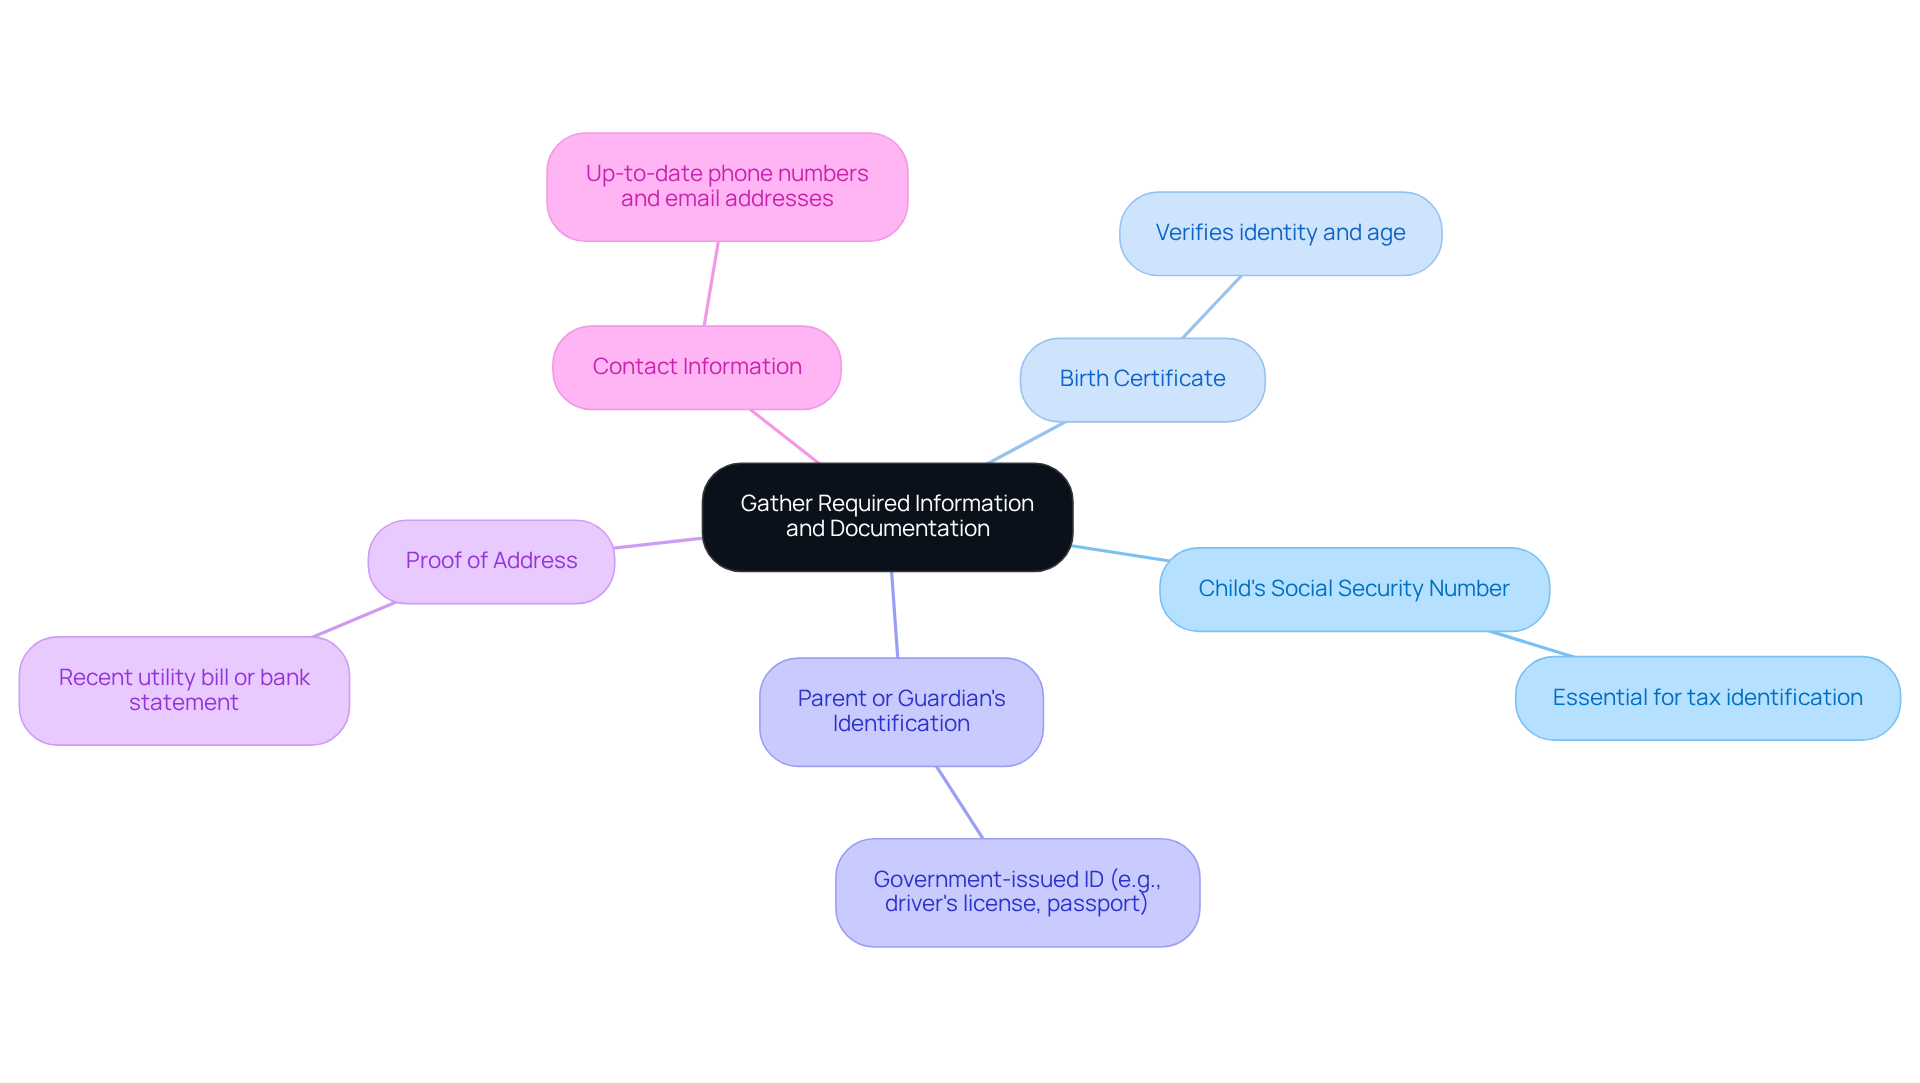
Opening an investment account for your child is an important step in securing their financial future. At Bright Advisers, we understand how crucial it is to lay a strong foundation for your family, and having the right documents ready is a vital part of that journey. Here’s what you’ll need:
- Child’s Social Security Number: This is essential for tax identification and setting up accounts.
- Birth Certificate: This document helps verify your child’s identity and age.
- Parent or Guardian’s Identification: A government-issued ID, like a driver’s license or passport, is necessary.
- Proof of Address: A recent utility bill or bank statement can confirm your current address.
- Contact Information: Make sure to have up-to-date phone numbers and email addresses for both you and your child.
Did you know that about 70% of parents have these documents ready when starting a kid’s investment fund? Being prepared can significantly ease anxiety and reduce processing delays. Financial advisors emphasize that having your paperwork organized can make creating a savings plan much smoother, allowing you to focus on what truly matters-your child’s financial future.
By gathering these documents in advance, you can simplify the process to open an investment account for your child and help guide them toward financial literacy and independence. Establishing a youth savings plan not only provides a financial advantage but also fosters essential money management skills that will benefit your child throughout their life.
Together, we can navigate this journey, ensuring your family is well-prepared for a .
Choose the Right Type of Investment Account
When it comes to choosing an open investment account for your child, it’s essential to explore the options that can best support their future. Here are some paths you might consider:
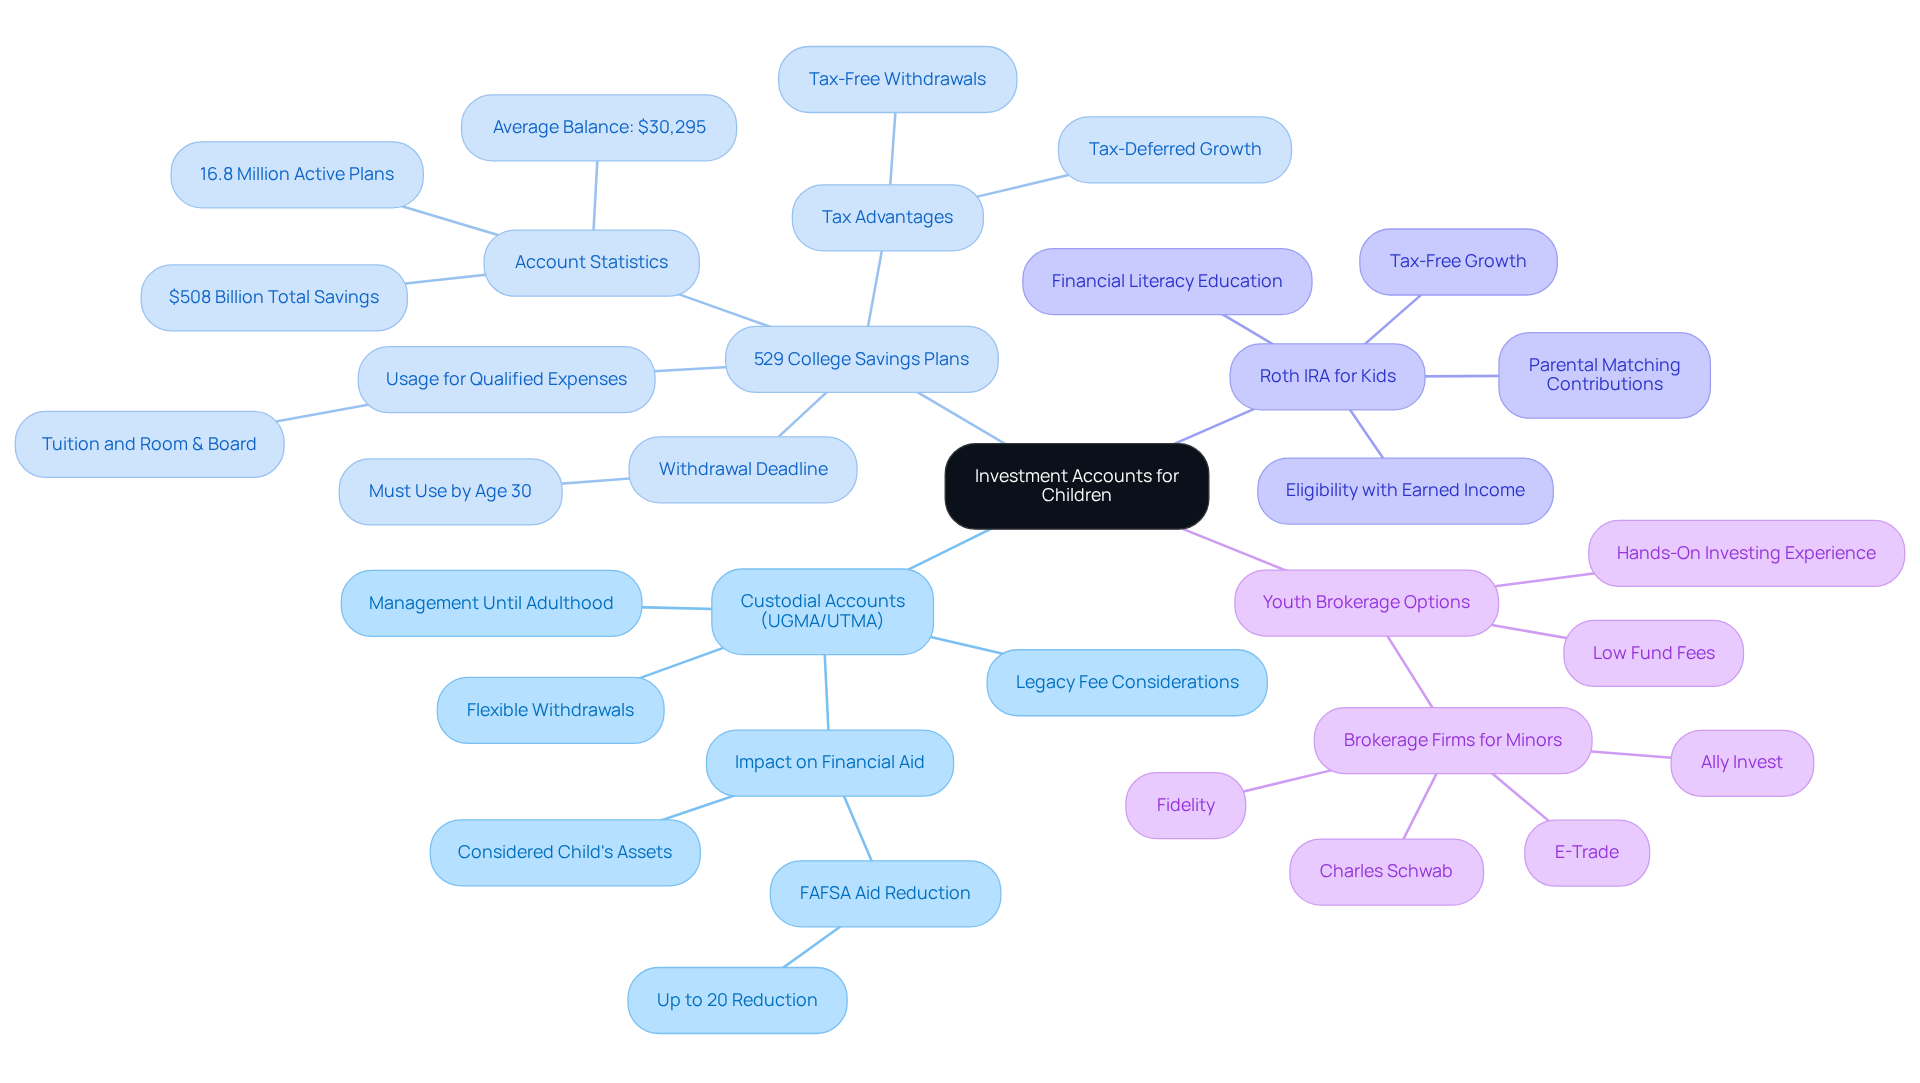
- Custodial Accounts (UGMA/UTMA): These accounts let you manage assets for your child until they reach adulthood. They can hold various investments, like stocks, bonds, and mutual funds. One of the great things about these accounts is that you can withdraw contributions anytime without penalty, giving you flexibility as your child’s needs change. However, keep in mind that assets in these accounts may impact financial aid eligibility, as they’re considered the child’s assets and could reduce FAFSA aid by up to 20%. Also, be aware of any legacy fee-bearing mutual funds you might have, as they can influence your overall investment strategy and costs.
- 529 College Savings Plans: Designed specifically for education savings, these plans offer tax advantages when funds are used for qualified expenses like tuition and room and board. Contributions grow tax-deferred, and withdrawals for eligible expenses are tax-free. With over 16.8 million across the country as of June 2024, totaling $508 billion in savings and an average balance of $30,295, they’re a popular choice for families wanting to secure their children’s educational future. Just remember, funds must be used by age 30 to avoid penalties, so planning is key.
- Roth IRA for Kids: If your child has earned income, a Roth IRA can be a fantastic way to save for retirement. Contributions are made with after-tax dollars, allowing for tax-free growth and withdrawals later on. This option not only teaches kids about investing but also highlights the importance of saving for long-term goals. Parents can even match contributions to encourage good saving habits, creating a valuable lesson in financial literacy.
- Youth Brokerage Options: Some brokerage firms, like Charles Schwab, E-Trade, Fidelity, and Ally Invest, offer services tailored for minors, allowing them to learn about investing firsthand. These portfolios can include a range of investment choices, from stocks to ETFs, providing a hands-on approach to financial education. Choosing a broker with low fund fees can enhance the experience for young investors, making wealth management more accessible for families.
Each of these options comes with its own set of advantages and challenges, so it’s important to consider your child’s future needs alongside your financial goals. Engaging in open conversations about money management can help normalize financial literacy in your home, guiding your child toward a successful financial future. Together, we can navigate this journey!
Open the Investment Account
Opening an investment account for a child can feel like a big step, but it’s a wonderful way to set them on a path toward financial knowledge and independence. Here’s how to get started:
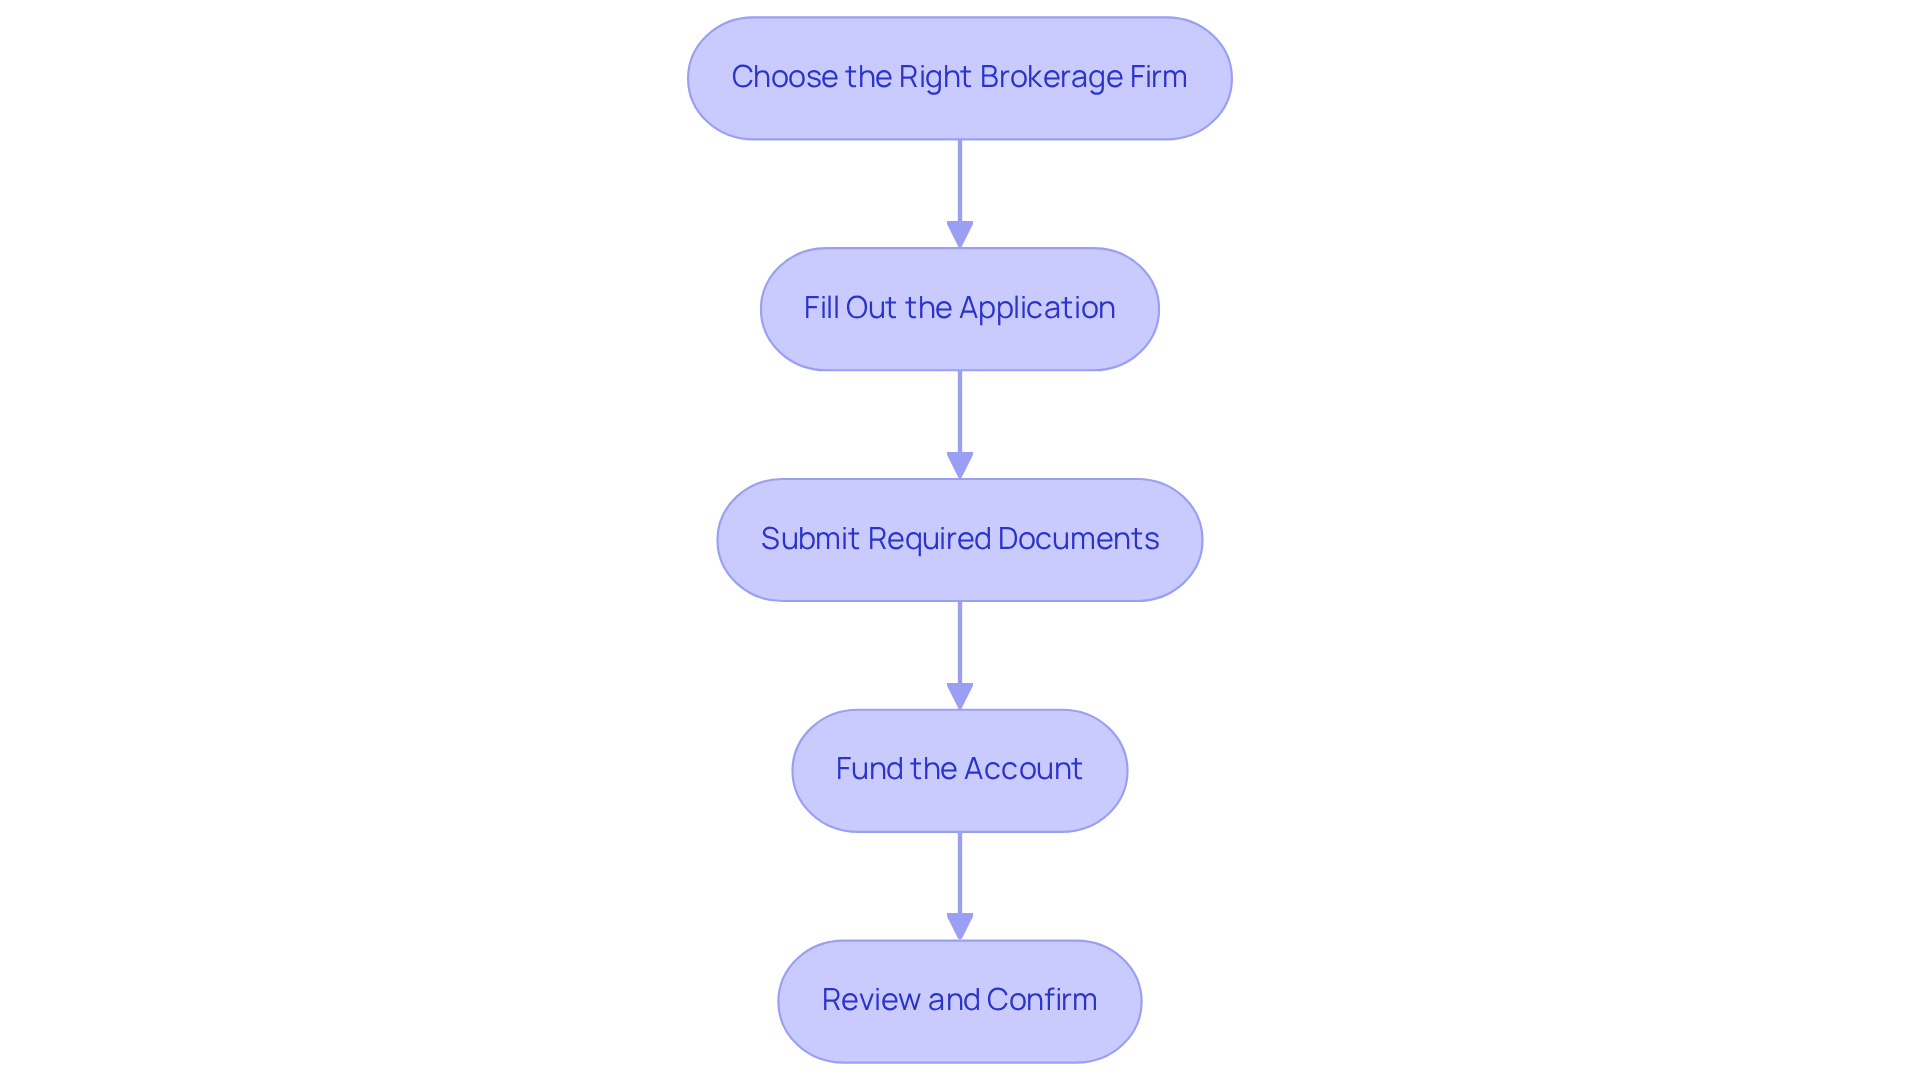
- Choose the Right Brokerage Firm: Take some time to research and select a reputable brokerage that offers the type of account you want to open, like a custodial account (UGMA or UTMA). Look for firms that provide educational resources and support for young investors, such as interactive platforms and financial literacy tools. Consider options like Bright Advisers, Fidelity, Charles Schwab, or E*TRADE. These firms cater to minors and offer valuable resources while keeping fund fees low, making wealth management more accessible for families.
- Fill Out the Application: Completing the application form is straightforward. Just make sure to provide all the necessary information about both your child and yourself as the parent or guardian. The good news? You can usually , which makes it super convenient.
- Submit Required Documents: You’ll need to upload or send in some important documents, including your child’s Social Security number and identification. Accuracy is key here to avoid any processing delays. Typically, it takes less than 15 minutes to establish a financial profile for minors, so you’ll be on your way in no time.
- Fund the Account: Decide how much you’d like to deposit initially. Many brokerages allow you to fund the account through bank transfers or checks, making it easy to get started. Bright Advisers even offers customized wealth management solutions to help families make informed choices about their assets.
- Review and Confirm: Once you’ve submitted the application, take a moment to review all the details for accuracy. You should receive a confirmation email once the profile is active, marking the exciting start of your child’s financial journey.
By following these steps, you’re not just opening an account; you’re taking the first steps to open an investment account for your child’s future. As Mark Zuckerberg wisely said, ‘The greatest risk is not taking any risk.’ Starting early can give your child a significant advantage. Remember, we’re here for you every step of the way, and together, we can navigate this journey toward financial empowerment.
Educate Your Child About Investing
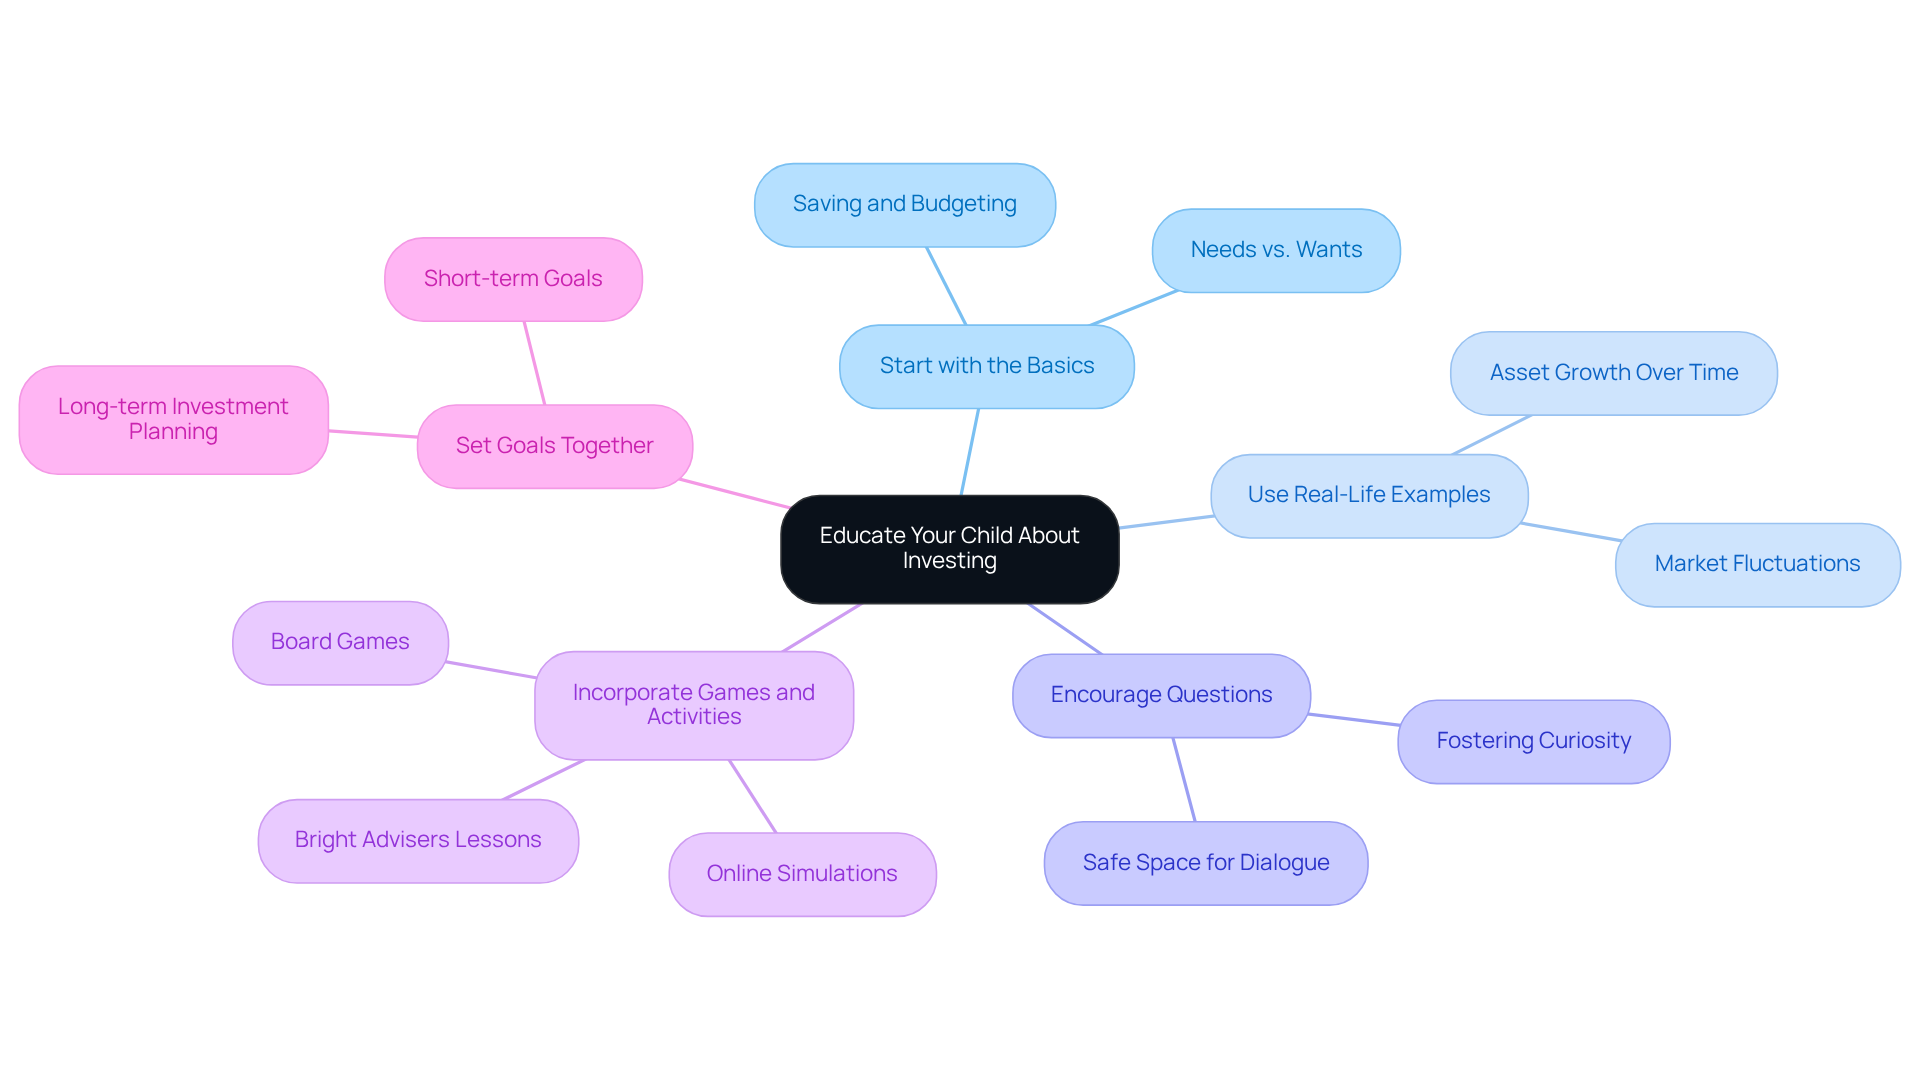
Once you open an investment account for your child, it’s time to gently introduce your child to the basics of investing. Here are some effective strategies to make this learning journey enjoyable and impactful:
- Start with the Basics: Begin by explaining essential concepts like saving, budgeting, and the difference between needs and wants. Use simple language and to make these ideas easy to grasp.
- Use Real-Life Examples: Show them how their assets can grow over time. Talk about market fluctuations and illustrate how investments can increase in value, helping them understand the economic world around them.
- Encourage Questions: Create a safe space where your child feels comfortable asking questions about money and investing. This open dialogue fosters critical thinking and curiosity about financial matters.
- Incorporate Games and Activities: Engage them with board games or online simulations that teach investing principles in a fun way. These interactive tools can make learning about finance enjoyable and memorable. Plus, Bright Advisers offers 30 on-demand interactive lessons designed to help young individuals manage their money wisely as they grow.
- Set Goals Together: Assist your child in setting financial goals, whether it’s saving for a toy or planning for a larger investment. This practice instills the importance of planning and patience in their financial journey.
By actively involving your child in their financial education, you’re laying a strong foundation for a lifelong understanding of investing. Together, we can navigate this journey, ensuring they’re well-prepared for the future.
Conclusion
Establishing an investment account for your child is a crucial step in nurturing their financial literacy and independence. This thoughtful approach not only equips them with essential money management skills but also lays a strong foundation for their future financial success. Imagine starting early – families can seize market opportunities and teach children the value of saving and investing, ultimately preparing them for significant milestones in life.
The article outlines a simple five-step process to open an investment account for your child, highlighting the importance of gathering necessary documentation, selecting the right type of account, and involving children in their financial education. From custodial accounts to 529 plans and Roth IRAs, each investment option offers unique benefits tailored to your child’s future needs. Plus, the strategies for educating children about investing – like using real-life examples and interactive games – ensure they not only understand but also appreciate the significance of financial planning.
In conclusion, investing in your child’s financial future is not just about the money; it’s about instilling a sense of responsibility and understanding that will serve them throughout their lives. By taking these steps, families can cultivate a culture of financial literacy, preparing the next generation to navigate their financial journeys with confidence. Together, we can embrace this opportunity to empower children with the knowledge and skills they need to thrive, ensuring they are well-equipped for a secure and prosperous future.
Frequently Asked Questions
Why is it important to set up investment accounts for children?
Setting up investment accounts for children lays the groundwork for their financial understanding and responsibility, teaching them concepts like compound interest and the importance of saving for milestones such as college or a first home.
How can savings accounts benefit children?
Savings accounts are effective tools for teaching kids essential money management skills, including budgeting, investing, and appreciating the value of money.
What services does Bright Advisers offer for children’s investment accounts?
Bright Advisers offers personalized investment portfolios that align with family financial goals, using advanced technology and strategies like smart beta and factor investing to create effective investment plans.
What are some initiatives that promote saving for education?
Initiatives like Keystone Scholars and CollegeBound Saint Paul have successfully raised awareness and engagement in saving for education among families, promoting financial literacy.
What documents are required to open an investment account for a child?
The required documents include the child’s Social Security Number, birth certificate, parent or guardian’s identification, proof of address, and current contact information for both the parent and child.
How does being prepared with documentation help when opening a child’s investment account?
Being prepared with the necessary documents can significantly ease anxiety, reduce processing delays, and make the process of creating a savings plan smoother.
What long-term benefits does establishing a youth savings plan provide?
Establishing a youth savings plan not only offers a financial advantage but also fosters essential money management skills that will benefit the child throughout their life.
List of Sources
- Understand the Importance of Investment Accounts for Children
- GoHenry | blog – not found (https://gohenry.com/us/blog/financial-education/40-quotes-to-help-your-child-learn-the-value-of-money)
- How Trump accounts for kids will work and more key details following Dell donation (https://cbsnews.com/news/trump-accounts-kids-explained)
- Unleashing the Power of Children’s Savings Accounts | Center on Assets, Education, and Inclusion (https://aedi.ssw.umich.edu/unleashing-the-power-of-children-savings-accounts)
- Gather Required Information and Documentation
- GoHenry | blog – not found (https://gohenry.com/us/blog/financial-education/40-quotes-to-help-your-child-learn-the-value-of-money)
- 4 Steps to Open a Kids Investing Account Successfully – Bright Advisers (https://brightadvisers.com/4-steps-to-open-a-kids-investing-account-successfully)
- Youth Accounts Map a Promising Path Forward for Banking Providers (https://thefinancialbrand.com/news/financial-education/the-kids-are-alright-youth-accounts-map-a-promising-path-forward-187314)
- 5 Steps to Open a Kid Investment Account for Your Child – Bright Advisers (https://brightadvisers.com/5-steps-to-open-a-kid-investment-account-for-your-child)
- Child Savings Accounts: Overview and Analysis (https://congress.gov/crs-product/R48554)
- Choose the Right Type of Investment Account
- Investing for kids: 7 investment account options – NerdWallet (https://nerdwallet.com/investing/learn/set-kids-brokerage-account)
- Make These 7 Investments To Set Your Kids Up For Life | Bankrate (https://bankrate.com/investing/7-investments-to-set-your-kids-up-for-life)
- College Saving Statistics [2025]: Average Savings & 529 Balance (https://educationdata.org/college-savings-statistics)
- Best Investment Accounts For Kids And Teens (https://kidvestors.co/post/investment-accounts-for-kids)
- Child Savings Accounts: Overview and Analysis (https://congress.gov/crs-product/R48554)
- Open the Investment Account
- Investing for kids: 7 investment account options – NerdWallet (https://nerdwallet.com/investing/learn/set-kids-brokerage-account)
- 4 Steps to Open a Kids Investing Account Successfully – Bright Advisers (https://brightadvisers.com/4-steps-to-open-a-kids-investing-account-successfully)
- 5 Amazing Investing Quotes To Share With Your Kids (https://bluetreesavings.com/post/5-amazing-investing-quotes)
- Educate Your Child About Investing
- Giving kids an early financial education pays off in the future (https://cnbc.com/2021/04/05/giving-kids-an-early-financial-education-pays-off-in-the-future.html)
- GoHenry | blog – not found (https://gohenry.com/us/blog/financial-education/40-quotes-to-help-your-child-learn-the-value-of-money)
- Teaching Kids about Investing for Financial Security (https://moneyfit.org/teaching-kids-about-investing)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Age Five Wealth Education for high-income W-2 families at Bright Advisers.
Keep reading