

Key Highlights
- Investing heavily in one company can jeopardise a family’s financial future due to market volatility.
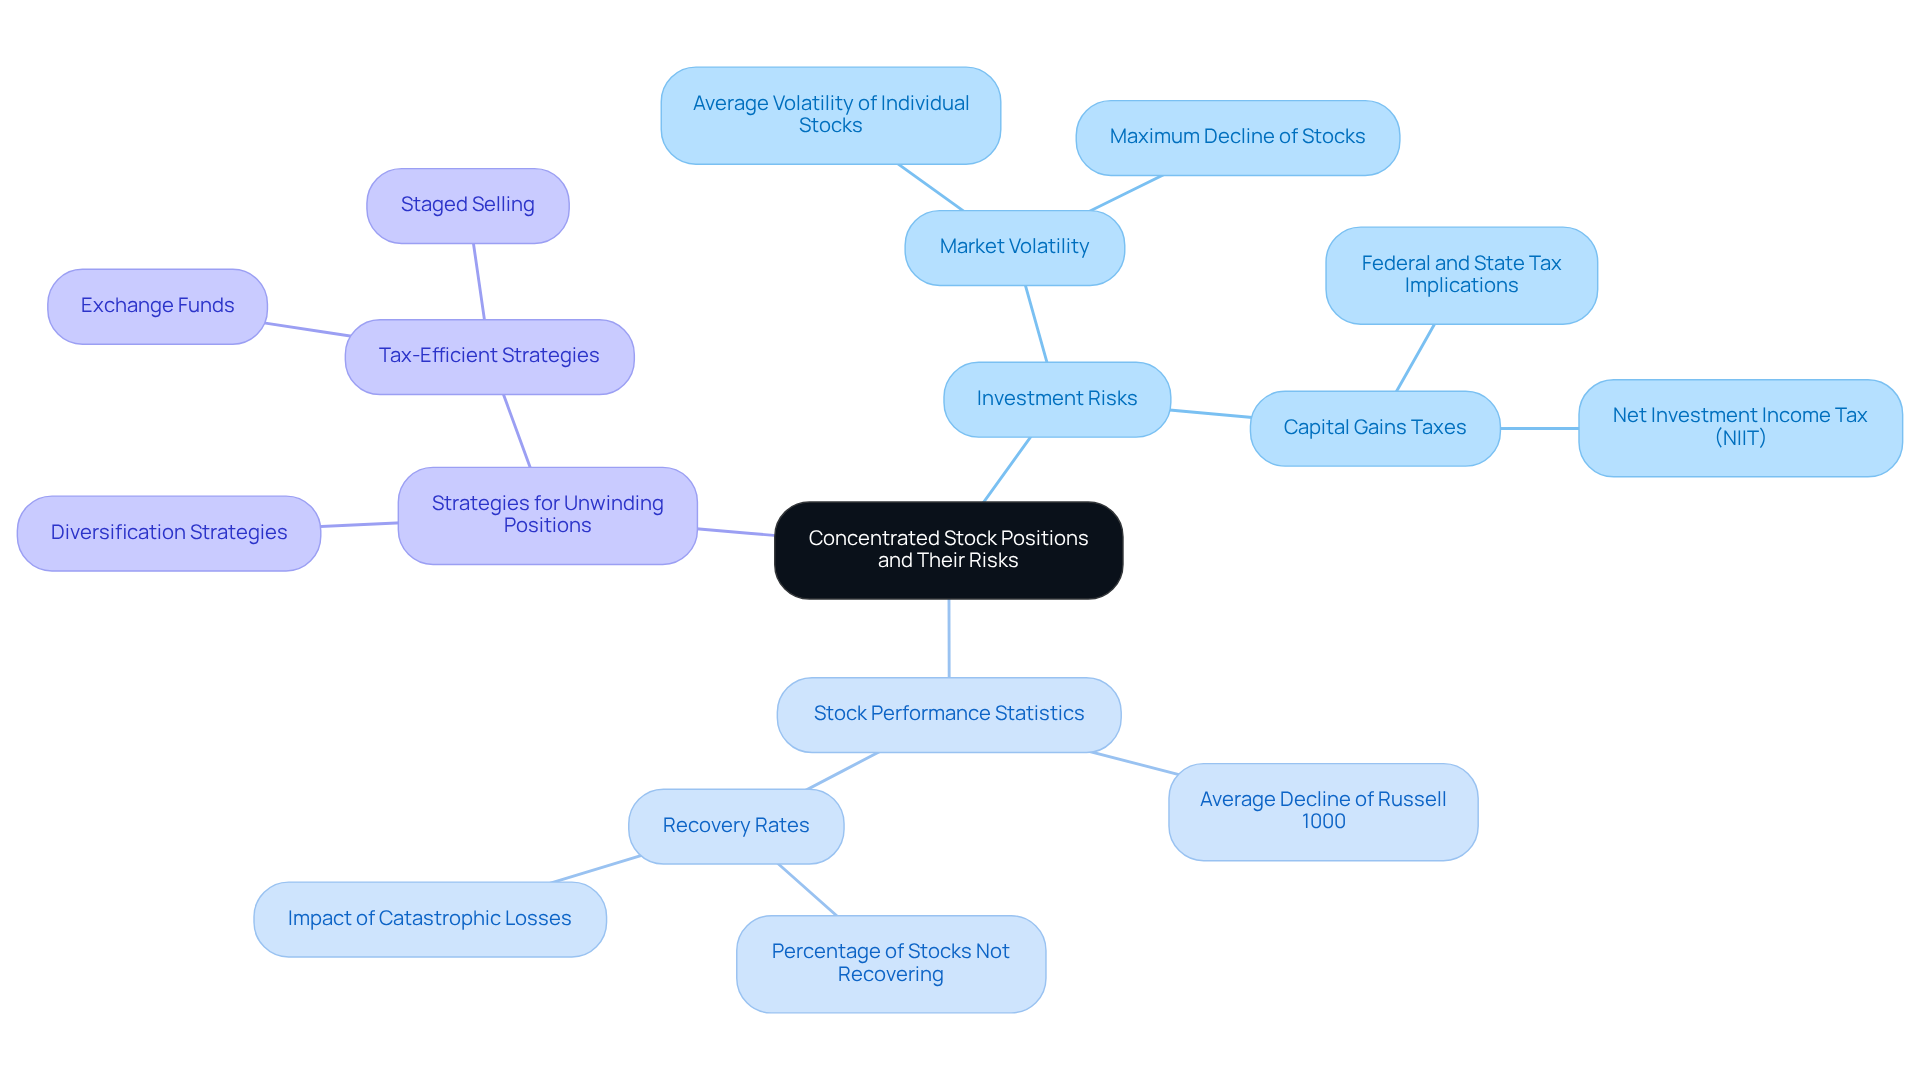
- The average stock in the Russell 1000 Index has seen declines of up to 50%, with 40% of stocks not recovering from such drops.
- Families should assess their exposure by calculating the total value of their equity and its percentage in their portfolio.
- Understanding risk tolerance is crucial, as concentrated investments can lead to significant stress during market fluctuations.
- Strategies for unwinding concentrated positions include gradual selling, tax-loss harvesting, and using exchange funds to defer taxes.
- Tax implications are significant; capital gains taxes can apply when selling appreciated shares, with rates varying based on income levels.
- Maintaining a balanced investment strategy post-unwinding involves diversification, regular rebalancing, and setting clear financial goals.
- Bright Advisers offers personalised strategies to help families manage concentrated stock positions and optimise their tax situations.
Introduction
Many families feel the pressure of having a single stock dominating their investment portfolio, which can bring both opportunities and challenges. It’s important for families to know how to gently transition away from a large stock holding, ensuring their financial future remains secure while managing the ups and downs of the market.
In this guide, we’ll share simple steps to help your family:
- Understand your investment exposure
- Explore ways to diversify
- Keep your portfolio balanced after making changes
So, how can your family smoothly shift from holding a concentrated stock to a more balanced and secure investment portfolio?
Understand Concentrated Stock Positions and Their Risks
Imagine putting your family’s future at risk by investing too heavily in one company. When you invest a large portion of your savings in just one company, it can feel like a big gamble for your family’s future. This can happen in different ways, like receiving stock options from your job or believing strongly in a company. While these investments can lead to great rewards if things go well, they also come with serious risks that can worry any parent.
For instance, the average stock in the Russell 1000 Index has faced a maximum decline of 50%, while the index itself has dropped only 25% at its worst. It’s concerning to note that 85% of stocks have seen a bigger drop than the Russell 1000 over the past decade. Even more alarming, nearly 40% of stocks that fell by 50% from their peak never fully recovered. This highlights the importance of understanding how to unwind a large concentrated stock position, as focused investments can be vulnerable, especially when market conditions shift or a company faces challenges.
Since 2014, individual stocks have been quite unpredictable, changing by an average of 37% each year, which can be stressful for families trying to plan ahead. Additionally, knowing how to unwind a large concentrated stock position might lead to significant capital gains taxes at both federal and state levels, including the Net Investment Income Tax (NIIT). Understanding these risks can help you protect your family’s financial future, ensuring you can focus on what truly matters. Consulting a financial advisor for personalized strategies can also be a great way to navigate these complexities together.
Assess Your Exposure and Risk Levels
Have you ever wondered how your investments could impact your family’s future? Understanding your focused equity holdings is a crucial step in ensuring financial security for your loved ones.
-
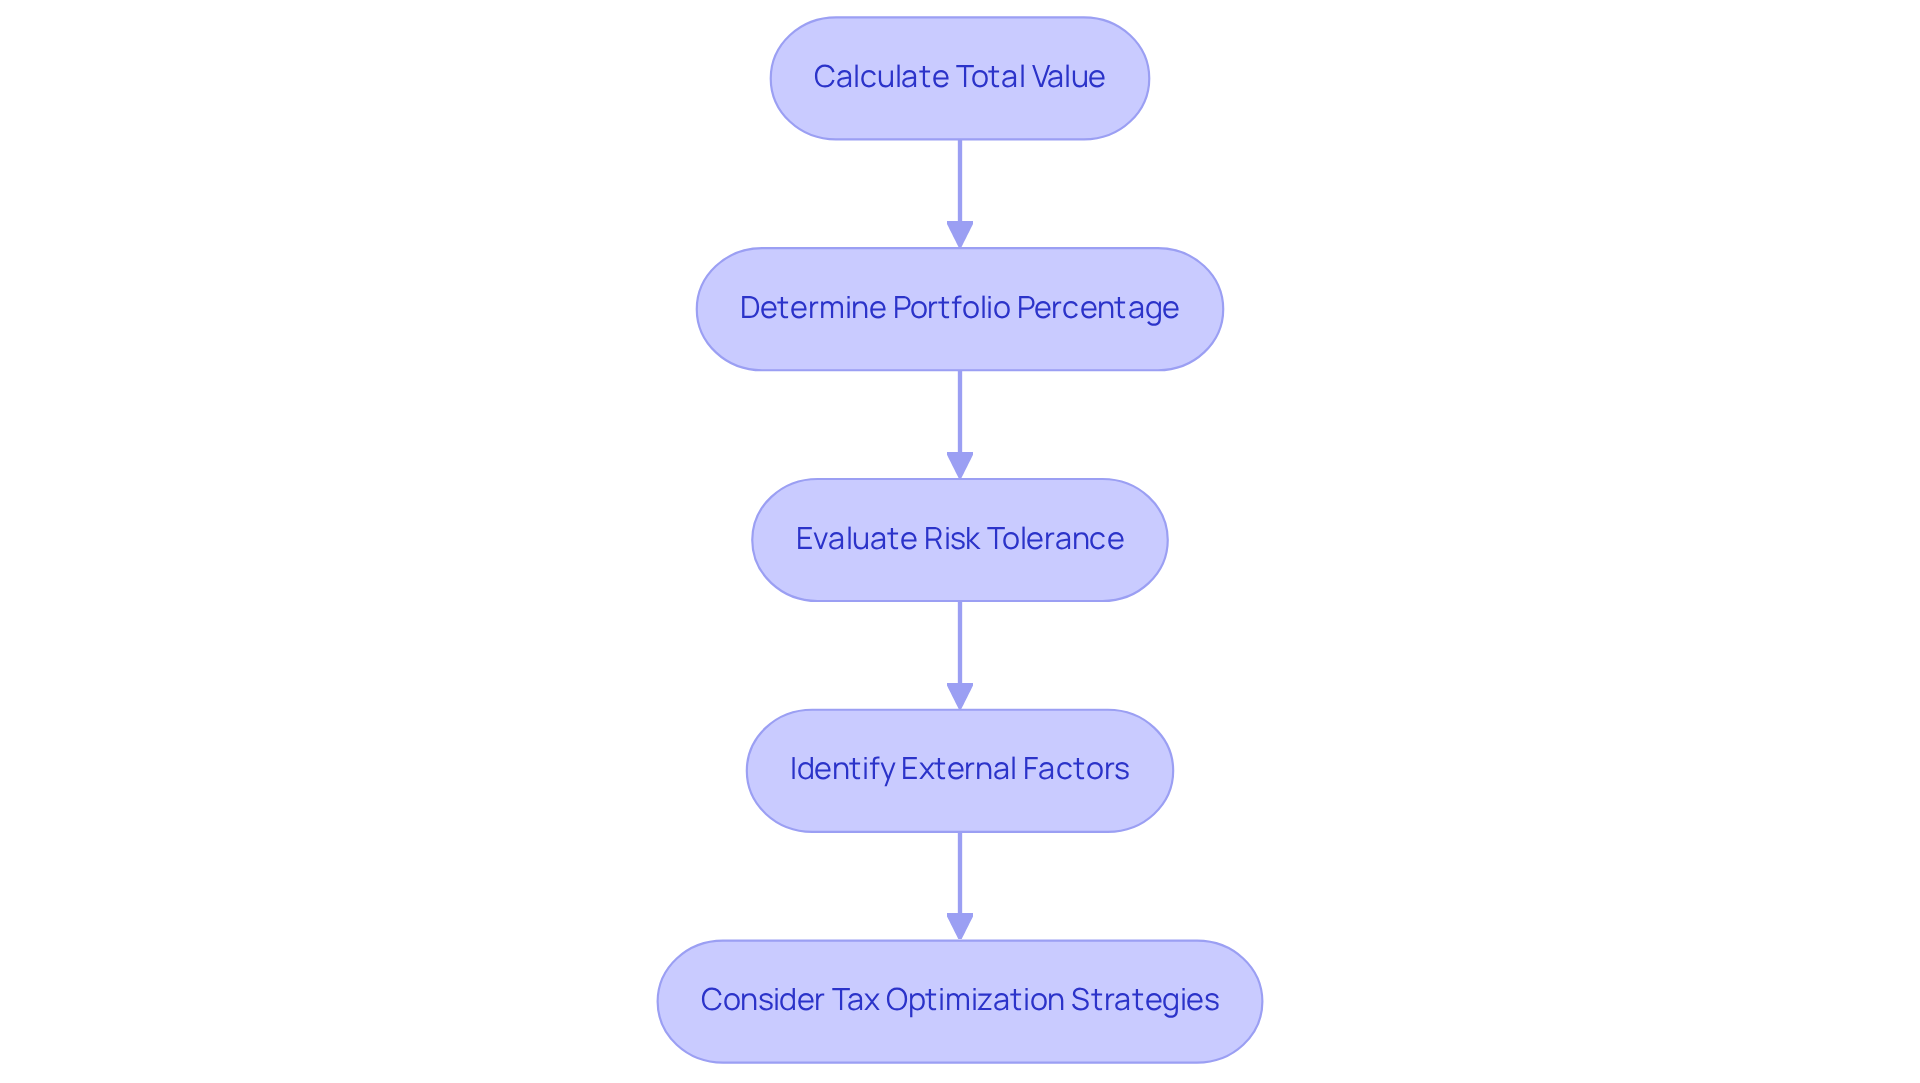
Calculate Total Value: Start by determining the current market worth of your equity. Multiply the number of shares you own by the current share price. This gives you a clear picture of what you have.
-
Determine Portfolio Percentage: Next, find out what portion of your total investment portfolio is tied up in this equity. If one investment makes up a large part of your portfolio, it’s important to understand the risks involved.
-
Evaluate Risk Tolerance: Reflect on your comfort level with potential fluctuations. Investing in just one stock can be risky, as its value can change a lot more than a mix of different investments. Imagine the stress of a sudden drop in your investment and how it could affect your family’s dreams and security. For context, to fund $1MM of annual living expenses to age 90, approximately $35MM in a diversified balanced allocation is needed.
-
Identify External Factors: Research any external elements that could influence the performance of your shares, such as market trends or economic conditions. Since 2014, individual equities in the Russell 1000 Index have shown an average annual volatility of 37%, compared to just 15% for the index as a whole. Taking a close look at your investments can help you see where you stand and why it might be time to make some changes.
-
Consider Tax Optimization Strategies: Working with Bright Advisers can help you find smart ways to manage your taxes while you adjust your investments. This can enhance your overall financial strategy and help secure your family’s future.
By routinely evaluating your focused investment holdings and integrating tax efficiency strategies, you can learn how to unwind a large concentrated stock position, enabling you to make knowledgeable choices that align with your financial goals and reduce risks linked to overexposure to a single asset. For families like Jay & Emma, Emily & Mark, and Allison & Brian, working with Bright Advisers has provided them with personalized strategies that not only address their immediate financial concerns but also set them on a path toward long-term security and educational readiness for their children. Bright Advisers’ expertise in tax optimization and comprehensive financial planning can help you navigate these complexities effectively.
By taking these steps, you can ensure a brighter future for your loved ones, filled with opportunities and security.
Explore Strategies for Unwinding Concentrated Positions
Imagine feeling the weight of your concentrated stock position and wondering how to unwind a large position concentrated stock position to secure your family’s financial future. When unwinding a concentrated stock position, consider these gentle strategies:
-
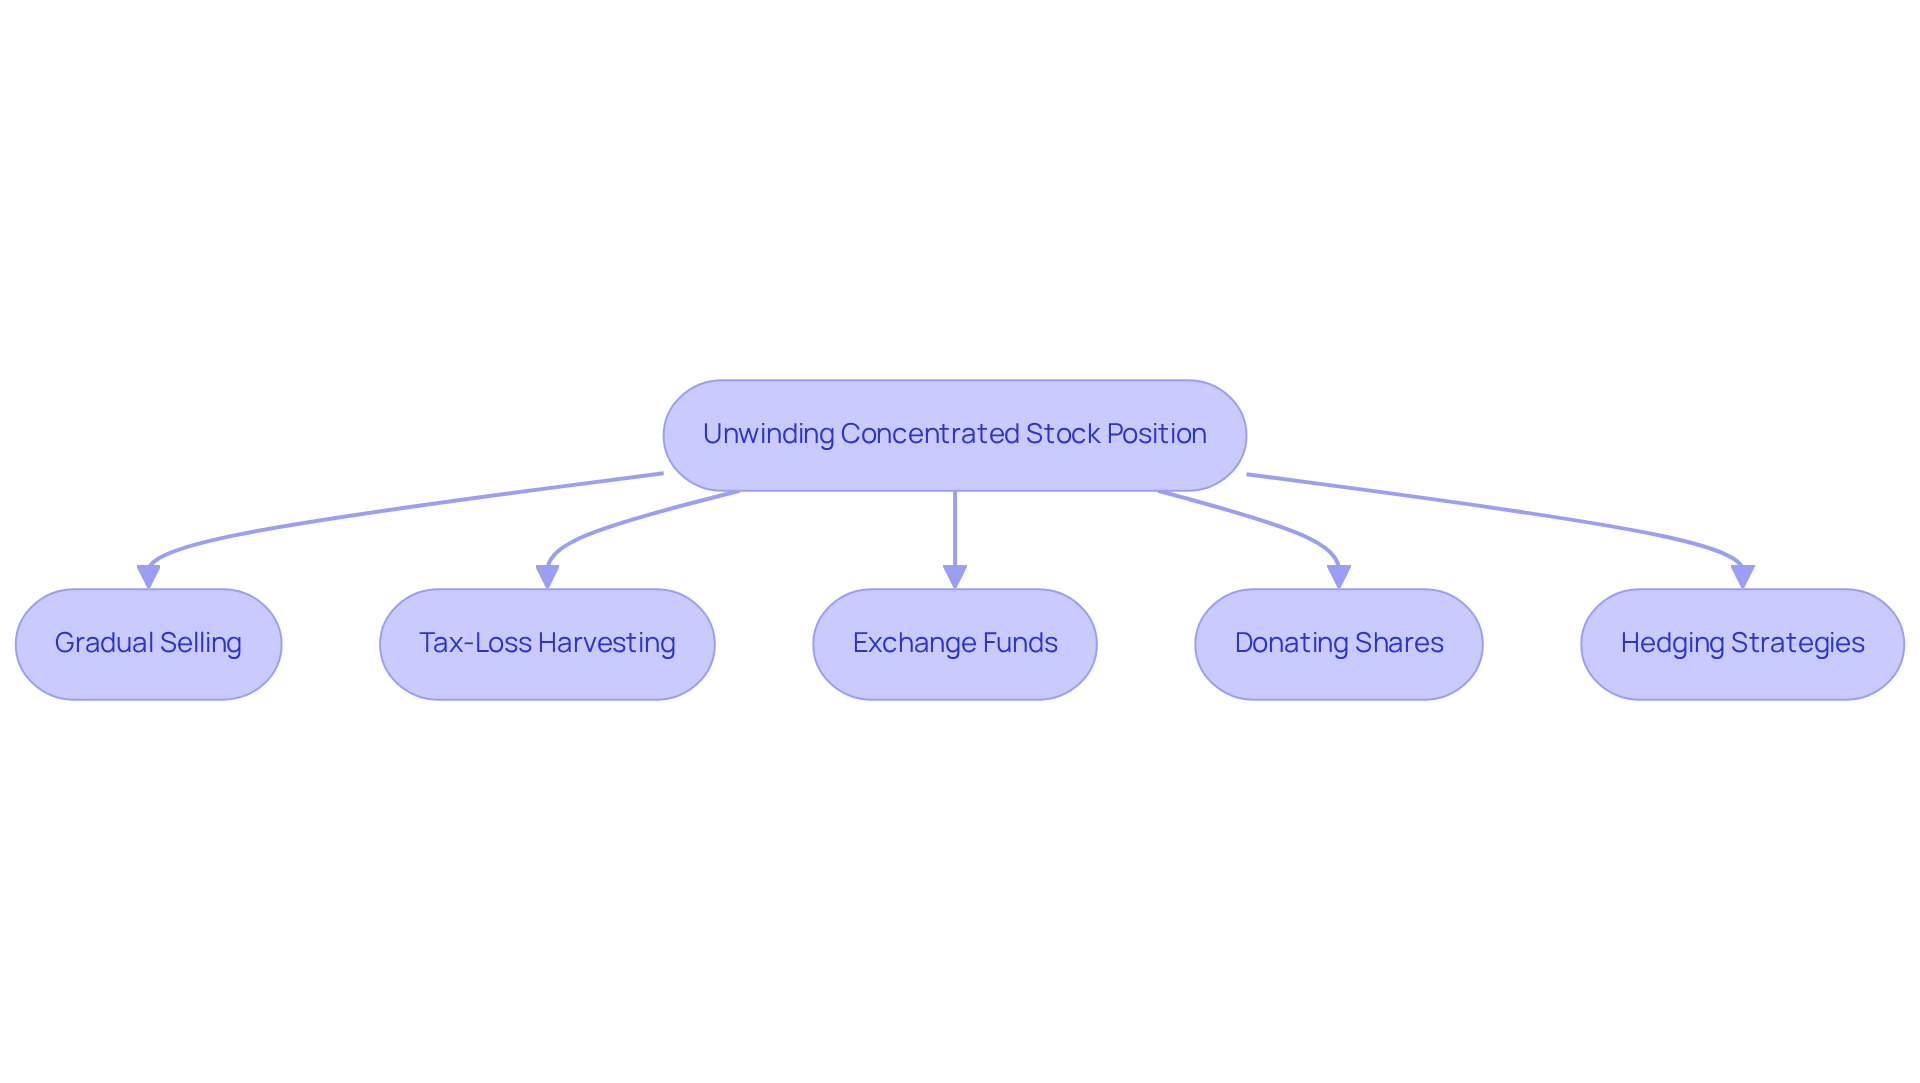
Gradual Selling: Instead of liquidating your entire position at once, think about a phased approach. Selling portions of your shares over time can help ease the impact of market fluctuations and reduce tax liabilities. This method allows for a more measured response to market conditions, which can help you understand how to unwind a large position concentrated stock position with less stress.
-
Tax-Loss Harvesting: If you have other investments that aren’t performing well, consider selling them at a loss to offset the gains from your focused equity sale. This strategy can effectively lighten your overall tax burden, especially in high-tax states where capital gains can be taxed at rates up to 37%, which is important to consider when thinking about how to unwind a large position concentrated stock position. It’s a smart way to keep more of your hard-earned money.
-
Exchange Funds: These funds let you swap your focused shares for interests in a diversified fund without triggering immediate capital gains taxes. This method helps you understand how to unwind a large position concentrated stock position while deferring tax liabilities, but remember, it usually requires a commitment of at least seven years. It’s a long-term strategy that can pay off.
-
Donating Shares: Consider donating shares to family members or charities. This can help reduce your significant stake while providing potential tax advantages. This strategy not only assists in estate planning but also illustrates how to unwind a large position concentrated stock position, enabling future appreciation to shift to recipients who may be in a lower tax bracket, thereby lowering the overall family tax burden.
-
Hedging Strategies: Use options to protect against potential losses in your focused equity holdings. This can provide a safety net while you gradually learn how to unwind a large position concentrated stock position, allowing you to manage risk effectively without sacrificing liquidity.
Navigating the world of investments can feel overwhelming, especially when it comes to making decisions about your family’s future. With these strategies, you can navigate the complexities of your investments, making it easier to focus on your family’s needs. By taking these steps, you can create a more secure financial future for your family, allowing you to focus on what truly matters.
Consider Tax Implications and Strategies
Imagine facing the daunting task of how to unwind a large concentrated stock position while trying to secure your family’s financial future. It’s essential to consider the tax implications that come with this process.
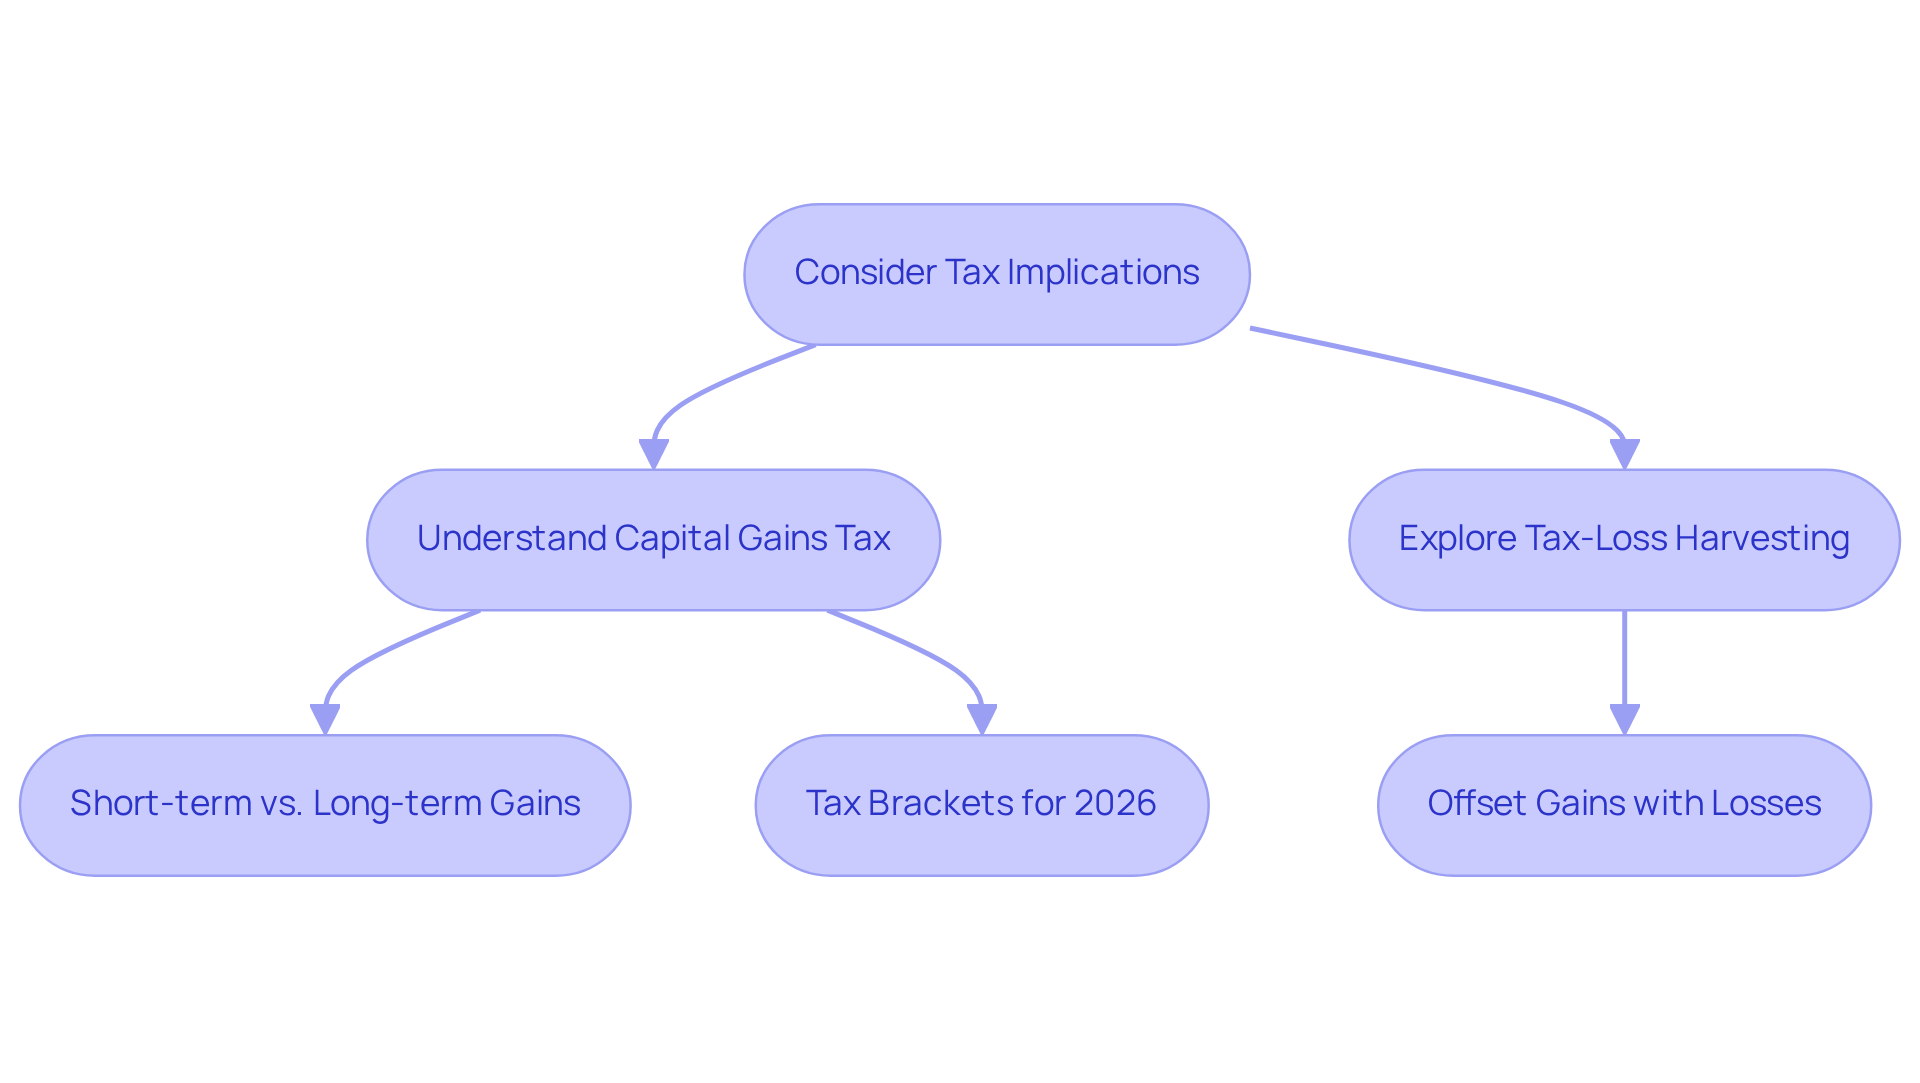
When you sell shares that have increased in value, it can lead to capital gains taxes on those profits. Understanding your tax bracket and the potential impact is crucial. For 2026, long-term capital gains tax rates for single filers are:
- 15% for income up to $49,450
- 20% for income over $545,500
Knowing whether your gains are short-term or long-term can empower you to make smarter decisions about selling, ensuring you keep more of what you’ve earned for your family. If you hold the shares for more than a year, you may qualify for lower long-term capital gains tax rates. Planning your sales accordingly can enhance tax efficiency.
Another strategy to consider is tax-loss harvesting. This involves offsetting gains with losses from other investments, effectively reducing your overall tax liability. Remaining net losses can offset ordinary income up to $3,000, making this strategy particularly effective in a volatile market.
We recommend reaching out to a tax professional who can guide you through these complexities with personalized advice. Given the intricacies of tax laws, their expertise can help you reduce your tax burden while understanding how to unwind a large concentrated stock position. Additionally, high-income earners may encounter an extra 3.8% net investment income tax (NIIT) on investment earnings, which is a significant factor for families managing large equity holdings.
By understanding these tax implications, you can make informed decisions that protect your family’s wealth for years to come.
Maintain a Balanced Investment Strategy Post-Unwinding
Imagine feeling secure about your family’s financial future, even amidst the chaos of daily life. After understanding how to unwind a large concentrated stock position, maintaining a balanced investment strategy is essential.
-
Diversification: It’s crucial to ensure your portfolio spans various asset classes, sectors, and geographic regions. This approach not only reduces risk but also enhances potential returns, preventing overexposure to any single investment. Think about using low-fee-bearing ETFs as a smart way to achieve this diversification while keeping costs minimal.
-
Regular Rebalancing: Periodically checking in on your portfolio and adjusting it helps maintain your desired asset allocation. This practice is vital for managing risk and ensures that you’re not overly reliant on any one investment, especially after significant changes in your holdings. By focusing on minimal fund fees, you can maximize your investment returns through disciplined rebalancing.
-
Set Clear Financial Goals: Clearly defining your long-term financial objectives and aligning your investment strategy accordingly is key. This focus will guide your decisions and help you navigate market fluctuations with confidence.
-
Stay Informed: Keeping up with market trends and economic conditions that may affect your investments is important. Regularly checking in on your portfolio and adjusting your strategy as necessary allows you to adapt to changing circumstances effectively.
-
Case Studies on Balanced Strategies: For instance, families who stick to a disciplined rebalancing schedule often avoid emotional decision-making, leading to better long-term outcomes. Additionally, maintaining a diversified portfolio can help mitigate risks associated with understanding how to unwind a large concentrated stock position. The case study titled “The Importance of Risk Management” illustrates how disciplined rebalancing can help families avoid emotional decision-making, leading to better long-term outcomes.
Together, by embracing these strategies, your family can navigate the investment landscape with confidence, all while enjoying the support of Bright Advisers’ commitment to keeping costs low. With the right strategies in place, you can transform your financial worries into a path toward stability and growth for your family.
Conclusion
Many families feel overwhelmed by the intricacies of managing concentrated investments, but there’s hope. Understanding how to unwind a large concentrated stock position is essential for safeguarding your family’s financial future. By taking deliberate steps to assess your exposure, explore unwinding strategies, and consider tax implications, families can navigate these complexities with greater confidence. This proactive approach not only mitigates risks but also sets the stage for a more balanced and diversified investment strategy.
Key insights from this guide emphasize the importance of:
- Gradual selling
- Tax-loss harvesting
- Maintaining a diversified portfolio
Each strategy serves to reduce potential tax burdens and enhance overall financial security. Families like Jay & Emma and Emily & Mark have successfully leveraged these strategies with the guidance of Bright Advisers, illustrating the tangible benefits of informed decision-making in wealth management.
As you navigate this journey, remember that learning and adapting is part of the process. By prioritizing diversification, regular portfolio rebalancing, and clear financial goals, families can transform concentrated stock positions into opportunities for growth and security. Engaging with a fiduciary advisor like Bright Advisers can further empower families to make wise wealth decisions, ensuring a brighter future for generations to come. By taking these steps, you’re not just protecting your wealth; you’re nurturing your family’s future.
Frequently Asked Questions
What are concentrated stock positions and why are they risky?
Concentrated stock positions occur when a significant portion of your savings is invested in one company, which can jeopardize your family’s financial future. While these investments can yield high rewards, they also carry serious risks, especially if the company faces challenges or market conditions shift.
What statistics highlight the risks of concentrated stock positions?
The average stock in the Russell 1000 Index has experienced a maximum decline of 50%, while the index itself has dropped only 25% at its worst. Additionally, 85% of stocks have seen larger declines than the Russell 1000 over the past decade, and nearly 40% of stocks that fell by 50% from their peak never fully recovered.
How can I assess my exposure and risk levels related to concentrated stock positions?
To assess your exposure, calculate the total value of your equity by multiplying the number of shares you own by the current share price. Then, determine what percentage of your total investment portfolio is tied to this equity. Reflect on your risk tolerance and consider external factors that could influence your shares’ performance.
What is the average annual volatility of individual stocks compared to the overall index?
Since 2014, individual equities in the Russell 1000 Index have shown an average annual volatility of 37%, compared to just 15% for the index as a whole.
What are the potential tax implications of unwinding a concentrated stock position?
Unwinding a large concentrated stock position may lead to significant capital gains taxes at both federal and state levels, including the Net Investment Income Tax (NIIT).
How can I manage the risks associated with concentrated stock positions?
Regularly evaluate your focused investment holdings and consider tax optimization strategies. Consulting a financial advisor, like those at Bright Advisers, can help you develop personalized strategies to manage your investments and reduce risks linked to overexposure to a single asset.
What role does Bright Advisers play in managing concentrated stock positions?
Bright Advisers provides expertise in tax optimization and comprehensive financial planning, helping families navigate the complexities of concentrated stock positions and develop strategies that align with their financial goals.
List of Sources
- Understand Concentrated Stock Positions and Their Risks
- Strategies for Managing a Concentrated Stock Position | BlackRock (https://blackrock.com/us/financial-professionals/investments/products/managed-accounts/concentrated-stock)
- Is Your Portfolio Too Concentrated? | Morgan Stanley (https://morganstanley.com/articles/diversify-risks-concentrated-positions)
- The Hidden Risk of Success: Managing Concentrated Stock Positions (https://fragassoadvisors.com/the-hidden-risk-of-success-managing-concentrated-stock-positions)
- Turn concentrated stock risk into potential tax-savings reward (https://am.jpmorgan.com/us/en/asset-management/adv/investment-strategies/separately-managed-accounts/tax-managed-solutions/concentrated-stock-risk)
- Assess Your Exposure and Risk Levels
- Managing concentrated stocks? Understand the risk and strategies (https://usecache.com/companion/concentrated-portfolio-risk-stock-strategies)
- Worried you may own too much of one stock? | J.P. Morgan Private Bank U.S. (https://privatebank.jpmorgan.com/nam/en/insights/wealth-planning/worried-you-may-own-too-much-of-one-stock)
- Standard Deviation, Beta, Alpha, and Sharpe Ratio Explained for Advisors (https://icfs.com/specialists-desk/risk-metrics-explained)
- Is Your Portfolio Too Concentrated? | Morgan Stanley (https://morganstanley.com/articles/diversify-risks-concentrated-positions)
- Concentrated Stock Position Calculator | Parametric Portfolio Associates (https://parametricportfolio.com/tools/concentrated-stock-position-calculator)
- Explore Strategies for Unwinding Concentrated Positions
- 5 Effective Ways to Diversify a Concentrated Stock Position (https://usecache.com/companion/diversify-concentrated-position)
- Tax-Efficient Ways to Diversify Concentrated Stock Positions (https://financialplanningassociation.org/learning/publications/journal/OCT24-tax-efficient-ways-diversify-concentrated-stock-positions-OPEN)
- Concentrated positions | Fidelity Investments (https://fidelity.com/learning-center/wealth-management-insights/diversify-concentrated-positions)
- Is Your Portfolio Too Concentrated? | Morgan Stanley (https://morganstanley.com/articles/diversify-risks-concentrated-positions)
- Turn concentrated stock risk into potential tax-savings reward (https://am.jpmorgan.com/us/en/asset-management/adv/investment-strategies/separately-managed-accounts/tax-managed-solutions/concentrated-stock-risk)
- Consider Tax Implications and Strategies
- 2026 Tax Brackets (https://taxfoundation.org/data/all/federal/2026-tax-brackets)
- Capital gains tax: Definition, rates, and ways to save | Fidelity (https://fidelity.com/learning-center/smart-money/capital-gains-tax-rates)
- Capital Gains Tax Rates: Short-term vs. Long-term (https://schwab.com/learn/story/how-are-capital-gains-taxed)
- What is capital gains tax? | Vanguard (https://investor.vanguard.com/investor-resources-education/taxes/realized-capital-gains)
- Maintain a Balanced Investment Strategy Post-Unwinding
- Strategies for Managing Concentrated Stock in a Diversified Portfolio (https://marinerwealthadvisors.com/insights/strategies-for-managing-concentrated-stock-in-a-diversified-portfolio)
- The Top 25 Investing Quotes of All Time (https://investopedia.com/financial-edge/0511/the-top-17-investing-quotes-of-all-time.aspx)
- Rebalancing your portfolio: How to rebalance | Vanguard (https://investor.vanguard.com/investor-resources-education/portfolio-management/rebalancing-your-portfolio)
- How Often Should I Rebalance My Portfolio? – Retirement Researcher (https://retirementresearcher.com/rebalancing-frequency)
- Strategies for Managing a Concentrated Stock Position | BlackRock (https://blackrock.com/us/financial-professionals/investments/products/managed-accounts/concentrated-stock)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Estate Planning for high-income W-2 families at Bright Advisers.
Keep reading