

Overview
The seven essential UTMA account withdrawal rules for parents focus on ensuring that withdrawals directly benefit your child. Misuse of these funds can lead to legal complications, which is a concern for many caring parents. It’s crucial to keep accurate records of withdrawals, understand the tax implications, and engage your children in financial discussions. This approach not only fosters responsible management as they approach adulthood but also strengthens family values and shared goals.
Imagine if you could navigate this journey together, feeling confident in your financial decisions. By following these guidelines, you can create a supportive environment that nurtures your child’s future. Remember, we’re here for you, and together, we can ensure that your family’s financial planning aligns with your values.
Key Highlights:
- Bright Advisers offers personalised financial planning for families managing UTMA accounts, focusing on customised strategies to secure children’s financial futures.
- Withdrawals from UTMA accounts must directly benefit the child, and misuse of funds can lead to legal complications.
- Keeping detailed records of withdrawals is essential to ensure compliance with the intended use of custodial funds.
- The first $1,350 of unearned income from UTMA accounts is tax-free for the child, with specific tax implications for higher amounts.
- The age of majority for UTMA accounts varies by state, typically between 18 and 21, after which the child gains full control of the funds.
- Custodians must manage UTMA funds ethically, prioritising the child’s well-being and maintaining transparency in financial dealings.
- When choosing between UTMA and UGMA accounts, parents should consider the types of assets they wish to manage and the associated tax implications.
- There are no set contribution limits for UTMA accounts, but contributions over $19,000 may incur gift tax implications.
- Custodial assets can impact a child’s financial aid eligibility, as 20% of the custodial fund’s value is considered in aid calculations.
- Parents should engage their children in discussions about financial responsibility as they approach adulthood, fostering money management skills.
Introduction
Navigating the complexities of custodial accounts can feel overwhelming for parents. It’s especially challenging to grasp the rules surrounding UTMA withdrawals. With the potential for legal complications and the vital task of safeguarding a child’s financial future, understanding the essential withdrawal guidelines becomes crucial.
Imagine if you could navigate these waters with confidence, knowing you’re making informed decisions for your child’s well-being. This article explores the key rules that govern UTMA account withdrawals, offering you valuable insights into managing these funds effectively.
Together, we can ensure that your child’s financial future is bright and secure. How can you make the best decisions for your child’s financial well-being amidst these challenges?
Bright Advisers: Personalized Financial Planning for UTMA Accounts
At Bright Advisers, we truly understand the unique challenges families face when overseeing custodial funds. Our commitment to customized monetary planning is designed with your family’s needs at heart. By harnessing advanced technology alongside a client-first approach, we clarify the often complex world of financial planning, making it easier for you to navigate.
Imagine having tailored investment strategies that align perfectly with your family’s distinct goals. We ensure that the assets in custodial arrangements are managed effectively, safeguarding your child’s economic future. This personalized approach is crucial for parents like you, who want to simplify the complexities of custodial funds while prioritizing your children’s long-term financial health.
Together, we can navigate this journey. We’re here for you, offering support and guidance every step of the way. Let us help you create a secure financial foundation for your family, allowing you to focus on what truly matters—your child’s bright future.
Understanding UTMA Withdrawal Timing: Key Rules for Parents
Withdrawals from custodial accounts can be made at any time, but they must serve the direct benefit of your child. As parents, it’s crucial to be attentive, as funds should never be used for personal expenses unrelated to your child’s welfare. Misusing these funds can lead to significant legal complications, including disputes over the appropriateness of the withdrawal. For instance, a family faced legal issues after withdrawing funds for a non-educational reason, such as a family holiday. This underscores the importance of adhering to the designated use of these assets.
To prevent such challenges, it’s wise to keep detailed records of all withdrawals, ensuring they align with the intended purpose of benefiting your child. This documentation is especially important, as guardianship of minor savings ends when your child reaches the age of majority, which varies by state. At that point, your child gains complete control of the resources and can use the funds as they wish, which may lead to careless spending if not managed properly. Bright Advisers can help you navigate this risk by providing guidance on how to structure withdrawals and manage funds effectively.
Moreover, understanding the tax implications associated with custodial savings is essential. The first $1,250 of unearned income is tax-free, but it’s important to know how to navigate these tax rules. Bright Advisers assists families in enhancing their tax situations related to custodial funds, ensuring compliance with regulations while maximizing resources for educational preparedness and long-term stability. By collaborating with Bright Advisers, families can create customized wealth management strategies that secure their children’s financial future. Together, we can navigate this journey and ensure a brighter tomorrow for your family.

Tax Implications of UTMA Withdrawals: What Parents Need to Know
Navigating the world of custodial funds can be challenging, especially when it comes to understanding the tax implications. For the 2025 tax year:
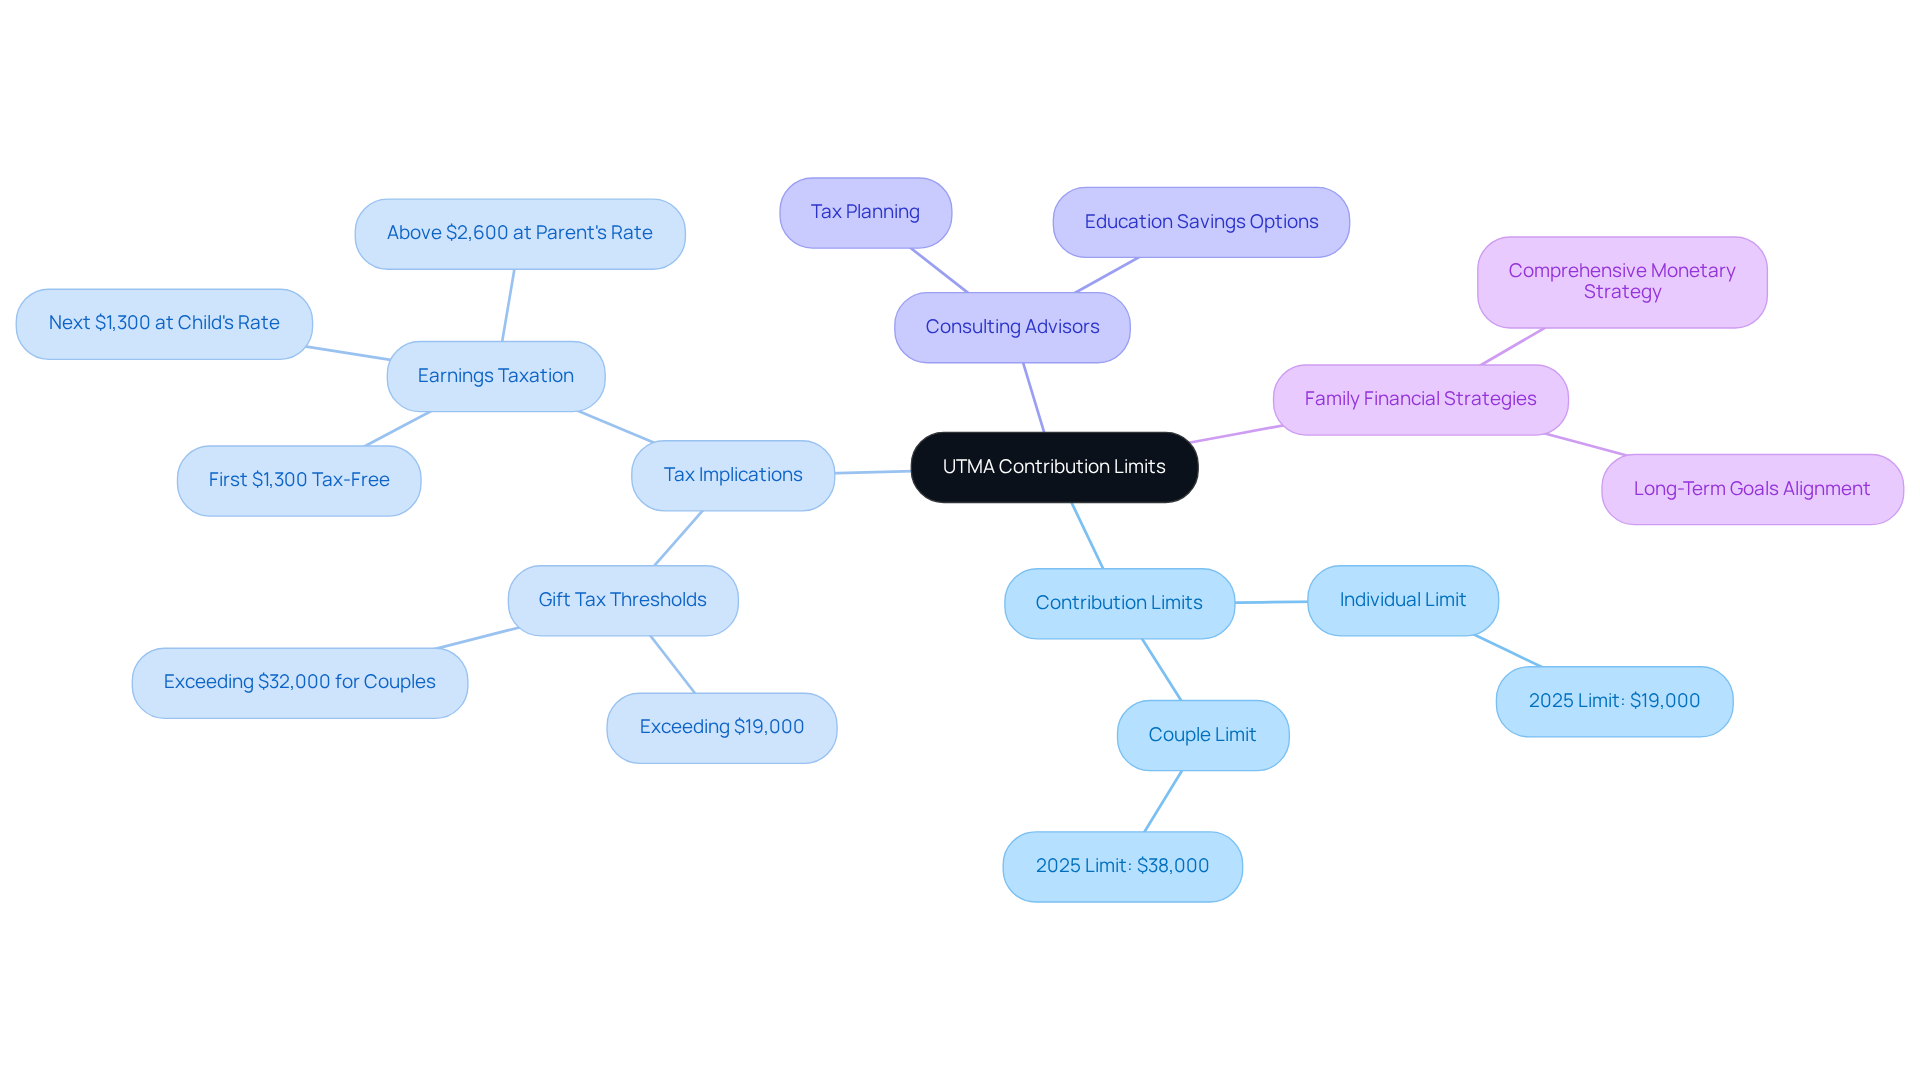
- The first $1,350 of unearned income from the fund is tax-free for your child.
- After that, the next $1,350 is taxed at your child’s rate.
- However, any income exceeding $2,700 is taxed at your marginal tax rate.
This structure highlights the importance of thoughtful planning. Imagine if you could make informed decisions that support your family’s financial goals. Consulting with a tax advisor can help you navigate these rules effectively, ensuring you feel confident in your choices. By understanding how UTMA account withdrawal rules influence tax obligations, you can improve tax efficiency and align with your family’s values. Remember, we’re here for you as you navigate this journey together.

Age of Majority: When Can Minors Withdraw from UTMA Accounts?
The age of majority for UTMA funds varies from state to state, typically falling between 18 and 21 years old. In some states, custodianship can extend up to age 25 if this is specified when the fund is established. Once a minor reaches the age of majority, they gain full control over their account, which means they can follow the UTMA account withdrawal rules to withdraw funds without needing the custodian’s approval.
Imagine if your child suddenly had access to their own financial resources. It’s essential for parents to engage in proactive conversations about monetary responsibility as their children approach this milestone. This preparation helps ensure that young adults are equipped to manage their economic independence effectively.
Financial educators emphasize the importance of these discussions, highlighting that early guidance can foster a sense of responsibility and understanding of money management. This foundation is crucial for long-term financial success. Together, we can navigate this journey, ensuring our children are ready to embrace their financial futures with confidence.

Custodian Responsibilities: Managing UTMA Funds Ethically
As custodians of UTMA accounts, often parents, you hold a special responsibility to manage these funds with care and integrity, always prioritizing the well-being of your child. Imagine making investment choices that not only secure their future but also provide for their immediate needs, such as education and healthcare. It’s essential to ensure that every withdrawal adheres to the UTMA account withdrawal rules and serves their best interests.
To honor this commitment, it’s crucial to steer clear of conflicts of interest and to maintain transparency in all financial dealings. Regularly reviewing the account and engaging in conversations about financial goals with your child can foster responsible use of these resources, ensuring they align with your family’s values.
At Bright Advisers, we understand the unique challenges young families face. We’re dedicated to offering tailored wealth management solutions that not only minimize fund fees but also empower you to manage custodial assets effectively. By embracing ethical management practices and leveraging the support we provide, you can confidently navigate the complexities of custodial funds, especially regarding the UTMA account withdrawal rules.
Together, we can safeguard the financial future of your children while ensuring that their needs are met today. Remember, you’re not alone on this journey; we’re here for you every step of the way.

UTMA vs. UGMA: Choosing the Right Custodial Account for Your Child
When choosing between custodial options and UGMA, it’s essential for parents to thoughtfully consider the types of assets they wish to manage. Imagine having the flexibility to oversee a variety of assets—UTMA arrangements allow this, including real estate, collectibles, and alternative investments. This provides a wonderful opportunity for enhanced flexibility in both withdrawals and fund utilization according to the UTMA account withdrawal rules. On the other hand, UGMA holdings are limited to cash and securities, which may restrict investment strategies.
As you navigate this decision, think about your financial goals and your child’s unique needs. This choice can have a significant impact on your asset management strategies and future funding eligibility. It’s vital to align your decision with your overall family financial planning. As Nathan Mueller, a wealth advisor, insightfully notes, “These arrangements were created to ease the procedure of transferring assets to minors while enabling the custodian to maintain some authority until the minor attains adulthood.”
Additionally, it’s important to be aware that any unearned income over $2,700 is taxed at the parent’s marginal rate, which can influence your decision-making process. Remember, we’re here for you as you navigate this journey together with your family, ensuring that your choices support your long-term aspirations.

Contribution Limits for UTMA Accounts: What Parents Should Know
UTMA accounts provide wonderful flexibility, allowing parents and other contributors to gift freely without set contribution limits. However, it’s crucial to be mindful that contributions exceeding $19,000 in 2025 for individuals (or $38,000 for married couples) may lead to gift tax implications. Parents should take care to track their contributions diligently to ensure compliance with IRS regulations and to optimize their gifting strategies.
Imagine families like Jay and Emma, who sought guidance from Bright Advisers. They discovered that consulting with an advisor offered invaluable insights into managing their resources effectively, including tax planning and education savings options. Engaging with tax professionals can further clarify the nuances of gift tax implications, helping families maximize the benefits of their contributions while minimizing potential tax liabilities.
By creating a comprehensive monetary strategy, families can navigate these regulations with confidence. Think of Emily and Mark, who gained the freedom to make informed economic decisions that align with their long-term goals. Data suggest that the typical contribution to custodial funds varies significantly, reflecting diverse economic approaches among families.
Together, we can navigate this journey, ensuring that your family’s financial future is secure and aligned with your values.
Financial Aid Considerations: How UTMA Accounts Affect Eligibility
Navigating financial assistance can feel overwhelming, especially for young parents. Student assets are categorized in a way that can significantly impact eligibility for aid. Typically, when assessing a student’s assistance package, 20% of the custodial fund’s value is considered, which might reduce the support available. For instance, a custodial asset valued at $30,000 could lead to a decrease of about $6,000 in assistance.
Imagine if there was a way to lessen this burden. Parents might consider converting custodial accounts into a 529 plan, which is viewed more favorably in aid calculations. In this case, only up to 5.64% of the account value is taken into account, potentially preserving more of your resources for your child’s education. Aid counselors often recommend using custodial funds for eligible educational expenses before submitting the FAFSA, as this can help mitigate the impact on assistance.
It’s also crucial for parents to meticulously document all educational costs. This careful record-keeping can illustrate the need for utilizing custodial funds for educational purposes. Remember, you’re not alone in this journey. Engaging with aid specialists can provide tailored strategies to navigate the complexities of asset reporting, ultimately enhancing your aid eligibility.
Together, we can navigate this journey, ensuring that your family’s financial future remains bright and supported.

Pros and Cons of UTMA Accounts: Weighing Your Options
Custodial savings options offer a range of benefits that can greatly assist families, especially when integrated into a comprehensive financial plan with the support of professionals like Bright Advisers. Imagine having the flexibility to contribute various assets—cash, stocks, bonds, or even real estate—tailored to your unique financial goals. This versatility allows families to enhance their tax circumstances and secure education funding for their children.
Understanding the UTMA account withdrawal rules is important, as it allows resources to be accessed for your child’s benefit without penalties, making custodial arrangements a practical choice for addressing their financial needs. Through effective financial planning, families can experience transformative outcomes, such as the ability to retire sooner and enjoy more quality time together, as seen in the success stories of families who have partnered with Bright Advisers.
However, there are some considerations related to UTMA account withdrawal rules to keep in mind. Contributions to custodial funds are irrevocable, meaning once assets are transferred, they cannot be reclaimed. This requires parents to feel confident in their financial decisions. Additionally, assets held in custodial funds can impact a minor’s eligibility for financial aid when applying for college, as these funds are considered the minor’s resources.
As of 2023, the first $1,250 of unearned income from a custodial fund is tax-free, with the next $1,250 taxed at the minor’s lower rate, offering a tax benefit that can lead to significant savings. Importantly, parents are not legally responsible for paying taxes on their child’s UTMA account withdrawal rules, as the tax responsibility falls on the minor. Yet, families should weigh these advantages against the potential long-term effects of asset ownership and the UTMA account withdrawal rules that could impact aid eligibility. Financial advisors often emphasize the importance of evaluating custodial arrangements within a family’s overall financial plan, particularly the UTMA account withdrawal rules, ensuring that parents make informed choices that align with their children’s future needs.
For instance, families may find themselves comparing custodial funds with options like 529 plans or trust funds, each offering unique benefits and drawbacks. While 529 plans provide tax-deferred growth for educational expenses, they come with stricter withdrawal rules and limited investment options, including a 10% penalty for non-college withdrawals. On the other hand, trust funds offer greater control over asset allocation but may be more costly to establish, often requiring several thousand dollars compared to the minimal or no setup costs associated with custodial arrangements.
Ultimately, the decision to establish a custodial account should be guided by a thorough understanding of these factors, ensuring that parents choose the best option for their child’s financial future. Together with Bright Advisers, families can navigate these choices with confidence, utilizing tailored wealth management solutions that promote financial security and freedom, all while benefiting from minimal fund fees that enhance accessibility.

Future Planning: Strategies for Managing UTMA Withdrawals
As young individuals approach adulthood, it’s vital for parents to engage them in meaningful discussions about financial responsibility and the thoughtful use of custodial funds, particularly regarding the UTMA account withdrawal rules. Imagine creating a withdrawal strategy that not only supports your child’s educational journey but also aligns with their personal dreams. This approach can truly enhance the impact of these funds. Parents might consider using UTMA funds for college expenses, enriching travel experiences, or even a first car—each a stepping stone that helps young individuals grasp the true value of money.
It’s important to understand that involving young individuals in conversations about money management and investment strategies not only prepares them to handle their resources effectively but also nurtures a sense of ownership and responsibility. Studies show that youngsters educated about financial principles are more likely to make informed decisions as adults. In fact, research indicates that only 24% of teenagers feel confident in their understanding of money matters. Money management instructors stress that teaching budgeting skills is essential for future success, with one educator noting, “Money literacy is not merely a skill; it’s a requirement for successfully navigating life.”
By prioritizing these important discussions and exploring tailored wealth management solutions, parents can ensure their children are well-prepared to manage their financial responsibilities while adhering to UTMA account withdrawal rules when they take control of their accounts. Together, we can navigate this journey, empowering our young adults to thrive in their financial futures.

Conclusion
Navigating the complexities of UTMA account withdrawals is vital for parents eager to secure their children’s financial futures. By understanding the rules surrounding these custodial accounts, parents can empower themselves to make informed decisions, ensuring that funds are used appropriately for the benefit of their children. With the right knowledge and support, families can manage these resources effectively, aligning them with their long-term financial goals.
It’s crucial to adhere to withdrawal rules that prioritize the child’s welfare. Additionally, understanding the tax implications associated with custodial funds and the ethical responsibilities custodians hold is essential. Engaging in proactive conversations about financial literacy with children prepares them for future independence as they approach adulthood.
Ultimately, managing UTMA accounts transcends mere compliance with regulations; it fosters a foundation of financial responsibility and security for the next generation. Families are encouraged to seek personalized financial planning and guidance from professionals, like Bright Advisers, to navigate this journey confidently. Together, we can ensure that children are well-equipped to embrace their financial futures with knowledge and responsibility.
Frequently Asked Questions
What services does Bright Advisers provide for families managing UTMA accounts?
Bright Advisers offers personalized financial planning tailored to families overseeing custodial funds, utilizing advanced technology and a client-first approach to simplify financial planning and safeguard children’s economic futures.
Can parents withdraw funds from UTMA accounts at any time?
Yes, withdrawals from custodial accounts can be made at any time, but they must directly benefit the child. Misuse of funds for personal expenses unrelated to the child’s welfare can lead to legal complications.
What should parents do to avoid legal issues with UTMA withdrawals?
Parents should keep detailed records of all withdrawals to ensure they align with the intended purpose of benefiting the child, thus preventing legal disputes.
What happens to custodial funds when a child reaches the age of majority?
When a child reaches the age of majority, which varies by state, they gain complete control of the custodial funds and can use them as they wish, potentially leading to careless spending if not managed properly.
How does Bright Advisers assist with managing UTMA withdrawals?
Bright Advisers provides guidance on structuring withdrawals and managing funds effectively to help families navigate risks associated with custodial accounts.
What are the tax implications of UTMA account withdrawals for the 2025 tax year?
For the 2025 tax year, the first $1,350 of unearned income from the fund is tax-free for the child. The next $1,350 is taxed at the child’s rate, while any income exceeding $2,700 is taxed at the parent’s marginal tax rate.
Why is it important to consult a tax advisor regarding UTMA accounts?
Consulting a tax advisor can help families navigate tax rules effectively, improve tax efficiency, and align their financial decisions with their family’s goals and values.
List of Sources
- Bright Advisers: Personalized Financial Planning for UTMA Accounts
- Understanding UTMA Accounts: A Guide for Parents and Guardians | Ruth Cantu, CPA (https://linkedin.com/pulse/understanding-utma-accounts-guide-parents-guardians-ruth-1ytpc)
- Understanding UTMA Withdrawal Timing: Key Rules for Parents
- Everything You Need to Know About UTMA Account Rules (https://getearlybird.io/blog/utma-account-rules)
- What is a UTMA Account, and Why Should You Consider One for Your Kids? | KidVestors (https://kidvestors.co/post/what-is-a-utma-account)
- UTMA Accounts Explained: Rules, Custodial Brokerages and More (https://kiplinger.com/personal-finance/603545/hey-parents-caution-is-critical-with-utma-custodial-accounts)
- Tax Implications of UTMA Withdrawals: What Parents Need to Know
- UGMA & UTMA accounts | Tips for custodial accounts | Fidelity (https://fidelity.com/learning-center/personal-finance/custodial-account-for-kids)
- What is the Kiddie Tax? (https://savingforcollege.com/article/what-is-the-kiddie-tax)
- Famous quotes about taxation | Scholes Chartered Accountants (https://scholesca.co.uk/blog/famous-quotes-about-tax)
- 130 Inspirational Quotes About Taxes (https://inc.com/geoffrey-james/130-inspirational-quotes-about-taxes.html)
- The Kiddie Tax: Rates, Limits and Rules for 2024 and 2025 (https://smartasset.com/taxes/kiddie-tax)
- Age of Majority: When Can Minors Withdraw from UTMA Accounts?
- Custodial Account | Plan For A Child’s Future | Fidelity Investments (https://fidelity.com/open-account/custodial-account)
- UGMA & UTMA accounts | Tips for custodial accounts | Fidelity (https://fidelity.com/learning-center/personal-finance/custodial-account-for-kids)
- What is a UGMA and UTMA Account? Understanding These Accounts (https://savingforcollege.com/article/what-is-an-ugma-or-utma-account)
- Are UTMA Accounts a Good Idea for your Minor Children? (https://vjrussolaw.com/are-utma-accounts-a-good-idea-for-your-minor-children)
- Age of Majority and Trust Termination – Finaid (https://finaid.org/savings/ageofmajority)
- Custodian Responsibilities: Managing UTMA Funds Ethically
- The SEC’s Proposed Safeguarding Rule Will Cost Investors (https://ici.org/viewpoints/24-view-safeguarding)
- UTMA Accounts Explained: Rules, Custodial Brokerages and More (https://kiplinger.com/personal-finance/603545/hey-parents-caution-is-critical-with-utma-custodial-accounts)
- Understanding UTMA Accounts and Their Role in Estate Planning . (https://legacycarelaw.com/blog/estate-planning-2/understanding-utma-accounts-and-their-role-in-estate-planning)
- UTMA Accounts – What You Need To Know – Bridgeview Capital Advisors, Inc. (https://bridgeviewadvisors.com/utma-accounts)
- UTMA vs. UGMA: Choosing the Right Custodial Account for Your Child
- Financial Advisors Guide: UTMA and UGMA Accounts for Kids (https://wealthtender.com/insights/utma-and-ugma-accounts-for-kids)
- UGMA vs. UTMA Custodial Accounts (https://smartasset.com/investing/ugma-vs-utma)
- UTMA vs. UGMA: Understanding for Investment Planning (https://westernsouthern.com/investments/utma-vs-ugma-accounts)
- Understanding UGMA vs. UTMA: Key Differences Explained (https://yieldstreet.com/blog/article/ugma-vs-utma)
- Contribution Limits for UTMA Accounts: What Parents Should Know
- Saving for College: Custodial Accounts (https://schwab.com/learn/story/saving-college-custodial-accounts)
- What Is a UTMA or UGMA Account for 2025 | Research.com (https://research.com/student-loans/what-is-a-utma-or-ugma-account)
- What Are UTMA Accounts? | City National Bank (https://cnb.com/personal-banking/insights/utma-ugma-accounts.html)
- UGMA & UTMA accounts | Tips for custodial accounts | Fidelity (https://fidelity.com/learning-center/personal-finance/custodial-account-for-kids)
- Financial Aid Considerations: How UTMA Accounts Affect Eligibility
- FAFSA confusion: UTMA account from ex’s parents – how badly will this affect my son’s financial aid? – Claimyr (https://claimyr.com/financial-services/fafsa/FAFSA-confusion-UTMA-account-from-exs-parents-how-badly-will-this-affect-my-sons-financial-aid/2025-03-28)
- How 6 Different Assets Can Affect Your FAFSA and Financial Aid Eligibility (https://savingforcollege.com/article/how-7-different-assets-can-affect-your-financial-aid-eligibility)
- Are Custodial Accounts a Good Option for Parents Saving for College? (https://savingforcollege.com/article/are-custodial-accounts-a-good-option-for-parents-saving-for-college)
- Pros and Cons of UTMA Accounts: Weighing Your Options
- UTMA vs. UGMA: Understanding for Investment Planning (https://westernsouthern.com/investments/utma-vs-ugma-accounts)
- 3 advantages of using a UTMA account to quick-start your child’s future | UNest (https://unest.co/3-advantages-of-a-utma-account)
- UTMA account – Everything you need to know about these custodial accounts (https://pasito.ai/utma-account)
- UTMA Tax Rules 2023 & 2024 – Greatest Gift (https://greatestgiftapp.com/blog/utma-tax-rules)
- 77 Financial Advisor Quotes to Send to Clients (https://billgoodmarketing.com/resources/financial-advisor-quotes)
- Future Planning: Strategies for Managing UTMA Withdrawals
- Financial Advisors Guide: UTMA and UGMA Accounts for Kids (https://wealthtender.com/insights/utma-and-ugma-accounts-for-kids)
- UTMA Accounts Explained: Rules, Custodial Brokerages and More (https://kiplinger.com/personal-finance/603545/hey-parents-caution-is-critical-with-utma-custodial-accounts)
- UTMA: A Flexible Alternative for Education Expenses and More (https://kiplinger.com/personal-finance/utma-a-flexible-alternative-for-education-expenses-and-more)
- 40 quotes to help your child learn the value of money | GoHenry (https://gohenry.com/us/blog/financial-education/40-quotes-to-help-your-child-learn-the-value-of-money)
- Teach Your Child About Money Through Play Quotes by Andrea Stephenson (https://goodreads.com/work/quotes/76065157-teach-your-child-about-money-through-play-110-games-activities-tips)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Age Five Wealth Education for high-income W-2 families at Bright Advisers.
Keep reading