

Overview
This article gently explores the pros and cons of infinite banking for young families. It highlights potential benefits such as:
- Tax-free growth
- Liquidity
- Legacy planning
while also addressing some drawbacks, including:
- High initial costs
- Slow cash value accumulation
Imagine if you could secure your family’s financial future while enjoying flexibility and peace of mind. Infinite banking can provide this through whole life insurance policies, fostering financial security and stability for your loved ones. However, it’s important to understand the long-term commitments and risks involved in this financial strategy. We’re here to help you navigate these complexities, ensuring you make informed decisions that align with your family’s values and goals. Together, we can explore how infinite banking might fit into your financial journey.
Key Highlights:
- Bright Advisers offers personalised financial planning services aimed at young families, focusing on wealth management through infinite banking.
- Infinite banking allows families to accumulate cash value through whole life insurance, providing liquidity and financial flexibility.
- Key advantages of infinite banking include tax-free growth, liquidity through policy loans, monetary control, and legacy planning.
- Disadvantages include high initial costs, slow cash value accumulation, risks associated with borrowing against the policy, and the need for long-term commitment.
- Cash value loans enable families to access funds without credit checks, offering flexible repayment terms and lower interest rates compared to traditional loans.
- Tax advantages of infinite banking include tax-deferred growth, tax-free loans, and tax-exempt death benefits for beneficiaries.
- Asset protection features of whole life insurance safeguard accumulated cash value from creditors, enhancing financial security for families.
- Qualifying for whole life policies involves health and monetary assessments, with younger applicants often benefiting from lower premiums.
- Common misconceptions about infinite banking include beliefs that it is a scam or only for the wealthy; proper guidance can clarify its benefits.
- Families are encouraged to educate themselves, consult professionals, choose appropriate plans, and consistently fund their policies to maximise benefits.
Introduction
Navigating the complexities of financial planning can feel overwhelming for young families striving for stability and growth. Imagine a strategy that not only aims to secure your family’s financial future but also empowers you to operate as your own banking system—this is where infinite banking comes into play.
By exploring the pros and cons of this approach, you can uncover valuable insights that will help you make informed decisions about your wealth management. However, it’s important to understand that with its potential benefits come significant challenges.
What are the hidden risks that families must consider before diving into this financial strategy? We’re here for you, ready to help you navigate this journey together.
Bright Advisers: Personalized Financial Planning for Infinite Banking
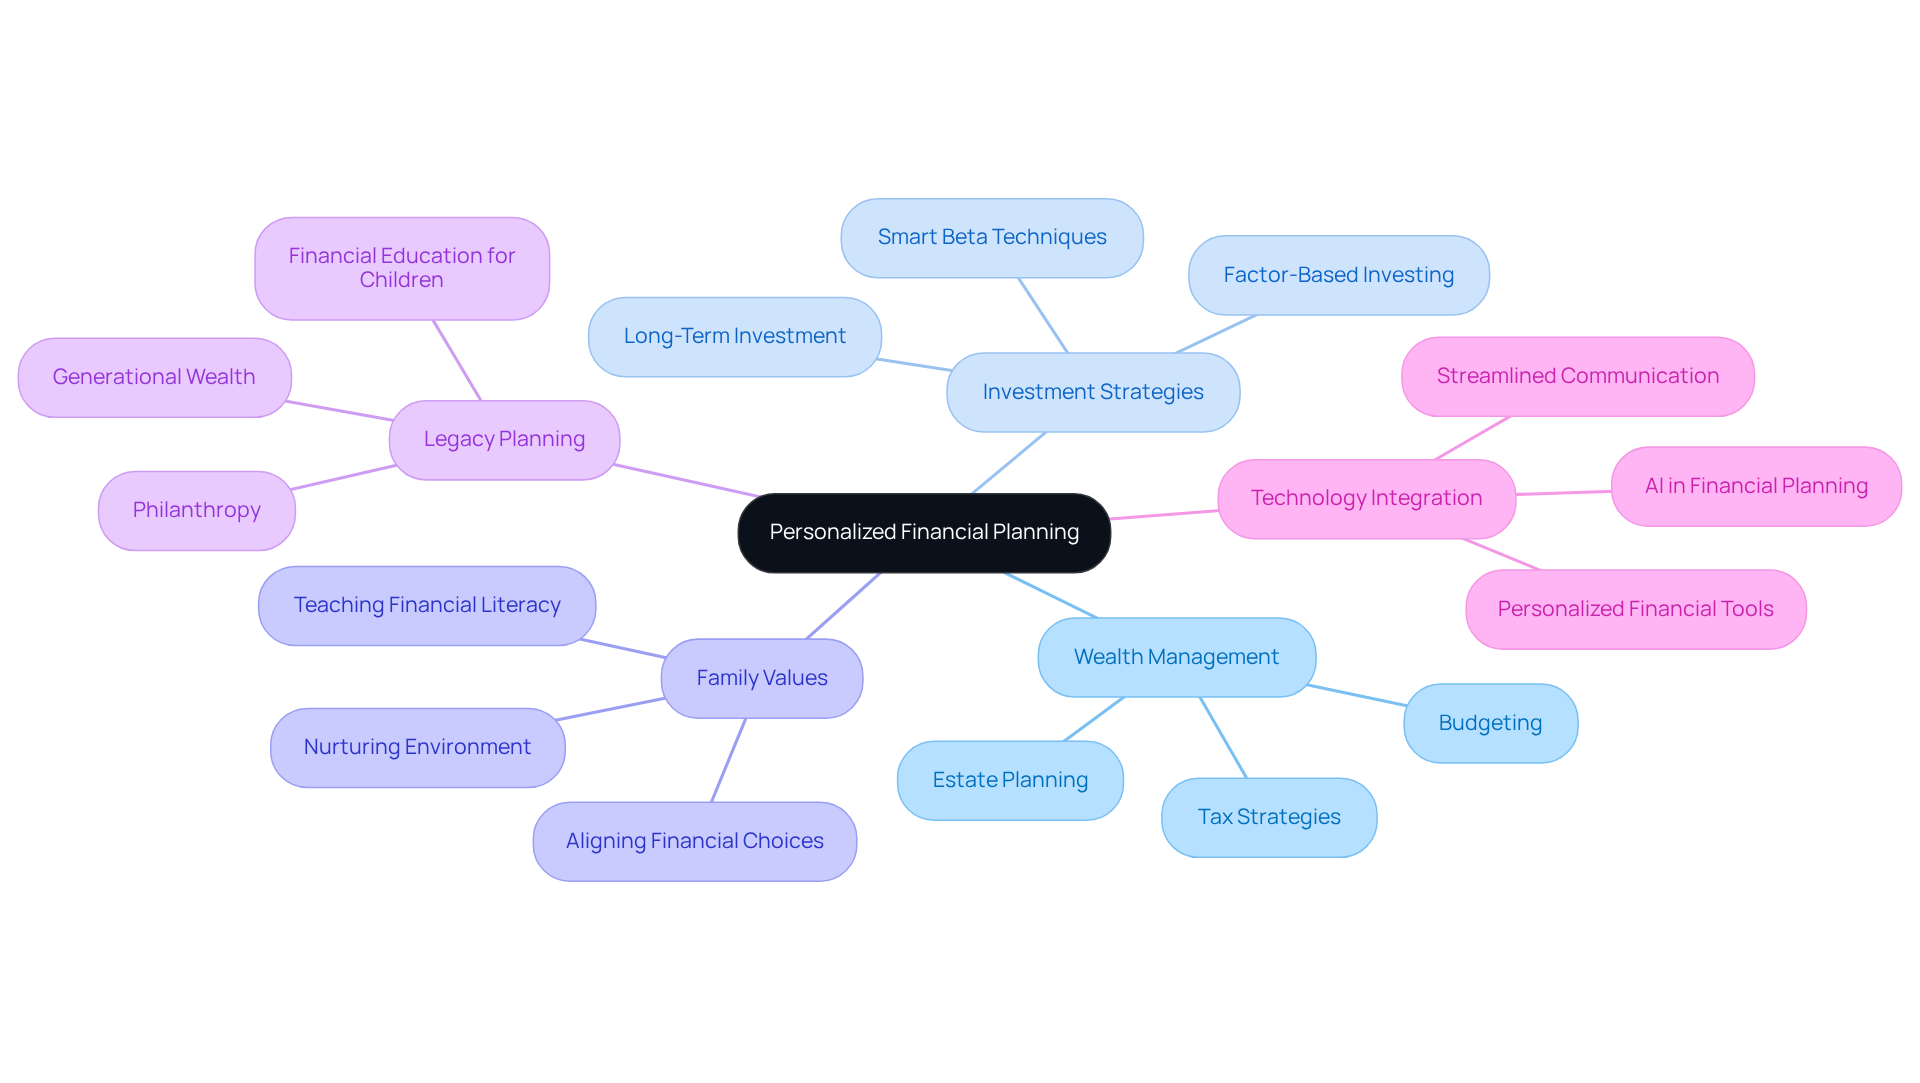
At Bright Advisers, we understand that navigating the world of wealth planning can feel overwhelming, especially for young families. Our tailored approach to wealth management takes into account the infinite banking pros and cons, leveraging cutting-edge technology to create personalized strategies that empower households to unlock their full wealth potential.
Imagine a method that not only simplifies budgeting but also supports you in raising your children. Our innovative solutions are designed with young families in mind, ensuring that you can access top-tier services tailored to your unique needs, no matter your financial situation. We believe that aligning your financial choices with your family’s values is essential, fostering a nurturing environment where you can confidently build a secure economic future.
With dedicated teams of consultants and integrated tax strategies that enhance financial efficiency, we offer a comprehensive wealth management experience. Our services also include estate and legacy planning, addressing the distinct challenges families face today.
Moreover, we employ advanced investment strategies, such as factor-based investing and smart beta techniques, to further enhance your financial outcomes. As technology evolves, we remain committed to staying ahead of trends in personalized wealth management. Our solutions not only aim to meet your immediate financial goals but also equip your family for lasting prosperity across generations.
Together, we can navigate this journey. We’re here for you, ready to support you every step of the way.
Understanding Infinite Banking: A Family-Centric Financial Strategy
Understanding Infinite Banking: A Family-Centric Financial Strategy
Imagine having a financial strategy that not only secures your family’s future but also acts as your personal banking system. Infinite banking does just that. By using a specially designed whole life insurance policy, you can accumulate cash value over time, which can be accessed through policy loans for important needs like education or emergencies, highlighting the infinite banking pros and cons.
It’s important to understand that by grasping the infinite banking pros and cons, you can take control of your financial future. This approach highlights the infinite banking pros and cons, ensuring you have the liquidity and adaptability to meet your family’s changing needs while creating a legacy of prosperity for generations to come.
At Bright Advisers, we are here for you. We are dedicated to offering young families customized wealth management options and educational resources. We provide insights on reducing fund fees, making strategies like infinite banking pros and cons more accessible and effective. Together, we can navigate this journey.
Start by assessing your current financial condition and establishing specific goals for utilizing loans. This way, you can optimize the advantages of this empowering approach, ensuring a brighter financial future for your family.
Advantages of Infinite Banking: Financial Security for Young Families
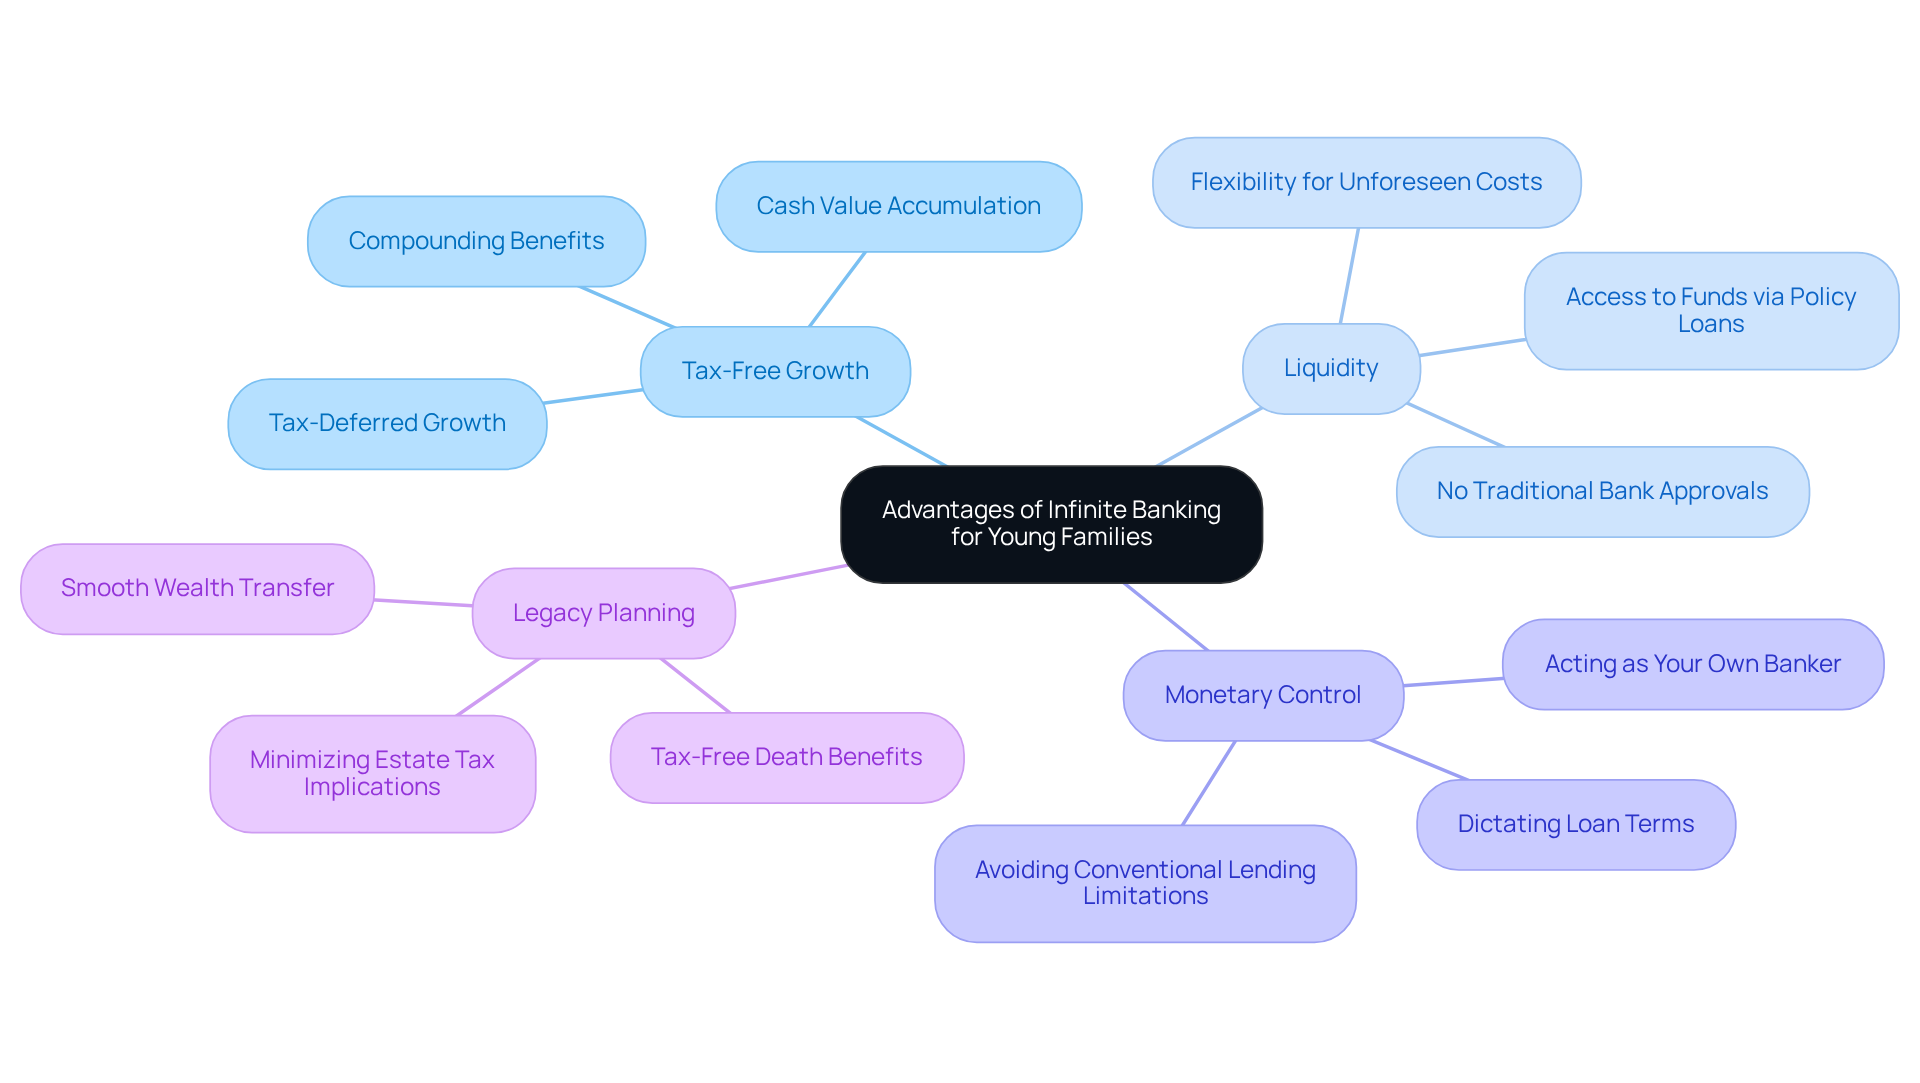
The advantages of infinite banking for young families are both significant and multifaceted:
-
Tax-Free Growth: Imagine a financial strategy where your cash value in a whole life insurance policy grows tax-deferred. This allows families to accumulate wealth without immediate tax implications. As the cash value rises, households can enjoy the benefits of compounding, free from the burden of taxes until they access the funds. For meaningful cash value accumulation, annual premiums of $5,000 to $10,000 are typically recommended. This method aligns perfectly with the goals of young families like Emily and Mark, who are eager to enhance their economic situation for future stability.
-
Liquidity: It’s important to understand that families can access funds through policy loans without the need for traditional bank approvals. This provides essential economic flexibility. Quick access to funds can be vital for handling unforeseen costs or seizing investment opportunities, allowing families to maintain control over their resources. With the guidance of Bright Advisers, Emily and Mark implemented strategies that provided them with the liquidity they needed to navigate their demanding careers while planning for their future.
-
Monetary Control: By acting as their own banker, families can dictate the terms of their loans and repayments, enhancing their economic autonomy. This flexibility empowers families to make informed choices regarding their finances, avoiding the limitations often imposed by conventional lending institutions. As Steve Gibbs observed, “We’re not just transferring assets, we’re conveying a monetary philosophy that can benefit households for generations.” This philosophy truly resonated with Emily and Mark as they worked towards achieving economic independence.
-
Legacy Planning: Infinite banking offers families the opportunity to establish a legacy, ensuring that wealth is transferred to future generations in a tax-efficient manner. The death benefits from whole life insurance plans are typically received income tax-free by beneficiaries, facilitating a smoother transfer of wealth and minimizing estate tax implications. However, it is essential for families to manage loan repayments responsibly to prevent possible policy lapses, ensuring that their economic legacy remains intact. Emily and Mark’s partnership with Bright Advisers beautifully illustrates how young families can successfully prepare for their economic future while cultivating a legacy of financial literacy and independence.
These advantages together establish infinite banking pros and cons as a robust approach for young families seeking to secure their economic future while nurturing a legacy of financial knowledge and autonomy. Together, we can navigate this journey toward a brighter financial future.
Disadvantages of Infinite Banking: Risks Young Families Should Consider
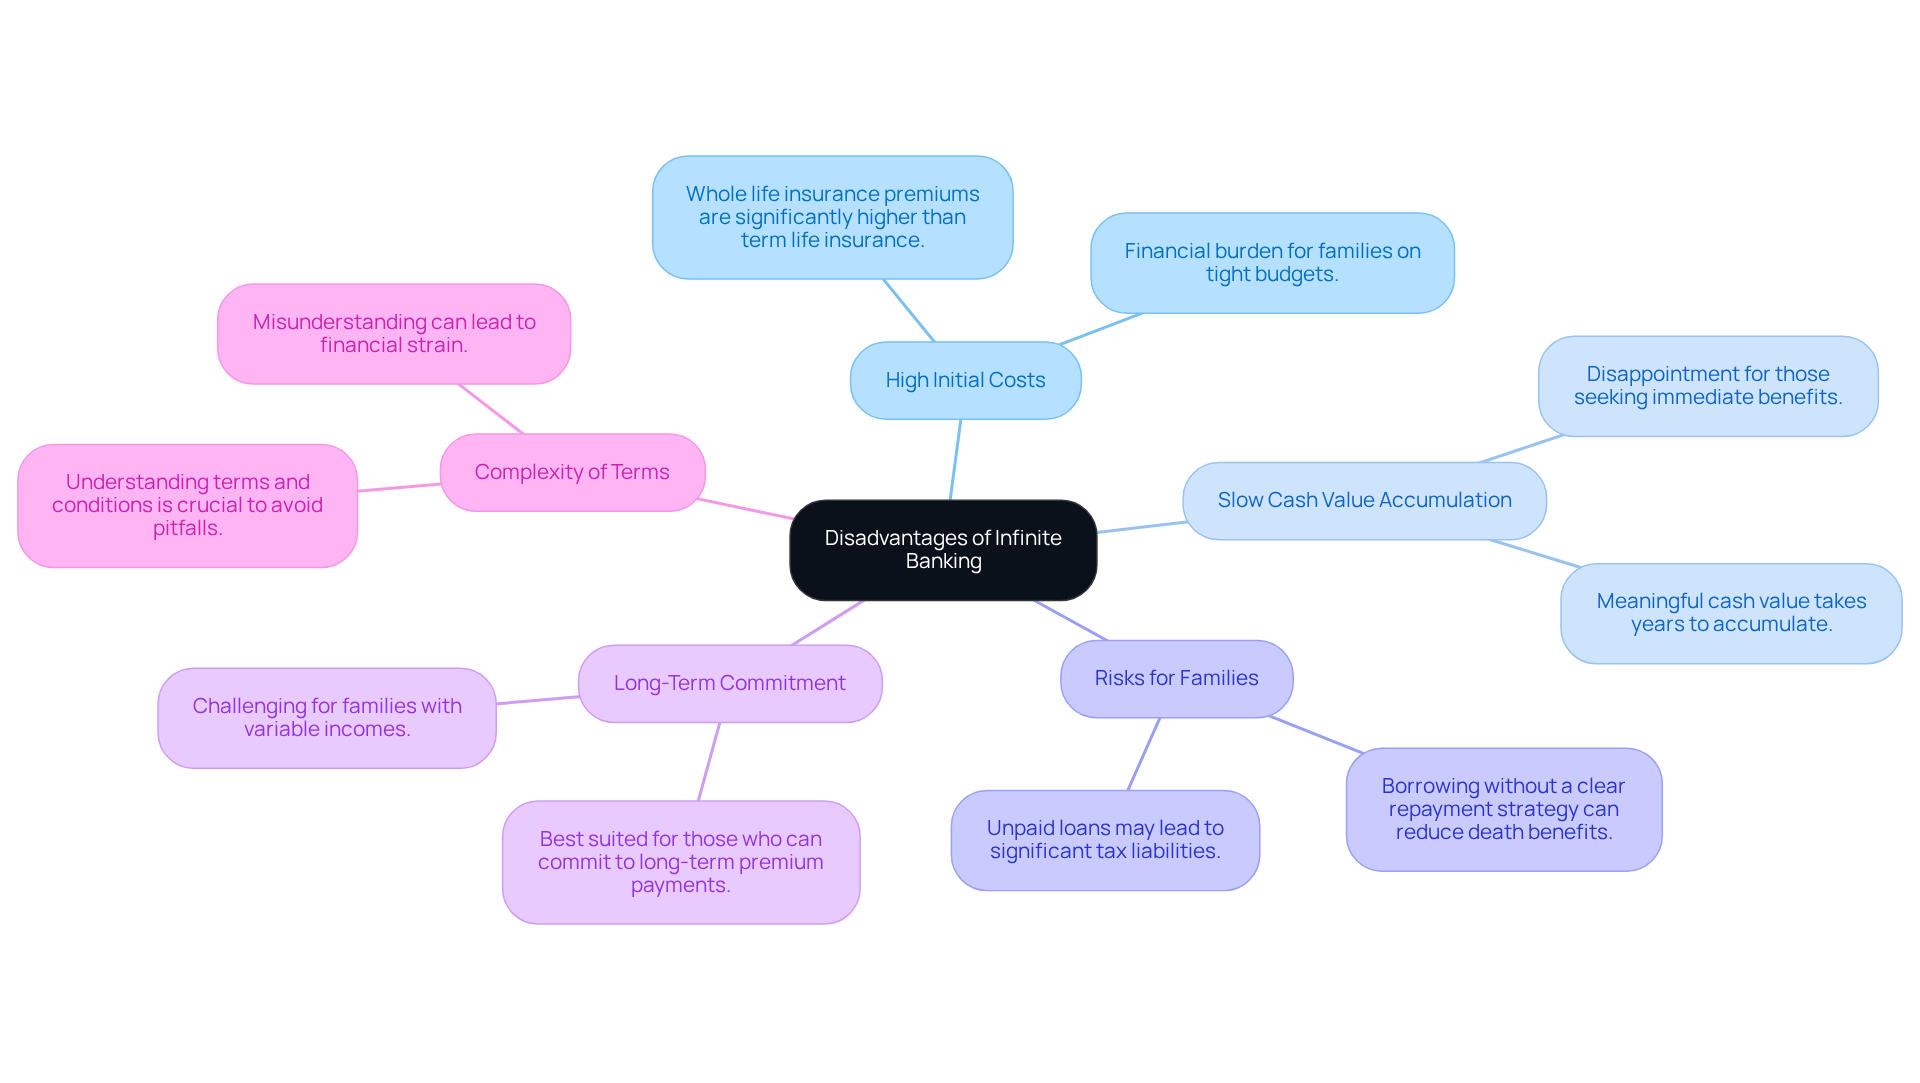
While considering the infinite banking pros and cons, it’s vital for young households to remain aware of its potential downsides. Understanding the infinite banking pros and cons is crucial for families contemplating it as a financial strategy, ensuring they make informed decisions that align with their long-term financial goals. At Bright Advisers, we are committed to providing tailored wealth management solutions to help families navigate these complexities with confidence.
- High Initial Costs: Whole life insurance plans typically come with significantly higher premiums than term life insurance. This financial obligation can pose a challenge for many families, particularly those on tight budgets.
- Slow Cash Value Accumulation: Families might discover that accumulating meaningful cash value within a whole life policy can take considerable time. It often necessitates several years of consistent premium payments before the cash value becomes substantial, which can be disheartening for those seeking immediate financial benefits.
The complexity of infinite banking pros and cons can feel overwhelming because of its intricacies. Families must fully grasp the terms and conditions of their agreements to effectively navigate potential pitfalls. Misunderstanding these details can lead to financial strain or disappointment.
- Risks for Families: Families could face challenges if they borrow against their plan without a clear repayment strategy. Unpaid loans can reduce the death benefit, impacting the financial legacy intended for beneficiaries. Furthermore, if the plan lapses due to unpaid premiums or excessive borrowing, it may lead to significant tax liabilities.
- Long-Term Commitment: Whole life insurance is generally best suited for those who can commit to long-term premium payments. Families with variable incomes or those needing immediate liquidity may find this commitment difficult.
To mitigate these risks, we encourage households to consult with Bright Advisers to understand the infinite banking pros and cons. Together, we can navigate this journey and make informed choices about infinite banking and other financial strategies, ensuring your family’s future is secure.
Cash Value Loans: Accessing Funds Through Infinite Banking
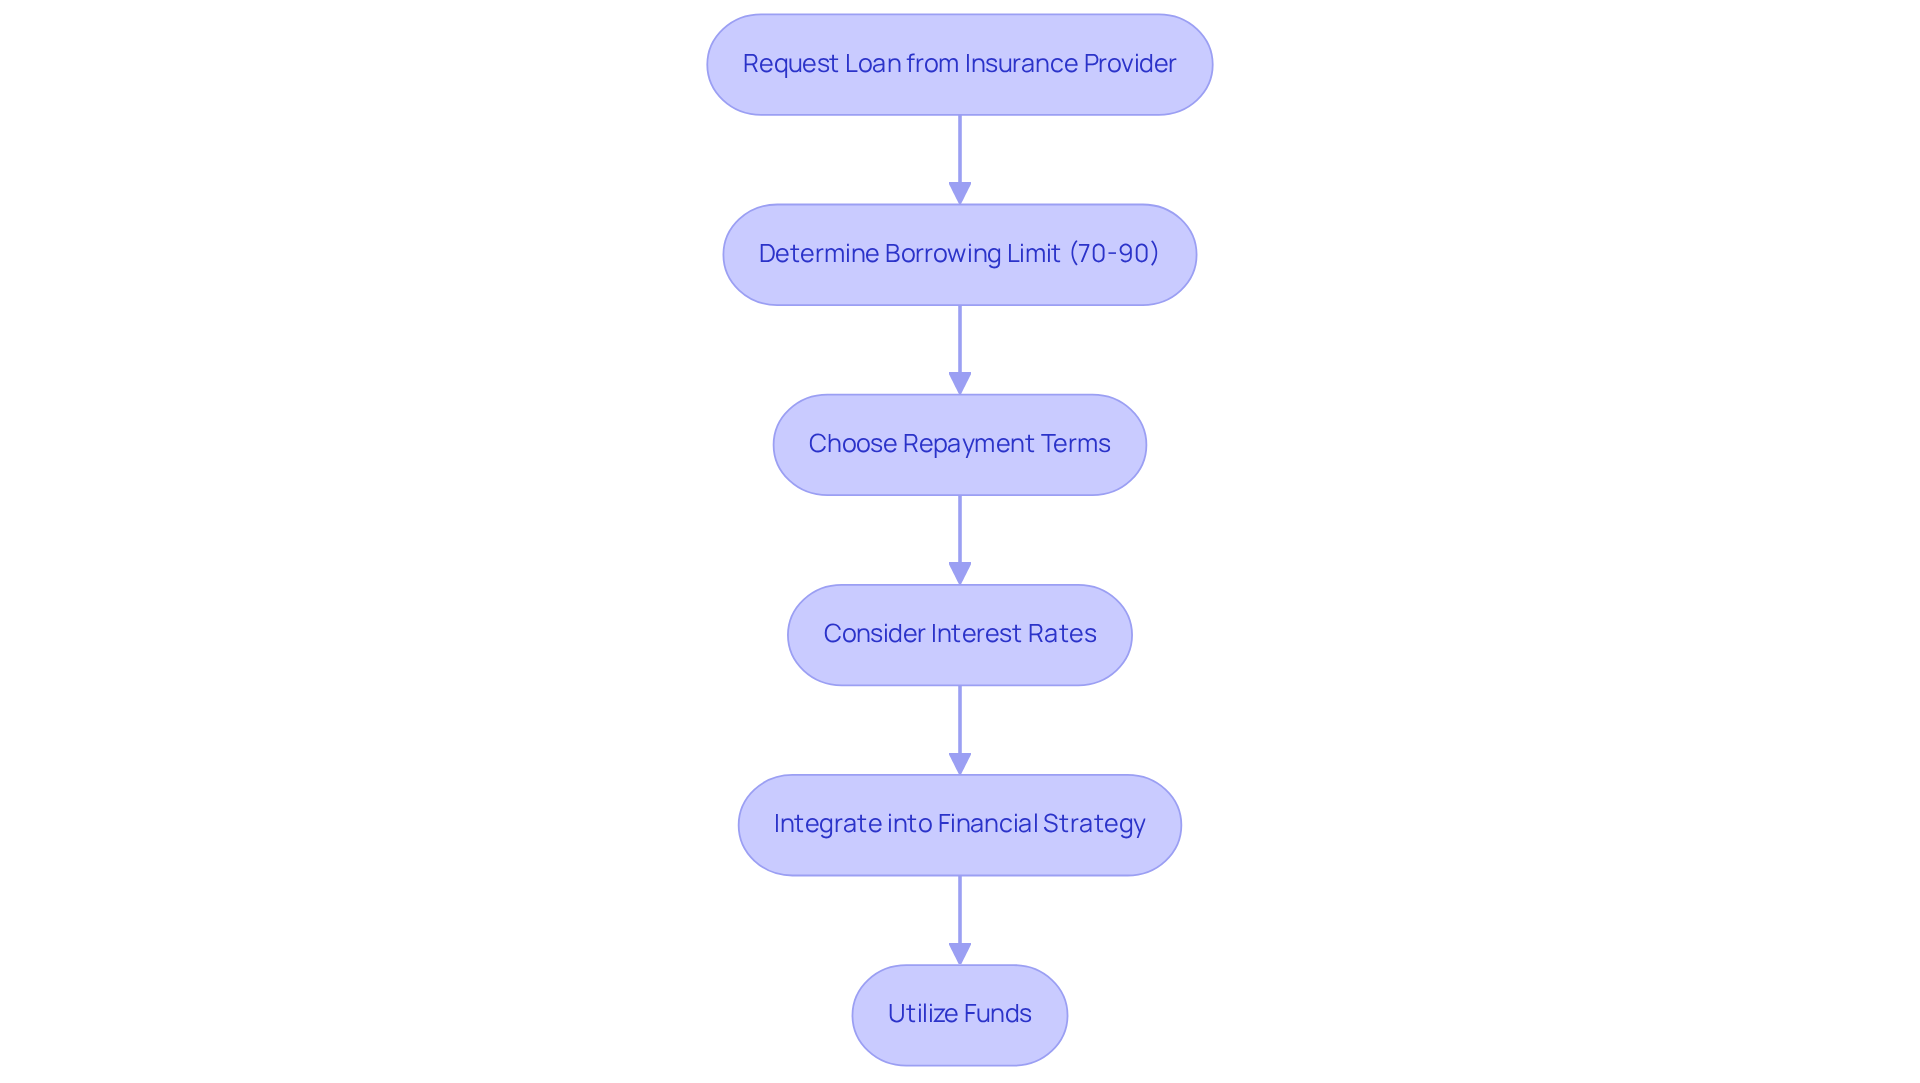
Cash value loans provide a wonderful opportunity for policyholders to tap into the accumulated cash value of their whole life insurance policies, serving as a versatile financial resource for families. The process is quite simple:
-
Imagine if you could easily access funds when you need them most. Families can request a loan from their insurance provider, typically without a credit check, making it easier to obtain the support they require.
-
The borrowing limit usually ranges from 70% to 90% of the cash value, allowing families to secure substantial amounts for various needs. This flexibility can be a game changer in times of financial uncertainty.
-
One of the most appealing aspects is the ability to choose repayment terms. Families can set their own schedules, which alleviates the stress of rigid repayment plans. While repayment isn’t mandatory, it’s wise to consider it to maintain the policy’s growth. Repaying loans can enhance the compounding interest benefits of whole life insurance, ensuring long-term financial health.
-
Although interest is charged on the loan, the rates are generally lower than those of traditional bank loans. This makes cash value loans particularly attractive for families looking to finance education or significant purchases.
-
Integrating cash value loans into your financial strategy can be further enhanced by considering minimal fund fees, which can improve overall wealth management accessibility. Families have successfully used cash value loans to cover educational expenses, showcasing the practical benefits of this approach. By borrowing against their policy, they not only access necessary funds but also allow their cash value to continue growing, securing their financial future.
Take John, for example. He borrowed $50,000 from his cash value, which grew to around $150,000 after ten years. This illustrates the compounding advantages of his plan and how it can benefit families in the long run.
Together, we can navigate this journey towards financial stability, ensuring that your family’s needs are met with care and understanding.
Tax Advantages of Infinite Banking: Maximizing Family Wealth
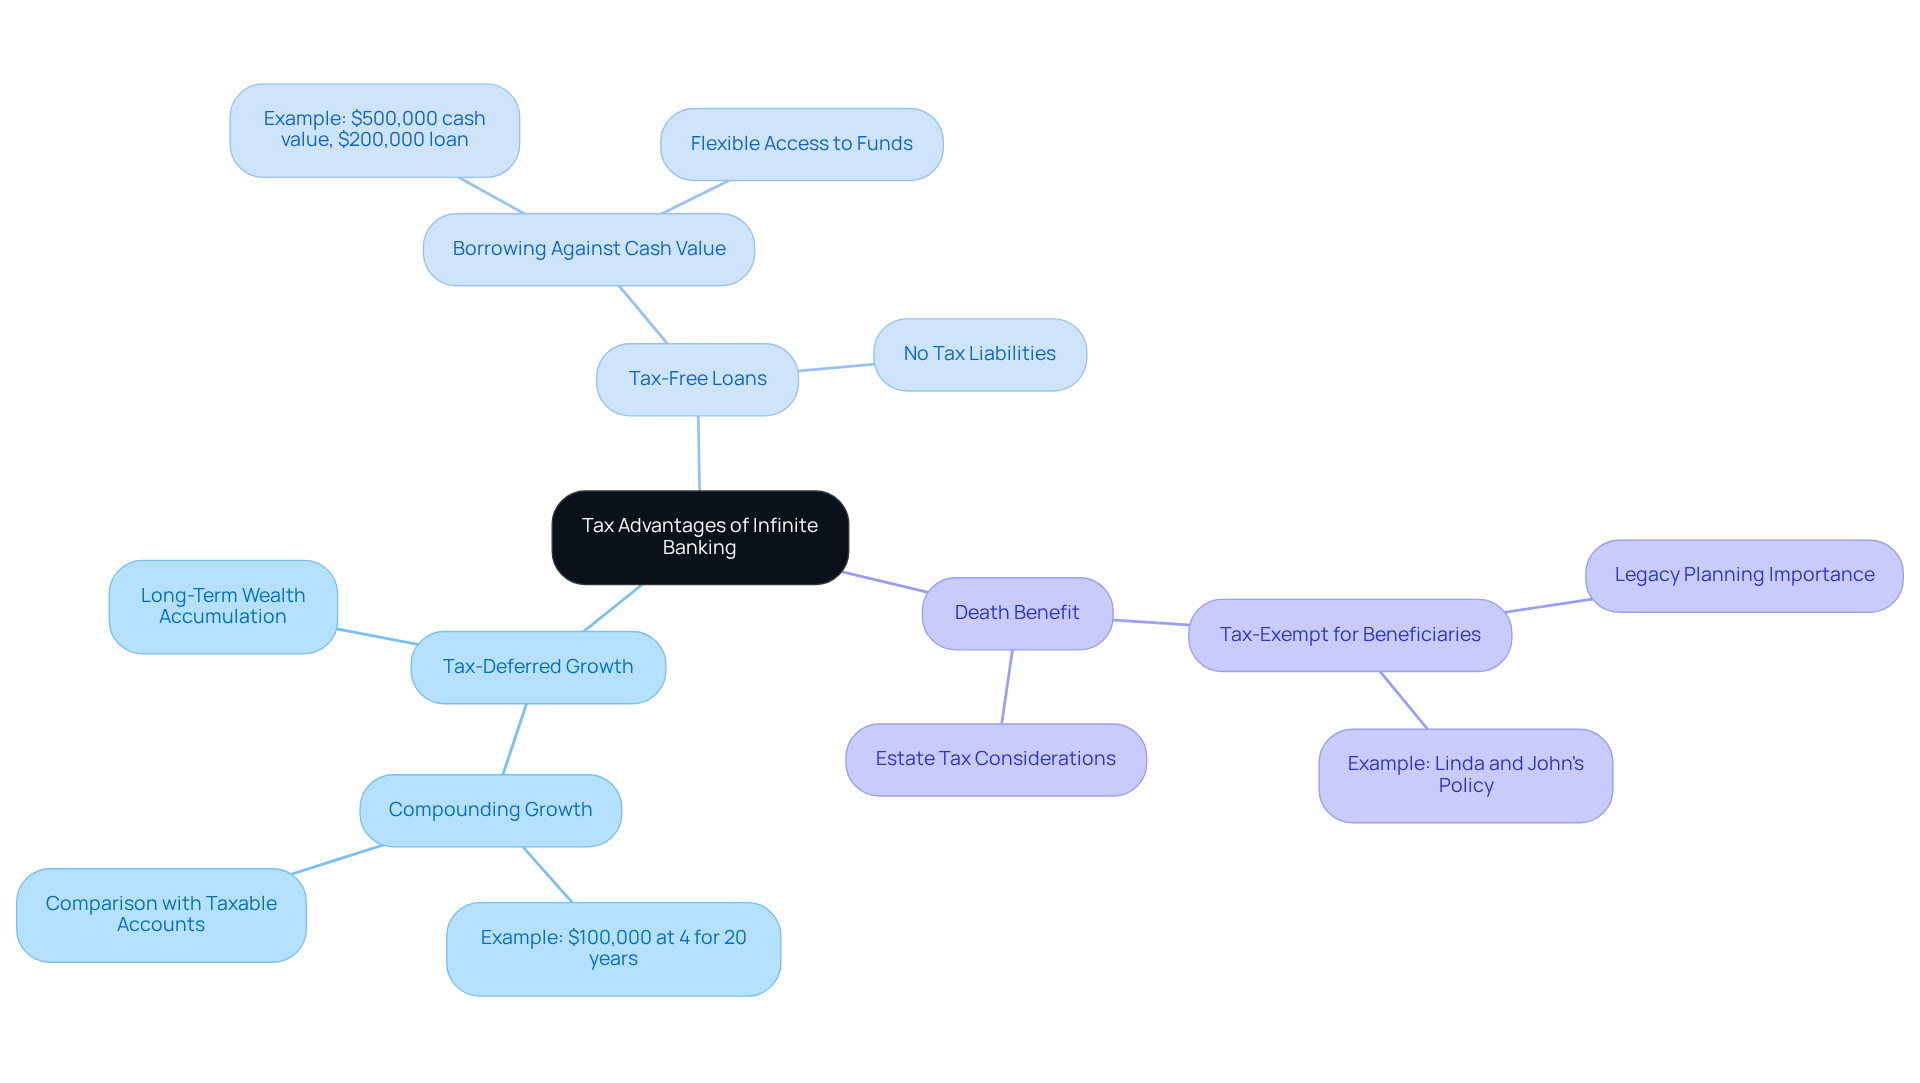
Infinite banking offers several tax advantages that can significantly enhance your family’s wealth.
-
Tax-Deferred Growth: Imagine the cash value within a whole life insurance policy growing without being taxed until you withdraw it. This allows your family to benefit from compounding growth over time, resulting in a more considerable resource reserve. For example, a plan starting with $100,000 at a 4% growth rate could expand to approximately $219,112 over 20 years. In contrast, a taxable account at the same rate with a 25% tax bracket would only grow to $180,611. This illustrates the powerful impact of tax-deferred growth on wealth accumulation, much like how Jay and Emma optimized their resources with Bright Advisers, achieving a sound financial strategy that alleviated their financial anxiety.
-
Tax-Free Loans: Picture being able to borrow against the cash value of your contract without incurring tax liabilities. These loans are not classified as taxable income, providing flexible access to funds for various needs, such as education or investment opportunities, without affecting cash value growth. For instance, if you have $500,000 in cash value, you can borrow $200,000 tax-free to invest in a business venture, enabling you to utilize your plan effectively. This adaptability shows how families, like Emily and Mark, can leverage their policies to achieve financial goals while balancing their careers and personal lives, ultimately gaining the freedom to choose their paths.
-
Death Benefit: The death benefit provided to your beneficiaries is usually tax-exempt, allowing your family to transfer wealth without facing tax liabilities. This aspect is crucial for legacy planning, as it ensures your economic future for the next generation. For instance, Linda and John, who invested in a whole life insurance policy, not only enjoyed tax-free income during retirement but also secured a substantial death benefit for their heirs, contributing to their overall estate planning strategy. It’s important to understand that while the death benefit is tax-free, it may count towards the estate value for estate tax purposes, a critical consideration in comprehensive legacy planning.
By understanding and applying these tax benefits, your family can enhance its wealth through the infinite banking pros and cons, establishing a strong economic base for future generations. As Nelson Nash, the originator of the Infinite Financing Concept, noted, “Infinite financing offers unique advantages for retirement planning compared to traditional retirement vehicles,” emphasizing the importance of strategic financial planning. Remember, together, we can navigate this journey toward financial security.
Asset Protection in Infinite Banking: Safeguarding Family Wealth
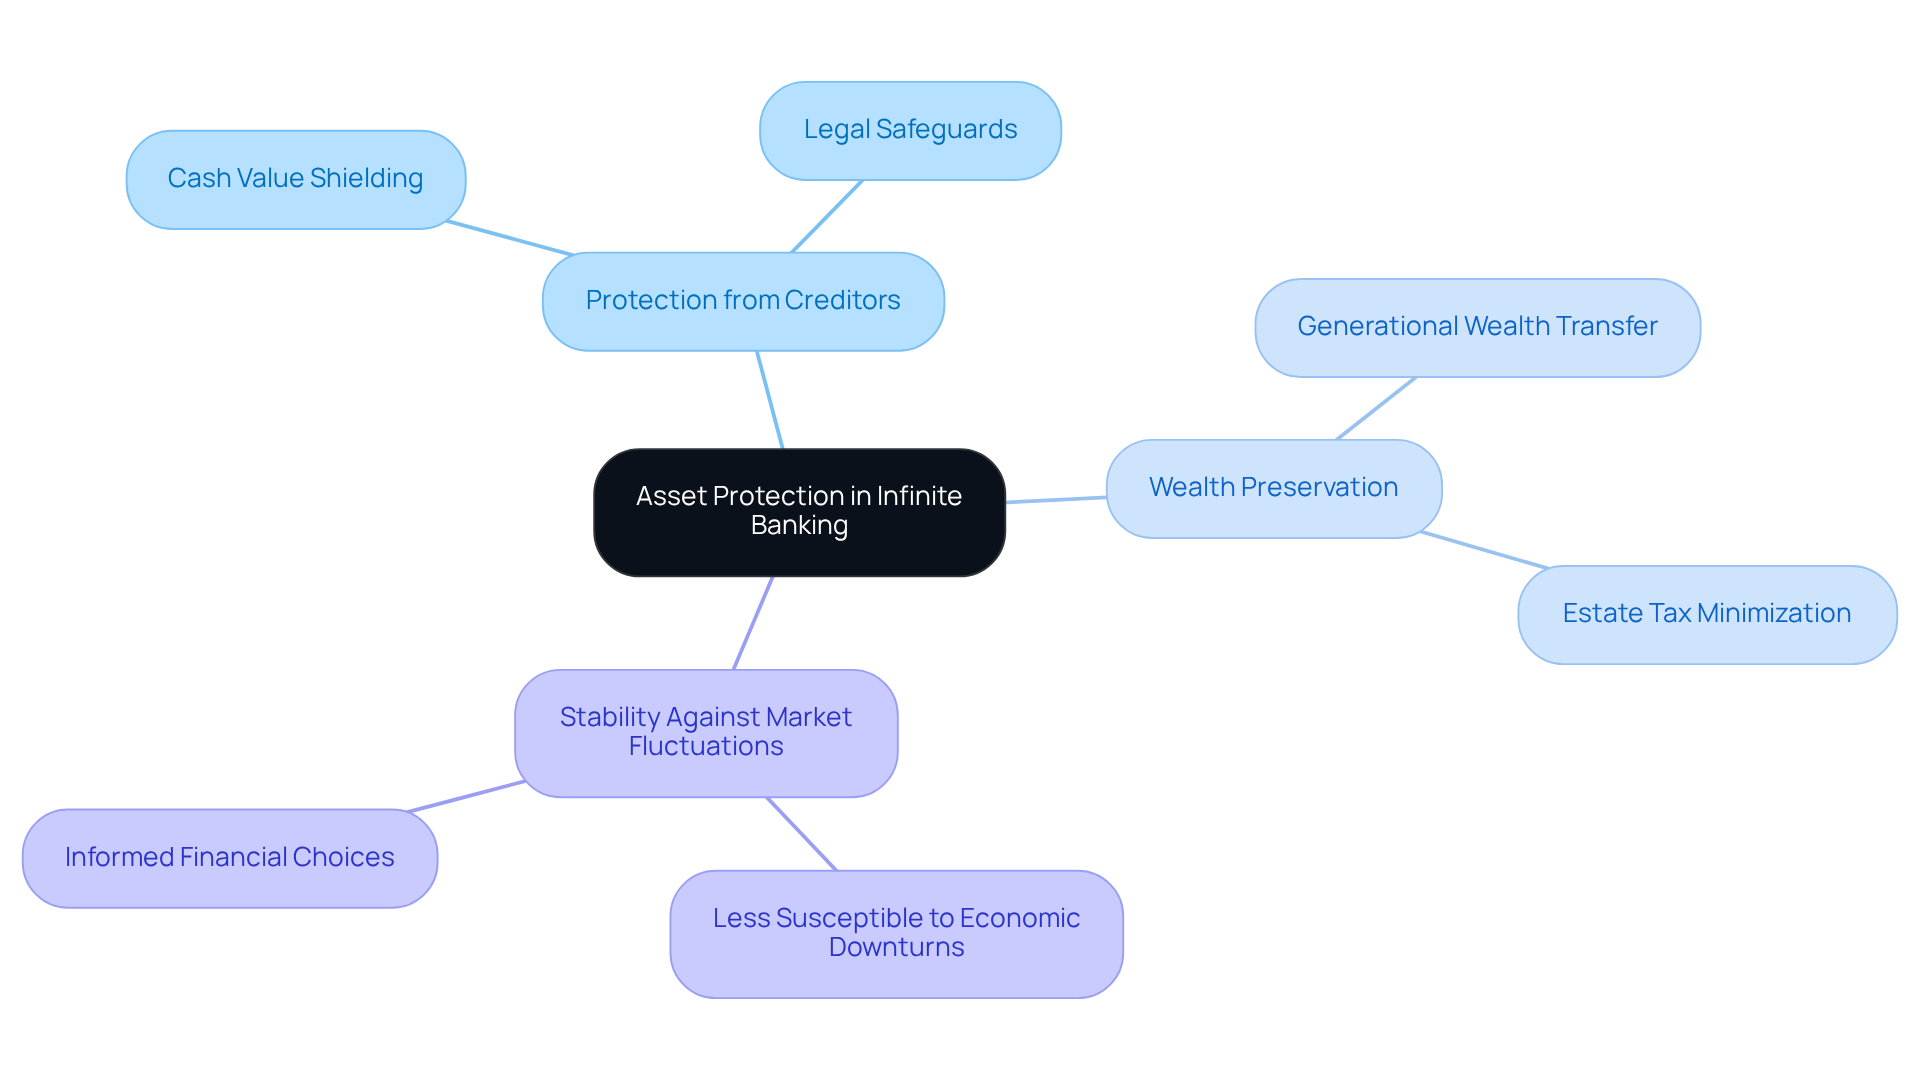
One of the main infinite banking pros and cons is the strong asset protection it offers for households. Imagine having a safety net that shields your family from unexpected financial challenges. In numerous jurisdictions, the cash value accumulated in life insurance contracts is protected from creditors, creating a vital layer of security for your loved ones. This protection is especially crucial for families looking to preserve their wealth against unforeseen monetary difficulties.
Whole life insurance policies often come with legal safeguards that can effectively shield assets from lawsuits and other financial obligations. This feature is essential for families aiming to maintain their wealth across generations, ensuring that their monetary legacy remains intact. It’s important to understand how these protections can provide peace of mind as you plan for your family’s future.
Furthermore, by utilizing infinite banking, families can create a secure economic base that reflects the infinite banking pros and cons, making it less susceptible to market fluctuations and economic downturns. This stability not only enhances your peace of mind but also empowers you to make informed financial choices without the fear of losing your hard-earned assets. As you navigate the complexities of wealth management, the protective advantages of whole life insurance become increasingly significant, allowing you to focus on what truly matters—your loved ones. Together, we can navigate this journey toward financial security.
Qualifying for Whole Life Policies: A Step for Young Families
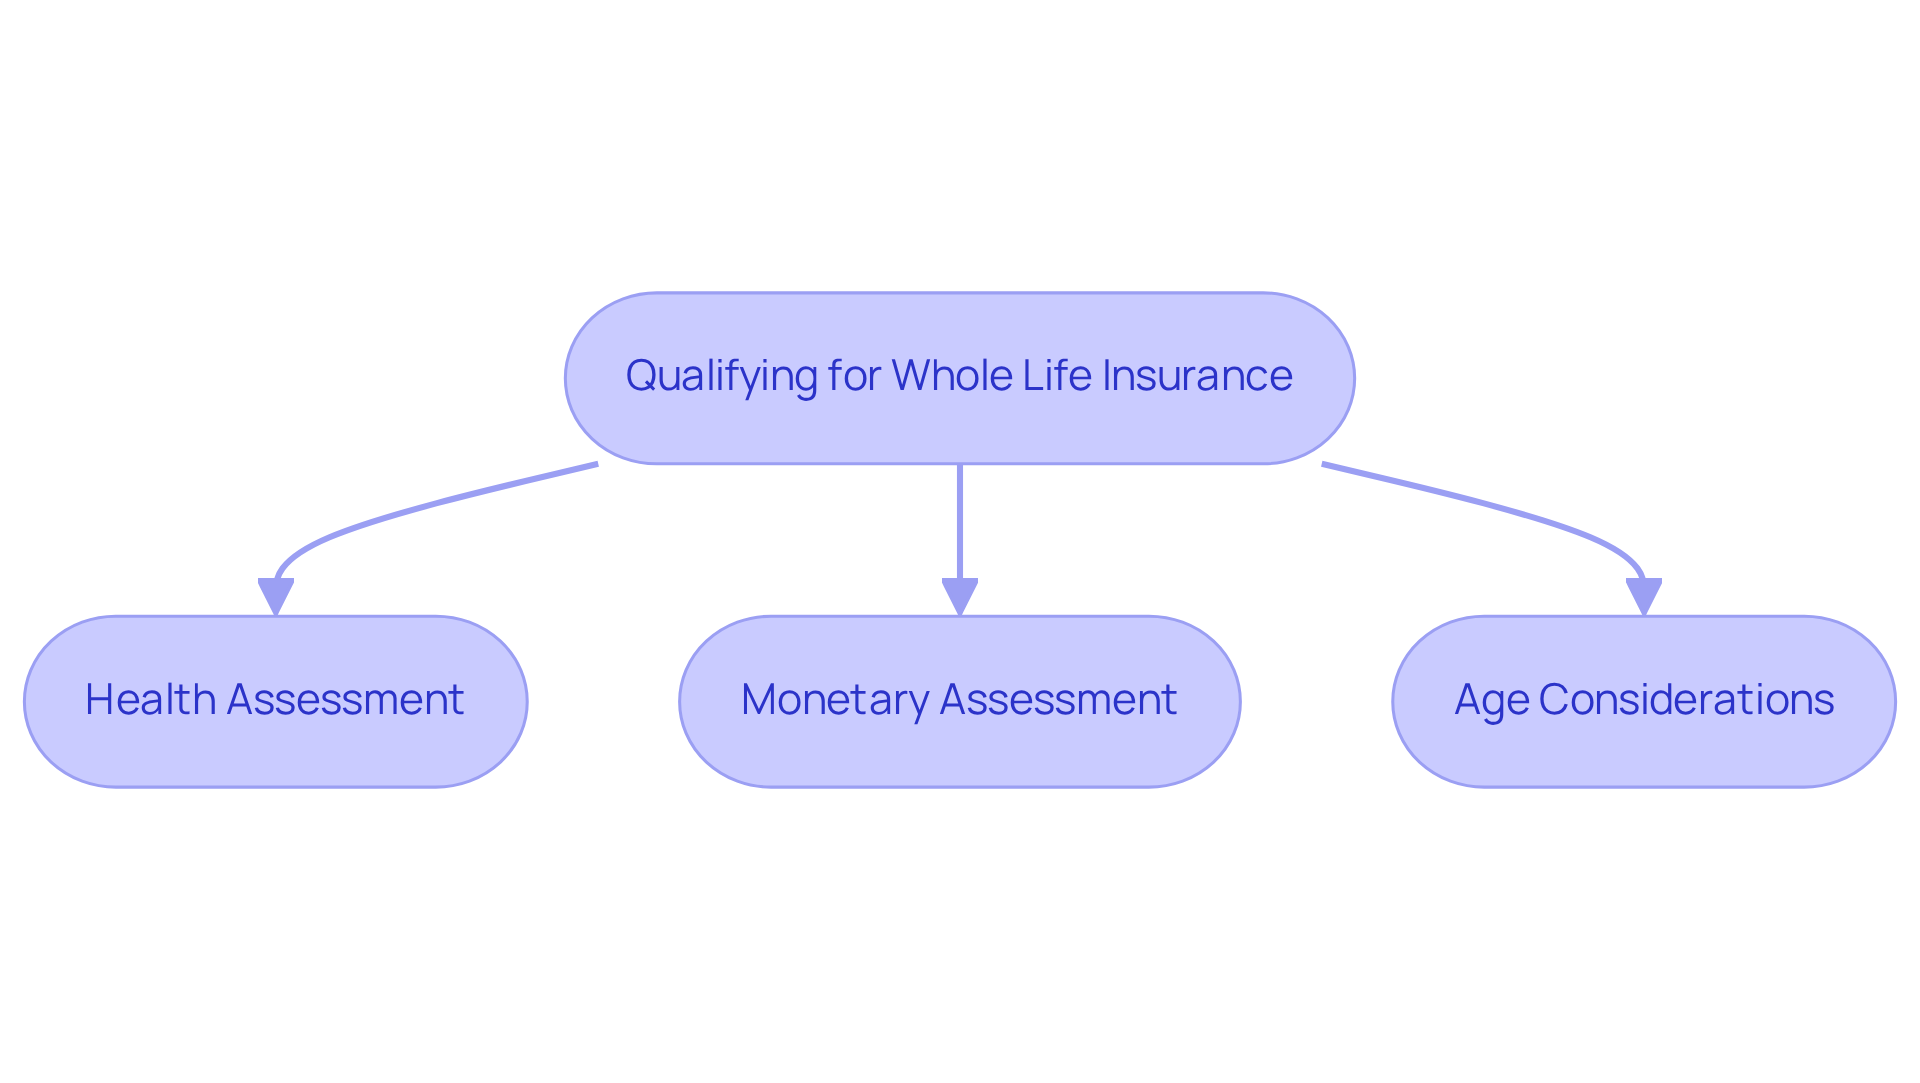
Qualifying for a whole life insurance plan is an important step for families evaluating the infinite banking pros and cons. Understanding this process can help you feel more confident in your financial decisions. Here are some key components to keep in mind:
- Health Assessment: Imagine the peace of mind that comes from knowing your health can influence your insurance premiums. Applicants often undergo a medical exam that evaluates their overall health, which can significantly affect costs. This assessment may include tests for vital signs, blood samples, and a review of health history. Full disclosure of health information is essential, as it helps insurers accurately gauge risk and avoids contestability issues later. Good health typically lowers premiums, while poor health can increase costs due to higher perceived risk.
- Monetary Assessment: It’s crucial to assess your family’s financial situation. Insurers perform a comprehensive examination of your economic circumstances to determine eligibility and suitable coverage amounts. This includes factors like income, debts, and future financial responsibilities, ensuring the plan aligns with your household’s financial goals. Remember, failing to repay loans secured by a whole life insurance policy can lead to lapses or diminished death benefits, so it’s important to stay informed.
- Age Considerations: If you’re a younger applicant, you may have an advantage when qualifying for whole life insurance, often benefiting from lower premiums. This is a favorable time for families to secure coverage, as premiums can rise with age and health changes. Additionally, it typically takes a couple of years for cash value to begin growing in a whole life policy, so starting early can be beneficial.
By understanding these elements, young families can more efficiently navigate the infinite banking pros and cons involved in acquiring whole life insurance. Together, we can establish a solid foundation for your family’s financial future, ensuring you have the support you need every step of the way.
Misinformation and Confusion: Clarifying Infinite Banking for Families
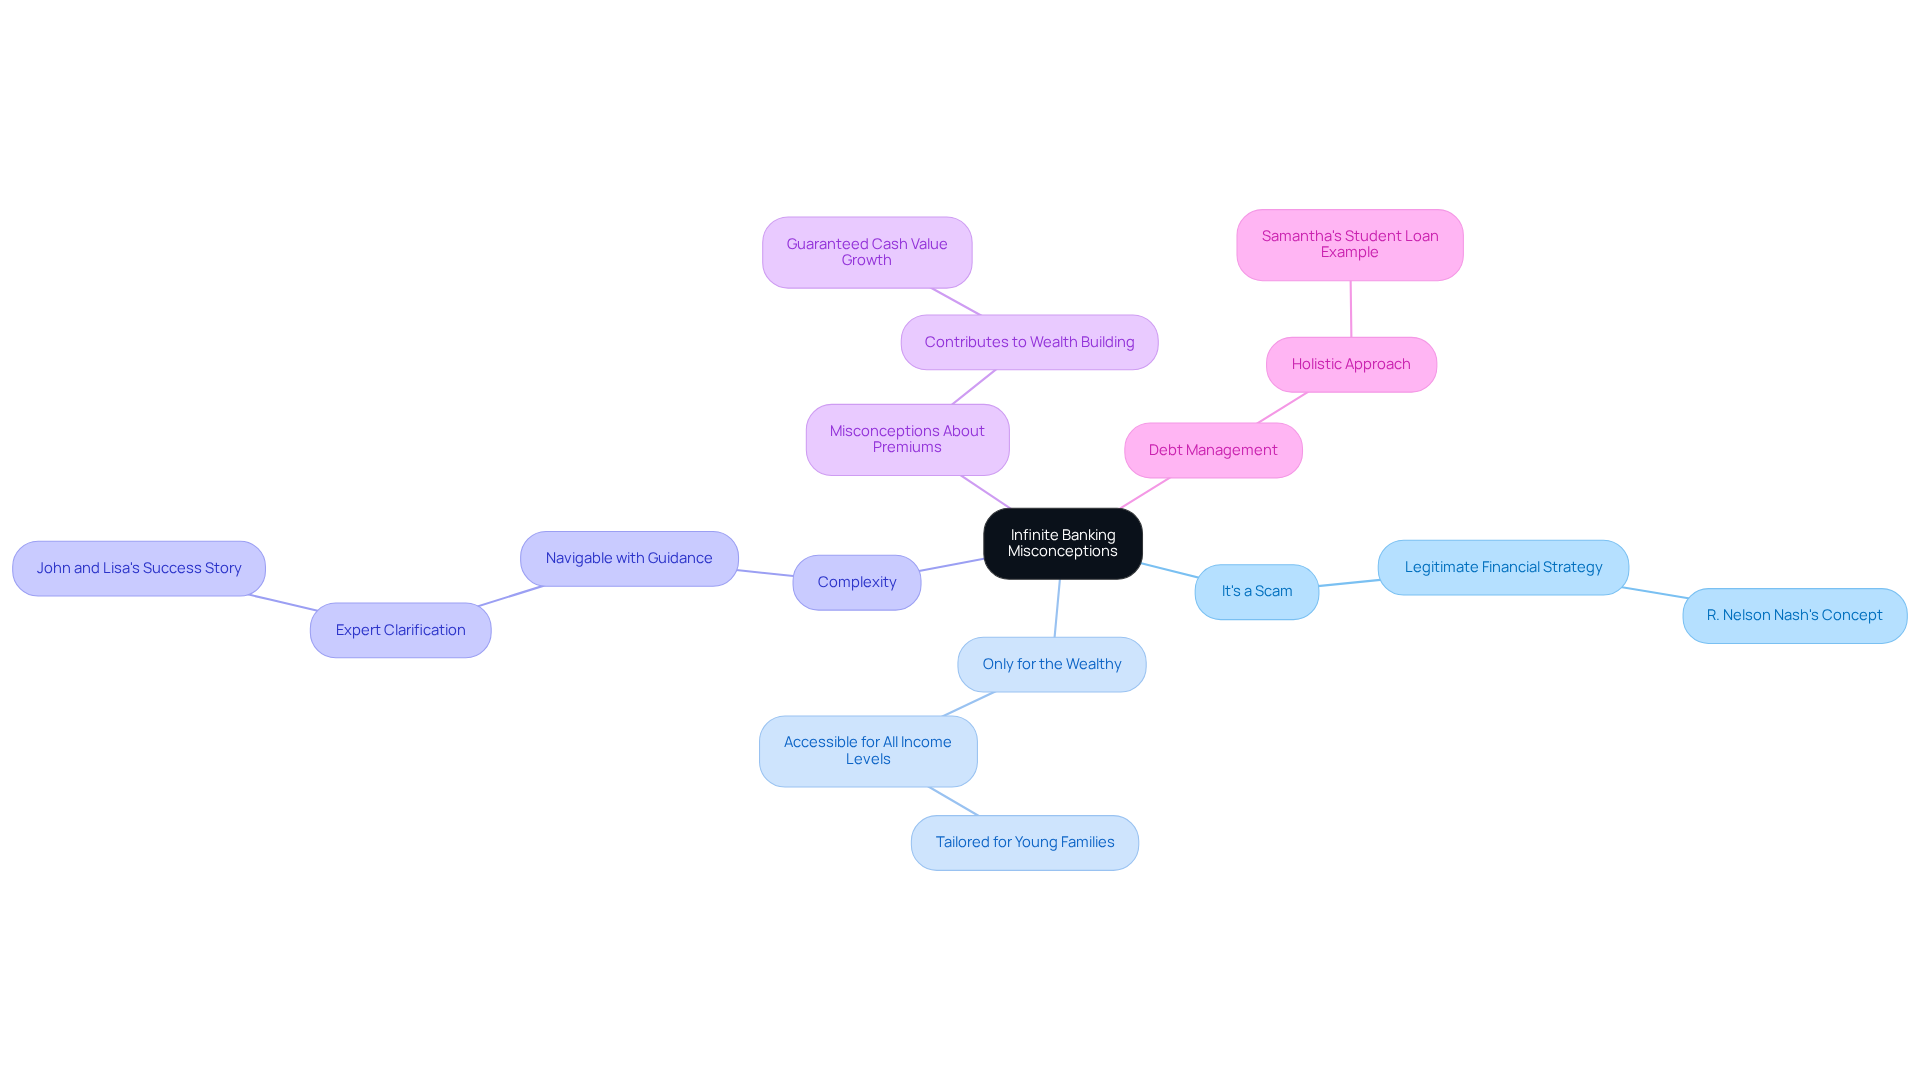
Misinformation about infinite finance can lead to confusion and hesitation among families. Let’s explore some common misconceptions together:
- It’s a Scam: Many people think that infinite banking is a scam. However, when understood and implemented correctly, it can be a legitimate financial strategy. R. Nelson Nash, who established the Infinite Banking Concept, emphasized that it involves creating a personal financial system using whole life insurance, which can help individuals achieve financial independence.
- Only for the Wealthy: There’s a belief that infinite banking is only for the wealthy. In reality, it can be tailored for households of all income levels. The structure of whole life insurance plans offers flexibility, making it a great option for young families looking to build wealth over time.
- Complexity: While the concept may seem complex, families can navigate it with the right guidance. Financial experts specializing in IBC can clarify the strategy, ensuring that families understand how to use their plans effectively. For instance, John and Lisa, a couple in their 40s, successfully implemented an IBC strategy to build cash value while enjoying tax benefits. This shows that with proper support, families can reap significant rewards.
- Misconceptions About Premiums: A common misconception is that whole life insurance plans come with high premiums. In fact, these premiums contribute to wealth building through cash value. By understanding the infinite banking pros and cons, families can recognize that the cash value grows steadily, providing a dependable financial foundation.
- Debt Management: Critics often argue that the money used for whole life premiums could be better invested elsewhere. However, IBC offers a holistic approach to managing debt while simultaneously building wealth. For example, Samantha, a young professional, utilized the cash value of her policy to pay off student loans while securing her financial future.
To effectively apply the Infinite Banking Concept, families should weigh the infinite banking pros and cons and consider seeking guidance from an advisor who specializes in this area. They can provide personalized strategies that align with each family’s unique financial situation and goals. By addressing these misunderstandings and pursuing expert advice, families can gain a clearer understanding of the potential of infinite finance as a tool for financial empowerment and legacy planning. Together, we can navigate this journey, aligning with Bright Advisers’ commitment to offering tailored wealth management solutions for young families.
Getting Started with Infinite Banking: A Guide for Young Families
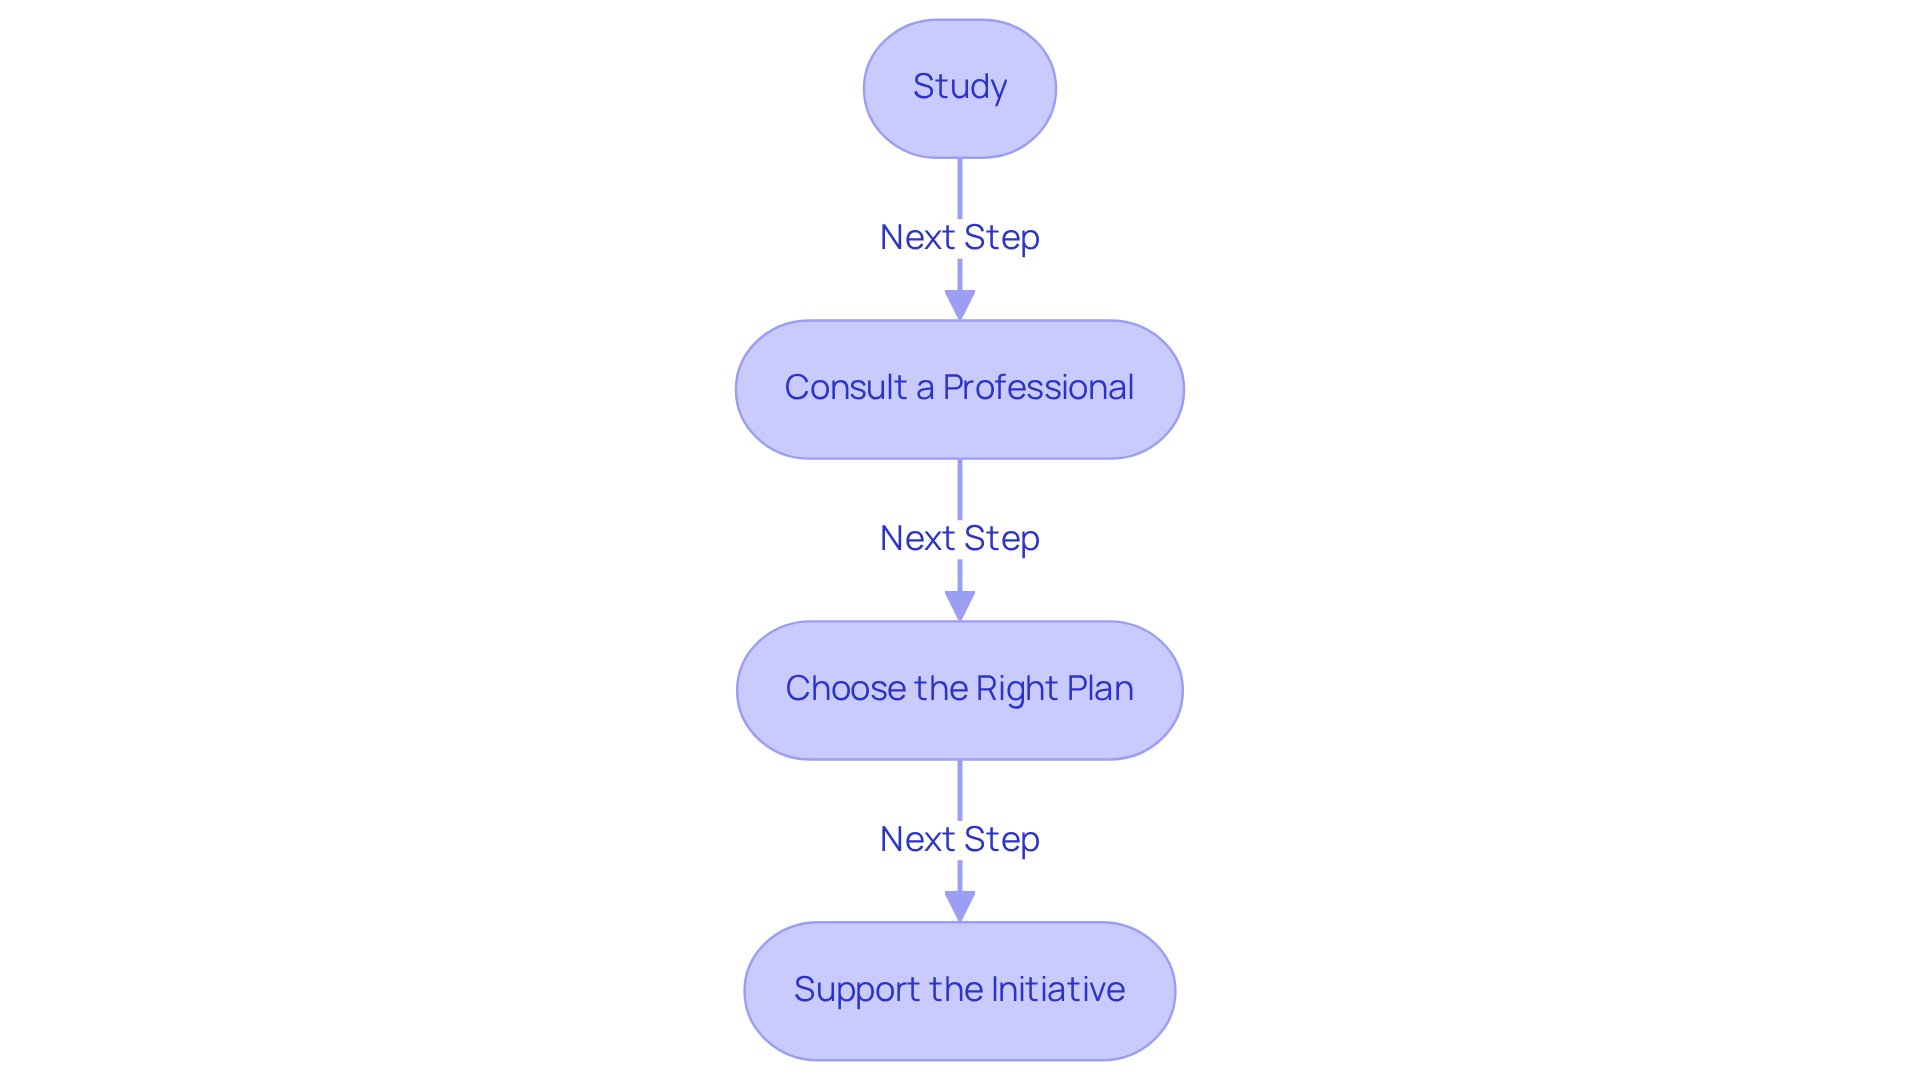
Embarking on the journey of infinite finance can feel overwhelming, but with a structured approach, it becomes manageable. Here are essential steps for families to consider:
-
Study: It’s important for families to thoroughly inform themselves about the infinite banking pros and cons, as well as understanding its potential advantages and consequences for their economic future. Imagine seeing a cash value exceeding $80,000 after 10 years with Volume-Based Financing, compared to only $15,000-20,000 with conventional financing.
-
Consult a Professional: Engaging with an advisor who specializes in infinite banking is crucial. This specialist can provide customized insights and strategies tailored to your family’s unique economic circumstances. As Nelson Nash wisely states, “You’re designing a system where your dollars are doing multiple jobs—providing protection, liquidity, and growth.” At Bright Advisers, we are dedicated to empowering young families by offering personalized wealth management solutions and educational resources, helping you navigate this intricate monetary strategy while keeping fund fees low to enhance accessibility.
-
Choose the Right Plan: Selecting a whole life insurance plan that aligns with your family goals is vital. Policies should be evaluated based on their cash value growth potential and the insurer’s financial strength. It’s advisable to work only with A+ rated companies that have long operating histories.
-
Support the Initiative: Consistent funding of your initiative is essential for building cash value over time. Families should aim to allocate a portion of their income—typically starting at 10-15%—to maximize the benefits of their investment. This method allows households to utilize their plans for investments, education financing, and unexpected costs.
Families who strategically utilize their policies for different monetary needs have effectively executed limitless funding. By following these steps and seeking professional advice, you can navigate the complexities of infinite banking pros and cons and secure your economic future. Together, we can explore how Infinite Banking could fit into your financial plans. We encourage you to schedule a complimentary analysis with a financial advisor at Bright Advisers to take the next step towards a brighter financial future.
Conclusion
Understanding the infinite banking concept can be a transformative financial strategy for young families, offering a unique blend of security, flexibility, and long-term wealth building. Imagine creating a personal banking system through whole life insurance policies that not only meets your immediate financial needs but also fosters a legacy of financial literacy and independence for future generations.
This article has explored the advantages and disadvantages of infinite banking, highlighting the importance of making informed decisions. Key benefits include:
- Tax-free growth
- Liquidity
- The ability to establish a solid financial legacy
Yet, it’s important to understand potential downsides, such as:
- High initial costs
- The necessity for long-term commitment
Recognizing these factors enables families to weigh the infinite banking pros and cons effectively.
Ultimately, the journey into infinite banking is one of empowerment. By consulting with financial advisors and carefully considering each aspect of this strategy, families can navigate the complexities of wealth management with confidence. Embracing this approach not only secures financial stability but also cultivates a nurturing environment for future generations. Together, we can take the first step towards infinite banking, unlocking a more prosperous financial future for your family.
Frequently Asked Questions
What is Bright Advisers’ approach to financial planning?
Bright Advisers offers a personalized approach to wealth management, focusing on young families and leveraging technology to create tailored strategies that enhance financial efficiency and support family values.
How does infinite banking work?
Infinite banking utilizes a specially designed whole life insurance policy that accumulates cash value over time. This cash value can be accessed through policy loans for needs such as education or emergencies, providing liquidity and adaptability for families.
What are the advantages of infinite banking for young families?
The advantages include tax-free growth of cash value, liquidity through policy loans without traditional bank approvals, monetary control allowing families to dictate loan terms, and legacy planning that facilitates tax-efficient wealth transfer to future generations.
How does Bright Advisers support families in implementing infinite banking?
Bright Advisers provides customized wealth management options, educational resources, insights on reducing fund fees, and guidance in assessing financial conditions and establishing goals to optimize the benefits of infinite banking.
What is the importance of legacy planning in infinite banking?
Legacy planning ensures that wealth is transferred to future generations in a tax-efficient manner, with death benefits typically received income tax-free by beneficiaries. Responsible management of loan repayments is crucial to prevent policy lapses and maintain the economic legacy.
What should families consider when starting with infinite banking?
Families should assess their current financial condition and establish specific goals for utilizing loans to optimize the advantages of infinite banking and secure a brighter financial future.
List of Sources
- Bright Advisers: Personalized Financial Planning for Infinite Banking
- highfivedad.com (https://highfivedad.com/15-quotes-to-teach-kids-about-money)
- 2024 Schwab Modern Wealth Survey Shows Increasing Financial Confidence From Generation to Generation and Younger Americans Investing at an Earlier Age (https://pressroom.aboutschwab.com/press-releases/press-release/2024/2024-Schwab-Modern-Wealth-Survey-Shows-Increasing-Financial-Confidence-From-Generation-to-Generation-and-Younger-Americans-Investing-at-an-Earlier-Age/default.aspx)
- AI could make financial advice more equitable and resilient (https://weforum.org/stories/2025/06/ai-financial-advice-accessible)
- Key Financial Literacy Statistics in 2023 (https://annuity.org/financial-literacy/financial-literacy-statistics)
- GoHenry | blog – not found (https://gohenry.com/us/blog/financial-education/40-quotes-to-help-your-child-learn-the-value-of-money)
- Advantages of Infinite Banking: Financial Security for Young Families
- Infinite Banking: Create Your Financial Legacy – I&E | Whole Life & Infinite Banking Strategies (https://insuranceandestates.com/infinite-banking-legacy)
- Is Infinite Banking A Smart Financial Strategy? | Canadian LIC (https://canadianlic.com/blog/is-infinite-banking-a-smart-financial-strategy)
- Infinite Banking: Unlocking Wealth with Whole Life Insurance | JRC Insurance Group™ (https://jrcinsurancegroup.com/infinite-banking-strategy)
- Infinite Banking | Using Life Insurance to Become Your Own Banker (https://lifeinsure.com/infinite-banking-using-life-insurance-to-become-your-own-banker)
- Infinite Banking: Using Life Insurance as a Source of Liquidity – NerdWallet (https://nerdwallet.com/article/insurance/infinite-banking)
- Disadvantages of Infinite Banking: Risks Young Families Should Consider
- Infinite Banking: What It Is and Who It’s For (https://moneygeek.com/insurance/life/infinite-banking)
- Infinite Banking with IUL: A Step-by-Step Guide to Becoming Your Own Banker | Capital for Life (https://capitalforlife.com/blog/iul-infinite-banking)
- Infinite Banking Concept in Canada: A Comprehensive Analysis — EverNorth Wealth Advisory (https://evernorthwealth.ca/articles/infinite-banking-strategy)
- Certified Financial Planner in Los Angeles – Retire Confidently and Invest Smarter (https://thepeakfp.com/blog/is-whole-life-insurance-worth-it)
- Infinite Banking: A Financial Advisor’s Review [Pros & Cons] (https://physiciansthrive.com/financial-planning/infinite-banking)
- Cash Value Loans: Accessing Funds Through Infinite Banking
- Infinite banking explained: Is this popular TikTok financial trend worth the hype? | Facet (https://facet.com/insurance-planning/infinite-banking-explained-is-this-popular-tiktok-financial-trend-worth-the-hype)
- Infinite Banking: What It Is and Who It’s For (https://moneygeek.com/insurance/life/infinite-banking)
- Whole Life Insurance & the “Infinite Banking” Concept: Too Good to be True? (https://bandcfinancial.com/whole-life-insurance-the-infinite-banking-concept-too-good-to-be-true)
- What is Infinite Banking, and How Does it Work? (https://b2broker.com/news/what-is-infinite-banking-and-how-can-you-make-it-work)
- Infinite Banking Gains Endorsement from Top Financial Advisors as Market Volatility Increases (https://cbs42.com/business/press-releases/ein-presswire/839285610/infinite-banking-gains-endorsement-from-top-financial-advisors-as-market-volatility-increases)
- Tax Advantages of Infinite Banking: Maximizing Family Wealth
- allstate.com (https://allstate.com/resources/life-insurance/what-is-infinite-banking)
- Infinite Banking | Using Life Insurance to Become Your Own Banker (https://lifeinsure.com/infinite-banking-using-life-insurance-to-become-your-own-banker)
- Navigating the Tax Advantages of Whole Life Insurance and Infinite Banking (https://linkedin.com/pulse/navigating-tax-advantages-whole-life-insurance-infinite-ezg7c)
- Top 10 Pros and Cons of Infinite Banking [2025 Updated Guide] – I&E | Whole Life & Infinite Banking Strategies (https://insuranceandestates.com/pros-and-cons-of-the-infinite-banking-concept)
- Asset Protection in Infinite Banking: Safeguarding Family Wealth
- Bank on Yourself – Problems with Infinite Banking Concept | White Coat Investor (https://whitecoatinvestor.com/infinite-banking-bank-on-yourself)
- A bumper sale of ‘jumbo’ life insurance policies | News | HSBC Holdings plc (https://hsbc.com/news-and-views/news/hsbc-news-archive/a-bumper-sale-of-jumbo-life-insurance-policies)
- Our record-breaking life insurance policy | HSBC news (https://hsbc.com/news-and-views/news/hsbc-news-archive/our-record-breaking-life-insurance-policy)
- Northwestern Mutual Expands Suite of Insurance Products to Help Families and Businesses Protect Their Legacies (https://news.northwesternmutual.com/2025-07-01-Northwestern-Mutual-Expands-Suite-of-Insurance-Products-to-Help-Families-and-Businesses-Protect-Their-Legacies)
- Qualifying for Whole Life Policies: A Step for Young Families
- allstate.com (https://allstate.com/resources/life-insurance/what-is-infinite-banking)
- Life Insurance: What Every Woman Should Know – 1891 Financial Life (https://1891financiallife.com/life-insurance-what-every-woman-should-know-before-choosing-a-policy)
- Understanding the Life Insurance Application Process (https://sofi.com/learn/content/understanding-the-life-insurance-application-process)
- 8 Things To Know Before Submitting a Life Insurance Application (https://money.com/things-to-know-before-submitting-a-life-insurance-application)
- What do Life Insurance Medical Exams Test For? [How to Avoid the Blood Draw] (https://insurancebrokersusa.com/what-do-life-insurance-medical-exams-test-for)
- Misinformation and Confusion: Clarifying Infinite Banking for Families
- Infinite Banking Concept: Everything You Need to Know (https://livingwealth.com/infinite-banking)
- 5 Lies Infinite Banking ‘Experts’ Are Telling You – Spicer Capital (https://spicercapital.com/ibc-lies)
- How to get more involved with Infinite Banking | McFie Insurance Podcast (https://mcfieinsurance.com/podcasts/how-to-get-more-involved-with-infinite-banking)
- YouTube (https://m.youtube.com/watch?v=rdygzK_2gYk)
- Getting Started with Infinite Banking: A Guide for Young Families
- Infinite Banking: A Comprehensive Guide to Becoming Your Own Banker in 2025 (https://pinnaclequote.com/blog/term-rider-infinite-banking)
- Volume-Based Banking: Your Alternative to Traditional Banks – I&E | Whole Life & Infinite Banking Strategies (https://insuranceandestates.com/beyond-the-10-rule-how-infinite-banking-maximizes-wealth-through-volume)
- The Guide to Infinite Banking: How It Works & Who It’s For (https://quotacy.com/infinite-banking)
- E220: How Infinite Banking Expert Makes Investments Using His Policies (https://livingwealth.com/how-infinite-banking-expert-makes-investments-using-his-policies)
- Industry Statistics (https://investmentadviser.org/industry-snapshots)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About Kevin