

Overview
This article gently guides you through the crucial due dates for SEP IRA contributions, highlighting the key dates and rules that both individuals and businesses should keep in mind to maximize retirement savings.
It’s vital to make your contributions by the typical deadline of April 15, with extensions allowing until October 15. Missing these dates can lead to penalties and lost tax benefits, which is why proactive financial planning is so important.
Imagine the peace of mind that comes from knowing you’re taking the right steps for your family’s future. We’re here for you, ready to support you in this journey toward financial security.
Key Highlights:
- Bright Advisers offers tailored financial planning for families, focusing on SEP IRA contributions.
- For 2025, individuals under 50 can contribute up to $7,000 to a SEP IRA; those over 50 can contribute up to $8,000.
- Contributions are tax-deductible, allowing businesses to reduce taxable income significantly.
- Typically, SEP IRA contributions must be made by April 15 of the following year, with extensions allowing until October 15.
- Missing contribution deadlines can incur a 6% tax penalty on excess amounts.
- The contribution limit for SEP IRAs in 2025 is set at 25% of earnings, with a maximum of $70,000.
- Eligibility for contributions requires employees to be at least 21 years old, have worked for three of the last five years, and earn a minimum of $750.
- Employers must report contributions on IRS Form 5500 if they have over 100 participants.
- Common mistakes include missing deadlines, over-contributing, and misunderstanding eligibility requirements.
- Setting up a SEP IRA involves selecting a financial institution, completing paperwork, opening an account, and maintaining records.
Introduction
Understanding the intricacies of SEP IRA contributions is essential for families who wish to secure their financial future. Imagine the relief of significantly reducing taxable income while enhancing your retirement savings. Knowing the key dates for contributions can truly make all the difference. But what if these critical deadlines are overlooked? It’s important to understand the vital dates and considerations surrounding SEP IRA contributions. This article aims to equip you with the knowledge to navigate your financial landscape confidently, helping you avoid costly mistakes. Together, we can navigate this journey toward a more secure future for your family.
Bright Advisers: Tailored Financial Planning for SEP IRA Contributions
At Bright Advisers, we understand the unique challenges that families with young children face when it comes to financial planning. Our focus is on developing customized monetary strategies tailored to your specific needs. When considering the due date for SEP IRA contributions, we emphasize a personalized approach that takes into account your family’s financial situation, goals, and timelines.
Imagine being able to reduce your taxable income significantly—this is possible because the due date for SEP IRA contributions allows businesses to deduct these contributions from their taxes in the year they are made. For 2025, if you’re under age 50, you can contribute up to $7,000, while those over 50 can contribute up to $8,000. This presents a wonderful opportunity for families to save more for their future.
With the help of advanced technology, we ensure that you can navigate the complexities of SEP IRAs, allowing you to focus on what truly matters—your family’s future. The flexibility to modify your inputs each year means you can adjust your savings strategies as your financial situation evolves.
This client-first philosophy not only simplifies the input process but empowers families to make informed decisions about their retirement savings. Remember, we’re here for you every step of the way, and together, we can navigate this journey to secure a brighter financial future for your family.

SEP IRA Contribution Deadline: Key Dates You Must Remember
It is vital to understand the due date for SEP IRA contributions in order to maximize your family’s retirement savings. Typically, contributions must be made by the due date for SEP IRA contributions, which is usually April 15 of the following year. However, if you file for an extension, you can continue contributing until the due date for SEP IRA contributions, which is often October 15. Missing these important dates can lead to significant tax penalties; for instance, failing to withdraw excess funds on time incurs a 6% tax on the surplus amount. It’s essential to mark these key dates on your calendar to avoid losing out on valuable tax benefits and opportunities for retirement savings.
Imagine if you were among the approximately 30% of individuals who overlook these deadlines—this highlights the importance of proactive planning. By staying on top of these timelines, families can not only maximize their retirement savings but also ensure a more secure financial future. As Megan Russell, Chief Operating Officer and CFP®, wisely points out, ‘Staying informed about funding deadlines is essential for effective retirement planning.’
Furthermore, for 2025, the contribution limit is set at 25% of earnings up to $70,000, reinforcing the need to keep track of these deadlines. Remember, payments to a SEP IRA are tax-deductible for employers and not subject to federal income tax for employees until distributions occur, further enhancing the advantages of timely payments. Together, we can navigate this journey towards a brighter financial future for your family.

Consequences of Missing the SEP IRA Contribution Deadline
Missing the due date for SEP IRA contributions can result in serious repercussions that impact your family’s financial well-being. Imagine forfeiting the chance to decrease your taxable income for the year; this can feel overwhelming. Additionally, late payments can result in penalties that only add to your worries. For instance, if surplus deposits aren’t removed promptly, a 6% tax on the excess amount can significantly diminish your savings.
It’s important to understand that the long-term effects on your retirement savings can be harmful. Missed payments hinder the growth potential of your investments, ultimately impacting your economic stability during retirement. Tax experts emphasize that being aware of the due date for SEP IRA contributions is crucial. Even minor oversights can lead to costly penalties and missed opportunities for tax deductions.
Families who have faced penalties for late payments often find themselves in a difficult position, needing to adjust their financial plans to accommodate unexpected expenses. Staying informed and proactive about the due date for SEP IRA contributions is essential for safeguarding your retirement future. Together, we can navigate this journey and ensure that your family’s financial goals remain on track.

SEP IRA Contribution Limits: What You Need to Know
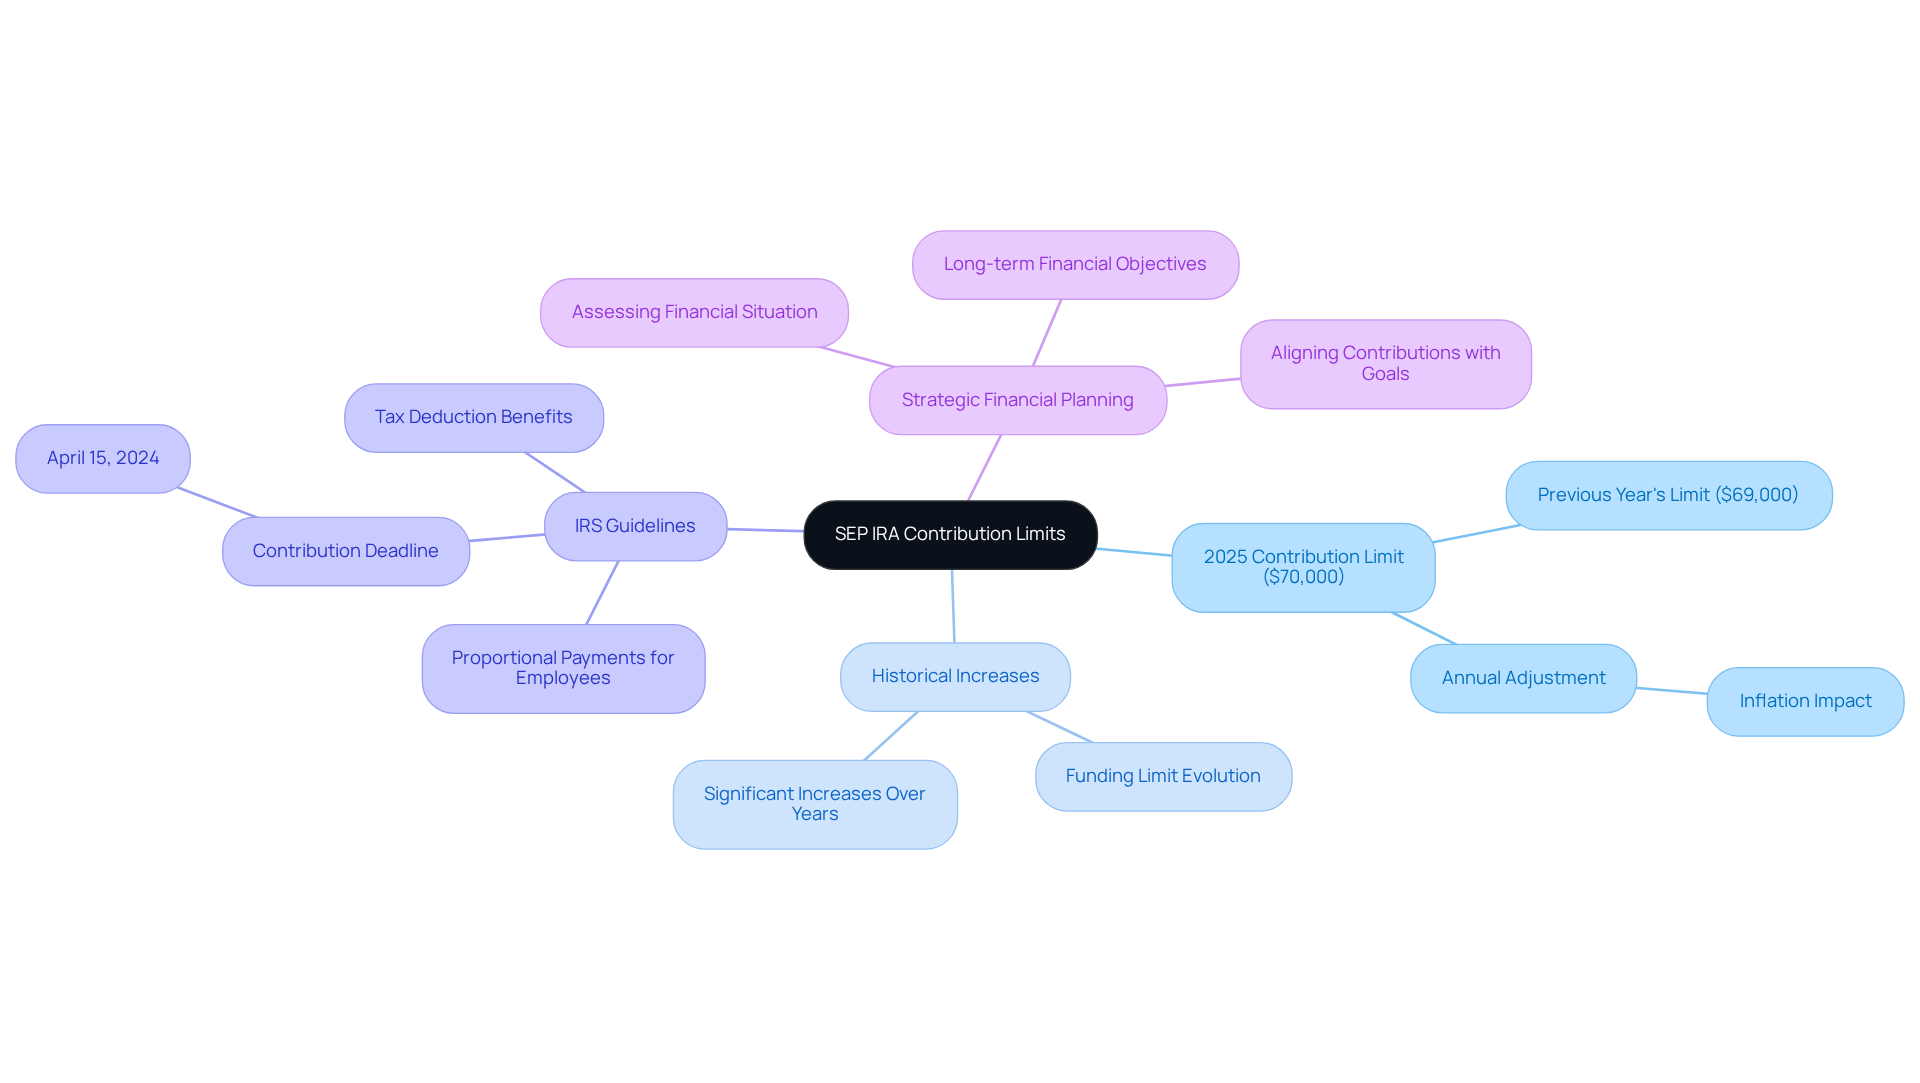
As we look ahead to 2025, the limit for a SEP IRA has been set at the lesser of 25% of your compensation or $70,000. This reflects a $1,000 increase from last year’s cap of $69,000. These limits are subject to annual adjustments, making it essential for families to stay informed about their financial options. When considering donations, it’s vital for families to assess their overall financial situation and retirement goals. This approach ensures they are optimizing tax advantages while effectively planning for their future.
It’s also important to understand that payments must be proportional across all eligible employees, as stipulated by IRS guidelines. Historically, SEP IRA funding limits have evolved, with significant increases over the years to accommodate inflation and changing economic conditions. Families can enhance their contributions by aligning them with their income levels and ensuring compliance with IRS guidelines.
Imagine a family-owned business that contributes the maximum allowable amount to their SEP IRA. This strategic decision not only boosts their retirement savings but also allows them to benefit from valuable tax deductions. Such an approach secures their financial future and sets a precedent for fiscal responsibility that can be passed down to future generations. Remember, to be deductible for the year, donations must be made by the due date for SEP IRA contributions, which is April 15, 2024, for the 2024 donation year.
By grasping the nuances of SEP IRA contributions, families can make informed choices that align with their long-term financial objectives. Together, we can navigate this journey, ensuring that your family’s financial future is bright and secure.
Eligibility Requirements for SEP IRA Contributions
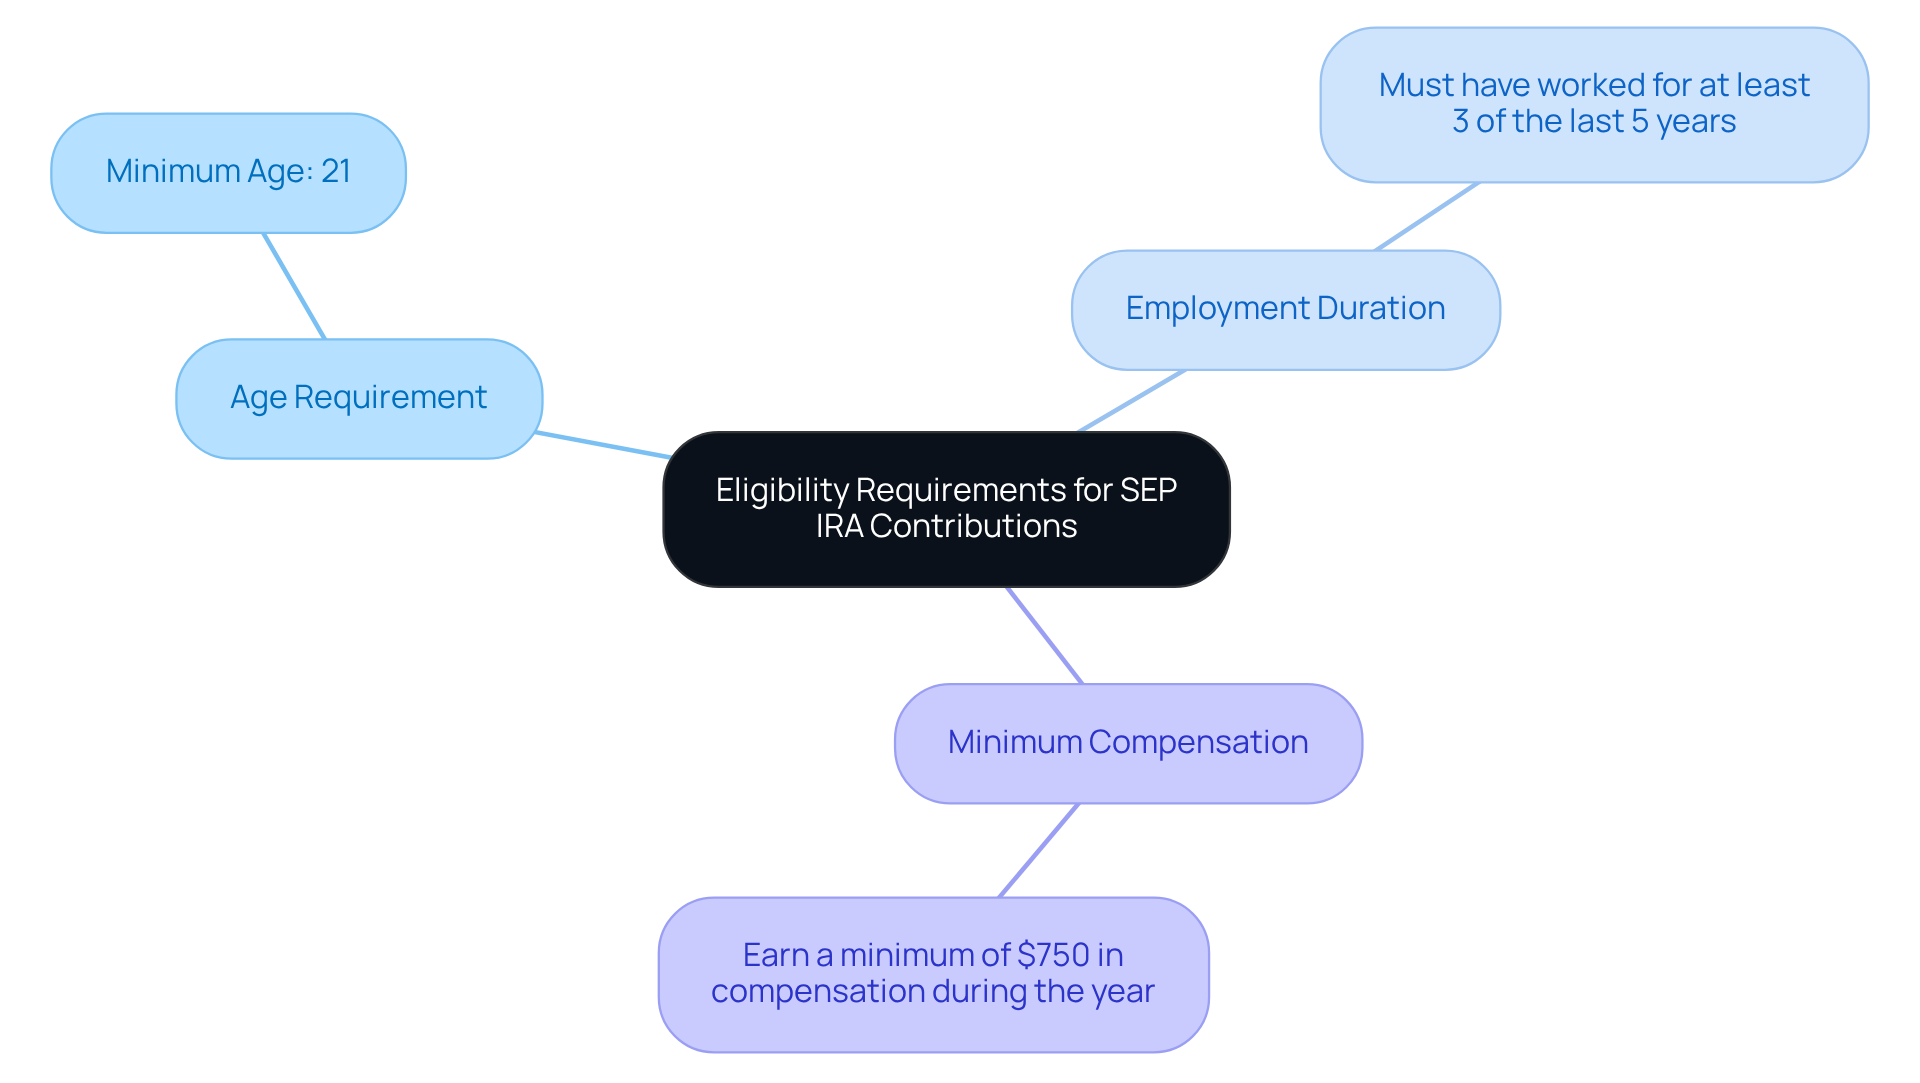
If you’re a business owner or self-employed, contributing to a SEP IRA can be a wonderful step toward securing your family’s financial future. To ensure that all eligible employees can benefit, there are specific requirements they must meet. For instance, employees need to:
- Be at least 21 years old
- Have worked for the employer for at least three of the last five years
- Earn a minimum of $750 in compensation during the year
This structured approach helps create equitable access to retirement savings opportunities for everyone involved.
Imagine the peace of mind that comes with knowing your retirement savings potential is significant. In 2024, the funding limit for a SEP IRA is set at 25% of an employee’s overall compensation, with a maximum contribution of $69,000, which will increase to $70,000 in 2025. This is especially beneficial for self-employed individuals, who can contribute based on their net earnings, allowing for greater savings.
It’s important to understand that contributions to a SEP IRA are made by employers on behalf of employees. This ensures that all qualified employees benefit equally, reinforcing the idea that we’re all in this together. Financial advisors often stress the importance of knowing who can contribute to a SEP IRA, as this knowledge can significantly influence your retirement planning. Dayana Yochim, a former authority on retirement and investing, encapsulates this sentiment beautifully: “Ultimately, it’s all about answering one key question: Am I saving enough, and in the right accounts?”
With nearly 54.4% of households possessing retirement accounts, understanding these requirements is essential for families looking to secure their financial futures. Remember, the percentage of income contributed to a SEP IRA must be consistent across all eligible employees, reinforcing the uniformity requirement for contributions. Together, we can navigate this journey toward financial security, ensuring that your family’s dreams are within reach.
Tax Benefits of Contributing to a SEP IRA
Imagine a future where your family’s financial security is within reach. Contributing to a SEP IRA can be a powerful step towards achieving that dream. Not only are contributions tax-deductible, but they also allow you to lower your taxable income for the year, potentially leading to significant tax savings that can ease your financial worries.
As we look towards 2025, it’s important to know that self-employed individuals can contribute up to 25% of their net self-employment income or $70,000, whichever is less. This means you can effectively reduce your tax liability while simultaneously enhancing your retirement savings.
Furthermore, the funds within a SEP IRA grow tax-deferred until you decide to withdraw them. This offers a wonderful opportunity for greater accumulation over time, allowing your savings to flourish.
This combination of immediate tax relief and long-term growth makes SEP IRAs not just a financial tool, but a nurturing option for households like yours, aiming to secure an economic future while minimizing current tax burdens. Together, we can navigate this journey towards financial stability and peace of mind.

How to Set Up a SEP IRA: A Step-by-Step Guide
Establishing a SEP IRA can feel overwhelming, but it’s a straightforward process that families can navigate with ease. Let’s walk through it together:
- Select a Financial Institution: Choose a brokerage firm that resonates with your family’s needs, like Vanguard, Fidelity, or Charles Schwab.
- Complete the Required Paperwork: Fill out the necessary documents, including the SEP IRA plan document that outlines the terms of the plan. Remember, providing a written agreement to eligible employees is essential in this process.
- Open the SEP IRA Account: Once your paperwork is complete, it’s time to establish the account with your chosen institution.
- Fund the Account: Make your deposits to the SEP IRA before the tax return due date to enjoy those valuable tax benefits. Contributions can vary each year based on your family’s economic circumstances, allowing you the flexibility you need.
- Maintain Records: Keep detailed records of donations and related documents for tax purposes, ensuring you’re prepared for the future.
This organized approach not only streamlines the setup procedure but also allows families to focus on their broader economic goals.
Many families have successfully established SEP IRAs by embracing the adaptability of payments. However, it’s important to recognize that challenges can arise, such as understanding the equal input requirement for all qualified workers, which can feel like a financial strain for small business owners. Financial advisors emphasize the importance of clear communication with employees regarding the SEP terms and payments, ensuring everyone is informed and aligned. As Chirag Chauhan, a CFP and financial advisor, wisely notes, “The employer can modify the percentage of input each year and can even choose to suspend payments for a year, for example, if the company is facing economic challenges.”
By following these steps and being aware of potential challenges, families can effectively set up a SEP IRA, paving the way for a secure financial future. Together, we can navigate this journey, ensuring that your family’s financial goals are within reach.

Reporting Requirements for SEP IRA Contributions
When contributing to a SEP IRA, it’s crucial to understand the specific reporting requirements that can impact your family’s financial future. For employers with more than 100 participants in the plan, payments must be reported on IRS Form 5500. Additionally, all contributions need to be documented on the employee’s W-2 form. It’s important to note that employees must earn at least $650 in compensation to participate in the SEP plan—this detail can significantly affect young families considering their eligibility.
The maximum funding limits for SEP IRAs are:
- $58,000 for 2021
- $61,000 for 2022
- $66,000 for 2023
These figures highlight the potential advantages of contributing to a SEP IRA, which can be a valuable tool for securing your family’s financial future. Maintaining precise records of donations and adhering to reporting requirements is essential to prevent possible penalties and ensure a smooth tax filing process.
Moreover, employers may qualify for a tax credit of up to $500 annually for starting a SEP, making it an appealing choice for young households looking to invest in their future. Once established, a SEP is easy to manage, allowing employers to focus on their business while efficiently handling retirement contributions. Remember, together, we can navigate this journey toward a secure financial future for your family.

Common Mistakes to Avoid with SEP IRA Contributions
Handling SEP IRA deposits can be a challenging journey for families, and it’s essential to approach it with care. Here are some common pitfalls to be aware of:
- Missing Payment Deadlines: Imagine the disappointment of losing valuable tax advantages simply because a deadline was overlooked. These advantages are crucial for maximizing your retirement savings.
- Over-Contributing: Surpassing contribution limits can lead to penalties that may impact your family’s financial planning. For 2025, remember that the limit is 25% of an employee’s total compensation, up to $70,000, with an additional catch-up payment of $8,000 for those over 50. Staying within these limits is vital to avoid unnecessary costs.
- Flawed Record-Keeping: It’s important to maintain precise records of your contributions. Without them, tax filings can become complicated, leading to compliance issues. Regularly monitoring your inputs can make a significant difference.
- Misunderstanding Eligibility Requirements: Each employee must meet specific criteria to be eligible for contributions, including age and service requirements. Familiarizing yourself with these rules ensures that all eligible employees are accounted for.
By recognizing these common mistakes, families can take proactive steps to safeguard their retirement savings and be mindful of the due date for SEP IRA contributions. Consulting with knowledgeable financial advisors can provide valuable insights into avoiding these pitfalls and ensuring compliance with SEP IRA regulations. As Sarah Brenner, an IRA Analyst, wisely points out, “A common error with SEPs involves the agreements not being amended in a timely fashion or even not at all.” Regular reviews of your SEP agreement can help identify necessary updates, preventing costly errors.
Furthermore, Bright Advisers offers educational materials that empower families to prepare for upcoming financial obligations, ensuring a stable economic foundation for generations to come. Remember, together, we can navigate this journey, and we’re here for you every step of the way.

Why Understanding SEP IRA Contributions is Crucial for Your Retirement
Understanding the subtleties of SEP IRA inputs is crucial for families who want to secure their economic future. Imagine being able to navigate your financial landscape with confidence. By understanding the contribution limits, deadlines, and tax benefits, including the due date for SEP IRA contributions, you can make informed choices that align with your long-term retirement goals.
For 2023, the due date for SEP IRA contributions allows self-employed individuals to contribute up to 25% of their income or $66,000, whichever is lower. This knowledge empowers you to maximize your savings and nurtures economic literacy that can be passed down to future generations, fostering a legacy of monetary responsibility.
It’s encouraging to know that approximately 70% of self-employed individuals meet the SEP IRA eligibility requirements. Families who work with advisors often report enhanced understanding of money and alignment on shared objectives. Real-life stories, like that of Allison and Brian, illustrate how families have effectively utilized their knowledge of SEP IRAs to improve their retirement savings, ultimately achieving greater economic stability.
As self-employed individuals increasingly recognize the benefits of these accounts—reflected in the growing interest among small business owners—this trend highlights a proactive approach to financial management. Together, we can navigate this journey, empowering your family to embrace a brighter financial future.

Conclusion
Understanding the intricacies of SEP IRA contributions is essential for families aiming to secure their financial futures. Imagine if you could grasp the contribution limits, deadlines, and associated tax benefits—this knowledge empowers families to make informed decisions that align with long-term retirement goals. The upcoming deadlines for 2025 present a significant opportunity to maximize savings and reduce taxable income, fostering a more stable economic environment for future generations.
Throughout this article, we shared key insights that matter to you, including the importance of adhering to contribution deadlines and the consequences of missing these dates. It’s important to understand the eligibility requirements that govern who can contribute. Remember, potential tax deductions are available, and maintaining accurate records can help you avoid costly penalties. Additionally, a personalized approach to financial planning can empower your family to navigate your unique financial landscape.
Ultimately, understanding and implementing effective SEP IRA contributions can pave the way for a secure financial future. We want you to stay informed and proactive about these opportunities, ensuring that your retirement savings are optimized. Embracing this knowledge not only enhances your financial literacy but also fosters a legacy of responsible financial management for generations to come. Together, we can take the first step towards effective SEP IRA contributions, leading to lasting financial stability and peace of mind.
Frequently Asked Questions
What is Bright Advisers’ approach to financial planning for SEP IRA contributions?
Bright Advisers focuses on developing customized monetary strategies tailored to the unique financial needs and goals of families with young children, ensuring a personalized approach to SEP IRA contributions.
What are the contribution limits for SEP IRAs in 2025?
For 2025, individuals under age 50 can contribute up to $7,000, while those over 50 can contribute up to $8,000.
What is the due date for SEP IRA contributions?
Contributions must typically be made by April 15 of the following year. If you file for an extension, you can continue contributing until October 15.
What are the consequences of missing the SEP IRA contribution deadline?
Missing the deadline can lead to significant tax penalties, such as a 6% tax on excess contributions, and can hinder the growth potential of your retirement savings.
How can families avoid missing the SEP IRA contribution deadlines?
Families should proactively mark key dates on their calendars and stay informed about funding deadlines to maximize their retirement savings and avoid penalties.
What tax benefits are associated with SEP IRA contributions?
Payments to a SEP IRA are tax-deductible for employers and are not subject to federal income tax for employees until distributions occur, enhancing the advantages of timely contributions.
How does Bright Advisers utilize technology in financial planning?
Bright Advisers uses advanced technology to help clients navigate the complexities of SEP IRAs, allowing families to focus on their future and adjust their savings strategies as their financial situations evolve.
List of Sources
- Bright Advisers: Tailored Financial Planning for SEP IRA Contributions
- 12 Financial Planning Quotes for Building Wealth Wisely — Phillip James Financial (https://phillipjamesfinancial.com/blog/12-financial-planning-quotes-for-building-wealth-wisely)
- 77 Financial Advisor Quotes to Send to Clients (https://billgoodmarketing.com/resources/financial-advisor-quotes)
- Maximizing Your SEP IRA (https://epwealth.com/blog/maximizing-your-sep-ira)
- What (https://synchrony.com/blog/bank/median-retirement-savings-by-age)
- 27 eye-opening financial planning statistics (https://contentsnare.com/financial-planning-statistics)
- SEP IRA Contribution Deadline: Key Dates You Must Remember
- SEP IRA Contribution Limits for 2024 and 2025 (https://smartasset.com/retirement/sep-ira-contribution-limits)
- SEP IRA contribution limits for 2024 and 2025 | Fidelity (https://fidelity.com/learning-center/smart-money/sep-ira-contribution-limits)
- Prior Year SEP IRA Contributions (https://marottaonmoney.com/prior-year-sep-ira-contributions)
- SEP IRA Contribution Limits for 2025 (https://kiplinger.com/retirement/sep-ira/sep-ira-limits)
- Consequences of Missing the SEP IRA Contribution Deadline
- SEP IRA Contribution Limits for 2024 and 2025 (https://smartasset.com/retirement/sep-ira-contribution-limits)
- Due Dates & Limits for SEP IRA Contributions (2024) (https://augur.cpa/blogs/sep-ira-contribution-deadline)
- SEP-IRA Contribution Limits and Deadlines (https://thebalancemoney.com/sep-ira-contribution-limits-and-deadlines-3859079)
- Retirement plans: FAQs regarding SEPs | Internal Revenue Service (https://irs.gov/retirement-plans/retirement-plans-faqs-regarding-seps)
- SEP IRA Contribution Limits: What You Need to Know
- SEP IRA Contribution Limits for 2024 and 2025 (https://smartasset.com/retirement/sep-ira-contribution-limits)
- SEP IRA contribution limits for 2024 and 2025 | Fidelity (https://fidelity.com/learning-center/smart-money/sep-ira-contribution-limits)
- SEP IRA Contribution Limits for 2025 (https://kiplinger.com/retirement/sep-ira/sep-ira-limits)
- SEP-IRA Contribution Limits 2025 | Maximize Your Retirement | Human Interest (https://humaninterest.com/learn/articles/sep-ira-contribution-limits)
- Eligibility Requirements for SEP IRA Contributions
- SEP IRA Contribution Limits for 2025 (https://kiplinger.com/retirement/sep-ira/sep-ira-limits)
- Retirement Account Statistics 2024 – NerdWallet (https://nerdwallet.com/article/investing/retirement-statistics)
- SEP IRA contribution limits for 2024 and 2025 | Fidelity (https://fidelity.com/learning-center/smart-money/sep-ira-contribution-limits)
- What Is a SEP IRA? How the Simplified Pension Works (https://ellevest.com/magazine/sep-ira)
- Tax Benefits of Contributing to a SEP IRA
- Maximizing Your SEP IRA (https://epwealth.com/blog/maximizing-your-sep-ira)
- SEP IRA contribution limits for 2024 and 2025 | Fidelity (https://fidelity.com/learning-center/smart-money/sep-ira-contribution-limits)
- EV Case Studies (https://avista.chooseev.com/commercial/case_studies)
- How to Set Up a SEP IRA: A Step-by-Step Guide
- SEP IRA Guide: Rules, Benefits, and Contributions Explained (https://businessinsider.com/personal-finance/investing/sep-ira)
- SEP IRA Contribution Limits for 2025 (https://kiplinger.com/retirement/sep-ira/sep-ira-limits)
- How to Set Up a SEP IRA | Guideline (https://guideline.com/education/articles/the-guide-to-starting-a-sep-ira)
- SEP Retirement Plans For Small Businesses (https://dol.gov/agencies/ebsa/about-ebsa/our-activities/resource-center/publications/sep-retirement-plans-for-small-businesses)
- Reporting Requirements for SEP IRA Contributions
- SEP IRA (https://schwab.com/small-business-retirement-plans/sep-ira)
- Retirement plans: FAQs regarding SEPs | Internal Revenue Service (https://irs.gov/retirement-plans/retirement-plans-faqs-regarding-seps)
- SEP Retirement Plans For Small Businesses (https://dol.gov/agencies/ebsa/about-ebsa/our-activities/resource-center/publications/sep-retirement-plans-for-small-businesses)
- Common Mistakes to Avoid with SEP IRA Contributions
- Maximizing Your SEP IRA (https://epwealth.com/blog/maximizing-your-sep-ira)
- Avoid This Common SEP IRA Mistake – Ed Slott and Company, LLC (https://irahelp.com/slottreport/avoid-common-sep-ira-mistake)
- SEP IRA contribution limits for 2024 and 2025 | Fidelity (https://fidelity.com/learning-center/smart-money/sep-ira-contribution-limits)
- Why Understanding SEP IRA Contributions is Crucial for Your Retirement
- Maximizing Your SEP IRA (https://epwealth.com/blog/maximizing-your-sep-ira)
- Key Insights on Self Employed IRA Contribution Deadline – Bright Advisers (https://brightadvisers.com/key-insights-on-self-employed-ira-contribution-deadline)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About Kevin