

Overview
Imagine a future where your child’s education is fully funded, allowing them to pursue their dreams without financial burden. 529 plan superfunding offers a strategic approach for parents to make substantial contributions to education savings accounts. With the ability to contribute up to $95,000 in a single year without incurring gift tax penalties, this option opens doors to significant savings.
It’s important to understand the benefits that come with this approach. Not only does it provide tax advantages, but it also allows for flexibility in changing beneficiaries, ensuring that your contributions can adapt to your family’s needs. However, consider the risks of overfunding, as it’s essential to strike the right balance.
Early and informed contributions can make a world of difference in enhancing your child’s educational savings. By taking action now, you can set your family on a path toward financial security in education. Together, we can navigate this journey, ensuring that your child has the opportunities they deserve.
Key Highlights:
- Bright Advisers offers personalised financial planning for families to maximise 529 plan contributions.
- Over 30 states provide tax deductions or credits for 529 contributions, enhancing savings potential.
- Starting in 2024, families can roll over unused 529 funds into a Roth IRA, increasing flexibility.
- 529 plans allow tax-free growth and qualified withdrawals for educational expenses without tax implications.
- Superfunding enables families to contribute up to $95,000 in a single year without gift tax consequences.
- In 2025, the annual contribution limit is $19,000 per beneficiary, or $38,000 for married couples.
- Families should be cautious of overfunding, which can lead to tax penalties and affect financial aid eligibility.
- 529 plans offer flexibility in changing beneficiaries, allowing funds to be reallocated as needed.
- Early contributions to 529 accounts result in significantly higher savings due to compounding interest.
- It’s important to understand the implications of contributions on estate planning and FAFSA assessments.
Introduction
In the ever-evolving landscape of educational savings, young parents are increasingly turning to 529 plans as a strategic tool to secure their children’s futures. Imagine if you could significantly enhance your savings through superfunding—these plans offer a unique opportunity to maximize tax advantages while preparing for rising educational costs.
However, as families navigate the complexities of contribution limits and potential pitfalls, it’s important to understand: how can parents effectively leverage 529 plan superfunding to ensure financial stability and educational success for their children?
This article delves into key insights that can empower parents to make informed decisions about their educational savings strategies, ensuring that together, we can navigate this journey.
Bright Advisers: Personalized Financial Planning for 529 Plan Superfunding
At Bright Advisers, we understand the unique challenges that families with young children face when it comes to financial planning. Our focus is on developing customized strategies that truly address your distinct needs. Imagine being able to invest significantly in your children’s educational savings while also maximizing tax advantages. With 529 plan superfunding, we help parents like you navigate this crucial aspect of financial planning.
Did you know that more than 30 states currently offer tax deductions or credits for 529 contributions? This means that your family can significantly enhance your savings potential. Our client-first approach ensures that you can prioritize your financial goals without sacrificing your children’s educational futures. We provide personalized services that include comprehensive economic education, empowering you to make informed decisions about your investments in 529 programs.
As advisor Andy Esser emphasizes, “It’s important for Americans to understand how flexible 529 plans have become.” Starting in 2024, families will also have the opportunity to roll over unused 529 funds into a Roth IRA, further maximizing your contributions. This is just one of the many ways we strive to support your family’s financial journey.
In addition to our focus on educational savings, Bright Advisers offers a holistic wealth management framework that encompasses integrated tax planning, risk management, and legacy planning. This ensures that we not only address your immediate financial goals but also promote long-term security for future generations. With tax-free growth and the fact that qualified withdrawals are not reportable as student income, you can feel confident in your financial decisions.
Consider Emily and Mark, a couple in their mid-30s, who successfully utilized our strategies to enhance their education savings while achieving financial freedom. Together, we can navigate this journey, ensuring that your family’s values and goals are at the forefront of your financial planning. We’re here for you, ready to assist you every step of the way.
Understanding 529 Plans: A Foundation for College Savings
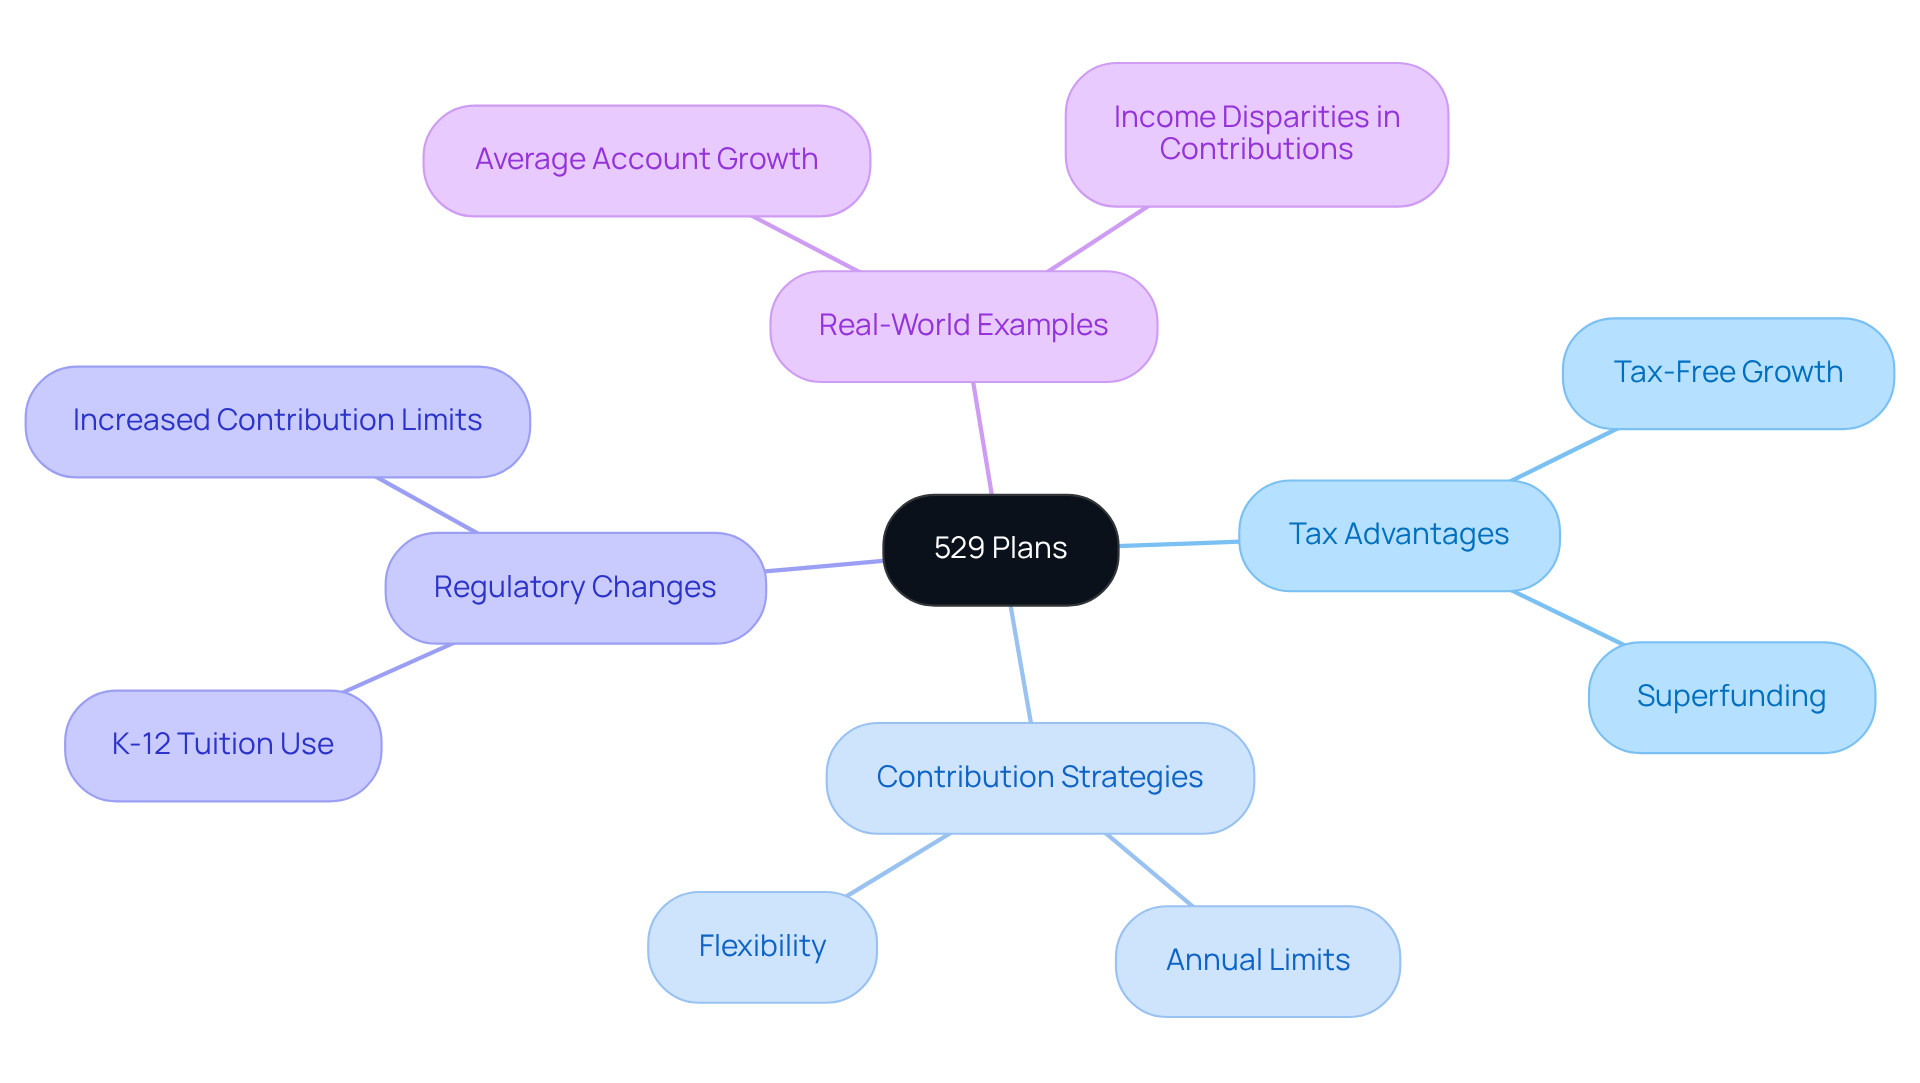
A 529 program is a nurturing savings tool designed specifically for educational expenses, offering a tax-advantaged way to prepare for your child’s future. When you contribute to these accounts, your savings grow without tax, and when it’s time to withdraw for eligible education expenses—like tuition, housing, and books—you won’t face any taxes. Sponsored by individual states, 529 programs provide the flexibility needed to address a wide range of educational costs, making them an essential resource for parents committed to their children’s academic success.
The tax benefits of 529 accounts are particularly advantageous for young parents. These strategies not only allow for tax-free growth, but they also enable families to benefit from 529 plan superfunding, contributing up to five years’ worth of contributions in a single year without incurring gift taxes. This approach can significantly enhance your savings potential, especially considering the rising costs of education.
Recent regulatory changes have made 529 options even more appealing. For example, families can now use funds for K-12 tuition costs, expanding the usefulness of these accounts beyond just college savings. It’s important to understand these tax benefits, as they are crucial for maximizing your savings and minimizing future educational debt.
Real-world examples illustrate the effectiveness of 529 programs. Families utilizing these accounts have reported remarkable savings, with the average account balance rising from $9,500 in 2008 to over $30,300 in 2024. This growth reflects the increasing reliance on 529 programs as families seek efficient ways to manage educational expenses. By embracing the benefits of 529 accounts, you can build a solid financial foundation for your children’s educational journeys. Together, we can navigate this journey toward a brighter future for your family.
What is Superfunding? Mechanisms and Benefits Explained
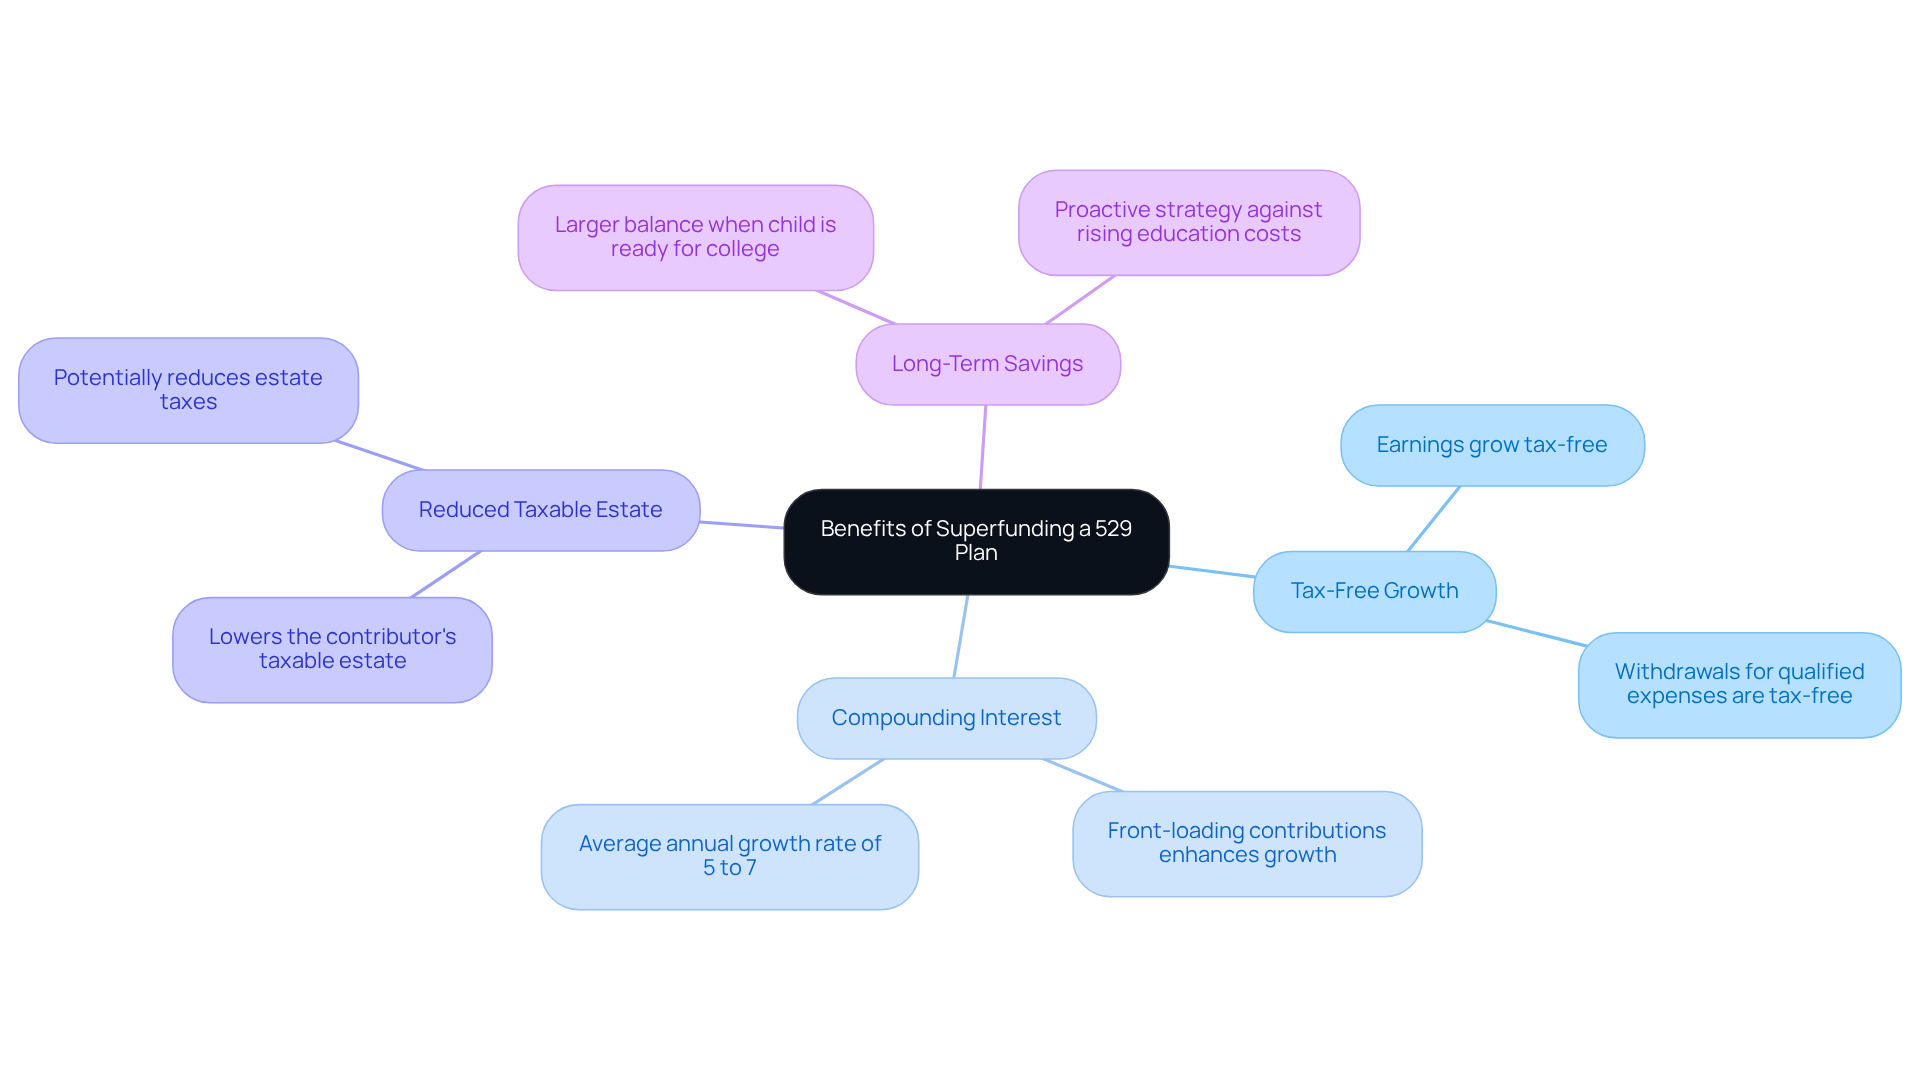
529 plan superfunding is a thoughtful strategy that enables families to make a significant, lump-sum payment to a 529 plan. Imagine being able to contribute up to $95,000 in 2025 without worrying about gift tax consequences. This approach effectively front-loads contributions, giving your invested funds the opportunity to grow tax-free over time.
By embracing 529 plan superfunding, families can truly enhance their savings potential, leveraging the power of compounding interest. This strategy not only accelerates the growth of education savings but also helps families meet future educational expenses with greater ease.
Together, we can navigate this journey, ensuring that your children’s educational dreams are within reach. We’re here for you, providing the support you need to make informed financial decisions that align with your family values.
Annual Contribution Limits: Navigating 529 Plan Regulations
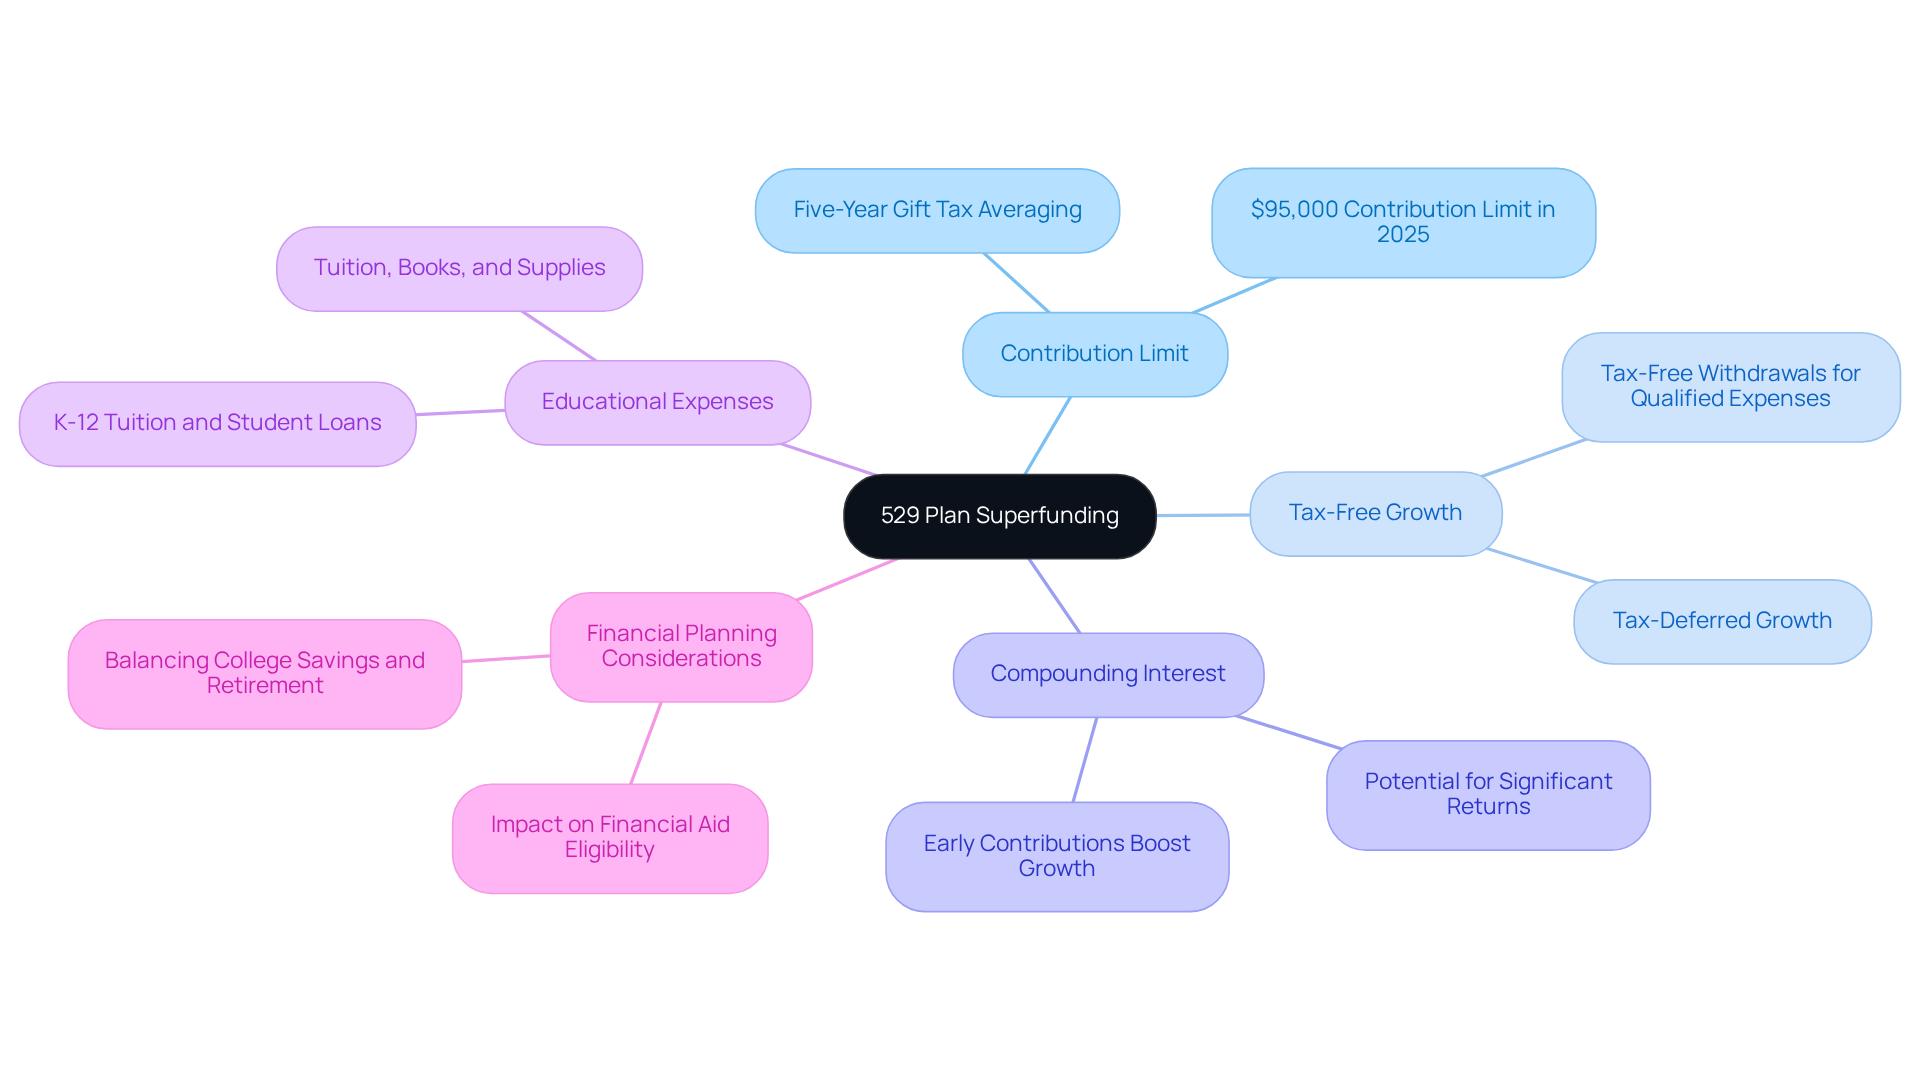
In 2025, the yearly donation limit for 529 accounts is set at $19,000 for each donor per beneficiary. For married couples, this limit doubles to $38,000. Imagine being able to contribute even more! Individuals can add up to $95,000 in a single year to a specific 529 account with 529 plan superfunding, allowing for substantial upfront deposits. The concept of 529 plan superfunding means providing larger amounts in one year to take advantage of tax benefits and enhance savings potential. It’s important to understand that contributions exceeding these amounts must be reported to the IRS and may count against the lifetime gift tax exemption. Parents should be aware of these limits to effectively plan their financial support and avoid any potential tax implications. Utilizing strategies like 529 plan superfunding not only maximizes savings but also provides your contributions with more time to grow and earn investment income.
Bright Advisers is here for families like Jay and Emma, who skillfully managed their financial planning, including education savings. By creating a comprehensive budget and choosing investment strategies aimed at diversification, they enhanced their financial security while aligning with their long-term aspirations. Together, we can navigate this journey. By collaborating with Bright Advisers, young parents can ensure they are maximizing their 529 account deposits while enjoying low fund fees, making wealth management more accessible. Let’s take this step together to secure your family’s future.
Benefits of Superfunding: Maximizing Your 529 Plan Potential
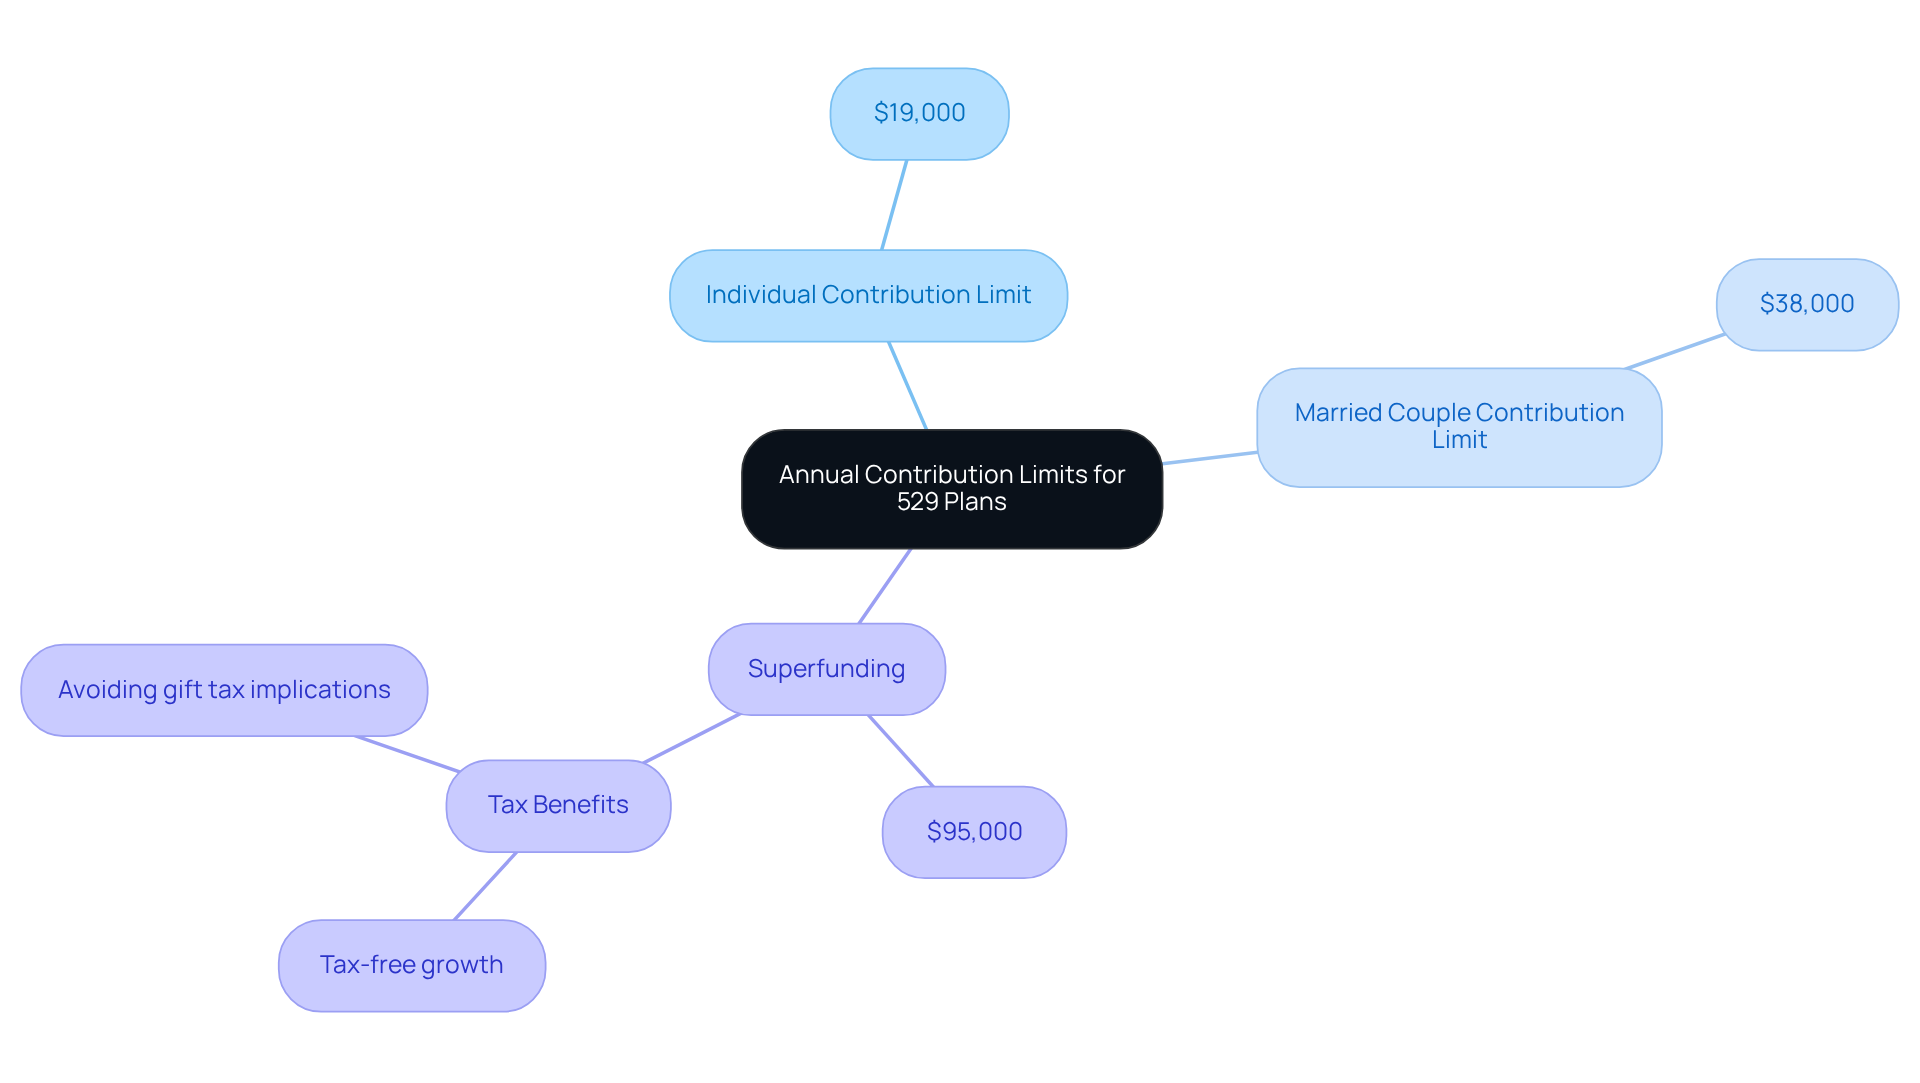
Superfunding a 529 plan can be a wonderful opportunity for families, primarily because 529 plan superfunding allows for a significant initial deposit that can significantly enhance tax-free growth over time. Imagine if you could front-load your contributions—this strategy enables households to harness the incredible power of compounding interest. As a result, you might see a much larger balance when your child is ready for college. Families who contribute early often experience their investments growing at an average annual rate of 5% to 7%, leading to impressive long-term savings.
Moreover, the process of 529 plan superfunding can effectively reduce the total taxable estate of the contributor, offering additional financial benefits. This approach not only boosts education savings but also aligns with the goal of securing a brighter economic future for your children. As families face the challenges of rising education costs, 529 plan superfunding emerges as a proactive strategy to help achieve financial goals, ensuring that you are well-prepared for your children’s educational journeys. We’re here for you as you navigate this important aspect of your family’s future.
Rules and Regulations: What Parents Need to Know About Superfunding
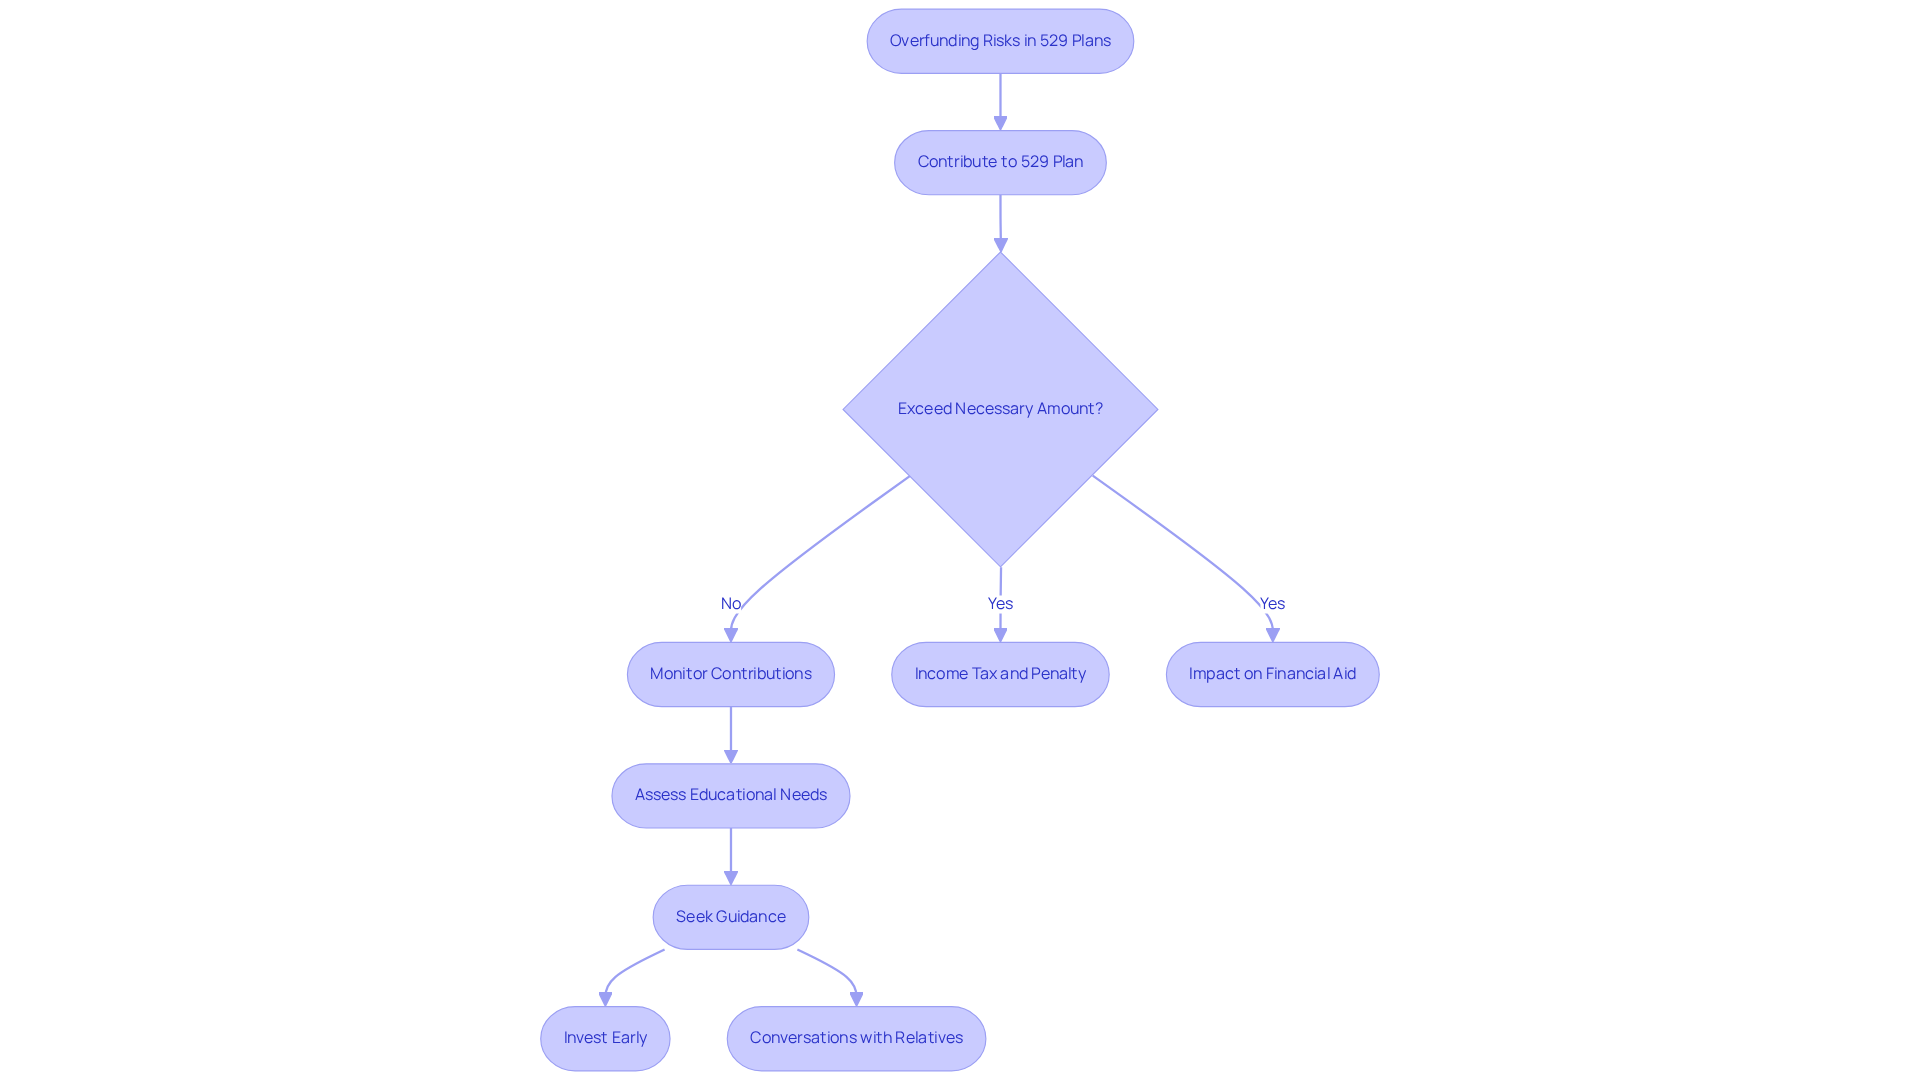
For parents, 529 plan superfunding can feel overwhelming, but understanding the process can make it manageable. It’s essential to navigate specific regulations, particularly the need to distribute funds over a five-year period for gift tax purposes. This means that a significant contribution made in a single year will be treated as if it were spread across five years when calculating tax implications. For instance, a donation of $95,000 can be averaged to $19,000 annually, allowing families to optimize their educational savings while easing immediate tax burdens.
Moreover, it’s crucial for parents to consider how these contributions fit into their overall estate planning. Contributions to a 529 plan are viewed as parental assets in FAFSA assessments, which can impact aid eligibility. Therefore, planning contributions carefully is essential, ensuring they align with both educational goals and budgeting needs. Financial consultants, like those at Bright Advisers, emphasize the importance of addressing these implications to avoid unintended consequences on estate taxes and financial aid opportunities.
Through personalized planning and tax optimization strategies, such as tax-loss harvesting and strategic asset allocation, Bright Advisers helps families secure their children’s educational futures while also achieving broader financial goals. For example, families like Allison and Brian have successfully optimized their tax situations and secured funding for their children’s education, allowing them to enjoy peace of mind and focus on their long-term aspirations. By partnering with a financial advisor, parents can navigate the complexities of 529 plan superfunding and develop a comprehensive strategy that supports their family’s financial stability and independence. Together, we can navigate this journey with confidence.
Flexibility with Beneficiaries: Adapting Your 529 Plan
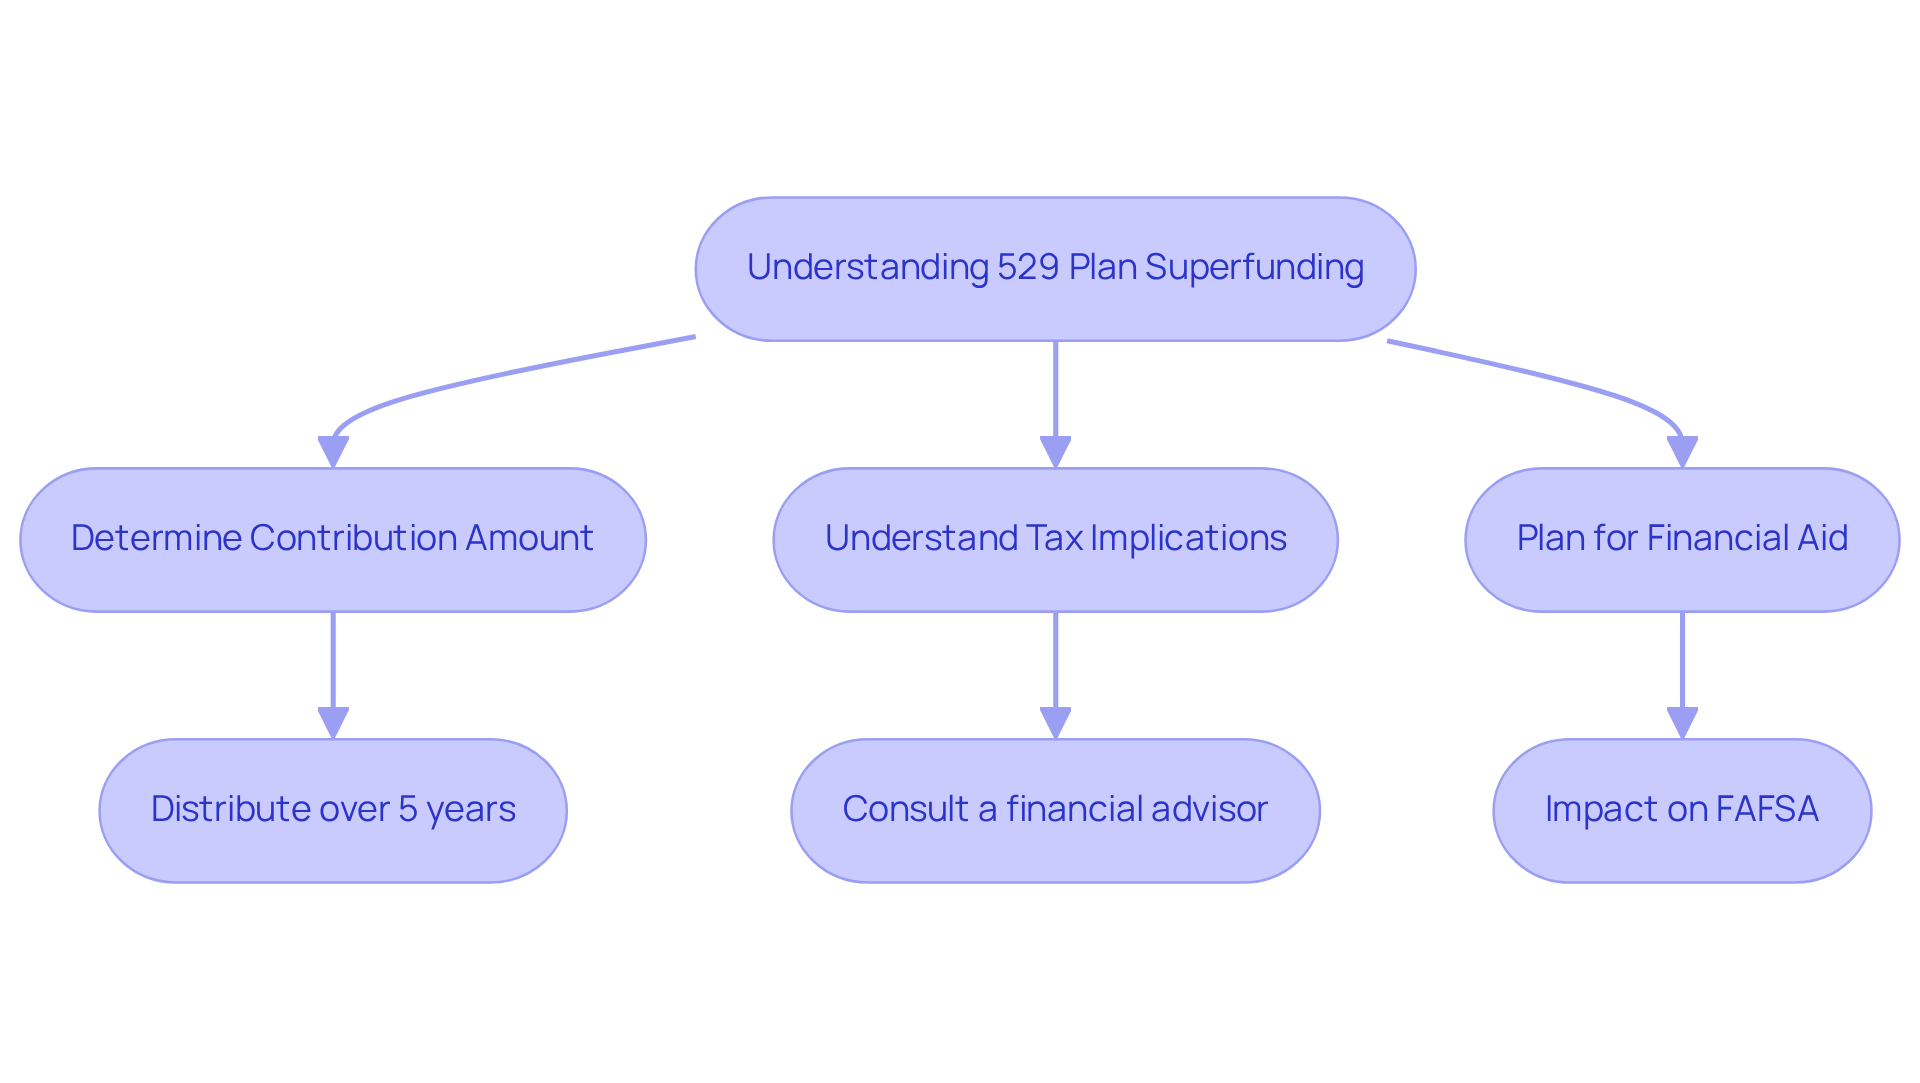
One of the most comforting aspects of 529 plans is their remarkable flexibility in changing beneficiaries. Imagine if one child doesn’t need the funds; parents can easily transfer the account to another qualifying relative without facing tax penalties. This adaptability allows families to tailor their savings strategies to evolving educational needs, ensuring that funds are effectively allocated for their intended purpose. As of June 2024, there were approximately 16.8 million 529 accounts in the U.S., a testament to the growing acknowledgment of these plans as vital tools for college savings.
Moreover, the ability to change beneficiaries without it being classified as a distribution is especially beneficial for families with multiple children, maximizing the value of their savings. This flexibility is crucial, especially considering that the average cost of college now exceeds $36,000 per year. Families like Jay and Emma, who strive to alleviate financial stress and secure their children’s futures, can truly benefit from optimizing their educational resources.
Additionally, 529 accounts offer significant tax advantages, such as tax-deductible contributions and tax-free qualified withdrawals, making them an attractive option for families. Through their partnership with Bright Advisers, Allison and Brian enhanced their financial strategies through tax optimization, achieving peace of mind and safeguarding their children’s futures by effectively utilizing these plans. Together, we can navigate this journey toward a brighter future for our families.
Potential Downsides of Superfunding: Risks to Consider
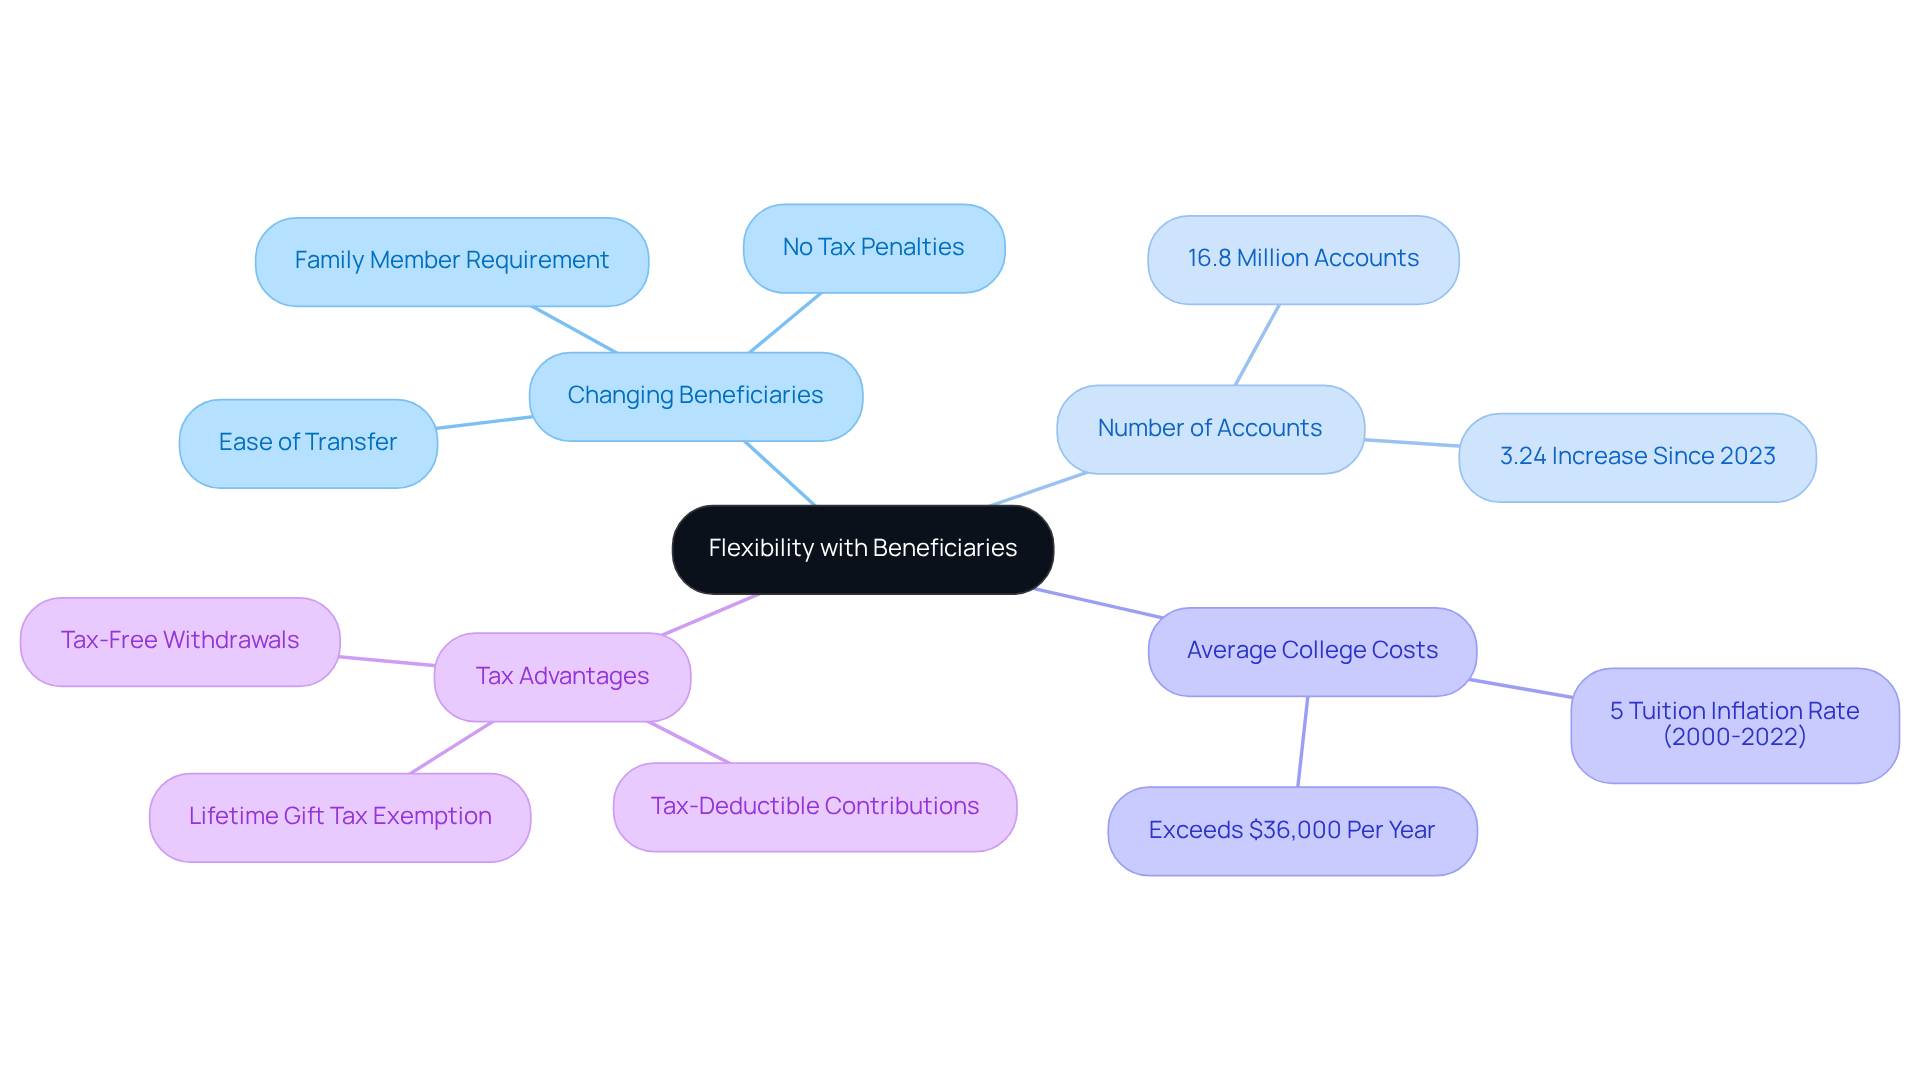
While 529 plan superfunding can significantly enhance your college savings, it’s important to be aware of its potential downsides. Imagine the worry of overfunding a 529 plan, resulting in excess funds that may not be necessary for your child’s educational expenses. Many households face challenges with overfunded accounts, leading to important considerations about how to manage these funds effectively.
It’s crucial to understand that if a contributor passes away within five years of making a superfunding donation, only a portion of that donation may qualify as a completed gift for tax purposes, complicating estate planning. Investment consultants frequently advise families to carefully assess their economic circumstances and future educational needs before deciding on 529 plan superfunding.
This thoughtful evaluation can help you avoid the pitfalls linked to overfunding and ensure that your financial inputs align with your family’s long-term objectives. Remember, we’re here for you, and together, we can navigate this journey toward securing your child’s future.
Overfunding Risks: What Happens If You Contribute Too Much?
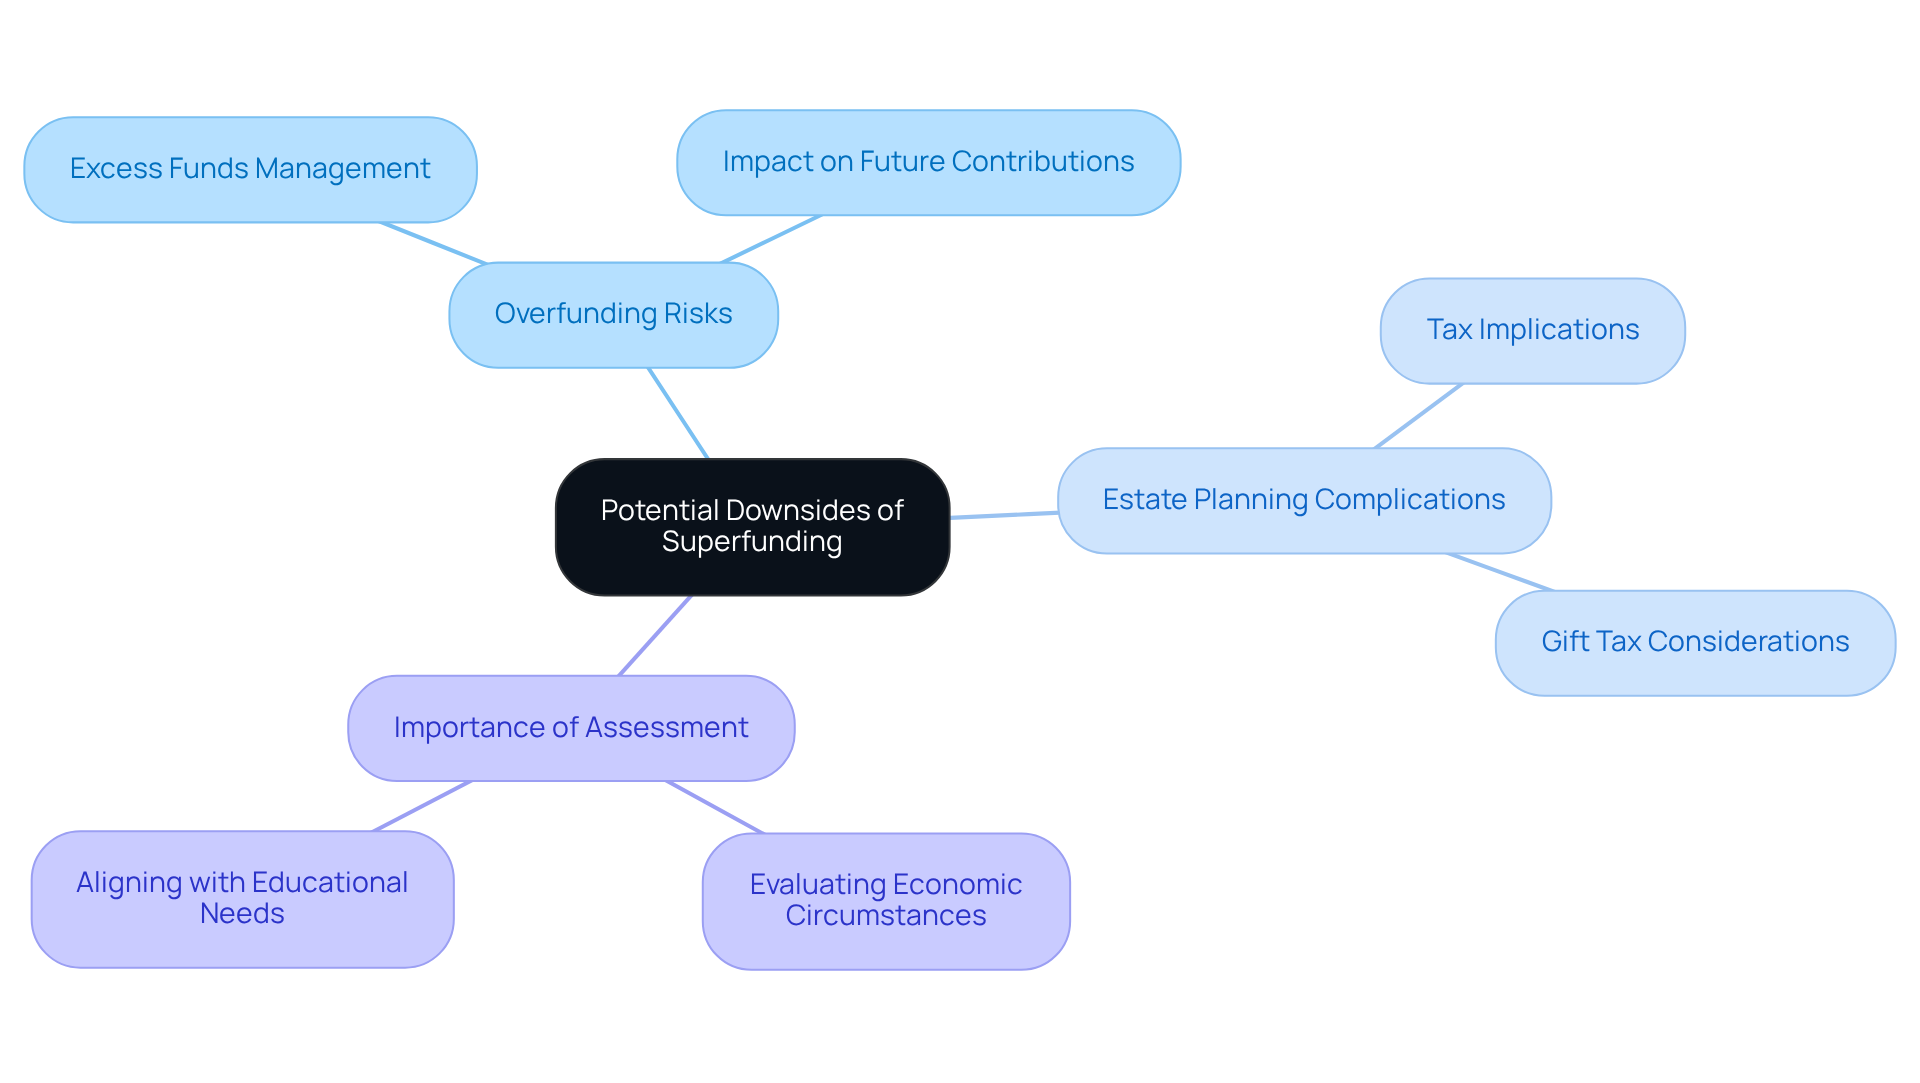
Overfunding a 529 plan through superfunding can create significant challenges for families. When contributions surpass the necessary amount for eligible educational expenses, the excess funds may incur income tax and a 10% penalty on the earnings. This situation is particularly concerning because substantial balances in a 529 plan superfunding account are considered assets, which can negatively impact a child’s eligibility for financial aid. In fact, a 2018 survey revealed that 35% of households utilized college savings plans to help with college costs, highlighting the importance of strategic funding and moderation to avoid the risks of overfunding.
Parents should closely monitor their contributions and consider their children’s future educational needs to prevent overfunding. For instance, families can benefit from investing early when children are young, enhancing growth potential while reducing the risk of excess funds. Engaging in early conversations with relatives about potential contributions can also help balance savings strategies and lessen the likelihood of overfunding.
Consider the story of Allison and Brian, a high-earning household that initially aimed to achieve 529 plan superfunding for their children’s college education. They faced challenges due to misunderstandings about the funding process. With the guidance of Bright Advisers, they discovered how to optimize their tax situation, secure their children’s educational future, and avoid penalties while maintaining eligibility for aid. Bright Advisers’ commitment to minimal fund fees further improved their wealth management accessibility.
Thus, seeking guidance from financial consultants and tax specialists is crucial to determine the appropriate amount to invest in 529 accounts. This ensures that families maximize the benefits of their investments while safeguarding their financial future. Additionally, families should know that any remaining funds can be transferred to another relative or converted to an IRA for children, providing further options for managing surplus amounts.
Key Takeaways: Essential Facts About 529 Plan Superfunding
529 plan superfunding is a wonderful strategy for parents looking to significantly enhance their education savings. Let’s explore some essential facts that can guide you on this journey:
-
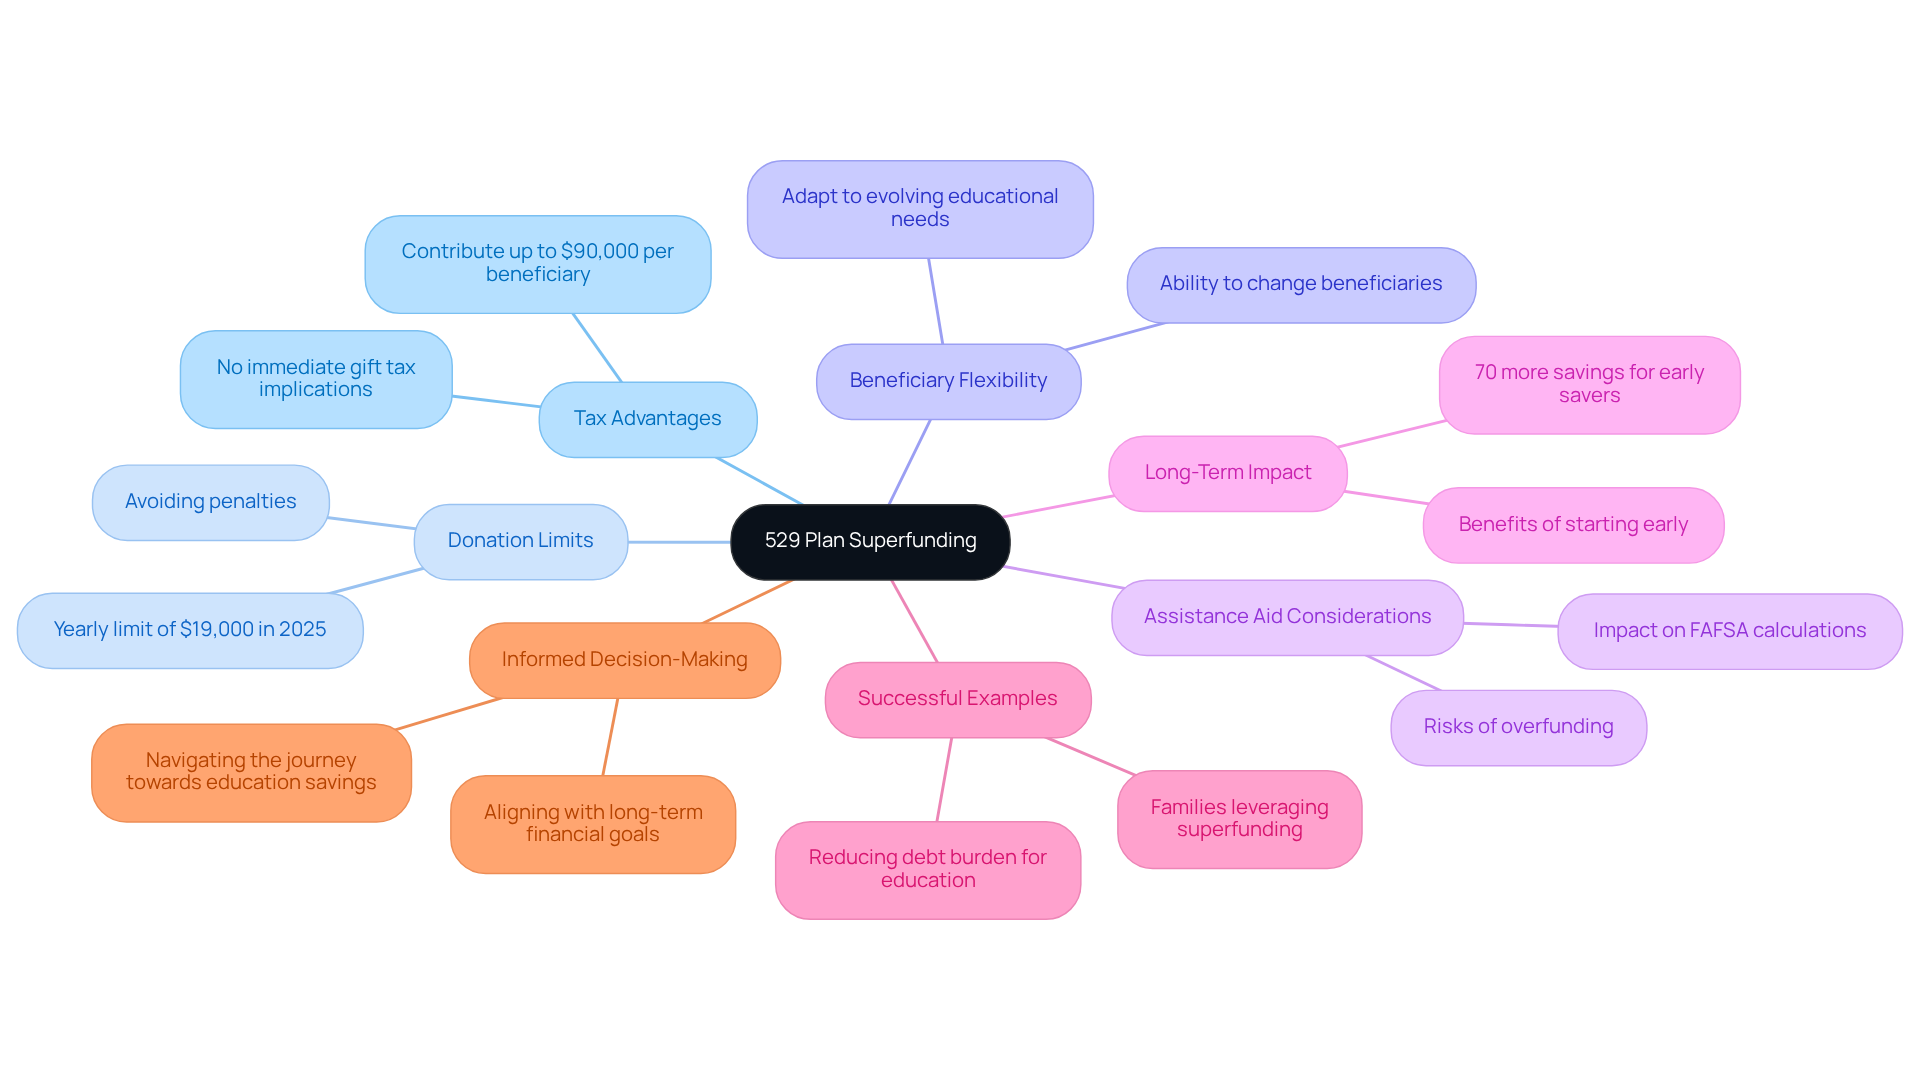
Tax Advantages: Imagine being able to contribute up to $90,000 per beneficiary in a single year without immediate gift tax implications. This powerful tool can help you maximize your savings for your child’s future.
-
Donation Limits: It’s important to understand yearly donation limits to avoid penalties. In 2025, you can gift up to $19,000 per beneficiary without affecting your lifetime gift tax exemption, ensuring you can contribute wisely.
-
Beneficiary Flexibility: Life is full of changes, and the ability to change beneficiaries allows you to adapt to evolving educational needs. This flexibility ensures that your funds can be redirected as circumstances change, providing peace of mind.
-
Assistance Aid Considerations: While planning, be cautious of the risks associated with overfunding. Contributions to 529 plans are considered parental assets in FAFSA calculations, which could impact your child’s aid eligibility.
-
Long-Term Impact: Families who began saving early in a 529 account have reported significantly higher savings. In fact, those who started when their child was 5 or younger had 70% more than those who began later, showcasing the benefits of early planning.
-
Successful Examples: Many families have successfully leveraged 529 plan superfunding to ensure their children’s educational futures. This proactive approach allows children to pursue degrees without the burden of debt, creating a brighter path ahead.
-
Informed Decision-Making: By understanding these insights, you can make informed decisions that not only enhance your children’s educational prospects but also align with your long-term financial goals. Remember, we’re here for you, and together, we can navigate this journey toward a secure future for your family.
Conclusion
Investing in a 529 plan through superfunding presents young parents with a remarkable opportunity to secure their children’s educational futures. This strategy not only allows for significant upfront contributions but also maximizes tax advantages and fosters long-term growth of savings. By understanding the various benefits and regulations associated with 529 plans, families can build a strong financial foundation that aligns with their educational aspirations.
Imagine the flexibility of 529 plans, where you can change beneficiaries as needed. It’s important to adhere to annual contribution limits while also being aware of the potential risks of overfunding. Real-life examples reveal how families have successfully utilized these strategies to enhance their savings, showcasing the effectiveness of early planning and informed decision-making.
Ultimately, navigating the complexities of 529 plan superfunding is vital for young parents aiming to provide a debt-free college experience for their children. By partnering with financial advisors like Bright Advisers, families can optimize their contributions and ensure long-term financial stability. Together, we can take proactive steps toward a brighter economic future for your children.
Frequently Asked Questions
What is a 529 plan?
A 529 plan is a savings tool specifically designed for educational expenses, allowing your savings to grow tax-free and providing tax-free withdrawals for eligible education costs like tuition, housing, and books.
What are the benefits of contributing to a 529 plan?
Contributing to a 529 plan offers tax-free growth on savings, tax-free withdrawals for qualified education expenses, and the ability to superfund contributions, allowing families to contribute up to five years’ worth of contributions in a single year without incurring gift taxes.
What is 529 plan superfunding?
529 plan superfunding is a strategy that allows families to make a significant, lump-sum contribution to a 529 plan, potentially contributing up to $95,000 in 2025 without facing gift tax consequences. This front-loading of contributions enables funds to grow tax-free over time.
How can 529 plans be used beyond college savings?
Recent regulatory changes allow families to use 529 funds for K-12 tuition costs, expanding the accounts’ usefulness beyond just college savings.
What tax advantages do 529 plans offer?
More than 30 states offer tax deductions or credits for 529 contributions, enabling families to enhance their savings potential while benefiting from tax-free growth and tax-free withdrawals for qualified expenses.
What additional services does Bright Advisers provide for financial planning?
Bright Advisers offers a holistic wealth management framework that includes integrated tax planning, risk management, and legacy planning, ensuring that both immediate financial goals and long-term security for future generations are addressed.
How have families benefited from using 529 plans?
Families utilizing 529 plans have reported significant savings, with average account balances increasing from $9,500 in 2008 to over $30,300 in 2024, reflecting the growing reliance on these programs for managing educational expenses.
How does Bright Advisers support families in financial planning?
Bright Advisers focuses on personalized financial strategies, comprehensive economic education, and client-first approaches to help families navigate their financial journeys and achieve their educational savings goals.
List of Sources
- Bright Advisers: Personalized Financial Planning for 529 Plan Superfunding
- Does a 529 plan affect financial aid eligibility? (https://savingforcollege.com/article/yes-your-529-plan-will-affect-financial-aid)
- 529 Savings Plans: Tax and Financial Planning Benefits (https://claconnect.com/en/resources/articles/2023/529-plans-learn-the-tax-and-financial-planning-benefits-of-college-savings)
- Does a 529 Plan Affect Eligibility for Financial Aid? (https://ml.com/articles/could-your-529-education-savings-account-limit-your-childs-financial-aid.html)
- Survey: Americans Unaware of 529 Plans (https://edwardjones.com/us-en/why-edward-jones/news-media/press-releases/americans-unaware-529-plans)
- 5 Things You May Not Know About 529s (But Should) | Morgan Stanley (https://advisor.morganstanley.com/alexandra.vanmeurs/articles/family/5-things-about-529s)
- Understanding 529 Plans: A Foundation for College Savings
- Assets of 529 savings plans by state U.S. 2023| Statista (https://statista.com/statistics/1232936/529-college-savings-plan-assets-of-american-households)
- 529 Plan Statistics | The Motley Fool (https://fool.com/research/529-plan-statistics)
- How Much You Can Contribute to a 529 Plan for 2025? | Research.com (https://research.com/student-loans/how-much-you-can-contribute-to-a-529-plan)
- 529 Plan And College Savings Statistics (https://thecollegeinvestor.com/529-plan-and-college-savings-statistics?srsltid=AfmBOootaJD1qqHfzDuCND0nikXYnDQUocSfJEG6pHbjsh5gmjb4-0rK)
- College Saving Statistics [2025]: Average Savings & 529 Balance (https://educationdata.org/college-savings-statistics)
- What is Superfunding? Mechanisms and Benefits Explained
- Comparing Education Savings Accounts (https://schwab.com/learn/story/comparing-education-savings-accounts)
- 10 Rules for Superfunding a 529 Plan for 2025 | Research.com (https://research.com/student-loans/rules-for-superfunding-a-529-plan)
- Maximizing Education Savings: Exploring the Power of 529 Superfunding | Beyond Wealth (https://beyond-wealth.com/blogs/maximizing-education-savings-exploring-the-power-of-529-superfunding)
- College Savings Accounts: 529 Plans and ESAs (https://schwabmoneywise.com/essentials/college-savings-accounts)
- Superfunding a 529 Plan (https://physiciansidegigs.com/superfunding-a-529-plan)
- Annual Contribution Limits: Navigating 529 Plan Regulations
- Ohio 529 Plan FAQ | General and Tax Questions | CollegeAdvantage (https://collegeadvantage.com/general-faqs)
- 529 contribution limits 2024 & 2025 | Fidelity (https://fidelity.com/learning-center/smart-money/529-contribution-limits)
- 529 Contribution Limits 2025: Maximums by State – NerdWallet (https://nerdwallet.com/article/investing/529-contribution-limits)
- 529 Plan Contribution Limits In 2024 and 2025: May 2025 Edition (https://forbes.com/sites/investor-hub/article/529-plan-contribution-limits)
- Benefits of Superfunding: Maximizing Your 529 Plan Potential
- Average 529 plan balance: How do you compare? (https://savingforcollege.com/article/average-529-plan-balance-how-do-you-compare)
- 529 Plan Statistics | The Motley Fool (https://fool.com/research/529-plan-statistics)
- How Much You Can Contribute to a 529 Plan for 2025? | Research.com (https://research.com/student-loans/how-much-you-can-contribute-to-a-529-plan)
- 529 College Savings Plan Statistics | BestColleges (https://bestcolleges.com/research/529-college-savings-plan-statistics)
- 10 Rules for Superfunding a 529 Plan for 2025 | Research.com (https://research.com/student-loans/rules-for-superfunding-a-529-plan)
- Rules and Regulations: What Parents Need to Know About Superfunding
- 10 Rules for Superfunding a 529 Plan (https://savingforcollege.com/article/10-rules-for-superfunding-a-529-plan)
- 10 Rules for Superfunding a 529 Plan for 2025 | Research.com (https://research.com/student-loans/rules-for-superfunding-a-529-plan)
- The Surprising Way to Superfund Your Child’s 529 Plan Without a Penalty (https://investopedia.com/superfund-a-529-plan-without-a-penalty-11698970)
- Supercharge your college savings with 529 plan superfunding (https://synovus.com/personal/resource-center/financial-newsletters/2022/february/supercharge-with-529)
- 529 Plan Contribution Limits: What Are The Annual And Aggregate Caps? (https://thecollegeinvestor.com/35147/529-plan-contribution-limits?srsltid=AfmBOoqLw1TA82Qy_xYup-2Qc3sDmXh9QcytYDk3H_J-P4aQM-wkuIlV)
- Flexibility with Beneficiaries: Adapting Your 529 Plan
- 529 College Savings Plan Statistics | BestColleges (https://bestcolleges.com/research/529-college-savings-plan-statistics)
- 529 Beneficiary Changes: Who Is Considered a Qualifying Family Member? (https://savingforcollege.com/article/who-is-a-member-of-the-family-of-a-529-plan-beneficiary)
- Release: 529 Plan Program Statistics, December 2024 (https://ici.org/research/stats/529s/529s_24_q4)
- 529 Plan And College Savings Statistics (https://thecollegeinvestor.com/529-plan-and-college-savings-statistics?srsltid=AfmBOoocN4n9vQmJtpa8V_VT582z-dQmjeZB88k3IWUPJQ16_xQOpaJr)
- Potential Downsides of Superfunding: Risks to Consider
- 529 Plan Statistics | The Motley Fool (https://fool.com/research/529-plan-statistics)
- Addressing Large ‘Overfunded’ 529 Plans – The CPA Journal (https://cpajournal.com/2024/08/09/addressing-large-overfunded-529-plans)
- How Much You Can Contribute to a 529 Plan for 2025? | Research.com (https://research.com/student-loans/how-much-you-can-contribute-to-a-529-plan)
- 529 College Savings Plan Statistics | BestColleges (https://bestcolleges.com/research/529-college-savings-plan-statistics)
- College Saving Statistics [2025]: Average Savings & 529 Balance (https://educationdata.org/college-savings-statistics)
- Overfunding Risks: What Happens If You Contribute Too Much?
- Addressing Large ‘Overfunded’ 529 Plans – The CPA Journal (https://cpajournal.com/2024/08/09/addressing-large-overfunded-529-plans)
- I overfunded my kids’ 529 plan — now I’m facing a punishing 10% penalty. Why I’d save less if I could go back (https://finance.yahoo.com/news/overfunded-kids-529-plan-now-120100801.html)
- 529 College Savings Plan Statistics | BestColleges (https://bestcolleges.com/research/529-college-savings-plan-statistics)
- The tax risks of overfunding your 529 college savings plan (https://investmentnews.com/industry-news/the-tax-risks-of-overfunding-your-529-college-savings-plan/63457)
- Key Takeaways: Essential Facts About 529 Plan Superfunding
- 529 contribution limits 2024 & 2025 | Fidelity (https://fidelity.com/learning-center/smart-money/529-contribution-limits)
- Education Savings (https://retsupport.com/resources/no-index/2019trends/educationsavings.html)
- 529 College Savings Plan Statistics | BestColleges (https://bestcolleges.com/research/529-college-savings-plan-statistics)
- College Saving Statistics [2025]: Average Savings & 529 Balance (https://educationdata.org/college-savings-statistics)
- 10 Rules for Superfunding a 529 Plan for 2025 | Research.com (https://research.com/student-loans/rules-for-superfunding-a-529-plan)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Age Five Wealth Education for high-income W-2 families at Bright Advisers.
Keep reading