

Key Highlights:
- Bright Advisers offers personalised financial planning to maximise 529 plan tax deductions for families.
- A 529 plan is a tax-advantaged savings account for education, allowing tax-free growth and withdrawals for qualified expenses.
- 529 plans support both K-12 and college education, making them versatile for family financial planning.
- Families can benefit from state-specific tax deductions or credits, enhancing the attractiveness of 529 plans.
- Eligibility for 529 plan tax deductions typically requires residency in the state offering the deduction and contributions to in-state plans.
- Contribution limits for 529 plans allow up to $19,000 annually without federal gift tax implications, doubling for married couples.
- State tax benefits vary significantly; some states offer generous deductions while others provide none.
- 529 plans have restrictions, including penalties for non-qualified withdrawals, which families must consider.
- Qualified expenses for 529 plans include tuition, fees, and supplies, with specific limits for K-12 education.
- Long-term financial planning with 529 plans can help families align educational savings with broader financial goals.
Introduction
Navigating the world of 529 plans can feel overwhelming, especially for young families who want to secure a bright educational future for their children. These tax-advantaged savings accounts not only provide valuable financial benefits but also open doors to optimizing educational expenses.
Imagine if you could make the most of your savings while preparing for your child’s future. With various state regulations and contribution limits, it’s crucial to understand how to effectively navigate these complexities to maximize your tax deductions.
This article shares seven key insights designed to empower you as you make informed decisions about your family’s financial strategies. Together, we can explore how to enhance your approach to saving for education, ensuring that your children have the opportunities they deserve. Remember, we’re here for you every step of the way.
Bright Advisers: Personalized Financial Planning for 529 Tax Deductions
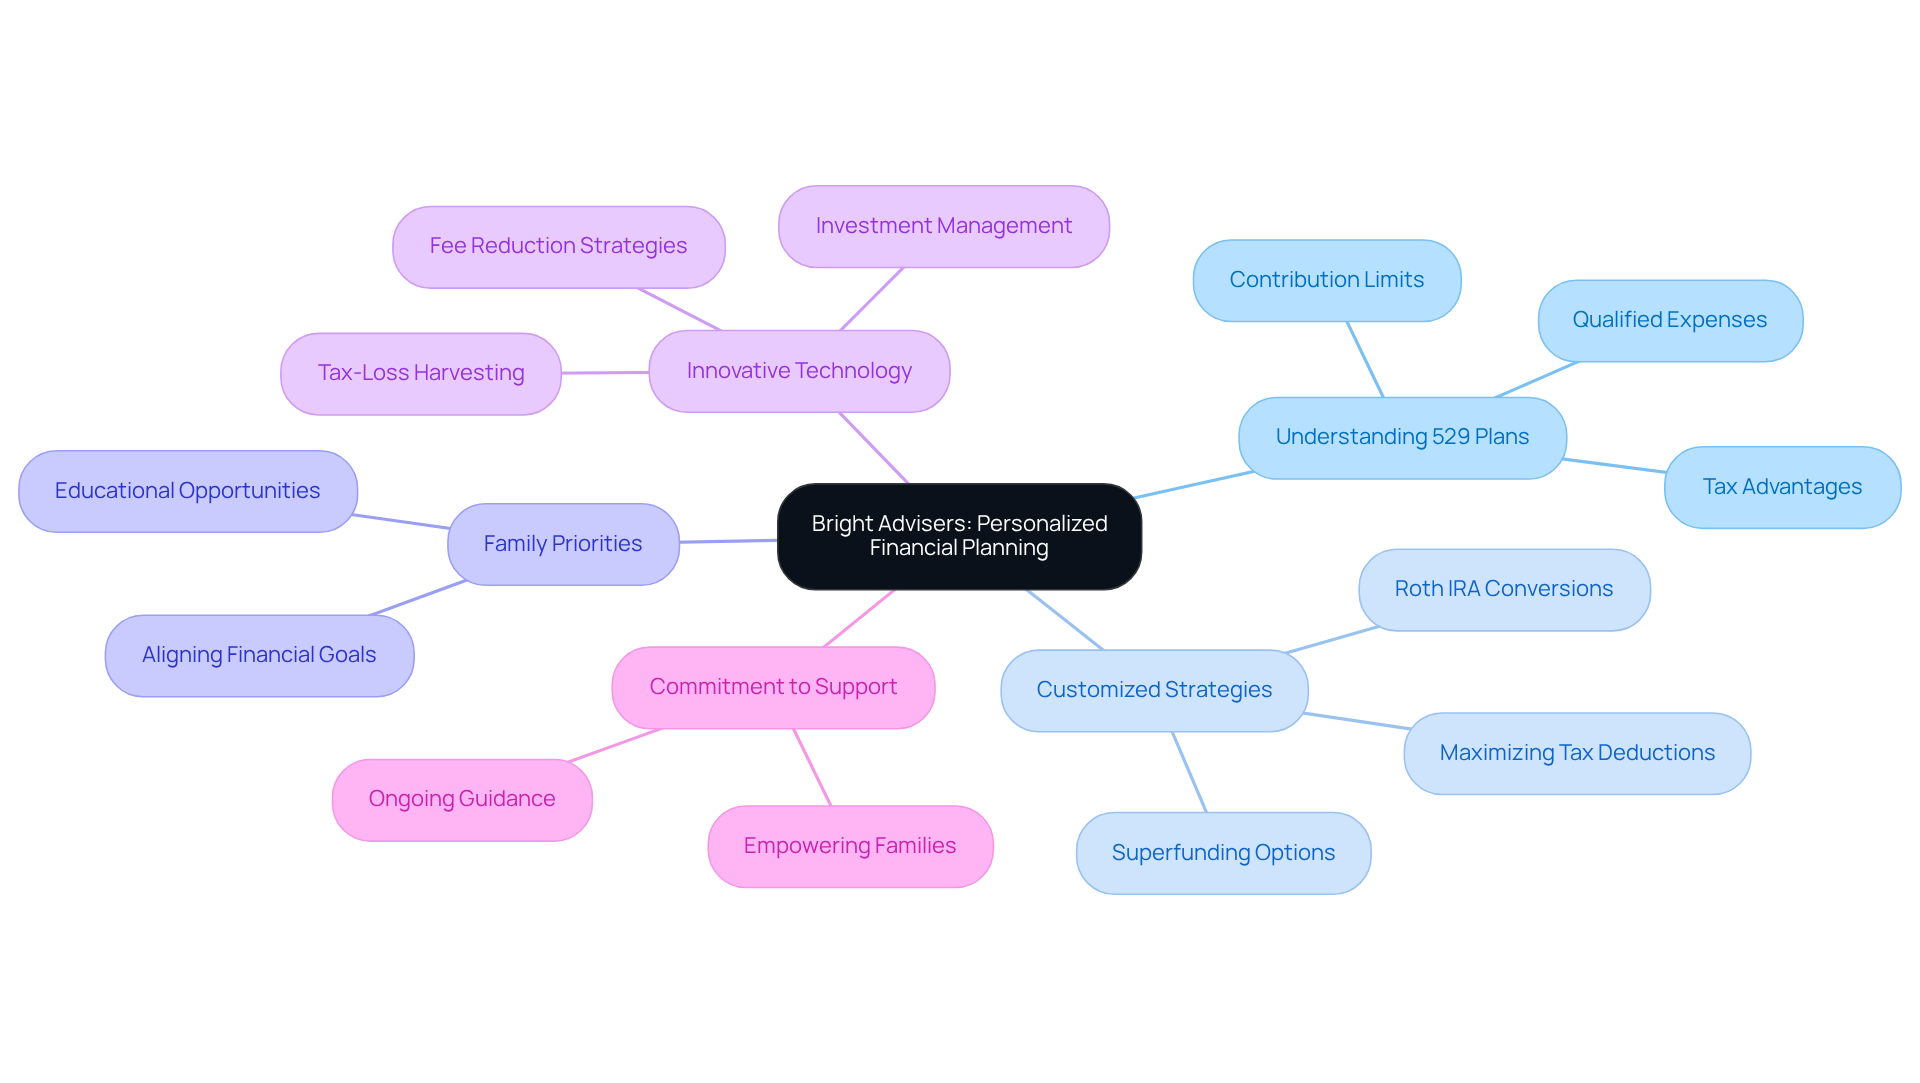
At Bright Advisers, we understand that navigating the complexities of 529 plans can feel overwhelming, especially for families with young children. Imagine if you could create a financial strategy that not only meets your family’s unique needs but also allows you to maximize the 529 plan tax deduction on your contributions. Our customized approach is designed to help you do just that, making the financial planning process smoother and more manageable.
We know that every family has its own priorities and values. That’s why we focus on what matters most to you, empowering you to make informed decisions about your educational savings strategies. With our innovative technology, we enhance investment management, eliminate unnecessary fund fees, and capture tax-loss harvesting opportunities. This means financial planning becomes not just accessible, but effective for every family.
Together, we can navigate this journey. Our commitment is to align your financial strategies with your family’s vision, ensuring that you feel supported every step of the way. Let us help you create a brighter future for your children, filled with educational opportunities and peace of mind. We’re here for you, ready to assist you in achieving your financial goals.
Understanding the 529 Plan: Definition and Purpose
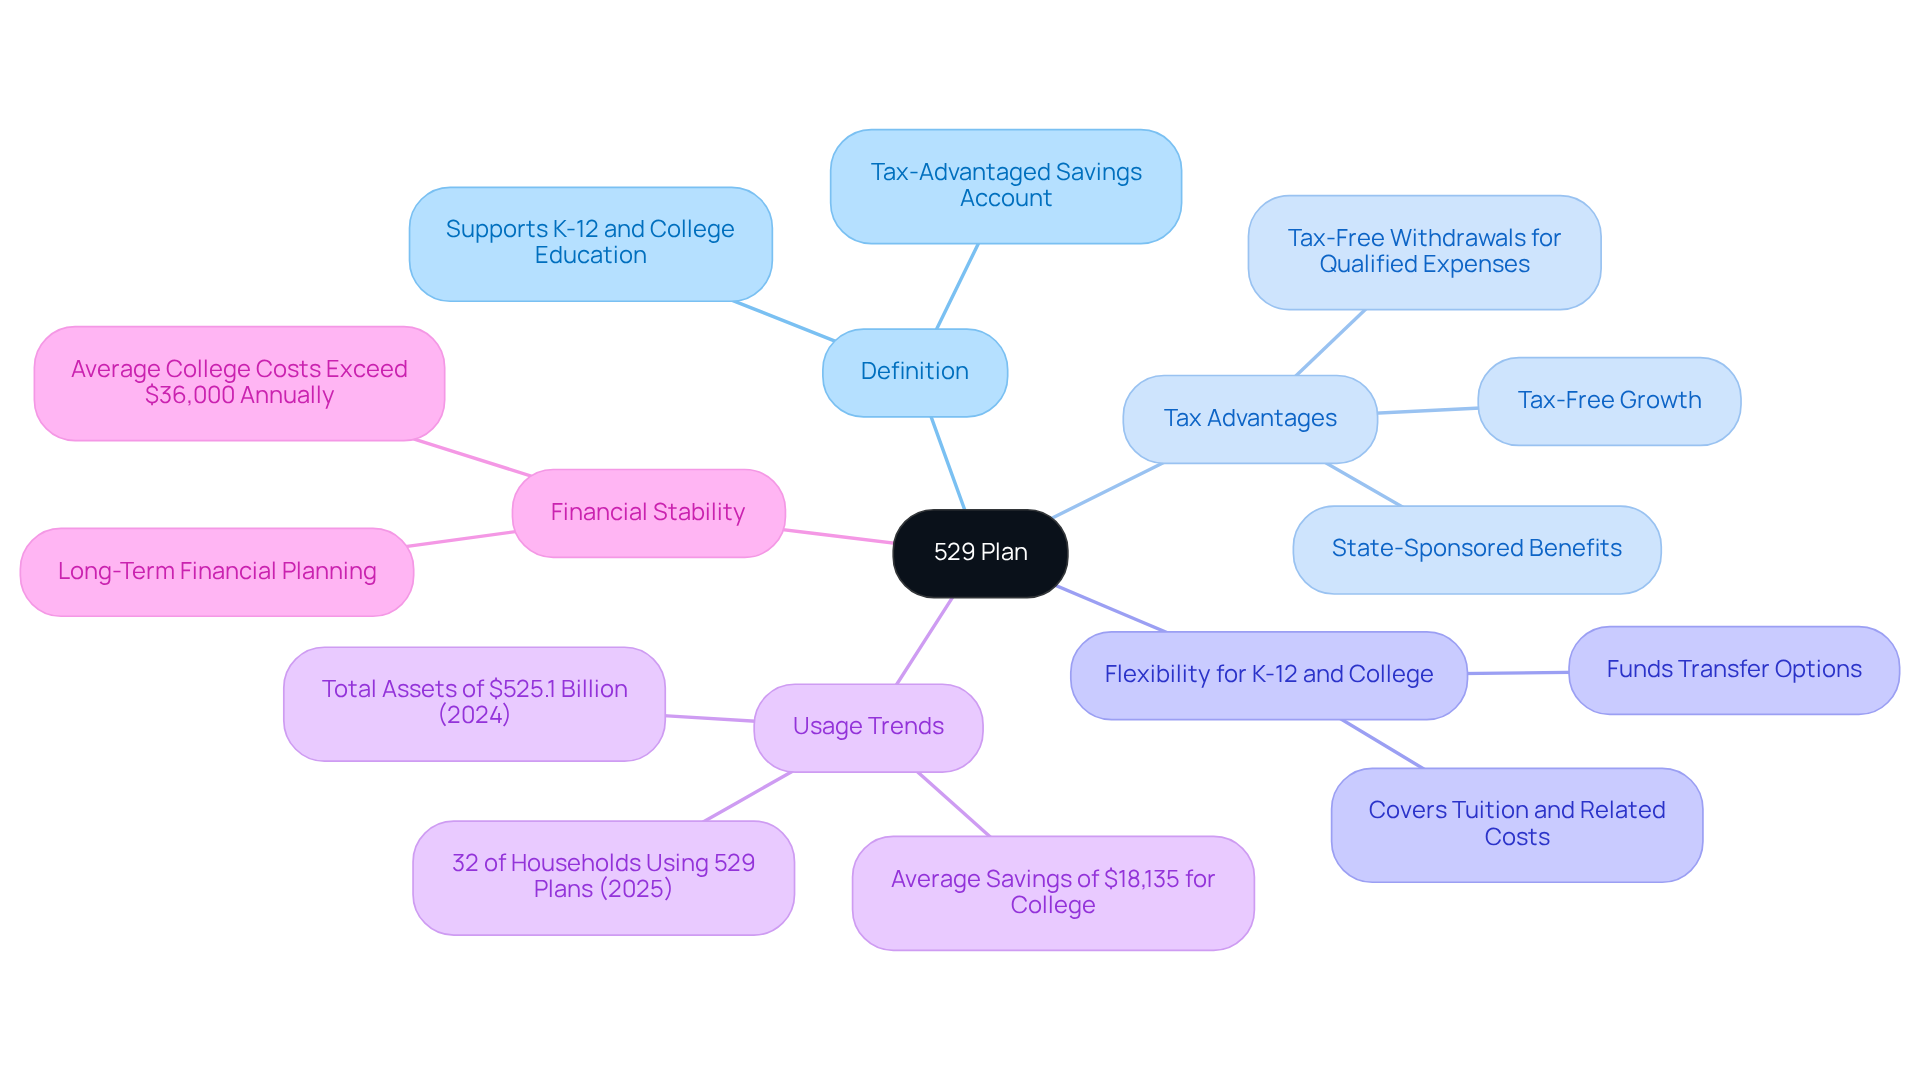
Imagine a future where your child’s education is secure and within reach. A 529 plan tax deduction is available through a tax-advantaged savings account designed to help families like yours save for future education expenses. With this program, you can invest funds that grow tax-free, and when it’s time to withdraw for qualified education costs, those withdrawals are also exempt from taxes.
The beauty of a 529 program lies in its flexibility. It’s not just for college; it supports K-12 education too, making it an essential resource for financial planning. As of 2025, 32% of households are turning to college savings programs to help with educational expenses. This growing trend shows how families are recognizing the value of 529 programs in securing their children’s futures.
Financial specialists emphasize that the 529 plan tax deduction is among these strategies that offer significant tax advantages, helping families manage the rising costs of education, which average over $36,000 annually. Picture this: families just like yours have successfully used 529 accounts to pave the way for their children’s educational journeys, showcasing how these accounts can foster long-term financial stability.
Together, we can navigate this journey toward a brighter future for your family. We’re here for you, ready to support you in making informed decisions that align with your family’s values and goals.
Tax Benefits of 529 Plans: What You Should Know
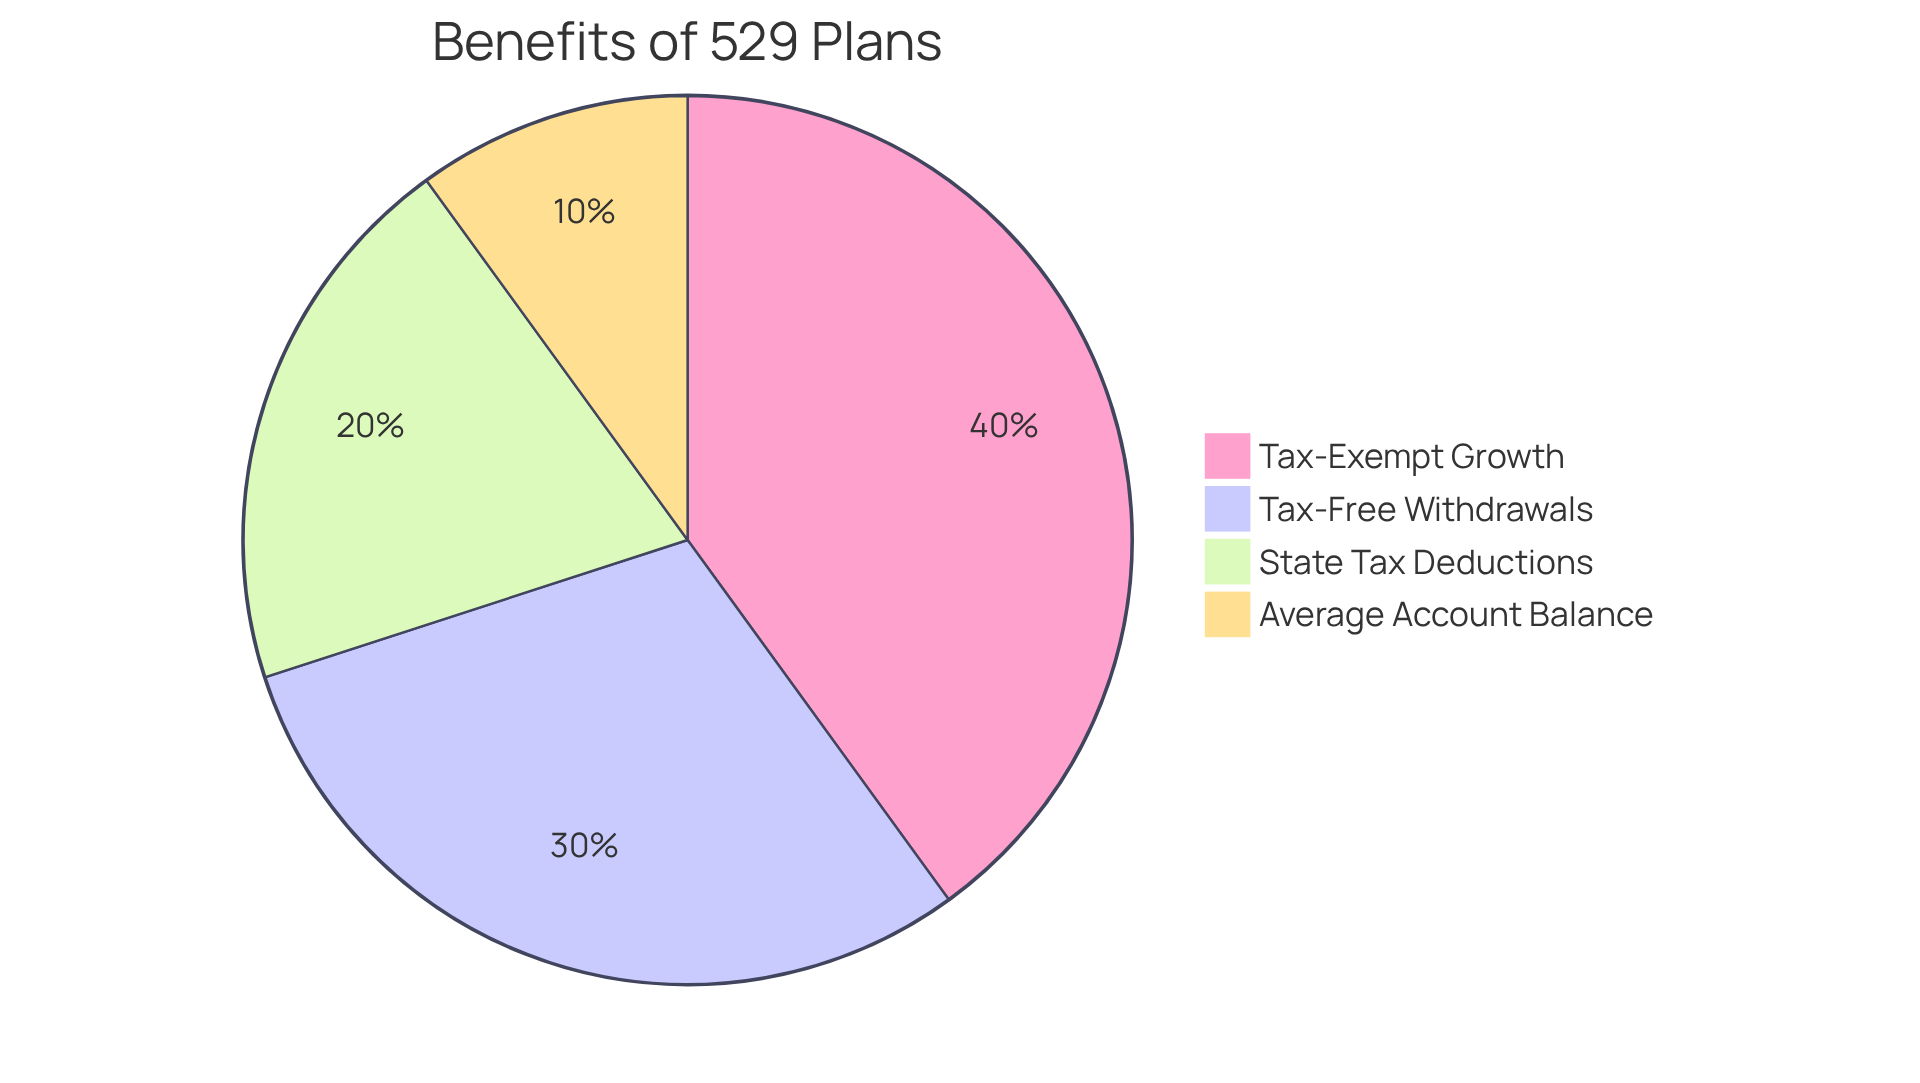
529 accounts offer substantial tax benefits, providing tax-exempt growth on investments and tax-free withdrawals for eligible education costs. While contributions aren’t federally tax-deductible, many states offer a 529 plan tax deduction or credits for contributions made to in-state programs. For instance, in Alabama, married couples can take advantage of a 529 plan tax deduction of up to $10,000 from their state income tax for contributions to a CollegeCounts 529 account, while single filers can receive a deduction of up to $5,000. This dual advantage of state and federal tax benefits makes 529 options an attractive choice for families looking to save for education.
Imagine the peace of mind knowing that the average balance in a 529 account is $30,295, with a total of $508 billion saved across the United States. This highlights just how effective these savings vehicles can be. With 16.8 million 529 accounts established, countless families are already reaping the rewards of these tax benefits. It’s reassuring to know that 49 out of 50 states provide 529 programs, ensuring that families have access to these valuable resources no matter where they are.
Real-life examples show how a 529 plan tax deduction can positively impact families’ education savings. Picture a household benefiting from a 529 plan tax deduction while contributing to a 529 account; they can see their total savings grow more effectively, allowing them to allocate more resources toward their children’s education. This approach not only helps families manage rising college expenses but also fosters financial responsibility and prepares future generations for success.
Together, we can navigate this journey of financial planning, ensuring that your family’s educational goals are within reach.
Eligibility for 529 Plan Tax Deductions: Key Criteria
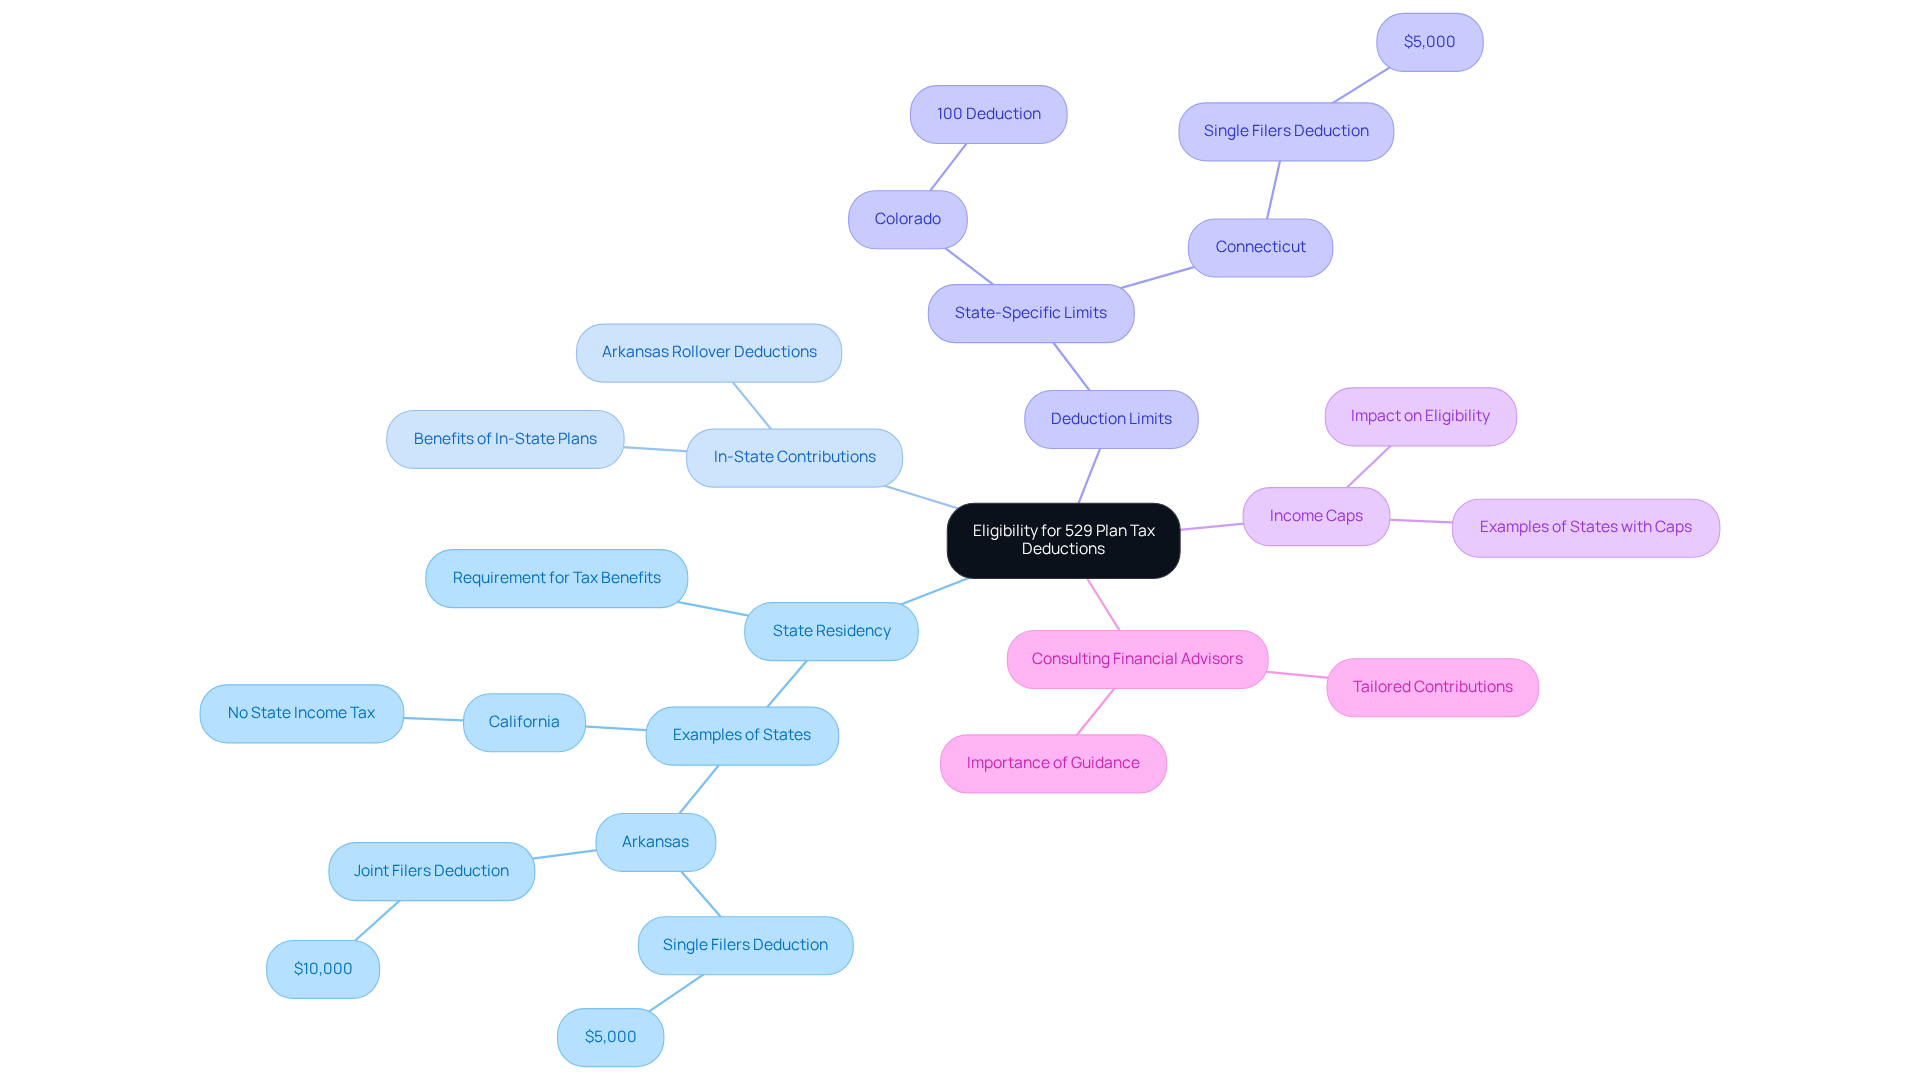
Navigating the world of 529 arrangements can feel overwhelming, especially for young parents looking to secure their children’s educational future. To qualify for the 529 plan tax deduction associated with these plans, it’s essential to understand the specific criteria that vary by state. Typically, the account owner needs to be a resident of the state offering the deduction, and contributions should be directed to an in-state 529 plan.
Imagine if you could save on taxes while investing in your child’s education. For instance, in Arkansas, single filers can deduct up to $5,000, while joint filers can deduct $10,000. However, some states may impose income limits or contribution caps that could affect your eligibility. It’s important to understand these nuances, as recent data shows that only about 30% of households are aware of their state’s specific requirements.
This is where financial advisors, like those at Bright Advisers, come in. They can guide you through the intricacies of 529 eligibility, ensuring you make the most of your tax advantages. Comprehending these criteria is vital for families striving to optimize their college savings. Together, we can navigate this journey, making informed choices about your 529 contributions.
It’s worth noting that while contributions to a 529 account won’t reduce your federal taxable income, they may allow for a 529 plan tax deduction that can lower your state taxable income if your state offers deductions. Plus, most states require contributions to be made by December 31 to qualify for a state income tax benefit. To maximize your benefits, consider consulting with a financial planner who can tailor your contributions based on your unique financial situation and state regulations.
Remember, we’re here for you. Bright Advisers offers tailored wealth management solutions that emphasize educational readiness and financial security, helping young families like yours make the best choices for a brighter future.
Contribution Limits for 529 Plans: How They Affect Deductions
Imagine planning for your child’s future education. In 2025, you can contribute up to $19,000 annually to a 529 plan without worrying about federal gift tax. If you’re married, that amount doubles to $38,000. This is a wonderful opportunity to invest in your child’s dreams with the benefit of a 529 plan tax deduction while staying within tax regulations.
It’s important to understand that if you contribute more than these limits, you’ll need to report it to the IRS. Those excess contributions will count against your lifetime gift tax exemption, which is currently set at $13.99 million for individuals and $27.98 million for couples. Knowing this can help you manage your contributions wisely, ensuring you maximize your benefits.
Imagine being able to strategically plan your contributions to avoid exceeding those limits. This way, you can enjoy the benefits of the 529 plan tax deduction available to you. Plus, some states even allow you to carry forward excess contributions to future tax years, giving you more flexibility in your financial planning.
By seeking guidance from financial consultants, you can navigate these complexities with ease. They can help you maximize your 529 benefits, ensuring that your children have the educational opportunities they deserve. Remember, we’re here for you, and together, we can navigate this journey toward securing your family’s future.

State-Specific Tax Benefits for 529 Plans: A Comparative Overview
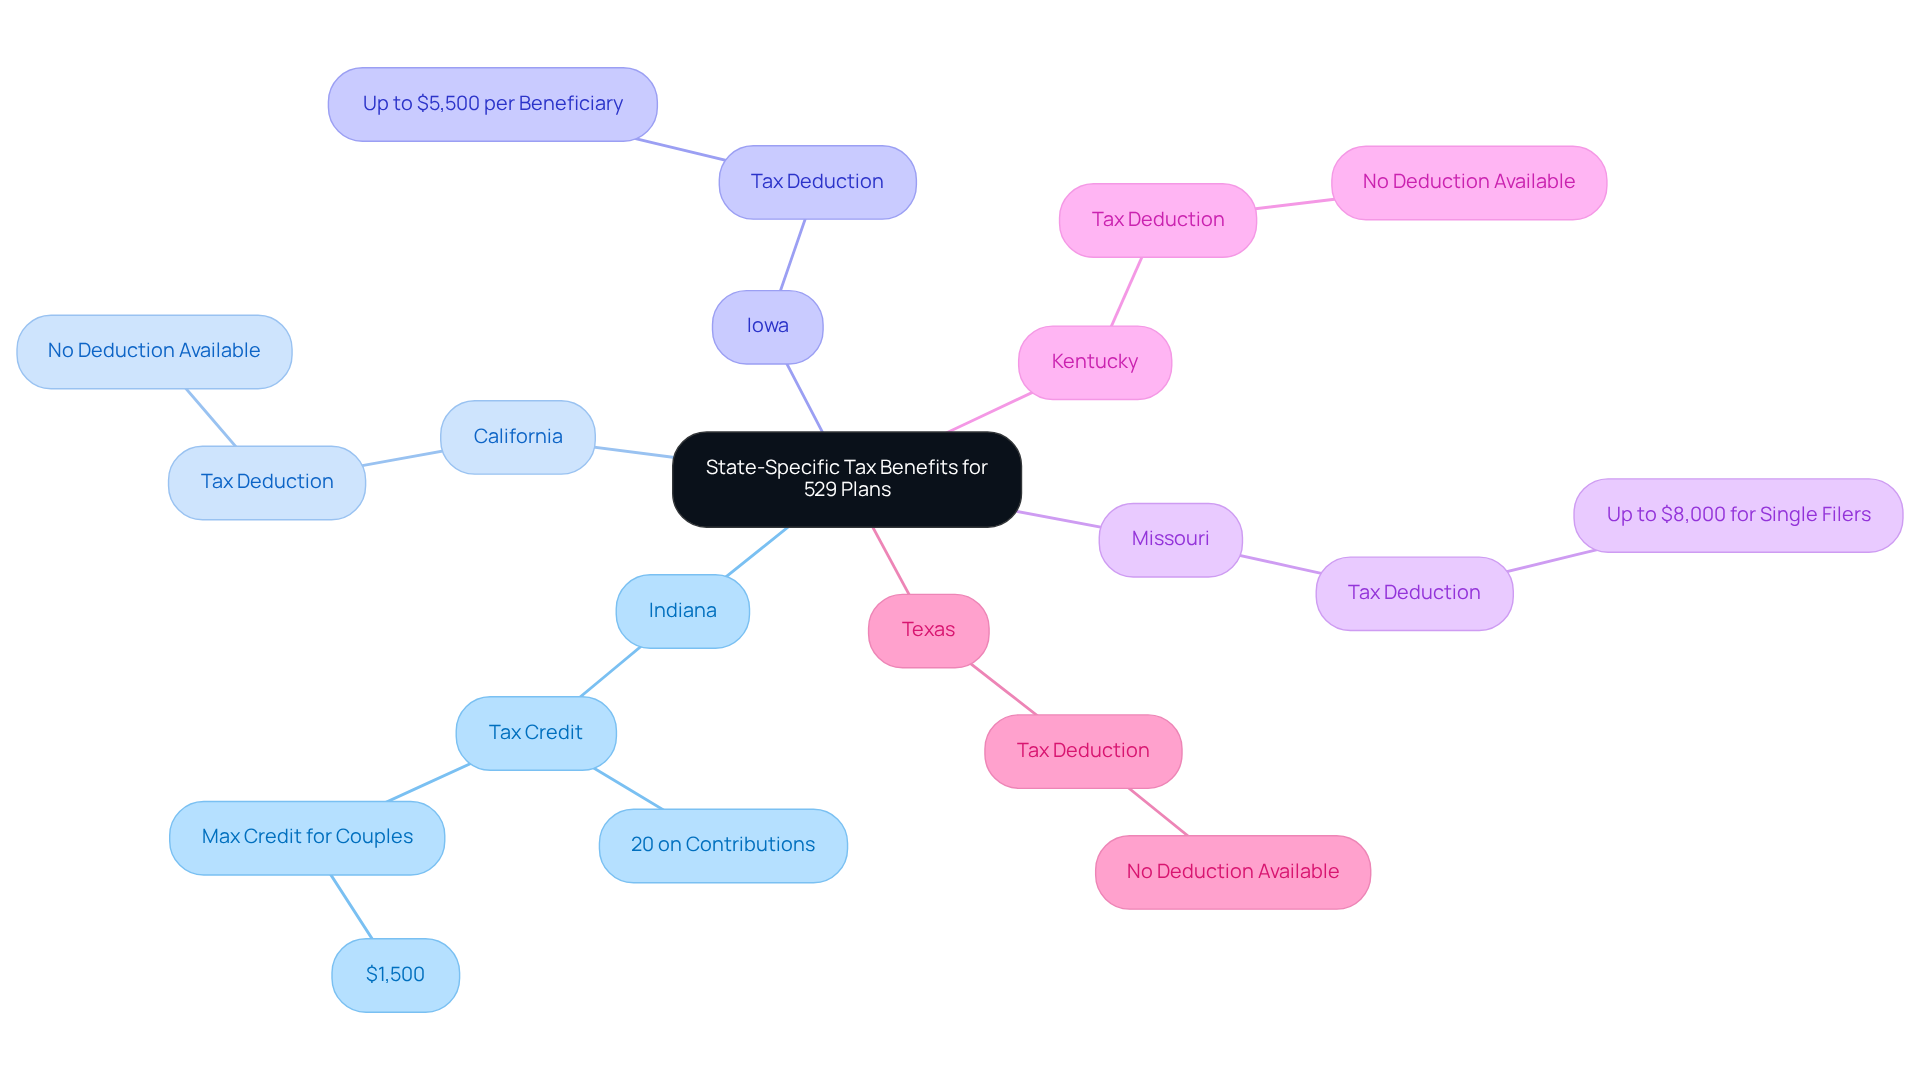
Understanding the 529 plan tax deduction and its tax advantages can feel overwhelming, but it’s crucial for families looking to save for education. Did you know that these benefits vary significantly from state to state? For instance, Indiana shines with a generous 20% tax credit on contributions, allowing couples filing jointly to claim up to $1,500. On the other hand, California doesn’t provide any state tax deduction, which can be disheartening for families there.
Imagine if you lived in Iowa, where the 529 plan tax deduction allows you to deduct up to $5,500 per beneficiary, or in Missouri, where single filers can deduct up to $8,000 each year. Unfortunately, some states, such as Kentucky and Texas, do not offer any 529 plan tax deduction for contributions. With recent changes in state tax benefits, it’s more important than ever for families to stay informed about their local regulations.
Research shows that around 30 states provide a 529 plan tax deduction or credit for contributions. This highlights a wonderful opportunity for families to save significantly. We encourage you to explore your state’s specific 529 program benefits. By doing so, you can maximize your savings and take full advantage of these tax benefits.
Consider the story of Allison and Brian. Through thoughtful tax planning with Bright Advisers, they secured their children’s educational future while enhancing their overall financial security. This allowed them to spend more quality time with their loved ones, creating cherished memories together.
Remember, we’re here for you. Together, we can navigate this journey of financial planning, ensuring that your family’s future is bright and filled with possibilities.
Drawbacks of 529 Plans: Understanding the Limitations
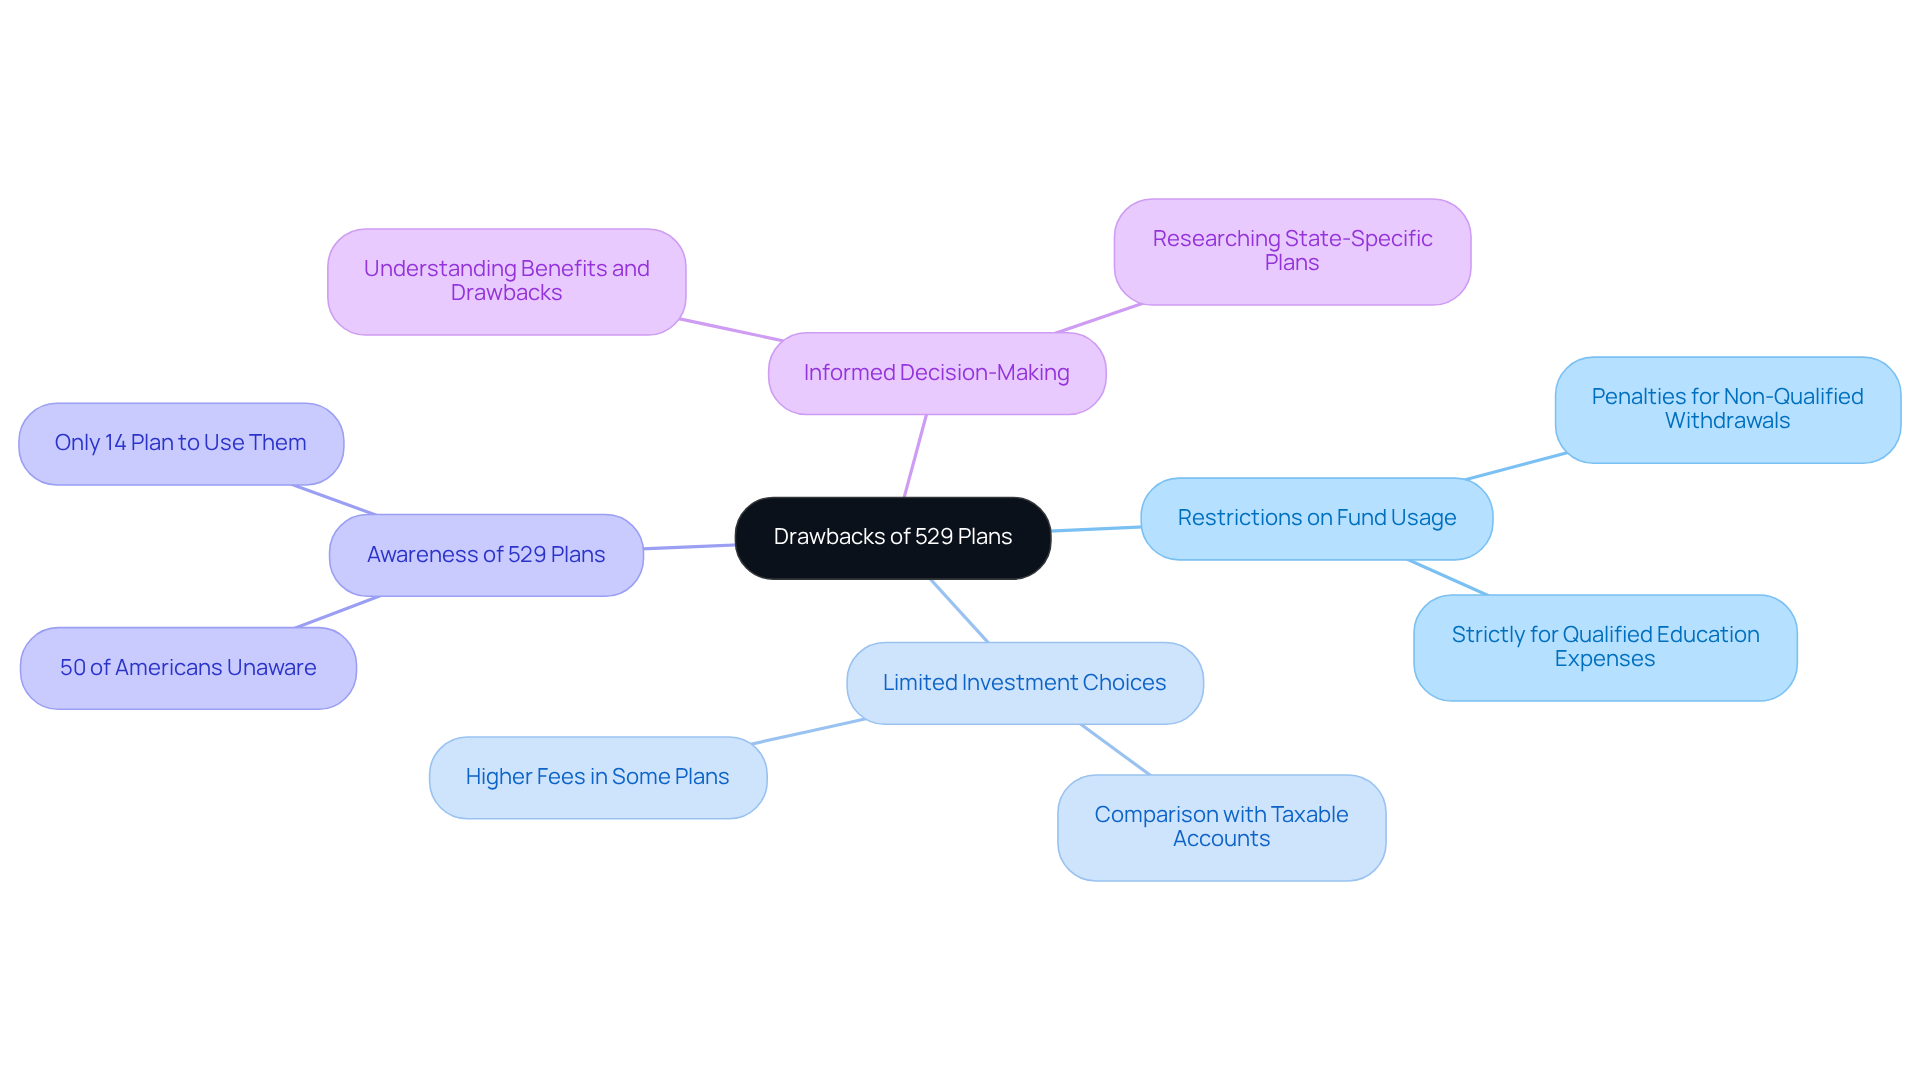
While a 529 plan tax deduction can offer significant benefits, it’s essential to recognize the restrictions that come with them. Funds in these accounts are strictly for qualified education expenses. If you withdraw for other purposes, you might face taxes and a 10% penalty on earnings. This can be a real concern for families who have diverse financial goals.
Imagine wanting to save for your child’s education but also needing flexibility for other important expenses. Unfortunately, investment choices within 529 accounts can be quite limited compared to options like taxable brokerage accounts or Roth IRAs, which often provide a broader selection and potentially lower fees.
For instance, some families, especially those working with financial advisors, have opted to focus on contributions to taxable accounts instead of 529 plans. This choice allows them to maintain greater financial flexibility for future needs.
As we look ahead to 2025, it’s concerning to note that half of Americans are still unaware of 529 options, and only 14% plan to use them. This highlights a significant gap in understanding the potential downsides.
Families should carefully consider these limitations alongside their educational savings strategies. It’s crucial to make informed decisions that align with your long-term financial goals. Remember, we’re here for you, and together, we can navigate this journey toward securing your family’s future.
Withdrawing Funds from 529 Plans: Tax Implications Explained
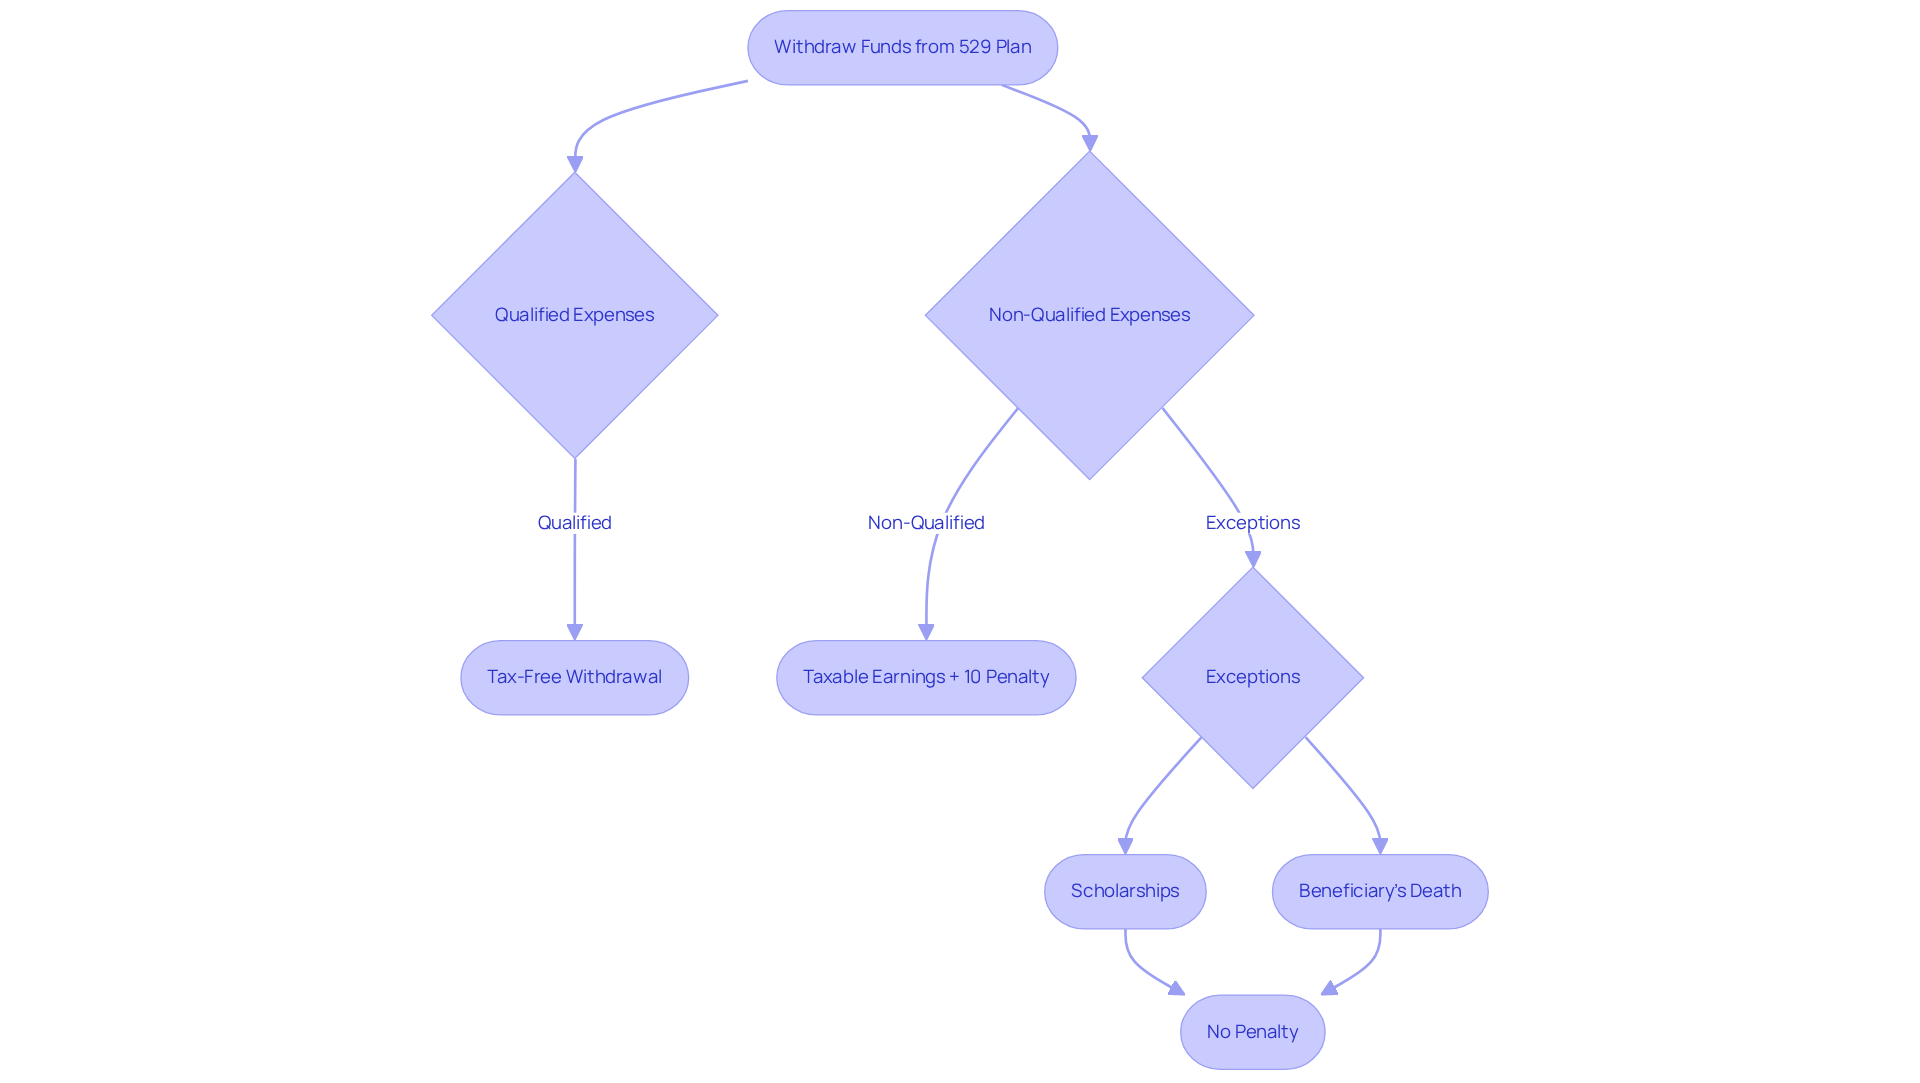
When it comes to saving for your child’s education, the 529 plan tax deduction offers a wonderful benefit: withdrawals for qualified education expenses are tax-free at the federal level. This makes them an appealing choice for families like yours who are planning for college and considering a 529 plan tax deduction.
However, it’s important to be aware that if funds are used for non-qualified expenses, the earnings portion of that withdrawal will be taxable. Plus, there’s a potential 10% penalty on those earnings. Imagine the stress of unexpected costs when you’re just trying to do what’s best for your child’s future. The recipient of a non-qualified distribution must report the taxable earnings on their tax return, which is crucial for staying compliant.
To avoid any surprises, families should keep detailed records of their expenses. This way, you can ensure compliance and steer clear of penalties when it’s time to withdraw funds. Remember, non-qualified withdrawals can lead to both federal income taxes and that 10% penalty on the earnings portion.
But don’t worry – there are exceptions! In certain situations, like receiving scholarships or in the unfortunate event of the beneficiary’s death, this penalty can be avoided. By understanding the ins and outs of 529 account withdrawals, you can manage your resources effectively and avoid unnecessary penalties. Together, we can navigate this journey and optimize your educational savings for your family’s future.
Qualified Expenses for 529 Plans: Maximizing Your Tax Deductions
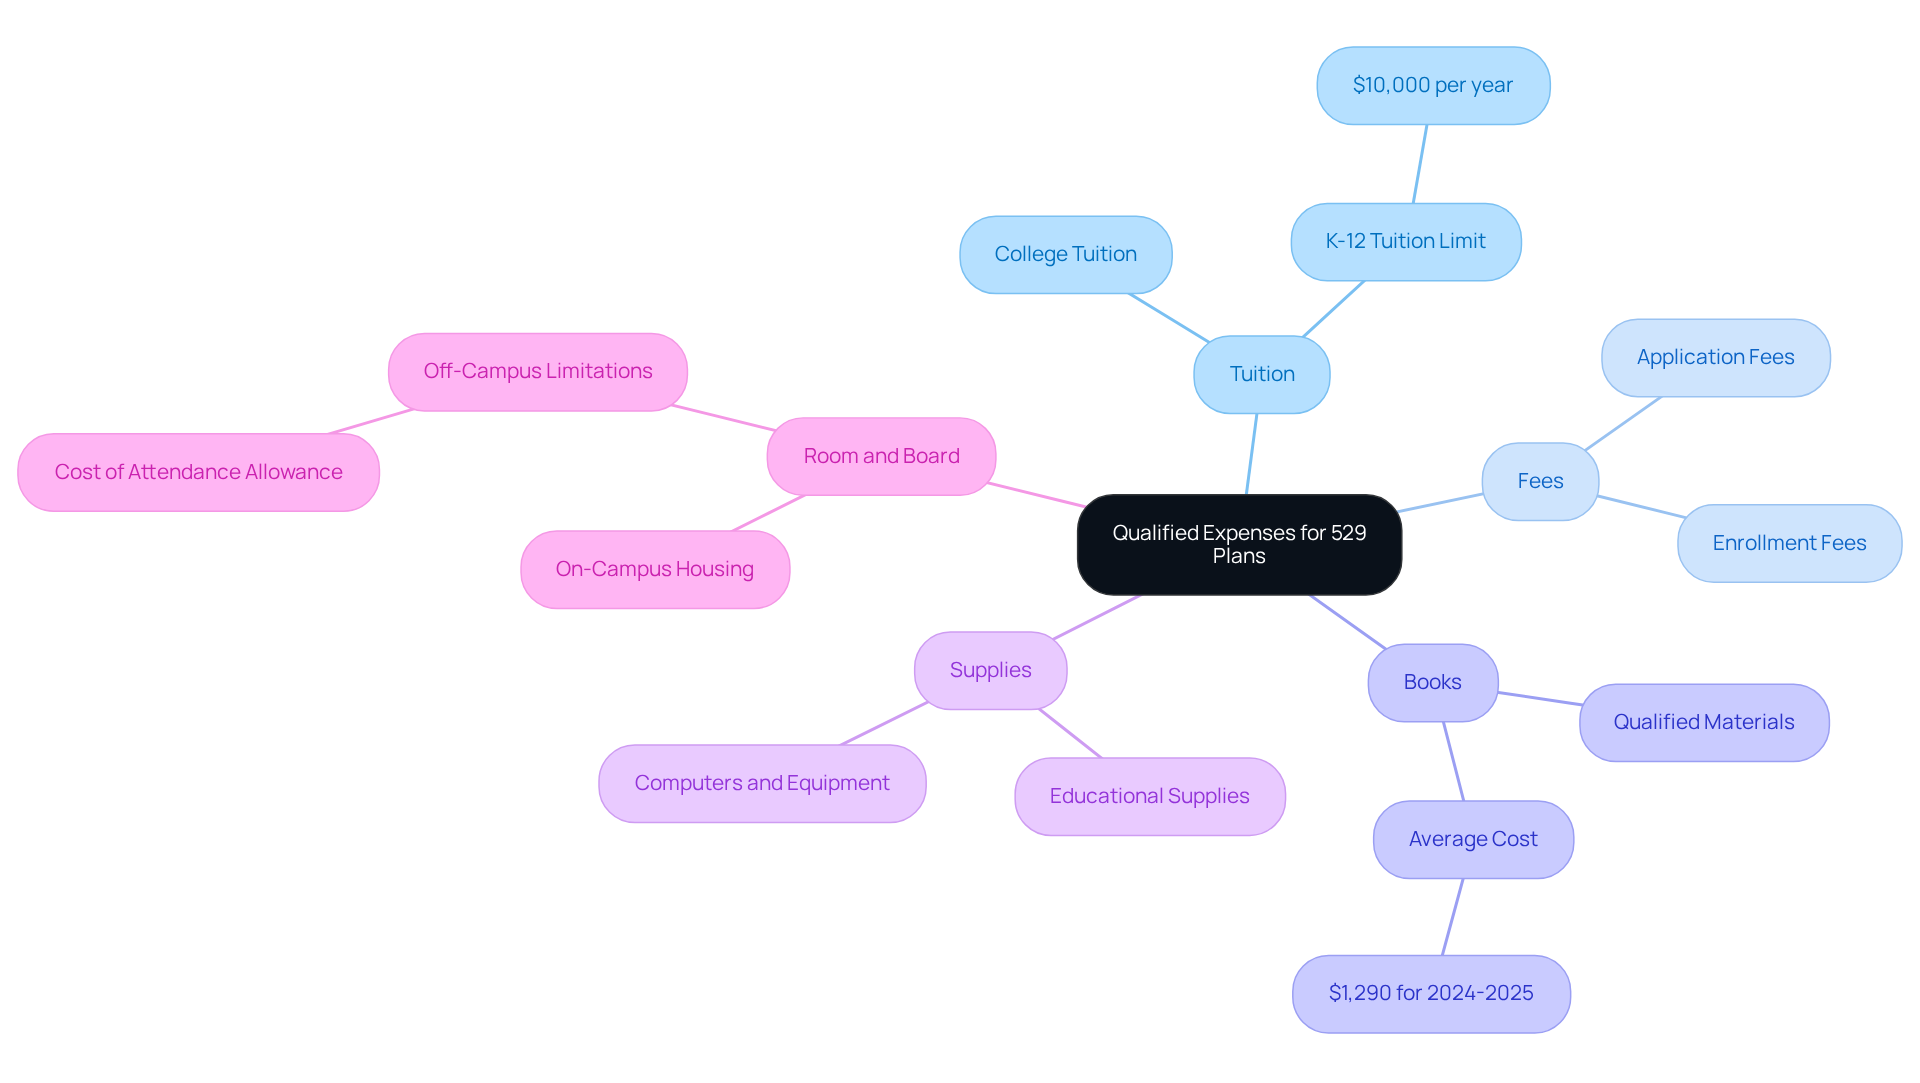
Navigating the world of educational expenses can feel overwhelming, especially for young parents. Did you know that qualified expenses for 529 plans cover a wide range of educational costs? This includes:
- Tuition
- Fees
- Books
- Supplies
- Room and board for college students
For K-12 education, families can withdraw up to $10,000 each year for tuition at public, private, or religious schools.
Imagine if you could ease some of that financial burden. In the 2024-2025 academic year, the average cost of books and supplies for on-campus undergraduate students is projected to be $1,290. This highlights just how important it is to utilize 529 funds for these necessary expenses. By ensuring that withdrawals are allocated to qualified expenses, families can maximize the 529 plan tax deduction and avoid the 10% federal penalty associated with non-qualified withdrawals.
It’s important to understand that working with a financial consultant, like those at Bright Advisers who focus on low fund fees, can help clarify what qualifies as eligible expenses. This guidance can be invaluable in navigating the complexities of 529 plans effectively. For instance, families can use 529 funds to cover the full amount of tuition and fees for college, including online courses. However, it’s essential to be aware of the restrictions on off-campus housing expenses, which are limited to the college’s cost of attendance allowance.
Moreover, some families may have legacy fee-bearing mutual funds or low-fee-bearing ETFs that can influence their overall savings strategy. This thoughtful approach not only improves tax efficiency but also supports families in achieving their educational funding goals with the help of a 529 plan tax deduction. Remember, we’re here for you, and together, we can navigate this journey toward securing a brighter future for your children.
Long-Term Financial Planning with 529 Plans: A Strategic Approach
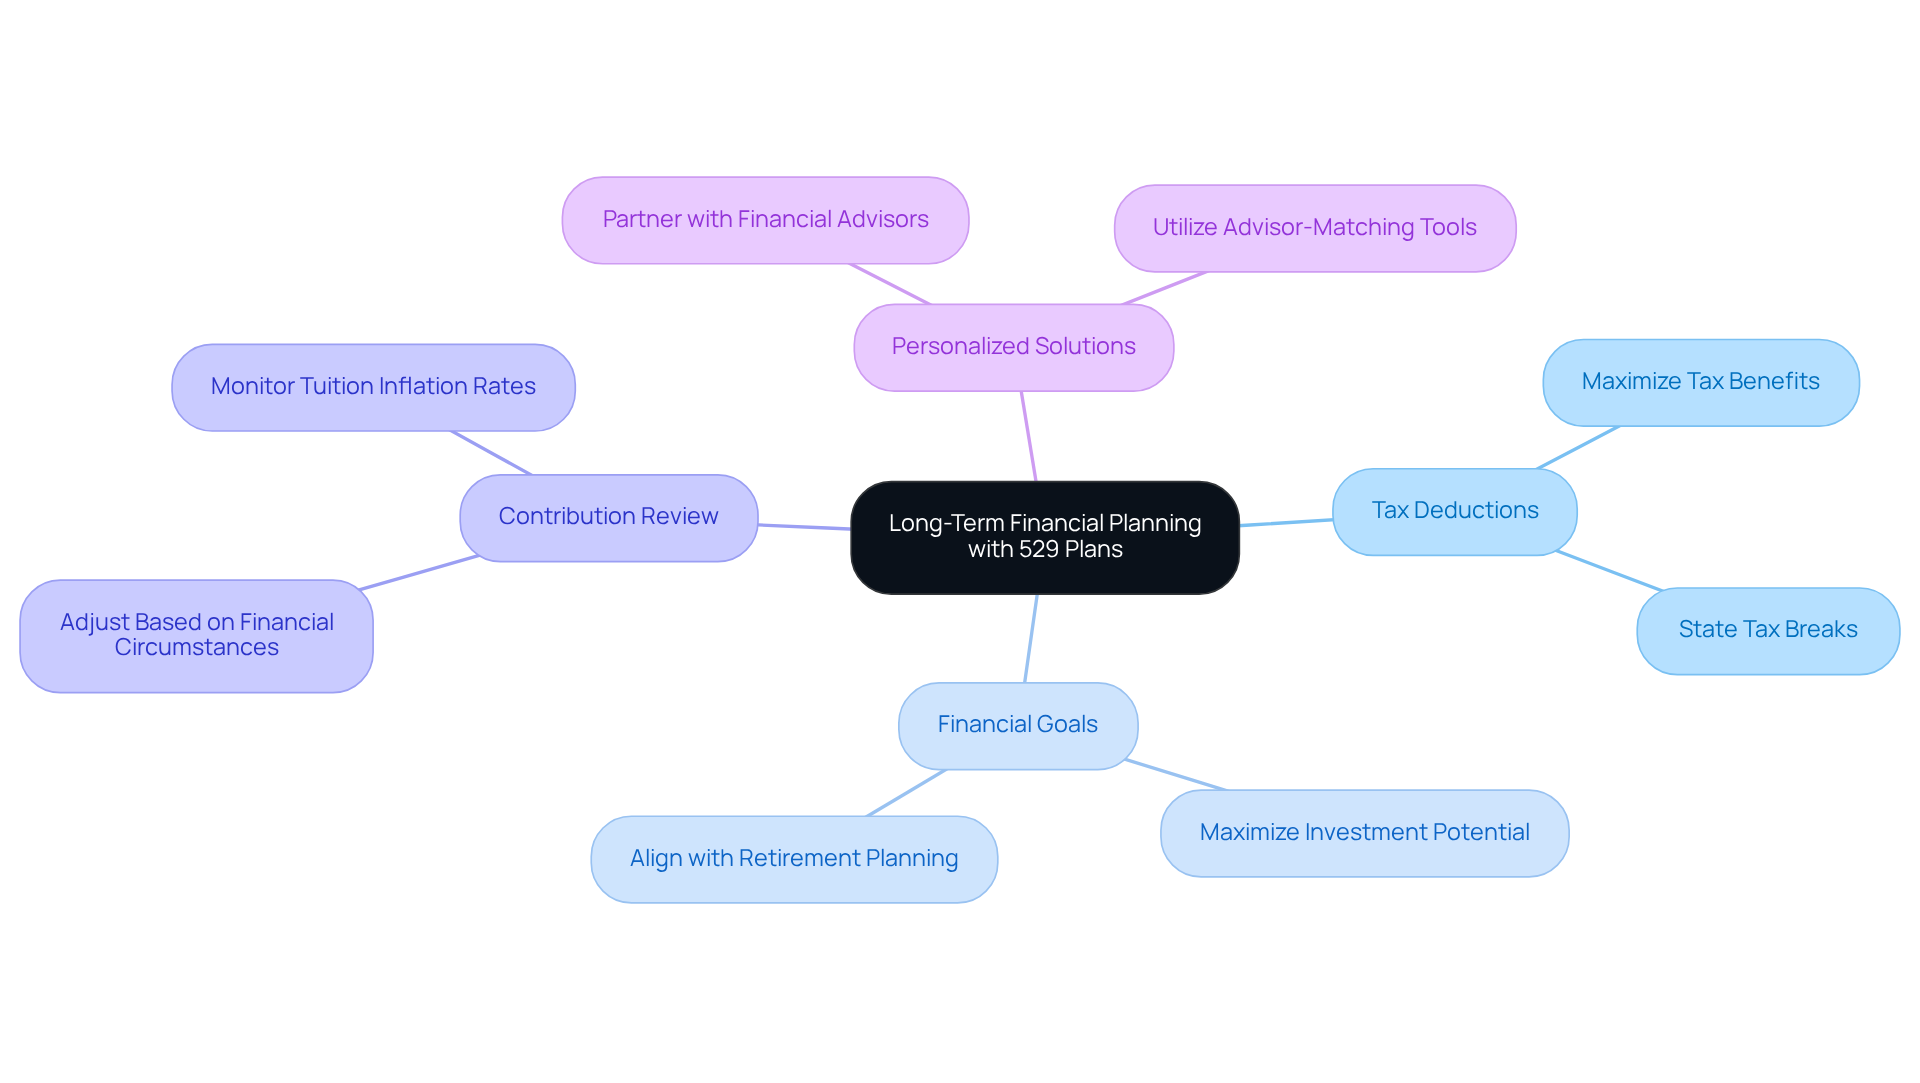
Imagine ensuring your child’s educational future with confidence. Incorporating a 529 plan tax deduction into your long-term financial strategies can be a game changer for families like yours. By partnering with Bright Advisers, you can optimize your tax situation and make the most of the 529 plan tax deduction while aligning it with other important financial goals, such as saving for retirement and planning your estate.
It’s essential to regularly review and adjust your contributions based on your changing financial circumstances and educational aspirations. This way, you can stay on track with your savings goals, ensuring that your family’s future is secure.
At Bright Advisers, we understand the unique challenges young families face. That’s why we offer personalized wealth management solutions designed to enhance your financial security and educational preparedness. Together, we can navigate this journey, allowing you to enjoy peace of mind and quality time with your loved ones.
Plus, with minimal fund fees, you can maximize your investment potential, further supporting your financial objectives. We’re here for you, ready to help you take the next step toward a brighter future for your family.
Conclusion
Understanding the nuances of 529 plans and their tax deductions is crucial for young families looking to secure their children’s educational futures. These plans provide a wonderful opportunity to save for education while enjoying tax benefits that can significantly lighten the financial load of rising educational costs. By embracing the insights shared in this article, families can make informed choices that align with their long-term financial aspirations.
Key points include:
- The tax advantages of 529 plans
- Eligibility criteria
- Contribution limits
- The importance of recognizing state-specific benefits
Families can enhance their savings by taking advantage of the tax deductions available in their states, all while being aware of the limitations and potential penalties tied to non-qualified withdrawals. Moreover, the role of financial advisers is emphasized as a valuable resource to help navigate these complexities and tailor strategies that meet individual family needs.
Ultimately, the importance of 529 plans goes beyond just tax deductions; they serve as a strategic tool for nurturing educational opportunities and ensuring financial security. Families are encouraged to explore their options, consult with financial professionals, and actively engage in long-term financial planning. By doing so, they can create a brighter future for their children, filled with educational possibilities and peace of mind.
Frequently Asked Questions
What is a 529 plan and its purpose?
A 529 plan is a tax-advantaged savings account designed to help families save for future education expenses, allowing funds to grow tax-free and providing tax-free withdrawals for qualified education costs.
What are the tax benefits of 529 plans?
529 plans offer tax-exempt growth on investments and tax-free withdrawals for eligible education costs. While contributions aren’t federally tax-deductible, many states provide tax deductions or credits for contributions to in-state programs.
Can 529 plans be used for education other than college?
Yes, 529 plans can be used for K-12 education as well as college expenses, making them a flexible resource for educational savings.
How can Bright Advisers help with 529 plans?
Bright Advisers provides personalized financial planning to help families create effective strategies for maximizing 529 plan tax deductions and managing their educational savings.
What is the average balance in a 529 account?
The average balance in a 529 account is $30,295, with a total of $508 billion saved across the United States.
How many states offer 529 programs?
49 out of 50 states provide 529 programs, ensuring widespread access for families to utilize these savings options.
What is the significance of the 529 plan tax deduction?
The 529 plan tax deduction helps families manage rising education costs by allowing them to save more effectively, thus fostering long-term financial stability for their children’s education.
How does Bright Advisers enhance the financial planning process for families?
Bright Advisers uses innovative technology to improve investment management, eliminate unnecessary fund fees, and capture tax-loss harvesting opportunities, making financial planning more accessible and effective.
List of Sources
- Bright Advisers: Personalized Financial Planning for 529 Tax Deductions
- Release: 529 Plan Program Statistics, December 2024 | Investment Company Institute (https://ici.org/research/stats/529s/529s_24_q4)
- 529 Plan Surge: Roth IRA Rollover Rule Changes the Game (https://thecollegeinvestor.com/59257/529-plan-account-balances-just-hit-a-record-in-2025?srsltid=AfmBOoo2HQZMjL6fF4SgzZEddJF3EzmyRcO8zoar9mvsaG9mcHt_fv0-)
- 529 college savings plans ‘are better now than they’ve ever been,’ expert says. Here are key changes for 2024 (https://cnbc.com/2024/05/15/529-college-savings-plans-have-even-more-benefits-in-2024.html)
- 529 Tax Deductions by State [2025]: Rules on Tax Benefits (https://educationdata.org/529-tax-deductions-by-state)
- 10 Key Benefits of the 529 Tax Deduction for Young Families – Bright Advisers (https://brightadvisers.com/10-key-benefits-of-the-529-tax-deduction-for-young-families)
- Understanding the 529 Plan: Definition and Purpose
- 9 Reasons a 529 Plan Is Worth It and 7 Reasons It’s Not (Plus the Best Alternatives) (https://annuityexpertadvice.com/reasons-529-plan-is-worth-it-and-reasons-its-not)
- 529 College Savings Plan Statistics | BestColleges (https://bestcolleges.com/research/529-college-savings-plan-statistics)
- Report: More U.S. families choosing 529 plans to save for college – Utah System of Higher Education (https://ushe.edu/report-more-u-s-families-choosing-529-plans-to-save-for-college)
- College Saving Statistics [2025]: Average Savings & 529 Balance (https://educationdata.org/college-savings-statistics)
- Release: 529 Plan Program Statistics, December 2024 | Investment Company Institute (https://ici.org/research/stats/529s/529s_24_q4)
- Tax Benefits of 529 Plans: What You Should Know
- 529 Plan And College Savings Statistics (https://thecollegeinvestor.com/529-plan-and-college-savings-statistics?srsltid=AfmBOoosE_756UOB_aDFuPZAbWZrhRP32wsjfhtB7TeK1iyibF1pBokV)
- 529 Plan Tax Benefits: Your Guide to Education Savings (https://taxhardshipcenter.com/blog/the-tax-benefits-of-529-plans-a-comprehensive-guide)
- 529 Tax Benefits | CollegeCounts (https://collegecounts529.com/tax-benefits)
- Release: 529 Plan Program Statistics, December 2024 | Investment Company Institute (https://ici.org/research/stats/529s/529s_24_q4)
- Eligibility for 529 Plan Tax Deductions: Key Criteria
- State Section 529 Deductions – Finaid (https://finaid.org/savings/state529deductions)
- 529 Plan Deductions for Every State (https://smartasset.com/taxes/529-plan-tax-deductions-for-every-state)
- Understand Your 529 State Tax Benefits (https://morningstar.com/personal-finance/how-do-your-states-529-tax-benefits-stack-up)
- How Much Is Your State’s 529 Plan Tax Deduction Really Worth? (https://savingforcollege.com/article/how-much-is-your-state-s-529-plan-tax-deduction-really-worth)
- 529 Tax Deductions by State [2025]: Rules on Tax Benefits (https://educationdata.org/529-tax-deductions-by-state)
- Contribution Limits for 529 Plans: How They Affect Deductions
- Do 529 Plans Have Contribution Limits? (https://morningstar.com/personal-finance/do-529-plans-have-contribution-limits)
- Maximum 529 Plan Contribution Limits by State (https://savingforcollege.com/article/maximum-529-plan-contribution-limits-by-state)
- 529 contribution limits 2024 & 2025 | Fidelity (https://fidelity.com/learning-center/smart-money/529-contribution-limits)
- 529 Plan Contribution Limits by State in 2024 and 2025 (https://smartasset.com/investing/529-plan-contribution-limits)
- Tax Benefits of a 529 Plan | Learn | Invest529 (https://invest529.com/529-basics/tax-benefits)
- State-Specific Tax Benefits for 529 Plans: A Comparative Overview
- State Section 529 Deductions – Finaid (https://finaid.org/savings/state529deductions)
- 529 plan tax benefits by state | Vanguard (https://investor.vanguard.com/tools-calculators/529-plan-tax-benefits-by-state)
- 529 Plan Deductions for Every State (https://smartasset.com/taxes/529-plan-tax-deductions-for-every-state)
- 529 Tax Deductions by State [2025]: Rules on Tax Benefits (https://educationdata.org/529-tax-deductions-by-state)
- 529 Plans by State: Tax Benefits Map (https://invesco.com/education-savings/en/collegebound-529-investor/resources/529-tax-benefits-by-state.html)
- Drawbacks of 529 Plans: Understanding the Limitations
- 5 Disadvantages Of A 529 College Savings Plan | Bankrate (https://bankrate.com/investing/529-plan-disadvantages)
- I’m a financial planner, and I have a 529 plan for my child, but I intentionally don’t max out my contributions (https://businessinsider.com/financial-planner-dont-max-out-childs-529-plan-2024-8)
- 529 College Savings Plan Statistics | BestColleges (https://bestcolleges.com/research/529-college-savings-plan-statistics)
- Benefits and Drawbacks of Investing in a 529 Plan – David Lerner Associates (https://davidlerner.com/newsroom/article/benefits-and-drawbacks-of-investing-in-a-529-plan)
- Pros and Cons of 529 Plans: Is a 529 Right for Your Education Savings? (https://savingforcollege.com/article/what-are-the-pros-and-cons-of-using-a-529-plan)
- Withdrawing Funds from 529 Plans: Tax Implications Explained
- Can I Avoid The 529 Plan Withdrawal Penalty? | Bankrate (https://bankrate.com/investing/no-escape-from-529-plan-penalty)
- Who Pays Taxes on Non-Qualified 529 Plan Withdrawal? (https://savingforcollege.com/article/whose-tax-rate-applies-to-a-non-qualified-529-plan-distribution)
- Tax Reduction Letter – How Are 529 College Savings Account Withdrawals Taxed? (https://bradfordtaxinstitute.com/Content/How-Are-529-College-Savings-Account-Withdrawals-Taxed.aspx)
- Release: 529 Plan Program Statistics, December 2024 | Investment Company Institute (https://ici.org/research/stats/529s/529s_24_q4)
- College Saving Statistics [2025]: Average Savings & 529 Balance (https://educationdata.org/college-savings-statistics)
- Qualified Expenses for 529 Plans: Maximizing Your Tax Deductions
- 529 Basics | The Education Plan (https://theeducationplan.com/basics/529-qualified-expenses)
- 529 Plan Qualified Expenses: What a 529 Can Be Used For (https://smartasset.com/investing/what-are-529-plan-qualified-expenses)
- 529 Qualified Expenses: What Can You Use 529 Money For? (https://savingforcollege.com/article/what-you-can-pay-for-with-a-529-plan)
- What 529 Plans Cover | Qualified Expenses | Invest529 (https://invest529.com/529-basics/qualified-expenses)
- Release: 529 Plan Program Statistics, December 2024 | Investment Company Institute (https://ici.org/research/stats/529s/529s_24_q4)
- Long-Term Financial Planning with 529 Plans: A Strategic Approach
- Release: 529 Plan Program Statistics, December 2024 | Investment Company Institute (https://ici.org/research/stats/529s/529s_24_q4)
- Report: More U.S. families choosing 529 plans to save for college – Utah System of Higher Education (https://ushe.edu/report-more-u-s-families-choosing-529-plans-to-save-for-college)
- Financial Advisor for 529 plan: Services and Examples (https://smartasset.com/financial-advisor/financial-advisor-for-529-plan)
- College Saving Statistics [2025]: Average Savings & 529 Balance (https://educationdata.org/college-savings-statistics)
- 529 & ABLE Assets Up 11.8% Year Over Year | PLANSPONSOR (https://plansponsor.com/529-able-account-assets-up-11-8-year-over-year-in-q2)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Tax Management for high-income W-2 families at Bright Advisers.
Keep reading