

Overview
Imagine having a high-yield savings account (HYSA) that can help you grow your family’s savings. The good news is that you can withdraw money from these accounts, but it’s important to know that withdrawals are generally limited to six per month. This limit helps you avoid unnecessary fees, which can be a concern for families trying to make the most of their finances.
It’s essential to understand these limits. Exceeding the allowed number of withdrawals can lead to penalties that might diminish the advantages of those higher interest rates. This is where careful financial planning comes into play, allowing you to optimize your savings while ensuring your family’s needs are met.
By being aware of these guidelines, you can navigate your financial journey more confidently. We’re here for you, supporting you every step of the way as you work towards your family’s financial goals. Together, we can ensure that your savings not only grow but also serve your family’s priorities effectively.
Key Highlights:
- Bright Advisers offers personalised financial planning for families, focusing on maximising savings through high-yield savings accounts (HYSAs).
- HYSAs provide higher interest rates than traditional savings accounts, making them ideal for families seeking to grow their savings.
- Withdrawals from HYSAs are typically limited to six per month, with potential fees for exceeding this limit, emphasising the need for careful financial planning.
- Most HYSAs are FDIC-insured, protecting deposits up to $250,000, which provides security for families’ savings.
- Interest earned on HYSAs is taxable income, requiring families to report it on their tax returns to avoid penalties.
- Families should strategically manage withdrawal frequency to maximise interest earnings and minimise fees.
- Bright Advisers emphasises the importance of understanding withdrawal rules and fees to enhance financial stability and resource optimization.
Introduction
Navigating the world of high-yield savings accounts (HYSAs) can feel overwhelming, especially for families striving to balance the growth of their savings with the need for accessibility. These accounts offer attractive interest rates, yet they come with specific withdrawal rules that can significantly impact your financial planning.
As families ask themselves, “Can you withdraw money from HYSA?” it’s essential to also consider:
- Potential fees
- Limits
- Strategies that can either support or challenge your financial goals
What key insights can empower families to make informed decisions about their savings while steering clear of common pitfalls? Together, we can navigate this journey, ensuring that your family’s financial future is bright and secure.
Bright Advisers: Personalized Financial Planning for High-Yield Savings Accounts
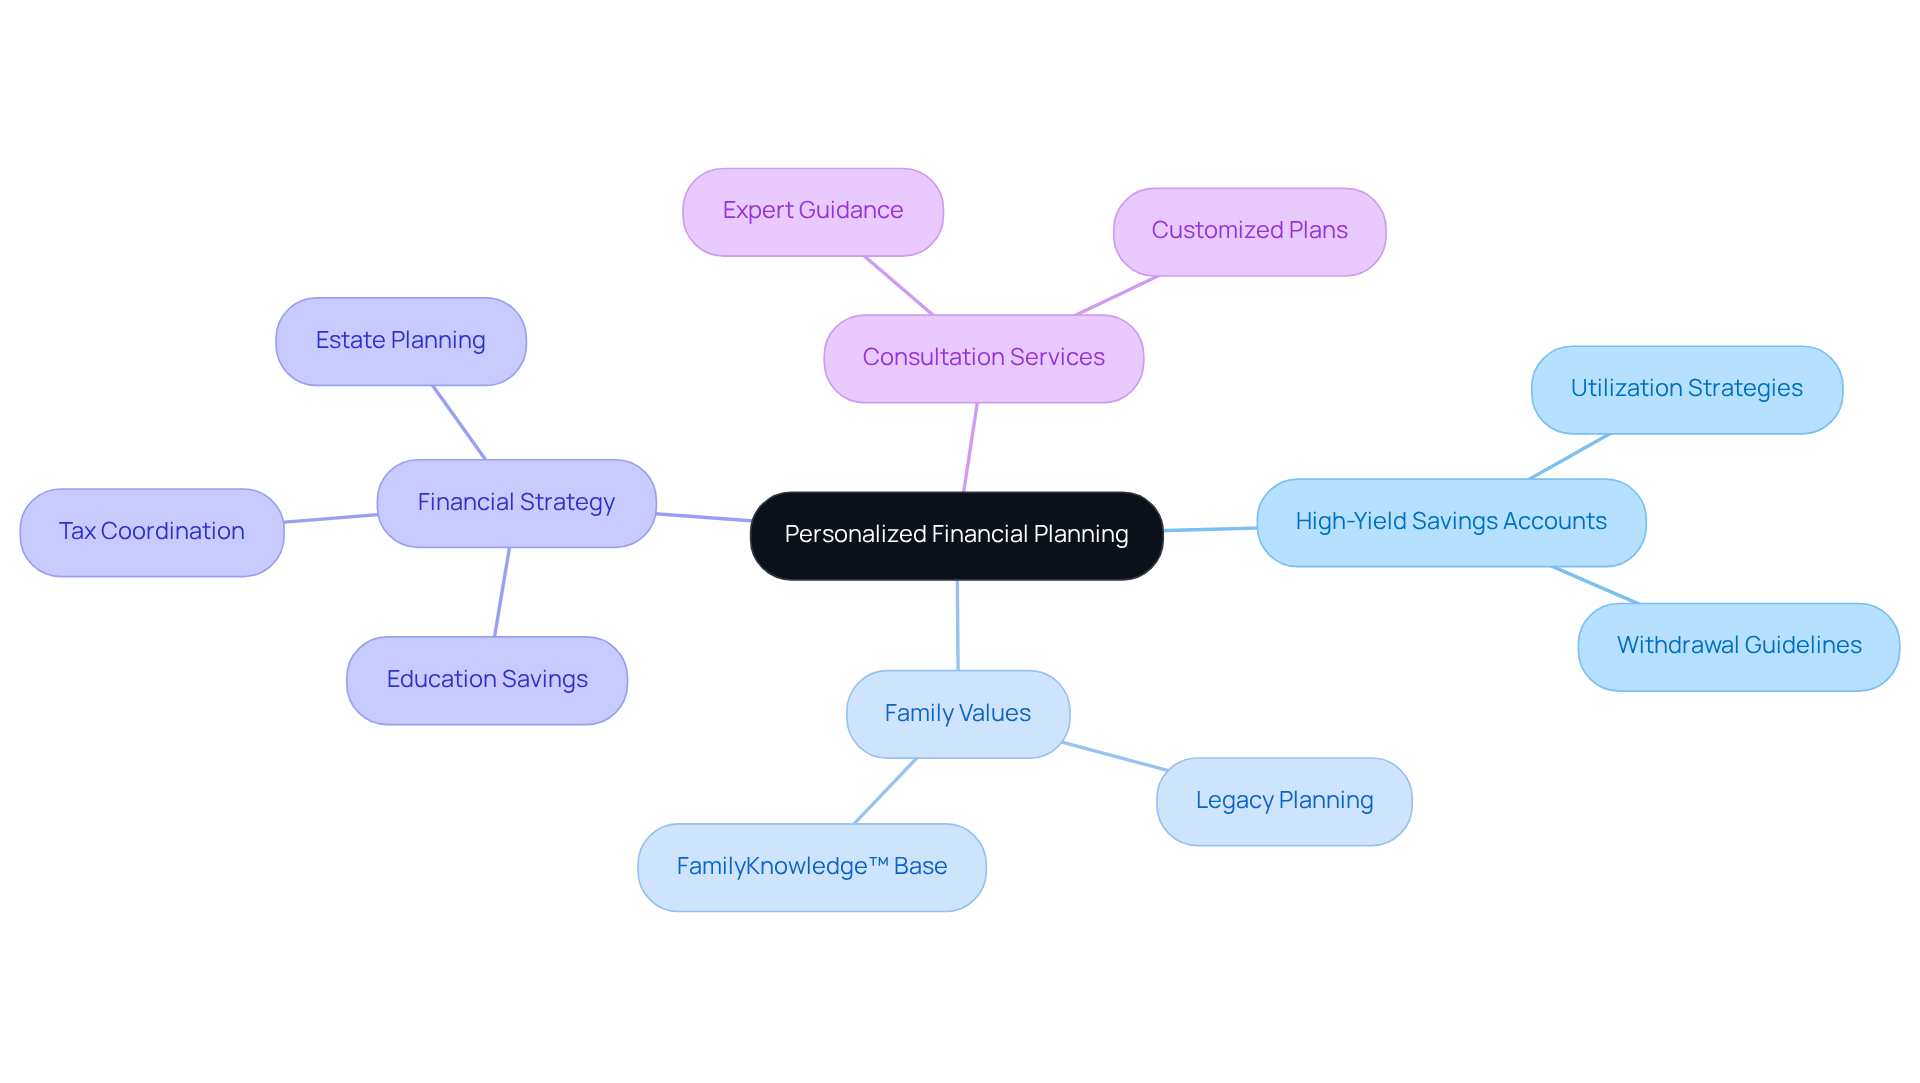
At Bright Advisers, we understand the unique challenges that families with young children face when it comes to financial planning. Imagine if you could effortlessly maximize your savings while preparing for future expenses related to education and your family’s well-being. Our customized monetary planning focuses on helping you effectively utilize high-yield accounts (HYSAs), addressing questions such as can you withdraw money from hysa while ensuring that your financial strategies align with your family’s values.
We know that navigating the complexities of HYSAs, including questions like can you withdraw money from hysa, can be daunting. That’s why our approach simplifies these challenges, allowing you to focus on what truly matters—your family’s future. With our extensive services, including estate planning and coordinated tax planning, we’re here to support you on your economic journey.
The FamilyKnowledge™ Base is a unique resource designed to help you organize, share, and protect your family’s values and traditions. This tool enhances your planning process, making it easier to create a strong financial strategy that adapts to the changing expenses of raising children.
Our financial consultants emphasize the importance of having a robust plan in place. With expert guidance on HYSAs and a comprehensive financial strategy, you can confidently work towards your long-term goals and understand how can you withdraw money from hysa. Together, we can navigate this journey and ensure a secure economic future for generations to come. Remember, we’re here for you every step of the way.
Understanding High-Yield Savings Accounts: Definition and Benefits
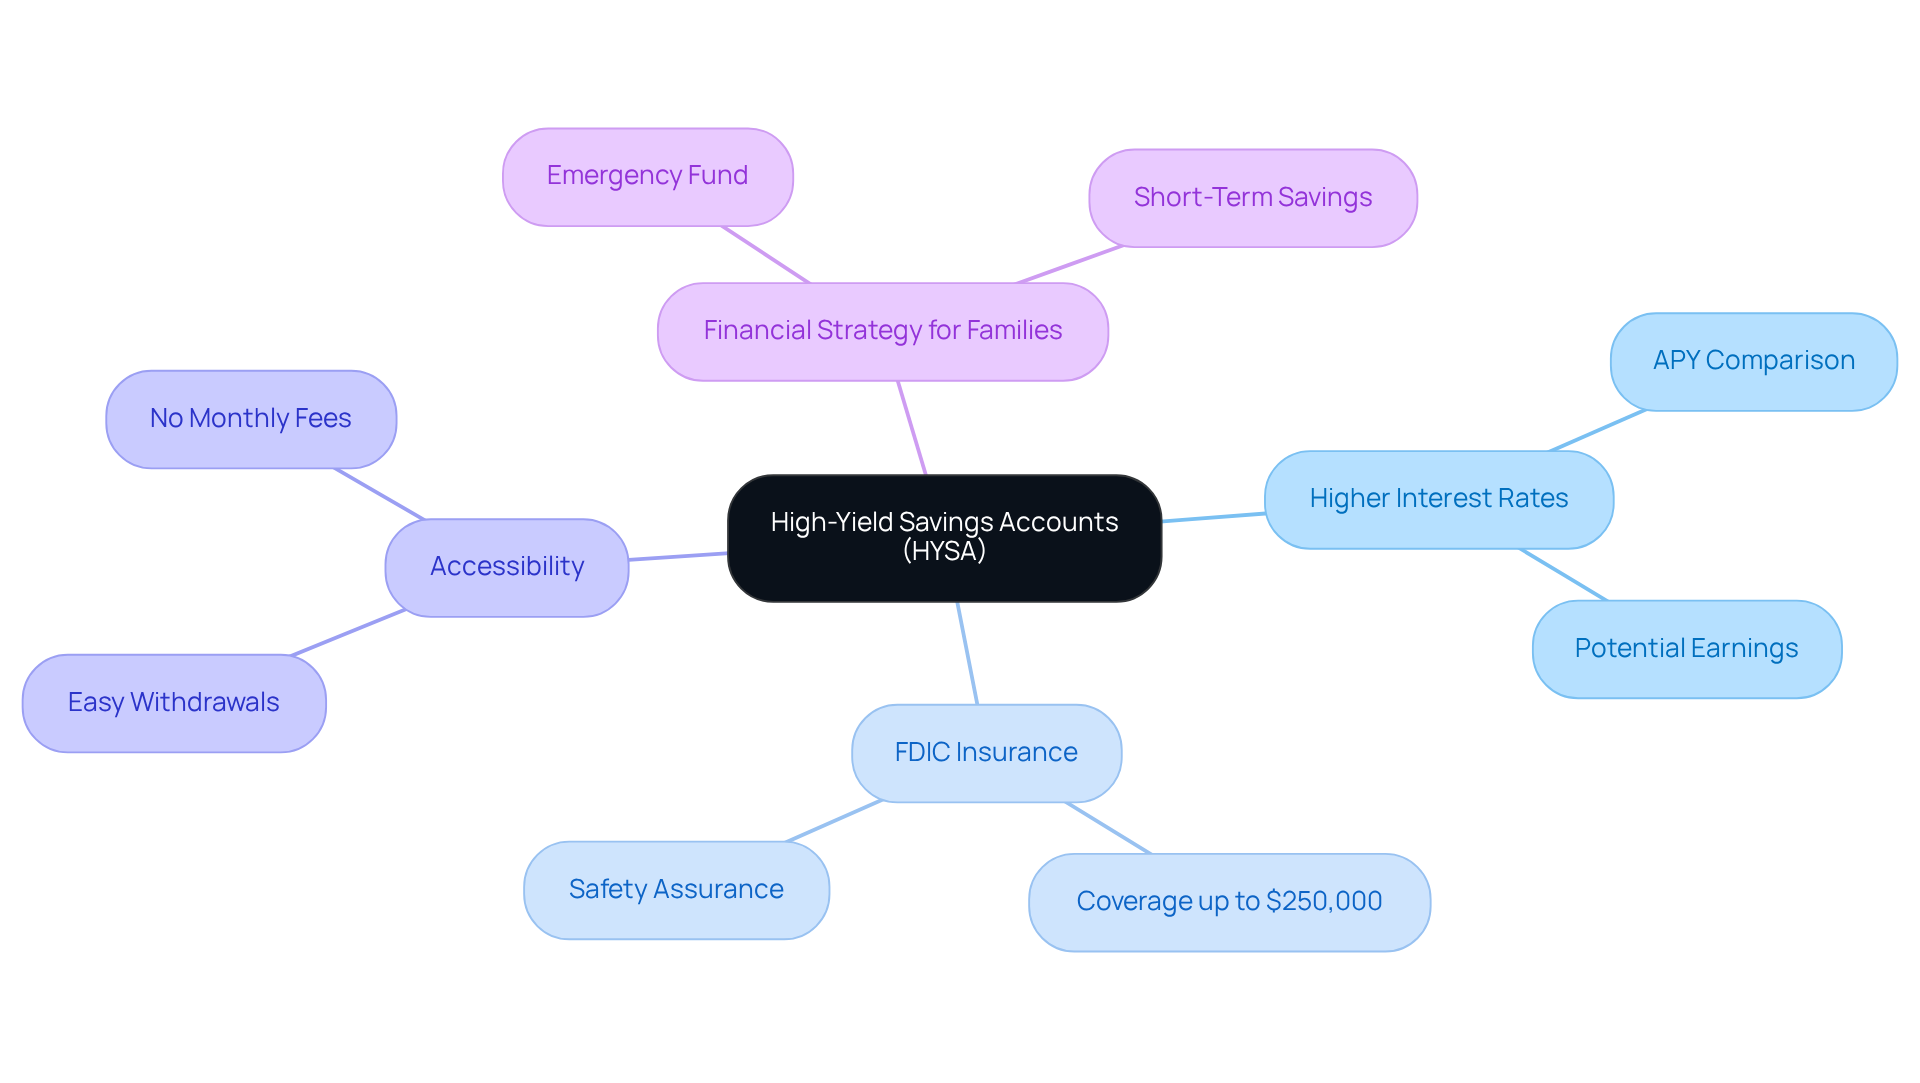
Imagine a financial product that not only secures your savings but also helps your family thrive. A high-yield savings account (HYSA) offers a significantly higher interest rate than traditional options, making it a wonderful choice for families looking to grow their funds. With HYSAs, you can enjoy greater returns on your deposits and have easy access to your money, which raises the question: can you withdraw money from HYSA while minimizing risk—all essential for households that want to increase their wealth while keeping their finances flexible?
At Bright Advisers, we understand the unique financial needs of young families. We believe that having the right resources is crucial for creating a personalized budgeting plan that works for you. Think about it: a HYSA can be a key part of your financial strategy, especially when you consider if you can withdraw money from HYSA, ensuring that your money is not only safe but also working hard for you.
One of the comforting aspects of HYSAs is that they are typically FDIC-insured, which means your deposits are protected up to $250,000. This assurance allows you to focus on what truly matters—your family’s future. By choosing a HYSA, you can enhance your wealth management options while ensuring your funds remain secure.
Together, we can navigate this journey towards financial stability and growth. Let’s make informed decisions that align with your family’s values and aspirations. We’re here for you, ready to support you in achieving your financial goals.
Withdrawal Rules for High-Yield Savings Accounts: What You Need to Know
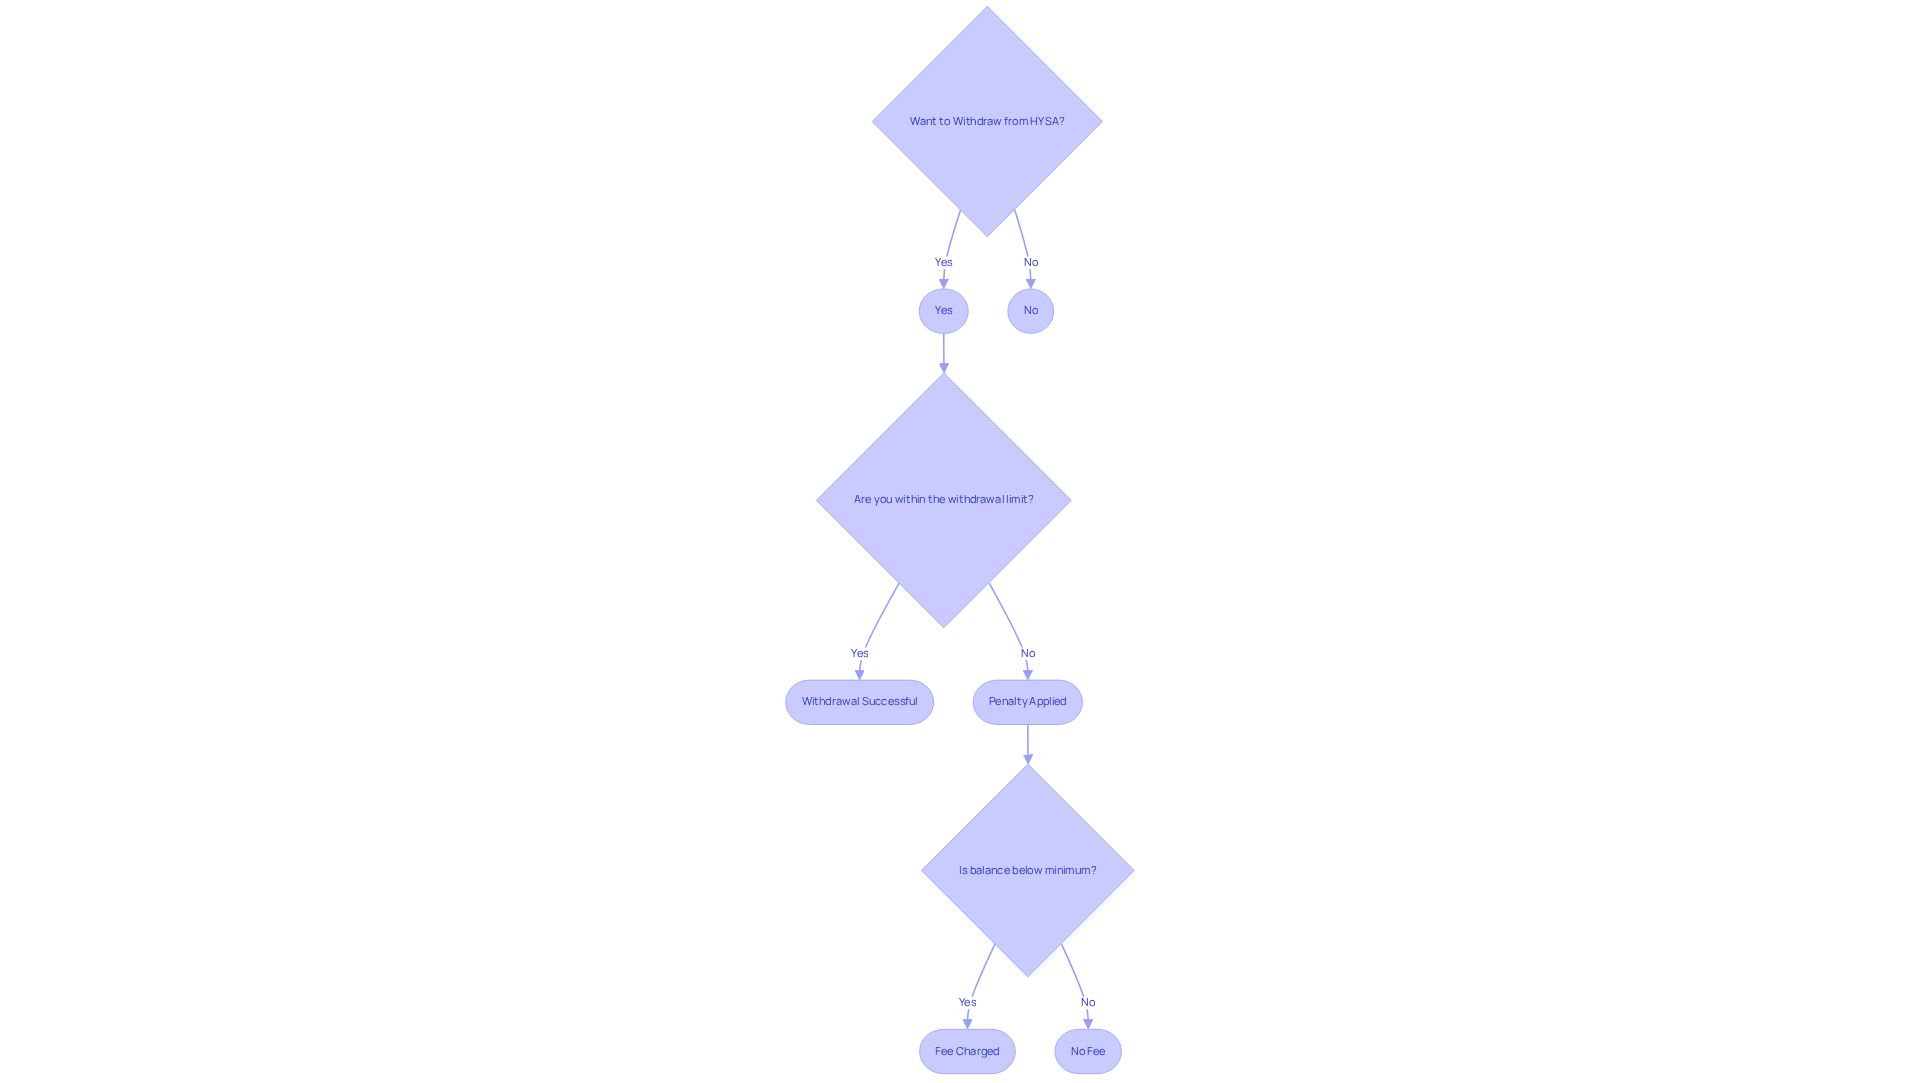
Understanding whether you can withdraw money from hysa and the withdrawal regulations for high-yield savings options (HYSAs) is crucial for effective financial management, especially for young families like Jay and Emma who are striving to ease financial burdens. Most banks limit withdrawals to six per month without incurring fees, a guideline rooted in historical practices. Going beyond this limit might result in additional charges, typically between $5 and $15 per transaction, or even a conversion of the account to a checking account, which often comes with different fees and lower interest rates.
To avoid these penalties, families should take the initiative to familiarize themselves with their bank’s specific policies. While direct deposits and incoming transfers are not counted against withdrawal limits, automated payments and electronic transfers are. Planning larger, less frequent withdrawals can help manage these limits effectively. For example, setting up alerts for withdrawal limits or using budgeting tools can aid in tracking expenses and withdrawals.
Many households find themselves navigating these restrictions, often feeling frustrated when unexpected expenses arise. By understanding the average number of withdrawals allowed and the potential fees associated with exceeding these limits, families can better organize their finances. If a household anticipates needing funds frequently, they might consider using a checking service for regular expenses while questioning, can you withdraw money from hysa for longer-term financial goals?
In closing, being mindful of withdrawal limits and planning accordingly can empower families to optimize their resources while minimizing costs linked to high-yield deposit options. We encourage you to set a monthly budget for withdrawals to avoid exceeding limits and incurring fees, ultimately contributing to a more secure financial future. Together, we can navigate this journey towards financial stability.

Fees and Penalties: What to Expect When Withdrawing from HYSAs
High-yield accounts (HYSAs) can be a wonderful opportunity for families seeking appealing interest rates and low fees. However, it’s crucial to remain vigilant about potential withdrawal penalties when asking, can you withdraw money from hysa? Imagine if you were to exceed the allowed number of withdrawals—can you withdraw money from hysa more than six times per month? This could lead to charges that might diminish your hard-earned funds.
Additionally, some banks impose fees if your balance falls below a certain limit, which can further impact your financial growth. Families who frequently wonder, ‘can you withdraw money from hysa,’ may find that these penalties significantly reduce the benefits of their high-interest accounts. It’s important to understand this dynamic fully.
Financial advisors often emphasize the importance of reviewing the fee structure of any chosen HYSA. By doing so, you can avoid unexpected costs that could hinder your financial journey. Together, we can navigate this landscape, ensuring that your funds continue to grow effectively and align with your family’s goals.
By comprehending these penalties, families can make informed choices that resonate with their financial objectives. Remember, we’re here for you, supporting you every step of the way on this journey to financial security.
Withdrawal Limits: Understanding the Restrictions on High-Yield Savings Accounts
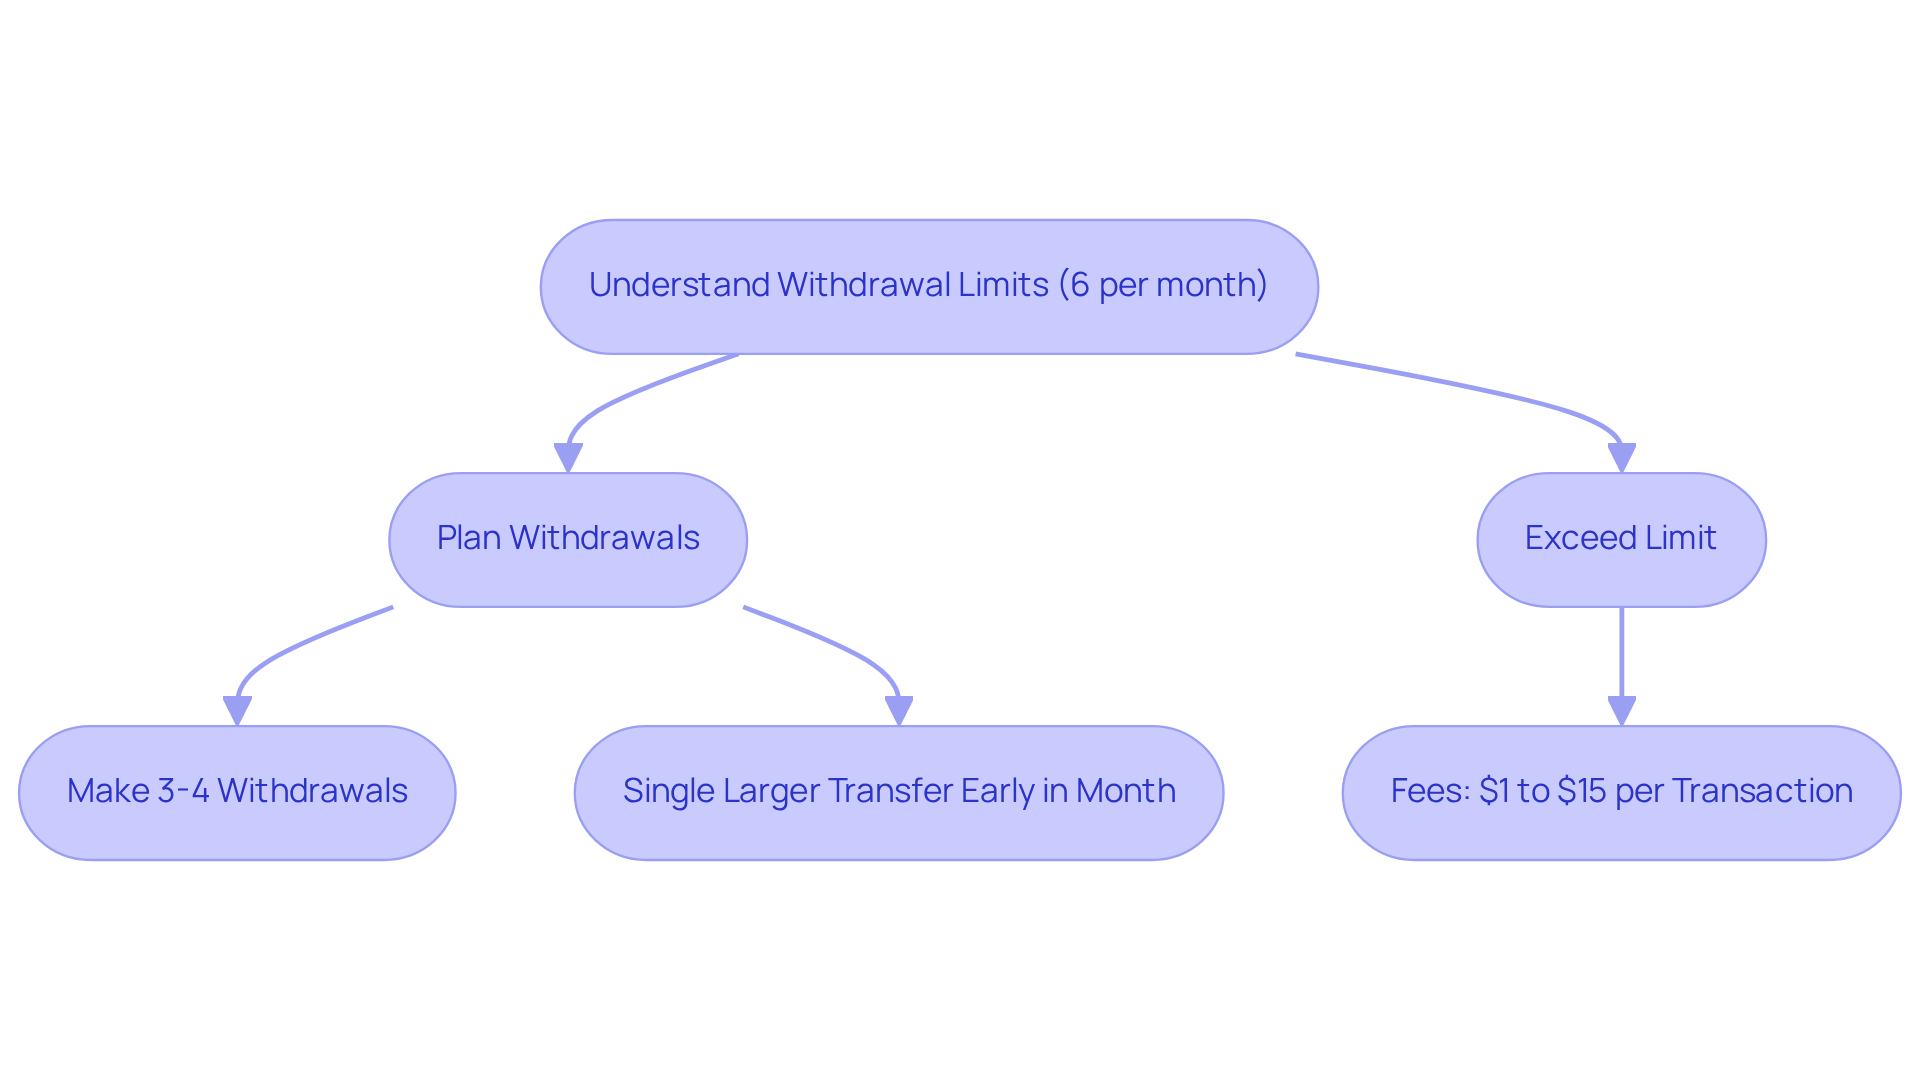
One common question about high-yield deposit accounts (HYSAs) is, can you withdraw money from HYSA, considering they typically set a monthly withdrawal limit of six transactions? This guideline, designed to promote saving over spending, can significantly influence a household’s cash flow management. Families often find themselves needing to adjust their financial strategies to navigate these restrictions, ensuring they can meet their cash flow needs without facing penalties, especially when they ask, can you withdraw money from HYSA? Exceeding the withdrawal limit may incur fees ranging from $1 to $15 per transaction, which can quickly accumulate and offset the advantages of higher interest rates.
On average, households may make about three to four withdrawals each month, providing some flexibility while remaining within the limits. Financial experts emphasize the importance of planning ahead; for example, if a household anticipates needing to know can you withdraw money from HYSA more than six times in a month, they might consider making a single larger transfer to their checking account at the beginning of the month. This proactive approach helps avoid unnecessary charges and maintains the integrity of their financial plan.
Moreover, the effect of these withdrawal limits on household cash flow can be significant. Families must balance their immediate financial needs with the long-term benefits of saving in a HYSA, which can offer interest rates much higher than traditional savings accounts—often between 4% and 5% APY. By understanding and navigating these restrictions, households can effectively manage their finances while also considering if they can withdraw money from HYSA to leverage the wealth-building potential that HYSAs offer. As financial specialists often say, ‘High Yield Savings Accounts can play a crucial role in building generational wealth,’ making them an attractive option for young parents seeking to secure their family’s financial future.
At Bright Advisers, we are dedicated to empowering young families with personalized wealth management solutions and educational resources. Our tailored financial planning sessions and workshops are designed to help you navigate these financial planning challenges with confidence. Together, we can navigate this journey and build a brighter future for your family.
Impact of Withdrawal Frequency on Interest Earnings in HYSAs
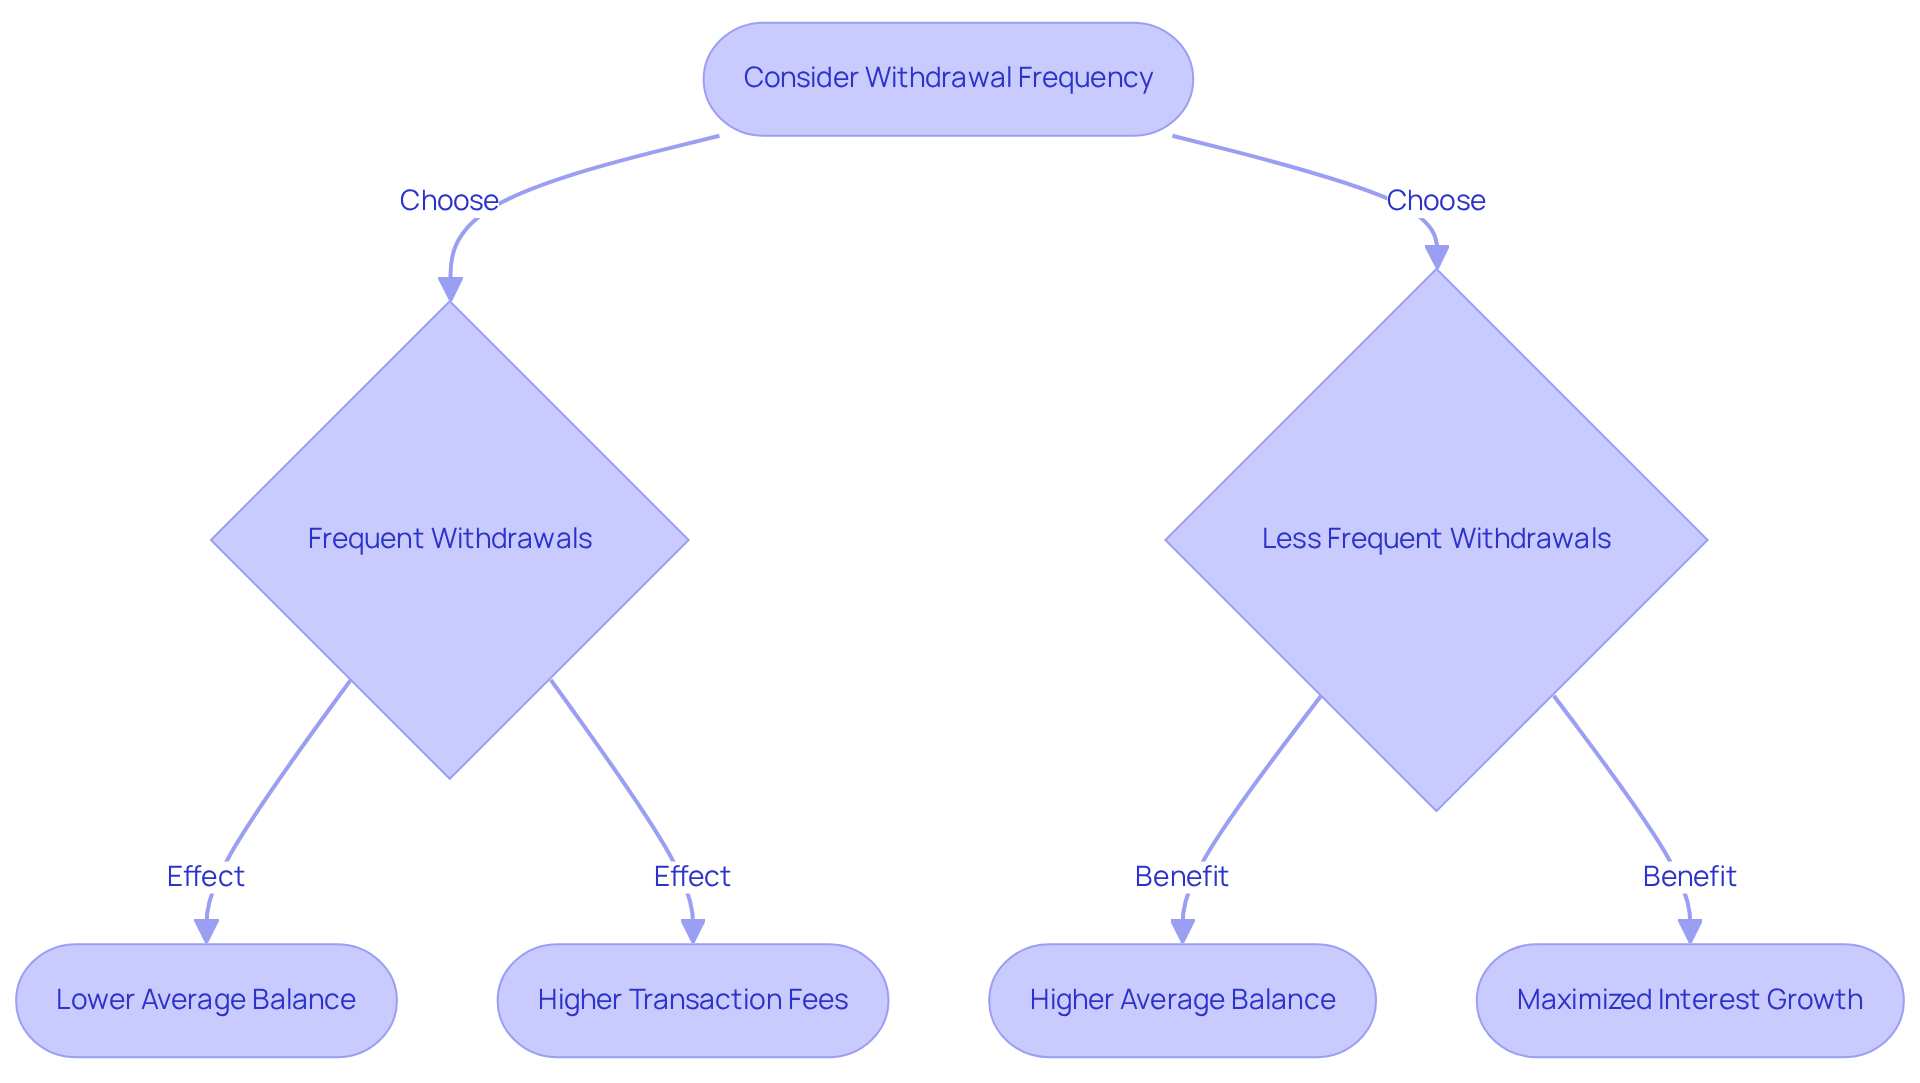
To understand the interest earned, it is crucial to know how often you can withdraw money from HYSA. When considering your account balance, you may wonder, can you withdraw money from HYSA, as each withdrawal reduces your balance and can lower the interest accrued? To maximize your interest earnings, it’s helpful to know, can you withdraw money from HYSA while adopting strategic withdrawal habits? Imagine if you could consolidate your withdrawals into fewer transactions; this can help maintain a higher average balance, which is essential for optimizing interest growth. Financial analysts emphasize that understanding the impact of withdrawal frequency is vital for effective savings management.
Many families have successfully maximized their interest earnings by planning for larger, less frequent withdrawals instead of several smaller ones. This approach not only helps sustain a strong balance but also reduces the likelihood of facing additional transaction fees, which can range from $5 to $15 for each withdrawal exceeding the bank’s limit. It’s important to recognize that while high-interest accounts typically restrict withdrawals to six each month, certain transactions—like ATM withdrawals and in-person bank teller activities—are usually excluded from these limitations, leading to the question: can you withdraw money from HYSA? This flexibility allows you to access funds without significantly affecting your interest earnings.
By being mindful of your withdrawal strategies, you can effectively enhance your savings growth in HYSAs, ensuring you make the most of your resources. Additionally, utilizing creative wealth management approaches, like those offered by Bright Advisers, can provide further assistance in your planning. Together, we can navigate this journey by utilizing hyper-personalized investment portfolios and advanced technology, allowing families to optimize their resource allocation, reduce anxiety about financial decisions, and secure their futures more effectively.
Transferring Funds: How to Move Money from Your High-Yield Savings Account
While you might ask, can you withdraw money from HYSA, transferring funds from a high-yield savings option (HYSA) is actually a straightforward process that most banks facilitate through user-friendly online platforms or mobile banking applications. Imagine having the ability to connect your HYSA to a checking service, which prompts the question, can you withdraw money from HYSA, allowing for seamless movement of funds when you need it most. While these transfers are generally efficient, it’s essential to plan ahead, as they may take a few business days to process. Understanding how your accounts work can significantly enhance your financial management.
Consider automating your transfers. This simple step can help you sustain a regular financial habit, ensuring that your household is prepared for both anticipated costs and unforeseen emergencies. At Bright Advisers, we understand the importance of keeping fund fees low, which can truly improve your financial potential. By being proactive and knowledgeable, you can effectively manage your finances and refine your strategies, ultimately enhancing your family’s economic security and freedom through personalized planning and tax optimization.
Together, we can navigate this journey towards financial well-being. We’re here for you, every step of the way.

Safety and Security: Are Your Funds Safe in a High-Yield Savings Account?
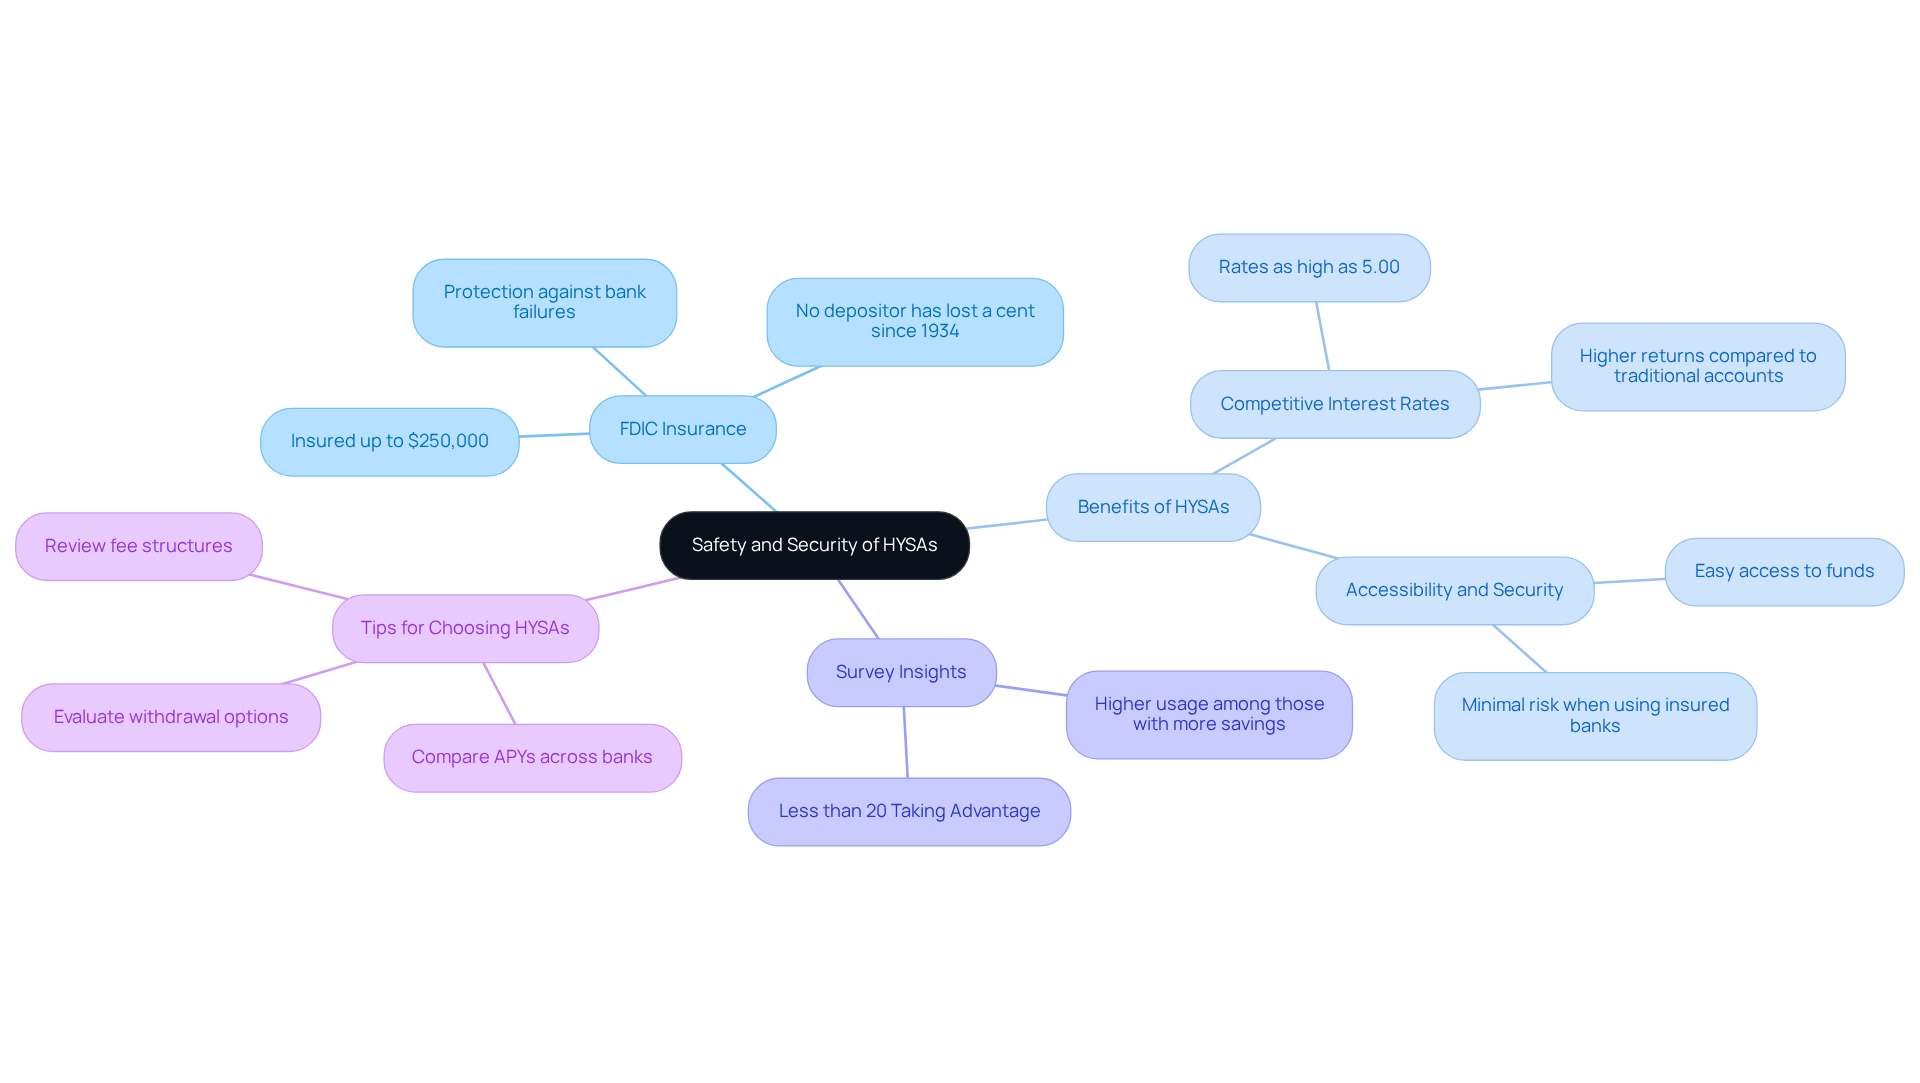
High-yield deposit accounts (HYSAs) are often viewed as a safe haven, particularly when held at FDIC-insured banks. The Federal Deposit Insurance Corporation (FDIC) safeguards deposits up to $250,000 per depositor, per institution, offering peace of mind for families who want to ensure their savings are protected against potential bank failures. This insurance is vital for households looking to grow their funds without the uncertainties associated with the stock market. Imagine knowing that since its inception in 1934, the FDIC has maintained a flawless record, with no depositor losing a cent of their insured funds. This reliability makes HYSAs an attractive choice for families aiming to secure their financial future.
However, it’s surprising that fewer than 20% of survey respondents are taking advantage of higher-interest financial options like HYSAs. Many families are missing out on the benefits these products offer, which not only feature competitive interest rates but also provide a sense of security. By choosing a high-yield account at an FDIC-insured institution, families can ensure their funds are both accessible and protected, which raises the question: can you withdraw money from hysa, making it a smart choice for short-term financial goals and emergency savings?
Yet, it’s essential for families to carefully evaluate different HYSAs to find the best annual percentage yields (APYs) and to be aware of any potential fees that could impact their finances. Understanding how even small fees can affect overall returns is key to maximizing the advantages of HYSAs. Here are some helpful tips for young parents when selecting a HYSA:
- Compare APYs across various banks to identify the highest rates.
- Review the fee structures to keep costs low.
- Consider whether you can withdraw money from hysa easily in case of emergencies.
By following these guidelines, families can make informed decisions that enhance their financial security. Remember, we’re here for you, and together, we can navigate this journey towards a more secure economic future.
Tax Implications: What to Know About Withdrawing from High-Yield Savings Accounts
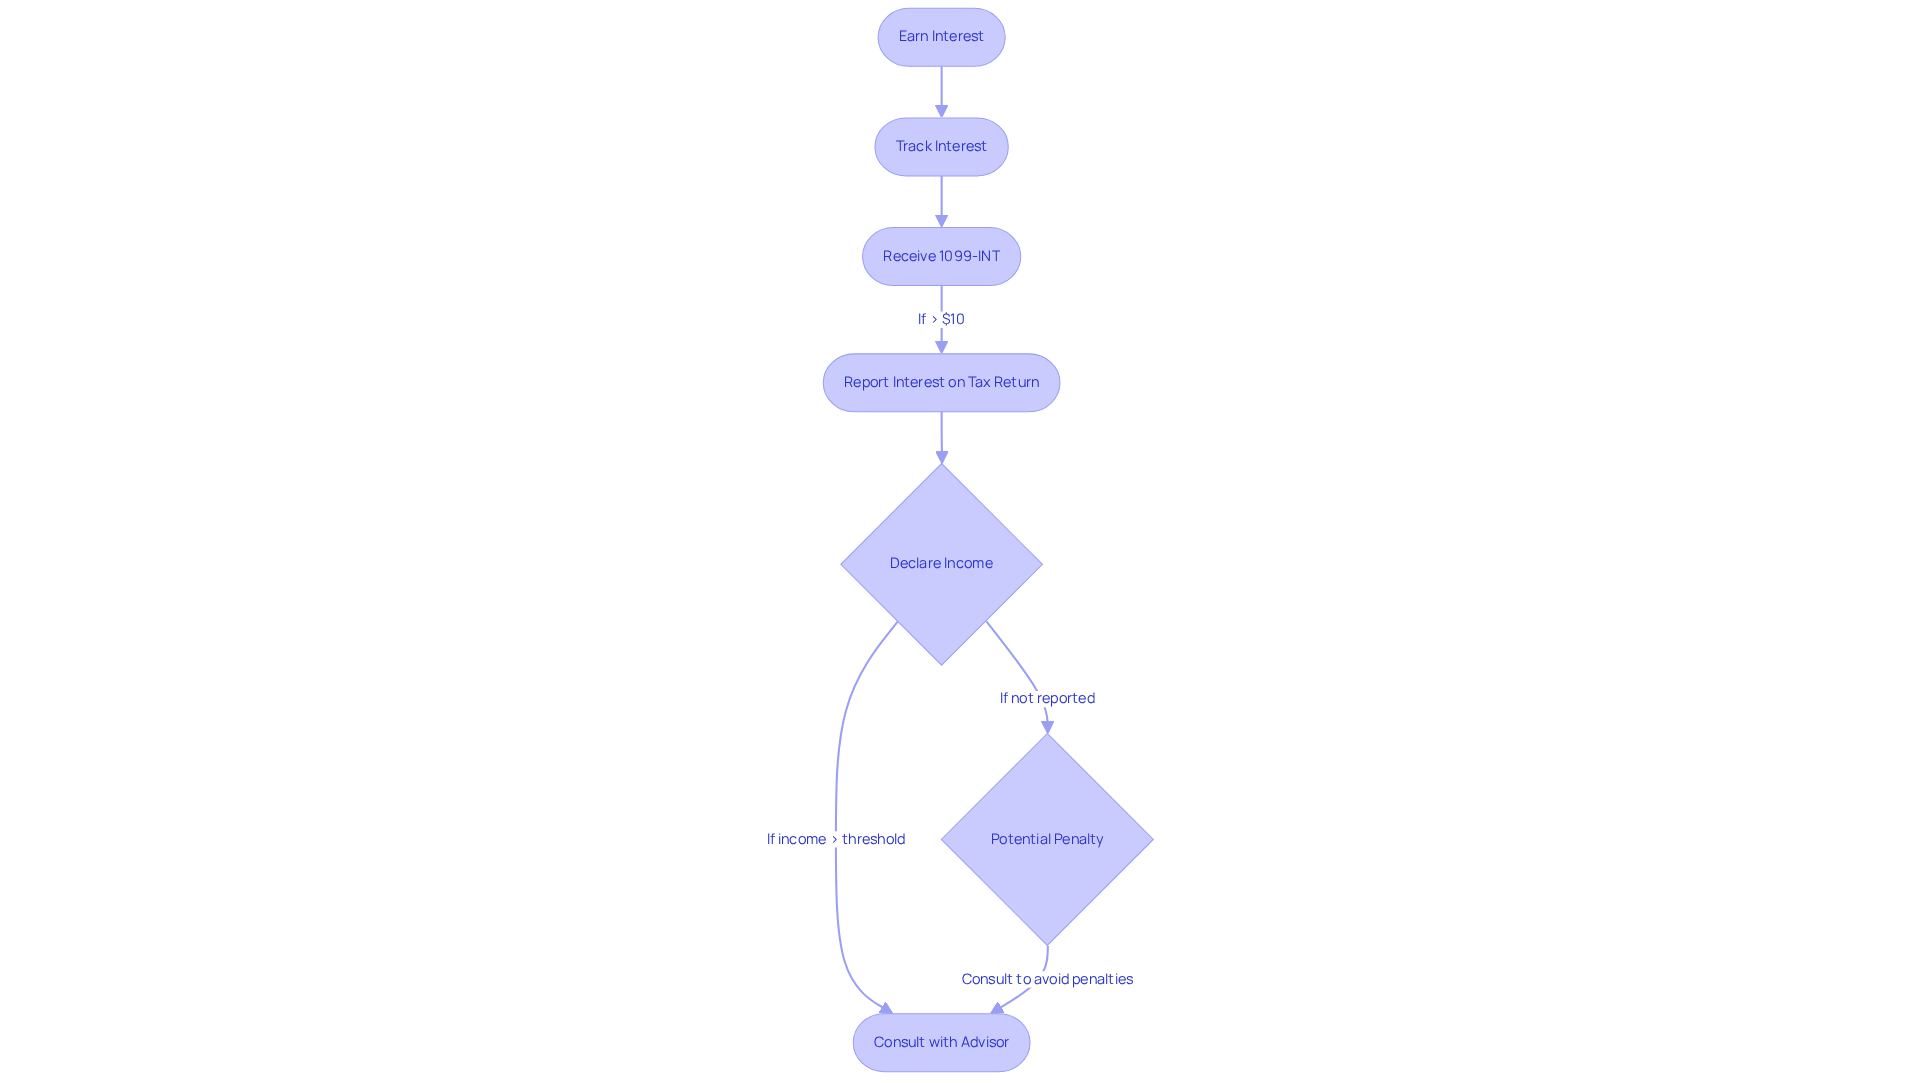
Withdrawals from high-yield savings accounts (HYSA) are typically not subject to taxation; however, the interest earned on these accounts is classified as taxable income. It’s essential for families to report any interest accrued on their tax returns, as this can significantly impact their financial planning. Chad Cummings, a certified public accountant, emphasizes, “Every penny of interest must be reported as taxable income.” To ensure compliance and avoid unexpected tax liabilities, households should diligently track their interest earnings throughout the year.
Imagine if a household earns $125 in interest from their HYSA. They are required to report this amount on their federal tax return. Financial institutions typically issue a Form 1099-INT if the interest earned exceeds $10, but even if this form isn’t received, the obligation to report remains. As Katelyn Washington, a former tax writer, wisely notes, “Knowledge is the key to success,” highlighting the importance of understanding these tax implications.
It’s important to understand that current tax reporting requirements dictate that all interest income, regardless of the amount, must be included in total taxable income for the year. This includes interest from various accounts, such as traditional savings accounts and certificates of deposit. Families should be proactive in gathering their 1099-INT forms and completing Form 1040 to ensure accurate reporting. By collaborating with Bright Advisers, individuals can create tailored financial strategies that not only tackle tax responsibilities but also help them reach their long-term financial objectives.
If gross income is below the IRS filing threshold, it may lead to zero taxable income, which can be significant for households managing their finances. To navigate the intricacies of tax reporting concerning their high-yield deposit options effectively, households are encouraged to consult with Bright Advisers for tailored tax planning strategies. Remember, failing to declare interest from a deposit can result in monetary penalties from the IRS. Together, we can navigate this journey and ensure your family’s financial future is secure.
Key Takeaways: Essential Facts About Withdrawing from High-Yield Savings Accounts
When managing withdrawals from high-yield savings accounts, families should consider several essential factors:
-
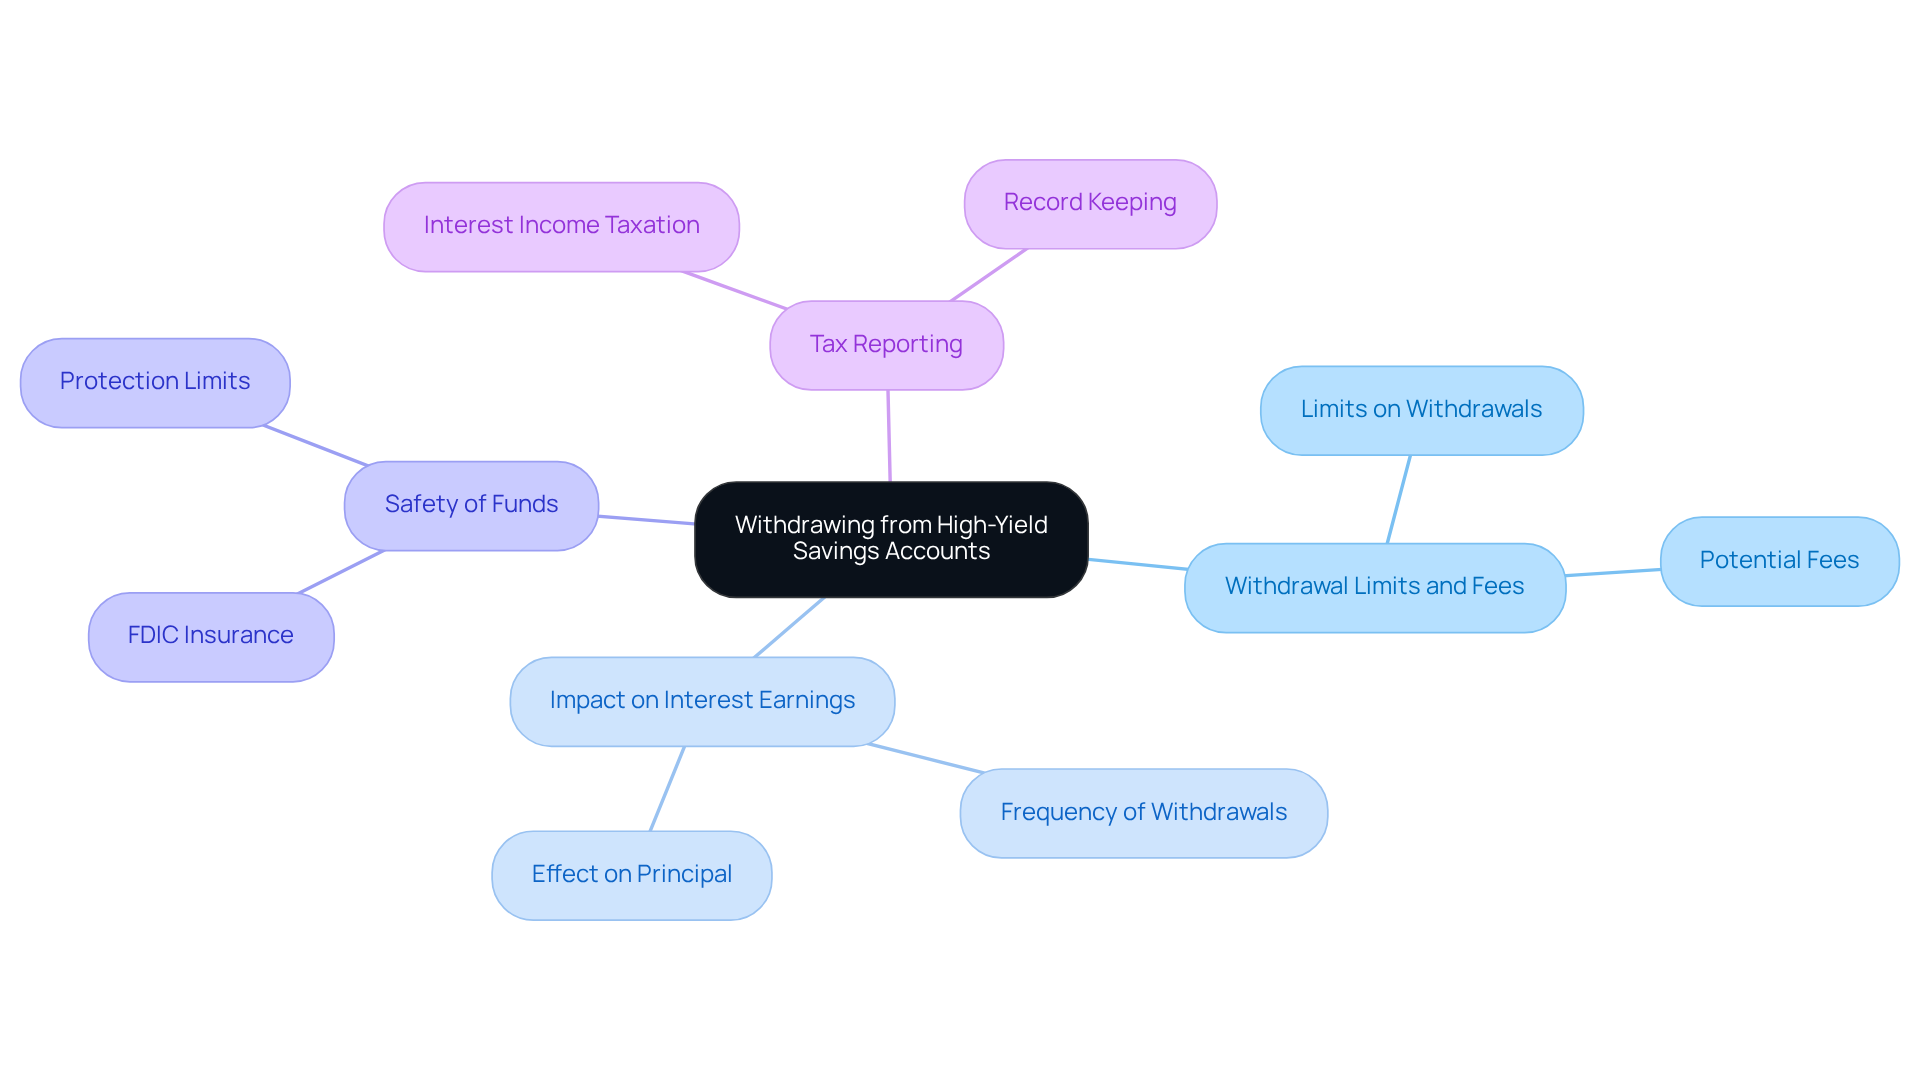
Withdrawal Limits and Fees: Many high-yield deposit products impose limits on the number of withdrawals or transfers permitted per statement cycle, usually up to six. Understanding these limits is crucial to avoid potential fees, especially if you are wondering can you withdraw money from hysa without diminishing interest earnings. At Bright Advisers, we are dedicated to reducing fund fees, ensuring families can optimize their resources without unnecessary expenses.
-
Impact on Interest Earnings: Imagine if frequent withdrawals could significantly affect the interest accrued. Families should be strategic about their withdrawal frequency to consider if they can withdraw money from hysa to maximize their returns. Even a small reduction in the principal can lead to lower interest earnings over time. For context, the average interest yield for a deposit is 0.60% as of June 3, 2025, while high-yield options can provide significantly greater rates.
-
Safety of Funds: It’s important to understand that ensuring the high-yield deposit account is held at an FDIC-insured institution protects deposits up to $250,000 per depositor. This safety net is essential for households seeking to protect their savings from possible bank failures.
-
Tax Reporting: Keep a detailed record of interest earned, as this income is subject to taxation. Being proactive about tax reporting can assist households in avoiding surprises during tax season.
Financial consultants stress that understanding these components can improve decision-making about whether you can withdraw money from hysa, ultimately strengthening a household’s economic stability.
By remaining knowledgeable about these essential elements, households can efficiently handle their high-return accounts, ensuring they enhance their strategies while prioritizing their long-term objectives. Together, we can navigate this journey. Additionally, Bright Advisers offers educational resources that empower families to make informed decisions about their savings, aligning with our commitment to financial literacy and tailored wealth management solutions.
Conclusion
Understanding the intricacies of withdrawing from high-yield savings accounts (HYSAs) is essential for families like yours who are striving to optimize their financial strategies. This article has explored various aspects surrounding HYSAs, including withdrawal limits, penalties, and the impact of withdrawal frequency on interest earnings. By grasping these concepts, you can make informed decisions that align with your long-term financial goals while maximizing the benefits of your savings.
Key insights highlighted include:
- The importance of adhering to monthly withdrawal limits to avoid fees
- The safety of funds in FDIC-insured accounts
- The tax implications of interest earned
Additionally, strategic planning around withdrawals can significantly enhance interest earnings, allowing your family to maintain a higher average balance. Understanding these factors empowers households to navigate their financial journeys with confidence and clarity.
Ultimately, high-yield savings accounts present a valuable opportunity for families to grow their wealth while ensuring liquidity and security. By leveraging personalized financial planning services, such as those offered by Bright Advisers, you can effectively manage your HYSAs, avoid pitfalls, and secure your financial future. Embracing these insights will not only enhance your financial literacy but also pave the way for informed decision-making that supports a prosperous and stable economic future. Together, we can navigate this journey, ensuring your family thrives.
Frequently Asked Questions
What is a High-Yield Savings Account (HYSA)?
A High-Yield Savings Account (HYSA) is a financial product that offers a significantly higher interest rate than traditional savings accounts, making it an ideal choice for families looking to grow their savings while having easy access to their funds.
What are the benefits of using a HYSA?
The benefits of a HYSA include greater returns on deposits, easy access to money, and FDIC insurance that protects deposits up to $250,000, ensuring that your savings are secure while working to increase wealth.
Can you withdraw money from a HYSA?
Yes, you can withdraw money from a HYSA; however, most banks limit withdrawals to six per month without incurring fees. Exceeding this limit may result in additional charges or conversion of the account to a checking account.
What happens if I exceed the withdrawal limit on my HYSA?
Exceeding the withdrawal limit on your HYSA may incur additional fees, typically between $5 and $15 per transaction, and could potentially lead to the account being converted to a checking account, which may have different fees and lower interest rates.
How can I manage my withdrawals from a HYSA effectively?
To manage withdrawals effectively, families should familiarize themselves with their bank’s specific policies, plan for larger, less frequent withdrawals, and consider setting up alerts for withdrawal limits or using budgeting tools to track expenses.
What resources does Bright Advisers provide for financial planning?
Bright Advisers offers personalized financial planning services, including guidance on HYSAs, estate planning, coordinated tax planning, and access to the FamilyKnowledge™ Base, a resource for organizing and protecting family values and traditions.
Why is it important to have a robust financial plan?
Having a robust financial plan is important as it helps families navigate financial complexities, prepares them for future expenses, and aligns their financial strategies with their values, ultimately contributing to long-term financial stability and growth.
List of Sources
- Bright Advisers: Personalized Financial Planning for High-Yield Savings Accounts
- 20 + Personal Finance Statistics for 2025 | Fortunly (https://fortunly.com/statistics/personal-finance-statistics)
- Financial Planning for Parents with Young Children (https://ffin.com/articles-financial-education/financial-planning-for-parents-with-young-children)
- 27 eye-opening financial planning statistics (https://contentsnare.com/financial-planning-statistics)
- 2024 Schwab Modern Wealth Survey Shows Increasing Financial Confidence From Generation to Generation and Younger Americans Investing at an Earlier Age (https://pressroom.aboutschwab.com/press-releases/press-release/2024/2024-Schwab-Modern-Wealth-Survey-Shows-Increasing-Financial-Confidence-From-Generation-to-Generation-and-Younger-Americans-Investing-at-an-Earlier-Age/default.aspx)
- Two-Thirds of Americans Say Their Financial Planning Needs Improvement (https://news.northwesternmutual.com/2023-07-24-Two-Thirds-of-Americans-Say-Their-Financial-Planning-Needs-Improvement)
- Understanding High-Yield Savings Accounts: Definition and Benefits
- Best High-Yield Savings Accounts of June 2025: Up to 4.66% – NerdWallet (https://nerdwallet.com/best/banking/high-yield-online-savings-accounts)
- 82% of Americans don’t use this kind of savings account that earns over 5% a year — here’s how much money you may be missing out on (https://cnbc.com/select/americans-not-using-high-yield-savings-accounts)
- Pros and cons of a high-yield savings account (https://cnbc.com/select/pros-and-cons-high-yield-savings-accounts)
- Survey: Two-thirds of savers still earn a savings account APY of less than 4% – Bankrate (https://bankrate.com/banking/savers-still-earning-less-than-4-percent)
- Pros and Cons of High-Yield Savings Accounts | The Motley Fool (https://fool.com/money/banks/guides-tools/pros-cons-of-high-yield-savings)
- Withdrawal Rules for High-Yield Savings Accounts: What You Need to Know
- Savings Account Withdrawal Limits (https://sofi.com/learn/content/savings-account-withdrawal-limit)
- How Do High Yield Savings Accounts Work? (https://sofi.com/learn/content/how-do-high-yield-savings-accounts-work)
- What Is a High-Yield Savings Account? (https://upgrade.com/credit-health/insights/what-is-a-high-yield-savings-account)
- 11 Ways to Use a High Yield Savings Account – Experian (https://experian.com/blogs/ask-experian/ways-to-use-high-yield-savings-account)
- Regulation D and savings account withdrawal limits – here’s what changed (https://finance.yahoo.com/news/regulation-d-savings-account-withdrawal-195856860.html)
- Fees and Penalties: What to Expect When Withdrawing from HYSAs
- Top 50 Financial Planning Quotes [2025] (https://digitaldefynd.com/IQ/financial-planning-quotes)
- 150 Quotes on Saving, Investing, and Financial Wellness (https://deliberatedirections.com/quotes-financial-wellness)
- 35 Quotes for Financial Advisors on a Tough Day | Don Connelly & Associates (https://donconnelly.com/35-quotes-for-financial-advisors)
- 77 Financial Advisor Quotes to Send to Clients (https://billgoodmarketing.com/resources/financial-advisor-quotes)
- 14 Quotes From Our Favorite Money Saving Experts (https://chime.com/blog/quotes-from-money-saving-experts)
- Withdrawal Limits: Understanding the Restrictions on High-Yield Savings Accounts
- Savings Account Withdrawal Limits (https://sofi.com/learn/content/savings-account-withdrawal-limit)
- What Is a High-Yield Savings Account? (https://upgrade.com/credit-health/insights/what-is-a-high-yield-savings-account)
- High Yield Savings Accounts (HYSA) and High Yield Cash Accounts for Physicians: Best Uses and Options (https://physiciansidegigs.com/high-yield-savings-accounts-hysa)
- What is a High Yield Savings Account? – Greatest Gift (https://greatestgiftapp.com/dictionary/high-yield-savings-account)
- Impact of Withdrawal Frequency on Interest Earnings in HYSAs
- Pros and cons of a high-yield savings account (https://cnbc.com/select/pros-and-cons-high-yield-savings-accounts)
- Regulation D and savings account withdrawal limits – here’s what changed (https://finance.yahoo.com/news/regulation-d-savings-account-withdrawal-195856860.html)
- The Basics of High Yield Savings Accounts (https://americanexpress.com/en-us/banking/online-savings/articles/all-about-high-yield-savings)
- Transferring Funds: How to Move Money from Your High-Yield Savings Account
- 14 Quotes From Our Favorite Money Saving Experts (https://chime.com/blog/quotes-from-money-saving-experts)
- 100 Inspirational Quotes About Finance and Money [2025] (https://digitaldefynd.com/IQ/inspirational-quotes-about-finance-and-money)
- Money Talk: 10 Great Quotes About Personal Finance (https://3riversfcu.org/blog/post/money-talk-10-great-quotes-about-personal-finance)
- You Need to Hear This Warren Buffett Quote About Saving Money (https://fool.com/money/banks/articles/you-need-to-hear-this-warren-buffett-quote-about-saving-money)
- My 50 Favorite Quotes About Banking (https://seattlepi.com/business/fool/article/My-50-Favorite-Quotes-About-Banking-6061330.php)
- Safety and Security: Are Your Funds Safe in a High-Yield Savings Account?
- Are High-Yield Savings Accounts Safe? (https://experian.com/blogs/ask-experian/are-high-yield-savings-accounts-safe)
- Are High-Yield Savings Accounts Safe? (https://smartasset.com/checking-account/are-high-yield-savings-accounts-safe)
- What Is FDIC Insurance and What Are the Coverage Limits? – NerdWallet (https://nerdwallet.com/article/banking/fdic-insurance)
- HYSA: Safe Pick in Volatile Markets | Openbank by Santander (https://openbank.us/resources/high-yield-savings/are-high-yield-savings-accounts-safe)
- Deposit Insurance At A Glance | FDIC.gov (https://fdic.gov/resources/deposit-insurance/brochures/deposits-at-a-glance)
- Tax Implications: What to Know About Withdrawing from High-Yield Savings Accounts
- Is High-Yield Savings Account Interest Taxable? (https://kiplinger.com/taxes/how-savings-account-interest-is-taxed)
- Is Savings Account Interest Taxable Income? (https://usnews.com/banking/articles/do-you-pay-taxes-on-savings-account-interest)
- Are High-Yield Savings Accounts Taxable? (https://experian.com/blogs/ask-experian/are-high-yield-savings-accounts-taxed)
- Key Takeaways: Essential Facts About Withdrawing from High-Yield Savings Accounts
- 82% of Americans don’t use this kind of savings account that earns over 5% a year — here’s how much money you may be missing out on (https://cnbc.com/select/americans-not-using-high-yield-savings-accounts)
- Survey: Two-thirds of savers still earn a savings account APY of less than 4% – Bankrate (https://bankrate.com/banking/savers-still-earning-less-than-4-percent)
- Best High-Yield Savings Accounts (https://wsj.com/buyside/personal-finance/banking/best-high-yield-savings-account?gaa_at=eafs&gaa_n=ASWzDAisNc40G_GXh03SFrGjebo1CsgrUihYVLWwcLOCkLPQOql8u_tpb7lb&gaa_ts=6851e793&gaa_sig=CnU6gp3hzAwshGymh0JCdNgIjMF-BWL5RbthjKbWbzZBn5i_lxCknKZqzRSz4IxBpP31PjSf-Yy8lN6GRLvzyQ%3D%3D)
- Key Savings Statistics And Trends In 2023 – DollarGeek (https://dollargeek.com/statistics/key-savings-statistics-and-trends-in-2023)
- Pros and Cons of High-Yield Savings Accounts – Experian (https://experian.com/blogs/ask-experian/pros-cons-high-yield-savings-account)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Investment & Risk Management for high-income W-2 families at Bright Advisers.
Keep reading