

Overview
The 401k 55 year old rule offers a compassionate lifeline for individuals aged 55 or older, allowing them to withdraw funds from their 401(k) or 403(b) plans without facing a 10% early withdrawal penalty, provided they have left their job.
Imagine navigating this critical phase of life with more financial flexibility. This article gently explores the eligibility criteria, potential tax implications, and the financial freedom this rule can provide during significant life transitions.
However, it’s important to understand the risks of depleting retirement savings too early. We’re here for you as you consider your options, ensuring you can make informed decisions that align with your family’s needs.
Key Highlights:
- Bright Advisers provides personalized financial planning for families, focusing on the 401k 55 year old rule.
- The 401k 55 year old rule allows individuals aged 55 or older to withdraw from their 401(k) or 403(b) without a 10% penalty if they leave their job.
- Financial literacy is essential, as many consumers face economic challenges despite feeling confident in saving.
- Eligibility for the rule requires individuals to be at least 55 years old and to withdraw from their most recent employer’s plan.
- Withdrawals under the rule are subject to ordinary income tax, which can increase overall tax liability.
- The rule provides financial flexibility during life transitions, allowing for urgent needs like education or healthcare.
- Pitfalls include the risk of depleting retirement savings too early and the potential for increased tax burdens.
- Alternatives to the rule include hardship withdrawals and 401(k) loans, which can also provide access to funds under certain conditions.
- Consulting financial planners can help families navigate the complexities of the rule and develop comprehensive strategies for financial security.
- Understanding the long-term implications of early withdrawals is crucial for maintaining future financial stability.
Introduction
In a world where financial stability is paramount, the 401k Rule of 55 shines as a beacon of hope for families navigating the complexities of early retirement withdrawals. Imagine if you could access your retirement funds without incurring hefty penalties—this IRS provision allows individuals aged 55 or older to do just that, offering a lifeline during unexpected transitions like job loss or early retirement. It’s important to understand the nuances of this rule, as they can significantly impact your long-term financial health.
With Bright Advisers leading the charge in personalized financial planning, families can harness this opportunity to make informed decisions that align with their unique aspirations. Together, we can navigate this journey and secure your financial future. As the landscape of retirement planning evolves, it’s essential for individuals to explore the advantages, pitfalls, and tax implications of the Rule of 55. By doing so, you ensure that you are well-equipped to thrive in your financial journey.
We’re here for you, ready to support you in making choices that resonate with your family’s values. Let’s take this step together, ensuring that your financial decisions reflect your hopes and dreams for the future.
Bright Advisers: Personalized Financial Planning for the 401k Rule of 55
At Bright Advisers, we understand that customized monetary planning is essential for households with young children. Our approach to the 401k 55 year old rule is based on a deep understanding of each family’s unique financial situation and aspirations. By leveraging innovative technology, we create personalized strategies that empower you to make informed decisions about early withdrawals from your 401k plans. This ensures that your family can secure a bright financial future while prioritizing what truly matters—your loved ones.
Consider this: current statistics show that 56% of consumers feel confident in their ability to save money, yet the average bank account balance is just $40,000. This highlights the economic challenges many families face. Unfortunately, many still encounter significant obstacles, as illustrated by a Kansas man’s experience of losing $30,000 in a prolonged scam. This underscores the critical need for financial literacy and professional guidance. At Bright Advisers, we address these challenges by offering tailored solutions that not only enhance your financial understanding but also protect your family from potential setbacks, ensuring you are well-informed and prepared, particularly concerning the 401k 55 year old rule.
With our innovative technology and dedicated team of advisors, we equip families with the essential tools to navigate the complexities of early 401k withdrawals. Take the success story of clients Emily and Mark, for instance. By partnering with us, they gained clarity about their financial situation and crafted a comprehensive plan that granted them the freedom to make career choices aligned with their desired work-life balance. Our client-centered model not only increases the likelihood of achieving financial goals but also fosters a nurturing environment where families can come together around shared values and aspirations.
By prioritizing personalized strategies, Bright Advisers stands as a trusted leader in wealth management for families, ensuring you are well-prepared to build and sustain multi-generational wealth.
Understanding the Rule of 55: Definition and Purpose
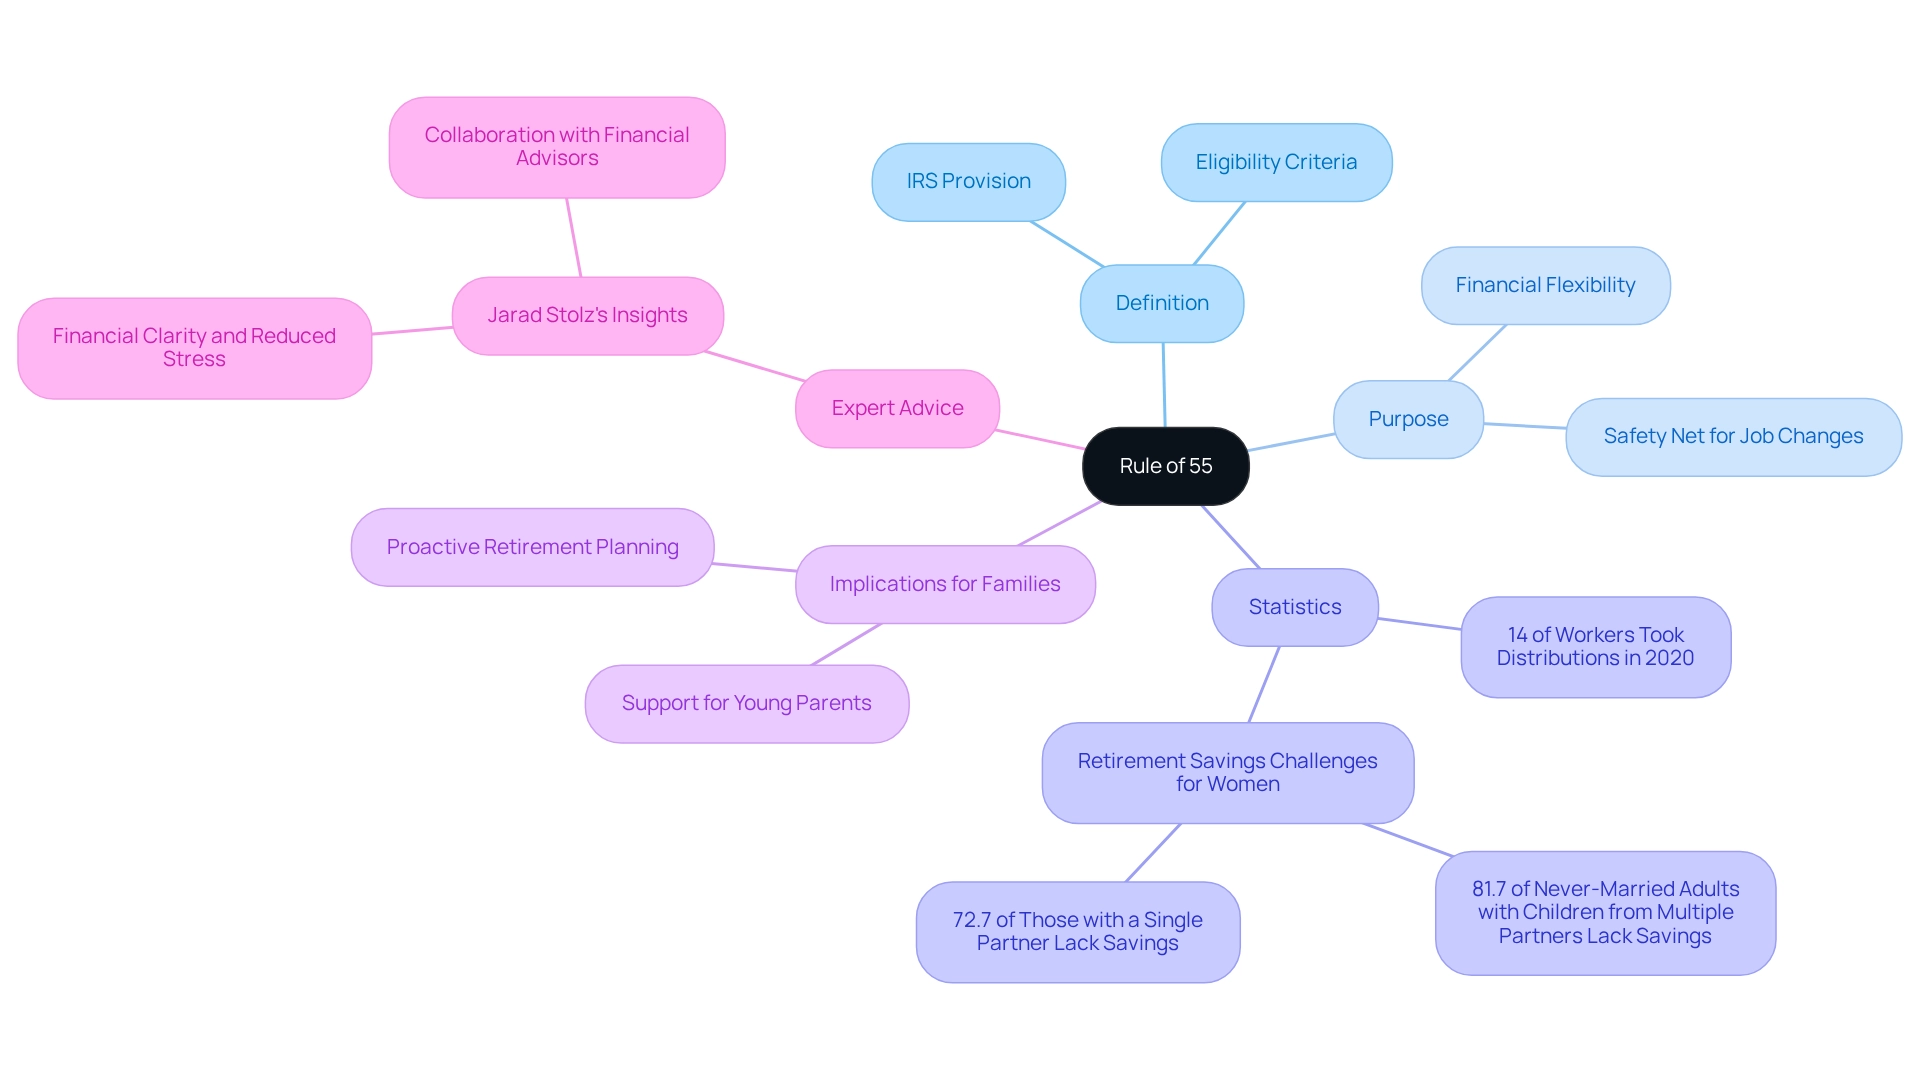
The 401k 55 year old rule is an IRS provision that allows individuals who leave their job during or after the year they turn 55 to withdraw funds from their 401(k) or 403(b) plans without incurring the standard 10% early withdrawal penalty. This guideline is designed to provide financial flexibility for those who may need to access their savings sooner than expected, especially in cases of unforeseen job loss or early withdrawal.
Imagine facing a sudden job change; it can be overwhelming. In 2020, 14% of workers in the US reported taking a coronavirus-related distribution from their 401(k) plans. This statistic highlights the critical need for financial adaptability during challenging times. By allowing penalty-free access to these funds, the 401k 55 year old rule serves as a vital safety net for individuals navigating significant life transitions, empowering them to manage their finances more effectively.
As Jarad Stolz, a long-term care certified and Chartered Retirement Planning Counselor, shares, “You’ll experience financial clarity, reduced stress, and a more secure phase of life by collaborating with us at Bright Advisers.” This underscores the importance of understanding the 401k 55 year old rule and seeking expert advice that is tailored to your unique needs.
It’s also essential to recognize that women who have children with a single partner are more likely to lack retirement savings than those without children. This reality emphasizes the importance of proactive retirement planning, especially for young parents. At Bright Advisers, we prioritize personalized financial planning and investment strategies that empower families to achieve financial security and freedom. Together, we can navigate this journey and ensure a brighter future for you and your loved ones.
Eligibility Criteria for the Rule of 55: Who Can Benefit?
To qualify for the 401k 55 year old rule, individuals must meet specific criteria:
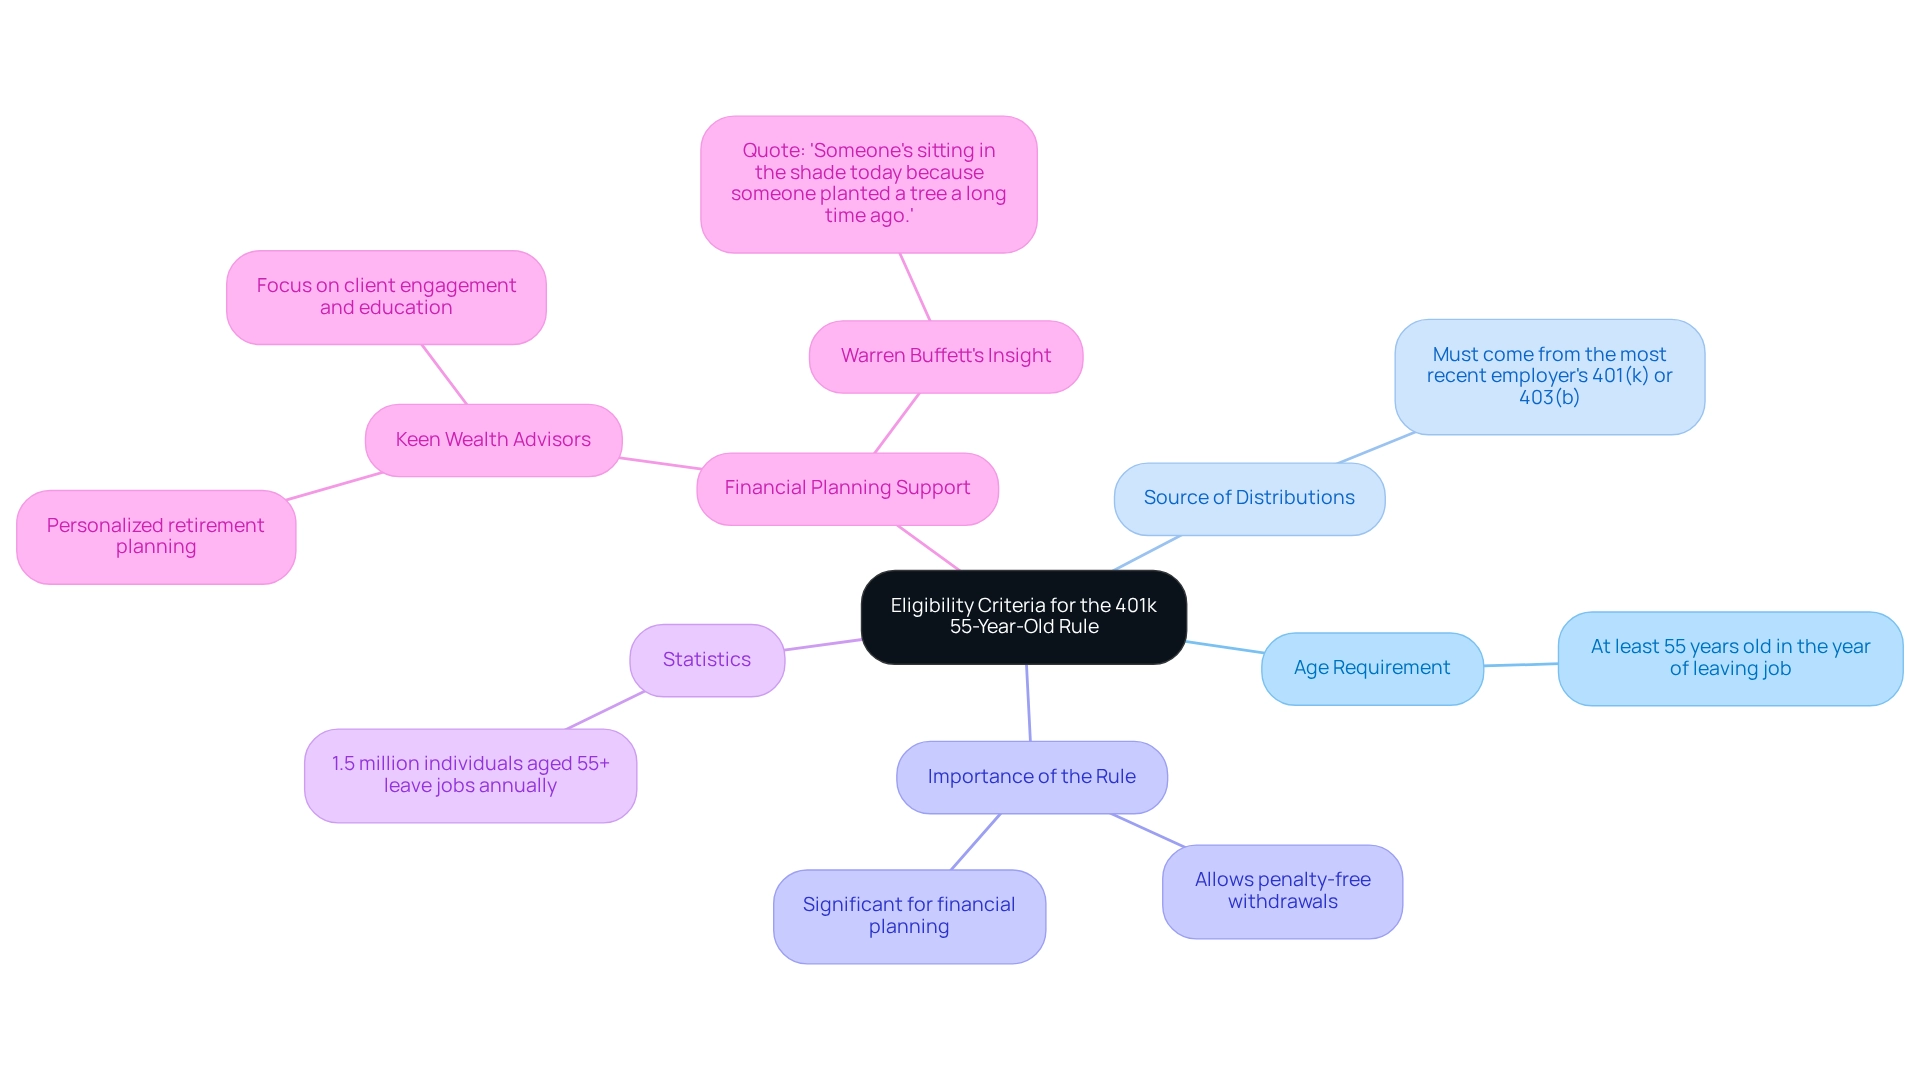
- They need to be at least 55 years old in the year they leave their job.
- The distributions must come from the 401(k) or 403(b) plan associated with their most recent employer.
This 401k 55 year old rule is particularly important as it allows for penalty-free withdrawals, providing a significant advantage for those entering their later years. Imagine if you could access your retirement funds without the worry of penalties.
However, it’s essential to understand that if you leave your job before turning 55, you will need to wait until you reach 59½ to access those funds without incurring penalties. This provision is crucial for many, as statistics show that around 1.5 million individuals aged 55 and older leave their jobs each year, highlighting the potential impact of this rule on their financial planning.
As Warren Buffett wisely stated, “Someone’s sitting in the shade today because someone planted a tree a long time ago,” reminding us of the importance of making sound financial decisions today for a brighter future.
Furthermore, companies like Keen Wealth Advisors are here to help. They focus on tailored financial planning, guiding clients through these regulations to ensure a secure economic future for their families. Together, we can navigate this journey and make informed choices that benefit you and your loved ones.
Advantages of the Rule of 55: Why Consider Early Withdrawals?
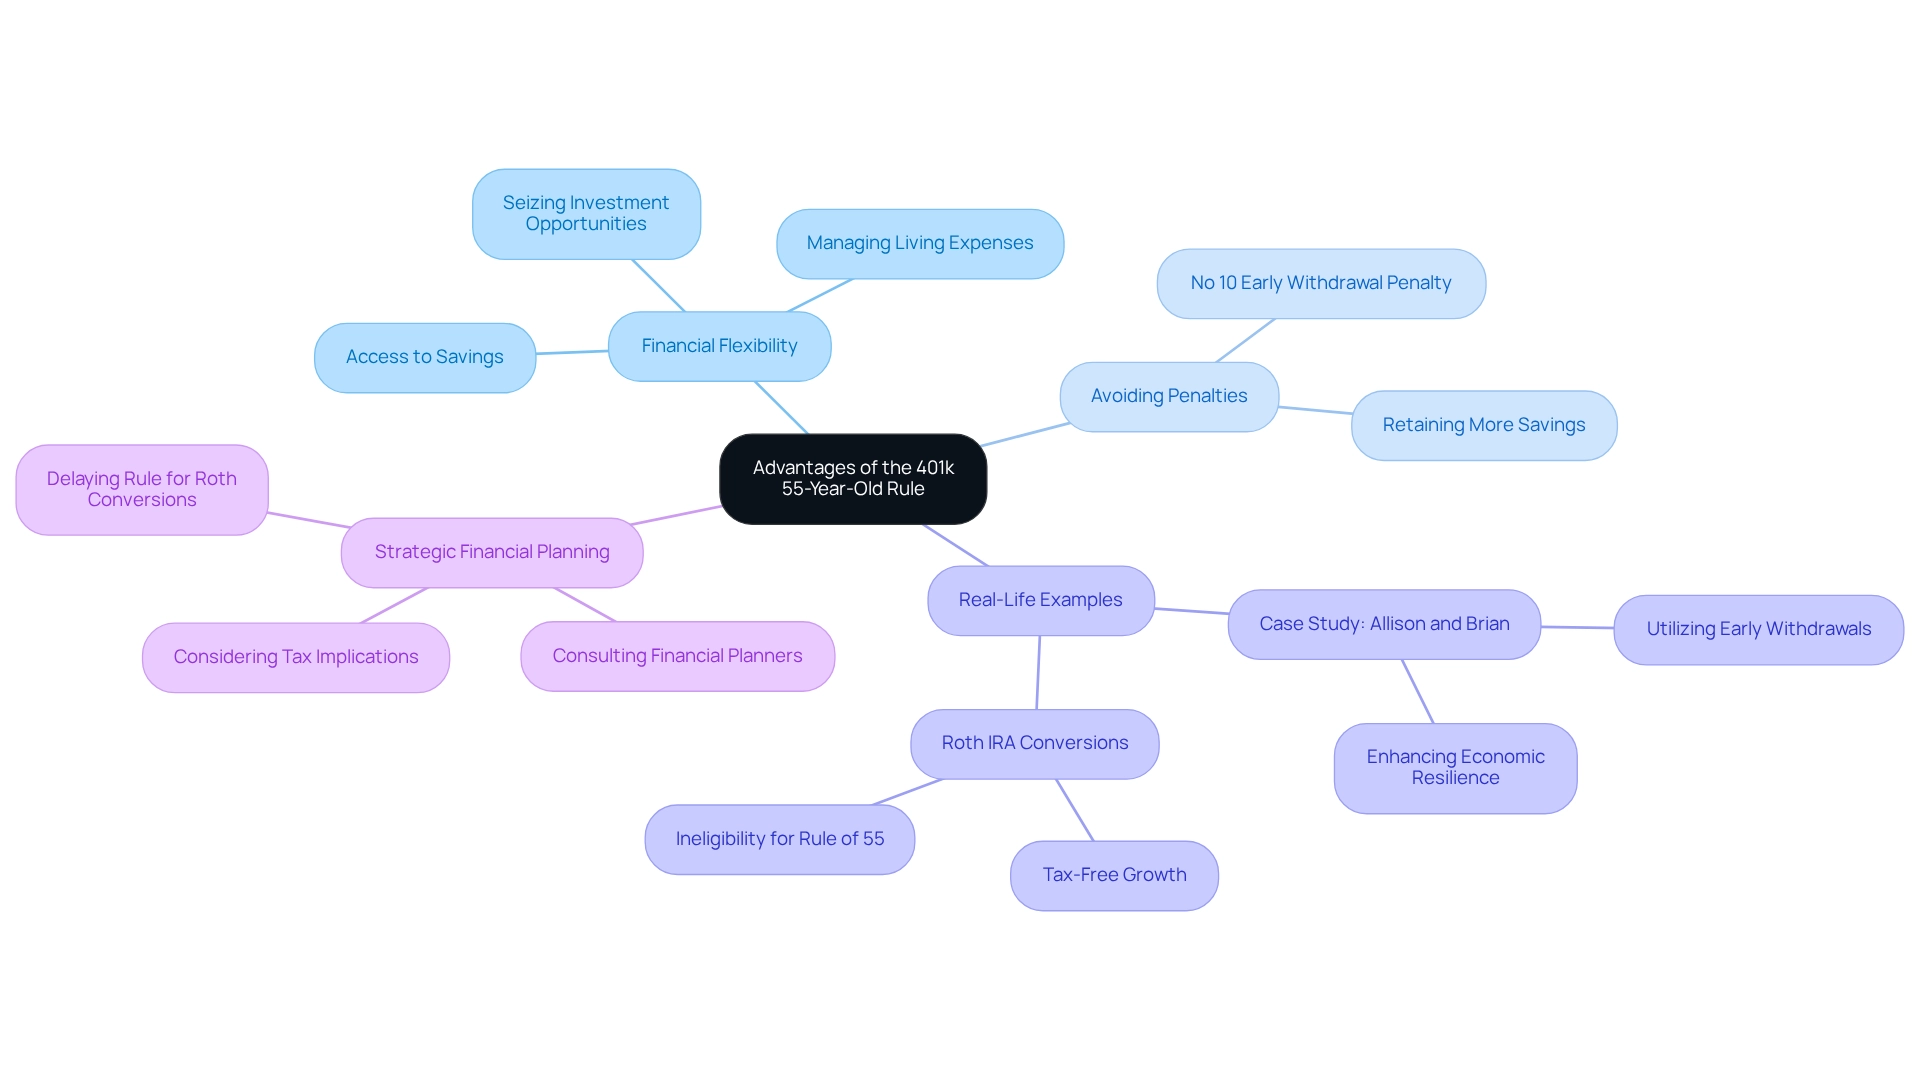
The 401k 55 year old rule offers numerous attractive benefits for individuals considering early access to their savings accounts. Imagine being able to access your savings without incurring the standard 10% early withdrawal penalty. This can lead to considerable savings, allowing you to keep thousands of dollars that would otherwise be forfeited to charges. This not only helps your finances but also improves your overall economic well-being, making it important to understand that the 401k 55 year old rule pertains solely to the savings plan at your latest employer. This means you can begin a new position and contribute to a different savings plan without affecting your current distributions. Grasping this detail is essential for making informed choices that benefit your household, and the 401k 55 year old rule provides vital economic flexibility during transitional periods, such as job loss or early retirement. It empowers you to manage living expenses or seize new investment opportunities without the weight of penalties. This adaptability is particularly beneficial for families who may need prompt access to resources for essential requirements like education or healthcare.
Statistics show that many people gain from this regulation, as it allows them to manage monetary challenges more efficiently. Families facing unexpected expenses can utilize these funds to maintain stability during uncertain times. Money planners frequently support the 401k 55 year old rule, emphasizing its strategic benefits in managing assets for later life. As Alvin Carlos, a certified planner, points out, accessing retirement funds early can be a wise choice, especially when aligned with broader monetary strategies. He also recommends considering strategic Roth conversions, which may involve delaying the 401k 55 year old rule to maximize tax benefits.
Consider the real-life stories that illustrate the practical benefits of the 401k 55 year old rule. For instance, converting funds from a 401(k) to a Roth IRA can provide tax-free growth, but it makes those funds ineligible for the Rule of 55 for five years. Families such as Allison and Brian, who collaborated with Bright Advisers, have effectively utilized early withdrawals to tackle urgent monetary needs, showcasing the rule’s potential to enhance economic resilience. By incorporating tax optimization into their comprehensive monetary plan, they not only secured their children’s future but also gained the ability to retire sooner.
Bright Advisers employs innovative technology that renders traditional investment products obsolete, allowing for more efficient investment portfolios. Their tactics, including smart beta and factor investing, enhance the 401k 55 year old rule by providing households with customized investment solutions that align with their monetary objectives. By understanding and applying the 401k 55 year old rule, you can make informed choices that support your economic aims while ensuring your family is well-prepared for the future. As you contemplate your budgeting strategies, it’s crucial to examine all accounts and possible tax implications before departing from a position. This proactive approach will assist you in navigating the complexities of early withdrawals and aligning your strategies with long-term monetary objectives. Remember, we’re here for you, and together, we can navigate this journey.
Pitfalls of the Rule of 55: What to Watch Out For
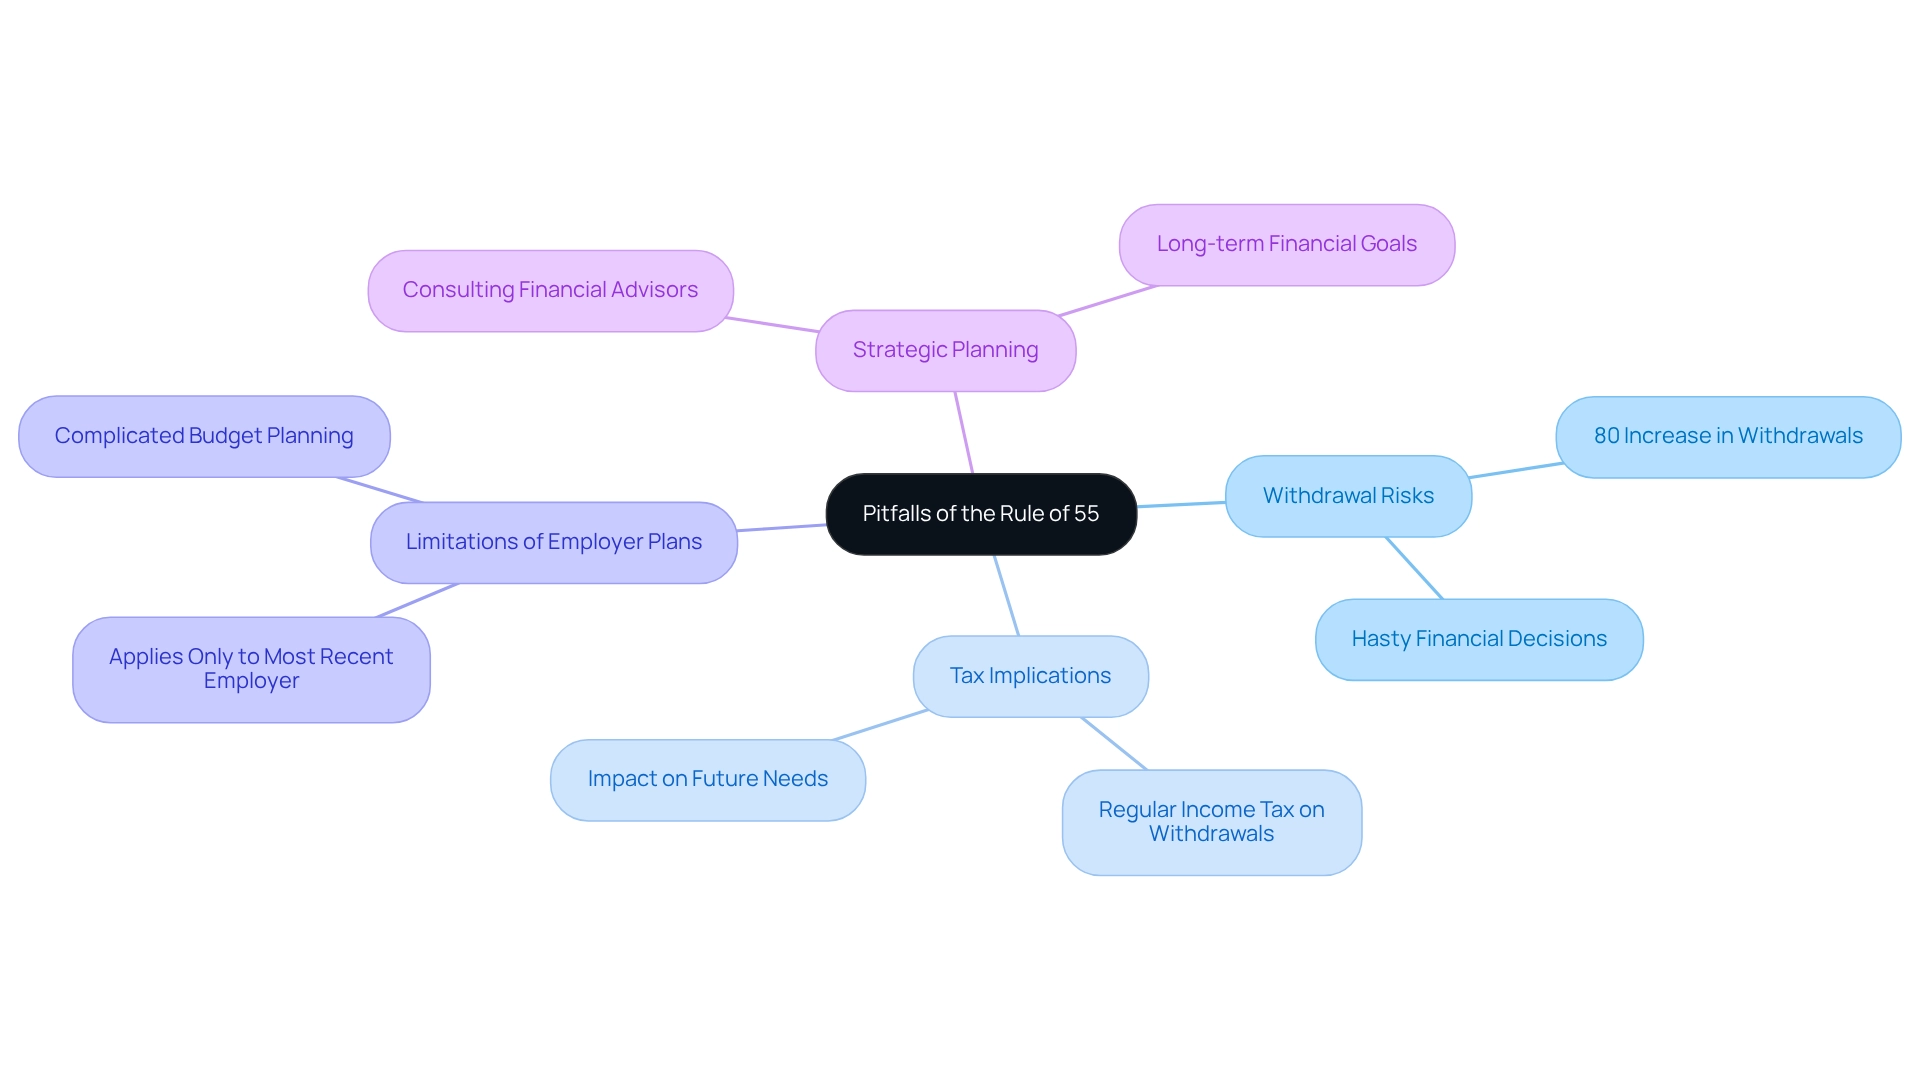
While the 401k 55 year old rule can provide early access to pension funds, it’s essential for families to consider its significant pitfalls. Imagine the worry of exhausting your savings too early—this can greatly impact your long-term economic stability. Statistics reveal that average withdrawals increase by about 80% once individuals reach the limit for early withdrawal penalties. This highlights the urgency that can lead to hasty financial decisions. Additionally, withdrawals under this rule are subject to regular income tax, which can further diminish the funds available for future needs. It’s important to understand that the 401k 55 year old rule applies only to the most recent employer’s retirement plan, which may limit options for those with multiple accounts. This restriction can complicate budget planning, leaving families with fewer resources than anticipated.
Consider the journey of Allison and Brian with Bright Advisers. Their story illustrates the importance of strategic tax planning. Despite their substantial incomes, they faced financial challenges initially due to inadequate tax strategies. Through their partnership with Bright Advisers, they optimized their tax situation, secured their children’s future through education funding, and gained the ability to retire sooner. This experience underscores the long-term consequences of financial choices, including the risks associated with early withdrawals from retirement accounts, especially under the 401k 55 year old rule. Expert insights emphasize the need for a strategic approach. Investment advisors, like Sam Swenson, caution that withdrawing money from employer-sponsored plans can significantly reduce overall retirement income in the future. Families, especially young caregivers, should carefully evaluate their financial situations and long-term goals before making any withdrawals, ensuring they do not jeopardize their future stability. Remember, consulting with a financial advisor can provide valuable insights and help families navigate these complex decisions. We’re here for you, ready to support you on this journey.
Tax Implications of the Rule of 55: Understanding Your Obligations
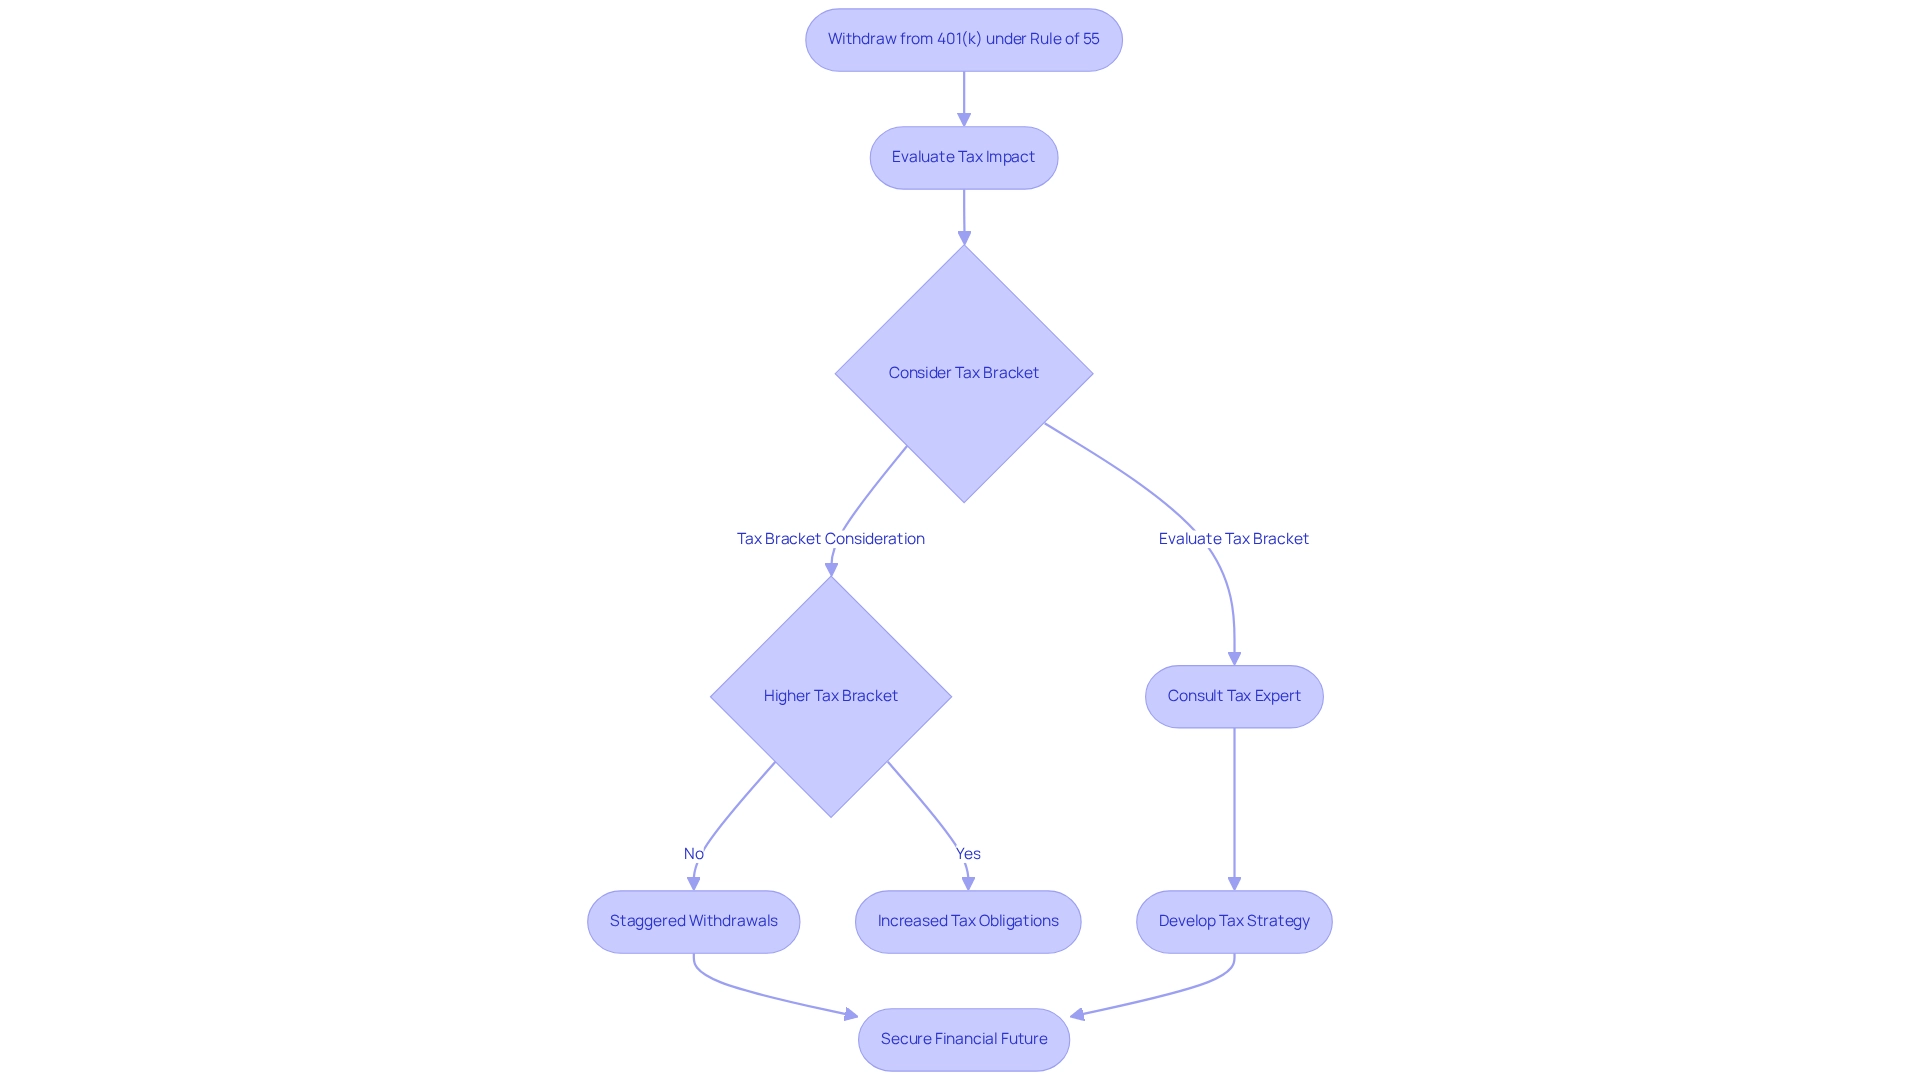
Withdrawals made under the 401k 55 year old rule can feel overwhelming, especially with the ordinary income tax implications. When you withdraw funds, that amount is added to your taxable income for the year, which could unexpectedly elevate you into a higher tax bracket. This means your tax bill might be larger than anticipated.
It’s essential for families to understand that the average tax rate for 401(k) distributions can vary significantly based on total income. For example, withdrawing $10,000 might push a family’s taxable income high enough to move into a higher bracket, leading to increased tax obligations. Consulting with a tax expert can be a valuable step in managing these complexities and creating strategies to reduce tax liabilities, particularly in light of the 401k 55 year old rule, which eliminates the 10% early penalty but retains significant tax consequences.
Families like Jay and Emma, who sought guidance from Bright Advisers, discovered ways to enhance their tax planning and develop a tailored savings strategy that met their immediate financial needs. Their journey underscores the importance of having a comprehensive plan that balances current monetary needs with future investment goals.
As tax brackets may shift with rising income, it’s crucial for families to consider how early distributions will impact their overall tax situation in 2025 and beyond. Expert insights suggest that taking a holistic approach and seeking professional guidance can help optimize financial strategies and effectively manage tax liabilities. Families should also explore options such as staggered withdrawals or working with a money advisor, just as Emily and Mark did with Bright Advisers, to better understand their tax implications and make informed decisions. Together, we can navigate this journey and ensure a secure financial future for your family.
Alternatives to the Rule of 55: Exploring Other Withdrawal Options
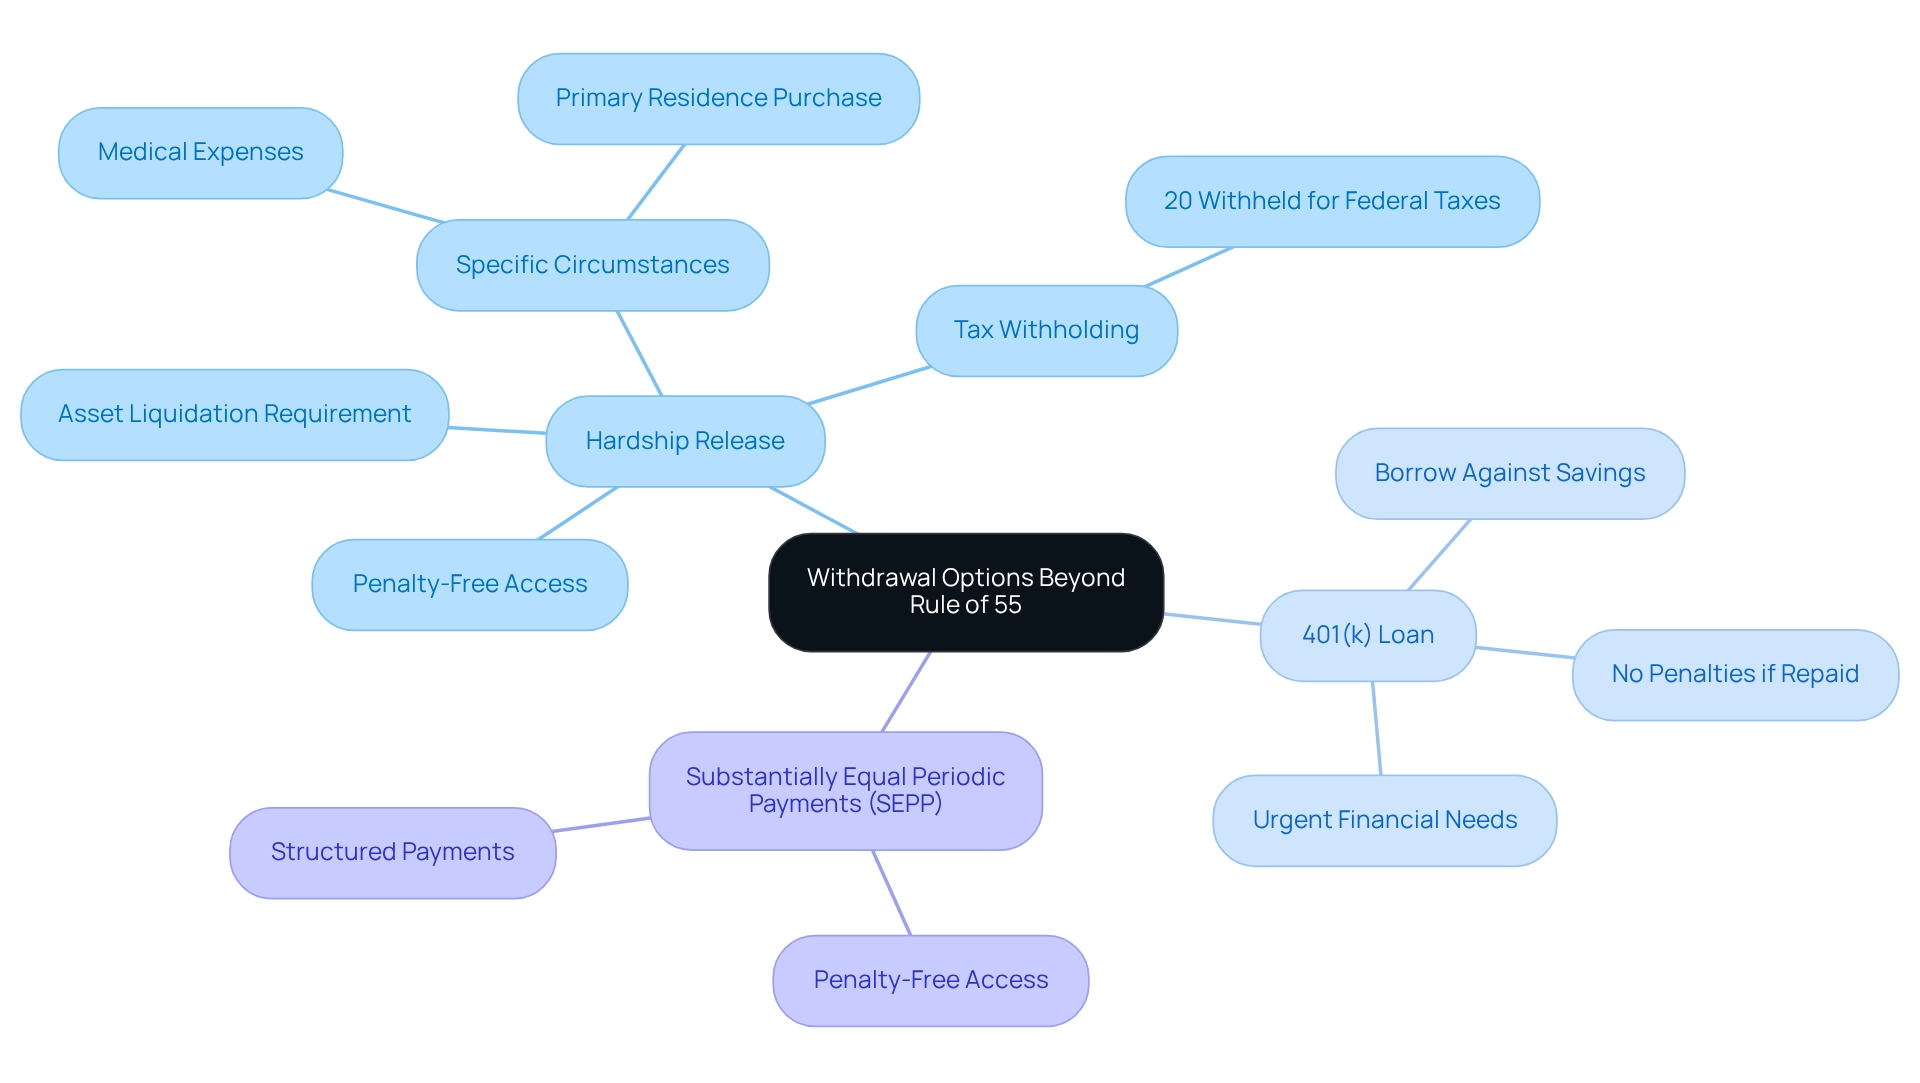
Navigating the complexities of early retirement fund access can be daunting, especially for young families like Emily and Mark. Beyond the 401k 55 year old rule, there are several alternatives available that can provide the support you need. One option is a hardship release, which allows for penalty-free access under specific circumstances, such as medical expenses or purchasing a primary residence. However, it’s important to understand that many plans may withhold 20% of the distribution to cover anticipated federal taxes, which can affect the net amount you receive. Additionally, the IRS may require liquidation of assets before allowing a hardship withdrawal, a crucial consideration for families looking to secure their futures.
Another option to consider is the 401(k) loan, which lets you borrow against your retirement savings. This can be particularly appealing for families facing urgent financial needs, as there are no penalties if the loan is repaid within the specified timeframe. Moreover, the Substantially Equal Periodic Payments (SEPP) method offers a way to access funds penalty-free through a series of equal payments over a designated period, providing a structured approach to utilizing your savings.
As you evaluate these alternatives, it’s essential to align them with your financial situation and long-term goals. Financial advisors at Bright Advisers emphasize the importance of considering how the 401k 55 year old rule allows for early access to funds and its impact on your future retirement security. For instance, while hardship distributions can provide immediate relief, they may hinder long-term growth potential if not managed wisely. As Connie Lee wisely points out, “For these reasons, early withdrawals are generally not recommended unless absolutely necessary.”
Understanding these options can empower families like Jay and Emma to make informed decisions that align with their financial goals. Remember, we’re here for you—together, we can navigate this journey, alleviating stress and safeguarding your family’s future.
Consulting Financial Planners: Navigating the Rule of 55 with Expert Guidance
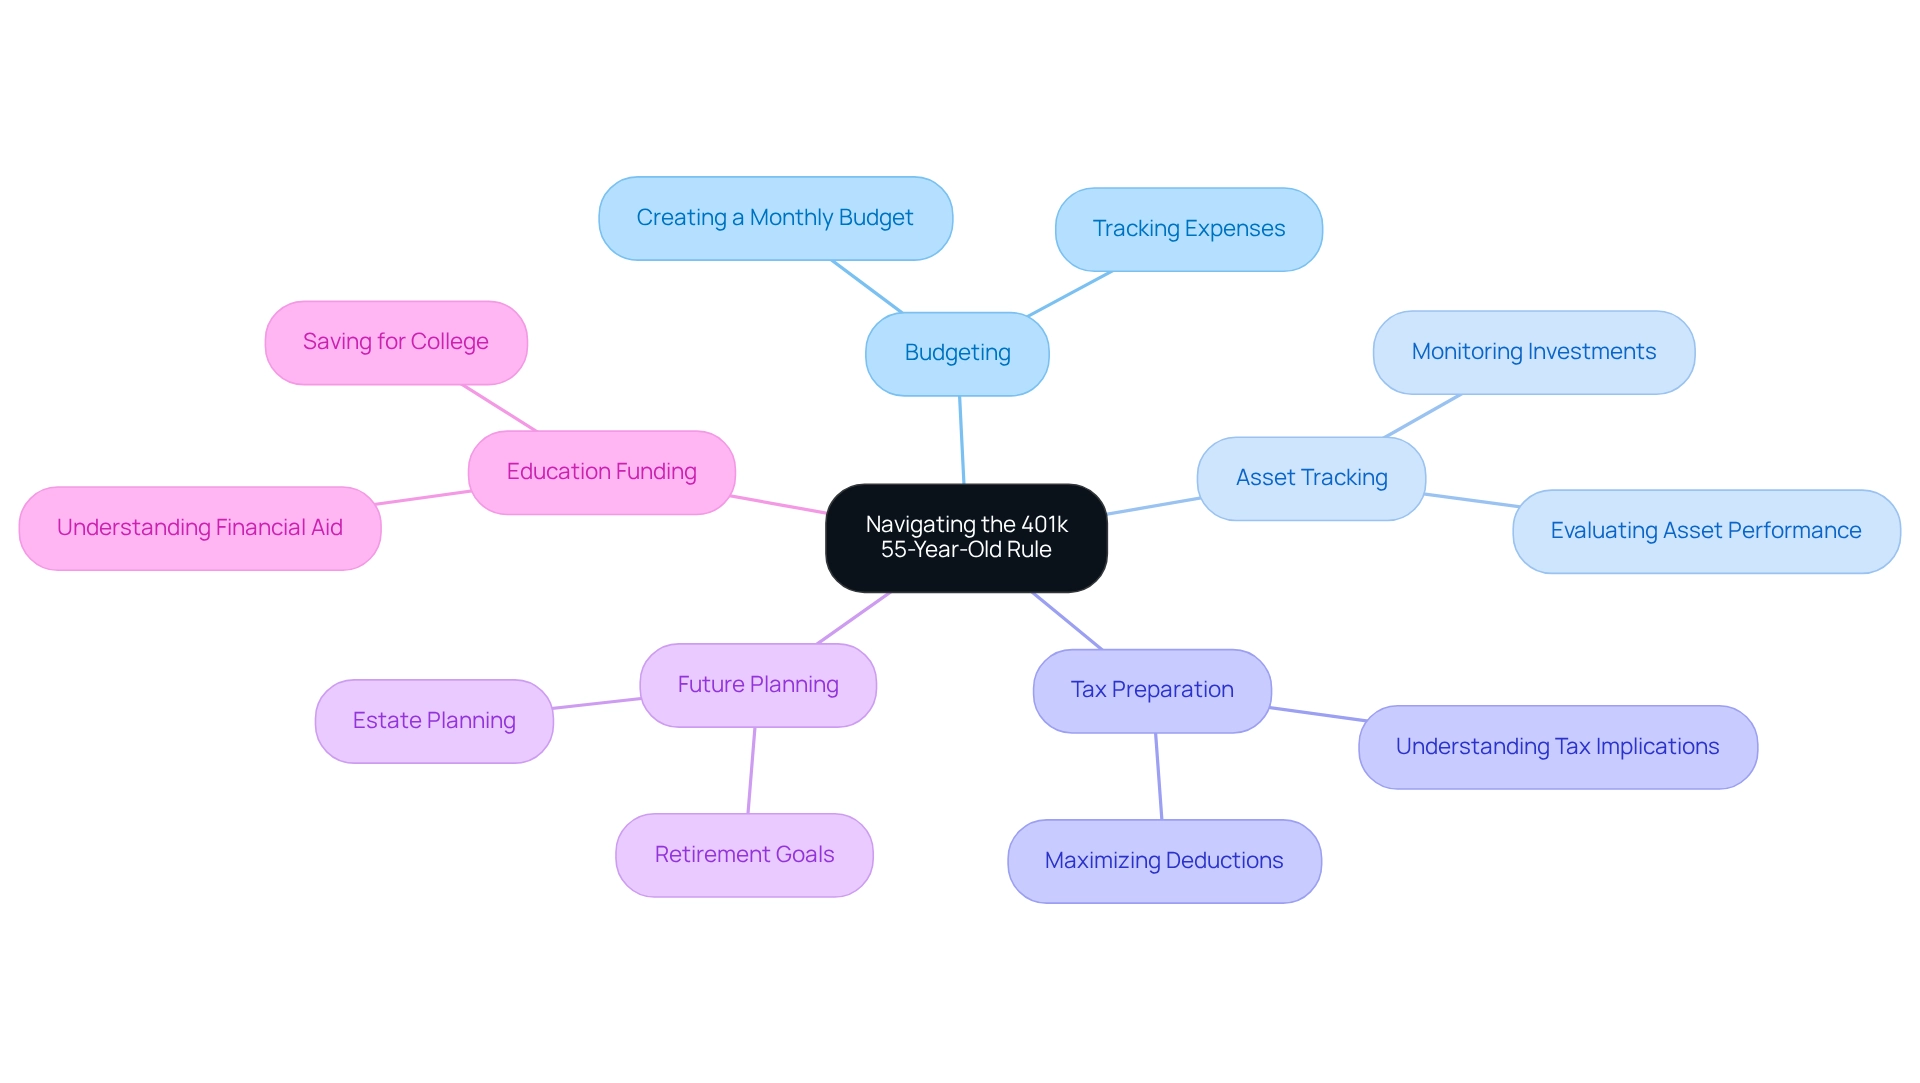
Navigating the complexities of the 401k 55 year old rule can feel overwhelming for families, making the expertise of planners at Bright Advisers truly invaluable. Our dedicated team provides personalized guidance that considers your unique situation, helping you understand the implications of early withdrawals while developing strategies that align with your financial goals. Together, we work closely with families to create comprehensive financial plans that encompass:
- Budgeting
- Asset tracking
- Tax preparation
- Future planning
- Education funding
This ensures you make informed choices that enhance your long-term financial well-being.
Imagine if you could face generational economic challenges with confidence. Families often seek planners to address their specific needs—Millennials may focus on managing student debt, while Baby Boomers prioritize future planning. This understanding allows our advisors to offer relevant guidance that resonates with your unique circumstances. By tailoring our support to these differences, we can better assist families in achieving their financial objectives.
Statistics reveal that families who consult planners are significantly more likely to achieve positive retirement outcomes. In fact, financial advisors are eight times more trusted than online influencers, highlighting the importance of professional guidance during times of financial uncertainty. As Emily and Mark discovered through their collaboration with Bright Advisers, the direction and support we provide can empower you to create a life that aligns with your personal and financial aspirations, ultimately leading to financial independence. By reaching out to financial planners, families can navigate the 401k 55 year old rule with assurance, ensuring that their early withdrawal strategies are compliant and optimized for long-term success. To take the next step on this journey, we invite you to join our waitlist and schedule a consultation with a financial planner at Bright Advisers. Together, we can discuss your unique circumstances regarding the 401k 55 year old rule and work towards securing your family’s financial future.
Long-Term Retirement Planning: Integrating the Rule of 55 into Your Strategy
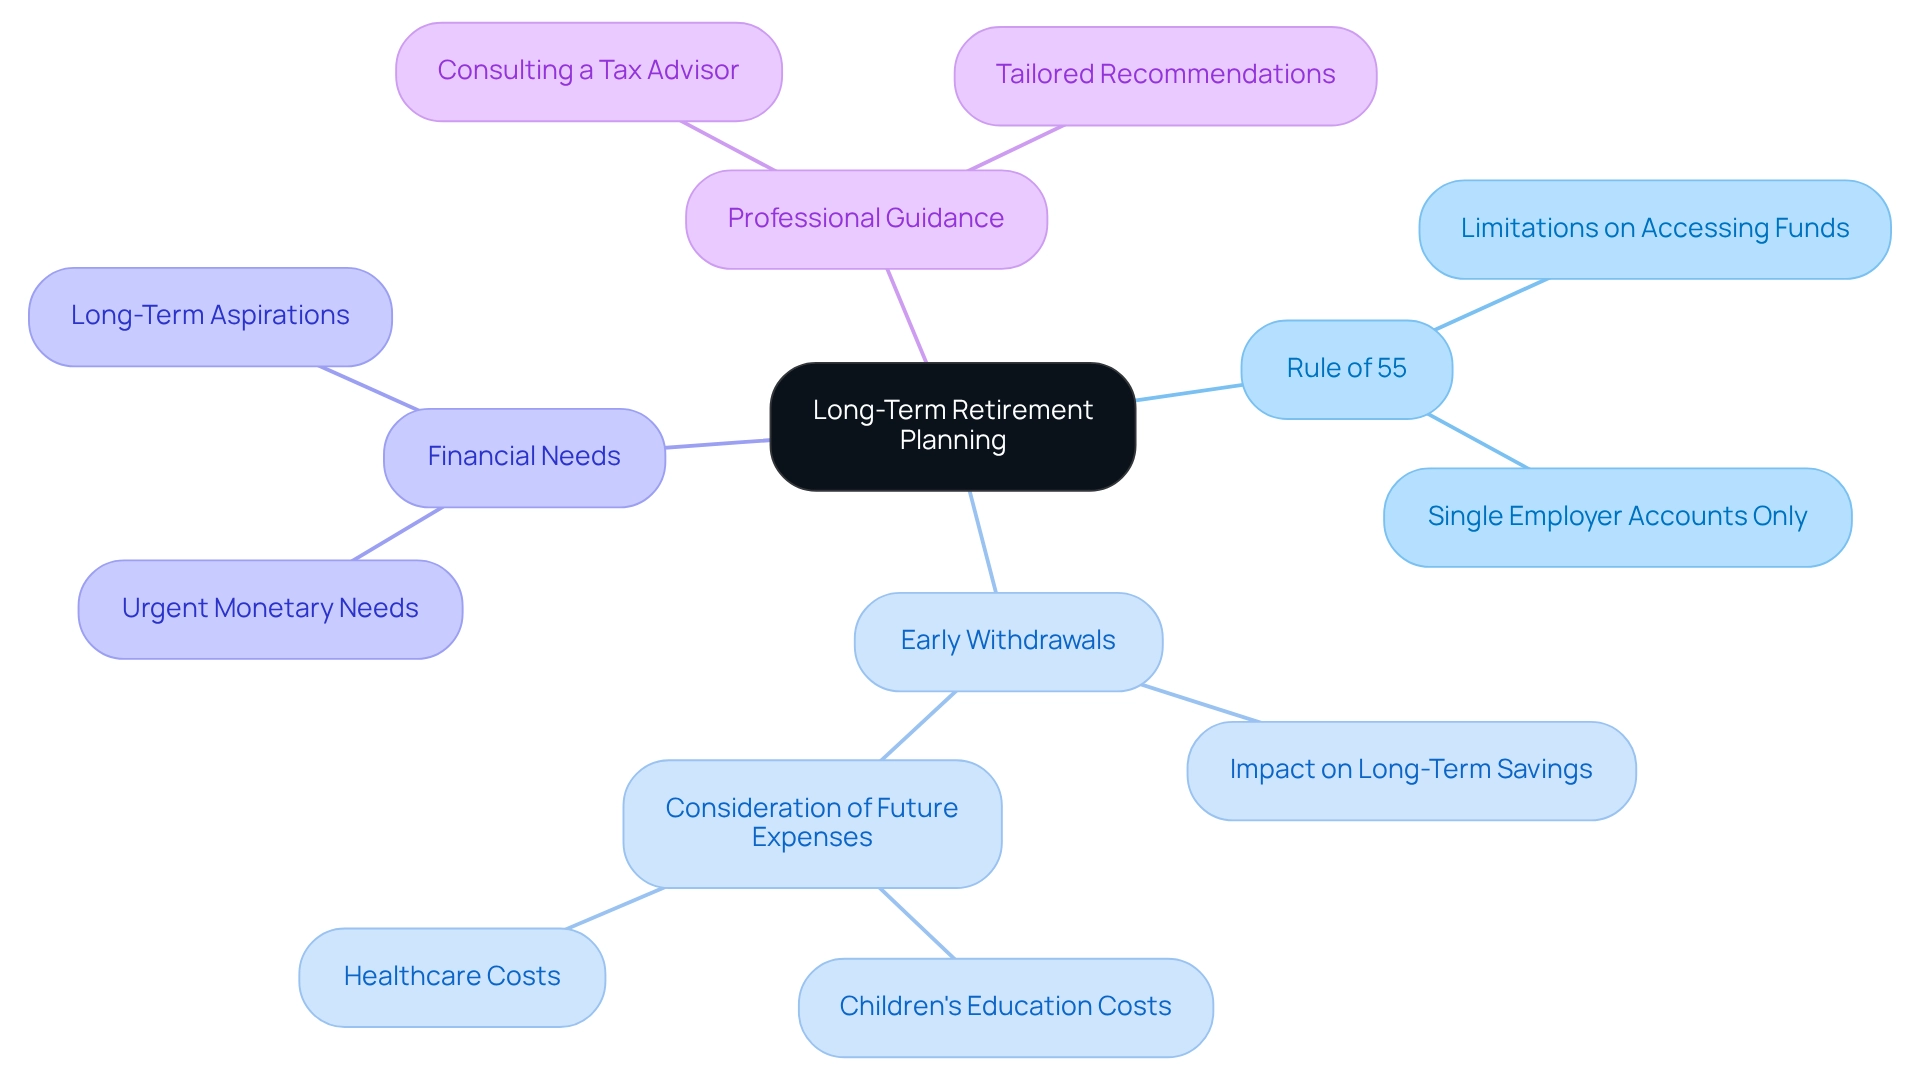
Incorporating the 401k 55 year old rule into your long-term financial strategy is vital for families striving to secure their financial future. Imagine if you could access your retirement funds early, but it’s important to understand that under the 401k 55 year old rule, you cannot use funds from multiple 401(k) accounts with previous employers. This limitation can restrict options for early access, which is a concern for many families.
Early withdrawals can significantly impact your overall savings for later years and your income requirements. It’s essential to carefully assess how these withdrawals align with future expenses, such as your children’s education and healthcare costs. Bright Advisers offers a comprehensive strategy for planning that not only addresses urgent monetary needs but also safeguards against potential future economic challenges.
Their innovative wealth management platform connects your financial plan with tailored investment strategies, ensuring that families receive personalized recommendations that reflect their unique situations. As Vision Retirement wisely advises, “You should consult with your tax advisor for guidance on your specific situation,” underscoring the importance of professional support.
This forward-thinking strategy is crucial, as research indicates that many households underestimate the impact of early withdrawals on their long-term savings, which could jeopardize their financial security in the years ahead. Bright Advisers empowers families like Emily and Mark to develop robust wealth management strategies that harmonize current needs with long-term aspirations.
Together, we can navigate this journey, demonstrating the importance of evaluating retirement strategies with a focus on both immediate needs and future goals. Remember, we’re here for you, and with the right guidance, you can confidently plan for a secure financial future.
Key Takeaways on the Rule of 55: Essential Facts to Remember
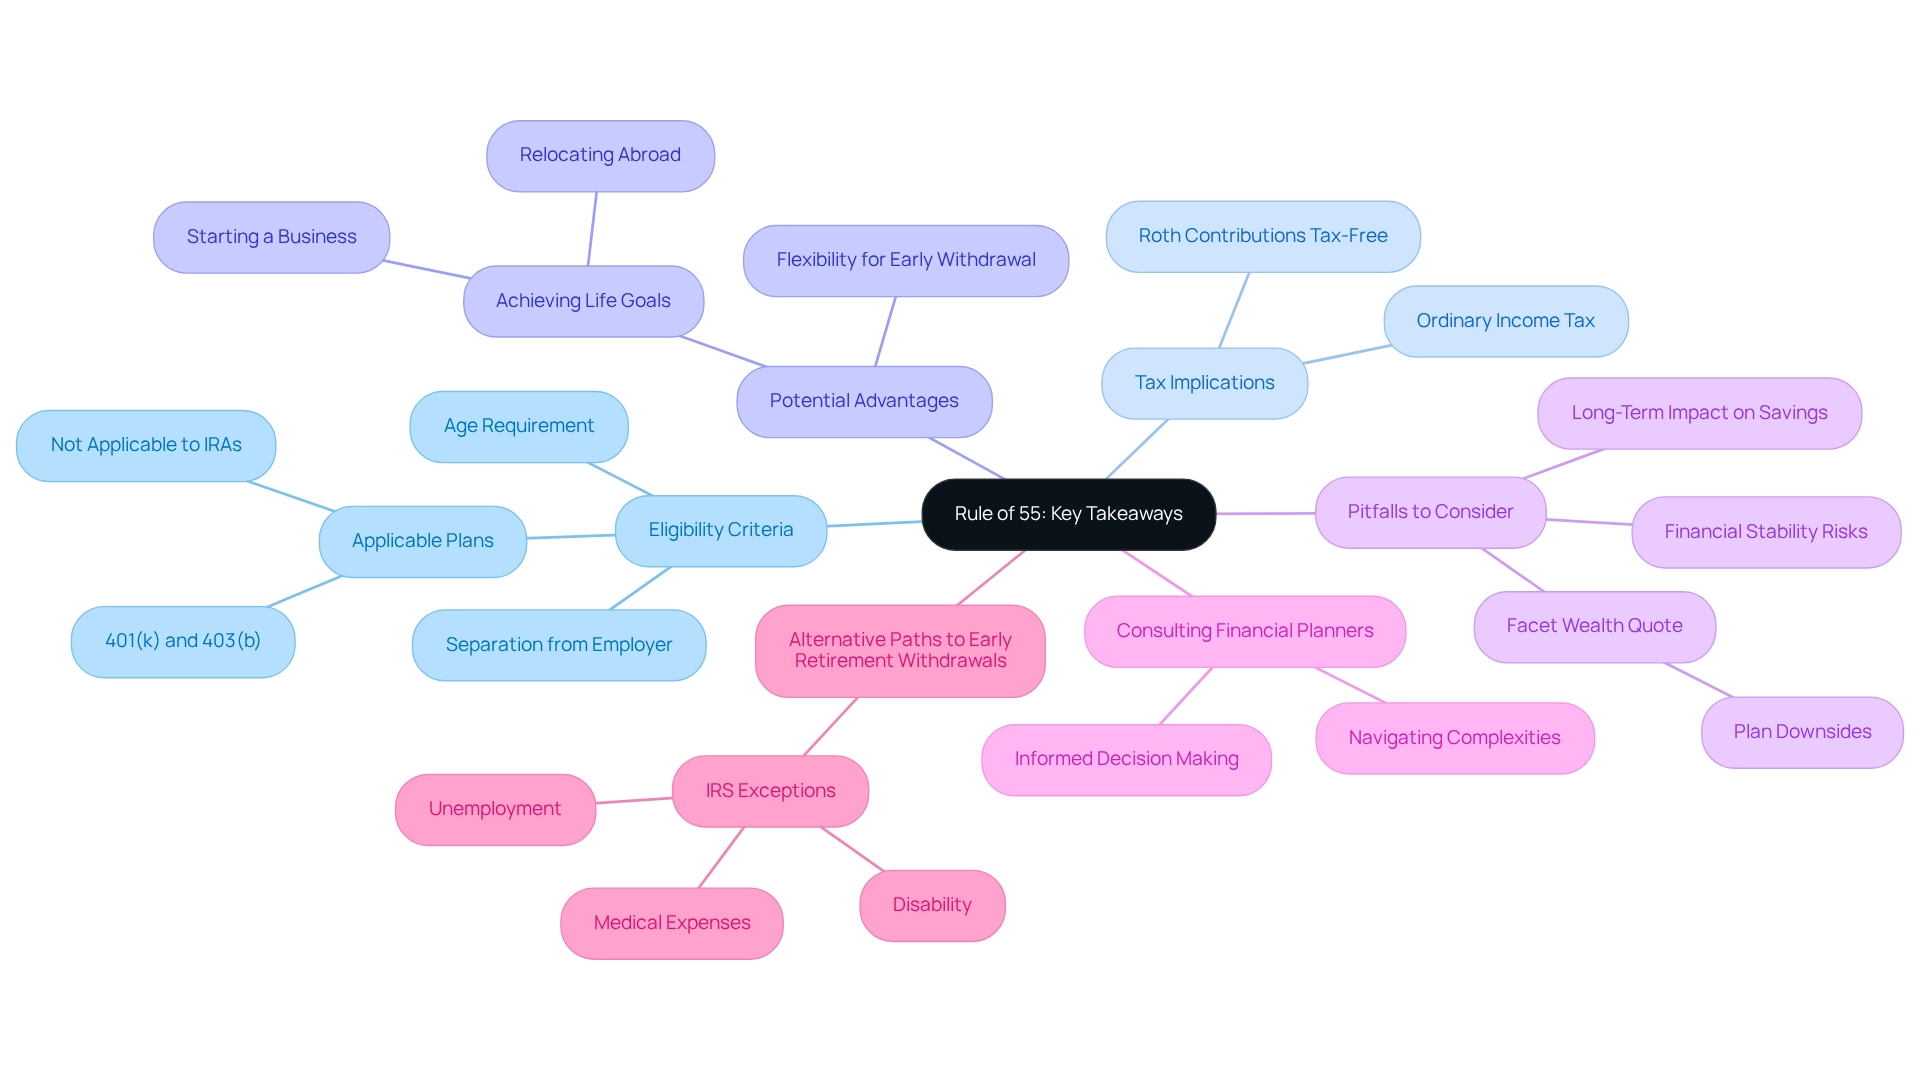
The 401k 55 year old rule offers a valuable opportunity for individuals aged 55 or older to access their 401(k) or 403(b) funds without incurring the usual 10% early exit penalty, provided they have left their job. Here are some essential facts to consider:
- Eligibility Criteria: To qualify, you need to be at least 55 years old and have separated from your employer. This rule applies specifically to 401(k) and 403(b) plans, not IRAs.
- Tax Implications: Withdrawals will be subject to ordinary income tax, making it crucial to evaluate the tax impact of your decisions. For example, withdrawing from Roth contributions in a 401(k) is generally tax-free, which can be a favorable option for many.
- Potential Advantages: This rule can provide much-needed flexibility for those contemplating early withdrawal or requiring immediate access to funds. It can help families achieve significant life goals, such as starting a business or relocating abroad.
- Pitfalls to Consider: While the Rule of 55 allows access to funds later in life, it’s important to consider the long-term impact on your savings. Premature withdrawals can significantly diminish your savings, affecting your financial stability in the years to come. As noted by Facet Wealth, Inc., ‘While early retirement distributions may offer flexibility, every plan has its disadvantages.’
- Consulting Financial Planners: Working with a financial advisor can be invaluable in navigating the complexities of early access, helping families make informed choices that align with their financial objectives.
Moreover, exploring alternatives to the Rule of 55, such as those outlined in the case study ‘Alternative Paths to Early Retirement Withdrawals,’ can present families with more options for penalty-free withdrawals. Recent trends show that older workers are increasingly turning to the 401k 55 year old rule, which reflects a shift in retirement planning strategies. Understanding these key takeaways can empower families to leverage the Rule of 55 effectively, ensuring a secure financial future. Together, we can navigate this journey with confidence and support.
Conclusion
Understanding the Rule of 55 offers families a unique opportunity to access their retirement funds without the burden of early withdrawal penalties. This provision is specifically designed for those aged 55 and older who have left their jobs, providing financial flexibility during critical life transitions. It underscores the importance of strategic financial planning, helping individuals recognize the eligibility criteria and tax implications tied to this rule. By doing so, families can make informed decisions that align with their long-term financial objectives.
However, while the Rule of 55 presents distinct advantages, it’s important to remain aware of its potential pitfalls. Premature withdrawals can deplete retirement savings and lead to unforeseen tax liabilities, which can significantly impact future financial security. Engaging with a financial planner can be a valuable step for families, helping them navigate these complexities and ensuring that their withdrawal strategies are compliant and optimized for their unique circumstances.
Ultimately, integrating the Rule of 55 into a comprehensive retirement strategy is essential for fostering both immediate financial relief and sustainable long-term growth. By prioritizing personalized financial planning, families can secure their financial futures, allowing them to focus on what truly matters—building a life that reflects their values and aspirations. Together, we can navigate this journey, ensuring that your family’s financial goals are met with care and understanding.
Frequently Asked Questions
What is the 401k 55 year old rule?
The 401k 55 year old rule is an IRS provision that allows individuals who leave their job during or after the year they turn 55 to withdraw funds from their 401(k) or 403(b) plans without incurring the standard 10% early withdrawal penalty.
Who qualifies for the 401k 55 year old rule?
To qualify for the 401k 55 year old rule, individuals must be at least 55 years old in the year they leave their job and the distributions must come from the 401(k) or 403(b) plan associated with their most recent employer.
What are the benefits of the 401k 55 year old rule?
The rule allows for penalty-free withdrawals, providing financial flexibility for individuals who may need to access their savings sooner than expected, especially during significant life transitions, such as job loss.
What happens if someone leaves their job before turning 55?
If an individual leaves their job before turning 55, they will need to wait until they reach 59½ to access their retirement funds without incurring penalties.
How does Bright Advisers assist families regarding financial planning?
Bright Advisers provides customized monetary planning for families, utilizing innovative technology to create personalized strategies that empower clients to make informed decisions about early withdrawals from their 401k plans.
Why is financial literacy important for families?
Financial literacy is crucial as it helps families understand economic challenges and make informed decisions, protecting them from potential setbacks, such as scams or poor financial choices.
Can you provide an example of how Bright Advisers has helped clients?
An example is the success story of clients Emily and Mark, who gained clarity about their financial situation and crafted a comprehensive plan that allowed them to make career choices aligned with their desired work-life balance.
What does Bright Advisers prioritize in their financial planning approach?
Bright Advisers prioritizes personalized strategies tailored to each family’s unique financial situation and aspirations, aiming to empower families to achieve financial security and build multi-generational wealth.
List of Sources
- Bright Advisers: Personalized Financial Planning for the 401k Rule of 55
- 20 + Personal Finance Statistics for 2025 | Fortunly (https://fortunly.com/statistics/personal-finance-statistics)
- 54 Personal Finance Statistics & Facts in 2025 [SOURCES INCLUDED] (https://moneywise.com/research/personal-finance-statistics)
- 20+ Incredible Personal Finance Statistics to Know in 2025 (https://spendmenot.com/personal-finance-statistics)
- 5 Ways Financial Planning Can Help (https://schwab.com/learn/story/5-ways-financial-planning-can-help)
- Understanding the Rule of 55: Definition and Purpose
- 48 Interesting 401k Plan Statistics For 2023 – Carry (https://carry.com/learn/401k-statistics)
- 106 Revealing Retirement Statistics – Curio Wealth (https://curiowealth.com/106-revealing-retirement-statistics)
- What is the Rule of 55, and What Are the Rules? – Georgia Safe Retirement Planners (https://georgiasaferetirementplanners.com/403b-401k-withdrawal-age-55-rule)
- Eligibility Criteria for the Rule of 55: Who Can Benefit?
- What Is The Rule Of 55 And How Does It Work? | Bankrate (https://bankrate.com/retirement/rule-of-55)
- 7 Quotes from Warren Buffett on How Retirees Should “Invest” in What Matters the Most (https://keenwealthadvisors.com/insights/7-quotes-from-warren-buffett-on-how-retirees-should-invest-in-what-matters-the-most)
- Advantages of the Rule of 55: Why Consider Early Withdrawals?
- Rule of 55: How to Access Your 401(k) Early Without Penalty | Facet (https://facet.com/retirement-planning/rule-of-55-how-it-works-pros-and-cons-considerations)
- How To Retire Early With The Rule Of 55 (https://nasdaq.com/articles/how-retire-early-rule-55)
- What Is The Rule Of 55? | Advantages of Retiring at 55 Using Rule of 55 (https://districtcapitalmanagement.com/rule-of-55)
- Pitfalls of the Rule of 55: What to Watch Out For
- The impact of withdrawal penalties on retirement savings (https://sciencedirect.com/science/article/pii/S0047272724000197)
- Rule of 55: How to Access Your 401(k) Early Without Penalty | Facet (https://facet.com/retirement-planning/rule-of-55-how-it-works-pros-and-cons-considerations)
- How to Use the Rule of 55 to Take Early 401(k) Withdrawals – Capitalize (https://hicapitalize.com/resources/rule-of-55-401k)
- Tax Implications of the Rule of 55: Understanding Your Obligations
- IRA and 401(k) Withdrawal Rules | U.S. Bank (https://usbank.com/retirement-planning/financial-perspectives/ira-and-401k-withdrawal-rules.html)
- Understanding the rule of 55: A comprehensive guide to early retirement (https://businessinsider.com/personal-finance/investing/rule-of-55-401k-early-withdrawal)
- Retire Early and Penalty-Free: Navigating the Rule of 55 (https://blog.acadviser.com/retire-early-penalty-free-navigating-the-rule-of-55)
- Early Retirement Distributions: 72t and Rule of 55 | RGWM Insights (https://rgwealth.com/insights/early-retirement-72t-rule-of-55)
- Alternatives to the Rule of 55: Exploring Other Withdrawal Options
- 2 ways to use retirement money early | Vanguard (https://investor.vanguard.com/investor-resources-education/article/2-ways-to-use-retirement-money-early)
- Considering a 401(k) Hardship Withdrawal? Here’s What to Know (https://myubiquity.com/resources/401k-hardship-withdrawal-rules)
- 401(k) Loans vs. Hardship Withdrawals (https://smartasset.com/retirement/401k-loans-vs-hardship-withdrawals)
- Consulting Financial Planners: Navigating the Rule of 55 with Expert Guidance
- Americans with a financial advisor expect to retire two years earlier according to Northwestern Mutual’s Planning & Progress Study (https://news.northwesternmutual.com/2024-07-09-Americans-with-a-financial-advisor-expect-to-retire-two-years-earlier-according-to-Northwestern-Mutuals-Planning-Progress-Study)
- Wealth Management Statistics – Facts, Tips & Basics (https://plancorp.com/blog/wealth-management-statistics-facts-tips-basics)
- 27 eye-opening financial planning statistics (https://contentsnare.com/financial-planning-statistics)
- Long-Term Retirement Planning: Integrating the Rule of 55 into Your Strategy
- Using the Rule of 55 to Take Early 401(k) Withdraws (https://visionretirement.com/articles/employee-benefits/rule-of-55)
- 7 Quotes from Warren Buffett on How Retirees Should “Invest” in What Matters the Most (https://keenwealthadvisors.com/insights/7-quotes-from-warren-buffett-on-how-retirees-should-invest-in-what-matters-the-most)
- Late-Stage Retirement Planning for Gen X – davidlerner.com (https://davidlerner.com/newsroom/article/late-stage-retirement-planning-for-gen-x)
- Key Takeaways on the Rule of 55: Essential Facts to Remember
- When Can You Withdraw? 401(k)s and the Rule of 55 (https://schwab.com/learn/story/retiring-early-5-key-points-about-rule-55)
- 35 Quotes for Financial Advisors on a Tough Day | Don Connelly & Associates (https://donconnelly.com/35-quotes-for-financial-advisors)
- Rule of 55: How to Access Your 401(k) Early Without Penalty | Facet (https://facet.com/retirement-planning/rule-of-55-how-it-works-pros-and-cons-considerations)
- 7 Quotes from Warren Buffett on How Retirees Should “Invest” in What Matters the Most (https://keenwealthadvisors.com/insights/7-quotes-from-warren-buffett-on-how-retirees-should-invest-in-what-matters-the-most)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Retirement & Employee Benefits for high-income W-2 families at Bright Advisers.
Keep reading