

Overview
The 403b Rule of 55 is a valuable opportunity for individuals aged 55 or older. It allows them to withdraw funds from their 403b accounts without facing a 10% early withdrawal penalty, provided they separate from their employer during or after the year they turn 55. Understanding the eligibility requirements is essential. It’s also important to consider the tax implications that come with these withdrawals.
Imagine if you could access your hard-earned savings when you need them most. This rule can be a lifeline for early retirees, but navigating the complexities can be daunting. That’s why seeking professional financial guidance is crucial. With the right support, you can avoid potential pitfalls and ensure a stable financial future for you and your family.
We’re here for you, ready to help you make informed decisions that align with your family’s values and goals. Together, we can navigate this journey toward financial security.
Key Highlights:
- Bright Advisers offers personalised financial planning for early retirees, focusing on their unique challenges.
- The 403b Rule of 55 allows individuals aged 55 or older to withdraw from 403b accounts without a 10% early withdrawal penalty if they separate from their employer during or after the year they turn 55.
- Eligibility for the 403b Rule of 55 requires being at least 55 years old and the funds must come from the 403b plan linked to the employer.
- Withdrawals under the 403b Rule of 55 are subject to ordinary income tax, which could increase the retiree’s tax bracket.
- Alternatives to the 403b Rule of 55 include borrowing against 403b plans or using the 72(t) rule for substantially equal periodic payments.
- Planning for long-term financial health is crucial, considering factors like healthcare costs and income sources.
- Professional guidance from financial advisors can help retirees navigate the complexities of the 403b Rule of 55 and minimise tax implications.
- Common pitfalls include withdrawing too soon and neglecting the tax consequences of distributions, which may lead to financial instability.
- Preparing for early retirement involves assessing savings, ongoing expenses, and income needs, along with creating a budget that reflects the new financial reality.
Introduction
Navigating the complexities of retirement planning can feel overwhelming, especially for early retirees who are striving to secure their financial future. The 403b Rule of 55 presents a significant opportunity, enabling individuals aged 55 and older to access their retirement savings without facing penalties, as long as they meet certain criteria. Yet, understanding this rule brings forth essential questions about:
- Eligibility
- Tax implications
- How it fits into broader long-term financial strategies
Imagine the peace of mind that comes with knowing the key insights that can empower you to make informed decisions and fully maximize your benefits under this rule. We’re here to help you through this journey.
Bright Advisers: Personalized Financial Planning for Early Retirees
At Bright Advisers, we understand the unique challenges that early retirees, especially those with young children, face. Our personalized monetary planning is designed to address your specific needs, helping you navigate this important life transition with confidence. Imagine having a strategy that aligns with your long-term financial goals while prioritizing your family’s well-being.
We conduct comprehensive evaluations of your economic situation, allowing you to manage the complexities of leaving the workforce early. Our client-first approach is essential for effectively utilizing the 403b Rule of 55, allowing for strategic withdrawals without penalties. This not only enhances your financial stability during retirement but also simplifies the planning process.
By empowering families like yours, we help you secure your future while you focus on what truly matters—your loved ones. Together, we can navigate this journey, ensuring that your financial plans reflect your family values and shared goals. We’re here for you, ready to support you every step of the way.
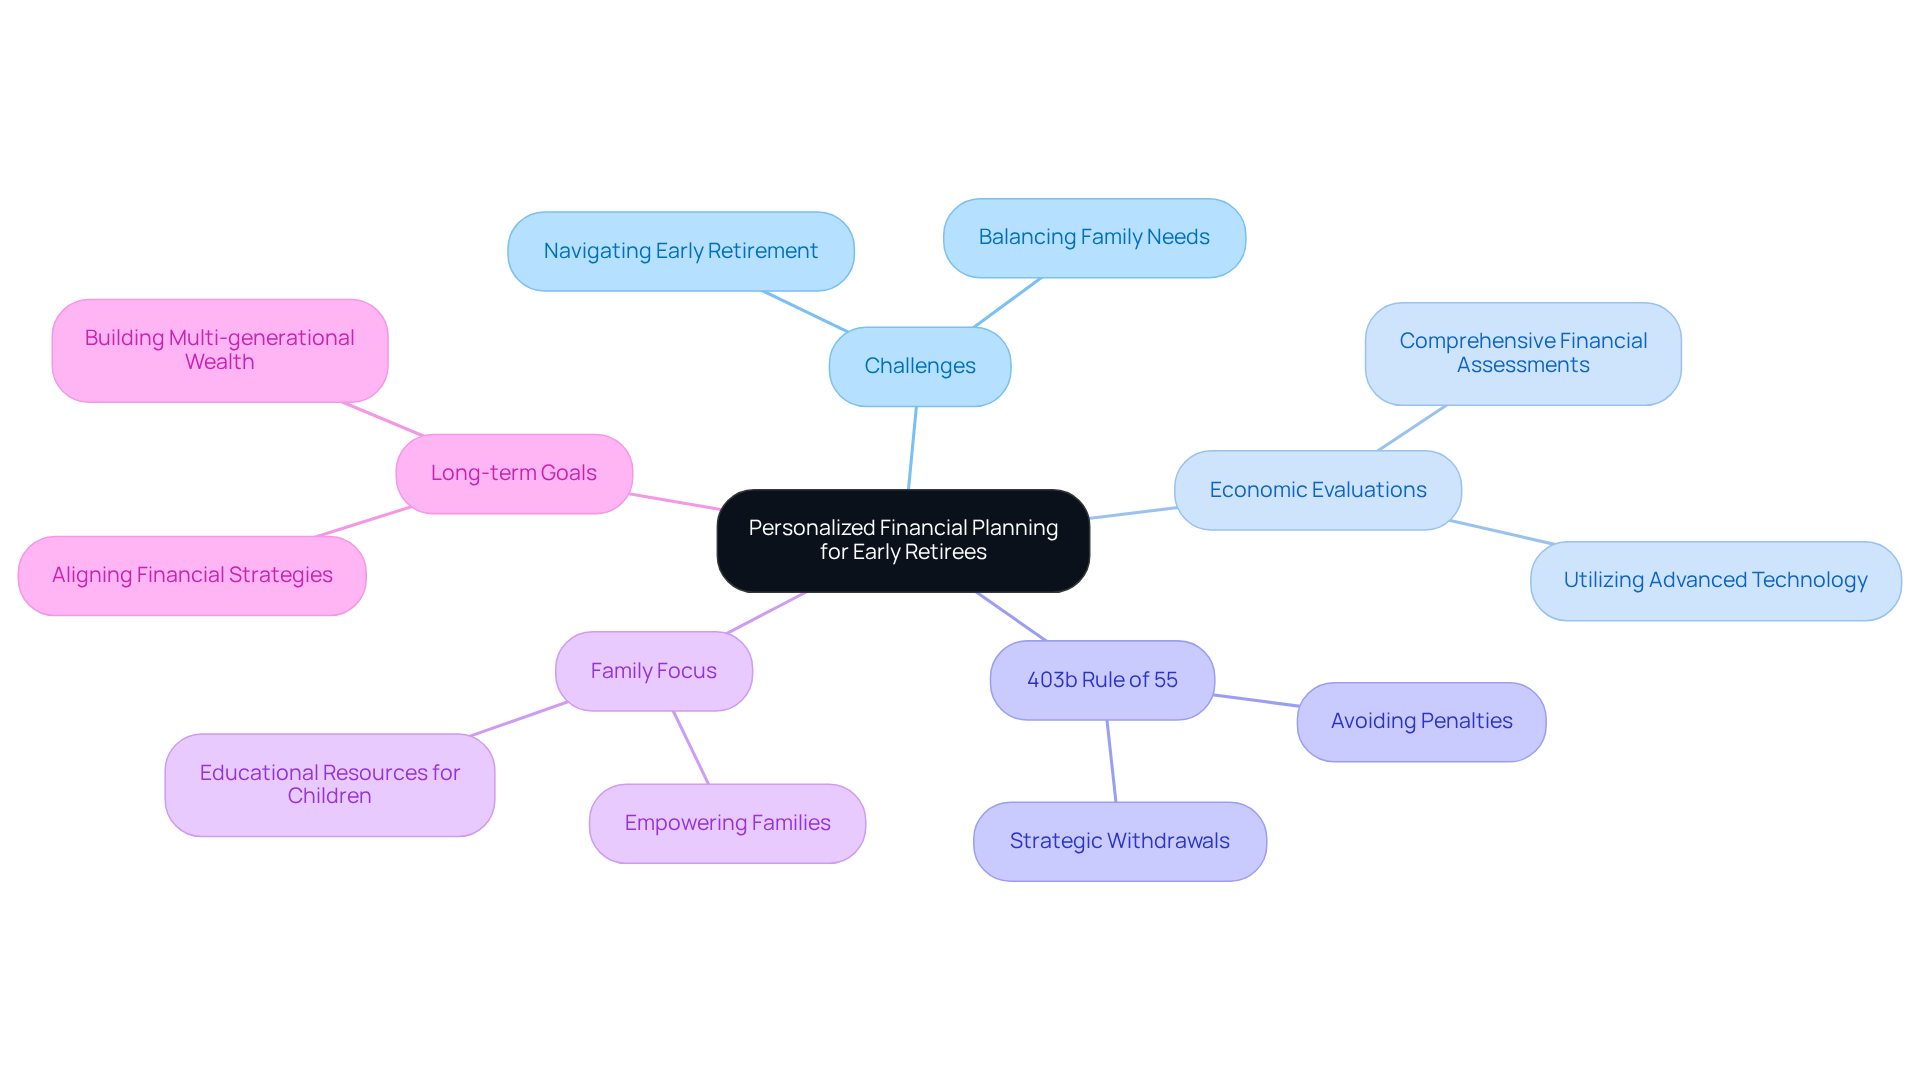
Understanding the 403b Rule of 55: Key Principles and Benefits
Individuals aged 55 or older can take advantage of the valuable opportunity presented by the 403b Rule of 55. The 403b rule of 55 enables you to withdraw funds from your 403b accounts without incurring the usual 10% early withdrawal penalty. According to the 403b rule of 55, this is available if you separate from your employer during or after the year you turn 55. Imagine the relief this can bring, especially for those who leave the workforce early and need access to their retirement savings before reaching 59½.
Understanding the 403b rule of 55 can empower you to make thoughtful financial decisions. By doing so, you can ensure that you have the necessary funds to support your lifestyle while avoiding unnecessary penalties. We’re here for you, helping you navigate these important choices with confidence and care. Together, we can explore the best options for your family’s financial future.
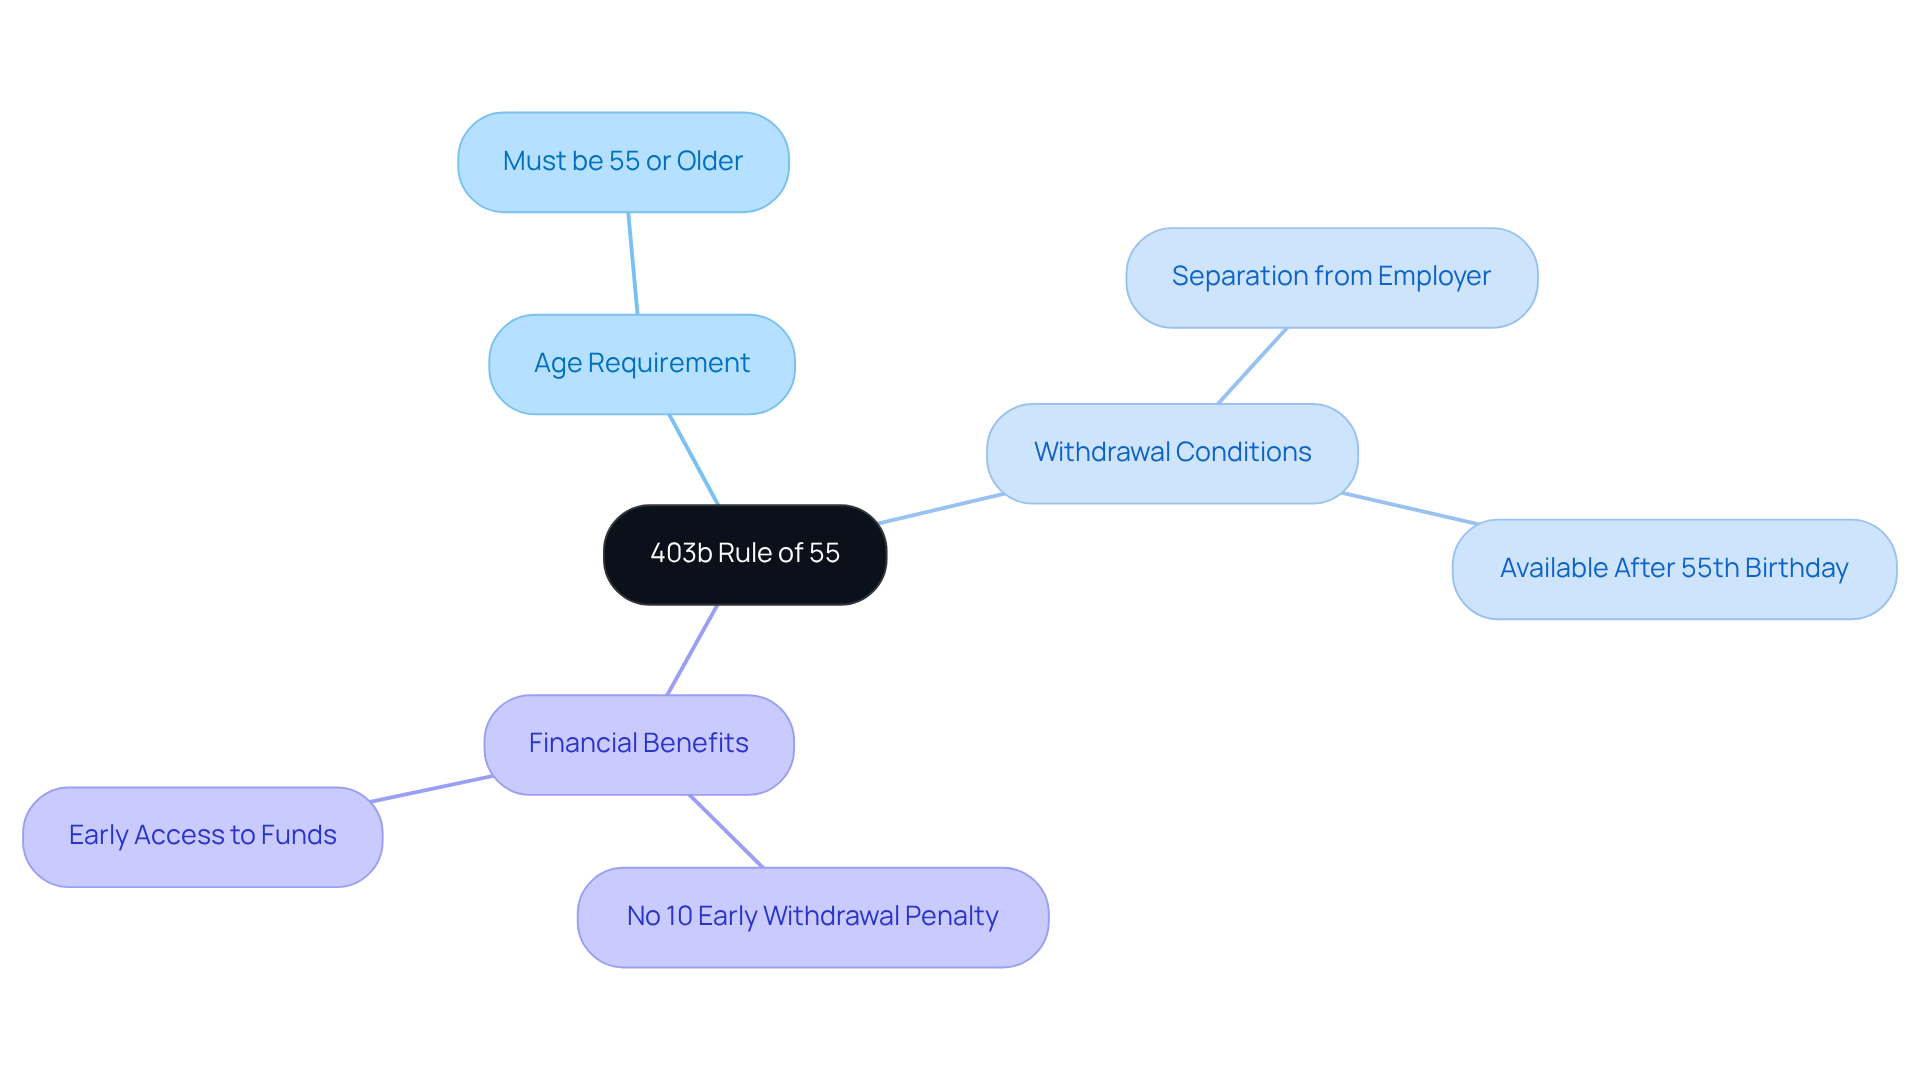
Eligibility Criteria for the 403b Rule of 55: Who Can Benefit?
Navigating your financial future can feel overwhelming, especially when considering retirement options. To qualify for the 403b rule of 55, you must meet specific criteria.
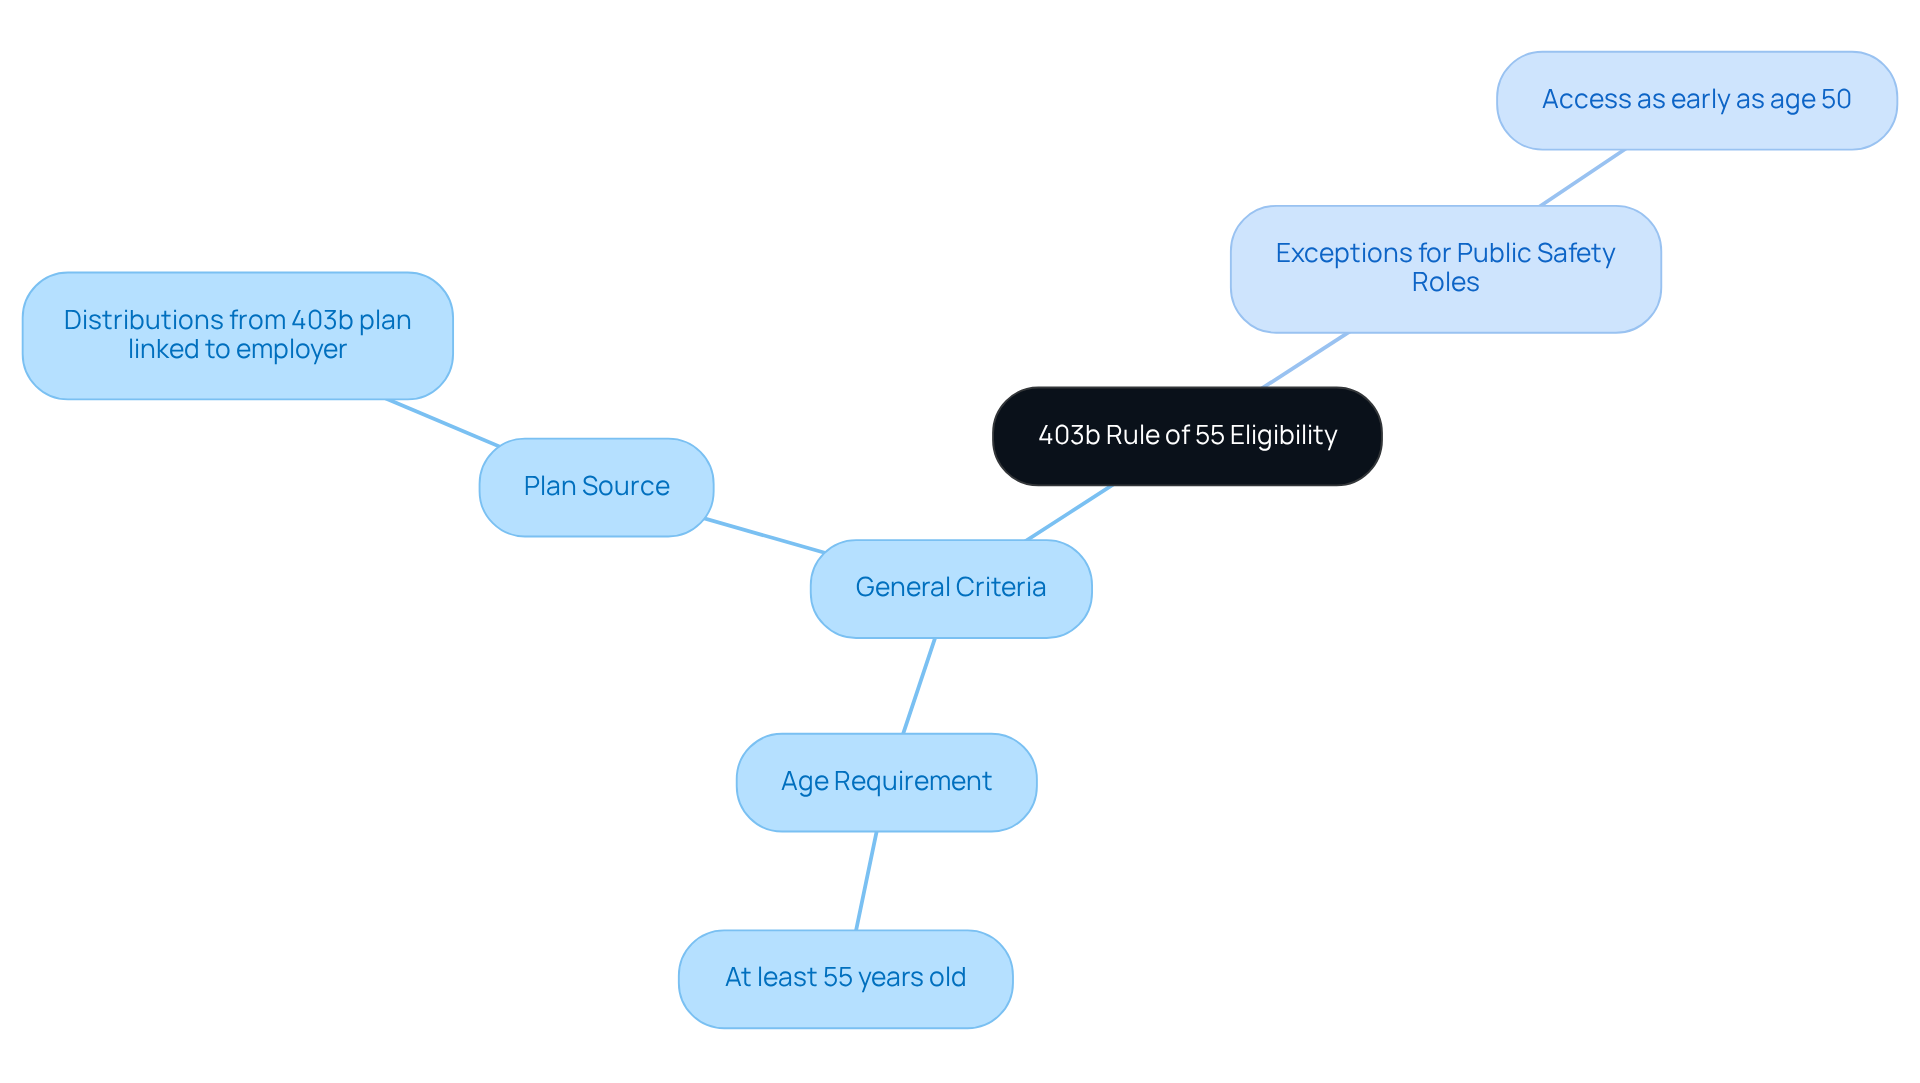
- You must be at least 55 years old during the calendar year you separate from your employer.
- It’s also essential that the distributions come from the 403b plan linked to that employer.
For those in public safety roles, there may be different rules that allow access to funds as early as age 50. Understanding these criteria is vital for anyone looking to access their retirement funds without penalties through the 403b rule of 55. Imagine being able to tap into your savings when you need it most, providing for your family’s needs.
We’re here to support you in this journey. By comprehending these rules, you can make informed decisions that align with your family’s financial goals. Together, we can navigate these options and ensure you have the resources you need for a secure future.
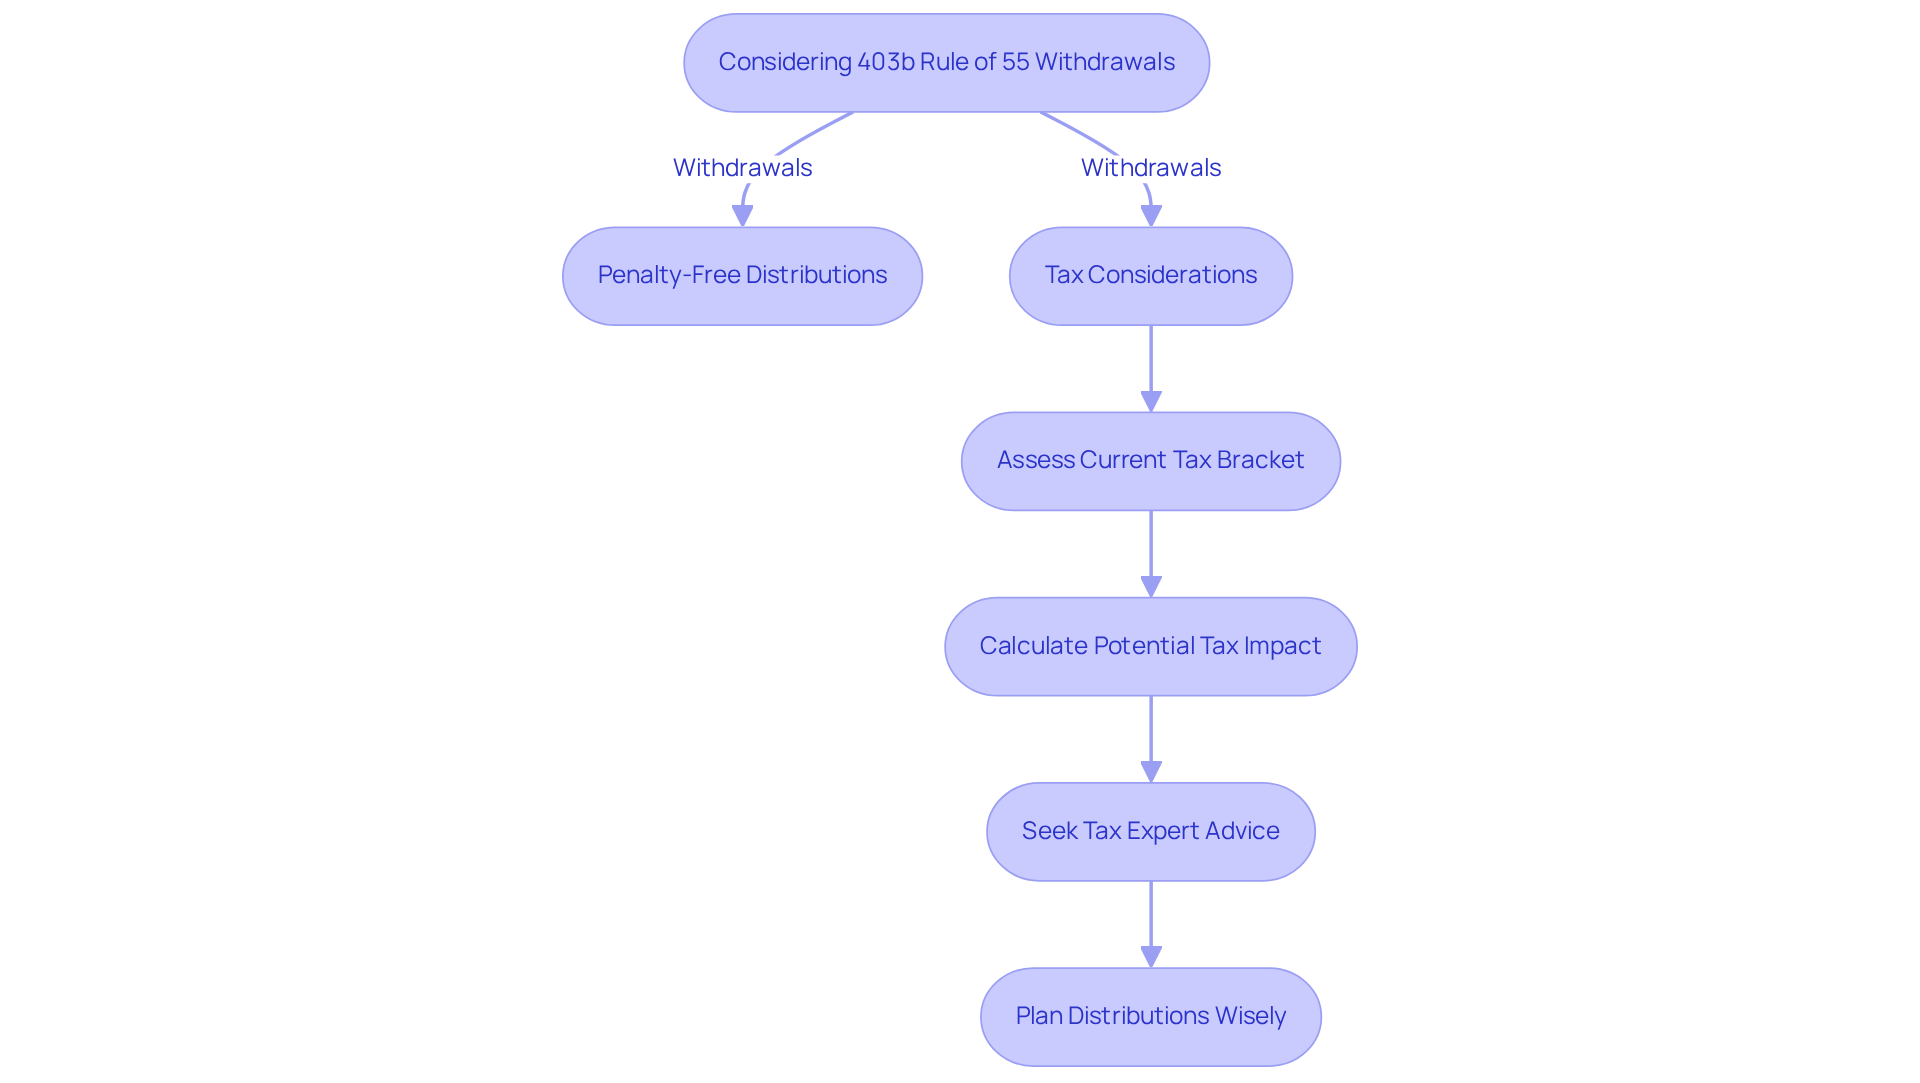
Tax Implications of the 403b Rule of 55 Withdrawals: What to Know
While the 403b rule of 55 permits penalty-free distributions, it’s crucial to recognize that these payments remain subject to ordinary income tax. This means that if you’ve stopped working, you need to consider the tax consequences of your distributions carefully. They could potentially push you into a higher tax bracket, which might not be what you want.
If you’ve retired early, it might be beneficial to think about seeking advice from a tax expert. By planning your distributions thoughtfully, you can reduce your tax obligations while ensuring you have enough resources for your needs. Remember, we’re here for you, and together, we can navigate this journey toward financial security.
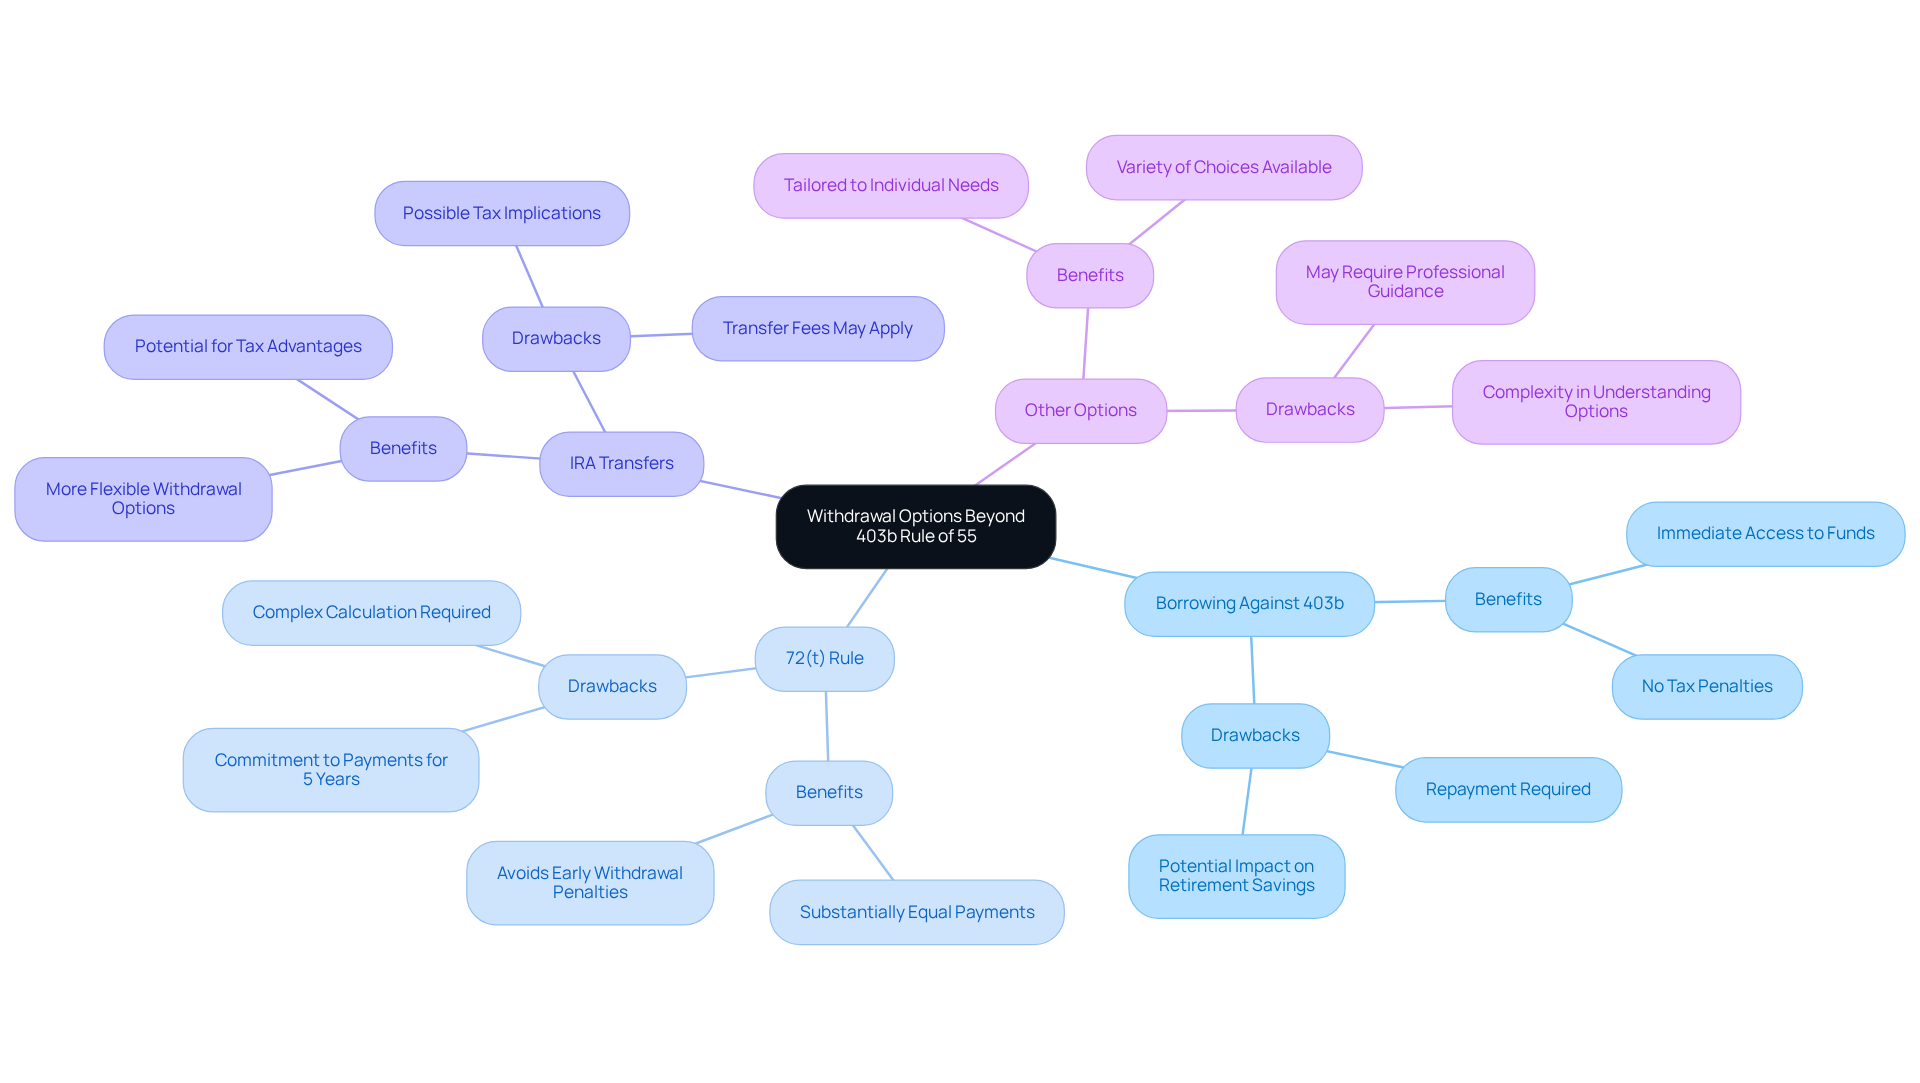
Alternatives to the 403b Rule of 55: Exploring Other Withdrawal Options
For those who have retired, there are several thoughtful options to access retirement funds in addition to the 403b Rule of 55. Imagine borrowing against your 403b plans or utilizing the 72(t) rule for substantially equal periodic payments. You might also consider transferring funds into an IRA, where various distribution rules can come into play. Each of these choices offers its own unique benefits and drawbacks.
It’s important to understand that taking the time to assess these options carefully can help you identify the best fit for your financial circumstances. Remember, we’re here for you as you navigate this journey together.
Long-Term Considerations for Early Retirement: Planning Beyond the 403b Rule of 55
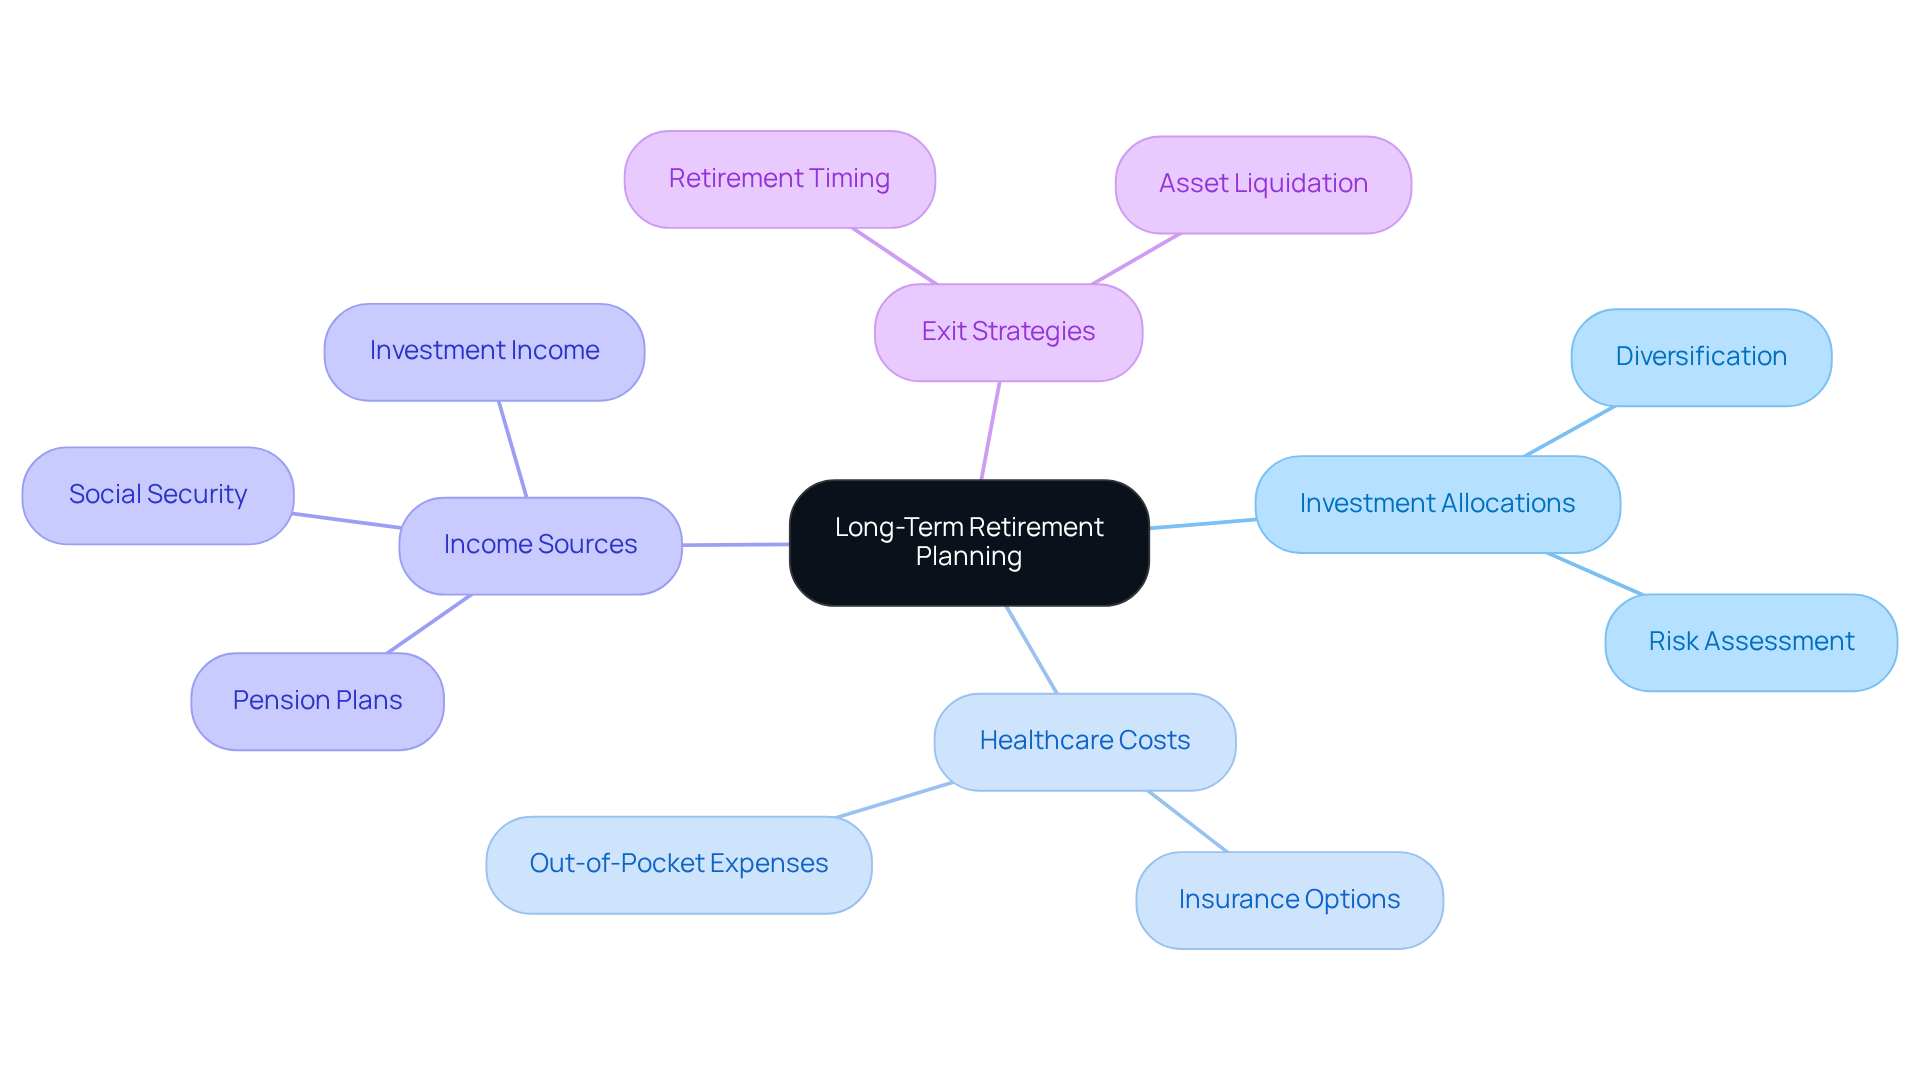
As you embark on the journey of transitioning your career, it’s essential to think about your long-term financial well-being, not just immediate gains. Imagine evaluating your retirement strategy holistically, considering not only your investment allocations but also healthcare costs and potential income sources.
It’s important to understand how your exit strategies might impact your long-term savings and investment growth. Collaborating with a money advisor can be a valuable step, helping you develop a comprehensive plan that addresses both your immediate needs and future aspirations.
Together, we can navigate this journey towards a secure financial future for you and your family.
Seeking Professional Guidance: Navigating the 403b Rule of 55 with Experts
Navigating the complexities of the 403b Rule of 55 can feel overwhelming, but you don’t have to tackle it by yourself. Seeking professional guidance can be a wonderful step towards securing your financial future. Imagine having a caring financial advisor by your side, providing personalized strategies that align with your unique goals and circumstances.
Financial advisors can help you understand the nuances of the 403b rule of 55, assess your eligibility, and develop a comprehensive withdrawal strategy that minimizes taxes while maximizing your retirement income. It’s important to know that you have support available, and interacting with a skilled consultant can empower you to make informed choices that enhance your economic well-being.
Together, we can navigate this journey, ensuring that your financial decisions reflect your family’s values and priorities. Remember, you’re not alone in this process—help is just a conversation away.
Common Pitfalls of the 403b Rule of 55: What to Avoid
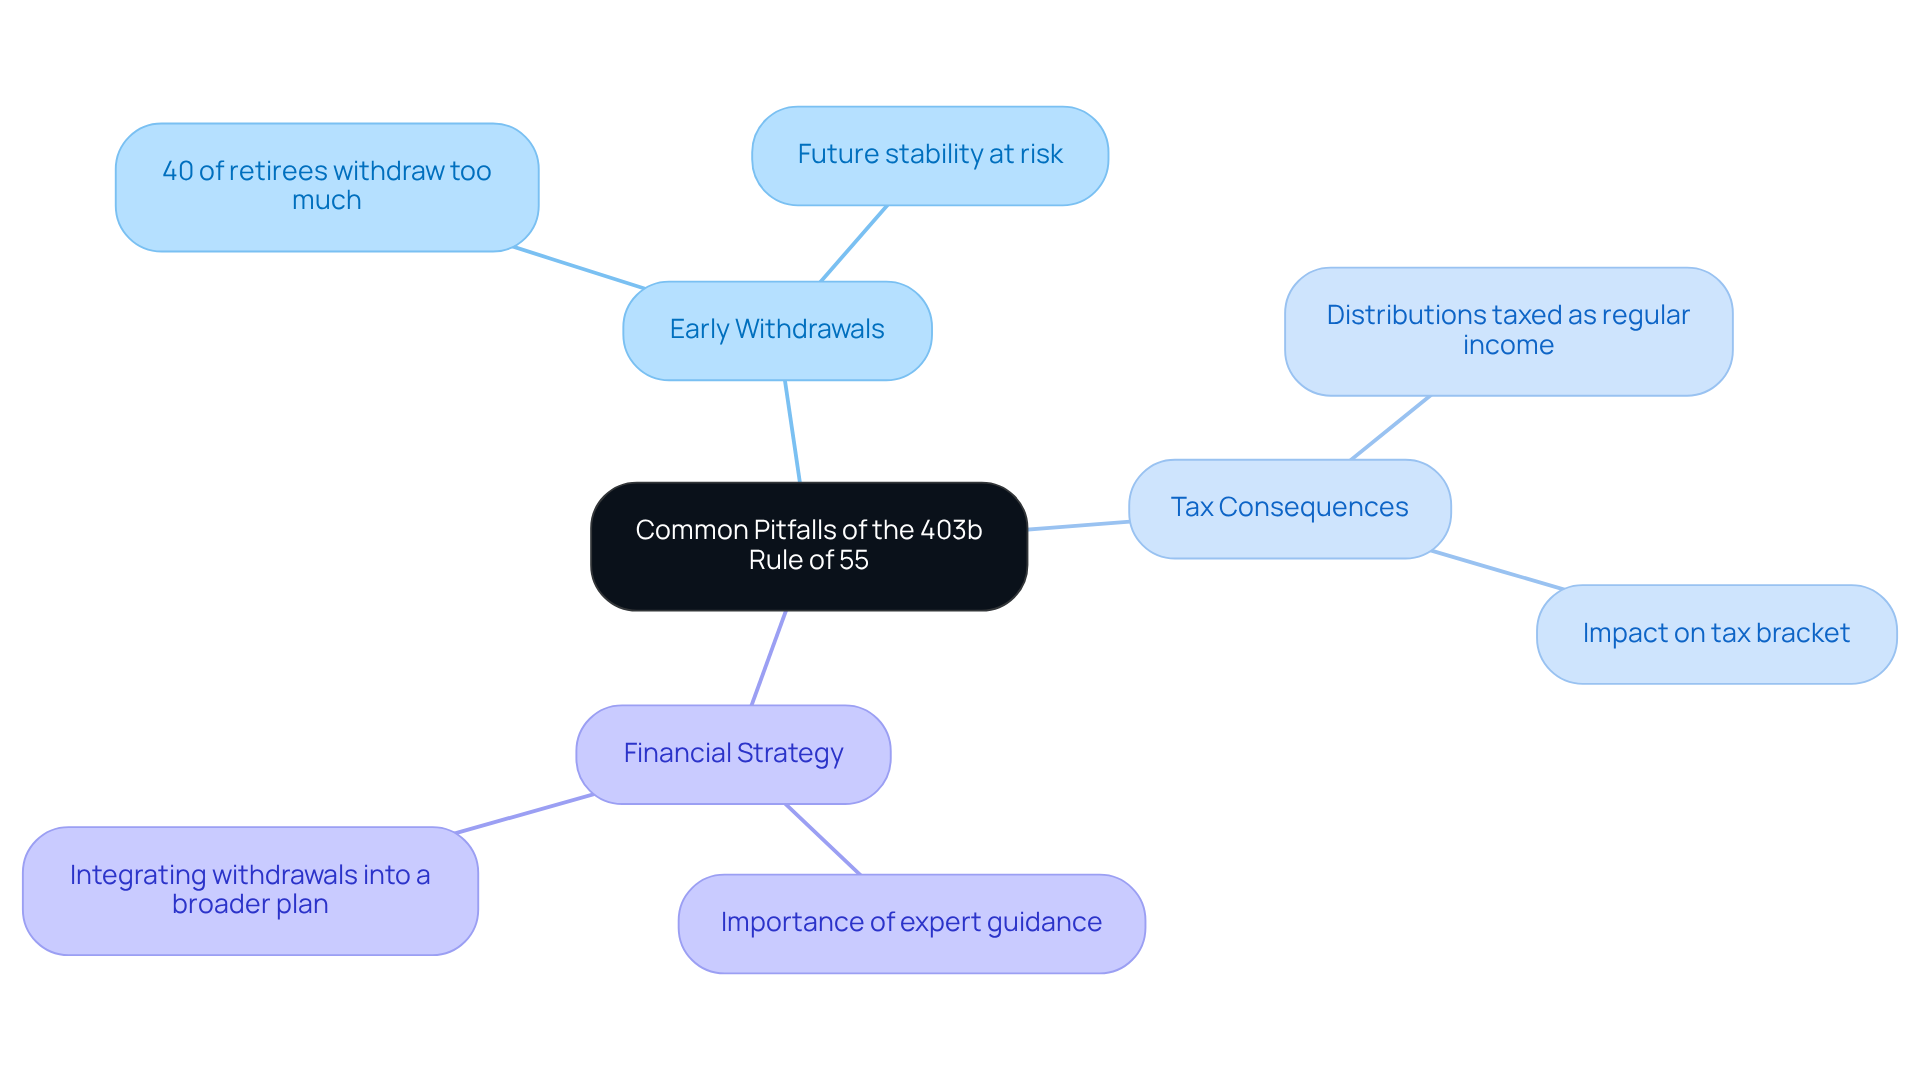
The 403b Rule of 55 provides significant opportunities for individuals who are leaving the workforce early, yet it also carries risks that may affect your financial well-being. Imagine withdrawing too soon—this common mistake can dramatically reduce your retirement savings and affect your future stability. In fact, statistics show that around 40% of retirees take out more than they should, often leading to regret later on. It’s crucial to consider the tax consequences of these distributions, as neglecting this aspect can result in unexpected tax burdens that strain your finances.
As money advisor Alvin Carlos wisely notes, “Although the 10% penalty is removed, any distributions are taxed as regular income, possibly influencing your tax bracket.” It’s important to remember that relying solely on the 403b rule of 55 without integrating it into a broader financial strategy can be risky. Working alongside a money advisor can provide invaluable support, helping you navigate the complexities of fund distributions and avoid common pitfalls.
For instance, many individuals overlook how their withdrawals may affect their tax brackets, which can lead to higher tax rates on their income. By embracing a comprehensive approach and seeking expert guidance, you can better secure your financial future while enjoying the benefits of early retirement. Together, we can navigate this journey, ensuring that your family’s financial goals are met with care and understanding.
Preparing to Use the 403b Rule of 55: Essential Steps for Early Retirees
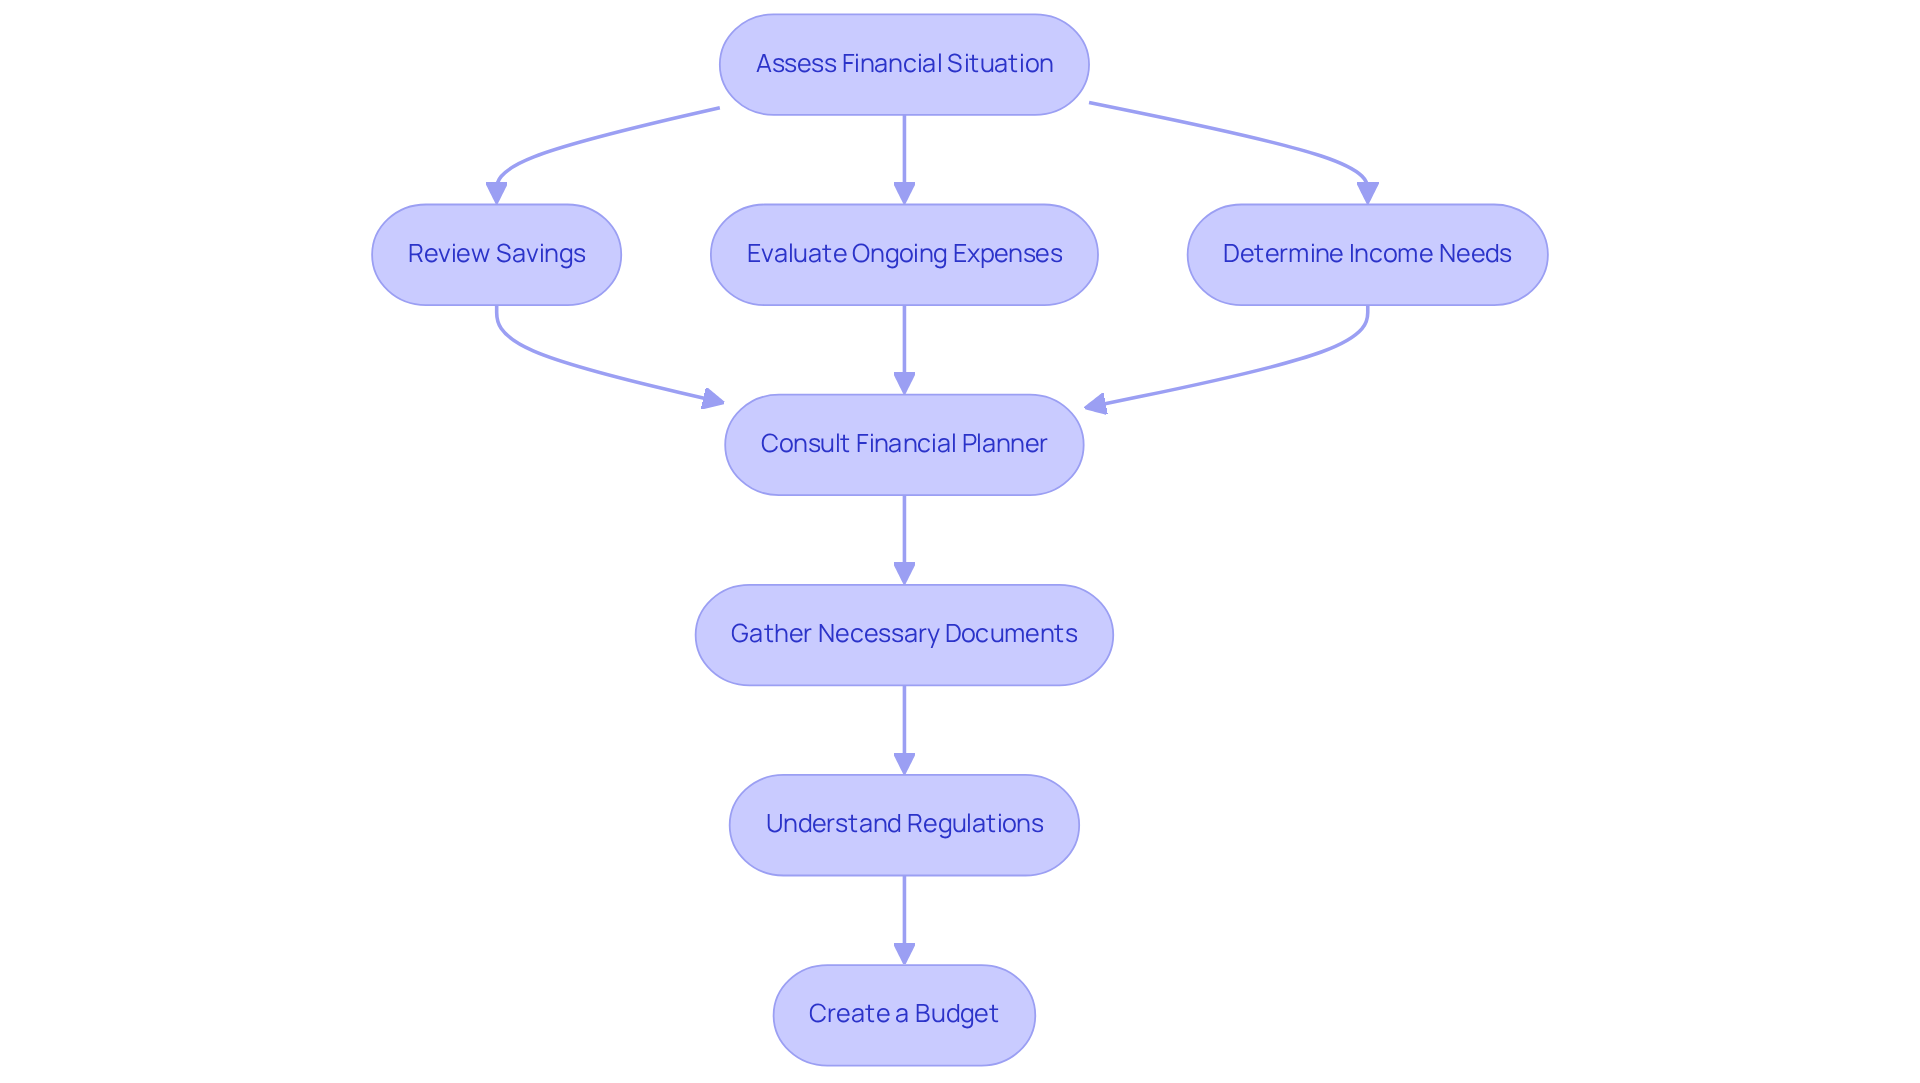
Navigating the 403b Rule of 55 can feel overwhelming, but with the right steps, early retirees can achieve peace of mind. Start by taking a close look at your financial situation. Consider your:
- Savings for the future
- Ongoing expenses
- Income needs
It’s wise to consult with a financial planner who can help craft a personalized withdrawal strategy that aligns with your long-term goals.
Remember, once you reach age 59 ½, you can withdraw from a 401(k) without facing penalties. This is a crucial point for those of you thinking about your financial future. If you’ve recently retired, gather all necessary documents related to your 403b plans. Understanding the specific regulations governing your accounts is vital, especially since the 403b rule of 55 only applies to 401(k) and 403(b) plans from your most recent employer.
Creating a budget that reflects your new financial reality is essential for a smooth transition into early retirement. Keep in mind that distributions under the 403b rule of 55 will be subject to income taxes on the amounts withdrawn from your 401(k) or 403(b). Together, we can navigate this journey, ensuring that your family’s financial future remains bright.
Key Takeaways on the 403b Rule of 55: Essential Facts for Early Retirees
Individuals who have stepped away from the workforce early can take advantage of the 403b Rule of 55 to access their funds without incurring penalties. Imagine if you could tap into your savings when you need them most, allowing you to support your family during crucial times. It’s essential to understand that eligibility for the 403b rule of 55 requires being 55 or older during the year of separation from employment. While withdrawals are subject to ordinary income tax, which may elevate your family’s tax bracket and lead to larger tax bills, careful planning can help you navigate these waters smoothly.
Collaborating with a financial advisor can be a comforting step for retirees, guiding them in managing this rule effectively. Together, you can make informed choices that enhance your financial well-being during your later years. Statistics reveal that 62% of working households in the U.S. lack savings for later life, underscoring the importance of education and guidance. As Michael Rusinak, Vice President of Fidelity Financial Solutions, wisely notes, ‘If you’ve conducted the analysis to determine that you can have a successful, strong, and resilient plan with withdrawal at age 55, then the 403b rule of 55 allows for earlier access to certain assets to assist in funding your lifestyle.’
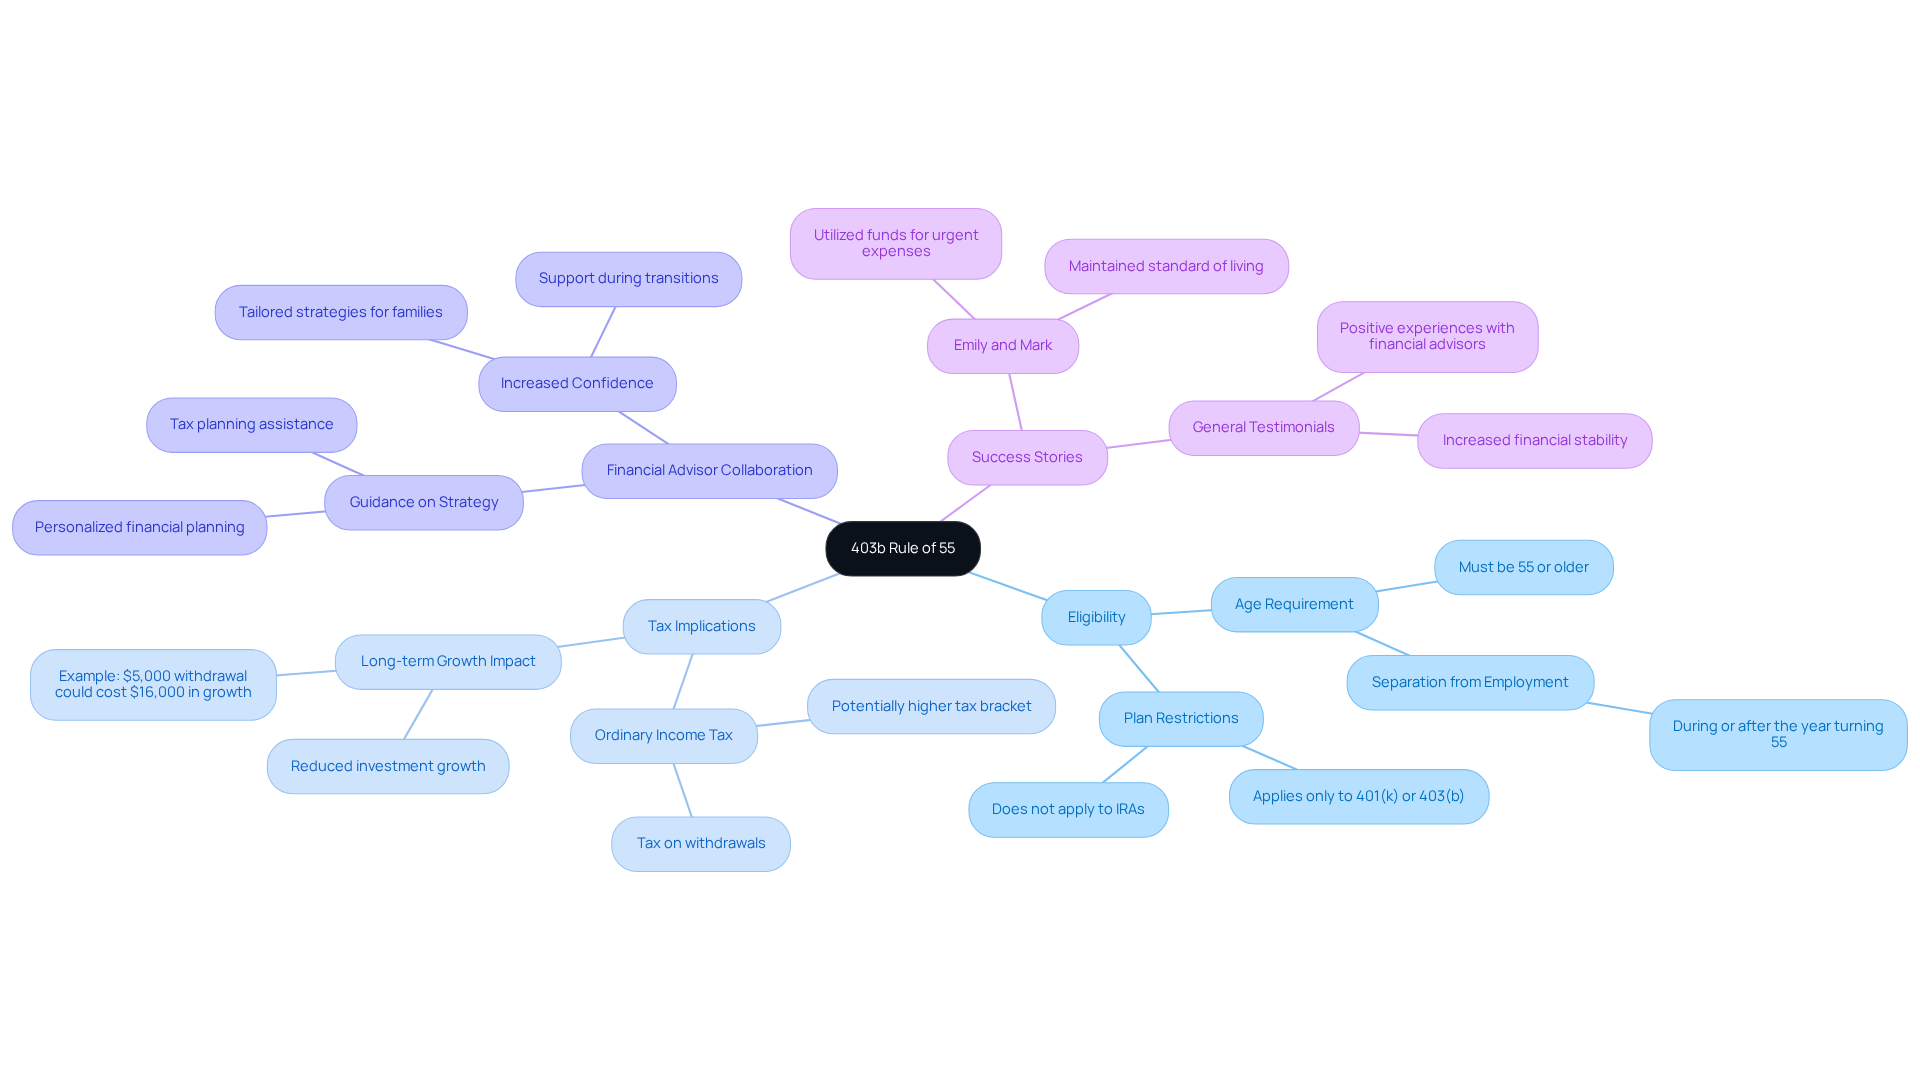
Consider the success stories of others, like Emily and Mark, who utilized this rule to enhance their economic flexibility during critical transitions. Their experience can inspire you to envision a well-devised strategy that maximizes the benefits of the 403b rule of 55 while ensuring your family’s future financial stability. Remember, we’re here for you, and together, we can navigate this journey toward a secure and fulfilling financial future.
Conclusion
Understanding the 403b Rule of 55 is essential for early retirees who wish to access their retirement funds without facing penalties. This rule offers a unique opportunity for individuals aged 55 and older to withdraw from their 403b accounts, providing financial flexibility during a significant transition in life. By grasping the intricacies of this rule, retirees can make informed decisions that align with their long-term financial goals while ensuring their family’s well-being.
Throughout this article, we’ve shared key insights regarding:
- Eligibility criteria
- Tax implications
- Alternative withdrawal options that complement the 403b Rule of 55
It’s important to understand the significance of careful planning and the potential pitfalls associated with premature withdrawals. Imagine collaborating with financial advisors who can empower you to navigate these complexities effectively, ensuring a strategy that maximizes benefits while minimizing risks.
Ultimately, the 403b Rule of 55 presents a valuable resource for early retirees aiming to secure their financial future. By leveraging this rule wisely and seeking professional guidance, you can create a sustainable financial plan that not only meets your immediate needs but also supports your long-term aspirations. Together, we can navigate this journey, taking proactive steps today that lead to a more confident and fulfilling retirement experience.
Frequently Asked Questions
What services does Bright Advisers offer for early retirees?
Bright Advisers provides personalized financial planning specifically designed for early retirees, especially those with young children. Their services include comprehensive evaluations of clients’ economic situations and strategies that align with long-term financial goals while prioritizing family well-being.
What is the 403b Rule of 55?
The 403b Rule of 55 allows individuals aged 55 or older to withdraw funds from their 403b accounts without incurring the usual 10% early withdrawal penalty if they separate from their employer during or after the year they turn 55.
Who is eligible for the 403b Rule of 55?
To qualify for the 403b Rule of 55, you must be at least 55 years old during the calendar year you separate from your employer, and the distributions must come from the 403b plan associated with that employer. Additionally, public safety workers may have different rules allowing access to funds as early as age 50.
How can the 403b Rule of 55 benefit early retirees?
The 403b Rule of 55 benefits early retirees by allowing them to access their retirement savings without penalties, providing necessary funds to support their lifestyle before reaching the age of 59½.
How does Bright Advisers help families navigate financial planning?
Bright Advisers helps families navigate financial planning by empowering them with knowledge about the 403b Rule of 55 and other financial strategies, ensuring that their financial plans reflect their family values and shared goals. They offer support throughout the planning process to enhance financial stability during retirement.
List of Sources
- Bright Advisers: Personalized Financial Planning for Early Retirees
- Top 150 Financial Planning Quotes [2025] (https://digitaldefynd.com/IQ/financial-planning-quotes)
- Common Pitfalls of the 403b Rule of 55: What to Avoid
- What Is The Rule Of 55? | Advantages of Retiring at 55 Using Rule of 55 (https://districtcapitalmanagement.com/rule-of-55)
- Understanding the “Rule of 55” for Early Retirement (https://savantwealth.com/savant-views-news/article/rule-of-55-early-retirement)
- More Americans are drawing from retirement savings early. Why financial pros say that’s a recipe for disaster. (https://aol.com/more-americans-drawing-retirement-savings-093002617.html)
- Early Retirement Distributions: 72t and Rule of 55 | RGWM Insights (https://rgwealth.com/insights/early-retirement-72t-rule-of-55)
- Preparing to Use the 403b Rule of 55: Essential Steps for Early Retirees
- Understanding the “Rule of 55” for Early Retirement (https://savantwealth.com/savant-views-news/article/rule-of-55-early-retirement)
- What Is the Rule of 55? How It Works for Early Retirement | SoFi (https://sofi.com/learn/content/rule-of-55-retirement)
- The Rule of 55: What It Is and How It Works (https://annuityexpertadvice.com/what-is-the-rule-of-55)
- Key Takeaways on the 403b Rule of 55: Essential Facts for Early Retirees
- 7 Key Insights on Rule of 55 401k Withdrawal for Young Families – Bright Advisers (https://brightadvisers.com/7-key-insights-on-rule-of-55-401-k-withdrawal-for-young-families)
- What is the Rule of 55? | Fidelity (https://fidelity.com/learning-center/personal-finance/what-is-rule-of-55)
- Rule of 55: An early retirement provision for your 401(k) or 403(b) (https://thrivent.com/insights/retirement-planning/rule-of-55-an-early-retirement-provision-for-your-401k-or-403b)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Retirement & Employee Benefits for high-income W-2 families at Bright Advisers.
Keep reading