

Overview
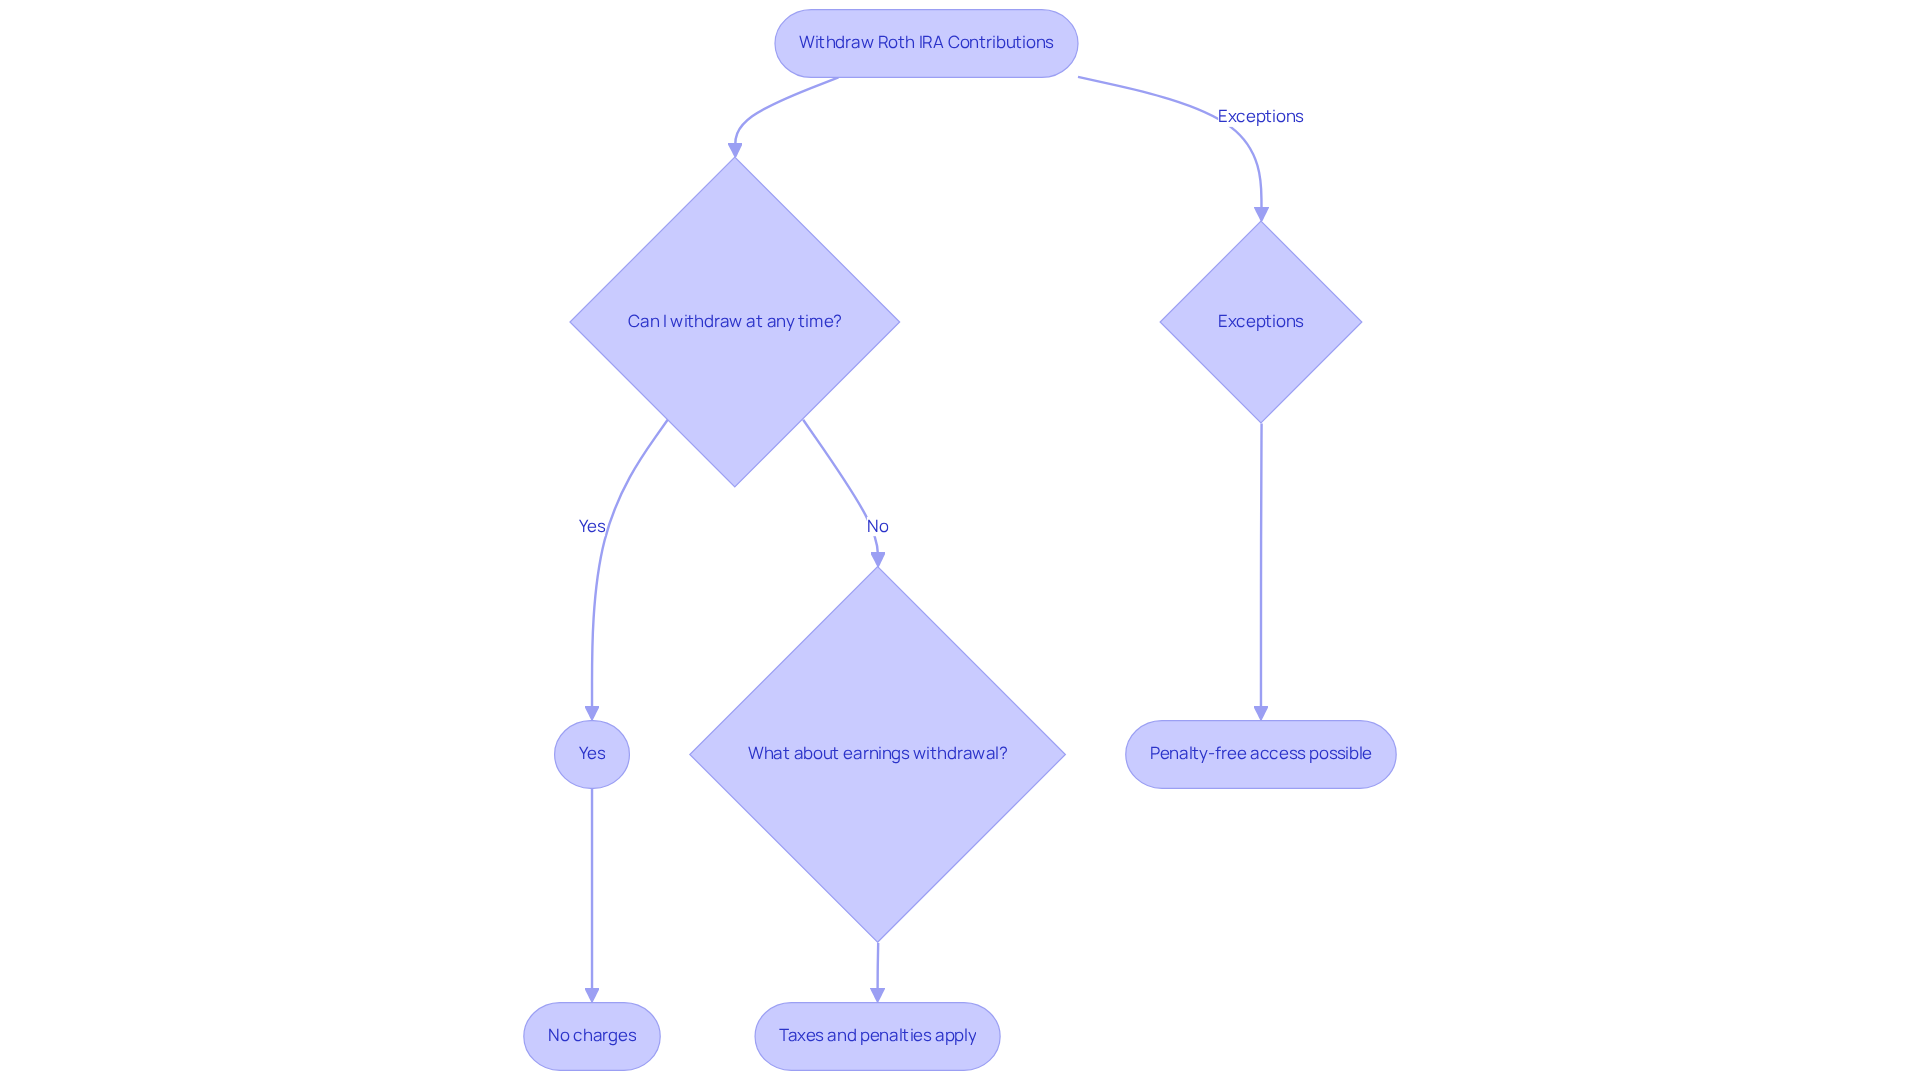
Have you ever wondered if you can access your Roth IRA contributions without penalties? The good news is that you can! Contributions to a Roth IRA can be withdrawn at any time, providing you with the freedom to manage your finances as needed. However, it’s essential to be aware that while you can access your contributions freely, the earnings might come with taxes and penalties if certain conditions aren’t met.
It’s important to understand the IRS guidelines surrounding these withdrawal rules. Many families face common pitfalls, and being informed about exceptions can lead to penalty-free access to your earnings. This knowledge is crucial for effective financial planning, especially when you’re navigating the many responsibilities of family life.
Imagine if you could confidently manage your family’s financial future, knowing that you have options available to you. Understanding these regulations not only empowers you but also helps you make informed decisions that align with your family’s values and goals. Remember, we’re here for you, ready to support you on this journey toward financial security.
Key Highlights:
- Bright Advisers offers personalised financial planning for young families, emphasising Roth IRA contributions and withdrawals.
- Contributions to a Roth IRA can be withdrawn at any time without penalties, but earnings may incur taxes if withdrawn before age 59½ or before the account has been active for five years.
- Nearly 49% of households mistakenly withdraw earnings without realising penalties, highlighting the need to understand IRS guidelines.
- Certain circumstances allow for penalty-free access to Roth IRA earnings, including first-time home purchases, disability, death of the account holder, and specific medical expenses.
- The article contrasts Roth IRAs with Traditional IRAs, noting that Roth IRA contributions can be accessed without penalties, while Traditional IRAs impose restrictions.
- Age affects withdrawal capabilities, with individuals over 59½ able to withdraw contributions and earnings without penalties, provided the account has been open for five years.
- Bright Advisers encourages families to develop a withdrawal strategy in collaboration with financial advisors to align with their long-term goals.
Introduction
Understanding the intricacies of Roth IRA contributions is essential for families who want to secure their financial future. Imagine having the ability to withdraw contributions at any time without penalties—this unique flexibility can be a lifesaver during unexpected financial challenges.
However, it’s important to recognize the potential pitfalls surrounding earnings withdrawals and the associated tax implications.
- How can families navigate these rules effectively?
- What strategies can be employed to maximize the benefits of their Roth IRA while avoiding costly mistakes?
Together, we can explore these questions. This article delves into the key insights surrounding Roth IRA contribution withdrawals, providing essential guidance for families looking to make informed financial decisions. We’re here for you as you navigate this journey.
Bright Advisers: Personalized Financial Planning for Roth IRA Contributions
At Bright Advisers, we understand the unique challenges young families face when planning for the future. Our tailored approach to financial planning addresses questions like ‘can I withdraw contributions from a Roth IRA,’ ensuring that your family’s needs are at the forefront. Imagine having a partner who thoroughly assesses your economic situation and future goals, identifying the best contribution levels and strategies that fit your personal circumstances.
This customized support empowers families to optimize their retirement savings while managing immediate financial responsibilities. It’s important to understand that we are here to help you navigate these decisions, providing peace of mind as you focus on what truly matters—your loved ones.
In addition to retirement planning, Bright Advisers offers estate planning and integrated tax planning services, creating a comprehensive monetary strategy that secures not only your financial future but also that of your children. Together, we can foster a legacy of financial stability and growth, ensuring that your family thrives for generations to come.
We invite you to reach out and explore how we can assist you on this journey. With Bright Advisers, you’re not just a client; you’re part of a community that cares deeply about your family’s well-being.
Understanding Roth IRA Contribution Withdrawals: Key Rules and Guidelines
Effectively managing your Roth IRA deposits is crucial, and understanding the essential rules for withdrawals can make a significant difference. You may wonder, can I withdraw contributions from a Roth IRA at any time without penalties, since they come from after-tax dollars? However, it’s easy to overlook the important distinction between your contributions and the earnings on those contributions, which can lead to unexpected tax consequences. Imagine this: while you can withdraw contributions from a Roth IRA freely, the question of ‘can I withdraw contributions from a Roth IRA’ must be considered carefully, as any earnings taken out before age 59½ or before the account has been active for five years may incur taxes and a 10% penalty, unless certain exceptions apply.
Statistics reveal that nearly 49% of households mistakenly withdraw earnings without realizing the penalties involved, potentially jeopardizing their long-term financial goals. To avoid such pitfalls, it’s vital to familiarize yourself with IRS guidelines. For instance, qualified distributions—those made after age 59½ and meeting the five-year rule—allow for tax-free access to both contributions and earnings.
Consider how families navigate these complexities. One family successfully funded their child’s education through their Roth IRA by following the guidelines for qualified higher education expenses, thus avoiding penalties. It’s also important to keep track of your contribution dates to prevent any tax surprises. Remember, penalty-free withdrawals are available for certain circumstances, such as qualified birth or adoption expenses. By understanding the rules and keeping detailed records of your contributions, you can determine when and how can I withdraw contributions from Roth IRA to make informed decisions that align with your family’s financial goals while adhering to IRS regulations.
Furthermore, understanding the IRS ordering rules for withdrawals is key. Deposits are taken out first, followed by conversions, and then earnings. Together, we can navigate this journey, ensuring your family’s financial future is secure.
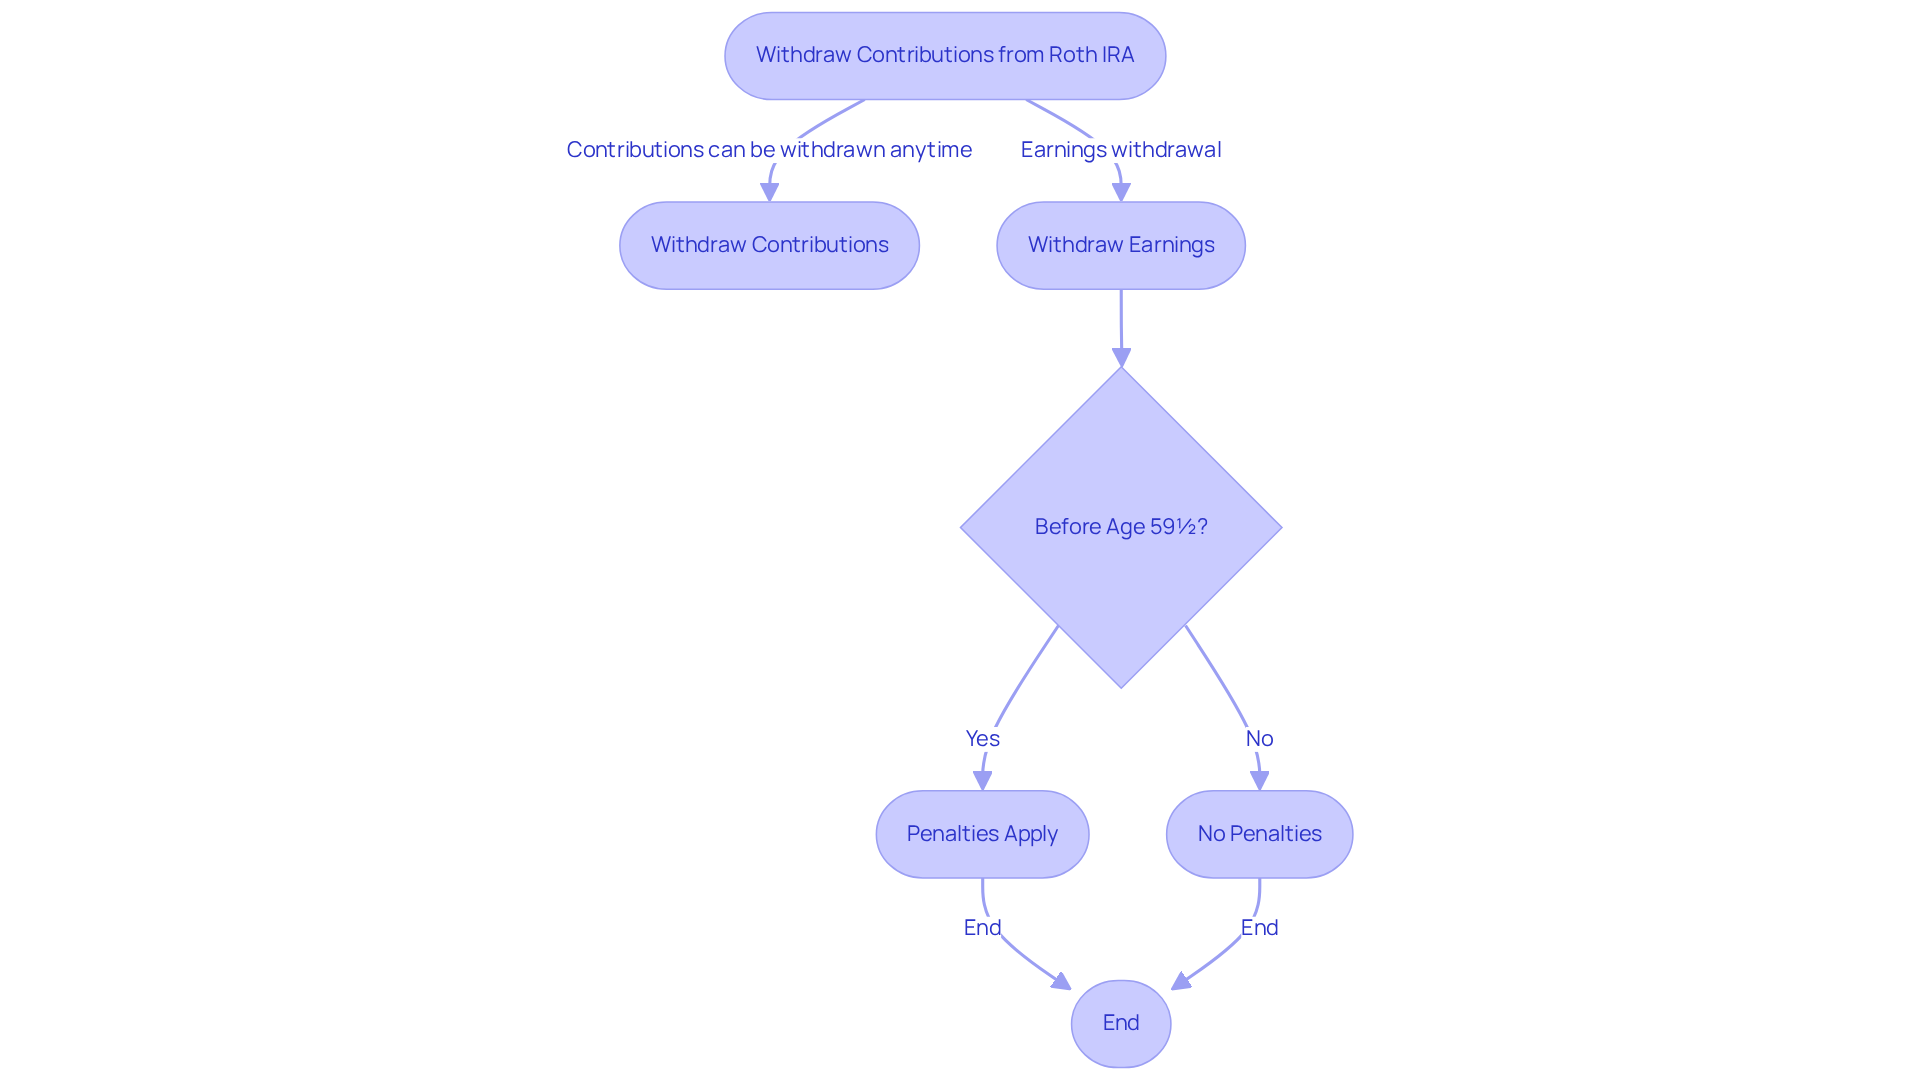
Withdrawal Conditions: When Can You Access Your Roth IRA Contributions Penalty-Free?
The question of whether I can withdraw contributions from a Roth IRA at any time without incurring penalties is answered positively, as long as only the contributions are accessed and not the earnings. Imagine facing unforeseen costs or crises—this feature is particularly beneficial for young households. For instance, if a household contributes $7,000 in 2024, they may wonder, can I withdraw contributions from Roth IRA in 2025 due to a monetary setback without encountering any tax consequences. It’s important to understand that maintaining detailed records of inputs is essential to ensure that only the principal is withdrawn, thereby avoiding taxes or penalties on any earnings.
In 2025, individuals can contribute up to $7,000 annually to a Roth IRA, with an additional $1,000 allowed for those aged 50 and over. This further enhances the potential for tax-free growth and flexibility. This accessibility enables households to utilize their savings effectively while planning for future financial needs. Remember, we’re here for you—together, we can navigate this journey toward financial security.
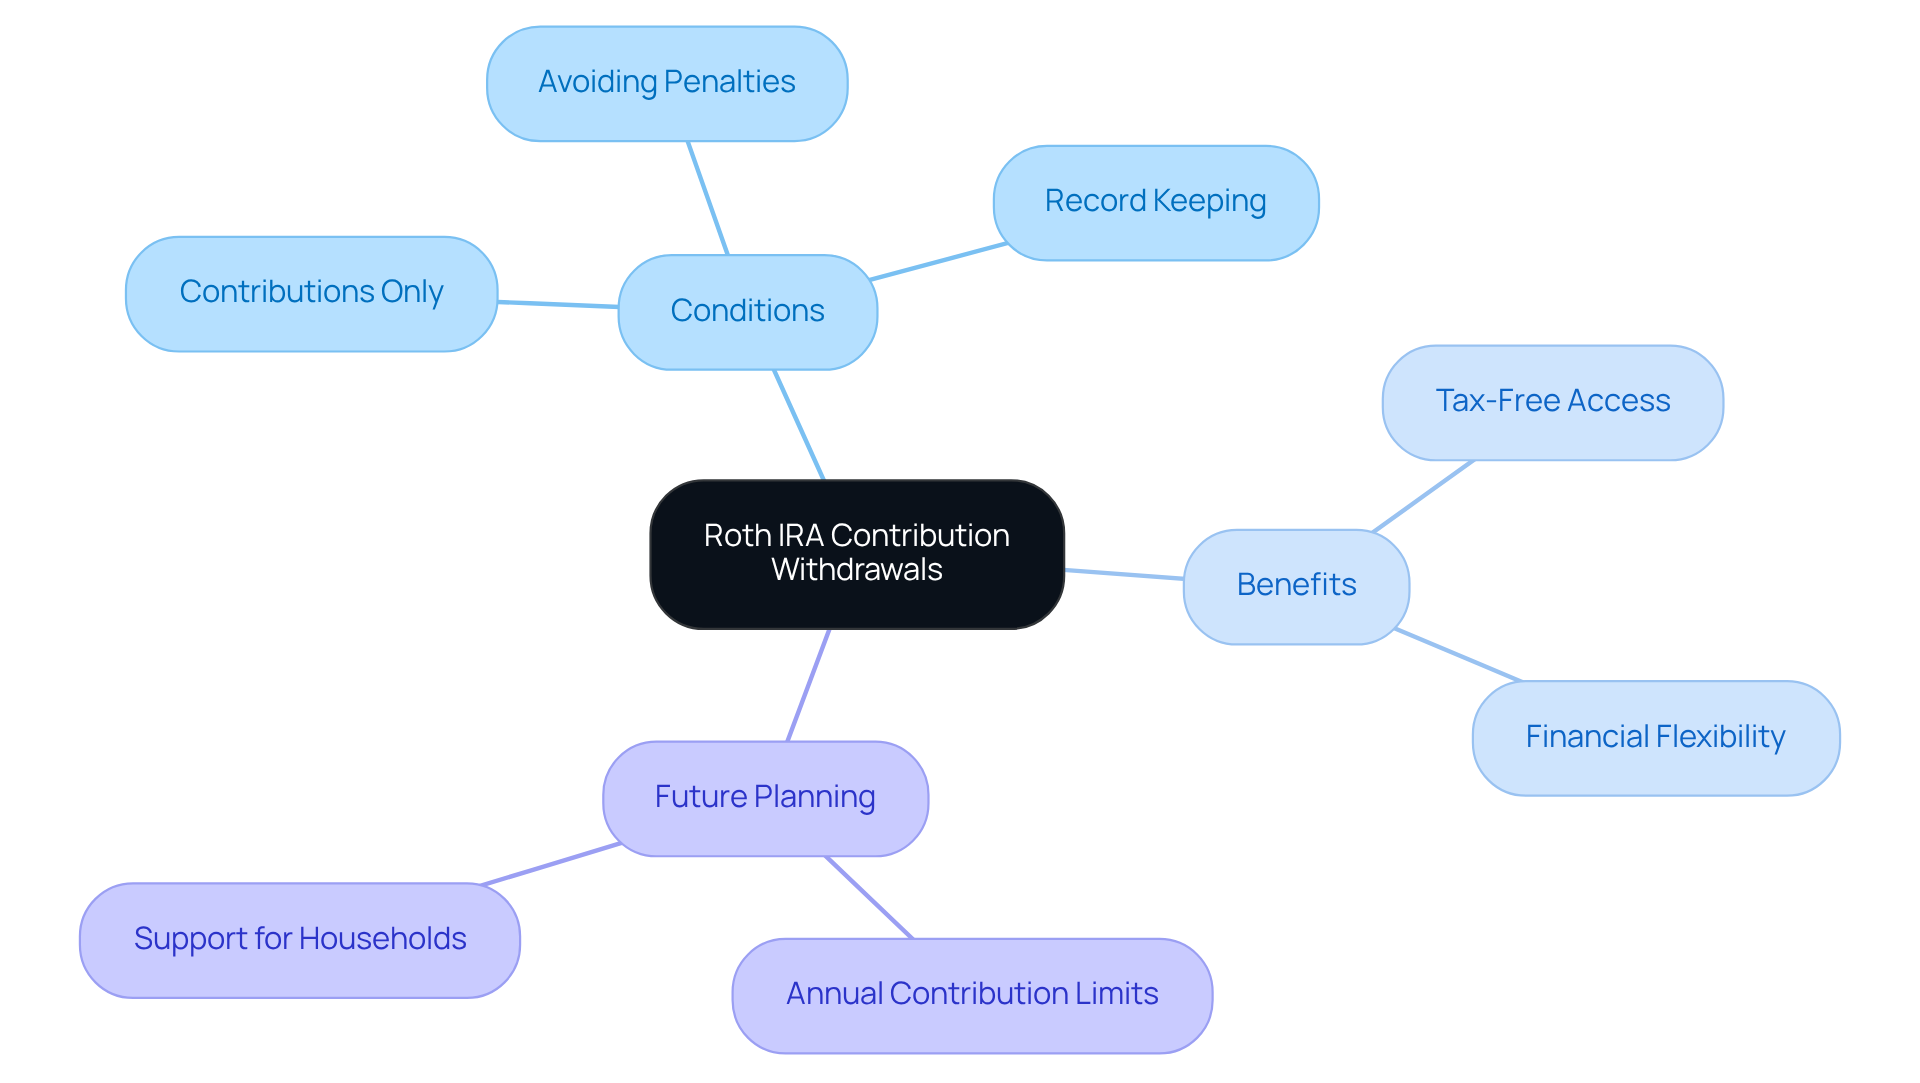
Tax Implications of Withdrawing Roth IRA Contributions: What You Need to Know
When considering whether I can withdraw contributions from a Roth IRA, it’s essential for families to know that these withdrawals are generally tax-free since contributions are made with after-tax dollars. However, imagine if you needed to access your earnings before the account has been active for five years or before you reach age 59½. In such cases, those earnings might be subject to taxes and fees, which can catch you off guard. Understanding these tax implications is crucial for effective financial planning, helping you avoid unexpected costs. Remember, we’re here for you as you navigate this journey.
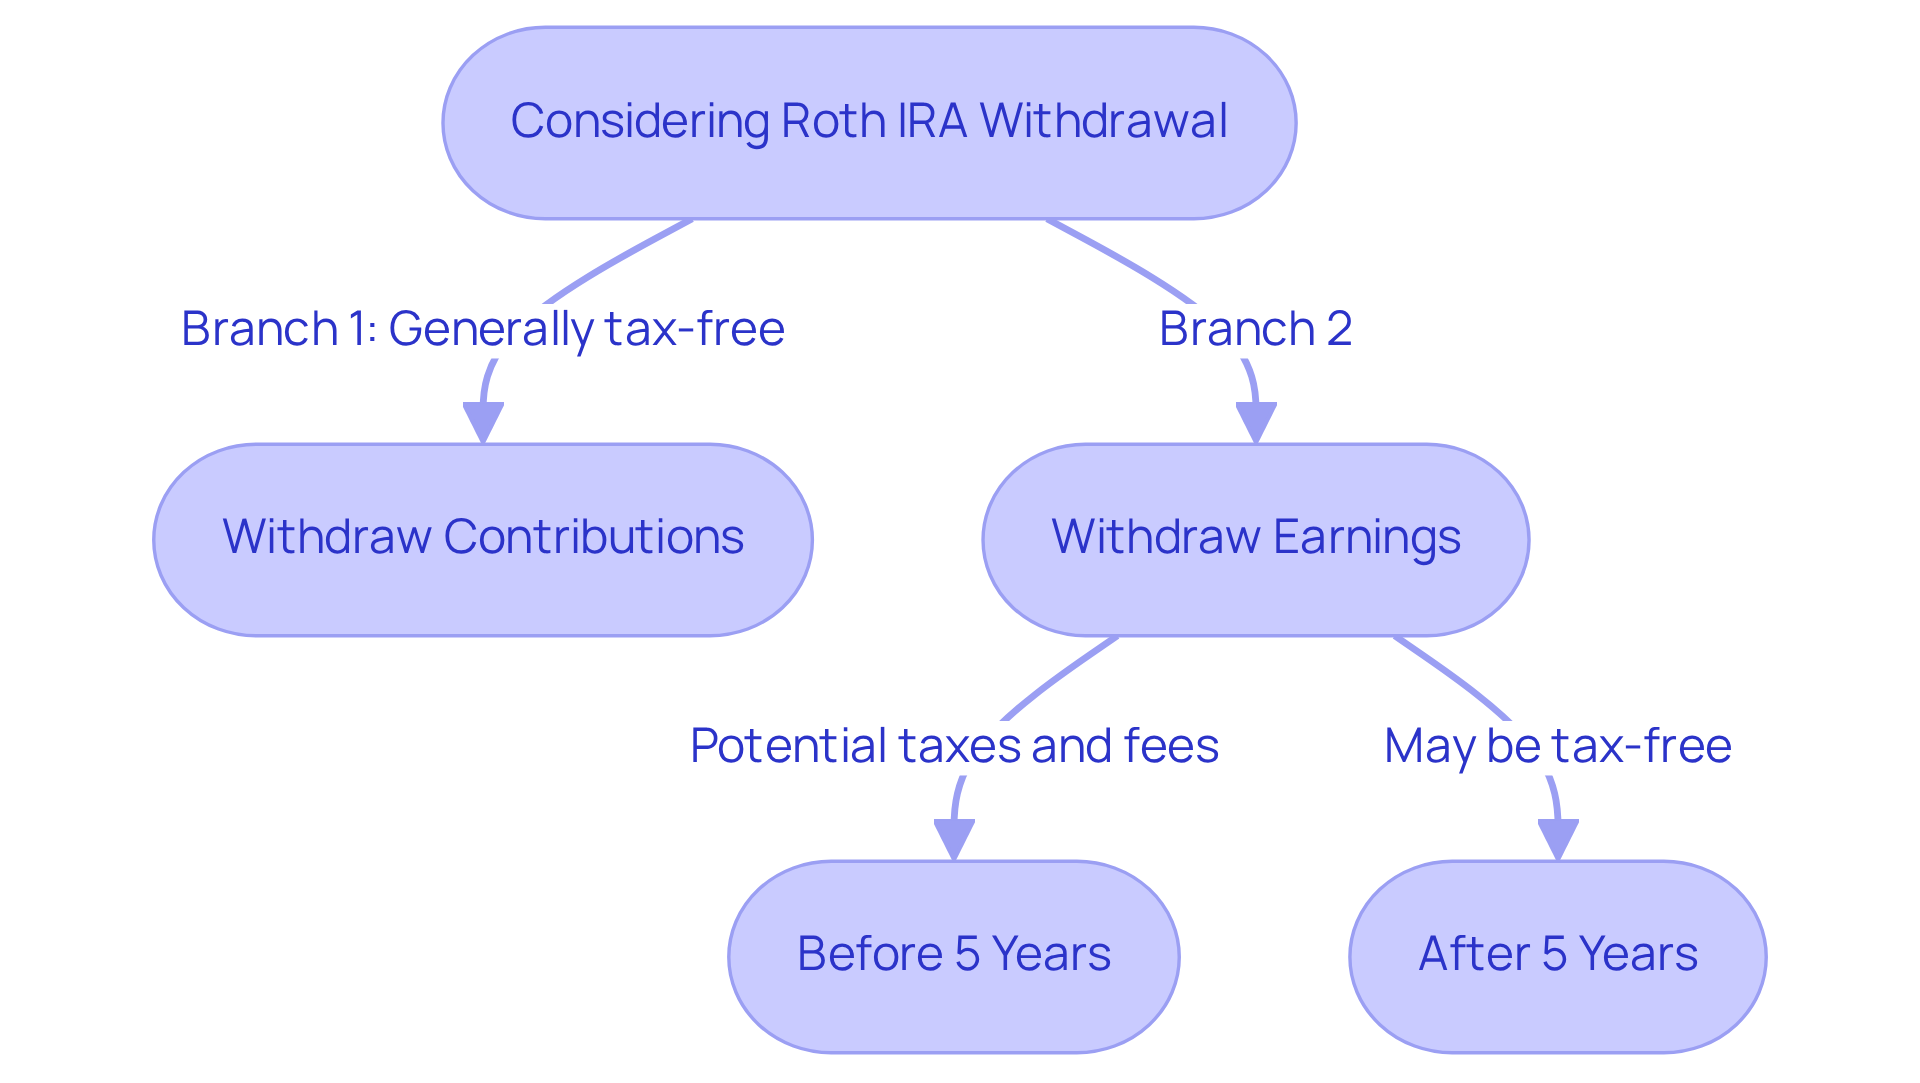
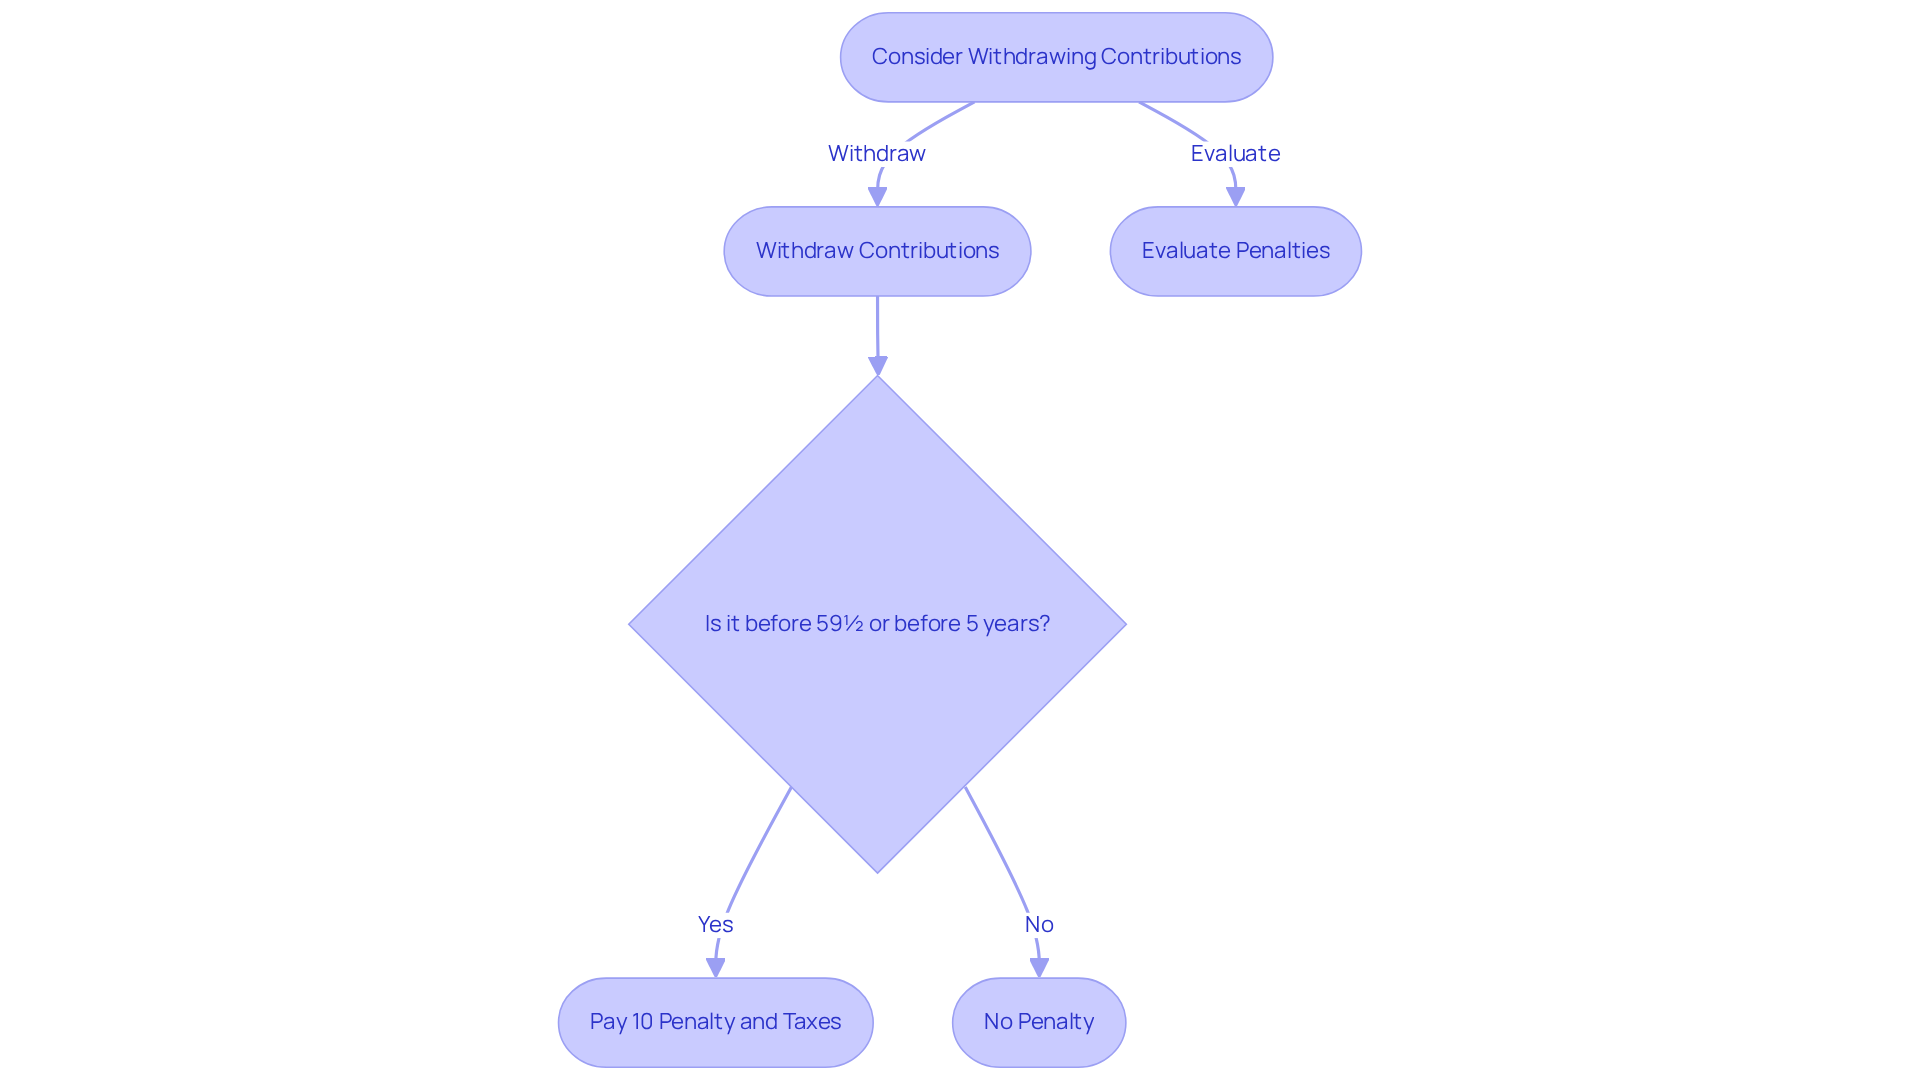
Early Withdrawal Penalties: What Happens If You Withdraw Contributions Too Soon?
While households like Emily and Mark can ask, can I withdraw contributions from Roth IRA at any time without penalty, it’s essential for them to thoughtfully consider the implications of withdrawing earnings. Imagine facing taxes and a 10% early withdrawal charge if they access their earnings before the account has been active for five years or before reaching 59½. Such penalties can significantly hinder their journey toward economic independence, especially for young families focused on building a secure future.
By collaborating with Bright Advisers, households can explore tailored strategies that guide them in timing their withdrawals. It’s important to understand the ideal age for accessing funds and the value of maintaining the account for the required duration. This personalized guidance empowers families to make informed decisions that align with their long-term financial goals.
Together, we can navigate this journey, ensuring that every step taken is a step toward a brighter future for their loved ones. We’re here for you, ready to support your financial planning needs.
Exceptions to Withdrawal Rules: Circumstances That Allow Penalty-Free Access
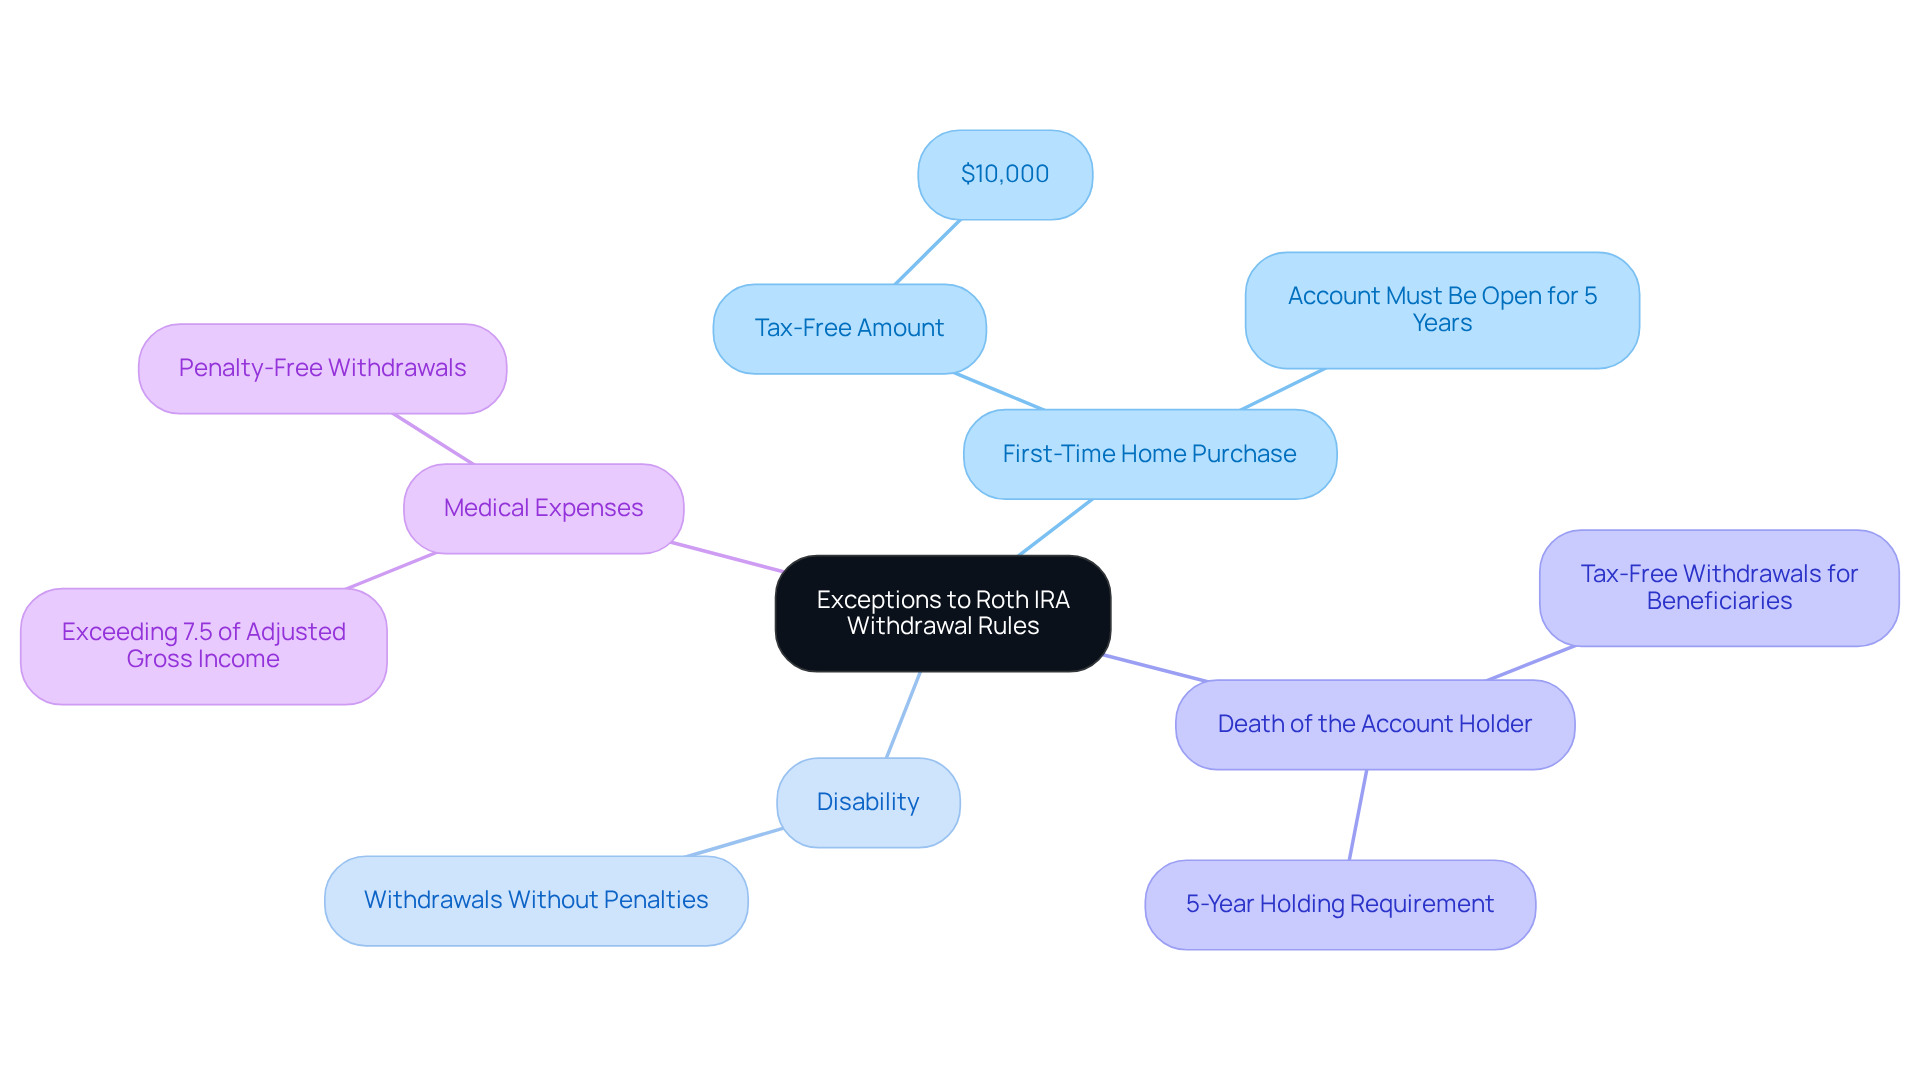
Families can access their Roth IRA earnings without facing charges under specific circumstances, providing essential financial flexibility during critical times. Imagine if you could tap into your savings without worry. Here are some notable exceptions that can truly make a difference:
- First-Time Home Purchase: Up to $10,000 can be withdrawn tax-free for purchasing a first home, as long as the account has been open for at least five years. This option is especially beneficial for families looking to secure their first residence, helping to turn dreams into reality.
- Disability: If the account holder becomes disabled, they can withdraw earnings without penalties, ensuring access to necessary funds during challenging times. It’s a comforting thought to know that support is there when you need it most.
- Death of the Account Holder: In the unfortunate event of the account holder’s passing, beneficiaries can withdraw funds tax-free, provided the account has met the five-year holding requirement. This allows families to manage financial obligations without the added burden of taxes, easing a difficult situation.
- Medical Expenses: Withdrawals may also be penalty-free if medical expenses exceed 7.5% of adjusted gross income, providing additional support when it’s needed most.
Understanding whether I can withdraw contributions from a Roth IRA is vital for families striving to navigate economic challenges effectively. In fact, many households utilizing these penalty-free withdrawal options often ask, ‘can I withdraw contributions from my Roth IRA,’ underscoring their importance in sound financial planning. Financial advisors often emphasize the value of being aware of these scenarios, as they can significantly influence your family’s financial strategy and long-term goals. Remember, evaluating how these withdrawal regulations can work alongside strategies to reduce fund fees can enhance your overall planning. We’re here for you—consulting with a financial advisor can offer tailored insights into both withdrawal strategies and fund fee optimization, ensuring you make informed choices for your family’s future.
Planning Your Roth IRA Withdrawals: Strategies for Financial Success
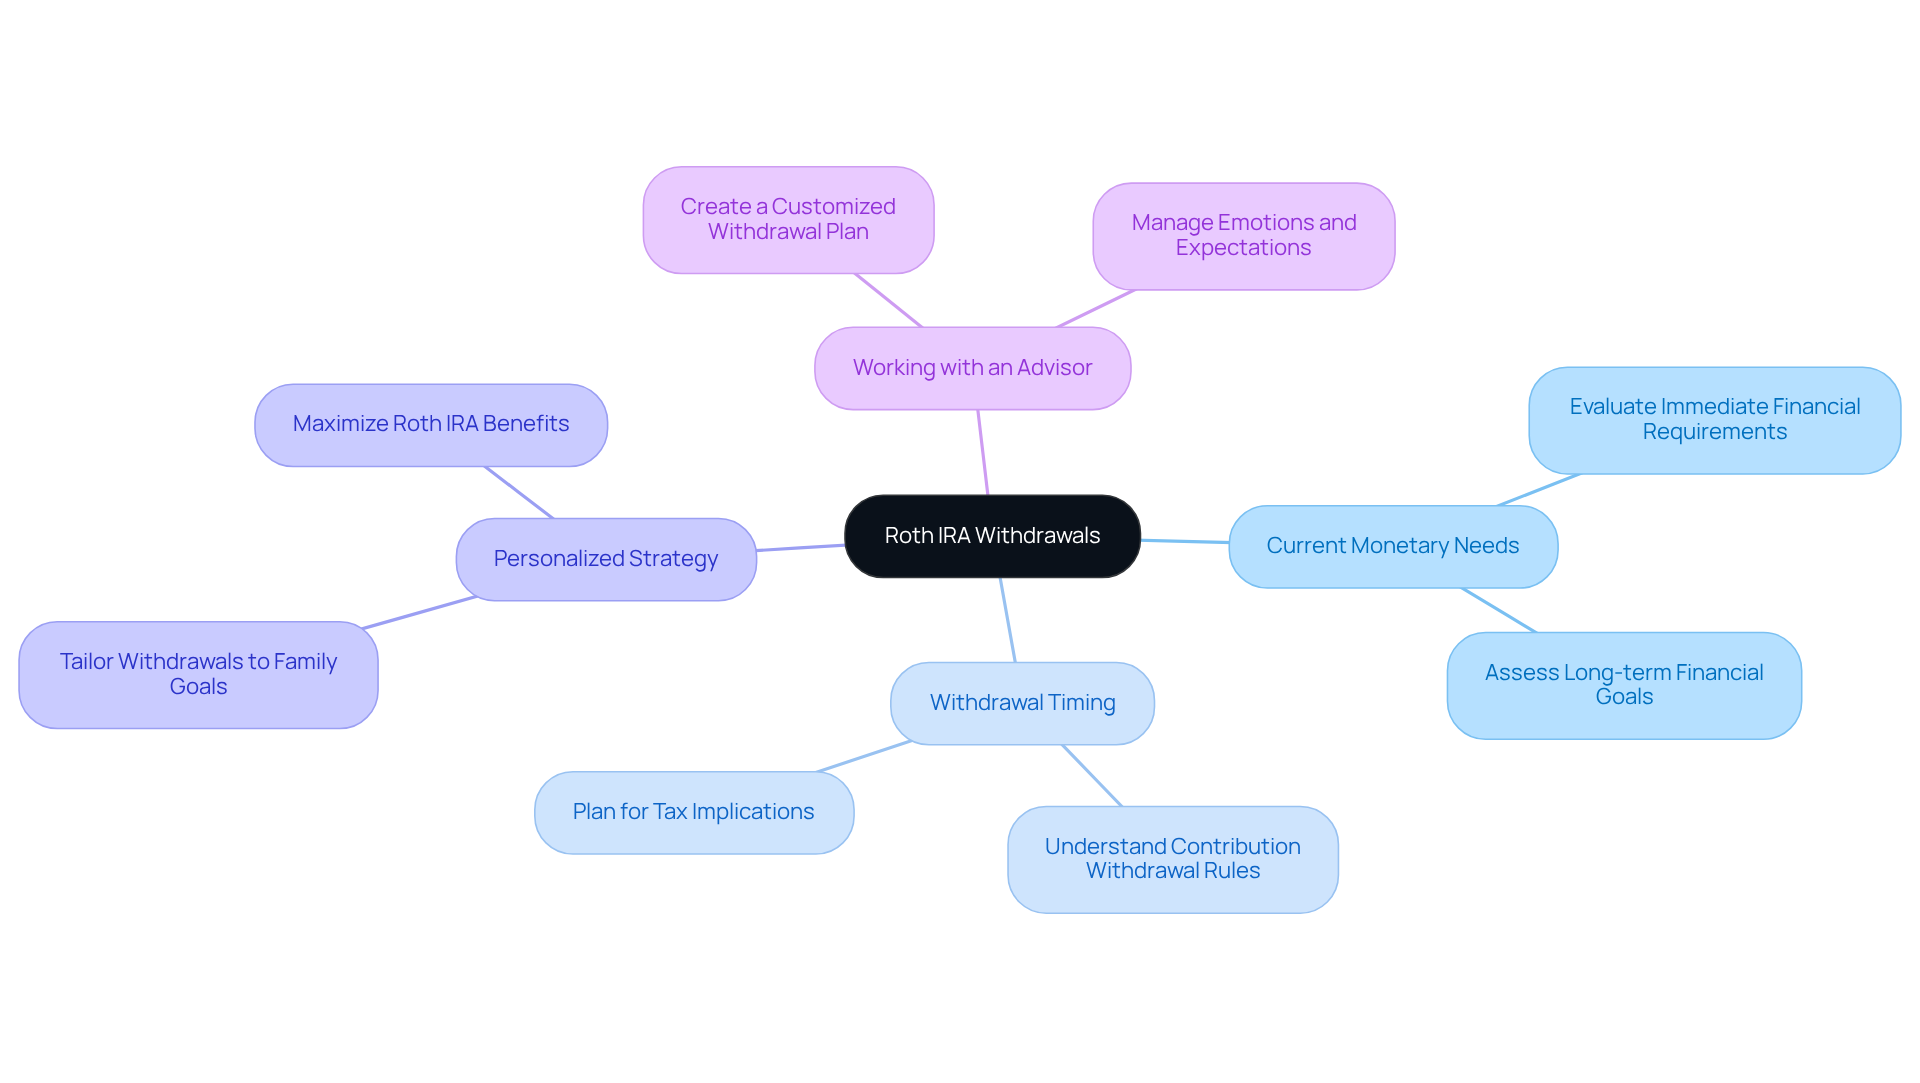
For households seeking economic success, it is essential to develop a thoughtful withdrawal plan, considering how can I withdraw contributions from Roth IRA. Imagine if you could navigate your financial future with confidence. This strategy begins with a careful evaluation of your current monetary needs, particularly regarding when can I withdraw contributions from a Roth IRA and their long-term effects on your retirement savings.
It’s important to understand that working together with a monetary advisor can greatly enhance this journey. They can help you create a personalized withdrawal strategy that considers whether you can withdraw contributions from a Roth IRA, aligning with your family’s financial goals. Such tailored strategies not only maximize the benefits of your Roth IRA deposits but also increase the likelihood of achieving your financial objectives.
Together, we can ensure your household is well-prepared for the future you envision.
Roth IRA vs. Traditional IRA: Contribution Withdrawal Differences Explained
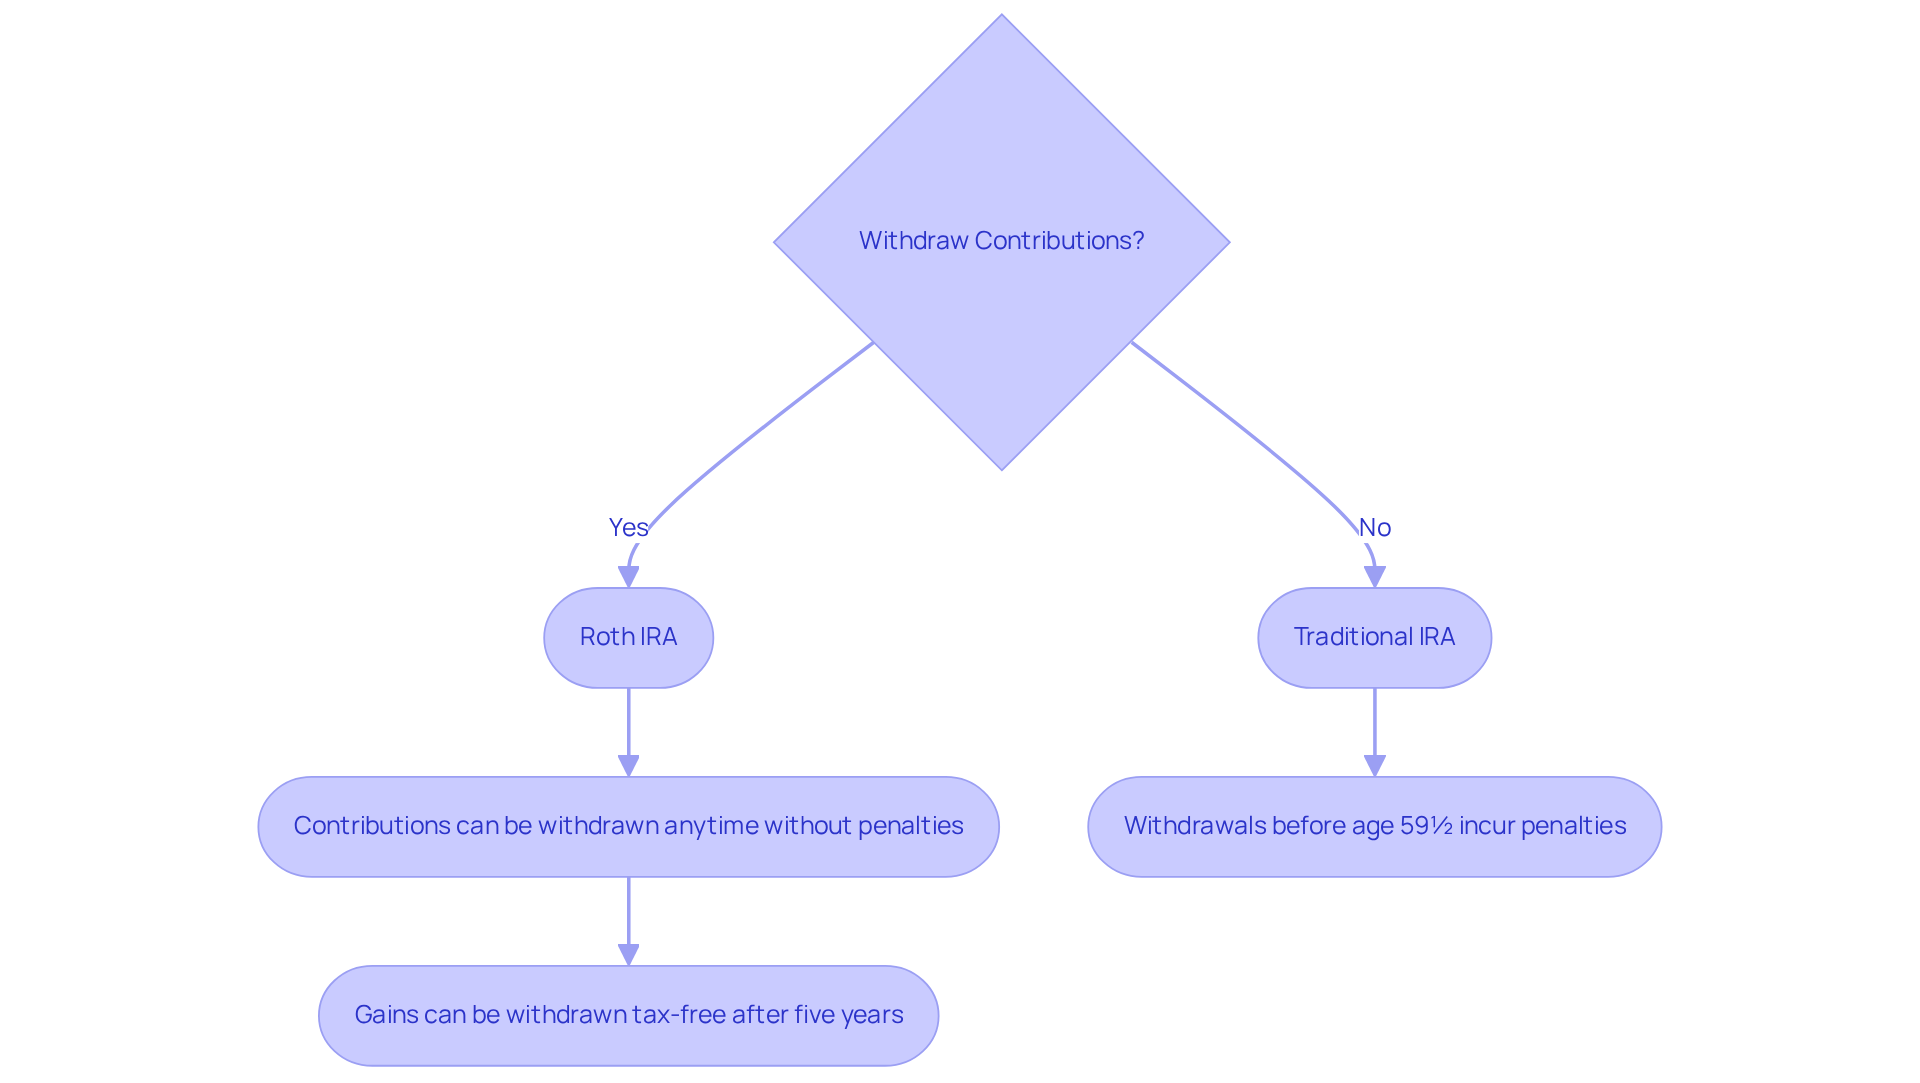
Understanding the differences between Roth and Traditional IRAs can be crucial for young families striving for economic stability. Imagine having the flexibility to access your deposits anytime without penalties, just like asking, can I withdraw contributions from a Roth IRA? With a Roth IRA, parents often wonder, can I withdraw contributions from a Roth IRA, as this adaptability allows them to manage multiple financial responsibilities with ease. On the other hand, Traditional IRA contributions come with penalties for withdrawals made before age 59½, which can create barriers when funds are needed most.
It’s also important to note that Roth IRA gains can be withdrawn tax-free after five years. This feature provides families with an opportunity to improve their financial situation without the burden of tax obligations. As you navigate these options, comprehending these distinctions becomes essential in determining which retirement account aligns best with your long-term financial goals.
We’re here for you, guiding you through these choices so you can make informed decisions that resonate with your family values. Together, we can navigate this journey towards a more secure financial future.
Age Considerations: How Your Age Affects Roth IRA Contribution Withdrawals
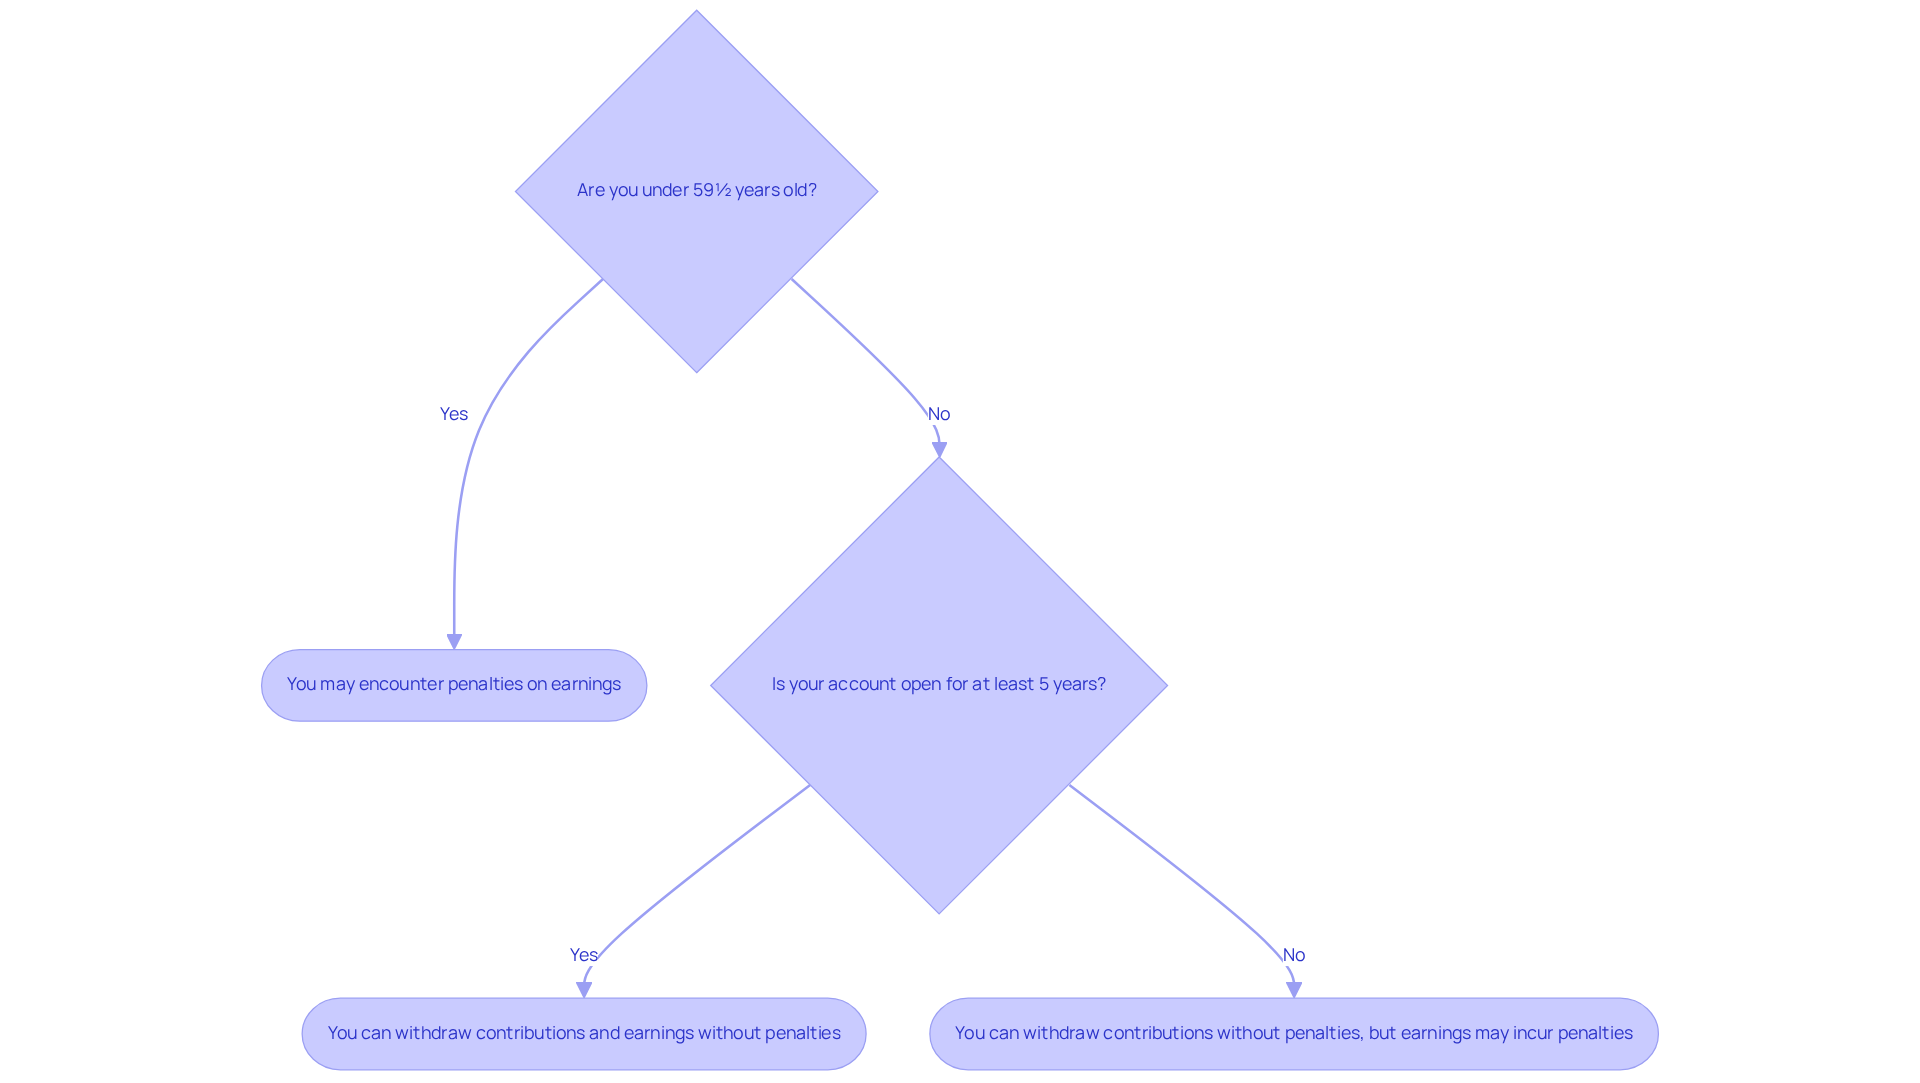
Families often wonder, ‘can I withdraw contributions from my Roth IRA?’, and age significantly influences how and when this can happen, particularly for young parents eager to secure their financial future. Imagine having the flexibility to access your funds at any age. However, it’s important to understand that the regulations regarding earnings, including the question of can I withdraw contributions from Roth IRA, vary based on your age. For instance, if you’re under 59½, you may encounter penalties on your earnings. In contrast, those over this age can withdraw contributions from a Roth IRA and earnings without penalties, which raises the question: can I withdraw contributions from a Roth IRA as long as the account has been open for at least five years?
Families like Jay and Emma or Emily and Mark should carefully consider their age and economic circumstances when planning their withdrawals. By collaborating with Bright Advisers, they can create customized strategies that not only meet their immediate financial needs—such as tax planning and retirement strategies—but also empower them to achieve their long-term goals. Together, we can navigate this journey, ensuring a balanced approach to retirement savings and financial freedom.
We’re here for you, ready to support you in making informed decisions that align with your family’s values and aspirations.
FAQs About Roth IRA Contribution Withdrawals: Common Questions Answered
Families often have questions about whether they can withdraw contributions from a Roth IRA, and that’s completely understandable. You might wonder, can I withdraw contributions from a Roth IRA at any time? The good news is, yes, you can withdraw contributions from a Roth IRA, so can I withdraw contributions from a Roth IRA without any charges. However, it’s important to consider what happens if you withdraw your earnings too soon. In that case, you may face taxes and penalties, which can be concerning.
Are there exceptions to these withdrawal rules? Absolutely! Certain circumstances allow for penalty-free access, providing some peace of mind. Addressing these common inquiries can empower families to navigate their Roth IRA contributions with greater confidence and clarity. Remember, we’re here for you, and together, we can navigate this journey toward financial security.
Conclusion
Understanding the intricacies of withdrawing contributions from a Roth IRA is essential for families aiming to secure their financial future. Imagine having the flexibility to access your contributions without penalties—this significant advantage allows for better management of immediate financial needs while also planning for long-term goals. It’s important to understand the distinction between contributions and earnings to avoid unexpected tax implications.
This article delves into key insights regarding Roth IRA withdrawals, emphasizing that:
- Contributions can be accessed freely.
- Earnings may incur taxes and penalties if withdrawn prematurely.
There are various exceptions that allow for penalty-free access, such as:
- First-time home purchases
- Medical expenses
These can be invaluable during critical times when you need support the most. By understanding these guidelines and working closely with financial advisers, families can develop effective withdrawal strategies that align with their unique circumstances.
Ultimately, the ability to withdraw contributions from a Roth IRA serves as a powerful tool for financial planning. It encourages families to leverage their savings wisely while fostering a sense of security as they navigate life’s challenges. Together, we can navigate this journey, and engaging with a financial advisor can further enhance this experience, ensuring that each decision made is a step toward a stable and prosperous future.
Frequently Asked Questions
What services does Bright Advisers provide for financial planning?
Bright Advisers offers personalized financial planning, including tailored strategies for Roth IRA contributions, estate planning, and integrated tax planning, focusing on the unique challenges faced by young families.
Can I withdraw contributions from a Roth IRA at any time?
Yes, you can withdraw contributions from a Roth IRA at any time without penalties, as long as you are only accessing the contributions and not the earnings.
What are the potential penalties for withdrawing earnings from a Roth IRA?
Withdrawing earnings from a Roth IRA before age 59½ or before the account has been active for five years may incur taxes and a 10% penalty, unless certain exceptions apply.
What are qualified distributions from a Roth IRA?
Qualified distributions are those made after age 59½ and that meet the five-year rule, allowing for tax-free access to both contributions and earnings.
How can families avoid penalties when withdrawing from their Roth IRA?
Families can avoid penalties by familiarizing themselves with IRS guidelines, keeping track of contribution dates, and understanding the rules for qualified distributions, such as for higher education expenses or birth/adoption costs.
What is the contribution limit for a Roth IRA in 2025?
In 2025, individuals can contribute up to $7,000 annually to a Roth IRA, with an additional $1,000 allowed for those aged 50 and over.
How are withdrawals from a Roth IRA ordered?
Withdrawals from a Roth IRA are taken out in the following order: contributions first, followed by conversions, and then earnings.
Why is it important to maintain detailed records of Roth IRA contributions?
Maintaining detailed records is essential to ensure that only the principal (contributions) is withdrawn, thereby avoiding taxes or penalties on any earnings.
List of Sources
- Bright Advisers: Personalized Financial Planning for Roth IRA Contributions
- Strategic+Corporate+Social+Responsibility+Stakeholders,+Glob… (https://academia.edu/32414373/Strategic_Corporate_Social_Responsibility_Stakeholders_Glob_)
- Understanding Roth IRA Contribution Withdrawals: Key Rules and Guidelines
- Roth IRA Withdrawal Options (https://weabenefits.com/resource/roth-ira-withdrawal-options)
- Roth IRA withdrawal rules (https://empower.com/the-currency/life/roth-ira-withdrawal-rules)
- Roth IRA withdrawal rules [2025]: Penalties and exceptions explained (https://public.com/learn/roth-ira-withdrawal-rules)
- The Roth IRA 5-Year Rule: What to Know – NerdWallet (https://nerdwallet.com/article/investing/roth-ira-5-year-rule)
- Traditional and Roth IRA Withdrawal Rules & Penalties | SoFi (https://sofi.com/learn/content/ira-withdrawal-rules)
- Withdrawal Conditions: When Can You Access Your Roth IRA Contributions Penalty-Free?
- Roth IRA withdrawal rules (https://empower.com/the-currency/life/roth-ira-withdrawal-rules)
- Exceptions to Withdrawal Rules: Circumstances That Allow Penalty-Free Access
- How to Make Penalty-Free IRA Withdrawals (https://smartasset.com/retirement/penalty-free-ira-withdrawal)
- Must-Ask Questions: Roth IRA Withdrawals (https://schwab.com/learn/story/must-ask-questions-roth-ira-withdrawals)
- Roth IRA Withdrawal Rules – NerdWallet (https://nerdwallet.com/article/investing/roth-ira-withdrawal-rules)
- Retirement plan distributions: IRS provides guidance on certain exceptions from 10% additional tax for emergency personal or family expenses and for survivors of domestic abuse | Internal Revenue Service (https://irs.gov/newsroom/retirement-plan-distributions-irs-provides-guidance-on-certain-exceptions-from-10-percent-additional-tax-for-emergency-personal-or-family-expenses-and-for-survivors-of-domestic-abuse)
- Planning Your Roth IRA Withdrawals: Strategies for Financial Success
- 12 Financial Planning Quotes for Building Wealth Wisely — Phillip James Financial (https://phillipjamesfinancial.com/blog/12-financial-planning-quotes-for-building-wealth-wisely)
- 77 Financial Advisor Quotes to Send to Clients (https://billgoodmarketing.com/resources/financial-advisor-quotes)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Retirement & Employee Benefits for high-income W-2 families at Bright Advisers.
Keep reading