

Overview
This article explores the important comparison between ‘withhold to cover’ and ‘sell to cover’ strategies for managing Restricted Stock Units (RSUs). We understand that navigating these financial decisions can be overwhelming, especially for young parents focused on their family’s future. By highlighting the implications for tax liabilities and financial planning, we aim to shed light on your options.
Imagine if you could simplify your immediate cash flow. The ‘withhold to cover’ strategy allows you to retain shares to meet tax obligations, providing a sense of security in your financial planning. On the other hand, the ‘sell to cover’ approach offers liquidity by selling shares to meet these obligations, which can be a practical solution for immediate needs.
Each method has distinct impacts on your long-term wealth accumulation and tax management, and it’s essential to consider what aligns best with your family values and goals. We want you to feel empowered in your financial journey, knowing that the right choice can support your family’s future.
Together, we can navigate these strategies, ensuring that your financial decisions reflect your priorities and aspirations. Remember, we’re here for you, ready to assist you in making informed choices that benefit your family.
Key Highlights:
- Bright Advisers specialises in personalised financial planning for families managing RSUs, simplifying complex financial decisions.
- Only 36% of U.S. households have a long-term financial plan, indicating a need for tailored financial strategies.
- The ‘withhold to cover’ strategy allows employers to retain shares to cover tax liabilities, easing immediate cash flow concerns.
- The ‘sell to cover’ strategy enables families to sell a portion of RSUs to meet tax obligations, preserving liquidity while retaining future growth potential.
- Understanding the timing of tax implications is crucial, as taxes are triggered at vesting, impacting financial planning.
- Families should consider the 83(b) election to potentially reduce their tax burden by paying taxes at grant instead of vesting.
- Cash flow management is vital, as choosing between ‘withhold to cover’ and ‘sell to cover’ affects investment growth and liquidity.
- Capital gains tax implications differ between strategies, with ‘sell to cover’ incurring taxes on appreciation, while ‘withhold to cover’ defers them.
- Employer policies significantly influence RSU management strategies, necessitating awareness of specific withholding methods.
- Financial advisors provide essential support in navigating RSU complexities, helping families align their financial goals with effective tax strategies.
Introduction
Navigating the intricate landscape of Restricted Stock Units (RSUs) can feel overwhelming, especially for young families eager to secure their financial future. Imagine the possibilities that come with understanding strategies like ‘withhold to cover’ and ‘sell to cover.’ Each approach offers unique advantages and challenges, providing families with opportunities to manage tax liabilities while keeping long-term wealth-building goals in sight.
It’s important to consider:
- Which method aligns best with your family’s financial aspirations?
- How can you optimize your RSU management to enhance both immediate cash flow and future investment potential?
Exploring these insights can empower you to make informed choices that resonate with your unique financial situation. Together, we can navigate this journey toward financial security.
Bright Advisers: Personalized Financial Planning for RSUs
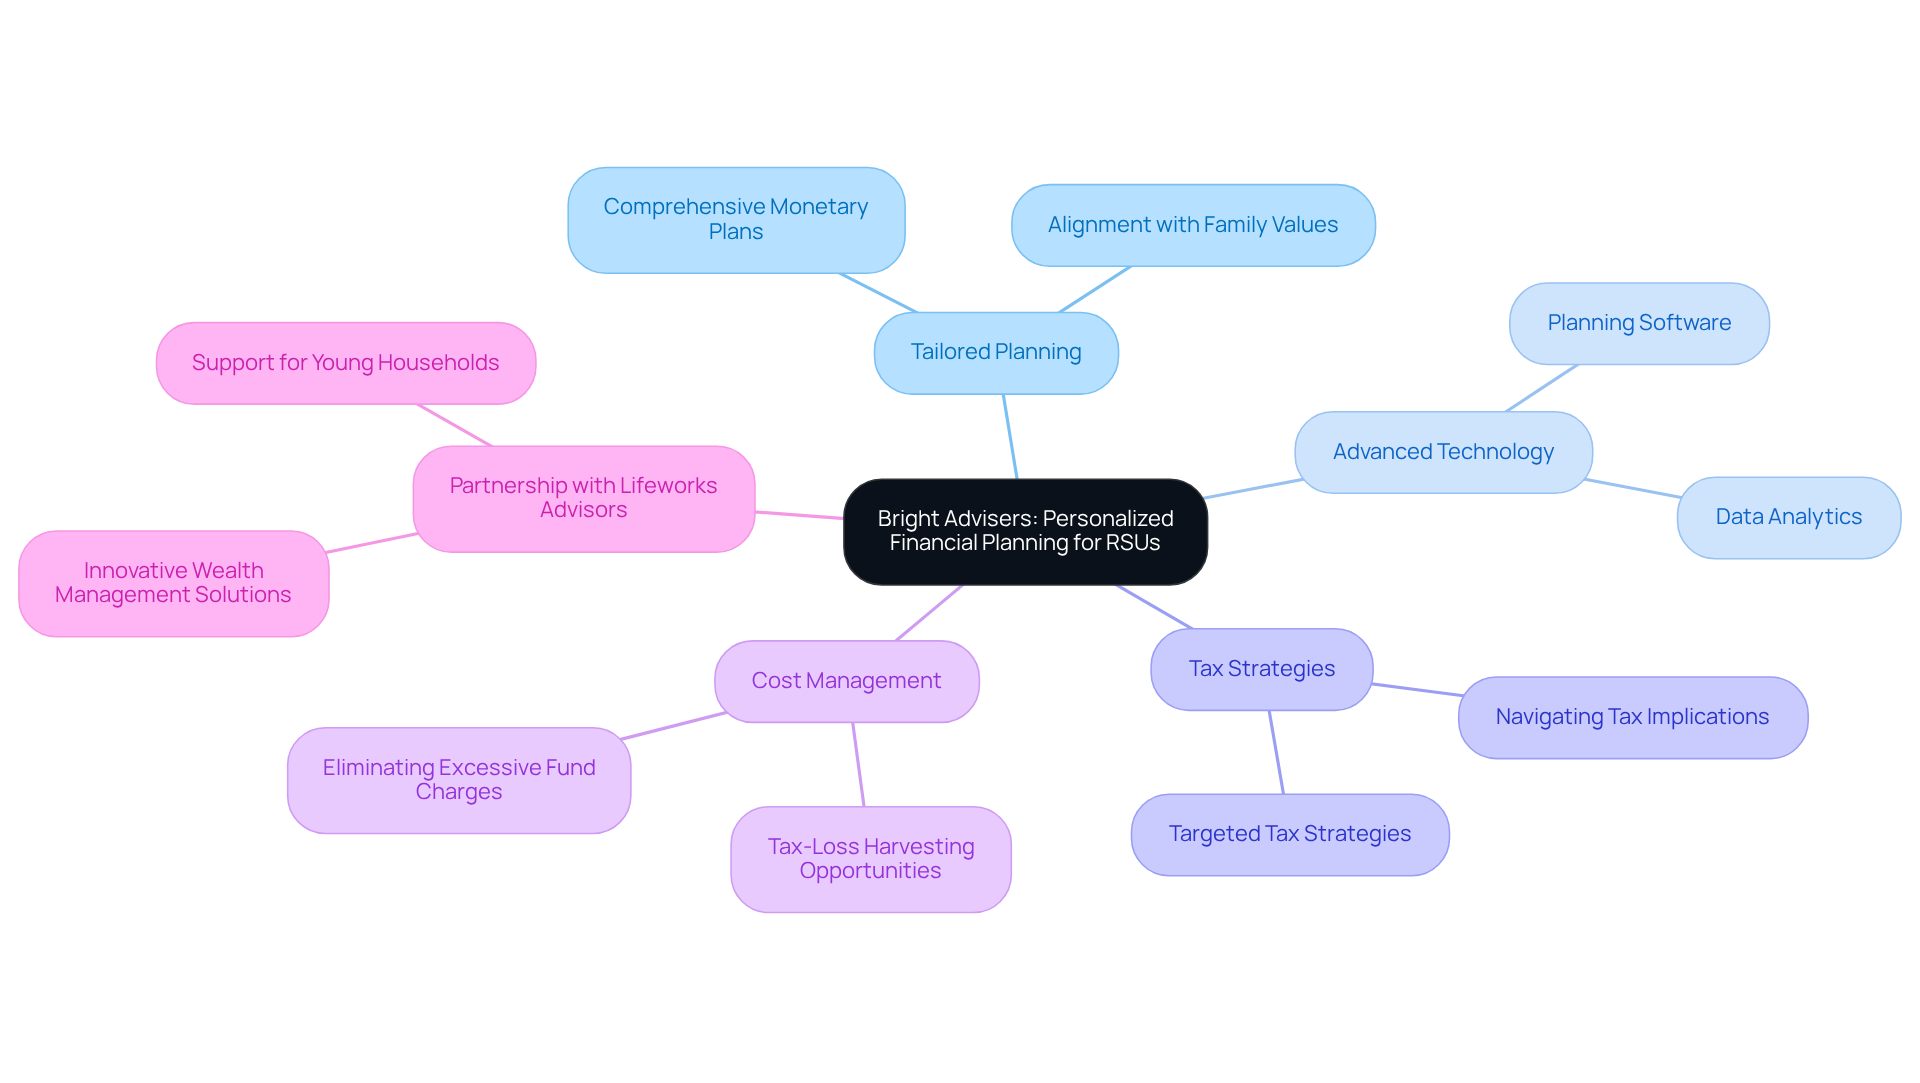
At Bright Advisers, we understand that managing Restricted Stock Units (RSUs) can feel overwhelming, especially for young families. That’s why we excel in providing tailored planning that simplifies these complexities, ensuring that you feel supported every step of the way. Our dedicated team of consultants partners with households like yours to create comprehensive monetary plans that align with your values and aspirations.
Imagine having a financial plan designed specifically for your family’s unique needs. By utilizing advanced planning software and data analytics, we craft personalized strategies that cater to families with young children. This includes strategic enhancements in RSU management, allowing you to navigate tax implications effectively while safeguarding your family’s financial future through targeted tax strategies.
We also focus on eliminating excessive fund charges and seizing tax-loss harvesting opportunities, all aimed at improving your family’s financial outcomes. Bright Advisers is committed to offering top-notch monetary services, ensuring that each plan reflects your distinct financial situation.
It’s important to recognize that in 2024, only 36% of U.S. households have a long-term financial plan. This highlights the critical need for personalized financial planning tailored to your family’s needs. Together with Lifeworks Advisors, we enhance our ability to provide innovative wealth management solutions designed specifically for young households.
We’re here for you, ready to navigate this journey together. Let us help you build a financial future that resonates with your family’s dreams and values.
Withhold to Cover: Understanding Tax Liability Management
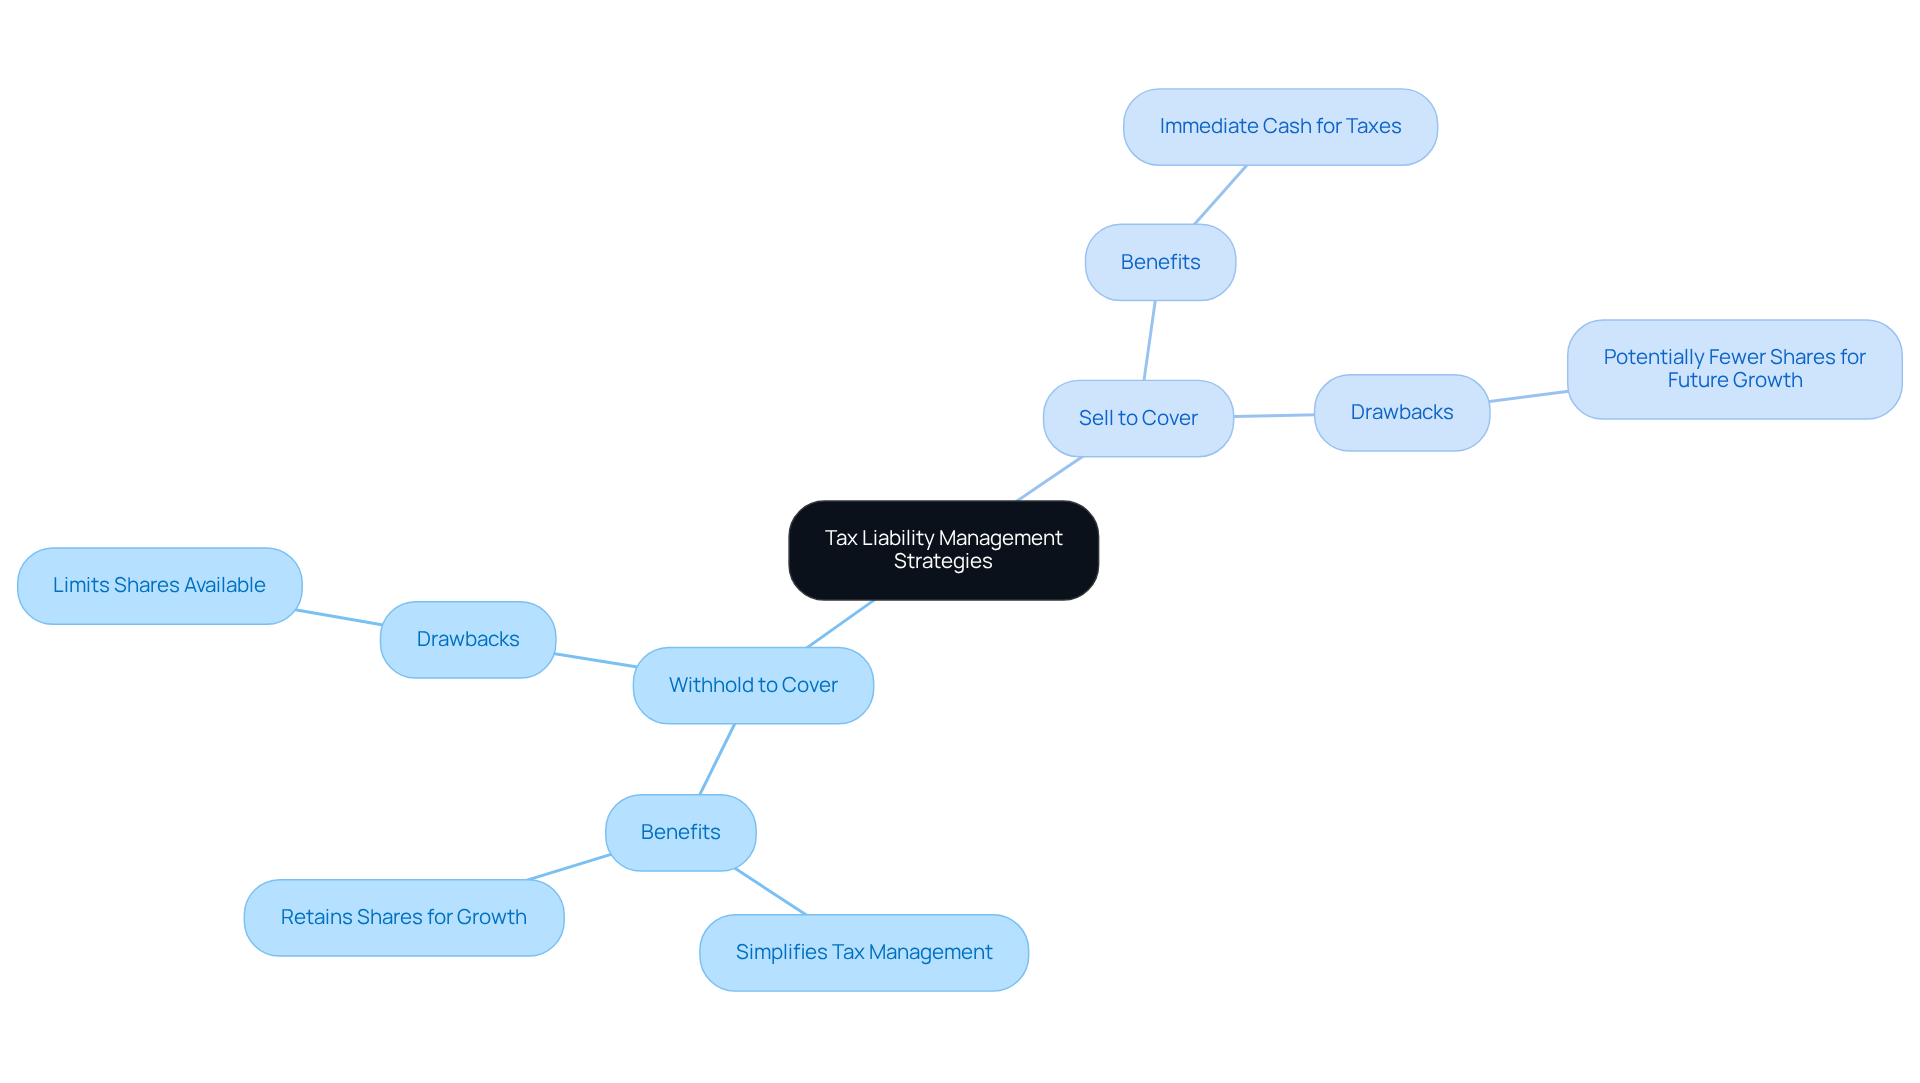
Navigating the complexities of financial planning can be overwhelming, especially for young families. The approach of ‘withhold to cover vs sell to cover’ offers a thoughtful solution, allowing employers to retain a portion of vested RSUs to address tax liabilities incurred at vesting. This method simplifies tax management, easing the burden of needing cash to pay taxes out of pocket. Imagine the relief of knowing that you won’t have to scramble for funds during tax season.
However, it’s important to recognize that while the strategy of withhold to cover vs sell to cover can simplify immediate tax obligations, it may also limit the number of shares available for future growth. Tax experts emphasize the need to align this strategy with your long-term wealth-building goals. For instance, if you have 1,000 RSUs vesting at $20 each, and your employer withholds 250 shares to cover a $500 tax liability, you would retain 750 shares for potential appreciation.
As you consider your financial situation, it’s crucial to evaluate whether the methods of ‘withhold to cover vs sell to cover’ align with your family’s overall financial objectives. Together, we can navigate this journey, ensuring that your decisions reflect your values and aspirations. We’re here for you, ready to support you in making the best choices for your family’s future.
Sell to Cover: A Strategy for Tax Obligation Fulfillment
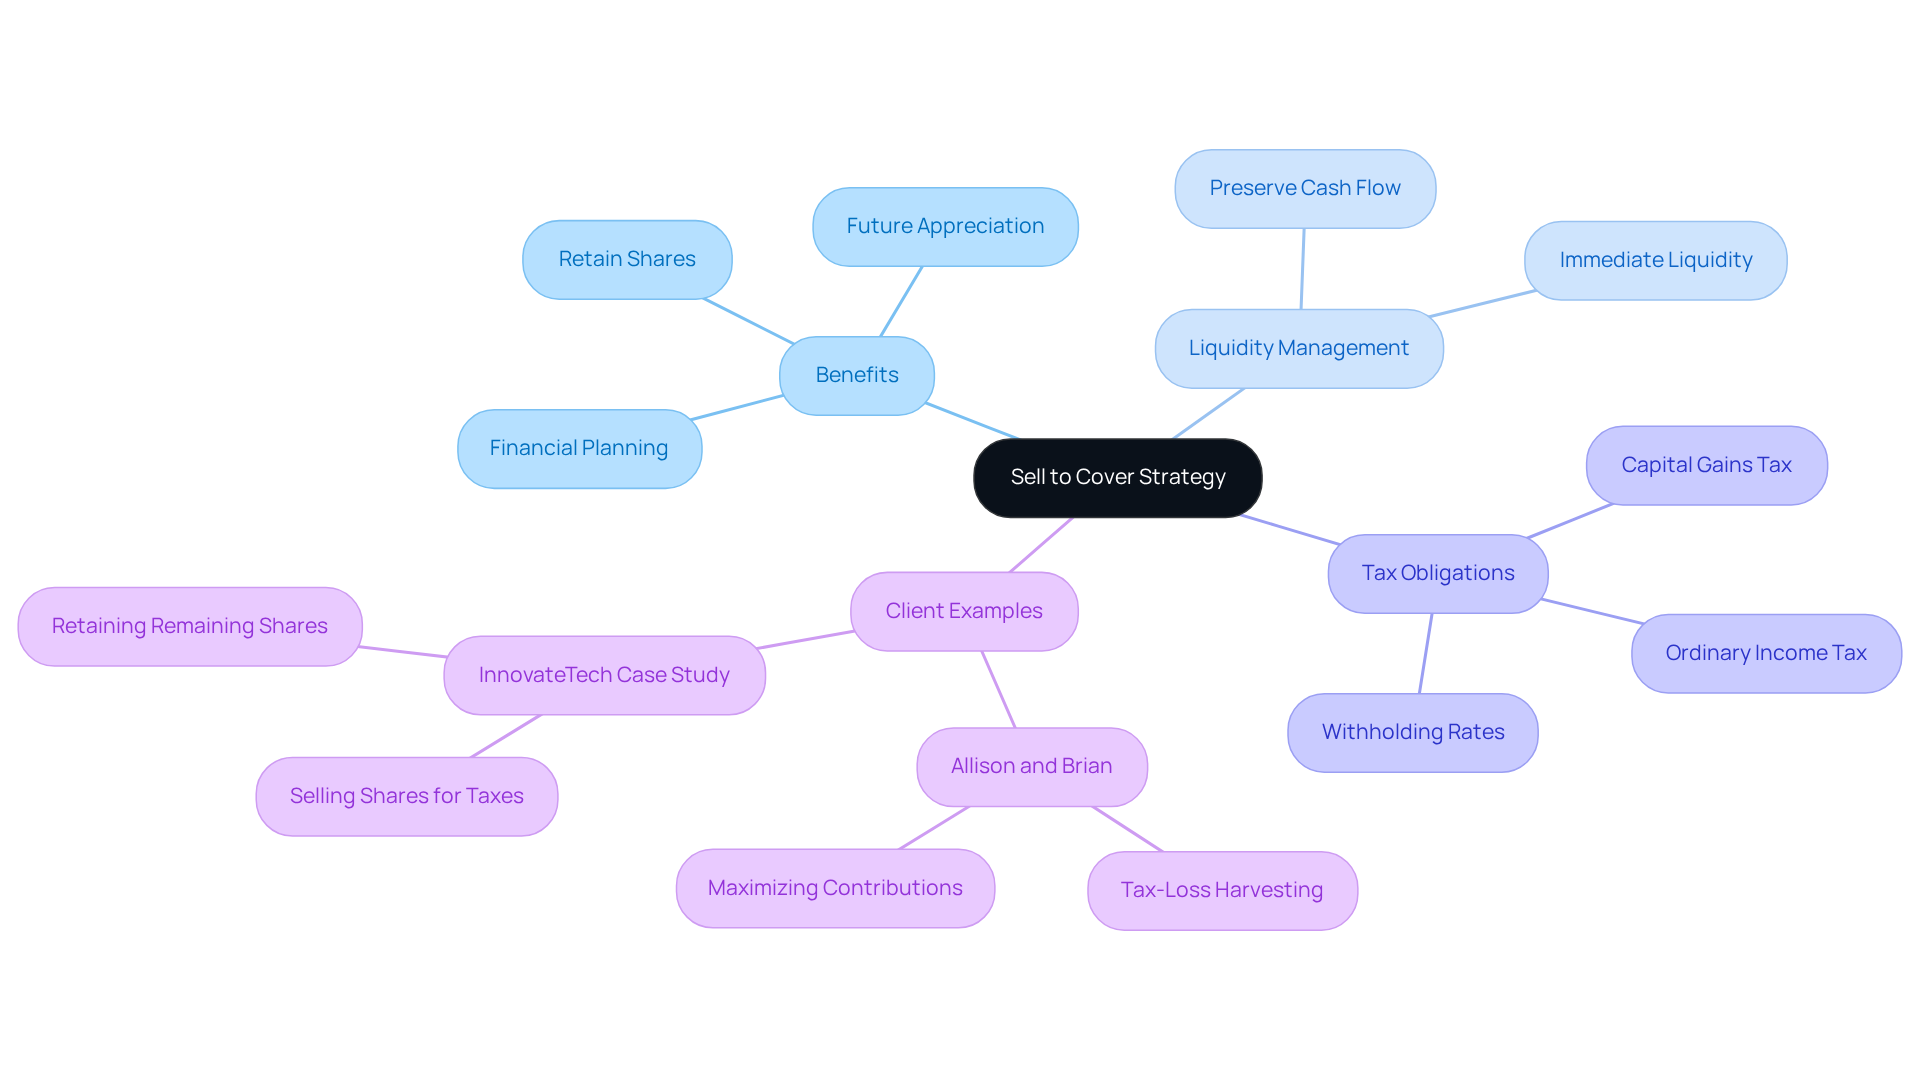
Navigating financial obligations can be overwhelming, especially for young parents. The strategy of ‘withhold to cover vs sell to cover’ is a thoughtful approach that allows employees to sell a portion of their vested Restricted Stock Units (RSUs) to meet tax obligations that arise upon vesting. This method is particularly beneficial for families aiming to preserve liquidity without straining their cash flow.
Imagine selling just enough shares to cover your taxes while still retaining the remaining shares. This way, you can benefit from potential future appreciation, aligning with your long-term investment goals. Not only does this approach address immediate monetary needs, but it also supports your family’s financial future, making it a valuable resource for liquidity management.
Financial consultants emphasize that this strategy can help families navigate the complexities of tax obligations while ensuring they remain engaged in their economic journey. For instance, through their partnership with Bright Advisers, clients like Allison and Brian improved their tax situation by utilizing strategies such as tax-loss harvesting and maximizing contributions to tax-advantaged accounts.
Did you know that over half of young professionals consider equity compensation, like RSUs, a vital factor when evaluating job offers? This highlights the importance of understanding how to manage these assets effectively. By considering the differences between withhold to cover vs sell to cover, families can enhance their financial planning and elevate their overall wealth management.
To maximize your financial potential, consider reaching out to a consultant who can help you explore how these strategies can work for your family. Remember, we’re here for you—together, we can navigate this journey toward a secure financial future.
Timing of Tax Implications: Key Considerations for RSU Holders
For holders of restricted stock units (RSUs), understanding the timing of tax implications is essential. Imagine the relief of knowing when taxes are triggered—at the time of vesting, when the fair market value of the shares is classified as ordinary income. Families, like Jay and Emma, who are managing their financial responsibilities, must pay close attention to their vesting schedules to effectively navigate their tax liabilities. This may involve adjusting withholding rates or planning for estimated tax payments to avoid underpayment penalties. If a household anticipates a significant increase in income due to RSU vesting, they might consider the options of withhold to cover vs sell to cover the expected tax burden.
The impact of vesting schedules on tax liabilities can be substantial. Families with various monetary obligations should strategize around these schedules to enhance their overall economic health. For example, if an RSU vests and the household is already facing a high income for the year, it’s important to consult a tax advisor to explore options for mitigating tax exposure. Tax experts emphasize the importance of proactive planning. One specialist observes that understanding the consequences of RSU vesting can help households align their financial strategies with their long-term objectives. By anticipating tax obligations and adjusting their monetary strategies accordingly, families can navigate the complexities of RSUs more effectively, ensuring they aren’t caught off guard by unexpected tax bills.
Furthermore, households should contemplate the 83(b) election, which allows them to pay taxes on RSUs at the time of grant instead of at vesting. This option can be significant, as it may reduce their overall tax burden if the stock appreciates in value. Ultimately, efficient tax strategies regarding RSU vesting timelines can empower families, like Emily and Mark, to make informed choices about whether to withhold to cover vs sell to cover, thereby ensuring they maintain economic stability while optimizing the benefits of their equity compensation. Moreover, if shares are sold after vesting, families may also need to account for capital gains tax, adding another layer of financial consideration. Bright Advisers is here for you, offering customized tax planning services to assist families in navigating these complexities and enhancing their economic approaches together.

Cash Flow Impact: Comparing Withhold to Cover and Sell to Cover
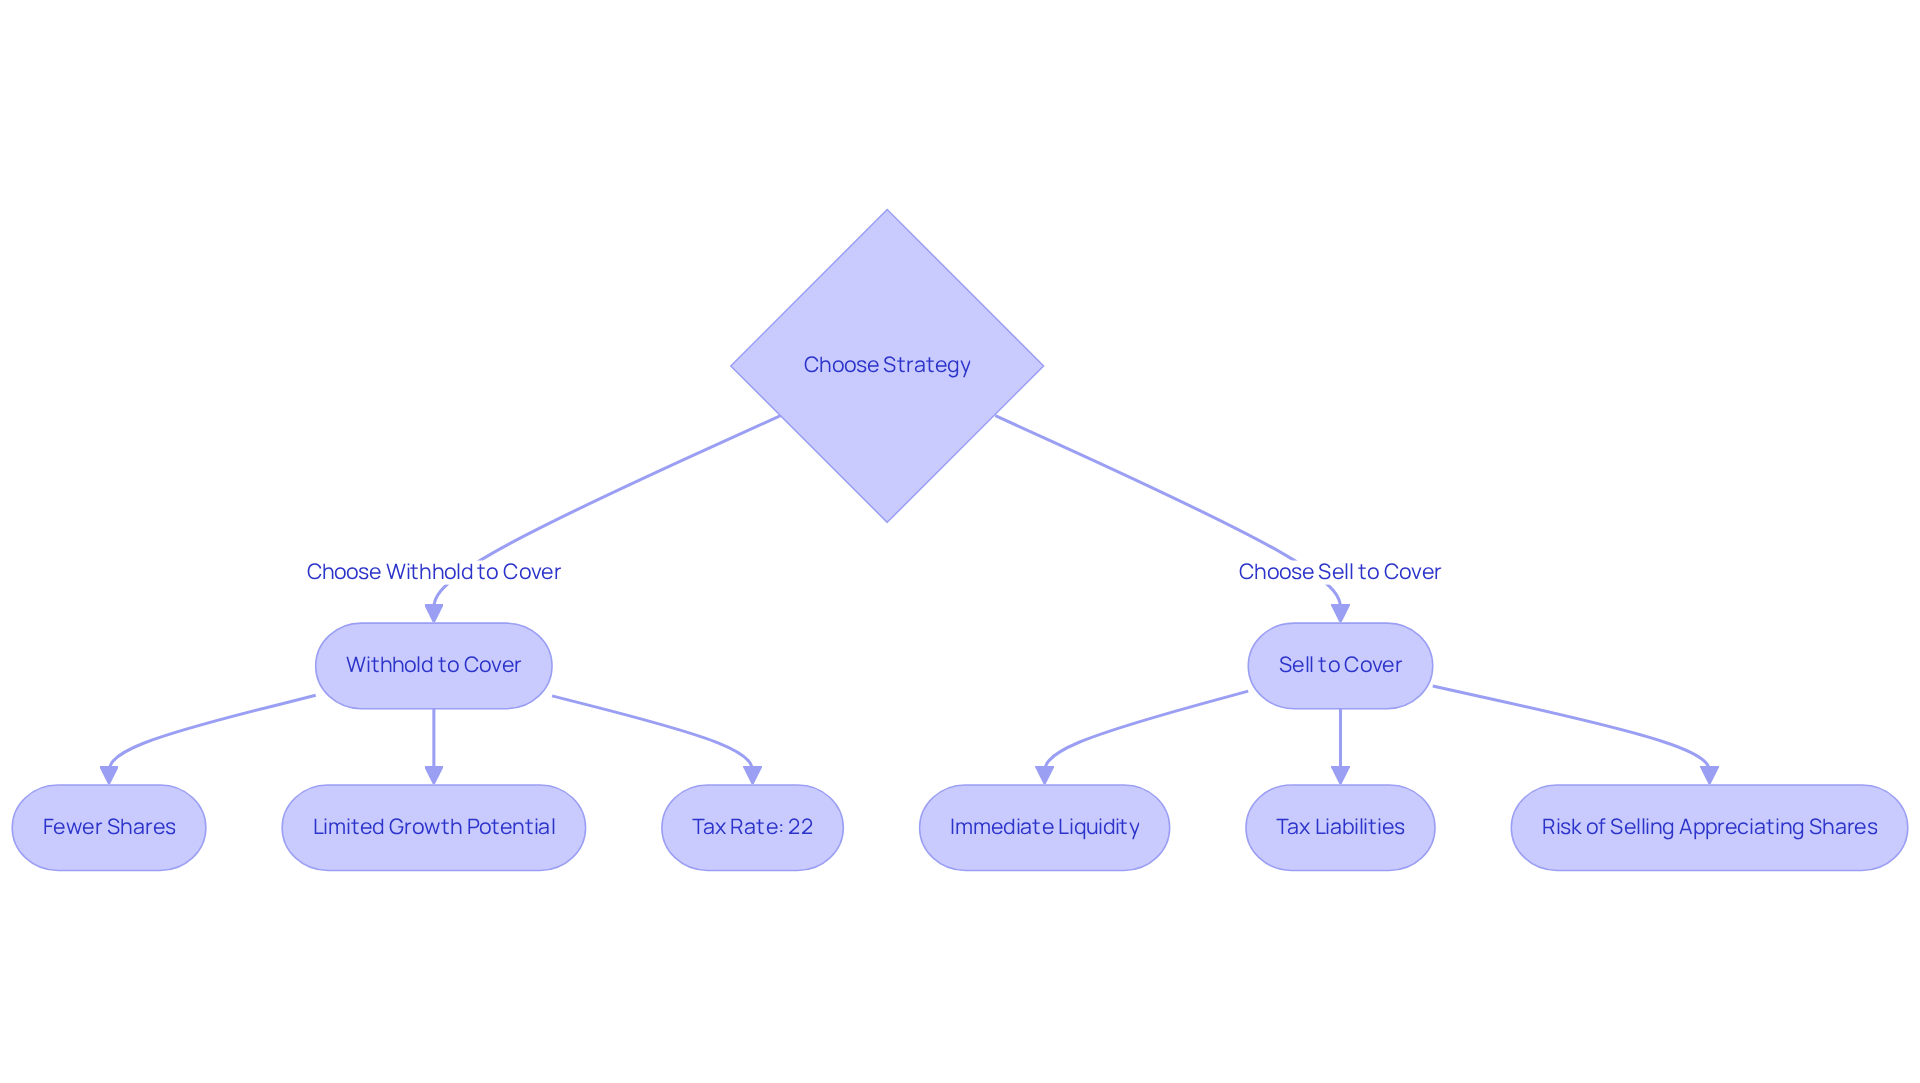
The cash flow consequences of ‘withhold to cover vs sell to cover’ strategies can significantly impact your family’s financial well-being, especially for young parents like you who are striving to enhance financial security. Choosing ‘withhold to cover’ often means retaining fewer shares, which may limit your future investment growth potential. This approach could lead to a situation where your household has a diminished stake in your company, potentially missing out on the appreciation in stock value over time.
On the other hand, when comparing ‘withhold to cover vs sell to cover’, the option to ‘sell to cover’ provides immediate liquidity, allowing families to address pressing cash flow needs, such as tax liabilities or essential expenses. This strategy can improve your cash management, particularly during uncertain economic times. However, it does come with the trade-off of selling shares that could appreciate, particularly when considering the implications of withhold to cover vs sell to cover, which may affect your long-term wealth accumulation.
As you navigate these decisions, it’s important to carefully evaluate your current financial circumstances and future aspirations. Financial advisors at Bright Advisers emphasize understanding the tax implications associated with RSUs, as well as the potential risks of holding a concentrated position in company stock. Imagine if a proactive approach to cash flow management could help you avoid the pitfalls of inadequate liquidity—something that is a common concern among small business owners. In fact, 69% report sleepless nights due to cash flow worries. Additionally, 82% of firms fail because of cash flow problems, underscoring the critical importance of effective cash flow management.
When considering your options, keep in mind that the flat tax withholding rate for RSUs is 22%. Ultimately, your choice should align with your household’s overall economic plan, taking into account aspects like investment diversification, tax responsibilities, and long-term monetary objectives. By assessing your cash flow requirements and the effects of each approach, you can make informed decisions that promote your family’s economic health and help you reach your goals. For instance, families like Jay and Emma have successfully managed their financial planning with Bright Advisers, optimizing their tax situation and creating a tailored retirement plan that balances immediate needs with long-term aspirations. Together, we can navigate this journey and ensure a brighter financial future for your family.
Capital Gains Tax Implications: Analyzing Both Strategies
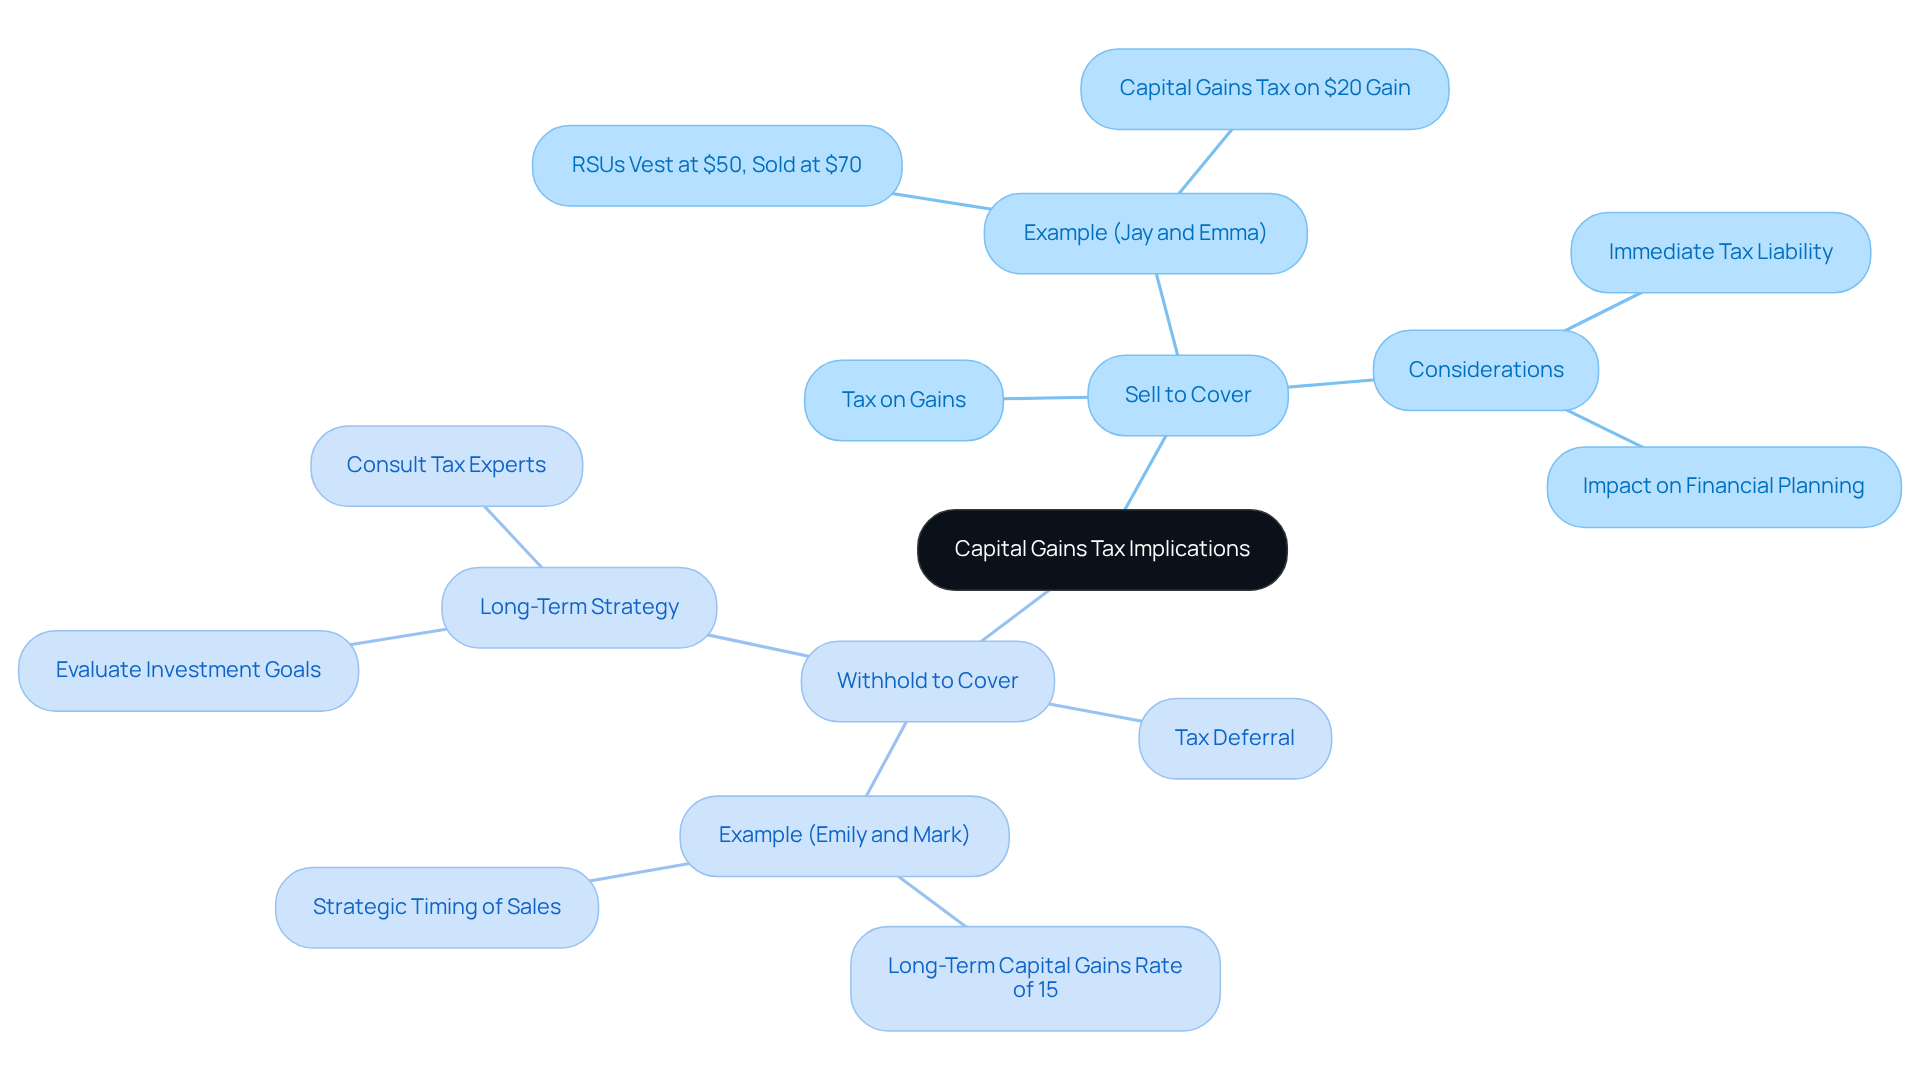
Navigating the world of capital gains tax can feel overwhelming, especially for young families. It’s essential to understand the distinct implications of the approaches ‘withhold to cover vs sell to cover’ when managing your Restricted Stock Units (RSUs). Imagine this: when you choose the ‘sell to cover’ method, any increase in share value from the vesting date to the sale date is subject to capital gains tax. For example, if Jay and Emma’s RSUs vest at $50 per share and they sell them later at $70, they face a $20 gain per share that incurs capital gains tax.
On the other hand, with the ‘withhold to cover’ approach, taxes are only triggered when the shares are ultimately sold. This potential for tax deferral can be a significant advantage. It’s crucial for families to evaluate their long-term investment strategies and the associated capital gains tax liabilities. Research shows that timing your sales wisely and understanding your tax brackets can lead to substantial savings, allowing for more informed financial decisions.
Consider Emily and Mark, who are thoughtfully managing their financial future. They should keep in mind the long-term capital gains tax rate of 15% for income between $89,251 and $553,850 as they plan their sales. Additionally, it’s important to recognize that RSU income contributes to total income, which may affect eligibility for means-tested benefits.
Consulting with tax experts can provide valuable insights into optimizing these strategies, ensuring your family’s financial objectives align with effective tax management. By utilizing tailored wealth management options, such as those offered by Bright Advisers, families can navigate these complexities with confidence, enhancing their economic security and independence.
To make the most of these opportunities, we encourage you to review your RSU vesting schedule and thoughtfully plan your sales. Remember, we’re here for you, and together, we can navigate this journey toward financial stability.
Employer Policies: How They Affect RSU Tax Strategies
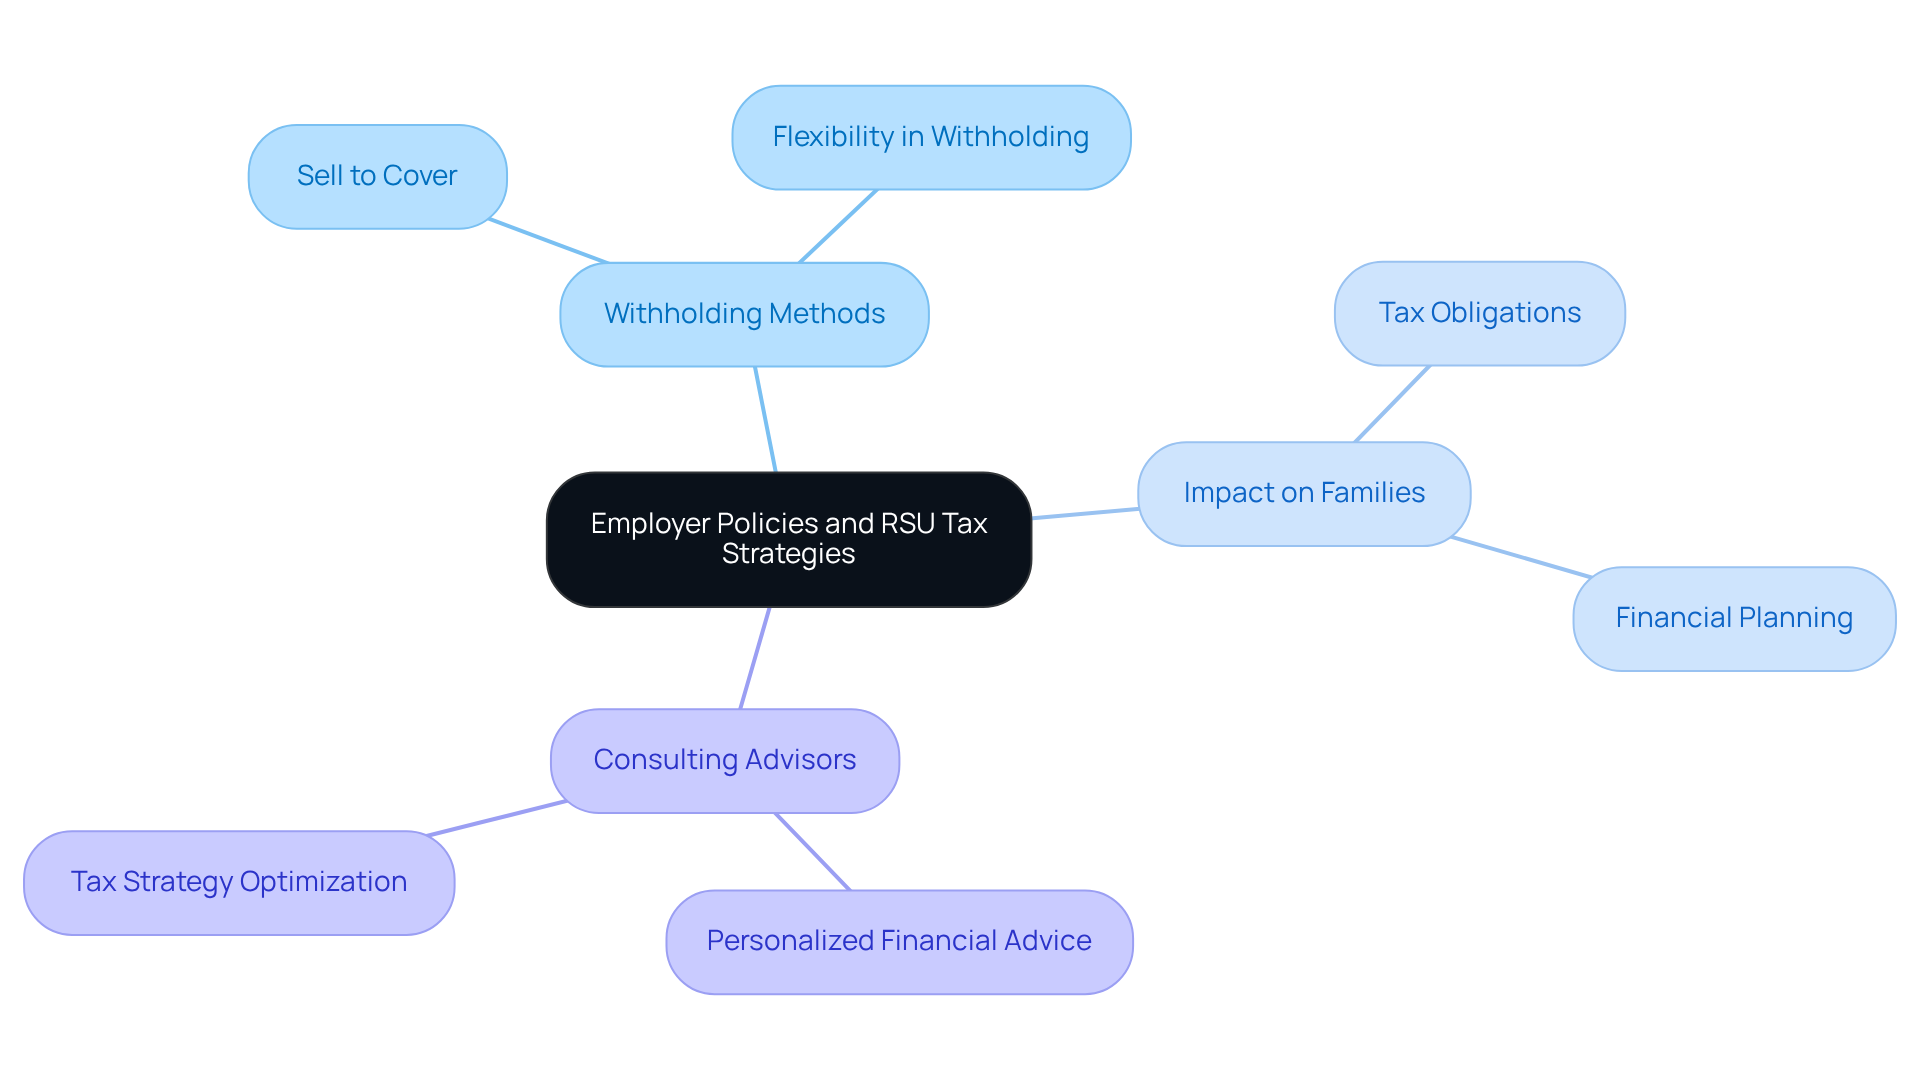
Employer policies play a crucial role in how Restricted Stock Units (RSUs) are managed, directly impacting the options available to employees like you. Imagine navigating a situation where your company mandates specific withholding methods, such as ‘sell to cover’, which requires you to sell a portion of your vested shares just to meet tax obligations. On the other hand, some employers provide greater flexibility, permitting you to decide between withholding to cover and selling to cover. Understanding these policies is essential for families as they develop their tax strategies and overall financial planning.
It’s important to grasp how clarity in RSU management can help prevent costly mistakes and unexpected tax liabilities. For instance, consider households like Allison and Brian, who collaborated with Bright Advisers. They optimized their tax situation and secured their children’s future through education funding, ultimately giving them the ability to retire sooner. This illustrates how being well-informed about employer RSU policies can empower families to prepare for tax implications while enhancing their economic outcomes.
Discussing your situation with a monetary consultant can further deepen your understanding, ensuring you make knowledgeable choices that align with your long-term financial goals. Remember, the case studies mentioned are hypothetical and do not guarantee similar results for all clients. Together, we can navigate this journey. To enhance your financial approach, think about reaching out to a consultant for personalized advice tailored to your family’s needs.
Role of Financial Advisors: Navigating RSU Strategies
Financial advisors are here to support you through the complexities of Restricted Stock Unit (RSU) approaches, understanding that every household has unique financial needs and dreams. Imagine being able to optimize your tax situation just like Allison and Brian did with the help of Bright Advisers. They implemented tailored tax planning strategies, such as tax-loss harvesting and strategic timing of RSU sales, which empowered them to secure their children’s education and even retire sooner.
It’s important to evaluate the tax consequences of different RSU management strategies, particularly when considering withhold to cover vs sell to cover. With the right guidance, you can ensure optimal cash flow and prepare for future tax obligations. By partnering with a monetary consultant, you can develop a comprehensive strategy that aligns your RSU management with your family’s broader economic goals.
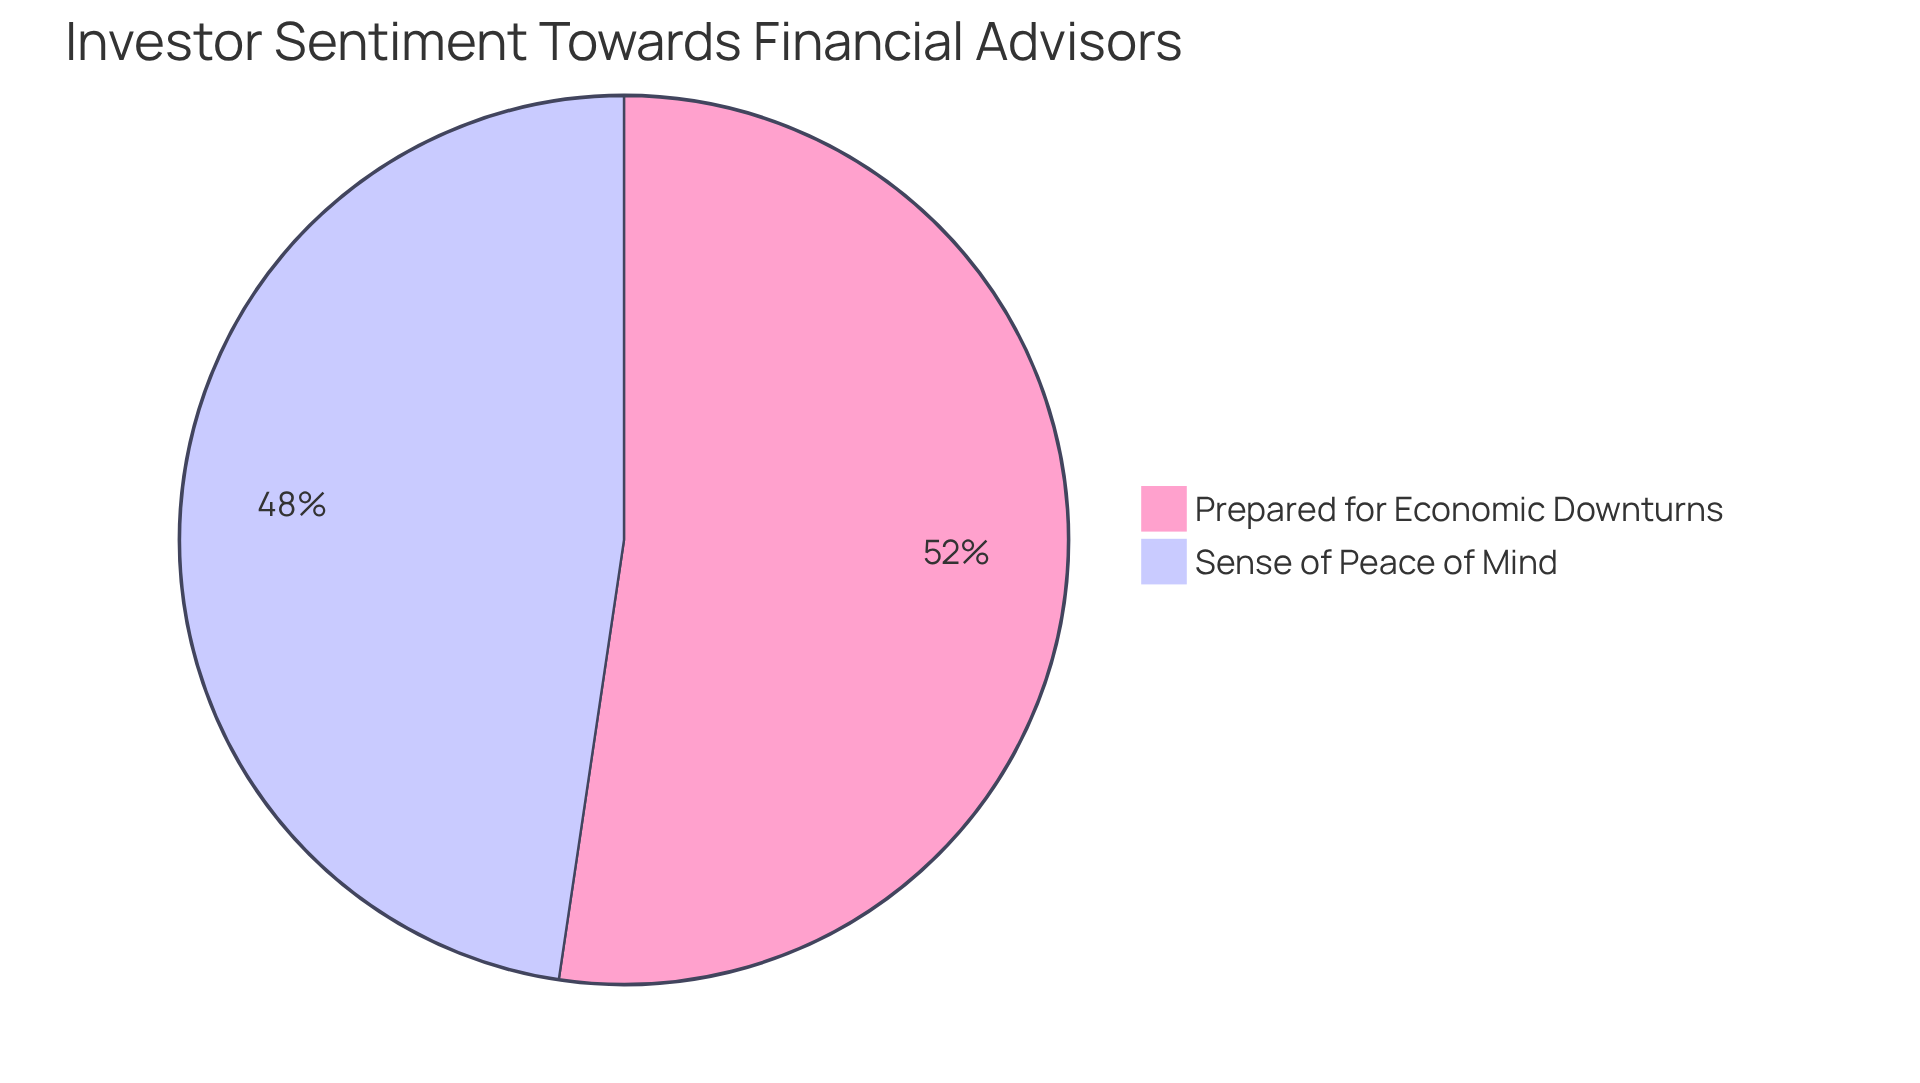
Statistics reveal that 67% of investors who work with an advisor feel prepared for economic downturns. This highlights the invaluable support that professional guidance provides in navigating the often overwhelming financial landscape. Furthermore, 61% of investors report feeling a sense of peace of mind when working with an advisor, showcasing the reassurance that comes from expert support in managing RSUs effectively.
Together, we can navigate this journey and ensure your family’s financial future is secure. We’re here for you, ready to help you take the next steps toward financial stability and peace of mind.
Common Misconceptions: Clarifying RSU Tax Strategies
Misunderstandings about RSU tax strategies can lead to significant confusion for families. Imagine if you believed that holding onto RSUs for a long time would always mean lower expenses. In reality, taxes are incurred at the time of vesting, and any appreciation thereafter may be subject to capital gains tax. For example, if RSUs vest at a fair market value of $100 and later sell for $150, that $50 gain is taxable as capital gains.
It’s important to understand that another common misunderstanding is that the strategy of ‘withhold to cover vs sell to cover’ is always viewed as the best choice. This method may not align with every household’s unique financial goals. Some families might find that the decision to withhold to cover vs sell to cover when selling shares immediately after vesting allows for better cash flow management and diversification of their investment portfolio.
We’re here for you, and informing families about these misconceptions is essential for effective RSU management. This knowledge empowers you to make informed choices that align with your long-term financial objectives. Engaging with tax experts can provide additional insight into these strategies, helping families navigate the complexities of RSUs with confidence. Together, we can navigate this journey and ensure that your financial future is secure.

Strategic Planning: Maximizing Benefits of RSU Management
To fully embrace the benefits of Restricted Stock Units (RSUs), it’s essential for families to engage in thoughtful planning that aligns with their overall economic goals. Imagine assessing the timing of vesting, understanding the tax implications, and deciding whether to sell or hold onto shares. One common approach involves the debate of withhold to cover vs sell to cover, where a portion of vested shares is sold to meet tax obligations. This strategy helps families manage their cash flow while retaining shares for potential growth.
For families like Emily and Mark, who face unique financial challenges, partnering with Bright Advisers can provide tailored tax planning strategies that enhance their economic potential. It’s important to remember that diversifying investments is crucial to minimizing the risks associated with holding a concentrated position in company stock, which can leave families vulnerable to market fluctuations.
Investment advisors emphasize that incorporating RSUs into a comprehensive strategy not only increases their value but also supports long-term wealth-building goals. Consulting with a financial advisor can empower families to navigate the complexities of RSUs, ensuring they feel confident and secure in their financial future. Together, we can navigate this journey and build a brighter tomorrow for your family.

Conclusion
Understanding the intricacies of Restricted Stock Units (RSUs) can be pivotal for families aiming to maximize their financial potential. Imagine if you could align your tax strategies with your long-term financial goals. The discussion around ‘withhold to cover vs sell to cover’ highlights the importance of this alignment. Each method presents unique benefits and challenges that can significantly impact a household’s economic health, particularly in terms of cash flow and investment growth.
Throughout this journey, key insights reveal how strategic planning around RSUs can empower families to navigate tax liabilities effectively. The ‘withhold to cover’ strategy simplifies immediate tax obligations but may limit future growth potential. On the other hand, ‘sell to cover’ provides liquidity to meet pressing financial needs. It’s important to understand the timing of tax implications, the role of employer policies, and the value of professional financial advice as critical components in making informed decisions.
Ultimately, we’re here for you. Engaging with a financial advisor can enhance your family’s approach to RSUs, ensuring that your strategies are tailored to your unique circumstances. By taking proactive steps to understand and manage these assets, families can secure their financial future and work towards their long-term aspirations. Together, we can navigate this journey, embracing these insights to lead to more confident financial planning, enabling a brighter tomorrow for you and your loved ones.
Frequently Asked Questions
What services does Bright Advisers provide for managing RSUs?
Bright Advisers offers personalized financial planning for managing Restricted Stock Units (RSUs), focusing on creating comprehensive monetary plans that align with families’ values and aspirations. They utilize advanced planning software and data analytics to craft tailored strategies, particularly for families with young children.
How does Bright Advisers help families with tax implications related to RSUs?
Bright Advisers helps families navigate tax implications by implementing targeted tax strategies, eliminating excessive fund charges, and taking advantage of tax-loss harvesting opportunities to improve financial outcomes.
What is the importance of having a long-term financial plan?
In 2024, only 36% of U.S. households have a long-term financial plan, highlighting the critical need for personalized financial planning tailored to individual family needs.
What is the ‘withhold to cover’ strategy in managing RSU tax liabilities?
The ‘withhold to cover’ strategy allows employers to retain a portion of vested RSUs to address tax liabilities incurred at vesting, simplifying tax management and reducing the need for cash to pay taxes out of pocket.
What are the potential downsides of the ‘withhold to cover’ strategy?
While ‘withhold to cover’ simplifies immediate tax obligations, it may limit the number of shares available for future growth, which could impact long-term wealth-building goals.
How does the ‘sell to cover’ strategy work for tax obligations?
The ‘sell to cover’ strategy allows employees to sell a portion of their vested RSUs to meet tax obligations arising upon vesting, helping preserve liquidity without straining cash flow.
What are the benefits of using the ‘sell to cover’ strategy?
This strategy allows families to sell just enough shares to cover taxes while retaining remaining shares for potential future appreciation, aligning with long-term investment goals.
Why is it important for young professionals to understand equity compensation like RSUs?
Over half of young professionals consider equity compensation, such as RSUs, a vital factor when evaluating job offers, making it crucial to understand how to manage these assets effectively for financial planning.
How can families maximize their financial potential regarding RSUs?
Families can maximize their financial potential by consulting with financial experts who can help them explore strategies like ‘withhold to cover’ and ‘sell to cover’ to enhance their overall wealth management.
List of Sources
- Bright Advisers: Personalized Financial Planning for RSUs
- 13 Important Personal Finance Stats You Need to Know – Savology (https://savology.com/13-financial-statistics-you-need-to-know)
- 27 eye-opening financial planning statistics (https://contentsnare.com/financial-planning-statistics)
- The State of Personal Finance in America (https://ramseysolutions.com/budgeting/state-of-personal-finance?srsltid=AfmBOoojKI9QWwJKlFcGawHnJriWx0K_Nw0jDgYhte07msb_kjKkxwhJ)
- 20 + Personal Finance Statistics for 2025 | Fortunly (https://fortunly.com/statistics/personal-finance-statistics)
- Personal Finance Statistics and Data Analysis – NerdWallet (https://nerdwallet.com/h/data/studies-and-data-analysis)
- Withhold to Cover: Understanding Tax Liability Management
- RSU Taxes Explained + 4 Tax Strategies for 2023 (https://cordantwealth.com/rsus-tax-saving-and-hedging)
- Top 4 Ways to Reduce Taxes on RSU Income | Consilio Wealth Advisors (https://consiliowealth.com/insights/top-4-ways-to-reduce-taxes-on-rsu-income)
- Restricted Stock Units (RSUs): A Comprehensive Guide (https://snowbirdswealthmanagement.com/blog/2023/05/30/restricted-stock-units-rsus-a-comprehensive-guide)
- Restricted stock units (https://tciwealth.com/equity-compensation/restricted-stock-units)
- Managing RSUs: 3 Tax-Efficient Strategies | SageMint Wealth (https://sagemintwealth.com/3-tax-efficient-strategies-for-managing-rsus)
- Sell to Cover: A Strategy for Tax Obligation Fulfillment
- The Sell to Cover Tax Strategy for Restricted Stock Units (RSUs) (https://kubera.com/blog/sell-to-cover-rsu)
- Your Guide to Navigating RSU Taxation | Massey and Company CPA (https://masseyandcompanycpa.com/your-guide-to-navigating-rsu-taxation)
- RSUs Explained: How Restricted Stock Units Work & Are Taxed (https://vestedfinance.com/blog/us-stocks/rsus-a-comprehensive-guide-to-restricted-stock-units)
- The Ultimate Guide to Sell-to-Cover Transactions for Public Companies (https://candor.co/articles/issuer-knowledge/the-ultimate-guide-to-sell-to-cover-transactions-for-public-companies)
- Sell to Cover RSU: Tax Strategies & Tips — Brooklyn Fi (https://brooklynfi.com/blog/sell-to-cover-rsu)
- Timing of Tax Implications: Key Considerations for RSU Holders
- Restricted Stock Unit (RSU): A Complete Guide to RSUs (https://carta.com/learn/equity/rsu)
- Restricted Stock Units (RSUs): Everything You Need to Know (https://harness.co/articles/what-you-need-to-know-about-restricted-stock-units-rsus)
- Tax considerations for public company equity incentive awards | DLA Piper (https://dlapiper.com/en-us/insights/publications/2025/03/tax-considerations-for-public-company-equity-incentive-awards)
- Restricted Stock Unit (RSU): How It Works and Pros and Cons (https://investopedia.com/terms/r/restricted-stock-unit.asp)
- Time is Gold: Optimizing Tax Treatment on Restricted Stock Units (RSU) | US Expat Tax Service (https://taxesforexpats.com/articles/tax-saving-strategies/effectively-manage-the-timing-of-restricted-stock-units-rsu-to-receive-optimal-tax-treatment.html)
- Cash Flow Impact: Comparing Withhold to Cover and Sell to Cover
- Restricted Stock & RSUs: 3 Planning Tips From Top Financial Advisors (https://forbes.com/sites/brucebrumberg/2021/06/17/restricted-stock–rsus-3-planning-tips-from-top-financial-advisors)
- Cash Flow Management Statistics 2025 – Everything You Need to Know (https://llcbuddy.com/data/cash-flow-management-statistics)
- 24 Cash Flow Metrics and KPIs (https://netsuite.com/portal/resource/articles/accounting/cashflow-metrics.shtml)
- Restricted Stock Units, Cash Flow, Income Tax, and Concentration (https://zajacgrp.com/insights/how-to-prepare-for-the-impact-of-restricted-stock-units-on-your-cash-flow-tax-bill-and-investment-portfolio)
- Capital Gains Tax Implications: Analyzing Both Strategies
- RSU Taxes Explained + 4 Tax Strategies for 2023 (https://cordantwealth.com/rsus-tax-saving-and-hedging)
- RSUs 101: A Tech Professional’s Guide to Equity, Tax Strategy, and Financial Planning (https://merceradvisors.com/insights/investing/rsus-101-a-tech-professionals-guide-to-equity-tax-strategy-and-financial-planning)
- SOI Tax Stats – Sales of capital assets reported on individual tax returns | Internal Revenue Service (https://irs.gov/statistics/soi-tax-stats-sales-of-capital-assets-reported-on-individual-tax-returns)
- How Restricted Stock Units (RSUs) are Taxed! | Learn it All! (https://mytaxaccountant.co.uk/post/how-rsus-are-taxed)
- Capital Gains Taxes: An Overview of the Issues (https://congress.gov/crs-product/R47113)
- Employer Policies: How They Affect RSU Tax Strategies
- The Most Common RSU Mistakes — And How to Avoid Them (https://plancorp.com/blog/restricted-stock-unit-rsu-mistakes)
- Restricted Stock Unit (RSU): A Complete Guide to RSUs (https://carta.com/learn/equity/rsu)
- The Taxation of Restricted Stock Units | Cerity Partners (https://ceritypartners.com/insights/the-taxation-of-restricted-stock-units)
- RSU Taxes Explained + 4 Tax Strategies for 2023 (https://cordantwealth.com/rsus-tax-saving-and-hedging)
- Restricted Stock, RSUs, and Tax Implications – Baker Newman Noyes (https://bnncpa.com/resources/restricted-stock-rsus-and-tax-implications)
- Role of Financial Advisors: Navigating RSU Strategies
- 77 Financial Advisor Quotes to Send to Clients (https://billgoodmarketing.com/resources/financial-advisor-quotes)
- Wealth Management Statistics – Facts, Tips & Basics (https://plancorp.com/blog/wealth-management-statistics-facts-tips-basics)
- digitaldefynd.com (https://digitaldefynd.com/IQ/financial-planning-quotes)
- 20+ Financial Advisor Statistics You Must Know in ([currentyear]) (https://upmetrics.co/blog/financial-advisor-statistics)
- Common Misconceptions: Clarifying RSU Tax Strategies
- RSU Taxes: How Are Restricted Stock Units (RSUs) Taxed? | Facet (https://facet.com/equity/rsu-taxes-calculations-reporting-strategies)
- 5 Must-Know Facts About RSUs Before You Cash In (https://juliemerrill.me/blog/5-must-know-facts-about-rsus-restricted-stock-units-before-you-cash-in)
- Thimbleberry Financial (https://thimbleberryfinancial.com/rsu-tax-misconceptions)
- Restricted Stock Units and How They Work | Wealthspire (https://wealthspire.com/blog/restricted-stock-units-rsus-how-they-work-6-common-misconceptions)
- Navigating the Maze: Understanding and Maximizing Your RSU & ISO Benefits – Confluence Financial Partners (https://confluencefp.com/navigating-the-maze-understanding-and-maximizing-your-rsu-iso-benefits)
- Strategic Planning: Maximizing Benefits of RSU Management
- Inspiring Quotes about Strategic Planning – Funding for Good (https://fundingforgood.org/inspiring-quotes-about-strategic-planning)
- Maximizing Wealth with Restricted Stock Units (RSUs): A Guide for High-Income Earners — LA Wealth Management (https://lawealthmanagement.com/lawm-blog/2024/12/16/maximizing-wealth-with-restricted-stock-units-rsus-a-guide-for-high-income-earners)
- RSU Tax Management: Strategies to Help Maximize Your Wealth and Minimize Taxes (https://investorsportfolioservices.com/comprehensive-rsu-tax-strategies-and-planning)
- Restricted Stock And RSUs: 3 Planning Tips (https://calbizjournal.com/restricted-stock-and-rsus-3-planning-tips)
- Maximizing RSU Benefits through Long-Term Financial Planning (https://upstock.io/post/maximizing-rsu-benefits-through-long-term-financial-planning)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Tax Management for high-income W-2 families at Bright Advisers.
Keep reading