

Overview
The Backdoor Roth IRA strategy, which began with the Taxpayer Relief Act of 1997, has become a beacon of hope for families since the 2010 Tax Act lifted income limits on IRA conversions. This change allows high-income earners to convert traditional IRAs into Roth IRAs, creating a pathway for tax-free growth in retirement savings. Imagine the peace of mind that comes from knowing your family’s financial future is secure.
Understanding these legislative changes is essential for families looking to maximize their savings. It’s important to seek professional guidance to navigate this complex financial landscape. Together, we can explore the opportunities that lie ahead and ensure that your family’s financial journey is as smooth as possible. Remember, we’re here for you every step of the way.
Key Highlights:
- The Backdoor Roth IRA strategy originated with the Taxpayer Relief Act of 1997 and was significantly advanced by the Tax Increase Prevention and Reconciliation Act of 2005.
- In 2010, Congress lifted the income cap on Roth IRA conversions, allowing high-income earners to convert traditional IRAs into Roth IRAs without penalties.
- As of 2022, 82% of top-income earners contributed to 401(k)-type plans, reflecting a shift in retirement savings dynamics influenced by fintech.
- The 2010 Tax Act removed the $100,000 income cap on conversions, reshaping retirement planning for high earners.
- Financial advisors play a crucial role in educating families about Backdoor IRAs and customizing strategies to optimize retirement savings.
- The IRS mandates the use of Form 8606 to report nondeductible contributions and conversions, ensuring compliance with tax regulations.
- The five-year rule is essential for tax-free withdrawals from a Roth IRA, emphasizing the importance of long-term planning.
- Concerns about potential legislative changes to the Backdoor Roth IRA strategy highlight the need for families to stay informed and proactive.
- Emerging technologies facilitate the management of retirement accounts, making it easier for families to execute Backdoor Roth IRA strategies.
- The future of Backdoor Roth IRAs may be uncertain due to legislative scrutiny, prompting families to act while the strategy remains viable.
Introduction
In recent years, the Backdoor Roth IRA has emerged as a crucial strategy for high-income earners who want to maximize their retirement savings without the burden of income limits. Imagine a pathway that allows you to secure a financially stable future for your family. This innovative approach, rooted in legislative changes dating back to the late 1990s, has gained traction, especially after the removal of income caps on Roth IRA conversions in 2010. As affluent families increasingly recognize the potential for tax-free growth and withdrawals, it’s important to understand the intricacies of this strategy.
With the financial landscape evolving rapidly, young parents and high-wage earners alike are seeking guidance from financial advisors to navigate these complexities and optimize their retirement planning. Together, we can explore how the Backdoor Roth IRA can be a valuable tool in your financial toolkit. This article delves into the historical context, legislative developments, and practical implications of the Backdoor Roth IRA, offering insights that can help you secure your family’s financial future. Remember, we’re here for you every step of the way.
Backdoor Roth IRA: Introduction and Historical Context
The question of when did backdoor Roth IRA start is answered by the introduction of the Backdoor IRA approach with the Taxpayer Relief Act of 1997, which created new retirement savings options. However, it was the Tax Increase Prevention and Reconciliation Act of 2005 that truly paved the way for this strategy, raising the question of when did backdoor Roth IRA start. Imagine the possibilities that emerged in 2010 when Congress lifted the income cap on Roth IRA conversions and consider when did backdoor Roth IRA start. This change allowed high-income earners to navigate around traditional contribution limits, converting funds from a traditional IRA into a Roth IRA with ease.
As of 2022, a remarkable 82 percent of contributors in the top income tercile already had a 401(k)-type plan, highlighting the economic landscape that affluent individuals navigate. Alicia H. Munnell points out that fintech has played a significant role in shifting the age distribution of contributors, with young, tech-savvy investors increasingly opting for mobile solutions to manage their retirement savings.
Furthermore, the adaptability showcased by the Employee Solo 401(k) Contributions case study illustrates the various choices available for retirement savings. This is especially significant for young parents contemplating their economic futures. This legislative shift not only broadened access to individual retirement accounts but also underscored the evolving environment of retirement savings options available to wealthy individuals, raising the question of when did backdoor Roth IRA start, which young parents should understand and utilize as a crucial step in building a strong financial foundation for their families. Together, we can navigate this journey, aligning with Bright Advisers’ commitment to providing accessible wealth management solutions. Remember, we’re here for you, ready to support you in making informed decisions that benefit your family’s future.

Legislative Changes: Key Laws Impacting Backdoor Roth IRA Development
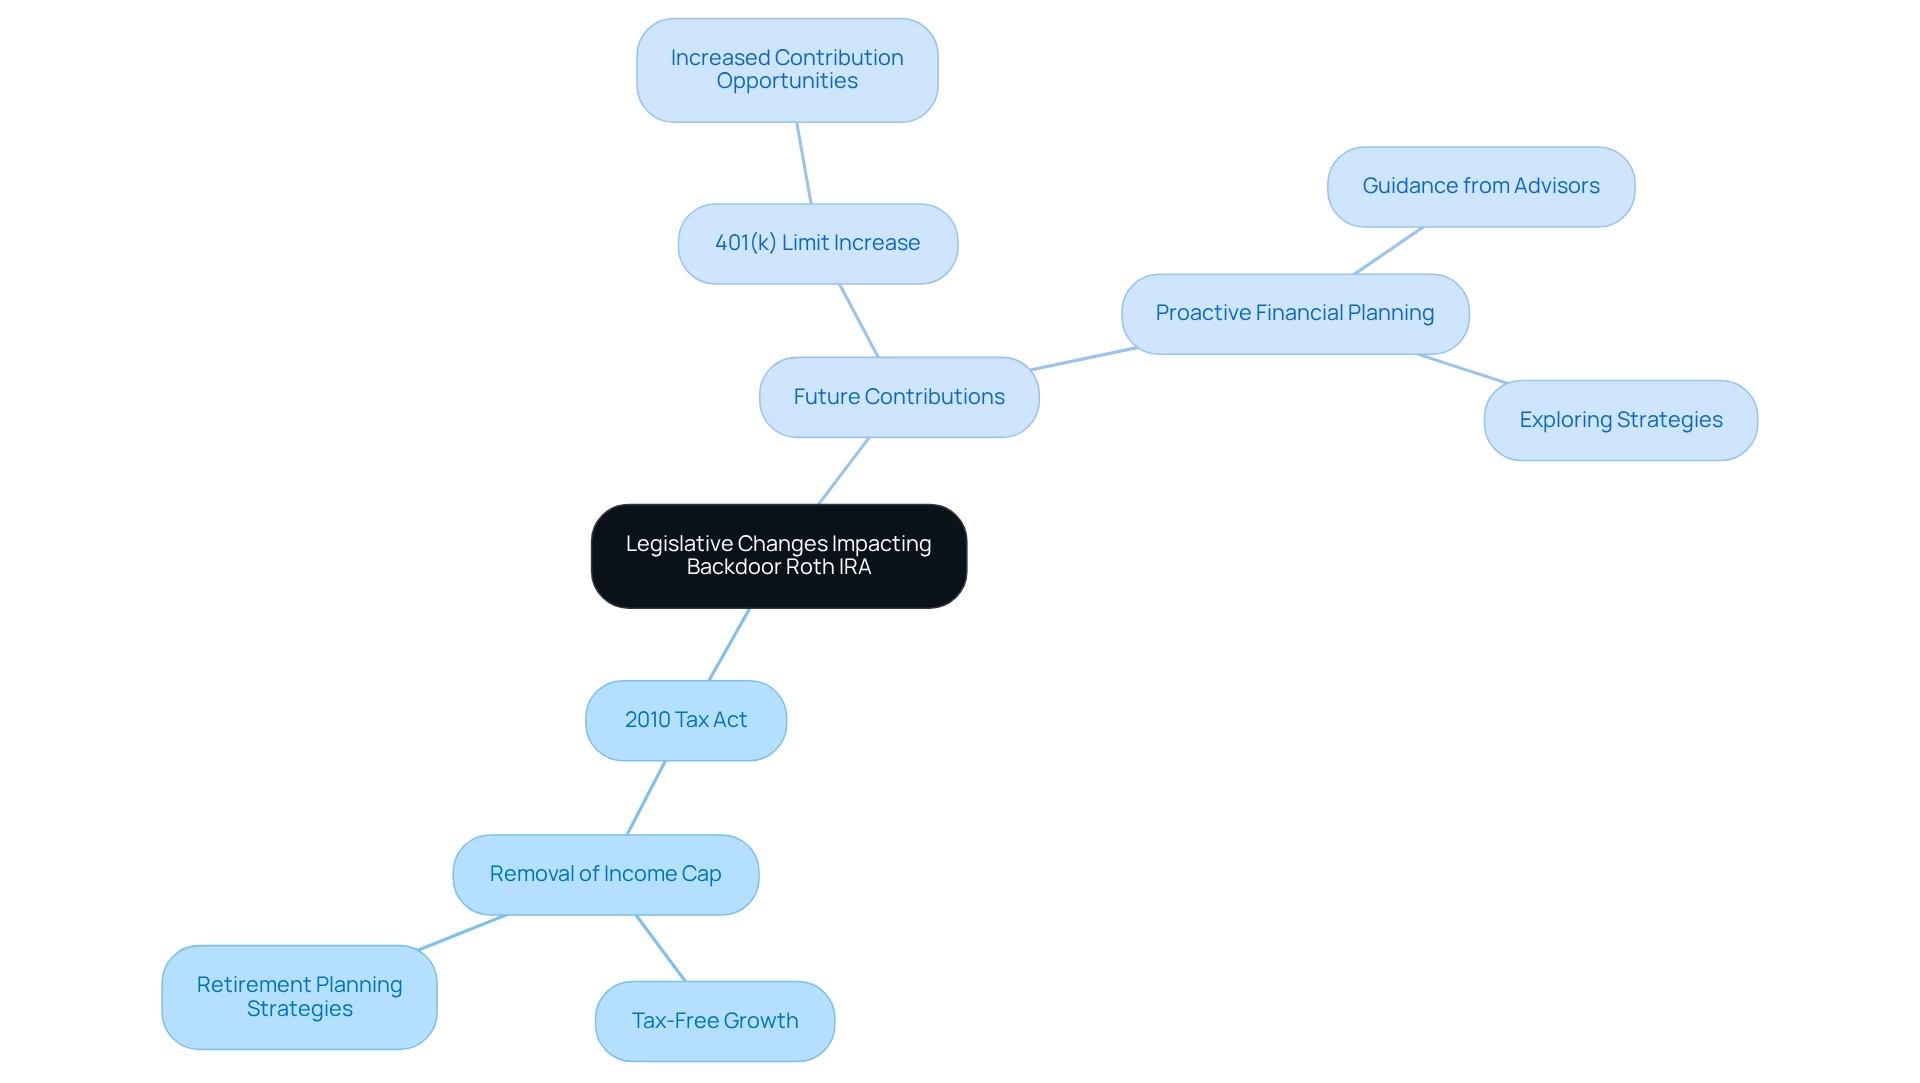
Many families wonder when did Backdoor Roth IRA start, as the 2010 Tax Act played a crucial role in making it more accessible. The removal of the $100,000 income cap on conversions raised questions about when did backdoor Roth IRA start, allowing individuals with higher incomes to transition their traditional IRAs into Roth-style accounts without facing penalties. This change has created meaningful opportunities for many to enjoy the tax-free growth potential of individual retirement accounts and raises the question of when did backdoor Roth IRA start, fundamentally reshaping retirement planning strategies for high earners.
As we look ahead to 2025, the 401(k) limit has increased to $23,500, underscoring the importance of understanding diverse retirement savings options. Steven Jarvis, CEO and Head CPA at Retirement Tax Services, highlights, ‘Congress has left open a backdoor, which raises the question of when did backdoor Roth IRA start, allowing us to contribute to a retirement account each year, albeit with an extra step.’ This insight emphasizes the ongoing potential for contributions to retirement accounts.
For young caregivers, proactive financial planning is essential. Imagine if you could secure your family’s future with informed decisions. Seeking guidance from a consultant can provide valuable insights into exploring strategies for when did Backdoor Roth IRA start. At Bright Advisers, we focus on personalized financial planning that aligns with your family’s values and vision. Together, we ensure you have the right strategies in place for retirement, education funding, and more.
Our commitment to minimizing fund fees enhances wealth management accessibility, empowering you to establish a stable financial future for your family. Remember, we’re here for you—navigating this journey together can make all the difference.
Early Adoption: When Investors Embraced the Backdoor Roth IRA
Since the implementation of the 2010 Tax Act, many high-income families have discovered the benefits of the Backdoor IRA, raising the question of when did Backdoor Roth IRA start. This approach has gained popularity as families recognize the significant advantages of tax-free growth and withdrawals during retirement. Imagine feeling restricted by income thresholds that once kept you from contributing directly to an IRA; now, more people are asking when did Backdoor Roth IRA start. Data shows that a considerable number of high-income individuals are embracing this strategy, reflecting a broader trend toward optimizing tax-efficient retirement savings, especially regarding when did Backdoor Roth IRA start, as its allure of tax-free growth is compelling for families keen on securing their financial future.
Financial specialists encourage all high-income earners to explore both the Backdoor IRA and the mega Backdoor IRA as viable options for enhancing their retirement portfolios, especially considering when did Backdoor Roth IRA start, as executing this strategy correctly is crucial. For instance, failing to submit necessary documentation like Form 8606 and Form 1099-R can lead to double taxation. This highlights the importance of seeking guidance from a financial advisor or tax specialist to navigate the complexities of IRA conversions effectively. Through their partnership with Bright Advisers, Allison and Brian were able to optimize their tax situation, secure their children’s education funding, and gain the freedom to retire sooner. Similarly, Emily and Mark crafted a comprehensive strategy that allowed them to build a life aligned with their aspirations.
As we look ahead to 2025, the contribution limits for retirement 401(k) accounts are set to rise to $23,500, providing even more motivation for high-income earners to consider these tax-advantaged options. The growing trend of Backdoor IRA adoption among families raises the question of when did Backdoor Roth IRA start, illustrating a proactive approach to wealth management and ensuring a strong financial foundation for future generations. Together, we can navigate this journey, creating a secure and prosperous future for our loved ones.

Tax Implications: Understanding the Financial Impact of Backdoor Roth IRAs
Navigating the world of retirement savings can feel overwhelming, especially for young parents. The IRS has laid out specific guidelines for executing a Backdoor IRA, and many people wonder when did Backdoor Roth IRA start as a helpful method that allows individuals to bypass income limits associated with direct IRA contributions. To start, individuals contribute to a traditional IRA, ensuring that this contribution is nondeductible. Afterward, they can convert the traditional IRA into a different type of IRA. It’s important to submit IRS Form 8606 to report both the nondeductible contribution and the conversion, helping you stay compliant with tax regulations.
As we look ahead to 2024, it’s crucial to understand that the phase-out for deducting contributions to a traditional IRA begins at a modified adjusted gross income (AGI) of $77,000 for single filers. This highlights the importance of being aware of income thresholds when considering this approach. Moreover, many individuals are submitting IRS Form 8606 for conversions, reflecting the growing appeal of this method. For young parents like Jay and Emma, who are eager to alleviate financial stress and secure their children’s future, they may wonder when did backdoor roth ira start and realize that utilizing a Backdoor IRA can be a strategic decision. Imagine if they could work with Bright Advisers to receive personalized guidance on effectively applying this approach while keeping their overall financial goals in mind.
Expert insights remind us that following IRS guidelines is key to successful execution. For example, ensuring that the conversion adheres to the five-year rule can lead to tax-free withdrawals, provided all other requirements are met. As tax regulations continue to evolve, staying informed about compliance and potential legislative changes is vital for those considering Backdoor IRA accounts. Recent discussions about the future of this approach suggest that clients should act while it remains a viable option, as uncertainty looms over possible changes to the regulations governing conversions.
Together, we can navigate this journey, ensuring that your family’s financial future is secure and bright.

Contribution Limits and Income Thresholds: Evolution Over Time
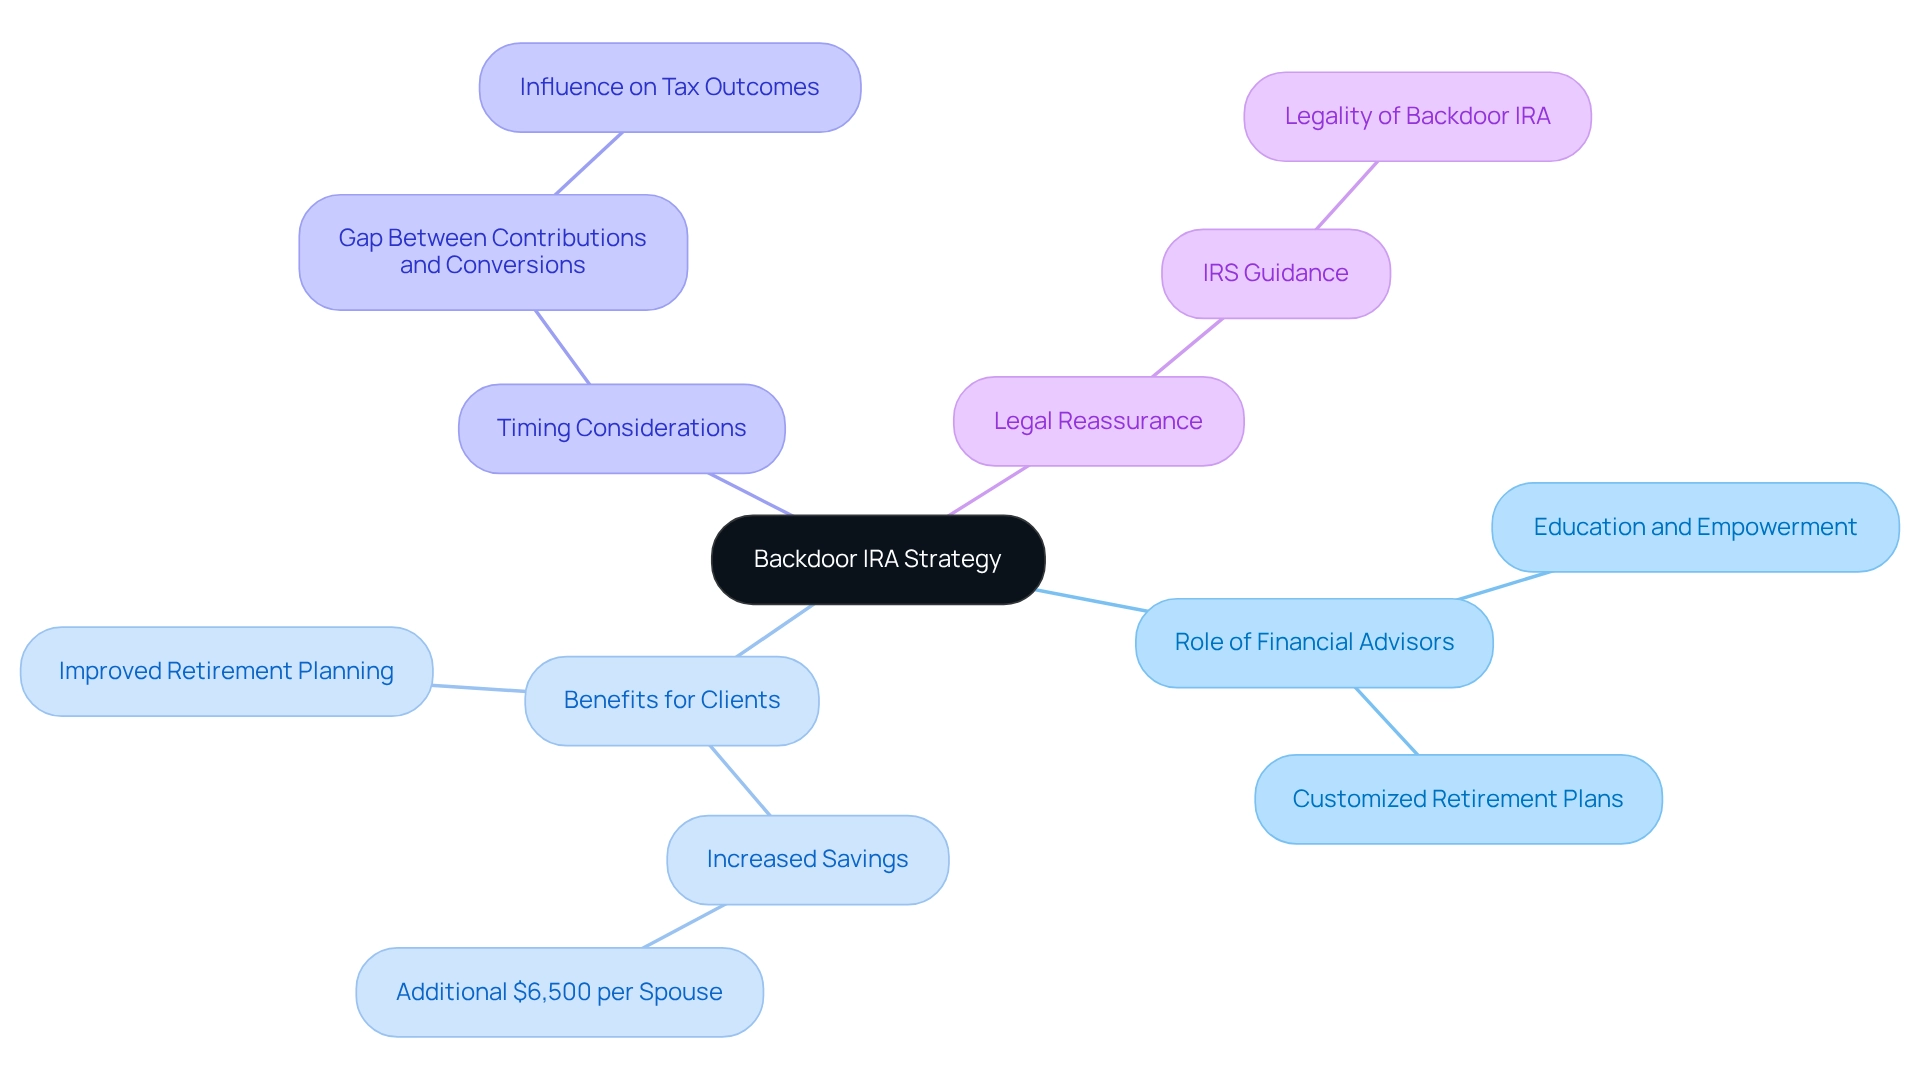
Financial advisors play a vital role in guiding families through the complexities of the Backdoor IRA approach. They understand the unique challenges that high-income earners face, especially when it comes to exceeding traditional contribution limits. By providing essential education on this strategy, advisors help clients feel informed and empowered about their retirement savings.
Imagine a couple like Emily and Mark, who could save an extra $6,500 for each partner through a Backdoor IRA conversion. This significant boost can make a real difference in their financial future. Advisors work closely with families to customize retirement plans, ensuring they can effectively leverage this valuable tool.
It’s important to understand the significance of timing in the conversion process. Industry leader Michael Kitces points out that some clients may find it beneficial to create a gap between their traditional IRA contributions and conversions. This thoughtful approach can influence tax outcomes, enhancing overall retirement plans. Additionally, informal guidance from the IRS has confirmed the legality of the Backdoor IRA, easing concerns for both clients and advisors. This reassurance encourages wealth advisors to actively promote this approach, helping families improve their retirement planning.
In summary, the role of wealth advisors in informing families about the Backdoor IRA is essential. Their expertise fosters a deeper understanding and builds confidence in implementing this strategy, ultimately contributing to more robust retirement planning. To maximize the advantages of the Backdoor IRA, we encourage clients to consult with their advisors, tailoring their strategy to fit their personal financial situations and family goals. Together, we can navigate this journey and secure a brighter financial future for your loved ones.
Role of Financial Advisors: How Bright Advisers Supports Backdoor Roth IRA Strategies
Navigating the tax implications of a Backdoor retirement account can feel overwhelming, especially when did Backdoor Roth IRA start. Imagine if you could simplify this process and secure your family’s financial future. While contributions to a traditional IRA may often be nondeductible, any earnings accrued prior to conversion are subject to taxation.
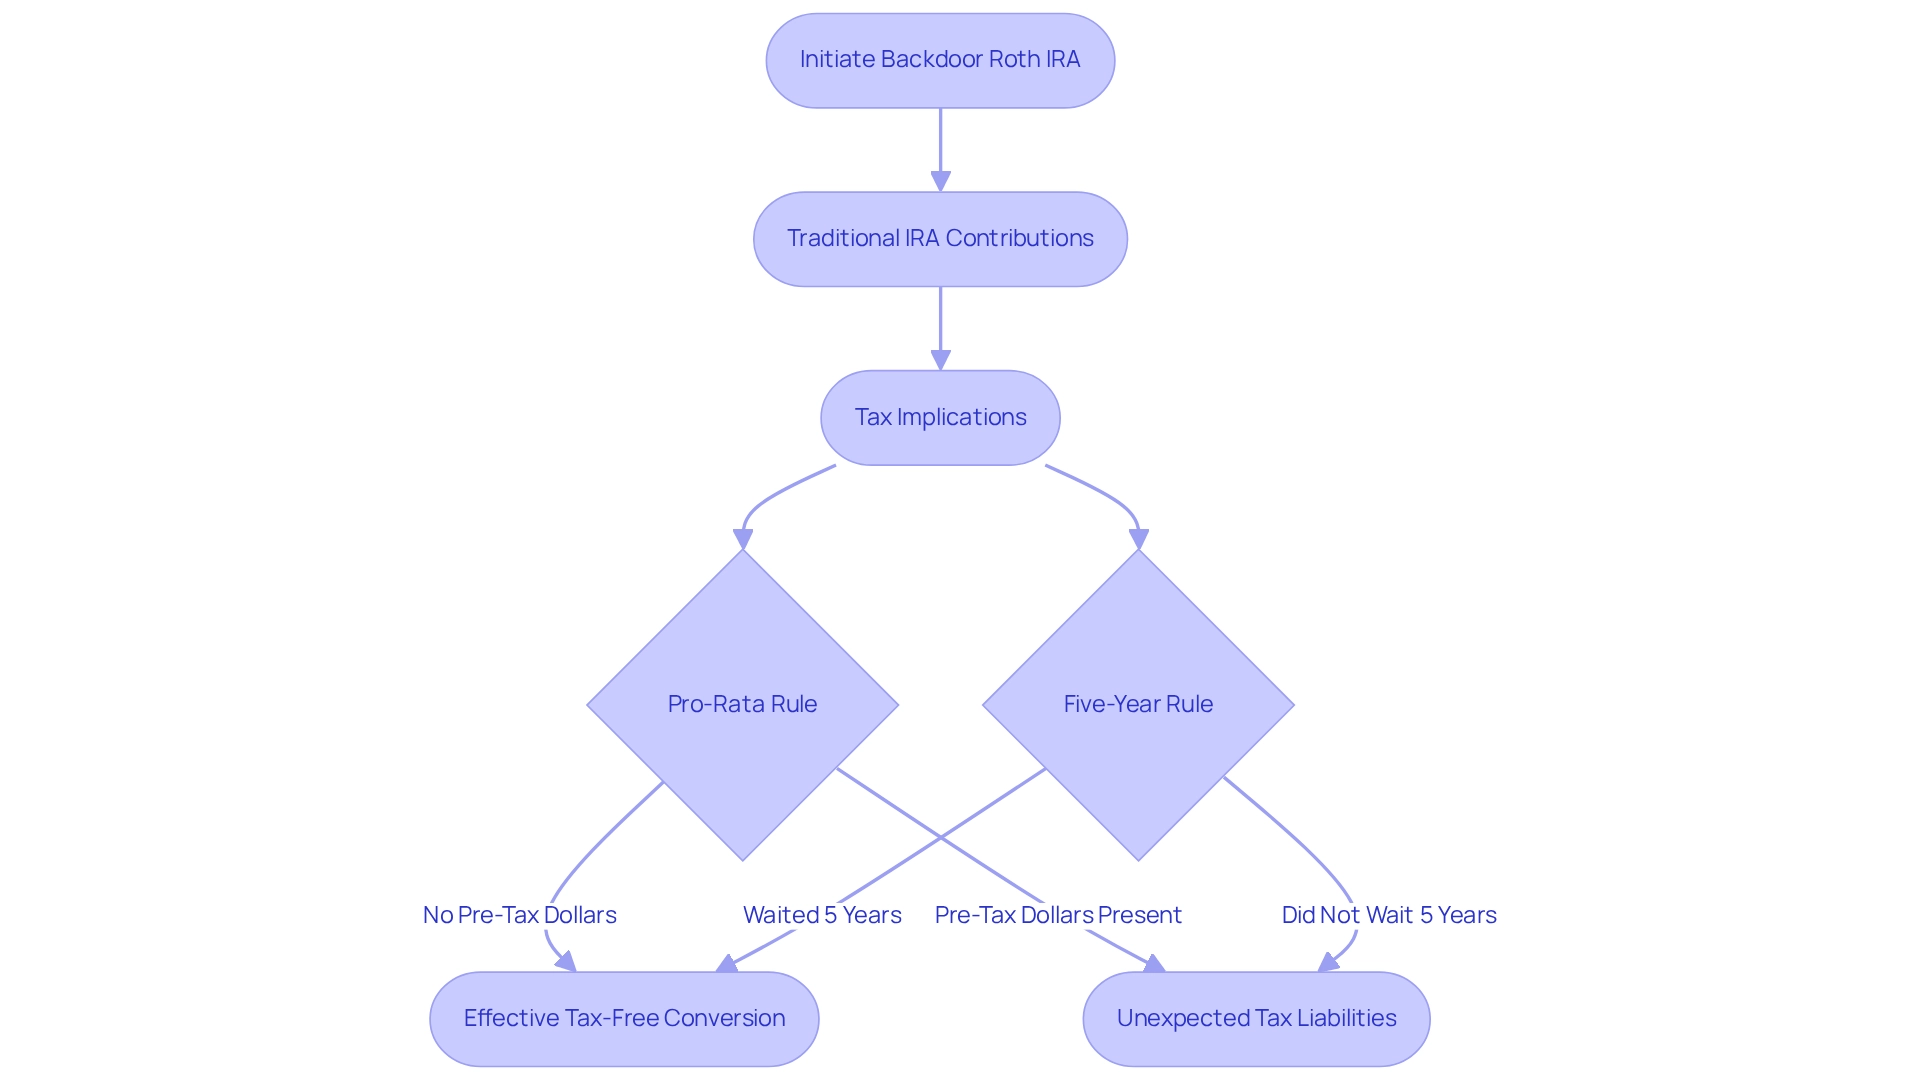
It’s important to understand the IRS’s pro-rata rule, which can complicate things for those with existing traditional IRAs. This rule requires that all IRA balances be considered when determining the taxability of a conversion, which might add to your concerns. For instance, if you have pre-tax dollars in your Traditional IRA, it’s crucial to remove these funds before executing a Backdoor Roth conversion to avoid unexpected tax liabilities. A practical approach could involve rolling over those pre-tax Traditional IRA balances into your employer’s retirement plan. This strategy effectively zeroes out your Traditional IRA, allowing for tax-free conversions.
At Bright Advisers, we’re here for you, providing customized services to assist families like Emily and Mark in managing these complexities. Our personalized financial planning and tax optimization approaches can help you feel more in control. Given these intricacies, consulting with tax professionals is essential to ensure compliance with current regulations and to tailor strategies to your unique circumstances.
Furthermore, understanding the five-year rule is vital. This rule necessitates waiting a minimum of five years after your initial IRA contribution before taking out any tax-free earnings. Together, we can navigate this journey, empowering you to make informed decisions about your retirement planning. Bright Advisers is dedicated to helping clients comprehend these nuances, ensuring you feel supported every step of the way.
Pros and Cons: Evaluating the Backdoor Roth IRA Strategy
When did Backdoor Roth IRA start making it easier for high-income earners to manage their retirement accounts through technological advancements? Many financial institutions, like Bright Advisers, now offer streamlined processes for contributions and conversions, allowing families to handle transactions quickly and efficiently. Imagine being a married filer earning $206,000 or more, where direct contributions to a Roth IRA aren’t an option. Backdoor Roth IRAs have become a vital strategy for you since when did backdoor Roth IRA start. Bright Advisers combines innovative technology with personalized investment strategies, helping families navigate these complexities while aligning their financial planning with long-term goals.
Moreover, online platforms now provide tools to track contributions, conversions, and tax implications, simplifying the management of retirement accounts. As Sandy Adams, CFP®, wisely points out, ‘If you’re 50 or older and concerned about retirement, consider the systematic approach detailed in this article and endorsed by planners nationwide.’ This shift towards automation and user-friendly interfaces not only eases the management of retirement accounts but also empowers families to make informed decisions about their financial futures.
Additionally, Bright Advisers highlights the importance of tax optimization within their comprehensive financial planning, which can lead to meaningful outcomes for families, such as securing education funding and enabling early retirement. The impact of investment returns on education funds, as illustrated in JPMorgan’s College Planning Essentials guide, underscores the value of starting early and employing diverse saving strategies, all of which can be adeptly managed through Backdoor IRAs. Together, we can navigate this journey towards a secure financial future.

Future Outlook: What Lies Ahead for Backdoor Roth IRAs
To understand the current market trends that significantly influence the Backdoor IRA landscape, one might ask when did Backdoor Roth IRA start, especially as interest rates fluctuate and investment opportunities evolve. Imagine the appeal of tax-free growth provided by a traditional IRA becoming increasingly attractive in a rising interest rate environment. This shift encourages high-income earners, like Emily and Mark—a vibrant couple pursuing financial security—to reevaluate their retirement savings plans. Often, this leads them to explore options related to when did Backdoor Roth IRA start as a feasible choice.
For instance, consider Bob and Sue, another high-earning couple. They can employ this approach to contribute to retirement accounts, even though their income surpasses the usual limits. As interest rates rise, the potential for improved returns on investments within an individual retirement account further strengthens its allure.
However, it’s important to recognize that the landscape is not without challenges. Recent congressional examination has raised concerns about affluent individuals potentially exploiting the Backdoor IRA approach, prompting discussions about when did Backdoor Roth IRA start and possible restrictions or elimination. As David Rodeck observes, ‘When did Backdoor Roth IRA start?’ This approach has become a focal point for lawmakers, and families should remain informed about any legislative changes that could affect their retirement planning. While the future remains uncertain, indications suggest that any changes would not be retroactive, encouraging individuals to take advantage of this approach while it remains available.
As market trends continue to change, grasping when did Backdoor Roth IRA start and understanding the effect of interest rates and investment approaches on the Backdoor IRA will be essential for families seeking to ensure their financial futures. Remember, Bright Advisers are here for you, ready to assist families in navigating these complexities and ensuring informed decisions about retirement planning. Together, we can navigate this journey towards a secure financial future for your family.

Myths and Misconceptions: Clarifying Common Misunderstandings About Backdoor Roth IRAs
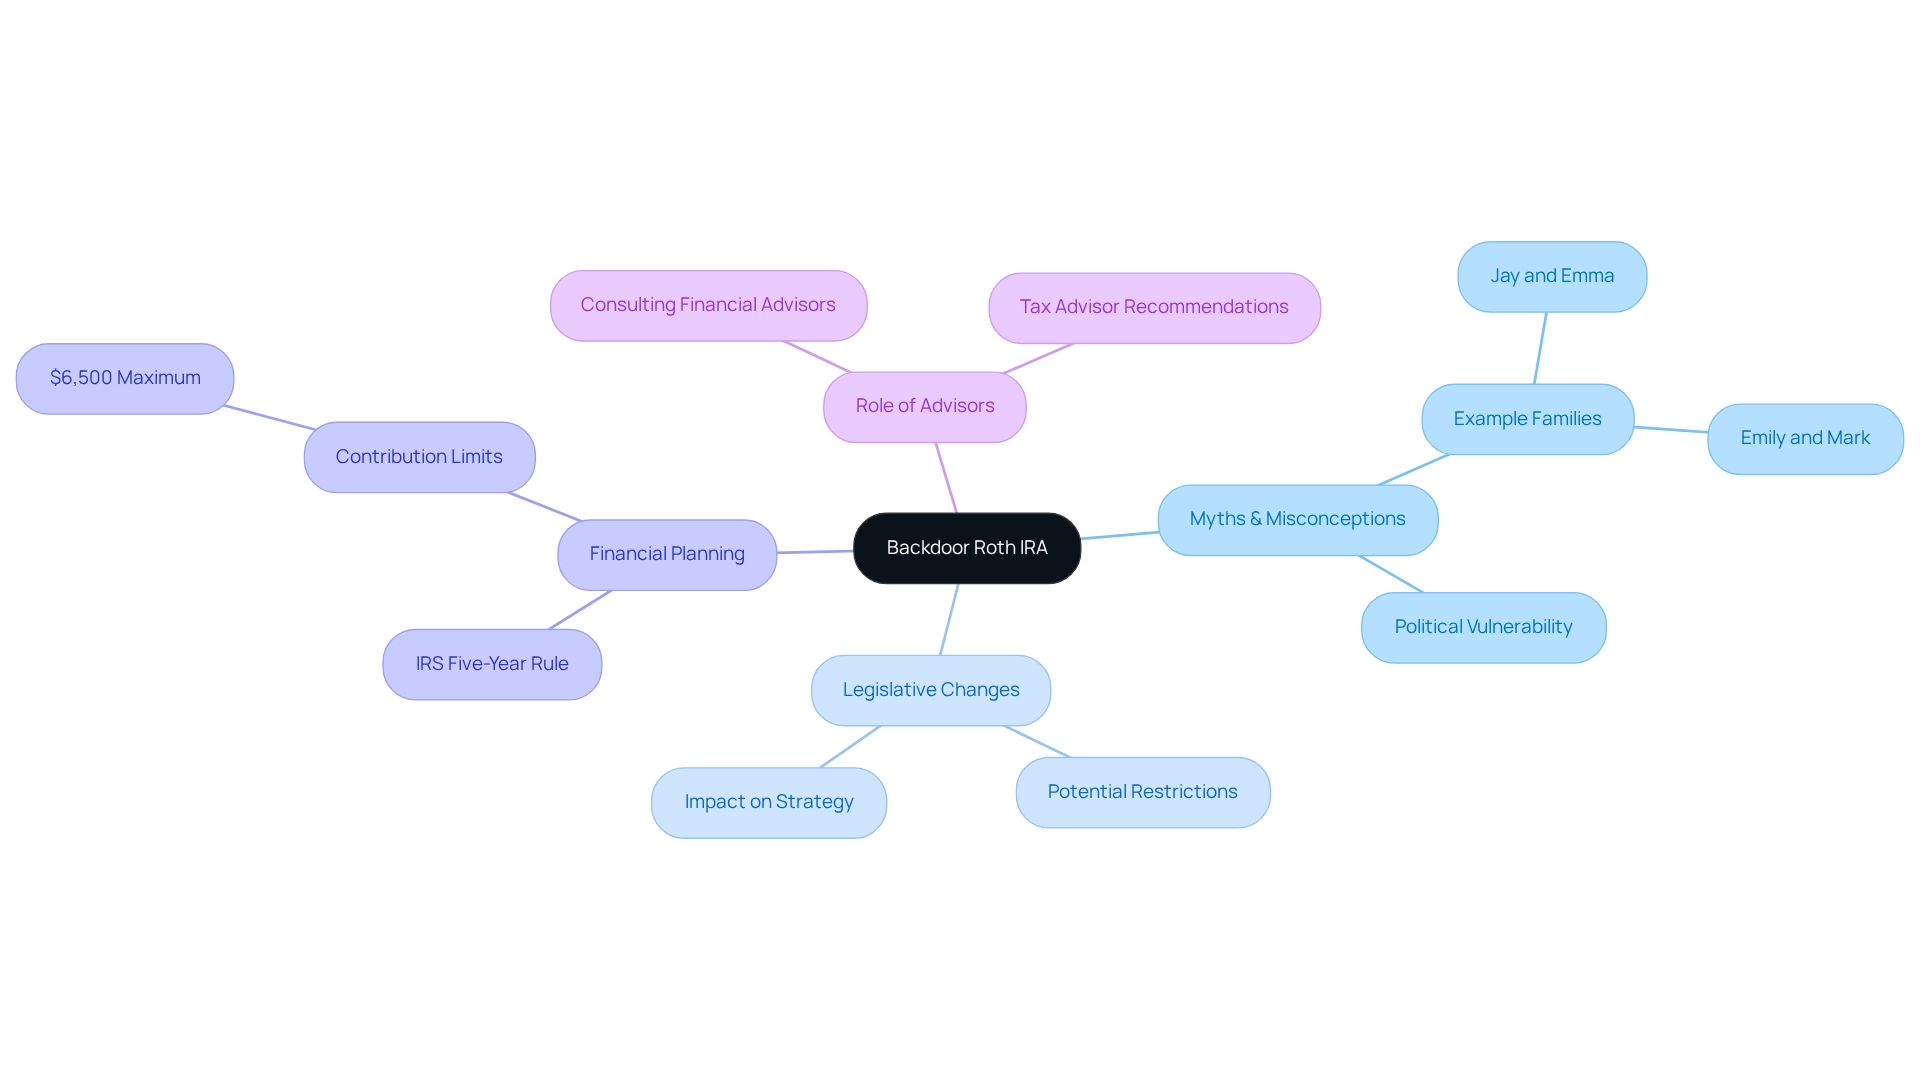
When did backdoor Roth IRA start is a question many have, as the future of the Backdoor IRA can feel uncertain, particularly with discussions about potential legislative changes that might restrict or remove this strategy. However, as long as high-income earners seek tax-efficient retirement savings options, many are curious about when did Backdoor Roth IRA start, which is likely to keep it a popular choice for families. Imagine young parents like Jay and Emma or Emily and Mark—it’s essential for them to stay informed about possible tax regulation changes and consider how these may impact their financial planning.
By collaborating with Bright Advisers, families can create customized wealth management solutions that help them navigate these complexities. This partnership ensures their financial plans align with their long-term goals, offering the freedom to make informed choices about their future. One crucial aspect to keep in mind is the IRS’s five-year holding period requirement for tax-free withdrawals from an individual retirement account. This underscores the importance of long-term planning.
Seeking guidance from a financial advisor is vital to effectively manage the intricacies of this approach. For instance, consider a scenario where a nondeductible contribution to a traditional IRA is immediately converted into a different type of IRA. This strategy helps avoid taxes on any earnings accrued before the conversion, maximizing the advantages of the Backdoor IRA method, which raises the question: when did Backdoor Roth IRA start? It allows families to invest their contributions without incurring unnecessary tax obligations.
As legislative discussions progress, it’s important for families to consult with tax advisors before utilizing a Backdoor IRA strategy. This ensures that their approach aligns with their unique financial circumstances and objectives. Remaining aware of suggested modifications and their potential effects on IRA adoption will be essential for families looking to safeguard their economic futures. Remember, together, we can navigate this journey.
Key Takeaways: Milestones in the Evolution of Backdoor Roth IRAs
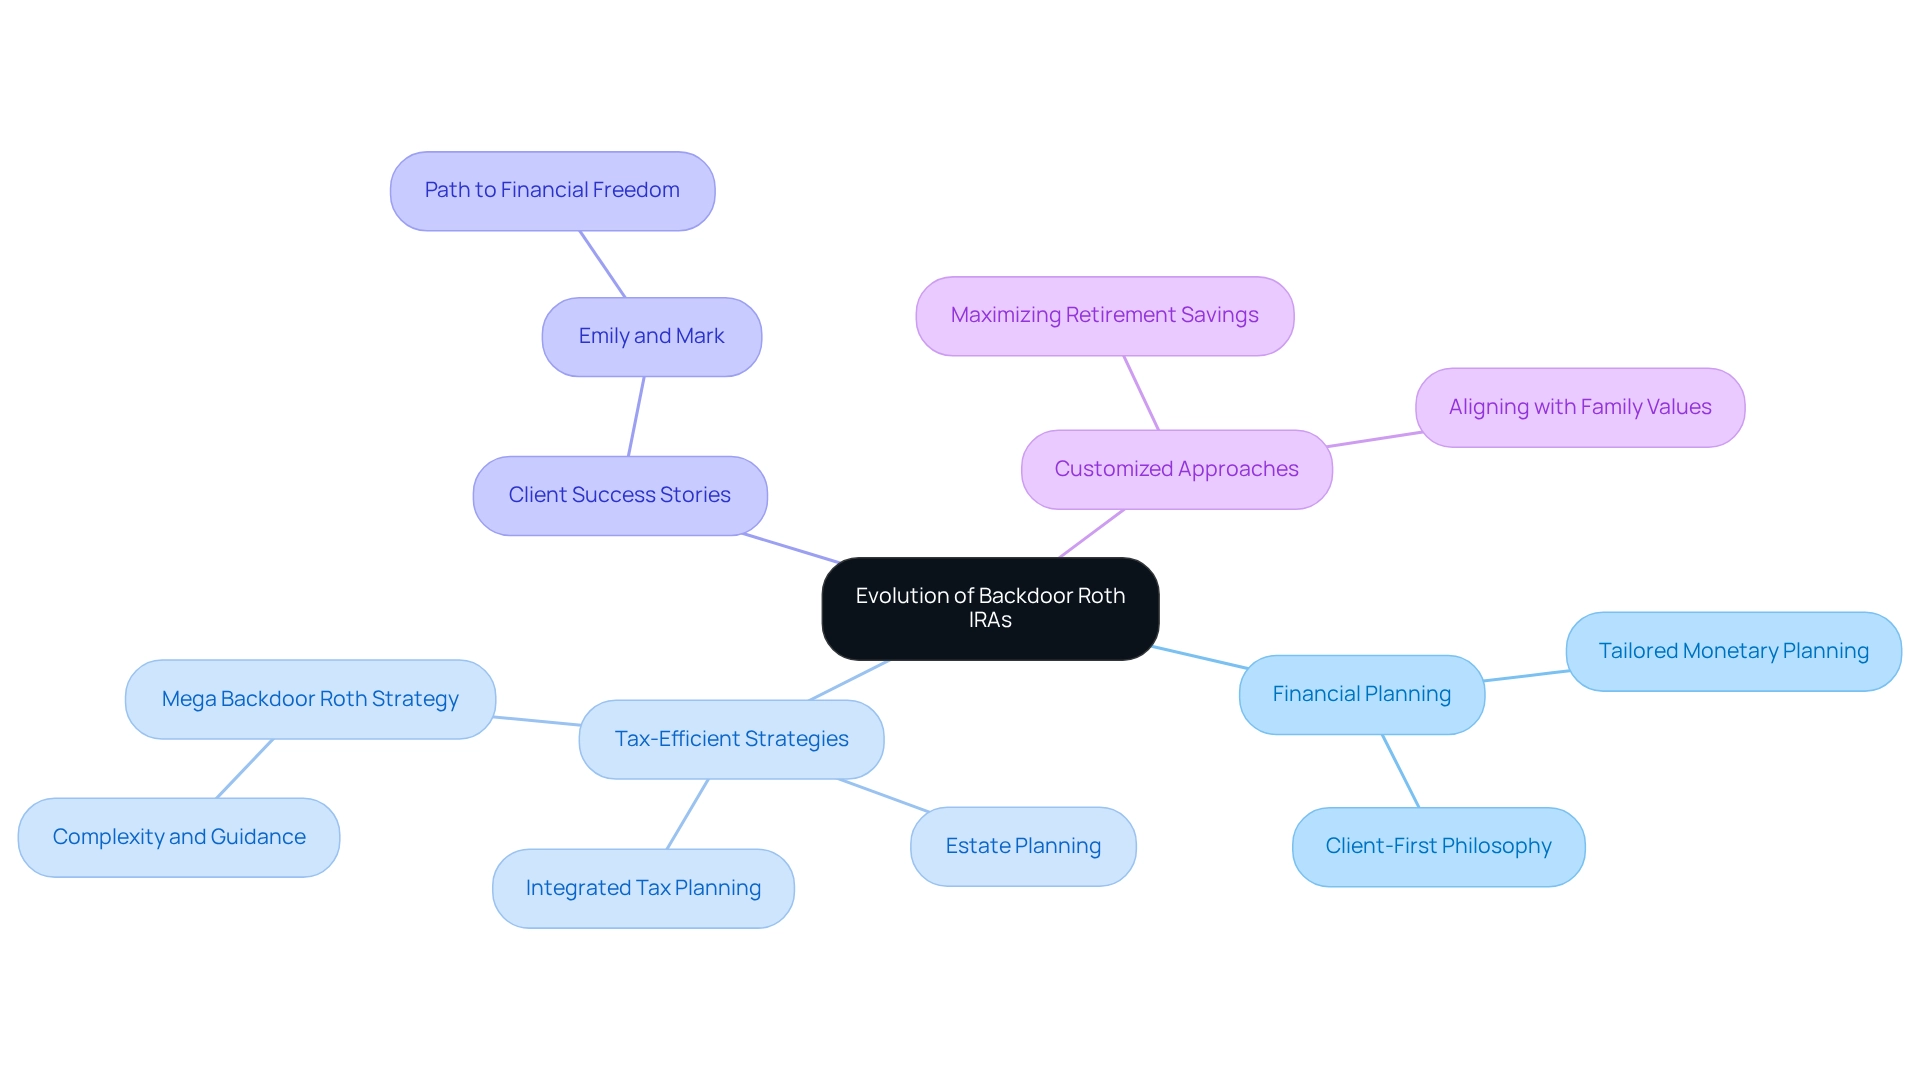
At Bright Advisers, we understand that financial planning can feel overwhelming, especially for families like yours. That’s why we excel in tailored monetary planning, positioning ourselves as your invaluable partner in understanding when did backdoor roth ira start. Imagine if you could simplify the complexities of retirement planning with a supportive team by your side. Our client-first philosophy, combined with cutting-edge technology, allows us to do just that.
Our deep knowledge in tax-efficient strategies, including integrated tax planning and estate planning, empowers you to maximize your retirement savings while ensuring your monetary goals resonate with your family values. This customized approach not only enhances the impact of your Roth IRA contributions but also fosters a nurturing atmosphere where you and your loved ones can confidently navigate your economic futures.
Consider the success story of Emily and Mark, who found clarity in their financial situation with our help. Together, we developed a comprehensive plan that set them on the path to financial freedom. We’re here for you, ready to guide you through this journey and support your family’s aspirations.
Conclusion
The Backdoor Roth IRA strategy offers a wonderful opportunity for high-income earners to enhance their retirement savings, especially in a time when traditional contribution limits can feel limiting. By taking advantage of recent legislative changes, particularly the removal of income caps on Roth conversions, this approach has gained remarkable popularity. It enables families to enjoy the benefits of tax-free growth and withdrawals. Understanding the intricacies of this strategy, including adherence to IRS guidelines and the significance of collaborating with financial advisors, is crucial for unlocking its full potential.
As the financial landscape evolves, the Backdoor Roth IRA continues to be a valuable tool for managing wealth. Families, especially young parents, can secure their financial futures by weaving this strategy into their retirement planning. With the promise of higher contribution limits and the appeal of tax-free investment growth, the Backdoor Roth IRA emerges as a strategic choice for those looking to establish a strong financial foundation.
Staying informed about potential legislative shifts and seeking guidance from knowledgeable advisors can aid in navigating the complexities of this strategy. By aligning financial aspirations with family values and utilizing customized wealth management solutions, individuals can approach their retirement planning with confidence, ensuring they are prepared for what lies ahead. As interest rates fluctuate and market trends change, now is the perfect moment to explore the advantages of the Backdoor Roth IRA and take proactive steps toward securing financial stability for generations to come.
Frequently Asked Questions
What is a Backdoor Roth IRA?
A Backdoor Roth IRA is a strategy that allows high-income earners to convert funds from a traditional IRA into a Roth IRA, enabling them to take advantage of tax-free growth and withdrawals during retirement.
When did the Backdoor Roth IRA strategy begin?
The roots of the Backdoor Roth IRA approach can be traced back to the Taxpayer Relief Act of 1997, but it gained significant traction in 2010 when Congress removed the income cap on IRA conversions, allowing individuals with higher incomes to convert their traditional IRAs without penalties.
What legislative change in 2010 impacted the Backdoor Roth IRA?
The 2010 Tax Act removed the $100,000 income cap on conversions, which opened up the Backdoor Roth IRA strategy for high-income earners, allowing them to enjoy tax-free growth potential in their retirement accounts.
Why are high-income earners increasingly adopting the Backdoor Roth IRA strategy?
High-income earners are recognizing the benefits of tax-free growth and withdrawals during retirement, leading to a surge in inquiries about alternative IRA strategies like the Backdoor Roth IRA, especially from those who previously felt limited by income thresholds.
What are the potential benefits of using a Backdoor Roth IRA?
The primary benefits include tax-free growth of investments and tax-free withdrawals during retirement, which can significantly enhance a family’s financial future and retirement portfolio.
What should individuals consider when executing a Backdoor Roth IRA strategy?
It’s crucial to file essential paperwork, such as Form 8606 and Form 1099-R, to avoid double taxation. Consulting with a financial advisor or tax expert is recommended to navigate the complexities of IRA conversions.
How can financial advisors assist with Backdoor Roth IRA strategies?
Financial advisors can provide personalized strategies for optimizing tax situations, effective income shifting, and strategic asset allocation, helping families secure their financial future and align their financial plans with their goals.
What is the contribution limit for 401(k) accounts as of 2025?
The contribution limit for 401(k) accounts has increased to $23,500, which encourages high-income earners to explore tax-advantaged options like the Backdoor Roth IRA to maximize their retirement savings potential.
List of Sources
- Backdoor Roth IRA: Introduction and Historical Context
- Have State Auto-IRAs and Fintech Shifted Who Contributes to IRAs? – Center for Retirement Research (https://crr.bc.edu/have-state-auto-iras-and-fintech-shifted-who-contributes-to-iras)
- How Does Secure Act 2.0 Impact Roth Accounts? | White Coat Investor (https://whitecoatinvestor.com/roth-accounts-secure-act-2-0)
- How to Set Up a Backdoor Roth IRA: A Step-by-Step Guide (https://investopedia.com/how-to-set-up-a-backdoor-roth-ira-4584775)
- SOI Tax Stats Accumulation and Distribution of Individual Retirement Arrangements | Internal Revenue Service (https://irs.gov/statistics/soi-tax-stats-accumulation-and-distribution-of-individual-retirement-arrangements)
- The sneaky but probably legal way rich people shield retirement savings from taxes (https://vox.com/personal-finance/2016/6/6/11821072/backdoor-roth-ira-contributions)
- Legislative Changes: Key Laws Impacting Backdoor Roth IRA Development
- nerdwallet.com (https://nerdwallet.com/article/investing/backdoor-roth-ira)
- Effective Backdoor Roth Strategy: Rules, IRS Form 8606 (https://kitces.com/blog/backdoor-roth-conversion-strategy-traditional-ira-tax-planning)
- The Roth IRA Is More Than Meets The Eye (https://forbes.com/sites/forbesfinancecouncil/2017/04/04/the-roth-ira-is-more-than-meets-the-eye)
- H.R.2014 – 105th Congress (1997-1998): Taxpayer Relief Act of 1997 (https://congress.gov/bill/105th-congress/house-bill/2014)
- Characteristics and Motives of Roth Converters: Evidence from the 2010 Repeal of Income Limits (https://papers.ssrn.com/sol3/Delivery.cfm/SSRN_ID3418610_code3040601.pdf?abstractid=3418610&mirid=1&type=2)
- Early Adoption: When Investors Embraced the Backdoor Roth IRA
- nerdwallet.com (https://nerdwallet.com/article/investing/backdoor-roth-ira)
- Backdoor Roth IRA Strategy for High-Income Earners | Sensible Money (https://sensiblemoney.com/learn/backdoor-roth-iras-explained-a-smart-strategy-for-high-income-retirement-savers)
- How high earners can funnel money to a Roth IRA, the ‘gold standard’ of retirement accounts (https://cnbc.com/2024/09/05/how-high-earners-can-use-a-backdoor-roth-ira.html)
- Backdoor Roth IRA: Advantages and Tax Implications Explained (https://investopedia.com/terms/b/backdoor-roth-ira.asp)
- How to Do a Backdoor Roth IRA [Step-by-Step Guide] | White Coat Investor (https://whitecoatinvestor.com/backdoor-roth-ira-tutorial/comment-page-22?mrcid=blog_payresource&MRC_6WBFKTSJTDED747&MRC_SVO1ZHN1CUPFSRQ&_storyblok=20660842&_storyblok_c=article-page&_storyblok_lang=default&_storyblok_release=0&_storyblok_rl=1738694039642&_storyblok_tk%5Bspace_id%5D=1022385&_storyblok_tk%5Btimestamp%5D=1738694040&_storyblok_tk%5Btoken%5D=6d6944b6cbdb7767e3192c5e1b0a6893c449a60e&_storyblok_version&cvid=MRC_2MDYLWFZWDZ6QGN&source=MRC_content_Blog&type=telehealth)
- Why You Should Consider a Backdoor Roth IRA (https://morningstar.com/personal-finance/why-you-should-consider-backdoor-roth-ira-2)
- Tax Implications: Understanding the Financial Impact of Backdoor Roth IRAs
- irs.gov (https://irs.gov/publications/p590a)
- What you need to know about backdoor Roth conversions (https://investmentnews.com/guides/what-you-need-to-know-about-backdoor-roth-conversions/247821)
- smartasset.com (https://smartasset.com/retirement/360000-combined-backdoor-roth-strategy-reduce-taxes)
- Slam the Door: Why Congress Should End the Backdoor Roth IRA
| Yale Law & Policy Review (https://yalelawandpolicy.org/inter_alia/slam-door-why-congress-should-end-backdoor-roth-ira) - Backdoor Roth IRAs Really a Smart Idea? (https://evergreensmallbusiness.com/backdoor-roth-iras-and-401ks-really-a-smart-idea)
- Contribution Limits and Income Thresholds: Evolution Over Time
- A Pitfall of the “Backdoor” Roth IRA Conversion | Cerity Partners (https://ceritypartners.com/insights/a-pitfall-of-the-backdoor-roth-ira-conversion)
- irahelp.com (https://irahelp.com/slottreport/backdoor-roth-conversion)
- Backdoor Roth IRA for High Earners | U.S. Bank (https://usbank.com/retirement-planning/financial-perspectives/backdoor-roth-ira-strategy.html)
- financialsamurai.com (https://financialsamurai.com/historical-roth-ira-contribution-limits)
- Retirement topics – IRA contribution limits | Internal Revenue Service (https://irs.gov/retirement-plans/plan-participant-employee/retirement-topics-ira-contribution-limits)
- 2023 – 2024 Roth IRA Contribution Limits (https://schwab.com/ira/roth-ira/contribution-limits)
- T. Rowe Price Personal Investor – 2025 Key Financial Numbers That You Need to Know (https://troweprice.com/personal-investing/resources/insights/key-financial-numbers.html)
- Role of Financial Advisors: How Bright Advisers Supports Backdoor Roth IRA Strategies
- Avoid the Pro Rata Rule with Backdoor & Mega Roth Conversions | RGWM (https://rgwealth.com/insights/how-to-avoid-the-pro-rata-rule-with-backdoor-and-mega-roth-conversions)
- Roth IRA Conversion: Is It Right for High Earners? (https://icpas.org/information/copy-desk/insight/article/digital-exclusive—2024/roth-ira-conversion-is-it-right-for-high-earners)
- Backdoor Roth IRA: Advantages and Tax Implications Explained (https://investopedia.com/terms/b/backdoor-roth-ira.asp)
- In The News 2020v2 — Center for Financial Planning, Inc. (https://centerfinplan.com/in-the-news-2020v2)
- How advisors can help clients get the most out of Roth IRAs (https://financial-planning.com/list/how-financial-advisors-can-help-clients-get-the-most-out-of-roth-iras)
- Pros and Cons: Evaluating the Backdoor Roth IRA Strategy
- centerfinplan.com (https://centerfinplan.com/in-the-news)
- Retirement Account Statistics 2024 – NerdWallet (https://nerdwallet.com/article/investing/retirement-statistics)
- planadviser.com (https://planadviser.com/traditional-iras-destination-rollover-dollars-roth-iras-conversions-contributions)
- Is It Worth Doing A Backdoor Roth IRA? Pros and Cons (https://financialsamurai.com/backdoor-roth-ira)
- Backdoor Roth IRA: Is It Worth the Effort? (https://morningstar.com/retirement/backdoor-roth-ira-is-it-worth-effort)
- Avoid the Pro Rata Rule with Backdoor & Mega Roth Conversions | RGWM (https://rgwealth.com/insights/how-to-avoid-the-pro-rata-rule-with-backdoor-and-mega-roth-conversions)
- Future Outlook: What Lies Ahead for Backdoor Roth IRAs
- Backdoor Roth IRAs: Good for Wealthy Retirees? (https://kiplinger.com/retirement/604962/retirees-make-the-most-of-a-roths-back-door)
- Is the Backdoor Roth IRA Worth the Trouble? (https://morningstar.com/financial-advisors/is-backdoor-roth-ira-worth-trouble)
- m1.com (https://m1.com/knowledge-bank/backdoor-roth-iras-everything-you-need-to-know)
- Congress Proposed Legislation on IRA Accounts | White Coat Investor (https://whitecoatinvestor.com/is-the-backdoor-roth-ira-in-danger-of-being-wiped-out)
- Myths and Misconceptions: Clarifying Common Misunderstandings About Backdoor Roth IRAs
- edwardjones.com (https://edwardjones.com/us-en/market-news-insights/retirement/iras/backdoor-roth-ira)
- uncommoncentsinvesting.com (https://uncommoncentsinvesting.com/retirement-planning/are-roth-conversions-going-away-ideal-timing-insights)
- Backdoor Roth IRA: Advantages and Tax Implications Explained (https://investopedia.com/terms/b/backdoor-roth-ira.asp)
- 3 Misconceptions About Roth IRA Conversions (https://morningstar.com/financial-advisors/3-misconceptions-about-roth-ira-conversions)
- How a Backdoor Roth IRA Works (and Its Drawbacks) (https://kiplinger.com/retirement/how-a-backdoor-roth-ira-works-and-drawbacks)
- Myths about IRA Conversions (https://mysccu.com/learn/4-common-misconceptions-about-roth-ira-conversions)
- Key Takeaways: Milestones in the Evolution of Backdoor Roth IRAs
- How We Work – Bright Advisers (https://brightadvisers.com/how-we-work)
- Good News, Bad News (https://iscfinancialadvisors.com/blog/good-news-bad-news)
- Backdoor Roth IRA for High Earners | U.S. Bank (https://usbank.com/retirement-planning/financial-perspectives/backdoor-roth-ira-strategy.html)
- Legislative History Defines the Roth IRA — Ascensus (https://thelink.ascensus.com/articles/2018/12/10/legislative-history-defines-the-roth-ira)
- Legislative Impacts on Roth IRA Conversions » STRATA Trust Company (https://stratatrust.com/insights/legislative-impacts-on-roth-ira-conversions)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Tax Management for high-income W-2 families at Bright Advisers.
Keep reading