

Overview
The article “7 Steps to Create Your Family Financial Plan” gently guides families through a structured approach to managing their finances. Imagine if you could take control of your family’s financial future—this article outlines essential steps like:
- Budgeting
- Setting financial goals
- Creating an emergency fund
- Exploring investment strategies
- Regularly reviewing your financial plan
Each of these steps is crucial for achieving economic stability and long-term financial health.
It’s important to understand that financial planning is not just about numbers; it’s about ensuring a secure future for your loved ones. By budgeting effectively, you can allocate resources wisely, setting the stage for reaching your family’s goals. Creating an emergency fund offers peace of mind, knowing that you’re prepared for unexpected challenges.
As you explore investment strategies, think about how they can work for your family’s unique needs. Regularly reviewing your financial plan allows you to adapt and ensure it aligns with your evolving priorities. Together, we can navigate this journey toward financial well-being, fostering a sense of security and hope for your family’s future.
We’re here for you, ready to support you every step of the way. Embrace this opportunity to cultivate a stable financial environment for your family, where dreams can flourish and shared goals can be achieved.
Key Highlights:
- Family financial planning is essential for securing economic stability and involves budgeting, saving, and investing.
- 30% of Americans recognize an emergency fund as crucial for financial readiness, highlighting the importance of budgeting and saving.
- 94% of adults have bank accounts, but access varies by income, stressing the need for effective budgeting.
- Families should assess their financial situation by calculating income, expenses, and net worth to identify improvement areas.
- The average family income in 2025 is projected at $75,000, with monthly expenses around $5,500, aiding families in contextualizing their finances.
- Setting clear financial goals using the SMART criteria helps families align their objectives with their values.
- The 50/30/20 rule is an effective budgeting method, encouraging families to allocate 50% for needs, 30% for wants, and 20% for savings.
- An emergency fund should cover three to six months of living expenses, providing a safety net for unforeseen circumstances.
- Investing in stocks, bonds, and retirement accounts is crucial for long-term financial health, with hyper-personalized portfolios recommended.
- Regular reviews of the financial plan are necessary to assess progress and adjust strategies in response to life changes.
Introduction
Navigating the complexities of family financial planning can feel overwhelming, yet it is so vital for securing a stable future. As families work hard to balance daily expenses, savings, and investments, understanding the fundamental principles of financial management becomes essential. Imagine if you could take control of your financial journey, feeling empowered and informed every step of the way. This article explores the key components of effective family financial planning, from assessing your current financial situation to setting clear goals and creating comprehensive budgets.
It’s important to understand that financial preparedness is increasingly crucial, especially for young families. Statistics reveal that many are facing challenges that can be addressed with the right strategies. Here, we aim to provide you with practical tools and insights to enhance your financial well-being. By embracing personalized planning and regular reviews, families can build a solid financial foundation that meets immediate needs while also paving the way for future generations. Together, we can navigate this journey, ensuring that your family’s financial future is secure.
Understand Family Financial Planning Basics
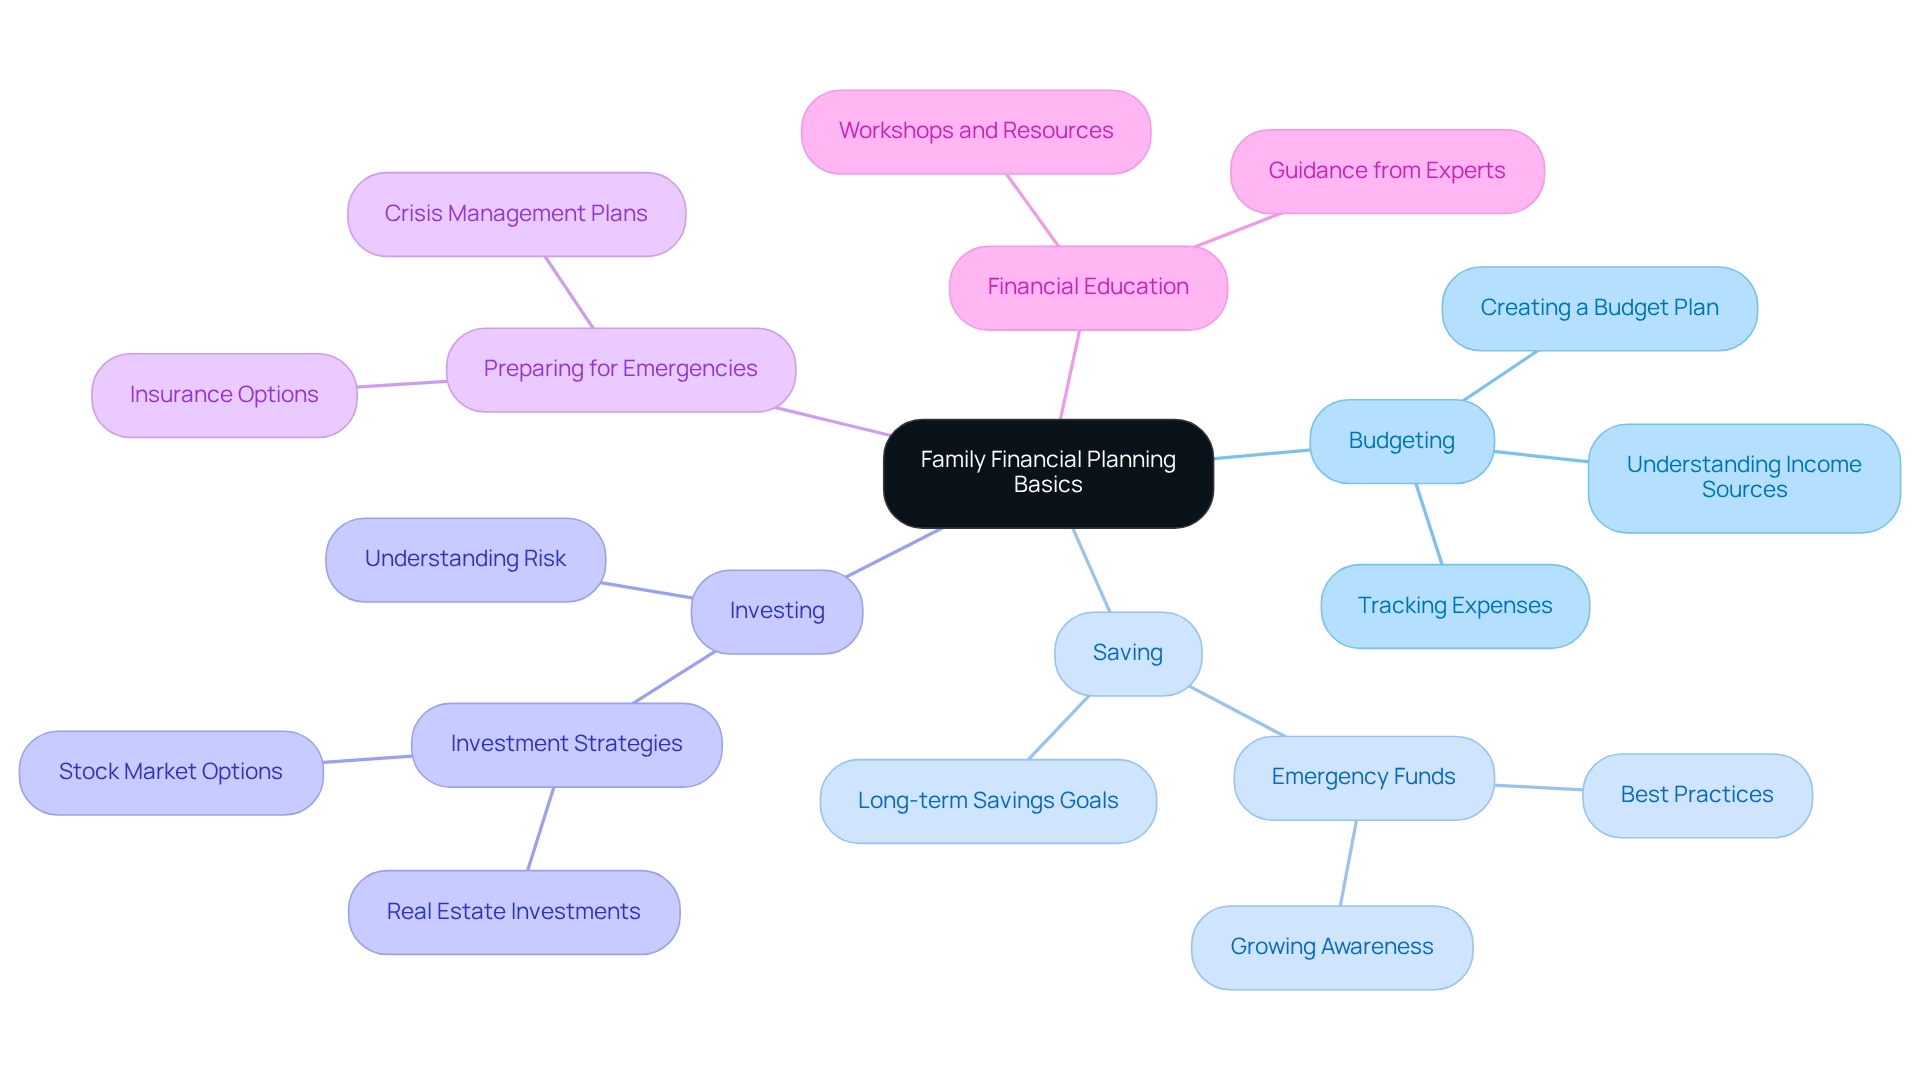
Creating a family financial plan is a vital roadmap for securing your family’s economic future. At Bright Advisers, we understand that this journey involves essential elements like budgeting, saving, investing, and preparing for unexpected expenses. It’s important to comprehend your income sources and expenses while establishing clear monetary goals. By grasping essential monetary concepts—such as net worth, cash flow, and various investment alternatives—you can build a strong foundation for your economic journey.
Imagine this: in 2025, a significant percentage of households recognized the importance of monetary readiness, with 30% of Americans identifying an emergency fund as the best safeguard against economic uncertainty. This growing awareness underscores the critical nature of budgeting and saving, especially for families navigating the challenges of raising children. Bright Advisers is committed to providing tailored wealth management solutions that empower young families to achieve economic security and independence.
It’s important to understand that, according to the Federal Reserve Board, while 94% of adults have a bank account, there are inequalities based on income tiers. For households earning under $25,000, only 77% have access to banking services, highlighting the necessity of budgeting to bridge these gaps. Our innovative wealth management approach focuses on addressing the unique obstacles faced by families.
Effective strategies for household wealth management often blend learning with practical implementation. By prioritizing savings and crafting a detailed family financial plan, families can create a secure economic environment. As Hristina Nikolovska notes, understanding the dynamics of single-family residences—of which there are about 100 million—can guide your investment choices and long-term strategies. Bright Advisers offers educational materials to help families navigate these challenges effectively, as understanding the fundamentals of household budgeting is key to developing a family financial plan that not only prepares you for current monetary challenges but also lays the groundwork for a legacy that can support future generations. By addressing the unique financial hurdles faced by young families, such as balancing childcare expenses and saving for education, you can create a more effective and personalized family financial plan with the guidance of Bright Advisers.
To embark on your journey towards economic stability, join our waitlist or reach out to us at (714) 987-2967 or hello@brightadvisers.com. Visit us at 135 S State College Blvd #200, Brea, CA 92821 for more information. Remember, all advisory services are provided through Lifeworks Advisors, a registered investment adviser.
Assess Your Current Financial Situation
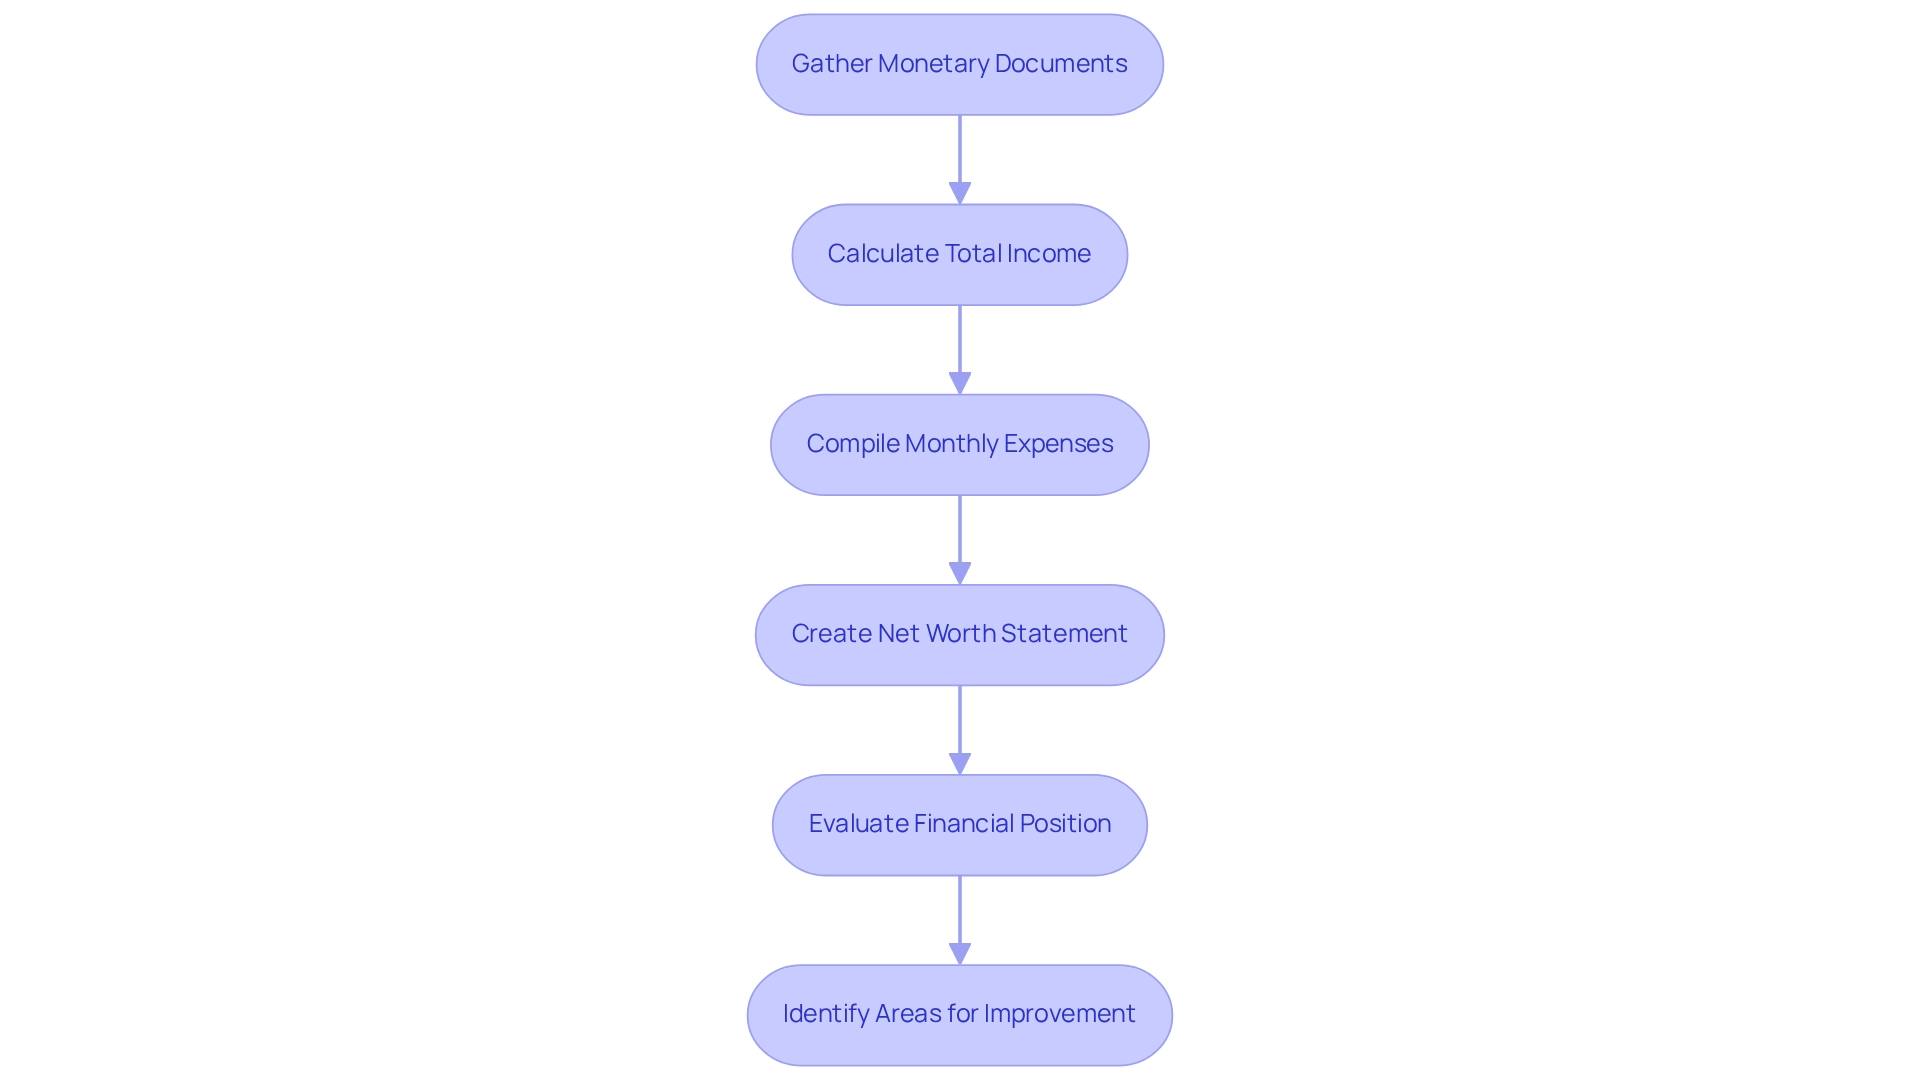
Begin by gathering all necessary monetary documents, such as bank statements, pay stubs, and bills. Next, calculate your total income and compile a comprehensive list of monthly expenses. To gain a clearer view of your monetary health, create a net worth statement by subtracting total liabilities from total assets. This process not only emphasizes your current economic position but also identifies areas that may need enhancement. Imagine using tools like budgeting apps or spreadsheets to streamline this task, making it easier to track your finances effectively.
In 2025, the average family income is projected to be around $75,000, while average monthly expenses are estimated at $5,500. Understanding these numbers can assist you in contextualizing your own economic situation. Moreover, automating savings can greatly aid in creating a monetary buffer without depending entirely on willpower, simplifying the process of reserving funds for upcoming needs.
Currently, the average net worth is estimated at $215,000, which acts as a benchmark for families to evaluate their economic status. Experts highlight the significance of frequently evaluating your monetary circumstances. Hal M. Bundrick, a certified money planner, notes that ‘net worth is what you own minus what you owe,’ underscoring the importance of maintaining an accurate net worth statement. This statement serves as an essential resource for young households, providing insights into their economic well-being and guiding them toward informed choices regarding their family financial plan.
Consider case studies that illustrate how families have improved their monetary well-being through diligent documentation and assessment. For example, Emily and Mark, a pair aged 35 and 37, with professions as a marketing executive and a software engineer, respectively, collaborated with Bright Advisers to manage their economic complexities. Through a thorough evaluation of their income, expenses, and assets, they created a customized plan that not only enhanced their economic well-being but also granted them the freedom to decide whether to continue working. This highlights the transformative impact of tailored economic planning.
Furthermore, the difference between median and average net worth is essential for comprehending economic data; the average can be distorted by outliers, whereas the median offers a more accurate representation of typical economic health. Families that regularly update their monetary records often find it easier to identify spending patterns and areas for potential savings. By prioritizing this evaluation process, households can establish a solid base for their family financial plan and economic future.
It’s important to recognize that student loans are the largest source of unsecured debt, affecting about two-fifths of all households, with a median debt of $20,000. This typical economic challenge emphasizes the need for careful budgeting that considers the broader population. Together, we can navigate this journey towards financial stability.
Set Clear Financial Goals Aligned with Family Values
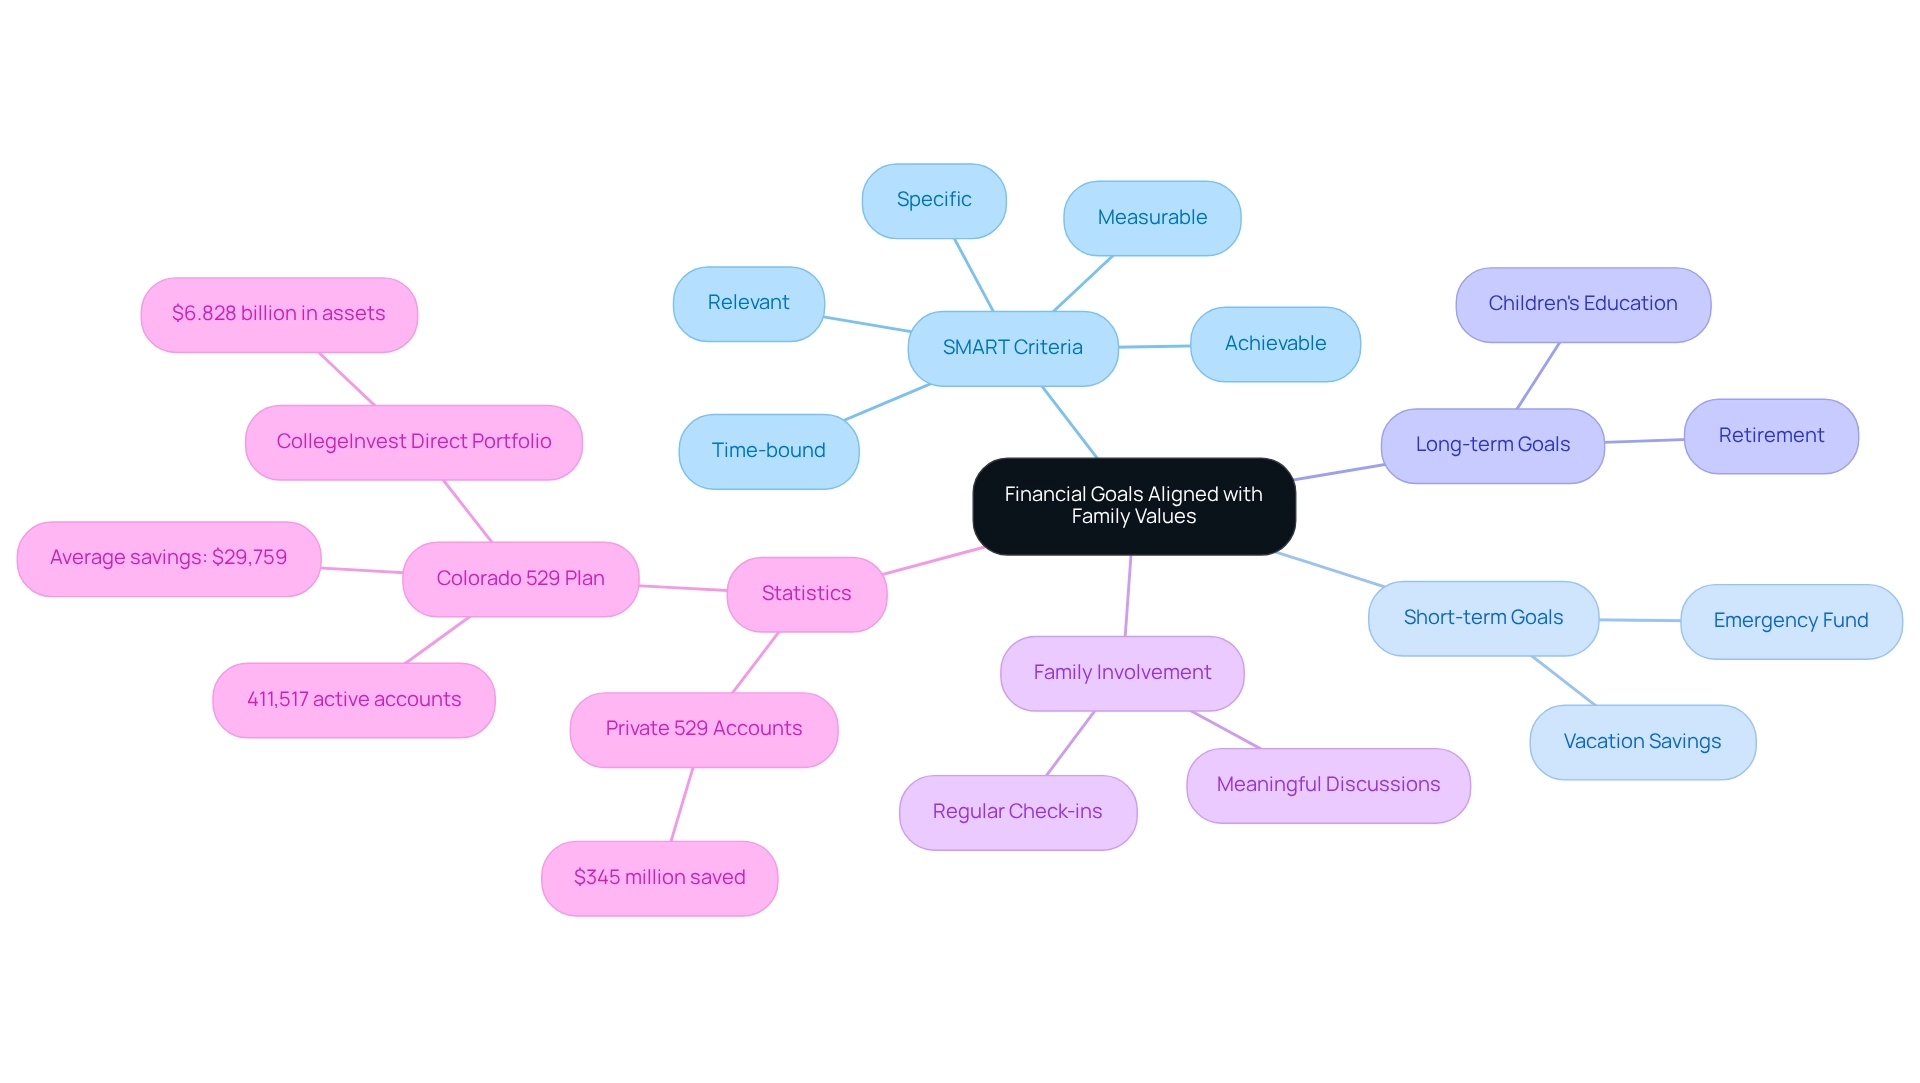
Involve your loved ones in meaningful discussions about financial priorities to foster a shared understanding of your goals. Imagine sitting down with your family, recognizing both short-term goals, like saving for a vacation together, and long-term ambitions, such as financing your children’s college education. To effectively formulate these goals, consider applying the SMART criteria: ensure they are Specific, Measurable, Achievable, Relevant, and Time-bound. For instance, your household might establish a goal to save $10,000 for a vacation within two years, making it clear and achievable.
Document these objectives and plan regular check-ins to monitor progress and make necessary adjustments. This practice not only holds everyone responsible but also emphasizes the significance of aligning monetary objectives with your family financial plan and core values. A recent statistic highlights the importance of setting aside funds for education: college-bound students and their families had $345 million accumulated in Private 529 accounts as of July 2024. This underscores the necessity of proactive economic planning for your children’s futures.
Consider the journey of Emily and Mark, a couple who collaborated with Bright Advisers to address their planning challenges. By conducting a comprehensive evaluation of their monetary situation, they developed a tailored strategy that addressed their goals of economic freedom and work-life balance. This method empowered them to enhance their economic well-being while ensuring they could assist with their children’s education.
Additionally, the Colorado 529 Plan reported 411,517 active accounts with an average accumulation of $29,759 per account. The CollegeInvest Direct Portfolio College Funds Plan, the most favored choice, has amassed $6.828 billion in assets, illustrating the effectiveness of organized financial strategies. By prioritizing monetary discussions and utilizing the SMART framework, households can create a robust budget that not only meets their needs but also reflects their values, ensuring a secure future for generations to come. Together, we can navigate this journey towards financial security.
Create a Comprehensive Family Budget
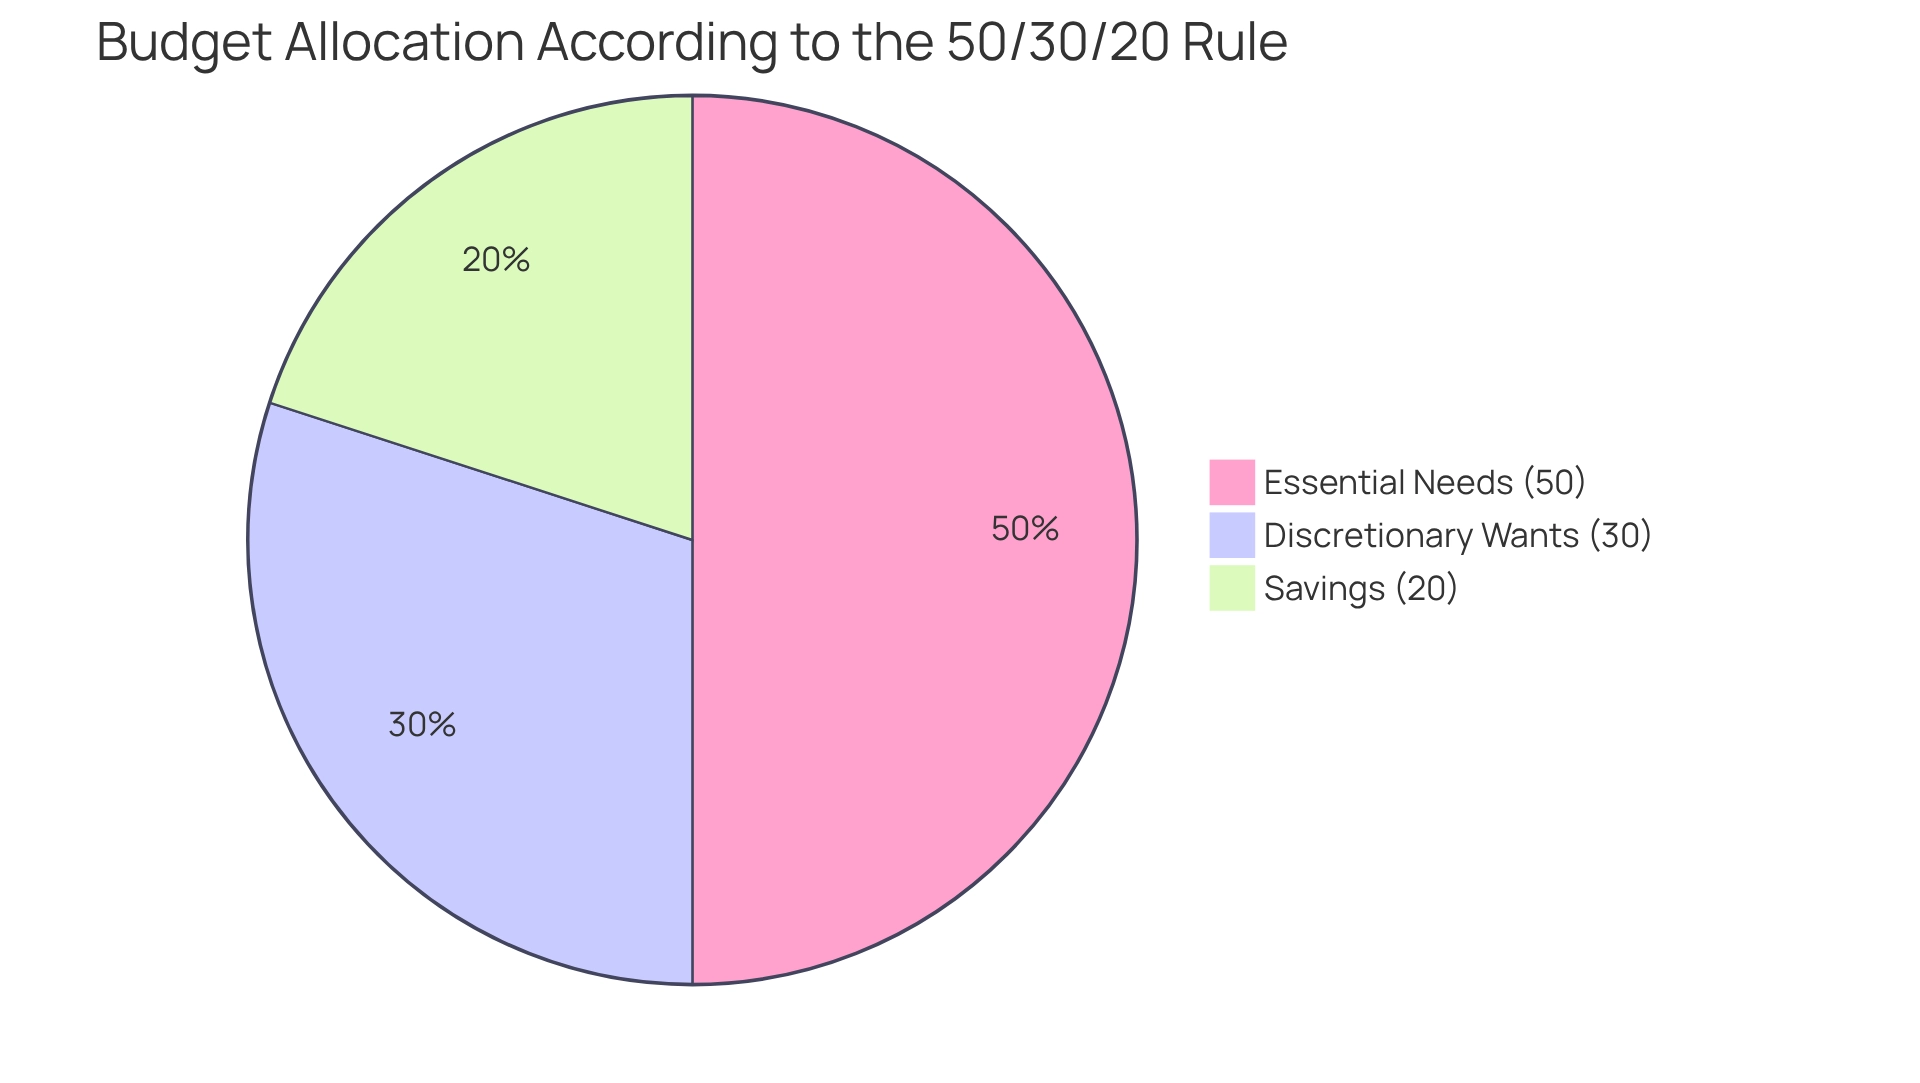
Start by gathering a comprehensive list of all your income sources and monthly expenses. It’s helpful to categorize these expenses into fixed costs, like rent and utilities, and variable costs, such as groceries and entertainment. One budgeting method that many families find effective is the 50/30/20 rule. This approach suggests allocating:
- 50% of your income to essential needs
- 30% to discretionary wants
- 20% to savings
By following this guideline, you can simplify your budgeting process and foster a balanced financial lifestyle, which supports your family financial plan and helps to alleviate economic stress while securing your family’s future.
Imagine if you could consistently review and adjust your budget to reflect any changes in your income or expenses. This practice ensures that your family financial plan remains relevant and effective. In 2025, household budget distributions reveal that families are increasingly prioritizing savings, with many embracing the 50/30/20 guideline to enhance their financial stability. Families who adopt this strategy often report better control over their spending and a clearer path toward achieving their family financial plan.
Additionally, consider budgeting techniques like the envelope system, which involves setting aside cash for specific spending categories. Many families have discovered that this method helps them avoid overspending and stay aligned with their budgets. By visually tracking their spending limits, they feel more empowered in managing their finances.
It’s essential to remember that delaying your family financial plan for even a decade can significantly impact your wealth, potentially cutting it in half. This underscores the importance of a family financial plan that emphasizes timely budgeting and proactive planning. As money expert Suze Orman wisely said, “A big part of freedom is having your heart and mind free from worry about the what-ifs of life.” By implementing these strategies, you can develop a comprehensive family financial plan that not only addresses your immediate needs but also lays the foundation for long-term financial security.
At Bright Advisers, we are committed to providing tailored wealth management solutions designed to support families like yours. With minimal fund fees, we strive to enhance accessibility and ensure that your financial journey is as smooth as possible. Together, we can navigate this journey toward a more secure financial future.
Establish an Emergency Fund for Financial Security
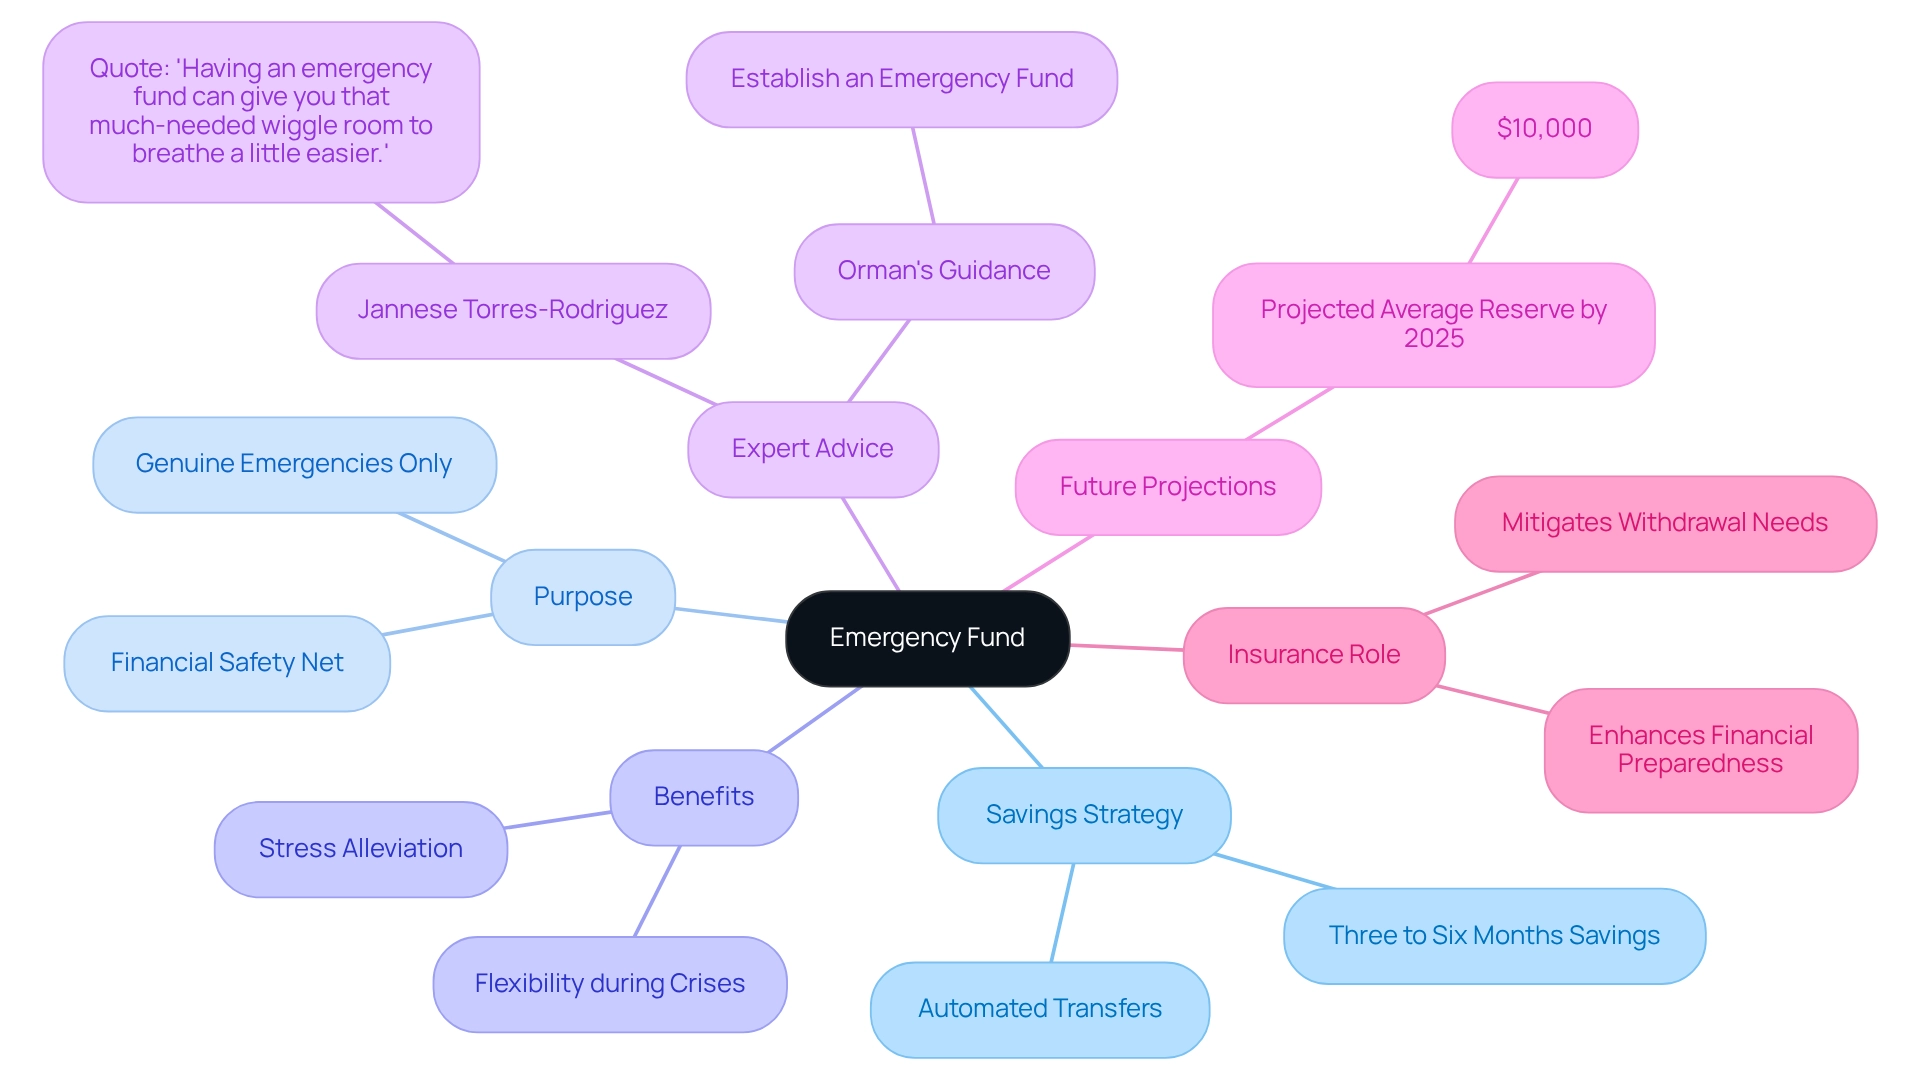
To secure your household’s financial future, it’s essential to save three to six months’ worth of living expenses in an easily accessible account. Begin by setting aside a small portion of your income each month, gradually building your emergency fund. Automating transfers can simplify this process, ensuring consistent contributions without needing constant attention. Remember, this fund is meant exclusively for genuine emergencies, such as unexpected medical expenses or job loss, to maintain its integrity and purpose.
Creating an emergency fund isn’t just a financial strategy; it’s a vital safety net that can alleviate stress during unforeseen situations. Financial experts emphasize that having an emergency fund provides families with the necessary flexibility to navigate life’s surprises. As Jannese Torres-Rodriguez, a Latina money expert, shares, “Having an emergency fund can give you that much-needed wiggle room to breathe a little easier.” Moreover, adequate insurance coverage can reduce the need to tap into emergency funds by addressing unexpected expenses, enhancing overall financial readiness. This is illustrated in the case study titled ‘The Role of Insurance in Emergency Preparedness,’ which highlights how insurance can lessen the need to withdraw from emergency funds during crises.
By 2025, the average emergency reserve for households is projected to be around $10,000, reflecting a growing awareness of the importance of security and preparedness among families. Many households have successfully built their emergency reserves by prioritizing savings and making informed financial decisions. The key takeaway from Orman’s guidance is to establish an emergency fund that serves as a safety net for unexpected events.
At Bright Advisers, we recognize the unique challenges young families face when developing a family financial plan. By partnering with us, you can access a personalized family financial plan tailored to your specific needs, helping you build a robust emergency fund and secure your family’s financial future. Join our waitlist today or reach out to us to learn more about how we can support you on your financial journey. By following these steps, young parents can establish a strong emergency fund that not only protects their financial stability but also empowers them to focus on what truly matters—their loved ones.
Explore Investment and Savings Strategies
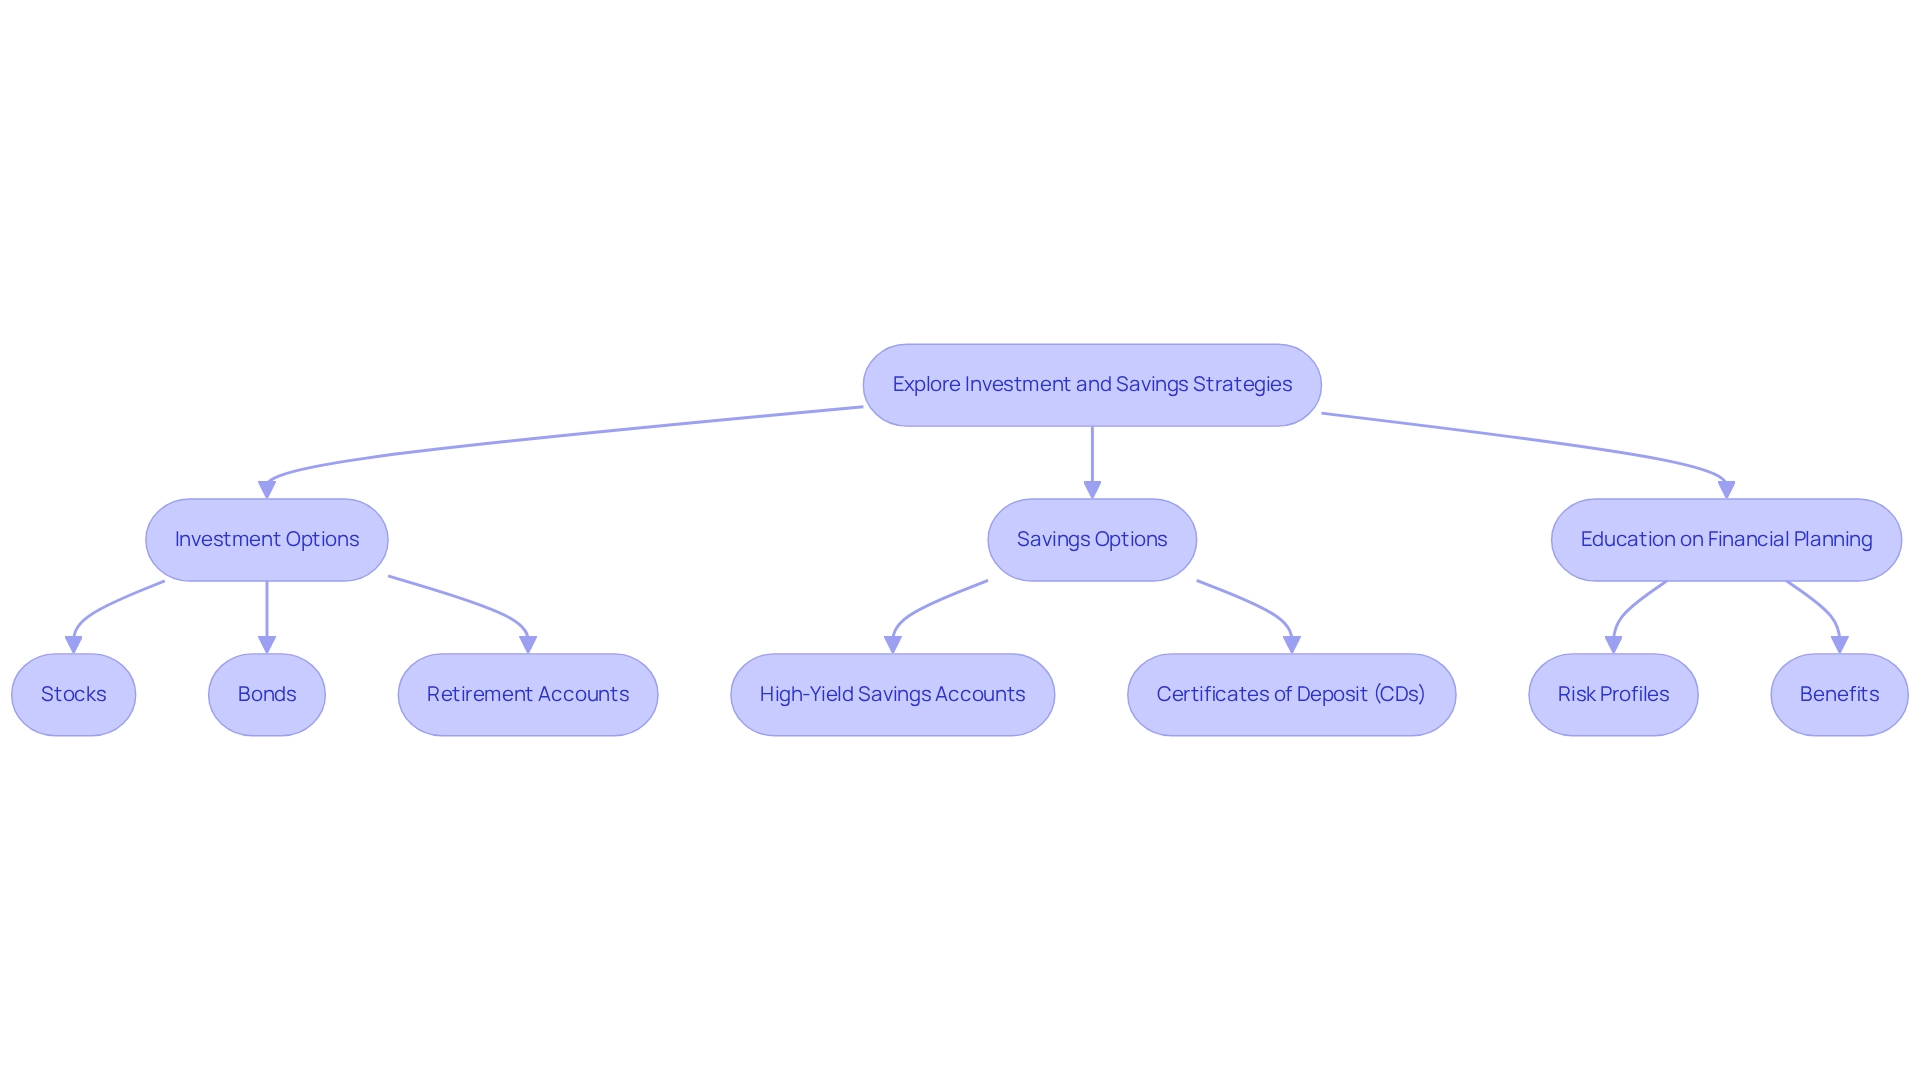
When evaluating investment choices, it’s essential for families to explore a variety of avenues as part of their family financial plan, such as stocks, bonds, and retirement accounts. Each option comes with its own risk and return profile, making it vital to consider your family’s financial plan, including risk tolerance and investment timeline. Bright Advisers emphasizes the importance of hyper-personalized investment portfolios within your family financial plan, which can help manage risk while potentially enhancing returns—crucial for your family’s long-term financial health.
Imagine if you could navigate the complexities of investing with strategies designed just for you. Bright Advisers’ innovative approaches, including the Diversified Premia and Opportunity Strategy, blend smart beta and factor investing techniques to improve economic outcomes. Notably, they stand apart in the wealth management landscape by not relying on risk scores, model portfolios, or traditional investment products.
When it comes to savings, high-yield savings accounts and certificates of deposit (CDs) offer more attractive interest rates than conventional savings accounts, making them appealing options for a family financial plan that aims to grow their savings. Additionally, consistently contributing to retirement accounts like a 401(k) or IRA is crucial for your family financial plan, as it allows you to harness the power of compound interest, significantly enhancing your household’s financial future. Research shows that families who regularly invest in their family financial plan can witness substantial growth over time.
As you navigate these choices, remember that education is a cornerstone of a successful family financial plan. As one expert wisely noted, “Education is a considerable investment, and beginning early with the appropriate financial plan can make a tremendous impact.” Starting early with the right family financial plan can profoundly influence your long-term goals. For example, a family financial plan that includes setting aside funds in tax-advantaged accounts can prepare your children for future educational expenses, ensuring they are ready to take on financial responsibilities.
Real-world stories illustrate how families are successfully exploring various investment options. Many are choosing a blend of fixed annuities, which offer guaranteed returns and tax-deferred growth, alongside more liquid investments to create balanced portfolios. Consider the case of Allison and Brian, clients of Bright Advisers, who transformed their financial future through strategic tax management, enhancing their tax situation and securing funding for their children’s education. This thoughtful approach not only provides a stable income stream but also aligns with their long-term aspirations.
Ultimately, the key to effective household budgeting is understanding the options available and making informed decisions that align with your family’s financial plan and unique values and goals. Bright Advisers’ methodologies, such as the Diversified Premia and Opportunity Strategy, focus on dynamic growth factors and robust value attributes, ensuring a customized investment approach that supports the specific needs of a family financial plan. Together, we can navigate this journey towards financial well-being.
Review and Adjust Your Financial Plan Regularly
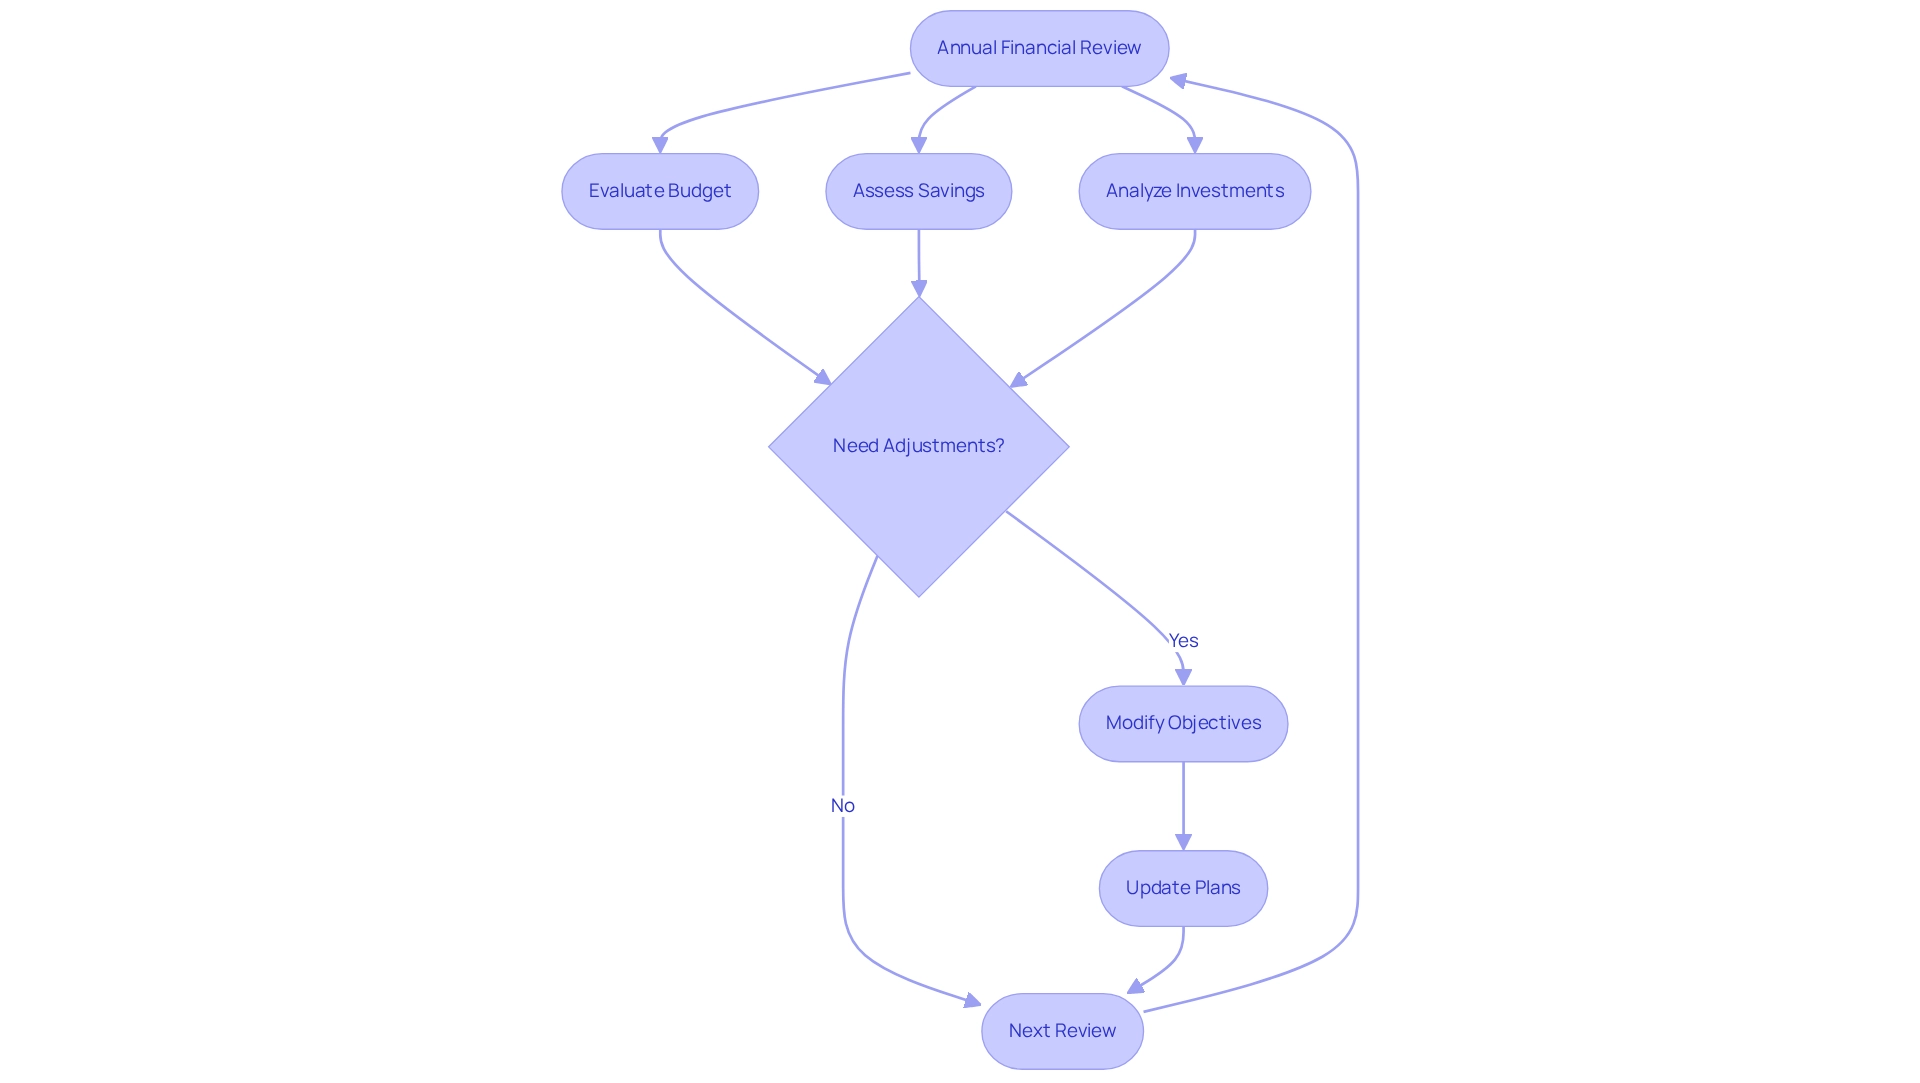
Conducting annual reviews of your financial plan is essential for assessing your progress toward your goals. These reviews should encompass a thorough evaluation of your budget, savings, and investment performance. Imagine if you could modify your objectives and plans, especially after major life changes like starting a new job, moving, or welcoming a child into your household. Flexibility in your monetary strategy enables you to remain in tune with your changing situations and priorities.
Statistics show that only 28% of American households possess a suitable monetary strategy, emphasizing the essential requirement for households to participate in budget management. This statistic highlights the significance of regular evaluations to ensure that households are on track to achieve their monetary objectives. Additionally, 79% of Americans in households making $100,000 or more feel wealthier than their parents, indicating a change in economic perspectives that can influence planning strategies. As life progresses, families often discover that monetary compatibility—regarded as more crucial than physical compatibility by 35% of individuals—plays a significant role in their economic choices.
It’s important to understand the interconnectedness of various monetary aspects. As Kris Borghesan observes, “When we consider all of these figures comprehensively, it’s clear that they all affect one another and influence other important aspects of your economic life.” This holistic approach is essential when reviewing and adjusting your budget plan, ensuring that all elements work together harmoniously. Moreover, the most prudent investment principle is to purchase when others are selling and sell when others are buying, as noted by Jonathan Sacks, which can assist families in making informed monetary choices.
For example, consider Emily and Mark, a young couple managing their careers while preparing for their future. They collaborated with Bright Advisers to create a thorough monetary strategy. Bright Advisers provided tailored services, including debt reduction strategies, cash flow management, and retirement planning. Through regular evaluations and modifications, they enhanced their monetary situation, ultimately gaining the freedom to decide whether or not to keep working. By regularly assessing your monetary progress and adjusting your strategies, you can manage the complexities of family funds more effectively, ensuring a stable economic future for your loved ones. The importance of having a financial plan is further emphasized by the fact that households with a proper financial plan significantly increase their likelihood of saving enough for retirement, as highlighted in the case study on the importance of financial planning.
Conclusion
Navigating the intricacies of family financial planning is essential for establishing a secure and prosperous future. Imagine if you could understand the fundamental components—assessing your current financial situation, setting clear goals, creating detailed budgets, and building emergency funds. By doing so, you can craft a tailored approach that meets your unique needs. The emphasis on education and regular reviews ensures that you remain adaptable and informed, allowing your family to thrive even amidst life’s uncertainties.
The importance of proactive financial management cannot be overstated. Families that engage in financial discussions and prioritize savings are better positioned to achieve their aspirations, whether it’s funding education or securing a comfortable retirement. By implementing effective budgeting strategies and exploring diverse investment options, you can maximize your financial potential and cultivate a legacy of financial stability for future generations.
Ultimately, the journey towards financial security is not a solitary endeavor. With the support of dedicated financial advisers and a commitment to ongoing education, you can navigate the complexities of your financial landscape with confidence. Taking the first steps towards comprehensive financial planning today will empower your family to focus on what truly matters—your loved ones and your collective well-being.
Frequently Asked Questions
What is the purpose of creating a family financial plan?
Creating a family financial plan serves as a roadmap for securing your family’s economic future by incorporating essential elements like budgeting, saving, investing, and preparing for unexpected expenses.
Why is budgeting and saving important for families?
Budgeting and saving are crucial for families, especially those raising children, as they help navigate economic uncertainty and prepare for unexpected financial challenges.
What are some key monetary concepts families should understand?
Families should understand concepts such as net worth, cash flow, and various investment options to build a strong foundation for their economic journey.
How prevalent is the use of banking services among different income tiers?
While 94% of adults have a bank account, only 77% of households earning under $25,000 have access to banking services, highlighting income disparities in financial readiness.
What strategies can families use for effective wealth management?
Effective strategies for household wealth management include prioritizing savings, crafting a detailed family financial plan, and understanding the dynamics of single-family residences to guide investment choices.
How can families begin the process of creating a financial plan?
Families can start by gathering monetary documents, calculating total income, compiling a list of monthly expenses, and creating a net worth statement to assess their economic health.
What is the significance of net worth in financial planning?
Net worth, defined as what you own minus what you owe, is essential for evaluating economic status and guiding informed financial choices for families.
How can families automate their savings?
Automating savings can simplify the process of reserving funds for future needs, making it easier to create a monetary buffer without relying solely on willpower.
What common financial challenges do families face?
One common challenge is student loans, which are the largest source of unsecured debt for about two-fifths of all households, emphasizing the need for careful budgeting.
How can families improve their financial well-being?
Families can enhance their financial well-being by diligently documenting and assessing their income, expenses, and assets to create customized financial plans that address their unique circumstances.
List of Sources
- Understand Family Financial Planning Basics
- 54 Personal Finance Statistics & Facts in 2025 [SOURCES INCLUDED] (https://moneywise.com/research/personal-finance-statistics)
- Personal Finance Statistics You Should Be Aware of in 2025 (https://moneyzine.com/personal-finance/personal-finance-statistics)
- Assess Your Current Financial Situation
- How Do You Calculate Net Worth? (https://experian.com/blogs/ask-experian/how-to-calculate-your-net-worth)
- What is the Average Net Worth by Age in the U.S.? – NerdWallet (https://nerdwallet.com/article/finance/average-net-worth-by-age)
- 14 Quotes From Our Favorite Money Saving Experts (https://chime.com/blog/quotes-from-money-saving-experts)
- Common Net Worth Statistics You Need to Know (https://smartasset.com/financial-advisor/net-worth-statistics)
- Average net worth by age: How do you compare? (https://creditkarma.com/net-worth/i/net-worth-by-age)
- Set Clear Financial Goals Aligned with Family Values
- College Saving Statistics [2025]: Average Savings & 529 Balance (https://educationdata.org/college-savings-statistics)
- 200 Quotes About Money And Personal Finance To Inspire You (https://marriagekidsandmoney.com/20-empowering-quotes-about-money-and-personal-finance)
- 2025 Financial New Year’s Resolutions Survey Findings | The Motley Fool (https://fool.com/money/research/financial-new-years-resolutions)
- Create a Comprehensive Family Budget
- 14 Quotes From Our Favorite Money Saving Experts (https://chime.com/blog/quotes-from-money-saving-experts)
- Ultimate Guide to Creating a Budget | MMI (https://moneymanagement.org/budget-guides/create-a-budget)
- The Best Budget Analysis Quotes From Famous Experts And Influencers – FasterCapital (https://fastercapital.com/topics/the-best-budget-analysis-quotes-from-famous-experts-and-influencers.html)
- How to Build a Bulletproof Budget: Worksheet + 50/30/20 Rule (https://iwillteachyoutoberich.com/budget-help)
- Establish an Emergency Fund for Financial Security
- Why families should have 2 emergency funds (https://cnbc.com/select/family-emergency-funds-heres-why-you-should-have-2-emergency-funds)
- How much emergency fund should you have and where should you keep it? | Fidelity (https://fidelity.com/viewpoints/personal-finance/save-for-an-emergency)
- 14 Quotes From Our Favorite Money Saving Experts (https://chime.com/blog/quotes-from-money-saving-experts)
- Explore Investment and Savings Strategies
- 6 low-risk investments to consider now | Fidelity (https://fidelity.com/learning-center/personal-finance/low-risk-investments)
- Investment planning for your goals | Vanguard (https://investor.vanguard.com/investor-resources-education/how-to-invest/investment-planning-for-your-goals)
- Investing 101: A Starter Guide for Young Professionals (https://johnsonfinancialgroup.com/resources/blogs/young-professionals/investing-101-a-starter-guide-for-young-professsionals)
- Investing for Kids: A Parent’s Guide for Your Child’s Long-Term Financial Success (https://goodegginvestments.com/blog/investing-for-kids)
- Review and Adjust Your Financial Plan Regularly
- 13 Important Personal Finance Stats You Need to Know – Savology (https://savology.com/13-financial-statistics-you-need-to-know)
- 20 + Personal Finance Statistics for 2025 | Fortunly (https://fortunly.com/statistics/personal-finance-statistics)
- Top 50 Financial Planning Quotes [2025] (https://digitaldefynd.com/IQ/financial-planning-quotes)
- Newsroom | Northwestern Mutual – Planning & Progress Study 2023 (https://news.northwesternmutual.com/planning-and-progress-study-2023)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Family Governance for high-income W-2 families at Bright Advisers.
Keep reading