

Key Highlights:
- Bright Advisers specialises in personalised financial planning for young families, focusing on tax-aware borrowing.
- Tax-aware borrowing helps families lower homeownership costs through mortgage interest deductions, averaging $2,364 in tax benefits in 2021.
- Home Equity Lines of Credit (HELOCs) allow families to borrow against home equity, often with tax-deductible interest.
- Investment loans can provide tax deductions if the investments generate taxable income, aligning with families’ growth goals.
- Intra-relational loans among family members can minimise gift tax implications when structured properly.
- Keeping detailed financial records is essential for maximising tax benefits and ensuring compliance with IRS regulations.
- Utilising tax-advantaged accounts like HSAs and 529 plans can yield significant tax benefits for families.
- Educating children about financial concepts early fosters responsible money management for future generations.
- Engaging with financial planning software, educational websites, and workshops enhances families’ financial literacy and planning skills.
Introduction
Navigating the financial landscape can feel overwhelming for young families. It’s not just about numbers; it’s about securing a future for your loved ones. Understanding the intricacies of tax-aware borrowing is crucial, yet it often presents unique challenges that require thoughtful, tailored strategies.
Imagine if you could minimize your tax liabilities while ensuring your family’s financial success. This article explores seven essential borrowing strategies designed to empower young households like yours. We’ll share insights on how to effectively leverage tax benefits, helping you to secure a brighter economic future.
With so many options available, it’s natural to feel uncertain. How can you confidently choose the right strategies that align with your family’s financial goals? Together, we can navigate this journey, ensuring that your choices enhance your long-term stability and peace of mind.
We’re here for you, ready to support you every step of the way.
Bright Advisers: Personalized Financial Planning for Tax-Aware Borrowing
Are you a young parent feeling overwhelmed by financial planning? Bright Advisers understands your concerns and is here to help. We specialize in creating customized monetary plans tailored to the unique needs of young households like yours.
Imagine navigating the complexities of managing your finances with confidence. Our strategies for tax aware borrowing empower you to simplify the borrowing process while enhancing tax efficiency. This means you can make informed choices that protect your family’s economic future.
But we don’t stop there. Bright Advisers also offers legacy planning and valuable educational resources, such as the FamilyKnowledge™ Base. This tool helps families organize and share their values and traditions, ensuring that your family’s legacy is preserved for generations to come.
With cutting-edge technology and a client-centered approach, we provide that aligns with your family’s unique situation and goals. Together, we can establish a strong foundation for lasting economic success.
Just like Emily and Mark, who found the support they needed to achieve financial independence, you too can make knowledgeable choices about your future. Remember, we’re here for you every step of the way. Let’s navigate this journey together.
Understanding Tax Implications: Key Considerations for Young Families
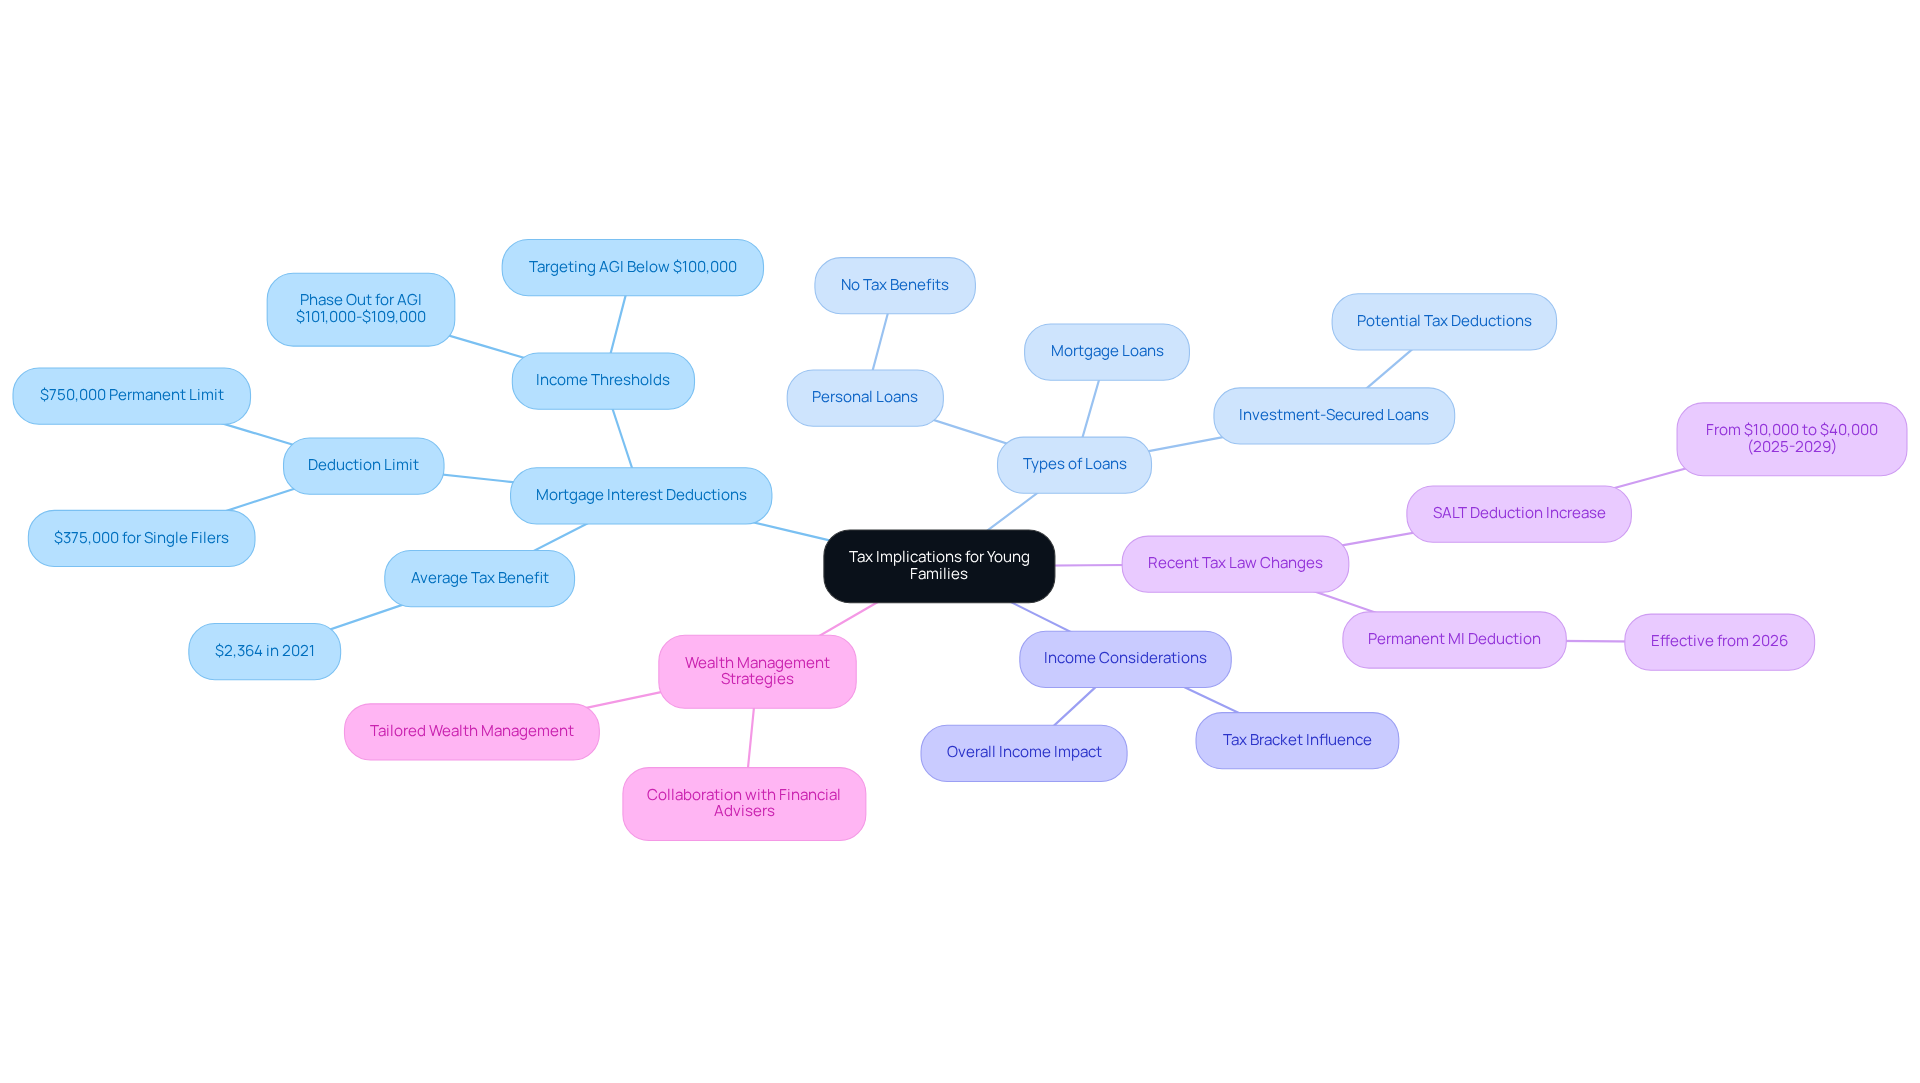
For young households, tax aware borrowing is crucial for understanding the tax implications of borrowing and achieving financial success. Imagine being able to lower the overall cost of homeownership through mortgage interest deductions. In fact, homeowners who claimed this deduction averaged a tax benefit of $2,364 in 2021. This deduction is especially beneficial for families with adjusted gross incomes below $100,000, as it phases out for individuals earning between $101,000 and $109,000. Plus, the mortgage interest deduction limit is permanently set at $750,000, giving you clarity on the maximum deductible amount.
While mortgages offer clear , other types of loans, like personal loans, typically don’t provide similar advantages. However, loans secured against investments might present opportunities for tax deductions, depending on your specific circumstances. When developing a borrowing strategy, it’s important to consider your overall income and tax bracket, as these factors can significantly influence how effectively you can implement tax aware borrowing to leverage available tax benefits.
Recent changes in tax laws, including the temporary rise in the state and local tax (SALT) deduction limit from $10,000 to $40,000 for tax years 2025-2029, make low-down-payment alternatives more appealing for families. Grasping these subtleties can empower you to make informed choices that align with your financial goals, paving the way for a more secure economic future. Moreover, keeping comprehensive records of intra-household loans is essential for tax aware borrowing, ensuring you maximize potential deductions.
By collaborating with Bright Advisers, families like Jay and Emma, who wanted to ease financial stress, or Emily and Mark, who sought economic independence, can create tailored wealth management strategies. Together, we can meet your immediate financial needs while ensuring your long-term economic health through effective tax planning. We’re here for you, ready to navigate this journey together.
Common Borrowing Structures: Strategies to Minimize Taxes
Navigating the world of finances can feel overwhelming, especially for young households. But there are several common borrowing structures that can help ease your tax burdens through tax aware borrowing and provide the support you need. Let’s explore these options together.
Home Equity Lines of Credit (HELOCs): Imagine being able to tap into the equity of your home. Families can borrow against this equity, often enjoying tax-deductible interest when the funds are used for significant home improvements or other qualifying expenses. With home equity at record levels, are becoming a popular choice, particularly as rates are expected to decrease in 2026. This option can give families like Emily and Mark the financial flexibility they need to invest in their home while managing their overall debt.
Investment Loans: What if borrowing could lead to growth? By taking out loans to invest, you can enjoy interest deductions, provided those investments generate taxable income. This strategy allows households to utilize tax aware borrowing to leverage their borrowing for potential growth while reaping tax benefits, aligning perfectly with the goals of families looking to improve their financial situation.
Intra-Relational Loans: Have you considered lending money within your family? Structuring loans among relatives can help minimize gift tax implications. By formalizing these loans with a signed agreement and a fixed repayment schedule, families can support one another while staying compliant with IRS guidelines. This approach can be especially beneficial for young households eager to lend a helping hand.
Secured Loans: Think about the advantages of loans secured by assets. These loans typically offer lower interest rates and potential tax benefits, making tax aware borrowing an attractive option for families aiming to manage their debt effectively while maximizing tax advantages. This way, you can focus on your long-term financial goals without added stress.
These strategies not only provide financial flexibility but also empower families like Emily and Mark, who worked with Bright Advisers, to make informed decisions that align with their long-term aspirations. By considering these borrowing frameworks, young households can alleviate financial pressure and work towards a stable future. Remember, we’re here for you, and together, we can navigate this journey.

Optimizing Tax Efficiencies: Best Practices for Young Families
To optimize tax efficiencies, young families can embrace some thoughtful practices that truly make a difference:
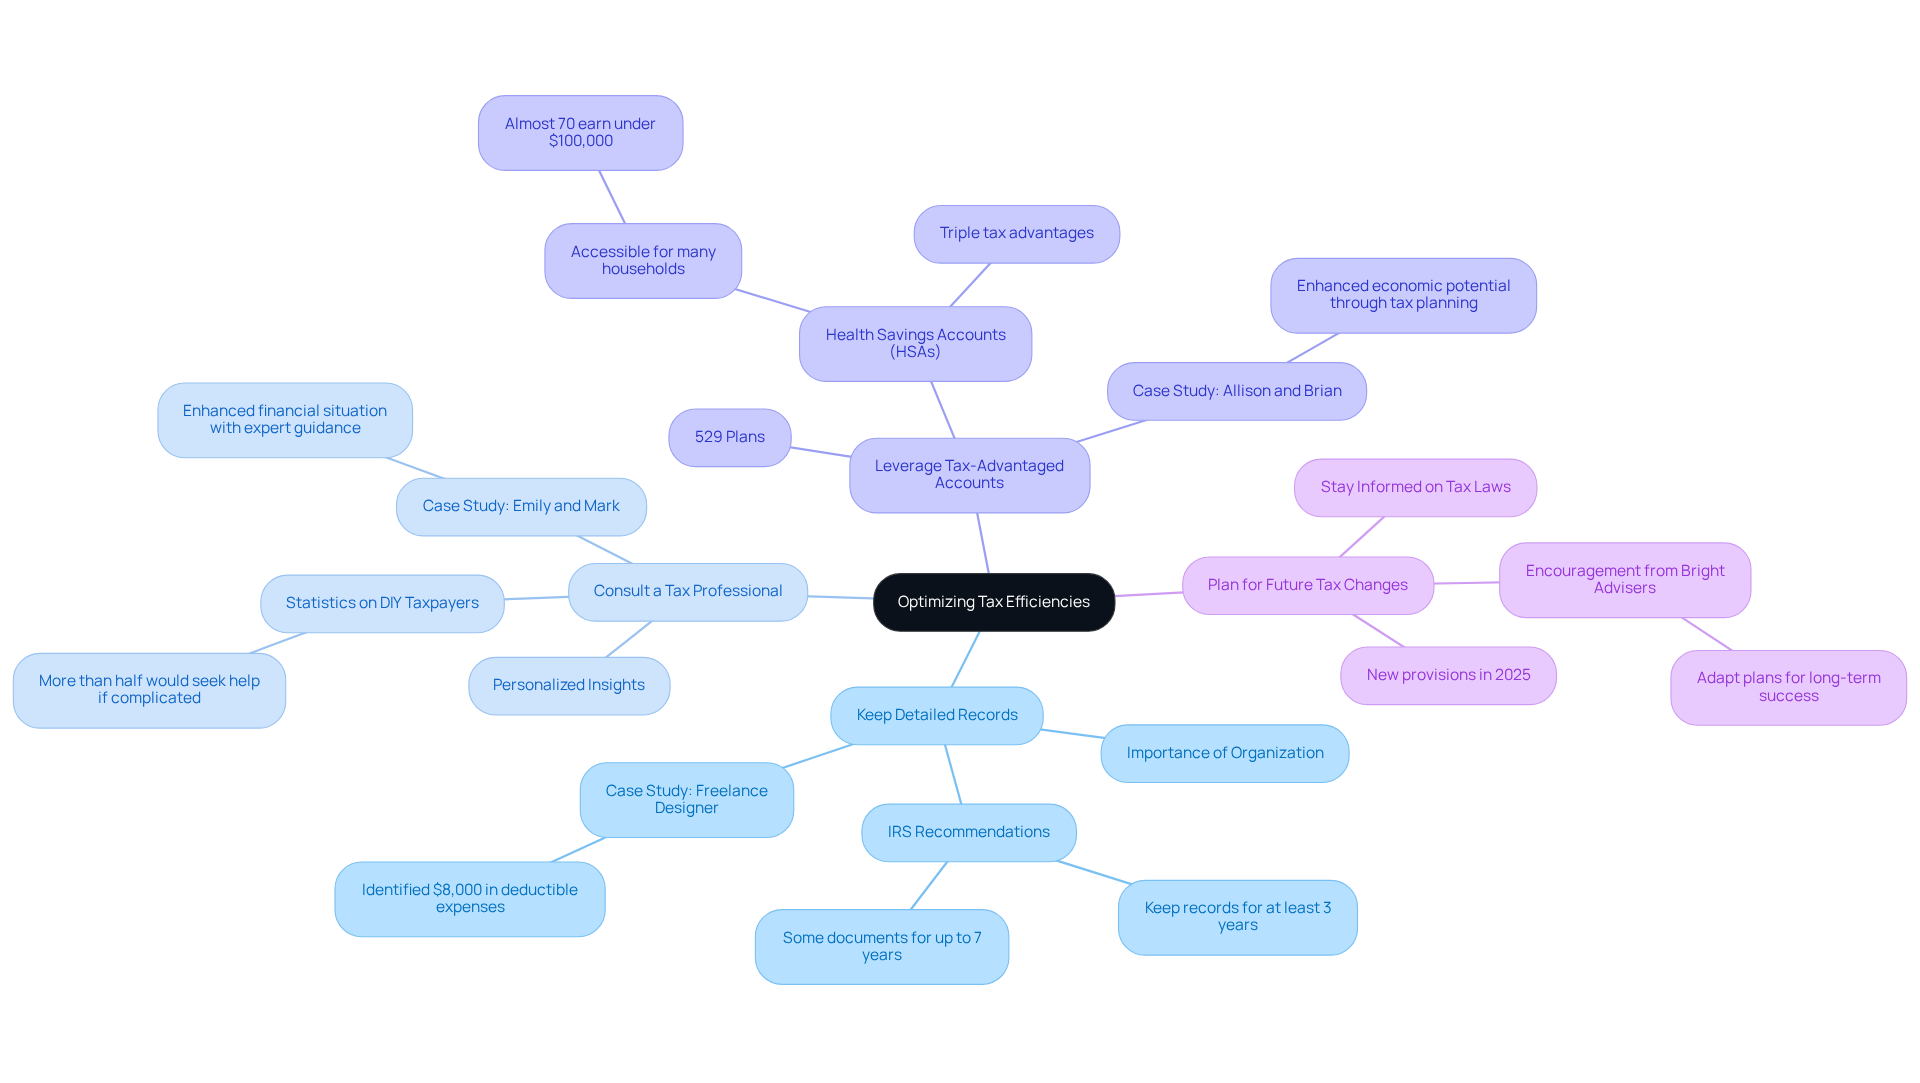
- [Keep Detailed Records](https://irs.gov/businesses/small-businesses-self-employed/why-should-i-keep-records): Imagine having all your financial documents neatly organized. Maintaining thorough documentation of loans and interest payments is crucial for accurate tax reporting. The IRS recommends keeping records for at least three years, with some documents needing to be stored for up to seven years. Effective record-keeping not only helps in tax compliance but also boosts your chances of success. Just like Jay and Emma, who managed their responsibilities with a comprehensive budget, you can find peace of mind in knowing you’re prepared.
It’s important to consult a tax professional, as they can provide personalized insights into structuring loans with tax aware borrowing for maximum tax benefits. Statistics reveal that more than half of do-it-yourself taxpayers would seek professional help if their situations became more complicated. This highlights the value of expert guidance in navigating tax implications. Emily and Mark, for instance, found great benefit from Bright Advisers‘ expertise, enhancing their financial situation and gaining the freedom to choose their career paths.
- Leverage Tax-Advantaged Accounts: Think about how utilizing accounts like Health Savings Accounts (HSAs) or 529 plans can yield significant tax benefits while supporting your family’s financial goals. HSAs, for example, offer triple tax advantages, making them an effective tool for managing healthcare costs and saving for future expenses. Notably, almost 70% of HSA users earn under $100,000 each year, showing that these accounts are accessible for many households. Just like Allison and Brian, who aimed to enhance their economic potential through effective tax planning, you too can take steps toward a brighter financial future.
Planning for future tax changes involves tax aware borrowing, as staying informed about potential changes in tax laws is essential for adapting your borrowing strategies proactively. With , it’s vital to regularly assess your financial strategies to ensure they align with current regulations and maximize your tax efficiencies. Bright Advisers encourages households to adapt their plans for long-term success, reminding you that you’re not alone in this journey.
Building Confidence: Securing Your Family’s Financial Future
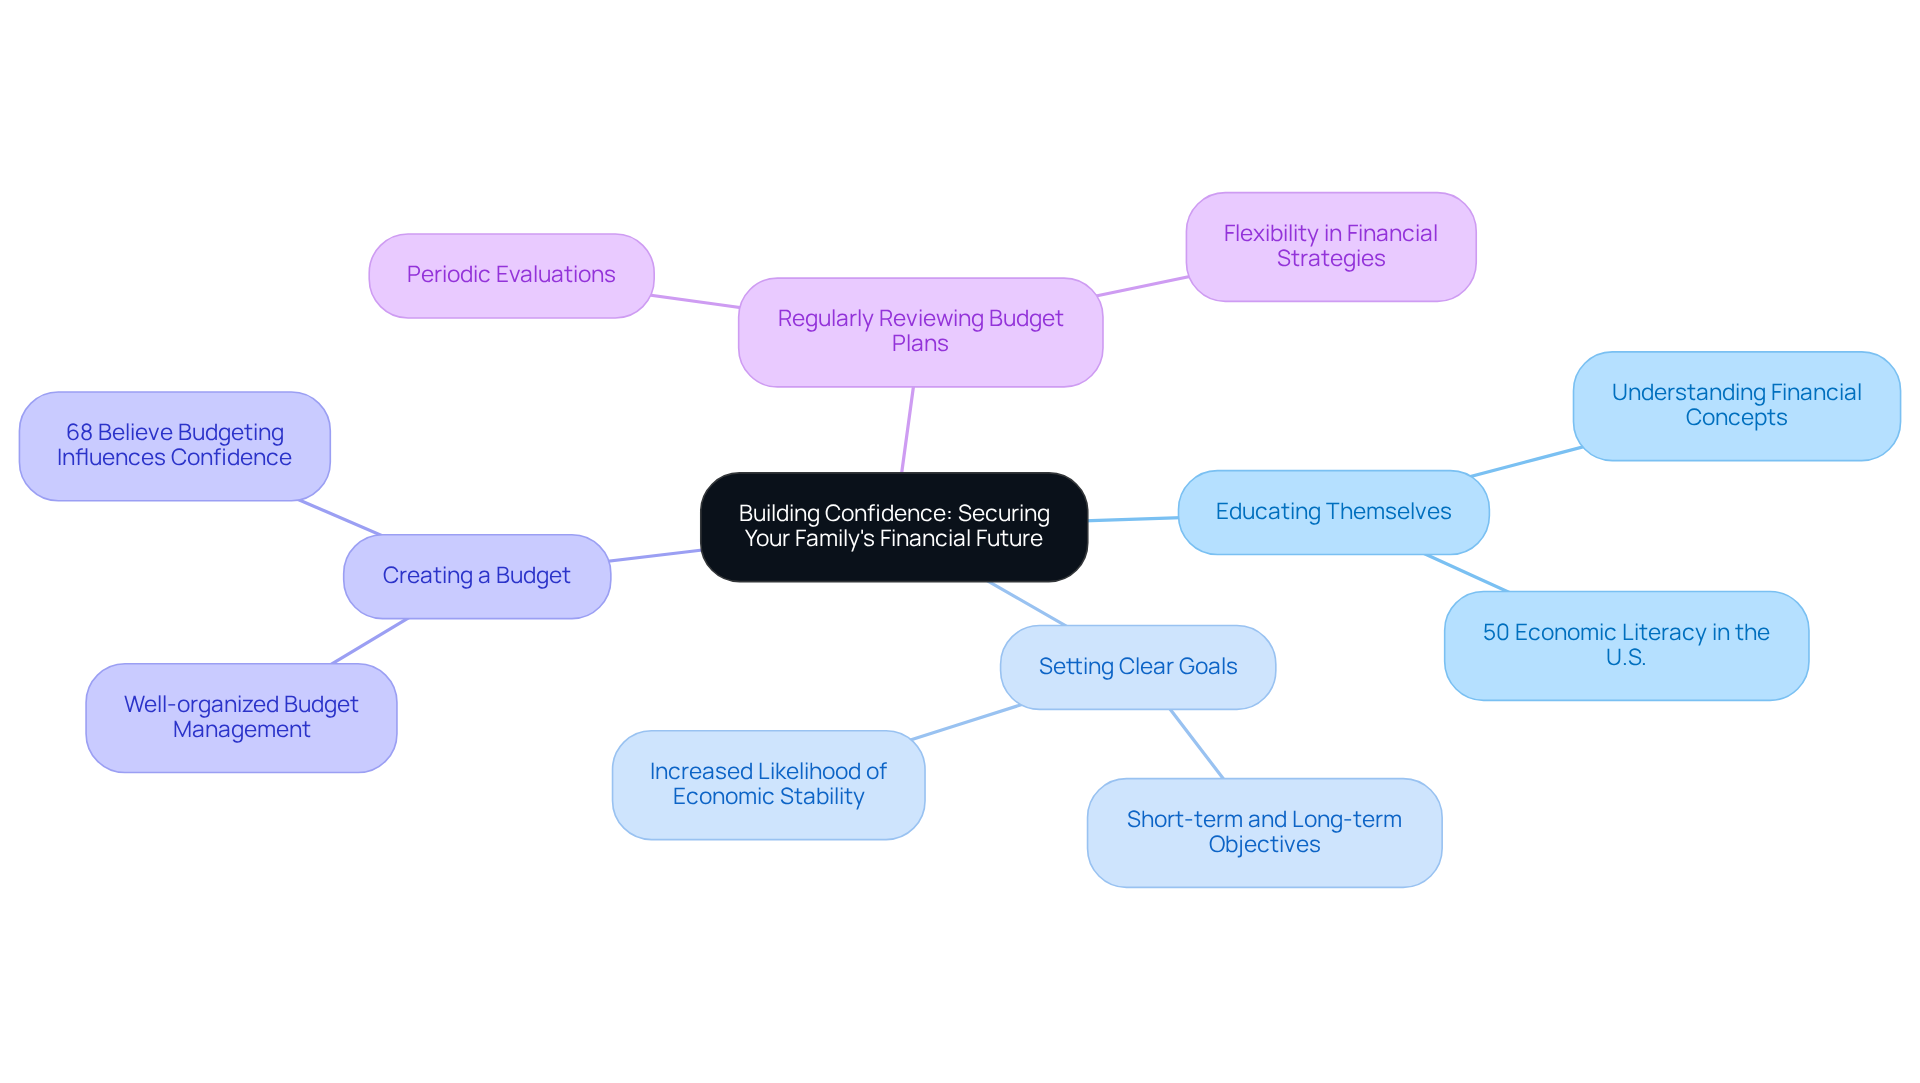
Ensuring your household’s economic future begins with building trust in your financial decisions. Imagine if you could navigate money matters with confidence and clarity. Families can achieve this by:
- Educating Themselves: Understanding financial concepts and tax implications empowers you to make informed choices. With in the U.S. hovering around 50%, enhancing your knowledge is crucial for effective money management. We’re here for you as you embark on this learning journey.
- Setting Clear Goals: Establishing both short-term and long-term monetary objectives gives you direction and motivation. Studies show that households with clear monetary goals are more likely to attain economic stability. Together, we can set these goals to create a brighter future for your family.
- Creating a Budget: A well-organized budget helps you manage expenses and allocate resources efficiently, ensuring you stay aligned with your financial goals. Significantly, 68% of respondents believe that having a household budget would greatly influence their confidence in managing money. Let’s work together to create a budget that suits your family’s needs.
- Regularly Reviewing Budget Plans: Periodic evaluations of your budget allow you to adjust your strategies as needed, keeping you in line with your evolving objectives. This practice is essential, especially as economic conditions change, impacting your household spending and savings. It’s important to understand that flexibility is key to financial success.
By emphasizing education, goal-setting, budgeting, and routine evaluations, you can incorporate tax aware borrowing to manage monetary complexities and ensure a thriving future for your family. Together, we can navigate this journey and build a secure economic foundation.
Additional Resources: Exploring More Financial Tools for Families
Families can tap into a range of financial tools and resources to boost their financial literacy and planning skills. Here’s how you can start:
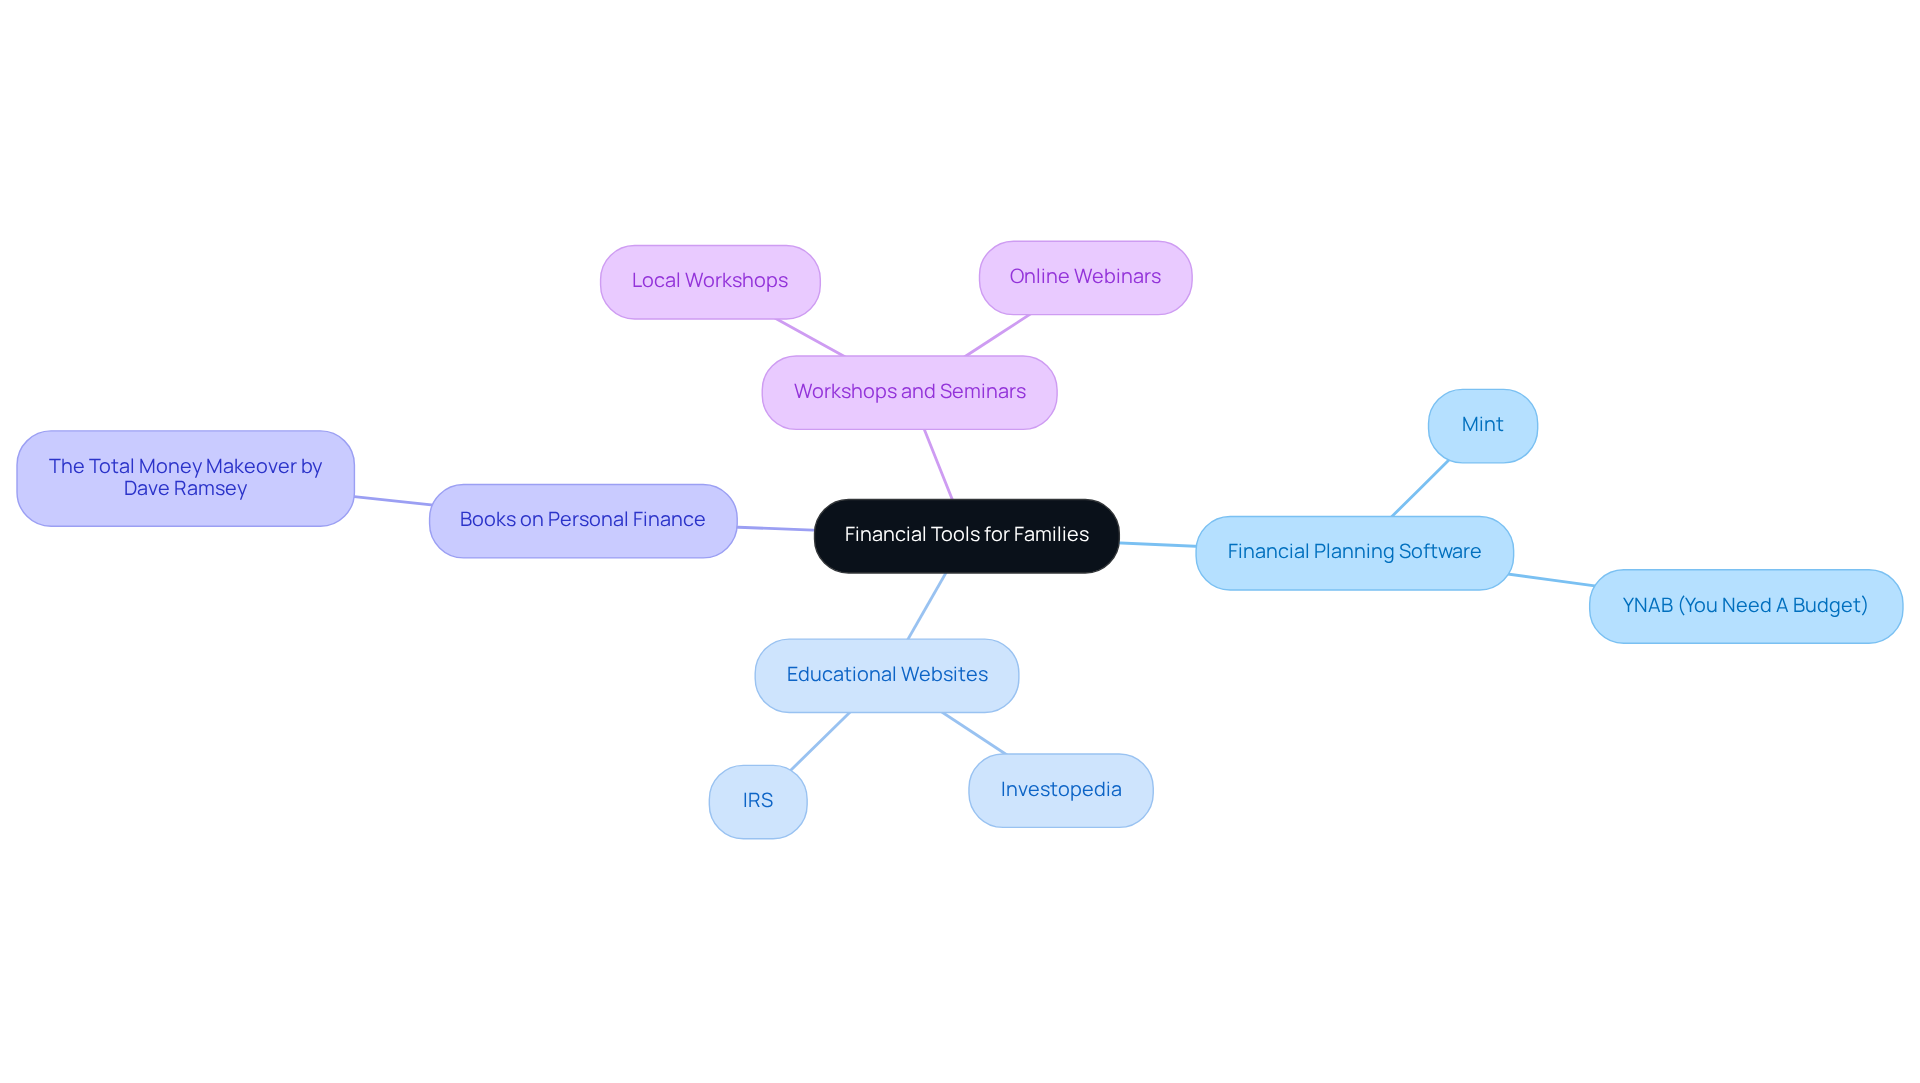
- Financial Planning Software: Imagine having tools like Mint and YNAB (You Need A Budget) at your fingertips. These empower families to track expenses and create effective budgets, nurturing better financial habits. As Robert Kiyosaki wisely says, ‘Financial freedom is available to those who learn about it and work for it.’ This highlights just how vital it is to use these tools.
- Educational Websites: Think about platforms like Investopedia and the IRS. They offer valuable insights into tax regulations and economic strategies, serving as essential resources for families navigating complex financial landscapes with a focus on tax aware borrowing. Engaging with these resources can significantly enhance your family’s money management knowledge.
- Books on Personal Finance: Have you ever read influential books like ‘The Total Money Makeover’ by Dave Ramsey? They provide practical insights into effective money management. As Dave Ramsey emphasizes, ‘You must gain control over your money, or the lack of it will forever control you.’ This underscores the importance of monetary education.
- Workshops and Seminars: Participating in local workshops or online webinars can be a game-changer. These events not only improve your financial knowledge but also offer networking opportunities with industry experts. They often focus on practical approaches that families can adopt to enhance their financial situations.
By actively engaging with these resources, families can build a solid foundation for their financial well-being. Together, we can navigate this journey, ensuring you’re well-prepared to make informed choices and .
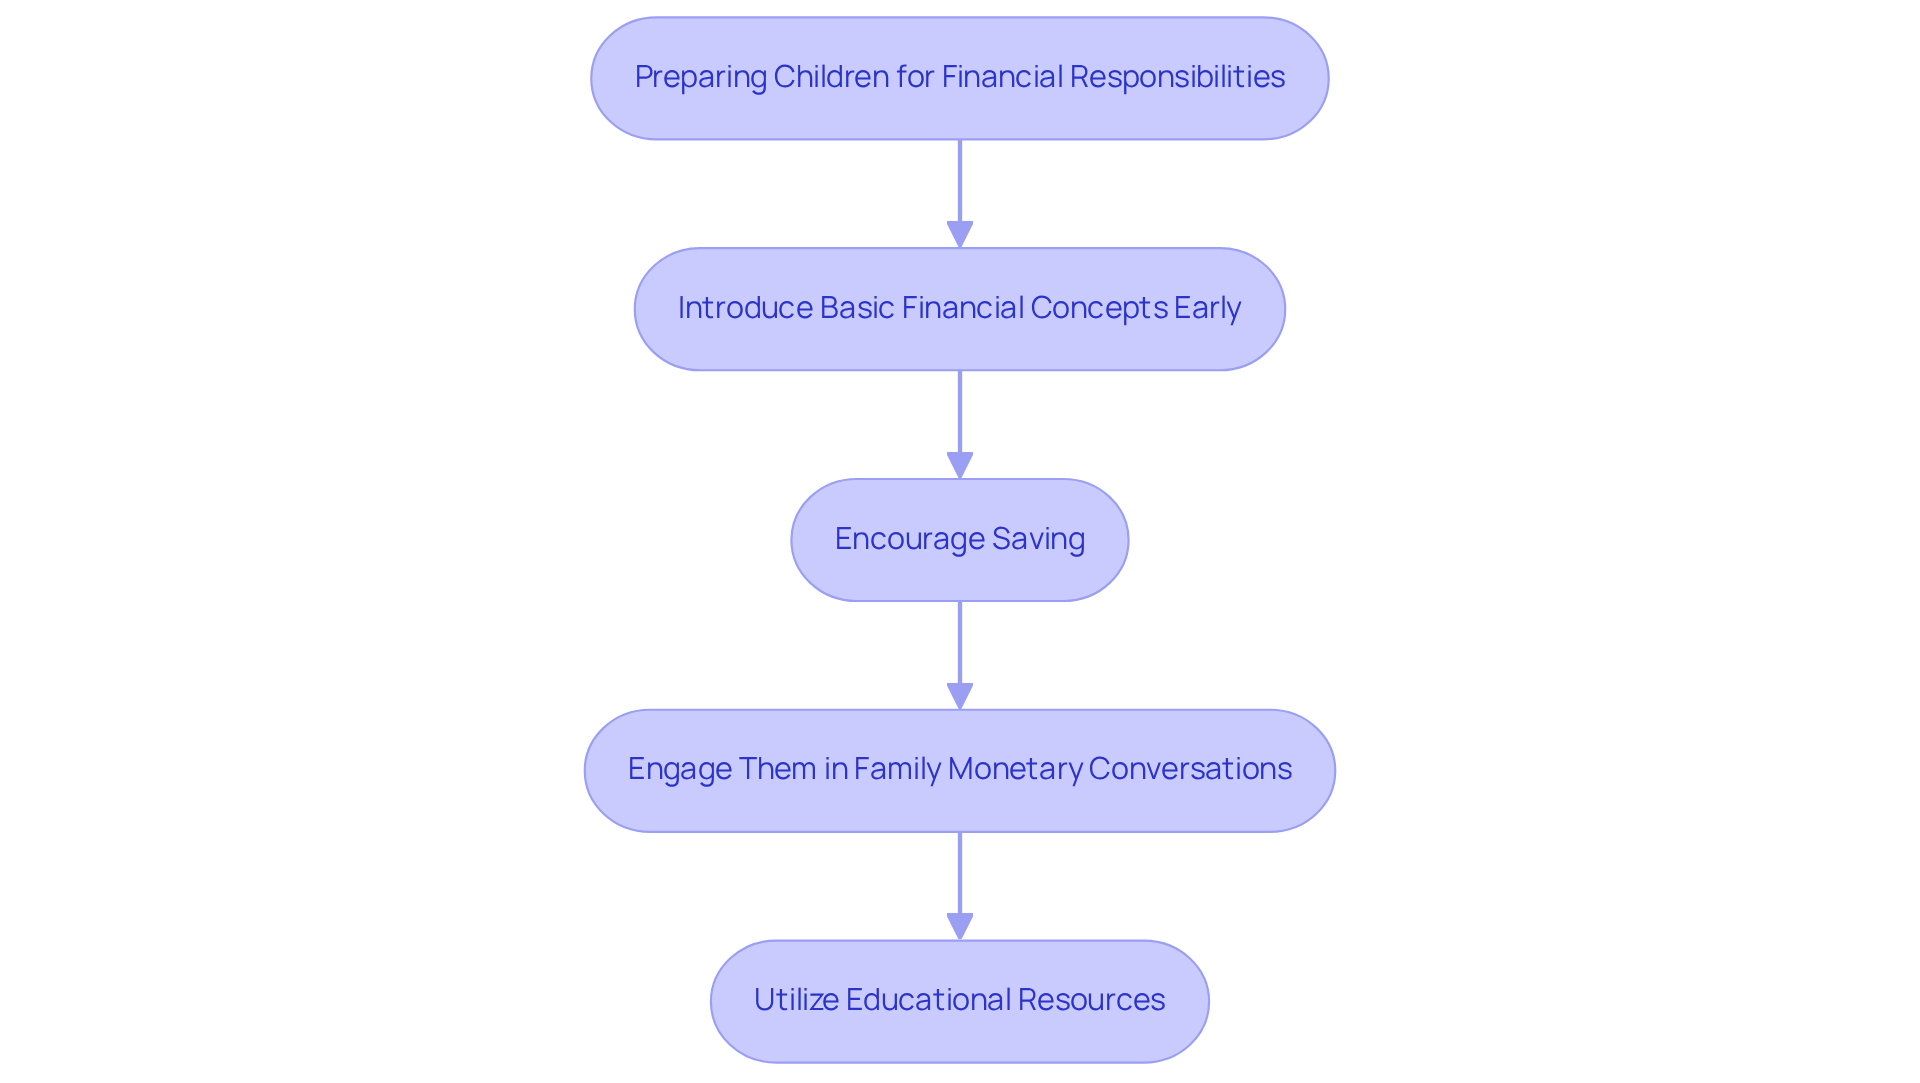
Educating Future Generations: Preparing Children for Financial Responsibilities
Preparing children for monetary responsibilities is essential for fostering a literate future generation. At Bright Advisers, we understand the importance of empowering young families through personalized planning to achieve long-term economic security. Together, we can navigate this journey by taking the following steps:
- Introduce Basic Financial Concepts Early: Imagine teaching your children about saving, spending, and budgeting from a young age. Instilling these good habits early on will serve them throughout their lives.
- Encourage Saving: Consider using tools like piggy banks or savings accounts to inspire your children to save for their goals. This reinforces the [importance of fiscal discipline](https://choosefifoundation.org/blog/scary financial literacy statistics) in a fun and engaging way.
- Engage Them in Family Monetary Conversations: It’s important to involve your children in discussions about budgeting and resource management. This helps them grasp the significance of these concepts and prepares them for future responsibilities.
- Utilize Educational Resources: Leverage age-appropriate financial literacy programs and games to make learning about money enjoyable. This ensures that your children are well-equipped for their financial futures.
We’re here for you, guiding your family towards a .
Conclusion
Navigating the financial landscape as a young family can feel overwhelming. But implementing tax-aware borrowing strategies can be a powerful way to secure a brighter economic future. These strategies not only simplify the borrowing process but also enhance tax efficiency, allowing families to make informed financial decisions that align with their long-term goals.
Imagine understanding the tax implications of your financial choices. By leveraging common borrowing structures like HELOCs and investment loans, you can optimize your tax efficiencies through diligent record-keeping and professional guidance. It’s essential for families to educate themselves on financial matters and actively engage in financial planning. This builds confidence and stability for the future.
Ultimately, your journey toward financial success hinges on informed decision-making and proactive planning. By embracing these tax-aware strategies and utilizing available resources, you can foster a secure economic foundation for your family and future generations. Taking these steps not only enhances financial literacy but also empowers you to navigate your financial future with confidence and clarity. Remember, we’re here for you – together, we can navigate this journey.
Frequently Asked Questions
What services does Bright Advisers offer for young families?
Bright Advisers specializes in personalized financial planning, including customized monetary plans, tax-aware borrowing strategies, legacy planning, and educational resources like the FamilyKnowledge™ Base.
How does tax-aware borrowing benefit young households?
Tax-aware borrowing helps young households understand the tax implications of borrowing, allowing them to simplify the borrowing process while enhancing tax efficiency, ultimately protecting their family’s economic future.
What is the mortgage interest deduction and who benefits from it?
The mortgage interest deduction allows homeowners to reduce their taxable income by deducting mortgage interest payments. It is particularly beneficial for families with adjusted gross incomes below $100,000, with an average tax benefit of $2,364 in 2021.
Are there tax benefits for other types of loans besides mortgages?
While mortgages offer clear tax benefits, other loans, like personal loans, typically do not provide similar advantages. However, loans secured against investments may present opportunities for tax deductions depending on individual circumstances.
What recent changes in tax laws should young families be aware of?
Recent changes include the temporary rise in the state and local tax (SALT) deduction limit from $10,000 to $40,000 for tax years 2025-2029, making low-down-payment alternatives more appealing for families.
Why is it important to keep records of intra-household loans?
Keeping comprehensive records of intra-household loans is essential for maximizing potential deductions in tax-aware borrowing, ensuring that families can fully benefit from available tax advantages.
Can Bright Advisers help families with immediate and long-term financial needs?
Yes, Bright Advisers collaborates with families to create tailored wealth management strategies that address immediate financial needs while ensuring long-term economic health through effective tax planning.
List of Sources
- Bright Advisers: Personalized Financial Planning for Tax-Aware Borrowing
- 12 Financial Planning Quotes for Building Wealth Wisely — Phillip James Financial (https://phillipjamesfinancial.com/blog/12-financial-planning-quotes-for-building-wealth-wisely)
- Can you maximize tax efficiency on your loans? (https://citizensbank.com/private-banking/insights/maximizing-tax-efficiency-on-loans.aspx)
- Tax-Aware Borrowing: Strategies for Minimizing Tax Liability: 500 Words to Sharpen Your Strategy (https://dermsquared.com/news-research/tax-aware-borrowing-strategies-500-words)
- Tax-Aware Borrowing | J.P. Morgan (https://jpmorgan.com/insights/real-estate/housing-market/what-to-know-about-tax-aware-borrowing)
- Tax aware borrowing – BMO Harris (https://uswealth.bmo.com/insights/tax-aware-borrowing)
- Understanding Tax Implications: Key Considerations for Young Families
- The $65 Billion Tax Break That Just Changed Everything for Homebuyers (https://mortgage.archgroup.com/the-65-billion-tax-break-that-just-changed-everything-for-homebuyers)
- Rebecca MacGregor quoted in Forbes’ “Need A Loan? Tax Rules Now Let You Borrow From Family At Ultra Low Interest Rates” – Don’t Tax Yourself (https://bowditch.com/estateandtaxplanningblog/2020/08/06/rebecca-macgregor-quoted-in-forbes-need-a-loan-tax-rules-now-let-you-borrow-from-family-at-ultra-low-interest-rates)
- Tax Implications of Lending Money to Family | Richmond VA (https://keitercpa.com/blog/family-loans-tax-considerations-lending-money)
- An Analysis of the Geographic Distribution of the Mortgage Interest Deduction: Before and After the 2017 Tax Revision (P.L. 115-97) (https://congress.gov/crs-product/R46685)
- Can Mortgage Interest Be Deducted from Taxes? Here’s What You Need to Know (https://thefederalsavingsbank.com/Blog/can-mortgage-interest-be-deducted-from-taxes-heres-what-you-need-to-know)
- Common Borrowing Structures: Strategies to Minimize Taxes
- Real estate (taxes, mortgage interest, points, other property expenses) 2 | Internal Revenue Service (https://irs.gov/faqs/itemized-deductions-standard-deduction/real-estate-taxes-mortgage-interest-points-other-property-expenses/real-estate-taxes-mortgage-interest-points-other-property-expenses-2)
- What You Need to Know About HELOCs in 2026 (https://experian.com/blogs/ask-experian/what-you-need-to-know-about-helocs)
- Mortgage Lock-In Spurs Recent HELOC Demand – Liberty Street Economics (https://libertystreeteconomics.newyorkfed.org/2024/08/mortgage-lock-in-spurs-recent-heloc-demand)
- MBA Home Equity Study Shows Increase in Originations, Debt Outstanding in 2024 (https://mba.org/news-and-research/newsroom/news/2025/07/28/mba-home-equity-study-shows-increase-in-originations–debt-outstanding-in-2024)
- Family Loans: Should You Lend It or Give It Away? (https://schwab.com/learn/story/family-loans-should-you-lend-it-or-give-it-away)
- Optimizing Tax Efficiencies: Best Practices for Young Families
- The Importance of Accurate Bookkeeping for Tax Compliance (https://outoftheboxtechnology.com/blog/importance-accurate-bookkeeping-for-tax-compliance)
- Why should I keep records? | Internal Revenue Service (https://irs.gov/businesses/small-businesses-self-employed/why-should-i-keep-records)
- When to Hire a Tax Pro: The Age Most Americans Switch to a CPA (https://kiplinger.com/taxes/the-age-most-americans-hire-a-tax-professional)
- 10 Best Tax-Free Investments for Young Families’ Financial Growth – Bright Advisers (https://brightadvisers.com/10-best-tax-free-investments-for-young-families-financial-growth)
- Building Family Economic Success: The Earned Income Tax Credit (EITC) (https://aecf.org/resources/building-family-economic-success-the-earned-income-tax-credit-eitc)
- Building Confidence: Securing Your Family’s Financial Future
- Can you answer these 3 questions about your finances? The majority of US adults cannot (https://weforum.org/stories/2024/04/financial-literacy-money-education)
- The Average American Household Budget | Bankrate (https://bankrate.com/personal-finance/average-household-budget)
- 27 eye-opening financial planning statistics (https://contentsnare.com/financial-planning-statistics)
- Key Financial Literacy Statistics in 2023 (https://annuity.org/financial-literacy/financial-literacy-statistics)
- New Survey Shows Consumers, No Matter Their Income or Assets, Need Support with Spending, Household Budgeting (https://cfp.net/news/2019/01/new-survey-shows-consumers-no-matter-their-income-or-assets-need-support-with-spending-household)
- Additional Resources: Exploring More Financial Tools for Families
- Smartphone Users Managing Finances on Apps (https://thinkwithgoogle.com/marketing-strategies/app-and-mobile/finance-app-usage-statistics-by-month)
- 27 eye-opening financial planning statistics (https://contentsnare.com/financial-planning-statistics)
- 200 Quotes About Money And Personal Finance To Inspire You (https://marriagekidsandmoney.com/20-empowering-quotes-about-money-and-personal-finance)
- 14 Quotes From Our Favorite Money Saving Experts (https://chime.com/blog/quotes-from-money-saving-experts)
- Consumer Financial Wellness Stats, Expectations, Graphics, and More | MX (https://mx.com/blog/financial-wellness-stats)
- Educating Future Generations: Preparing Children for Financial Responsibilities
- Can America Compete? (https://nefe.org/news/nefe-digest/2017/can-america-compete.aspx)
- Youth Financial Literacy Statistics (https://financialeducatorscouncil.org/youth-financial-literacy-statistics)
- A “Compounding” Problem: Financial Illiteracy in Youth (https://jointsdgfund.org/article/compounding-problem-financial-illiteracy-youth)
- Scary Financial Literacy Statistics for Kids, Teens & Adults (2021) (https://choosefifoundation.org/blog/scary financial literacy statistics)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Tax Management for high-income W-2 families at Bright Advisers.
Keep reading