

Overview
Navigating the world of Traditional IRAs can feel overwhelming for young parents. It’s essential to be aware of the seven key disadvantages that could impact your family’s financial future. For instance, early withdrawals can lead to penalties, and the limited investment options may not align with your family’s goals. Additionally, the complex management requirements can add to the stress of financial planning.
Imagine if you could make informed decisions that not only secure your family’s future but also simplify your financial journey. Understanding the tax implications, contribution limits, and the long-term commitment required for effective retirement savings is crucial. These considerations highlight the importance of careful planning and informed decision-making.
We’re here for you, guiding you through these challenges. Together, we can navigate this journey, ensuring that your family’s financial health is prioritized. Remember, investing in your family’s future means being proactive and seeking support when needed. With the right guidance, you can turn these challenges into opportunities for growth and stability.
Key Highlights:
- Bright Advisers offers personalized financial planning tailored for families with young children, focusing on Traditional IRAs.
- Contributing to a Traditional IRA can yield significant tax savings, making it a strategic choice for families.
- Early withdrawals from Traditional IRAs incur a 10% penalty before age 59½, necessitating careful financial navigation.
- For 2025, the contribution limit for Traditional IRAs is $7,000 for individuals under 50 and $8,000 for those 50 and older.
- Required Minimum Distributions (RMDs) begin at age 73, impacting long-term financial planning for families.
- Traditional IRAs limit investment options compared to self-directed IRAs, which may restrict growth potential.
- Tax deductions for Traditional IRA contributions can phase out based on income, requiring families to evaluate their eligibility.
- Exceeding contribution limits results in a 6% excise tax on excess amounts, emphasizing the need for careful monitoring.
- Long-term commitment is essential for Traditional IRA investments, with families needing to balance current financial responsibilities with future savings.
Introduction
In the intricate world of retirement planning, families with young children encounter unique challenges that call for tailored solutions. At Bright Advisers, we specialize in personalized financial strategies, particularly focusing on Traditional IRAs, to help these families navigate the complexities of retirement savings.
Imagine being able to maximize tax benefits while understanding contribution limits and avoiding penalties. We empower parents to build a secure financial future for their children.
As families strive to balance immediate needs with long-term goals, the guidance of expert financial advisors becomes essential. It’s important to understand that our support can demystify the process, ensuring that every decision aligns with your values and aspirations.
This article delves into the critical aspects of Traditional IRAs, offering insights and strategies designed to significantly enhance your family’s financial foundation. Together, we can navigate this journey.
Bright Advisers: Personalized Financial Planning for Traditional IRAs
At Bright Advisers, we understand the unique challenges faced by families with young children, especially when it comes to financial planning. Our personalized approach addresses the traditional IRA cons while empowering you and guiding you through the complexities of saving for your family’s future. Imagine contributing $5,000 to a Traditional IRA and considering some traditional IRA cons, such as the potential for significant tax savings of $1,250 if you’re in the 25% tax bracket. This means more resources to invest in your children’s dreams and aspirations.
This client-focused approach not only clarifies your financial future but also aligns your monetary strategies with your family’s values and long-term goals. We believe in the importance of flexibility in managing your investment accounts. Our financial consultants encourage you to regularly review your portfolio and make adjustments as your circumstances evolve. As one of our clients wisely said, “Stay flexible, review your portfolio often, and be ready to make quick adjustments as the situation evolves.”
At Bright Advisers, we emphasize the power of tailored economic strategies for young parents. By focusing on customized approaches—like tax-loss harvesting and eliminating unnecessary fund fees—you can build a solid financial foundation that supports your children’s needs while preparing for a secure future. Our comprehensive services, including tax optimization, education funding, and early retirement planning, are designed to empower families like Emily and Mark to achieve economic independence.
This holistic service model positions Bright Advisers as a trusted partner in wealth management, ensuring that you can navigate the complexities and traditional IRA cons with confidence and clarity. Remember, together, we can navigate this journey, and we’re here for you every step of the way.
Tax Penalties: Understanding the Consequences of Early Withdrawals from Traditional IRAs
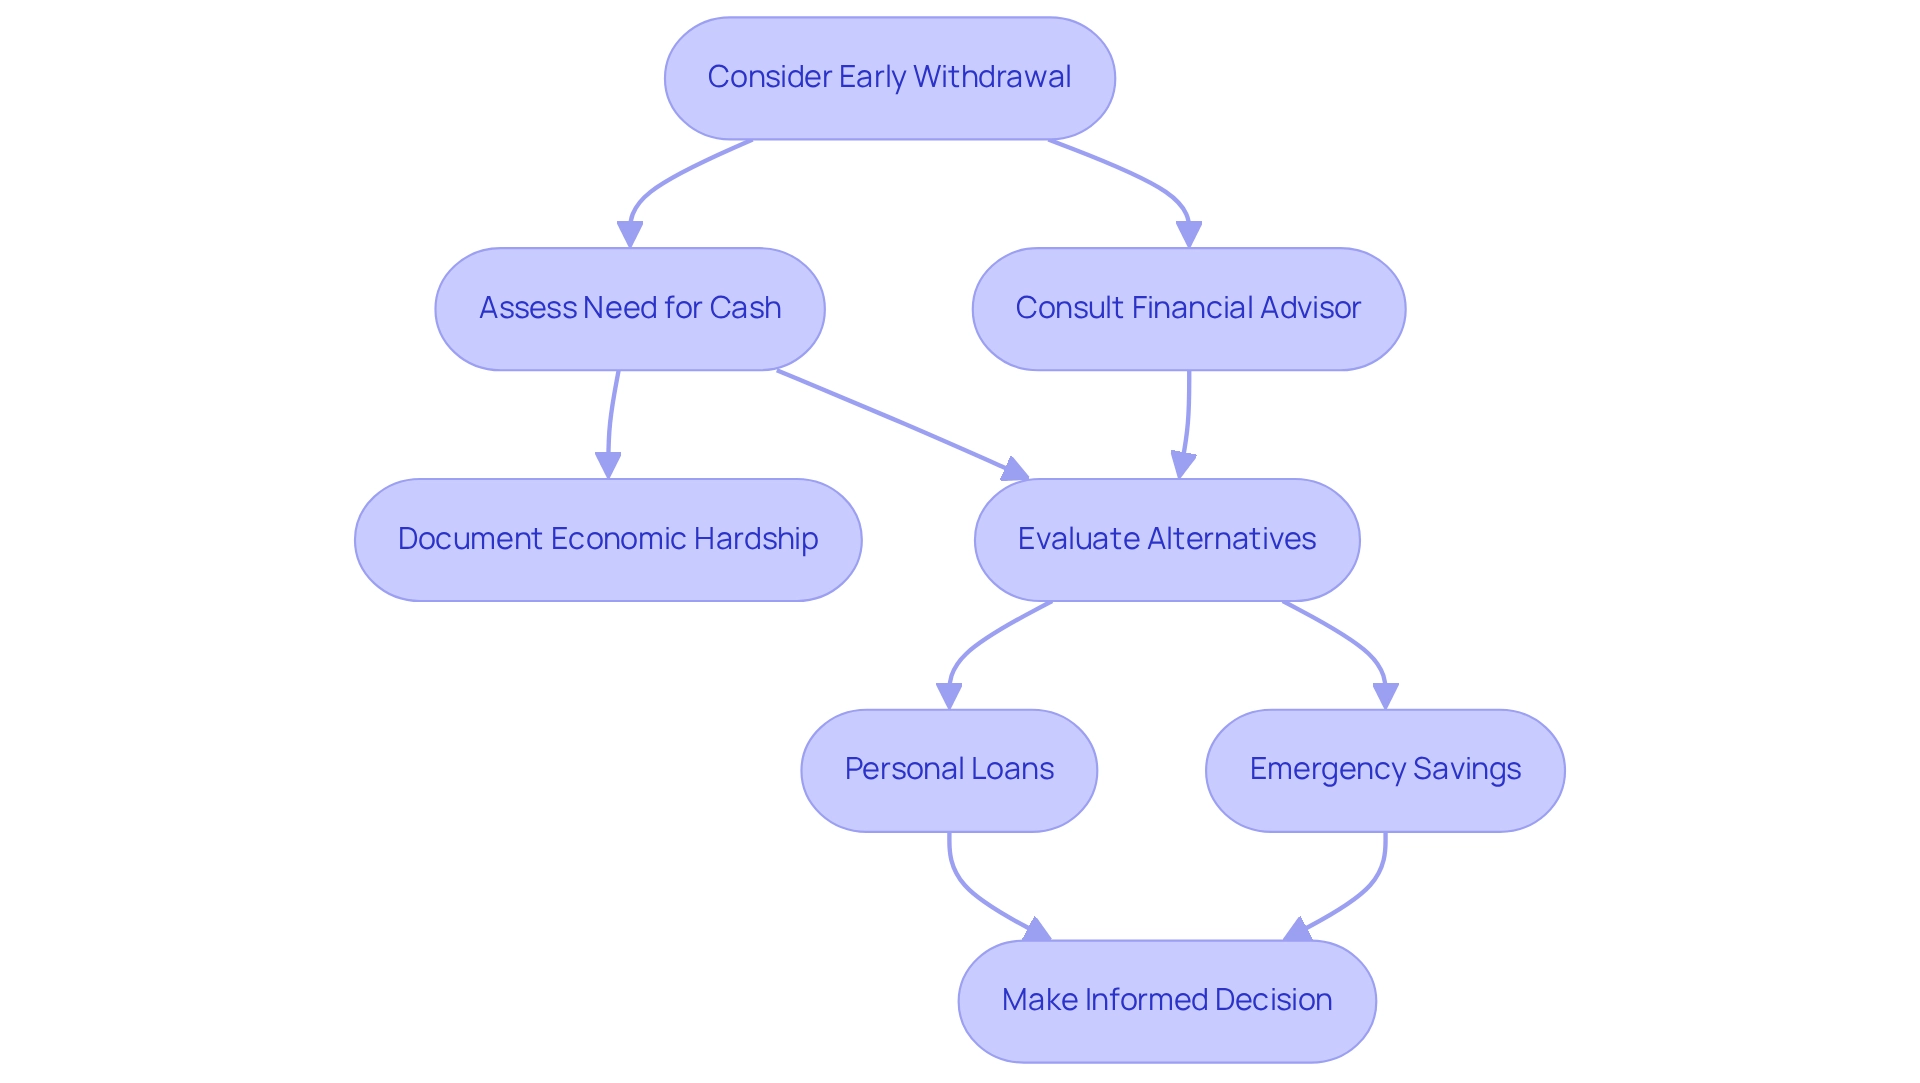
One of the traditional IRA cons is the significant drawback of a 10% penalty imposed on early withdrawals made before the age of 59½. This penalty can drastically diminish the funds available for immediate needs, making it essential for young parents to navigate their finances with care. Families encountering unforeseen costs may find themselves in a challenging situation if they resort to early withdrawals, as the penalties can lead to a significant economic setback. It’s important to understand that individuals must provide detailed documentation to support a claim of economic hardship for early withdrawal, underscoring the complexities involved in accessing these funds.
Imagine if you could find guidance during these tough times. Consulting with a qualified monetary advisor, like those at Bright Advisers, can provide invaluable insights for households considering early withdrawals. Bright Advisers is dedicated to low fund fees, which improves wealth management accessibility and enables families to make informed choices. As noted by Kevin O’Neil, Managing Director and Product Management Executive at Merrill, “You should consult your personal tax advisor regarding your specific situation before making any decisions.” This expert advice aids in evaluating overall monetary circumstances and balancing urgent requirements with long-term goals for the future.
Understanding the rules surrounding IRA withdrawals is crucial. For example, if taxes are withheld from a Traditional IRA distribution, the entire amount must be rolled over using other funds to avoid additional penalties. Real-life instances demonstrate how households can handle monetary crises without endangering their savings for the future. By examining different financing methods, like personal loans or emergency savings accounts, families can reduce the necessity for early withdrawals and safeguard their savings for later.
Moreover, remaining updated on the latest regulations and penalties related to traditional IRA cons enables young parents to make knowledgeable choices that protect their economic future. Ultimately, steering clear of early withdrawal penalties is not merely about safeguarding savings; it’s about securing a stable economic base for everyone. Together, we can navigate this journey and ensure a brighter financial future for your family.
Contribution Limits: Navigating the Restrictions on Traditional IRA Contributions
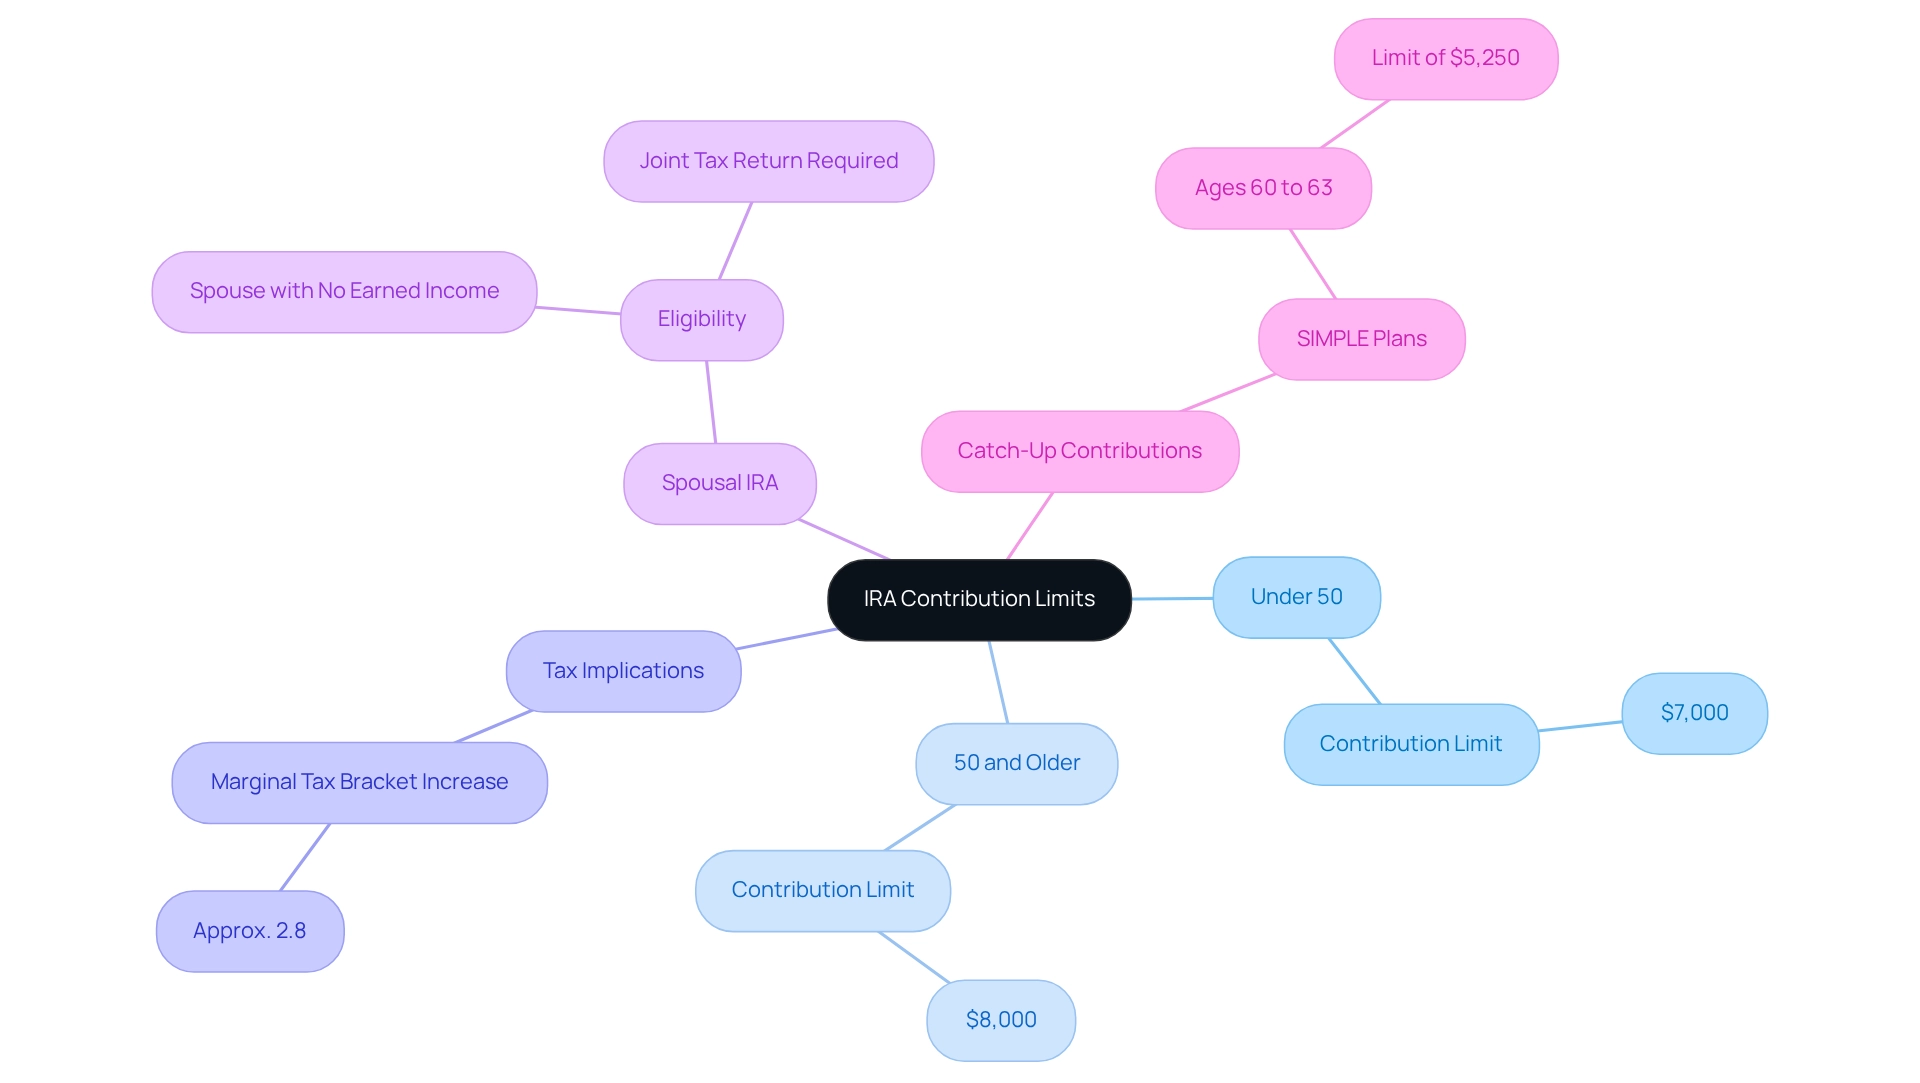
For the tax year 2025, the contribution limit for Traditional IRAs is set at $7,000 for individuals under 50, while those aged 50 and older can contribute up to $8,000. Understanding these limits is vital for young households, as they directly influence the amount that can be saved each year in a tax-advantaged account. Imagine the peace of mind that comes from fully utilizing these contribution limits; households can significantly enhance their savings for the future, paving the way for a more secure financial situation.
It’s important to recognize that the recent increase in marginal tax brackets by approximately 2.8% for 2025 further underscores the importance of maximizing contributions. This adjustment allows households to potentially save more without incurring higher tax obligations. Financial advisors emphasize that maximizing these limits can lead to substantial long-term gains, making it an essential strategy for families aiming to build a robust investment portfolio. At Bright Advisers, our commitment to minimal fund fees enhances wealth management accessibility, empowering households to navigate their financial futures with confidence.
Furthermore, consider the option of a spousal IRA. This allows a spouse without earned income to contribute to an IRA, provided the couple files a joint tax return with sufficient earned income to cover both contributions. This thoughtful approach can further bolster savings for families, ensuring that both partners are actively engaged in their economic planning. Together, we can explore Bright Advisers’ innovative wealth management strategies, enabling households to create hyper-personalized investment portfolios that align with their unique financial objectives. We’re here for you, ready to support you on this journey.
Required Minimum Distributions: Planning for Mandatory Withdrawals from Traditional IRAs
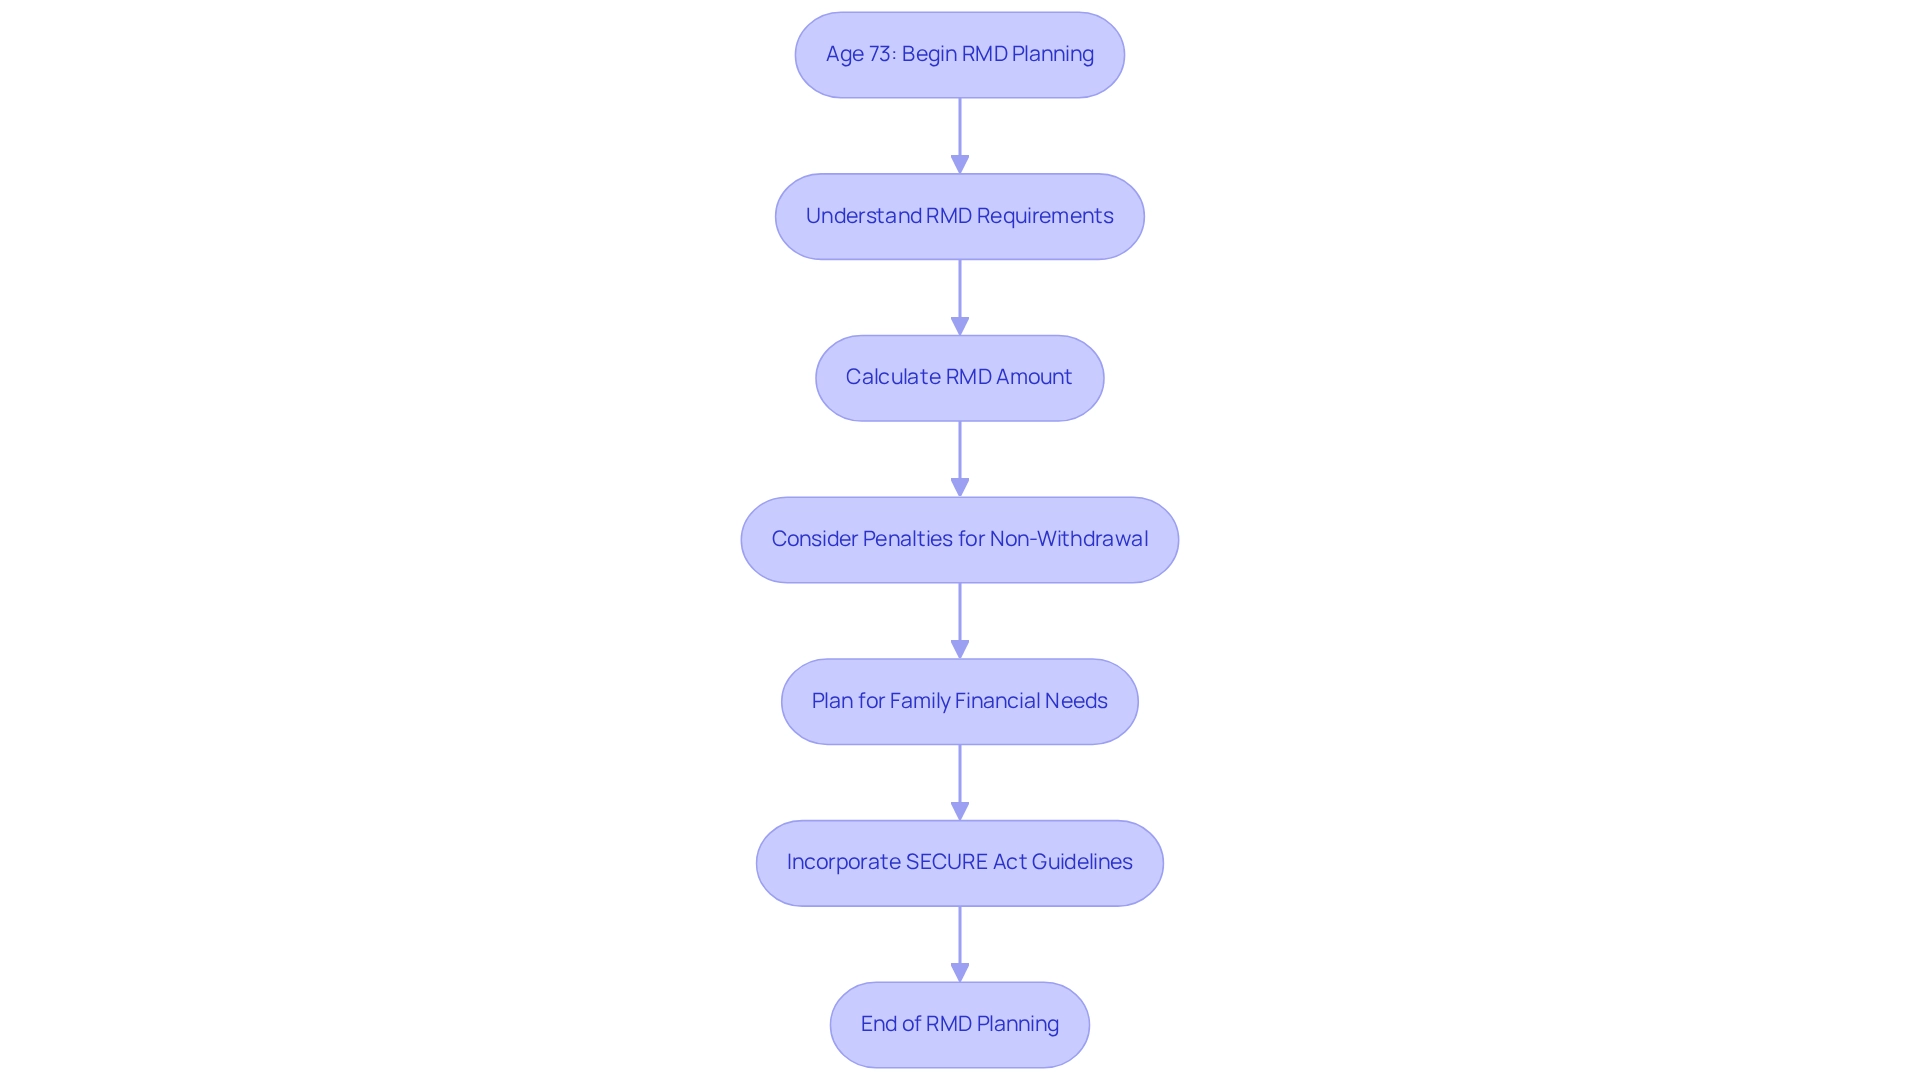
As you reach the age of 73, it’s important to be aware of traditional IRA cons, specifically the requirement to take Required Minimum Distributions (RMDs) from your Traditional IRAs. This requirement can significantly impact how you plan your household’s income for the years ahead. Failing to withdraw the minimum amount can lead to substantial penalties, which is a concern for many families.
For young parents, incorporating RMD considerations into your retirement planning is essential. Imagine ensuring that you have enough funds available to meet RMD obligations while still supporting your family’s financial needs. At Bright Advisers, we are committed to providing personalized wealth management solutions that empower young families like yours. We offer educational resources designed to help you navigate these complexities with confidence.
Under the SECURE Act, if you inherit an IRA, you must withdraw all funds within ten years of the original beneficiary’s passing. This adds another layer of complexity for families organizing their futures. Research shows that individuals with fewer non-retirement assets are more likely to face penalties from early withdrawals, often due to unforeseen life events. Thus, proactive financial education and planning are vital.
As investment adviser Chris Gullotti explains, “Say your IRA was worth $500,000 at the end of 2023, and you were taking your first RMD at age 73 that year. Your distribution amount would be $18,868 ($500,000 divided by 26.5).” Understanding RMDs and the traditional IRA cons can help families align their future strategies with long-term financial goals.
Moreover, establishing charitable organizations can instill values in future generations, enriching your family’s financial legacy. Together, we can navigate this journey, ensuring that your family’s financial future is secure and aligned with your shared values.
Limited Investment Options: Exploring the Constraints of Traditional IRAs
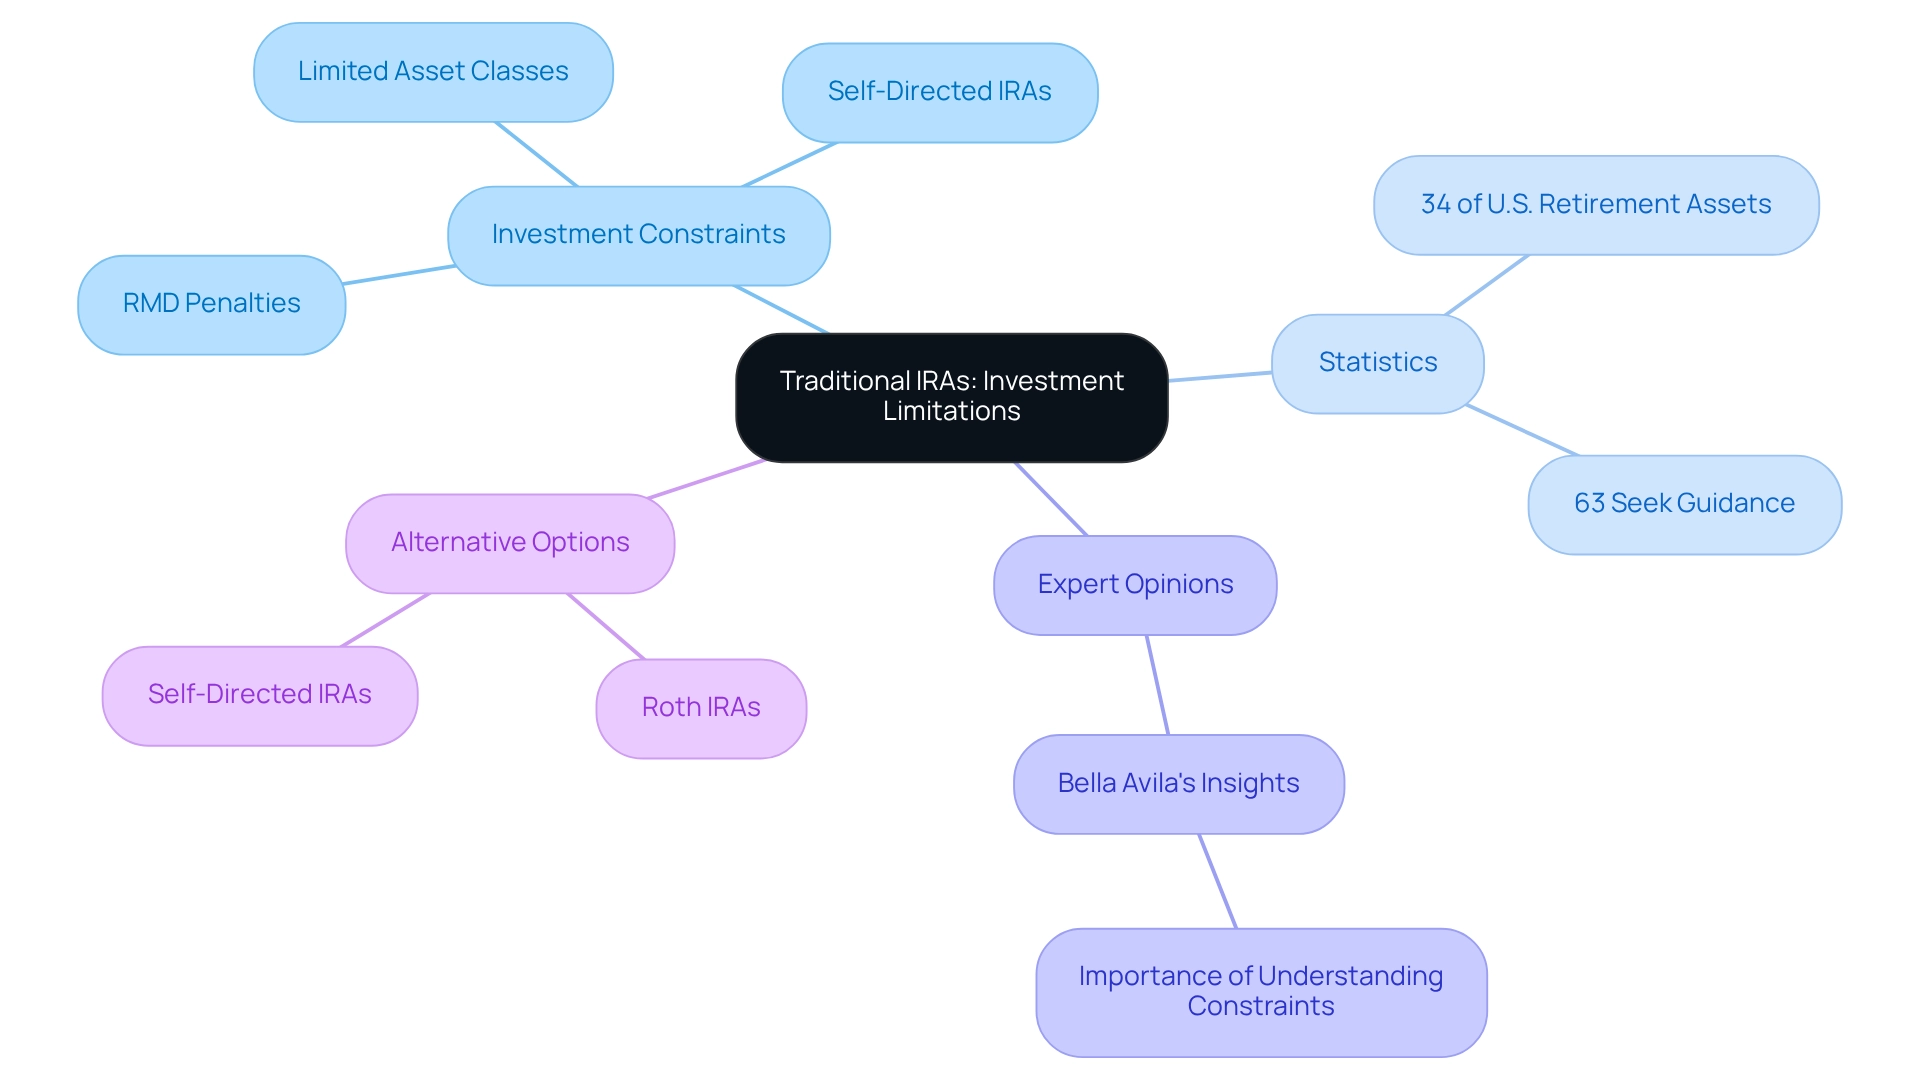
Families eager to diversify their investment choices may find traditional IRA cons to be limiting. While these accounts allow for investments in stocks, bonds, and mutual funds, they often restrict access to alternative assets like real estate or commodities unless you opt for a self-directed IRA. This limitation can hinder your family’s potential for growth and diversification, both of which are essential for securing your economic future.
As of mid-2022, IRAs collectively held a staggering $11.7 trillion in assets, representing 34% of all U.S. retirement assets. This statistic highlights their popularity among households. However, a survey by the Investment Company Institute revealed that 63% of traditional IRA owners sought guidance from advisors before making significant changes. This underscores the importance of informed decision-making in navigating these investment constraints. Bella Avila, a content management expert at NerdWallet, wisely notes, “Comprehending the constraints of your investment choices is essential for successful monetary planning, particularly for households aiming to create a stable future.”
Imagine young families like Emily and Mark, who are striving for financial independence and the freedom to make work optional. The traditional IRA cons, such as limited investment options, could obstruct their ability to achieve savings objectives efficiently. Experts recommend that households save between 12% to 15% of their salary for retirement. Yet, the traditional IRA cons can make this process more complicated. Recent changes introduced by the SECURE Act allow contributions to a traditional IRA regardless of age, which is especially beneficial for young families wishing to start saving early. However, the investment options remain fundamentally unchanged, which may not meet the diverse needs of today’s families.
On the other hand, other savings accounts, such as Roth IRAs or self-directed IRAs, provide a broader array of investment possibilities. These options enable families to explore various asset classes that could enhance their portfolio’s resilience and growth potential. Additionally, it’s crucial to understand that most conventional IRA holders must begin withdrawing a portion of their savings at age 72, facing penalties for failing to meet required minimum distributions (RMDs). This can further complicate budgeting for families.
Investment planning companies like Bright Advisers focus on delivering customized strategies to help families manage these constraints. We’re here for you, ensuring you maximize your savings while aligning with your long-term monetary objectives. By partnering with experts, families can optimize their financial situation and build a solid foundation for their future. Together, we can navigate this journey towards financial security.
Misleading Tax Deductions: Evaluating the True Benefits of Traditional IRA Contributions
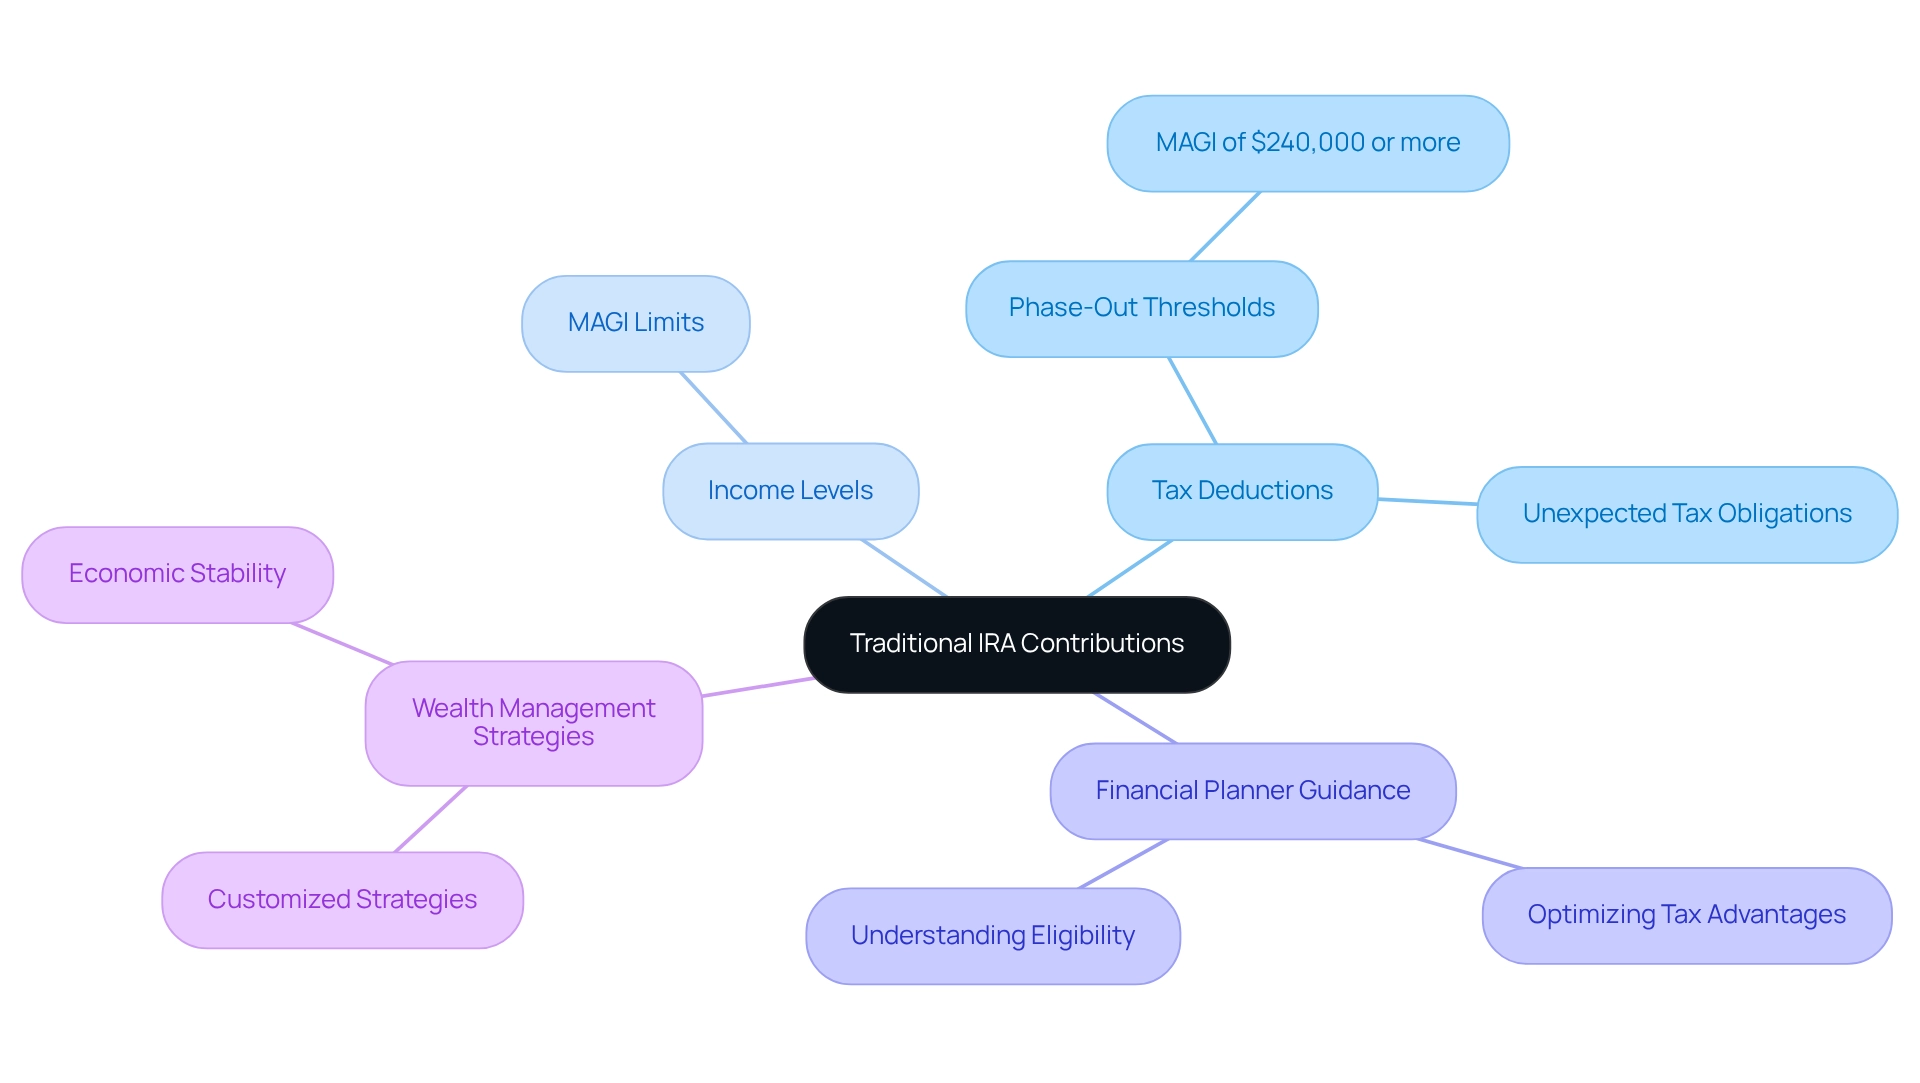
Contributions to a Traditional IRA can provide valuable tax deductions, but it is important to consider the traditional IRA cons, as the actual benefits may vary based on your income levels and participation in employer-sponsored pension plans. Many families might not realize that the ability to deduct contributions starts to phase out at modified adjusted gross incomes (MAGI) of $240,000 or more for those not covered by a workplace retirement plan. This lack of awareness about traditional IRA cons can lead to unexpected tax obligations, making it crucial for households to thoroughly evaluate their financial situations.
Imagine if you could navigate this complex landscape with ease. Collaborating with a caring financial planner, like those at Bright Advisers, can be essential in optimizing your tax advantages and making informed choices about your IRA contributions. Bright Advisers is dedicated to helping families understand how income levels influence their eligibility for tax deductions, guiding you through the intricacies of financial preparation with compassion and clarity.
It’s important to understand that the Taxpayer Advocate Service emphasizes, “TAS strives to protect taxpayer rights and ensure the IRS is administering the tax law in a fair and equitable way.” This highlights the importance of being informed about tax laws and how they affect your family. Moreover, households should be aware that they can recharacterize contributions between different types of IRAs, providing greater flexibility in managing retirement savings.
By utilizing customized wealth management strategies, families can enhance their economic stability and independence. Together, we can navigate this journey, ensuring your financial future aligns with your family values and goals. We’re here for you, ready to support your efforts in achieving financial peace of mind.
Complex Management: The Challenges of Overseeing a Traditional IRA
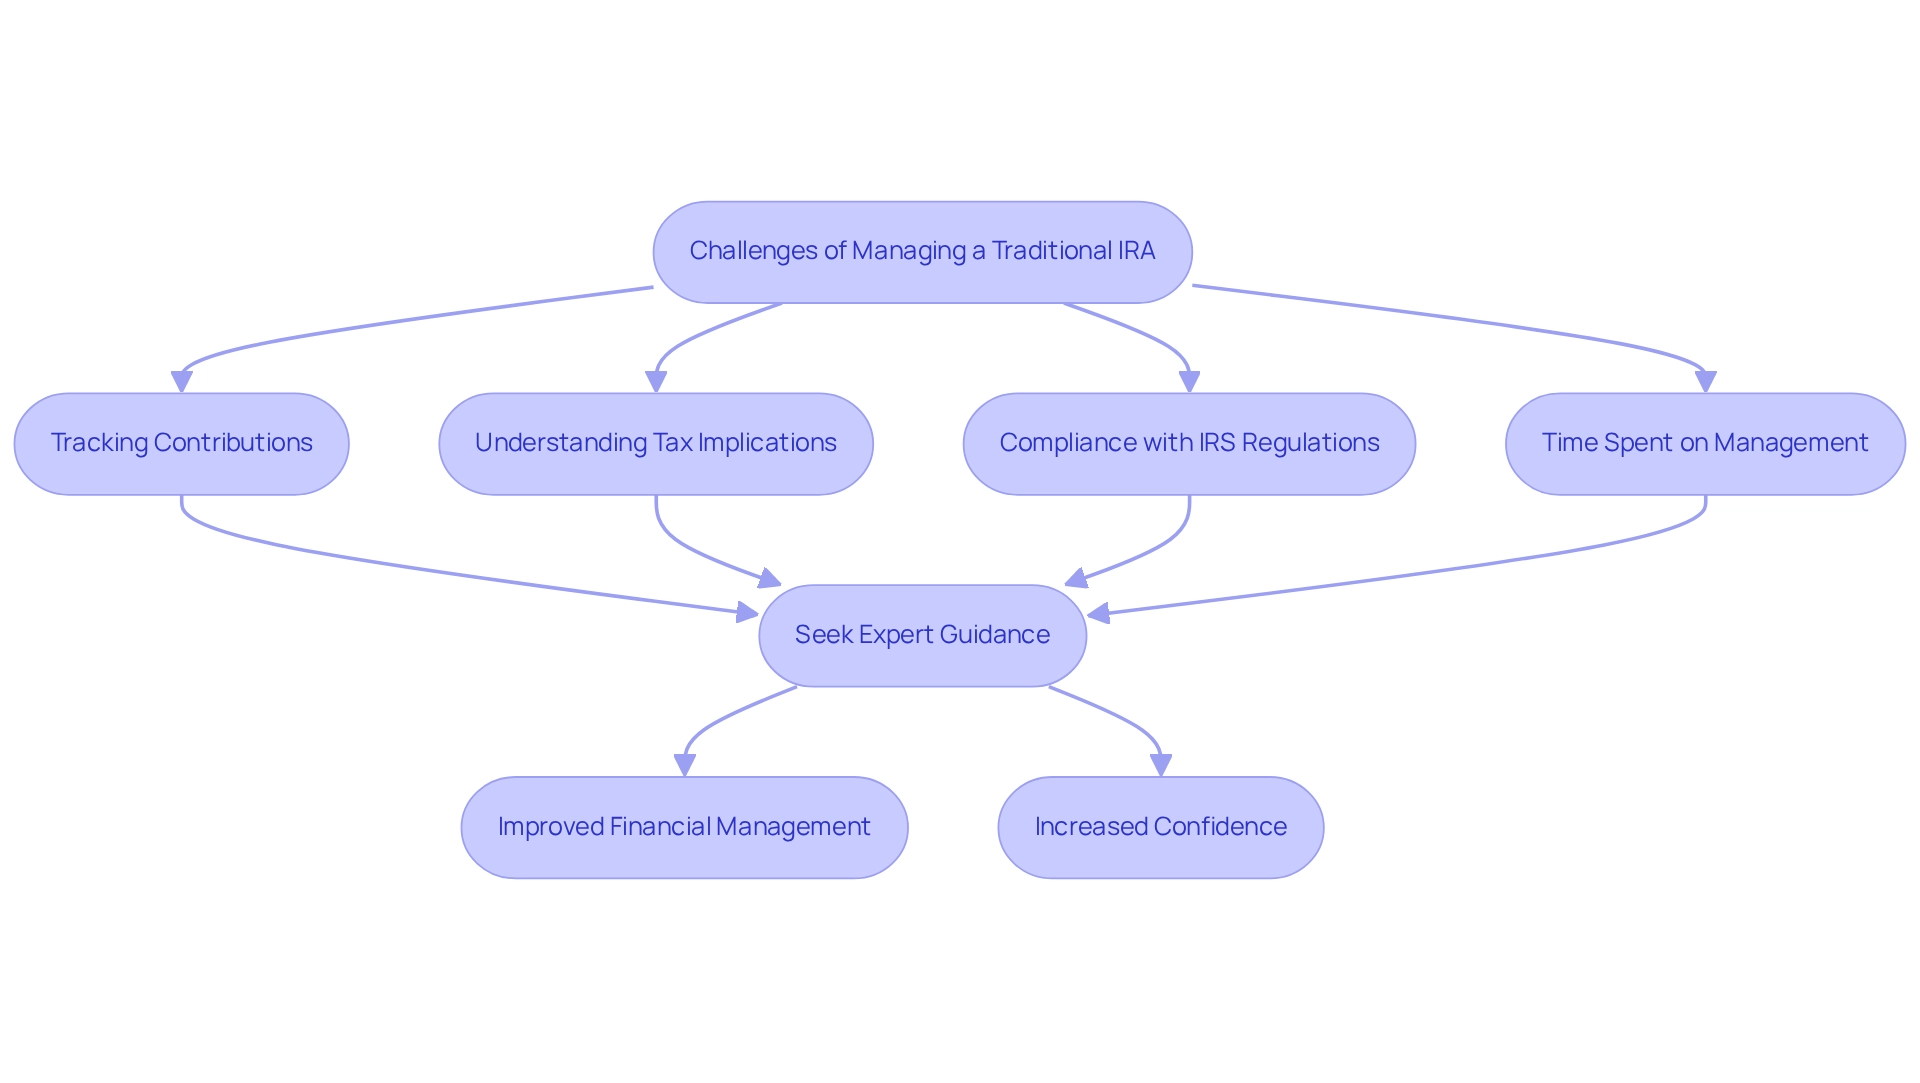
Handling a Traditional IRA can feel overwhelming for families, especially when considering the traditional IRA cons, particularly for those with limited financial knowledge. The complexities of tracking contributions, understanding tax implications, and ensuring compliance with IRS regulations can be daunting. Imagine this: only 5% of households led by individuals under 59 withdrew from their Traditional IRAs in mid-2024. This hesitance to engage with these accounts may stem from the intricate details involved, which can hinder effective resource management for young families.
Many young parents find themselves spending several hours each month just to keep their savings accounts in order. This time could be better spent with their children or managing other important responsibilities. Managing a Traditional IRA can present traditional IRA cons that often necessitate expert guidance. At Bright Advisers, we understand the unique challenges faced by families like Emily and Mark, who turned to us for help with their financial planning. Our onboarding process is designed to provide personalized support, ensuring that accounts are compliant and strategically aligned with long-term financial goals.
Families who partner with us often express a newfound confidence in their financial choices and see improved outcomes in their retirement planning. Financial experts highlight the importance of this kind of support. They frequently note that the complexities of IRA management can overwhelm even the most diligent individuals, making it essential to have a knowledgeable ally by your side.
As Emily and Mark discovered, responsible money management is vital for families, especially when considering how debt can impact their financial future. It’s also crucial to remember that wealth is relative; managing a Traditional IRA involves understanding the traditional IRA cons alongside aligning it with broader financial goals and values. In today’s world, where financial literacy is more important than ever, seeking professional assistance can truly transform the financial landscape for families striving to secure their future. Together, we can navigate this journey.
Income Limits: Understanding Eligibility Criteria for Traditional IRAs
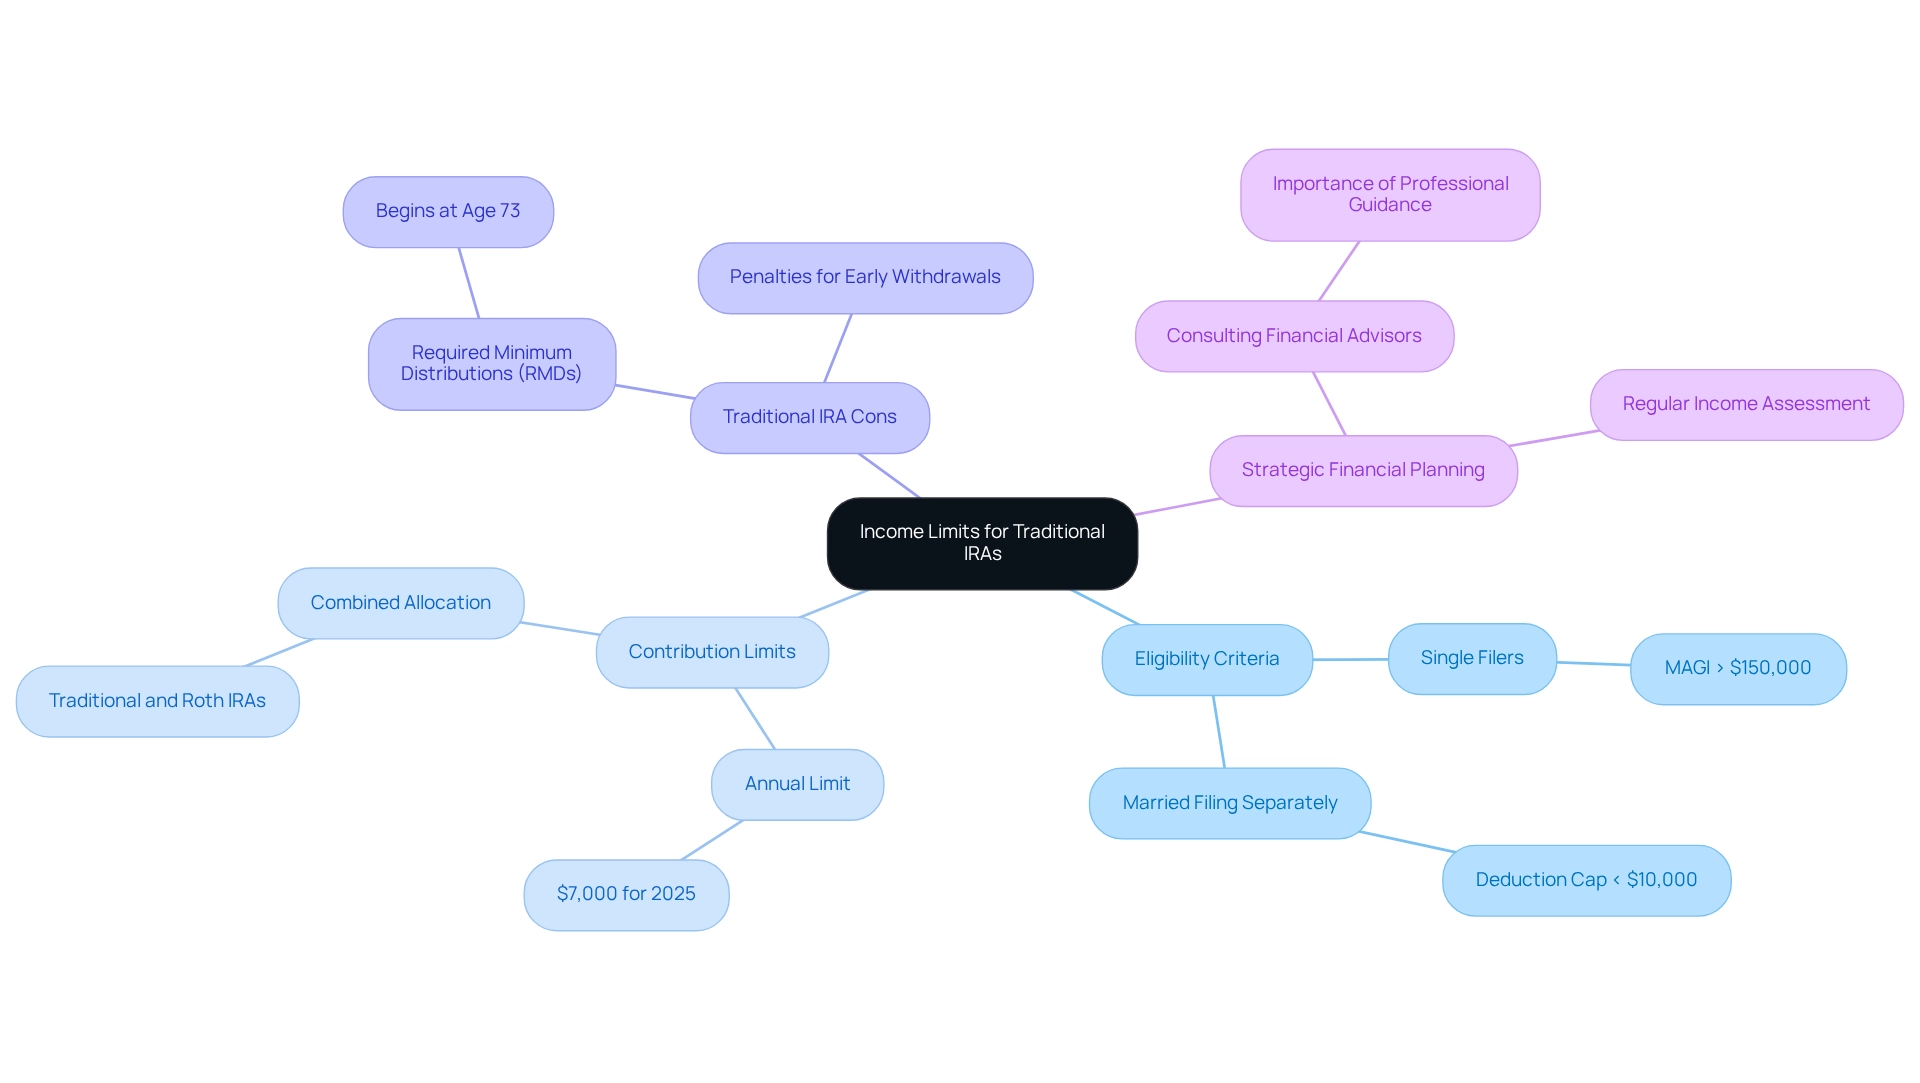
Contributing to a Traditional IRA is something that anyone with earned income can do, but the ability to deduct those contributions depends on income levels. Imagine this: in 2025, single filers with a modified adjusted gross income (MAGI) exceeding $150,000 will face limitations on their deduction eligibility. For married individuals filing separately, the deduction cap is set at under $10,000 if either partner is included in a workplace pension plan. Understanding these thresholds is crucial for families looking to strategically plan their contributions and minimize potential tax implications.
The regular contribution limit for both Traditional and Roth IRAs remains steady at $7,000 for 2025. This means individuals can allocate their contributions across both types of accounts without exceeding this maximum. This consistency in contribution limits provides families with a reliable framework for retirement savings, even as income scenarios change. As highlighted in the case study titled ‘2025 IRA Contribution Limits Hold Steady,’ this stability is essential for effective resource management.
While Traditional IRAs provide tax-deferred growth and possible tax deductions, individuals should be aware of the traditional IRA cons that may arise. Required minimum distributions (RMDs) begin at age 73, and there are penalties for early withdrawals. These factors can influence long-term financial strategies, especially for young families eager to enhance their savings for the future.
As families navigate these income limits, it’s vital to understand how MAGI affects deduction eligibility. Tax advisors often stress that being aware of these criteria can help families optimize their retirement savings strategies. At Bright Advisers, we understand the complexities of financial organization, and we are committed to empowering young families with personalized wealth management options and educational resources. Brian Baker, CFA, emphasizes the importance of grasping complex financial topics, stating, “Helping individuals understand intricate economic subjects is key for better preparation for their financial futures.” For instance, families may need to explore different financial approaches if they find themselves near the income limits, ensuring they continue to benefit from tax-advantaged savings accounts.
Additionally, the IRS Notice 2024-80 provides detailed insights on retirement-related cost-of-living adjustments for 2025, which is important for families to consider during their planning.
In conclusion, the traditional IRA cons, such as the impact of income restrictions on contributions, are significant for young families, as it directly affects their savings potential for the future. By staying informed about these limits and planning accordingly, families can make more effective financial choices that align with their long-term goals. A practical approach would be to regularly assess income levels and consult with a Bright Advisers advisor to explore the best strategies for maximizing contribution levels. Together, we can navigate this journey towards a secure financial future.
Contribution Penalties: Avoiding Fees for Exceeding Traditional IRA Limits
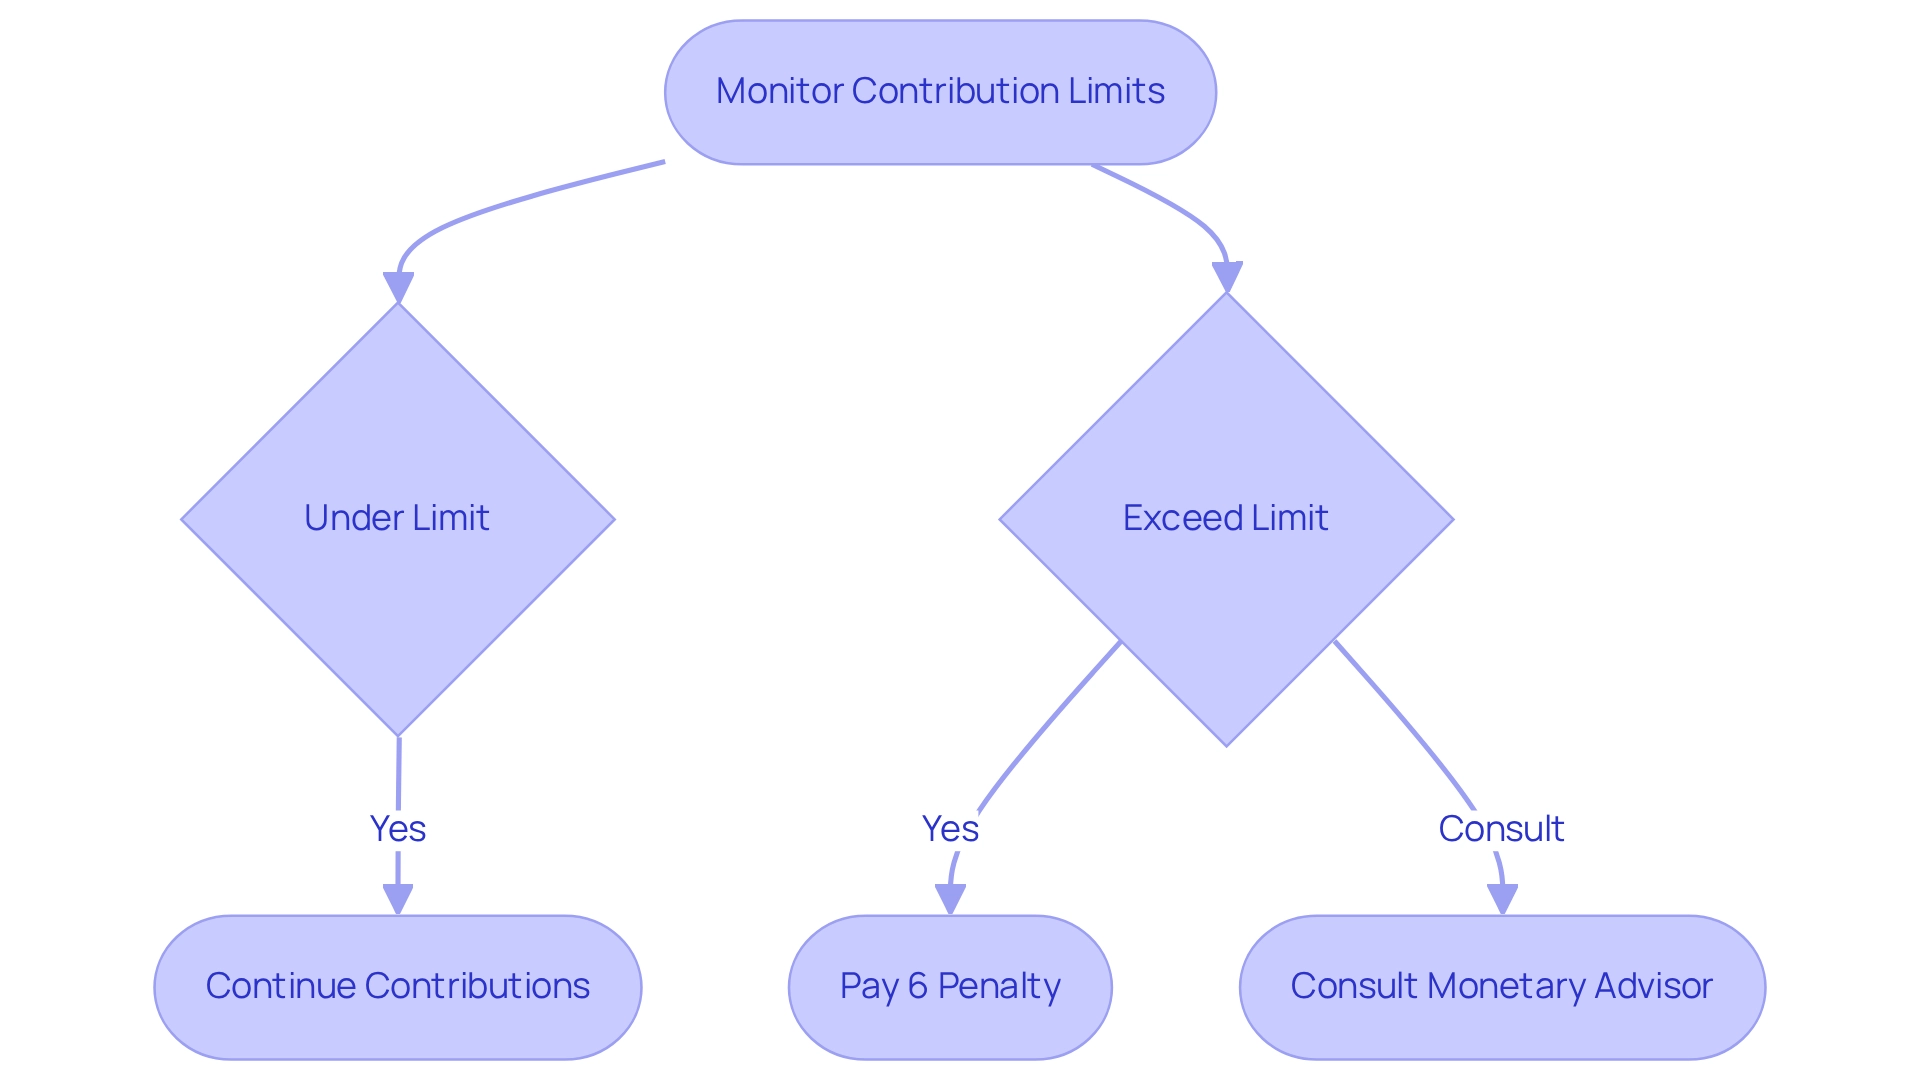
Exceeding the contribution limits for a Traditional IRA can lead to a significant 6% excise tax on the excess amount for each year it remains in the account. For 2023, the contribution limit is $6,500 for individuals under 50 and $7,500 for those 50 and older. This penalty can significantly reduce retirement savings, highlighting some traditional IRA cons. It’s essential for households to diligently monitor their contributions to avoid such pitfalls.
Imagine if you could navigate these constraints with ease. Collaborating with a monetary consultant, like those at Bright Advisers, can provide the essential direction your family needs. They help ensure you optimize your contributions while steering clear of excessive charges. Bright Advisers is dedicated to empowering young households through customized wealth management strategies and educational materials.
Keeping accurate records and frequently assessing contribution levels is vital to avoid penalties. Families who proactively monitor the traditional IRA cons regarding their contributions can foster a more secure economic future. Statistics indicate that roughly 30% of households face penalties, highlighting some traditional IRA cons due to a lack of awareness. This underscores the value of professional advice in managing retirement accounts.
As Benjamin Franklin wisely noted, ‘An investment in knowledge pays the best interest.’ This highlights the significance of education in monetary management. By prioritizing education and clarity in money management, families can safeguard their investments and enhance their long-term wealth. Remember, we’re here for you—together, we can navigate this journey.
Long-Term Commitment: Assessing the Implications of Traditional IRA Investments
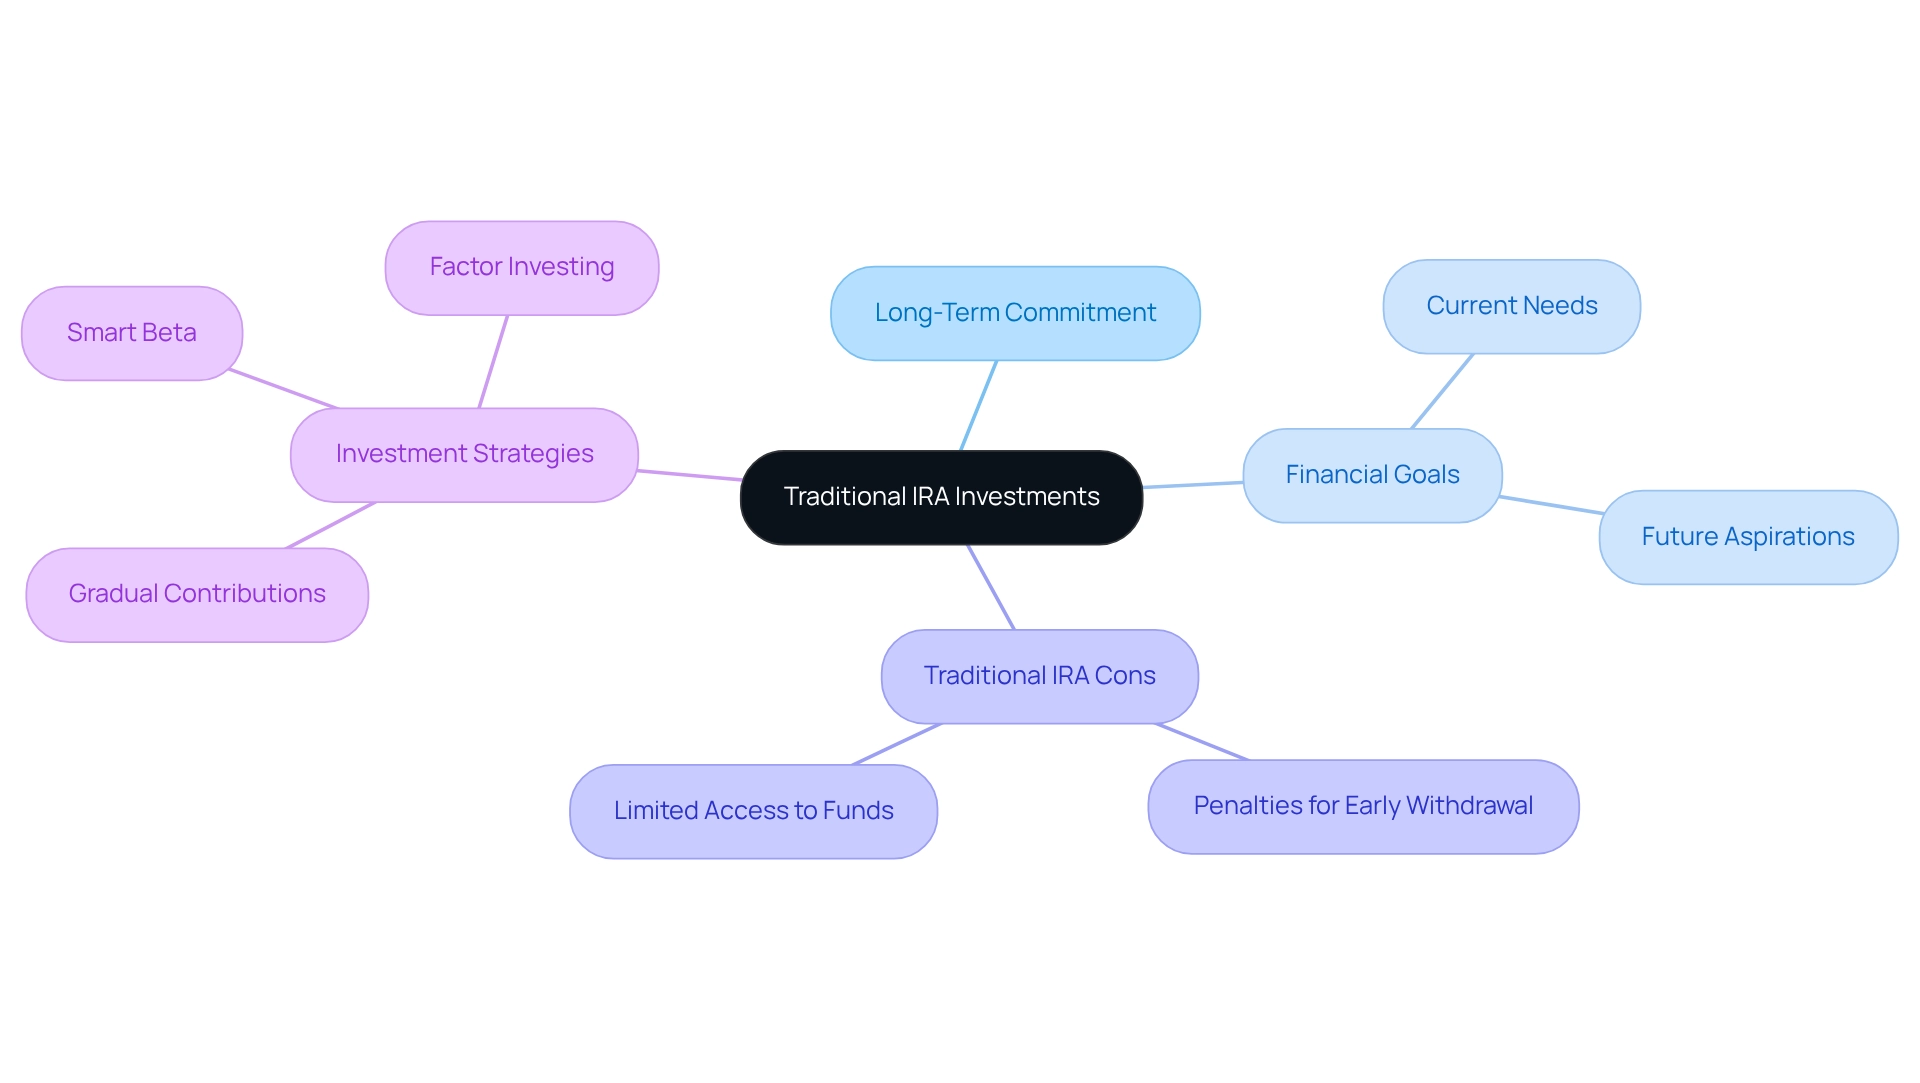
Investing in a Traditional IRA is a journey that requires a long-term commitment, as these funds are specifically designated for your later years. Imagine a family like Emily and Mark, navigating challenging careers while striving for economic stability. They must thoughtfully evaluate their monetary goals and timelines when contributing to these accounts. It’s important to consider the traditional IRA cons, particularly the limitations on accessing funds without incurring penalties until reaching retirement age, as this can greatly influence financial planning. Therefore, families should perform a comprehensive assessment of their overall financial circumstances to ensure that their savings plan aligns with both current needs and future aspirations.
Statistics remind us that investments may be worth more or less than their original cost when sold. This highlights the importance of a steady, informed approach to contributions. As Benjamin Graham wisely noted, distinguishing between investors and speculators is vital. Households should adopt an investor mindset, focusing on consistent, long-term gains rather than high-risk, short-term trading. This perspective not only fosters stable wealth accumulation but also helps mitigate exposure to market volatility.
Financial advisors often emphasize the importance of balancing retirement savings with present household responsibilities. For example, young families might explore strategies that allow for gradual contributions to their Traditional IRA, keeping in mind the traditional IRA cons while also addressing pressing financial needs, such as education costs or housing expenses. By collaborating with Bright Advisers, families can access customized planning solutions, including innovative investment approaches like smart beta and factor investing, that alleviate anxiety and ensure a brighter future. We encourage novices to start investing with manageable amounts, allowing them to balance their future savings with current obligations. By assessing their monetary objectives and the average length of investments, families can make informed choices that consider the traditional IRA cons, supporting both their present and future economic well-being.
As Mike Shamrell, Vice President of Thought Leadership at Fidelity, aptly puts it, “Saving for retirement is a marathon, not a sprint.” To take the first step towards financial freedom, we encourage families to consult with a financial advisor to create a personalized plan that aligns with their unique circumstances. Together, we can navigate this journey towards a secure and fulfilling future.
Conclusion
Navigating the complexities of Traditional IRAs is essential for young families aiming to secure their financial future. Imagine the unique challenges and opportunities that families face when planning for retirement, particularly through the lens of Traditional IRAs. Understanding the contribution limits, potential tax benefits, and the implications of early withdrawals empowers parents to make informed decisions that align with their long-term financial goals.
It’s important to understand that seeking professional guidance can make a significant difference. Financial advisors play a critical role in helping families maximize their retirement savings while minimizing penalties and tax liabilities. Engaging with experts like Bright Advisers ensures that families not only comply with regulations but also tailor their financial strategies to meet their specific needs and values.
In conclusion, effective retirement planning for young families involves a proactive approach to understanding Traditional IRAs and the associated rules. By leveraging personalized financial strategies, families can build a robust foundation for their children’s future while preparing for a secure retirement. Together, we can navigate this journey, and prioritizing financial education and expert advice is a crucial step towards achieving long-term financial stability and peace of mind.
Frequently Asked Questions
What challenges do families with young children face regarding financial planning?
Families with young children face unique challenges in financial planning, including navigating the complexities of saving for their future while considering the potential drawbacks of traditional IRAs.
What are some cons of traditional IRAs?
One significant con of traditional IRAs is the 10% penalty on early withdrawals made before age 59½, which can lead to substantial financial setbacks for families needing immediate funds.
How can Bright Advisers assist families with financial planning?
Bright Advisers offers a personalized approach to financial planning that addresses the challenges faced by families, providing guidance on saving strategies, tax optimization, and education funding to empower families toward economic independence.
What is the importance of flexibility in managing investment accounts?
Flexibility is crucial for managing investment accounts, as it allows families to regularly review and adjust their portfolios based on evolving circumstances and financial needs.
What are the contribution limits for Traditional IRAs in 2025?
For the tax year 2025, individuals under 50 can contribute up to $7,000 to Traditional IRAs, while those aged 50 and older can contribute up to $8,000.
How can families maximize their IRA contributions?
Families can maximize their IRA contributions by fully utilizing the contribution limits and considering options like spousal IRAs, which allow a spouse without earned income to contribute, provided the couple files a joint tax return with sufficient earned income.
What advice is given regarding early withdrawals from a Traditional IRA?
It is advised to avoid early withdrawals from a Traditional IRA due to penalties and to consult with a qualified monetary advisor for guidance on managing financial emergencies without jeopardizing long-term savings.
How does Bright Advisers ensure accessibility in wealth management?
Bright Advisers emphasizes low fund fees and a client-focused approach, making wealth management more accessible and enabling families to make informed financial decisions.
List of Sources
- Bright Advisers: Personalized Financial Planning for Traditional IRAs
- Tax Benefits Of Traditional Iras – FasterCapital (https://fastercapital.com/topics/tax-benefits-of-traditional-iras.html)
- Case Studies – Financial Engineer (https://thefinangineer.com/category/case_studies)
- Tax Penalties: Understanding the Consequences of Early Withdrawals from Traditional IRAs
- SIMPLE IRA Early Withdrawal Penalty | Alternatives & Strategies (https://nasdaq.com/articles/simple-ira-early-withdrawal-penalty-alternatives-strategies)
- investor.vanguard.com (https://investor.vanguard.com/investor-resources-education/iras/ira-withdrawal-rules)
- merrilledge.com (https://merrilledge.com/article/retirement-account-withdrawal)
- Contribution Limits: Navigating the Restrictions on Traditional IRA Contributions
- 401(k) limit increases to $23,500 for 2025, IRA limit remains $7,000 | Internal Revenue Service (https://irs.gov/newsroom/401k-limit-increases-to-23500-for-2025-ira-limit-remains-7000)
- 2025 Retirement Contribution Limits (https://carsonallaria.com/2024/12/23/2025-contribution-limit)
- 2025 Roth and Traditional IRA Contribution Limits (https://investopedia.com/retirement/ira-contribution-limits)
- 2025 IRA Contribution And Income Limits: What Retirement Savers Need To Know | Bankrate (https://bankrate.com/retirement/401k-ira-contribution-and-income-limits)
- Required Minimum Distributions: Planning for Mandatory Withdrawals from Traditional IRAs
- Required Minimum Retirement RMD Distributions by Plan Type (https://efile.com/retirement-plan-required-minimum-distribution-ira-401k)
- The impact of withdrawal penalties on retirement savings (https://sciencedirect.com/science/article/pii/S0047272724000197)
- kiplinger.com (https://kiplinger.com/retirement/retirement-plans/required-minimum-distributions-rmds/602350/rmd-basics-12-things-you)
- 7 Quotes from Warren Buffett on How Retirees Should “Invest” in What Matters the Most (https://keenwealthadvisors.com/insights/7-quotes-from-warren-buffett-on-how-retirees-should-invest-in-what-matters-the-most)
- Limited Investment Options: Exploring the Constraints of Traditional IRAs
- Roth IRA vs. Traditional IRA: Rules & Tax Benefits | Vanguard (https://investor.vanguard.com/investor-resources-education/iras/roth-vs-traditional-ira)
- Retirement Account Statistics 2024 – NerdWallet (https://nerdwallet.com/article/investing/retirement-statistics)
- Recent IRA Statistics – Greenleaf Trust (https://greenleaftrust.com/missives/recent-ira-statistics)
- Misleading Tax Deductions: Evaluating the True Benefits of Traditional IRA Contributions
- irs.gov (https://irs.gov/publications/p590a)
- Complex Management: The Challenges of Overseeing a Traditional IRA
- IRA Use Has Risen 10% Over Past Decade, ICI Study Finds (https://401kspecialistmag.com/ira-use-up-10-in-past-decade-study)
- Top 50 Financial Planning Quotes [2025] (https://digitaldefynd.com/IQ/financial-planning-quotes)
- Quotes from famous people on financial planning & investment (https://serrarigroup.com/quotes-from-famous-people-on-financial-planning-investment)
- Income Limits: Understanding Eligibility Criteria for Traditional IRAs
- 2025 Roth and Traditional IRA Contribution Limits (https://investopedia.com/retirement/ira-contribution-limits)
- IRS Unveils Increased 2025 IRA Contribution Limits (https://theentrustgroup.com/blog/ira-contribution-limits)
- 2025 IRA Contribution And Income Limits: What Retirement Savers Need To Know | Bankrate (https://bankrate.com/retirement/401k-ira-contribution-and-income-limits)
- Contribution Penalties: Avoiding Fees for Exceeding Traditional IRA Limits
- Individual Retirement Account (IRA) Ownership: Data and Policy Issues (https://congress.gov/crs-product/R46635)
- 77 Financial Advisor Quotes to Send to Clients (https://billgoodmarketing.com/resources/financial-advisor-quotes)
- 13 Quotes to Help Plan for Retirement | The Motley Fool (https://fool.com/retirement/2020/06/25/13-quotes-to-help-plan-for-retirement.aspx)
- Long-Term Commitment: Assessing the Implications of Traditional IRA Investments
- The Top 25 Investing Quotes of All Time (https://investopedia.com/financial-edge/0511/the-top-17-investing-quotes-of-all-time.aspx)
- Eight Great Investing Quotes (https://texasfa.com/Eight-Great-Investing-Quotes.c10271.htm)
- 10 Great Investing Quotes to Consider (https://smartasset.com/investing/top-10-investing-quotes-of-all-time)
- Average retirement savings by age | Fidelity (https://fidelity.com/learning-center/personal-finance/average-retirement-savings)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Retirement & Employee Benefits for high-income W-2 families at Bright Advisers.
Keep reading