

Overview
Navigating the world of life insurance can feel overwhelming, especially for young parents. Imagine if you could access cash from your life insurance policy when you need it most. This article explores various methods for withdrawing cash from permanent life insurance policies, such as whole and universal life insurance, which build cash value over time.
It’s important to understand that options like partial withdrawals, loans, and policy surrender can offer financial relief during challenging times. However, these choices may also reduce the death benefit and come with tax implications. That’s why it’s essential for policyholders to carefully review their policy terms.
By consulting with financial advisors, you can align these decisions with your family’s long-term goals. We’re here for you, ready to help you navigate this journey. Together, we can ensure that your financial choices support the future you envision for your loved ones.
Key Highlights:
- Permanent life insurance policies, such as whole and universal life, accumulate cash value that can be accessed through withdrawals.
- Withdrawals up to the total premiums paid are generally tax-free, but any excess may incur income tax, impacting budgeting.
- Withdrawals can reduce the death benefit, potentially leaving beneficiaries with less financial support.
- Families should consider alternatives to withdrawals, such as policy loans or partial surrenders, to maintain coverage while accessing cash.
- Consulting with financial advisors is crucial for understanding the implications of withdrawals and aligning them with long-term financial goals.
- Term life insurance does not build cash value, making it less flexible than permanent options for accessing funds.
- Real-life examples illustrate how families have successfully navigated financial needs through strategic use of life insurance cash value.
Introduction
In the world of financial planning, life insurance is often seen simply as a safety net for loved ones after one’s passing. Yet, many policyholders may not realize the potential of accessing the cash value accumulated in permanent life insurance policies, such as whole or universal life. Imagine if you could leverage these funds to address immediate financial needs while still protecting your family’s long-term security. This article explores the intricacies of life insurance withdrawals, helping families understand how to navigate these options.
It’s important to grasp the implications of withdrawals on death benefits and consider alternatives like policy loans and life settlements. The insights shared aim to empower families in making informed decisions that align with their values and priorities. With expert guidance from Bright Advisers, we’re here for you, ensuring your financial strategies reflect both your current circumstances and your future aspirations. Together, we can navigate this journey, providing the support you need to secure your family’s financial future.
Bright Advisers: Personalized Financial Planning for Life Insurance Withdrawals
When considering your options, you may wonder, can you withdraw life insurance money from a coverage plan to access the cash value that has built up in your permanent plans, like whole or universal life insurance? Unlike term life insurance, which doesn’t accumulate cash value, these permanent plans grow over time, providing a helpful resource for you. Generally, you can make withdrawals without incurring taxes, up to the total amount of premiums you’ve contributed to the contract. However, it’s important to understand that these withdrawals may reduce the plan’s death benefit and overall value. Many contract holders take advantage of this option, often looking to use their cash value for various financial needs. Recent data shows that early withdrawals from protection policies can incur fees, so it’s essential to know the terms of your agreements before moving forward.
At Bright Advisers, we recognize the complexities of financial planning, and our innovative wealth management platform is here to support you in navigating the process of protection withdrawals. Imagine families like Emily and Mark, who are striving to secure their financial legacy while addressing pressing economic needs. Expert insights highlight the advantages of accessing cash value, especially for passing wealth on to children or grandchildren. Permanent coverage can serve as a strategic resource for families who wish to safeguard their financial legacy. Real-life stories illustrate how policyholders have successfully accessed funds to meet urgent financial requirements while staying aligned with their long-term goals, which raises the question, can you withdraw life insurance money? In conclusion, understanding how to retrieve cash value in these plans is vital for you. By being aware of the implications of withdrawals, you can make informed financial decisions that align with your overall wealth management strategies. Remember, we’re here for you, and together, we can navigate this journey.
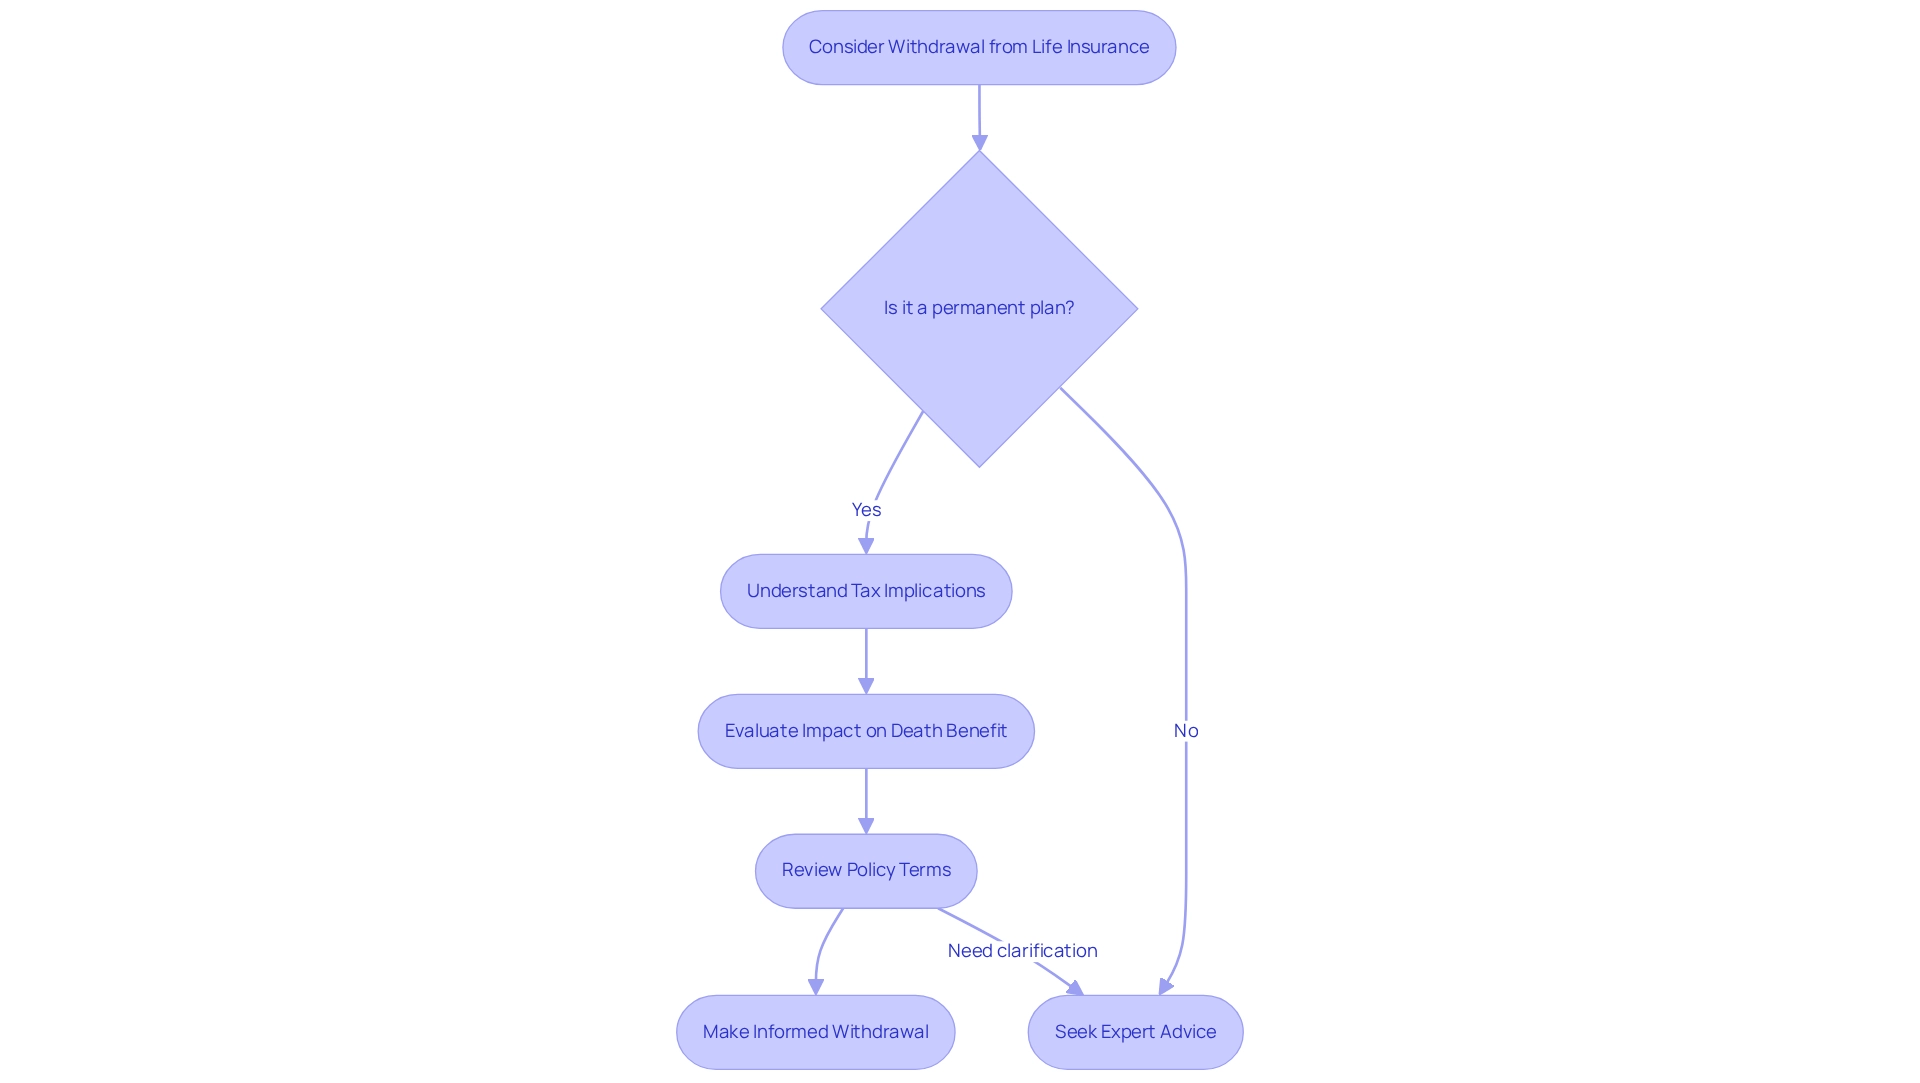
Whole Life Insurance: Understanding Cash Value and Withdrawal Options
Pulling out of a coverage plan can be a crucial financial strategy for families, especially young households like Emily and Mark, who are navigating unexpected expenses while striving for economic independence. Accessing cash value can provide essential funds for emergencies, educational costs, or other significant financial needs, effectively serving as a safety net. This flexibility is vital, particularly since about 60% of households face at least one financial crisis each year, underscoring the importance of having accessible resources.
Term coverage typically offers protection for 1, 10, 20, or 30 years, allowing families to choose a plan that aligns with their financial goals and milestones. Understanding the implications of whether you can withdraw life insurance money is equally important, as it can affect the policy’s death benefit, which is essential for ensuring the financial future of beneficiaries. For instance, through their partnership with Bright Advisers, Emily and Mark learned how to strategically utilize insurance withdrawals to manage unexpected medical expenses, allowing them to maintain their stability without compromising their long-term security. This approach not only alleviated immediate financial pressure but also reinforced their commitment to safeguarding their loved ones.
Bright Advisers employs innovative investment strategies and advanced technology to enhance financial planning, empowering families to optimize their resources effectively. As suggested by the Unbiased Editorial Team, when deciding on the duration of your coverage, consider the milestones in your child’s journey, such as their education or when they are expected to achieve financial independence. Ultimately, when considering financial protection plans, many wonder, can you withdraw life insurance money, which enables families to manage their finances more effectively and prioritize what truly matters—their loved ones. By contemplating the long-term effects and aligning withdrawals with their financial objectives, young families can leverage protection as a foundational element of their planning, just like Emily and Mark did with the guidance of Bright Advisers.
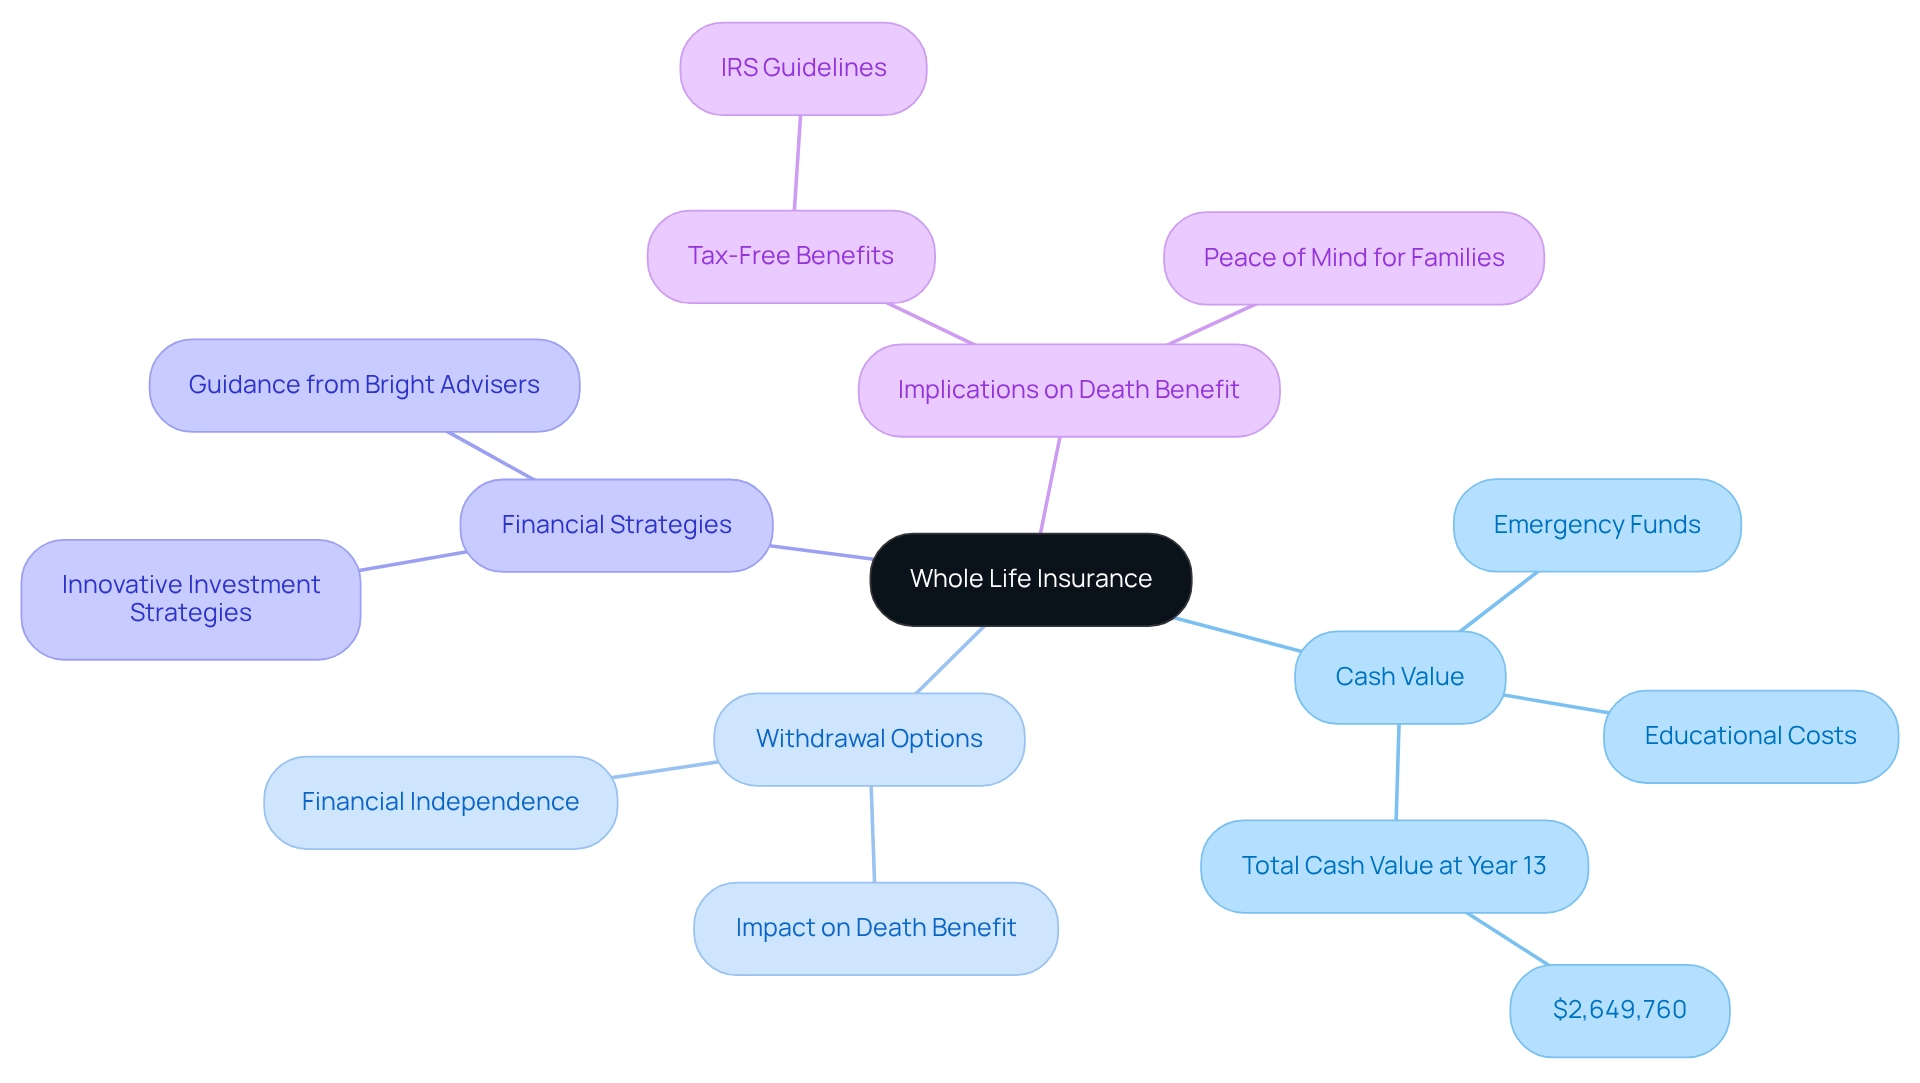
Surrendering Your Policy: How to Access Cash from Life Insurance
Navigating financial choices can be overwhelming, especially for young families like Emily and Mark who are striving to enhance their economic well-being. Fortunately, there are various efficient techniques for extracting cash from life insurance plans, and one important question is, can you withdraw life insurance money through partial withdrawals, allowing you to access a portion of your cash value without sacrificing your entire plan? This flexible option raises the question of how can you withdraw life insurance money while still retaining some level of coverage. The best part? Partial withdrawals are generally exempt from tax under certain conditions, providing a financial advantage that can ease your worries. Plus, indexed universal life insurance products can help your cash value grow without the risk of losing money, making them even more appealing.
Policy Loans: Instead of withdrawing cash directly, consider securing a loan based on your coverage’s cash value. This option often comes with lower interest rates compared to traditional loans, making it an attractive choice for families. While repayment isn’t mandatory, it’s crucial to remember that any unpaid loans will reduce the death benefit, which can impact your loved ones.
Surrendering the Contract: Sometimes, you may need immediate access to cash. Surrendering the contract allows you to cash out the entire agreement, but it’s important to note that this terminates your coverage. While it provides quick cash, it raises the question, can you withdraw life insurance money, as it eliminates the death benefit and may incur surrender charges, which can significantly affect your beneficiaries. In times of economic difficulty, certain plans allow you to use your cash value to cover premium dues. This option can be especially beneficial, ensuring that your policy remains active while alleviating immediate financial pressures.
Understanding these methods is vital for young families who want to make informed financial choices. At Bright Advisers, we emphasize minimal fund charges and innovative wealth management techniques, ready to assist families in navigating their economic futures. By carefully evaluating the benefits and drawbacks of each approach, you can align your choices with your financial objectives, creating a solid foundation for your family’s future. Remember, we’re here for you, and together, we can navigate this journey towards financial security.
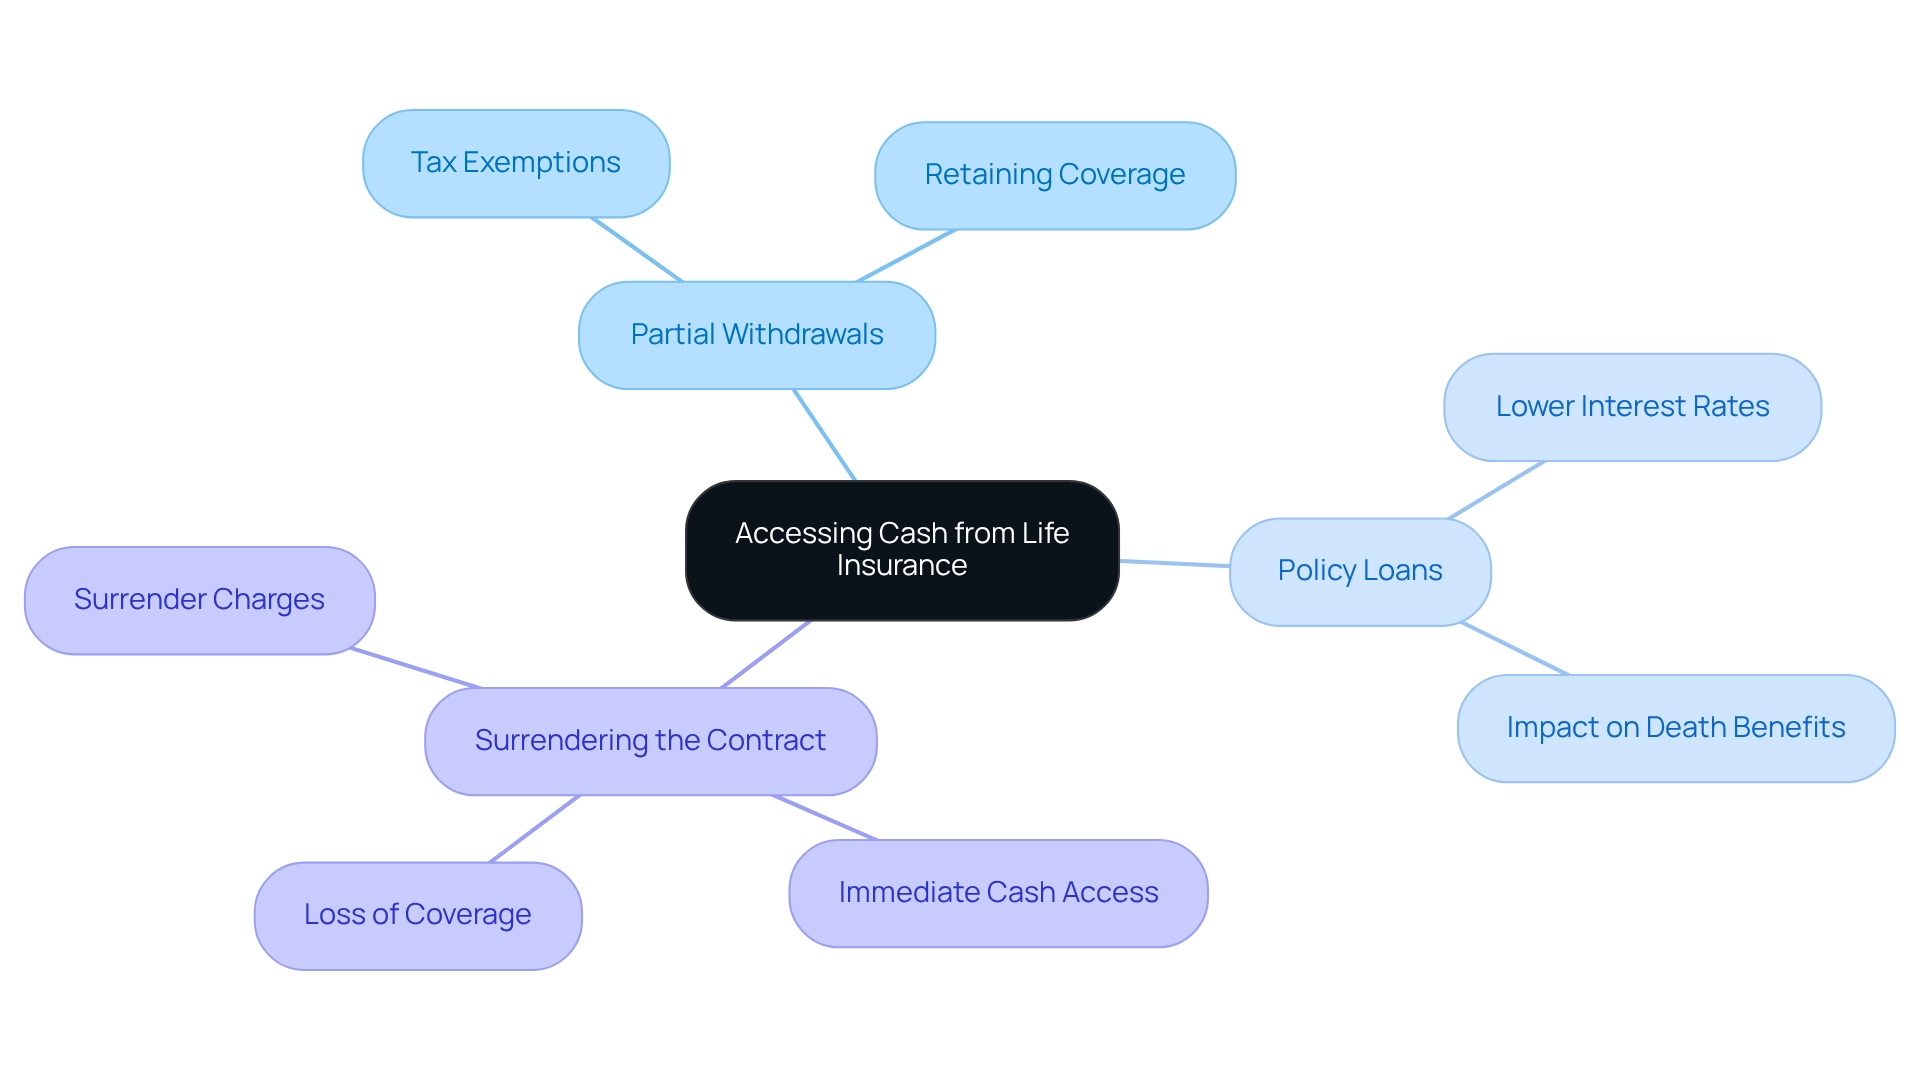
Borrowing Against Your Policy: Pros and Cons of Life Insurance Loans
Withdrawing cash from a life insurance policy can provide immediate financial relief, but it’s essential to consider the significant consequences involved:
- Reduction in Death Benefit: Any amount withdrawn directly reduces the policy’s death benefit, potentially leaving your loved ones with less financial support when they need it most. This concern is heightened by the fact that the average unclaimed life insurance benefit is around $2,000, while other payouts can reach up to $300,000. Understanding how withdrawals can diminish these benefits is crucial for families.
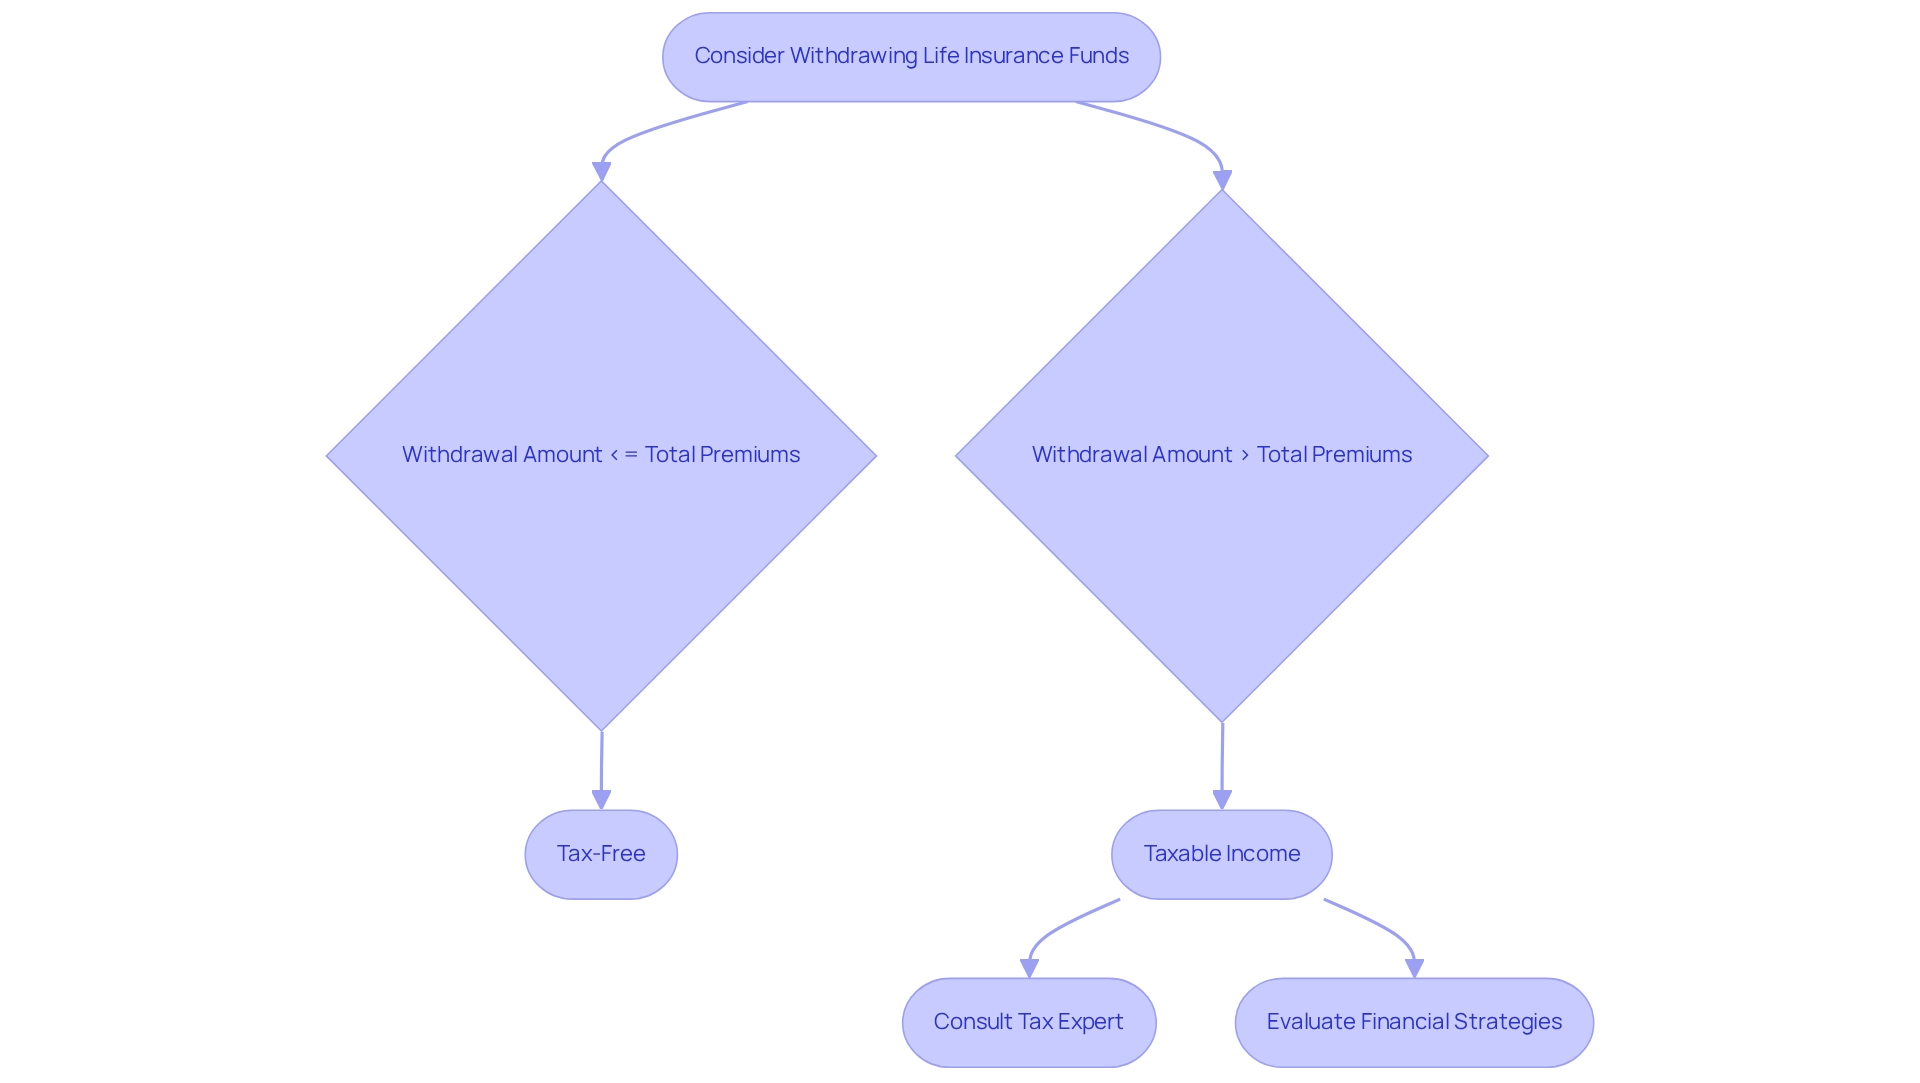
- Tax Implications: Withdrawals up to the total amount of premiums paid are typically tax-free. However, any gains exceeding this amount may incur income tax, leading to unexpected tax obligations that could affect your overall budgeting.
- Coverage Lapse Risk: Excessive withdrawals can jeopardize the plan’s status, risking a lapse in protection. This is especially troubling for families who depend on the system for economic stability during challenging times.
- Impact on Future Premiums: Withdrawals can hinder the cash value growth of the plan and may require increased premiums to maintain the same death benefit, complicating long-term financial strategies.
Imagine the situation of Allison and Brian; they initially wondered, can you withdraw life insurance money to cover immediate expenses? However, with the guidance of Bright Advisers, they realized that such a withdrawal could significantly reduce their death benefit, affecting their children’s future economic security. Instead, they chose a comprehensive financial strategy that included tax optimization and education funding, ensuring they could meet their immediate needs without jeopardizing their long-term goals.
Financial consultants emphasize that understanding these consequences is vital for making informed choices about life coverage. It’s advisable for families to consult with a financial advisor to explore alternative options that can provide immediate relief without compromising their financial future. As stated by Coverage.com, LLC, “All coverage products are regulated by the terms in the relevant coverage agreement, and all associated decisions (such as approval for protection, premiums, commissions and fees) and agreement obligations are the exclusive responsibility of the underwriting insurer.” This highlights the importance of comprehending terms when evaluating withdrawals. Together, we can navigate this journey with care and informed decision-making.
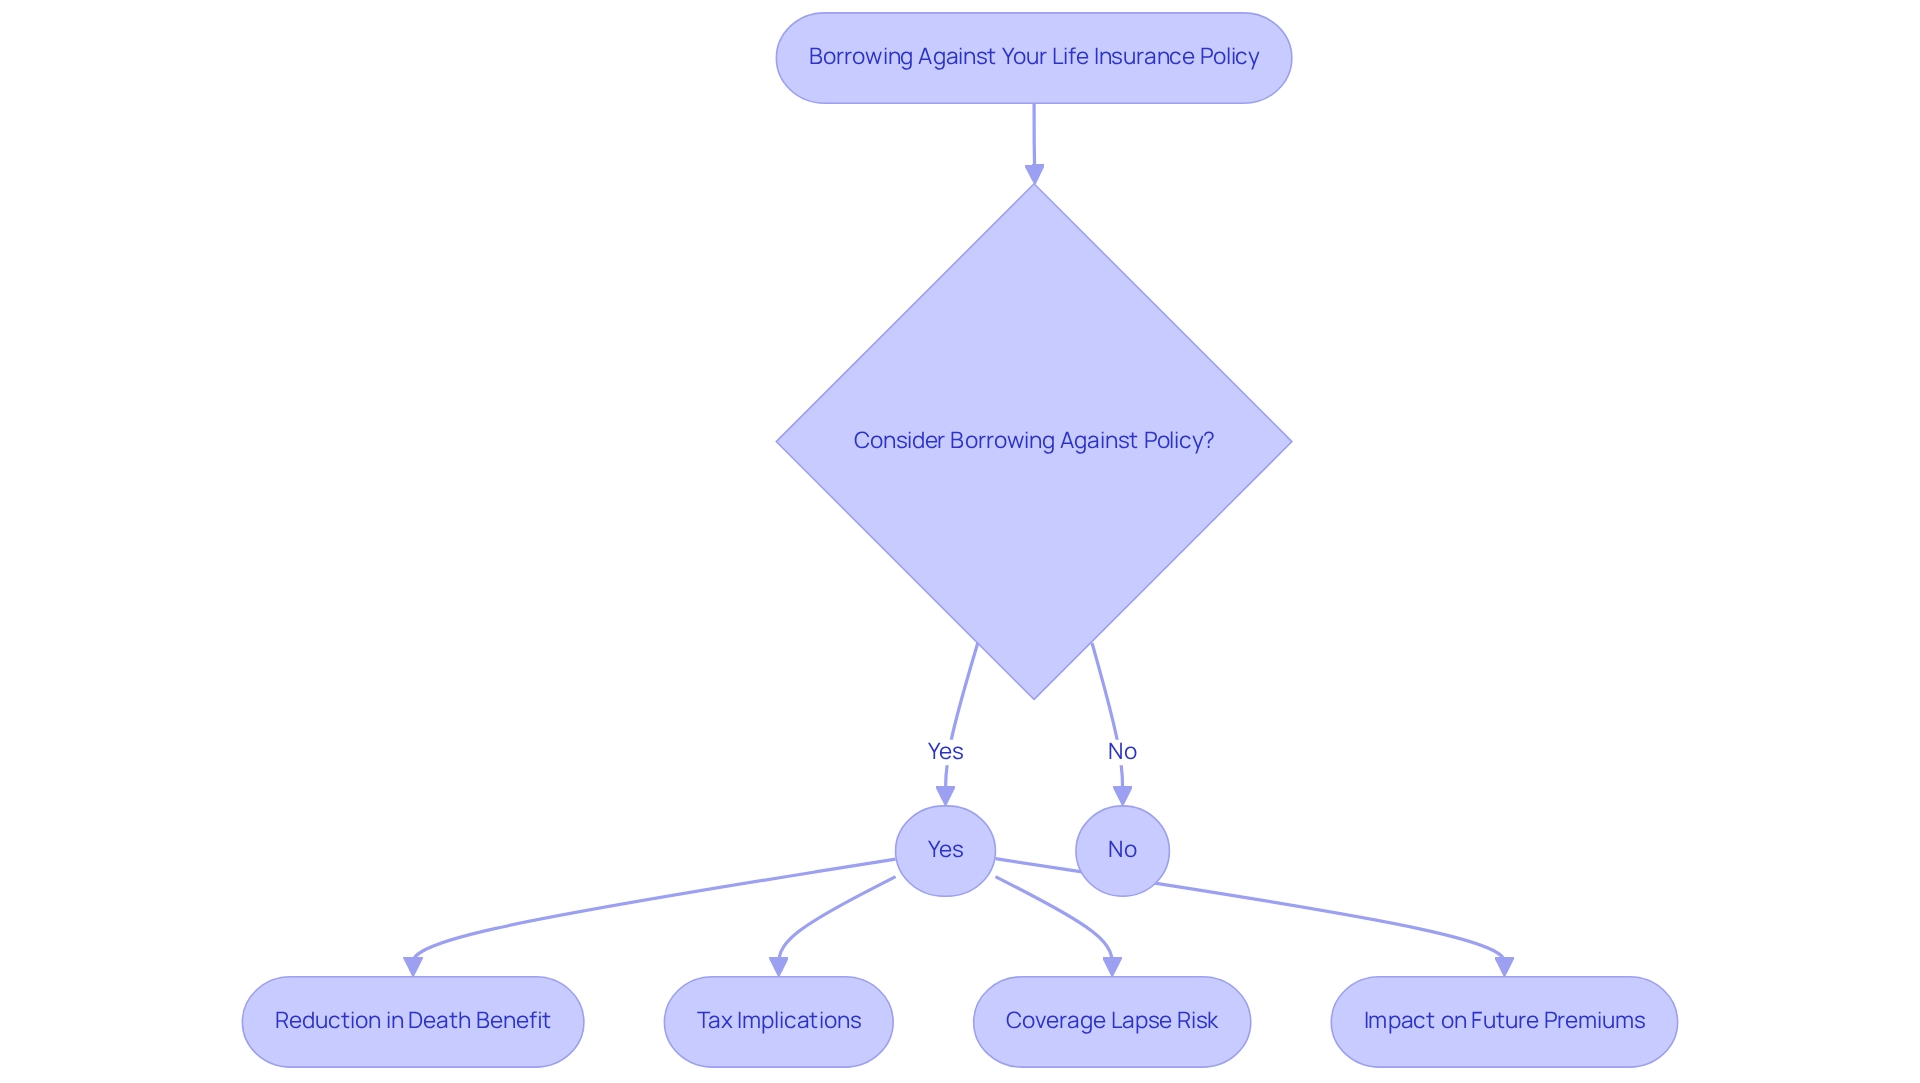
Tax Implications: What to Know Before Withdrawing Life Insurance Funds
When considering your options, can you withdraw life insurance money from a plan, knowing it can have considerable tax consequences, especially if the amount exceeds the total premiums contributed? Generally, withdrawals up to the plan’s basis—the total premiums paid—are tax-free. However, any amount exceeding this basis raises the question of can you withdraw life insurance money, which may be subject to income tax and can impact a family’s budgeting. Imagine if a family is considering, can you withdraw life insurance money, and they take out $15,000 from a plan where they have paid $10,000 in premiums; the additional $5,000 could be taxable income. It’s important to understand that families are encouraged to consult with a tax expert to navigate these complexities and ensure they are making informed decisions regarding withdrawals. Grasping the intricacies of tax obligations is essential, as giving up a policy entirely results in losing the death benefit, which can have lasting effects on financial stability.
Recent conversations in the economic community emphasize options to cashing out, such as lowering premiums or reducing the death benefit. These strategies can help preserve coverage while providing needed liquidity. Additionally, exploring options like personal loans or life settlements may offer viable solutions without incurring immediate tax liabilities.
Real-life examples illustrate the importance of beneficiary designations in life insurance taxation. Benefits paid directly to named beneficiaries typically avoid probate and are generally not taxed, while those payable to an estate may incur estate taxes if the estate exceeds exemption limits. This highlights the need for families to thoughtfully evaluate their financial strategies and the potential tax implications of their choices.
In the case of Allison and Brian, who sought guidance from Bright Advisers to enhance their economic potential through proper tax planning, they learned how to navigate these complexities effectively. By integrating tax optimization into their financial strategy, they not only ensured their children’s future through education funding but also gained the capability to retire earlier. This showcases the transformative effect of customized wealth management solutions and underscores the significance of strategic financial planning. Together, we can navigate this journey and ensure families evaluate their own financial strategies in light of these implications to make the most informed decisions.
Alternatives to Withdrawals: Exploring Other Options for Life Insurance Cash
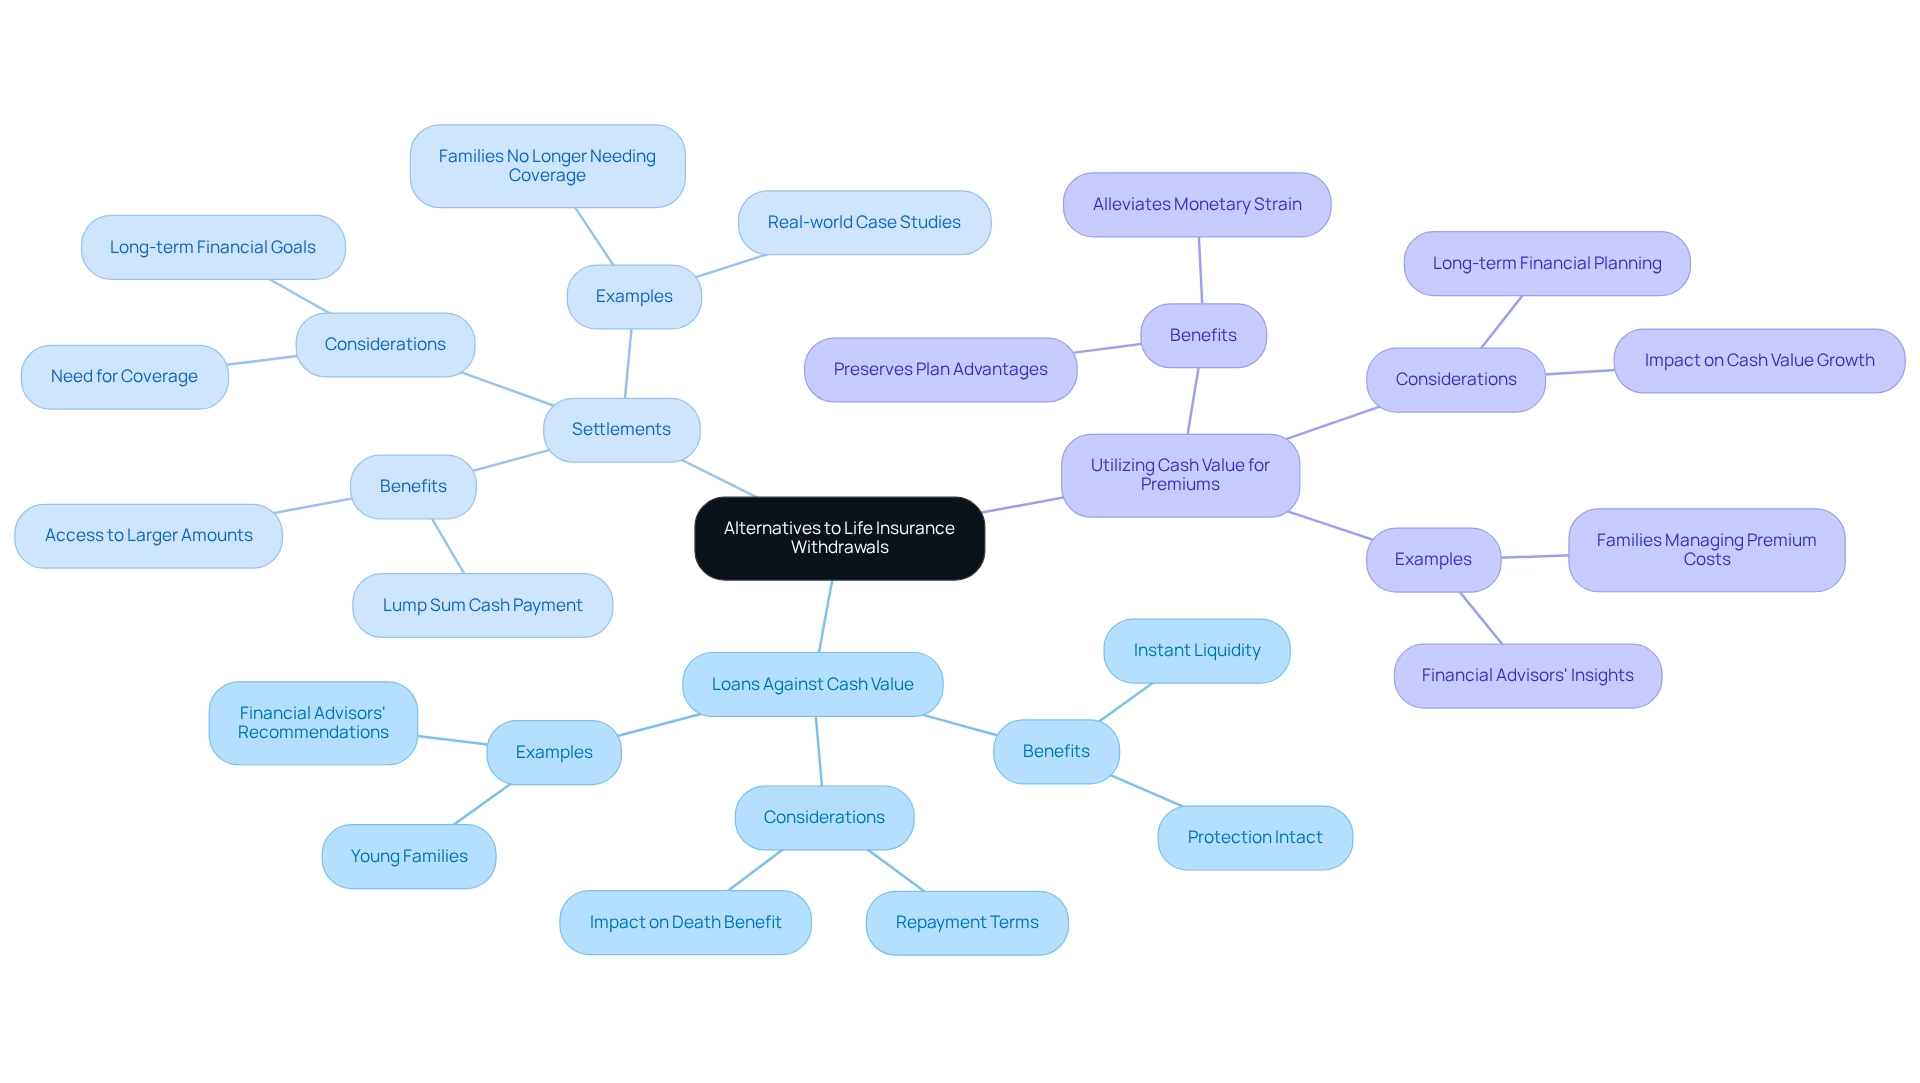
Families seeking to understand if they can withdraw life insurance money have several alternatives beyond straightforward withdrawals. One popular choice is obtaining a loan from the plan. This allows holders to borrow against the cash value of their coverage while keeping their protection intact. Imagine how beneficial this can be for young families like Jay and Emma; it offers instant liquidity without the need to relinquish the plan. This approach can help ease financial stress while still striving toward long-term goals, such as saving for retirement and fulfilling educational needs. Additionally, utilizing the cash value to cover premium costs can help preserve the plan’s advantages while alleviating monetary strain.
Another viable option is exploring settlements, where the holder sells their coverage for a lump sum cash payment. This can be particularly advantageous for families who no longer need the coverage or wish to access a larger amount of cash than what a withdrawal would provide. However, it’s important for families to thoughtfully assess the advantages and disadvantages of each choice, including considerations for whether they can withdraw life insurance money, while also considering their unique financial circumstances and long-term aspirations. Furthermore, a notable 7.3% of agreements lapsed, often due to non-payment of premiums, underscoring the necessity for financial education and support in navigating these choices.
Real-world examples show how families have effectively utilized loans against insurance or settlements to meet their financial needs. Financial advisors often recommend these alternatives as they can provide essential funds while preserving the benefits of the plan. Ultimately, families should engage in comprehensive discussions about their financial objectives and seek guidance from experts, such as Bright Advisers, to determine the most suitable approach regarding their coverage plans. Together, we can navigate this journey, safeguarding your family’s future and alleviating monetary stress.
Impact on Death Benefit: How Withdrawals Affect Your Life Insurance Policy
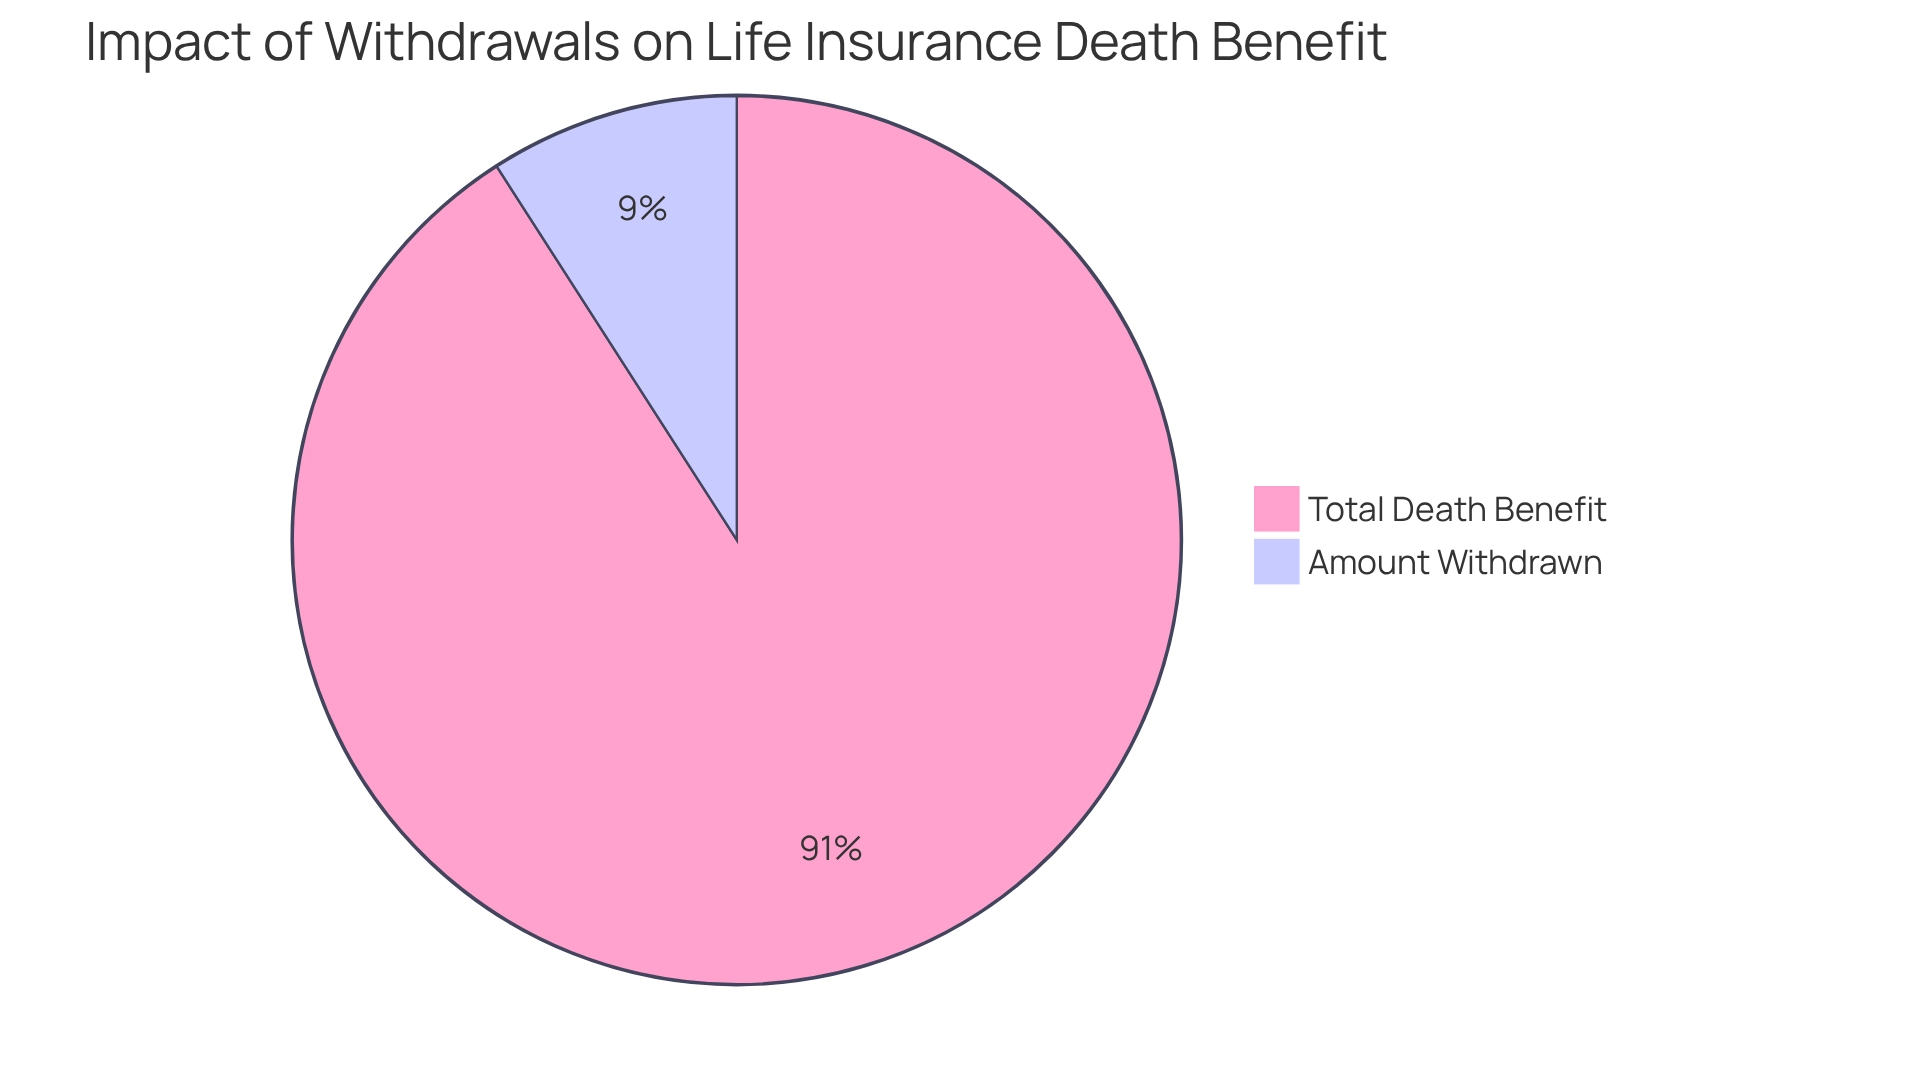
When considering your options, can you withdraw life insurance money from a plan without significantly impacting the death benefit, which could affect your loved ones’ financial security? Imagine if an insured individual takes out $10,000 from a plan that originally offers a $100,000 death benefit; the remaining benefit would drop to $90,000. This reduction can create serious challenges for families who rely on that financial support in the future. It’s often advised that you wait at least 10 to 15 years for the cash value to grow before considering withdrawals, as doing so too early can lead to substantial losses in death benefits.
Recent trends reveal a growing recognition of the value of life insurance, as evidenced by an increase in policy sales. This shift indicates that families are becoming more economically prepared. However, it’s crucial for policyholders to weigh their immediate cash needs against the long-term impact on their family’s financial stability. Even small withdrawals can accumulate over time, leading to significant reductions in the death benefit.
Consider the story of Jay and Emma, a couple who sought to relieve their financial stress. They faced challenges after withdrawing funds for an urgent expense, only to later find that the reduced death benefit affected their overall budgeting. Understanding how withdrawals can diminish death benefits is essential; even a modest withdrawal can lead to a decrease that may not be easily recoverable.
In conclusion, it’s important to ask, can you withdraw life insurance money from a policy, as this can provide immediate relief, but it’s vital to reflect on the long-term implications for your beneficiaries. As the investment consultants at Bright Advisers emphasize, maintaining the integrity of your plan is key to ensuring future financial stability. To navigate withdrawals wisely, we encourage you to consult with a financial advisor who can help you evaluate your choices and create a strategy that balances your immediate needs with your long-term family goals.
Term Life Insurance: Can You Access Cash Value?
Since term coverage plans do not build cash value, the question arises: can you withdraw life insurance money through withdrawals or loans? These arrangements are designed solely to provide a death benefit during the coverage period. Families considering term coverage should understand that while it offers lower premiums, it lacks the monetary flexibility found in permanent policies.
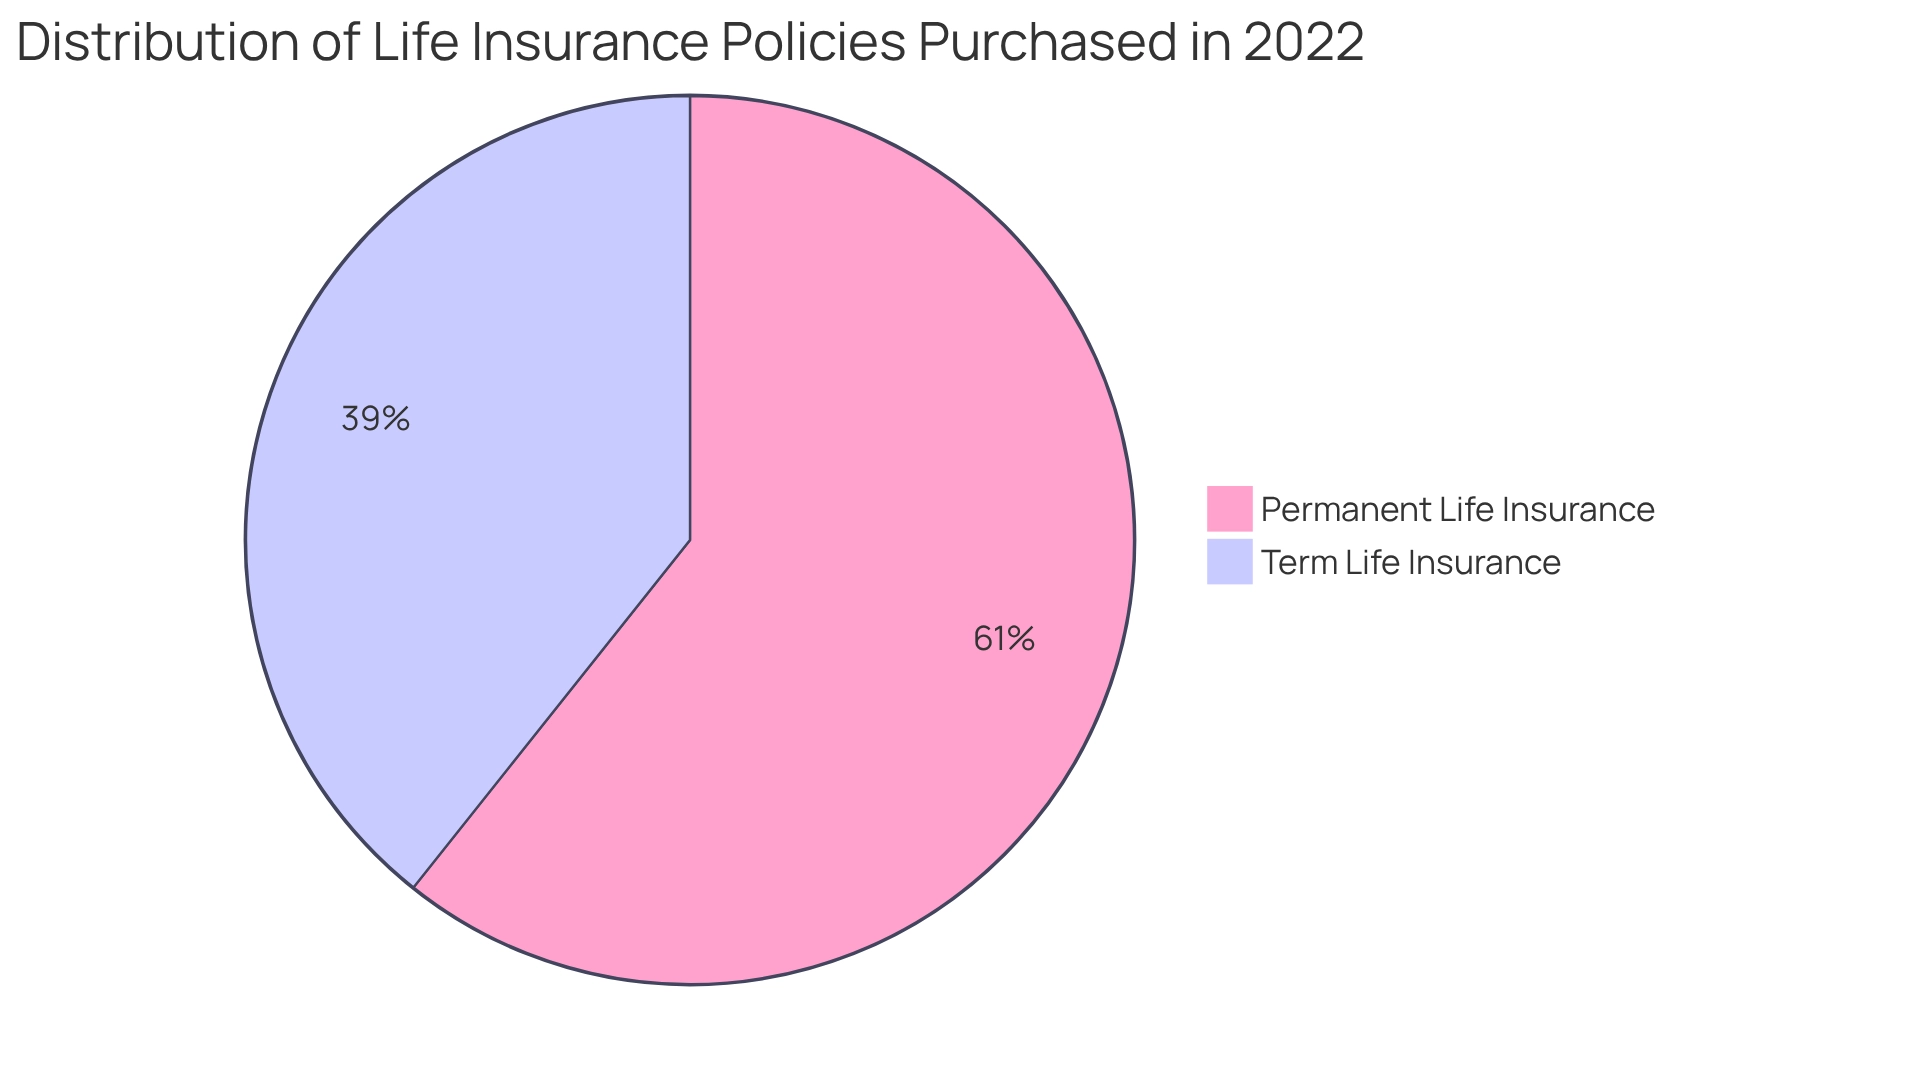
In 2022, term coverage accounted for 39.3% of all policies purchased, while permanent plans made up 60.7%. This difference highlights the preference for permanent options among families seeking long-term financial solutions. Coverage experts often point out that the limitations of temporary coverage can pose challenges for families looking for more comprehensive financial solutions. Imagine if you could not only secure a death benefit but also have the option to ask, can you withdraw life insurance money that accumulates as cash value during your lifetime. As Amy Danise, a former managing editor, noted, ‘Permanent coverage not only delivers a death benefit but also accumulates cash value that can be accessed during the policyholder’s lifetime, raising the question of can you withdraw life insurance money, thus providing enhanced economic security and flexibility.’
As families explore their insurance options, it’s important to weigh the short-term affordability of term life insurance against the long-term benefits of permanent plans. By reaching out to a financial consultant, families can assess how different plans align with their financial goals, ensuring they allocate resources effectively to reduce financial stress and protect their futures. We’re here for you at Bright Advisers, dedicated to empowering young families through personalized planning and investment strategies, helping you find the balance between current responsibilities and long-term aspirations.
Making Partial Withdrawals: A Step-by-Step Guide for Policyholders
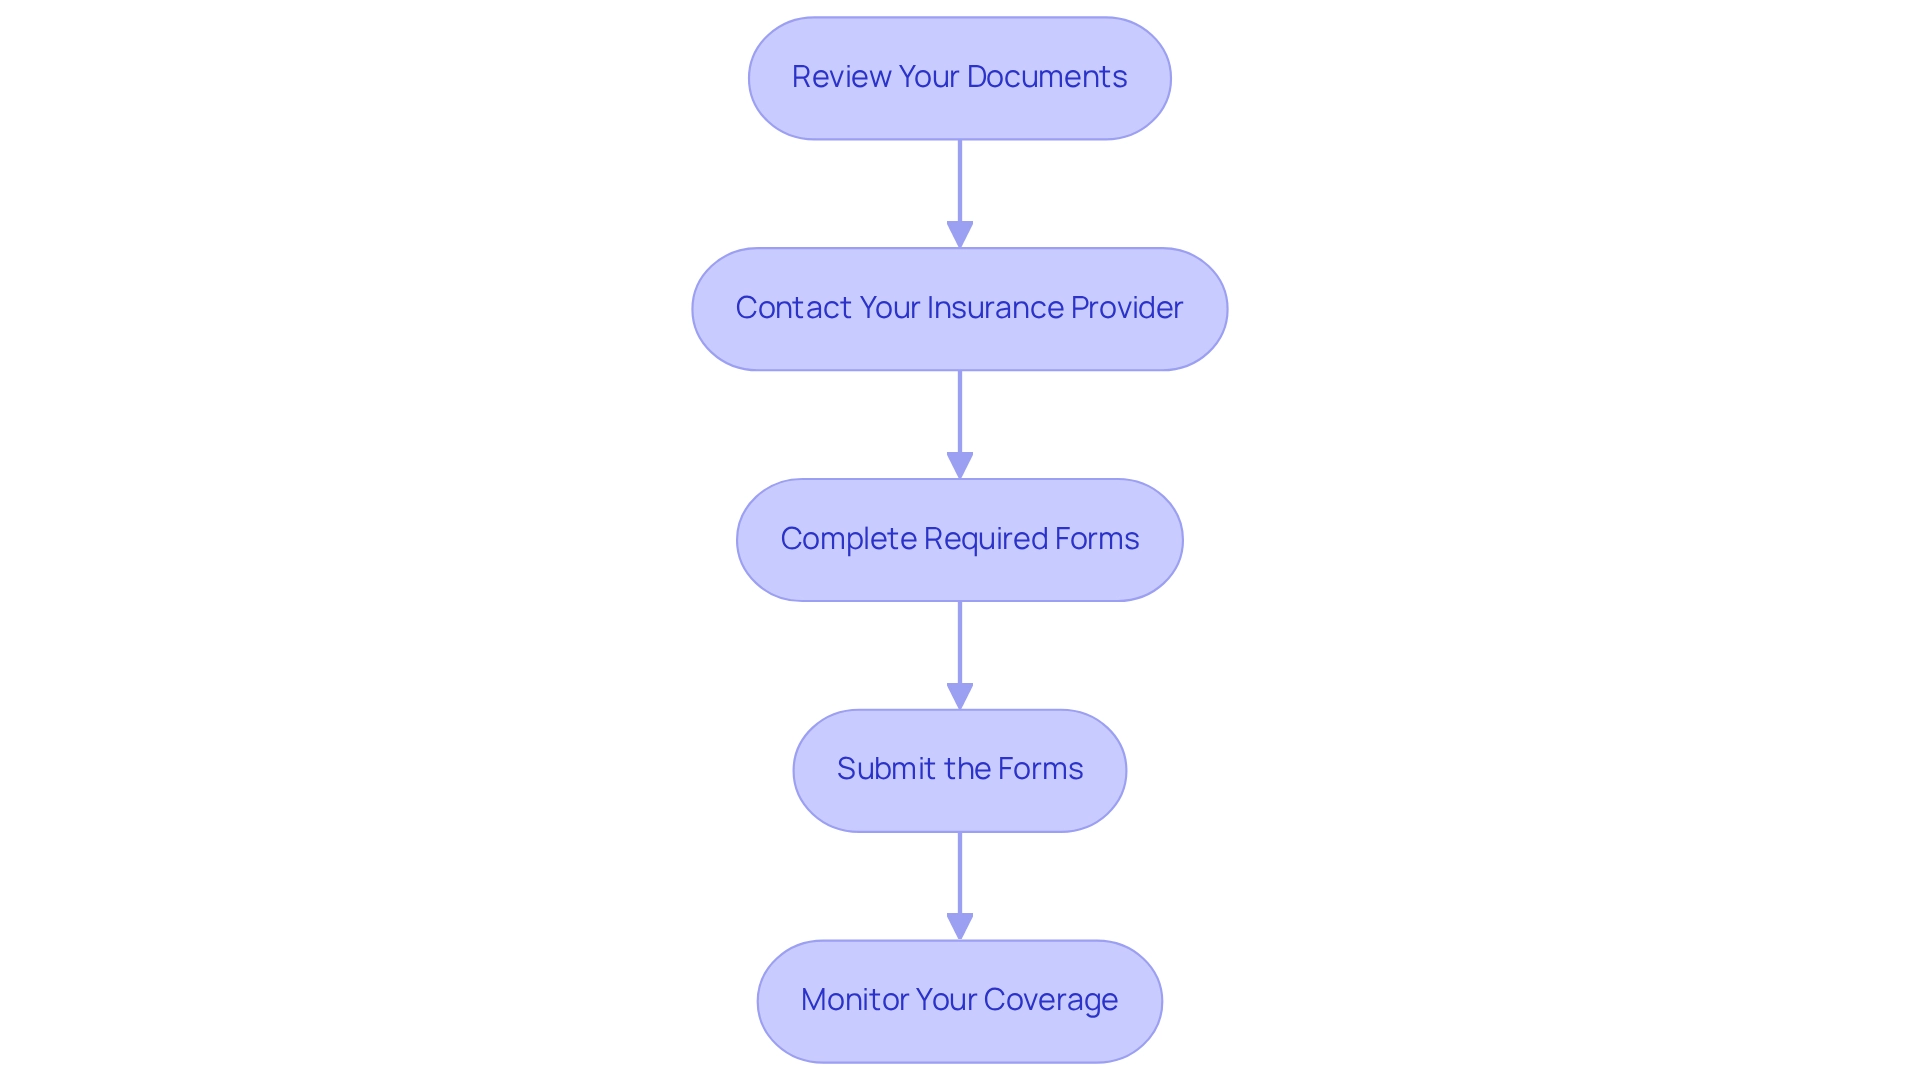
For families, especially young parents striving to balance immediate needs with long-term goals, understanding whether you can withdraw life insurance money can be a strategic financial move when considering a partial withdrawal from a life insurance plan. Here’s a step-by-step guide to navigate this process effectively:
- Review Your Documents: Start by examining your agreement to determine the available cash value. Understanding this figure is crucial, as it dictates how much you can withdraw life insurance money without jeopardizing your coverage.
- Contact Your Insurance Provider: Reach out to your insurer to clarify the withdrawal process. Each company may have different procedures, so gathering specific information regarding your policy is essential.
- Complete Required Forms: Fill out any necessary forms, clearly indicating the amount you wish to withdraw. Ensure that all information is accurate to avoid delays in processing.
- Submit the Forms: Send your completed forms to your insurer and await confirmation. This step may take some time—typically ranging from a few days to a couple of weeks—so patience is key.
- Monitor Your Coverage: After the withdrawal, keep an eye on your coverage to understand how it affects both your cash value and death benefit. Withdrawals can decrease the overall worth of your plan, so it’s essential to remain informed.
Consulting with a monetary advisor, such as those at Bright Advisers, is strongly advised to ensure that your withdrawal aligns with your broader economic strategy. This is particularly important as many younger families feel underinsured; 49% of Gen Z and 46% of Millennials report needing more coverage, and this figure jumps to 56% for households earning under $50,000 per year. By making informed decisions about withdrawals, families can better manage their economic futures while prioritizing their loved ones, particularly when considering if they can withdraw life insurance money.
Imagine if a family could use a partial withdrawal to cover unexpected medical expenses. This scenario illustrates how these funds can provide crucial support in times of need. Remember, we’re here for you—together, we can navigate this journey toward financial stability.
Key Considerations for Families: Making Informed Decisions on Life Insurance Withdrawals
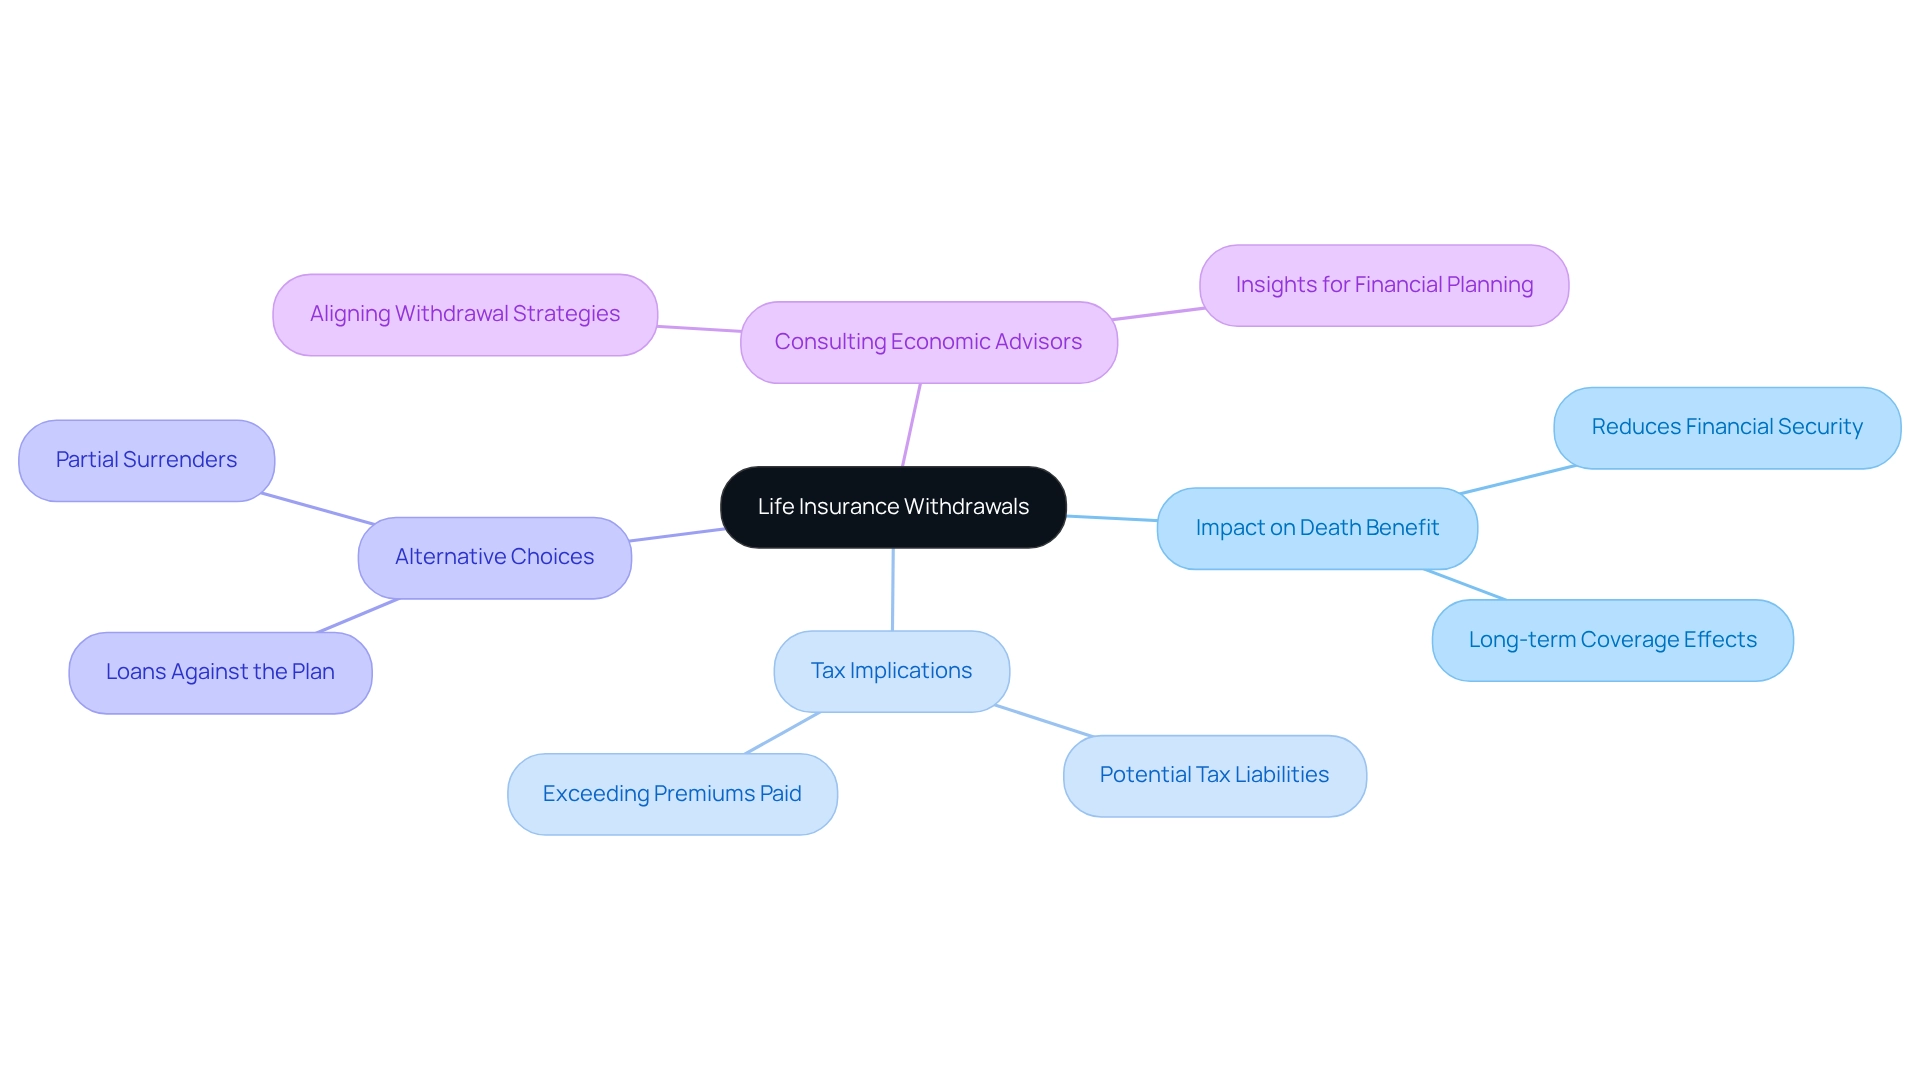
When families think about whether they can withdraw life insurance money, it’s crucial to balance immediate needs with the long-term effects on their coverage. Let’s explore some key considerations that can help guide your decision.
-
Impact on Death Benefit: Withdrawals can significantly reduce the death benefit, affecting the financial security of your loved ones. It’s important to understand how this impact plays a role in your decision-making process.
-
Tax Implications: Be aware that withdrawals may incur tax liabilities, especially if the amount exceeds the premiums paid. Evaluating these implications can help you avoid unexpected tax burdens down the line.
-
Alternative Choices: Consider exploring alternatives like loans against the plan or partial surrenders. These options can provide necessary funds without permanently diminishing the plan’s value, offering you flexibility while preserving your policy’s benefits.
-
Consulting Economic Advisors: Working with an economic advisor can be invaluable in aligning your withdrawal strategies with your broader financial goals. Advisors can provide insights into how withdrawals fit into your overall financial planning, ensuring that your decisions support both your current needs and future security.
Imagine a family facing unforeseen medical costs who chooses a loan option, allowing them to access funds without compromising their long-term coverage. Conversely, another family might decide to keep their policy unchanged, prioritizing the death benefit for their children’s future.
Statistics reveal that many people seek coverage around the age of 30 or after significant life events, such as marriage. This demographic often faces unique economic pressures, making it essential to understand the implications of life insurance choices. Experts emphasize that families should consider if they can withdraw life insurance money with a comprehensive strategy, taking into account both immediate needs and the potential long-term effects on their financial landscape. By reflecting on these key considerations, families can make informed decisions that protect their financial future. Remember, we’re here for you, and together, we can navigate this journey.
Conclusion
Accessing cash from life insurance policies can be a valuable financial resource for families, but it’s essential to approach this option with a clear understanding of its implications. Imagine the peace of mind that comes from knowing your financial decisions are well-informed. This article highlights various methods available for withdrawing funds, such as:
- Partial withdrawals
- Policy loans
- The option to surrender the policy
Each method presents unique advantages and considerations that require careful evaluation, particularly regarding their impact on the death benefit and potential tax consequences.
As families navigate their financial needs, it’s crucial to weigh the immediate benefits of accessing cash against the long-term effects on their loved ones’ financial security. Withdrawals can significantly reduce the death benefit, which may compromise the financial support beneficiaries expect in the future. It’s important to understand the tax implications of withdrawals to avoid unexpected liabilities that could undermine overall financial planning.
We’re here for you. The guidance provided by financial advisors, such as those at Bright Advisers, can empower families to make informed decisions that align with both their current circumstances and future aspirations. By exploring alternatives to withdrawals and considering comprehensive financial strategies, families can manage their resources effectively while prioritizing what truly matters — their loved ones. Together, we can navigate this journey of financial planning with care, ensuring that every decision contributes positively to securing a stable financial future.
Frequently Asked Questions
What is life insurance withdrawal?
Life insurance withdrawal refers to accessing the cash value from permanent life insurance policies, such as whole or universal life insurance, which can provide financial resources for unexpected expenses.
Can you withdraw money from life insurance?
Yes, you can withdraw money from permanent life insurance policies, but it’s important to note that these withdrawals may reduce the death benefit and overall value of your policy.
Are there tax implications when withdrawing from life insurance?
You can withdraw life insurance money without facing taxes up to the total sum of premiums you’ve contributed, but it’s essential to understand the specific terms of your policy.
What are the potential fees associated with early withdrawals?
Early withdrawals from life insurance policies may come with fees, so it’s crucial to be aware of the terms outlined in your agreement before proceeding.
How can accessing cash value from life insurance benefit my family?
Accessing cash value can serve as a strategic resource for families, helping to meet immediate financial needs while also supporting long-term financial goals, such as wealth transfer to children or grandchildren.
What should I consider before withdrawing from my life insurance policy?
Before withdrawing, you should consider the implications of reduced death benefits, potential fees, and how the withdrawal aligns with your family’s financial objectives.
List of Sources
- Bright Advisers: Personalized Financial Planning for Life Insurance Withdrawals
- When Is It OK To Draw Cash From a Life Insurance Policy? (https://usnews.com/insurance/life-insurance/when-to-draw-cash-from-life-insurance-policies)
- The tax benefits of cash value life insurance (https://transamerica.com/knowledge-place/tax-benefits-cash-value-life-insurance)
- Four Ways to Access the Value of a Life Insurance Policy | Pacific Life (https://pacificlife.com/insights-articles/four-ways-to-access-the-value-of-a-life-insurance-policy.html)
- Life Insurance Statistics: 25 Key Insights for 2025 – I&E | Whole Life & Infinite Banking Strategies (https://insuranceandestates.com/life-insurance-statistics-facts-trends)
- Life Insurance Statistics in 2025 | The Zebra (https://thezebra.com/resources/research/life-insurance-statistics)
- Whole Life Insurance: Understanding Cash Value and Withdrawal Options
- Introduction to family life insurance (https://kaleido.ca/en/blog/why-do-young-families-need-life-insurance)
- Life insurance for new parents: what do you need to consider? (https://unbiased.co.uk/discover/insurance/life-insurance/life-insurance-for-new-parents-what-do-you-need-to-consider)
- Whole Life Insurance Cash Value Chart (https://forbes.com/advisor/life-insurance/whole-life-insurance-cash-value-chart)
- 15 New Whole Life Insurance Statistics and Trends (https://term-life-online.com/15-new-whole-life-insurance-statistics.html)
- 6 Powerful Advantages of Whole Life Insurance for Individuals – Brilliant, The Insurance Company (https://brilliantinsurance.us/blog/6-powerful-advantages-of-whole-life-insurance-for-individuals)
- Aflac Supplemental Insurance (https://aflac.com/business/resources/articles/whole-life-insurance-vs-term-life-insurance.aspx)
- Whole Life Insurance Cash Value Chart [3 Great Examples] – I&E | Whole Life & Infinite Banking Strategies (https://insuranceandestates.com/whole-life-insurance-cash-value-chart)
- Surrendering Your Policy: How to Access Cash from Life Insurance
- Partial Surrender of Life Insurance: A Strategic Financial Move (https://abramsinc.com/partial-surrender-life-insurance)
- Life Insurance Statistics in 2025 | The Zebra (https://thezebra.com/resources/research/life-insurance-statistics)
- Life Insurance Facts and Statistics 2025 | Bankrate (https://bankrate.com/insurance/life-insurance/life-insurance-statistics)
- Cashing In Your Life Insurance Policy (https://investopedia.com/articles/pf/08/life-insurance-cash-in.asp)
- Partial withdrawal from life insurance policy reduces sum assured (https://m.economictimes.com/wealth/insure/life-insurance/partial-withdrawal-from-life-insurance-policy-reduces-sum-assured/articleshow/74457926.cms)
- Decline in US Life Insurance Policy Numbers Offset by Rising Aggregate Face Amount – Life Risk News (https://liferisk.news/decline-in-us-life-insurance-policy-numbers-offset-by-rising-aggregate-face-amount)
- Life Insurance and Life Settlement Statistics for 2025 (https://harborlifesettlements.com/life-insurance-settlements-and-settlement-statistics)
- Borrowing Against Your Policy: Pros and Cons of Life Insurance Loans
- Life Insurance Statistics in 2025 | The Zebra (https://thezebra.com/resources/research/life-insurance-statistics)
- Why Life Insurance Is Important: 9 Meaningful Benefits (https://westernsouthern.com/life-insurance/why-life-insurance-is-important)
- Life Insurance Facts and Statistics 2025 | Bankrate (https://bankrate.com/insurance/life-insurance/life-insurance-statistics)
- Borrowing Against Life Insurance [11 Pros and Cons] – I&E | Whole Life & Infinite Banking Strategies (https://insuranceandestates.com/borrowing-against-life-insurance-pros-and-cons)
- How to Borrow Against Life Insurance (https://progressive.com/answers/life-insurance-loans)
- Tax Implications: What to Know Before Withdrawing Life Insurance Funds
- Navigate the Tax Implications of Life Insurance Cash Value (https://westernsouthern.com/life-insurance/is-cash-value-life-insurance-taxable)
- How to Cash Out Life Insurance: Pros, Cons & Tax Implications | Facet (https://facet.com/insurance-planning/your-complete-guide-to-cashing-out-life-insurance-policies)
- Cashing In Your Life Insurance Policy (https://investopedia.com/articles/pf/08/life-insurance-cash-in.asp)
- Learning the ins and outs of taxes and life insurance (https://protective.com/learn/life-insurance/life-insurance-and-taxes)
- Alternatives to Withdrawals: Exploring Other Options for Life Insurance Cash
- 89 Essential Insurance Statistics You Need to Know (https://worthinsurance.com/statistics/insurance-statistics)
- Life Insurance and Life Settlement Statistics for 2025 (https://harborlifesettlements.com/life-insurance-settlements-and-settlement-statistics)
- Life Insurance Facts and Statistics 2025 | Bankrate (https://bankrate.com/insurance/life-insurance/life-insurance-statistics)
- Life Insurance Statistics, Data and Industry Trends 2025 (https://forbes.com/advisor/life-insurance/life-insurance-statistics)
- Impact on Death Benefit: How Withdrawals Affect Your Life Insurance Policy
- Life Insurance Statistics in 2025 | The Zebra (https://thezebra.com/resources/research/life-insurance-statistics)
- Cashing In Your Life Insurance Policy (https://investopedia.com/articles/pf/08/life-insurance-cash-in.asp)
- Life Insurance Facts and Statistics 2025 | Bankrate (https://bankrate.com/insurance/life-insurance/life-insurance-statistics)
- Term Life Insurance: Can You Access Cash Value?
- Top Life Insurance Statistics for 2025 (https://marketwatch.com/insurance-services/life-insurance/life-insurance-statistics)
- Life Insurance Facts and Statistics 2025 | Bankrate (https://bankrate.com/insurance/life-insurance/life-insurance-statistics)
- Life Insurance Statistics, Data and Industry Trends 2025 (https://forbes.com/advisor/life-insurance/life-insurance-statistics)
- Making Partial Withdrawals: A Step-by-Step Guide for Policyholders
- Top Life Insurance Statistics, Trends & Facts (2025) | Feather Blog (https://feather-insurance.com/blog/life-insurance-statistics)
- Life Insurance Statistics in 2025 | The Zebra (https://thezebra.com/resources/research/life-insurance-statistics)
- Key Considerations for Families: Making Informed Decisions on Life Insurance Withdrawals
- Life Insurance Statistics in 2025 | The Zebra (https://thezebra.com/resources/research/life-insurance-statistics)
- How to Cash Out Life Insurance: Pros, Cons & Tax Implications | Facet (https://facet.com/insurance-planning/your-complete-guide-to-cashing-out-life-insurance-policies)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Estate Planning for high-income W-2 families at Bright Advisers.
Keep reading