

Overview
This article presents seven thoughtful strategies for withdrawing money from a high-yield savings account (HYSA) without incurring penalties. By understanding withdrawal limits, maintaining a minimum balance, and setting specific savings goals, families can navigate their financial needs with confidence. Each strategy is accompanied by practical advice on managing transactions and automating deposits, along with considerations for tax implications. All of this is designed to help families maximize their savings while ensuring they have access to their funds when needed.
Imagine if you could manage your savings effectively while still being there for your loved ones. These strategies not only focus on the practical aspects of money management but also resonate with your family’s values and priorities. We’re here for you as you embark on this journey, offering support and guidance every step of the way.
Key Highlights:
- Bright Advisers offers customised financial plans for families, emphasising high-yield savings accounts (HYSAs) for better interest returns.
- Families should understand withdrawal limits of HYSAs, typically allowing six transactions per month to avoid fees.
- Maintaining a minimum balance in HYSAs helps avoid penalties; some accounts require specific thresholds.
- Utilising direct deposit into HYSAs can streamline savings and enhance compound interest benefits.
- Establishing an emergency fund within a HYSA provides liquidity and growth for unexpected expenses.
- Setting specific savings goals helps families plan withdrawals without jeopardising long-term savings.
- Interest earned on HYSAs is taxable; families should consider tax implications when planning withdrawals.
- Comparing different HYSA options is crucial for finding favourable withdrawal terms and competitive interest rates.
- Monitoring interest rates allows families to adjust withdrawal strategies to maximise savings.
- Seeking professional financial guidance can help families navigate HYSA complexities and optimise their savings strategies.
Introduction
Navigating the world of high-yield savings accounts (HYSAs) can feel overwhelming, especially when it comes to understanding withdrawal policies and avoiding penalties. As families increasingly depend on these accounts for their financial security, knowing how to access funds without incurring fees becomes essential.
In this article, we explore seven effective strategies that empower you to withdraw money from your HYSAs while maximizing your savings potential. Imagine facing unexpected expenses—how can you ensure access to your funds without compromising your financial goals?
We’re here to help you navigate this journey with confidence.
Bright Advisers: Personalized Strategies for HYSA Withdrawals
At Bright Advisers, we understand the unique financial challenges faced by families with young children. That’s why we focus on creating customized monetary plans tailored to your specific needs. Imagine being able to manage your funds effectively while ensuring that your withdrawals align with your financial goals. By concentrating on high-yield savings accounts (HYSAs), we help you maximize your interest gains, which often yield greater returns than traditional deposit accounts.
This approach not only optimizes your savings but also addresses whether you can take money out of a HYSA, providing the flexibility to withdraw funds when necessary while avoiding penalties. Experts recommend maintaining an emergency fund equivalent to three to six months’ worth of living expenses, a guideline supported by financial professionals. With the personal reserve rate in the U.S. expected to be around 4.60 percent by the end of this quarter, now is a great time for families to take advantage of the competitive rates offered by HYSAs, which frequently exceed those of conventional deposit accounts.
By utilizing these resources, you can work towards achieving your financial objectives while ensuring your strategies remain adaptable to changing circumstances. Remember, we’re here for you every step of the way, helping you navigate this journey towards financial well-being for your family.

Review Your HYSA Terms: Understand Withdrawal Policies
Before you withdraw funds from your high-yield deposit account (HYDA), it’s important to understand, can you take money out of a hysa by reviewing the account’s terms and conditions? When considering high-yield savings accounts, one might wonder, can you take money out of a hysa, given that they often impose specific withdrawal limits, typically allowing a maximum of six transactions per month. This limit, once enforced by Regulation D, was suspended in April 2020. By understanding these policies, you can avoid unnecessary fees, which can range from $5 to $15 per transaction if you ask, ‘can you take money out of a hysa’ and exceed the limits.
Imagine if you could manage your monthly transactions effectively. Households that keep a close eye on their spending and arrange larger, less frequent transfers can navigate these limitations successfully, ensuring access to their funds without facing penalties. Plus, it’s reassuring to know that direct deposits and incoming transfers don’t count toward your withdrawal limits. This means you can add funds without worrying about your transaction allowance.
It’s also worth noting that ATM withdrawals and in-person transactions with tellers are generally exempt from these limits, so can you take money out of a hysa when you need it? By staying informed about your bank’s current policies, you can keep your financial strategy on track and ensure you have access to your funds whenever necessary.
As banking specialist Matthew Goldberg emphasizes, understanding your bank’s policies can help you avoid unexpected charges and choose the right options for your family’s needs. Remember, we’re here for you, and together, we can navigate this journey toward financial stability.

Maintain Minimum Balance: Avoid Withdrawal Penalties
To help you avoid withdrawal penalties, it’s essential to keep the minimum balance required for your high-yield savings account (HYSA). Many HYSAs set a specific threshold that must be maintained to prevent fees. For example, CIT Bank’s Platinum Savings account requires a minimum balance of $5,000 to avoid monthly charges, while some accounts might not require any minimum at all. Imagine the peace of mind you’ll have by ensuring your balance consistently exceeds this threshold, allowing you to access your funds freely without incurring extra costs.
This practice not only safeguards your savings but also empowers you to plan your finances more strategically. Families can adopt simple strategies, such as:
- Automating deposits
- Setting aside a portion of their income to maintain this balance
It’s important to understand the specific requirements of your HYSA, particularly regarding can you take money out of a HYSA, as this knowledge can help you avoid penalties and optimize your financial growth potential. Together, we can navigate this journey toward financial security for your family.

Utilize Direct Deposit: Streamline Your HYSA Access
Imagine establishing direct deposit into your high-yield account (HYSA) as a simple yet powerful step towards a brighter financial future for your family. By directing your paycheck straight into your HYSA, you can ensure consistent growth of your funds without the hassle of manual transfers. This automation not only streamlines your money management but also enhances the advantages of compound interest, allowing your cash to work harder for you over time.
It’s important to understand that financial specialists emphasize how automating deposits can help families stay on track with their fiscal goals, paving the way for a more stable future. Many households have successfully embraced this approach, ensuring that a portion of their income is automatically set aside for their HYSA. According to the American Payroll Association, 93% of American employees prefer receiving their paycheck via direct deposit. This method encourages disciplined saving habits while improving overall growth, enabling families to reach their financial aspirations more efficiently.
As Ben Heinze wisely notes, “Direct deposit is extremely convenient, enabling employees to transfer their paychecks straight to their bank.” Together, we can navigate this journey towards financial stability, ensuring that you and your loved ones can thrive. We’re here for you, ready to support you every step of the way.
Establish an Emergency Fund: Access Cash Without Penalties
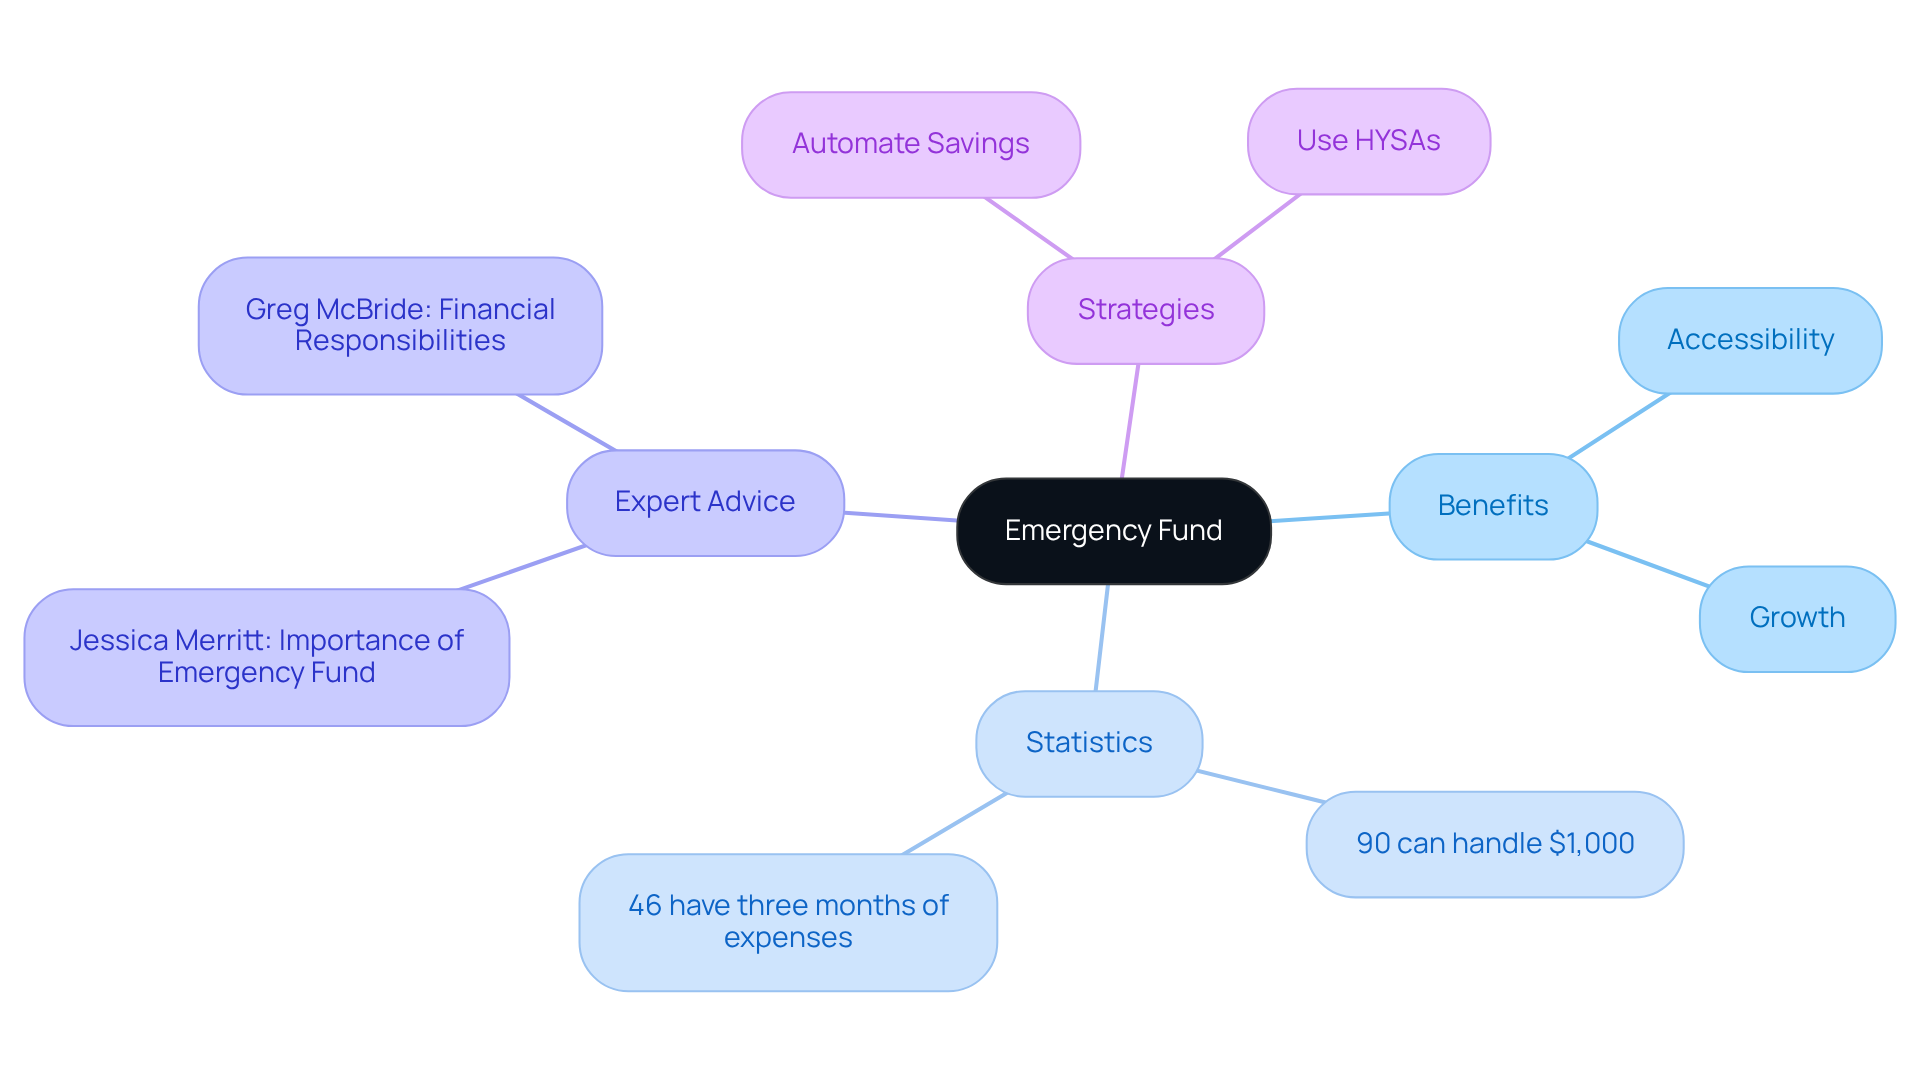
Creating an emergency fund within your high-yield account (HYSA) is a wise strategy that offers both accessibility and growth—an essential step for families navigating unexpected expenses. Imagine having a safety net for those unforeseen moments, like medical emergencies or urgent home repairs. By utilizing a HYSA, you not only earn interest on your deposits but also ensure that your funds remain liquid and accessible without penalties. This dual benefit provides peace of mind during monetary uncertainties, allowing families to handle unexpected expenses more effectively.
Financial advisors stress the essential role of emergency funds in ensuring financial stability. Jessica Merritt reminds us, “It’s impossible to overemphasize the importance of having a strong emergency fund to address unforeseen costs such as vehicle repairs or healthcare expenses.” Research shows that 90% of Americans with an emergency fund can manage an unexpected $1,000 expense in cash or reserves. It’s important to understand that specialists advise households to strive for three to six months’ worth of living costs to feel secure, as only 46% of U.S. adults currently possess sufficient emergency funds to cover three months of expenses.
To establish a successful emergency fund, consider automating your savings through regular transfers from your checking account to your HYSAs. This method not only streamlines the accumulation process but also helps create a financial cushion over time. Plus, when considering your options, you might wonder, can you take money out of a HYSA without penalties, since most HYSAs allow withdrawals at any time—making them an ideal option for emergency reserves.
Real-life examples illustrate the effectiveness of HYSAs for emergency savings. Many families have successfully used these accounts to address unforeseen expenses, ensuring they remain financially stable while managing their daily costs. By prioritizing the creation of an emergency fund in a HYSA, families can strengthen their economic resilience and protect their future. Together, we can navigate this journey toward financial security.
Target Savings Goals: Plan Withdrawals from Your HYSA
Setting clear financial objectives is essential for efficient budgeting, especially for households with young kids. Imagine allocating funds for a family vacation, a new vehicle, or your child’s education. Having specific goals can significantly influence your understanding of when you can take money out of a hysa. For instance, families might aim to save $5,000 for a vacation, allowing them to plan withdrawals thoughtfully without jeopardizing their long-term savings.
By aligning your withdrawals with these objectives, you can address the question of can you take money out of a hysa to meet immediate monetary needs while also progressing toward long-term aspirations. This strategic approach helps maintain the integrity of your finances while ensuring access to necessary funds. Financial consultants often emphasize that planning withdrawals, including the question of can you take money out of a hysa based on financial objectives, can lead to improved monetary outcomes, helping families stay on track to achieve their goals.
For families with young children, financial objectives can vary, but aiming for an emergency fund of at least six months’ worth of expenses is increasingly recommended due to economic uncertainties. As Anna Liu observes, having multiple accounts for different financial objectives can enhance overall savings. By setting mini-goals and regularly reviewing your financial strategy, you can develop a robust plan that supports both current needs and future dreams. Furthermore, households with a budget typically set aside an average of $300 more each month, underscoring the importance of organized financial reserves. Together, we can navigate this journey toward financial stability and peace of mind.

Consider Tax Implications: Plan Your HYSA Withdrawals Wisely
When considering if you can take money out of a HYSA, it’s essential to understand the tax implications. Interest earned on HYSAs is generally considered taxable income, which can significantly impact your overall financial strategy. Imagine if you could navigate this complexity with ease! The average tax rate on interest income varies based on your income bracket, typically ranging from 10% to 37%. This variability means it’s crucial to consider how these taxes will affect your net savings.
For families, strategic planning around withdrawals can help minimize tax liabilities. For instance, some households choose to withdraw funds during lower-income years to ease their tax burden. Consulting with a tax advisor can provide tailored strategies to manage interest income effectively. As LaToya Irby wisely points out, ‘Maintaining a high balance in your high-yield account can assist you in maximizing your interest earnings over time.’
Additionally, it’s important to remember that while HYSAs offer higher interest rates—often around 4% or more compared to the national average of 0.41%—the interest earned is still subject to taxation. For example, CIT Bank offers an interest rate of up to 4.00% APY, and Synchrony Bank features a 3.8% APY. Understanding how interest is taxed can empower you to make informed choices about when and how much to withdraw, specifically addressing the question of can you take money out of a HYSA, optimizing your finances while reducing tax obligations.
Furthermore, remember that deposits in HYSAs are insured by the FDIC up to $250,000, providing an added layer of security for your funds. Together, we can navigate this journey. To optimize your financial strategy, consider reviewing your financial situation with a tax advisor regularly. We’re here for you, supporting your family’s financial goals every step of the way.

Compare HYSA Options: Find the Best Withdrawal Terms
Not all high-yield savings options (HYSOs) are created equal, and it’s crucial for families to carefully evaluate the withdrawal terms and conditions offered by different banks. When choosing a high-yield savings account (HYSA), it’s important to ask, can you take money out of a HYSA, along with considering options that provide flexibility in withdrawals, minimal fees, and competitive interest rates? For example, as of July 30, 2025, SoFi offers a 3.80% APY, while Peak Bank provides a compelling 4.44% APY.
It’s important to understand that Federal Regulation D limits how many times you can take money out of a HYSA to six withdrawals per month, and exceeding this limit may lead to fees. By comparing various choices, families can select a plan that meets their financial needs and goals, ensuring they have access to their funds when they need them most.
Financial experts emphasize that understanding the question of can you take money out of a HYSA is vital for effective financial planning. Margarette Burnette wisely notes, “When selecting a financial option, a high rate isn’t the only factor you’ll want to evaluate. You’ll want to see whether there are any monthly fees or withdrawal limits.” This understanding empowers families to maintain liquidity while maximizing their financial potential.
Imagine having the peace of mind that comes from knowing you’ve made an informed decision about your savings. Together, we can navigate this journey, ensuring your family’s financial future is secure and bright.

Monitor Interest Rates: Optimize Your HYSA Withdrawals
Navigating the world of high-yield deposit options (HYSAs) can feel overwhelming, especially when interest rates fluctuate frequently. As of July 30, 2025, many HYSAs are offering rates over 4%, with Varo Money leading the way at an impressive 5.00% APY, applicable only to the first $5,000 in your balance. In this competitive landscape, it’s essential for families to stay informed about market trends and interest rate changes to make the most of their savings.
Imagine a family with a HYSA that offers a 4% APY. If they discover a new account with a 5% APY, transferring their funds could significantly boost their interest earnings. Financial experts emphasize the importance of understanding how the Federal Reserve’s interest rate decisions affect deposit yields. As Greg McBride, Chief Financial Analyst at Bankrate, wisely notes, “The longer the Federal Reserve delays reducing interest rates, the longer that depositors can benefit from returns on high-yield financial products that exceed 4 percent — and most importantly, surpass the inflation rate.” Andrew Herzog also highlights that HYSAs provide excellent principal protection, flexibility, and ease of use.
Families can further enhance their financial strategies by asking, can you take money out of a HYSA, and adjusting their withdrawal plans in response to interest rate shifts. For instance, if rates are expected to rise, it may be beneficial to keep funds in the account longer to take advantage of higher yields. Conversely, if rates are projected to drop, can you take money out of a HYSA beforehand to help maintain those higher interest earnings? With the national average deposit rate currently sitting at just 0.56% APY, the advantages of HYSAs become even clearer, especially in light of the recent inflation increase of 2.7% year-over-year as of June.
By proactively monitoring interest rates and considering the accessibility and lack of fees associated with HYSAs, families can ensure their funds work as effectively as possible, supporting their financial goals. Together, we can navigate this journey towards financial security, ensuring that your family’s future is bright and secure.

Seek Professional Guidance: Navigate HYSA Withdrawals with Experts
Navigating high-yield investment options (HYSA) can feel overwhelming for families facing unique financial challenges. Imagine if you could consult a money advisor who understands your situation and can answer the question of how can you take money out of a hysa with personalized strategies. These professionals can help clarify account complexities, enhance your investment approach, and align your choices with your family’s long-term goals.
Many families that have worked with money advisors often share stories of improved savings outcomes, as these experts guide them in making informed decisions that maximize their financial potential. As one financial advisor wisely noted, ‘Expert guidance is essential for families to navigate their financial journeys effectively.’ It’s important to understand that with 57% of young adults aged 18 to 29 relying on friends and family for financial advice, seeking professional support becomes even more vital.
By reaching out to a money advisor, families can boost their financial knowledge and confidence, ensuring they make the most of their savings without incurring penalties. To find a financial planner who resonates with your needs, consider:
- Asking for referrals from trusted sources
- Researching local professionals who specialize in family financial planning
Remember, together, we can navigate this journey toward financial security.

Conclusion
Taking money out of a high-yield savings account (HYSA) can be a strategic move to enhance your financial flexibility while maximizing interest gains. Understanding the various withdrawal options and policies can empower you to make informed decisions that align with your family’s financial goals. This article has outlined practical strategies, from reviewing account terms to establishing an emergency fund, ensuring that withdrawals can be made without incurring penalties.
Key insights discussed include:
- The importance of maintaining a minimum balance to avoid fees
- Utilizing direct deposits for seamless access
- Setting specific savings goals to guide your withdrawal decisions
Additionally, being aware of tax implications and comparing different HYSA options can further optimize your financial outcomes. By taking these steps, you can navigate your financial landscape with confidence.
Ultimately, the journey toward financial stability is best approached with a clear understanding of how to manage HYSAs effectively. We encourage you to seek professional guidance to tailor strategies that meet your unique needs, ensuring that you can maximize your savings while maintaining liquidity. By implementing these practices, you can secure your financial future and achieve peace of mind in your monetary management.
Frequently Asked Questions
What is Bright Advisers and what do they offer?
Bright Advisers specializes in creating personalized financial strategies for families with young children, focusing on high-yield savings accounts (HYSAs) to help maximize interest gains and align withdrawals with financial goals.
Can I withdraw money from a high-yield savings account (HYSA)?
Yes, you can withdraw money from a HYSA, but it’s important to review the account’s terms and conditions, as there may be specific withdrawal limits.
What are the withdrawal limits for HYSAs?
HYSAs typically allow a maximum of six transactions per month. While Regulation D previously enforced this limit, it was suspended in April 2020.
What happens if I exceed the withdrawal limits on my HYSA?
Exceeding the withdrawal limits can result in unnecessary fees, which may range from $5 to $15 per transaction.
Are there any transactions that do not count towards the withdrawal limits?
Yes, direct deposits and incoming transfers do not count towards the withdrawal limits. Additionally, ATM withdrawals and in-person transactions with tellers are generally exempt from these limits.
How can I avoid withdrawal penalties with my HYSA?
To avoid withdrawal penalties, it is essential to maintain the minimum balance required for your HYSA, which varies by account. For example, some accounts may require a minimum balance of $5,000 to avoid monthly charges.
What strategies can families use to maintain the minimum balance in their HYSA?
Families can automate deposits and set aside a portion of their income to ensure they maintain the required minimum balance.
Why is it important to understand my HYSA’s terms regarding withdrawals?
Understanding your HYSA’s terms can help you avoid penalties, manage your finances more effectively, and optimize your financial growth potential.
List of Sources
- Bright Advisers: Personalized Strategies for HYSA Withdrawals
- Advantages and Disadvantages of High-Yield Savings Account (https://incharge.org/financial-literacy/budgeting-saving/high-yield-savings-account-pros-cons)
- How much money should you keep in a high-yield savings account? (https://finance.yahoo.com/personal-finance/banking/article/how-much-money-in-hysa-214435626.html)
- United States Personal Savings Rate (https://tradingeconomics.com/united-states/personal-savings)
- Average American Savings in 2025: How Your Savings Compare (https://marketwatch.com/financial-guides/banking/average-american-savings)
- Review Your HYSA Terms: Understand Withdrawal Policies
- What Are the Withdrawal Limits for Savings Accounts? (https://investopedia.com/faq-what-are-the-withdrawal-limits-for-savings-accounts-4589981)
- Savings Account Withdrawal Limits and Federal Reserve Regulation D Explained – NerdWallet (https://nerdwallet.com/article/banking/how-regulation-d-affects-your-savings-withdrawals)
- Regulation D and savings account withdrawal limits – here’s what changed (https://finance.yahoo.com/news/regulation-d-savings-account-withdrawal-195856860.html)
- Best High-Yield Savings Accounts of July 2025: Up to 4.66% – NerdWallet (https://nerdwallet.com/best/banking/high-yield-online-savings-accounts)
- Maintain Minimum Balance: Avoid Withdrawal Penalties
- How much money should you keep in a high-yield savings account? (https://finance.yahoo.com/personal-finance/banking/article/how-much-money-in-hysa-214435626.html)
- High Yield Savings Account vs. CD – Choosing The Best Option (https://debt.org/advice/high-yield-savings-account-vs-cd)
- Basics of High-Yield Savings Accounts (https://ourfirstfed.com/support/financial-education/basics-of-high-yield-savings-accounts)
- Best High-Yield Savings Accounts Of July 2025 – Up to 4.44% | Bankrate (https://bankrate.com/banking/savings/best-high-yield-interests-savings-accounts)
- Advantages and Disadvantages of High-Yield Savings Account (https://incharge.org/financial-literacy/budgeting-saving/high-yield-savings-account-pros-cons)
- Utilize Direct Deposit: Streamline Your HYSA Access
- Direct Deposit Help – Paycheck Tools | National Payroll Week (https://nationalpayrollweek.com/direct-deposit)
- QoD (Update): 93% of employees receive paycheck via… – Blog (https://ngpf.org/blog/question-of-the-day/question-of-the-day-93-of-employees-receive-their-paycheck-via-a-cash-b-direct-deposit-c-check2)
- Nacha Research Shows 97% of Workers Ages 22-34 Have a Bank Account and 88% of Them That Are W2 Workers Use Direct Deposit | Nacha (https://nacha.org/news/nacha-research-shows-97-workers-ages-22-34-have-bank-account-and-88-them-are-w2-workers-use)
- How And Why You Should Set Up Split Direct Deposit | Alliant Credit Union (https://alliantcreditunion.org/money-mentor/how-and-why-you-should-set-up-split-direct-deposit)
- Establish an Emergency Fund: Access Cash Without Penalties
- Bankrate’s 2025 Emergency Savings Report | Bankrate (https://bankrate.com/banking/savings/emergency-savings-survey)
- Most Americans can’t afford a $1,000 emergency expense, report finds (https://cbsnews.com/news/saving-money-emergency-expenses-2025)
- Bankrate’s 2025 Emergency Savings Report | Bankrate (https://bankrate.com/banking/savings/emergency-savings-report)
- 42% of Americans Don’t Have an Emergency Fund – Including 49% of Women (https://usnews.com/banking/articles/2025-financial-wellness-survey)
- US Emergency Savings Fund Statistics (https://blog.remitly.com/finance/us-emergency-savings-statistics)
- Target Savings Goals: Plan Withdrawals from Your HYSA
- Average American Savings in 2025: How Your Savings Compare (https://marketwatch.com/financial-guides/banking/average-american-savings)
- 14 Eye‑Opening Stats About Saving Money That Could Change Your Paycheck (https://savingadvice.com/articles/2025/05/11/10156175_14-eye‑opening-stats-about-saving-money-that-could-change-your-paycheck.html)
- 23 Savings Statistics & Facts for 2024 | Balancing Everything (https://balancingeverything.com/savings-statistics)
- 50+ Essential Retirement Statistics for 2025: Demographics (https://annuity.org/retirement/retirement-statistics)
- Drivers for saving among families U.S.| Statista (https://statista.com/statistics/246194/american-families-reasons-for-saving-in-the-united-states)
- Consider Tax Implications: Plan Your HYSA Withdrawals Wisely
- Best High-Yield Savings Accounts for July 2025 (https://millennialmoney.com/high-yield-online-savings-accounts)
- 10 best high-yield savings accounts for July 2025: Earn up to 4.30% APY (https://finance.yahoo.com/personal-finance/banking/article/best-high-yield-savings-account-171334498.html)
- Do You Pay Taxes on a High-Yield Savings Account? (https://incharge.org/financial-literacy/budgeting-saving/do-you-pay-taxes-on-high-yield-savings-account)
- Best High-Yield Savings Accounts of July 2025 (https://experian.com/blogs/ask-experian/best-high-yield-savings-accounts)
- How to Move Money Into a High-Yield Savings Account (https://experian.com/blogs/ask-experian/how-to-move-money-into-high-yield-savings-account)
- Compare HYSA Options: Find the Best Withdrawal Terms
- Advantages and Disadvantages of High-Yield Savings Account (https://incharge.org/financial-literacy/budgeting-saving/high-yield-savings-account-pros-cons)
- Best High-Yield Savings Accounts Of July 2025 – Up to 4.44% | Bankrate (https://bankrate.com/banking/savings/best-high-yield-interests-savings-accounts)
- Best High-Yield Savings Accounts of July 2025 (https://experian.com/blogs/ask-experian/best-high-yield-savings-accounts)
- Best High-Yield Savings Accounts of July 2025: Up to 4.66% – NerdWallet (https://nerdwallet.com/best/banking/high-yield-online-savings-accounts)
- A Simple Savings Account Switch Could Multiply Your Money (https://menshealth.com/trending-news/a61407832/high-yield-savings-accounts)
- Monitor Interest Rates: Optimize Your HYSA Withdrawals
- Best High-Yield Savings Accounts of July 2025: Up to 4.66% – NerdWallet (https://nerdwallet.com/best/banking/high-yield-online-savings-accounts)
- High-yield savings rates today: July 28, 2025 | Top APY hits 5% ahead of Fed meeting (https://finance.yahoo.com/news/high-yield-savings-rates-today-080000575.html)
- Best High-Yield Savings Accounts Of July 2025 – Up to 4.44% | Bankrate (https://bankrate.com/banking/savings/best-high-yield-interests-savings-accounts)
- You can still earn up to 5.00% APY in a high-yield savings account. See our listing of the best high-yield savings account rates of July 30, 2025 (https://fortune.com/article/best-savings-account-rates-7-30-2025)
- Average Savings Account Interest Rate For July 2025 | Bankrate (https://bankrate.com/banking/savings/average-savings-interest-rates)
- Seek Professional Guidance: Navigate HYSA Withdrawals with Experts
- Here’s The Top Place Americans Get Financial Advice – Even Young Americans | Bankrate (https://bankrate.com/investing/financial-advisors/americans-financial-advice-top-place)
- Americans Still Turn to People for Financial Advice (https://news.gallup.com/poll/660467/americans-financial-advice-rooted-people.aspx)
- 85% of Consumers Are Looking for Financial Advice. Here’s How to Start Taking Control of Your Finances (https://money.usnews.com/money/personal-finance/family-finance/articles/85-of-consumers-are-looking-for-financial-advice-heres-how-to-start-taking-control-of-your-finances)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Investment & Risk Management for high-income W-2 families at Bright Advisers.
Keep reading