

Overview
The article “8 Powerful Infinite Banking Examples for Young Families” highlights how infinite banking can be a nurturing financial strategy for young families seeking to build lasting wealth and ensure a secure future. It gently introduces various insurance products, such as whole life and indexed universal life insurance, while emphasizing their benefits. These include:
- Cash value accumulation
- Tax advantages
- The potential to finance real estate investments
By illustrating how these tools can enhance financial literacy, the article fosters a sense of long-term economic stability for families. Imagine how empowering it could feel to take control of your financial journey together. We’re here for you, guiding you through these concepts to make informed decisions that align with your family values. Together, we can navigate this journey toward a brighter financial future.
Key Highlights:
- Bright Advisers specialises in personalised financial strategies for families, focusing on secure financial futures.
- Infinite banking is a transformative approach to wealth accumulation that promotes financial literacy in children.
- Whole life insurance provides lifelong protection and builds cash value, which can be used for loans to cover expenses like education.
- Indexed universal life insurance offers flexible premiums and potential cash value growth linked to market indices.
- Families can leverage insurance policies for real estate investments, enhancing financial portfolios with potential rental income.
- Understanding risks is crucial, including high initial costs and gradual cash value growth in whole life plans.
- Tax advantages of infinite banking include tax-exempt policy loans and tax-deferred growth of cash value.
- Policy loans allow access to cash value for various needs, but must be managed carefully to avoid diminishing benefits.
- Cash value accumulation through life insurance can support long-term wealth building and financial security.
- The future of infinite banking involves evolving strategies and technology to enhance financial planning for families.
Introduction
The financial landscape is shifting, and young families are increasingly seeking innovative strategies to secure their financial futures. Imagine a tool that not only provides protection but also empowers you to build wealth. Infinite banking has emerged as just that—a powerful strategy that allows families to leverage whole life insurance policies for both security and financial growth.
This article delves into eight compelling examples that illustrate how you can effectively utilize infinite banking to achieve your financial goals. However, it’s important to understand the challenges you might face in navigating this complex yet rewarding approach to personal finance.
Together, we can navigate this journey, ensuring that your family’s future is secure and prosperous.
Bright Advisers: Personalized Financial Planning for Infinite Banking Success
At Bright Advisers, we understand the dreams and aspirations of families with young children. We specialize in crafting personalized financial strategies that resonate with your hopes. Imagine a world where your family’s financial future is secure—our liability-driven wealth management system can guide you there. Infinite banking example illustrates that it’s not just a concept; it’s a transformative approach to wealth accumulation that empowers you and your loved ones.
This method goes beyond numbers; it nurtures economic awareness in your children, preparing them for the future. We believe that financial literacy is a gift that lasts a lifetime. Our tailored support is crucial for families like yours, providing an infinite banking example to help you navigate the complexities with ease and confidence.
With our innovative technology, we simplify financial planning, making it not only accessible but also understandable. Together, we can achieve your financial goals, ensuring that your family thrives. We’re here for you every step of the way, offering the guidance and reassurance needed to embark on this journey toward financial empowerment.
Whole Life Insurance: A Foundation for Infinite Banking
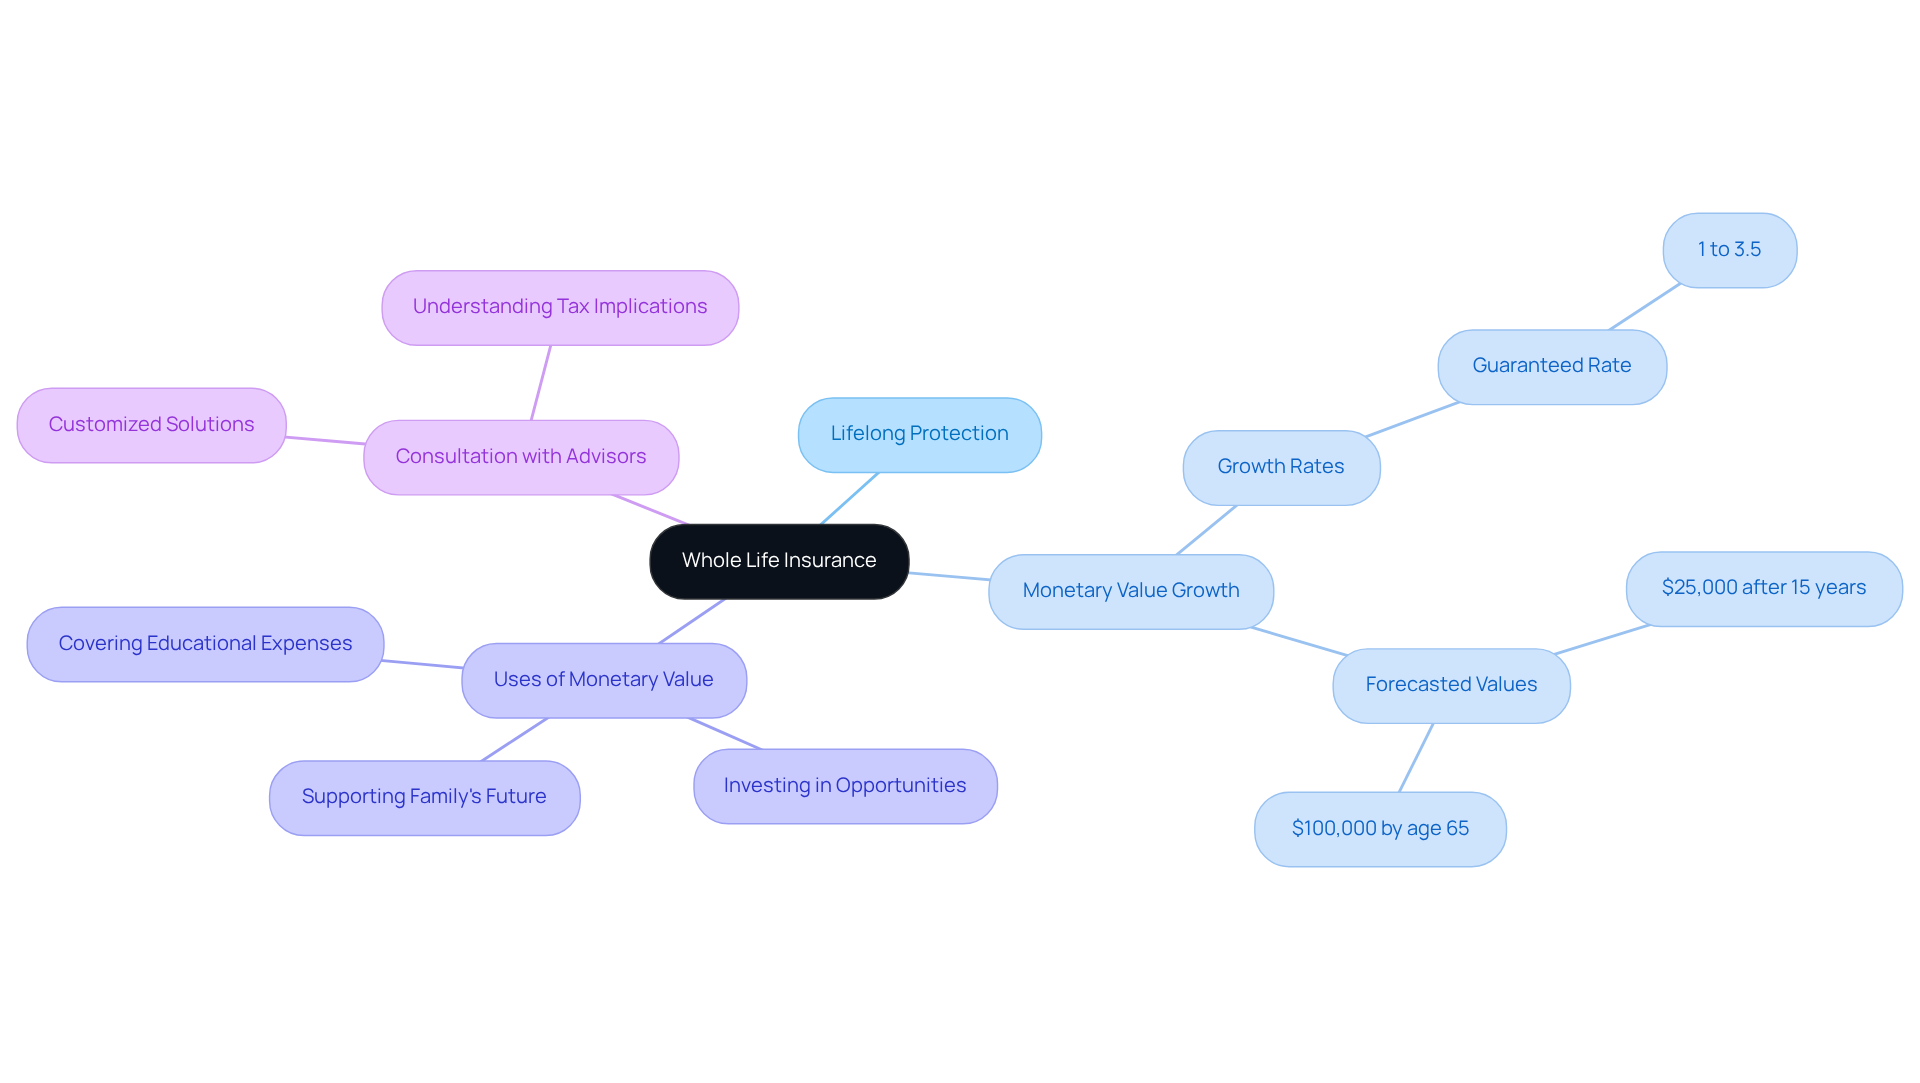
Whole life insurance plans provide lifelong protection while building value over time. This monetary value can be accessed through loans against the plan, making it an essential element of an infinite banking example. Imagine Emily and Mark, who can utilize this monetary value to cover significant costs, invest in opportunities, or support their children’s education, alleviating economic stress and ensuring brighter futures. By overfinancing these policies, families can enhance their monetary value growth, establishing a strong financial base for generations to come.
For instance, families can tap into this monetary value to cover educational expenses, ensuring their children have access to quality schooling without the burden of debt. Experts emphasize that the accumulation of monetary value in whole life insurance generally increases at a guaranteed rate of 1% to 3.5% per year, offering a dependable return that families can rely on over time. Furthermore, the typical monetary value growth for whole life insurance policies can reach significant amounts, with forecasts suggesting that after 15 years, the monetary value may approach around $25,000, and by age 65, it could grow to roughly $100,000.
This growth not only supports short-term household expenses but also contributes to long-term economic stability, making whole life insurance a valuable resource for young families aiming to accumulate wealth and secure their children’s future. However, it’s important to understand the potential tax consequences when accessing this value, as withdrawals may incur taxes on amounts exceeding the premiums paid. We encourage families to consult with a monetary advisor, such as those at Bright Advisers, who can assist in customizing whole life insurance policies to meet their specific economic needs and objectives. Together, we can navigate this journey toward financial security.
Indexed Universal Life Insurance: Flexibility in Infinite Banking
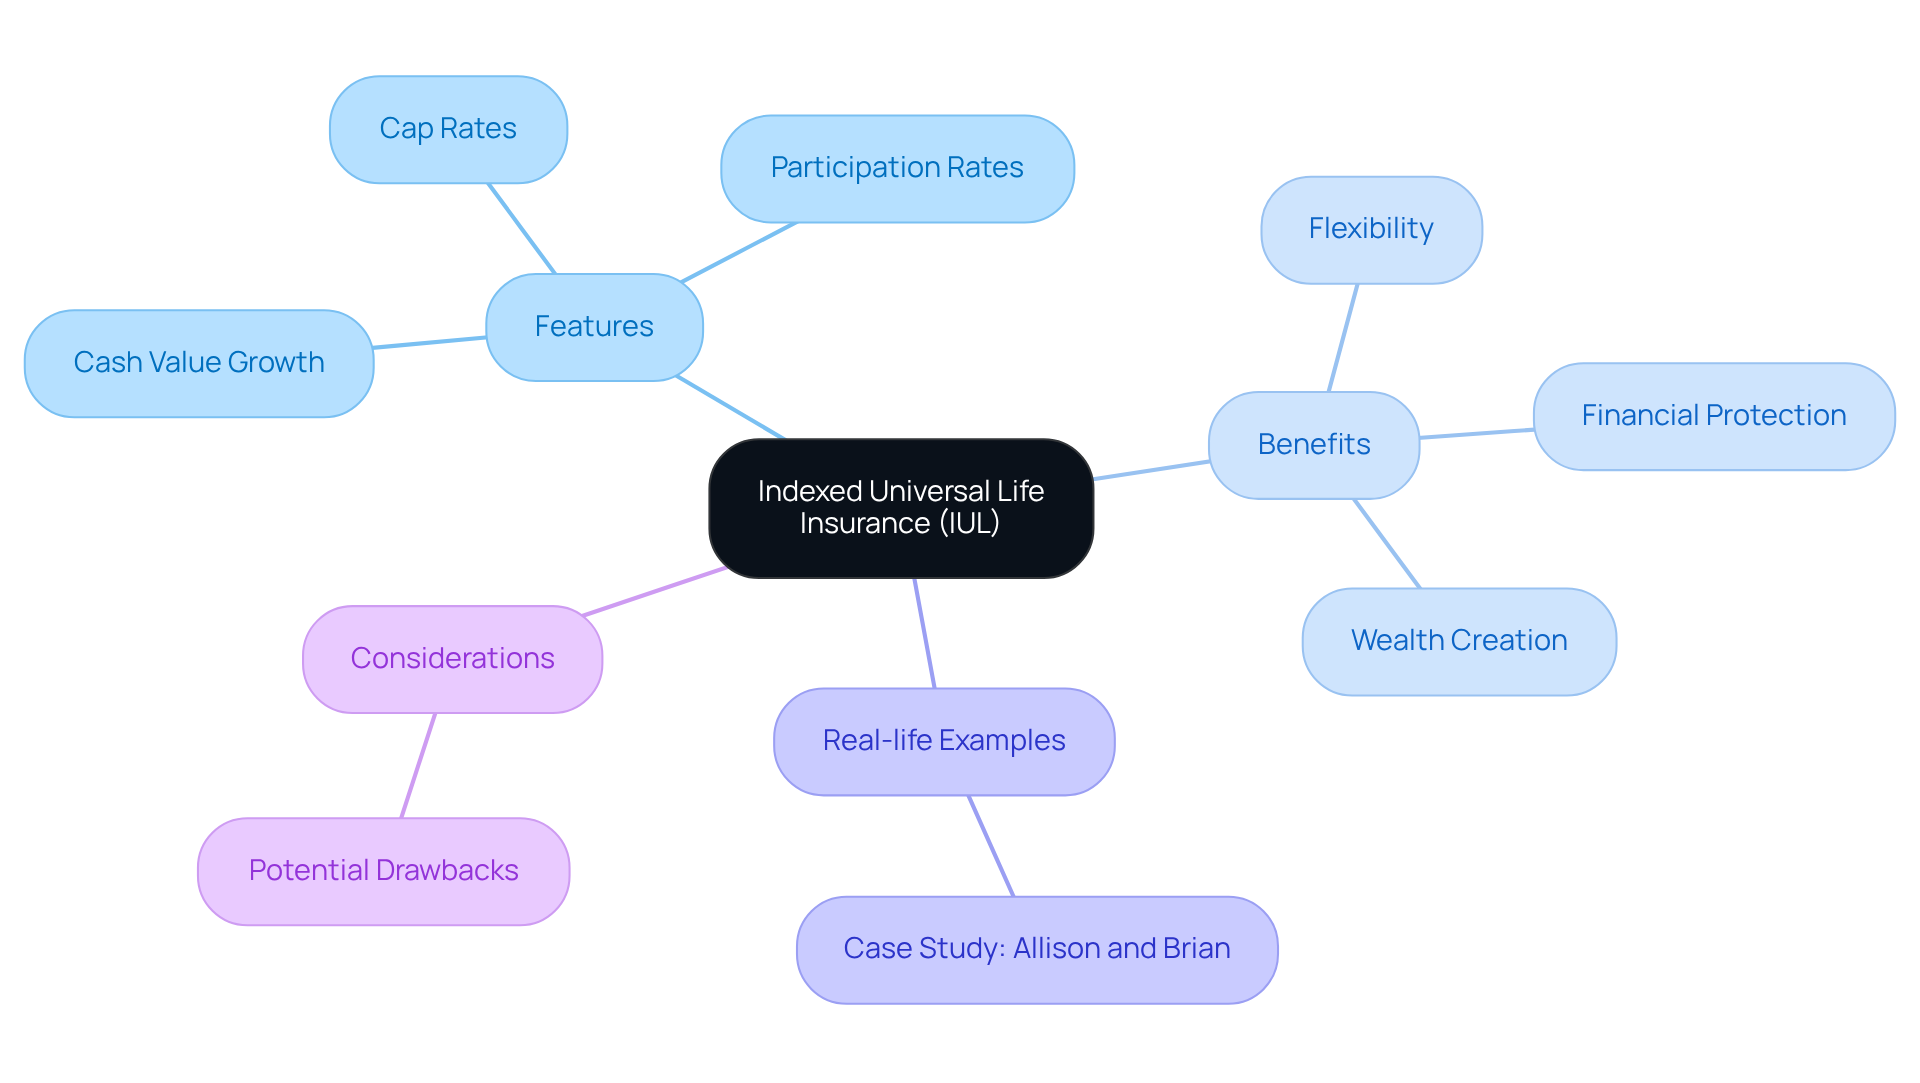
Indexed universal life (IUL) insurance offers a unique blend of whole life insurance benefits with the exciting potential for value growth linked to stock market indices. This flexibility empowers you, as a policyholder, to adapt your premiums and death benefits based on your evolving financial needs. Imagine being able to see average cash value growth of around 9% to 10% over the long term—this reflects the average total return of the S&P 500.
IULs often feature participation rates of about 85% and cap rates that range from 7% to 11%. Understanding these elements is crucial to grasp how these plans work. The combination of growth potential and the security of life insurance makes IULs an attractive option for families seeking an infinite banking example through effective strategies.
Wealth advisors often highlight the adaptability of IULs, showcasing their versatility in financial planning. For instance, consider Allison and Brian, who partnered with Bright Advisers. They utilized their IUL to support their children’s education while ensuring financial protection for their family. This illustrates how an infinite banking example can be vital in wealth creation and securing a prosperous future for your loved ones.
However, it’s important to keep a balanced perspective by considering potential drawbacks, such as competing premiums with other financial priorities. We’re here for you, ready to help you navigate your financial journey and find the best solutions for your family’s needs.
Real Estate Investment: Financing Through Infinite Banking
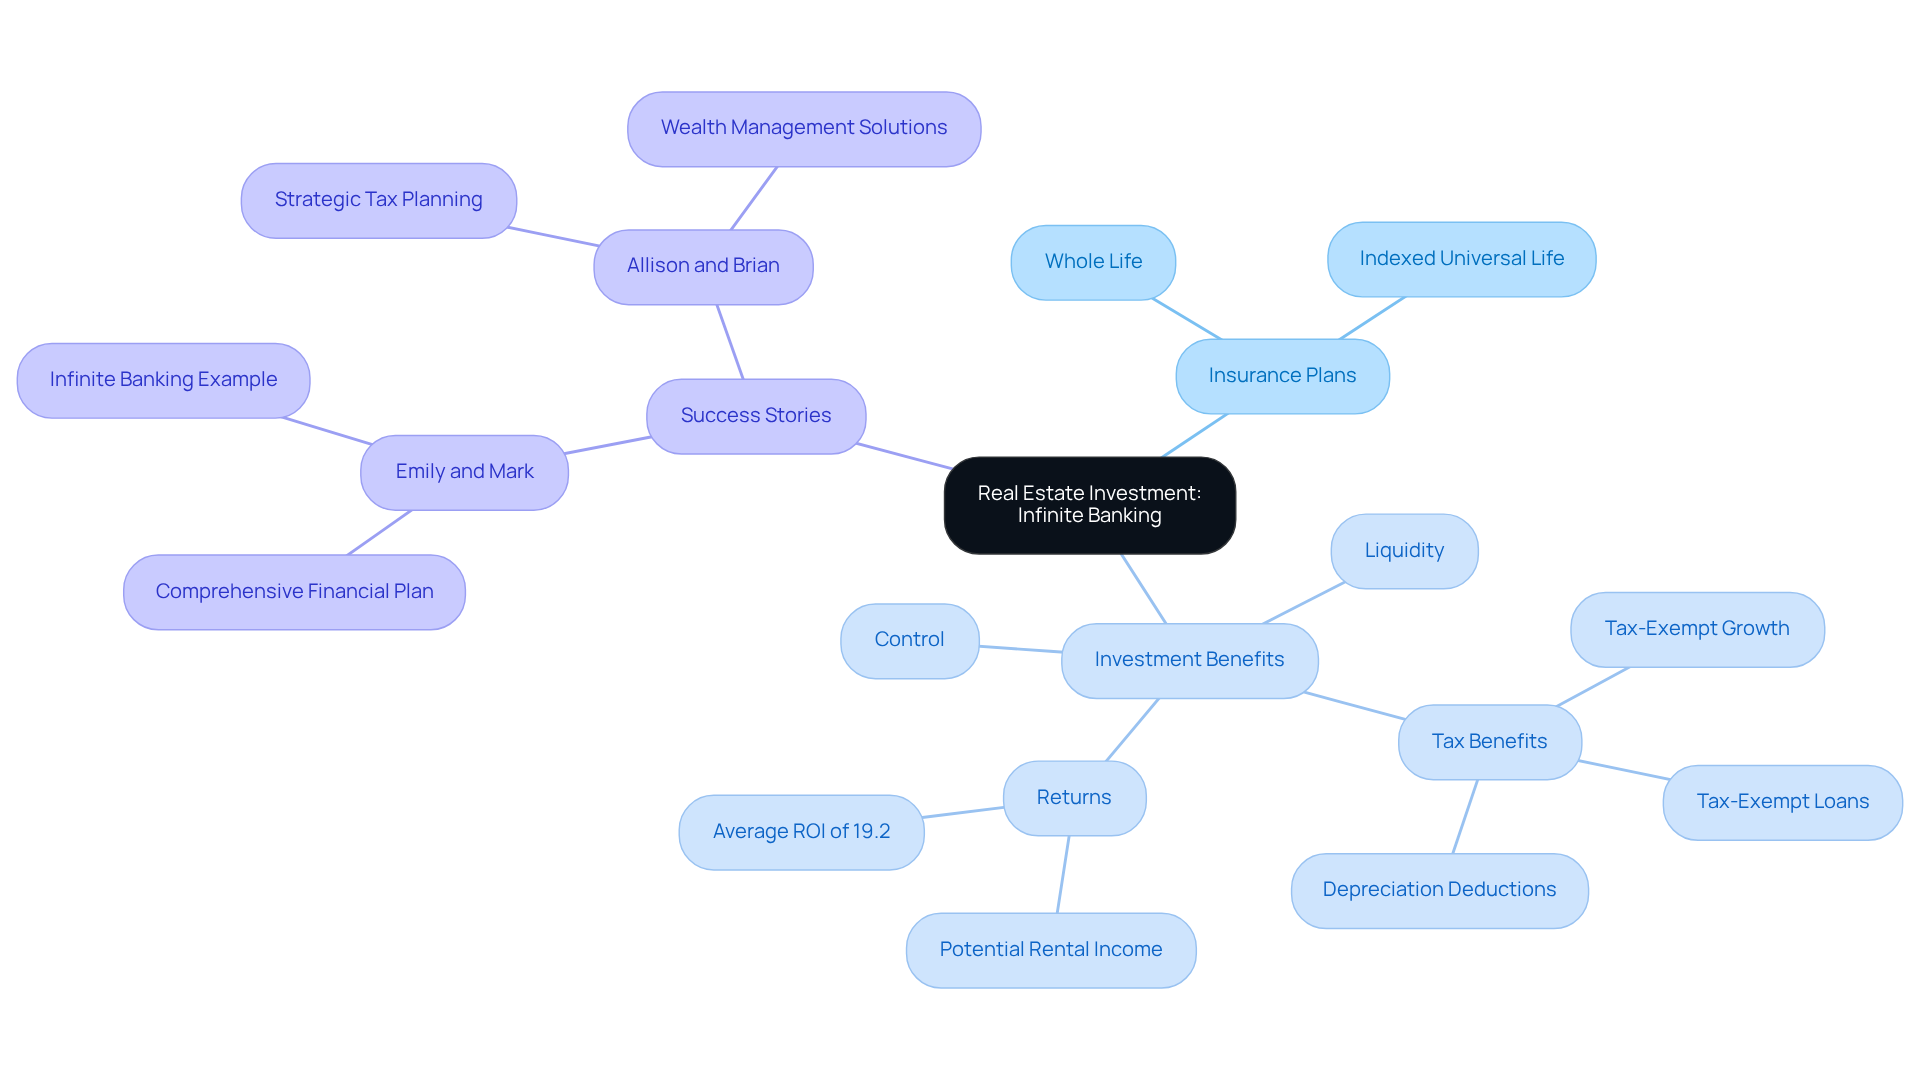
Families can thoughtfully harness the value of whole life or indexed universal life insurance plans to finance real estate investments. Imagine being able to secure down payments or even purchase properties outright by utilizing loans against your insurance. This approach not only opens doors to potential rental income but also allows for capital appreciation over time. For instance, a well-funded whole life plan could provide access to $80,000 in liquid value. When invested in real estate, this could lead to substantial returns. With an average return on investment of 19.2% achievable through smart investments—calculated from a flow of $5,760 divided by a $30,000 down payment—families can effectively enhance their portfolios.
It’s important to understand the tax benefits linked to loan agreements, such as tax-exempt growth of value and tax-exempt loans. Additionally, depreciation and interest deductions in real estate further enhance the advantages of this strategy. Expert insights highlight that an infinite banking example illustrates how using insurance policies for real estate investments not only offers liquidity and control but also fosters a mindset of economic independence.
Consider the success stories of families like Emily and Mark, who, with the support of Bright Advisers, developed a comprehensive financial plan that featured an infinite banking example along with strategies for debt reduction and cash flow management. This empowered them to improve their financial situation and gain the freedom to choose their career paths. Similarly, Allison and Brian optimized their financial prospects through strategic tax planning, demonstrating how tailored wealth management solutions can help families safeguard their financial future. Together, we can navigate this journey, ensuring that your family’s values and goals are at the forefront of your financial planning.
Understanding the Risks: Potential Drawbacks of Infinite Banking
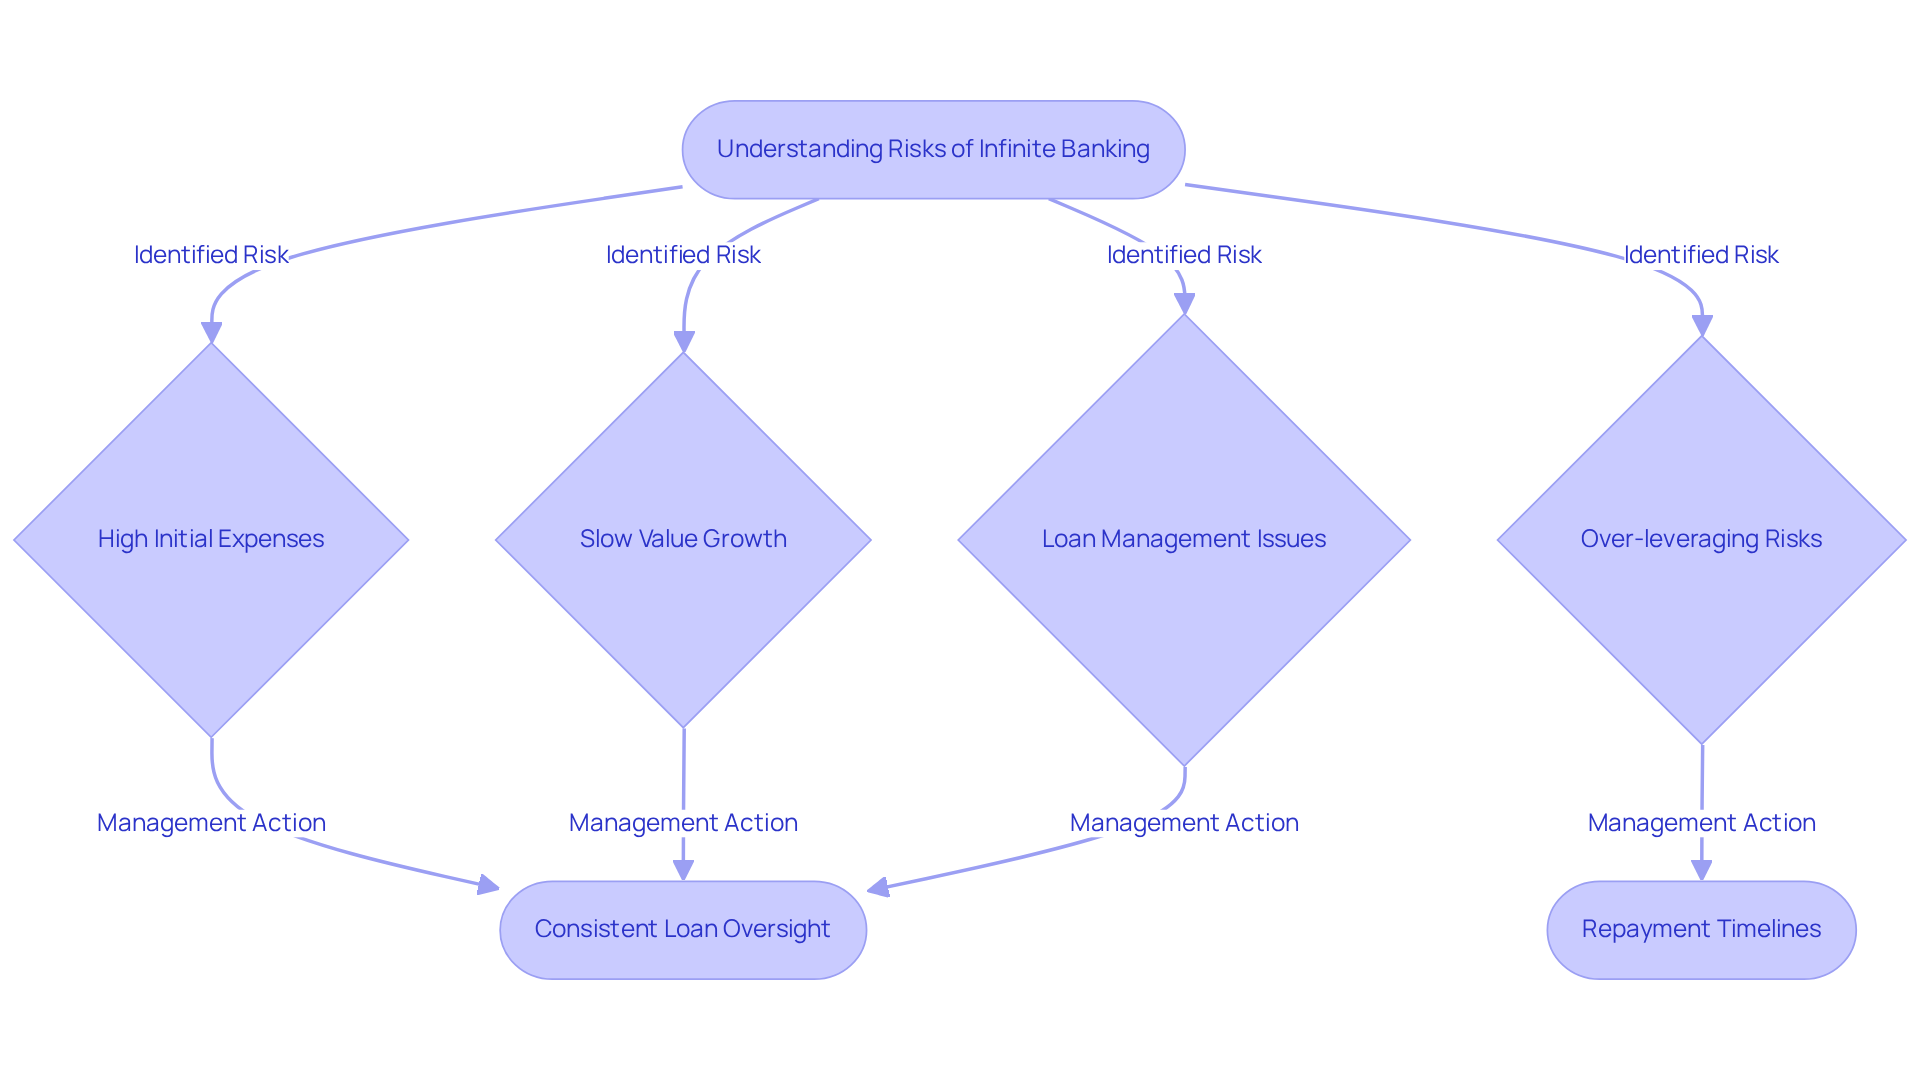
While infinite banking offers several benefits, it’s essential to recognize the considerable risks that families must evaluate. Imagine facing high initial expenses related to setting up a whole life insurance plan, which can vary from $6,000 to $9,000 each year. This investment typically requires families to allocate 10-15% of their income towards premiums. It’s important to ensure that these contributions are sustainable over the long term, providing peace of mind for the future.
Furthermore, value growth in whole life plans can be gradual, often requiring 7-8 years to reach a break-even point. Families should prepare for this slow growth and understand that immediate returns may not be realized. If loan agreements aren’t managed effectively, they can lead to lapses, resulting in the loss of death benefits and potential tax liabilities. For instance, unpaid loans may decrease the plan’s cash value and death benefit, complicating financial planning. Interest rates on insurance loans generally vary from 5% to 6%, adding to the financial implications of borrowing against the coverage.
Financial advisors emphasize the importance of disciplined handling of loans to avoid these pitfalls. They suggest:
- Consistent oversight of loan balances
- Repayment timelines to uphold the framework’s integrity, ensuring it remains effective for its intended purpose
Moreover, households should be cautious of the temptation to over-leverage their policies, as this can jeopardize their economic stability.
Understanding these risks is vital for families navigating an infinite banking example. By being aware of the potential drawbacks and committing to disciplined money management practices, families can effectively leverage an infinite banking example to build wealth and secure their financial future. Together, we can navigate this journey and ensure a brighter tomorrow for our loved ones.
Tax Advantages: Maximizing Benefits of Infinite Banking
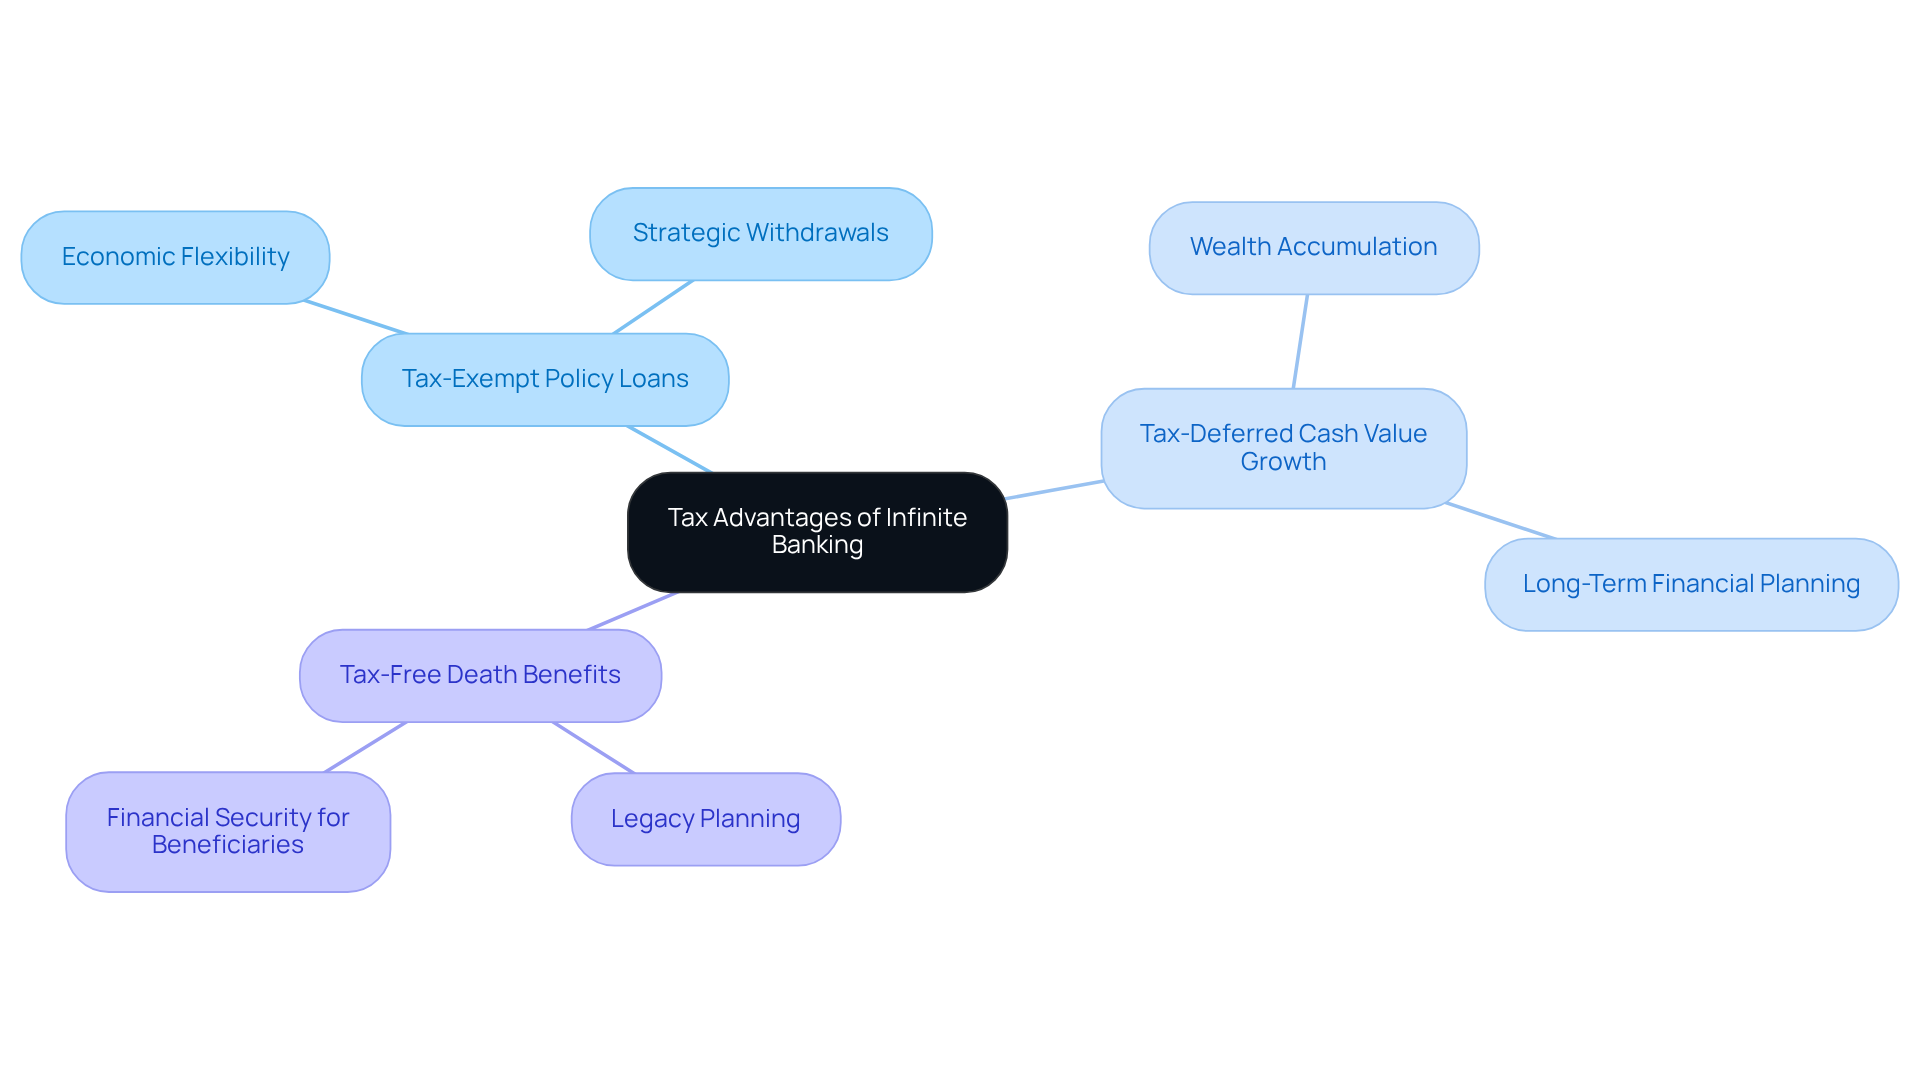
One of the most compelling advantages of infinite banking lies in its tax benefits. Imagine being able to access funds without incurring tax obligations—policy loans are typically tax-exempt, which greatly improves your family’s economic flexibility. Additionally, the cash value in these plans grows on a tax-deferred basis, allowing you to build wealth without immediate tax implications. This feature is especially beneficial for long-term financial planning, as it permits strategic withdrawals or loans to cover significant expenses, such as education or home purchases, without the burden of taxation.
It’s important to understand that the death benefit offered by these policies is generally tax-exempt for recipients. This means you can leave a legacy for your loved ones without worrying about tax consequences. Families employing infinite banking strategies have reported average tax savings that can significantly enhance their overall financial well-being. By comprehending and optimizing these tax benefits, you can develop a strong financial plan that not only addresses your current needs but also secures your family’s monetary future.
The thorough evaluation carried out by Bright Advisers for Emily and Mark was essential in recognizing these tax advantages and customizing their financial strategy accordingly. Expert opinions emphasize that the tax-deferred growth of cash value plans is a valuable resource for families seeking to accumulate wealth over time. As retirement planner Shawn Plummer observes, “Cash value life insurance is more than merely a death benefit—it’s a potent resource that can generate wealth, offer liquidity, and enhance retirement income.”
By efficiently managing loans and understanding the details of tax consequences, you can enhance your resources, ensuring that you are well-equipped for both anticipated and unforeseen costs. Real-life infinite banking examples demonstrate how families have effectively managed these strategies. Take Emily, a marketing executive, who utilized loans to invest in professional development courses and later for a down payment on a home. Her journey showcases the potential for significant tax savings and improved financial security through an infinite banking example.
Together, we can navigate this journey toward financial empowerment, ensuring that your family’s needs are met with compassion and understanding.
Policy Loans: Accessing Cash Value in Infinite Banking
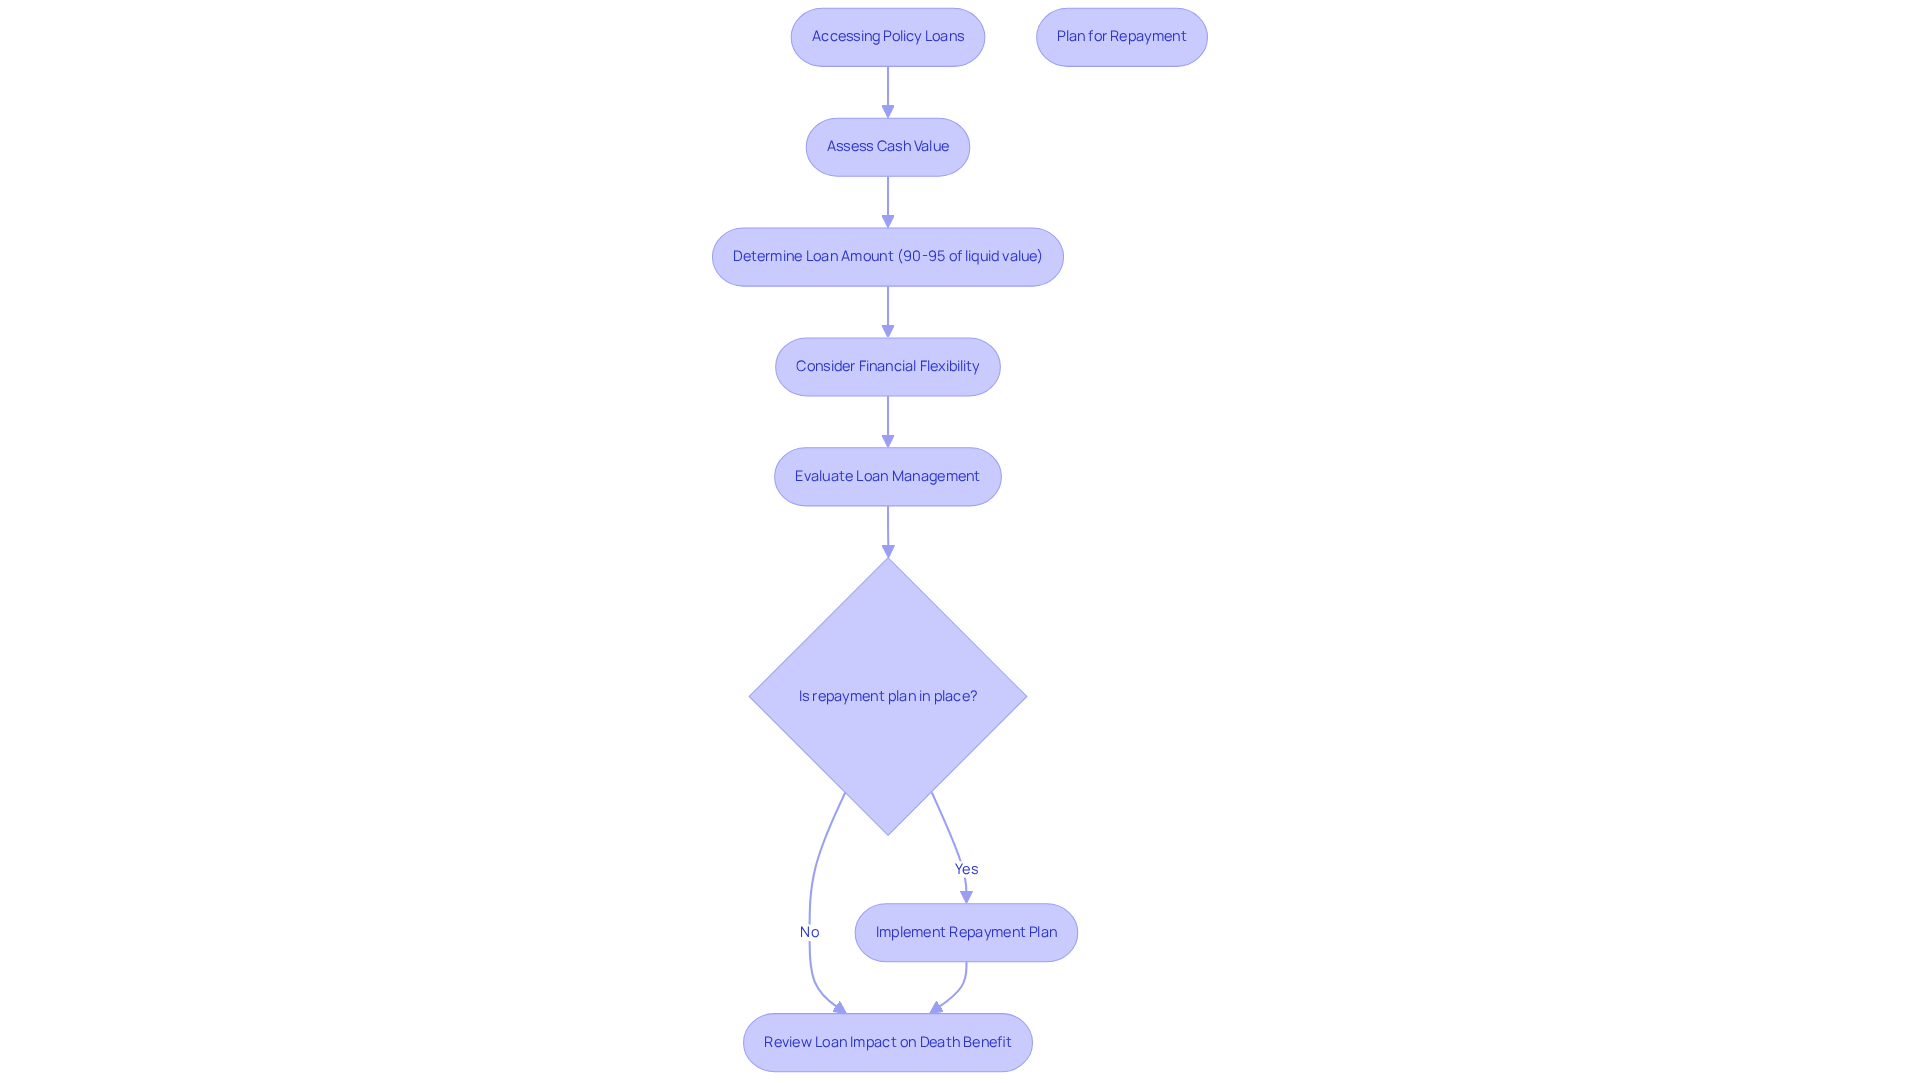
An infinite banking example shows how loan options provide a valuable opportunity for households to tap into the wealth accumulated in whole life or indexed universal life insurance plans. Imagine being able to fund your child’s education, invest in real estate, or cover unexpected expenses with ease. The borrowing process is straightforward; you can access funds based on your plan’s monetary value without the stress of credit checks or lengthy approval times. Typically, you can borrow up to 90-95% of your plan’s liquid value, offering you significant financial flexibility that aligns with Bright Advisers’ commitment to making wealth management accessible for families.
However, it’s essential to manage these loans responsibly to preserve the integrity of your program and ensure your cash value continues to grow. Outstanding life insurance loans can reduce the death benefit for your loved ones by the amount owed in principal and interest, making it crucial to have a repayment plan in place. Financial advisors stress the importance of this planning to prevent potential tax implications, as unpaid loans could lead to tax liabilities and a diminished death benefit. For instance, an infinite banking example involves using loans strategically for educational expenses, allowing you to invest in your children’s future while keeping your insurance protection intact. This approach not only alleviates financial worries but also helps you balance your retirement goals with your children’s educational needs.
Furthermore, utilizing loans from insurance for investments can open doors to wealth accumulation, provided that you thoughtfully assess the risks involved. Interest rates on life insurance loans generally range from 4% to 8%, which is significantly lower than personal loan rates that can soar to nearly 36%. This makes insurance loans an attractive option for families aiming to manage their finances effectively. Ultimately, policy loans serve as a practical financial tool, offering both quick access to cash and the potential for long-term growth, as long as they are managed with care and foresight. Additionally, Bright Advisers’ commitment to low fund fees enhances the accessibility of these financial strategies, ensuring that families can allocate their resources wisely without incurring excessive costs. Together, we can navigate this journey towards financial stability and security for your family.
Cash Value Accumulation: Building Wealth Through Infinite Banking
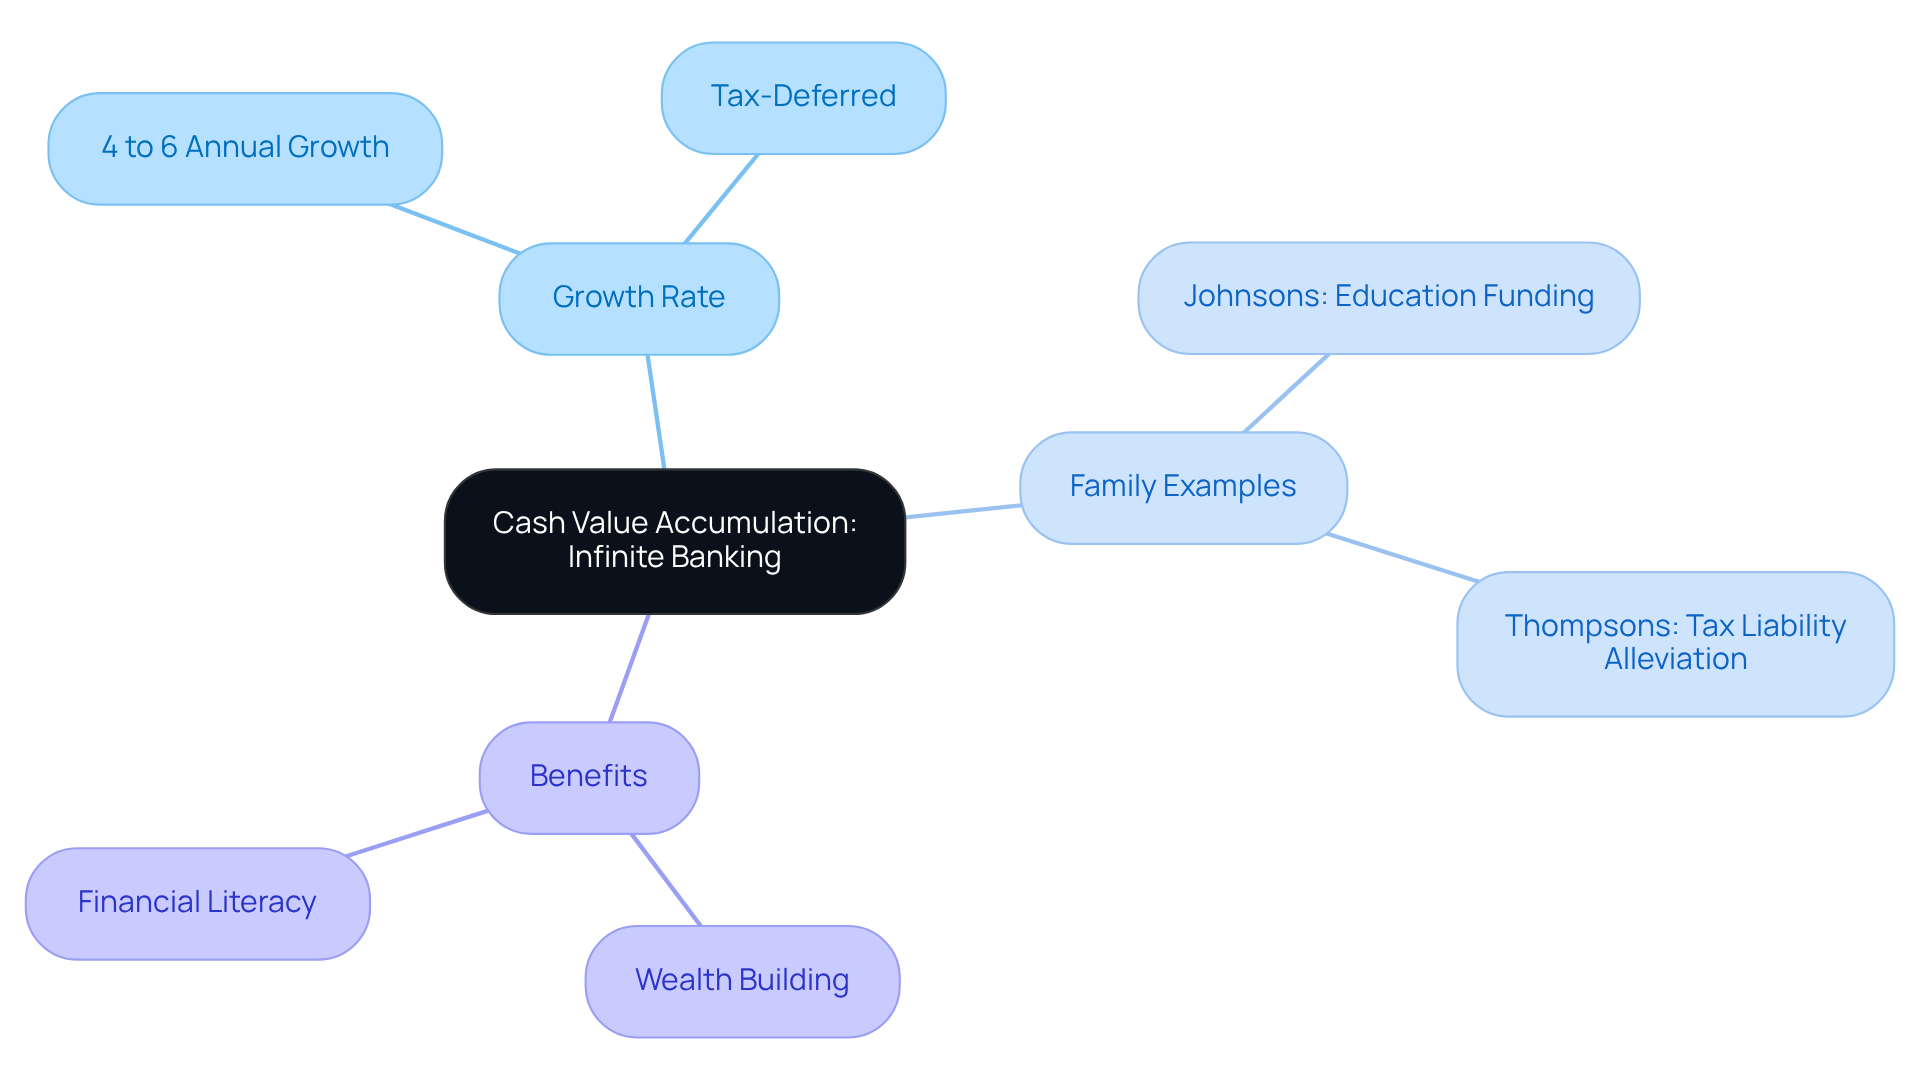
Cash value growth is a crucial infinite banking example, empowering families to build significant wealth over time. By consistently nurturing whole life or indexed universal life insurance plans, families can witness their value increase at an average rate of 4% to 6% each year, influenced by the plan structure and market conditions. This growth is not only guaranteed but also tax-deferred, allowing families to use their value for loans without the worry of tax obligations.
Imagine the Johnsons, who set up whole life insurance plans for their grandchildren. They ensured that the cash value would grow over time, ultimately providing financial support for their education. Similarly, the Thompson family utilized life insurance to alleviate tax liabilities tied to their real estate holdings, enabling their children to inherit properties without the weight of significant tax bills.
Experts agree that whole life insurance policies can be a powerful tool for wealth building, especially when paired with disciplined funding strategies. Families can create a self-sustaining economic system by using an infinite banking example, which involves viewing their life insurance as a long-term investment and tapping into the cash value for various needs such as education, business growth, or retirement funding. This approach not only secures their financial future but also fosters financial literacy in the next generation, equipping them for responsible wealth management.
Together, we can navigate this journey towards financial security, ensuring that your family’s values and aspirations are at the forefront of your planning.
Case Study: Successful Implementation of Infinite Banking
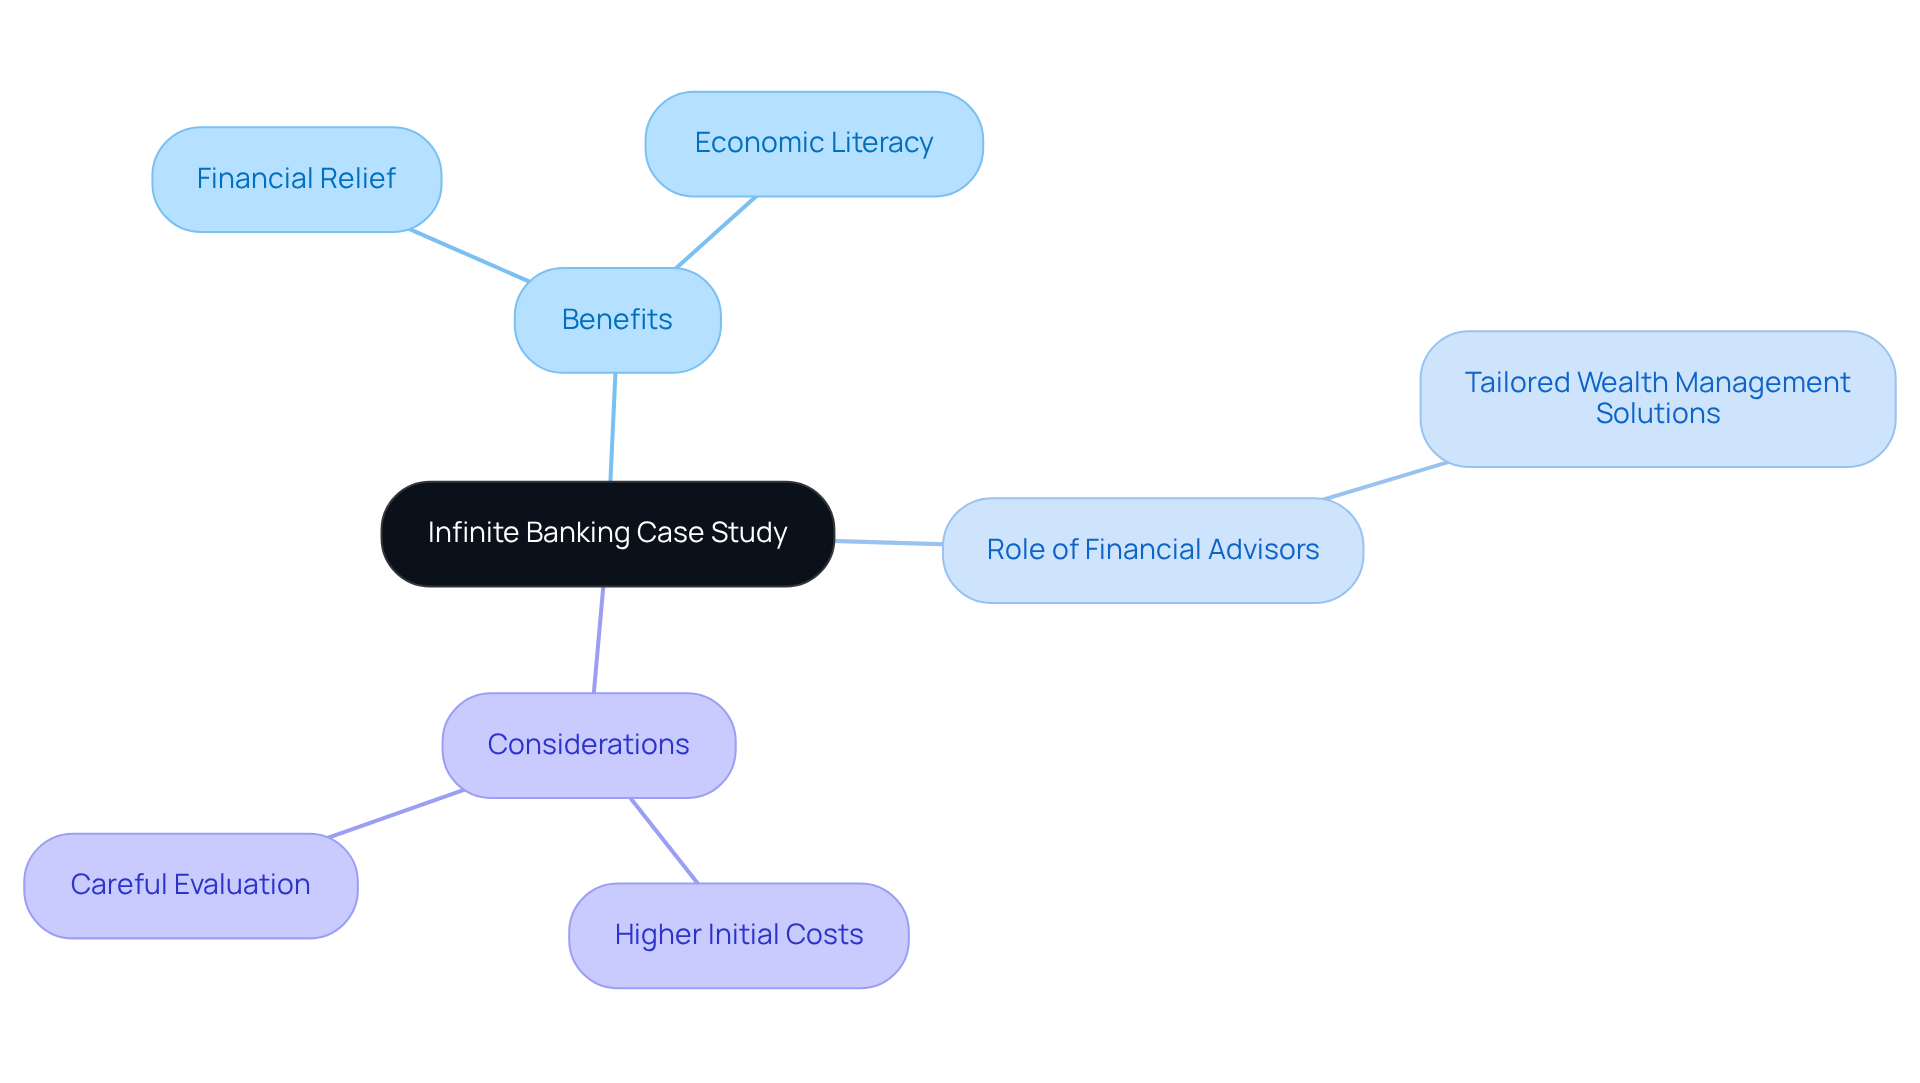
The Johnson family beautifully illustrates an infinite banking example through their thoughtful use of a whole life insurance plan for their newborn. By generously funding this plan, they built substantial monetary value in just a few years. When their child reached college age, they accessed this value through a loan to cover tuition costs, allowing them to sidestep the burden of student debt. This approach not only provided immediate financial relief but also fostered their child’s future economic literacy and independence.
Financial advisors often highlight that overfunding whole life policies can significantly boost cash value growth, making it an invaluable resource for families eager to secure their children’s educational journeys. Bright Advisers has empowered families like Emily and Mark to address similar financial challenges, offering tailored wealth management solutions that ease stress and pave the way for brighter futures.
However, it’s important to acknowledge that an infinite banking example can come with complexities and higher initial costs. Families should carefully consider these factors when evaluating their financial strategies. Remember, we’re here for you—together, we can navigate this journey toward financial security for your loved ones.
The Future of Infinite Banking: Evolving Strategies for Financial Growth
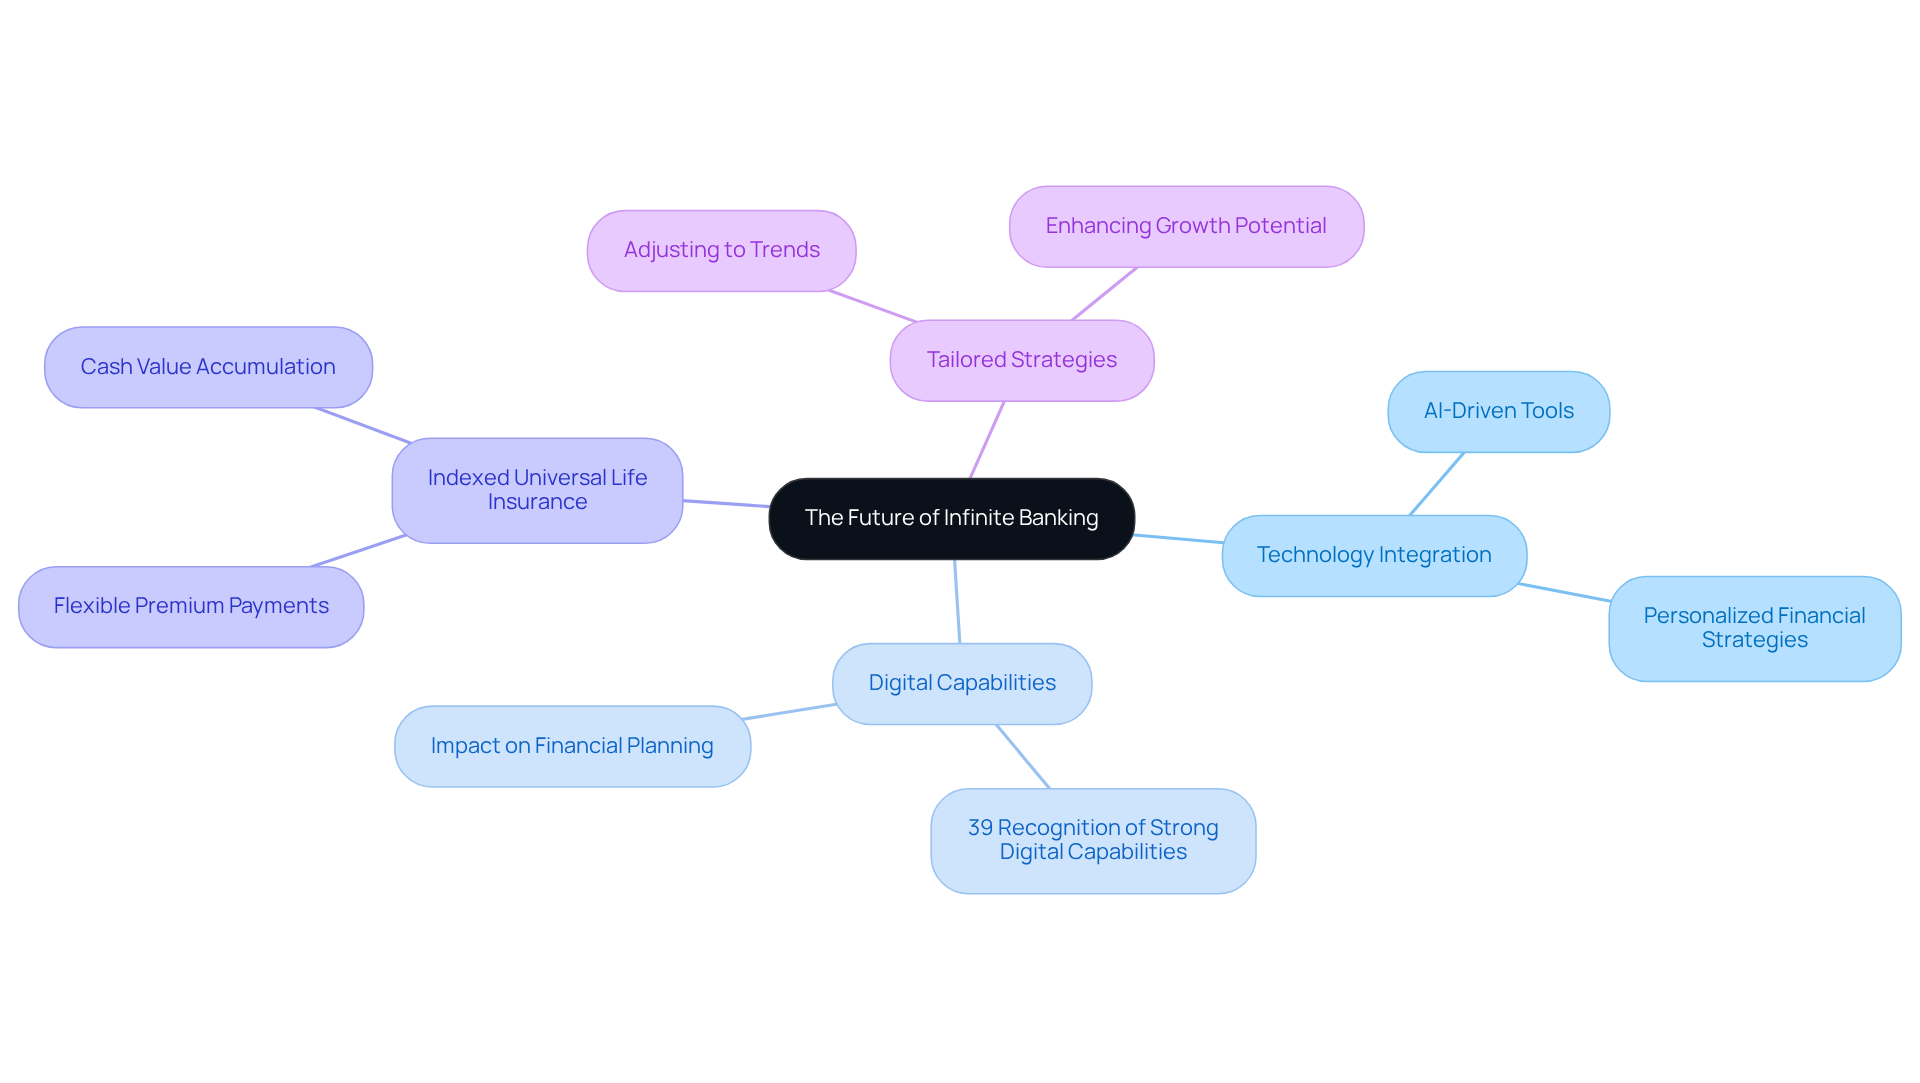
As monetary landscapes evolve, so do the strategies associated with an infinite banking example. Imagine households progressively incorporating technology into their monetary planning. Currently, 39% of domestic enterprises recognize robust digital capabilities, a minor decrease from earlier years. This shift is particularly evident in the rising popularity of indexed universal life insurance, which offers flexible premium payments and cash value accumulation.
At Bright Advisers, we’re dedicated to offering innovative wealth management solutions designed specifically for families with young children. We understand that your planning needs are unique, and we’re here to ensure that they are met. By using an infinite banking example to adjust your strategies in alignment with these trends, you can significantly boost your growth potential.
With the help of AI-driven tools, households can now develop tailored monetary strategies that account for their specific situations and objectives. You can benefit from our commitment to minimal fund fees, which improves your access to wealth management. Ongoing education and proactive interaction with advisors will be crucial for successfully navigating the future of an infinite banking example. Together, we can leverage these advancements to secure your family’s economic future.
As Dan Schulman, President of PayPal, wisely stated, “You have to re-imagine how money can be managed and moved because there’s going to be more change in the next five years in monetary services than occurred in the past 30.” This underscores the necessity of staying ahead in an ever-evolving financial landscape. Remember, we’re here for you, ready to support you on this journey.
Conclusion
The concept of infinite banking offers young families a transformative opportunity to secure their financial futures through thoughtfully designed insurance policies. Imagine creating a self-sustaining economic system that not only builds wealth but also nurtures financial literacy for future generations. By utilizing whole life and indexed universal life insurance, families can navigate their financial journeys with confidence, ensuring they can meet both immediate needs and long-term aspirations.
Throughout this article, we’ve explored key examples illustrating how families can leverage the benefits of infinite banking. From covering significant expenses to investing in real estate, each scenario highlights the potential for enhanced financial stability. Consider the tax advantages of policy loans and the gradual cash value accumulation in whole life insurance—each point reinforces the path toward financial independence. It’s important to understand that working with knowledgeable financial advisors can be a game-changer; they can guide families in customizing their strategies to maximize benefits while managing risks effectively.
Ultimately, embracing infinite banking strategies can lead to profound financial empowerment for young families. By taking proactive steps to understand and implement these concepts, families can secure their current financial needs and lay the groundwork for a prosperous future. Remember, we’re here for you—staying informed and engaged with evolving financial strategies is crucial. Together, we can navigate the complexities of wealth management in an ever-changing economic landscape, ensuring that families are well-equipped for the journey ahead.
Frequently Asked Questions
What is Bright Advisers’ approach to financial planning?
Bright Advisers specializes in personalized financial strategies that focus on securing families’ financial futures, particularly for those with young children. They utilize a liability-driven wealth management system to guide families toward financial empowerment.
How does infinite banking work according to Bright Advisers?
Infinite banking is a transformative approach to wealth accumulation that not only focuses on financial growth but also fosters economic awareness in children, preparing them for their financial futures.
What role does whole life insurance play in infinite banking?
Whole life insurance provides lifelong protection while building monetary value over time, which can be accessed through loans. This value can be used for significant expenses, investments, or educational support, helping to alleviate economic stress for families.
What are the expected growth rates for whole life insurance monetary value?
The monetary value in whole life insurance typically grows at a guaranteed rate of 1% to 3.5% per year. After 15 years, it may approach around $25,000, and by age 65, it could grow to approximately $100,000.
What are the tax implications of accessing monetary value in whole life insurance?
Withdrawals from whole life insurance policies may incur taxes on amounts exceeding the premiums paid, so it is advisable for families to consult with a monetary advisor to understand the potential tax consequences.
What is indexed universal life (IUL) insurance?
Indexed universal life insurance combines whole life benefits with growth potential linked to stock market indices, allowing policyholders to adjust premiums and death benefits according to their financial needs.
What is the average cash value growth for IUL policies?
The average cash value growth for indexed universal life insurance is around 9% to 10% over the long term, reflecting the average total return of the S&P 500.
What should families consider when choosing IUL insurance?
Families should consider the potential drawbacks, such as competing premiums with other financial priorities, while recognizing the adaptability and versatility of IULs in financial planning.
How can Bright Advisers assist families in financial planning?
Bright Advisers provides tailored support and guidance to help families navigate their financial journeys, customize insurance policies, and achieve their financial goals.
List of Sources
- Bright Advisers: Personalized Financial Planning for Infinite Banking Success
- 77 Financial Advisor Quotes to Send to Clients (https://billgoodmarketing.com/resources/financial-advisor-quotes)
- 27 eye-opening financial planning statistics (https://contentsnare.com/financial-planning-statistics)
- The State of Personal Finance in America Q2 2025 (https://ramseysolutions.com/budgeting/state-of-personal-finance?srsltid=AfmBOop_F8Sn8Ku-UOcbLqKQ16x3aleEvY-WiXCS357iXrlOkIoP9SCU)
- Roughly half of Americans are knowledgeable about personal finances (https://pewresearch.org/short-reads/2024/12/09/roughly-half-of-americans-are-knowledgeable-about-personal-finances)
- 20 + Personal Finance Statistics for 2025 | Fortunly (https://fortunly.com/statistics/personal-finance-statistics)
- Whole Life Insurance: A Foundation for Infinite Banking
- Life Insurance Statistics in 2025 | The Zebra (https://thezebra.com/resources/research/life-insurance-statistics)
- Is Whole Life Insurance a Good Investment in 2025? – NerdWallet (https://nerdwallet.com/article/insurance/is-whole-life-insurance-good-investment)
- Does Whole Life Insurance Have Cash Value? | Fidelity Life (https://fidelitylife.com/life-insurance-basics/whole-life-insurance-101/does-whole-life-insurance-have-cash-value)
- Whole Life Insurance Cash Value Chart (https://forbes.com/advisor/life-insurance/whole-life-insurance-cash-value-chart)
- Life Insurance Statistics, Data and Industry Trends 2025 (https://forbes.com/advisor/life-insurance/life-insurance-statistics)
- Indexed Universal Life Insurance: Flexibility in Infinite Banking
- Best Selling Index Universal Life Insurance 2025: Top Policies & Market Trends (https://accio.com/business/best-selling-index-universal-life-insurance)
- Best IUL Companies 2025: Complete Rankings & Benefits Guide – I&E | Whole Life & Infinite Banking Strategies (https://insuranceandestates.com/indexed-universal-life-iul-insurance)
- Life Insurance Facts and Statistics in the US (2025) (https://moneygeek.com/insurance/life/life-insurance-statistics)
- Life Insurance Facts and Statistics 2025 | Bankrate (https://bankrate.com/insurance/life-insurance/life-insurance-statistics)
- Real Estate Investment: Financing Through Infinite Banking
- Infinite Banking for Real Estate Investors | Control and Compound Financial (https://controlandcompound.com/blog/infinite-banking-for-real-estate-investors)
- Infinite Banking Strategies for Real Estate Entrepreneurs (https://linkedin.com/pulse/infinite-banking-strategies-real-estate-entrepreneurs-patrick-trainor-btrxe)
- How to Triple Your Real Estate Returns with Infinite Banking – I&E | Whole Life & Infinite Banking Strategies (https://insuranceandestates.com/how-to-triple-your-real-estate-returns-with-infinite-banking)
- Investing in Commercial Real Estate: Financing Options (https://ml.com/articles/commercial-real-estate-financing.html)
- Market discipline and policy loans (https://sciencedirect.com/science/article/abs/pii/S0378426623002716)
- Understanding the Risks: Potential Drawbacks of Infinite Banking
- What is Infinite Banking? All You Need to Know (https://quadcode.com/glossary/what-is-infinite-banking-all-you-need-to-know)
- What Are The Downsides To The Infinite Banking Concept? | Monegenix® | (https://monegenix.com/what-are-the-downsides-to-the-infinite-banking-concept)
- Infinite Banking: A Comprehensive Guide to Becoming Your Own Banker in 2025 (https://pinnaclequote.com/blog/term-rider-infinite-banking)
- Infinite Banking: What It Is and Who It’s For (https://moneygeek.com/insurance/life/infinite-banking)
- Bank on Yourself – Problems with Infinite Banking Concept | White Coat Investor (https://whitecoatinvestor.com/infinite-banking-bank-on-yourself)
- Tax Advantages: Maximizing Benefits of Infinite Banking
- Cash Value Life Insurance Quotes And Everything You Need to Know Before You Buy | The Annuity Expert (https://annuityexpertadvice.com/life-insurance/cash-value-life-insurance)
- E65: How To Make Money from Taxes Using Infinite Banking (https://livingwealth.com/how-to-make-money-from-taxes)
- Tax Strategies Using Infinite Banking With Barry Brooksby (https://capitalgainstaxsolutions.com/tax-strategies-using-infinite-banking-with-barry-brooksby)
- Infinite Banking | Using Life Insurance to Become Your Own Banker (https://lifeinsure.com/infinite-banking-using-life-insurance-to-become-your-own-banker)
- Does Infinite Banking Really Work? (https://policyadvisor.com/magazine/does-infinite-banking-really-work)
- Policy Loans: Accessing Cash Value in Infinite Banking
- How to Borrow Money From Your Life Insurance Policy (https://experian.com/blogs/ask-experian/how-to-borrow-money-from-life-insurance)
- Borrowing Against Life Insurance [11 Pros and Cons] – I&E | Whole Life & Infinite Banking Strategies (https://insuranceandestates.com/borrowing-against-life-insurance-pros-and-cons)
- When to Borrow Against a Life Insurance Policy – NerdWallet (https://nerdwallet.com/article/insurance/borrow-against-life-insurance)
- The Guide to Infinite Banking: How It Works & Who It’s For (https://quotacy.com/infinite-banking)
- Cash Value Accumulation: Building Wealth Through Infinite Banking
- Infinite Banking with Indexed Universal Life Insurance for Early Cash Value – I&E | Whole Life & Infinite Banking Strategies (https://insuranceandestates.com/infinite-banking-indexed-universal-life)
- How Can You Use Whole Life Insurance to Create Wealth? | Canadian LIC (https://canadianlic.com/blog/how-can-you-use-whole-life-insurance-to-create-wealth)
- Benefits of Using Whole Life Insurance for Infinite Banking Purposes (https://topwholelife.com/benefits-of-using-whole-life-insurance-for-infinite-banking-purposes)
- Is Whole Life Insurance a Worthwhile Investment? | Guardian (https://guardianlife.com/life-insurance/is-whole-life-worthwhile)
- How Much Money Should I Have In Order to Retire in Canada? – Dundas Life (https://dundaslife.com/blog/life-insurance-to-build-wealth)
- Case Study: Successful Implementation of Infinite Banking
- My Personal Finance Journey (https://mypersonalfinancejourney.com/infinite-banking-concept-whole-life-insurance)
- A Whole Life Insurance Success Story | White Coat Investor (https://whitecoatinvestor.com/a-whole-life-insurance-success-story-the-friday-qa-series)
- What is the Immediate Financing Arrangement? (https://safepacific.com/immediate-financing-arrangement)
- Key Concepts from the Most Influential Infinite Banking Books (https://topwholelife.com/key-concepts-from-the-most-influential-infinite-banking-books)
- 7 Steps to Determine if Is Infinite Banking Legit for Your Family – Bright Advisers (https://brightadvisers.com/7-steps-to-determine-if-is-infinite-banking-legit-for-your-family)
- The Future of Infinite Banking: Evolving Strategies for Financial Growth
- PwC’s 2023 US Family Business Survey (https://pwc.com/us/en/services/audit-assurance/private-company-services/library/family-business-survey.html)
- 50 Powerful Quotes to Inspire Fintech Leaders & Innovators (https://fintechly.com/leadership/50-powerful-quotes-to-inspire-fintech-leaders-and-innovators)
- AI could make financial advice more equitable and resilient (https://weforum.org/stories/2025/06/ai-financial-advice-accessible)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About Kevin