

Key Highlights:
- 529 plans allow families to save for educational expenses like college tuition and K-12 costs.
- Earnings in a 529 plan grow tax-free, and withdrawals for qualified expenses are also tax-free.
- 529 plans offer flexibility as funds can be used at accredited colleges and for K-12 tuition in many states.
- Contribution limits for 529 accounts can exceed $300,000, providing significant savings potential.
- At the federal level, 529 plan contributions are not tax deductible, but many states offer tax deductions or credits.
- State-specific rules vary; for example, Georgia allows a deduction of up to $4,000 per beneficiary.
- Families should verify their state’s 529 programme for potential tax benefits and contribution limits.
- Strategies to maximise 529 benefits include starting early, automating contributions, and planning withdrawals wisely.
- Regularly updating knowledge on tax laws and 529 regulations is essential for optimising savings.
Introduction
Navigating the complexities of saving for your child’s education can feel overwhelming. As a parent, you want the best for your little ones, and finding the right options for their future is crucial. Among the many choices available, 529 plans shine brightly, offering potential tax advantages that can make a significant difference.
Imagine if you could save for your child’s education while enjoying tax-free growth. This article explores the ins and outs of 529 plans, answering the important question: Are they tax deductible? We’ll highlight the various benefits these plans offer, from state-specific deductions to the peace of mind that comes with knowing you’re investing in your child’s future.
But with different rules and regulations across states, it’s essential to understand how to maximize these educational savings accounts. Together, we can navigate this journey, ensuring you make informed decisions that align with your family’s values and goals. Remember, you’re not alone in this; we’re here for you every step of the way.
Understand 529 Plans: Basics and Benefits
Imagine if you could secure your child’s educational future with a simple savings plan. A 529 program, which allows families to save for upcoming costs like college tuition, K-12 expenses, and certain apprenticeship programs, also raises the question of whether 529 plans are tax deductible.
Why consider a 529 plan? Here are some key benefits that can make a real difference for your family:
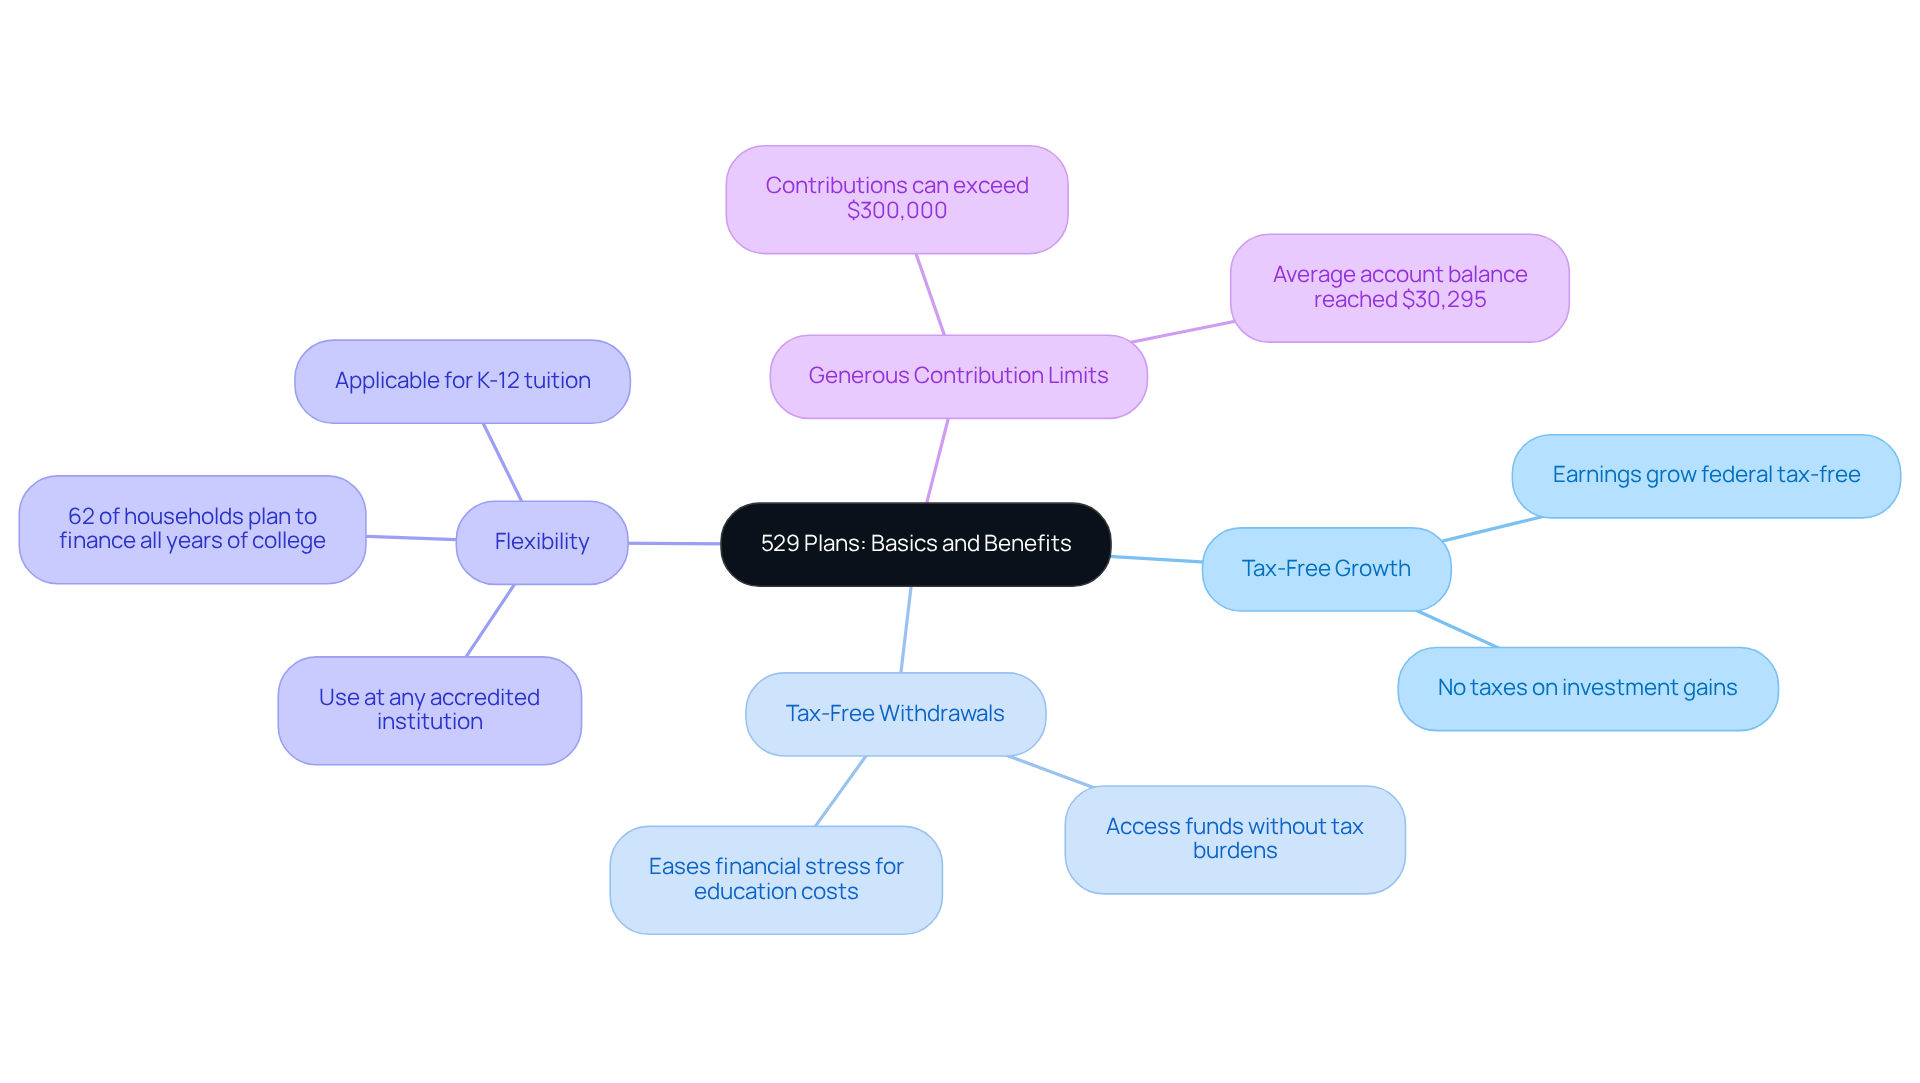
- Tax-Free Growth: Your earnings in a 529 plan grow federal tax-free. This means you won’t have to worry about taxes on investment gains as long as the funds are used for qualified education expenses. It’s a wonderful way to optimize your savings over time.
- Tax-Free Withdrawals: When it’s time to access your funds for qualifying educational expenses, you can do so without any extra tax burdens. This can ease the financial stress when those bills come due.
- Flexibility: You can use these funds at any accredited college or university. Plus, many states allow the use of 529 funds for K-12 tuition, giving you versatile options for your child’s educational journey.
- Generous Contribution Limits: With 529 accounts, you can save significant sums for education. Many programs allow contributions exceeding $300,000, which can greatly alleviate the financial strain of college costs.
As we look ahead to 2025, more families are recognizing the importance of 529 accounts. In fact, 62% of households plan to finance all years of college before their child even enrolls. This proactive approach highlights a growing awareness of effective education savings strategies. Financial advisors emphasize the importance of tax-free growth in 529 accounts and often discuss whether 529 plans are tax deductible, noting that the average account balance has reached $30,295. This can be a tremendous help when it comes to covering college tuition expenses.
Real-life stories show that families using 529 accounts can successfully manage their education savings, making informed choices that align with their financial goals. Understanding these fundamentals is essential for parents as they navigate their options for .
Together, we can navigate this journey and ensure that your child has the best opportunities for their future.
Explore Tax Deductibility: Federal and State Perspectives
At the federal level, it is important to note that [529 plans are not tax deductible](https://irs.gov/newsroom/529-plans-questions-and-answers). But here’s the silver lining: the real advantage comes from [tax-free growth and withdrawals](https://brightadvisers.com/?p=11115) for qualified education expenses. Many states offer tax deductions or credits for contributions made to in-state 529 accounts, which can really boost your savings potential. Let’s explore some key points together:
- Federal Tax Treatment: Contributions are made with after-tax dollars. Although many wonder if 529 plans are tax deductible, the earnings grow tax-free, allowing families to accumulate savings more efficiently.
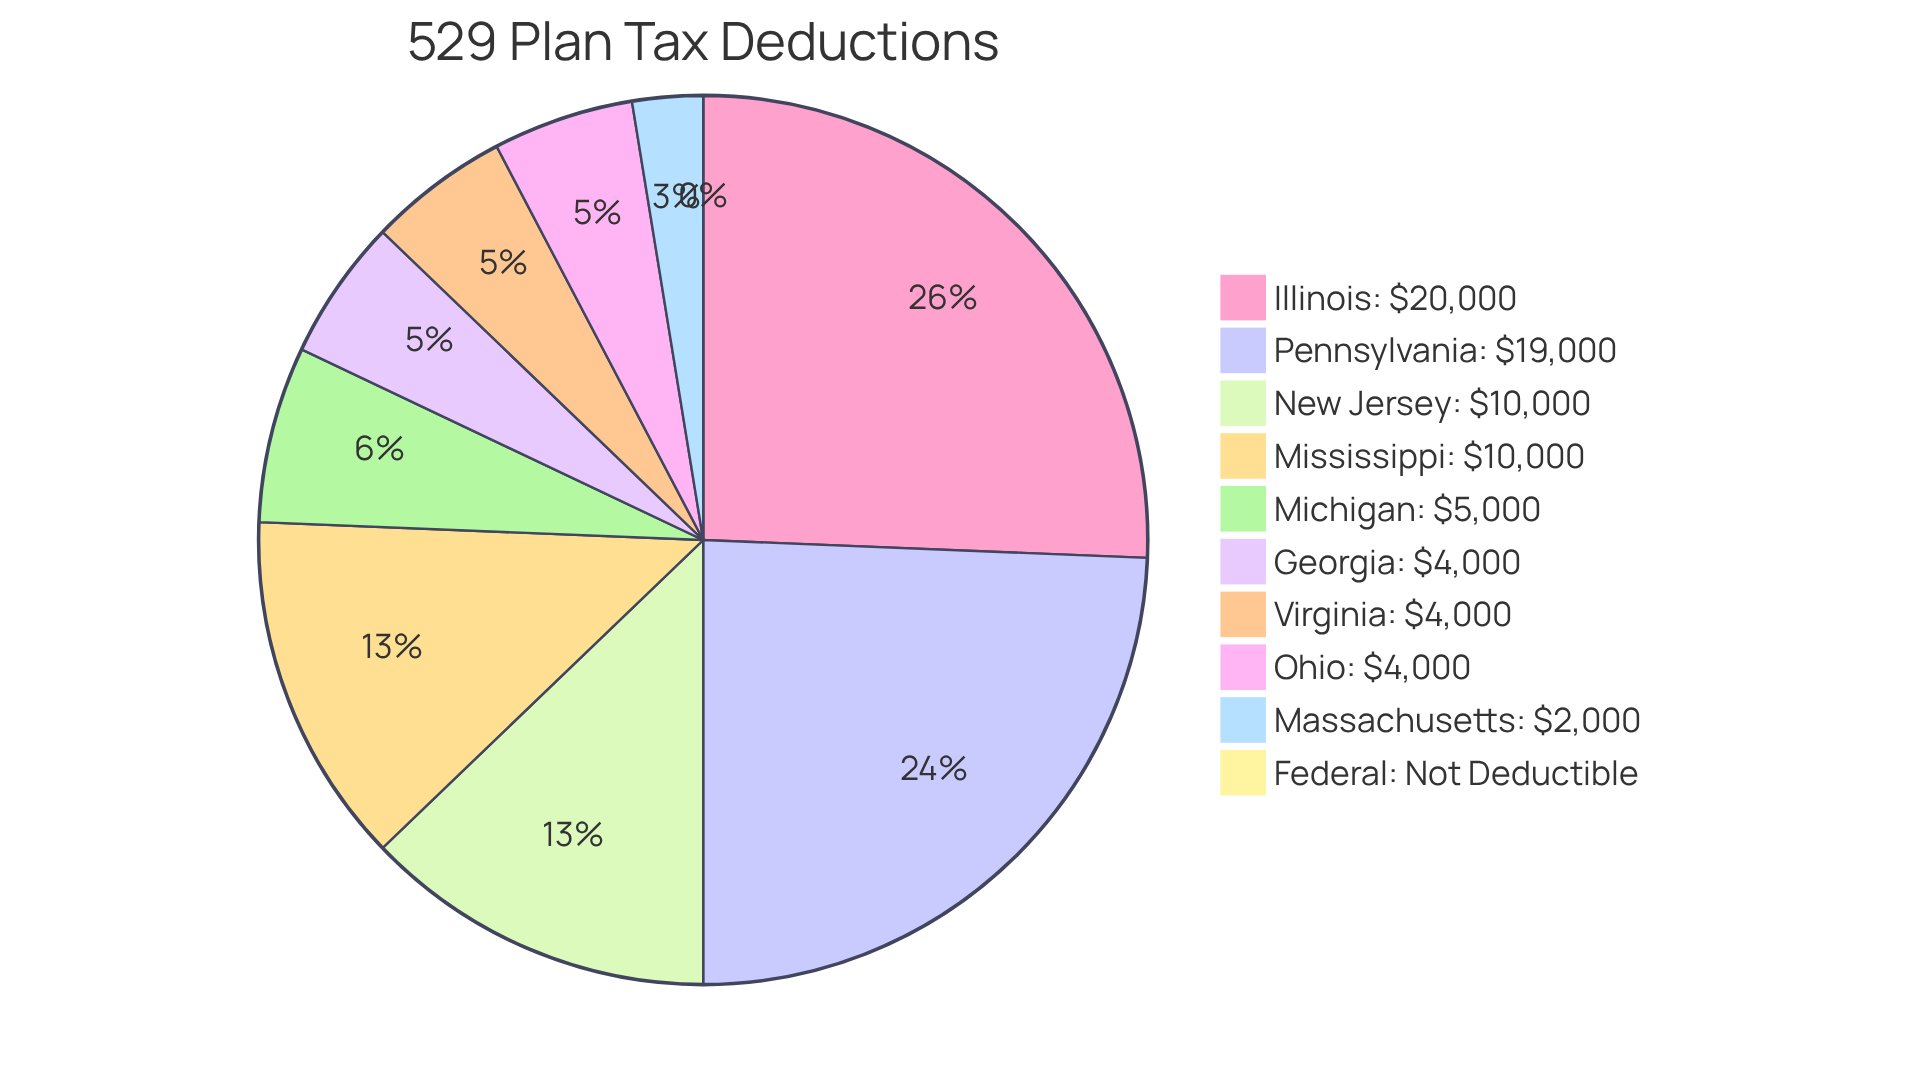
- State Tax Benefits: Depending on where you live, you might qualify for a state income tax deduction or credit. For example, Georgia allows single filers to deduct up to $4,000 per beneficiary, while Virginia permits deductions of up to $4,000 per account each year for joint filers. These deductions can lead to significant tax savings.
- State-Specific Rules: Each state has its own regulations regarding tax benefits, so it’s essential to review your state’s specific rules to maximize your tax advantages. For instance, Pennsylvania provides joint filers a deduction of up to $19,000 per beneficiary, making 529 accounts even more appealing for families focused on education savings.
- Real-World Examples: Families using 529 plans have shared how much they’ve benefited from state tax deductions. For instance, households in Illinois can deduct up to $20,000 for joint filers, encouraging more contributions and ultimately leading to greater educational savings.
Understanding these can help families navigate their education savings journey effectively. Together, we can make informed decisions that align with your financial goals, ensuring a brighter future for your loved ones.
Assess Eligibility: Steps to Determine Your Tax Benefits
Navigating the world of tax benefits, especially regarding whether 529 plans are tax deductible, can feel overwhelming, but we’re here to help you every step of the way. Let’s explore how you can make the most of these opportunities for your family.
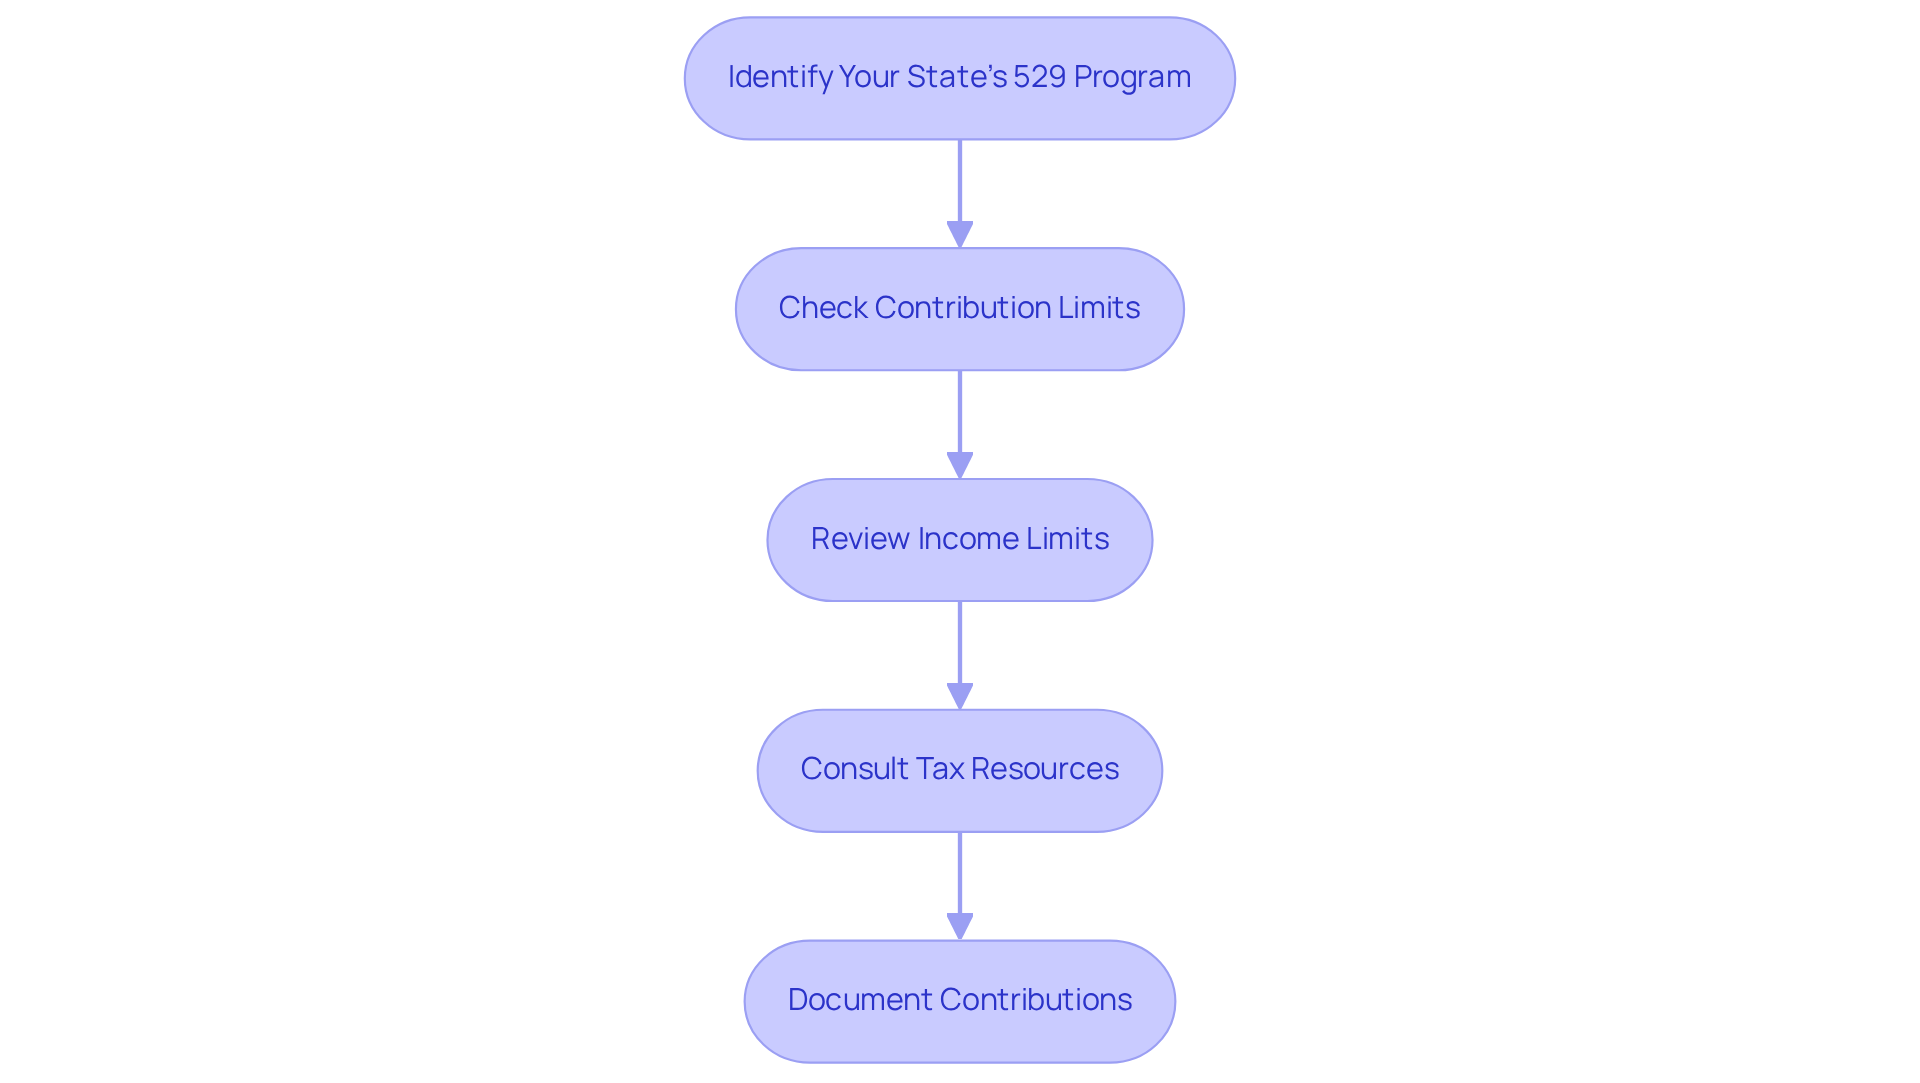
- Identify Your State’s 529 Program: Start by looking into your state’s 529 program options. Did you know that nearly 40 states offer tax deductions or credits for contributions, and that contributions to 529 plans are tax deductible? It is crucial to understand whether 529 plans are tax deductible and the specific benefits available in your state for maximizing your savings.
- Check Contribution Limits: Each state has its own contribution limits for tax deductions. For example, Virginia allows deductions of up to $4,000 per account per year, while Colorado permits deductions of up to $20,700 per taxpayer per beneficiary, which raises the question of how 529 plans are tax deductible. Make sure your contributions stay within these limits to qualify for those valuable deductions.
- Review Income Limits: Some states set income limits for tax deductions. Take New Jersey, for instance, where filers with a gross income of $200,000 or less can benefit from a deduction. It’s important to verify if your income level affects your eligibility for deductions or credits regarding whether 529 plans are tax deductible.
- Consult Tax Resources: Don’t hesitate to utilize state tax resources or consult a tax professional. They can clarify any uncertainties regarding your eligibility for deductions or credits. A tax professional can provide insights on how contribution limits impact your tax situation and whether 529 plans are tax deductible. For example, in New York, possible yearly tax savings for 529 contributions can reach $5,000 ($10,000 if married filing jointly).
- Document Contributions: Keeping accurate records of your contributions is essential. This ensures you can on your state tax return, including if 529 plans are tax deductible. For instance, Ms. Jones, who contributed $8,000 for her two children, successfully deducted this amount on her Virginia state income tax return, benefiting from the state’s specific tax regulations. Also, remember that total lifetime contribution limits for 529 accounts generally vary from $235,000 to $621,411 for each beneficiary.
By following these steps, you can effectively manage the intricacies of 529 accounts and optimize your tax advantages. Together, we can navigate this journey and secure a brighter financial future for your family.
Maximize Benefits: Strategies for Contributions and Withdrawals
To maximize the benefits of your 529 plan, consider these thoughtful strategies:
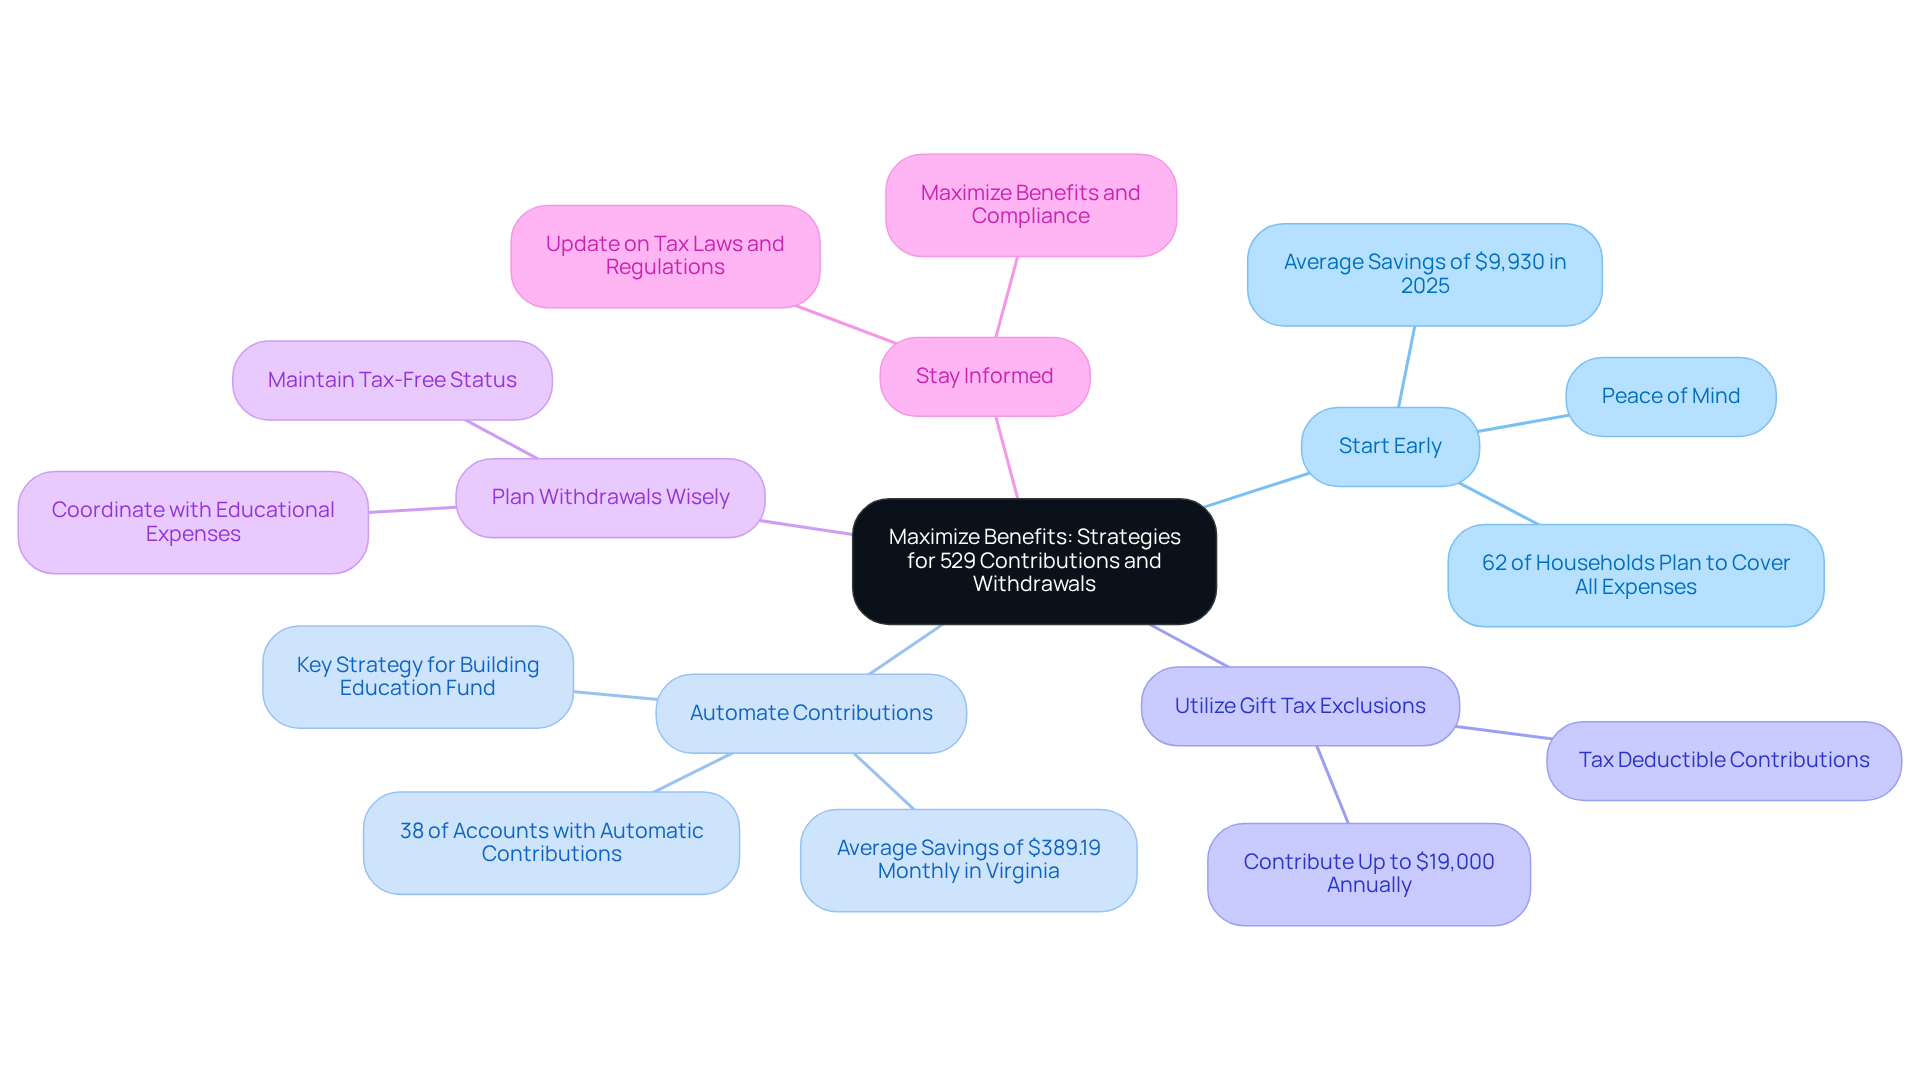
- Start Early: Imagine the peace of mind that comes with starting contributions to a 529 plan as soon as possible. This allows your investments to grow tax-free over time. In 2025, a survey revealed that 62% of households planned to cover all college expenses before their child enrolled, underscoring the importance of early financial planning. Parents reported an average savings of $9,930 in a 529 account in 2025, highlighting the proactive approach many families are taking.
- Automate Contributions: It’s important to simplify your savings process. Setting up automatic contributions can significantly enhance your savings. As of December 2024, 38% of 529 accounts were receiving automatic contributions, showing a growing trend among families. For instance, families with Virginia 529 accounts saved an average of $389.19 monthly in the first half of 2024, demonstrating how automation can lead to substantial savings over time. Financial advisors emphasize that automating contributions is a key strategy for building a robust education fund.
- Utilize Gift Tax Exclusions: Take advantage of the gift tax exclusion by contributing up to $19,000 per year (or $38,000 for married couples) without incurring gift taxes. This strategy can significantly enhance your account balance, especially considering how 529 plans are tax deductible, helping you reach your goals faster.
- Plan Withdrawals Wisely: It’s crucial to coordinate your withdrawals with educational expenses to maintain tax-free status. Ensure that withdrawals correspond with qualified expenses incurred in the same calendar year to maximize the tax benefits, especially considering how 529 plans are tax deductible.
- Stay Informed: Regularly updating yourself on changes in tax laws and 529 account regulations is essential. This ensures you are maximizing your benefits and complying with all requirements. Financial advisors emphasize that starting early with 529 plans, which are 529 plans tax deductible, is vital for building a strong education fund, allowing for greater growth potential and flexibility in managing future expenses.
Together, we can navigate this journey, .
Conclusion
Understanding the intricacies of 529 plans is essential for parents who want to secure their children’s educational future. While these plans may not offer federal tax deductions, they shine with significant advantages like tax-free growth and withdrawals for qualified expenses. This unique combination empowers families to maximize their savings potential, making 529 accounts a valuable tool in education financing.
Imagine if you could navigate the complexities of education savings with confidence. Throughout this article, we’ve highlighted the benefits of 529 plans, including their flexibility, generous contribution limits, and state-specific tax incentives. By exploring various state regulations, families can uncover opportunities for deductions that enhance their overall savings strategy. Additionally, practical steps to assess eligibility and maximize contributions emphasize the importance of proactive financial planning in achieving educational goals.
It’s important to understand that leveraging the power of 529 plans requires informed decision-making and strategic planning. By starting early, automating contributions, and staying updated on tax regulations, families can confidently navigate the world of education savings. Embracing these strategies not only ensures a brighter financial future for children but also empowers parents to make the most of their education funding options. Together, we can navigate this journey, ensuring that your family’s educational aspirations become a reality.
Frequently Asked Questions
What is a 529 plan?
A 529 plan is a savings program that allows families to save for educational expenses, including college tuition, K-12 expenses, and certain apprenticeship programs.
What are the main benefits of a 529 plan?
The main benefits of a 529 plan include tax-free growth of earnings, tax-free withdrawals for qualified educational expenses, flexibility in using funds at any accredited institution, and generous contribution limits that can exceed $300,000.
Are the earnings in a 529 plan subject to federal taxes?
No, the earnings in a 529 plan grow federal tax-free, meaning you won’t owe taxes on investment gains as long as the funds are used for qualified education expenses.
Can I withdraw money from a 529 plan without incurring taxes?
Yes, you can withdraw funds from a 529 plan for qualifying educational expenses without facing additional tax burdens.
How flexible is a 529 plan in terms of educational institutions?
Funds from a 529 plan can be used at any accredited college or university, and many states also allow the use of 529 funds for K-12 tuition.
What are the contribution limits for a 529 plan?
Many 529 programs allow contributions exceeding $300,000, providing families with the ability to save significant amounts for education.
How prevalent are 529 plans among families planning for college expenses?
As of 2025, 62% of households plan to finance all years of college before their child enrolls, indicating a growing awareness of effective education savings strategies.
What is the average account balance for 529 plans?
The average account balance for 529 plans has reached $30,295, which can significantly help cover college tuition expenses.
Why is it important for parents to understand 529 plans?
Understanding 529 plans is essential for parents as they navigate their options for funding their children’s education and making informed financial choices.
List of Sources
- Understand 529 Plans: Basics and Benefits
- Release: 529 Plan Program Statistics, December 2024 | Investment Company Institute (https://ici.org/research/stats/529s/529s_24_q4)
- 529 College Savings Plan Statistics | BestColleges (https://bestcolleges.com/research/529-college-savings-plan-statistics)
- College Saving Statistics [2025]: Average Savings & 529 Balance (https://educationdata.org/college-savings-statistics)
- Report: More U.S. families choosing 529 plans to save for college – Utah System of Higher Education (https://ushe.edu/report-more-u-s-families-choosing-529-plans-to-save-for-college)
- 9 Reasons a 529 Plan Is Worth It and 7 Reasons It’s Not (Plus the Best Alternatives) (https://annuityexpertadvice.com/reasons-529-plan-is-worth-it-and-reasons-its-not)
- Explore Tax Deductibility: Federal and State Perspectives
- 529 Tax Deductions by State [2025]: Rules on Tax Benefits (https://educationdata.org/529-tax-deductions-by-state)
- State Section 529 Deductions – Finaid (https://finaid.org/savings/state529deductions)
- 529 Plans: Questions and answers | Internal Revenue Service (https://irs.gov/newsroom/529-plans-questions-and-answers)
- 10 States with 529 Tax Benefits Every Young Parent Should Know – Bright Advisers (https://brightadvisers.com/10-states-with-529-tax-benefits-every-young-parent-should-know)
- How Much is Your State’s 529 Tax Deduction Really Worth for 2026? | Research.com (https://research.com/student-loans/how-much-is-your-states-529-tax-deduction-really-worth)
- Assess Eligibility: Steps to Determine Your Tax Benefits
- Maximum 529 Plan Contribution Limits by State (https://savingforcollege.com/article/maximum-529-plan-contribution-limits-by-state)
- Tax Benefits of a 529 Plan | Learn | Invest529 (https://invest529.com/529-basics/tax-benefits)
- Tax strategies for college savings and gifting (https://ameriprise.com/financial-goals-priorities/education-planning/529-plan-tax-benefits)
- 529 Tax Deductions by State [2025]: Rules on Tax Benefits (https://educationdata.org/529-tax-deductions-by-state)
- How Much Is Your State’s 529 Plan Tax Deduction Really Worth? (https://savingforcollege.com/article/how-much-is-your-state-s-529-plan-tax-deduction-really-worth)
- Maximize Benefits: Strategies for Contributions and Withdrawals
- 529 College Savings Plan Statistics | BestColleges (https://bestcolleges.com/research/529-college-savings-plan-statistics)
- Release: 529 Plan Program Statistics, December 2024 | Investment Company Institute (https://ici.org/research/stats/529s/529s_24_q4)
- 529 Plan Statistics | The Motley Fool (https://fool.com/research/529-plan-statistics)
- College Saving Statistics [2025]: Average Savings & 529 Balance (https://educationdata.org/college-savings-statistics)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Tax Management for high-income W-2 families at Bright Advisers.
Keep reading