

Key Highlights:
- 529 plans are tax-advantaged savings accounts designed to help families save for future education costs.
- There are two main types of 529 accounts: college savings programmes and prepaid tuition programmes.
- 529 plans offer tax-free growth and tax-free withdrawals for qualified educational expenses.
- As of 2026, families can contribute up to $20,000 per student annually for K-12 tuition without tax penalties.
- Qualified expenses include tuition, fees, room and board, books, and certain educational materials.
- Withdrawals for non-qualified expenses may incur taxes and penalties.
- 529 accounts are considered parental assets for financial aid purposes, generally having a minimal impact on aid eligibility.
- Recent changes allow grandparent-owned 529 withdrawals to not affect student financial aid eligibility.
- Taxpayers saved approximately $2 billion in federal income tax in 2017 by utilising 529 college savings accounts.
Introduction
Navigating the complexities of funding your child’s education can feel daunting. But 529 plans shine as a guiding light, offering a tax-advantaged way to save for future educational expenses while delivering significant financial benefits.
Imagine if you could set aside money for your child’s future without the burden of taxes weighing you down. As the landscape of educational funding shifts, it’s crucial to understand how to truly maximize the advantages of these tax-free accounts. What should you keep in mind to ensure you’re making the most of your 529 plans?
We’re here for you, ready to help you explore the possibilities and ease your worries. Together, we can navigate this journey toward securing a brighter future for your family.
Define 529 Plans: An Overview of Their Purpose and Structure
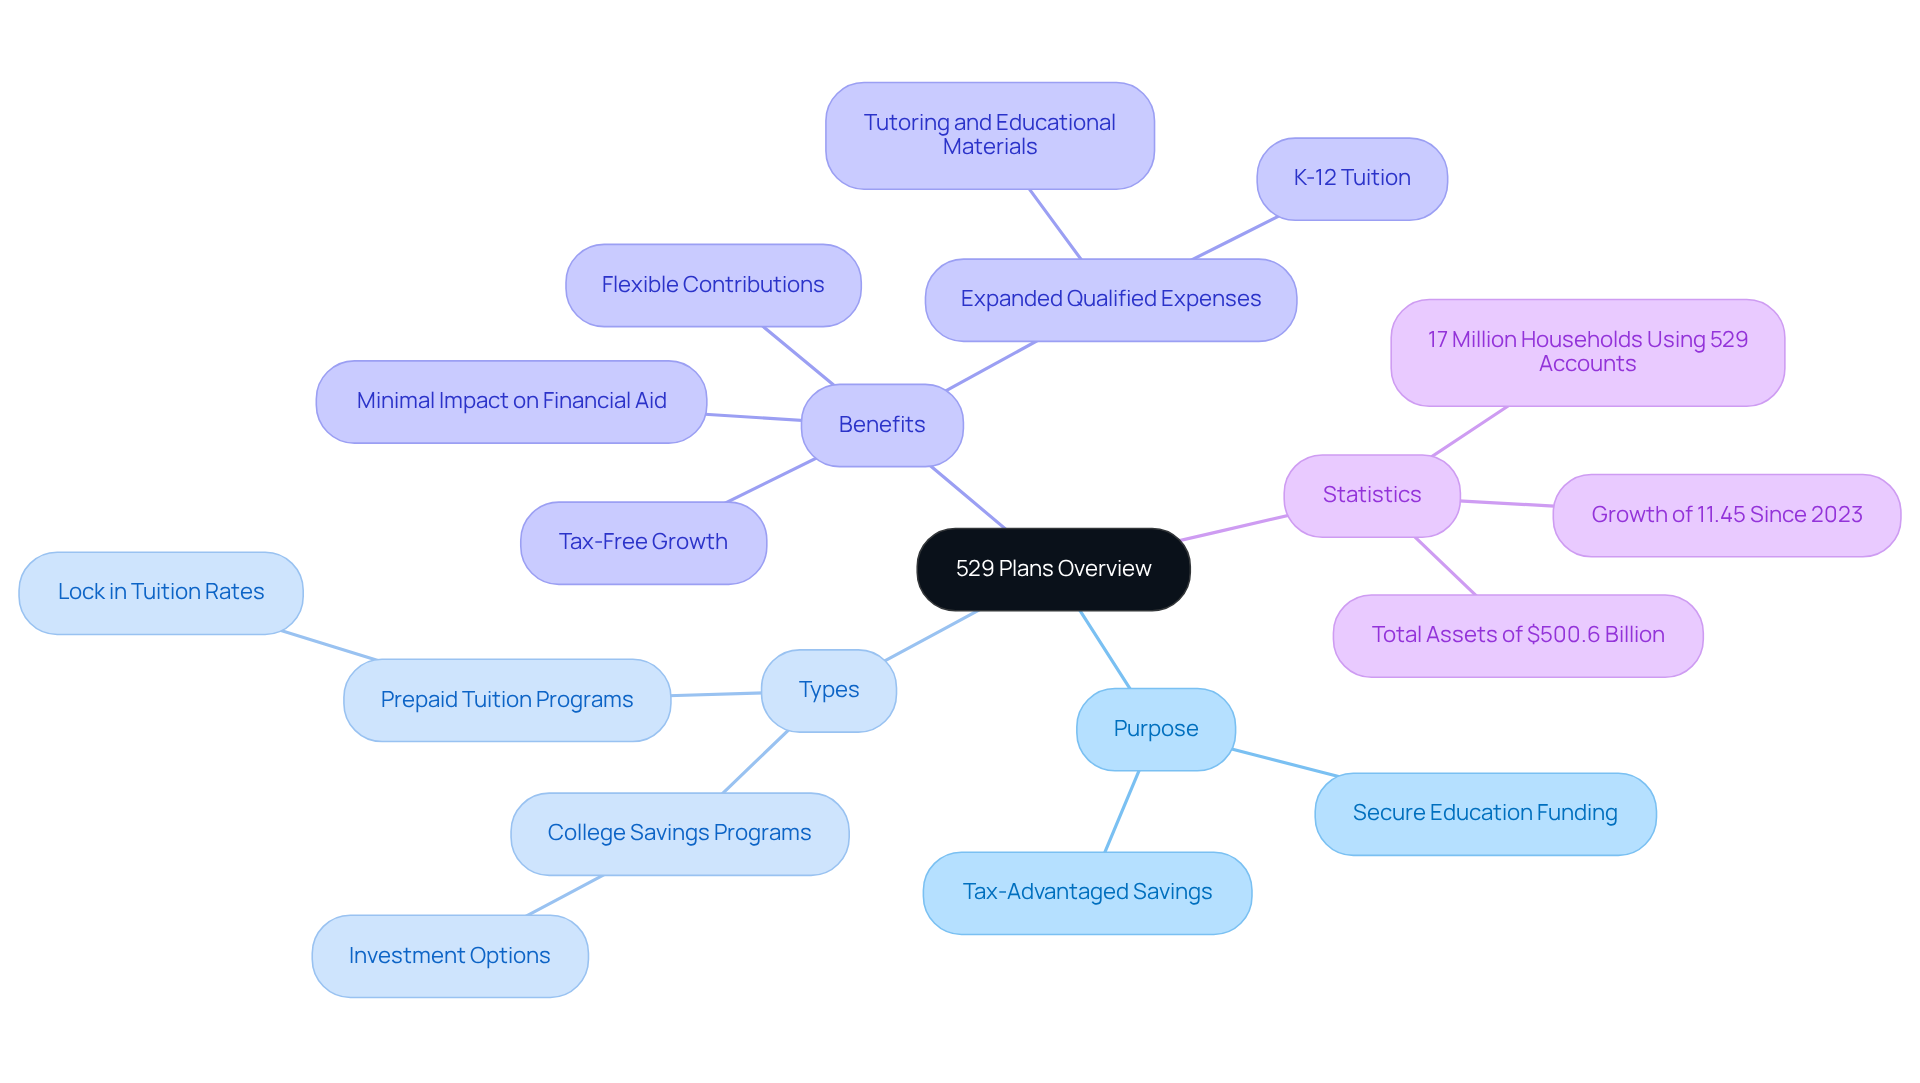
Imagine a future where your child’s education is secure, and you can breathe a little easier. A 529 program is a tax-advantaged savings account designed just for that purpose-helping families save for future education costs, and importantly, 529 plans are tax free. Established under Section 529 of the Internal Revenue Code, these programs are typically sponsored by states or educational institutions. There are two main types of 529 accounts:
- College savings programs, which allow families to invest in various options.
- Prepaid tuition programs, which let families lock in current tuition rates at qualifying colleges.
The primary goal of a 529 program is to provide a flexible and effective way to save for educational expenses, including college tuition, K-12 costs, and other approved educational expenditures, all while enjoying significant tax benefits.
As we look ahead to 2026, nearly 17 million households are utilizing 529 accounts for their education savings. This growing trend in educational financial planning shows that families are taking proactive steps to secure their children’s futures. These accounts, which are 529 plans tax free, allow for tax-free growth of investments and enable tax-free withdrawals for eligible expenses, making them an attractive option for families focused on education. For instance, families can withdraw up to $10,000 each year without tax for K-12 tuition, and the recent expansion of qualified expenses now includes tutoring and educational materials, further enhancing the value of 529 accounts.
At Bright Advisers, we understand the financial pressures that young families like Jay and Emma face when planning for their children’s education while also preparing for their own retirement. Financial advisors emphasize the importance of 529 accounts in educational savings strategies. Contributions to these plans are considered completed gifts for tax purposes, allowing families to contribute up to five times the annual gift tax exemption in a single year without incurring tax penalties. This flexibility, combined with the ability to change beneficiaries and the minimal impact on financial aid assessments, makes 529 options a vital resource for families navigating the complexities of education funding. Plus, our commitment to low fund fees enhances the accessibility of these options, ensuring that families can maximize their savings potential while easing financial stress.
Together, we can navigate this journey toward . We’re here for you, ready to support you every step of the way.
Explore Tax Advantages: How 529 Plans Offer Tax-Free Growth and Withdrawals
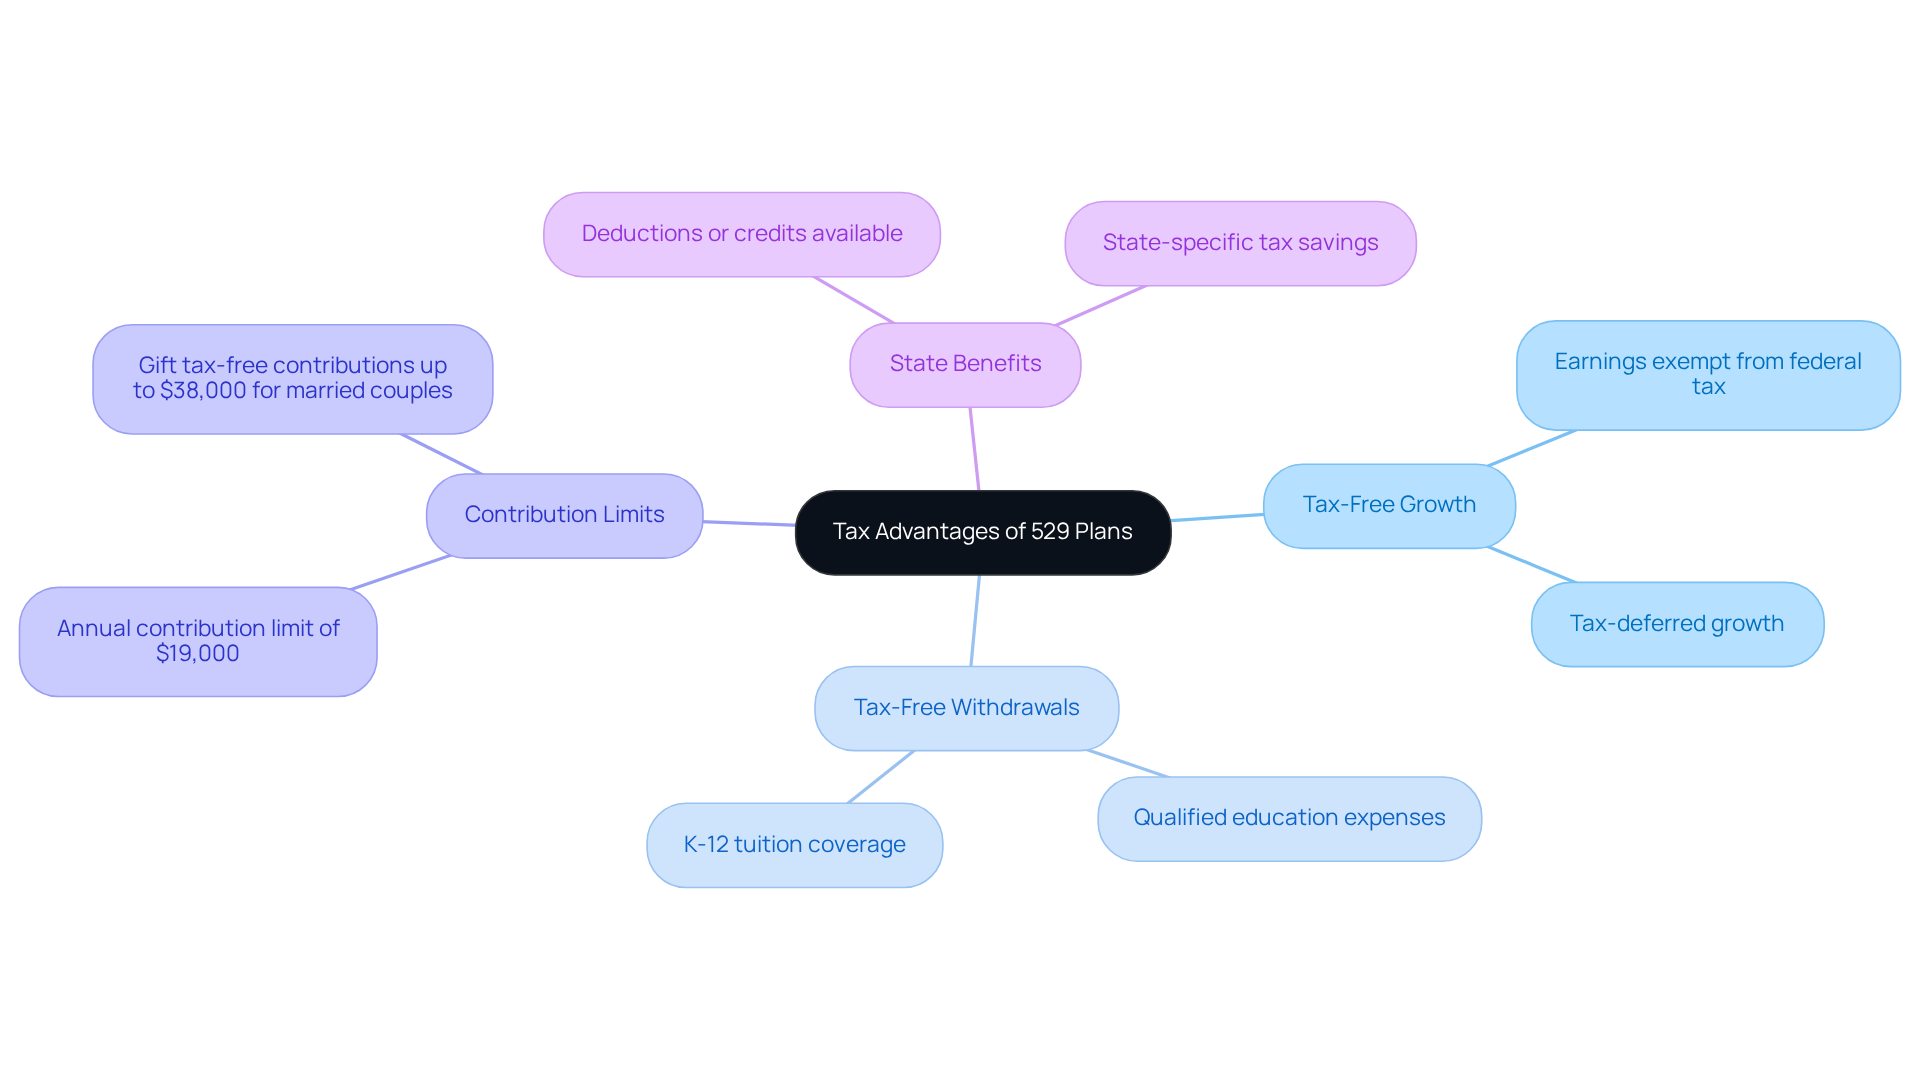
Imagine a future where your child’s education is secure and stress-free. One of the most compelling aspects of 529 options is that they are 529 plans tax free, providing significant tax benefits that can greatly ease financial worries for families like Jay and Emma. Earnings in a 529 account, including interest, dividends, or capital gains, are 529 plans tax free, meaning they are exempt from federal income tax as long as they remain in the account. Plus, when you withdraw funds for qualified education expenses-covering tuition, fees, books, and even room and board for college, as well as K-12 tuition costs-those withdrawals are 529 plans tax free.
As we look ahead to 2026, contributions up to $19,000 annually, or $38,000 for married couples, will be exempt from gift tax. This makes these options even more appealing for families planning for their children’s future. Many states also offer tax deductions or credits for contributions made to a 529 account, further enhancing the financial benefits for households. In fact, taxpayers saved around $2 billion in federal income tax in 2017 by utilizing 529 college savings accounts.
The fact that 529 accounts offer tax-free growth and withdrawals raises the question of whether are 529 plans tax free, positioning them as a powerful resource for long-term educational savings. It enables families to maximize their investment in their children’s future, ensuring they have the opportunities they deserve. At Bright Advisers, we understand the importance of these decisions. We’re dedicated to , making our wealth management solutions accessible and efficient for individuals like you, who are aiming to secure a bright financial future for your family. Together, we can navigate this journey.
Identify Qualified Expenses: What You Can Fund with a 529 Plan
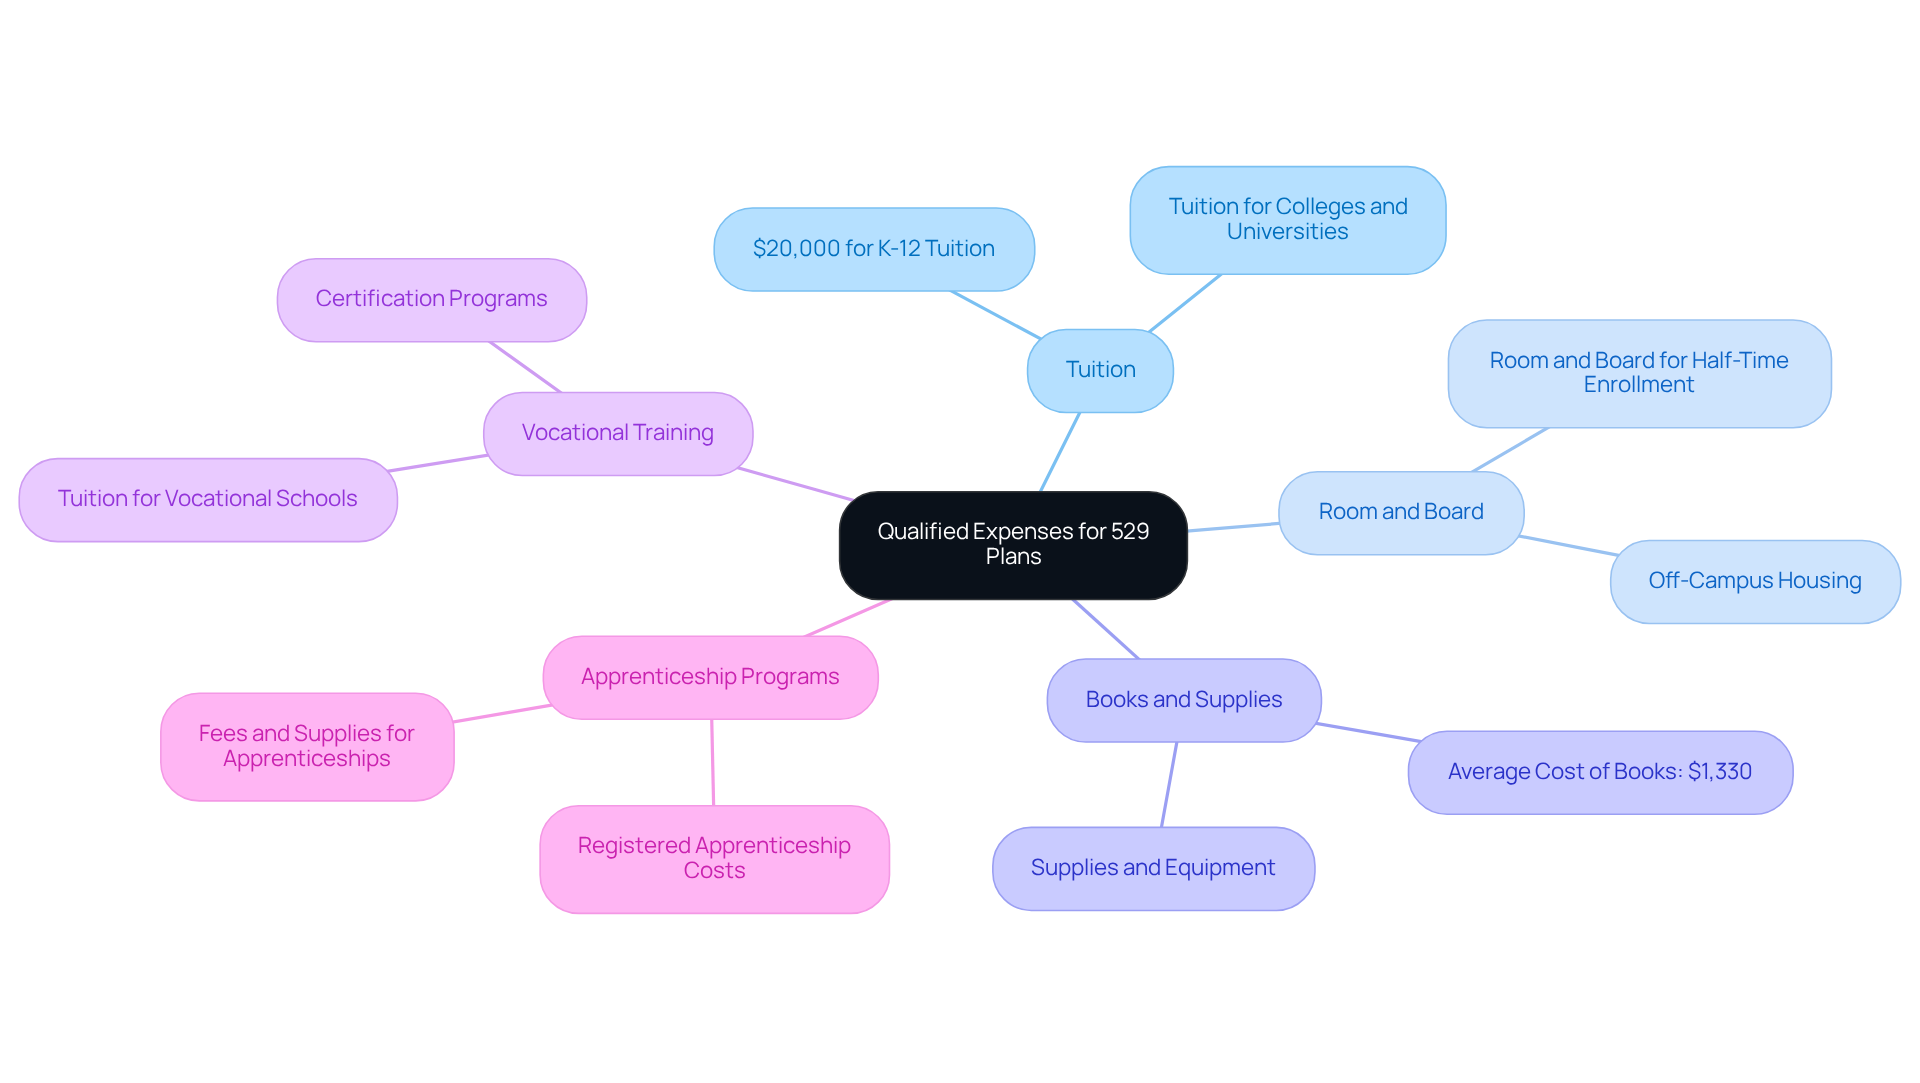
Imagine a world where your child’s education is within reach, no matter the path they choose. One of the benefits of 529 accounts, which are 529 plans tax free, is that they can be a significant asset for families, covering a wide range of educational expenses. From tuition and required fees at colleges, universities, and vocational schools, these accounts are designed to support your family’s educational journey.
Starting in 2026, families can set aside up to $20,000 per student each year for K-12 tuition costs. This flexibility means you can adapt your financial planning to meet your child’s needs as they grow. Plus, 529 funds can also help with room and board for students enrolled at least half-time, along with books, supplies, and necessary equipment for their courses.
It’s important to understand that if you withdraw funds from a 529 account for non-qualified educational expenses, those amounts will be taxed as ordinary income and may incur a 10% federal penalty, unless exceptions apply, despite the fact that 529 plans are tax free when used correctly. Recent changes in legislation have expanded the range of qualified costs, now including expenses related to apprenticeship programs and specific educational materials. This means you can utilize 529 accounts not just for traditional education but also for and certification programs.
We encourage you to consult with a tax expert or your 529 program administrator to ensure that your expenses qualify. This way, you can effectively support your child’s educational journey. Understanding the typical costs of books and supplies-around $1,330 for on-campus undergraduate students during the 2025-2026 academic year-can also help you plan your budget more effectively.
Together, we can navigate this journey, ensuring that your family’s educational goals are met with confidence and care.
Assess Financial Aid Impact: How 529 Plans Affect Eligibility and Aid Packages
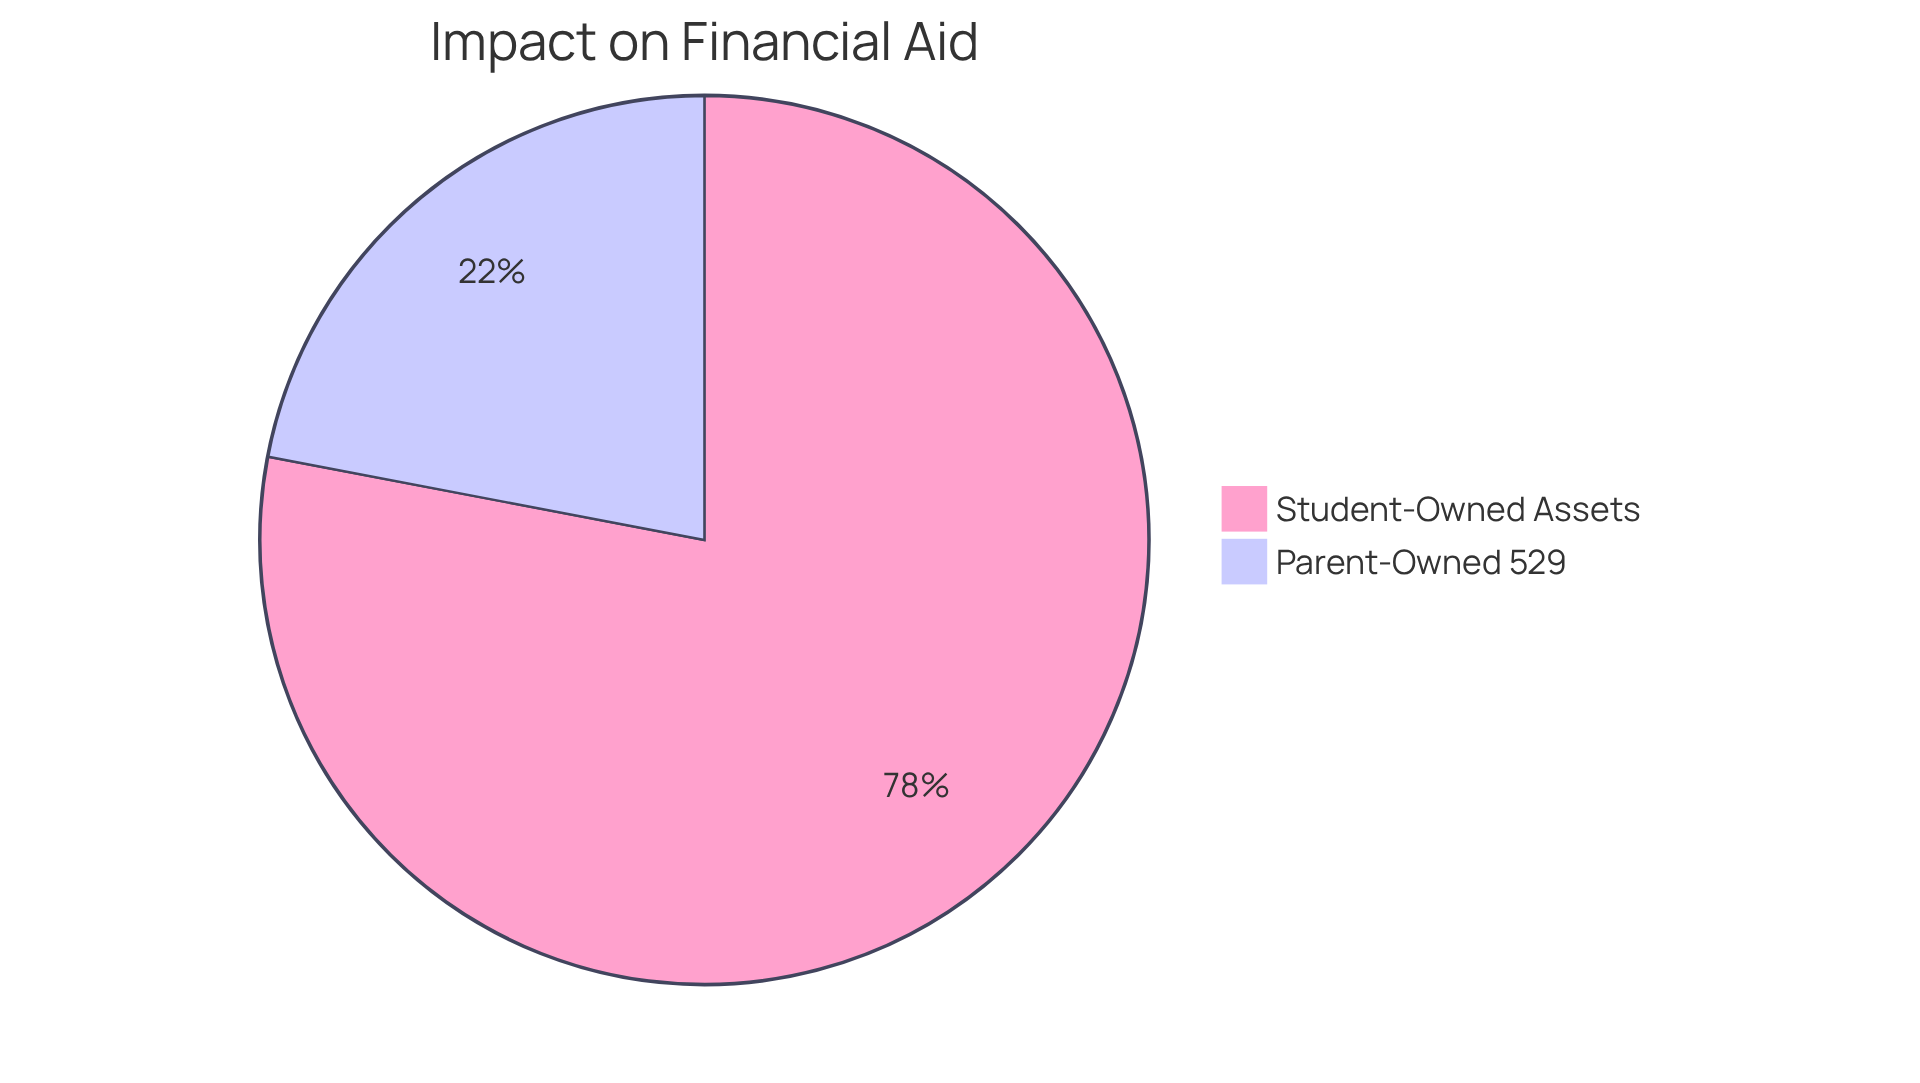
529 accounts play a crucial role in determining financial aid eligibility, especially since they’re classified as parental assets on the FAFSA (Free Application for Federal Student Aid). This classification is beneficial, as it leads to a more favorable assessment compared to student-owned assets, which can negatively impact need-based financial aid. For instance, if you have a 529 account worth $10,000, it might reduce your aid eligibility by about $564, reflecting a maximum assessment rate of 5.64% of the account’s value.
Imagine the relief for families with recent legislative changes that have refined how 529 accounts are treated, particularly those owned by grandparents. Starting in the 2024-25 academic year, withdrawals from grandparent-owned 529 accounts won’t be reported as untaxed student income on the FAFSA. This means grandparents can contribute to college expenses without worrying about hurting a student’s financial aid eligibility. It’s a game-changer for families trying to navigate the complexities of financial aid, providing a strategic edge in funding education.
It’s important to understand that the impact of 529 account assets on financial aid evaluations is generally minimal. For example, while a $10,000 balance in a parent-owned 529 account may reduce need-based assistance by $564, student-owned non-529 assets can decrease aid by as much as $2,000 due to their higher assessment rate of 20%. Understanding these nuances is vital for families as they plan for . Together, we can navigate this journey, ensuring you maximize your financial resources while minimizing the impact on aid eligibility.
Conclusion
Understanding the details of 529 plans is crucial for securing a brighter educational future for your children. These tax-advantaged accounts not only help you save for various educational expenses but also offer significant financial relief through tax-free growth and withdrawals. By taking advantage of 529 plans, you can navigate the complexities of educational funding with greater confidence and ease.
Imagine being able to cover a wide range of qualified expenses – from college tuition to K-12 costs and even tutoring. 529 accounts are designed to adapt to the ever-changing educational landscape, making them a flexible choice for families. Plus, the favorable treatment of these accounts in financial aid assessments means you can maximize your resources while minimizing the impact on aid eligibility.
Embracing the potential of 529 plans is a meaningful step toward achieving your child’s educational dreams. We encourage you to explore these options thoroughly, consult with financial advisors, and understand the specific benefits that align with your unique circumstances. Together, we can navigate this journey, ensuring that your financial planning effectively supports your children’s educational paths and paves the way for a successful future.
Frequently Asked Questions
What is a 529 plan?
A 529 plan is a tax-advantaged savings account designed to help families save for future education costs, including college tuition and K-12 expenses.
What are the two main types of 529 accounts?
The two main types of 529 accounts are college savings programs, which allow families to invest in various options, and prepaid tuition programs, which enable families to lock in current tuition rates at qualifying colleges.
What are the tax benefits associated with 529 plans?
529 plans offer tax-free growth of investments and allow for tax-free withdrawals for eligible educational expenses, making them an attractive option for families focused on education.
How much can families withdraw from a 529 plan for K-12 tuition without incurring taxes?
Families can withdraw up to $10,000 each year for K-12 tuition without incurring taxes.
What recent expansions have been made to the qualified expenses for 529 plans?
Recent expansions include qualified expenses for tutoring and educational materials, enhancing the value of 529 accounts.
How do contributions to 529 plans affect tax purposes?
Contributions to 529 plans are considered completed gifts for tax purposes, allowing families to contribute up to five times the annual gift tax exemption in a single year without incurring tax penalties.
What flexibility do 529 plans offer regarding beneficiaries?
529 plans allow families to change beneficiaries, providing flexibility in how the funds can be used.
What is the impact of 529 plans on financial aid assessments?
529 plans have a minimal impact on financial aid assessments, making them a vital resource for families navigating education funding.
How do low fund fees benefit families using 529 plans?
Low fund fees enhance the accessibility of 529 options, ensuring that families can maximize their savings potential while easing financial stress.
List of Sources
- Define 529 Plans: An Overview of Their Purpose and Structure
- Navigating 529 Plans: 11 Features You Need To Know (https://merceradvisors.com/insights/personal-finance/navigating-529-plans-11-features-you-need-to-know)
- 6 Benefits of a 529 College Savings Plan (https://merrilledge.com/article/5-hidden-benefits-529-college-savings-plans)
- Pros and Cons of 529 Plans: Is a 529 Right for Your Education Savings? (https://savingforcollege.com/article/what-are-the-pros-and-cons-of-using-a-529-plan)
- Release: 529 Plan Program Statistics, December 2024 | Investment Company Institute (https://ici.org/research/stats/529s/529s_24_q4)
- The unique benefits of 529 college savings plans (https://thetaxadviser.com/issues/2023/may/the-unique-benefits-of-529-college-savings-plans)
- Explore Tax Advantages: How 529 Plans Offer Tax-Free Growth and Withdrawals
- 9 Reasons a 529 Plan Is Worth It and 7 Reasons It’s Not (Plus the Best Alternatives) (https://annuityexpertadvice.com/reasons-529-plan-is-worth-it-and-reasons-its-not)
- Tax Benefits of a 529 Plan | Learn (https://invest529.com/529-basics/tax-benefits)
- Families using 529 plans save record $2 billion in federal income tax (https://savingforcollege.com/article/families-using-529-plans-save-record-2-billion-in-federal-income-tax)
- College Saving Statistics [2025]: Average Savings & 529 Balance (https://educationdata.org/college-savings-statistics)
- Report: More U.S. families choosing 529 plans to save for college – Utah System of Higher Education (https://ushe.edu/report-more-u-s-families-choosing-529-plans-to-save-for-college)
- Identify Qualified Expenses: What You Can Fund with a 529 Plan
- What 529 Plans Cover | Qualified Expenses | Invest529 (https://invest529.com/529-basics/qualified-expenses)
- 529 Basics | The Education Plan (https://theeducationplan.com/basics/529-qualified-expenses)
- Assess Financial Aid Impact: How 529 Plans Affect Eligibility and Aid Packages
- Does a 529 Plan Affect Financial Aid? (https://savingforcollege.com/article/yes-your-529-plan-will-affect-financial-aid)
- Will a 529 Plan Affect Financial Aid Eligibility or Amount Awarded? (https://smartasset.com/student-loans/will-529-plan-affect-financial-aid)
- Impact on Financial Aid | Invest529 (https://invest529.com/529-basics/impact-on-financial-aid)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Tax Management for high-income W-2 families at Bright Advisers.
Keep reading