

Overview
Mutual funds can seem complex, especially when it comes to taxes. While they offer the potential for tax deferral within accounts like IRAs and 401(k) plans, it’s important to know that capital gains distributions and dividends are taxed in the year they are received.
Imagine if you could postpone tax payments on your returns. Families can truly benefit from tax-deferred accounts, allowing for more time to grow their investments. However, navigating the taxable events from mutual fund investments requires strategic planning.
It’s essential to approach this with care. By understanding the tax implications, you can make informed decisions that align with your family’s financial goals. We’re here for you, guiding you through these complexities, ensuring that you can manage your investments effectively. Together, we can navigate this journey toward financial security.
Key Highlights:
- Mutual funds pool capital from various investors to invest in a diversified portfolio managed by professionals.
- Understanding mutual funds is essential for families, particularly regarding tax deferral, which allows delaying tax payments on gains until withdrawal.
- Mutual funds can lead to taxable events through capital gains distributions and dividends, which are taxed in the year they are distributed.
- Short-term capital gains are taxed at higher rates (up to 37%), while long-term gains are taxed at lower rates (0%, 15%, or 20%).
- Tax-deferred accounts like IRAs and 401(k) plans allow families to invest in mutual funds while postponing taxes on returns until withdrawal.
- Investing in tax-efficient vehicles and managing holding periods can help minimise taxes on mutual fund investments.
- Tax-loss harvesting can offset gains, providing a proactive approach to managing tax liabilities.
Introduction
Navigating the world of investments can feel overwhelming, especially for families striving to secure their financial future. Mutual funds present a wonderful opportunity to pool resources and benefit from professional management. However, the complexities of tax implications can leave many feeling uncertain.
Imagine if you could grow your wealth while minimizing immediate tax burdens. This article explores whether mutual funds truly provide tax deferral benefits and how families can leverage these investment vehicles to achieve their financial goals. As you ponder your financial strategies, it’s important to understand the potential tax pitfalls associated with mutual fund investments.
Together, we can navigate this journey, ensuring you feel supported every step of the way.
Define Mutual Funds and Tax Deferral
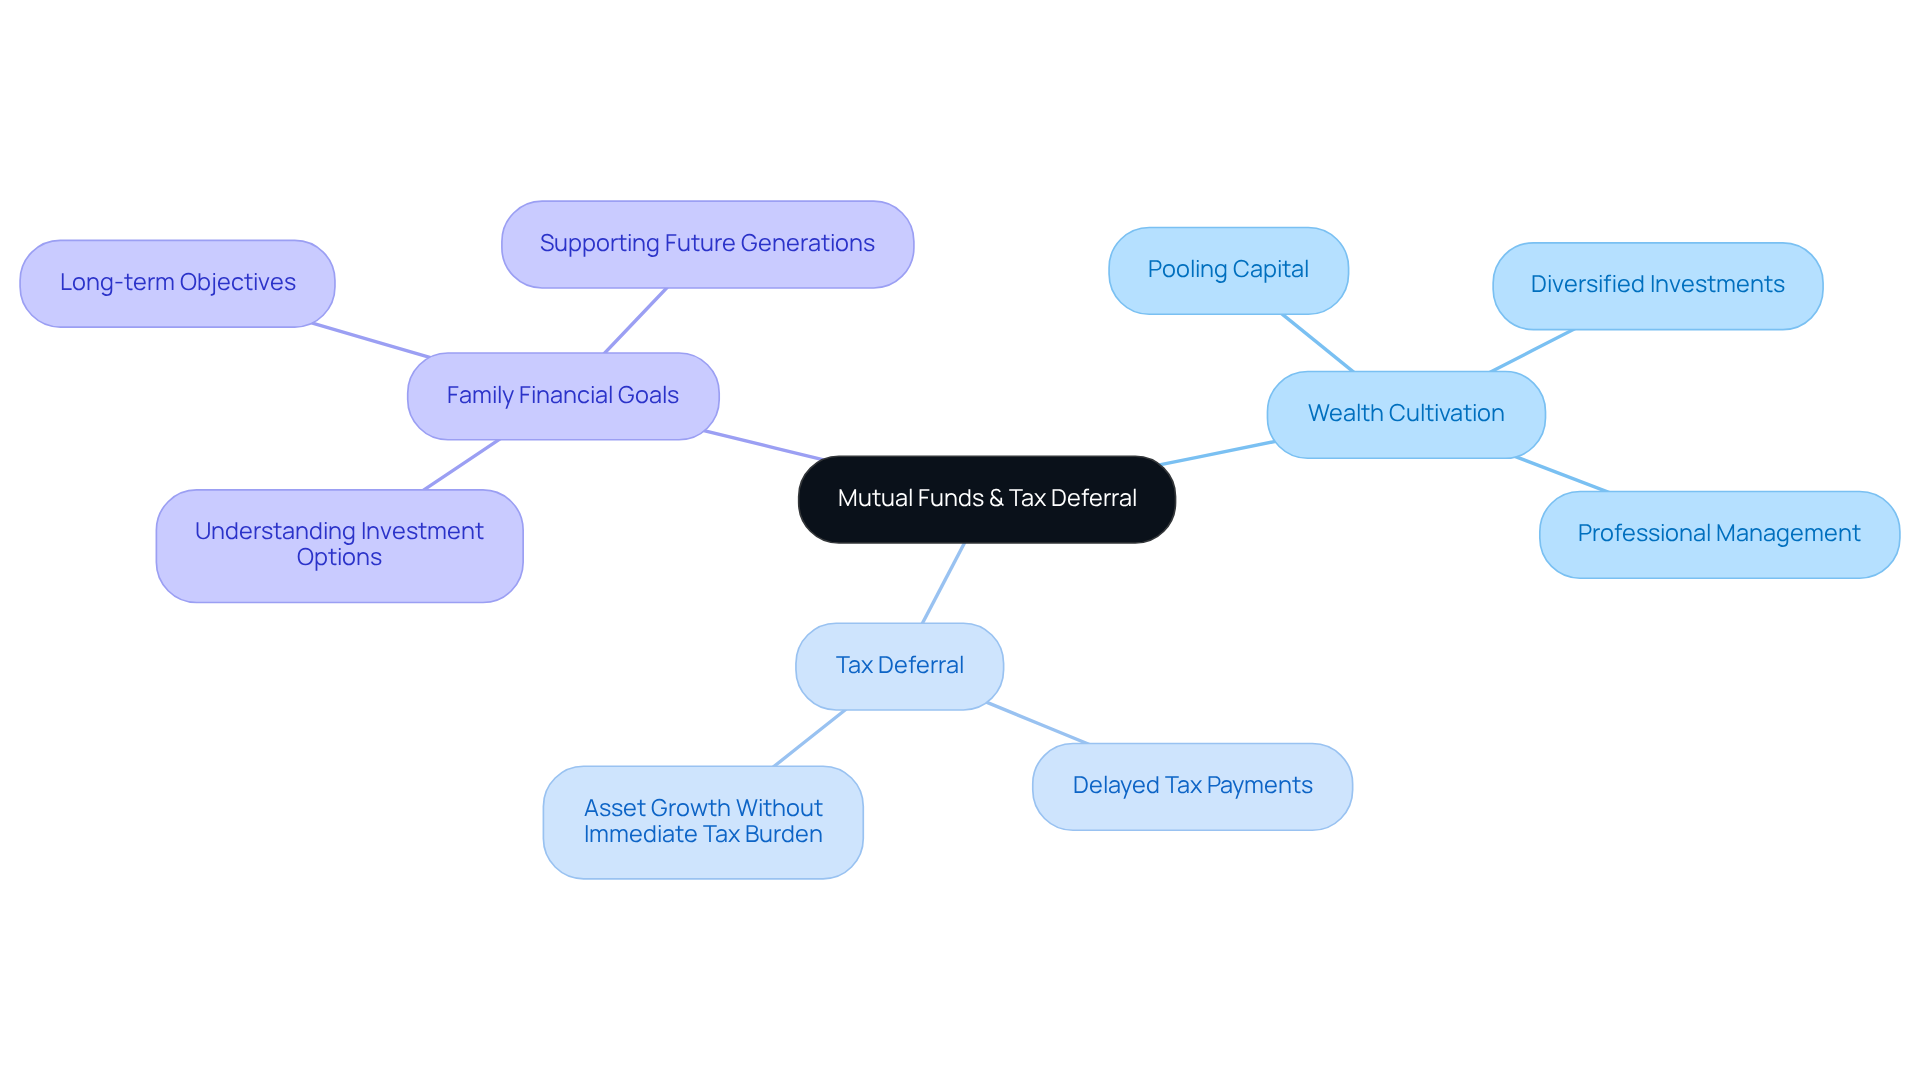
Mutual funds are more than just financial instruments; they represent a pathway for families to cultivate wealth together. By pooling capital from various investors, these funds acquire a diversified collection of stocks, bonds, and other securities, all under the careful guidance of expert portfolio managers. Imagine how reassuring it is to know that professionals are striving to meet your family’s financial goals.
For households with young kids, understanding investment options is essential. These choices symbolize a deliberate approach to building a secure future for your loved ones. It’s important to understand how mutual funds are tax deferred. This concept raises the question of whether mutual funds are tax deferred, allowing you to delay tax payments on profit gains until you withdraw your resources and enabling your family to grow its assets without the immediate tax burden.
This strategy can be incredibly valuable for those seeking to secure their financial future. By utilizing shared investment vehicles and considering how mutual funds are tax deferred, families can align their financial strategies with their core values. This means you’re not just accumulating wealth; you’re doing so in a way that supports your long-term objectives and the well-being of future generations.
Together, we can navigate this journey towards financial security, ensuring that your family’s future is bright and filled with opportunities.
Explain How Mutual Funds Generate Taxable Events
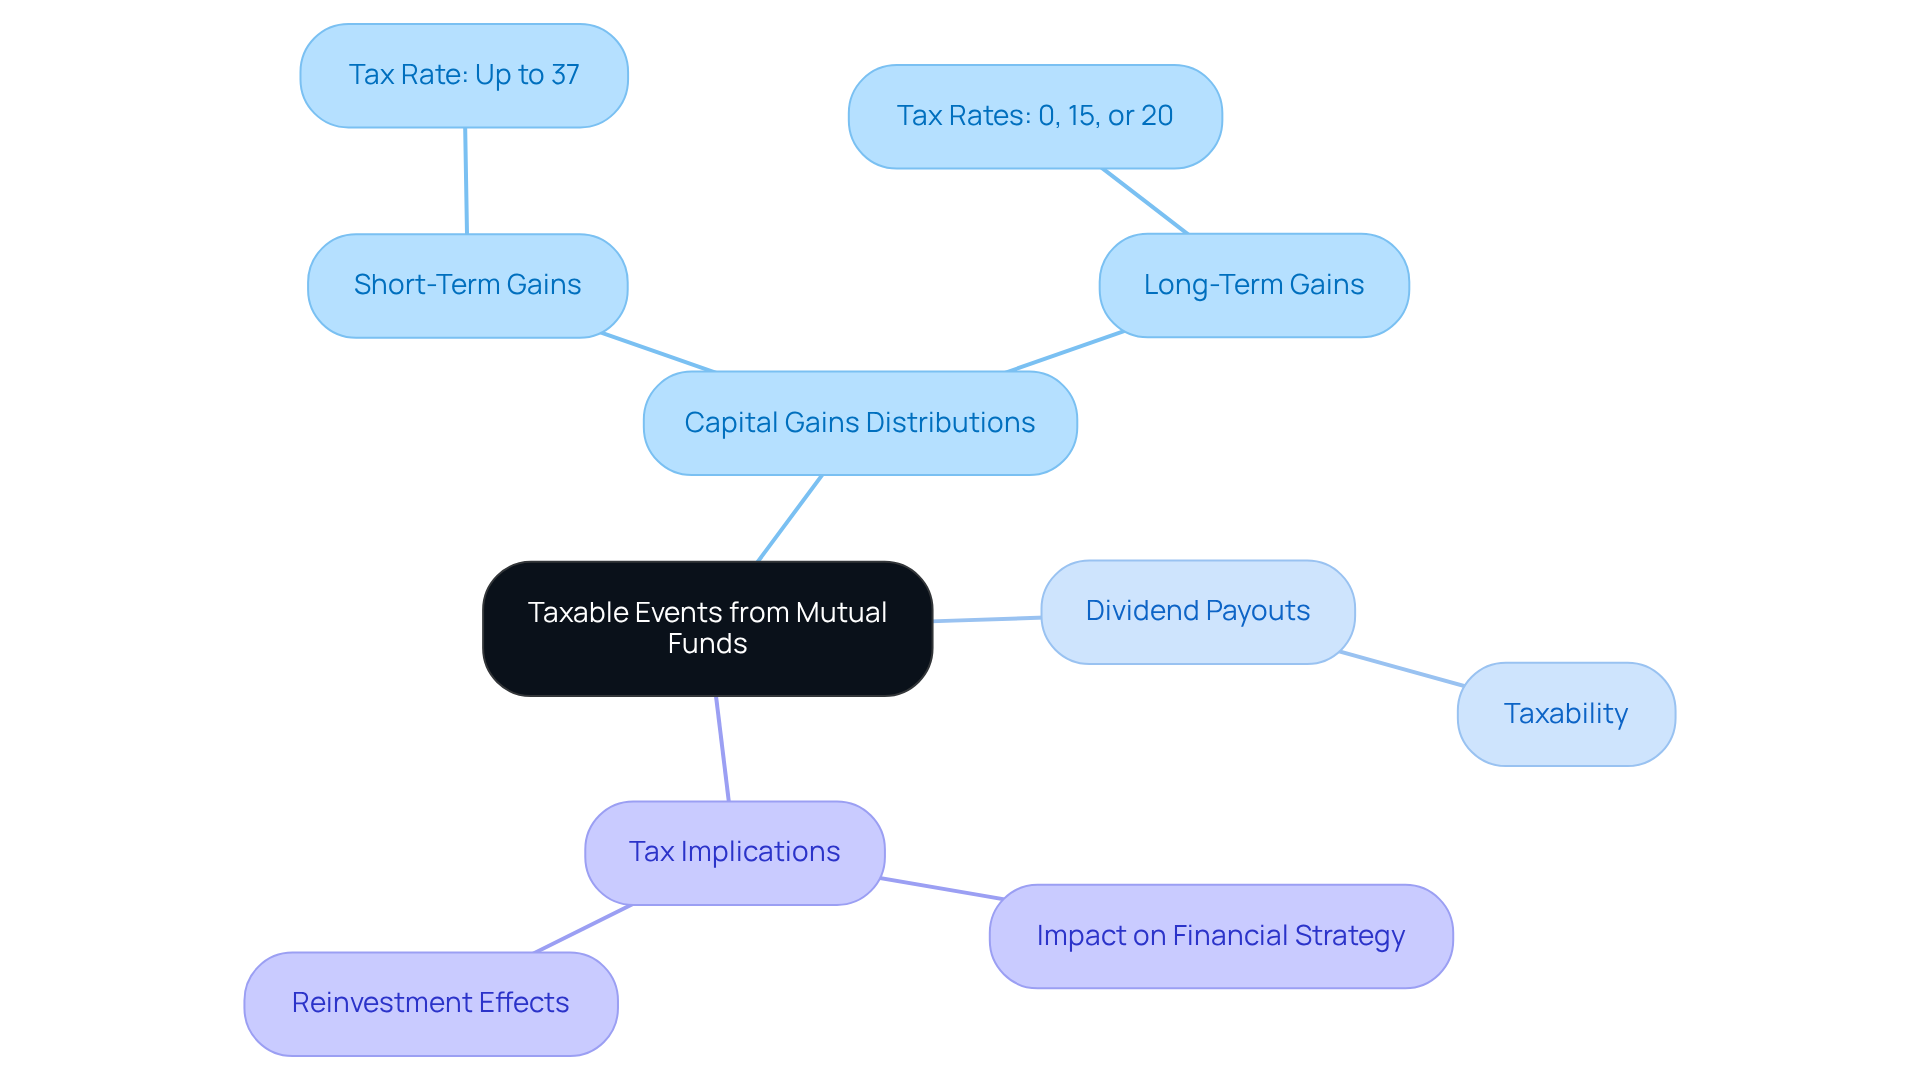
Mutual investments can lead to taxable events, primarily through capital gains distributions and dividend payouts. When a portfolio manager sells securities within the investment for a profit, the resulting capital gains are shared with investors. This means that investors need to pay taxes on these gains in the year they are distributed, even if they opt to reinvest those distributions. As we look ahead to 2025, average capital gains distributions for investment vehicles are expected to reflect the current market dynamics, with many portfolios enjoying significant unrealized gains thanks to the strong performance of global equities over the past decade.
In addition to capital gains, mutual funds may also distribute dividends from the income generated by the underlying securities. These dividends are also subject to taxation, adding another layer of complexity to a household’s financial strategy. For families, understanding these taxable events is crucial for anticipating tax obligations and planning effectively.
Imagine if you’re managing your household assets: it’s important to recognize that short-term capital gains, from securities held for less than one year, can be taxed at rates as high as 37%. In contrast, long-term capital gains, from securities held for over one year, are taxed at 0%, 15%, or 20%, depending on your taxable income. This distinction can significantly impact your overall tax strategy and investment choices, guiding your family’s financial journey.
Furthermore, while capital gains distributions do not affect the overall performance of a portfolio or ETF, the price of the portfolio typically declines by the amount of the distribution after it is issued. This can create opportunities for portfolio rebalancing or meeting cash-flow needs, which families can navigate with the guidance of financial advisors. By understanding these dynamics, you can better manage the complexities of collective investments and enhance your financial planning.
Together, we can navigate this journey, ensuring your family’s financial future is secure and well-planned.
Discuss Benefits of Tax-Deferred Accounts for Mutual Funds
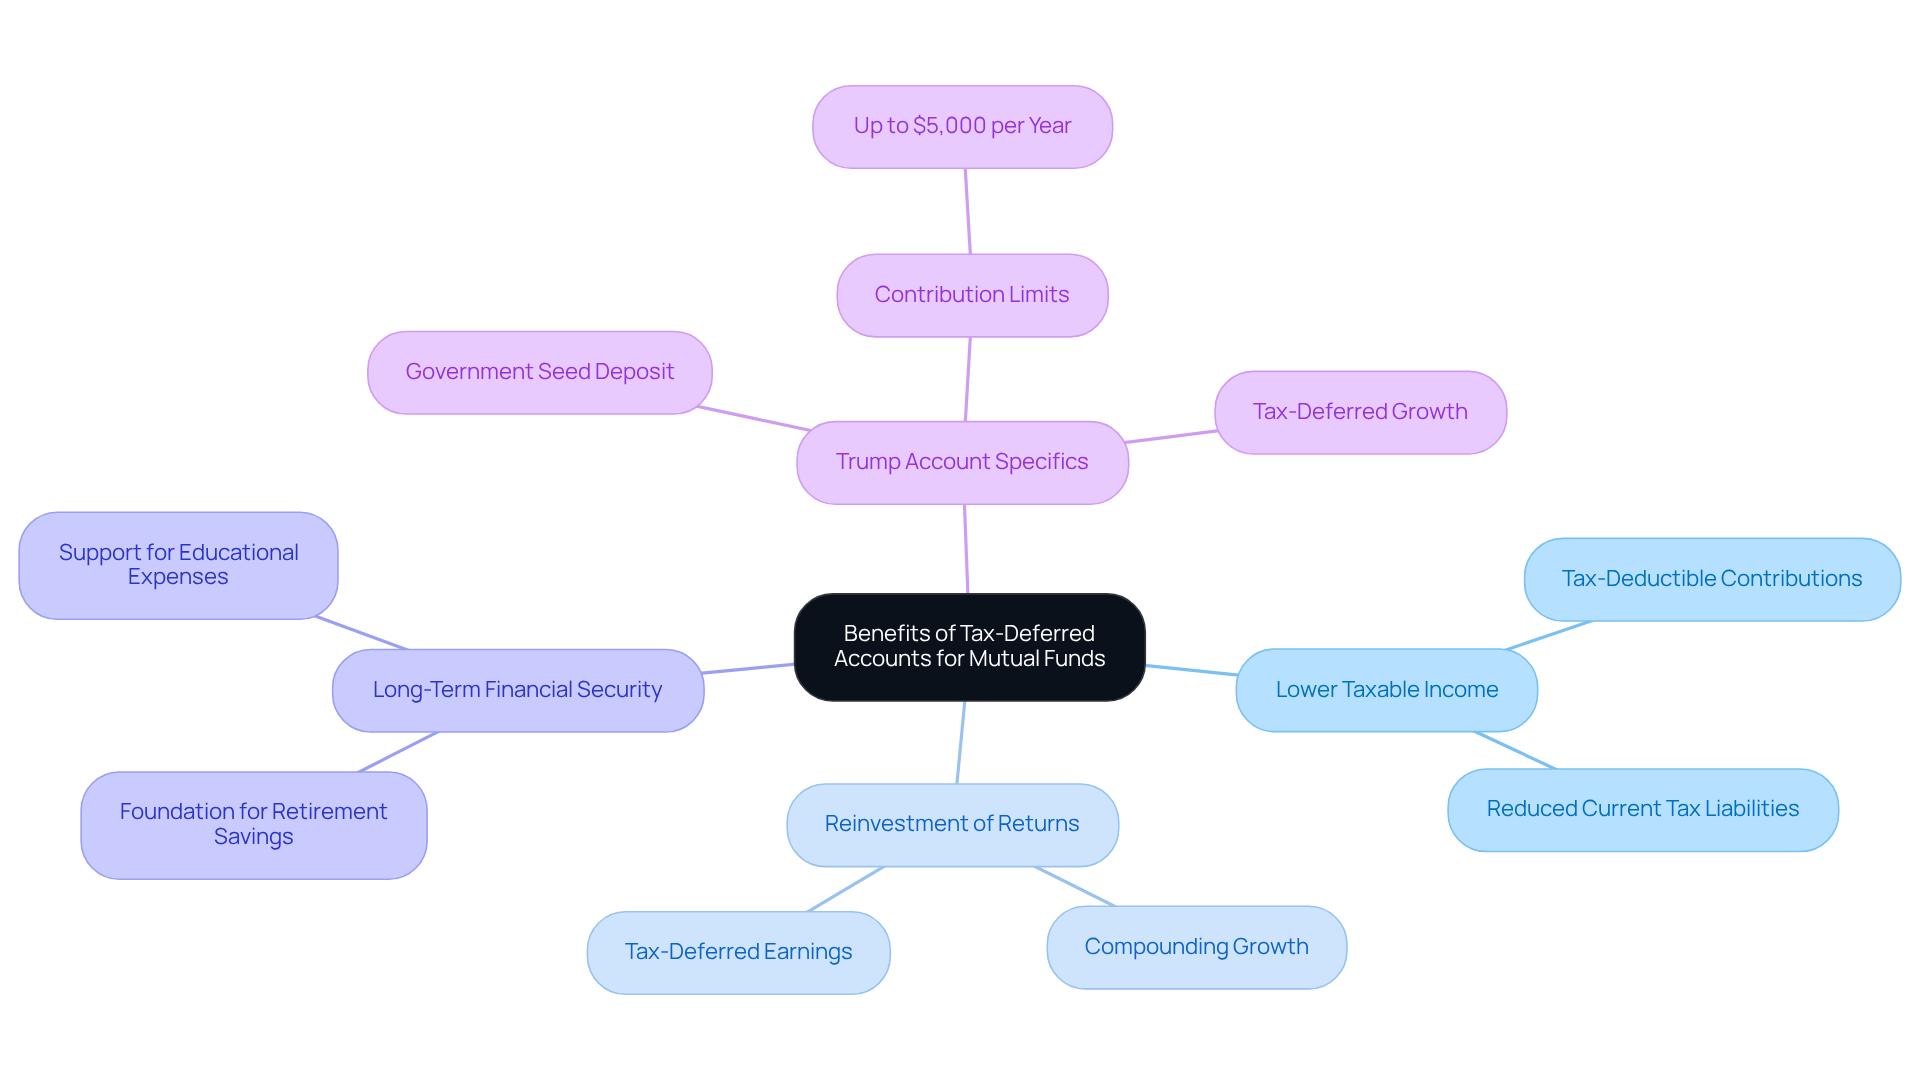
Tax-deferred accounts, like Individual Retirement Accounts (IRAs) and 401(k) plans, can be a wonderful way for families to invest in their future. Imagine being able to contribute to these accounts while potentially lowering your taxable income. Contributions often come with tax-deductible benefits, allowing you to keep more of your hard-earned money. Plus, any returns—such as capital gains and dividends—aren’t taxed until you withdraw them. This means you can reinvest your earnings, nurturing compounding growth over time without the immediate tax burden.
Think about how families using IRAs and 401(k) plans can thoughtfully allocate their investments in mutual assets to meet long-term goals, whether it’s saving for retirement or funding educational expenses. Financial planners often highlight that these accounts not only help reduce current tax liabilities but also lay a strong foundation for future financial security. It’s reassuring to know that a significant portion of retirement savings is held in these tax-deferred accounts, showcasing their effectiveness in building wealth.
In summary, families can invest in mutual assets while improving their tax situation, as mutual funds are tax deferred. Together, we can navigate this journey towards achieving your financial goals and long-term aspirations, knowing that support is always available.
Outline Strategies to Minimize Taxes on Mutual Funds
Are you feeling overwhelmed by the thought of taxes on your mutual investments? You’re not alone. Many families share this concern, and there are ways to ease the burden while nurturing your financial future.
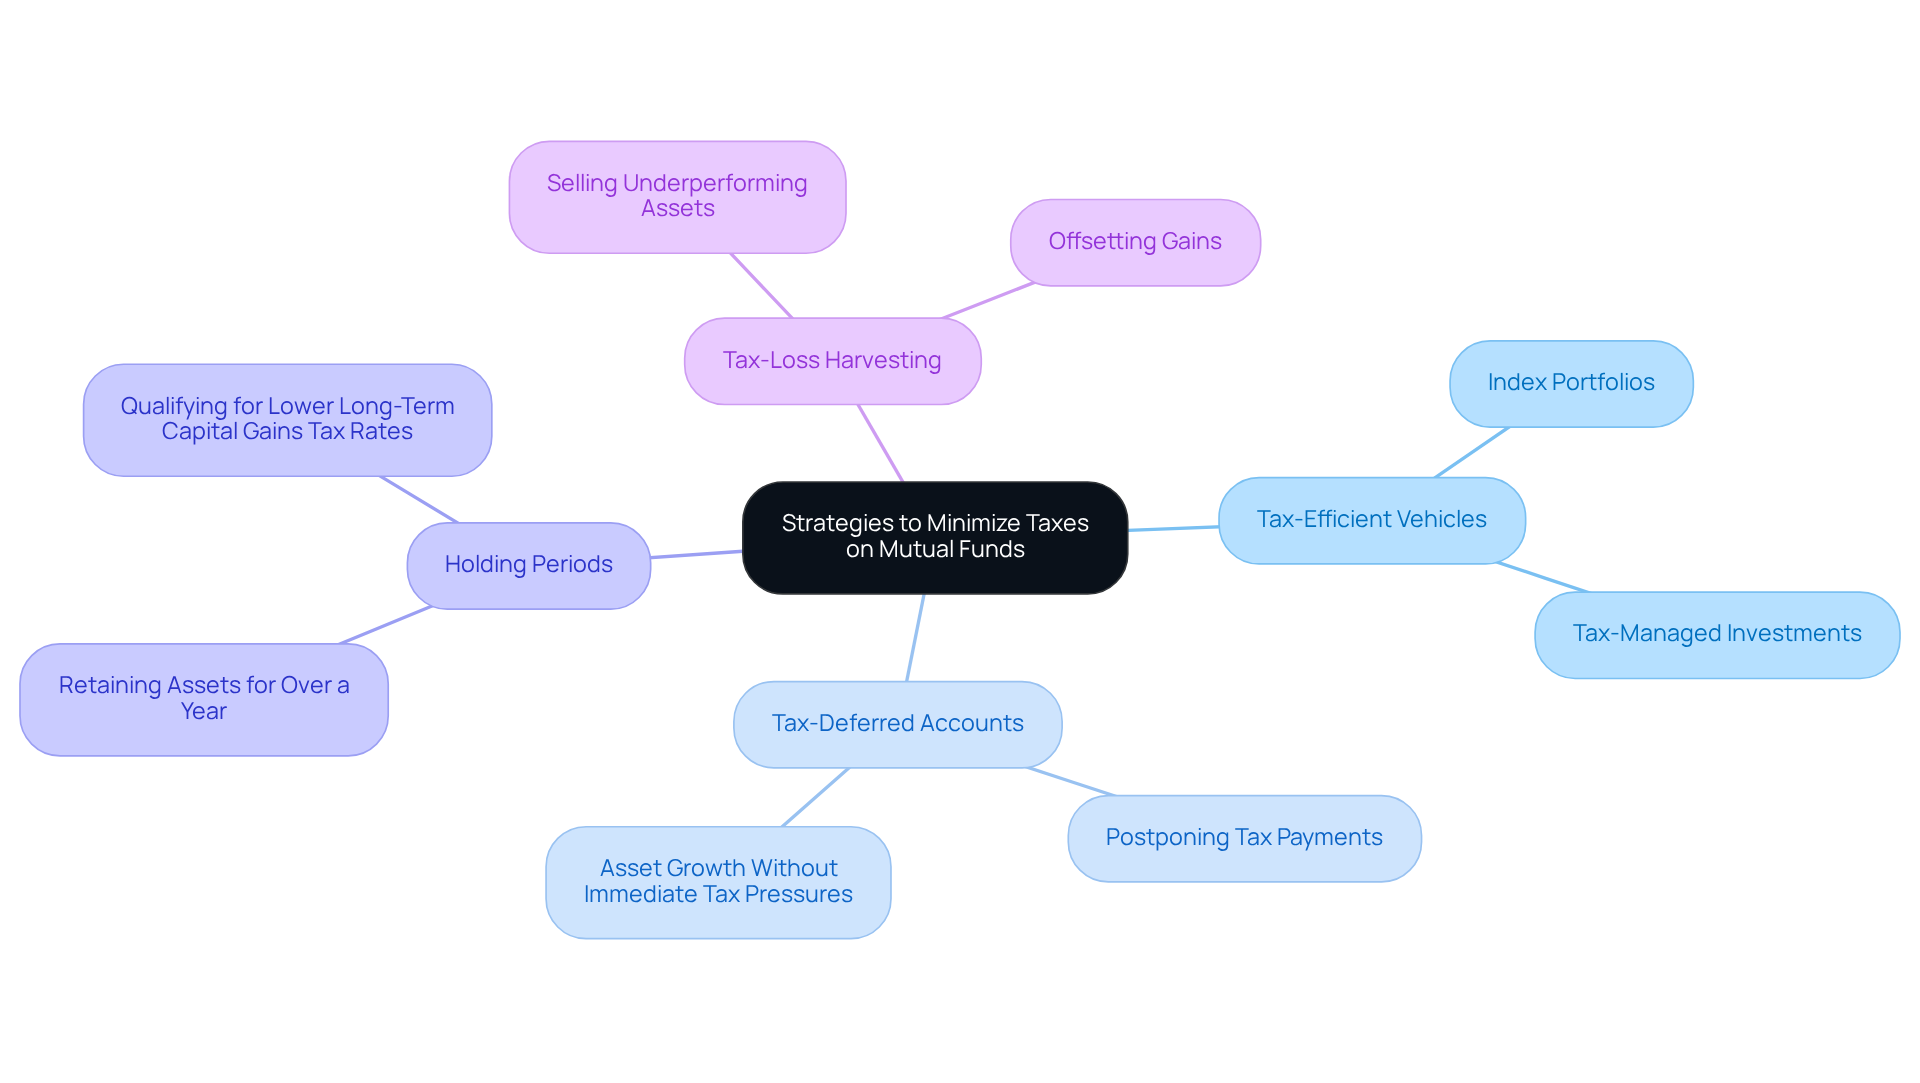
Imagine investing in tax-efficient vehicles, like index portfolios or tax-managed investments. This approach can significantly reduce capital gains distributions, which is crucial for families striving to improve their financial well-being. By choosing these options, you’re not just making investments; you’re making smart choices for your family’s future.
It’s also important to consider if mutual funds are tax deferred for your contributions to tax-deferred accounts. This strategy demonstrates that mutual funds are tax deferred, allowing you to postpone tax payments and giving you the freedom to grow your assets without immediate tax pressures. Think of it as planting seeds for your family’s future without the worry of immediate costs.
Moreover, being mindful of your holding periods can make a significant difference. By retaining assets for over a year, you can qualify for lower long-term capital gains tax rates. This simple shift can enhance your wealth accumulation potential, allowing you to provide more for your loved ones.
Another effective strategy is tax-loss harvesting. This involves selling underperforming assets to offset gains. It’s a proactive way to manage your tax liabilities, ensuring that your family’s financial health remains a priority.
By implementing these strategies and seeking professional guidance, you can enhance your investment outcomes while minimizing tax impacts. Remember, you’re not alone in this journey; together, we can navigate the complexities of financial planning. Let’s empower your family’s financial security and freedom.
Conclusion
Understanding the intricacies of mutual funds and their tax implications is vital for families aiming to secure their financial future. Imagine being able to leverage tax-deferred accounts while recognizing the potential taxable events associated with mutual fund investments. By doing so, families can create a robust financial strategy that aligns with their long-term goals. The ability to delay tax payments allows for greater asset growth, ultimately benefiting future generations.
Key insights discussed include:
- The nature of mutual funds as collective investment vehicles
- The nuances of capital gains and dividend distributions
- The advantages of utilizing tax-deferred accounts like IRAs and 401(k) plans
- Strategies to minimize tax liabilities, such as tax-loss harvesting
- The selection of tax-efficient investment options
These insights empower families to make informed decisions that enhance their overall financial well-being.
In conclusion, navigating the world of mutual funds and taxes is not just about compliance; it’s about empowerment and strategic planning. Together, we can navigate this journey. Families are encouraged to take proactive steps toward understanding their investment options and tax implications, ensuring that they are well-equipped to build a secure financial future. By embracing these principles, families can cultivate wealth that supports their aspirations and provides lasting opportunities for generations to come.
Frequently Asked Questions
What are mutual funds?
Mutual funds are investment vehicles that pool capital from various investors to acquire a diversified collection of stocks, bonds, and other securities, managed by expert portfolio managers.
How do mutual funds benefit families?
Mutual funds provide a pathway for families to cultivate wealth together by allowing them to invest collectively and work towards their financial goals with the guidance of professionals.
Why is it important for households with young kids to understand investment options?
Understanding investment options, such as mutual funds, is essential for families with young kids as it represents a deliberate approach to building a secure financial future for their loved ones.
Are mutual funds tax deferred?
Yes, mutual funds can be tax deferred, meaning that investors can delay tax payments on profit gains until they withdraw their resources, allowing families to grow their assets without the immediate tax burden.
How does tax deferral benefit families?
Tax deferral allows families to accumulate wealth and secure their financial future without the immediate impact of taxes, aligning their financial strategies with long-term objectives and the well-being of future generations.
List of Sources
- Explain How Mutual Funds Generate Taxable Events
- Mutual funds, ETFs, and capital gains distributions (https://corporate.vanguard.com/content/corporatesite/us/en/corp/articles/mutual-funds-etfs-and-capital-gains-distributions.html)
- Why are dividends and capital gains in mutual funds important? (https://thriventfunds.com/insights/mutual-fund-focus/why-are-dividends-capital-gains-mutual-funds-important.html)
- Discuss Benefits of Tax-Deferred Accounts for Mutual Funds
- How the One Big Beautiful Bill may affect families | Fidelity (https://fidelity.com/learning-center/personal-finance/trump-accounts-big-beautiful-bill)
- What We Know About Trump Accounts and How to Make Them Work for Our Children (https://ebwllc.com/blog/what-we-know-about-trump-accounts-and-how-to-make-them-work-for-our-childre)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Investment & Risk Management for high-income W-2 families at Bright Advisers.
Keep reading