

Overview
Understanding RSUs (Restricted Stock Units) can feel overwhelming, especially when they become part of your W-2 as taxable earnings once they vest. This inclusion impacts your overall taxable income and could even affect your tax bracket. Imagine if you were caught off guard by unexpected tax consequences—it’s important to know how approximately 90% of employers report RSUs in Box 1 of the W-2. Verifying this information can help you avoid surprises.
We recommend consulting with tax professionals who can guide you through effective financial planning tailored to your family’s needs. Remember, you’re not alone in this journey. Together, we can navigate the complexities of wealth management and prioritize what truly matters for your family.
Key Highlights:
- RSUs are a form of equity compensation that vest over time and are treated as taxable earnings once vested.
- The fair market value of vested RSUs is included in W-2 reporting, impacting taxable income and potentially tax brackets.
- Families should implement strategies like tax-loss harvesting and adjusting withholding rates to optimise RSU taxation.
- RSU withholding rates can vary from 22% to 37%, making it essential for families to understand these rates for financial planning.
- Approximately 90% of employers report RSUs on W-2 forms, typically in Box 1 (wages) and sometimes in Box 14.
- Discrepancies in W-2 reporting of RSUs can lead to unexpected tax consequences, necessitating careful verification.
- Consulting tax professionals is recommended for navigating RSU taxation complexities and ensuring accurate reporting.
- Families are advised to limit RSUs to no more than 10% of their portfolio to manage financial risk effectively.
Introduction
Navigating the complexities of Restricted Stock Units (RSUs) can feel overwhelming for parents who are focused on securing their family’s financial future. These equity compensation tools hold the potential to significantly influence a family’s taxable income and financial planning, especially when preparing for major expenses like education. As families ponder whether RSUs appear on their W-2 forms, it’s essential to consider the possible tax implications and reporting discrepancies that may arise.
Imagine the peace of mind that comes from effectively managing these challenges—ensuring your family’s well-being and avoiding unexpected tax burdens. We’re here to support you in this journey.
Understand Restricted Stock Units (RSUs) and Their Tax Implications
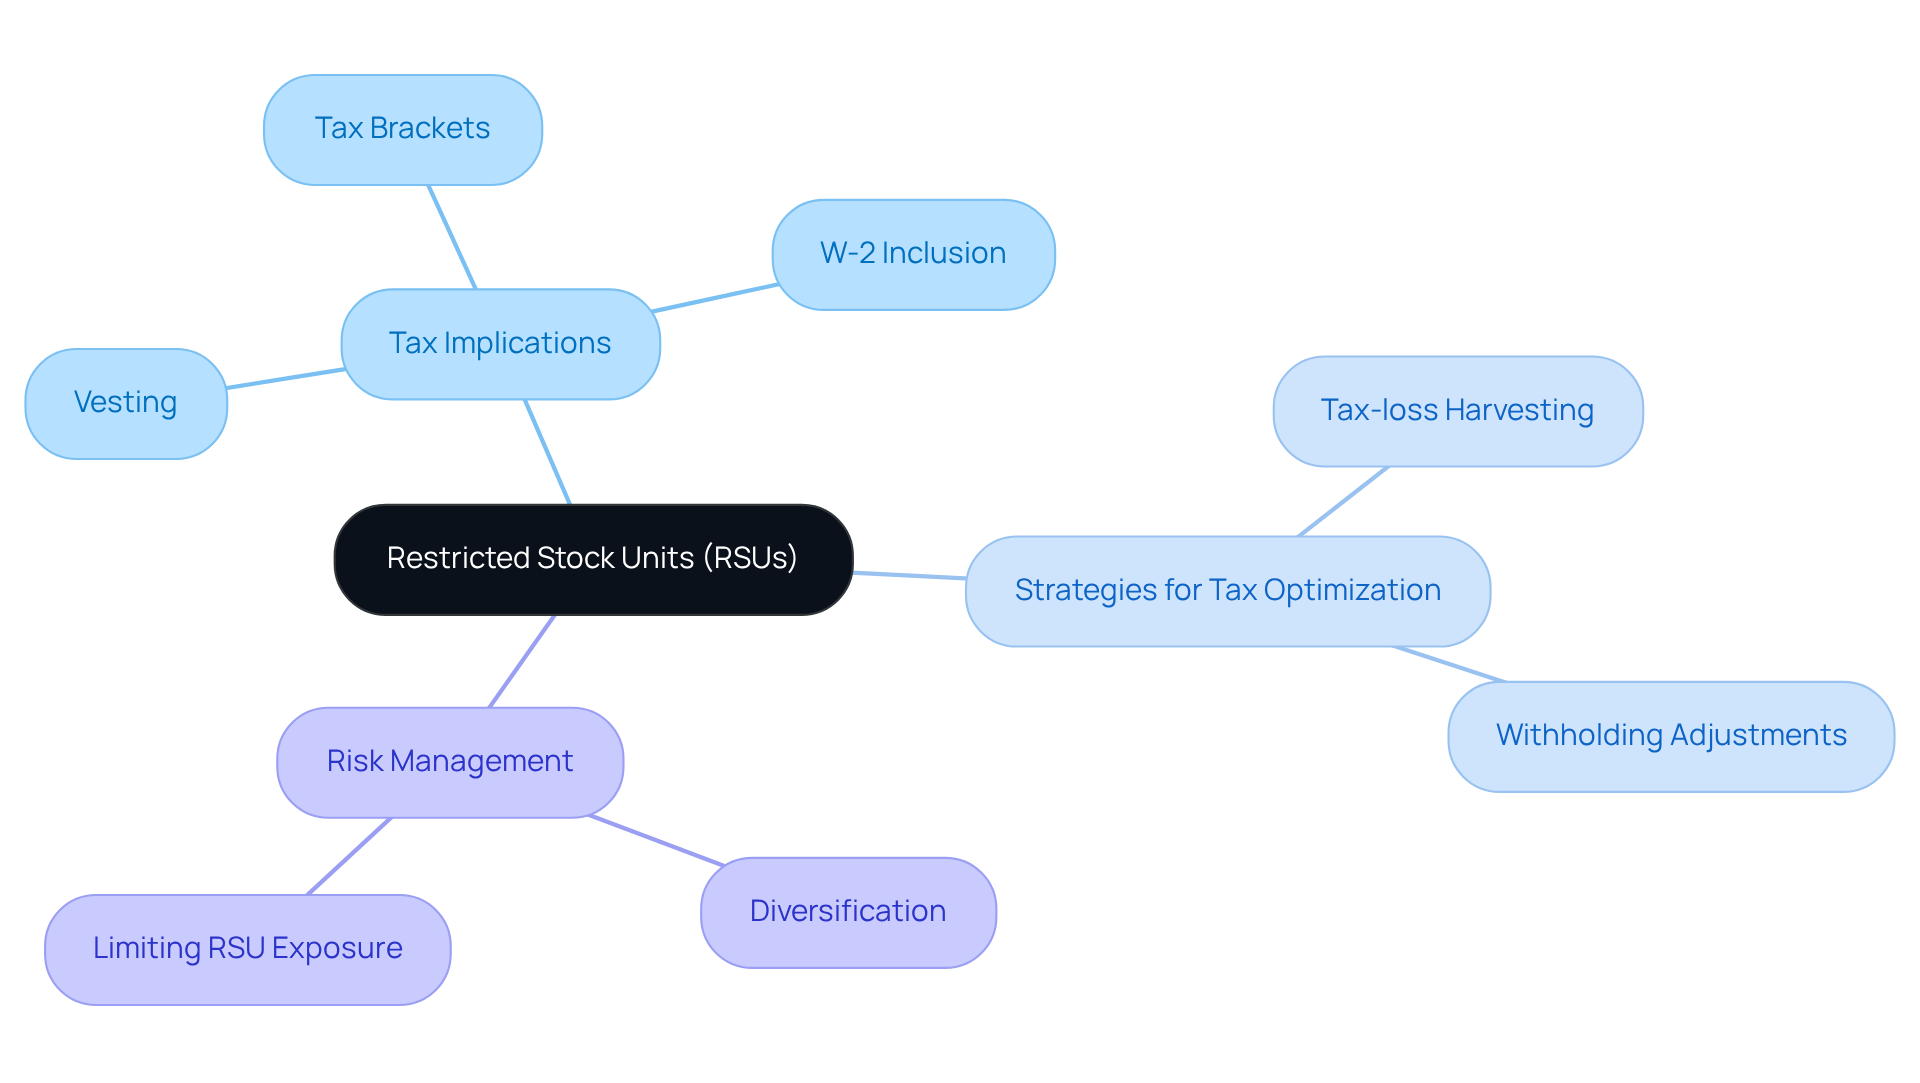
Restricted Stock Units (RSUs) represent a valuable form of equity compensation that many employers offer as part of their benefits packages. Unlike traditional stock options, RSUs don’t require employees to purchase shares; instead, they receive shares that vest over a specific period. Once vested, these units are treated as taxable earnings, and it raises the question of whether RSUs are included in W-2, based on their fair market value at that time. This taxation can significantly impact a family’s overall taxable income, potentially pushing them into a higher tax bracket. It’s crucial for families to understand these implications, as RSUs can greatly affect financial planning, especially for parents who are preparing for future expenses like their children’s education.
Imagine families like Allison and Brian, who have successfully navigated RSU tax planning. They implemented strategies such as:
- Tax-loss harvesting
- Adjusting their withholding rates
By incorporating tax optimization into their financial plan, they not only minimized their tax liabilities but also secured their children’s future through education funding. This proactive approach allowed them to retire sooner, giving them peace of mind and more quality time with their loved ones.
It’s important to be aware of the varying withholding rates for RSUs, particularly regarding whether they are RSUs included in W-2, which can range from 22% to 37%. By understanding these rates, Allison and Brian aligned their financial strategies with their long-term goals, ensuring they were prepared for the costs of raising children. Furthermore, it’s advisable for families to limit their exposure to RSUs to no more than 10% of their portfolio to manage risk effectively. Together, we can navigate this journey and ensure a secure financial future for our families.
Identify How RSUs Are Reported on Your W-2 Form
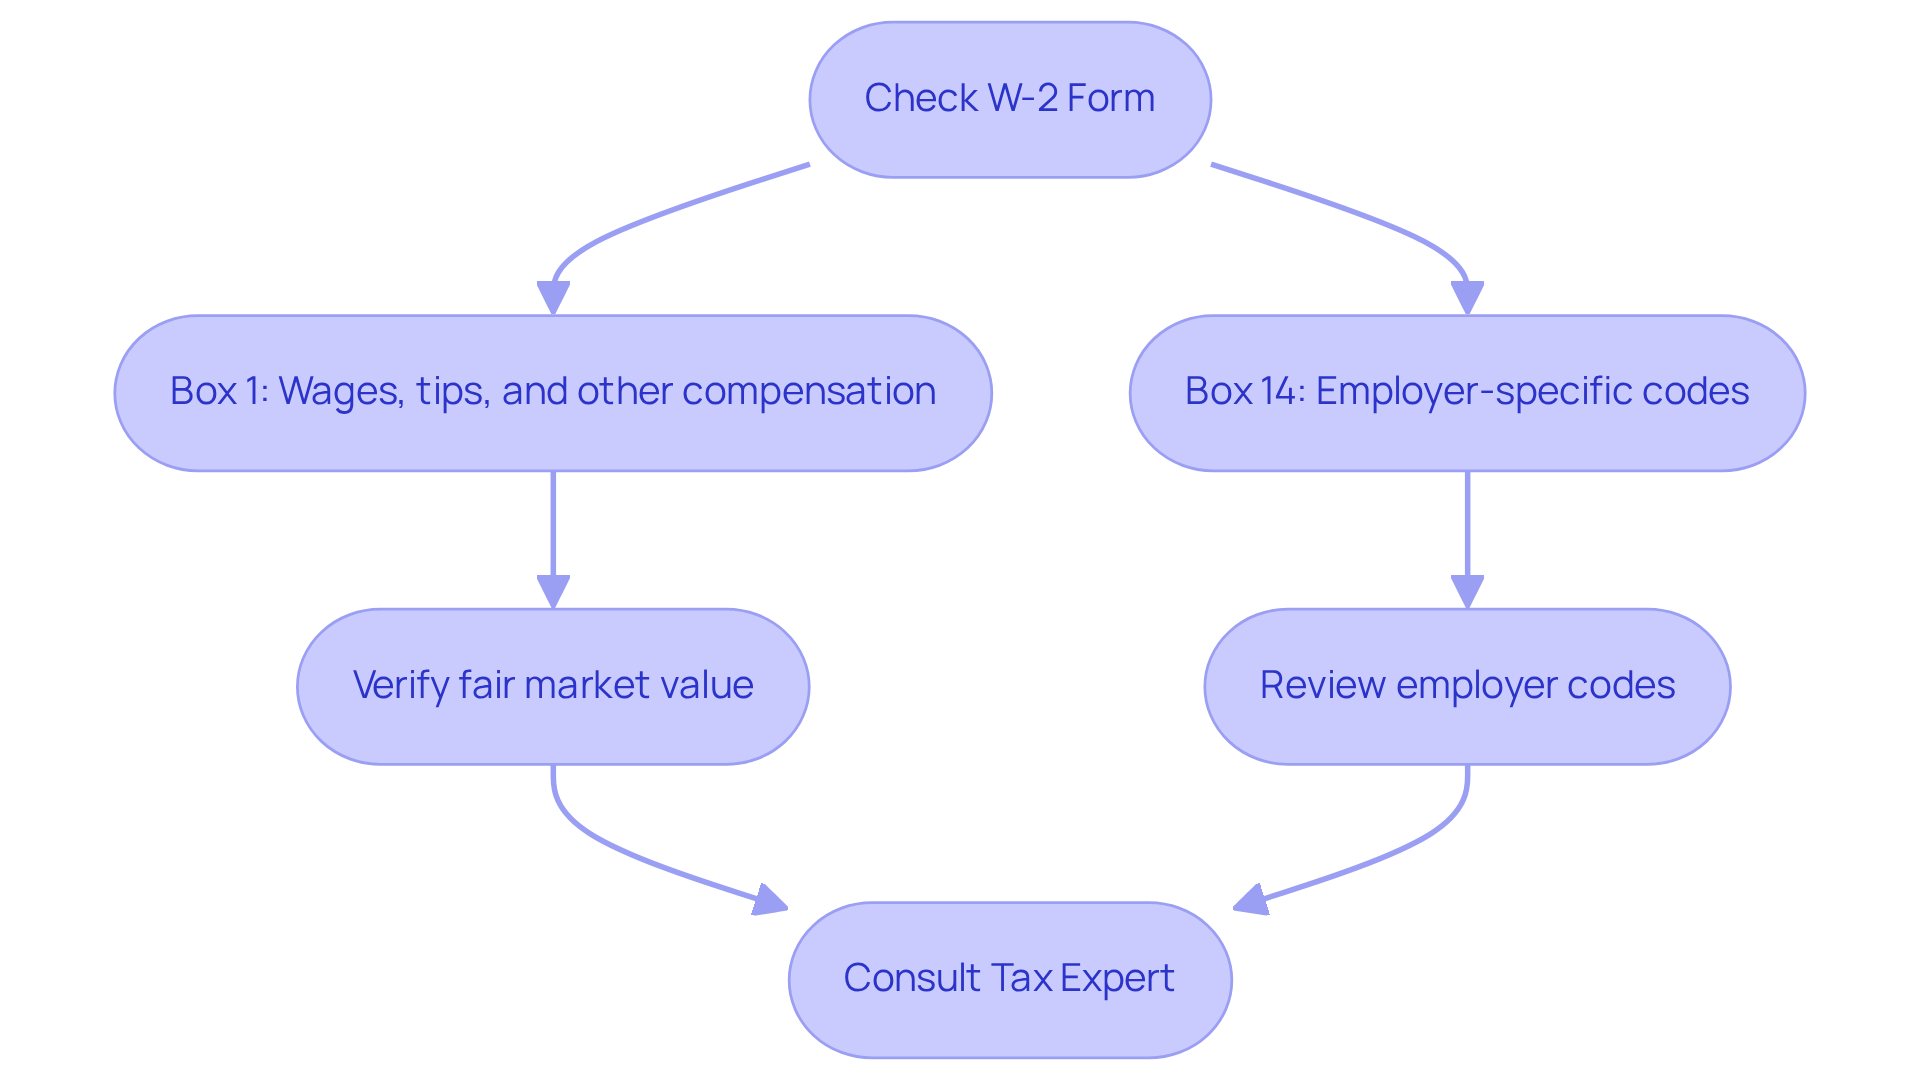
When Restricted Stock Units become available, one might wonder if they are RSUs included in W-2 as part of your taxable earnings. Imagine receiving a notice that the fair market value of your vested shares is reported in Box 1 (Wages, tips, and other compensation) of the W-2. It’s also possible that this amount may appear in Box 14, which is designated for various employer-specific codes. As a parent, it’s important to carefully review these boxes to ensure that the RSU earnings are accurately reflected, as this directly impacts your overall tax liability.
It’s crucial to verify that the amounts reported align with your expectations based on the vesting schedule. Discrepancies can lead to unexpected tax consequences, which can add stress to your financial planning. Notably, the cost basis for restricted stock units is typically reported as $0, and the default withholding rate for these units is usually around 22%. It’s important to know that approximately 90% of employers are RSUs included in W-2 reporting, making this a common practice.
For example, if you obtained restricted stock units valued at $12,000 during the tax year, this amount should be clearly indicated on your W-2, reflecting the total value at the time of vesting. Ensuring accuracy in these reports is essential for effective tax planning and compliance.
Remember, seeking advice from a tax expert can offer tailored approaches for handling your tax responsibilities associated with restricted stock units. Together, we can navigate this journey and ensure that your family’s financial future is secure.
Check Your W-2 for RSU Inclusion and Tax Codes
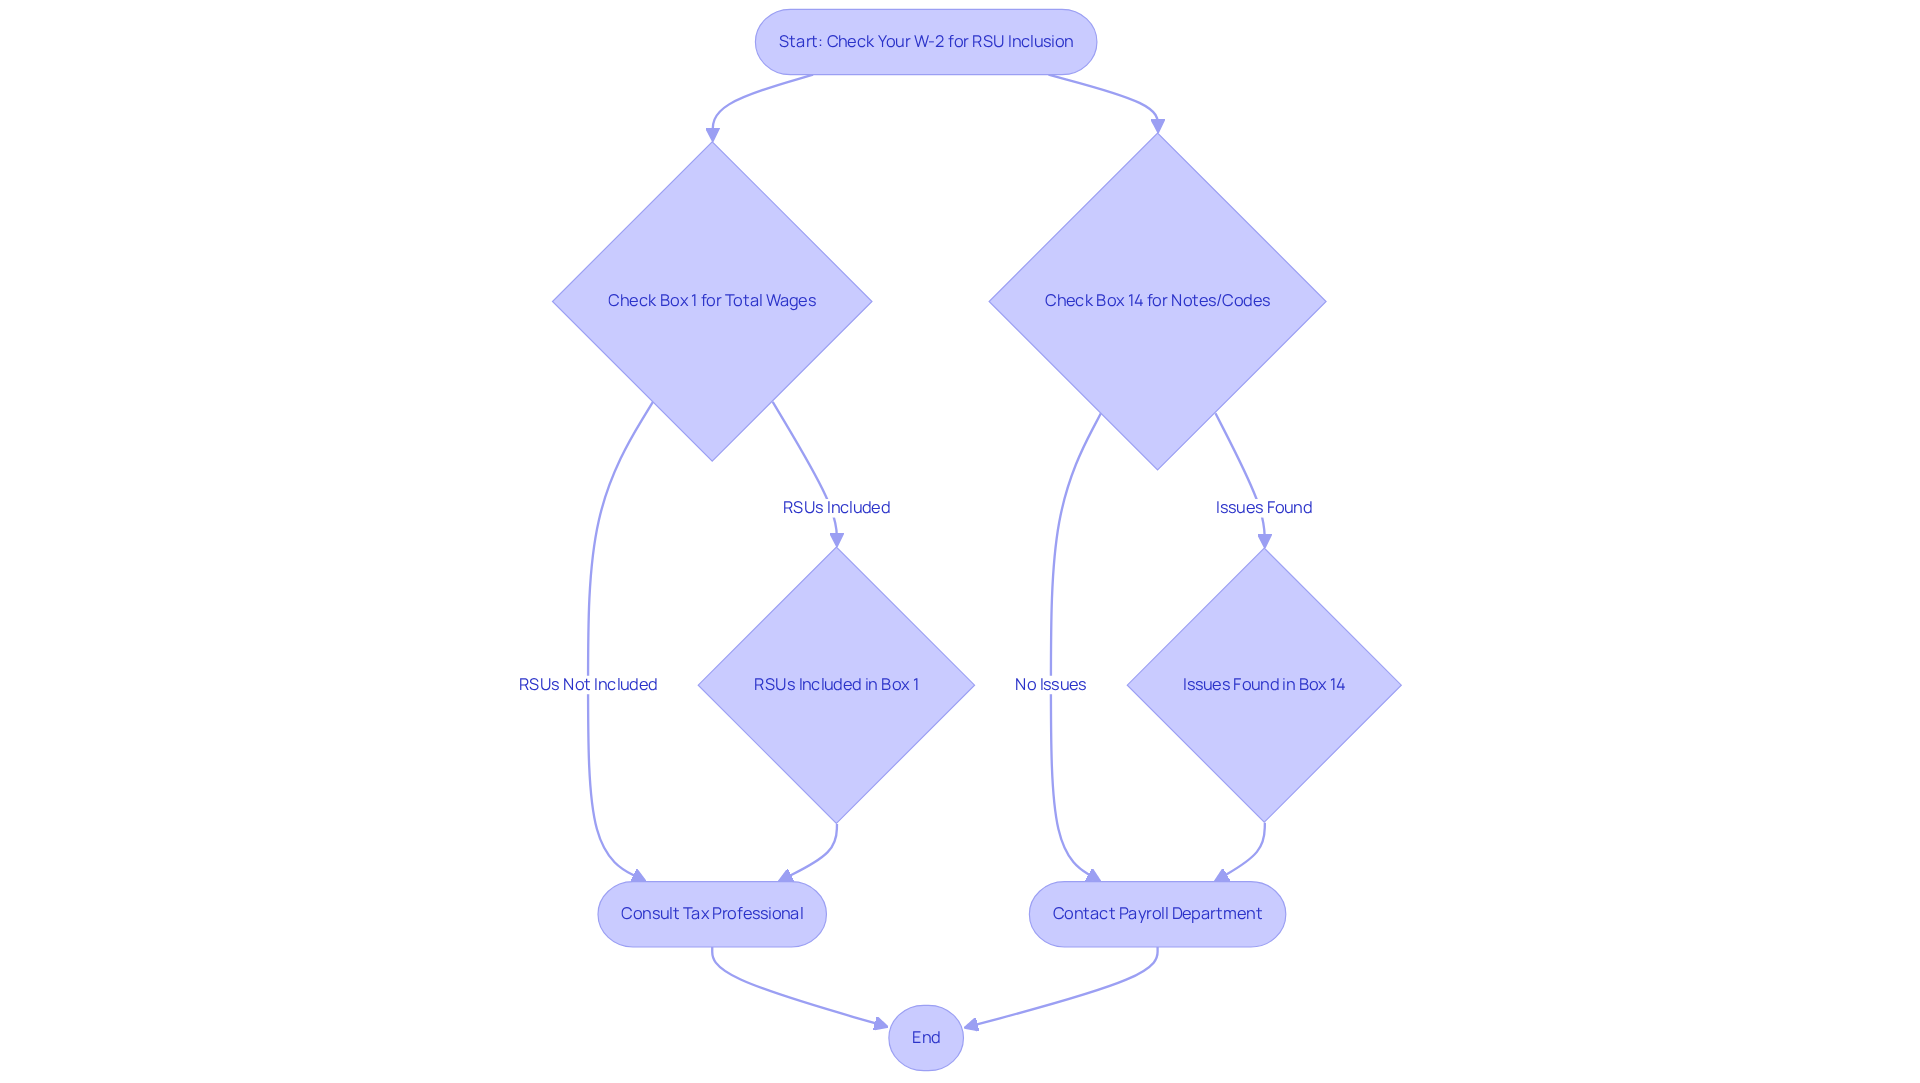
To ensure that the inclusion of your RSUs is correct, check if they are RSUs included in W-2 by starting with Box 1, which details your total wages. This figure should include both your salary and any RSU income, which raises the question of whether RSUs are included in W-2. Next, take a moment to check Box 14 for any notes or codes to see if RSUs are included in W-2. It’s crucial to ensure these amounts are correct, as any discrepancies can lead to complications during tax filing. Imagine if you found out that your RSU reporting had errors—this is a common concern for many.
Tax experts stress the importance of consulting a professional for RSU taxation, as Austin Bell, a tax manager, wisely advises, “Consulting a tax professional for RSU taxation is essential to navigate complex rules and optimize your financial benefits.” In fact, studies show that around 30% of employees have RSUs included in W-2 forms, which highlights the need for vigilance to avoid errors in reporting.
If you notice a missing RSU amount or an unexpected tax code, it’s important to reach out to your employer’s payroll department for clarification. They can help explain how restricted stock units were reported and assist in resolving any issues. Regularly monitoring these details can help you avoid potential errors, ensuring your tax documents accurately reflect your financial situation.
Remember, RSU earnings are subject to a federal tax withholding rate of 22%, so precise reporting is essential. Together, we can navigate this journey and ensure your family’s financial well-being.
Resolve Discrepancies in RSU Reporting on Your W-2
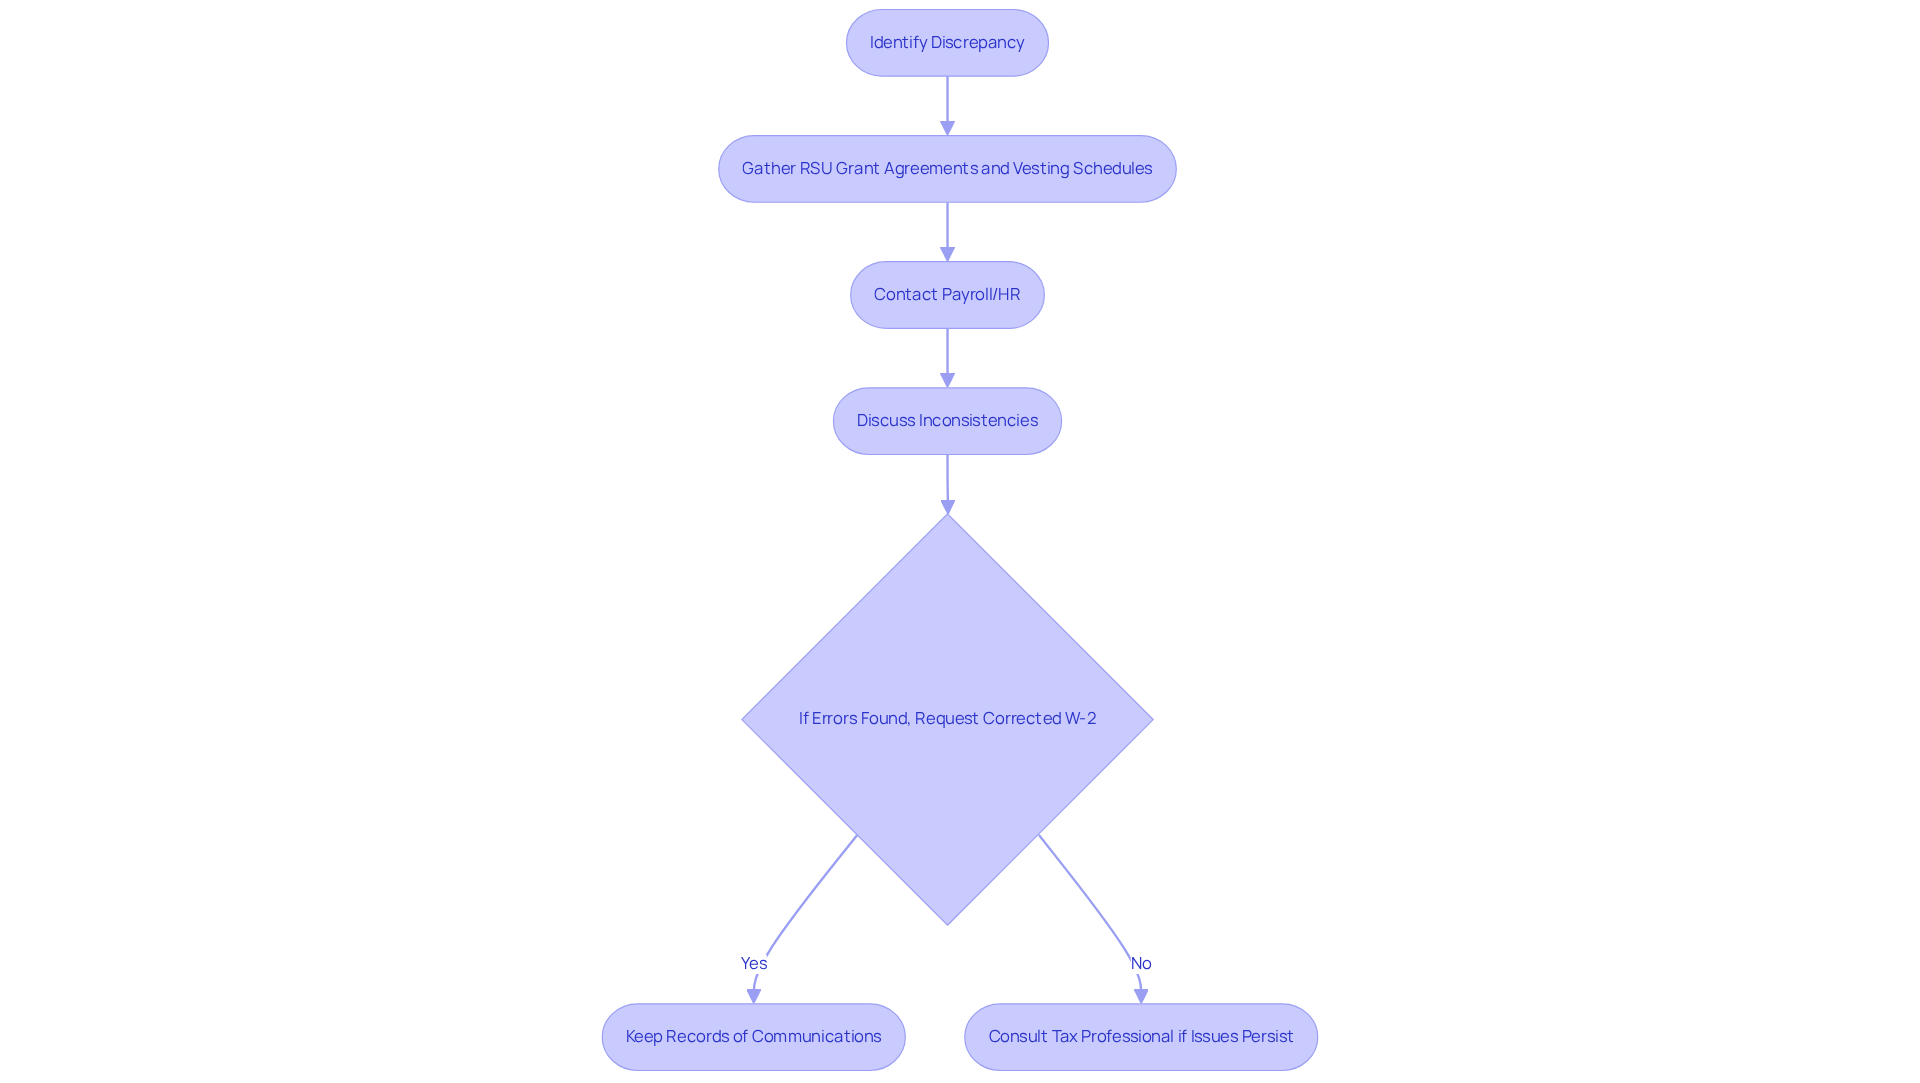
If you’re facing discrepancies in your W-2 concerning whether RSUs are included in W-2 reporting, it’s important to take a step back and gather all the necessary documentation. Start with your RSU grant agreements and vesting schedules; these documents are essential for creating a clear record of your restricted stock units. Next, reach out to your employer’s payroll or HR department to discuss any inconsistencies you’ve noticed. If errors are found, they may need to issue a corrected W-2. Remember, keeping thorough records of all communications and any corrected documents is vital for your peace of mind.
On average, resolving RSU reporting issues may require multiple conversations with your employer. This highlights the importance of persistence and organization in this process. If the issue persists and you’re worried it might affect your tax return, consulting a tax professional can be a wise step. They can provide tailored advice on how to navigate these challenges and ensure your tax filings are accurate.
As Gino G., a CPA, notes, ‘You’re not doubly taxed on the earnings from restricted stock units themselves, but you may perceive it that way because the amount you paid in taxes at vesting was regarded as regular earnings.’ It’s important to understand that income from vested RSUs could push you into a higher tax bracket due to its addition to your total taxable income. Tax professionals emphasize that addressing W-2 errors promptly, especially regarding whether RSUs are included in W-2, can help prevent complications during tax season, allowing families to focus on what truly matters—securing their financial future.
Together, we can navigate this journey, ensuring that you feel supported every step of the way.
Conclusion
Understanding the intricacies of Restricted Stock Units (RSUs) and their implications for tax reporting is essential for parents navigating their financial futures. This article has explored how RSUs are treated as taxable earnings once vested and the importance of verifying their inclusion on W-2 forms. By grasping these concepts, families can better prepare for potential tax liabilities and make informed decisions regarding their financial strategies.
Imagine the relief of knowing that you’ve checked your W-2 forms for accurate reporting of RSU values, which can significantly impact your overall taxable income. Families like Allison and Brian have shown us that proactive tax planning—adjusting withholding rates and consulting tax professionals—can help minimize liabilities. It’s important to understand the various tax codes associated with RSUs to ensure compliance and avoid surprises during tax season.
Ultimately, managing RSUs is not just about understanding tax codes; it’s about securing a stable financial future for your family. By staying informed and seeking professional guidance, you can effectively navigate the complexities of RSU reporting and make strategic decisions that align with your long-term goals. Taking these steps not only alleviates stress but also empowers you to focus on what truly matters—providing for your children’s future and enjoying peace of mind in your financial journey. Together, we can navigate this journey.
Frequently Asked Questions
What are Restricted Stock Units (RSUs)?
Restricted Stock Units (RSUs) are a form of equity compensation offered by employers, where employees receive shares that vest over a specific period without needing to purchase them.
How are RSUs taxed?
Once RSUs vest, they are treated as taxable earnings based on their fair market value at that time, which can significantly impact a family’s overall taxable income.
Are RSUs included in W-2 forms?
Yes, RSUs are included in W-2 forms based on their fair market value at the time they vest.
How can RSUs affect a family’s financial planning?
The taxation of RSUs can potentially push families into a higher tax bracket, affecting their overall financial planning, especially for future expenses like children’s education.
What strategies can families use for RSU tax planning?
Families can implement strategies such as tax-loss harvesting and adjusting withholding rates to minimize tax liabilities related to RSUs.
What are the withholding rates for RSUs?
Withholding rates for RSUs can range from 22% to 37%, depending on various factors.
How can families manage risk associated with RSUs?
It is advisable for families to limit their exposure to RSUs to no more than 10% of their investment portfolio to manage risk effectively.
What benefits did Allison and Brian experience through RSU tax planning?
By incorporating tax optimization strategies, they minimized their tax liabilities, secured funding for their children’s education, and were able to retire sooner, enhancing their quality of life.
List of Sources
- Understand Restricted Stock Units (RSUs) and Their Tax Implications
- The Taxation of Restricted Stock Units | Cerity Partners (https://ceritypartners.com/insights/the-taxation-of-restricted-stock-units)
- How Are Restricted Stock Units Taxed? Vesting, Withholding, and Selling Explained (https://plancorp.com/blog/restricted-stock-units-taxes)
- Understanding RSU Tax Rates: Comprehensive Guide with Calculator (https://advisorfinder.com/resources-for-clients/tax/rsu-tax-rate)
- Master Restricted Stock Tax Treatment for Your Family’s Future – Bright Advisers (https://brightadvisers.com/master-restricted-stock-tax-treatment-for-your-familys-future)
- RSU Taxes Explained + 4 Tax Strategies for 2023 (https://cordantwealth.com/rsus-tax-saving-and-hedging)
- Identify How RSUs Are Reported on Your W-2 Form
- How to Avoid Double Taxation on Restricted Stock Units (RSUs) (https://insights.wjohnsonassociates.com/blog/how-to-avoid-paying-double-tax-for-restricted-stock-units-rsus)
- Here’s How Restricted Stock Units (RSUs) Work | Bankrate (https://bankrate.com/investing/restricted-stock-units)
- How should I expect to see RSUs reported on W-2 and other forms? – Bogleheads.org (https://bogleheads.org/forum/viewtopic.php?t=374635)
- How Are Restricted Stock Units (RSUs) Taxed? (https://smartasset.com/investing/how-are-restricted-stock-units-taxed)
- Your Guide to Navigating RSU Taxation | Massey and Company CPA (https://masseyandcompanycpa.com/your-guide-to-navigating-rsu-taxation)
- Check Your W-2 for RSU Inclusion and Tax Codes
- How do RSU taxes work? Anytime I vest, my company includes it on my pay stub so federal and state taxes are withheld but E-Trade also wit… (https://quora.com/How-do-RSU-taxes-work-Anytime-I-vest-my-company-includes-it-on-my-pay-stub-so-federal-and-state-taxes-are-withheld-but-E-Trade-also-withholds-shares-for-tax-Am-I-getting-taxed-twice)
- Here’s How Restricted Stock Units (RSUs) Work | Bankrate (https://bankrate.com/investing/restricted-stock-units)
- How Are Restricted Stock Units (RSUs) Taxed? (https://smartasset.com/investing/how-are-restricted-stock-units-taxed)
- Restricted Stock Units – RSU Taxation, Vesting, Calculator & More (https://janefinancial.com/restricted-stock-units)
- Your Guide to Navigating RSU Taxation | Massey and Company CPA (https://masseyandcompanycpa.com/your-guide-to-navigating-rsu-taxation)
- Resolve Discrepancies in RSU Reporting on Your W-2
- Avoiding Double Taxation on RSU Grants: Q&A (https://justanswer.com/tax/routb-looking-confirm-not-getting-double-taxed-rsu.html)
- How to Avoid Double Taxation on Restricted Stock Units (RSUs) (https://insights.wjohnsonassociates.com/blog/how-to-avoid-paying-double-tax-for-restricted-stock-units-rsus)
- The Complete Guide to Restricted Stock Units (RSUs) (https://districtcapitalmanagement.com/rsu)
- Stock-based compensation: Tax forms and implications (https://thetaxadviser.com/newsletters/2024/jan/stock-based-compensation-tax-forms-and-implications)
- Restricted Stock Units – RSU Tax Tips: Avoid Double Taxation (https://juliemerrill.me/blog/rsu-tax-tips-avoid-double-taxation)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Tax Management for high-income W-2 families at Bright Advisers.
Keep reading