

Key Highlights:
- Asset management focuses on managing investments to maximise returns across asset classes like stocks and bonds.
- Wealth management takes a holistic approach, including investment management, financial planning, estate planning, and tax optimization.
- Asset managers prioritise investment performance, while wealth managers offer comprehensive financial services tailored to clients’ overall economic situations.
- Statistics show that high-net-worth individuals who work with asset managers accumulate 17% more liquid assets than those who do not.
- Wealth management services are particularly beneficial for families, emphasising long-term financial security and aligning with family values.
- Fiduciary duties are stronger in wealth management, requiring advisors to act in clients’ best interests, leading to higher client satisfaction.
- 92% of wealth advisors use AUM fees as their primary revenue source, which can affect their service offerings and client relationships.
- Technology enhances both asset and wealth management, with firms using data analytics for investment strategies and personalised client tools.
- The global wealth management market is projected to reach $834 billion by 2030, highlighting the importance of adapting to technological advancements.
Introduction
Navigating the financial landscape can feel overwhelming for young families striving to secure their future. It’s essential to understand the difference between asset management and wealth management, as each offers unique benefits tailored to your family’s financial needs.
Imagine if you could confidently navigate these two approaches, ensuring your financial strategies align with both your immediate goals and long-term aspirations. This article explores the key differences, empowering you to make informed decisions that foster lasting financial security for your loved ones.
We’re here for you, guiding you through the complexities of financial planning. Together, we can navigate this journey, ensuring that your family’s values and priorities are at the forefront of your financial decisions.
Let’s take this step together, so you can build a secure future for your family.
Define Asset Management and Wealth Management
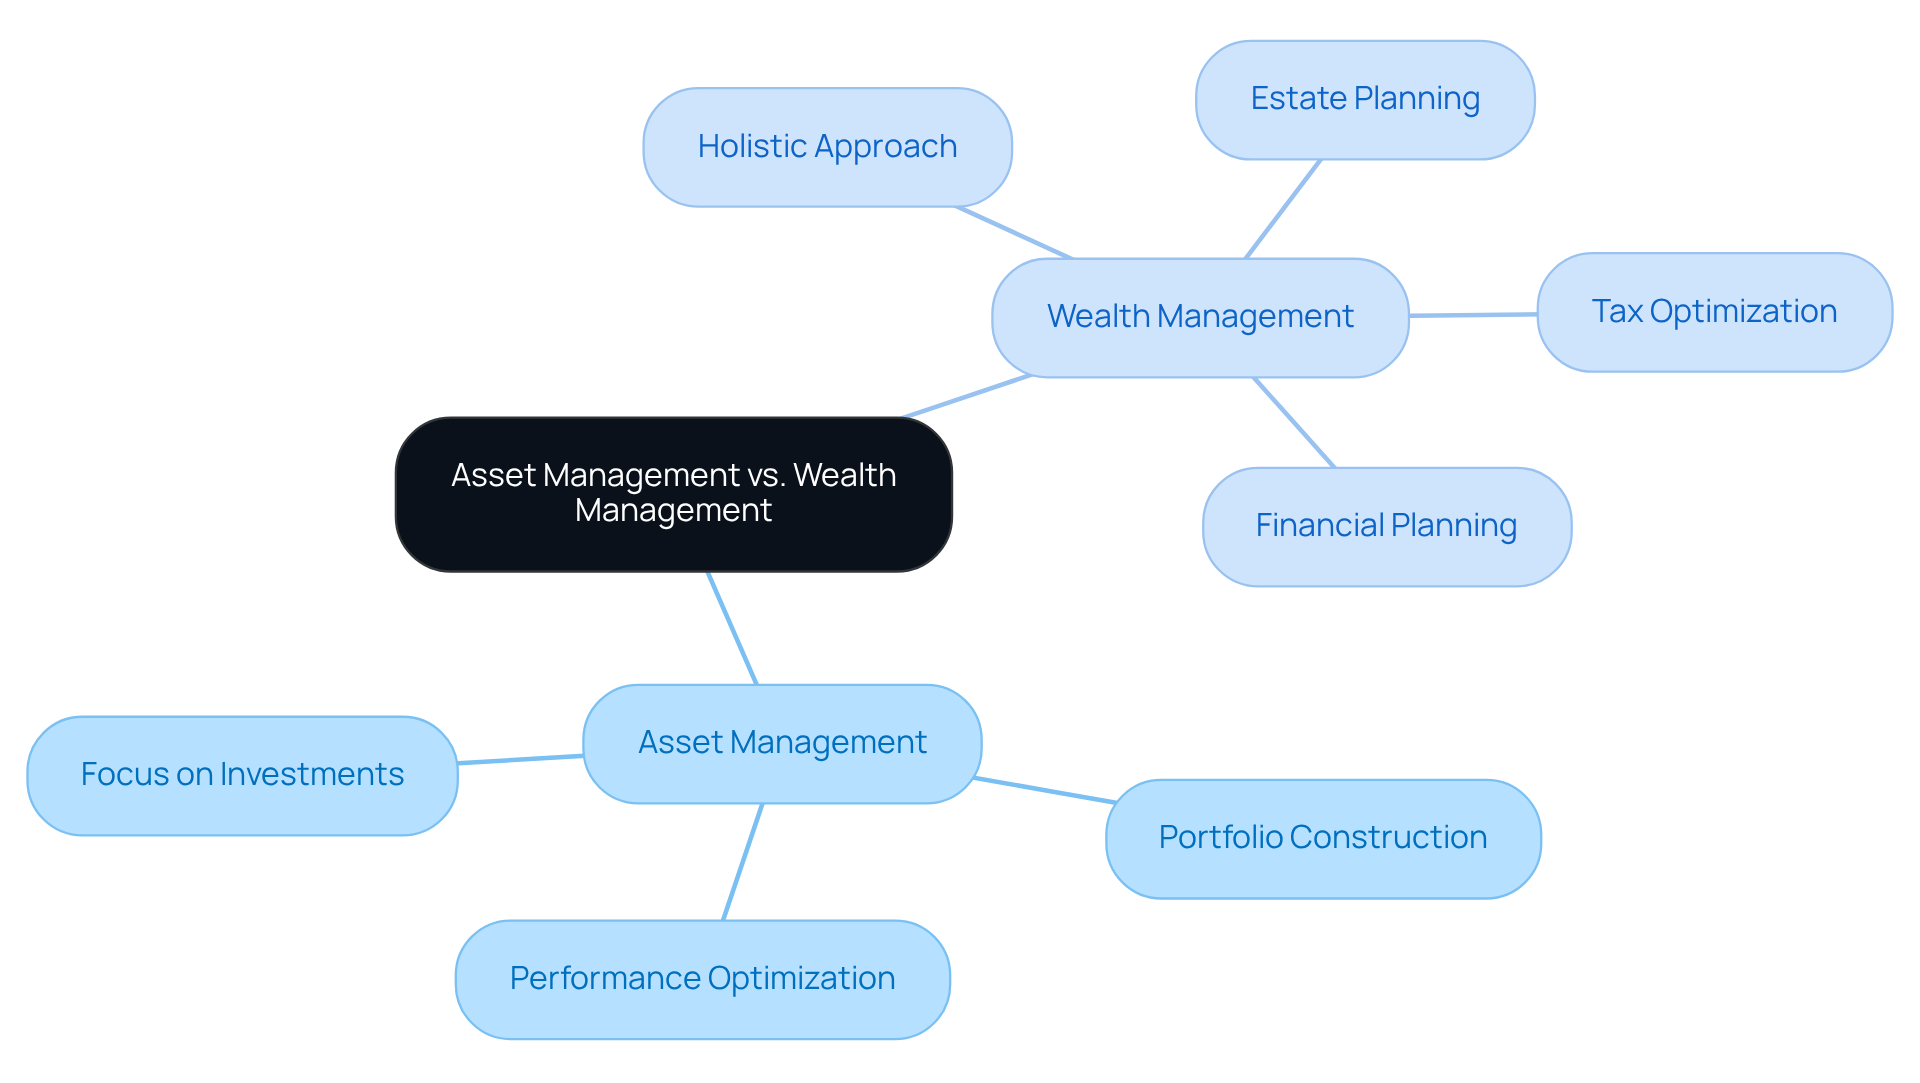
Managing your family’s financial future can feel overwhelming, but understanding asset management versus wealth management is a great first step. Asset management is all about systematically managing investments to maximize returns across various asset classes like stocks, bonds, and real estate. Think of it as a focused approach where asset managers work diligently on portfolio construction and performance optimization. For instance, a family might hire an asset manager to ensure their investment portfolio aligns perfectly with their risk tolerance and financial goals.
On the other hand, the difference between asset management versus wealth management takes a broader view. It encompasses a range of financial services, including investment management, financial planning, estate planning, and tax optimization. Wealth managers adopt a holistic approach, considering your entire economic situation and long-term objectives, especially when discussing asset management versus wealth management. This is especially beneficial for families looking to secure their financial future while raising children. Imagine working with a wealth manager at Bright Advisers who helps you develop a comprehensive financial plan that not only addresses investment strategies but also includes education savings for your kids and estate planning to ensure a smooth transfer of wealth across generations.
Consider the story of Emily and Mark, a young couple striving for financial independence. By partnering with Bright Advisers, they crafted a personalized budget plan that reflected their values and aspirations. This collaboration empowered them to navigate the complexities of financial planning while balancing their careers and personal lives. With this comprehensive strategy, they , reduced debt, and planned for retirement, giving them the freedom to make career choices that align with their desired work-life balance.
Statistics reveal that by June 2025, global assets under management (AUM) are projected to reach an impressive $147 trillion, underscoring the growing reliance on expert financial advice. Moreover, studies show that high-net-worth individuals who seek guidance from asset managers accumulate 17% more in liquid assets than those who don’t. This highlights the essential role of asset management versus wealth management in enhancing financial stability and growth for families, making it a crucial factor for those aiming to build and sustain multi-generational prosperity. Additionally, mass-affluent investor assets are expected to grow at an average rate of 5.4% until 2028, suggesting a bright future for management services.
Together, we can navigate this journey toward financial security. Remember, you’re not alone in this process; we’re here for you, ready to support you every step of the way.
Compare Services Offered by Asset Managers and Wealth Managers
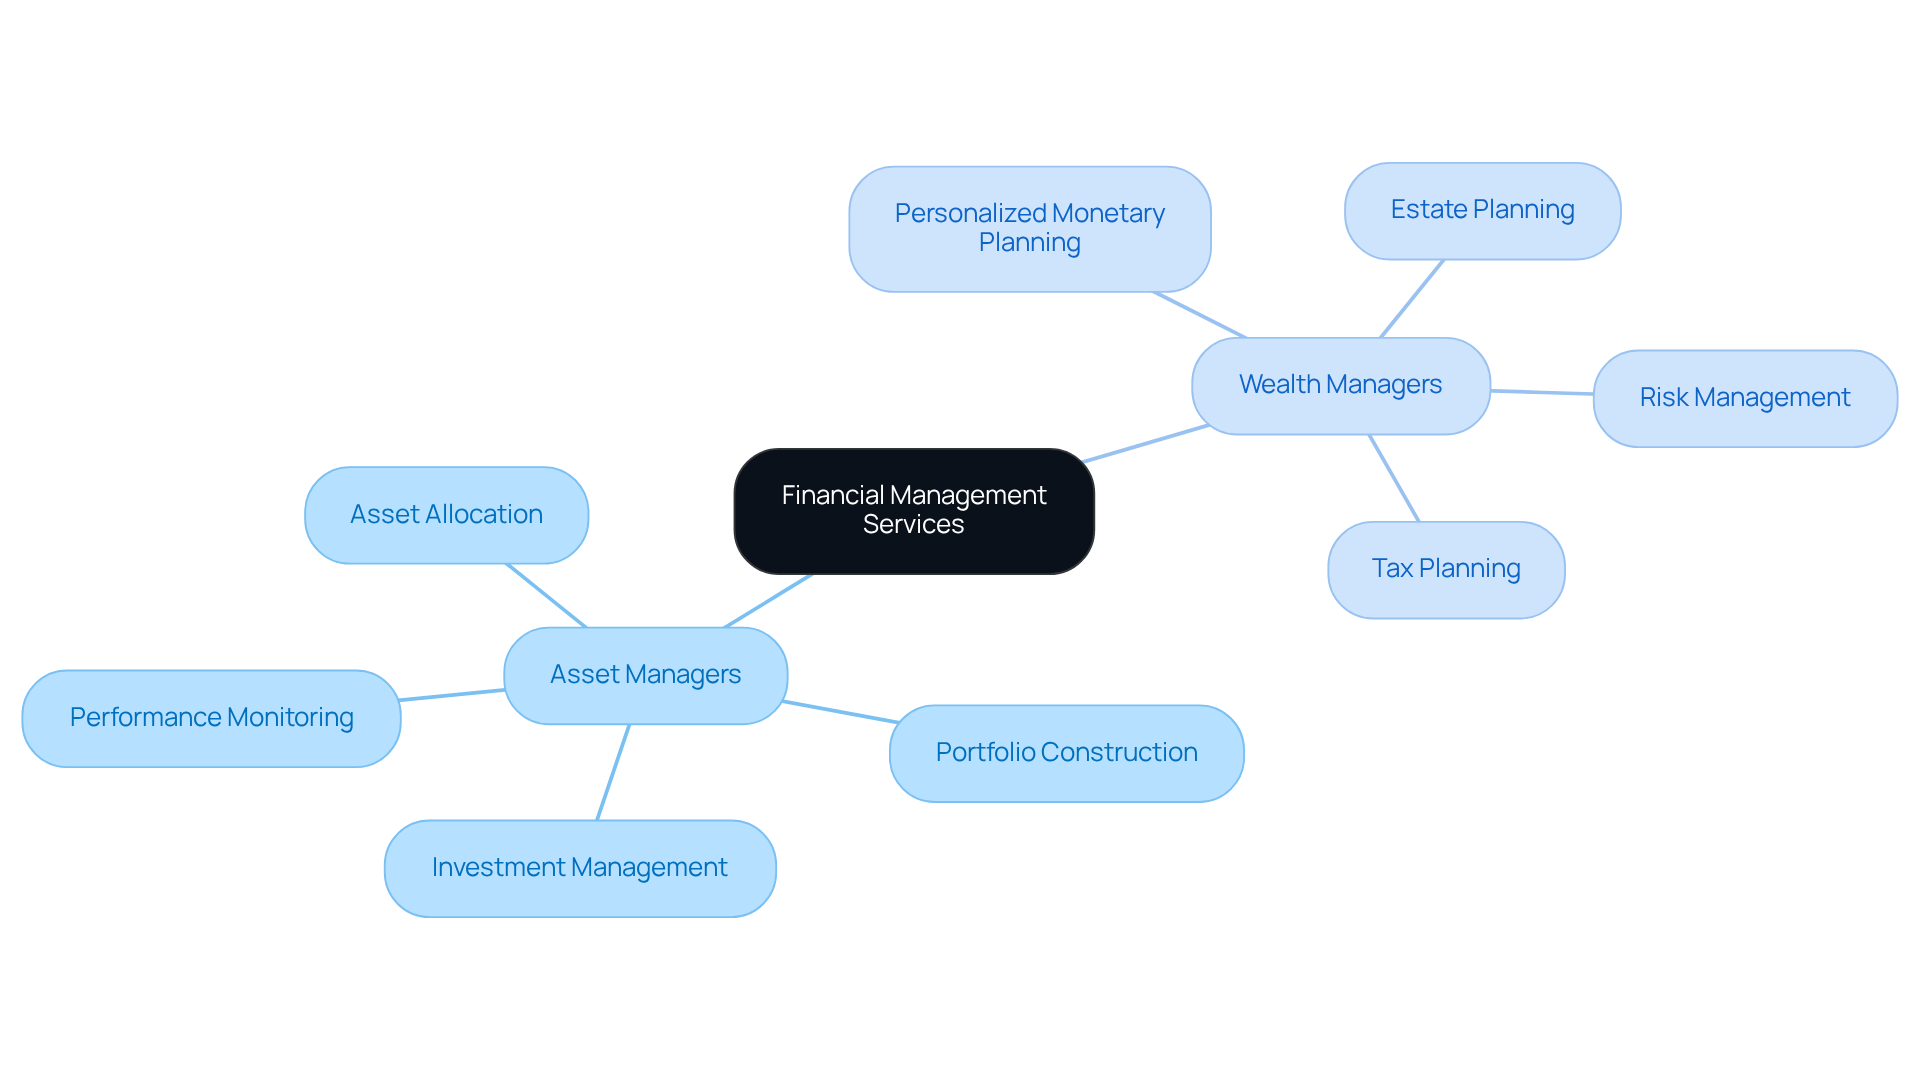
Asset managers primarily focus on investment management, offering services like portfolio construction, asset allocation, and performance monitoring. Their main goal? Maximizing the value of assets under management. But what if you need more than just investment management? That’s where financial managers come in. They provide a broader range of services, including personalized monetary planning, tax planning, estate planning, and risk management, all tailored to meet your unique needs.
For young households, wealth management services can be a game changer. They not only promote investment growth but also emphasize the importance of preserving wealth for future generations. Imagine having a financial strategy that aligns with your family values and long-term goals. It’s reassuring to know that around 61% of asset managers are now offering personalized planning, reflecting a growing recognition of the need for customized services.
Experts highlight the advantages of wealth management as compared to asset management versus wealth management, especially for families navigating complex financial landscapes. provide peace of mind by integrating various financial elements, allowing you to focus on what truly matters-your loved ones and their future. This holistic support is vital for young families striving to establish a secure financial foundation while honoring their unique aspirations.
Together, we can navigate this journey, ensuring that your financial strategies not only support your current needs but also safeguard your family’s future.
Examine Client Relationships and Fiduciary Duties
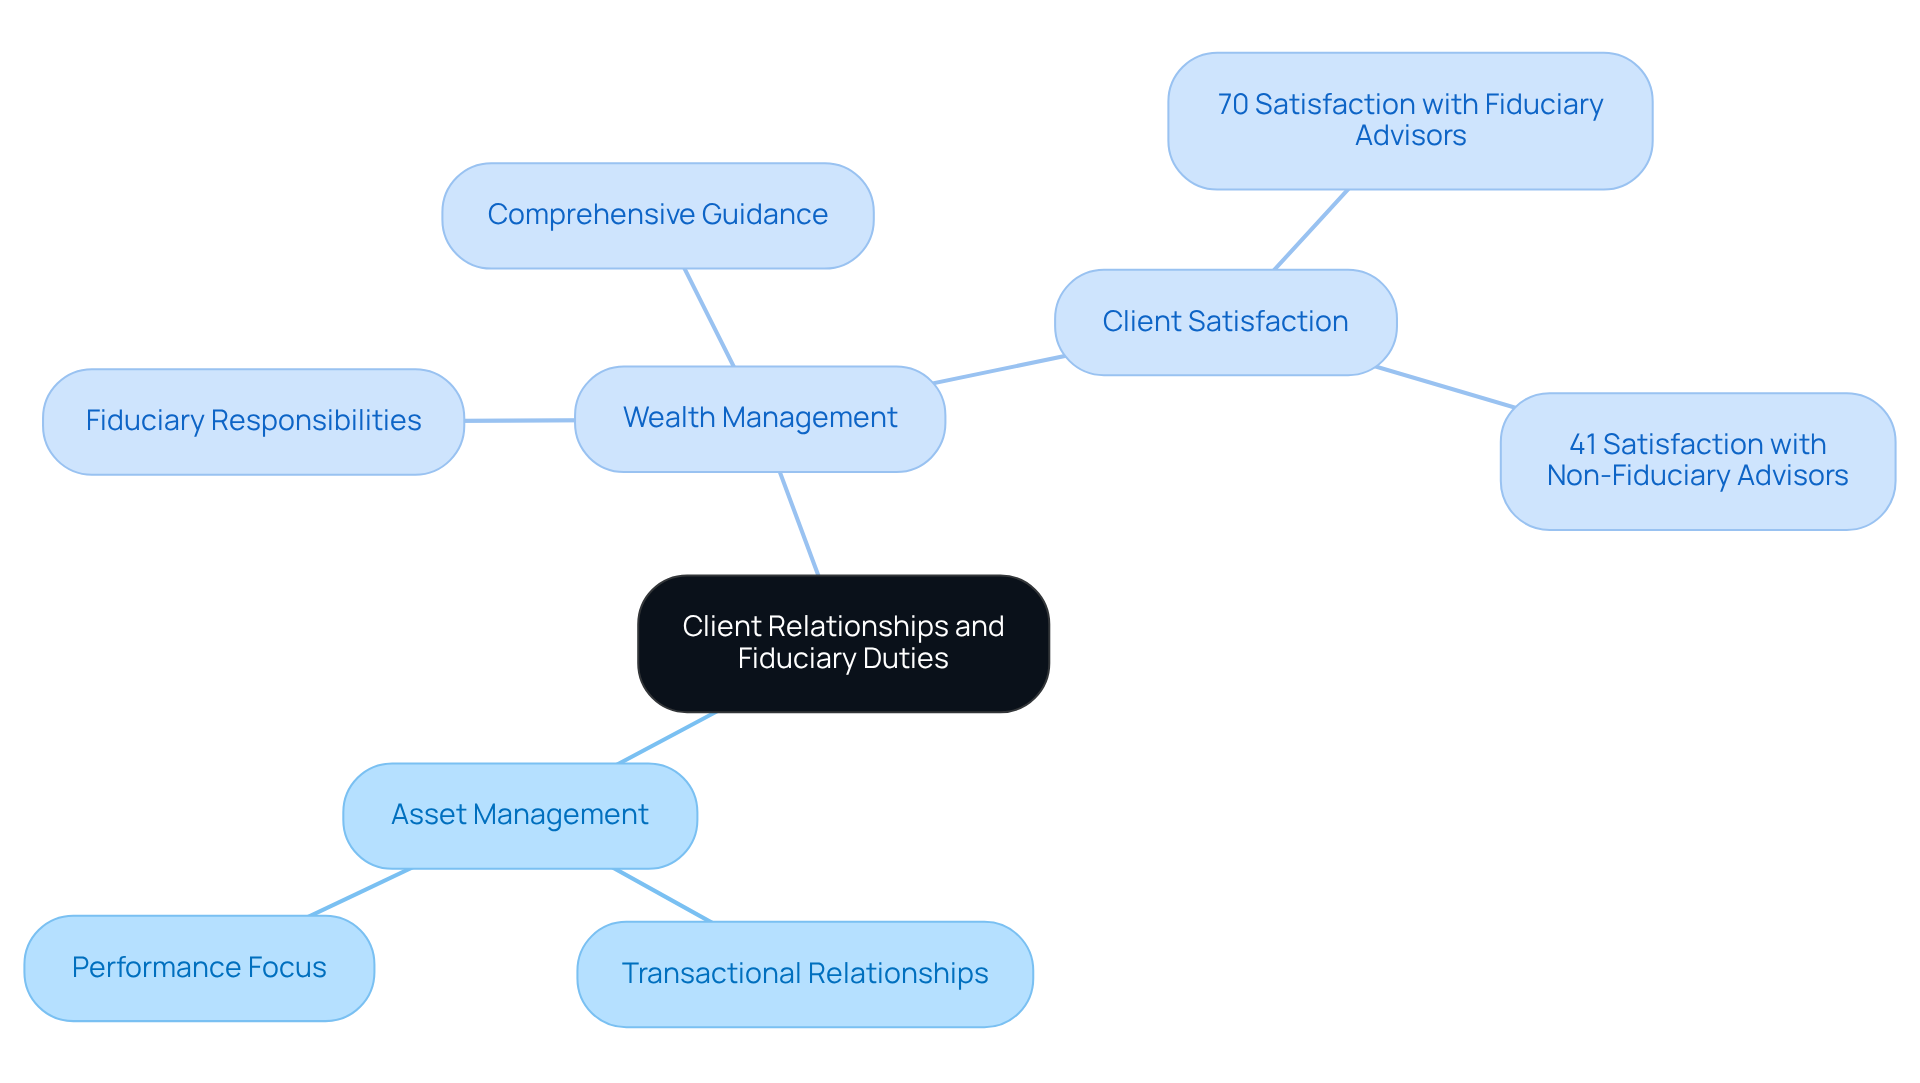
When discussing asset management versus wealth management, it’s clear that asset managers often follow a less rigorous fiduciary standard, focusing mainly on the performance of the investments they manage. Their relationships with clients can feel more transactional, emphasizing returns in asset management versus wealth management rather than providing thorough financial advice. On the other hand, financial advisors, like Bright Advisers, are bound by fiduciary responsibilities, which legally require them to act in the best interests of their clients, particularly when considering the differences in asset management versus wealth management. This commitment means offering comprehensive guidance that considers the client’s entire financial situation, particularly in the context of asset management versus wealth management.
Imagine being a young household, where working with a fiduciary asset manager creates a trusting relationship. This partnership ensures that your financial goals and family values are at the heart of all planning efforts. By leveraging the innovative integrated wealth management system developed with Lifeworks Advisors, families gain access to tailored solutions that help them achieve financial security and independence.
It’s important to understand that individuals who trust their advisors to prioritize their interests often feel more satisfied. In fact, 70% of wealthy investors report contentment when collaborating with fiduciary advisors. This statistic underscores the vital role fiduciary relationships play in fostering long-term satisfaction and loyalty, especially for families navigating complex financial landscapes.
Take Emily and Mark, for example. They partnered with Bright Advisers and underwent a thorough evaluation of their financial situation. This process led to a customized plan that aligned perfectly with their aspirations and values.
Together, we can navigate this journey toward , ensuring that your family’s future is secure and bright.
Analyze Compensation Structures in Asset and Wealth Management
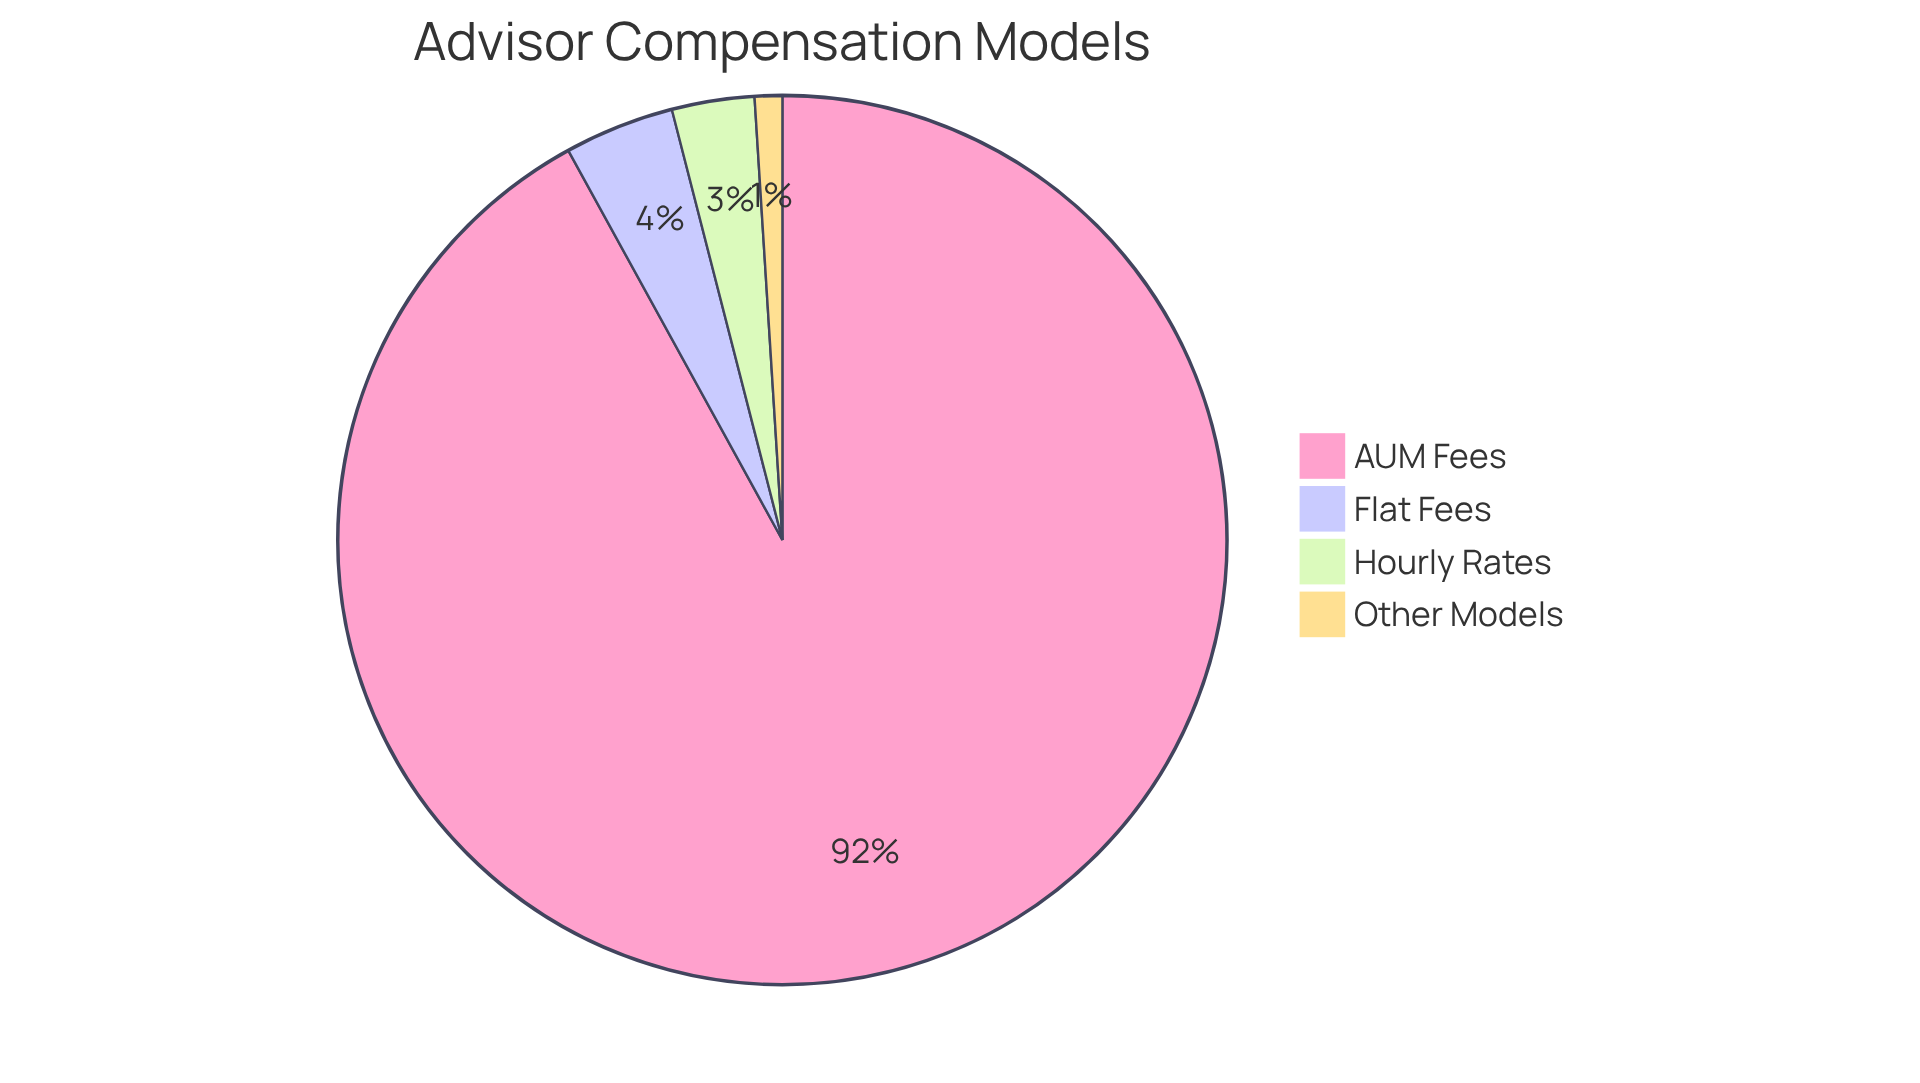
Asset managers often charge fees based on a percentage of assets under management (AUM), which can lead to potential conflicts of interest. Imagine if your advisor’s pay was tied solely to short-term gains-there’s a risk they might prioritize quick profits over your family’s long-term financial health. Thankfully, many asset managers offer various compensation structures, like flat fees or hourly rates, allowing them to align their incentives with your family’s goals. This flexibility promotes a more holistic approach to financial planning.
For young households, understanding these compensation models is crucial. They can significantly influence your choice of advisor and the effectiveness of your financial planning. Did you know that 92% of wealth advisors rely on AUM fees as their primary revenue source when comparing asset management versus wealth management? This reliance can limit the types of clients they serve and the services they provide. In contrast, the differences between asset management versus wealth management reveal that wealth managers who adopt alternative fee structures can tailor their solutions to meet your family’s unique needs, ensuring that the guidance you receive is not only comprehensive but also aligned with your long-term aspirations.
It’s important to recognize the value of transparent pricing in building trust between you and your advisor. Open discussions about service costs can strengthen relationships and attract those eager to invest in their financial future. As the landscape of asset management versus wealth management evolves, consider how these fee arrangements affect your planning. Choose advisors who genuinely prioritize your family’s long-term well-being. Together, we can navigate this journey, ensuring your is secure.
Consider the Impact of Technology on Asset and Wealth Management
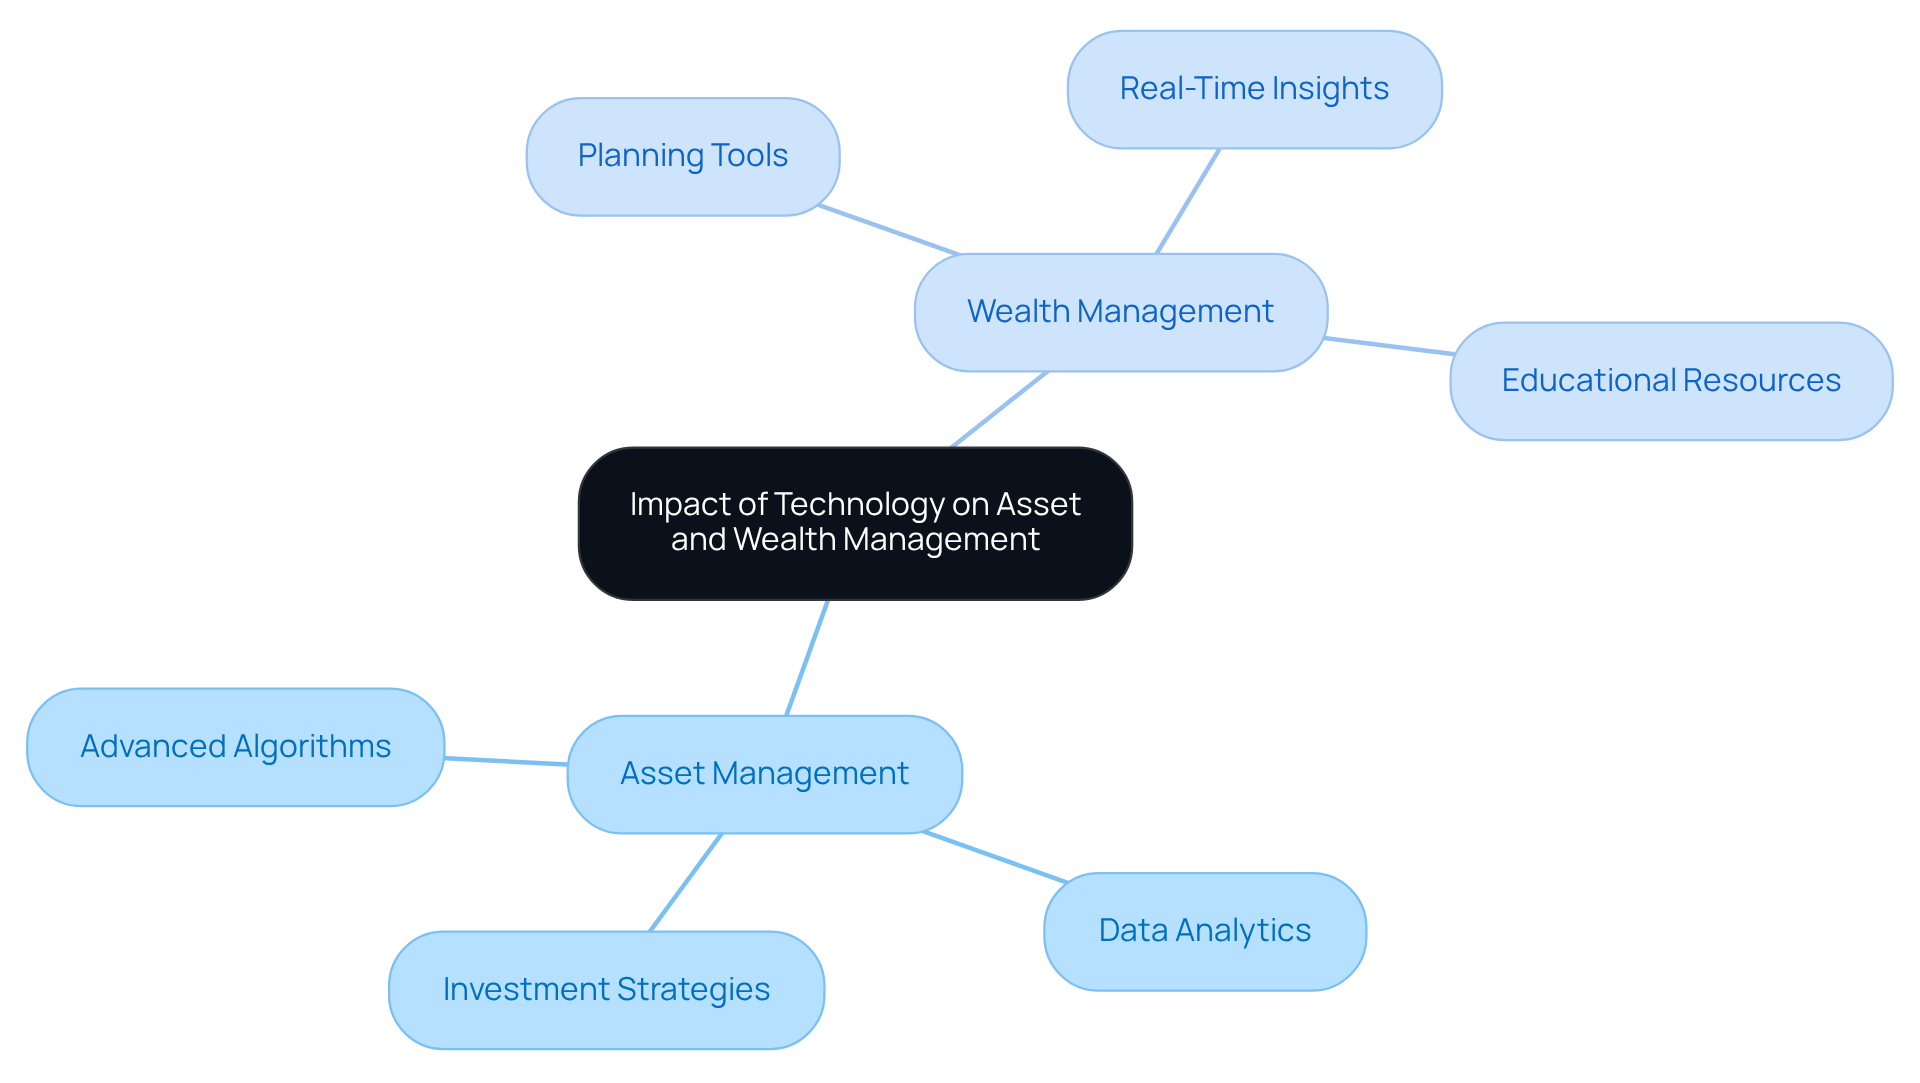
Technology has truly changed the way we handle asset management versus wealth management, significantly improving service delivery and customer experiences. Imagine how asset managers are now using advanced algorithms and data analytics to fine-tune investment strategies in the debate of asset management versus wealth management and keep up with market changes. Meanwhile, wealth managers are harnessing technology to offer planning tools that are easy to use, real-time insights through accessible user portals, and educational resources that empower families to make informed decisions, illustrating the distinction between asset management versus wealth management.
For young families, this integration of technology means better communication with advisors, personalized financial planning, and initiatives that help prepare children for their future financial responsibilities. As the industry evolves, the emphasis on tailored, goal-driven support is becoming increasingly important. Many firms recognize that innovation is essential to meet the growing demands of their clients.
Did you know that the global wealth management sector is expected to reach a market value of $834 billion by 2030? This highlights just how crucial it is to adapt to technological advancements to stay competitive. Leaders in the field are focusing on enhancing their data infrastructures to provide personalized experiences. In fact, 86% of firms are increasing their investments in AI and data analytics.
This shift not only boosts client engagement but also positions firms to anticipate client needs with remarkable accuracy. Ultimately, this leads to more effective financial strategies that are tailored to the unique circumstances of families. We’re here for you, ready to help you together.
Conclusion
Understanding the distinctions between asset management and wealth management is crucial for young families aiming to secure their financial future. Imagine if you could not only optimize your investments but also ensure that your financial strategies align with your family’s long-term goals and values. While asset management focuses on investments across various asset classes, wealth management takes a more comprehensive approach, addressing financial planning, estate planning, and tax optimization. This broader perspective is particularly valuable for families like yours.
The article highlights key insights, such as the importance of fiduciary relationships and the range of services offered by both asset and wealth managers. It’s important to understand how evolving compensation structures can impact your financial planning. By emphasizing the holistic nature of wealth management, it becomes clear that young families can benefit significantly from tailored financial strategies that prioritize their unique aspirations. Together, we can navigate this journey, ensuring you stay informed and engaged in your financial decisions.
Ultimately, navigating the complexities of asset and wealth management is essential for building a secure financial foundation. Families should seek out advisors who prioritize their best interests, leverage technology for personalized insights, and offer transparent fee structures. By making informed choices, you can foster long-term prosperity and ensure your financial strategies support not just your current needs, but also the legacy you wish to create for future generations. Remember, we’re here for you, ready to support you every step of the way.
Frequently Asked Questions
What is asset management?
Asset management is the systematic management of investments to maximize returns across various asset classes like stocks, bonds, and real estate. It focuses on portfolio construction and performance optimization to align with an individual or family’s risk tolerance and financial goals.
How does wealth management differ from asset management?
Wealth management takes a broader view, encompassing a range of financial services including investment management, financial planning, estate planning, and tax optimization. It adopts a holistic approach, considering the entire economic situation and long-term objectives of the client.
What services do asset managers provide?
Asset managers primarily focus on investment management services such as portfolio construction, asset allocation, and performance monitoring, with the main goal of maximizing the value of assets under management.
What additional services do wealth managers offer?
Wealth managers provide a wider range of services beyond investment management, including personalized monetary planning, tax planning, estate planning, and risk management, all tailored to meet the unique needs of their clients.
Why is wealth management beneficial for families?
Wealth management is beneficial for families as it promotes investment growth while emphasizing the preservation of wealth for future generations. It helps create a financial strategy that aligns with family values and long-term goals.
What statistics support the importance of asset and wealth management?
By June 2025, global assets under management (AUM) are projected to reach $147 trillion. Additionally, studies show that high-net-worth individuals who seek guidance from asset managers accumulate 17% more in liquid assets than those who do not.
How can wealth management help young households?
Wealth management can be a game changer for young households by providing a comprehensive financial strategy that integrates various financial elements, allowing them to focus on their loved ones and secure their financial future.
What is the projected growth rate for mass-affluent investor assets?
Mass-affluent investor assets are expected to grow at an average rate of 5.4% until 2028, indicating a positive outlook for management services.
List of Sources
- Define Asset Management and Wealth Management
- Industry Statistics (https://investmentadviser.org/industry-snapshots)
- 12 Financial Planning Quotes for Building Wealth Wisely — Phillip James Financial (https://phillipjamesfinancial.com/blog/12-financial-planning-quotes-for-building-wealth-wisely)
- Asset management 2025: The great convergence (https://mckinsey.com/industries/financial-services/our-insights/asset-management-2025-the-great-convergence)
- Wealth Management Statistics – Facts, Tips & Basics (https://plancorp.com/blog/wealth-management-statistics-facts-tips-basics)
- Next in asset and wealth management 2025 (https://pwc.com/us/en/industries/financial-services/library/asset-wealth-management-trends.html)
- Compare Services Offered by Asset Managers and Wealth Managers
- Industry Statistics (https://investmentadviser.org/industry-snapshots)
- Wealth Management Statistics – Facts, Tips & Basics (https://plancorp.com/blog/wealth-management-statistics-facts-tips-basics)
- US wealth management: Amid market turbulence, an industry converges (https://mckinsey.com/industries/financial-services/our-insights/us-wealth-management-amid-market-turbulence-an-industry-converges)
- Wealth Management Industry Outlook | Natixis Investment Managers (https://im.natixis.com/en-us/insights/investor-sentiment/2025/wealth-industry-survey/wealth-management-industry-outlook)
- As the high-net-worth seek out new wealth managers, how do you retain clients and capture money-in-motion? (https://pwc.com/us/en/industries/financial-services/asset-wealth-management/high-net-worth-investor.html)
- Examine Client Relationships and Fiduciary Duties
- 70% of investors satisfied with their fiduciary advisor: Cerulli (https://citywire.com/ria/news/70-of-investors-satisfied-with-their-fiduciary-advisor-cerulli/a2462535)
- Fiduciary relationships pay off for advisors to the affluent: Cerulli (https://investmentnews.com/practice-management/fiduciary-relationships-pay-off-for-advisors-to-the-affluent-cerulli/259937)
- Quotes – The Institute for the Fiduciary Standard (https://thefiduciaryinstitute.org/quotes)
- The Most Important Wealth Management Statistics To Know (https://passivesecrets.com/wealth-management-statistics)
- 2025 Voice of the Client Study: What Americans Really Think About Their Financial Advisors (https://wealthtender.com/advisors/marketing/voice-of-the-client-study)
- Analyze Compensation Structures in Asset and Wealth Management
- How Financial Advisors Actually Charge For Their Services (https://kitces.com/blog/financial-advisors-charge-services-fee-structure-advisory-firm-profession-aum-pricing-insight)
- Cerulli Associates | More Than 72% of Financial Advisors Are… (https://cerulli.com/press-releases/more-than-72-of-financial-advisors-are-compensated-by-fee-based-models)
- 77 Financial Advisor Quotes to Send to Clients (https://billgoodmarketing.com/resources/financial-advisor-quotes)
- How Much Does a Financial Advisor Cost? (https://smartasset.com/financial-advisor/financial-advisor-cost)
- Knightsbridge Advisors | Compensation Trends In Wealth Management (https://knightsbridgesearch.com/compensation-trends-in-wealth-management)
- Consider the Impact of Technology on Asset and Wealth Management
- The Digital Wealth Manager of Today (https://deloitte.com/us/en/Industries/financial-services/articles/digital-transformation-in-wealth-management.html)
- 50 Powerful Quotes to Inspire Fintech Leaders & Innovators (https://fintechly.com/leadership/50-powerful-quotes-to-inspire-fintech-leaders-and-innovators)
- Wealth Tech Trends Shaping the Next Decade (https://fusioniq.io/thought-leadership/wealth-management-tech-trends)
- The future of asset management will be shaped by technology — and most firms aren’t ready (https://thoughtworks.com/en-us/insights/articles/the-future-of-asset-management-will-be-shaped-by-technology)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Family Governance for high-income W-2 families at Bright Advisers.
Keep reading