

Key Highlights
- Open discussions about financial goals and risk tolerance are crucial for family financial well-being.
- Families with young children often prefer low risk portfolio allocations to preserve capital.
- External factors, such as job displacement fears, can influence risk tolerance; individuals anticipating job loss are 19% more tolerant of uncertainty.
- Diversifying investments across stocks, bonds, and alternative assets can mitigate financial risks.
- Regular portfolio reviews are essential to align investments with changing family needs and risk tolerance.
- Bright Advisers offers personalised wealth management solutions through Lifeworks Advisors, a registered financial adviser.
- All investments carry risks, and past performance does not guarantee future results.
Introduction
Many families feel overwhelmed by the financial decisions they face while juggling the demands of parenthood. As parents, you might find it challenging to navigate the ups and downs of the market while ensuring your family’s future is secure. Many seek investment strategies that focus on stability rather than high-risk growth.
In this article, we’ll explore how to create a balanced investment portfolio that reflects your family’s values and priorities, helping you feel more secure in your financial journey. It’s important to understand how to navigate these financial waters effectively, ensuring your investments align with your family’s long-term dreams and goals.
Assess Risk Tolerance for Family Investments
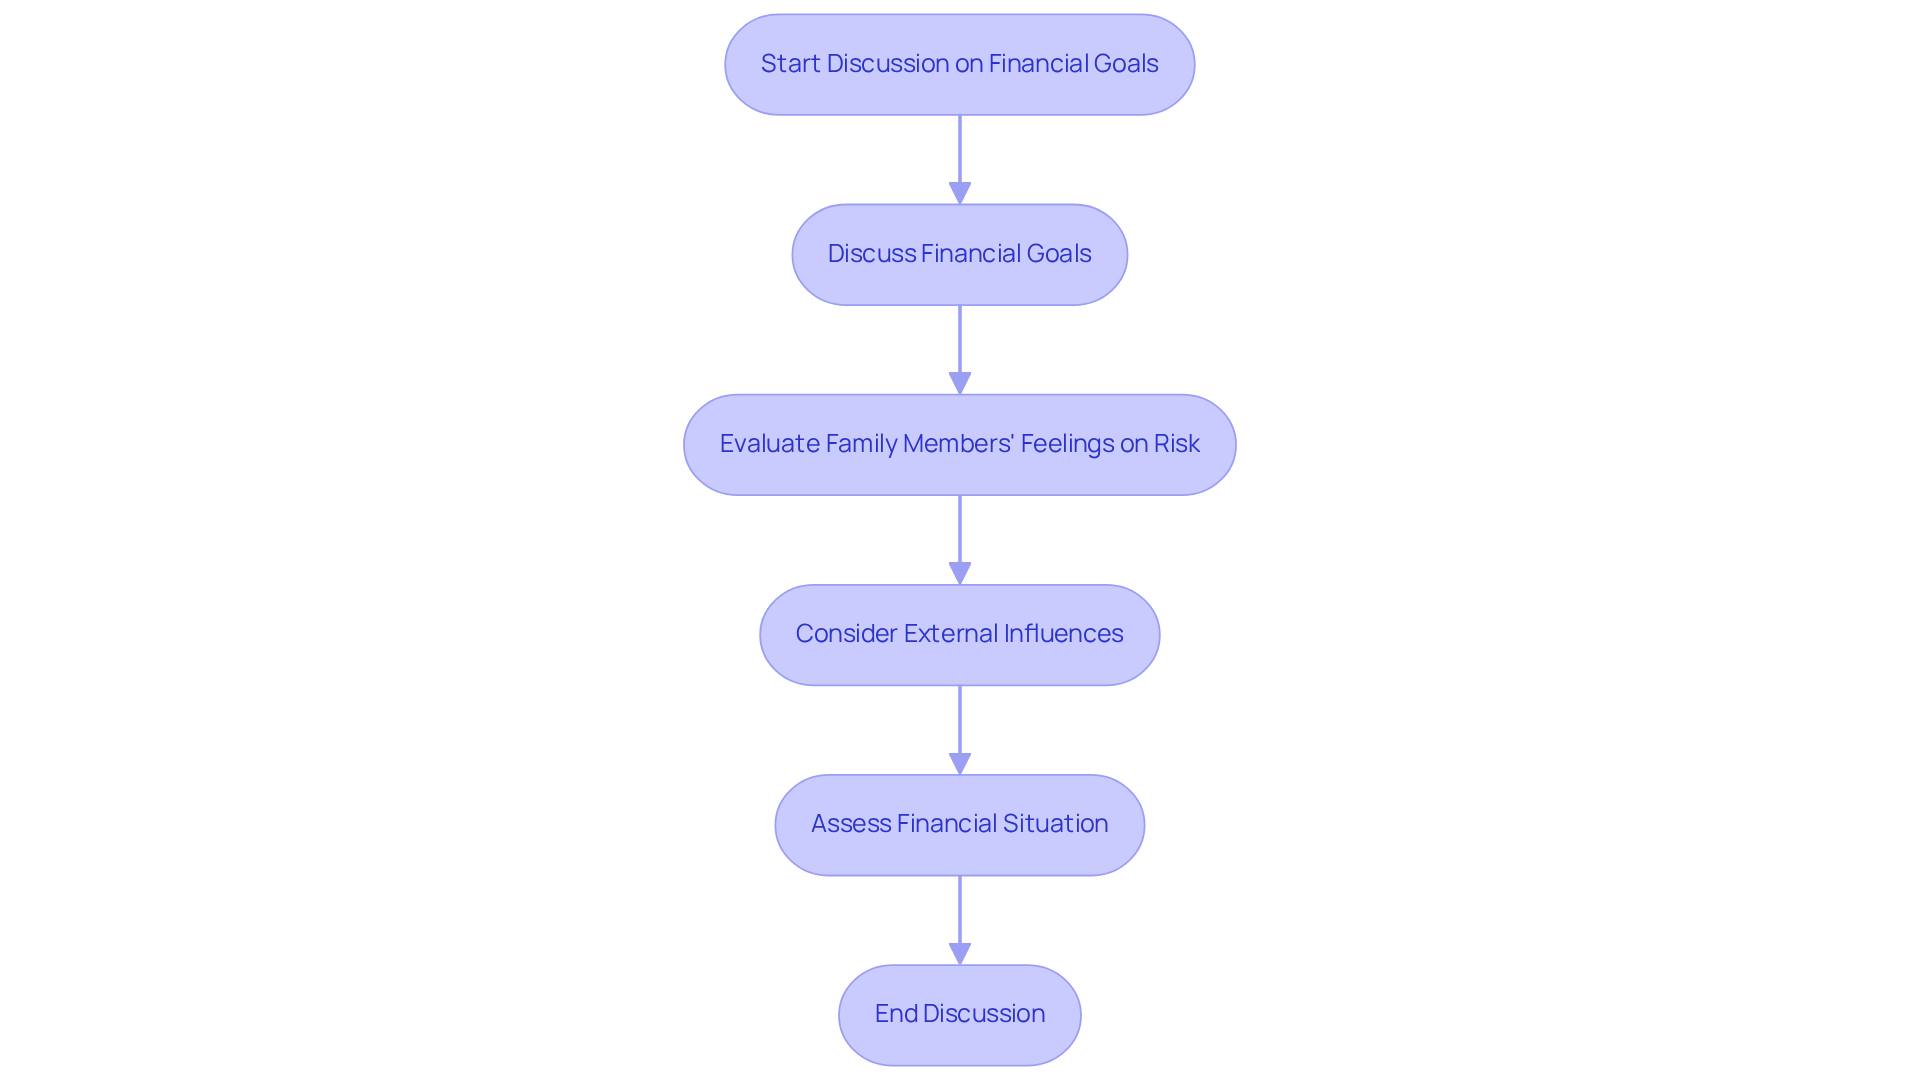
It can be tough to talk about money, especially when it feels uncertain, but having these conversations is crucial for your family’s financial well-being. Open discussions about your financial goals, timelines for contributions, and how market changes make you feel can really help.
Imagine using simple tools to understand how each family member feels about financial uncertainty; it can really help guide your discussions. For instance, families with young children often prioritize a low risk portfolio allocation to preserve their capital over seeking aggressive growth, leading to a more cautious investment approach.
Recognizing how external factors influence our choices can empower families to make informed decisions. Did you know that individuals who foresee job displacement later are 19% more tolerant of uncertainty? This highlights how important it is to understand how outside influences can shape our willingness to take risks.
Think about your family’s income, any debts, and what future expenses might come up; these are all important when figuring out how much risk you can handle. Regularly checking in on these discussions is essential, especially as your family’s needs change over time.
At Bright Advisers, we encourage families to join our waitlist to explore personalized wealth management solutions tailored to their unique needs. Remember, all advisory services are offered through Lifeworks Advisors, a registered financial adviser. Previous performance does not assure future outcomes, and securities holdings are exposed to uncertainty. For more information, please contact us at (714) 987-2967 or hello@brightadvisers.com. By understanding your family’s unique financial landscape, you can navigate uncertainty together, ensuring a brighter future for your loved ones.
Diversify Asset Allocation to Mitigate Risk
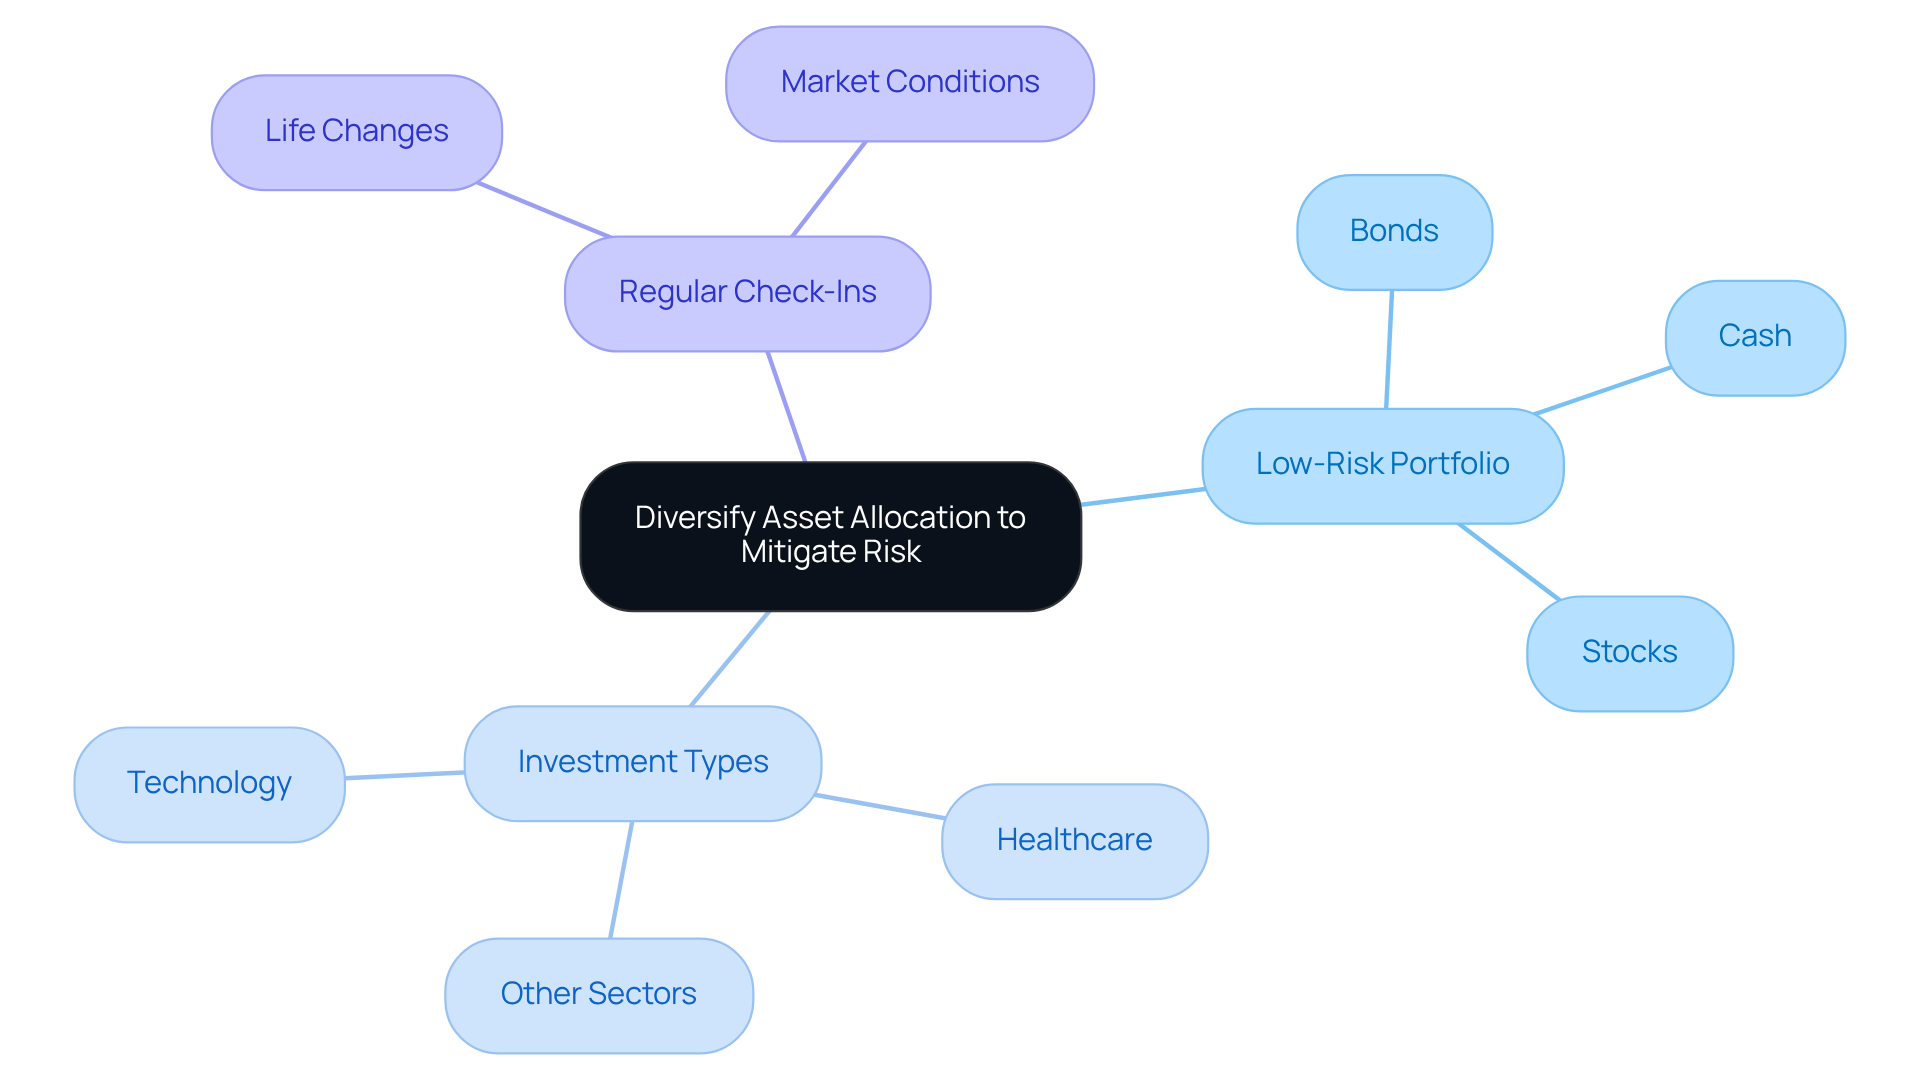
Imagine feeling uncertain about your family’s financial future, especially when you want to provide the best for them. To ease your worries about the future, consider a low risk portfolio allocation that incorporates a balanced mix of stocks, bonds, and other investments that can work together for your family. If uncertainty feels heavy, it might help to adopt a low risk portfolio allocation by leaning more on bonds and cash, while still keeping a little in stocks for growth. You can also spread your investments across different areas, like technology or healthcare, to help balance things out. This way, you can feel more secure and ready for whatever the market brings.
It’s important to check in on your investments regularly, especially when life changes, like welcoming a new baby or starting a new job. Studies show that a thoughtful mix of investments through low risk portfolio allocation can help ease your worries about uncertainty. For instance, a low risk portfolio allocation that includes a variety of 12 to 15 different stocks can really help reduce risks you might face.
At Bright Advisers, we focus on keeping costs low, so more of your money can work for your family’s future. With our clear fee structure, you won’t have to worry about hidden costs, letting you concentrate on what truly matters for your family. With the right support, you can navigate these financial waters with confidence, ensuring your family’s dreams are within reach.
Incorporate Alternatives for Enhanced Portfolio Resilience
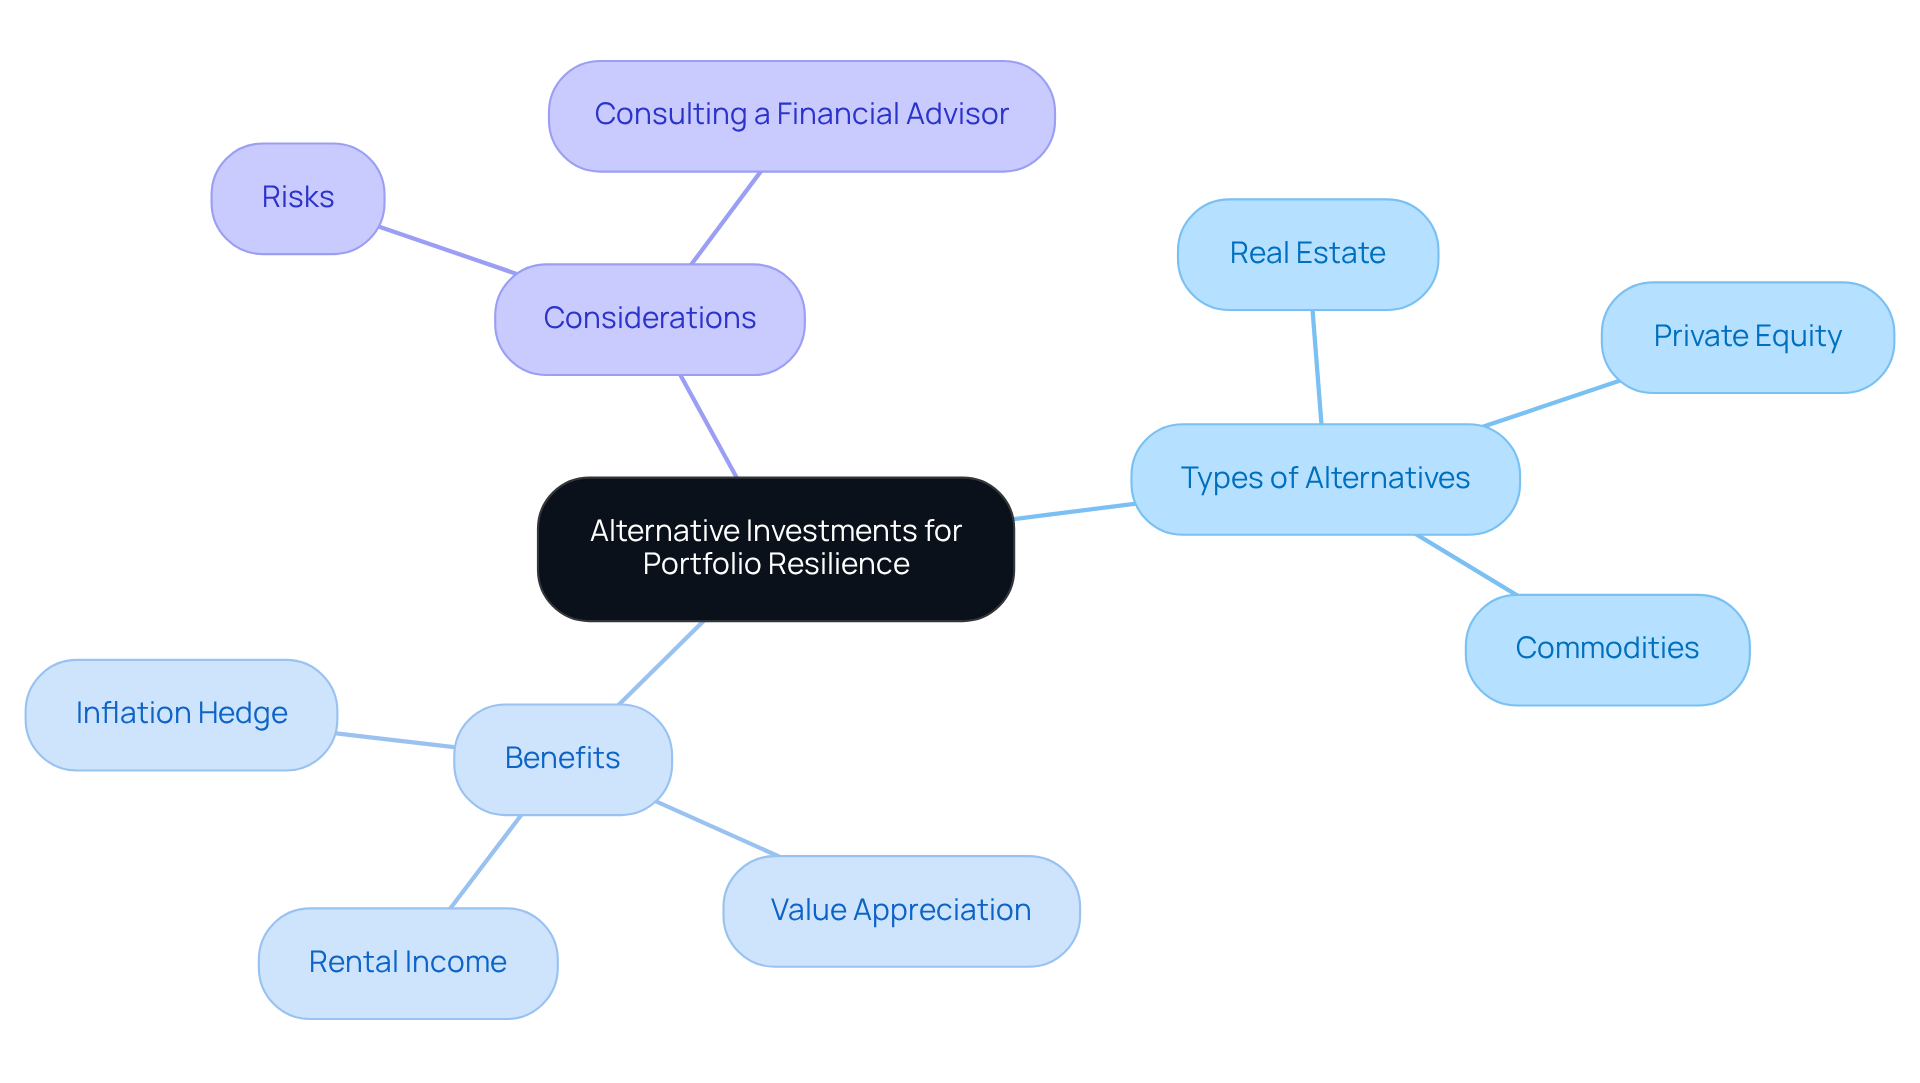
Imagine a world where your family’s financial future feels secure, even when the market gets rocky. Families should consider incorporating alternative assets like real estate, private equity, or commodities into their portfolios. Imagine having investments that can help protect your family during tough market times. For instance, real estate can generate rental income and appreciate in value, while commodities can serve as a hedge against inflation.
Many families are discovering the benefits of diversifying their investments, with a significant number turning to alternatives for added security. Just a small part of your investments in alternatives can help your family feel more secure, even when markets are unpredictable.
At Bright Advisers, we create personalized investment plans that truly reflect your family’s goals and values. It’s important to keep an eye on your investments and make adjustments as needed, ensuring they continue to serve your family’s best interests. Talking to a financial advisor can help your family understand the benefits and risks of these investment options, guiding you towards informed choices.
Remember, every investment comes with its own risks, and it’s essential to stay informed about what that means for your family. We believe in being upfront about our fees, so you can focus on what truly matters-your family’s financial journey.
As more families explore alternative investments, the market is growing rapidly, showing just how important these options can be for your family’s future. By exploring these opportunities, you can take a proactive step towards a more secure financial future for your family.
Conduct Regular Portfolio Reviews and Adjustments
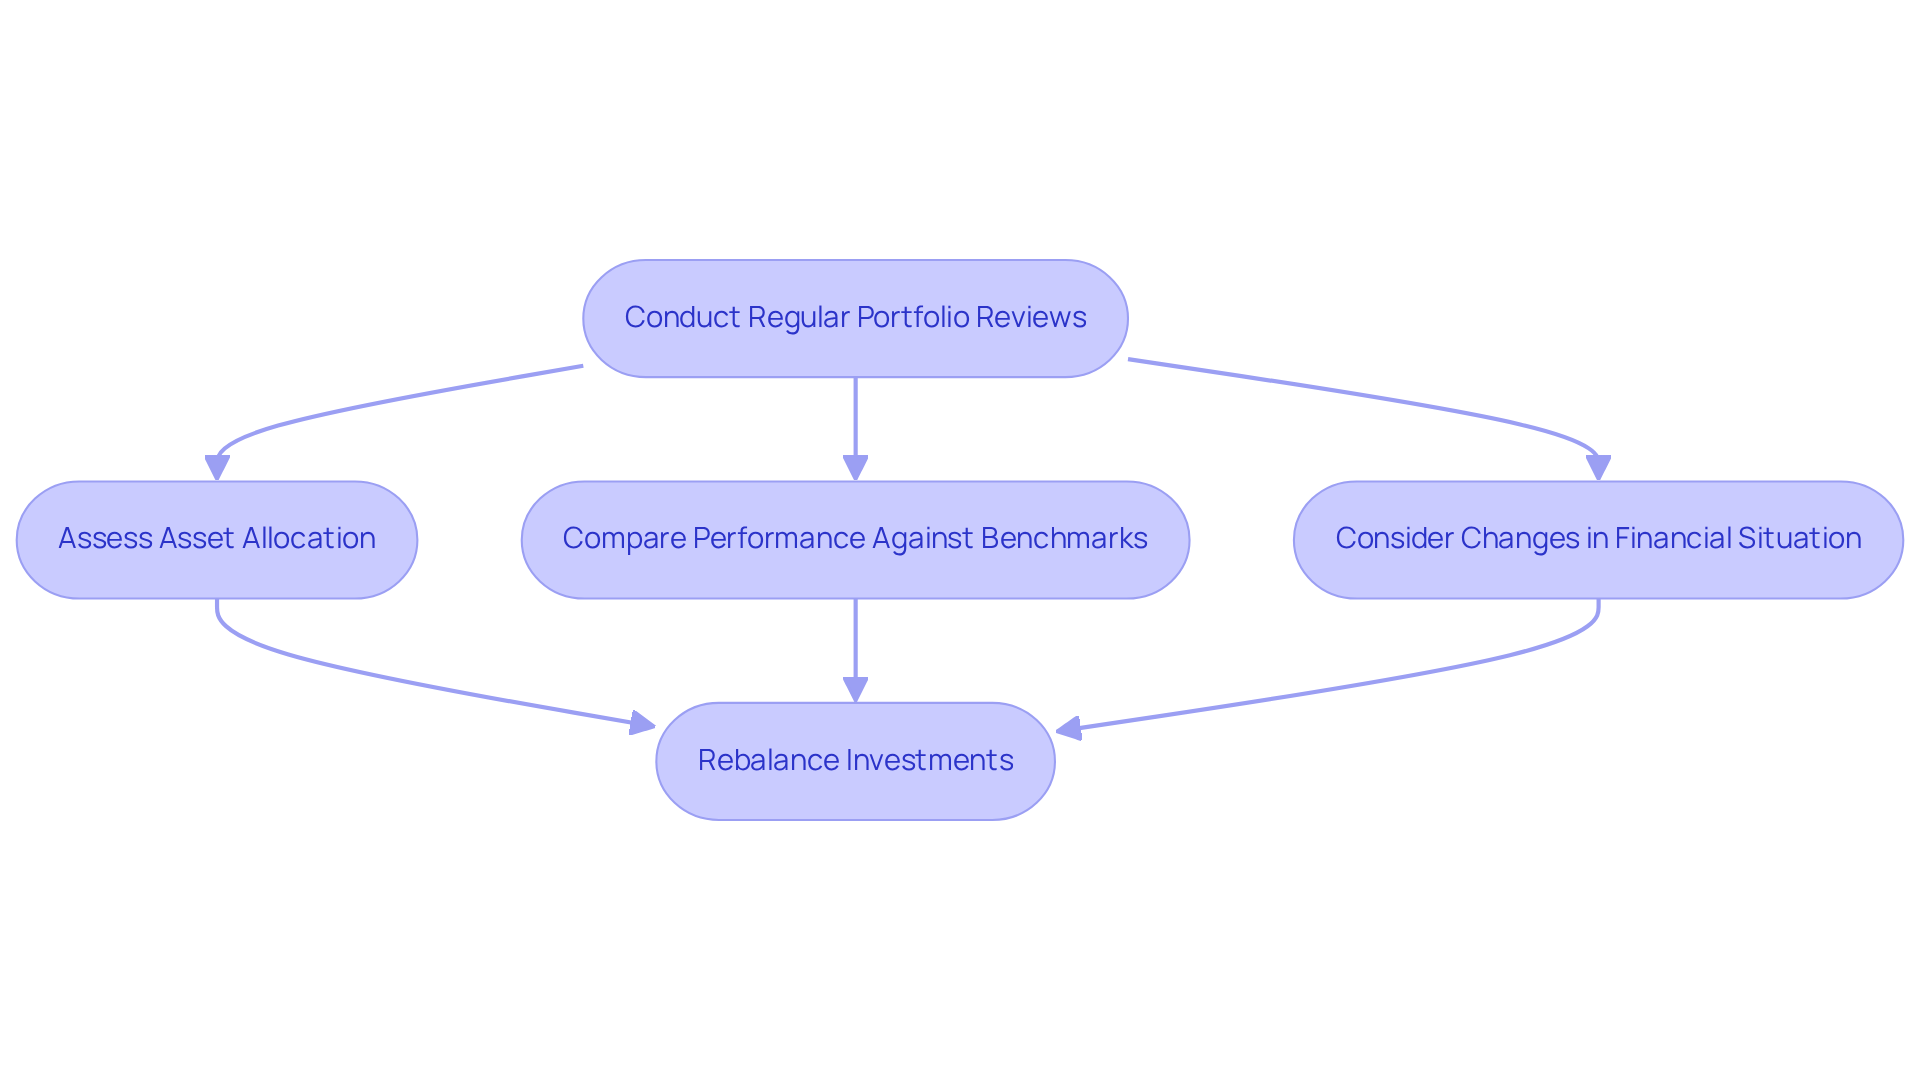
Imagine the worry that comes with uncertain financial futures, especially when you have little ones depending on you. Taking a moment each year to reflect on your family’s financial journey can bring peace of mind and clarity to your goals. Regular portfolio assessments are essential for evaluating performance and ensuring alignment with your family’s low risk portfolio allocation goals. These reviews should focus on:
- Assessing asset allocation, including low risk portfolio allocation
- Comparing performance against benchmarks
- Considering any changes in your financial situation or risk tolerance
Major life events, like a job change or the arrival of a child, often require a reassessment of financial strategies.
Rebalancing your investments is crucial for maintaining a low risk portfolio allocation, especially when certain investments have significantly outperformed or underperformed. This proactive strategy helps families stay aligned with their monetary goals and adapt to evolving market conditions. Families who regularly check in on their financial plans often find themselves feeling more secure and aligned with their dreams.
Let’s take a moment to consider Emily and Mark, who found clarity and confidence through their financial journey with Bright Advisers. By collaborating with them, they conducted a thorough evaluation of their financial situation, encompassing their income, expenses, assets, and liabilities. This partnership enabled them to gain a clearer insight into their economic landscape and formulate a comprehensive strategy to achieve their monetary objectives. The plan not only concentrated on their economic well-being but also offered them the liberty to decide whether or not to continue working.
By prioritizing these reviews, you can feel empowered to make informed decisions that truly support your family’s dreams and aspirations. As a reminder, all advisory services are provided through Lifeworks Advisors, a registered investment adviser, with a transparent fee structure that includes no hidden fees, commissions, or trade fees. Previous performance does not assure future outcomes, and securities holdings are exposed to uncertainty.
Conclusion
Imagine feeling secure about your family’s financial future, knowing you have a plan in place that truly reflects your values. Understanding how to allocate a low-risk portfolio is a key step for young families like yours. When families focus on understanding their comfort with risk and spreading their investments, they can build a strong strategy that protects their money and helps it grow over time.
Talking openly about your financial dreams and checking in on your investments regularly can make a big difference in reaching your goals together as a family. Each of these elements plays a crucial role in building a low-risk portfolio that aligns with your unique financial landscape. Regularly reviewing and adjusting investments ensures that you stay on track to meet your financial objectives, especially during significant life changes.
The path to financial security for your family is all about making informed choices and staying on top of your investments together. By embracing these best practices, you can navigate uncertainties with confidence, ensuring a brighter financial future for your loved ones. Engaging with a fiduciary advisor like Bright Advisers can provide the necessary guidance to tailor investment strategies that reflect your family values and goals. Taking that first step towards a secure financial future means embracing these practices and knowing you’re not alone on this journey.
Frequently Asked Questions
Why is it important to discuss financial goals within a family?
Open discussions about financial goals, timelines for contributions, and feelings about market changes are crucial for a family’s financial well-being.
How can families assess their risk tolerance for investments?
Families can use simple tools to understand how each member feels about financial uncertainty, which can guide investment discussions and decisions.
What investment approach do families with young children typically prefer?
Families with young children often prioritize a low-risk portfolio allocation to preserve capital over seeking aggressive growth, leading to a more cautious investment approach.
How do external factors influence a family’s risk tolerance?
External factors, such as the anticipation of job displacement, can significantly influence risk tolerance. For example, individuals who foresee job displacement are 19% more tolerant of uncertainty.
What factors should families consider when determining their risk tolerance?
Families should consider their income, any debts, and potential future expenses when figuring out how much risk they can handle.
How often should families revisit discussions about their financial situation?
Regularly checking in on financial discussions is essential, especially as a family’s needs change over time.
What services does Bright Advisers offer to families?
Bright Advisers encourages families to join their waitlist to explore personalized wealth management solutions tailored to their unique needs, with all advisory services provided through Lifeworks Advisors, a registered financial adviser.
Are there any disclaimers regarding investment performance?
Yes, previous performance does not assure future outcomes, and securities holdings are exposed to uncertainty.
List of Sources
- Assess Risk Tolerance for Family Investments
- How Much Does Risk Tolerance Change? – PMC (https://pmc.ncbi.nlm.nih.gov/articles/PMC4276321)
- Risk Tolerance: What It Is and How You Can Measure Yours (https://privatebank.bankofamerica.com/articles/what-is-risk-tolerance.html)
- Investment Risk Tolerance Assessment (https://cafnr.missouri.edu/divisions/division-of-applied-social-sciences/research/investment-risk-tolerance-assessment)
- Investment Risk Tolerance and Financial Stress Assessments (https://extension.purdue.edu/hhs/money/programs/investment-risk-tolerance.html)
- Risk Tolerance Assessment | Definition, Types, and Process (https://financestrategists.com/wealth-management/risk-profile/risk-tolerance-assessment)
- Diversify Asset Allocation to Mitigate Risk
- Retirement Portfolio Assets: Allocation by Age (https://schwab.com/learn/story/retirement-portfolio-assets-allocation-by-age)
- Asset Allocation and Diversification | Investor.gov (https://investor.gov/introduction-investing/getting-started/asset-allocation)
- Diversificationquotes — Investment Masters Class (https://mastersinvest.com/diversificationquotes)
- Quotes on Risk Management • Novel Investor (https://novelinvestor.com/quote-category/risk-management)
- 90 Warren Buffet Quotes to Inspire Your Investing Journey (https://sarwa.co/blog/warren-buffett-quotes)
- Incorporate Alternatives for Enhanced Portfolio Resilience
- Alternative Investment Trends 2026 (https://crystalfunds.com/insights/2026-alternative-investment-trends-report)
- The historical benefits of US private real estate (https://invesco.com/us/en/insights/private-real-estate-income-returns.html)
- Why Family Offices Struggle with Alternative Investment Reporting (https://copiawealthstudios.com/blog/why-family-offices-struggle-with-alternative-investment-reporting)
- Alternative Investments Key Part of Single-Family Office Portfolio Strategy (https://icapital.com/newsroom/press-releases/alternative-investments-key-part-of-single-family-office-portfolio-strategy)
- The State of Alternative Investments in Wealth Management 2025 (https://mercer.com/en-us/insights/investments/financial-intermediaries/the-state-of-alternative-investments-in-wealth-management-2025)
- Conduct Regular Portfolio Reviews and Adjustments
- The 11 Best Quotes about Investing (https://birchstreetadvisors.com/blog/the-11-best-quotes-about-investing)
- How Often Should My Investment Portfolio Be Reviewed? – Towerpoint Wealth (https://towerpointwealth.com/how-often-should-my-investment-portfolio-be-reviewed)
- When Life Changes, So Should Your Financial Plan: Here’s Why (https://floydfinancialgroup.com/when-life-changes-so-should-your-financial-plan)
- How Major Life Events Should Reshape Your Financial Plan – Diversified LLC (https://diversifiedllc.com/financial-planning/how-major-life-events-should-reshape-your-financial-plan)
- How Often Should I Review my Investment Portfolio? | BentOak (https://bentoakcapital.com/how-often-should-i-review-my-investment-portfolio)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Investment & Risk Management for high-income W-2 families at Bright Advisers.
Keep reading