

Key Highlights
- Pension plans are essential for ensuring financial security in retirement.
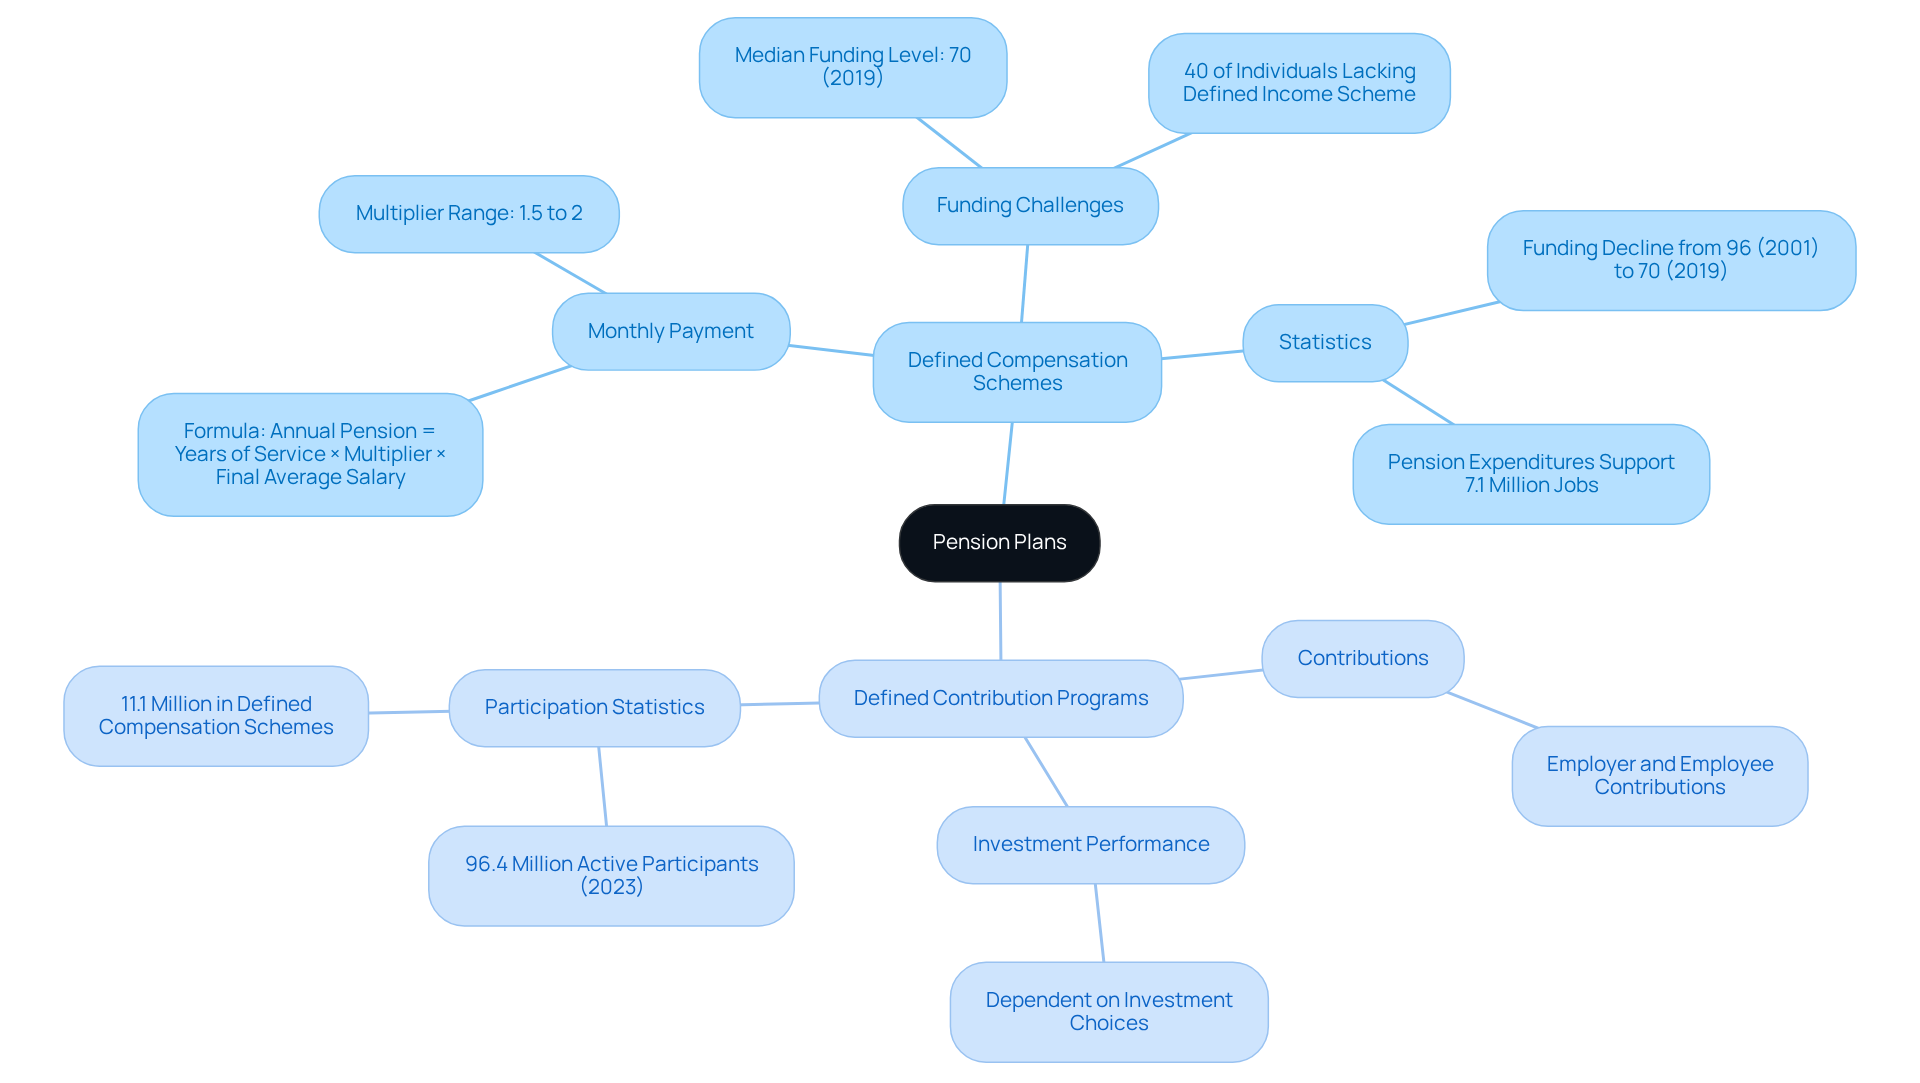
- Defined compensation schemes promise a specific monthly payment based on salary history and years of service.
- Funding challenges exist, with many defined compensation schemes underfunded; for example, the median educator pension system was only 70% financed by 2019.
- Defined contribution programmes, like 401(k) plans, rely on contributions and investment performance, with 96.4 million active participants as of 2023.
- The pension benefit calculation formula is: Pension Benefit = Years of Service × Multiplier × Final Average Salary.
- An example calculation shows that 25 years of service with a 1.8% multiplier and a final average salary of $80,000 results in a $36,000 annual pension.
- Steps to calculate your pension include gathering information, applying the formula, considering additional factors like cost-of-living adjustments, and consulting a financial advisor.
- Understanding pension plans and calculations is crucial for families to secure their financial future.
Introduction
Imagine feeling confident about your family’s financial future, knowing exactly how to calculate your pension benefits. With your family’s financial security on the line, understanding the details of pension plans is essential for long-term stability. This guide will gently walk you through the essential formulas and steps needed to estimate pension benefits, empowering you to make informed decisions about your retirement. It’s important to understand how to navigate the complexities of pension calculations, ensuring a reliable income for your retirement.
Understand the Basics of Pension Plans
Imagine a future where your family’s financial security is assured, even after you’ve stepped away from your career. Pension schemes are vital savings tools that can help determine how much pension will I get with 500k, providing stability in your later years. Let’s explore the two primary types of pension plans that can help you navigate this important aspect of financial planning.
-
Defined Compensation Schemes: These plans promise a specific monthly payment once you retire, based on factors like your salary history and years of service. For example, a common formula might look like this:
- Annual Pension = Years of Service × Multiplier × Final Average Salary
- The multiplier usually ranges from 1.5% to 2%. However, many defined compensation schemes are facing funding challenges. Did you know that by 2019, the median educator pension system was only 70% financed, down from 96% in 2001? This highlights the risks of insufficient funding that could impact the benefits you and your family rely on. It’s also concerning that 40% of individuals nearing retirement lack a defined income scheme, which underscores a significant gap in financial security for many families.
-
Defined Contribution Programs: In these plans, contributions come from the employer, employee, or both, going into an individual account. The amount of pension you receive, specifically how much pension will I get with 500k, depends on the total contributions and how well the investments perform. Common examples include 401(k) plans. As of 2023, there were about 96.4 million active participants in defined contribution schemes, compared to only 11.1 million in defined compensation schemes. This shift indicates a change in how families are planning for retirement.
It’s important to understand these differences so you can make the best choices for your family’s future. Defined benefit schemes can offer a steady income, but it’s essential to be aware that some may not be fully funded, which could affect your family’s security. On the other hand, defined contribution arrangements provide flexibility, but they also mean you’ll need to manage investment risks. By grasping these distinctions, you can take confident steps toward a secure retirement for your family. Remember, we’re here for you as you navigate this journey.
Learn the Pension Calculation Formula
Imagine feeling confident about your family’s financial future, knowing exactly how to calculate your pension benefits. Let’s break down how you can calculate your pension benefits in a way that feels manageable and clear:
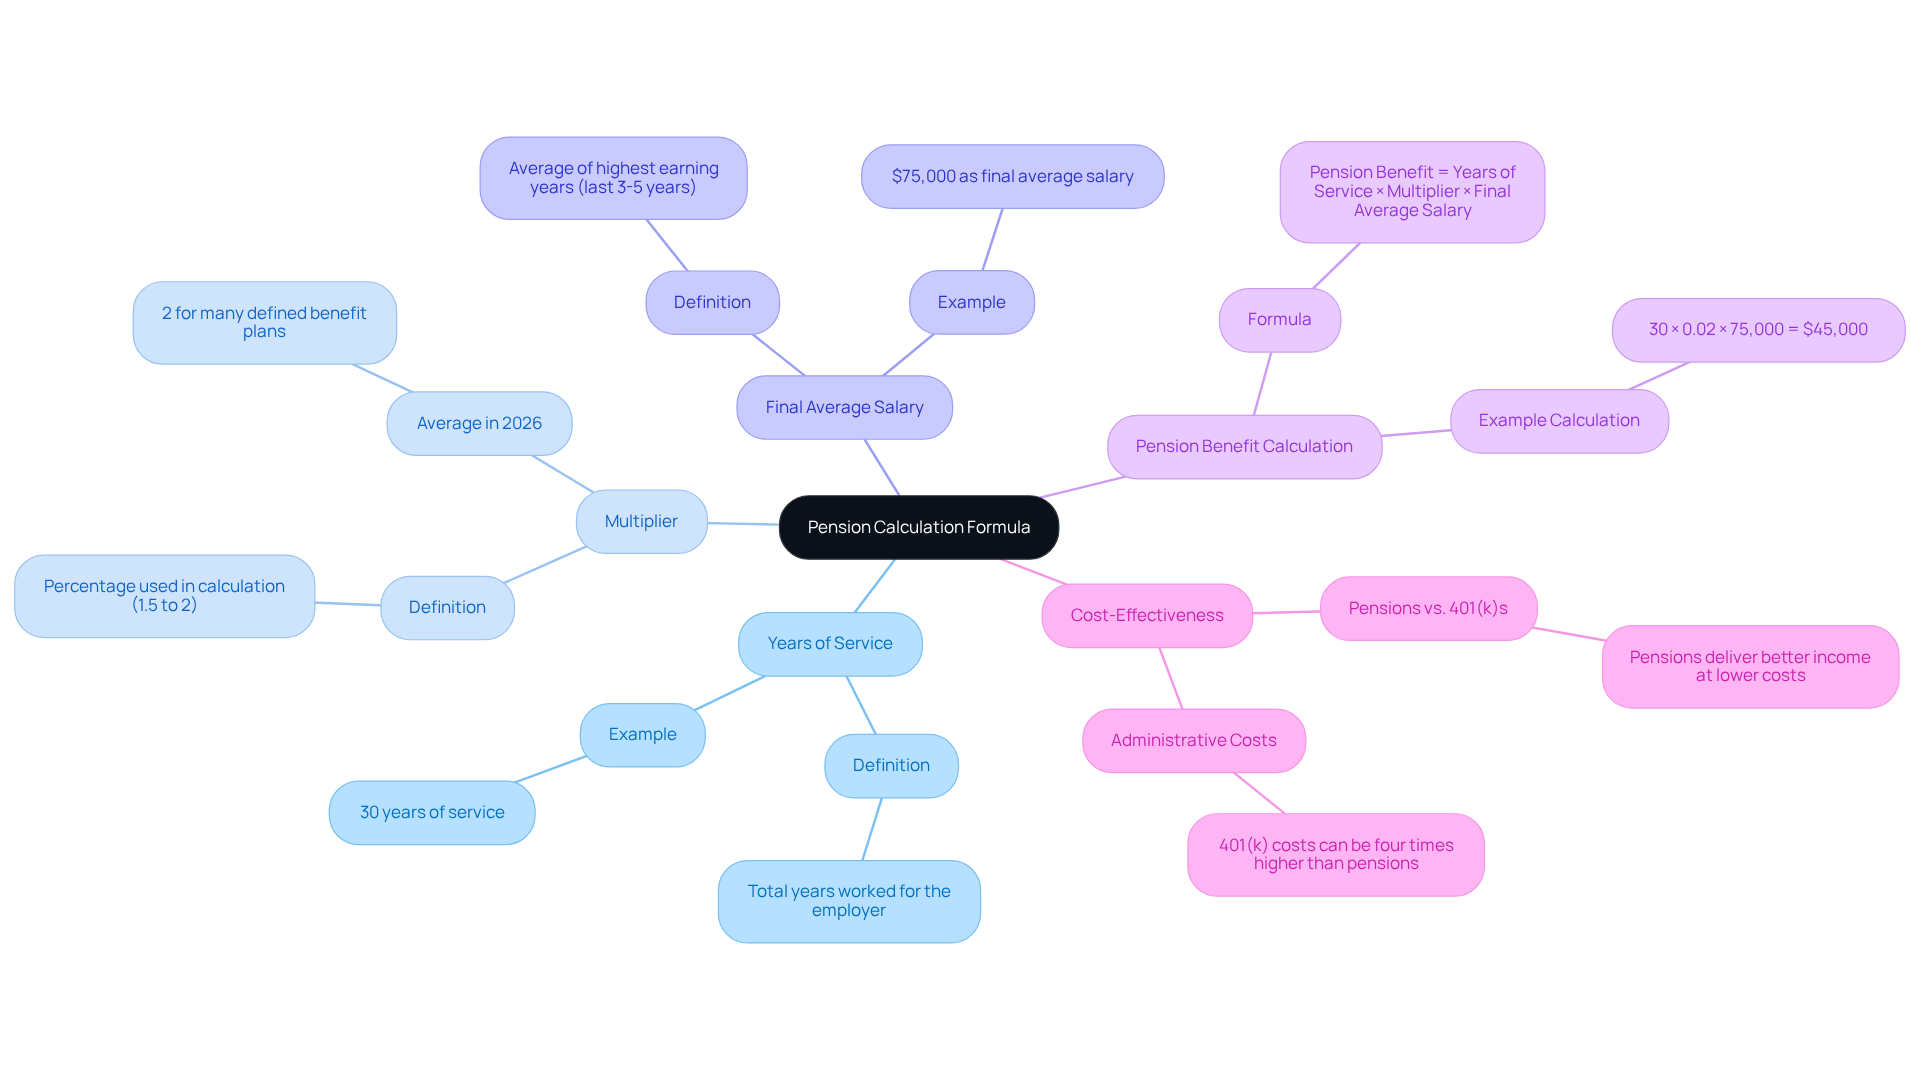
Pension Benefit = Years of Service × Multiplier × Final Average Salary
- Years of Service: This represents the total number of years you have worked for the employer sponsoring the pension plan.
- Multiplier: This percentage varies by option, typically ranging from 1.5% to 2%. In 2026, the average retirement multiplier is around 2% for many defined benefit plans.
- Final Average Salary: This is usually calculated based on your highest earning years, often the last three to five years of employment.
For example, if you worked for 30 years, have a multiplier of 2%, and your final average salary is $75,000, your annual pension would be:
Pension Benefit = 30 × 0.02 × 75,000 = $45,000
This means that pensions can offer you a reliable income in retirement, helping you maintain your family’s lifestyle and peace of mind. Pensions are recognized for their cost-effectiveness, providing similar or superior income for later years at nearly half the expense of 401(k)-style accounts. Indeed, a 2019 study showed that the yearly distribution from a 401(k) was merely 24% of the average allocations offered by a retirement scheme.
Many families find the pension calculation process daunting and overwhelming, especially when planning for their future. However, understanding this formula is crucial for families like yours, as it highlights how your hard work and dedication can lead to a secure retirement for you and your loved ones. Together, we can navigate this journey toward financial stability.
Apply the Formula: Example Calculation
Imagine facing retirement without a clear plan – how would that impact your family’s future? Let’s walk through an example calculation together, using a simple formula that can help you understand how much pension will I get with 500k.
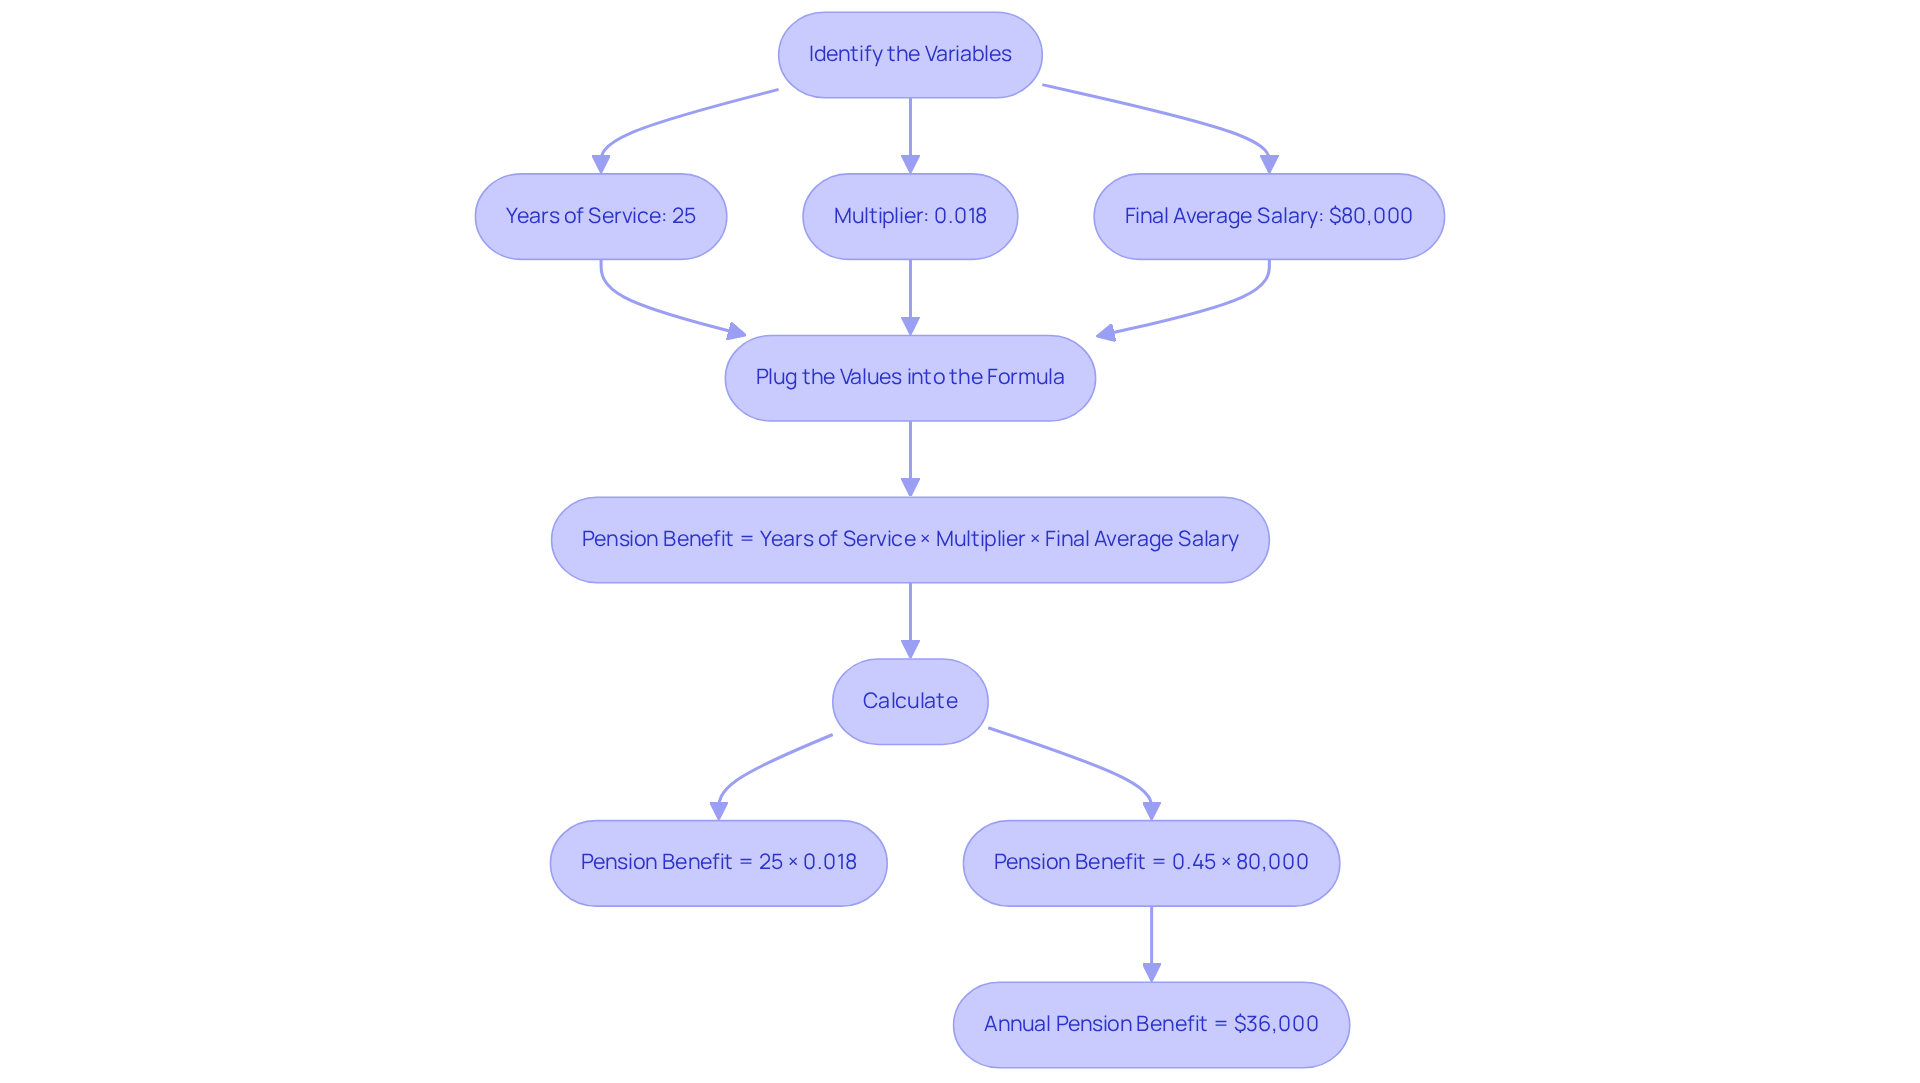
Scenario: You’ve dedicated 25 years to your company, your multiplier is 1.8%, and your final average salary is $80,000.
-
Identify the Variables:
- Years of Service = 25
- Multiplier = 0.018
- Final Average Salary = $80,000
-
Plug the Values into the Formula:
- To find your pension benefit, we can use this formula:
- Pension Benefit = Years of Service × Multiplier × Final Average Salary
- So, Pension Benefit = 25 × 0.018 × 80,000
-
Calculate:
- First, let’s break it down:
- Pension Benefit = 25 × 0.018 = 0.45
- Now, multiply that by your final average salary:
- Pension Benefit = 0.45 × 80,000 = $36,000
This means that, with careful planning, your family could count on an annual pension benefit of $36,000, providing peace of mind for your future together. Remember, understanding these numbers is a step toward securing a brighter tomorrow for your loved ones. We’re here for you, ready to help you navigate this journey.
Calculate Your Pension: A Step-by-Step Process
Imagine feeling confident about your retirement, knowing you’ve planned well for your family’s future.
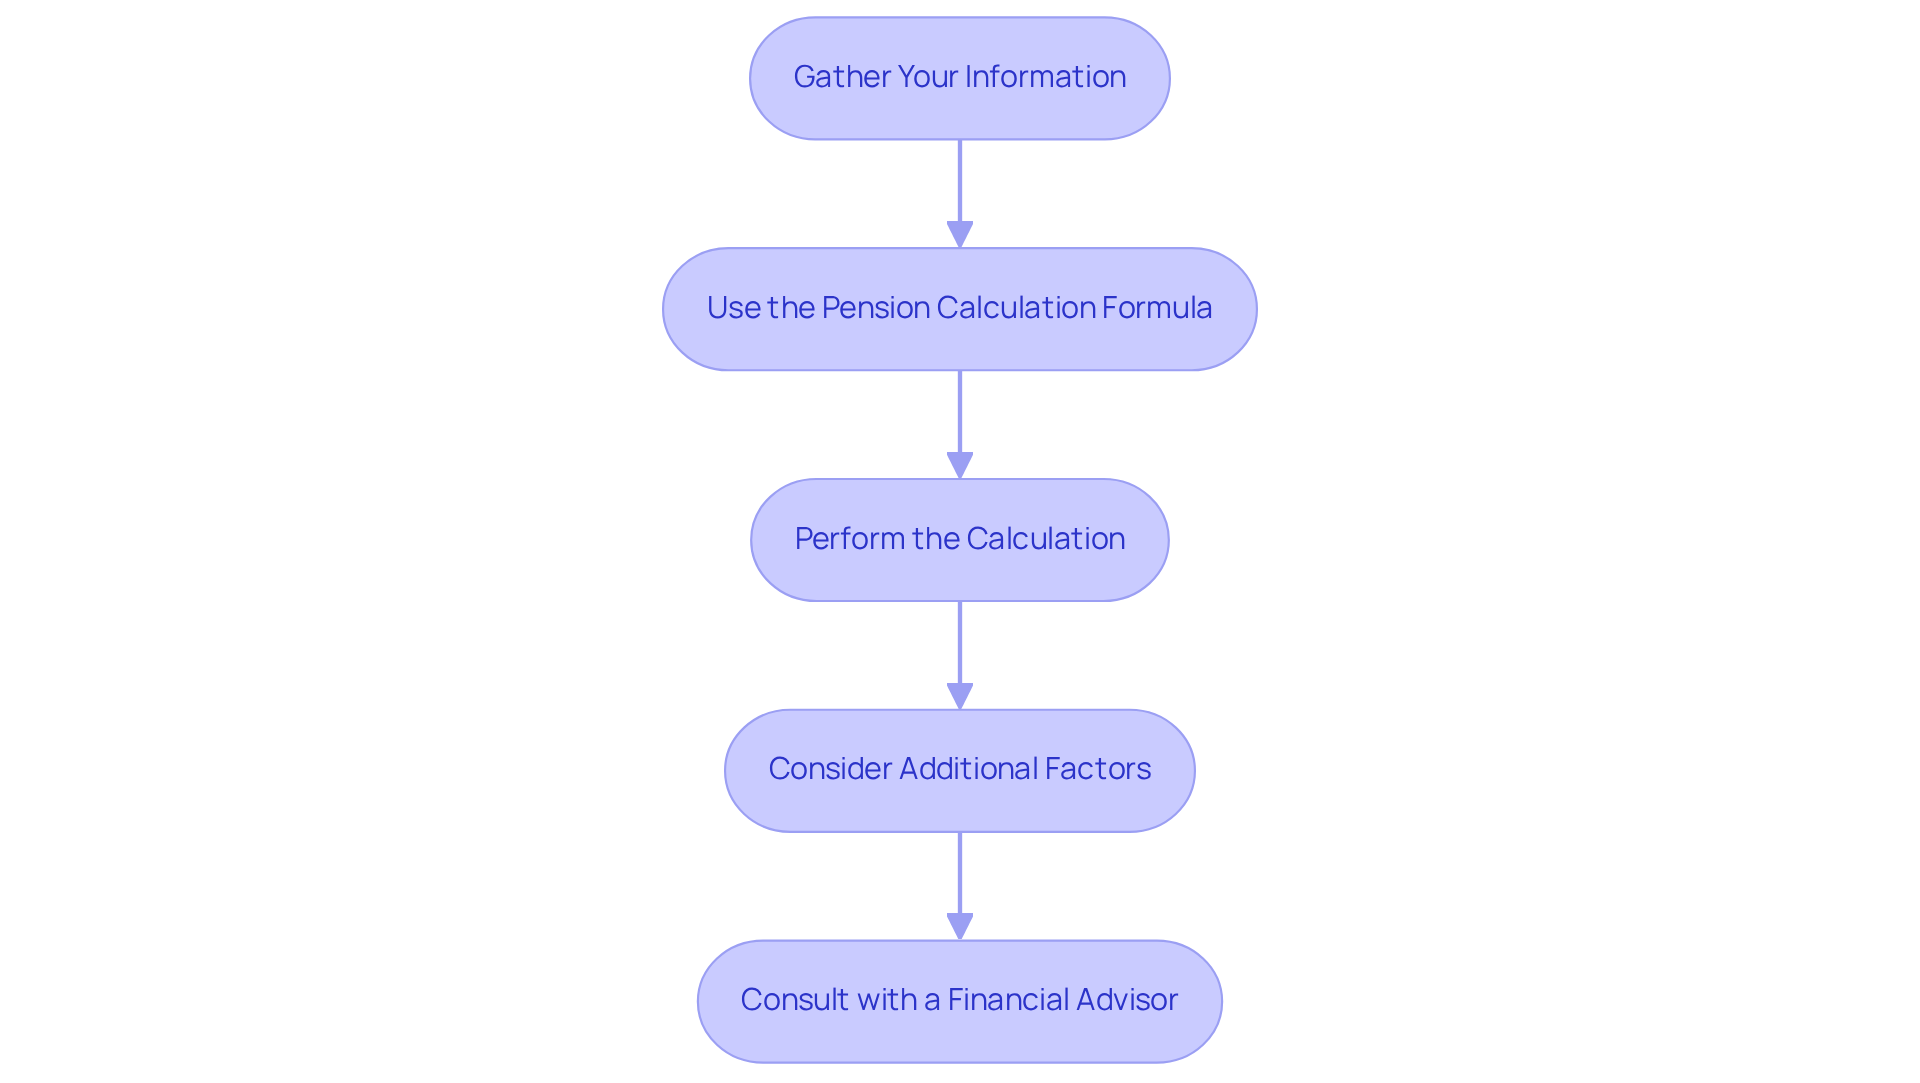
To calculate your pension, follow these steps:
-
Gather Your Information:
- Start by determining your total years of service with your employer. You earn one year of service credit for every 2,080 regular hours worked.
- Next, find out your retirement plan’s multiplier, which is typically set at 1.5% for most state employees.
- Finally, calculate your final average salary (FAC) based on your highest earning years, usually the highest three consecutive years of compensation.
-
Use the Pension Calculation Formula:
- Now, apply the formula: Pension Benefit = Years of Service × Multiplier × Final Average Salary. For instance, if you have 25 years of service, a multiplier of 1.5%, and a final average salary of $60,000, your annual retirement payment would be $22,500.
-
Perform the Calculation:
- Substitute your values into the formula to calculate your annual pension benefit. This simple calculation shows you what to expect for your retirement.
-
Consider Additional Factors:
- It’s important to check if your pension plan includes cost-of-living adjustments (COLAs) or survivor benefits. Approximately 75% of public retirement plans in the U.S. offer automatic COLAs, which help maintain purchasing power against inflation. Without these adjustments, the value of your retirement fund can erode significantly over time. In fact, inflation can reduce the purchasing power of your retirement funds, making it crucial to consider these factors in your planning.
-
Consult with a Financial Advisor:
- If you’re feeling uncertain or have questions, we’re here to help. Reach out to a fiduciary advisor like Bright Advisers for personalized guidance. They can assist you in exploring your retirement options and incorporating them into your overall financial strategy, ensuring you make informed choices that align with your family’s financial objectives. As mentioned by Matt Kasper, ‘Pensions as an employee benefit have been on the decline but they still serve as a significant income source for those that have them.’
Taking these steps today can lead to a more secure tomorrow for you and your loved ones.
Conclusion
Imagine the peace of mind that comes from knowing your family’s financial future is secure. Understanding how to calculate your pension can help you see what your retirement might look like. It’s important to understand the differences between pension plans so you can make choices that benefit your family. Knowing these details can empower your family to build a secure financial future together.
Throughout this guide, we’ve shared key insights that can help you navigate this journey. From understanding your pension plan’s specifics to recognizing the potential risks of underfunded plans, each step is crucial for your family’s stability. Consulting with a fiduciary advisor like Bright Advisers can provide the support you need to feel confident in your decisions.
Taking control of your pension planning can bring peace of mind and security for your loved ones. Engaging with a knowledgeable advisor can further enhance this process, ensuring that your financial strategy aligns with your family’s goals. Reaching out for support today can pave the way for a brighter tomorrow for you and your family.
Frequently Asked Questions
What are the two primary types of pension plans?
The two primary types of pension plans are Defined Compensation Schemes and Defined Contribution Programs.
How do Defined Compensation Schemes work?
Defined Compensation Schemes promise a specific monthly payment upon retirement, calculated based on factors like salary history and years of service. A common formula is: Annual Pension = Years of Service × Multiplier × Final Average Salary, with the multiplier typically ranging from 1.5% to 2%.
What are the funding challenges associated with Defined Compensation Schemes?
Many Defined Compensation Schemes are facing funding challenges, with the median educator pension system only 70% financed as of 2019, down from 96% in 2001. This indicates potential risks to the benefits that retirees rely on.
What are Defined Contribution Programs?
Defined Contribution Programs involve contributions from the employer, employee, or both, deposited into an individual account. The pension amount received depends on total contributions and investment performance, with common examples being 401(k) plans.
How many participants are there in Defined Contribution Programs compared to Defined Compensation Schemes?
As of 2023, there were approximately 96.4 million active participants in Defined Contribution Programs, compared to only 11.1 million in Defined Compensation Schemes.
What are the advantages and disadvantages of Defined Compensation Schemes?
Defined Compensation Schemes can offer a steady income in retirement, but they may not be fully funded, which could impact financial security.
What are the advantages and disadvantages of Defined Contribution Programs?
Defined Contribution Programs provide flexibility in retirement planning, but they also require individuals to manage investment risks, as the pension amount depends on investment performance.
Why is it important to understand the differences between these pension plans?
Understanding the differences between Defined Compensation Schemes and Defined Contribution Programs is crucial for making informed decisions about retirement planning and ensuring financial security for your family.
List of Sources
- Understand the Basics of Pension Plans
- U.S. Bureau of Labor Statistics (https://bls.gov/charts/employee-benefits/percent-access-participation-takeup-retirement-benefits.htm)
- Are Pensions Dead? Comparing Defined Benefit Plans to Defined Contribution Plans (https://wealthtender.com/insights/defined-benefit-vs-defined-contribution)
- Why Pensions Are Important – Pension Rights Center (https://pensionrights.org/resource/why-pensions-are-important)
- A Better Bang for the Buck 3.0 – NIRS (https://nirsonline.org/research/betterbang3)
- A Visual Depiction of the Shift from Defined Benefit (DB) to Defined Contribution (DC) Pension Plans in the Private Sector (https://congress.gov/crs-product/IF12007)
- Learn the Pension Calculation Formula
- Final Average Salary (https://osc.ny.gov/retirement/publications/1644/final-average-salary)
- Pension Facts and Retirement Basics | NCPERS – National Conference on Public Employee Retirement Systems (https://ncpers.org/pension-facts)
- What is a Defined Benefit Plan? (https://equable.org/resource/what-is-a-defined-benefit-plan-pension-plan)
- Pension Basics: How Pension Benefits Are Calculated (https://equable.org/resource/pension-basics-how-pension-benefits-are-calculated)
- Apply the Formula: Example Calculation
- How to Calculate Your Pension | Steps, Types, Key Factors (https://financestrategists.com/retirement-planning/qualified-retirement-plans/defined-benefit-plan/how-to-calculate-your-pension)
- FERS Retirement Calculator 2026 — Estimate Your Federal Pension | Capital Wealth (https://capitalwealth.com/services/federal-benefits/fers-calculator)
- Pension Basics: How Pension Benefits Are Calculated (https://equable.org/resource/pension-basics-how-pension-benefits-are-calculated)
- Calculate Your Pension: A Step-by-Step Process
- Why COLAs Matter for Retirement Security (https://equable.org/resource/why-colas-matter-for-retirement-security)
- How to Calculate Your Pension in 3 Steps (https://modwm.com/how-to-calculate-your-pension-in-3-steps)
- Estimating Your Pension (https://michigan.gov/orsstatedb/overview/estimating-your-pension)
- Can Your Pension Plan Afford To Give COLAs? – Pension Rights Center (https://pensionrights.org/resource/can-your-pension-plan-afford-to-give-colas)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Estate Planning for high-income W-2 families at Bright Advisers.
Keep reading