

Key Highlights:
- A Roth IRA allows for after-tax contributions, leading to tax-free growth and withdrawals during retirement.
- Grandparents can open a Roth IRA for grandchildren who have earned income, with no minimum age requirement.
- Contributing $2,000 annually for ten years could grow to over $143,000 by retirement, illustrating the power of compounding interest.
- Eligibility for a custodial IRA requires the child to have earned income from jobs like babysitting or lawn care.
- An adult custodian must manage the account until the child reaches the age of majority (typically 18 or 21).
- Contributions are limited to the child’s earned income or a maximum of $7,500 for 2026.
- Starting a Roth IRA early provides significant long-term financial security and teaches children about financial responsibility.
- Tax-free growth and flexible withdrawals make Roth IRAs an attractive option for young investors.
Introduction
Imagine a world where your grandchildren’s financial futures are secure, thanks to the thoughtful investments made by you, their grandparents. A Roth IRA offers a wonderful opportunity to nurture long-term wealth. Contributions can grow tax-free, and under certain conditions, withdrawals can be made without penalties. But you might be wondering: can a grandparent actually open a Roth IRA for their grandchild?
This question opens the door to understanding custodial accounts and highlights the profound impact that early financial planning can have on a child’s future. Imagine if you could set your grandchild on a path to financial stability, giving them a head start in life.
It’s important to understand that starting a Roth IRA for your grandchild is not just about the money; it’s about instilling values of saving and investing. By taking this step, you’re not only securing their financial future but also teaching them the importance of planning ahead.
Together, we can navigate this journey. With the right guidance, you can make informed decisions that align with your family’s values and priorities. We’re here for you, ready to support you in making these meaningful investments for your loved ones.
Understand the Basics of a Roth IRA for Grandchildren
Imagine a future where your grandchildren can thrive financially, thanks to a thoughtful investment today. An Individual Retirement Account (IRA) is a wonderful way to help them build a secure financial foundation. With an IRA, individuals can contribute , meaning taxes are settled upfront. The beauty of this account lies in its key advantages: tax-free growth of investments and tax-free withdrawals during retirement, as long as certain conditions are met.
It is important for grandparents to know if a grandparent can open a Roth IRA for a grandchild, as it can be especially beneficial. It allows for long-term growth, harnessing the power of compounding interest over many years. What’s even more encouraging is that there’s no minimum age to open an IRA. This means children who have earned income from jobs or self-employment can start their journey toward financial independence early. This account can be a powerful tool for grandparents who want to secure their grandchildren’s financial future, raising the question of how can a grandparent open a Roth IRA for a grandchild, which perfectly aligns with Bright Advisers’ commitment to innovative wealth management for families.
Consider this: contributing just $2,000 annually for ten years could grow to over $143,000 by age 66, assuming a 6% annual return. This illustrates the importance of starting early, as funds can grow exponentially over time. A contribution made at age 8 can yield significant returns over 50 years, potentially reaching around $500,000 by retirement. It’s heartening to see that parents and grandparents are increasingly recognizing the value of individual retirement accounts for minors. In fact, the percentage of young households (ages 20-29) with an IRA tripled from 6.6% in 2016 to 19.2% in 2022, reflecting a growing trend.
Families are taking action by establishing custodial IRAs for children involved in jobs like babysitting or lawn care. This not only allows them to benefit from compound interest but also ensures a tax-free income in retirement. Investment consultants at Bright Advisers emphasize that starting an IRA early not only provides an economic advantage but also teaches valuable lessons about earning and investing.
In summary, an Individual Retirement Account is a powerful tool for grandparents, as it raises the question of can a grandparent open a Roth IRA for a grandchild to enhance their financial future. It offers a unique opportunity for tax-free growth and withdrawals while instilling the importance of financial responsibility. Together, we can navigate this journey and ensure a brighter tomorrow for our loved ones.

Learn the Custodial Roth IRA Rules and Requirements
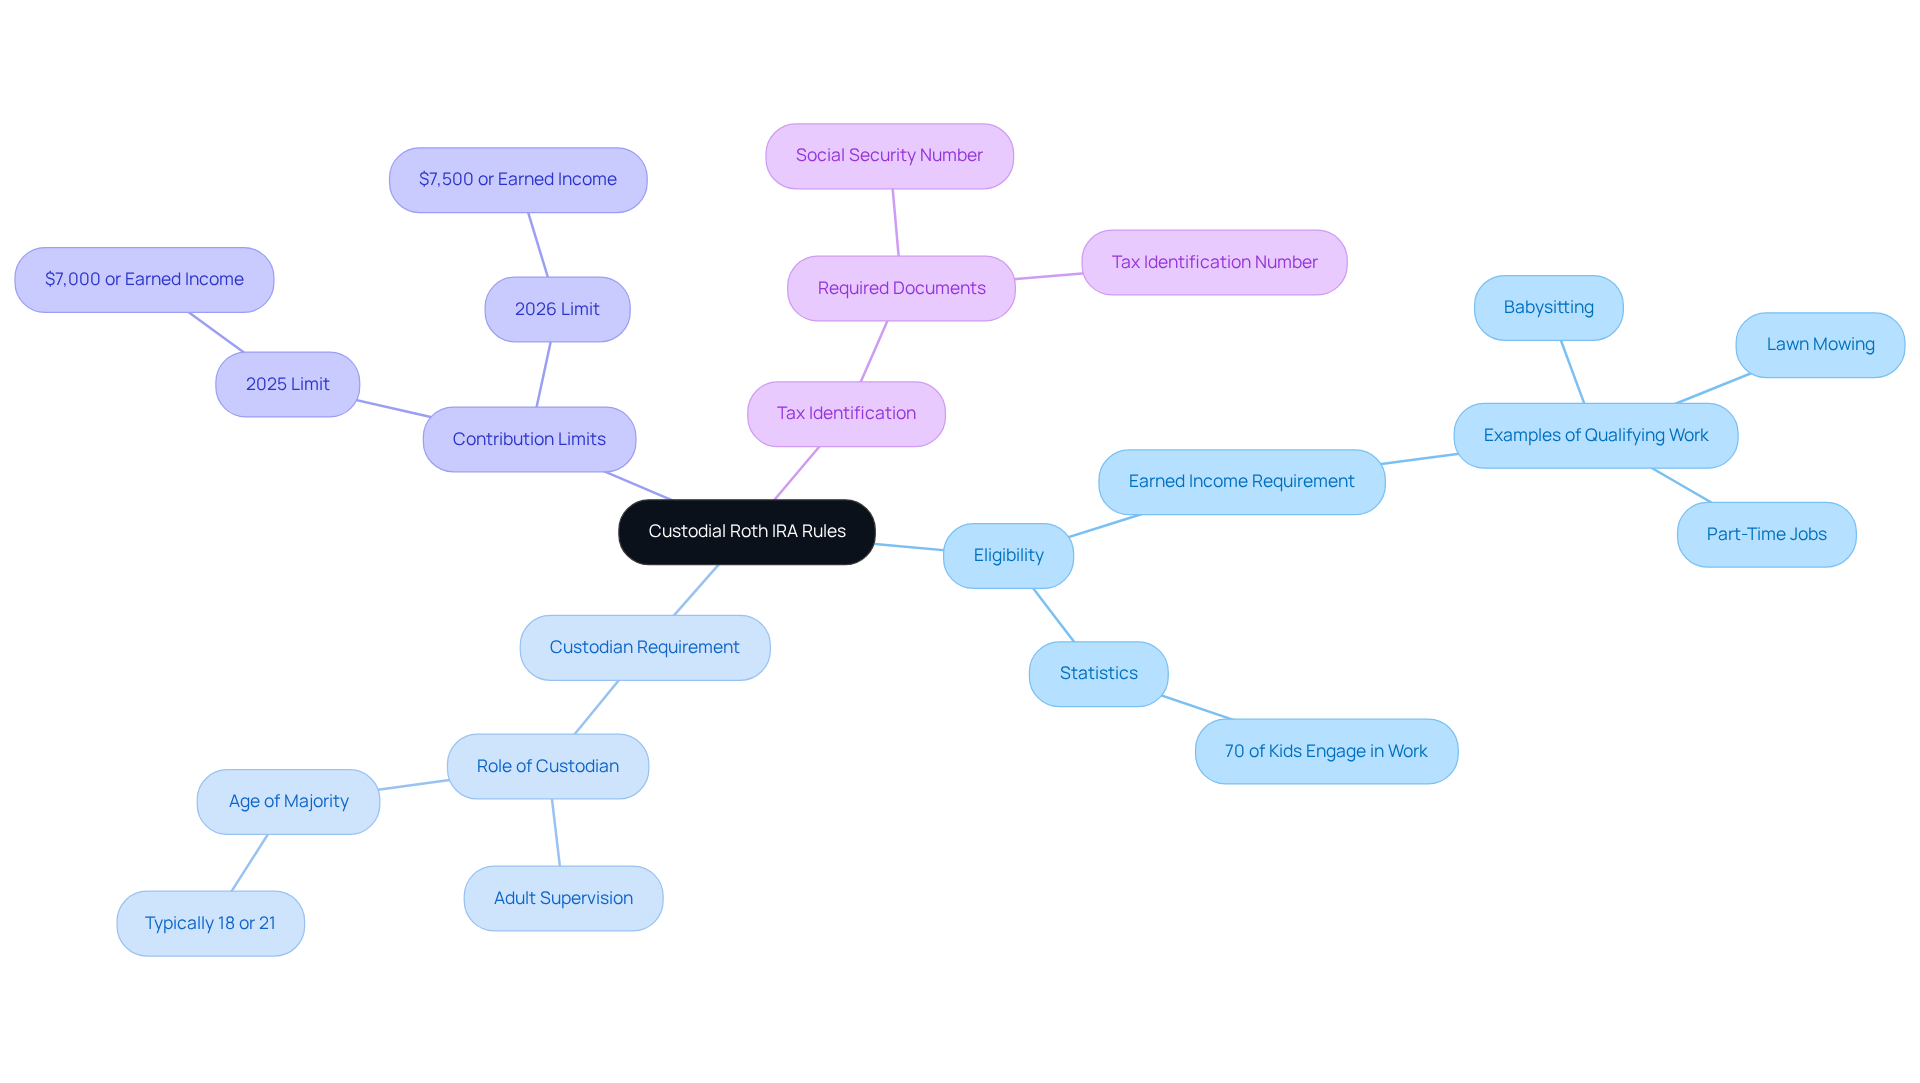
A wonderful step towards your grandchild’s financial future is establishing a custodial Roth IRA, and many wonder, can a grandparent open a Roth IRA for a grandchild? Here are some key rules to keep in mind:
- Eligibility: Your grandchild needs to have earned income, which can come from various jobs like babysitting, lawn mowing, or any work that generates taxable income. Did you know that around 70% of kids engage in some form of work that qualifies them for this account?
- Custodian Requirement: An adult, usually a parent or grandparent, must act as the custodian of the account until the child reaches the age of majority, which varies by state (typically 18 or 21). This oversight is crucial, ensuring the account is managed responsibly during their formative years.
- Contribution Limits: Contributions to the IRA can’t exceed the child’s earned income for the year or the annual contribution limit, which is set at $7,500 for 2026. This limit allows for significant tax-free growth over time, making it a powerful tool for long-term savings.
- Tax Identification: Your grandchild will need a Social Security number or tax identification number to open the account. This is essential for complying with IRS regulations.
By understanding these guidelines, you can effectively set up a custodial IRA for your grandchildren, which leads to the question of whether a grandparent can open a Roth IRA for a grandchild, fostering financial literacy and giving them a head start on building wealth. As one tax expert wisely noted, “Starting a retirement account early can significantly enhance a child’s economic future, allowing them to benefit from tax-free growth over time.”
Together, we can navigate this journey, ensuring your grandchild has the .
Follow Steps to Open a Roth IRA for Your Grandchild
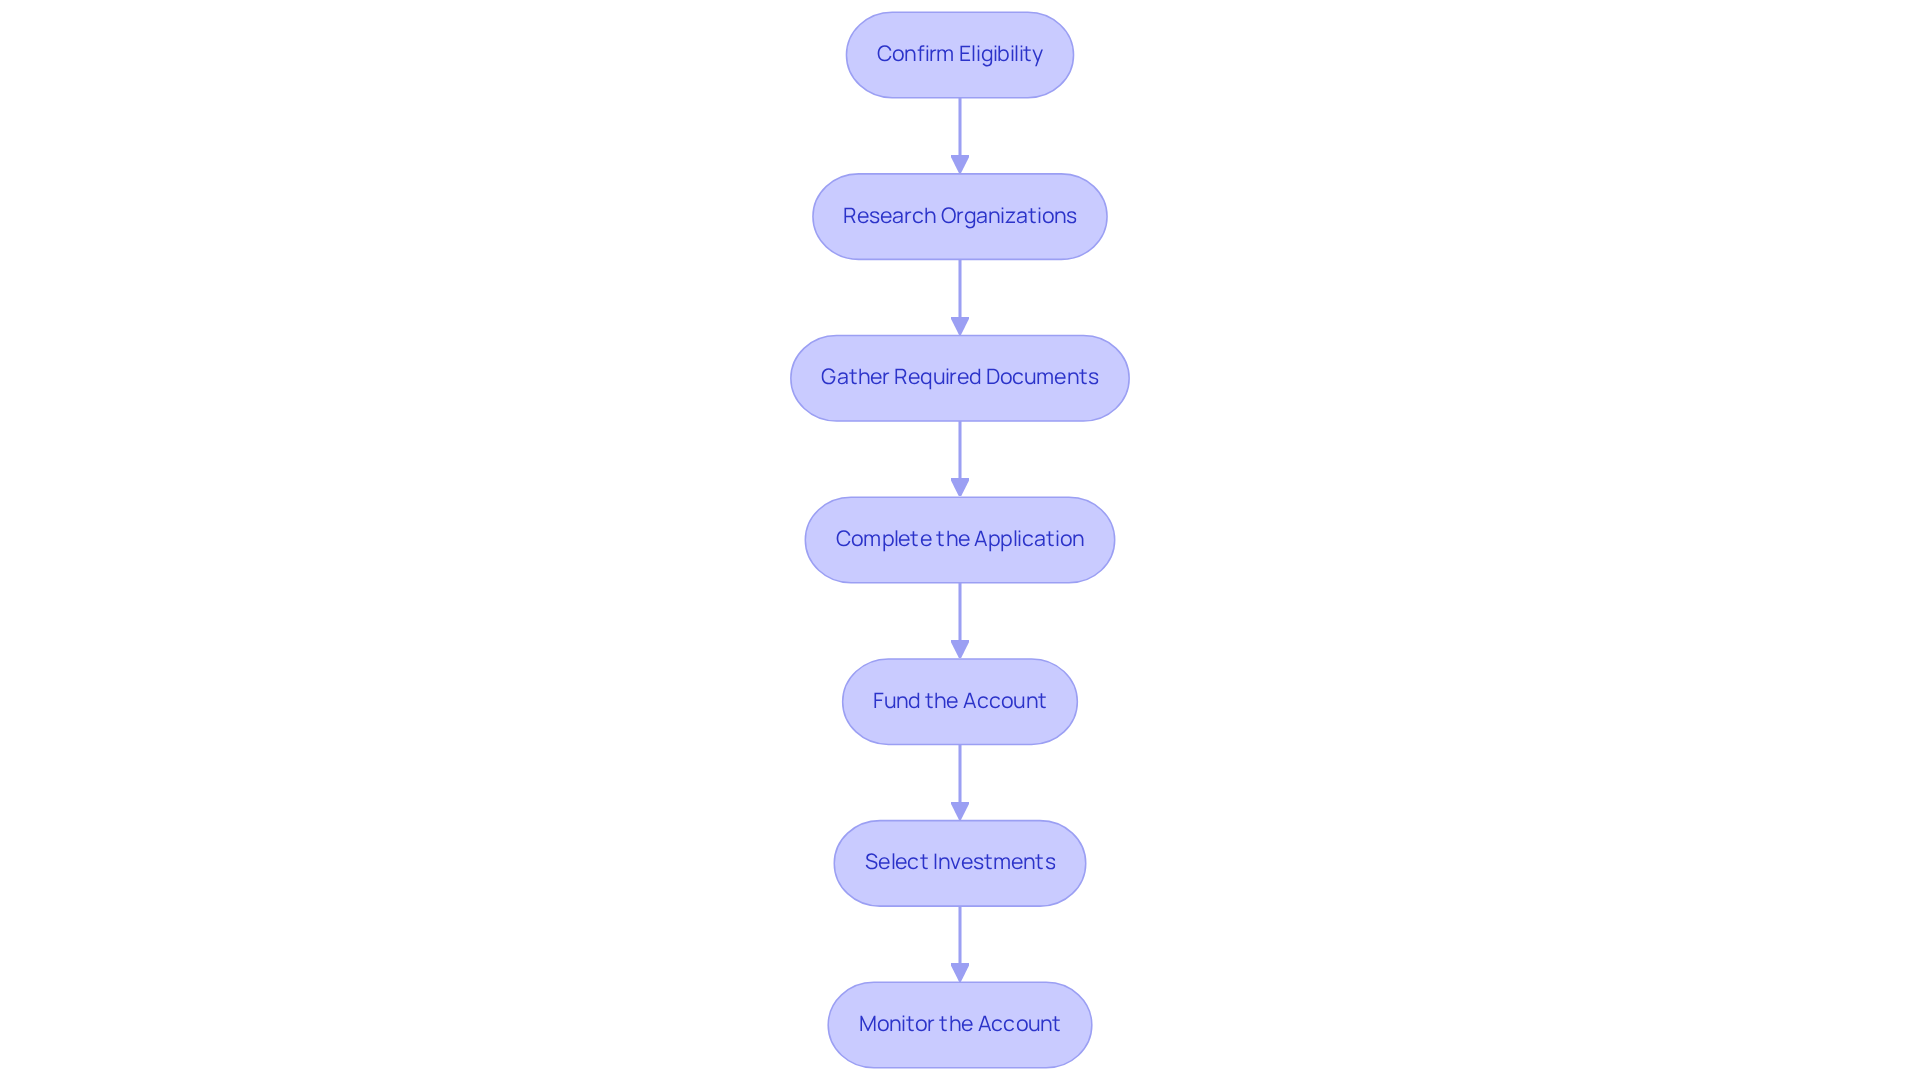
A wonderful step towards your grandchild’s financial future is to consider, can a grandparent open a Roth IRA for a grandchild? Here’s how to do it, step by step:
- Confirm Eligibility: First, check if your grandchild has earned income for the year. This can be shown through pay stubs or tax returns. It’s important to ensure they qualify, especially when considering if a grandparent can open a Roth IRA for a grandchild, as this sets the foundation for their savings.
- Take some time to research and select an organization that answers the question, can a grandparent open a Roth IRA for a grandchild, by offering custodial Roth IRAs. Look for one that has low fees and a variety of investment options. This choice can make a big difference in their financial journey.
- Gather Required Documents: You’ll need to collect some essential documents. This includes the minor’s Social Security number, proof of their earned income, and identification for both you (the custodian) and the minor. Having everything ready will make the process smoother.
- Complete the Application: Fill out the application form provided by the institution carefully. Accuracy is key here to avoid any delays that could hinder your grandchild’s savings.
- Fund the Account: Make the initial contribution to the Roth IRA. Just remember, when considering if a grandparent can open a Roth IRA for a grandchild, it shouldn’t exceed your grandchild’s earned income or the annual limit, which is $7,500 for 2026. This step is crucial for kickstarting their investment journey.
- Select Investments: Work alongside the financial institution to choose suitable investments for the account. Focus on options that have long-term growth potential. For example, a single $7,500 deposit made at age 15 could grow to over $200,000 in 50 years with a 7% annual return. Imagine the possibilities for your grandchild’s future!
- Monitor the Account: Regularly check in on the account’s performance. Make adjustments as needed to align with your grandchild’s financial goals. This proactive approach not only nurtures their financial literacy but also lays the groundwork for a .
Together, we can navigate this journey, ensuring your grandchild has the best start possible!
Explore the Benefits of a Roth IRA for Your Grandchild
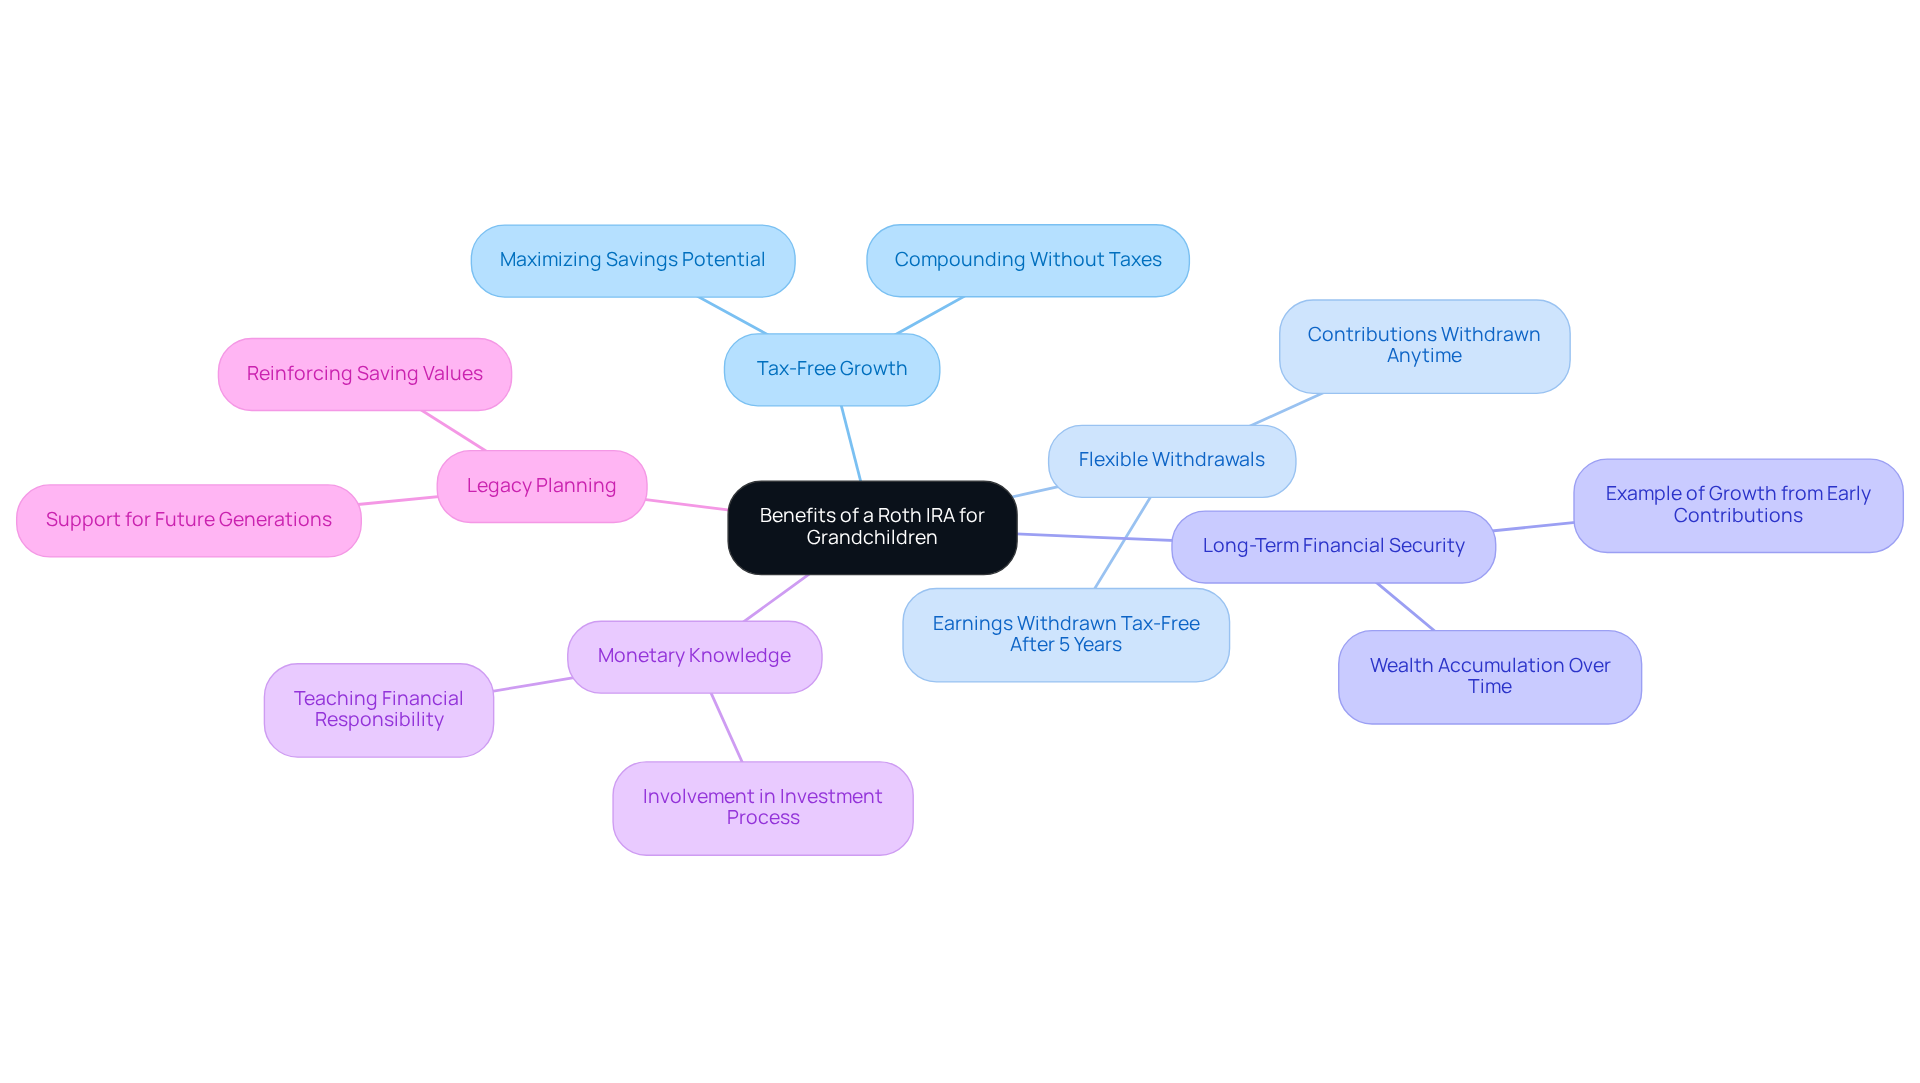
Imagine the benefits of asking, can a grandparent open a Roth IRA for a grandchild, to give your grandchild a head start in life? A custodial Roth IRA offers several compelling benefits that can truly make a difference:
- Tax-Free Growth: Contributions to a Roth IRA grow tax-free, allowing investments to compound over time without the burden of taxes on earnings. This feature is especially beneficial for young individuals, as they generally fall into lower tax brackets, maximizing their savings potential.
- Flexible Withdrawals: Contributions can be withdrawn at any time without penalty, offering immediate access to funds if needed. Plus, earnings can be withdrawn tax-free after the account has been open for at least five years and the beneficiary reaches 59½ years old. This flexibility provides a significant advantage for long-term planning.
- Long-Term Financial Security: Starting a Roth IRA at a young age can set your grandchild on a path to substantial wealth accumulation. For instance, if a child contributes $2,000 annually starting at age 15, the account could grow to approximately $27,000 by age 25, and potentially exceed $1 million by retirement, thanks to the power of compounding.
- Monetary Knowledge: Involving your grandchild in the investment process nurtures monetary knowledge and responsibility. Teaching them about saving and investing from a young age equips them for informed financial choices in adulthood, instilling confidence in their economic abilities.
- Legacy Planning: An individual retirement account can play a crucial role in a broader legacy plan, ensuring that your support continues to benefit your grandchild well into their future. This not only secures their economic foundation but also reinforces the values of saving and investing.
By understanding these advantages, you can see the profound influence that asking, ‘can a grandparent open a Roth IRA for a grandchild?’ can have on your grandchild’s economic future, paving the way for long-term security and success. At Bright Advisers, we’re here for you, committed to providing personalized financial planning and investment strategies that empower families. Together, we can navigate this journey, ensuring that and tailored to your unique needs, including our focus on minimal fund fees.
Conclusion
Establishing a Roth IRA for your grandchildren isn’t just a financial choice; it’s a heartfelt investment in their future. Imagine the impact you can have by opening a custodial Roth IRA. By understanding the eligibility requirements, contribution limits, and the benefits of tax-free growth, you can empower your grandchildren with the tools they need for a prosperous economic future.
Starting early is key. Even modest contributions can blossom into substantial growth over time. The flexibility of withdrawals and the chance for tax-free growth make a Roth IRA an ideal choice for young savers. Plus, involving your grandchildren in this process can nurture their financial literacy and responsibility, ensuring they’re well-equipped to manage their wealth as they grow.
Ultimately, deciding to open a Roth IRA for your grandchild is more than just a financial strategy; it’s a legacy of support and guidance. By taking action today, you can help them build a secure foundation for tomorrow, paving the way for a lifetime of financial success. Embracing this opportunity not only enhances their economic future but also instills values of saving and investing that will resonate for generations to come. Together, we can navigate this journey and create a brighter future for your family.
Frequently Asked Questions
What is a Roth IRA and how does it benefit grandchildren?
A Roth IRA is an Individual Retirement Account that allows individuals to contribute after-tax income, leading to tax-free growth of investments and tax-free withdrawals during retirement, provided certain conditions are met. It is beneficial for grandchildren as it helps build a secure financial foundation.
Can grandparents open a Roth IRA for their grandchildren?
Yes, grandparents can open a Roth IRA for their grandchildren, which can be especially beneficial for long-term growth through compounding interest.
Is there a minimum age to open a Roth IRA for a grandchild?
No, there is no minimum age to open a Roth IRA. Children who have earned income from jobs or self-employment can start an IRA early.
How much can a grandparent contribute to a Roth IRA for their grandchild?
A grandparent can contribute up to the annual contribution limit set by the IRS, which varies each year. For example, contributing just $2,000 annually for ten years could grow significantly over time.
What is the potential growth of a Roth IRA if contributions are made early?
If a grandparent contributes $2,000 annually for ten years, it could grow to over $143,000 by age 66, assuming a 6% annual return. Contributions made at a young age can yield even more significant returns by retirement.
How are families currently utilizing Roth IRAs for minors?
Families are establishing custodial IRAs for children involved in jobs like babysitting or lawn care, allowing them to benefit from compound interest and ensuring a tax-free income in retirement.
What trends are observed regarding young households and IRAs?
The percentage of young households (ages 20-29) with an IRA has increased significantly, tripling from 6.6% in 2016 to 19.2% in 2022, reflecting a growing recognition of the value of individual retirement accounts for minors.
What lessons can be learned from starting a Roth IRA early?
Starting a Roth IRA early provides economic advantages and teaches valuable lessons about earning and investing, instilling a sense of financial responsibility in grandchildren.
List of Sources
- Understand the Basics of a Roth IRA for Grandchildren
- The Benefits of a Roth IRA for Minor Children (https://fhassoc.com/the-benefits-of-a-roth-ira-for-minor-children)
- Why Parents Are Opening Roth IRAs for 8-Year-Olds (https://finance.yahoo.com/news/why-parents-opening-roth-iras-141405048.html)
- Seed a Roth IRA for Your Grandkids (https://kiplinger.com/article/retirement/t046-c000-s004-seed-a-roth-ira-for-your-grandkids.html)
- Roth IRAs for Minors: A Powerful Tool for Long-Term Growth | Hassell Wealth Management (https://hassellwealth.com/our-blog/roth-iras-for-minors-a-powerful-tool-for-long-term-growth)
- Roth IRAs Holdings Have Shot Up among Young Households – Center for Retirement Research (https://crr.bc.edu/roth-iras-holdings-have-shot-up-among-young-households)
- Learn the Custodial Roth IRA Rules and Requirements
- Custodial Roth IRA For Kids Explained – Carry (https://carry.com/learn/custodial-roth-ira-explained)
- Your Step-by-Step Guide to Custodial Roth IRA for Kids – Bright Advisers (https://brightadvisers.com/your-step-by-step-guide-to-custodial-roth-ira-for-kids)
- Custodial Roth IRA: Roth IRAs for Children – NerdWallet (https://nerdwallet.com/retirement/learn/why-your-kid-needs-a-roth-ira)
- Unsupported browser | TIAA (https://tiaa.org/public/invest/services/wealth-management/perspectives/roth-ira-for-adult-children)
- How a custodial Roth IRA can help your kid | MassMutual (https://blog.massmutual.com/retiring-investing/custodial-roth-ira)
- Follow Steps to Open a Roth IRA for Your Grandchild
- Roth IRA For Kids: Make Your Grandchildren Millionaires – RetireGuide (https://retireguide.com/retirement-planning/investing/accounts/ira/roth-ira-for-grandchildren)
- Start a Roth IRA for Kids | U.S. Bank (https://usbank.com/retirement-planning/financial-perspectives/roth-ira-for-kids.html)
- Custodial Roth IRA: Your guide to Roth IRAs for kids | Fidelity (https://fidelity.com/learning-center/personal-finance/retirement/turbocharge-childs-retirement)
- Step-by-Step Guide to Setting Up a Roth IRA for Your Child – Bright Advisers (https://brightadvisers.com/step-by-step-guide-to-setting-up-a-roth-ira-for-your-child)
- Custodial Roth IRA: How to Open a Roth IRA for Kids (https://annuity.org/retirement/ira/roth-ira/custodial)
- Explore the Benefits of a Roth IRA for Your Grandchild
- The Benefits of a Roth IRA for Minor Children (https://fhassoc.com/the-benefits-of-a-roth-ira-for-minor-children)
- Roth IRA For Kids: Make Your Grandchildren Millionaires – RetireGuide (https://retireguide.com/retirement-planning/investing/accounts/ira/roth-ira-for-grandchildren)
- This retirement account can be ‘triple-tax efficient’ for teens this summer, advisor says (https://cnbc.com/2024/05/23/roth-iras-for-kids-offer-triple-tax-benefits.html)
- Custodial Roth IRA: Roth IRAs for Children – NerdWallet (https://nerdwallet.com/retirement/learn/why-your-kid-needs-a-roth-ira)
- How to turbocharge your kids’ earnings from babysitting and other jobs (https://today.com/money/roth-ira-kids-how-it-can-set-them-success-t210683)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Age Five Wealth Education for high-income W-2 families at Bright Advisers.
Keep reading