

Overview
Navigating your IRA transfer can feel overwhelming, but it doesn’t have to be. You have the option to move your IRA to another bank through either a direct transfer or an indirect transfer. Each method comes with its own steps and tax implications, and understanding these can help you make the best choice for your family.
Imagine if you could simplify this process. This article not only highlights the importance of selecting the right transfer method but also provides a clear, step-by-step guide to initiating the transfer. We understand that the financial world can be daunting, especially for young parents, which is why we want to ensure you are equipped with the knowledge to navigate this journey smoothly.
However, it’s essential to be aware of potential challenges that may arise during the transfer process. By being informed, you can avoid unnecessary penalties that could impact your family’s financial future. Remember, we’re here for you, ready to support you in making the best decisions for your loved ones. Together, we can navigate this journey and secure a brighter financial future for your family.
Key Highlights:
- Types of IRA transfers include Direct Transfer (trustee-to-trustee) and Indirect Transfer, each with distinct implications.
- Direct Transfers avoid tax implications by moving funds directly between institutions.
- Indirect Transfers require funds to be redeposited into a new IRA within 60 days to avoid taxes and penalties.
- Rollovers allow movement from 401(k) plans to IRAs, with only one indirect rollover permitted per year.
- Steps to initiate an IRA transfer include selecting a new provider, opening a new account, and completing necessary documentation.
- Challenges in transferring an IRA include timing issues, potential charges, tax implications, and ensuring account compatibility.
- Resources such as checklists, online calculators, and monetary consultants can facilitate a smooth IRA transfer process.
- Maintaining documentation of the transfer process is crucial for resolving any issues that may arise.
Introduction
Navigating the complexities of individual retirement accounts (IRAs) can feel overwhelming, especially when considering a transfer to another bank. Many individuals are relocating their funds into IRAs, and it’s essential to understand the different transfer methods and their implications for safeguarding your family’s financial future. Imagine facing challenges during this process—what if you could ensure a seamless transition while avoiding costly penalties?
This guide is here to offer essential steps and insights, empowering you to make informed decisions about your IRA transfers. Together, we can navigate this journey with confidence.
Understand IRA Transfer Basics
Before you embark on the journey of an IRA transfer, it’s important to understand the different types of transfers available to you:
-
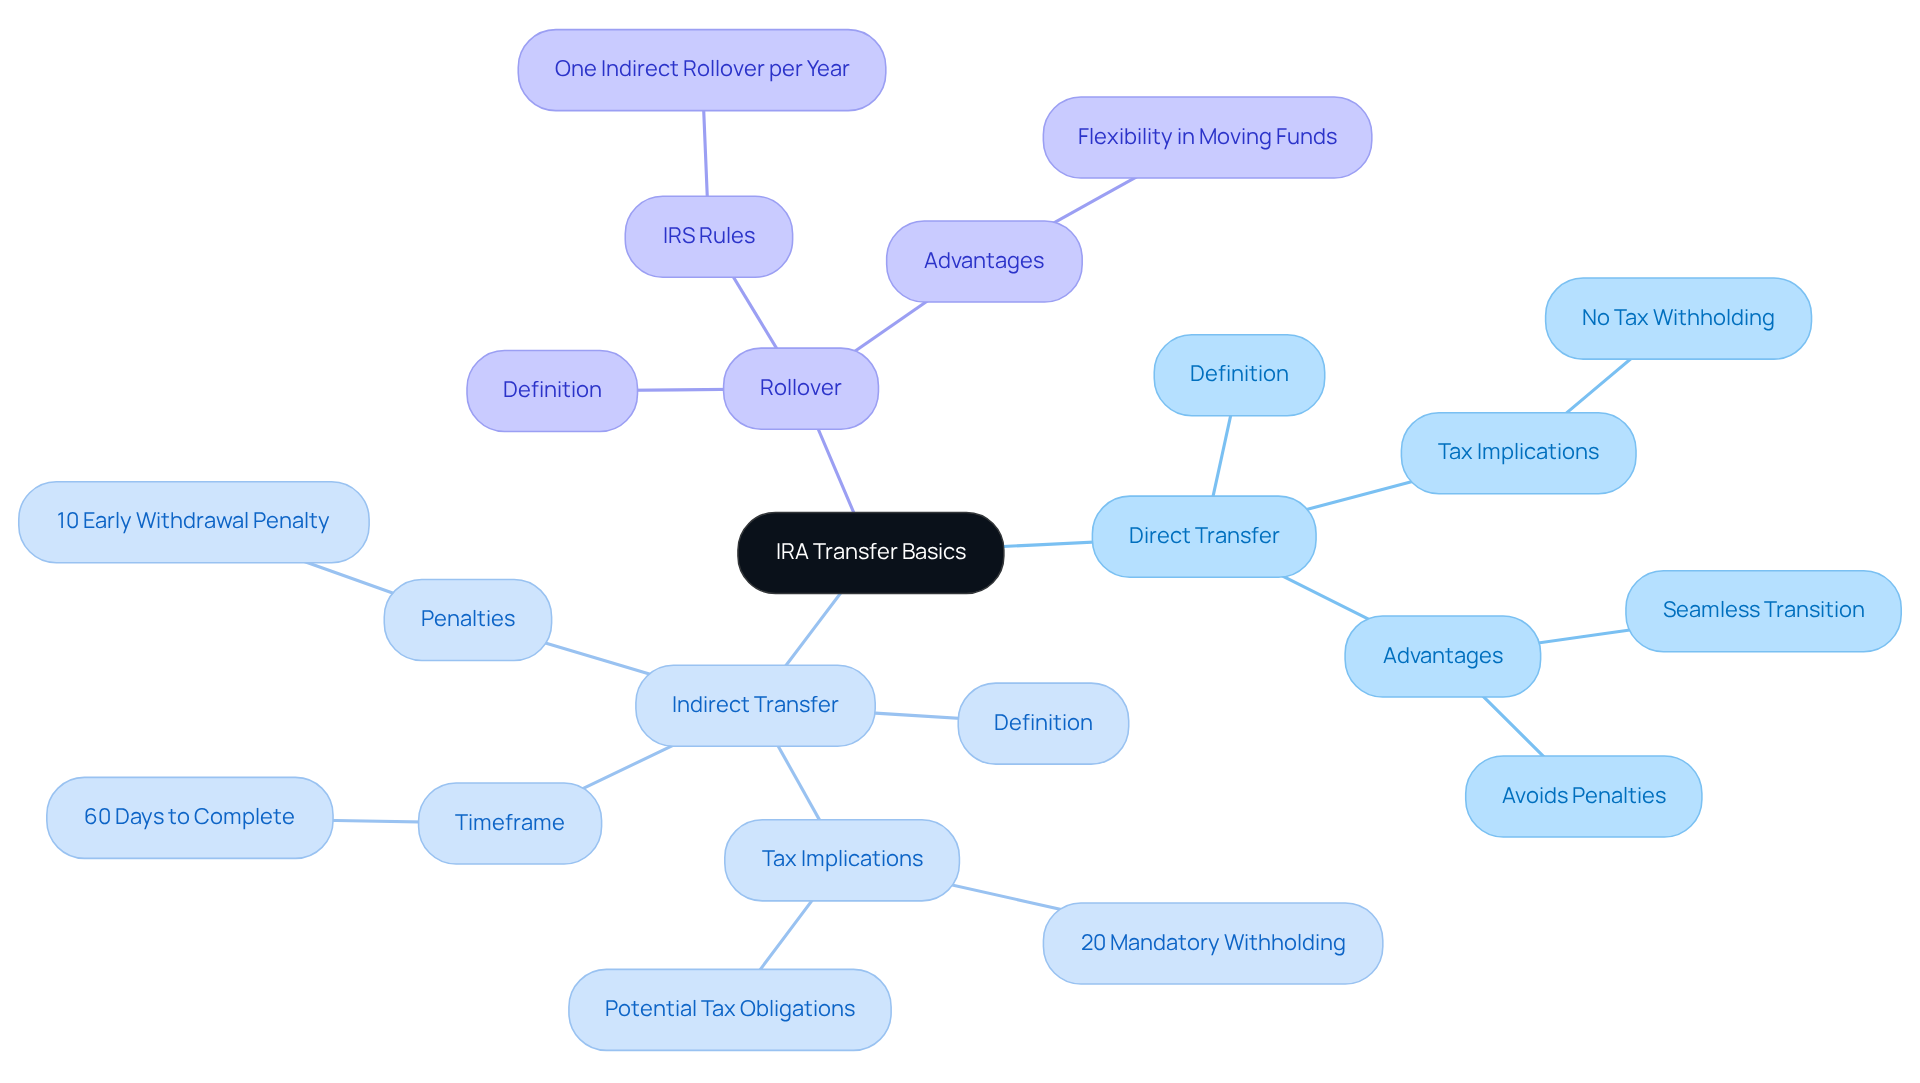
Direct Transfer (Trustee-to-Trustee Transfer): This straightforward approach allows you to transfer funds directly from one financial institution to another without ever taking possession of the money. It’s a simple option that helps you avoid tax implications, ensuring a smooth and seamless transition.
-
Indirect Transfer: In this scenario, you withdraw money from your IRA and must deposit it into another IRA within 60 days. This method carries risks; failing to complete the transfer within the timeframe can lead to tax obligations, including a mandatory 20% withholding if assets aren’t directly moved from a 401(k) to an IRA. Additionally, if you’re under 59 ½, you may face a 10% early withdrawal penalty if the rollover isn’t completed within 60 days.
-
Rollover: Similar to an indirect transfer, a rollover typically involves moving assets from a 401(k) or another employer-sponsored plan into an IRA. It’s crucial to remember that the IRS permits only one indirect rollover per year, so if you’re asking, can I move my IRA to another bank, it’s important to keep this rule in mind.
Understanding these basics is vital in helping you choose the right method for your situation, allowing you to avoid unnecessary penalties or taxes. Recent statistics indicate that 62% of individuals withdrawing from workplace plans are relocating funds into an IRA, highlighting the importance of being informed about these options. Furthermore, opting for direct deposits is recommended to mitigate the risks associated with indirect rollovers and missed deadlines, ensuring a smoother financial transition.
Imagine if you could navigate this process with confidence, knowing you have the right information at your fingertips. Together, we can ensure that your financial decisions align with your family’s goals, providing you with peace of mind as you plan for the future.
Initiate the Transfer Process
To initiate the transfer of your IRA, follow these steps with confidence:
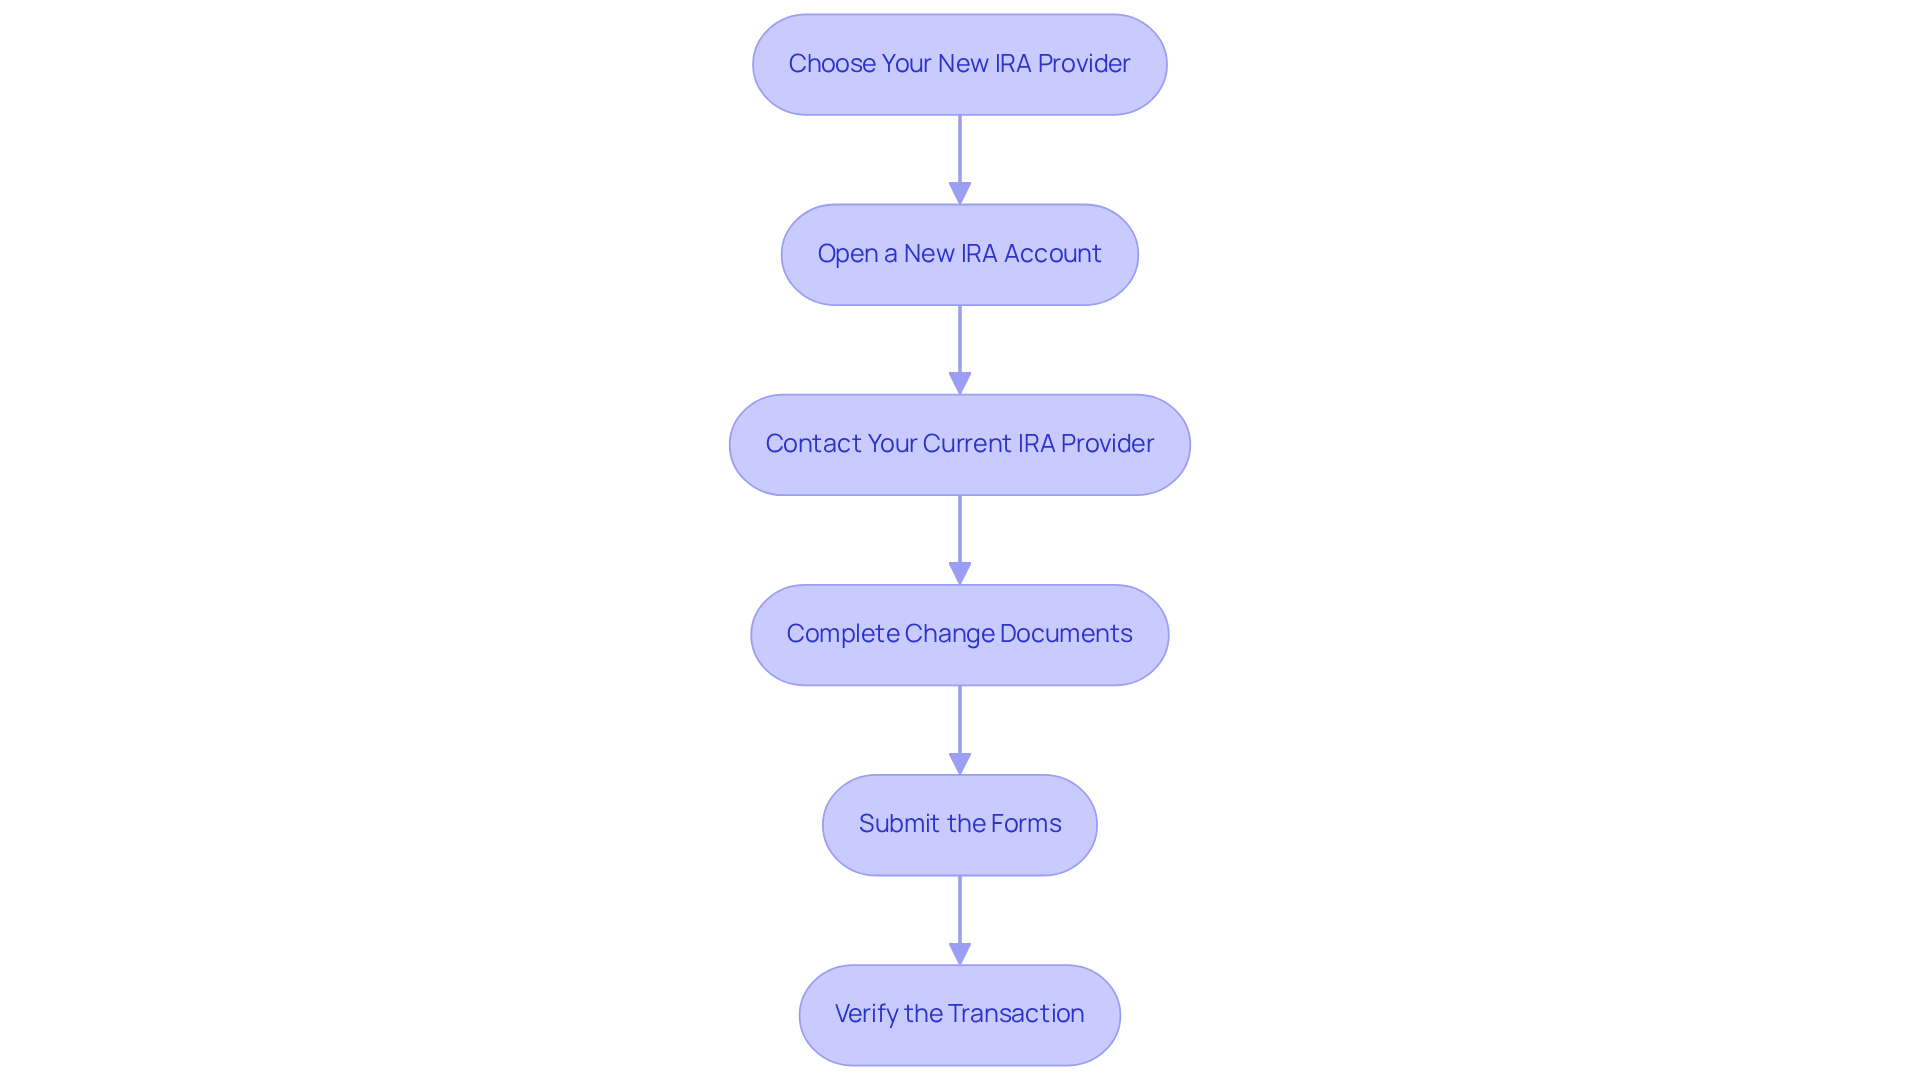
- Choose Your New IRA Provider: Take the time to research and select a financial institution that aligns with your family’s financial goals. Consider factors such as fees, investment options, and customer service. Many providers, including Bright Advisers, offer minimal fund fees, leading to significant savings. Choosing a provider with no platform or trading fees can help you avoid unnecessary costs, allowing you to allocate more towards your retirement savings—an essential step for young parents planning for their family’s future.
- Open a New IRA Account: If you don’t already have an IRA with the new provider, you’ll need to open one. This process is often straightforward and can typically be completed online, making it convenient for your busy schedule.
- Contact Your Current IRA Provider: Reach out to your current provider to inform them of your intention to move your IRA. Request the necessary forms for a direct movement, as this method helps avoid potential tax implications. It’s important to remember that moving an IRA might lead to taxable occurrences and fines if you withdraw money before age 59.5.
- Complete Change Documents: Fill out the change documents provided by your current institution. Ensure that all information is accurate to prevent any delays in processing. Taking this step carefully can ease your mind during the transition.
- Submit the Forms: Send the completed forms to your current provider. They will handle the transaction and send the funds directly to your new IRA provider, typically within 1 to 2 weeks. This process is designed to be smooth, allowing you to focus on what matters most—your family.
- Verify the Transaction: After a few days, check with both financial institutions to ensure that the transaction has been completed successfully. This step is crucial to ensure that your retirement savings are consolidated and properly managed, giving you peace of mind.
Remember, when considering if you can move your IRA to another bank, you can only do so once per 12-month period, so plan accordingly to maximize your retirement savings potential. Together, we can navigate this journey, ensuring a secure future for your loved ones.
Navigate Common Challenges and Considerations
Although transferring your IRA can feel daunting, understanding the process can help answer the question, can I move my IRA to another bank, making it a manageable task. Here are some key challenges to consider:
-
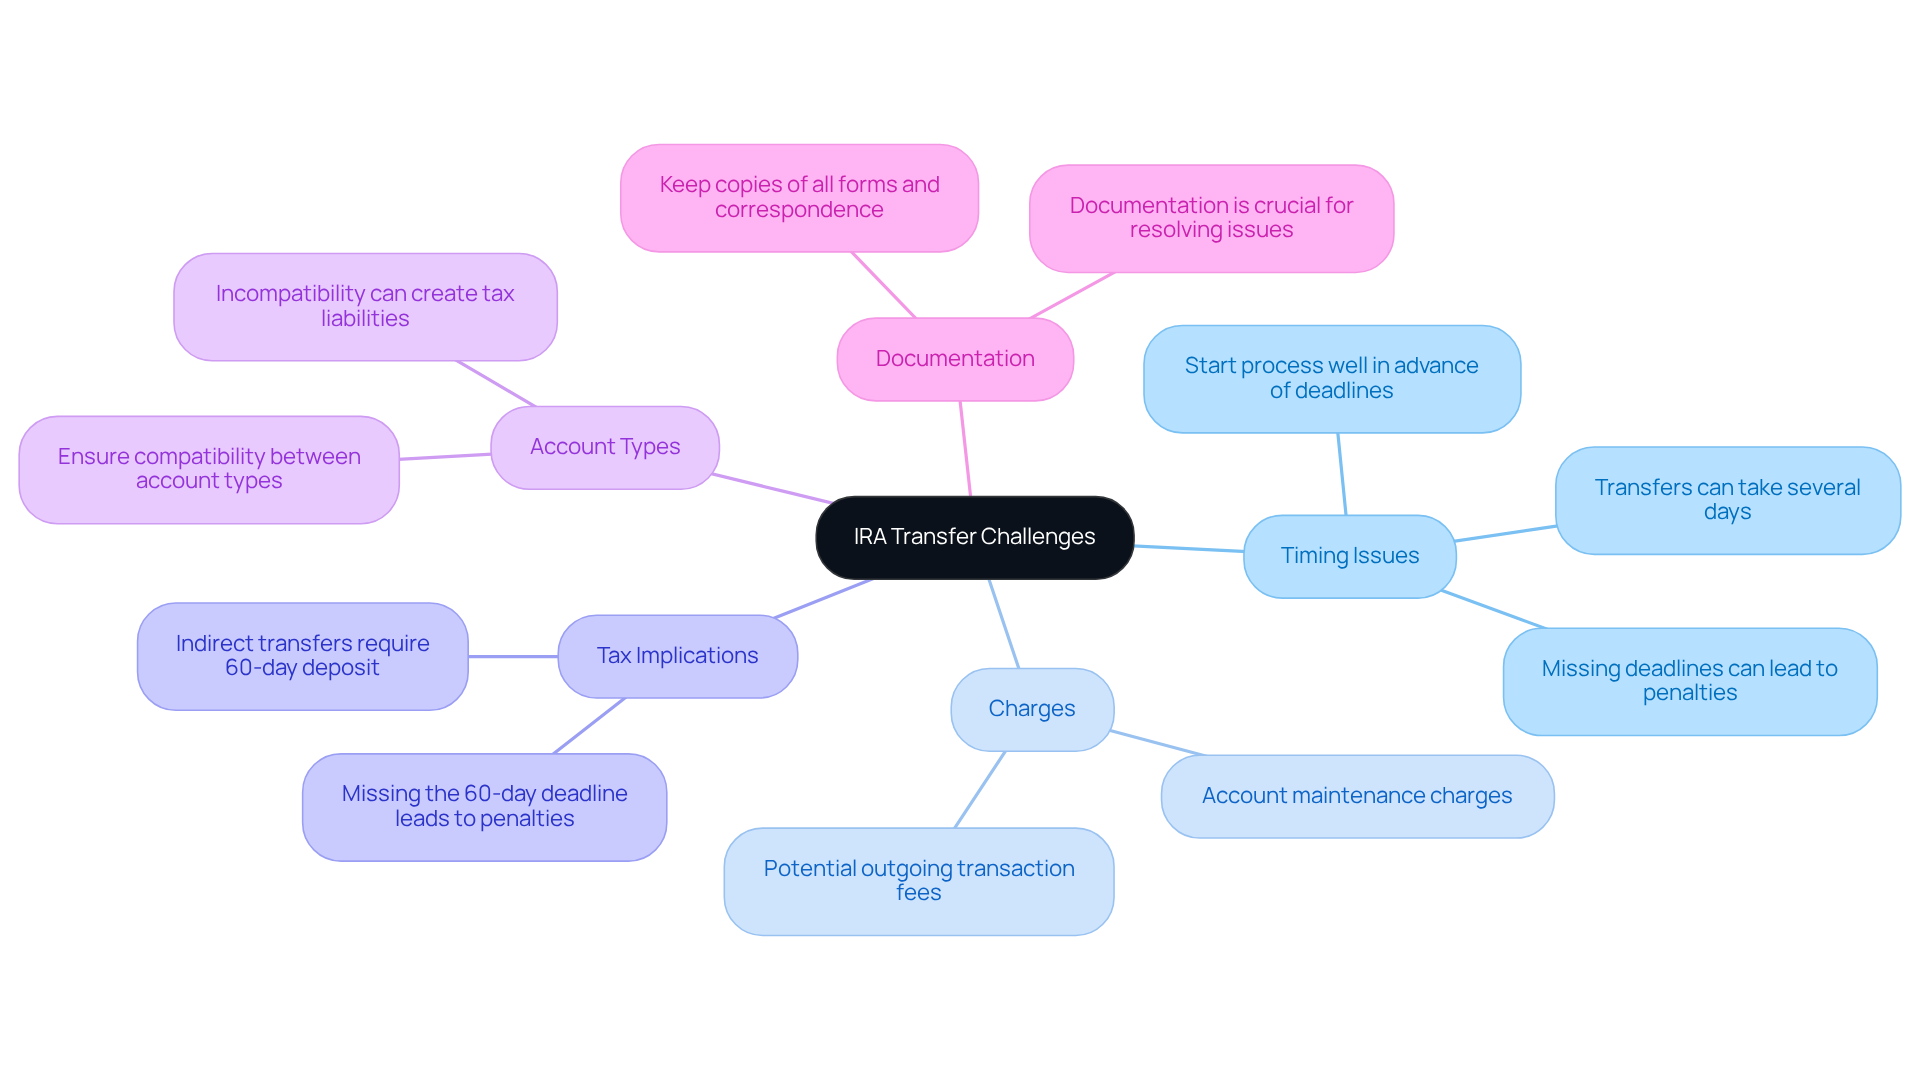
Timing Issues: Transfers can take several days to complete. It’s important to start this process well in advance of any deadlines, like required minimum distributions (RMDs). Missing these deadlines can lead to penalties that you don’t want to face.
-
Charges: Be aware of potential charges that might come with the transfer. Some financial institutions may impose fees for outgoing transactions, while others might have account maintenance charges that could impact your savings.
-
Tax Implications: If you choose an indirect transfer, make sure to deposit the funds into your new IRA within 60 days to avoid tax penalties. Missing this deadline can lead to significant tax consequences, so timely action is essential.
-
Account Types: Verify that you are transferring between compatible account types, such as from one traditional IRA to another. Incompatibility can create complications and possible tax liabilities that you want to avoid.
-
Documentation: Keep copies of all forms and correspondence related to your transfer. This documentation is crucial for resolving any issues that may arise along the way.
Understanding these elements can help you navigate the complexities of IRA transfers, particularly when considering if I can move my IRA to another bank. Remember, you’re not alone in this journey; we’re here for you, ready to support you in securing your family’s financial future.
Utilize Resources and Tools for a Smooth Transfer
To facilitate a seamless IRA transfer, consider leveraging these supportive resources:
-
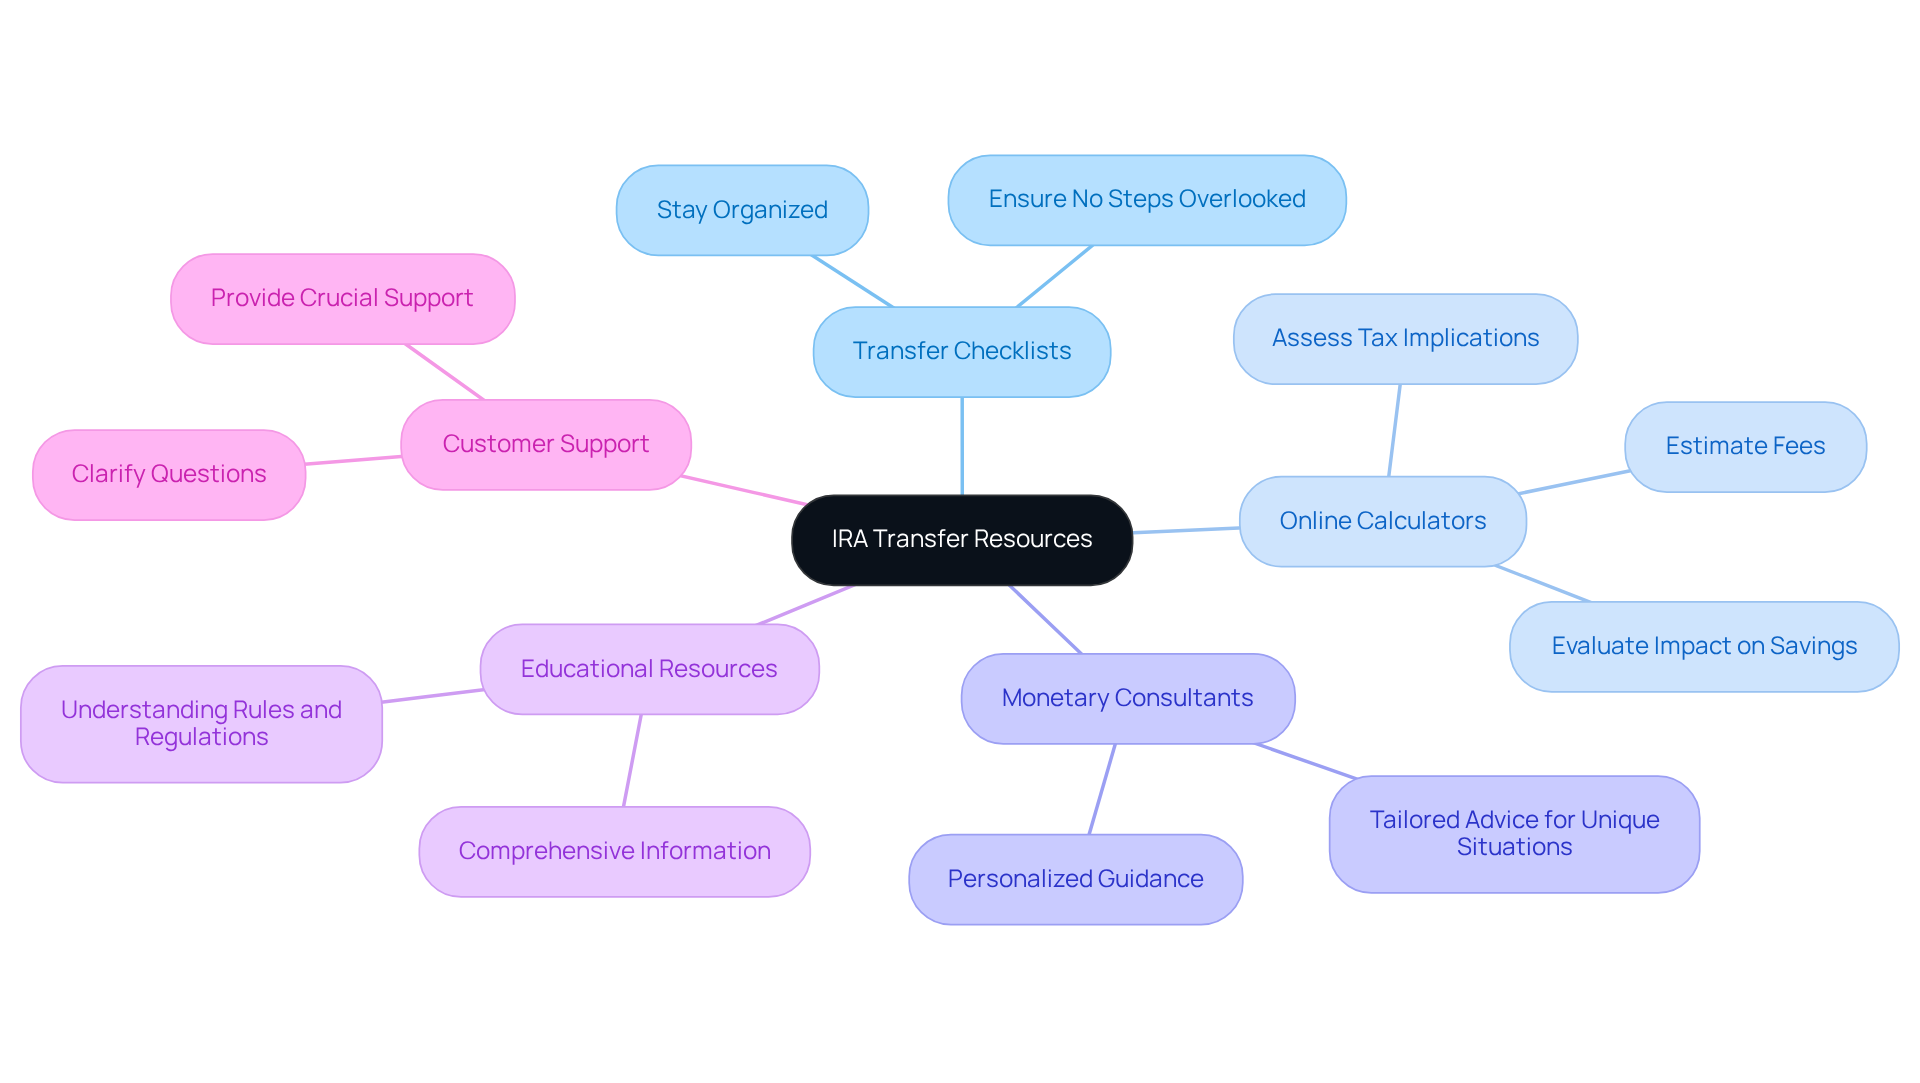
IRA Transfer Checklists: Many banks offer helpful lists that outline essential actions for a successful relocation. By using these checklists, you can stay organized and ensure that no critical steps are overlooked. As advisor Dayana Yochim wisely points out, “Ultimately, it’s all about addressing one crucial question: Am I saving enough, and in the appropriate accounts?” This highlights the importance of being thorough in your planning.
-
Online Calculators: Imagine having the ability to estimate potential fees, tax implications, and the overall impact of the transfer on your retirement savings. Online tools from resources like Bankrate and NerdWallet can empower you to make informed decisions that align with your family’s future.
-
Monetary Consultants: Involving a monetary consultant can be invaluable, especially if you feel uncertain about the process or need personalized guidance. These advisors can offer tailored advice based on your unique financial situation. Remember, 54.4% of families possess retirement accounts, yet many navigate these complexities alone. Additionally, the average IRA balance was $129,200 in Q3 2024, underscoring the importance of managing these assets wisely.
-
Educational Resources: It’s important to familiarize yourself with comprehensive information available on platforms like Investopedia and the IRS. Understanding the rules and regulations surrounding IRA movements can significantly boost your confidence and readiness for this journey.
-
Customer Support: Don’t hesitate to reach out to customer service representatives at both your current and prospective financial institutions. They can provide crucial support and clarify any questions you may have during the process of moving.
By utilizing these resources, you can streamline your IRA transfer, which raises the question, can I move my IRA to another bank, while ensuring that your retirement savings remain on track. Remember, together, we can navigate this journey toward a secure financial future for your family.
Conclusion
Transferring an IRA to another bank can be a straightforward process when equipped with the right knowledge and tools. Imagine if you could navigate this journey with confidence, avoiding unnecessary penalties and tax implications. This guide emphasizes the importance of understanding the various transfer methods:
- Direct transfers
- Indirect transfers
- Rollovers
along with the necessary steps to ensure a smooth transition. By being informed, you can secure your financial future for your family.
It’s essential to choose a suitable new IRA provider and to initiate the transfer with proper documentation. Be aware of common challenges such as timing issues and potential fees. Utilizing resources like checklists, online calculators, and the support of financial advisors can significantly ease the process. This way, you can focus on what truly matters—your long-term financial goals and the well-being of your loved ones.
Navigating the complexities of IRA transfers is crucial for anyone looking to enhance their retirement savings strategy. Together, we can confidently answer the question, “Can I move my IRA to another bank?” By taking proactive steps and leveraging available resources, you can make informed decisions that align with your family’s financial aspirations. The journey toward a secure financial future begins with understanding and action—take the first step today. We’re here for you, every step of the way.
Frequently Asked Questions
What are the different types of IRA transfers?
The two main types of IRA transfers are Direct Transfer (Trustee-to-Trustee Transfer) and Indirect Transfer. A Direct Transfer allows funds to move directly between financial institutions without tax implications, while an Indirect Transfer involves withdrawing money and depositing it into another IRA within 60 days, which carries risks.
What is a Direct Transfer?
A Direct Transfer is a straightforward method where funds are transferred directly from one financial institution to another without the account holder taking possession of the money. This approach avoids tax implications and ensures a smooth transition.
What is an Indirect Transfer?
An Indirect Transfer involves withdrawing funds from your IRA and depositing them into another IRA within 60 days. If not completed within this timeframe, it may result in tax obligations, including a mandatory 20% withholding, and a 10% early withdrawal penalty if the individual is under 59 ½.
What is a Rollover in the context of IRA transfers?
A Rollover is similar to an Indirect Transfer but typically involves moving assets from a 401(k) or another employer-sponsored plan into an IRA. It is important to note that the IRS allows only one indirect rollover per year.
Why is it important to understand IRA transfer basics?
Understanding IRA transfer basics is vital to choosing the right transfer method for your situation, helping you avoid unnecessary penalties or taxes. Being informed can ensure a smoother financial transition when relocating funds.
What percentage of individuals withdrawing from workplace plans are moving funds into an IRA?
Recent statistics indicate that 62% of individuals withdrawing from workplace plans are relocating their funds into an IRA.
What is recommended to mitigate risks associated with indirect rollovers?
Opting for Direct Transfers is recommended to mitigate the risks associated with indirect rollovers and missed deadlines, ensuring a smoother financial transition.
List of Sources
- Understand IRA Transfer Basics
- Don’t Make These Fatal Errors With IRA Rollovers (https://morningstar.com/retirement/dont-make-these-fatal-errors-with-ira-rollovers)
- IRA Transfer vs Rollover (https://sofi.com/learn/content/ira-transfer-vs-rollover)
- Retirement Account Statistics 2024 – NerdWallet (https://nerdwallet.com/article/investing/retirement-statistics)
- IRA Rollovers Set to Grow, but by How Much? | PLANADVISER (https://planadviser.com/ira-rollovers-set-grow-much)
- Recent IRA Statistics – Greenleaf Trust (https://greenleaftrust.com/missives/recent-ira-statistics)
- Initiate the Transfer Process
- How to Transfer an IRA from One Institution to Another (https://carboncollective.co/sustainable-investing/how-to-transfer-an-ira-from-one-institution-to-another)
- Retirement Account Statistics 2024 – NerdWallet (https://nerdwallet.com/article/investing/retirement-statistics)
- Average retirement savings by age | Fidelity (https://fidelity.com/learning-center/personal-finance/average-retirement-savings)
- U.S.: value of IRA assets by type 2023| Statista (https://statista.com/statistics/1273780/value-of-ira-assets-by-type-us)
- Navigate Common Challenges and Considerations
- 10 Of The Best Warren Buffett Quotes Of All Time | Bankrate (https://bankrate.com/investing/best-warren-buffett-quotes)
- Wisdom of Great Investors – Quotes | Davis ETFs (https://davisetfs.com/investor_education/quotes)
- 10 IRA Rollover Mistakes to Avoid (https://jlsmithgroup.com/blog/10-ira-rollover-mistakes-to-avoid)
- How 401(k) Rollover Activity Fueled Recent IRA Growth (https://asppa-net.org/news/2024/3/how-401k-rollover-activity-fueled-recent-ira-growth)
- SOI Tax Stats Accumulation and Distribution of Individual Retirement Arrangements | Internal Revenue Service (https://irs.gov/statistics/soi-tax-stats-accumulation-and-distribution-of-individual-retirement-arrangements)
- Utilize Resources and Tools for a Smooth Transfer
- 77 Financial Advisor Quotes to Send to Clients (https://billgoodmarketing.com/resources/financial-advisor-quotes)
- Average retirement savings by age (https://empower.com/the-currency/money/average-retirement-savings-by-age)
- Retirement Account Statistics 2024 – NerdWallet (https://nerdwallet.com/article/investing/retirement-statistics)
- U.S. Retirement Assets: Data in Brief (https://congress.gov/crs-product/R47699)
- None (https://fa.wellsfargoadvisors.com/DavidCGreen/Eight-Great-Investing-Quotes.c10271.htm)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Retirement & Employee Benefits for high-income W-2 families at Bright Advisers.
Keep reading