

Overview
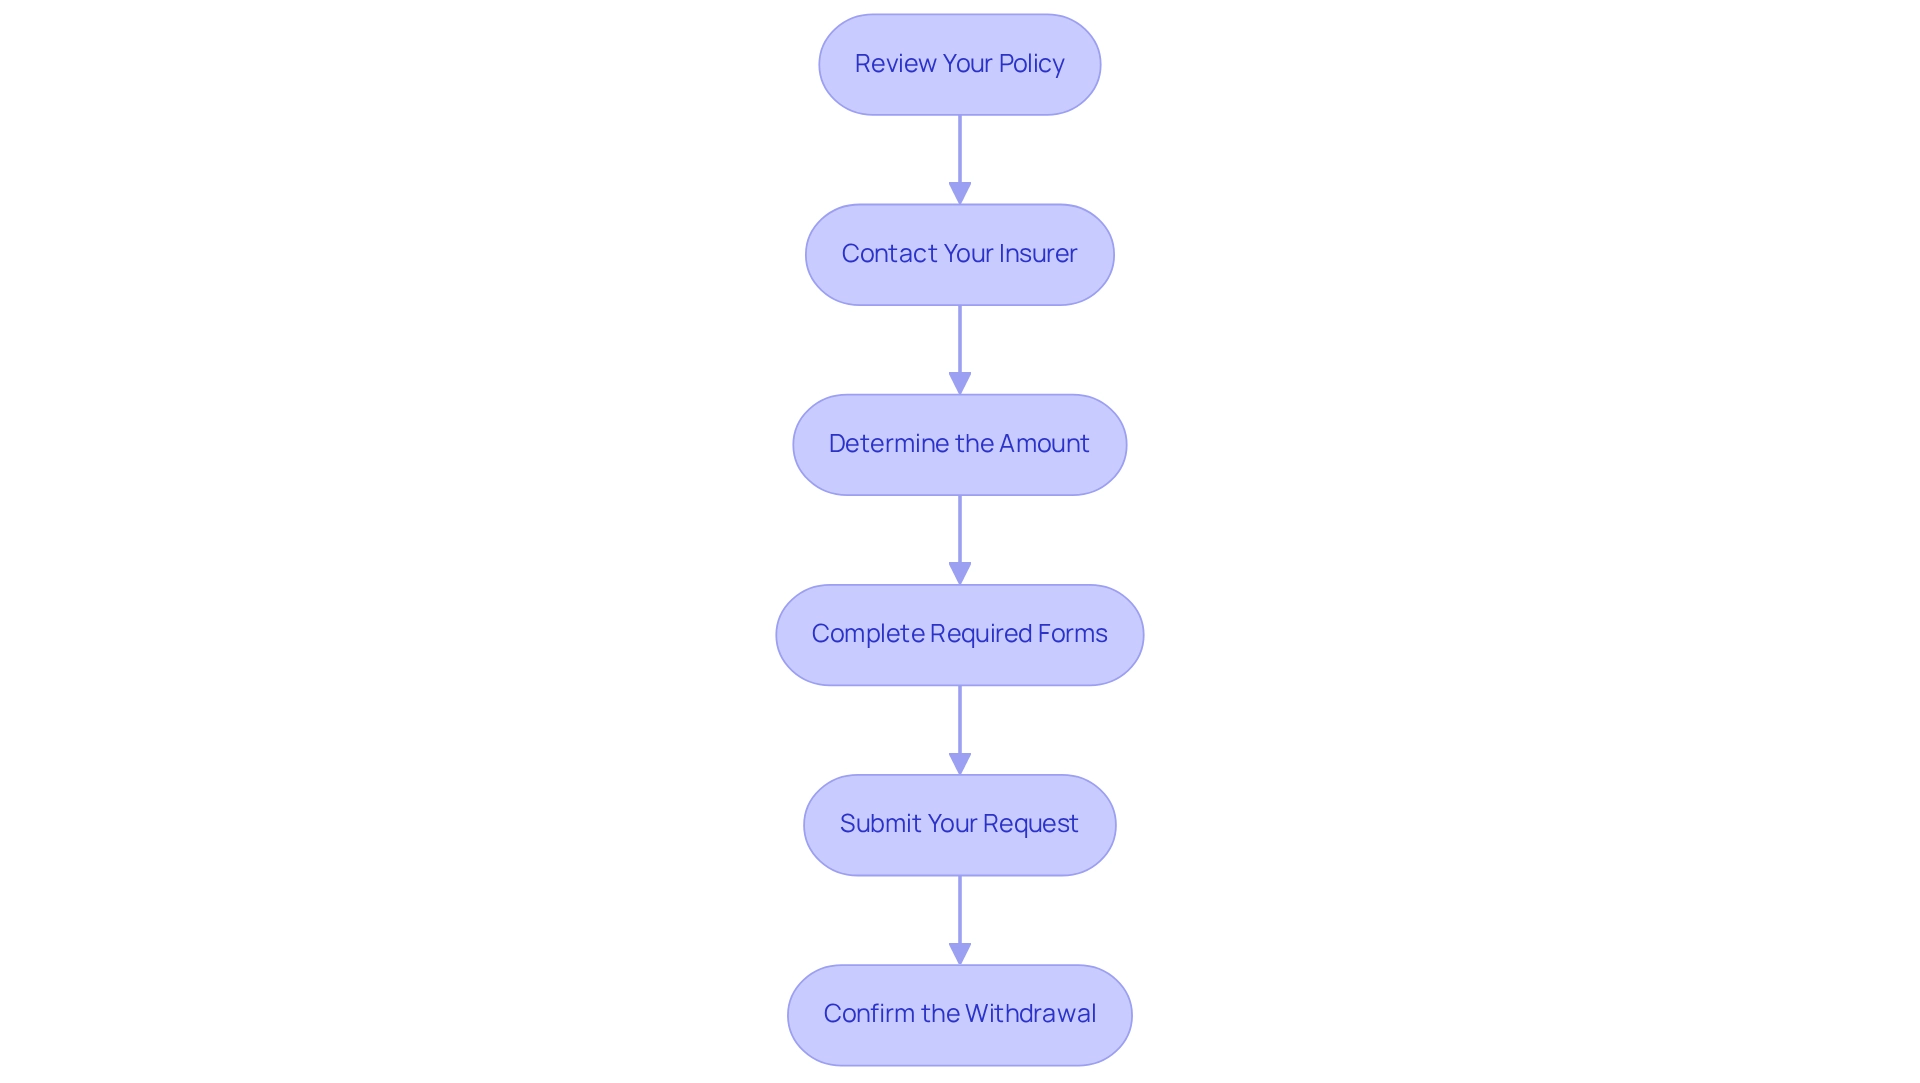
Withdrawing money from your universal life insurance policy can be a thoughtful decision for your family’s financial needs. Begin by reviewing your policy carefully, as understanding its terms is crucial. Next, reach out to your insurer, who can guide you through the process with care and expertise.
Consider the amount you wish to withdraw, keeping in mind that while this provides immediate access to funds, it may reduce the death benefit. It’s important to recognize that there could be tax implications as well. Understanding these factors is essential to making informed financial decisions that align with your family’s values.
As you complete the necessary forms, remember that you’re taking a step towards securing your family’s future. Confirming the transaction is the final piece of this journey.
Together, we can navigate this process smoothly, ensuring that your choices support your family’s goals. We’re here for you, ready to assist you in making the best decisions for your loved ones.
Key Highlights:
- Universal life insurance combines a death benefit with a cash value component, offering flexibility and growth potential.
- Flexible premiums allow families to adjust payments based on their financial situations.
- A portion of premiums contributes to a cash value account, which can be accessed for various needs, such as education.
- The death benefit can be adjusted to meet changing family needs, providing security against unexpected events.
- Cash value growth is influenced by fluctuating interest rates, necessitating regular policy reviews.
- In 2025, an estimated 57% of private industry workers will have access to universal life insurance through employers.
- The withdrawal process involves reviewing the policy, contacting the insurer, determining the withdrawal amount, completing forms, and confirming the transaction.
- Withdrawals can reduce the death benefit and may incur tax liabilities if they exceed total premiums paid.
- Alternatives to withdrawals include taking loans against the cash value, preserving the death benefit while accessing funds.
- It’s crucial to evaluate other financial resources before utilizing life insurance to meet immediate needs.
Introduction
In the intricate world of financial planning, universal life insurance emerges as a remarkable tool that not only provides a death benefit but also offers the potential for cash value growth. Imagine having the flexibility to tailor your premium payments to fit your family’s financial situation. This unique insurance option allows for access to funds that can be vital during significant moments, such as funding a child’s education or managing unexpected expenses.
However, it’s important to understand the intricacies of withdrawals from these policies. Navigating this process requires clarity regarding the associated procedures and implications. As families increasingly recognize the critical role life insurance plays in securing their financial futures, it becomes essential to explore the fundamental aspects of universal life insurance, delve into the withdrawal process, and consider the financial ramifications of these decisions. Together, we can navigate this journey, ensuring that your family’s needs are met with care and understanding.
Understand Universal Life Insurance Basics
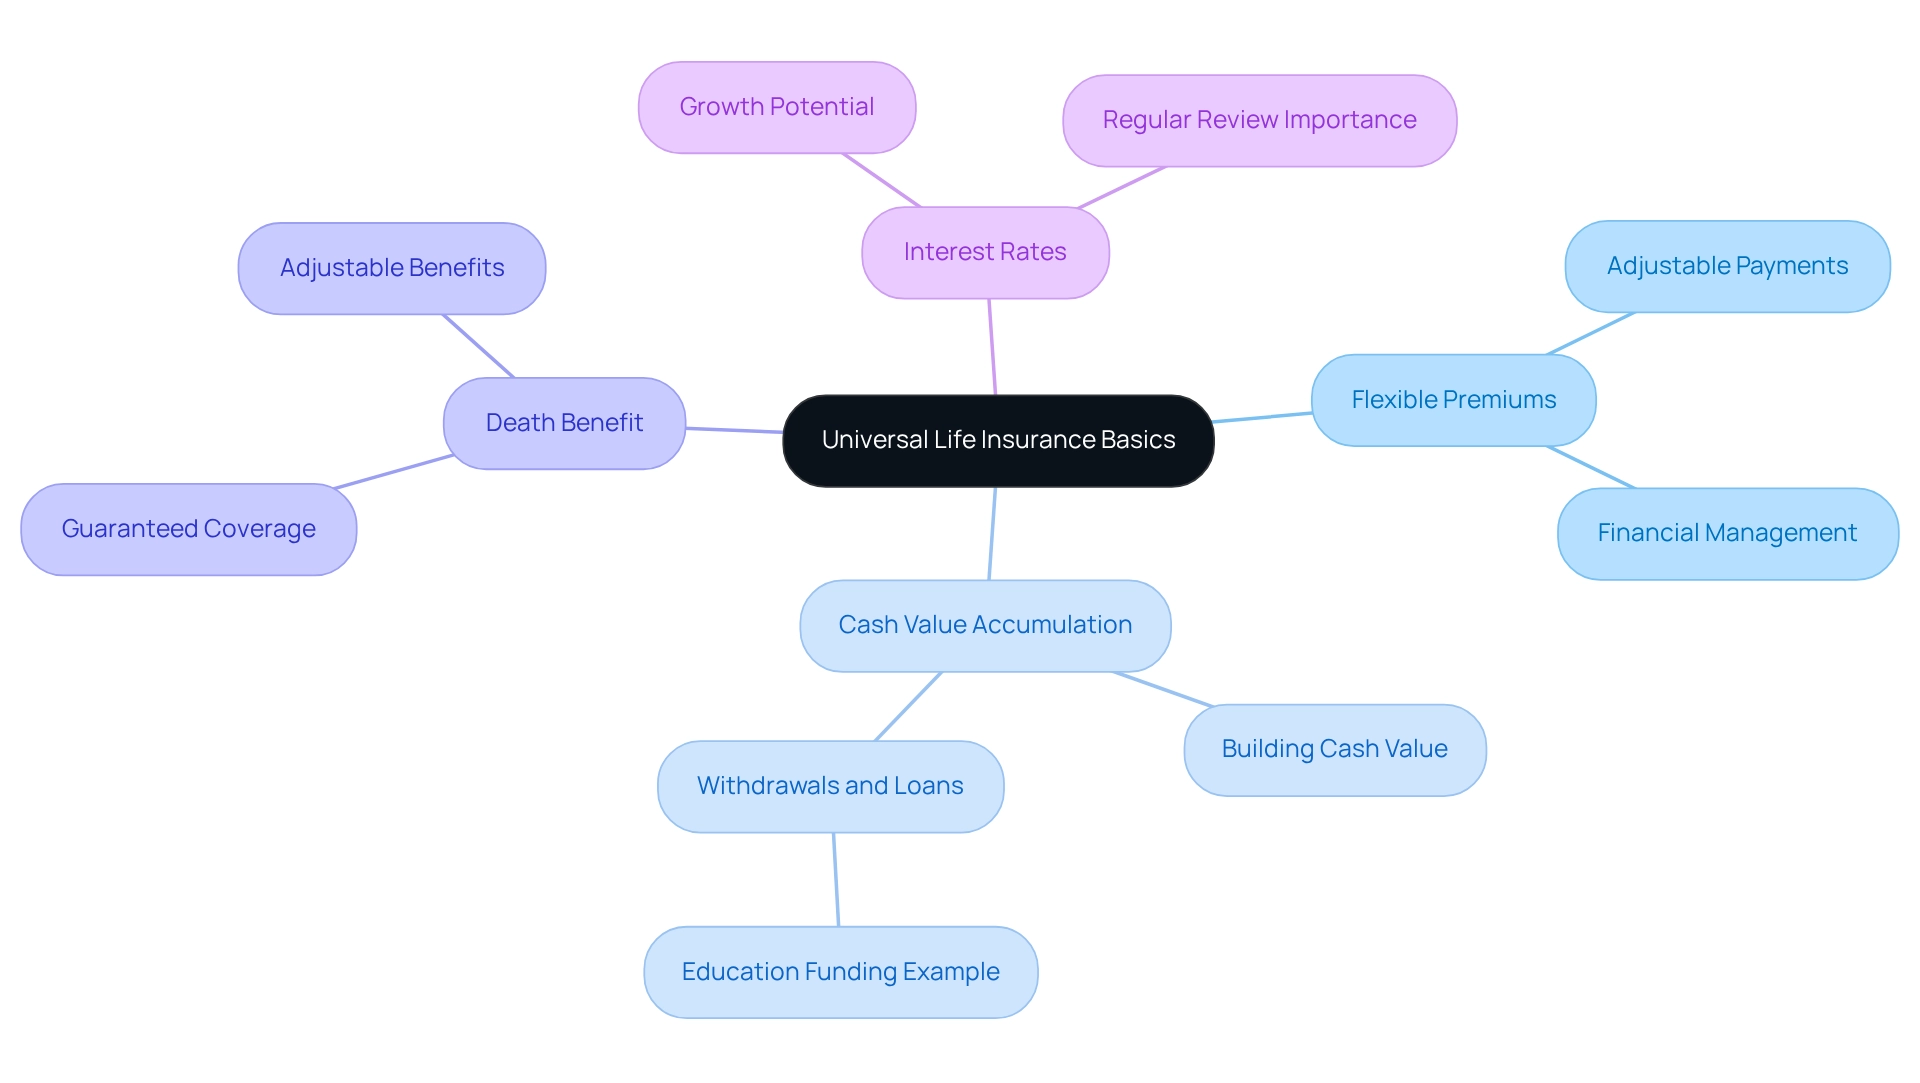
Universal coverage offers a compassionate safety net that blends a death benefit with a cash value component, providing both flexibility and growth potential for families. Let’s explore some key elements together:
- Flexible Premiums: Unlike whole life insurance, universal life plans allow you to adjust your premium payments. This means families with varying income levels, like Jay and Emma, can manage their financial commitments more effectively, ensuring peace of mind.
- Cash Value Accumulation: With universal coverage, a portion of each premium builds a cash value account. This account provides financial flexibility when life’s needs arise, as you may wonder, can I withdraw money from my universal life insurance policy through withdrawals or loans? For instance, Allison and Brian utilized their plan’s cash value to support their children’s education, demonstrating how this feature can align with your family’s aspirations.
- Death Benefit: This coverage guarantees a death benefit for your loved ones, which can be adjusted as your family’s needs change. It’s a way to ensure that you’re prepared for the unexpected, providing a sense of security.
- Interest Rates: The cash value grows with interest, which may fluctuate. It’s important to regularly review your coverage to understand its performance and growth potential, especially when planning for the challenges that families often face.
In 2025, approximately 57% of workers in private industry will have access to coverage through their employers, highlighting the importance of understanding these options. Moreover, the expected cash value growth rates for universal policies are competitive, making it a wise choice for families looking to secure their financial future. A recent survey revealed that only 29% of consumers felt their coverage providers simplified plans, underscoring the need for clearer communication and education. By familiarizing yourself with these essentials, you can confidently navigate the withdrawal process and understand if you can withdraw money from my universal life insurance policy, making informed decisions that align with your family’s financial goals. Remember, we’re here for you—together, we can navigate this journey.
Follow the Step-by-Step Withdrawal Process
Navigating the process of understanding if I can withdraw money from my universal life insurance policy can feel daunting, but we’re here to guide you through it with care. Follow these steps to ensure a smooth experience:
-
Review Your Policy: Begin by carefully reviewing your policy documents. It is crucial to understand the terms regarding withdrawals, including any fees or penalties, especially when considering if I can withdraw money from my universal life insurance policy. Remember, this coverage can provide an inheritance for your loved ones, so consider the implications of your withdrawal.
-
Contact Your Insurer: Reach out to your provider’s customer service or your agent. Discuss your intention by asking, can I withdraw money from my universal life insurance policy; they can offer specific instructions tailored to your policy.
-
Determine the Amount: Take a moment to decide how much money you wish to withdraw. It’s essential to consider that if you are wondering, ‘can I withdraw money from my universal life insurance policy,’ withdrawing too much may impact your death benefit and cash value. Did you know that around 3.7 million millennials in the UK have coverage that isn’t an employee benefit? This highlights the importance of fully understanding your policy.
-
Complete Required Forms: Your insurer will likely require you to fill out a withdrawal request form. Make sure all information is accurate to avoid any delays in processing.
-
Submit Your Request: Once you’ve completed the form, send it to your insurer using their specified method—whether that’s mail, email, or an online portal.
-
Confirm the Withdrawal: After your request has been processed, confirm with your insurer that the withdrawal has been completed. Check your cash value and death benefit to understand any impacts, as this will help you determine if you can withdraw money from my universal life insurance policy. As trends indicate, more families are recognizing the importance of life insurance, with increased sales reflecting a move towards enhanced economic security. Remember, while we strive to provide a diverse selection of options, it’s vital to understand the products available to you. Together, we can navigate this journey and effectively manage your policy to benefit your loved ones.
Consider Financial Implications and Alternatives
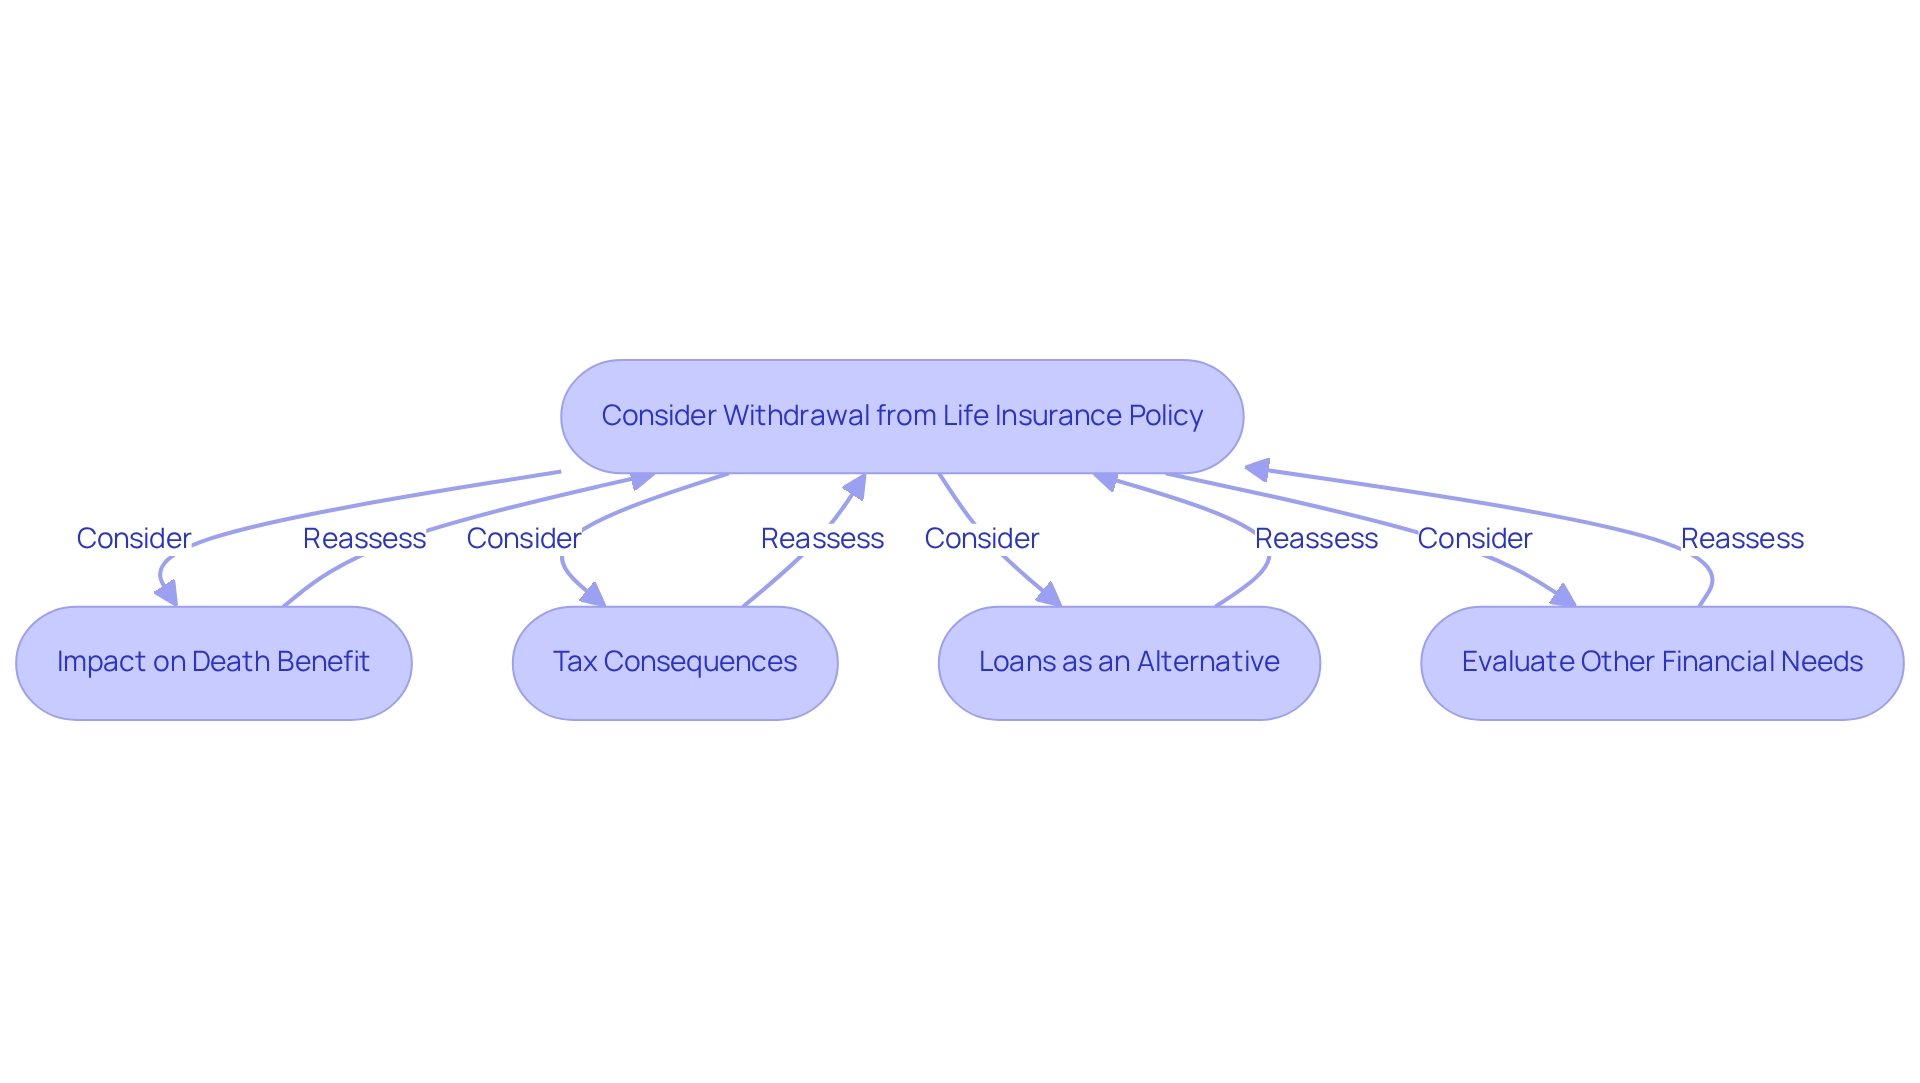
Before proceeding with a withdrawal, it’s important to consider the financial implications that could affect your family’s future:
- Impact on Death Benefit: Withdrawing funds can significantly reduce the death benefit available to your beneficiaries, potentially undermining your family’s long-term financial security. This reduction may not align with your family’s monetary objectives, especially if you rely on this benefit for future needs. Imagine if your loved ones faced financial uncertainty after your passing. For instance, the maximum Social Security survivors’ monthly income benefits for a spouse and two children under age 18 could be about $2,400 per month for a 35-year-old earning a $36,000 salary at death. This highlights the importance of maintaining adequate coverage, a vital factor that Allison and Brian encountered when enhancing their financial situation with Bright Advisers, ensuring their family’s future was secure.
- Tax Consequences: When considering whether I can withdraw money from my universal life insurance policy, it’s important to note that withdrawals can trigger tax liabilities, particularly if the amount exceeds the total premiums paid. It’s important to understand these potential tax implications; consulting a tax advisor can provide clarity on how these withdrawals may affect your overall financial situation. Just as Allison and Brian learned to leverage tax planning to minimize liabilities, you too can benefit from professional guidance.
- Loans as an Alternative: Instead of choosing a withdrawal, consider taking a loan against your coverage’s cash value. This alternative allows you to access funds without diminishing your death benefit. However, be mindful that any outstanding loan will accrue interest, which could affect the value of your plan over time, especially when considering if I can withdraw money from my universal life insurance policy. This strategy reflects the method adopted by Allison and Brian, who examined various options to improve their financial flexibility.
- Evaluate Other Financial Needs: Assess whether there are alternative resources available to meet your needs without utilizing your life insurance plan. Utilizing savings or other investments may provide the necessary funds while preserving your plan’s benefits. This assessment is comparable to the thorough financial planning that Bright Advisers offered to Allison and Brian, assisting them in ensuring their children’s future while maximizing their economic resources.
As Michela Buttignol notes, “Surrendering the policy means you are giving up the right to the death benefit altogether.” By carefully weighing these factors and considering insights from case studies like that of Allison and Brian, you can make a more informed decision that supports your family’s financial future. Remember, we’re here for you, and together, we can navigate this journey.
Conclusion
Understanding the intricacies of universal life insurance is essential for families seeking financial security. This type of insurance not only offers the flexibility of adjustable premiums but also includes a cash value component that can be accessed during critical life moments. Imagine having the ability to withdraw or borrow against this cash value, providing options to support important goals like education or unexpected expenses, all while ensuring a death benefit remains in place.
Navigating the withdrawal process requires thoughtful consideration. It’s important to:
- Review policy documents
- Determine the amount to withdraw
- Understand how this may impact the death benefit
As families increasingly recognize the importance of life insurance, being informed about these processes can lead to better financial decisions that align with their long-term goals.
Moreover, the financial implications of withdrawals should not be overlooked. Reducing the death benefit or triggering potential tax consequences can significantly affect a family’s financial landscape. Exploring alternatives, such as policy loans or other financial resources, ensures that families can meet their needs without compromising their life insurance benefits. Together, we can navigate this journey, empowering families to make informed choices that safeguard their financial futures.
Frequently Asked Questions
What is universal life insurance?
Universal life insurance is a type of permanent insurance that combines a death benefit with a cash value element, offering flexibility and growth potential for your family’s future.
What are the benefits of flexible premiums in universal life insurance?
Flexible premiums allow policyholders to adjust their premium payments according to their financial situation, making universal life plans suitable for families with varying income levels.
Can I withdraw money from my universal life insurance policy?
Yes, you can withdraw money from your universal life insurance policy since a portion of each premium builds a cash value account that can be accessed through withdrawals or loans.
How does the death benefit work in universal life insurance?
The death benefit in universal life insurance can be adjusted as your family’s needs evolve, ensuring financial protection for your loved ones.
How does the cash value earn interest?
The cash value of a universal life insurance policy earns interest that may vary over time, so it’s important to regularly review your plan to understand its performance and growth potential.
What is the projected access to insurance through employers by 2025?
It is projected that around 57% of workers in private industry will have access to insurance through their employers by 2025.
How competitive are the cash value growth rates for universal life insurance?
The anticipated cash value growth rates for universal life insurance are competitive, making it a viable option for families looking to secure their financial future.
Why is communication and education important in understanding universal life insurance?
Clear communication and education are crucial because a recent survey revealed that only 29% of consumers felt their insurance providers explained complex agreements clearly, highlighting the need for better understanding of these plans.
List of Sources
- Understand Universal Life Insurance Basics
- Life Insurance Facts and Statistics 2025 | Bankrate (https://bankrate.com/insurance/life-insurance/life-insurance-statistics)
- 62 Life Insurance Statistics in 2025 | Shortlister (https://myshortlister.com/insights/life-insurance-statistics)
- Life Insurance Statistics, Data and Industry Trends 2025 (https://forbes.com/advisor/life-insurance/life-insurance-statistics)
- What’s Universal Life Insurance? Why Choose UL Policies? (https://ethos.com/life-insurance/what-is-universal-life-insurance-ul)
- 5 Key Benefits of Universal Life Insurance: Quotes & Rates (https://insurancegeek.com/life-insurance/universal-life-insurance)
- Follow the Step-by-Step Withdrawal Process
- Life Insurance Statistics in 2025 | The Zebra (https://thezebra.com/resources/research/life-insurance-statistics)
- Life Insurance Facts and Statistics 2025 | Bankrate (https://bankrate.com/insurance/life-insurance/life-insurance-statistics)
- Life Insurance Statistics, Data and Industry Trends 2025 (https://forbes.com/advisor/life-insurance/life-insurance-statistics)
- Consider Financial Implications and Alternatives
- When Is It OK To Draw Cash From a Life Insurance Policy? (https://usnews.com/insurance/life-insurance/when-to-draw-cash-from-life-insurance-policies)
- How to Cash Out a Life Insurance Policy | Capital for Life (https://capitalforlife.com/blog/how-to-cash-out-a-life-insurance-policy)
- Cashing In Your Life Insurance Policy (https://investopedia.com/articles/pf/08/life-insurance-cash-in.asp)
- Life Insurance Statistics in 2025 | The Zebra (https://thezebra.com/resources/research/life-insurance-statistics)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Estate Planning for high-income W-2 families at Bright Advisers.
Keep reading