

Overview
Absolutely, you can contribute to both a 403(b) and a Roth IRA, as long as you meet the eligibility requirements for each account. Imagine having the flexibility to enhance your retirement savings strategy while caring for your family’s future.
Contributions to a 403(b) are made pre-tax, which means they can lower your taxable income, and this opportunity is tied to your employment with a qualifying organization. On the other hand, contributions to a Roth IRA are made after-tax, which requires you to have earned income within certain limits. This allows you to effectively diversify your retirement savings strategy, ensuring a more secure future for you and your loved ones.
Together, we can navigate this journey of financial planning, making informed decisions that align with your family’s values and goals.
Key Highlights:
- A 403(b) is a retirement savings plan for employees of public schools and certain tax-exempt organisations, allowing pre-tax contributions.
- A Roth IRA is an individual retirement account funded with after-tax dollars, enabling tax-free growth and withdrawals in retirement.
- Eligibility for a 403(b) requires employment with a qualifying organisation; a Roth IRA requires earned income and adherence to income limits.
- For 2025, the contribution limit for a 403(b) is $23,500, with an additional $7,500 catch-up for those aged 50 and above; the Roth IRA limit is $7,000, with a $1,000 catch-up for older individuals.
- Contributions to a 403(b) reduce taxable income, but withdrawals are taxed as ordinary income; Roth IRA contributions are made after taxes, allowing tax-free withdrawals under certain conditions.
- Consulting a tax advisor can help navigate the implications of contributions and withdrawals for effective financial planning.
Introduction
Navigating the complexities of retirement savings can feel overwhelming, especially for young parents who are eager to secure their family’s financial future. Imagine the peace of mind that comes with knowing you’re making the right choices for your loved ones. Among the myriad of options available, two standout choices are the 403(b) and the Roth IRA, each offering unique benefits and considerations.
It’s important to understand: can one contribute to both accounts simultaneously? By exploring the eligibility requirements, contribution limits, and tax implications of these accounts, families can empower themselves to make informed decisions that align with their long-term goals.
As parents strive to balance immediate needs with future aspirations, understanding these savings vehicles becomes crucial in crafting a solid financial strategy. Together, we can navigate this journey, ensuring that your family’s financial well-being is prioritized.
Understand the Basics of 403(b) and Roth IRA Accounts
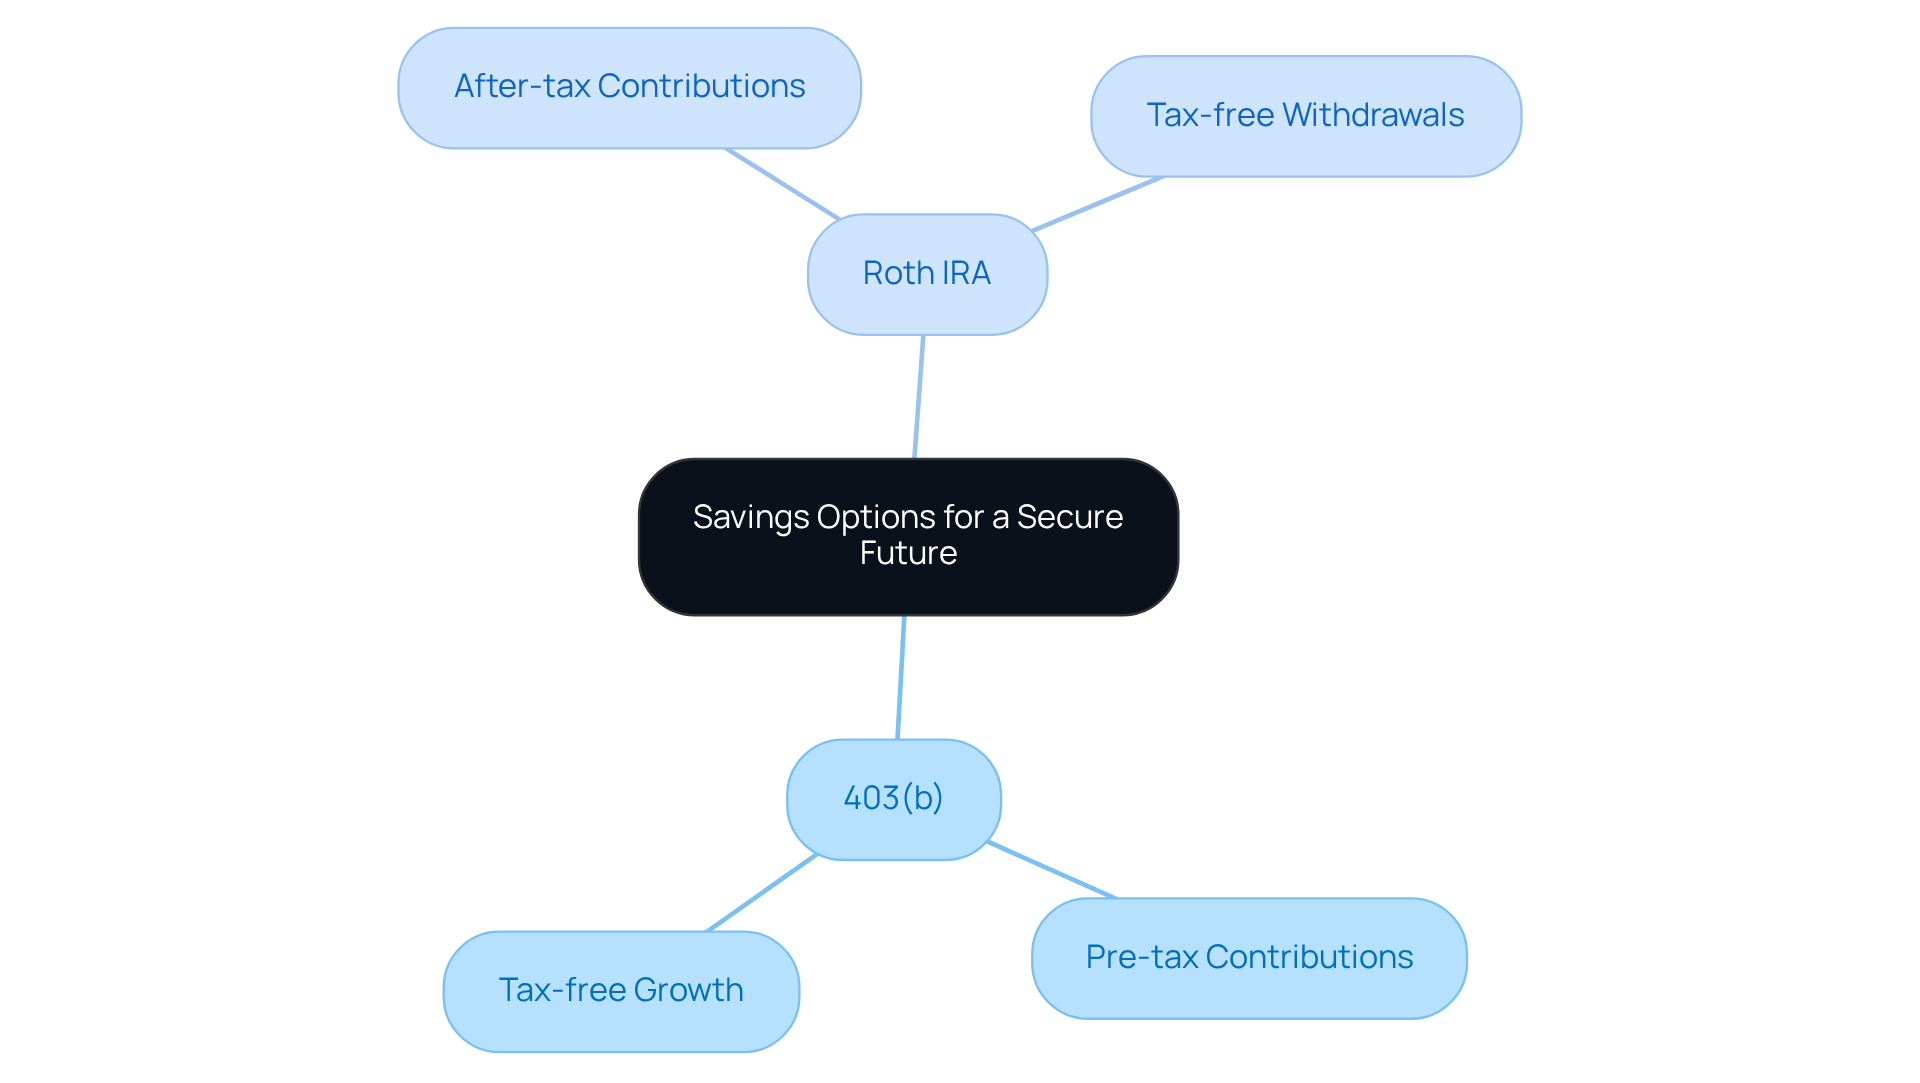
Understanding Your Savings Options for a Secure Future
As a young parent, you want the best for your family, and that includes planning for a secure financial future. Let’s explore two important savings options that can help you achieve your goals:
-
403(b): This is a savings plan designed for employees of public schools and certain tax-exempt organizations. It allows you to make pre-tax contributions, which can be a great way to save for retirement while managing your current budget.
-
Roth IRA: On the other hand, a Roth IRA is an individual retirement plan funded with after-tax dollars. This means that your money grows tax-free, and when you withdraw it in retirement, you won’t owe any taxes on it. Imagine the peace of mind that comes with knowing your savings can be accessed tax-free when you need it most.
It’s important to recognize that when considering the key differences, one must ask, can you contribute to a 403b and a roth ira, as contribution limits, tax treatment, and eligibility requirements differ significantly between these two options. Understanding these differences can empower you to make informed choices that align with your family’s needs.
Action Step: We encourage you to familiarize yourself with the specific rules governing each type. Remember, you don’t have to navigate this journey alone. Together, we can explore these options and find the best path forward for your family.
Verify Eligibility for Contributing to Both Accounts
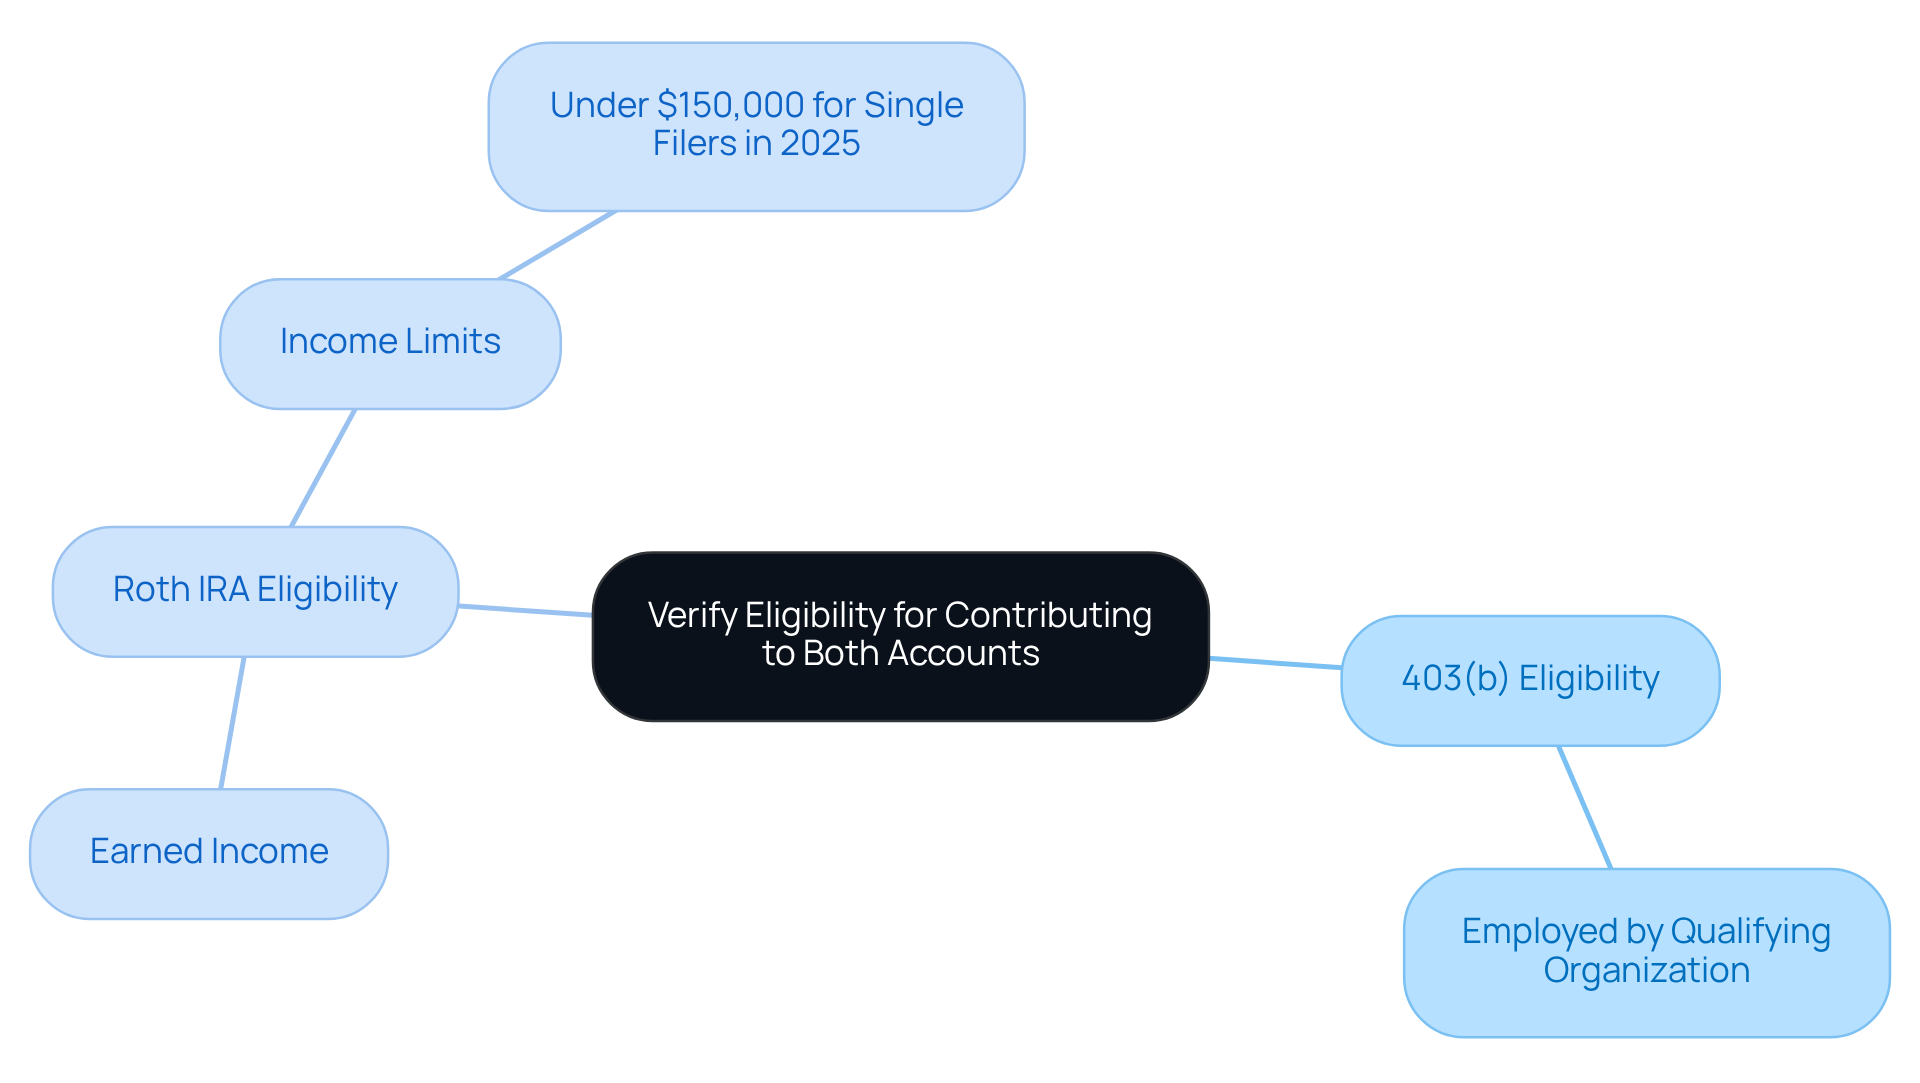
403(b) Eligibility: If you’re employed by a qualifying organization, such as public schools or non-profits, you may be eligible for a 403(b) plan.
Roth IRA Eligibility: To qualify for a Roth IRA, it’s essential to have earned income and stay within certain income limits—like under $150,000 for single filers in 2025.
Action Step: Imagine how peace of mind can come from knowing your options. Take a moment to verify your employment status and income level against IRS guidelines. This simple step can help confirm your eligibility for both options, specifically addressing the question of can you contribute to a 403b and a roth ira, ensuring you’re on the right path for your family’s financial future.
Check Contribution Limits for 403(b) and Roth IRA
Young families striving to secure their financial future often wonder, can you contribute to a 403b and a Roth IRA, given the funding limits for these accounts? For 2025, the 403(b) limit for deposits is set at $23,500, with an additional $7,500 catch-up amount available for individuals aged 50 and above. Similarly, the Roth IRA funding limit is $7,000, with a $1,000 catch-up for those aged 50 and older.
Imagine if you could enhance your economic security and independence. It’s essential to organize your contributions thoughtfully, considering your unique financial situation and retirement goals. Bright Advisers is here to help you maximize your contributions to these funds, guiding you in building a strong foundation for your family’s future. By understanding the specific strategies available, you can navigate the complexities of money management with confidence.
It’s important to understand how you can contribute to a 403b and a Roth IRA to maximize the limits for both accounts. Together, we can stay on the right path toward achieving your financial aspirations, creating a brighter future for your loved ones.

Evaluate Tax Implications of Contributions and Withdrawals
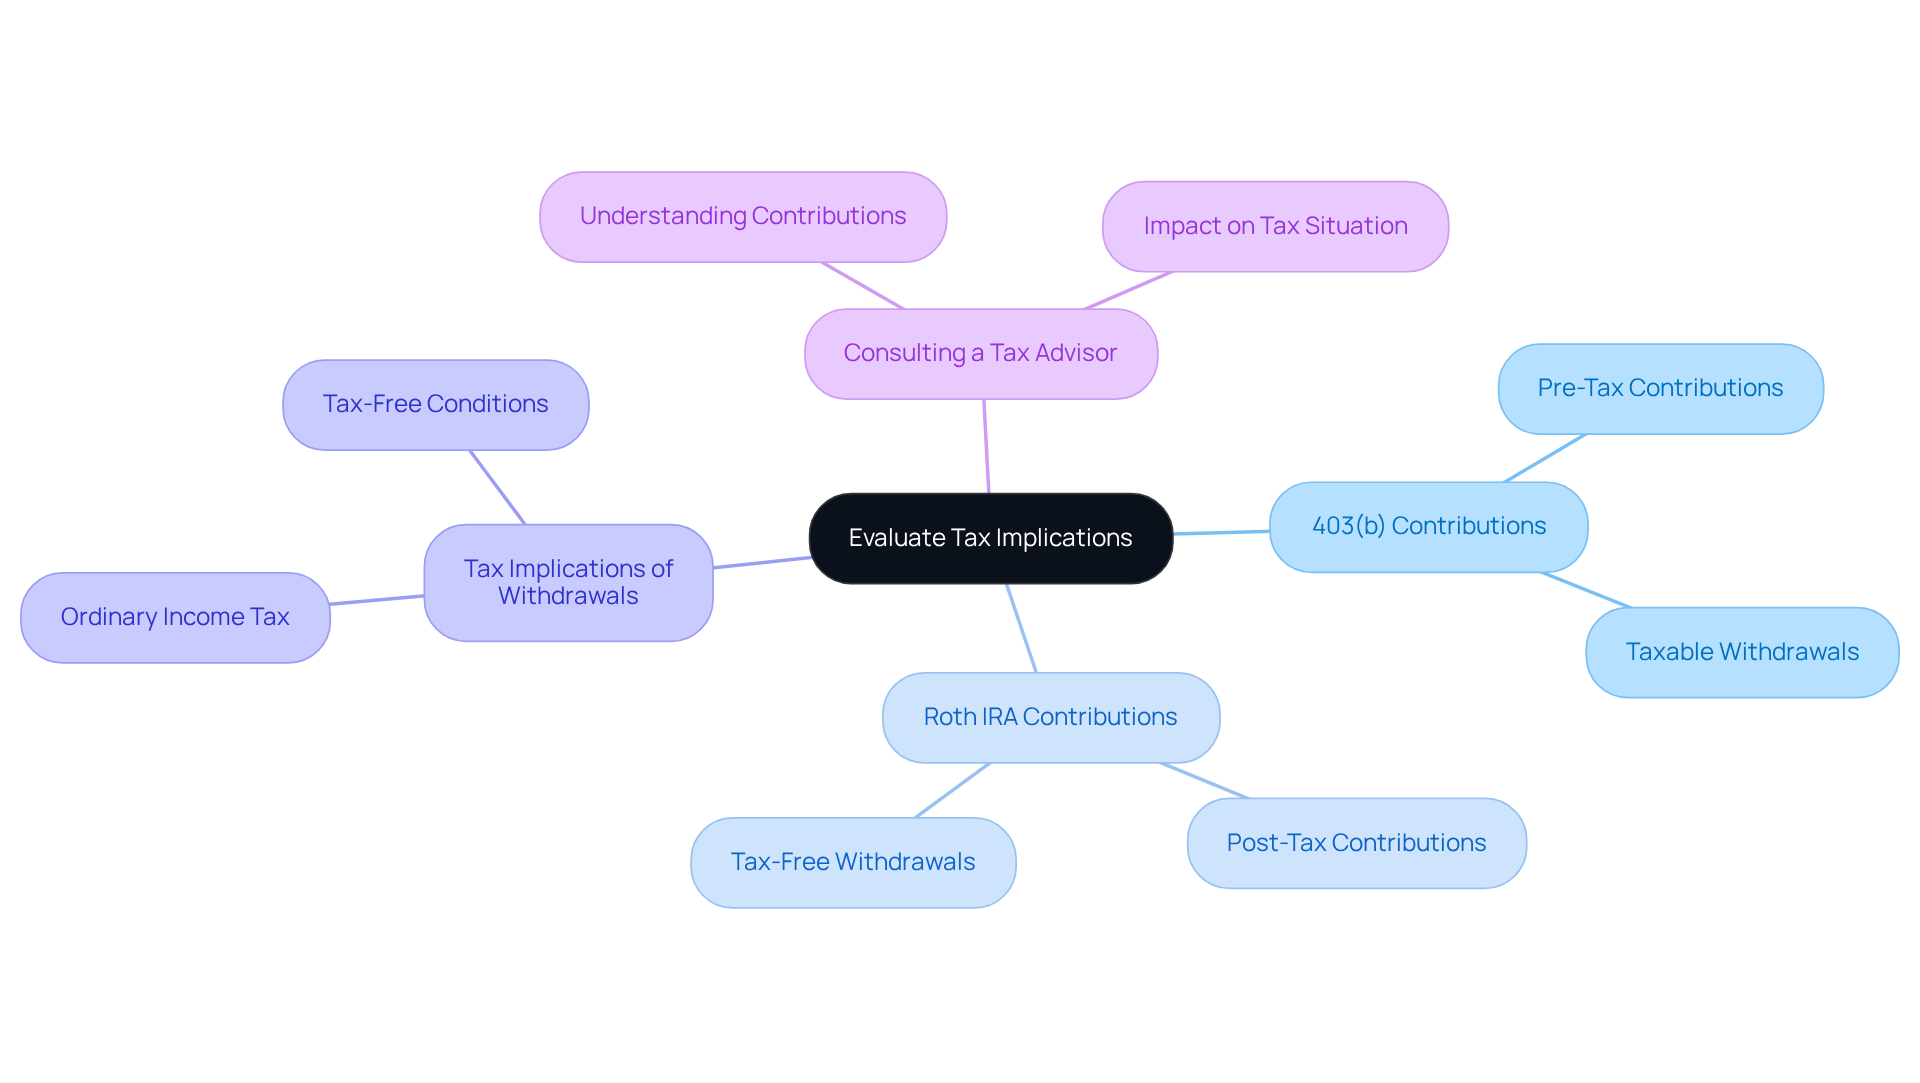
When it comes to planning for your family’s financial future, understanding your options can be both empowering and reassuring. When considering your financial options, you might wonder, can you contribute to a 403(b) and a Roth IRA, especially since contributions to a 403(b) are made pre-tax and can help lower your taxable income for the year. However, it’s important to understand that when you withdraw funds from a 403(b) later on, those amounts will be taxed as ordinary income.
Imagine if you could make contributions that allow you to enjoy tax-free withdrawals in your later years. One question that often arises is, can you contribute to a 403(b) and a Roth IRA, considering that with a Roth IRA, payments are made post-tax, enabling you to withdraw funds without tax implications, as long as certain conditions are met. This can provide peace of mind as you think about your family’s future.
To effectively oversee your family’s economic future, consider how these contributions influence your overall budgeting and asset monitoring. Utilizing services like cash flow forecasts and income strategies for later life can offer valuable insights tailored to your family’s needs.
It’s also wise to consult with a tax advisor who can help you understand the impact of your contributions and withdrawals on your tax situation. This is especially crucial as you navigate your broader financial management strategies, including retirement planning and education funding. Together, we can navigate this journey, ensuring that your family’s goals are met with confidence.
Conclusion
Understanding the nuances of both 403(b) and Roth IRA accounts is essential for parents aiming to secure their family’s financial future. Imagine the peace of mind that comes with knowing you’re making informed decisions that align with your long-term goals. By exploring these two savings options, you can open up a world of financial possibilities, allowing your family to strategically enhance their retirement savings.
Key points to consider include:
- Eligibility requirements
- Contribution limits
- Tax implications associated with each account
It’s important to understand that 403(b) contributions are pre-tax, while Roth IRA contributions are made with after-tax dollars. This distinction can significantly influence your financial planning. Additionally, recognizing the specific contribution limits for 2025, such as $23,500 for a 403(b) and $7,000 for a Roth IRA, empowers you to maximize your savings potential.
Ultimately, the journey toward financial security involves careful planning and informed choices. We encourage you to evaluate your eligibility for both accounts and consider how your contributions can impact your overall financial strategy. By taking proactive steps, such as consulting with a financial advisor, you can confidently navigate the complexities of retirement planning and set your family up for a prosperous future. Together, we can navigate this journey.
Frequently Asked Questions
What is a 403(b) account?
A 403(b) account is a savings plan designed for employees of public schools and certain tax-exempt organizations, allowing for pre-tax contributions to save for retirement.
What is a Roth IRA?
A Roth IRA is an individual retirement plan funded with after-tax dollars, allowing your money to grow tax-free and enabling tax-free withdrawals in retirement.
What are the tax implications of a 403(b) account?
Contributions to a 403(b) account are made with pre-tax dollars, which can help manage your current budget while saving for retirement.
What are the tax implications of a Roth IRA?
Contributions to a Roth IRA are made with after-tax dollars, meaning your money grows tax-free, and withdrawals in retirement are also tax-free.
Can you contribute to both a 403(b) and a Roth IRA?
Yes, you can contribute to both a 403(b) and a Roth IRA, but there are different contribution limits, tax treatments, and eligibility requirements for each.
Why is it important to understand the differences between a 403(b) and a Roth IRA?
Understanding the differences between a 403(b) and a Roth IRA can empower you to make informed choices that align with your family’s financial needs and retirement goals.
List of Sources

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Tax Management for high-income W-2 families at Bright Advisers.
Keep reading