

Overview
Have you ever wondered if your second home could help you financially? It’s a question many families face, especially when considering the potential tax benefits. While it’s important to know that depreciation primarily applies to rental properties, understanding how this works can be crucial for your financial planning.
Imagine if you could make the most out of your second home. Homeowners often have the opportunity to deduct mortgage interest and real estate taxes, which can ease financial burdens. However, the ability to depreciate a second home truly hinges on its rental status and how it’s used.
It’s essential to understand IRS regulations, as they can significantly impact your financial decisions. By grasping these concepts, you can navigate the complexities of wealth management with confidence. Remember, we’re here for you, and together, we can explore the best options for your family’s financial future.
Key Highlights:
- Depreciation serves as a tax deduction, allowing asset owners to recoup costs over time, particularly for rental properties.
- The standard depreciation period for residential rental properties is 27.5 years, allowing a deduction of approximately 3.636% of the property’s value annually.
- IRS defines a second home as one used for personal enjoyment if the owner stays at least 14 days a year or 10% of the leased days.
- Recapture tax of 25% applies to total depreciation deducted during ownership, impacting financial planning.
- Tax benefits differ between primary residences and second homes; primary residences allow mortgage interest deductions up to $750,000 and capital gains exclusions up to $250,000 for individuals and $500,000 for couples.
- Second homes do not allow for capital gains exclusion upon sale, making tax implications different.
- Mortgage interest and real estate taxes on second homes are deductible, but state and local tax deductions are capped at $10,000.
- If a second home is rented for fewer than 15 days a year, rental income is not taxable, and expenses cannot be deducted.
- Understanding these tax considerations helps families optimise their financial strategies and make informed investment decisions.
Introduction
Navigating the complexities of home ownership can feel overwhelming for young families. You may find yourself wondering about the potential tax benefits that come with owning a second home. With the right knowledge, families like yours can harness depreciation as a powerful financial strategy, turning tax obligations into meaningful savings.
But this raises an important question: can a second home truly be depreciated? What does this mean for families eager to secure their financial future?
By exploring the nuances of IRS regulations and tax deductions, you could uncover valuable opportunities that await those willing to delve into this essential aspect of real estate investment. Together, we can navigate this journey and empower your family’s financial growth.
Understand Depreciation for Second Homes
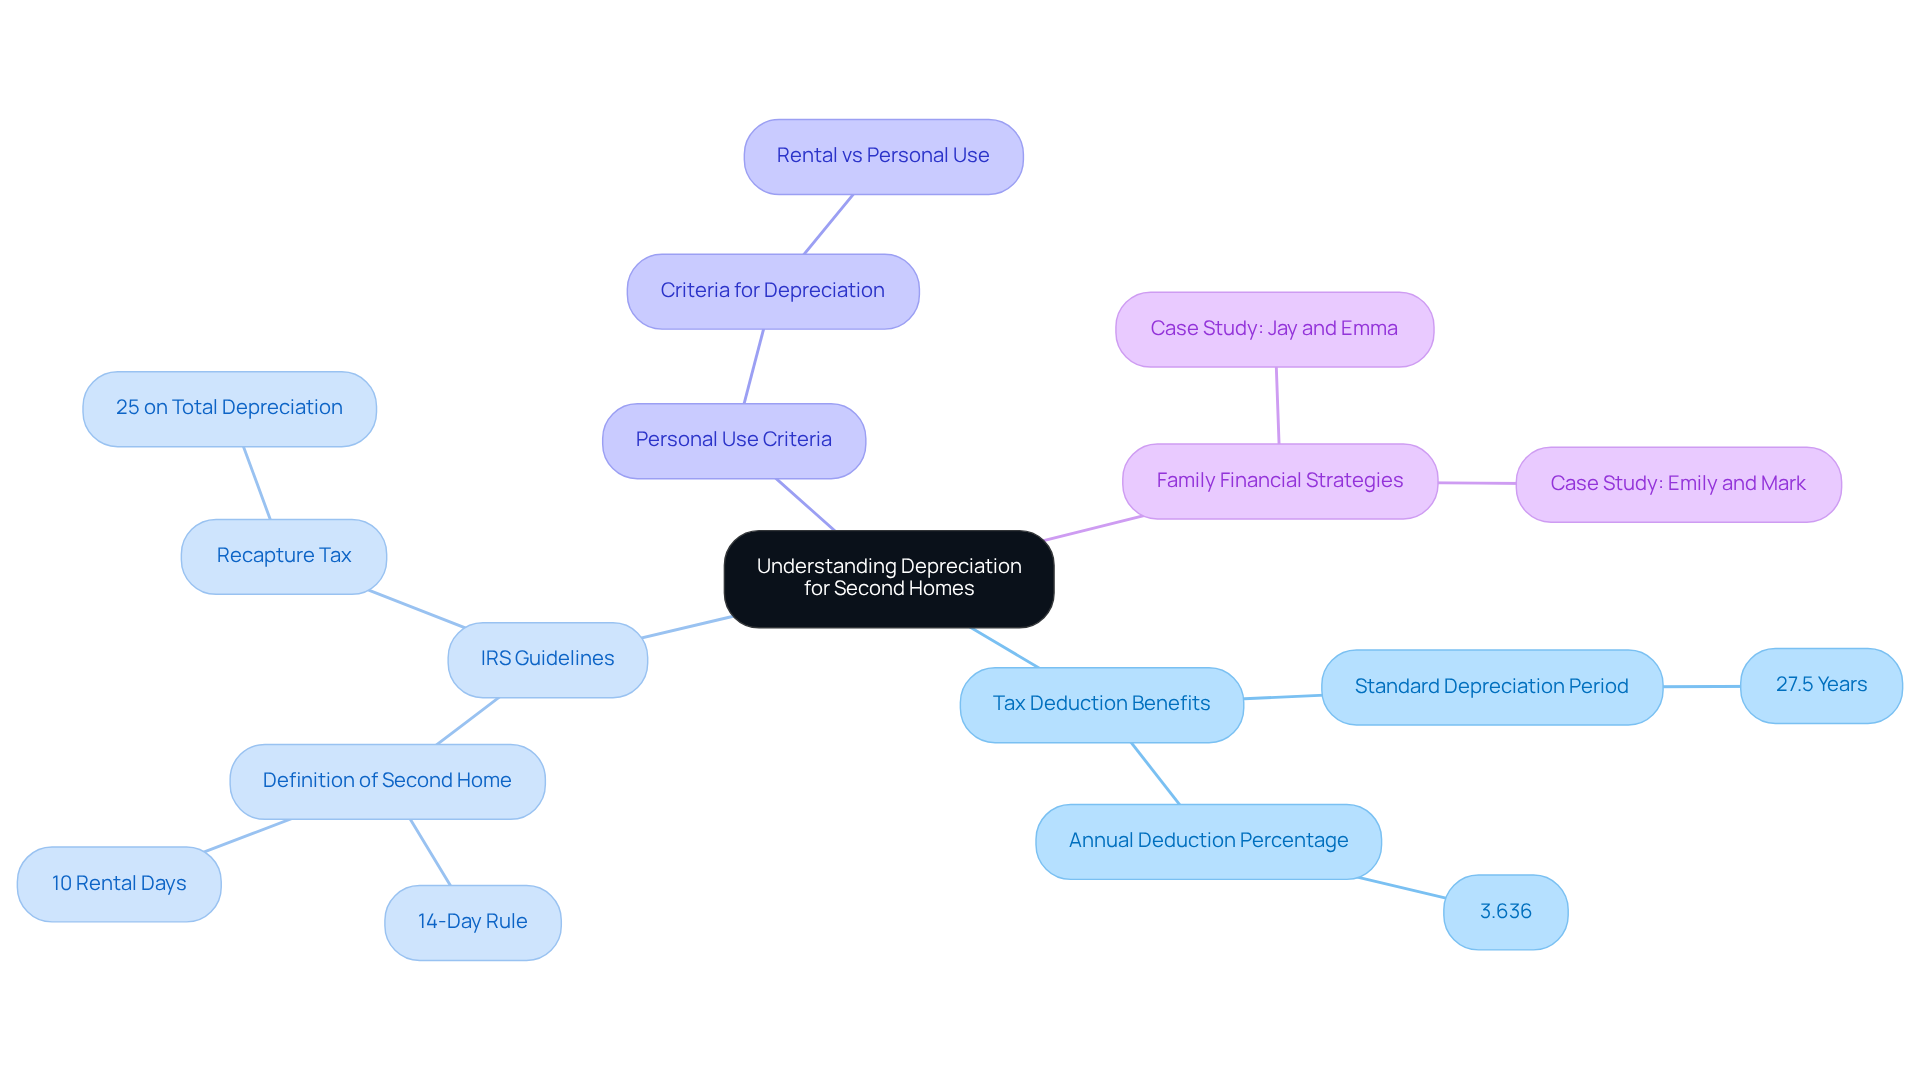
Understanding depreciation can be a valuable tool for families looking to optimize their financial planning. It serves as a beneficial tax deduction, enabling asset owners to recoup the expense of their possessions over time. For vacation homes, the IRS allows depreciation primarily for those classified as rental units, leading to the question: can you depreciate a second home? Did you know that the standard depreciation period for residential rental properties is 27.5 years? This means homeowners can deduct approximately 3.636% of the property’s value from their taxable income each year, providing a helpful financial cushion.
However, it’s important to note that if your additional residence is used solely for personal enjoyment, can you depreciate a second home? The IRS defines an additional residence as a property where the owner stays for at least 14 days each year or at least 10% of the days it is leased. Understanding these criteria is essential for answering the question of can you depreciate a second home.
As families navigate these financial waters, they should also be aware of the recapture tax of 25% on total depreciation deducted during ownership. This aspect can significantly impact your financial planning. By understanding these IRS regulations regarding depreciation for additional properties, families can determine how can you depreciate a second home to enhance their tax advantages and make informed decisions about their investments.
Consider the journey of young families like Jay and Emma. With the support of Bright Advisers, they optimized their tax planning and crafted a comprehensive financial strategy tailored to their needs. Similarly, Emily and Mark found empowerment in creating a solid foundation for their future, enjoying the freedom to choose their work-life balance, thanks to personalized financial strategies that included effective tax optimization.
Together, we can navigate this journey, ensuring that your family’s financial future is secure and thriving.
Compare Tax Benefits of Second Homes and Primary Residences
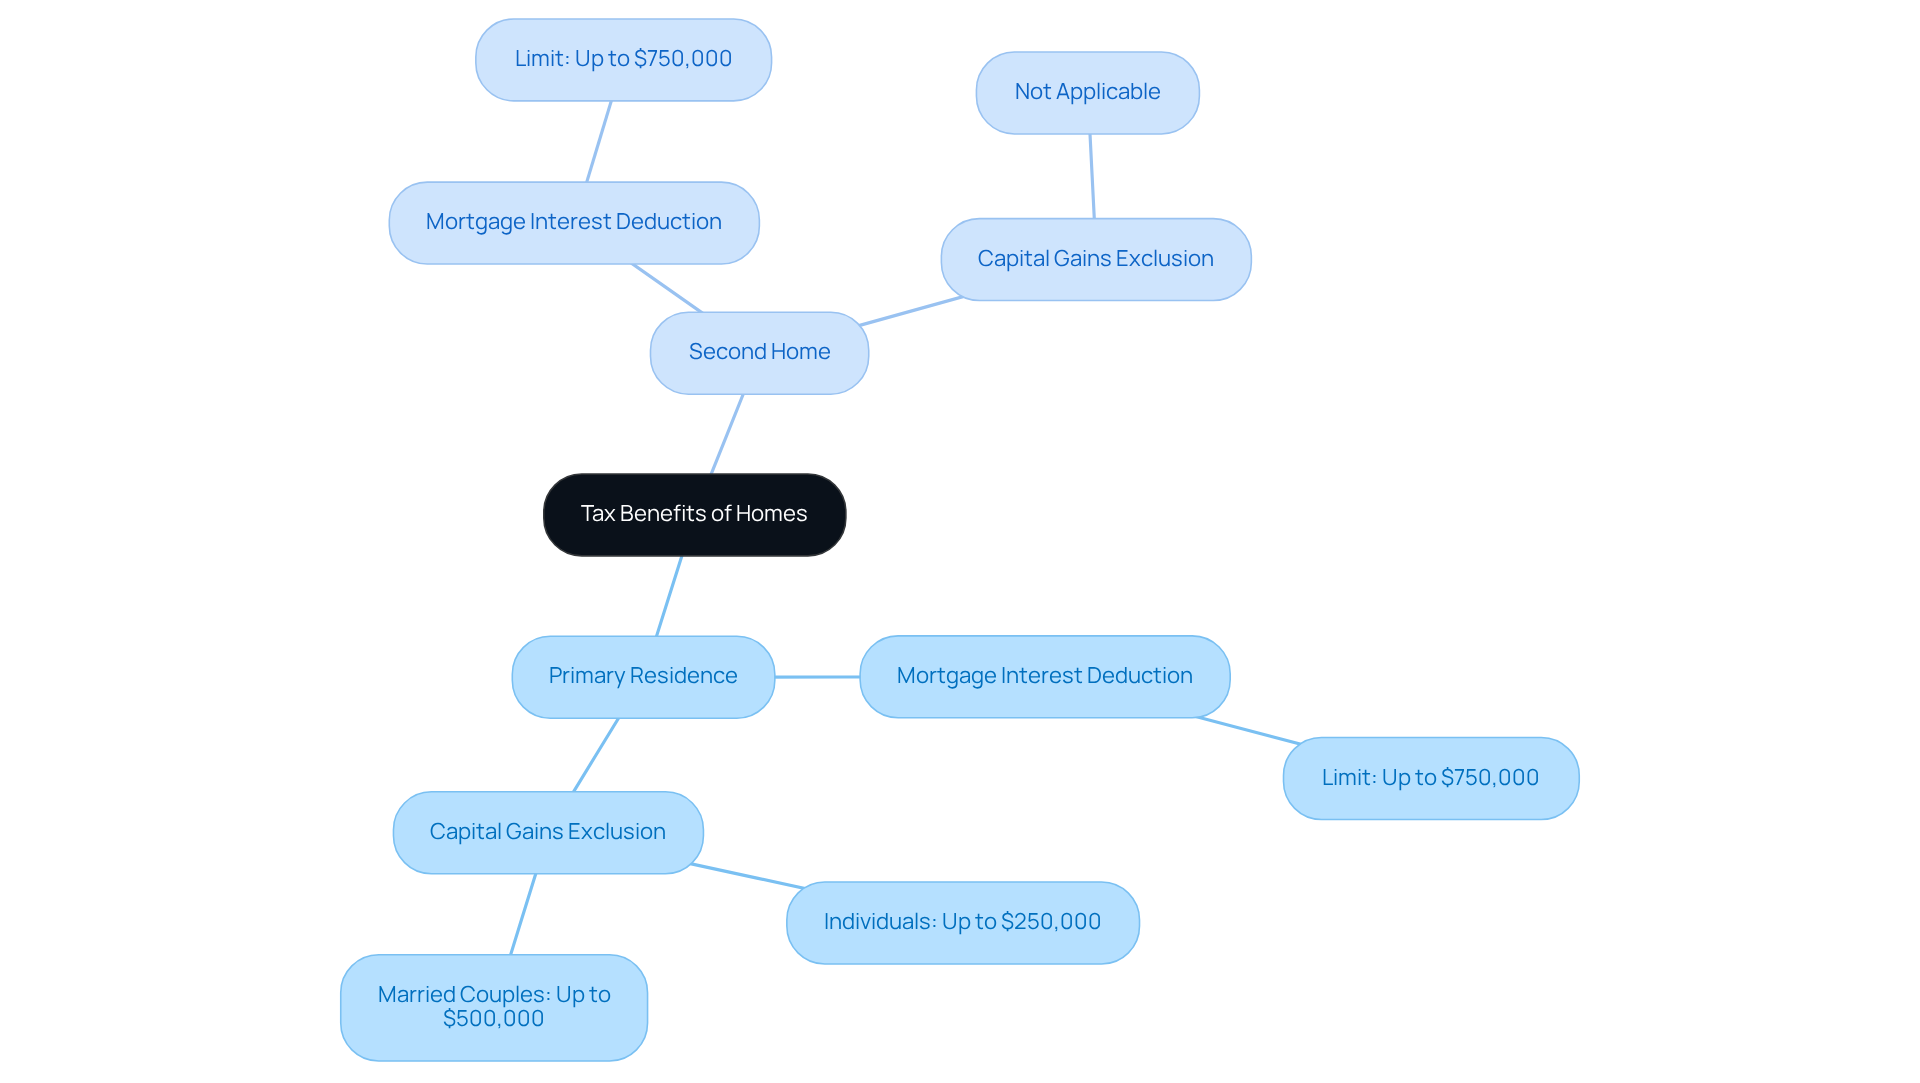
Understanding the tax advantages linked to your primary residence can be a game-changer for your family’s financial future. Typically, these benefits raise the question, can you depreciate a second home more favorably than those for additional properties? As a homeowner, you can deduct mortgage interest on both types of properties, but it’s essential to know the limits:
- For primary residences, you can deduct interest on mortgages up to $750,000.
- For additional residences, the same limit applies, yet the overall tax advantages may be less favorable.
Moreover, primary residences allow you to exclude capital gains from the sale of your home, which can significantly impact your wealth-building journey:
- Up to $250,000 for individuals.
- Up to $500,000 for married couples.
In contrast, vacation homes do not offer this exclusion. This comparison underscores the importance of understanding how each type of asset influences your overall tax obligation, especially for families like yours, who are aiming to create wealth through real estate and may wonder, can you depreciate a second home? Imagine if you could optimize your tax situation just like Allison and Brian did with Bright Advisers. Their effective tax planning not only secured their children’s future through education funding but also enabled them to retire sooner.
This experience illustrates how young families can benefit from tailored wealth management strategies. Together, we can navigate this journey, empowering you to make informed decisions about your primary residence and other investments. Remember, you’re not alone in this; we’re here for you, ready to support your family’s financial goals.
Explore Tax Deductions for Second Home Ownership
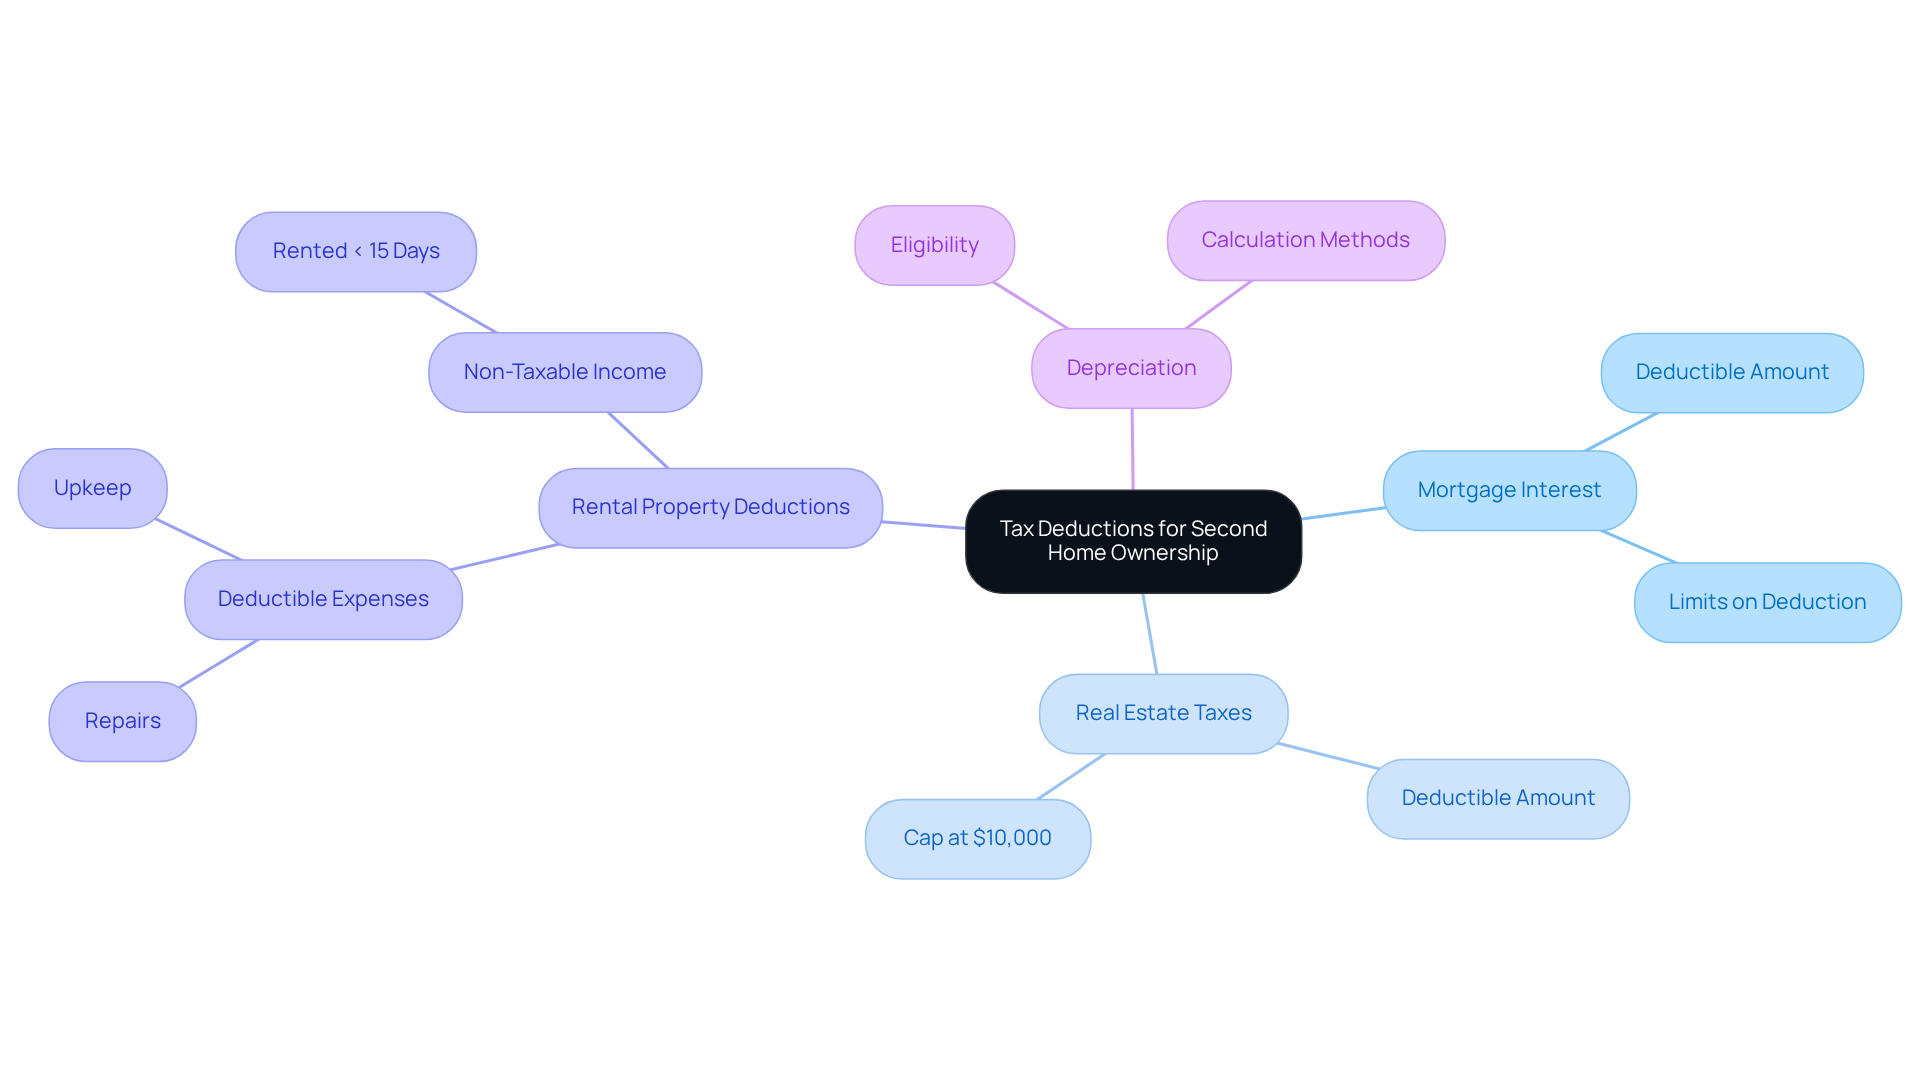
If you own additional homes, you may find comfort in knowing that you can consider, can you depreciate a second home, to help ease your financial burden. Just like with your primary residence, mortgage interest on an additional property is deductible, though it comes with the same limits. Additionally, real estate taxes can be deducted, but remember that the overall deduction for state and local taxes is capped at $10,000.
Imagine if you’ve leased that extra property—property owners can subtract costs related to the rental operation, including repairs, upkeep, and they often wonder, can you depreciate a second home? For families like Jay and Emma, understanding these deductions was a crucial step in crafting a comprehensive financial strategy. They focused on optimizing tax planning while also evaluating education savings options for their kids.
It’s important to understand that if your asset is rented for fewer than 15 days a year, the rental income is not taxable, and unfortunately, expenses cannot be deducted. By leveraging these thoughtful tax strategies, families can ensure they aren’t leaving money on the table. Take Emily and Mark, for instance; they discovered the flexibility to make career decisions that aligned with their desired work-life balance.
Understanding these deductions is essential for families looking to optimize their tax strategies, particularly to answer the question of how can you depreciate a second home and secure their financial future. Remember, we’re here for you, and together, we can navigate this journey toward financial wellness.
Assess Tax Implications of Renting a Second Home
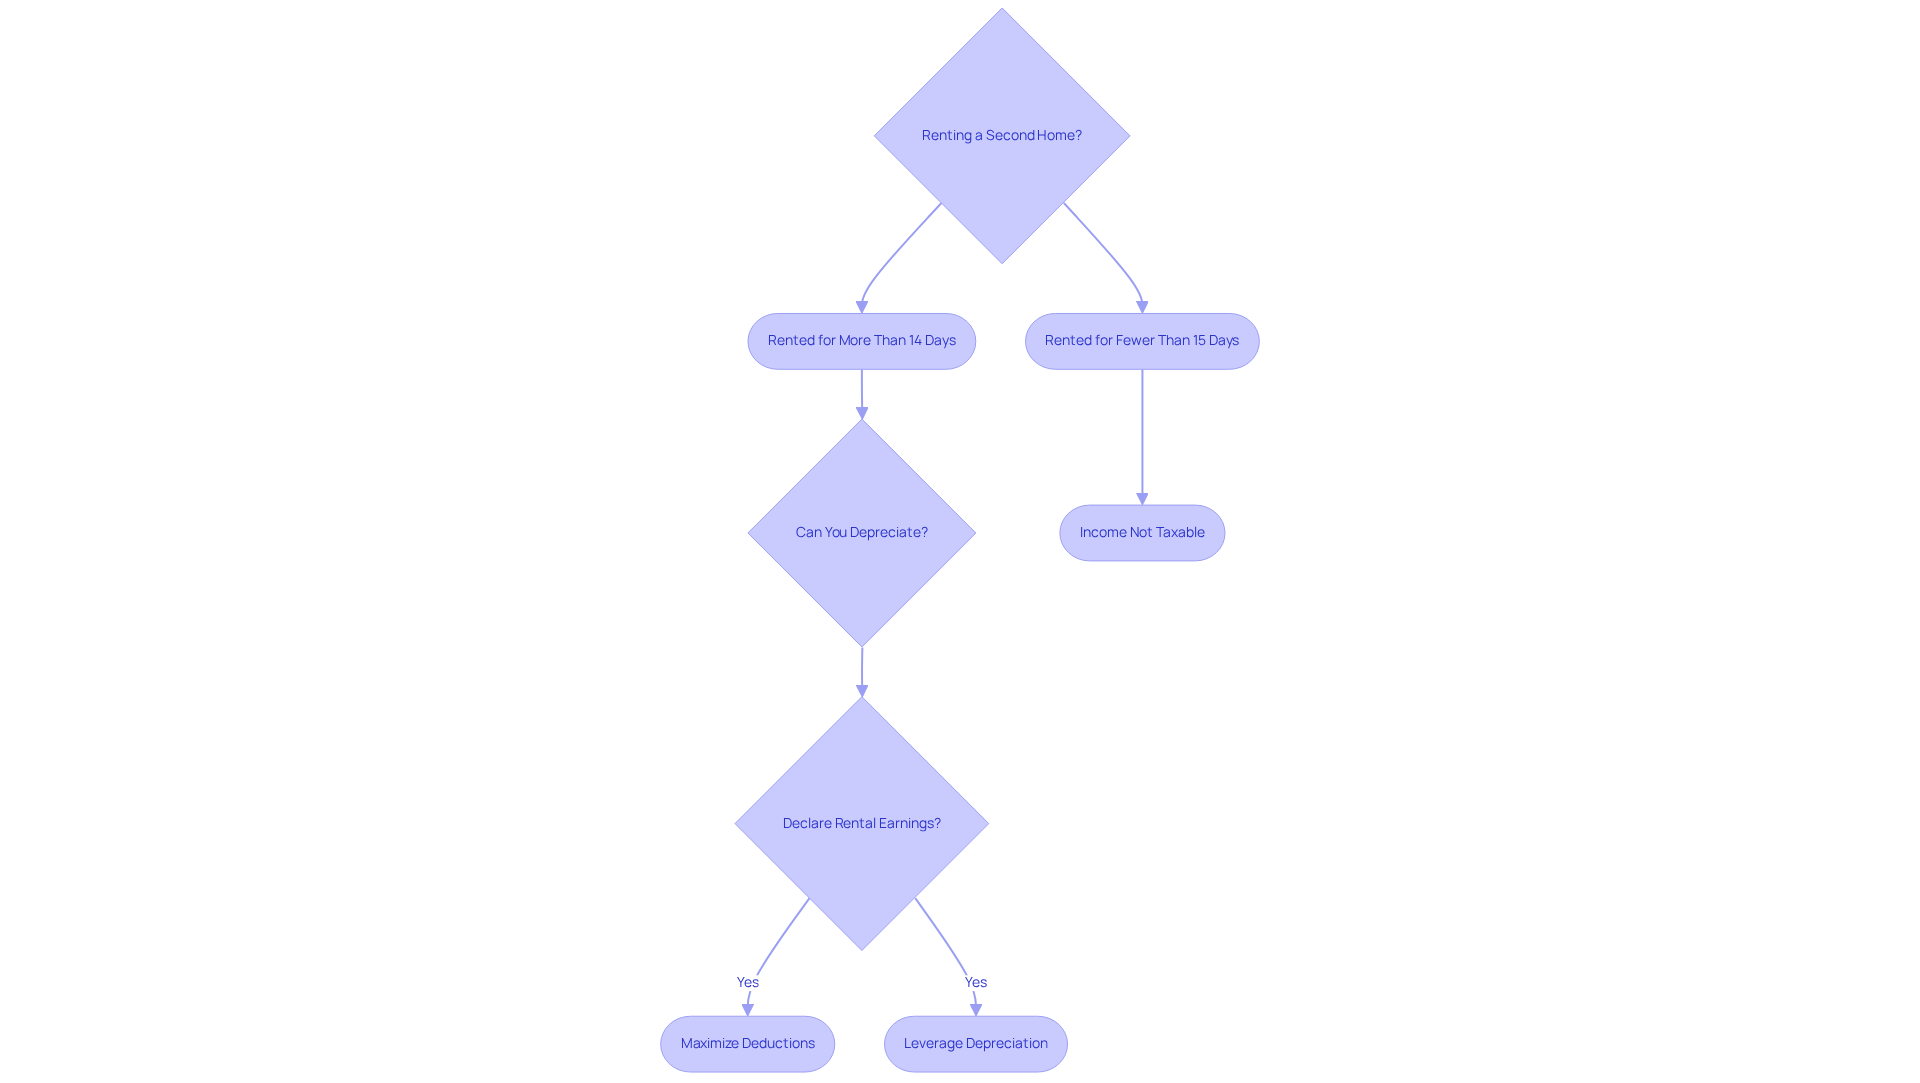
When renting out a second home, families should thoughtfully address important tax considerations, including the question of can you depreciate a second home. Imagine if your asset is leased for more than 14 days each year; in that case, it’s essential to declare the rental earnings on your tax filings. Fortunately, homeowners often ask, can you depreciate a second home, and they also have the opportunity to deduct related expenses, such as mortgage interest and real estate taxes. It’s important to understand that if the property is used for both personal and rental purposes, the IRS requires costs to be divided accordingly.
Now, consider this: if the property is rented out for fewer than 15 days, the income is not taxable. This scenario can be particularly advantageous for families looking to earn extra income without facing significant tax implications. Understanding these nuances is key to effectively managing your second home, particularly when exploring how can you depreciate a second home as a valuable investment.
Together, we can navigate this journey. By partnering with Bright Advisers, families can explore tailored tax optimization strategies. Imagine maximizing deductions and leveraging depreciation to enhance your financial security and achieve your long-term goals. We’re here for you, ready to support you every step of the way.
Conclusion
Understanding the intricacies of tax benefits associated with second home ownership can truly empower families to make informed financial decisions. Imagine exploring the potential for depreciation—this can be a game changer for enhancing tax strategies and optimizing financial planning. The ability to deduct costs related to a second home, especially when it’s classified as a rental property, can offer significant financial relief and support long-term wealth-building goals.
Throughout this article, we’ve shared key insights about:
- Eligibility for depreciation
- Comparing tax benefits between primary and secondary residences
- The implications of renting out a second home
Families have learned that while depreciation can be advantageous, it’s essential to navigate IRS guidelines carefully. It’s important to understand mortgage interest deductions, capital gains exclusions, and the nuances of rental income, as these are crucial components of effective tax planning.
Ultimately, the journey toward financial wellness for young families can be greatly enhanced by leveraging the available tax benefits of second home ownership. By seeking guidance from financial experts and utilizing tailored strategies, families can secure a brighter financial future. Together, we can navigate this journey—embracing these insights and taking proactive steps can lead to greater financial security, allowing families to thrive and enjoy the benefits of their investments.
Frequently Asked Questions
What is depreciation in the context of second homes?
Depreciation is a tax deduction that allows asset owners to recoup the expense of their possessions over time, which can be particularly beneficial for families in their financial planning.
Can you depreciate a second home?
You can depreciate a second home only if it is classified as a rental unit by the IRS. If the property is used solely for personal enjoyment, it cannot be depreciated.
What is the standard depreciation period for residential rental properties?
The standard depreciation period for residential rental properties is 27.5 years.
How much can homeowners deduct from their taxable income each year for depreciation?
Homeowners can deduct approximately 3.636% of the property’s value from their taxable income each year.
What criteria does the IRS use to define an additional residence?
The IRS defines an additional residence as a property where the owner stays for at least 14 days each year or at least 10% of the days it is leased.
What is the recapture tax associated with depreciation?
The recapture tax is 25% on the total depreciation deducted during ownership, which can significantly impact financial planning.
How can understanding IRS regulations on depreciation benefit families?
By understanding IRS regulations regarding depreciation for additional properties, families can enhance their tax advantages and make informed decisions about their investments.
List of Sources
- Understand Depreciation for Second Homes
- Buying a Second Home—Tax Tips for Homeowners (https://turbotax.intuit.com/tax-tips/home-ownership/buying-a-second-home-tax-tips-for-homeowners/L5Mzc5URo)
- Second Home Tax Deduction and Depreciation | Real Living Real Estate (https://realliving.com/pages/second-home-tax-depreciation)
- Second home tax benefits and deductions: A complete guide | Pacaso (https://pacaso.com/blog/second-home-tax-benefits)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Tax Management for high-income W-2 families at Bright Advisers.
Keep reading