

Overview
As a parent, you might be wondering how to access the dividends from your life insurance policy, especially if you have whole life insurance. There are several ways to do this, including:
- Cash withdrawals
- Premium reductions
- Paid-up additions
- Allowing the funds to accumulate at interest
Imagine if you could tap into these resources when your family needs it most. Cash withdrawals are the most common choice among policyholders, but it’s important to understand the potential tax implications and how this might affect your death benefit.
That’s why consulting with financial and tax professionals is so crucial. They can help you navigate these choices, ensuring you make informed decisions that align with your family’s needs. Remember, we’re here for you, ready to support you on this journey towards financial security.
Key Highlights:
- Life insurance dividends serve as reimbursements for policyholders, particularly in whole life insurance, enhancing financial security.
- Approximately 80% of comprehensive life insurance plans are dividend-paying, aiding family budgeting and economic stability.
- Policyholders can withdraw dividends through methods like cash withdrawals, premium reductions, paid-up additions, or accumulation at interest.
- Cash withdrawals are the most common choice, with about 60% of policyholders preferring immediate access to funds.
- Tax implications vary; dividends are generally tax-free if they do not exceed total premiums paid, but excess withdrawals may incur taxes.
- Withdrawals can reduce the death benefit, impacting financial security for beneficiaries.
- Consulting with financial and tax professionals is recommended to navigate the complexities of withdrawals and tax regulations.
Introduction
Understanding the ins and outs of life insurance dividends can be a true game-changer for families seeking financial stability. These dividends, often linked to whole life insurance policies, not only offer a potential source of income but also present various options for managing premiums and enhancing coverage. Imagine if you could access these dividends without jeopardizing your long-term financial goals. This guide gently delves into the intricacies of withdrawing dividends from life insurance, exploring methods, benefits, and critical tax implications. Together, we can empower families on their financial planning journey.
Understand Life Insurance Dividends
Life insurance distributions represent a meaningful way for mutual insurance firms to provide support to policyholders when their financial performance exceeds expectations. Often associated with whole life insurance plans, these payments can be seen as a reimbursement of contributions, offering a sense of relief and security. Understanding how these benefits work is crucial for policyholders, particularly regarding the options available, such as cash withdrawals, fee reductions, or acquiring additional coverage, and whether can you withdraw dividends from life insurance. Imagine if a policyholder pays a monthly premium of $100 and receives $25 in returns—this effectively lowers their new premium to $75. This flexibility empowers families to align their financial strategies with their long-term goals.
Did you know that about 80% of comprehensive life insurance plans are designed to distribute returns? This makes them an essential part of budgeting for families. These returns can be utilized to enhance economic stability, whether by reinvesting to increase the policy’s cash value or by using them to lower ongoing premium costs. Real-life examples show how families have successfully integrated life insurance payouts into their financial planning, like using these funds to support children’s education or bolster retirement savings.
Wealth consultants emphasize the importance of understanding life insurance payouts, as they can significantly impact a household’s financial situation. By actively managing these earnings, insurance holders can maximize their benefits and ensure that their life coverage contracts contribute positively to their overall financial strategy. Together, we can navigate this journey, ensuring your family’s financial future is secure and bright.

Identify Dividend-Paying Life Insurance Policies
If you’re looking for ways to secure your family’s financial future, you might ask, can you withdraw dividends from life insurance plans? Whole life or participating options from mutual insurance firms can be excellent choices. These plans are designed to share profits with policyholders, creating a sense of community and support. As you review your coverage documents, keep an eye out for terms like ‘participating’ or ‘dividend-eligible.’ It’s important to understand what these mean for your family’s financial health.
Imagine having a safety net that not only protects your loved ones but also offers potential financial benefits. By discussing your policy with your insurance representative, you can find out if you can withdraw dividends from life insurance and whether your coverage qualifies for profit-sharing. This conversation is crucial for understanding the specific conditions that apply. We’re here for you, guiding you through these important decisions.
This knowledge can empower families like yours to enhance economic advantages, ensuring a brighter future together. Remember, navigating financial planning is a journey, and together, we can explore the best options for your family’s needs.

Explore Methods to Withdraw Dividends
Can you withdraw dividends from a life insurance policy as a thoughtful way to meet your family’s financial needs? Let’s explore several methods that cater to different situations, each offering unique benefits:
-
Cash Withdrawal: Imagine needing immediate access to funds. This straightforward option allows you to request a cash payment of your earnings, with the insurer providing a check or direct deposit. It’s a popular choice for policyholders seeking liquidity when it matters most.
-
Premium Reduction: Picture this: utilizing your earnings to offset upcoming premium payments. This can effectively decrease your out-of-pocket expenses, making it a favored approach for families looking to manage their budgets while still enjoying the peace of mind that comes with coverage.
-
Paid-Up Additions: Consider reinvesting your earnings to acquire extra coverage. This strategy can increase your plan’s cash value and death benefit over time, especially beneficial for those aiming to build wealth and secure their family’s financial future.
-
Accumulation at Interest: What if you preferred to let your earnings grow? Keeping your dividends with the insurer allows them to earn interest, which you can access later without affecting your policy’s cash value. This option is ideal for those who want to nurture their dividends before tapping into them.
Research shows that around 60% of policyholders choose cash withdrawals over premium reductions, indicating a trend towards immediate access to funds. It’s essential to discuss with an advisor whether you can withdraw dividends from life insurance, along with the advantages and disadvantages of these options, ensuring your decisions align with your long-term monetary goals. Consulting with a financial advisor can also help you understand the tax implications of withdrawals, as the earnings portion may be taxable.
Ultimately, assessing these approaches will empower you to make informed choices that best accommodate your family’s needs. Remember, we’re here for you, and together, we can navigate this journey, always keeping in mind the possible loss of death benefit when withdrawing earnings.

Consider Tax Implications of Withdrawals
When considering if you can withdraw dividends from life insurance, it’s essential to understand the tax implications, especially for young families eager to secure their financial future.
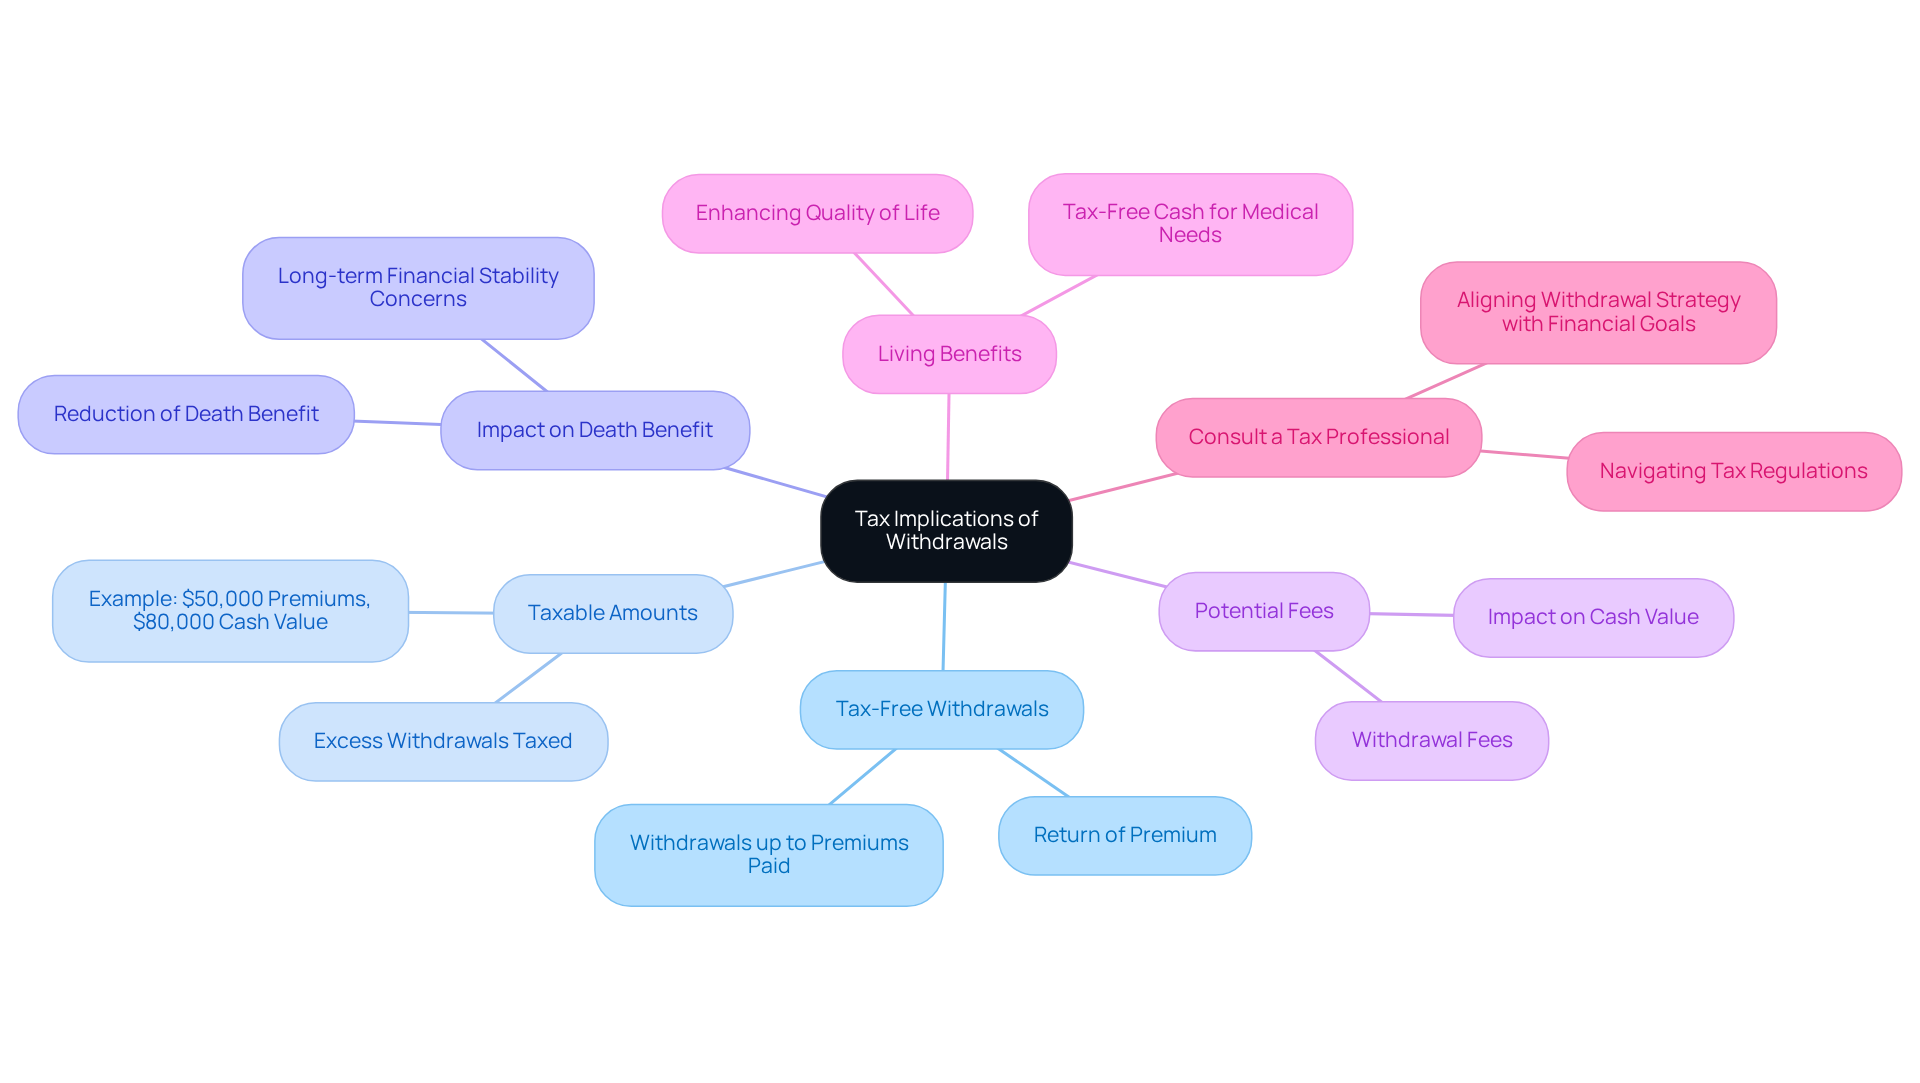
- Tax-Free Withdrawals: Typically, dividends are seen as a return of premium and are not taxable, as long as the total amount withdrawn does not surpass the premiums paid into the policy. This means that if you’ve contributed $50,000, you might wonder can you withdraw dividends from life insurance up to that amount without facing tax consequences.
- Taxable Amounts: However, if your withdrawals exceed your total contributions, the excess may be subject to income tax. For instance, if your cash value has grown significantly thanks to accumulated dividends, any amount taken out beyond your total contributions could lead to unexpected tax obligations. Imagine if you paid $50,000 in premiums, and your cash value is now $80,000; can you withdraw dividends from life insurance, considering that withdrawing $30,000 would be taxable as ordinary income?
- Impact on Death Benefit: It’s crucial to recognize that withdrawals can considerably reduce the death benefit available to your loved ones. This reduction can have lasting implications for your family’s financial stability, a primary concern for parents preparing for their children’s future.
- Potential Fees: Additionally, some policies may impose fees for withdrawals, which can further decrease the cash value and overall benefit of your policy.
- Living Benefits: Accessing living benefits can offer tax-free cash for medical needs or enhancing your quality of life, which may be particularly relevant for young families striving to improve their economic well-being.
- Consult a Tax Professional: Given the complexities of tax regulations, it’s wise to consult a tax professional. They can help you navigate your specific circumstances and ensure your withdrawal strategy aligns with your overall financial goals. This step is vital for making informed choices that protect your economic future and allow you to fulfill your family’s dreams.
At Bright Advisers, we emphasize the importance of crafting a lasting plan and investment approach tailored to your unique needs. Our personalized financial planning and investment strategies ensure you have the support necessary to make the best financial decisions for your family.
Conclusion
Understanding the intricacies of life insurance dividends is essential for policyholders who wish to enhance their financial well-being. Imagine having a resource that can support your family’s future. These dividends, primarily associated with whole life insurance policies from mutual insurance companies, can be utilized in various meaningful ways. By grasping how to withdraw dividends and the options available, families can strategically align these benefits with their long-term financial objectives.
Throughout this discussion, we’ve explored key methods for accessing life insurance dividends, including:
- Cash withdrawals
- Premium reductions
- Paid-up additions
- Accumulation at interest
Each approach offers unique advantages tailored to different financial needs, empowering you to make informed decisions that best suit your family’s circumstances. It’s important to understand the tax implications of these withdrawals, as they play a pivotal role in safeguarding your family’s financial future.
Navigating the world of life insurance dividends requires careful consideration and proactive planning. Engaging with a financial advisor can provide invaluable insights, ensuring that you not only maximize your benefits but also secure your loved ones’ financial stability. Together, we can navigate this journey. By taking the time to understand and manage these dividends effectively, you can create a robust financial strategy that supports your goals and enhances your overall economic health.
Frequently Asked Questions
What are life insurance dividends?
Life insurance dividends are payments made by mutual insurance firms to policyholders when their financial performance exceeds expectations. They are often associated with whole life insurance plans and can be seen as a reimbursement of contributions.
How can policyholders use life insurance dividends?
Policyholders can use life insurance dividends in several ways, including cash withdrawals, reducing premium fees, or acquiring additional coverage.
Can you withdraw dividends from life insurance?
Yes, policyholders can withdraw dividends from their life insurance policies, providing flexibility in managing their financial strategies.
How do life insurance dividends affect premium costs?
Life insurance dividends can lower the effective premium cost. For example, if a policyholder pays a monthly premium of $100 and receives $25 in dividends, their new premium effectively becomes $75.
What percentage of life insurance plans are designed to distribute returns?
Approximately 80% of comprehensive life insurance plans are designed to distribute returns, making them an essential part of budgeting for families.
How can families benefit from life insurance payouts?
Families can benefit from life insurance payouts by using the funds to enhance economic stability, such as reinvesting to increase the policy’s cash value or using the payouts to support children’s education or bolster retirement savings.
Why is it important to understand life insurance payouts?
Understanding life insurance payouts is crucial as they can significantly impact a household’s financial situation. By actively managing these earnings, insurance holders can maximize their benefits and ensure their life coverage contributes positively to their overall financial strategy.
List of Sources
- Understand Life Insurance Dividends
- How to use your life insurance policy dividends (https://policyadvisor.com/life-insurance/how-to-use-your-life-insurance-policy-dividends)
- New York Life Dividends: A Key Factor in Whole Life Insurance Performance (https://topwholelife.com/new-york-life-dividends-a-key-factor-in-whole-life-insurance-performance)
- Explore Methods to Withdraw Dividends
- The Pros and Cons of Withdrawing Cash from Your Life Insurance (https://peakesinsurance.com/blog/the-pros-and-cons-of-withdrawing-cash-from-your-life-insurance)
- Can You Cash Out a Life Insurance Policy? – NerdWallet (https://nerdwallet.com/article/insurance/getting-cash-from-life-insurance)
- How to Cash Out Life Insurance: Pros, Cons & Tax Implications | Facet (https://facet.com/insurance-planning/your-complete-guide-to-cashing-out-life-insurance-policies)
- When and How to Cash Out Life Insurance (https://smartasset.com/insurance/cash-out-life-insurance)
- Consider Tax Implications of Withdrawals
- Will Life Insurance Withdrawals Reduce The Death Benefit? (https://annuityexpertadvice.com/life-insurance-policy-withdrawals-reduce-benefit)
- Are Withdrawals from a Cash Value Life Insurance Policy Ever Tax Free? – Henssler Financial (https://henssler.com/are-withdrawals-from-a-cash-value-life-insurance-policy-ever-tax-free)
- Financial – Planning – Case – Studies 2023 | PDF | Investment Fund | Exchange Traded Fund (https://scribd.com/document/695749725/Financial-Planning-Case-Studies-2023)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Estate Planning for high-income W-2 families at Bright Advisers.
Keep reading