

Overview
Understanding the differences between compounded daily and monthly can profoundly impact the total earnings your family can accumulate over time. Daily compounding often yields higher returns, which is something every family aspires to achieve. Imagine if your savings could grow more rapidly just by choosing a different compounding method.
This article illustrates these concepts through relatable examples, showing how daily compounding allows for more frequent interest calculations. This can significantly enhance your savings growth and provide your family with greater financial security. On the other hand, monthly compounding offers a simpler approach, which may feel more manageable for families just beginning their financial journey.
It’s important to understand that each option has its benefits, and choosing the right one can make a real difference in your family’s financial future. We’re here for you, ready to support you as you navigate these important decisions. Together, we can explore the best strategies to help your family thrive.
Key Highlights:
- Compound interest allows earnings to be added to the principal, generating additional returns over time.
- Understanding compound returns is crucial for families to optimise their savings strategies.
- The frequency of compounding (daily vs. monthly) significantly affects total earnings.
- An example shows that investing $100 monthly at 4% interest compounded monthly could yield approximately $151,550 by retirement.
- Daily compounding generally results in higher total savings compared to monthly compounding due to more frequent interest calculations.
- For instance, a $10,000 deposit at 2% APY could grow to $17,361.75 with daily compounding versus $17,355.52 with monthly compounding after five years.
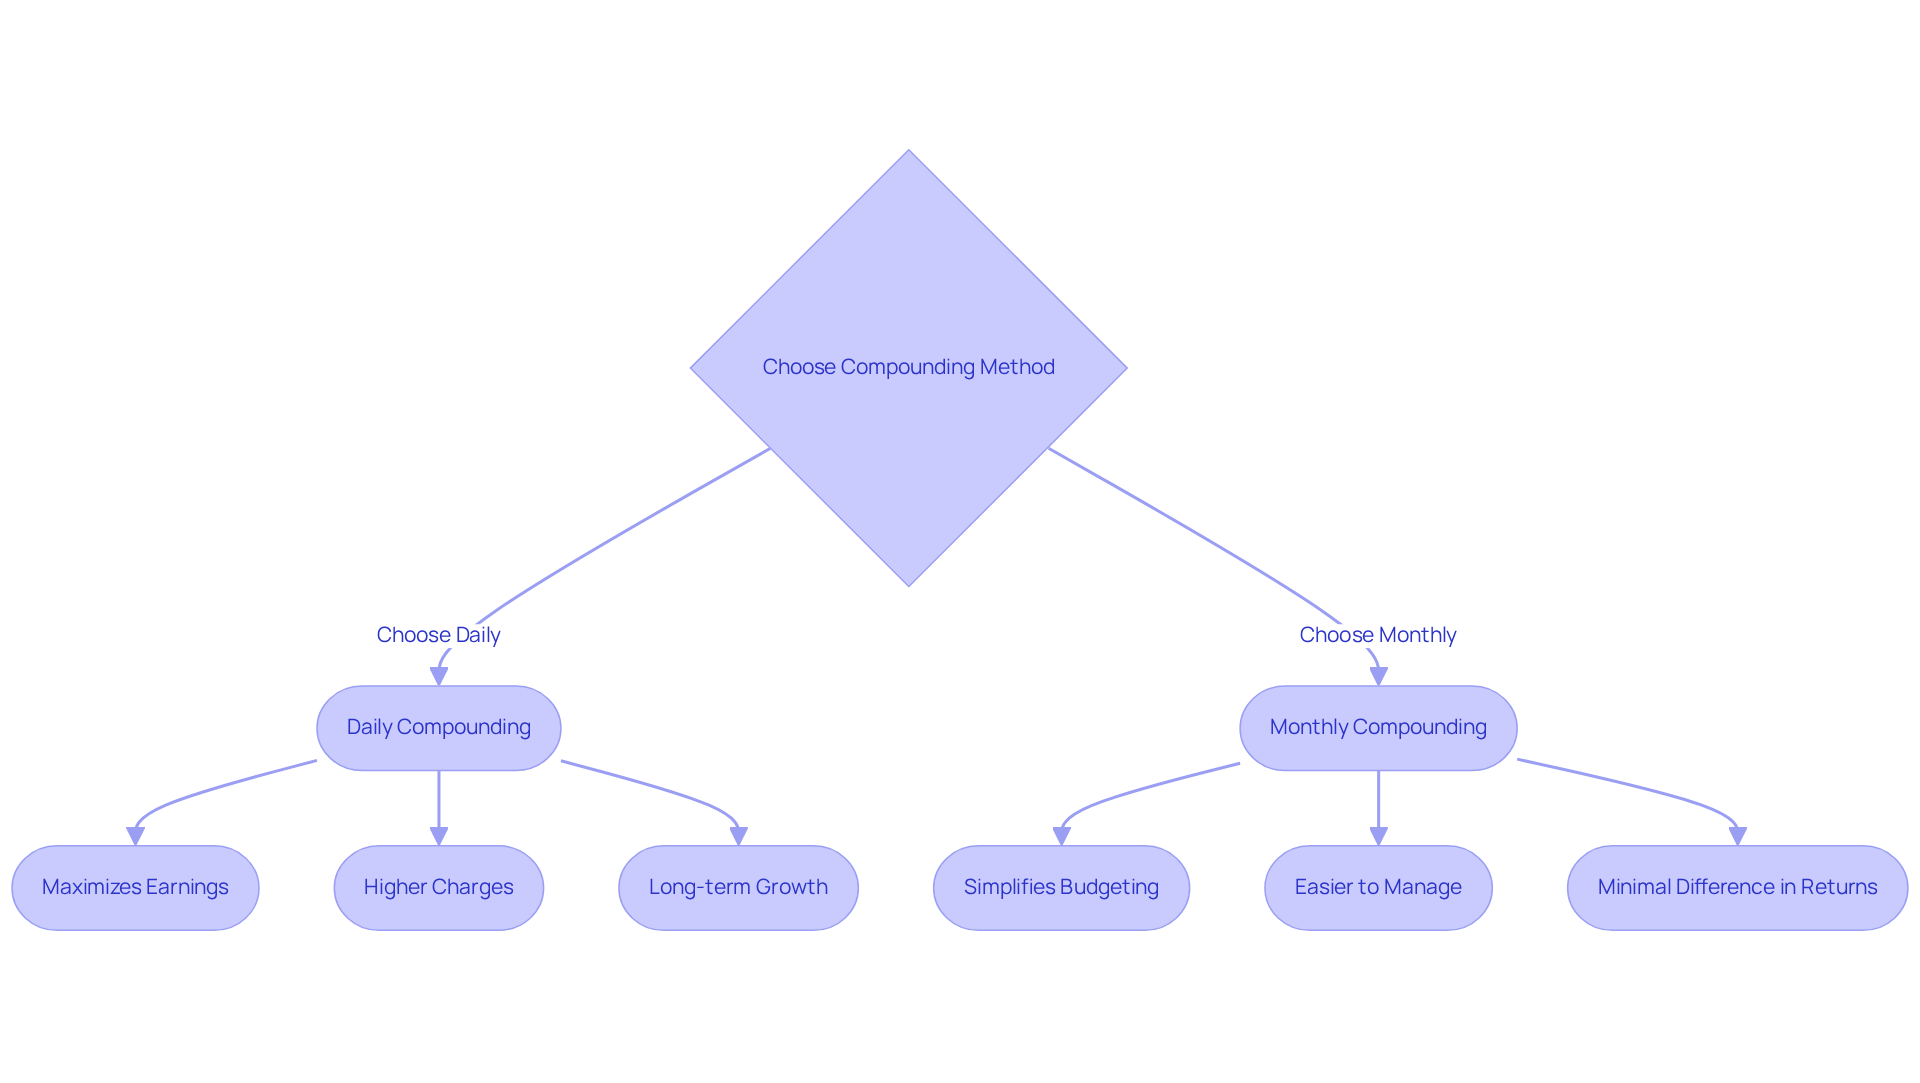
- Daily accumulation can maximise earnings, but may come with higher fees or balance requirements.
- Monthly accumulation simplifies budgeting and cash flow management, making it more accessible for families starting their financial journey.
- Choosing the right compounding method depends on financial goals, timelines, and risk tolerance.
- Consulting financial advisors can help families align their compounding strategies with their financial objectives.
Introduction
Understanding the nuances of compound interest is essential for young families striving to secure their financial future. Imagine the peace of mind that comes from knowing your savings can grow effectively. The frequency of compounding—whether daily or monthly—can significantly influence savings growth, impacting how quickly investments can accumulate wealth. As families navigate their financial journeys, it’s important to understand:
- Does the difference between daily and monthly compounding truly matter in the long run?
Exploring this question reveals not only the mechanics of compound interest but also the strategic decisions that can enhance your family’s financial well-being. Together, we can navigate this journey toward a more secure future.
Understanding Compound Interest: Basics and Mechanisms
Understanding compound returns is a vital step for young households looking to secure their financial future. This process involves adding earnings to the principal amount of a loan or deposit, enabling those earnings to generate even more returns. Imagine how much quicker your savings could grow compared to basic returns, which only consider the initial amount.
It’s essential for families to grasp the basics of compound returns, as it directly influences their savings and financial strategies. Bright Advisers is here to help, offering customized financial strategies that incorporate the concept of compound growth. We want to assist you in understanding how to enhance your investments for a brighter future.
The frequency of compounding, particularly when comparing compounded daily vs monthly, plays a significant role in the total earnings you can accumulate over time. For example, consider a household that invests $100 monthly at a 4% interest rate compounded monthly. By the time they reach retirement age, they could accumulate approximately $151,550. This illustrates the incredible power of starting early and making consistent contributions.
At Bright Advisers, we prioritize minimal fund fees, ensuring that your family can maximize investment returns. Financial advisors emphasize that understanding these mechanisms empowers households to make informed decisions, optimizing savings strategies to secure a prosperous future for your children.
By embracing the benefits of compound returns, families can effectively enhance their financial stability and growth potential. Together, we can navigate this journey and build a secure future for your loved ones.
Daily vs. Monthly Compounding: Key Differences Explained
Understanding the difference in how savings are compounded daily vs monthly can significantly impact your family’s financial future. Daily accumulation means that your earnings are calculated and added to your principal balance every single day. This frequent calculation leads to more regular increases in your balance, which can elevate your effective interest rate over time. In contrast, with monthly accumulation, returns are only calculated once a month.
Imagine if you invested $1,000 at an annual interest rate of 5%. When comparing compounded daily vs monthly, you would earn more interest over the year with daily compounding. This is because the interest is calculated more often, allowing your savings to grow faster. This difference, while it may seem small at first, can significantly enhance the growth of your savings and investments, especially over the long term.
Now, consider a family that deposits $10,000 into a high-yield savings account with a 2% APY. If the interest is accrued daily, after five years, their total savings would grow to $17,361.75. However, with monthly accumulation, they would have $17,355.52. The extra interest gained through daily accumulation, although it may appear minor, highlights the cumulative benefits of the approach when comparing compounded daily vs monthly methods over time.
Financial analysts emphasize that understanding how interest accumulates can profoundly influence your family’s wealth. By recognizing these differences, you can make informed decisions that maximize your savings potential. Together, we can navigate this journey towards a more secure financial future for your family.

Evaluating the Benefits and Drawbacks of Daily and Monthly Compounding
Daily accumulation can truly maximize your earnings, making it especially beneficial for long-term savings. Even minor sums of returns can grow significantly over time, which is something every family should consider. For instance, imagine contributing $10,000 at a 2% annual percentage yield (APY) compounded daily. After 30 years, that could amount to $67,546.22, with $21,542.22 coming from interest alone. However, it’s important to be aware that daily accumulation may come with higher charges or minimum balance requirements in certain accounts, which could pose challenges for some households just starting their financial journey. This is where Bright Advisers’ commitment to minimal fund fees becomes essential, as it enhances accessibility to wealth management for families, allowing them to invest without the worry of excessive costs.
On the other hand, monthly accumulation, while slightly less effective in terms of growth, offers a simpler method that might be more manageable for families beginning their financial paths. It simplifies budgeting and cash flow management, making it easier for you to keep track of your finances. For example, the same $10,000 contribution compounded each month would lead to a total of $67,540.00 after 30 years. This illustrates that, although the difference in interest accrued when considering compounded daily vs monthly calculations is minimal—only $6.23 over five years—it can still impact overall returns.
As you navigate these options, it’s crucial for families to assess their investment timeline, liquidity needs, and the specific conditions of their financial products. By understanding the nuances of compounded daily vs monthly interest accumulation, you can make informed choices that align with your financial objectives and family situation. Consulting a financial advisor, like those at Bright Advisers, can provide valuable guidance in this journey, ensuring that young families receive tailored wealth management solutions that empower your financial security and freedom. We’re here for you, every step of the way.
Choosing the Right Compounding Method for Your Financial Goals
Choosing the right aggregation method—whether daily or monthly—requires families to thoughtfully consider their financial goals, timelines for funding, and risk tolerance. Imagine if you could optimize your savings over a long period; daily accumulation often proves to be beneficial as it can significantly enhance wealth growth through the power of compound interest. On the other hand, families who prefer a more straightforward financial strategy with less frequent oversight may find monthly accumulation to be more appealing.
It’s also crucial to think about the types of investment accounts available, as some accounts may offer better terms for one method over the other. For instance, consider this: if you invest $200 monthly starting at age 25, you could accumulate around $698,000 by age 65 with an 8% annual return. This example highlights the immense benefits of beginning early and selecting the right accumulation frequency.
Ultimately, aligning your compounding method with your family’s specific financial goals not only supports effective wealth management but also paves the way for a brighter financial future for your children. Together, we can prioritize what truly matters and ensure that your family’s dreams are within reach.
Conclusion
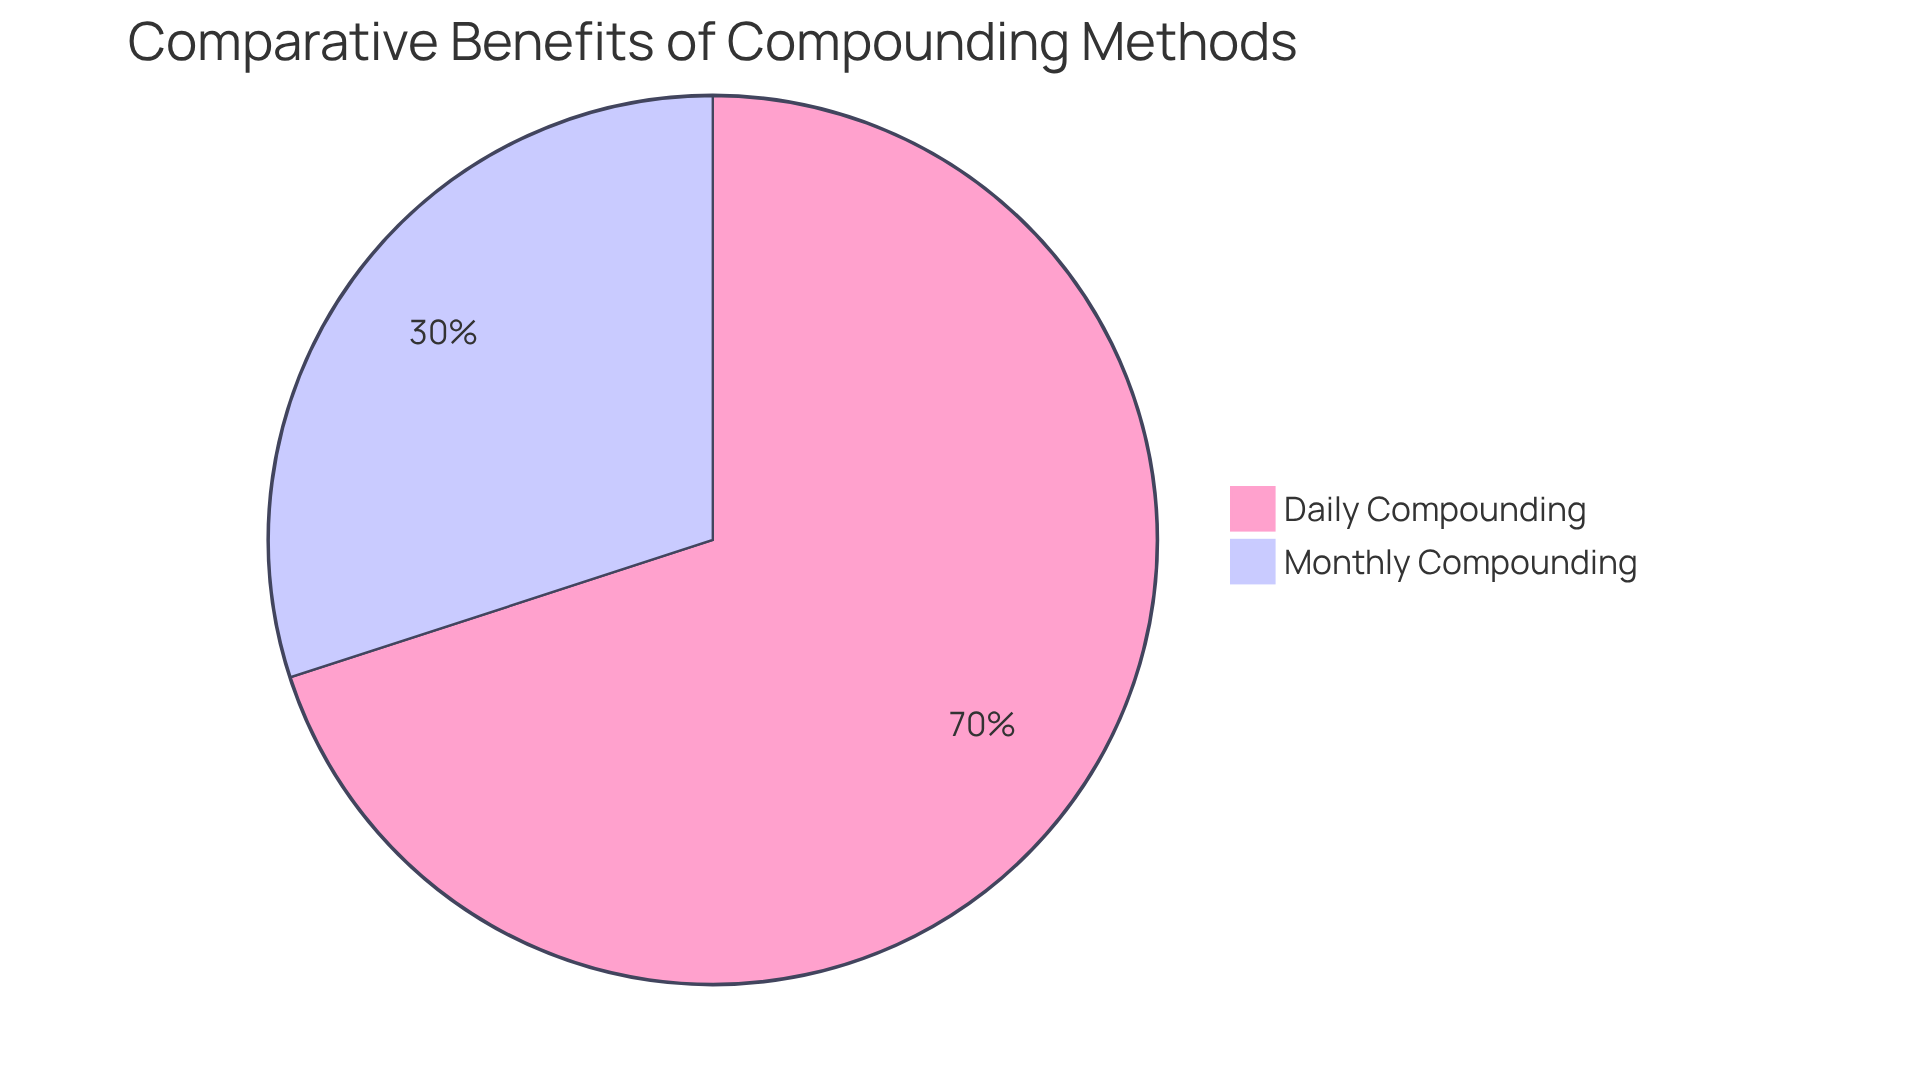
Understanding the differences between compounded daily and monthly is essential for young families aiming to enhance their financial futures. The choice between these two methods can significantly affect the growth of savings and investments, ultimately impacting long-term financial stability. Imagine leveraging the power of compound interest to maximize your earnings—this is the advantage of daily compounding that can help secure a prosperous future for your family.
Throughout this discussion, we’ve highlighted the importance of compounding frequency. It’s important to understand how daily accumulation can lead to greater total returns compared to monthly accumulation. Even small differences in interest can lead to significant growth over time, as illustrated by the cumulative benefits of daily compounding. As you evaluate your financial goals, investment timelines, and risk tolerance, remember that these factors can guide you toward the most suitable compounding method.
In conclusion, the financial decisions made today can lay the groundwork for a brighter tomorrow. Young families are encouraged to take an active role in understanding the nuances of compound interest. Together, we can navigate this journey—consulting financial advisors for tailored strategies can be a great step forward. By making informed choices regarding compounding methods, you can not only optimize your savings but also pave the way for achieving your dreams and ensuring a secure financial future for your children.
Frequently Asked Questions
What is compound interest?
Compound interest is the process of adding earnings to the principal amount of a loan or deposit, allowing those earnings to generate even more returns over time.
Why is understanding compound interest important for families?
Understanding compound interest is crucial for families as it directly influences their savings and financial strategies, helping them secure a better financial future.
How does the frequency of compounding affect total earnings?
The frequency of compounding, such as daily versus monthly, significantly impacts the total earnings accumulated over time. More frequent compounding can lead to higher returns.
Can you provide an example of how compound interest works?
For instance, if a household invests $100 monthly at a 4% interest rate compounded monthly, they could accumulate approximately $151,550 by retirement age, demonstrating the benefits of starting early and making consistent contributions.
How does Bright Advisers help families with compound interest?
Bright Advisers offers customized financial strategies that incorporate the concept of compound growth, aiming to help families enhance their investments and secure a brighter financial future.
What is the significance of minimal fund fees in investment returns?
Minimal fund fees are prioritized by Bright Advisers to ensure that families can maximize their investment returns, allowing more of their money to benefit from compound growth.
How can families enhance their financial stability using compound interest?
By embracing the benefits of compound returns, families can effectively improve their financial stability and growth potential, leading to a more secure future for their loved ones.
List of Sources
- Understanding Compound Interest: Basics and Mechanisms
- The Power of Compound Interest | Carson Wealth (https://carsonwealth.com/insights/blog/compounding-wealth-and-wisdom)
- The Power of Compound Interest: Calculations and Examples (https://investopedia.com/terms/c/compoundinterest.asp)
- Investing early and often: the magic of compound interest (https://rathbones.com/individuals-and-families/know-where-life-can-take-you/bespoke-portfolio-management/investing-early-and-often-the-magic-of-compound-interest)
- What is the Best Compound Interest Account for 2025? [5.25% Tax-Free vs 4.66% Taxable] – I&E | Whole Life & Infinite Banking Strategies (https://insuranceandestates.com/compound-interest-growth)
- College Saving Statistics [2025]: Average Savings & 529 Balance (https://educationdata.org/college-savings-statistics)
- Daily vs. Monthly Compounding: Key Differences Explained
- Which Accounts Earn Compound Interest? | The Motley Fool (https://fool.com/investing/how-to-invest/stocks/compound-interest-accounts)
- Interest Compounded Daily vs. Monthly: Which Is Actually Better? (https://finance.yahoo.com/news/interest-compounded-daily-vs-monthly-130053355.html)
- Interest Compounded Daily vs. Monthly – SmartAsset (https://smartasset.com/checking-account/interest-compounded-daily-vs-monthly)
- Evaluating the Benefits and Drawbacks of Daily and Monthly Compounding
- 100 Famous Investing Quotes [2025] (https://digitaldefynd.com/IQ/investing-quotes)
- Interest Compounded Daily vs. Monthly: Which Is Actually Better? (https://finance.yahoo.com/news/interest-compounded-daily-vs-monthly-130053355.html)
- 150 Quotes on Saving, Investing, and Financial Wellness (https://deliberatedirections.com/quotes-financial-wellness)
- Choosing the Right Compounding Method for Your Financial Goals
- Top 50 Financial Planning Quotes [2025] (https://digitaldefynd.com/IQ/financial-planning-quotes)
- No Surprises: Managing Risk in Family Portfolios – Cambridge Associates (https://cambridgeassociates.com/insight/no-surprises-managing-risk-in-family-portfolios)
- 14 Quotes From Our Favorite Money Saving Experts (https://chime.com/blog/quotes-from-money-saving-experts)
- Effects of Marriage and Children on Financial Risk Tolerance: A Synthesis of Family Development and Prospect Theory | Request PDF (https://researchgate.net/publication/226656757_Effects_of_Marriage_and_Children_on_Financial_Risk_Tolerance_A_Synthesis_of_Family_Development_and_Prospect_Theory)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Investment & Risk Management for high-income W-2 families at Bright Advisers.
Keep reading