

Key Highlights:
- Age significantly impacts 401(k) investment strategies, necessitating adjustments based on life stages.
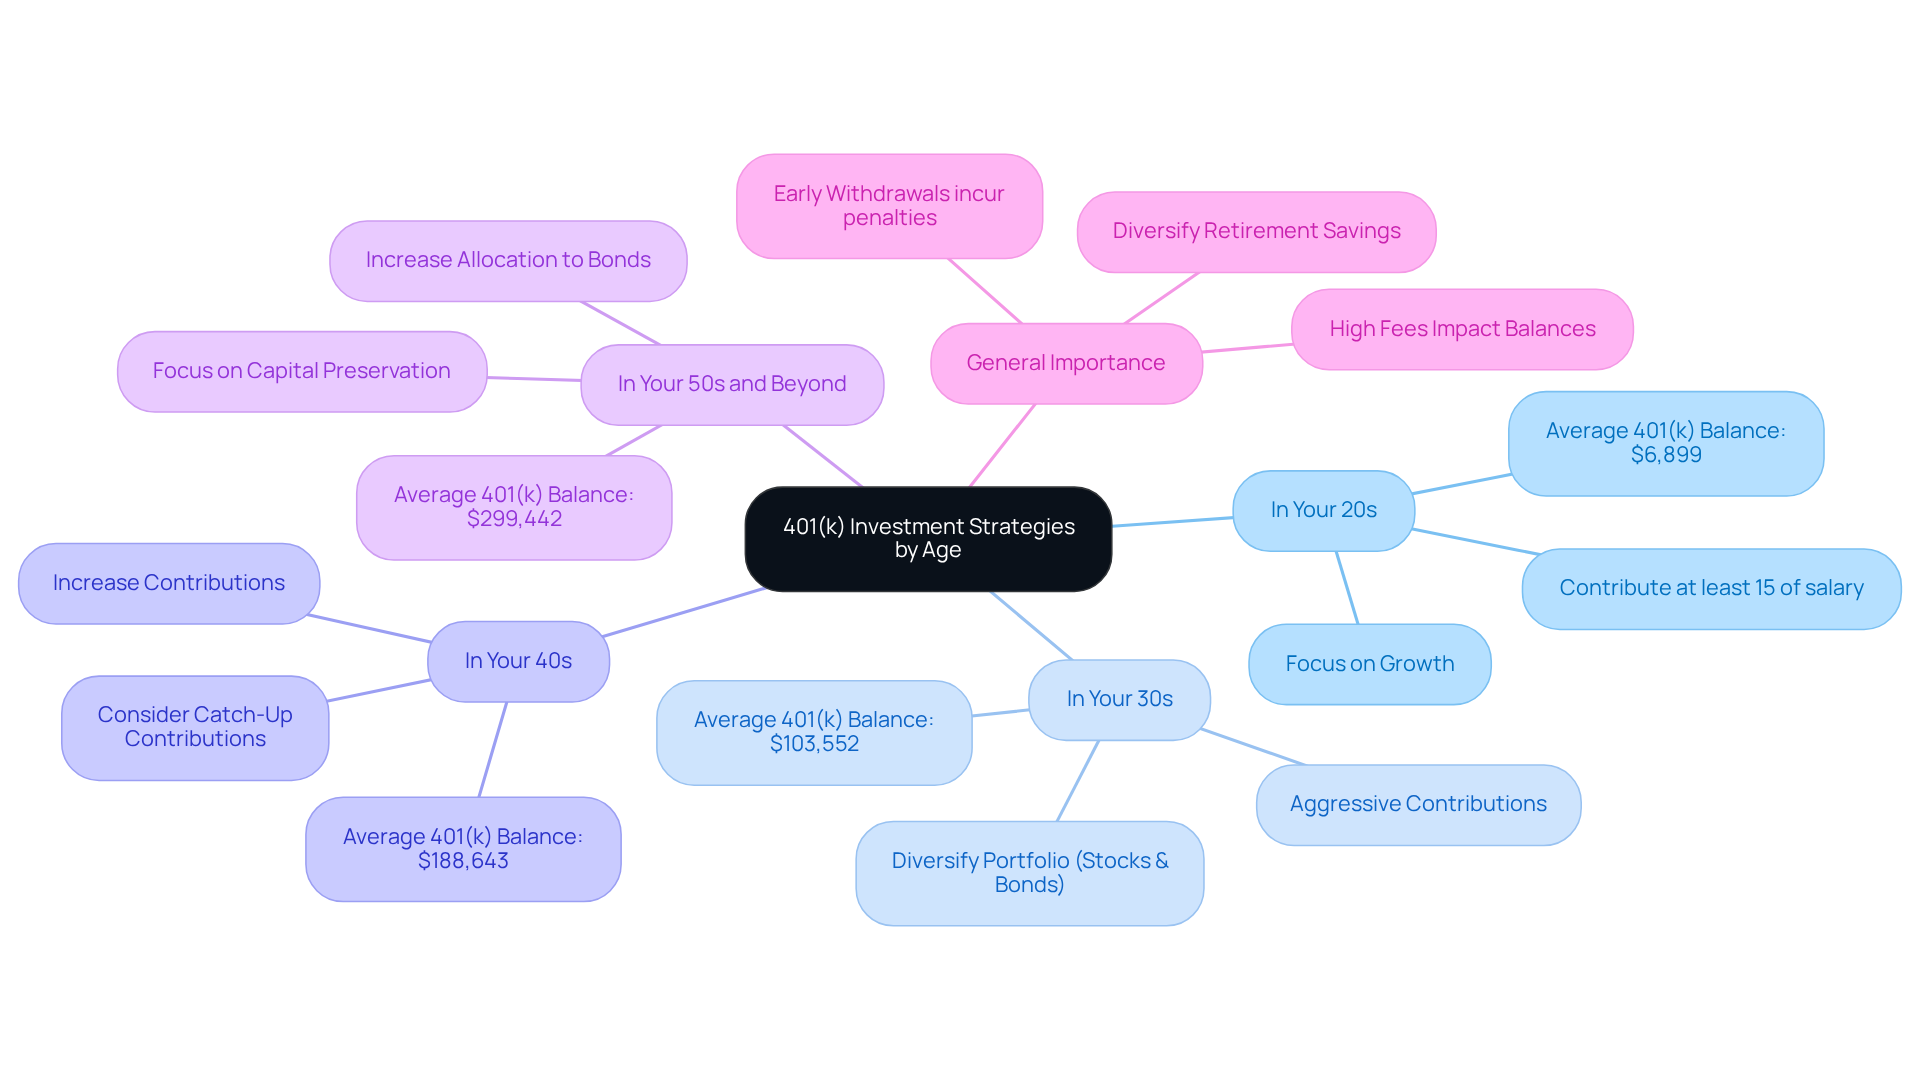
- In your 20s, prioritise growth by investing 80-90% in stocks; aim to contribute at least 15% of your salary.
- In your 30s, continue aggressive contributions while diversifying with a mix of 70% stocks and 30% bonds.
- In your 40s, increase contributions and consider catch-up contributions; a balanced approach should include 60% stocks and 40% bonds.
- In your 50s and beyond, focus on capital preservation with a shift towards 40% stocks and 60% bonds for income generation.
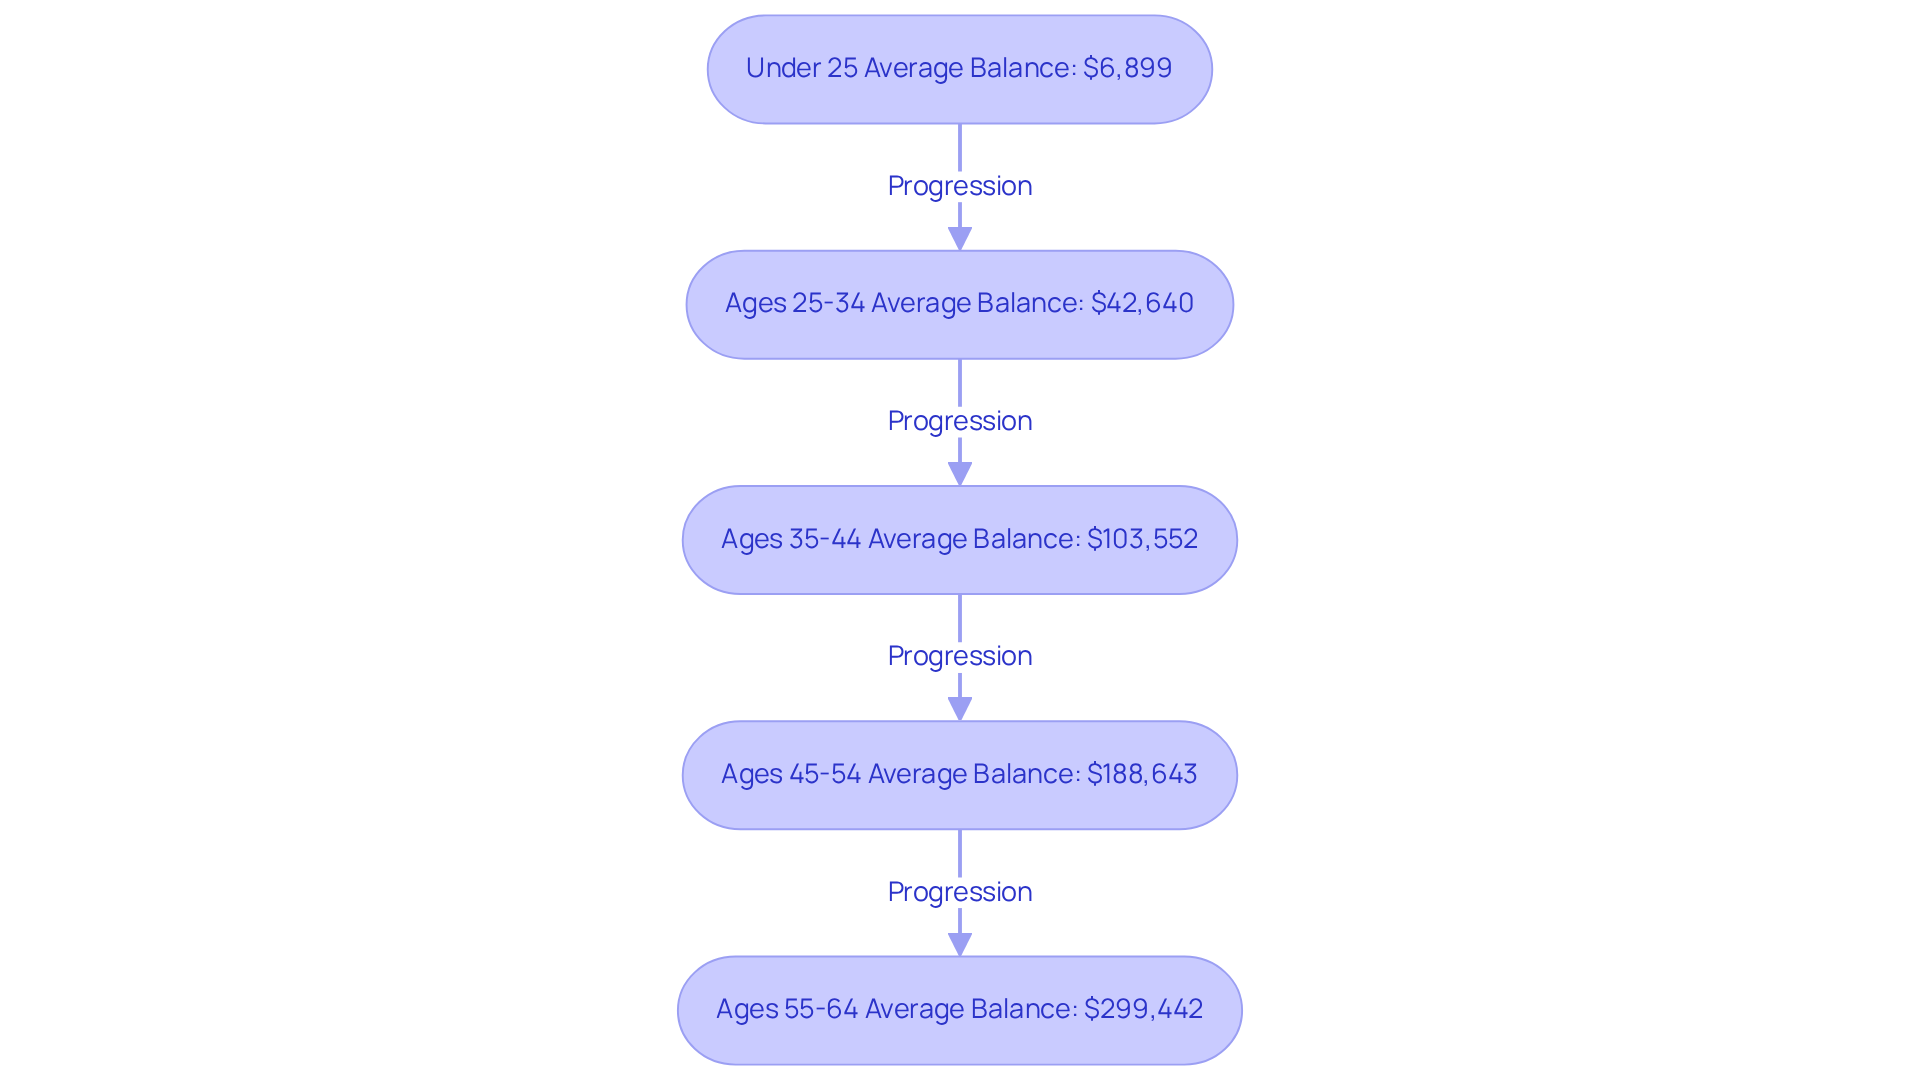
- Average 401(k) balances increase with age: $6,899 (under 25), $42,640 (25-34), $103,552 (35-44), $188,643 (45-54), and $299,442 (55-64).
- Employers often match contributions, enhancing savings potential; the average balance in Fidelity 401(k) plans reached $137,800 as of June 2025.
- Regularly review and adjust your investment strategy to align with evolving financial goals and utilise catch-up contributions if over 50.
Introduction
Understanding the nuances of 401(k) investment strategies can truly change the game for young parents who are striving to secure their family’s financial future. As life unfolds, your age plays a significant role in shaping your investment approach, risk tolerance, and financial goals. This article gently explores essential strategies tailored by age, offering insights that empower you to make informed decisions.
Imagine if you could navigate your 401(k) plan with confidence, ensuring a stable and prosperous retirement for your family, despite the unique challenges you face. It’s important to understand that you’re not alone in this journey. Many young families share similar concerns, and together, we can find the best path forward.
By focusing on age-specific strategies, we can help you align your financial planning with your family’s values and priorities. As you read on, you’ll discover practical tips and heartfelt stories that resonate with your experiences, making the journey feel less daunting. Remember, we’re here for you, ready to support you every step of the way.
Understand the Importance of Age in 401(k) Strategies
Age plays a crucial role in determining your 401k investment strategy by age, especially for young parents like Jay and Emma, who are eager to alleviate monetary stress while preparing for their family’s future. As you move through different life phases, your financial objectives, risk appetite, and investment time frame evolve. Understanding this evolution is essential for effective resource allocation. Here’s how age impacts your 401(k):
- In Your 20s: Focus on growth. You have time on your side, allowing you to take on more risk with equities. To maximize growth potential, aim to contribute at least 15% of your salary in line with your 401k investment strategy by age. The average 401(k) balance for individuals under 25 is only $6,899, highlighting the importance of starting early.
- In Your 30s: Continue aggressive contributions but start diversifying your portfolio. Think about mixing stocks and bonds to reduce risk as your responsibilities increase. This 401k investment strategy by age is crucial, especially considering that the average 401(k) balance for those aged 35-44 is $103,552, indicating the need for a solid foundation.
- In Your 40s: This is often a peak earning period. Increase your contributions and consider catch-up contributions if you’re behind on savings. For those aged 50 and older, the catch-up contribution limit is $7,500 for 2024. Your funding approach should transition towards safeguarding capital while still enabling growth, as it relates to the 401k investment strategy by age, with the being $188,643.
- In Your 50s and Beyond: Focus on capital preservation and income generation. As retirement nears, slowly decrease your exposure to high-risk assets and boost your allocation to bonds and other fixed-income securities. The average 401(k) balance for individuals aged 65 and older is $299,442, emphasizing the need for strategic planning in these years.
By understanding the 401k investment strategy by age, you can make informed choices that align with your family’s monetary future. Bright Advisers is dedicated to offering tailored financial planning and asset management strategies that empower young families to tackle these challenges efficiently. Remember, high fees can greatly diminish your 401(k) balance over time, so it’s crucial to select low-cost financial options. Integrating these strategies will assist in securing a stable and prosperous future after work. Together, we can navigate this journey.
Review Average 401(k) Balances by Age Group
Creating a solid 401(k) savings strategy is crucial, especially for young parents. Understanding the 401k investment strategy by age can help you navigate this journey with confidence. Here’s a closer look:
- Under 25: The average balance is around $6,899. At this stage, it’s all about starting to save and investing early. The sooner you begin, the more you can benefit from compounding growth.
- Ages 25-34: Here, the average balance rises to about $42,640. As your income grows, focus on increasing your contributions—aim for at least 12% of your salary, including any employer matches. Remember, the regular 401(k) contribution limit for 2025 is $23,500, giving you a clear target for your annual savings.
- Ages 35-44: The average balance reaches around $103,552. By now, it’s essential to have a strong 401k investment strategy by age in place. Aim to save three times your yearly income to prepare for the future. Bright Advisers is here to help families like Emily and Mark create tailored plans that empower them to make informed financial decisions.
- Ages 45-54: The average balance jumps to $188,643. This is a critical time to optimize your contributions. If you’re 50 or older, consider catch-up contributions, allowing you to add an extra $7,500 in 2025 to boost your savings.
- Ages 55-64: The average balance climbs to $299,442. Focus on aligning your portfolio with your future financial goals and maximizing those catch-up contributions.
These averages serve as benchmarks, encouraging young parents to and make necessary adjustments for a secure future. It’s also important to note that many employers offer a 50% match on the first 6% of your salary contributed to a 401(k). This can significantly enhance your savings over time. As of June 2025, the average account balance in Fidelity 401(k) plans reached $137,800, reflecting positive trends in retirement savings.
Engaging with resources like those provided by Bright Advisers can empower you to make informed choices about your financial future. Together, we can navigate this journey toward monetary freedom and security.
Create a Tailored 401(k) Investment Strategy by Age
Creating a personalized 401k investment strategy by age that truly reflects your family’s financial goals can feel overwhelming, but it doesn’t have to be. Let’s explore some thoughtful steps based on your age that can help you navigate this journey with confidence:
-
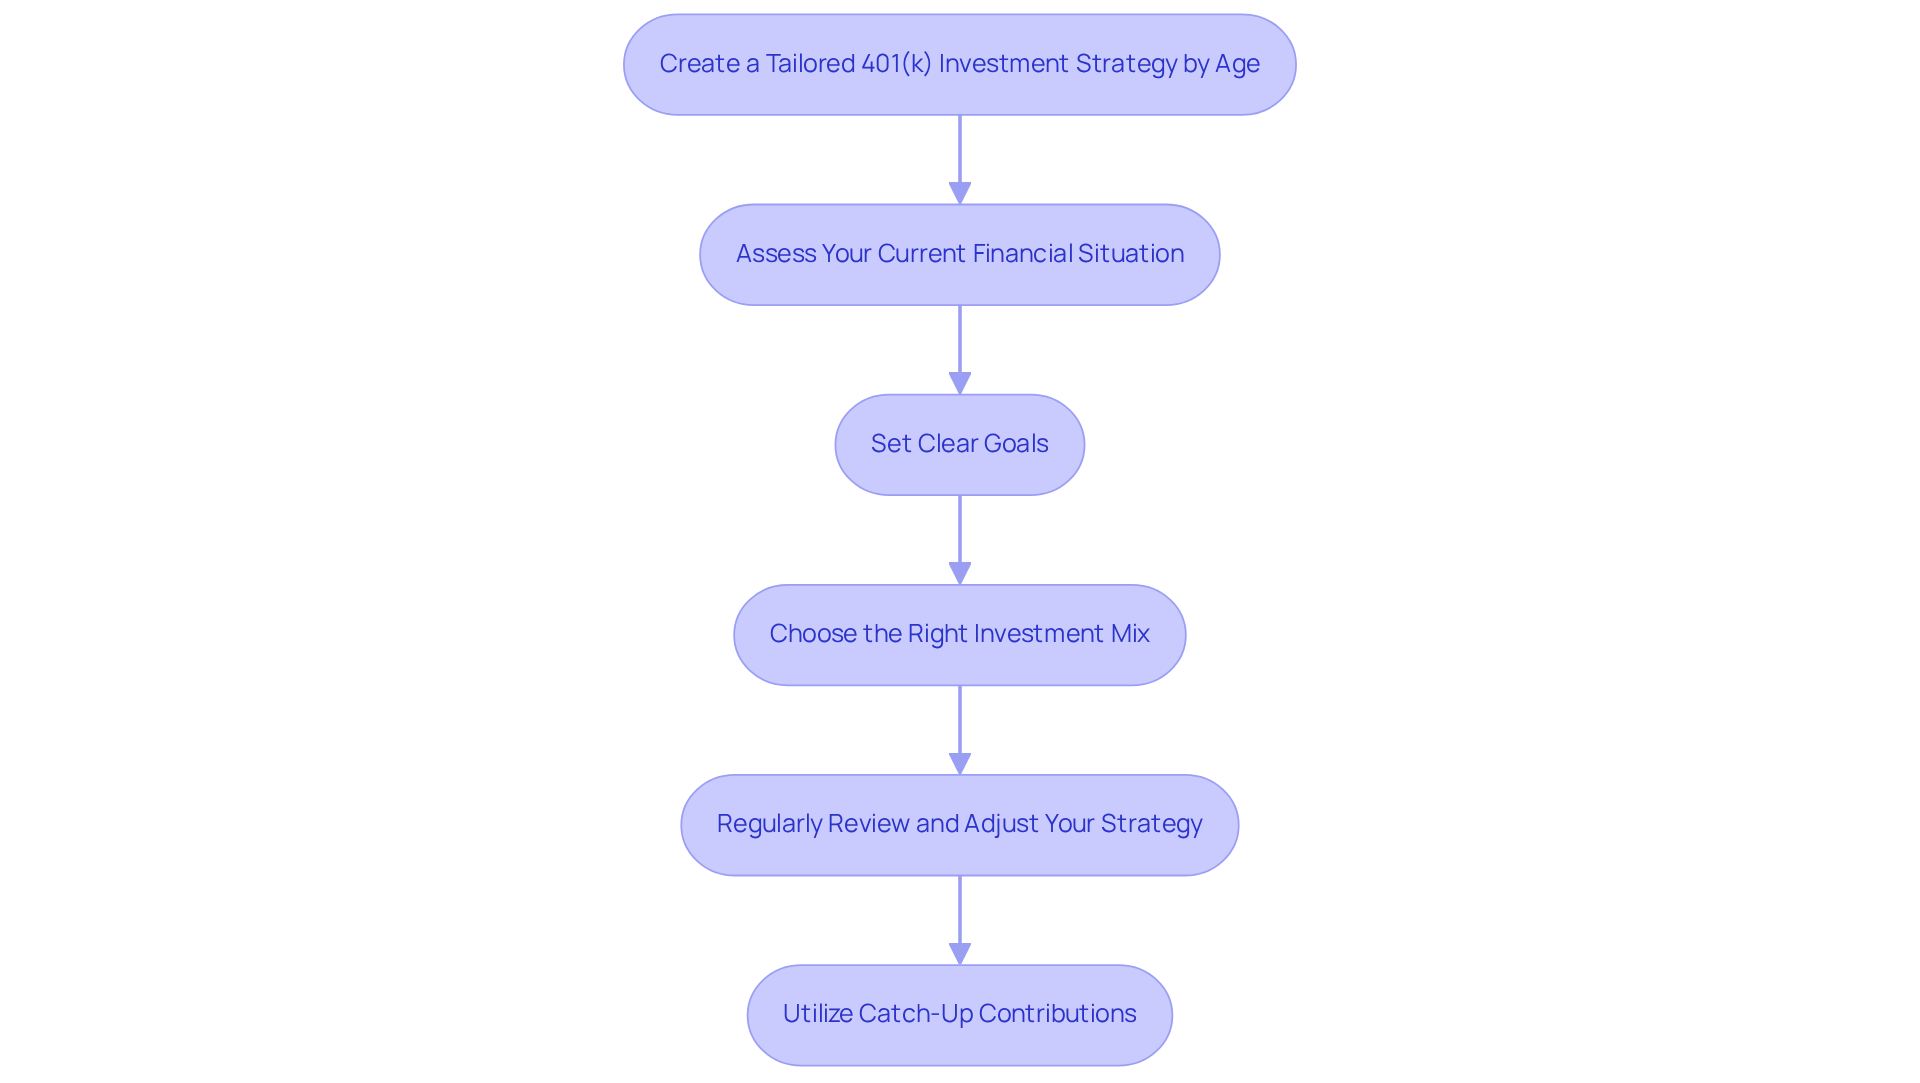
Assess Your Current Financial Situation: Start by taking a close look at your income, expenses, and existing savings. This honest assessment will give you a clearer picture of how much you can realistically contribute to your 401(k).
-
Set Clear Goals: What do you envision for your family’s future? Think about when you’d like to retire, the lifestyle you aspire to, and any educational expenses for your children. By defining these objectives, you can make informed financial choices that align with your family’s needs.
-
Choose the Right Investment Mix:
- In Your 20s: Embrace growth by allocating 80-90% of your portfolio to stocks. This strategy allows you to harness the power of compounding returns over time.
- In Your 30s: Shift to a balanced approach with 70% in stocks and 30% in bonds, as you start to prioritize stability alongside growth.
- In Your 40s: Consider a more conservative mix, aiming for 60% stocks and 40% bonds. This helps safeguard your savings while still allowing for some growth potential.
- In Your 50s and Beyond: Focus on income-producing assets, targeting a 40% stock and 60% bond allocation to prepare for your retirement income needs.
-
Regularly Review and Adjust Your Strategy: Life is full of changes—new jobs, growing families, and shifting financial goals. It’s essential to revisit your investment strategy regularly. Adjust your contributions and asset distribution to stay aligned with your evolving goals, ensuring your plan remains effective and tailored to your family’s needs.
-
Utilize Catch-Up Contributions: If you’re over 50, don’t forget about . This option allows you to significantly boost your savings, helping to secure a brighter financial future for you and your loved ones.
By following these steps, you can create a robust 401k investment strategy by age that adapts to your family’s changing needs and financial aspirations. Together, we can enhance your retirement readiness and empower your financial security.
Conclusion
Understanding the nuances of a 401(k) investment strategy as you navigate parenthood is crucial for securing your family’s financial future. This guide sheds light on how age plays a pivotal role in shaping your investment choices, highlighting the need to adapt your strategies as your life evolves. By starting early, increasing contributions, and diversifying your investments, you can confidently steer your financial journey toward a stable retirement.
Imagine being in your 20s, where aggressive growth is essential. As you move into your 30s, diversification becomes key, and by your 50s and beyond, focusing on capital preservation is critical. Regularly assessing and adjusting your investment strategy ensures it aligns with your personal goals and the changing dynamics of your family. The statistics on average 401(k) balances serve as motivating benchmarks, encouraging you to take actionable steps toward enhancing your retirement savings.
Ultimately, your journey to financial security begins with informed decisions and proactive planning. We encourage you to leverage the insights shared in this guide to create a personalized 401(k) investment strategy that meets your immediate needs while paving the way for a prosperous future. Engaging with financial advisors and utilizing available resources can empower your family to make sound financial choices, reinforcing the importance of strategic planning in achieving long-term monetary freedom. Together, we can navigate this journey.
Frequently Asked Questions
How does age influence 401(k) investment strategies?
Age plays a crucial role in shaping your 401(k) investment strategy as your financial objectives, risk appetite, and investment time frame evolve through different life phases. Understanding these changes is essential for effective resource allocation.
What should individuals in their 20s focus on regarding their 401(k)?
Individuals in their 20s should focus on growth by taking on more risk with equities. It is recommended to contribute at least 15% of their salary to maximize growth potential, as starting early is important.
What investment strategies are advisable for those in their 30s?
In their 30s, individuals should continue making aggressive contributions while starting to diversify their portfolios by mixing stocks and bonds to reduce risk as their responsibilities increase.
What financial strategies should individuals in their 40s consider?
Individuals in their 40s, often in a peak earning period, should increase their contributions and consider catch-up contributions if they are behind on savings. Their funding approach should begin transitioning towards safeguarding capital while still allowing for growth.
What is the focus for those in their 50s and beyond regarding their 401(k)?
Those in their 50s and beyond should focus on capital preservation and income generation. As retirement approaches, they should gradually decrease exposure to high-risk assets and increase allocations to bonds and other fixed-income securities.
Why is it important to understand the 401(k) investment strategy by age?
Understanding the 401(k) investment strategy by age helps individuals make informed choices that align with their family’s monetary future and ensures they are prepared for retirement.
How can high fees impact a 401(k) balance?
High fees can significantly diminish a 401(k) balance over time, making it crucial to select low-cost financial options to maximize savings and investment growth.
List of Sources
- Understand the Importance of Age in 401(k) Strategies
- The average 401(k) balance by age (https://empower.com/the-currency/life/average-401k-balance-age)
- Average 401k balance by Age – Quiver Financial (https://quiverfinancial.com/blog/average-401k-balance-by-age-boost-savings)
- Average retirement savings by age | Fidelity (https://fidelity.com/learning-center/personal-finance/average-retirement-savings)
- The Average 401(k) Balance by Age (https://tha.org/blog/the-average-401k-balance-by-age)
- Average 401(k) Balance by Age in 2025 – NerdWallet (https://nerdwallet.com/article/investing/the-average-401k-balance-by-age)
- Review Average 401(k) Balances by Age Group
- The average 401(k) balance by age (https://empower.com/the-currency/life/average-401k-balance-age)
- The Average 401(k) Balance by Age and Generation (https://kiplinger.com/retirement/401ks/the-average-401k-balance-by-age)
- Average 401(k) Balance by Age in 2025 – NerdWallet (https://nerdwallet.com/article/investing/the-average-401k-balance-by-age)
- Create a Tailored 401(k) Investment Strategy by Age
- How Much Should I Save for Retirement (https://tha.org/blog/how-much-should-i-save-for-retirement)
- Retirement savings goals 2025: 20-somethings have double the recommended balance (https://empower.com/the-currency/money/retirement-savings-goals-benchmarks-news)
- Average Retirement Savings by Age | Guardian (https://guardianlife.com/retirement/savings-by-age)
- Average retirement savings by age (https://edwardjones.com/us-en/market-news-insights/investor-education/investment-age/average-retirement-savings-age)
- How much do I need to retire? | Fidelity (https://fidelity.com/viewpoints/retirement/how-much-do-i-need-to-retire)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Retirement & Employee Benefits for high-income W-2 families at Bright Advisers.
Keep reading