

Key Highlights:
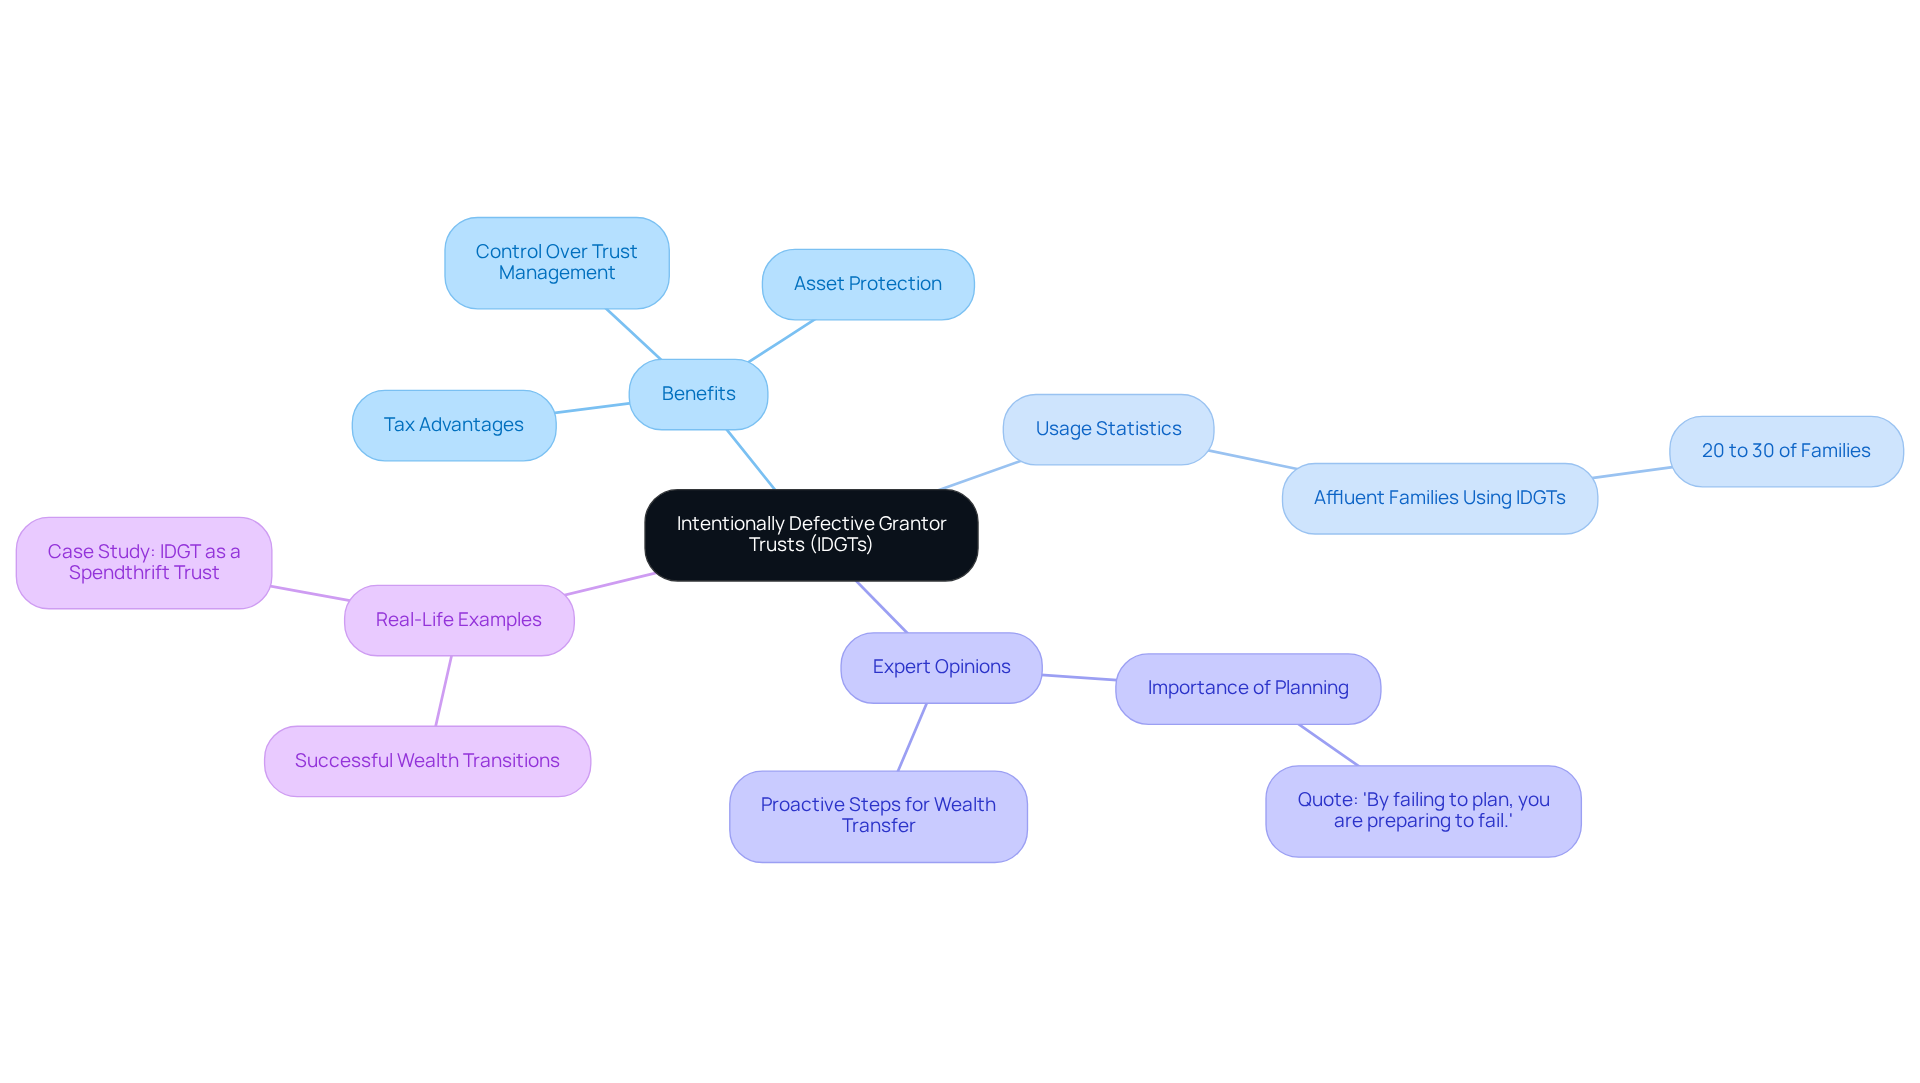
- Intentionally defective grantor trusts (IDGTs) are irrevocable trusts that help remove assets from the grantor’s holdings for inheritance tax purposes while allowing the grantor to retain certain powers.
- Around 20% to 30% of affluent families utilise IDGTs for effective wealth transfer and inheritance tax reduction.
- IDGTs protect assets from creditors and mismanagement, offering significant advantages for families with young children.
- The grantor is responsible for income taxes on the trust’s earnings, allowing the trust to grow without tax liabilities, benefiting long-term wealth accumulation.
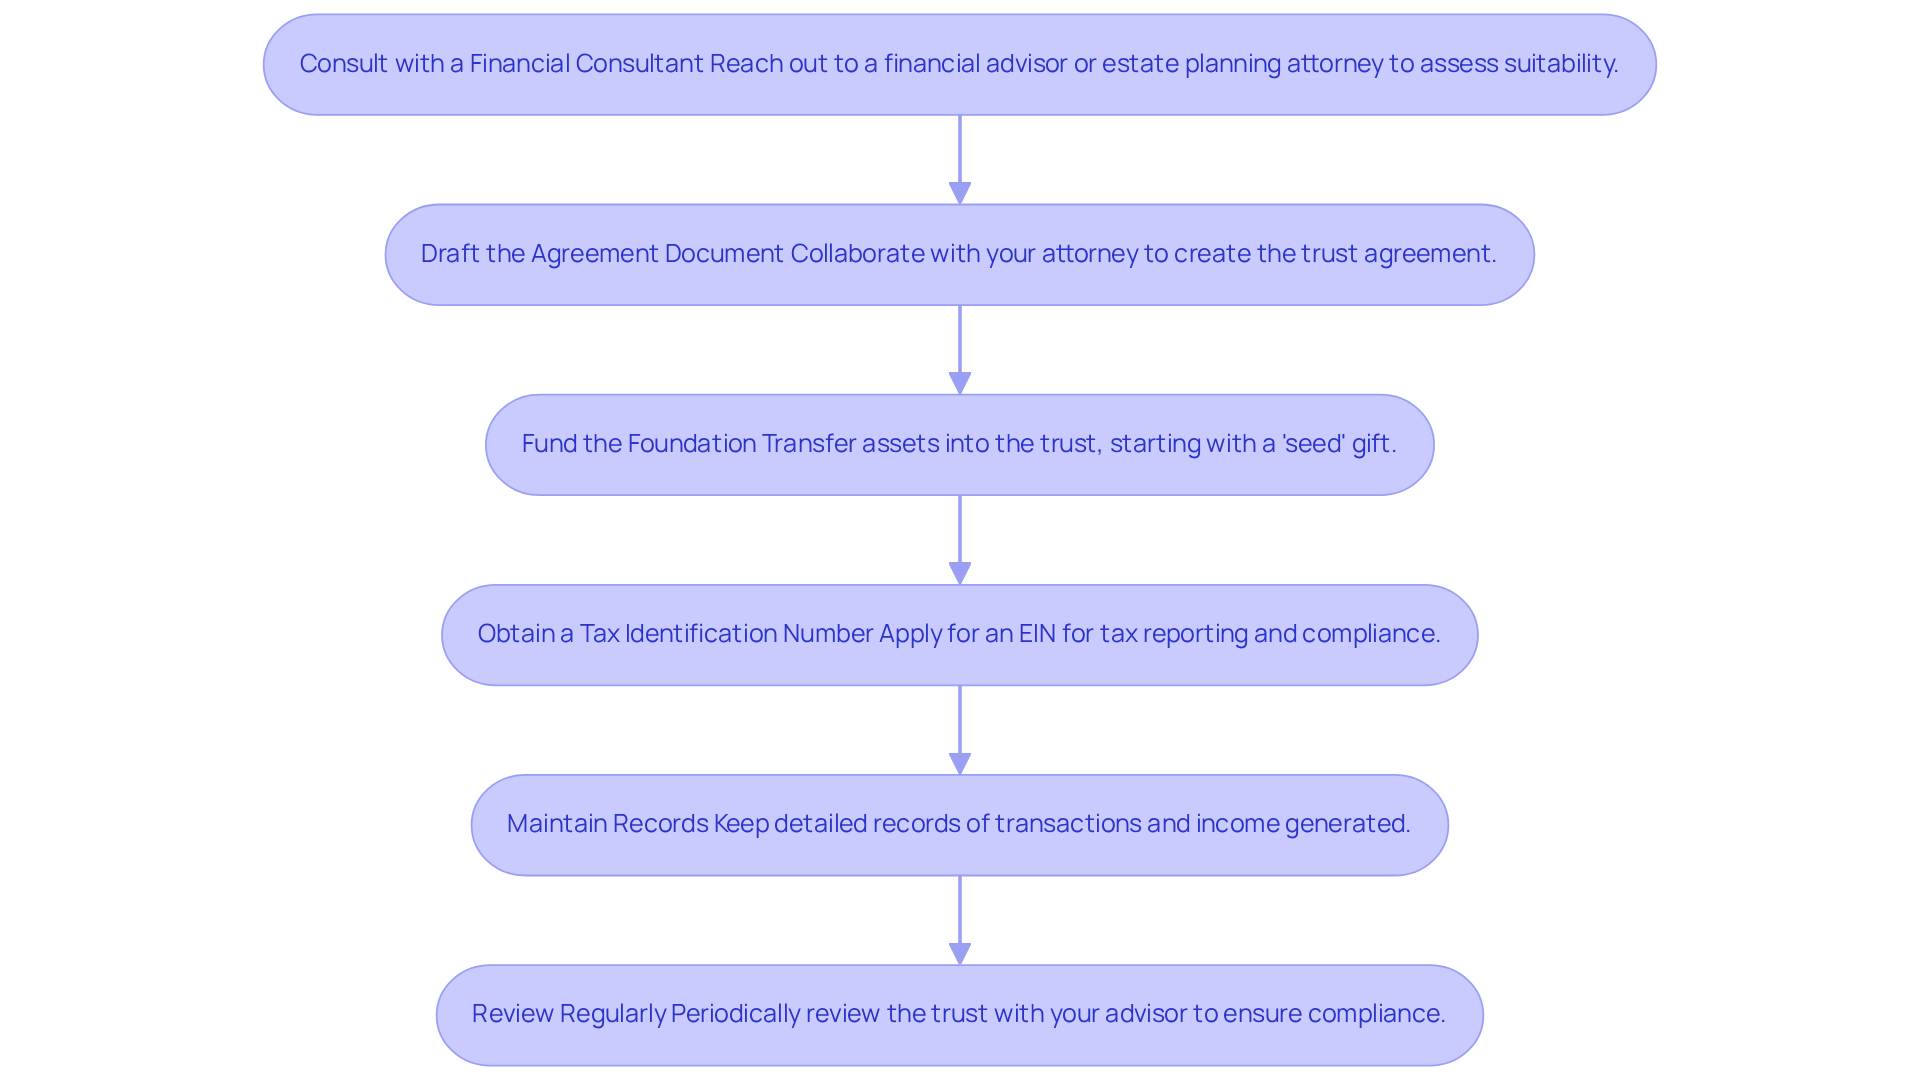
- Establishing an IDGT involves consulting with a financial advisor, drafting an agreement, funding the trust, obtaining a tax ID number, maintaining records, and regular reviews.
- Key factors in creating an IDGT include understanding its irrevocability, funding approaches, tax responsibilities, beneficiary designations, legal compliance, and the importance of routine evaluations.
- Families should avoid common pitfalls such as neglecting legal compliance and failing to communicate with beneficiaries to ensure the trust meets its intended purpose.
Introduction
Creating a secure financial future for your family can feel overwhelming, can’t it? The complexities of wealth transfer and tax implications often add to the stress. But here’s some good news: an intentionally defective grantor trust (IDGT) can be a strategic solution. It offers families a way to manage and protect their assets while minimizing inheritance taxes.
Now, you might be wondering about the term “defective”—what does that really mean for your financial planning? Let’s explore the mechanics and benefits of IDGTs together. They not only have the potential to safeguard your wealth but also come with critical considerations and common pitfalls that we need to navigate.
Imagine if you could secure your family’s future with confidence, knowing that your assets are protected and your loved ones are taken care of. We’re here for you, ready to help you understand how IDGTs can fit into your financial strategy. Together, we can navigate this journey and ensure that your family’s values and priorities are at the forefront of your planning.
Understand the Basics of Intentionally Defective Grantor Trusts
Secure Your Family’s Future with Intentionally Defective Grantor Vehicles (IDGTs)
As a parent, you want to ensure that your children are well taken care of, even after you’re gone. An intentionally defective grantor trust sample can be a powerful tool in your financial planning arsenal. This specialized irrevocable arrangement, known as an intentionally defective grantor trust sample, helps you strategically remove assets from your holdings for inheritance tax purposes, all while allowing you to maintain certain powers over the vehicle. It’s designed to give you peace of mind, knowing that your family’s future is secure.
The term ‘defective’ might sound concerning, but it actually means that you remain responsible for paying income taxes on the entity’s income. This can be beneficial for your financial strategy, allowing you to pass on wealth to your beneficiaries while effectively reducing inheritance taxes. Did you know that around 20% to 30% of affluent families use IDGTs? They recognize the value in this approach to wealth transfer.
For families with young children, IDGTs offer significant advantages. Imagine being able to secure financial assets for your kids while still having control over how the trust is managed. This structure not only aids in inheritance tax planning but also protects your assets from potential creditors and mismanagement by beneficiaries. It’s a way to safeguard your family’s future.
Experts in estate planning emphasize the significance of the intentionally defective grantor trust sample in wealth transfer strategies. One expert wisely noted, “By failing to plan, you are preparing to fail.” This underscores the necessity of taking proactive steps to secure your family’s economic legacy. Real-life stories show how high-net-worth families have successfully used IDGTs to ensure smooth wealth transitions, preparing their children for future financial responsibilities.
In summary, understanding the mechanics and benefits of IDGTs is crucial for families like yours. Together, we can navigate this journey to build a strong financial foundation and ensure a seamless transfer of wealth to the next generation. Remember, we’re here for you, ready to support you every step of the way.
Explore Tax Implications of IDGTs
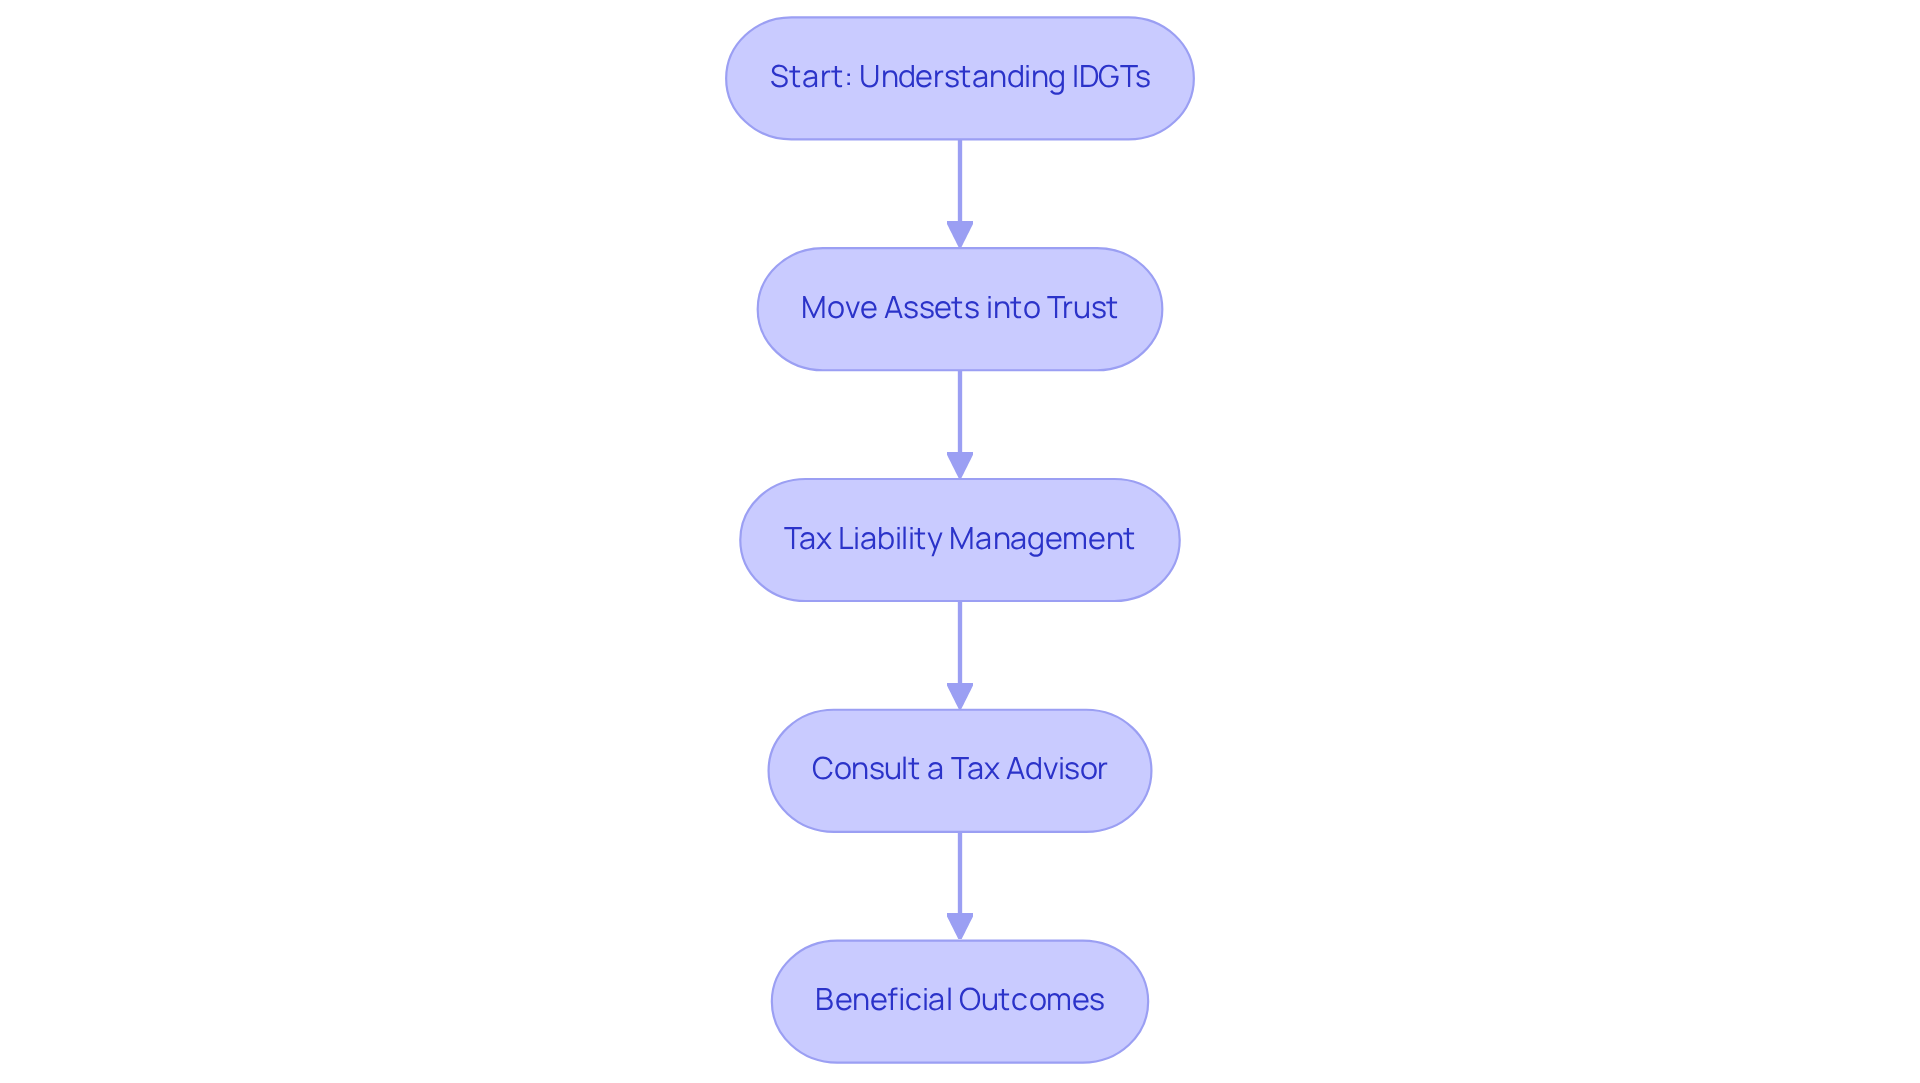
The tax implications of an intentionally defective grantor trust sample are significant and multifaceted, especially for families like yours. When assets are moved into the trust, they’re excluded from the grantor’s holdings for inheritance tax purposes. This effectively decreases the overall taxable holdings, which can be a real blessing for families with appreciating assets. Imagine the peace of mind knowing that an intentionally defective grantor trust sample of $10 million, growing at an average rate of 5% annually, could potentially exceed $43 million over 30 years—all while remaining outside your estate.
What’s even more reassuring is that the grantor keeps the obligation for paying income taxes on the fund’s earnings. This means the fund can grow without the tax liability that usually comes with being a separate taxable entity. By covering these tax liabilities, you can reduce your taxable estate while allowing the trust to accumulate wealth tax-free. It’s a smart way to secure your family’s future.
Consider the story of Allison and Brian. They turned to Bright Advisers to help maximize their financial potential through thoughtful tax planning. As high-income professionals, they were initially unaware of the opportunities slipping through their fingers due to inadequate tax strategies. With guidance from Bright Advisers, they optimized their tax situation, secured their children’s education funding, and even gained the ability to retire sooner. Their journey underscores the importance of strategic tax planning in enhancing long-term economic stability for families.
Given the complexities involved, it’s crucial to consult with a tax advisor who can help you understand how these implications relate to your unique financial situation. This strategic approach not only aids in tax reduction but also fosters long-term economic stability for families. Remember, an intentionally defective grantor trust sample can serve as a valuable tool in your wealth management journey. Together, we can navigate this path to a brighter financial future.
Establish Your Intentionally Defective Grantor Trust: A Step-by-Step Process
Establishing your intentionally defective grantor trust sample can feel overwhelming, but we’re here to guide you through each step with care and understanding. Let’s explore how you can secure your family’s financial future together.
-
Consult with a Financial Consultant: Start by reaching out to a financial advisor or estate planning attorney. They can help you determine if an intentionally defective grantor trust sample is suitable for your financial goals and estate planning strategy. At Bright Advisers, we believe it’s crucial to understand your ongoing liquidity needs as part of a comprehensive financial plan tailored just for you.
-
Draft the Agreement Document: Collaborate with your attorney to create an agreement that outlines the terms of the IDGT. This document will detail the powers you retain as the grantor and the rights of the beneficiaries, ensuring everyone is on the same page.
-
Fund the Foundation: Next, transfer assets into the trust. You can do this through outright gifts or by selling assets to the trust in exchange for a promissory note. Remember, starting with a ‘seed’ gift of at least 10% of the asset’s value is a common practice that helps establish credibility.
-
Obtain a Tax Identification Number: Don’t forget to apply for an Employer Identification Number (EIN) for the trust. This is essential for tax reporting and compliance, keeping everything above board.
-
Maintain Records: Keeping detailed records of all transactions related to the trust is vital. This includes tracking income generated and any fees you pay as the grantor. Good documentation is key for tax compliance and future planning, as you’ll be responsible for paying income taxes on any revenue produced by the trust’s assets.
-
Review Regularly: Finally, make it a habit to periodically review the trust with your advisor. This ensures it continues to meet your evolving financial and estate planning needs, especially as tax laws and personal circumstances change.
Creating an intentionally defective grantor trust sample can significantly enhance your family’s wealth management strategy. It allows for efficient asset transfer while minimizing inheritance tax responsibilities. For families focused on preserving wealth, IDGTs offer a way to transfer substantial assets without tapping into lifetime gift tax exemptions. At Bright Advisers, we’re dedicated to providing personalized financial planning, including tax strategies and estate planning, to help you achieve your family’s economic goals. Together, we can navigate this journey with confidence.
Consider Key Factors and Avoid Common Pitfalls in IDGT Creation
Creating an intentionally defective grantor trust sample can feel overwhelming, but it’s a powerful step toward securing your family’s financial future. Let’s explore some key factors to consider, ensuring you feel confident and informed every step of the way.
-
Irrevocability: Once you establish an IDGT, it’s irrevocable. This means the terms are set in stone, and you can’t reclaim the assets. It’s crucial to be fully committed to this decision, understanding that using an intentionally defective grantor trust sample represents a long-term commitment to your family’s well-being.
-
Funding Approaches: Think about how you want to finance this arrangement. Will you use donations or sales? Each method comes with its own tax implications and advantages. For instance, Allison and Brian chose a mix of gifts and sales, which helped them enhance their tax situation and maximize their financial potential.
-
Tax Responsibilities: As the grantor, you’ll be responsible for income taxes on the fund’s earnings. This can impact your overall cash flow, so understanding this responsibility is vital for effective financial planning. Allison and Brian discovered that managing these responsibilities could lead to greater wealth accumulation for their family.
-
Beneficiary Designations: Clearly outlining your beneficiaries and how assets will be distributed is essential. This clarity helps prevent disputes down the line, fostering family harmony. By defining their beneficiaries, Allison and Brian ensured their children’s future was secure, especially when it came to funding their education.
-
Legal Compliance: It’s important to ensure that your IDGT complies with all applicable laws and regulations. Non-compliance can lead to significant complications. For example, the IRS ruling on the intentionally defective grantor trust sample. Rul is an example of an intentionally defective grantor trust sample. 2023-2 confirms that a basis step-up doesn’t apply to assets gifted to an intentionally defective grantor trust sample. Understanding these tax effects is crucial. Allison and Brian’s proactive approach to compliance helped them avoid common pitfalls.
-
Routine Evaluations: Regularly evaluating the fund’s performance and your financial situation is key. This proactive approach ensures that your trust remains relevant and effective as your goals change. Through consistent evaluations, Allison and Brian were able to adjust their strategies, allowing them to retire sooner and enjoy more quality time with their loved ones.
Avoiding common pitfalls—like neglecting legal compliance or failing to communicate with beneficiaries—can significantly enhance the likelihood that your intentionally defective grantor trust sample will achieve its intended purpose. Real-life examples show that families who engage in thorough planning and regular reviews often sidestep legal challenges. Studies indicate that nearly 30% of IDGTs face legal issues due to non-compliance. As Benjamin Franklin wisely stated, “By failing to prepare, you are preparing to fail.”
By prioritizing these considerations, you can create a robust IDGT that secures your family’s financial future. Remember, we’re here for you, ready to support you on this journey.

Conclusion
Creating an intentionally defective grantor trust (IDGT) is a thoughtful step toward securing your family’s financial future. This specialized trust not only helps reduce inheritance taxes but also allows you to keep certain controls, ensuring that your wealth is passed down effectively to the next generation. By understanding the nuances of IDGTs, you can make informed choices that protect your family’s financial legacy.
Let’s explore the essential aspects of IDGTs together. We’ll highlight:
- Their benefits
- Tax implications
- The key steps to set one up
It’s crucial to consult with financial experts, maintain thorough documentation, and be aware of potential pitfalls. For instance, consider the story of Allison and Brian, who strategically planned their finances to enhance their wealth management and ensure long-term stability for their family.
Establishing an IDGT isn’t just a financial strategy; it’s a proactive measure to ensure your family’s security and harmony. By prioritizing careful planning and regular evaluations, you can navigate the complexities of wealth transfer with confidence. Embracing this approach not only safeguards your assets but also nurtures a legacy of financial responsibility for generations to come.
Remember, you’re not alone in this journey. Together, we can navigate these important decisions, ensuring that your family’s values and goals are at the forefront of your financial planning.
Frequently Asked Questions
What is an intentionally defective grantor trust (IDGT)?
An IDGT is a specialized irrevocable trust that helps parents strategically remove assets from their holdings for inheritance tax purposes while allowing them to maintain certain powers over the trust.
How does an IDGT benefit families?
IDGTs provide peace of mind by securing financial assets for children, aiding in inheritance tax planning, protecting assets from creditors, and preventing mismanagement by beneficiaries.
What does the term ‘defective’ mean in the context of IDGTs?
In this context, ‘defective’ means that the grantor remains responsible for paying income taxes on the trust’s income, which can be beneficial for wealth transfer strategies.
How common are IDGTs among affluent families?
Approximately 20% to 30% of affluent families utilize IDGTs as a strategy for wealth transfer.
Why is planning with IDGTs emphasized by estate planning experts?
Experts stress the importance of IDGTs in wealth transfer strategies, as failing to plan can jeopardize a family’s economic legacy.
Can you provide an example of how IDGTs have been used successfully?
High-net-worth families have successfully utilized IDGTs to ensure smooth transitions of wealth, preparing their children for future financial responsibilities.
What should families understand about IDGTs?
Families should understand the mechanics and benefits of IDGTs to build a strong financial foundation and ensure a seamless transfer of wealth to the next generation.
List of Sources
- Understand the Basics of Intentionally Defective Grantor Trusts
- Intentionally Defective Grantor Trusts (IDGT) | White Coat Investor (https://whitecoatinvestor.com/intentionally-defective-grantor-trusts-idgt)
- Intentionally Defective Grantor Trusts (IDGTs) – Wealthspire (https://wealthspire.com/blog/intentionally-defective-grantor-trusts-idgt)
- 12 Inspirational Quotes About Estate Planning – Leigh Hilton (https://dentonestateplanninglawyer.com/12-inspirational-quotes-about-estate-planning)
- 10 Inspirational Quotes About Estate Planning (https://nelsonlawgrouppc.com/10-inspirational-quotes-about-estate-planning)
- Explore Tax Implications of IDGTs
- Intentionally Defective Grantor Trusts (IDGTs) – Wealthspire (https://wealthspire.com/blog/intentionally-defective-grantor-trusts-idgt)
- Grantor Trusts & IDGTs: Estate Planning & Tax Considerations (https://commercetrustcompany.com/research-and-insights/articles/understanding-intentionally-defective-grantor-trusts)
- The Case for an Intentionally Defective Grantor Trust (https://thetaxadviser.com/issues/2008/nov/thecaseforanintentionallydefectivegrantortrust)
- Using an Intentionally Defective Grantor Trust to Transfer Assets (https://mblawfirm.com/insights/using-an-intentionally-defective-grantor-trust-to-transfer-assets)
- Establish Your Intentionally Defective Grantor Trust: A Step-by-Step Process
- IDGTs Explained: A Powerful Trust Strategy for Tax-Efficient Wealth Transfer (https://harness.co/articles/intentionally-defective-grantor-trusts-wealth-transfer-strategies)
- An Overview of Intentionally Defective Grantor Trusts – Smith and Howard (https://smith-howard.com/an-overview-of-intentionally-defective-grantor-trusts)
- Your IDGT Guide: How to Strategically Use IDGTs Before 2026 (https://tawlawtx.com/trusts/your-idgt-guide-how-to-strategically-use-idgts-before-2026)
- Intentionally Defective Grantor Trusts: A Guide (https://learn.valur.com/intentionally-defective-grantor-trusts-idgt-guide)
- The Case for an Intentionally Defective Grantor Trust (https://thetaxadviser.com/issues/2008/nov/thecaseforanintentionallydefectivegrantortrust)
- Consider Key Factors and Avoid Common Pitfalls in IDGT Creation
- IRS signals it will challenge IDGT basis step-up at death (https://thetaxadviser.com/issues/2023/sep/irs-signals-it-will-challenge-idgt-basis-step-up-at-death)
- 10 Inspirational Quotes About Estate Planning (https://nelsonlawgrouppc.com/10-inspirational-quotes-about-estate-planning)
- Intentionally Defective Grantor Trusts (IDGT) | White Coat Investor (https://whitecoatinvestor.com/intentionally-defective-grantor-trusts-idgt)
- 12 Inspirational Quotes About Estate Planning – Leigh Hilton (https://dentonestateplanninglawyer.com/12-inspirational-quotes-about-estate-planning)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Estate Planning for high-income W-2 families at Bright Advisers.
Keep reading