

Key Highlights
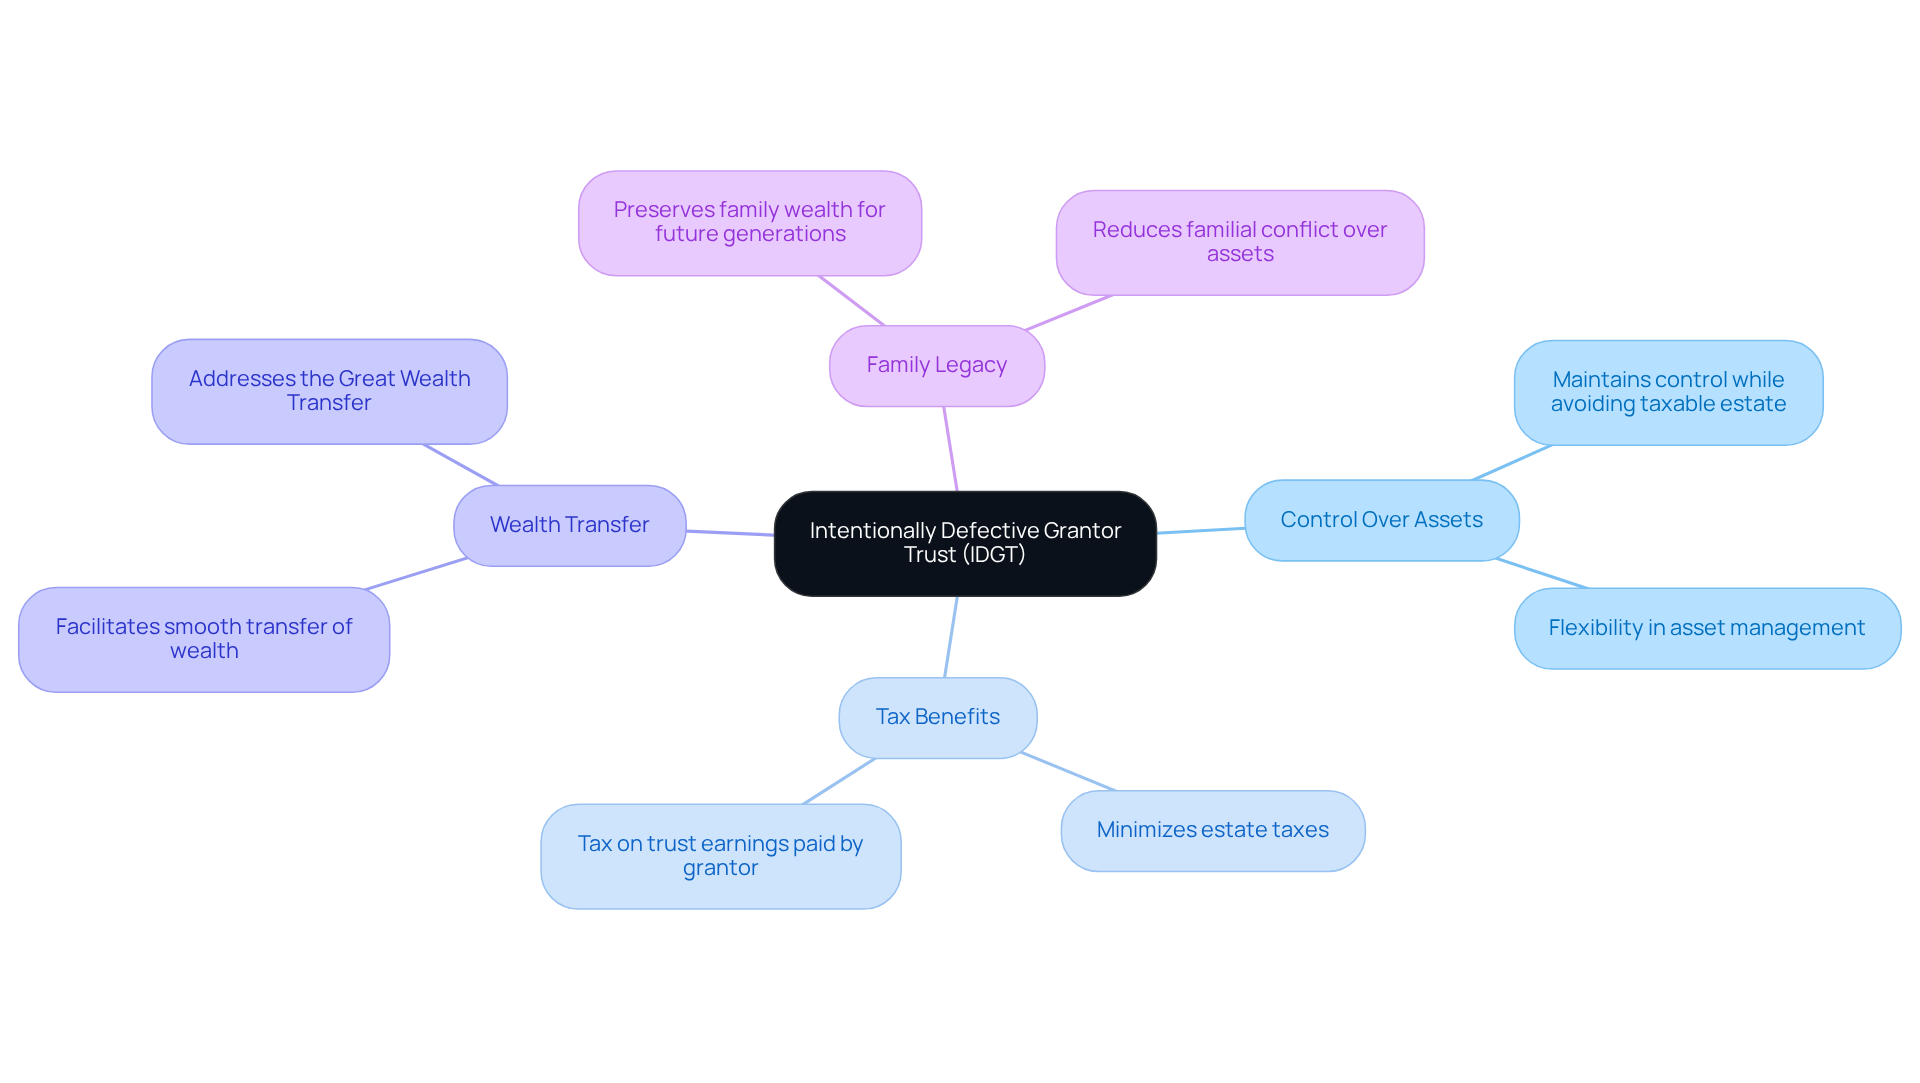
- An Intentionally Defective Grantor Trust (IDGT) allows families to maintain control over assets while keeping them out of their taxable estate.
- IDGTs enable grantors to pay taxes on trust earnings, facilitating growth without increasing the taxable estate.
- The Great Wealth Transfer is projected to pass down $84.4 trillion, highlighting the importance of protecting family legacies.
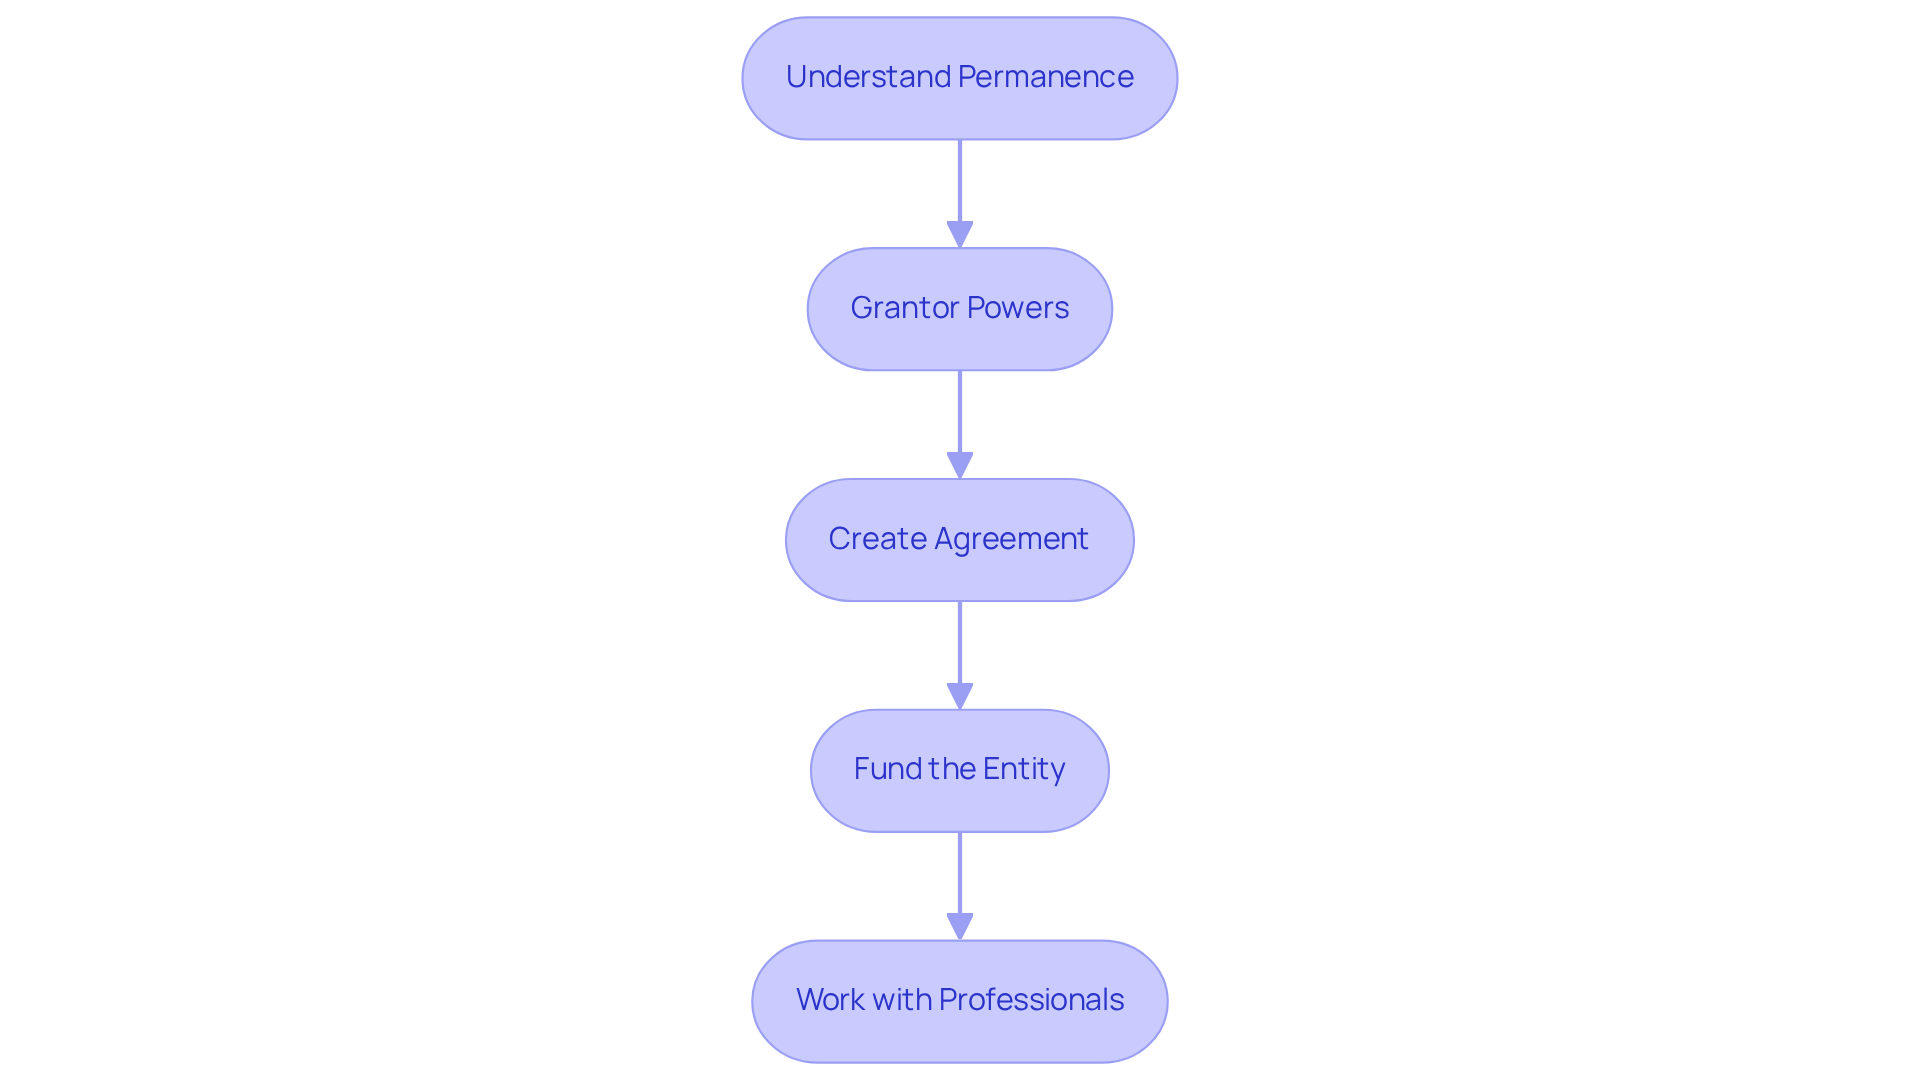
- Key components of establishing an IDGT include permanence, grantor powers, clear agreements, funding strategies, and professional guidance.
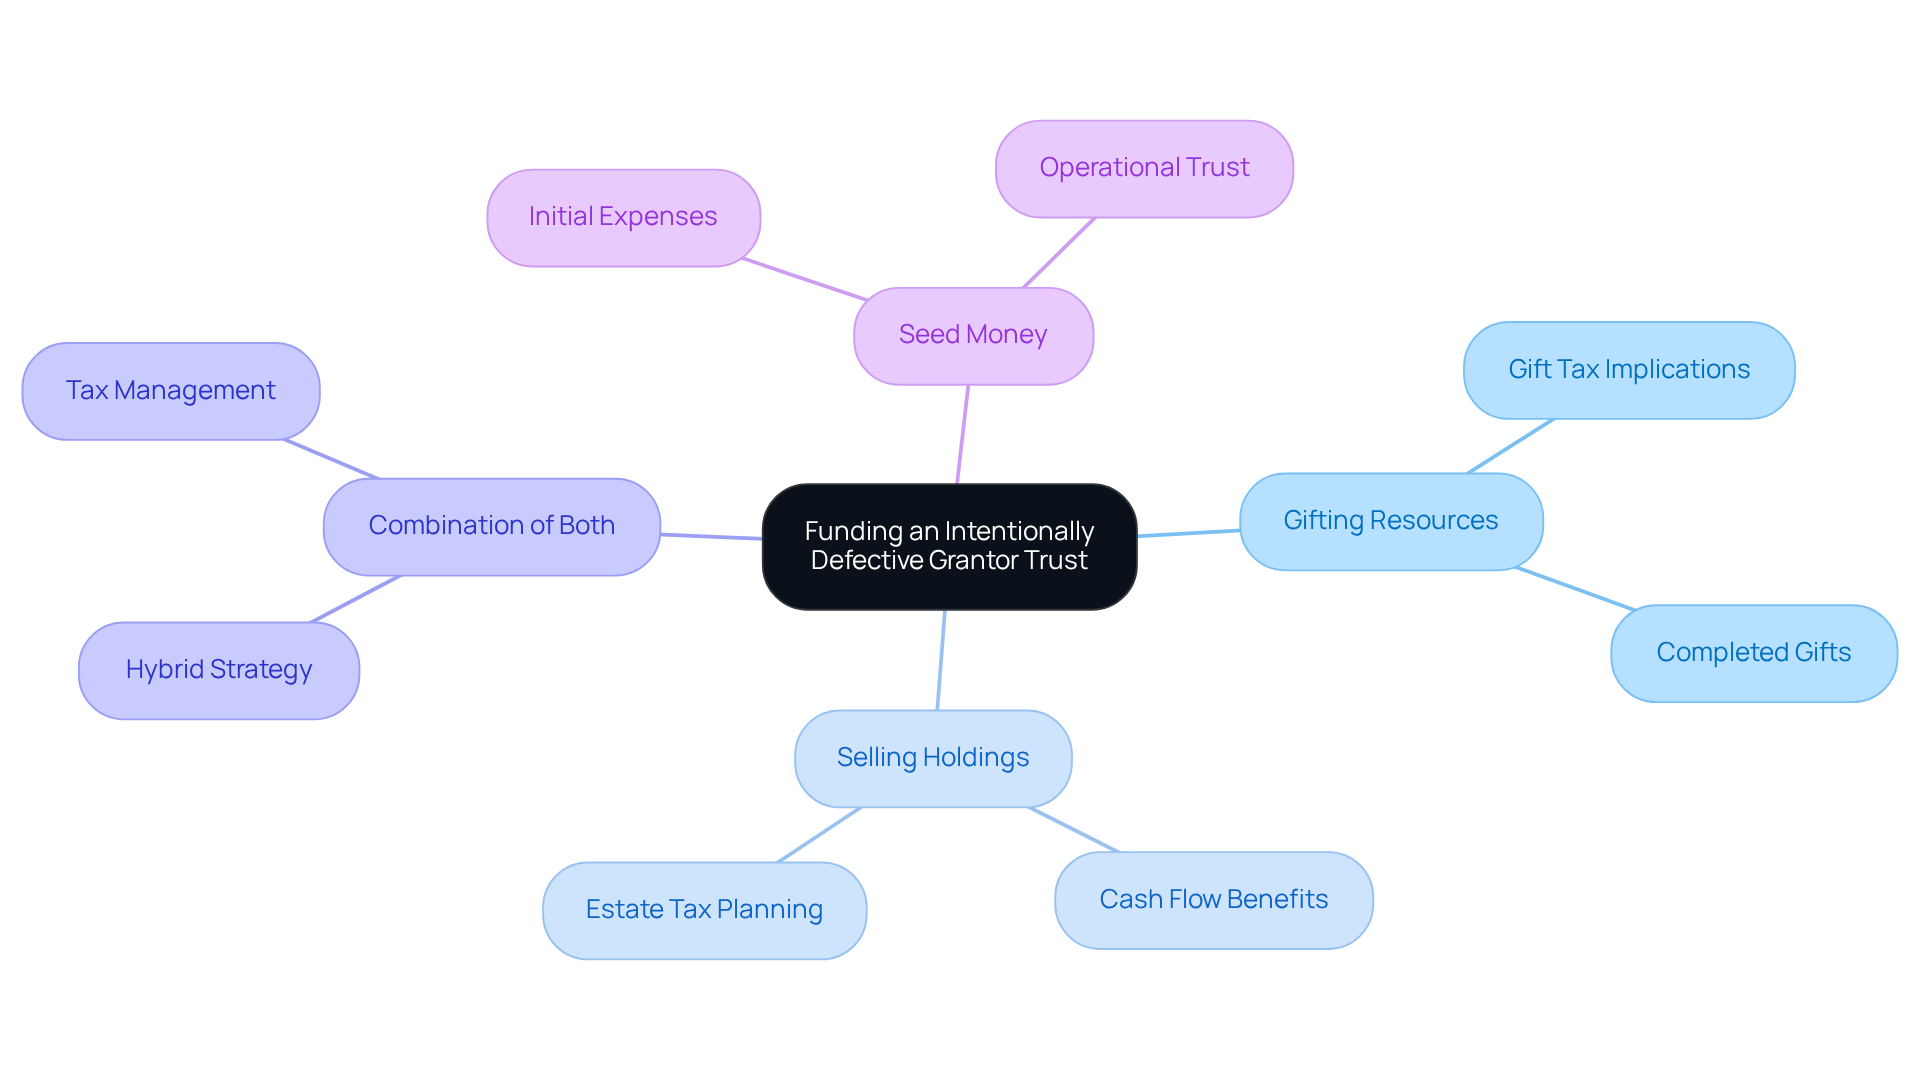
- Funding methods for an IDGT include gifting resources, selling holdings, a combination of both, and providing seed money.
- Tax implications of IDGTs involve the grantor paying income taxes on trust earnings, potential gift tax implications, and estate tax benefits.
- Understanding IRS guidelines and maintaining compliance is crucial for effective management of an IDGT.
Introduction
Imagine feeling overwhelmed by the complexities of financial planning, yet knowing there’s a way to secure your family’s future. An intentionally defective grantor trust (IDGT) promissory note offers a unique opportunity to maintain control over assets while minimizing estate taxes. This tool is essential for high-income families.
Many families feel overwhelmed by the complexities of setting up an IDGT, unsure of where to start. But with the right support, you can navigate this journey with confidence. By understanding the process, families can confidently secure their financial future and ensure their values are passed down for generations to come.
Define Intentionally Defective Grantor Trust (IDGT)
Imagine feeling secure about your family’s financial future, even amidst the complexities of wealth management. An intentionally defective grantor trust promissory note is a special type of trust that allows you to maintain some control over your assets while keeping them out of your taxable estate. This means you can pay taxes on the trust’s earnings, allowing it to grow without the burden of additional financial obligations.
For high-income families, this trust can be a powerful tool for passing down wealth and minimizing estate taxes. When families understand how trusts work, they can create a solid plan that protects their financial future and brings peace of mind.
As we witness the Great Wealth Transfer, with an estimated $84.4 trillion set to be passed down, it’s more important than ever to think about how to protect your family’s legacy. By taking proactive steps now, you can ensure your family’s legacy is preserved and cherished for generations to come.
Identify Key Components and Requirements for an IDGT
Imagine securing your family’s future while navigating the complexities of financial planning. To establish an intentionally defective grantor trust promissory note, there are several key components to consider that can help you protect your family’s wealth.
- First, it’s important to understand that this arrangement is designed to be permanent, ensuring your family’s future is secure. Once established, the grantor cannot modify its conditions or reclaim the resources, which might sound daunting, but it’s a step towards lasting security.
- Next, the grantor retains certain powers, like the ability to pay income taxes on the entity’s earnings. This unique aspect makes the arrangement ‘defective’ for income tax purposes, allowing the entity’s resources to grow without increasing the grantor’s taxable estate, specifically when considering an intentionally defective grantor trust promissory note. This means more for your family in the long run.
- Creating a clear agreement is essential; it outlines how your trust will work and who will benefit from it. This document is not just a formality; it’s a roadmap for your family’s future, detailing how resources are managed and distributed.
- Funding the entity is another crucial step. You might consider transferring a business or other assets into the trust, allowing future appreciation to occur outside your taxable estate. This can be a smart move for business owners looking to secure their legacy.
- Lastly, working with trusted legal and tax professionals can make this journey smoother and ensure you’re making the best choices for your family. They can help you navigate the complexities involved in establishing an irrevocable trust, ensuring compliance with IRS regulations while optimizing the trust’s structure for tax efficiency.
By understanding these elements, you can effectively establish a trust that aligns with your estate planning objectives. With the right guidance, you can create a legacy that supports your family’s dreams for generations to come.
Draft the Promissory Note for the IDGT
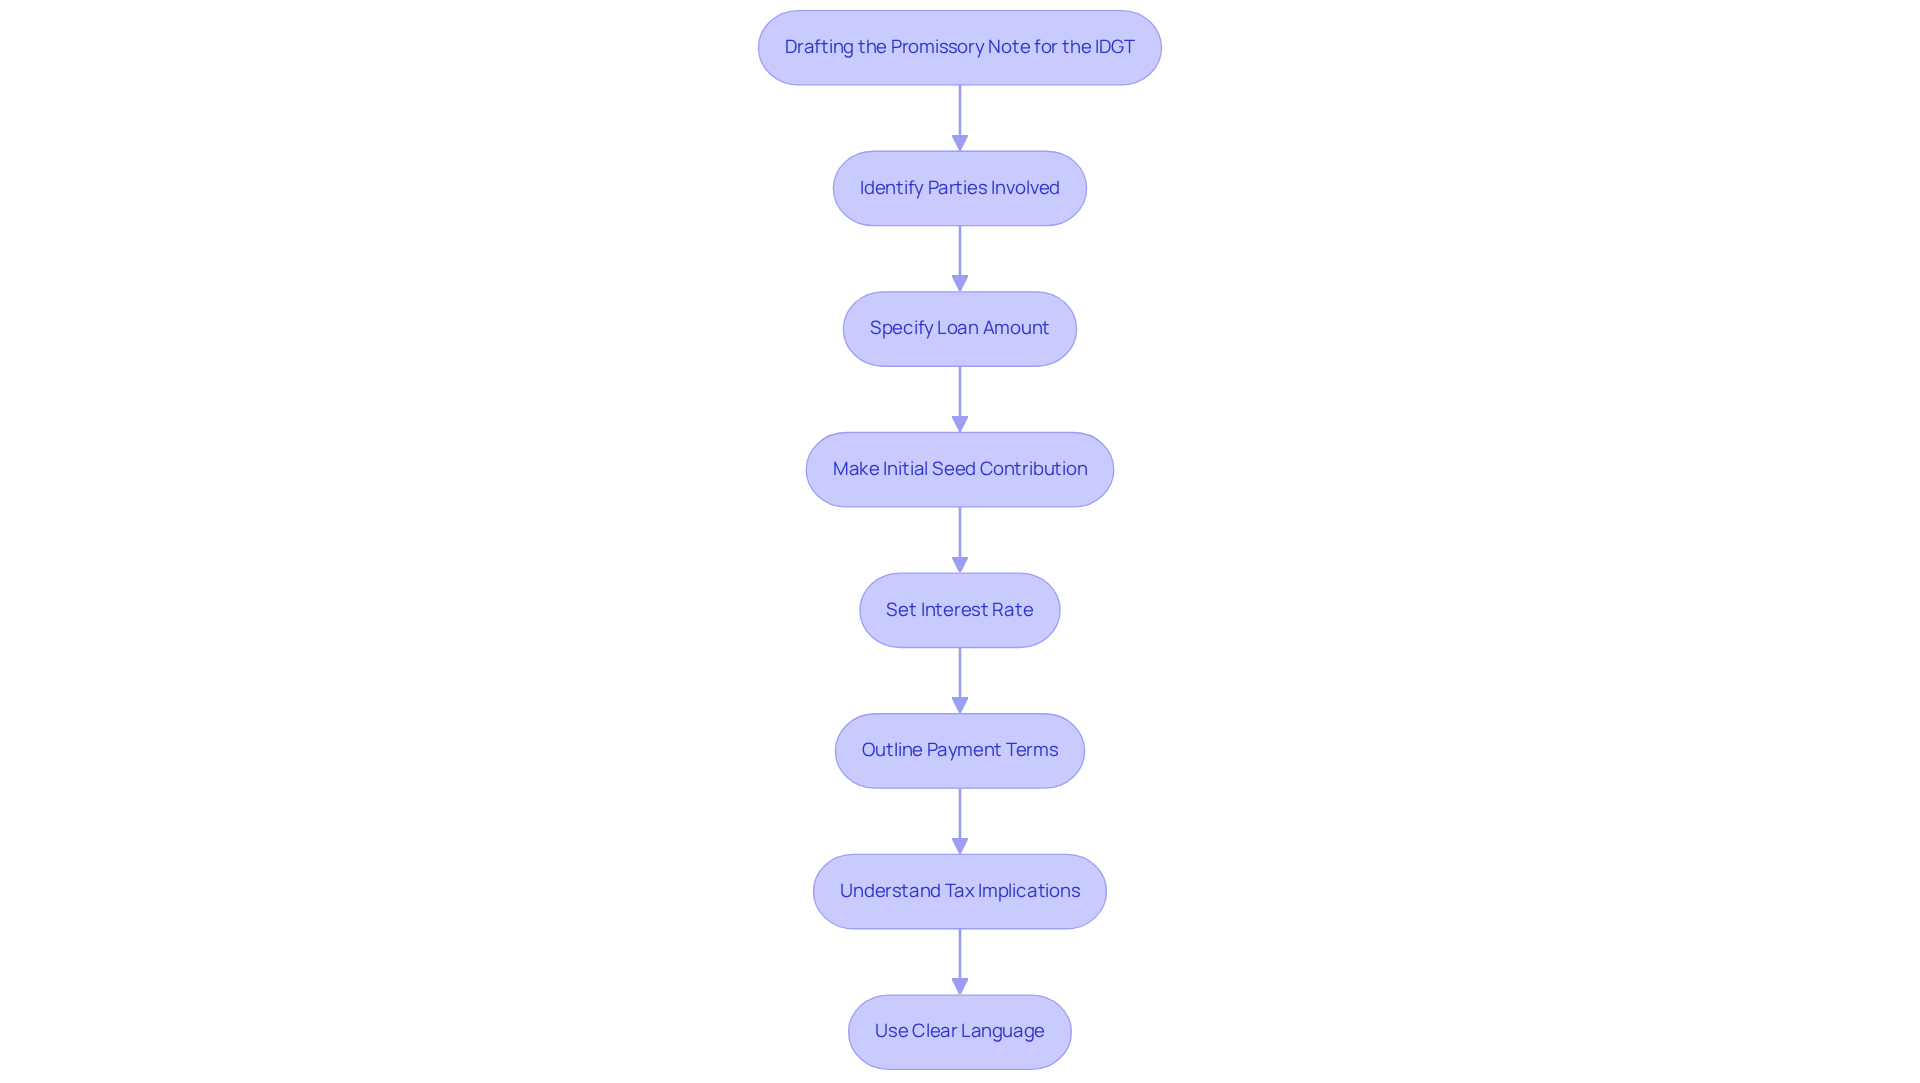
Navigating the complexities of financial planning can feel overwhelming, especially when you’re focused on providing the best for your family.
Let’s start by identifying who’s involved in this important transaction – think of it as bringing together the grantor (the seller) and the buyer in a way that feels right for your family.
Next, it’s essential to specify the loan amount, ensuring it reflects the fair market value of the properties you’re entrusting to the trust – this step is vital for your family’s peace of mind.
Consider making an initial ‘seed’ contribution of at least 10% of the asset’s value you plan to sell to the irrevocable trust – this helps validate the sale and shows your commitment to your family’s future.
When it comes to the interest rate, aim to set it at or above the IRS Applicable Federal Rate (AFR) – this way, you can avoid any unexpected gift tax implications and keep your family’s finances secure.
Let’s talk about payment terms – consider outlining a structure that includes interest-only payments, with a balloon payment of the principal at the end. This approach can help your trust manage cash flow more effectively, giving you peace of mind.
It’s also important to understand the tax implications of an intentionally defective grantor trust promissory note, since interest income received from the trust through these promissory note payments isn’t taxable during your lifetime, which can be a significant financial benefit for your family.
Finally, when drafting the note, use clear and precise language to ensure it’s enforceable and meets IRS regulations – consider consulting with a legal professional to make this process smoother for your family.
By taking these steps, you’re not just securing your financial future; you’re creating a legacy of stability and love for your family.
Fund the Intentionally Defective Grantor Trust
Imagine feeling secure about your family’s financial future while navigating the complexities of trust funding. Funding an intentionally defective grantor trust promissory note can be accomplished through several effective methods, especially for high-income families looking to optimize their financial situation through strategic tax planning.
- Gifting Resources: The grantor can make a completed gift of resources to the trust. This simple method can lead to gift tax implications, especially if the value exceeds certain limits. Understanding these implications is crucial for families aiming to minimize tax liabilities.
- Selling Holdings: The grantor can sell holdings to the intentionally defective grantor trust in exchange for an intentionally defective grantor trust promissory note. This approach allows the grantor to maintain cash flow while effectively removing the holdings from their estate, which can be advantageous for estate tax planning. Professional guidance can help families navigate this process to ensure they are making the most of their financial resources.
- Combination of Both: A hybrid strategy can be employed, where the grantor gifts a portion of the resources and sells the remainder. This method helps manage tax implications while achieving desired estate planning outcomes, addressing the financial challenges that high-income families often face.
- Seed Money: It’s wise to seed the trust with a small amount of liquid assets to cover initial expenses and ensure the trust is operational from the outset.
As you explore these funding options, remember that seeking guidance can make this journey smoother for your family. With the right support, you can confidently create a trust that not only meets your family’s needs but also paves the way for a brighter financial future. We’re here for you, ready to help your family navigate these complexities and make informed decisions.
Manage and Understand Tax Implications of the IDGT
Imagine feeling secure about your family’s financial future while navigating the complexities of taxes with confidence. Managing the tax implications of an intentionally defective grantor trust promissory note can seem daunting, but understanding a few key aspects can make all the difference.
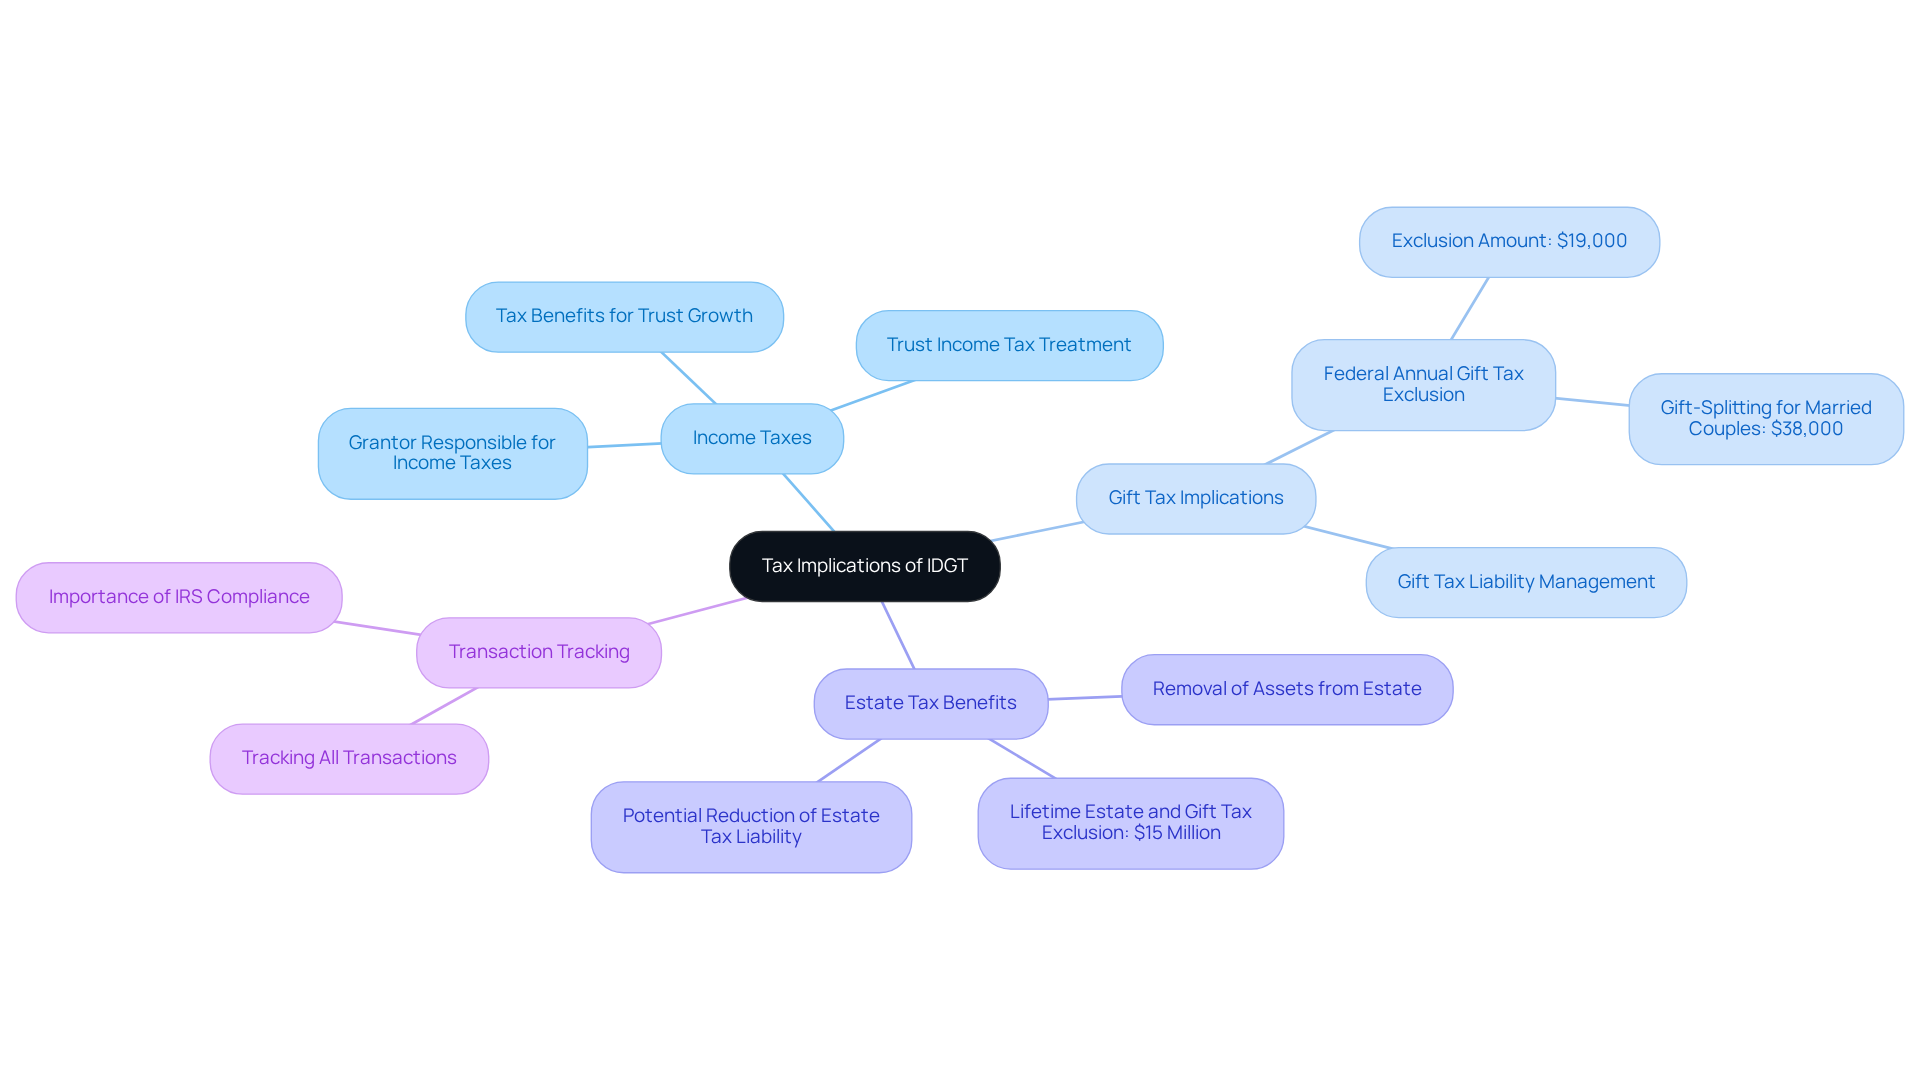
As the grantor, you’ll be responsible for the income taxes on the trust’s earnings, but this can actually help your property grow without immediate tax worries. This arrangement allows your assets to appreciate in value, providing a notable benefit of the irrevocable grantor setup.
When you transfer property to the trust, it may trigger gift tax implications based on the property’s value. Staying within the federal annual gift tax exclusion limit of $19,000 per recipient for 2026 is essential to avoid unnecessary tax liabilities. If you’re married, this exclusion can effectively double to $38,000 through gift-splitting, giving you more flexibility.
Transferring assets to the irrevocable trust removes them from your estate for estate tax purposes. This can significantly lighten the estate tax burden for your family when you pass, especially with the federal lifetime estate and gift tax exclusion of $15 million per individual effective January 1, 2026.
It’s important to keep track of all transactions to ensure everything aligns with IRS guidelines, giving you peace of mind. By understanding these tax implications, you can effectively manage your intentionally defective grantor trust promissory note and leverage its benefits for long-term wealth preservation and transfer.
By taking the time to understand these tax implications, you’re not just protecting your assets; you’re investing in your family’s legacy.
Conclusion
Imagine feeling secure about your family’s financial future, knowing you’re taking steps to minimize tax burdens. We’ve shared some important steps to help you create an IDGT, focusing on:
- What you need to know about its components
- How to draft a clear promissory note
- Ways to fund the trust effectively
Taking these steps can help your family preserve its wealth and pass it down through generations with love and care. It’s important to understand how retaining certain powers as a grantor, having a solid agreement, and exploring different funding options can make a difference for your family. Creating an IDGT isn’t just about finances; it’s about building a legacy that truly reflects your family’s values and dreams. By reaching out to Bright Advisers, you can take confident steps toward a future that honors your family’s dreams and values.
Frequently Asked Questions
What is an intentionally defective grantor trust (IDGT)?
An intentionally defective grantor trust is a special type of trust that allows the grantor to maintain some control over their assets while keeping them out of their taxable estate. This enables the grantor to pay taxes on the trust’s earnings, allowing the trust to grow without additional financial obligations.
How can an IDGT benefit high-income families?
An IDGT can be a powerful tool for high-income families to pass down wealth and minimize estate taxes. It helps protect the family’s financial future and legacy, especially during the Great Wealth Transfer, which is expected to involve an estimated $84.4 trillion.
What are the key components required to establish an IDGT?
Key components include: – Permanence: The trust is designed to be permanent, meaning the grantor cannot modify its conditions or reclaim resources. – Powers of the grantor: The grantor retains the ability to pay income taxes on the trust’s earnings, which allows the trust’s resources to grow without increasing the grantor’s taxable estate. – Clear agreement: A detailed agreement outlining how the trust will operate and who will benefit is essential. – Funding: Transferring assets, such as a business, into the trust allows future appreciation to occur outside the taxable estate. – Professional guidance: Working with legal and tax professionals ensures compliance with IRS regulations and optimizes the trust’s structure for tax efficiency.
Why is it important to have a clear agreement for an IDGT?
A clear agreement serves as a roadmap for the trust, detailing how resources are managed and distributed. It outlines the operational framework of the trust and ensures that the intentions of the grantor are clearly defined for future beneficiaries.
What role do legal and tax professionals play in establishing an IDGT?
Legal and tax professionals help navigate the complexities of establishing an IDGT, ensuring compliance with IRS regulations and optimizing the trust’s structure for tax efficiency. Their expertise is crucial for making informed decisions that align with the family’s estate planning objectives.
List of Sources
- Define Intentionally Defective Grantor Trust (IDGT)
- 50 Estate Planning Statistics and Facts You Need to Know (https://justvanilla.com/blog/estate-planning-statistics-and-facts-you-need-to-know)
- Estate Planning Statistics & Trends for 2026 | Empathy (https://empathy.com/blog/estate-planning-statistics-and-trends)
- 26 SHOCKING STATISTICS ABOUT ESTATE PLANNING – Bedlam Law (https://bedlamlaw.com/26-shocking-statistics-about-estate-planning)
- Identify Key Components and Requirements for an IDGT
- Intentionally Defective Grantor Trusts (https://marinerwealthadvisors.com/insights/intentionally-defective-grantor-trusts)
- Estate Planning with Intentionally Defective Grantor Trusts (https://commonwealth.com/insights/estate-planning-with-intentionally-defective-grantor-trusts)
- What is an intentionally defective grantor trust (IDGT)? | Fidelity (https://fidelity.com/viewpoints/wealth-management/insights/intentionally-defective-grantor-trusts)
- Intentionally Defective Grantor Trusts | National Advisors Trust (https://nationaladvisors.com/a-guide-to-intentionally-defective-grantor-trusts-idgts)
- Understanding the Intentionally Defective Grantor Trust Benefits (https://evolutiontaxlegal.com/intentionally-defective-grantor-trust-idgt-estate-planning)
- Draft the Promissory Note for the IDGT
- An Overview of Intentionally Defective Grantor Trusts – Smith and Howard (https://smith-howard.com/an-overview-of-intentionally-defective-grantor-trusts)
- Estate planning Q&A: Sales to Intentionally Defective Grantor Trusts explained (https://rsmus.com/insights/services/business-tax/sales-to-intentionally-defective-grantor-trusts-explained.html)
- AFR Rates | IRS Applicable Federal Rates (https://nationalfamilymortgage.com/afr-rates)
- Federal Gift and Estate Tax Planning- Part 5 of 7: Advanced Planning with IDGTs (https://blog.lawfirmcarolinas.com/federal-gift-and-estate-tax-planning-part-5-of-7-advanced-planning-with-idgts)
- Fund the Intentionally Defective Grantor Trust
- Intentionally Defective Grantor Trusts (IDGTs) – Wealthspire (https://wealthspire.com/blog/intentionally-defective-grantor-trusts-idgt)
- Intentionally Defective Grantor Trust (IDGT): Definition, Benefits & Examples — Farther (https://farther.com/foundations/intentionally-defective-grantor-trust-idgt)
- Estate Planning with Intentionally Defective Grantor Trusts (https://commonwealth.com/insights/estate-planning-with-intentionally-defective-grantor-trusts)
- Estate planning Q&A: Sales to Intentionally Defective Grantor Trusts explained (https://rsmus.com/insights/services/business-tax/sales-to-intentionally-defective-grantor-trusts-explained.html)
- Manage and Understand Tax Implications of the IDGT
- Nelson Mullins – 2026 Estate and Gift Tax Update (https://nelsonmullins.com/insights/blogs/tax-reports/all/2026-estate-and-gift-tax-update)
- Grantor Trusts & IDGTs: Estate Planning & Tax Considerations (https://commercetrustcompany.com/research-and-insights/articles/understanding-intentionally-defective-grantor-trusts)
- Intentionally Defective Grantor Trusts (IDGTs) – Wealthspire (https://wealthspire.com/blog/intentionally-defective-grantor-trusts-idgt)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Estate Planning for high-income W-2 families at Bright Advisers.
Keep reading