

Key Highlights:
- A Family LLC (FLLC) helps families manage and protect shared assets, facilitating wealth transfer while minimising tax burdens.
- Assets such as real estate and investments can be placed in an FLLC, allowing parents to retain control and secure financial well-being for their children.
- FLLCs offer valuation discounts that can reduce estate taxes when assets are inherited.
- Creating an FLLC can help avoid probate, ensuring smooth asset transitions to heirs.
- Steps to establish an FLLC include choosing a name, designating members, creating an operating agreement, and filing necessary documents.
- Initial costs for forming an FLLC can range from $50 to over $10,000, depending on complexity and state requirements.
- Benefits of FLLCs for young families include asset protection, tax advantages, control over management, simplified wealth transfer, and educational opportunities for children.
- Challenges include formation and maintenance costs, complexity in management, potential disputes among family members, tax implications, and limited applicability for smaller estates.
Introduction
Creating a family LLC can be a wonderful way for young parents to secure their financial future and make wealth transfer smoother for generations to come. Imagine having a powerful tool that not only protects your valuable assets but also helps your children learn about financial responsibility. It’s about preparing them for the future and ensuring they manage family resources wisely.
However, starting a family LLC isn’t always straightforward. There can be complexities and challenges along the way. It’s important to understand the key steps to take and how to navigate potential pitfalls. By doing so, you can maximize the benefits for your family.
Together, we can explore this journey, ensuring you feel supported every step of the way. We’re here for you, ready to help you make informed decisions that align with your family values.
Define Family LLC and Its Purpose in Estate Planning
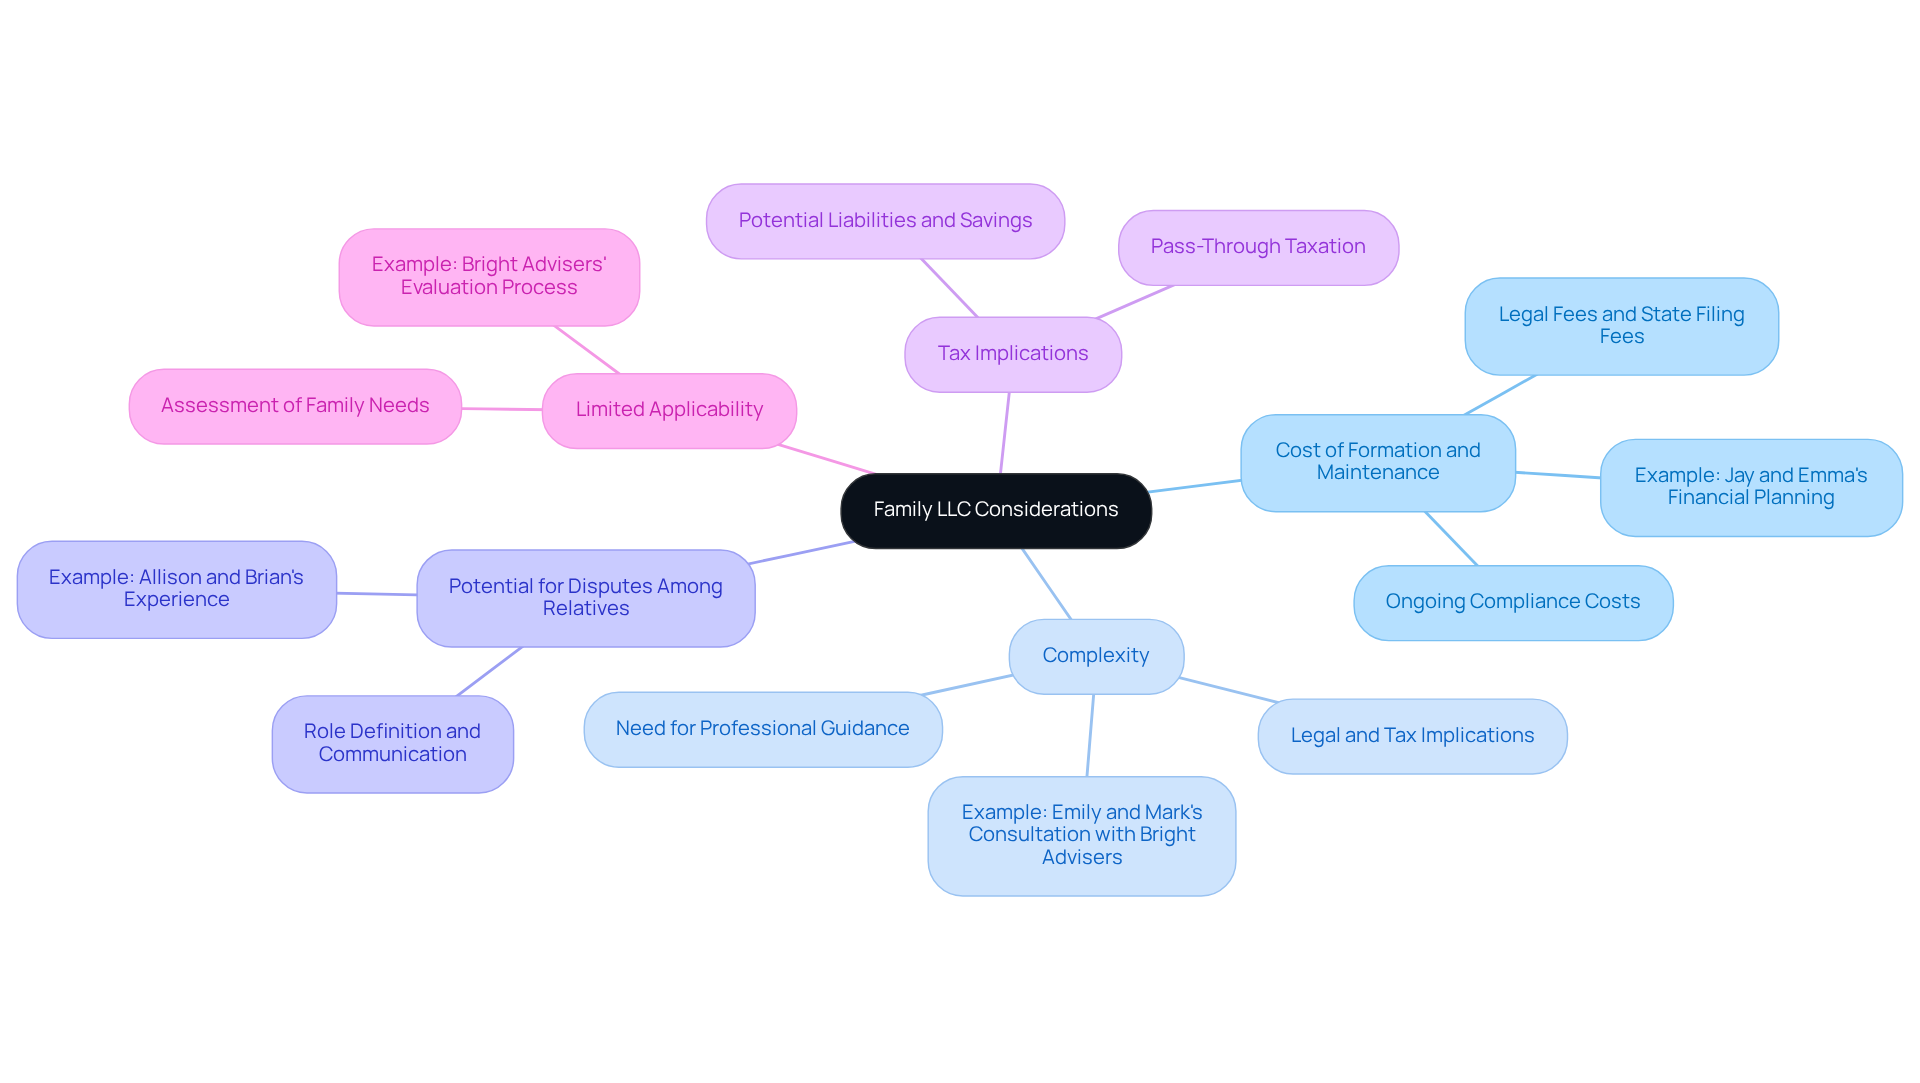
Imagine if you could protect your family’s future while ensuring a smooth transition of your wealth. Creating a family LLC is a wonderful way for relatives to come together, managing and safeguarding their shared resources. It plays a crucial role in estate planning, helping to pass down wealth across generations while keeping tax burdens low.
By placing assets like real estate, investments, or businesses into an FLLC, parents can retain control over these valuable holdings, all while securing their children’s financial well-being. This structure not only shields your assets but also offers valuation discounts, which can significantly lessen estate taxes when your loved ones inherit. For instance, families using an FLLC can freeze the growth of business interests, allowing older generations to transfer ownership while taking advantage of gift exclusions to sidestep gift tax.
It’s also important to understand that an FLLC can help avoid the often complicated probate process, ensuring that your assets transition smoothly to your family when the time comes. Statistics show that 31% of people believe the most damaging consequence of poor estate planning is leaving loved ones without enough financial support. This highlights the need for proactive steps, such as creating a family LLC, to safeguard your family’s future.
At Bright Advisers, we’re here for families like Jay and Emma, Emily and Mark, and Allison and Brian. We guide you through the complexities of with tailored solutions that resonate with your family values. Our personalized financial planning and tax optimization strategies, along with innovative investment approaches, empower you to preserve your wealth and legacy for generations to come.
Together, we can navigate this journey, ensuring your family achieves financial security and freedom. The FLLC is a powerful tool for families creating a family LLC to protect their assets and create a prosperous future.
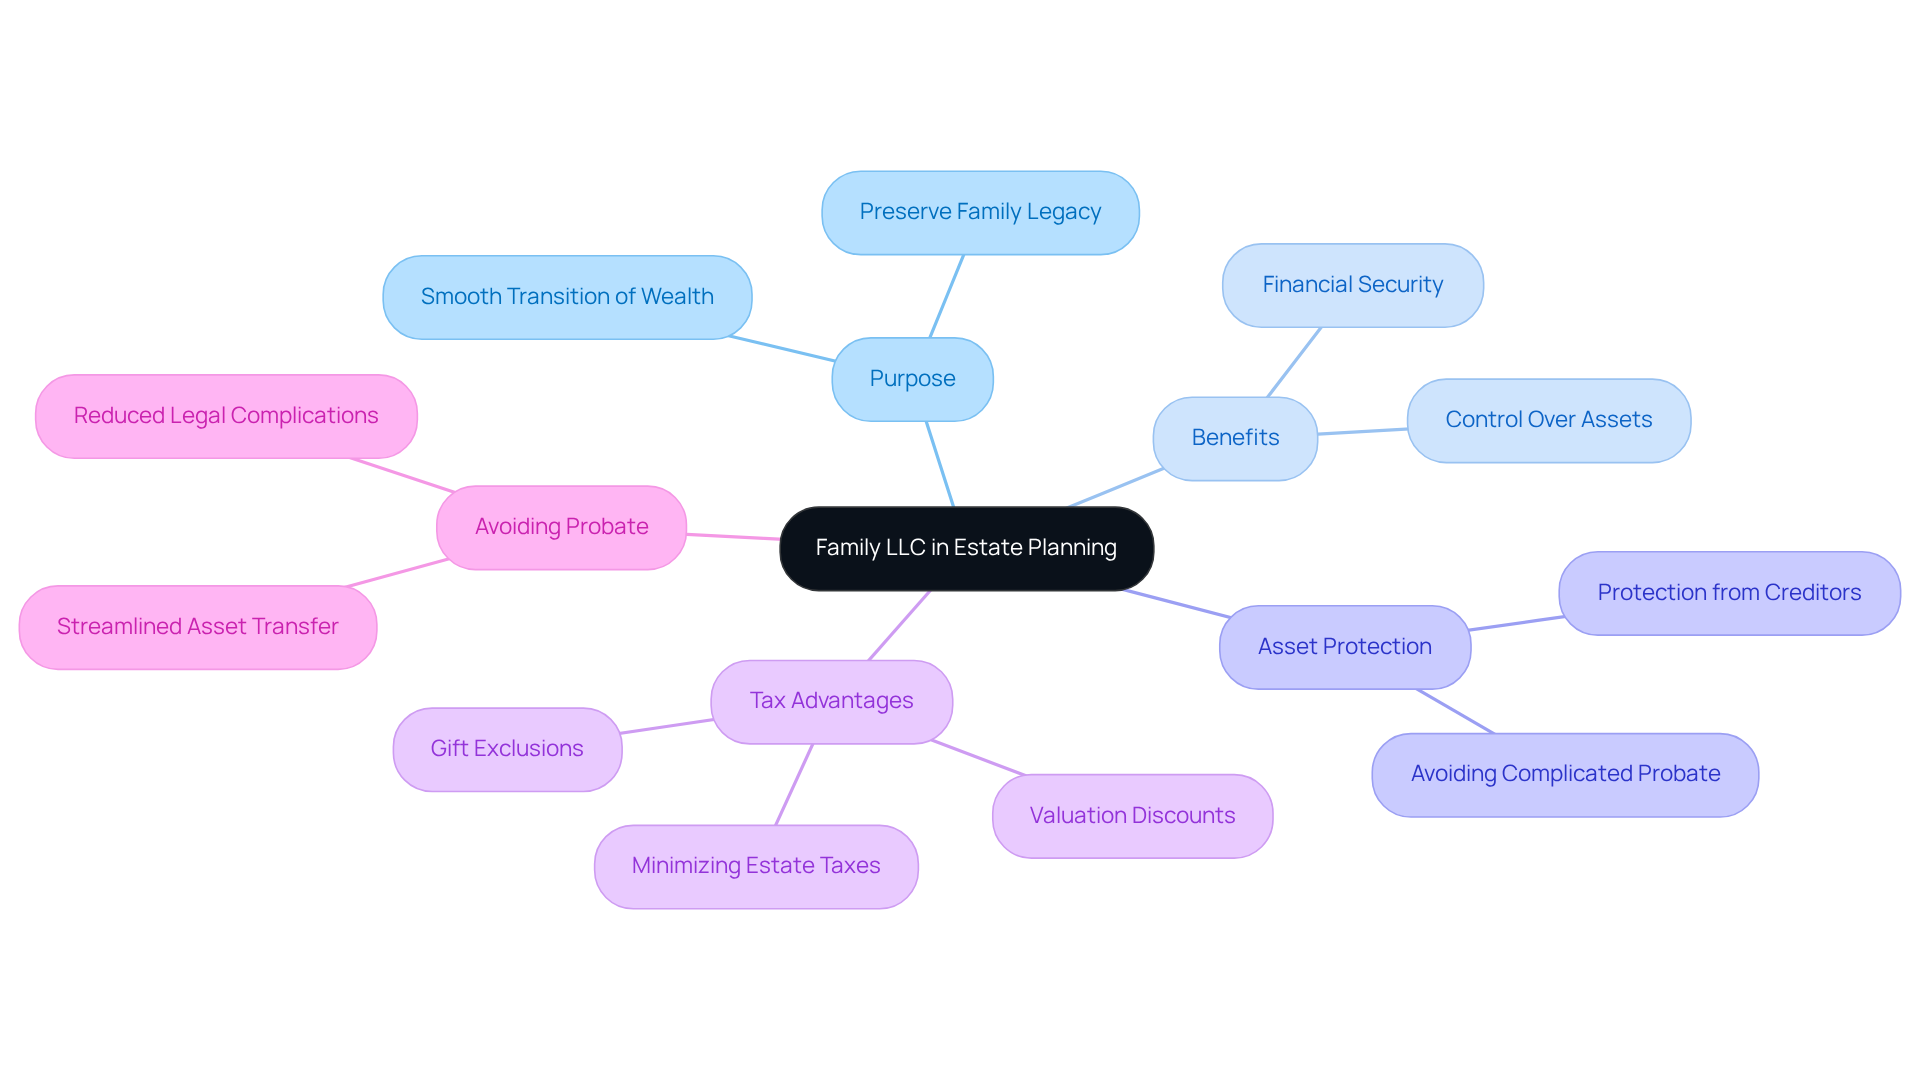
Establish Your Family LLC: Step-by-Step Setup Guide
Creating a family LLC can feel like a big step, but it’s a journey worth taking for your family’s future. Here’s how to get started:
- Choose a Name: Think about a unique name for your LLC that meets your state’s requirements. It’s important that it stands out from other businesses.
- Designate Members: Identify family members who will be part of the LLC. Usually, parents take on managing roles, while children can have non-managing positions.
- Create an Operating Agreement: Draft an operating agreement that outlines how your LLC will run. This document is crucial for detailing responsibilities and profit sharing, helping to prevent misunderstandings down the road.
- Designate a Registered Agent: Appoint someone to receive legal documents for your LLC. This step is essential for staying compliant with state laws.
- File Articles of Organization: Submit the Articles of Organization to your state’s Secretary of State office. This officially registers your LLC and is a key part of the formation process.
- Obtain an EIN: Apply for an Employer Identification Number (EIN) from the IRS. You’ll need this for tax purposes and to open a business bank account.
- Open a Bank Account: Set up a separate bank account for your LLC. This helps keep your personal and business finances distinct, which is vital for protecting your assets.
- Transfer Assets: Move any intended assets into the LLC, making sure to document each transfer. This keeps your ownership records clear.
- Maintain Compliance: Stay updated on state requirements, like filing annual reports and paying necessary fees, to keep your LLC in good standing.
Creating a family LLC involves some initial costs, such as state filing fees that can range from $50 to $500, depending on where you live. You might also want to consider for drafting your operating agreement. Online services like LegalZoom can help simplify the process and save you money, which is beneficial when creating a family LLC.
Take the Johnson family, for example. They’ve found that a Limited Liability Company helps them manage and transfer resources effectively, all while minimizing estate taxes and keeping control over their business interests. However, it’s also wise to think about potential challenges, like disagreements among family members regarding management and profit sharing.
Remember, you’re not alone in this journey. Together, we can navigate the complexities of financial planning for your family.
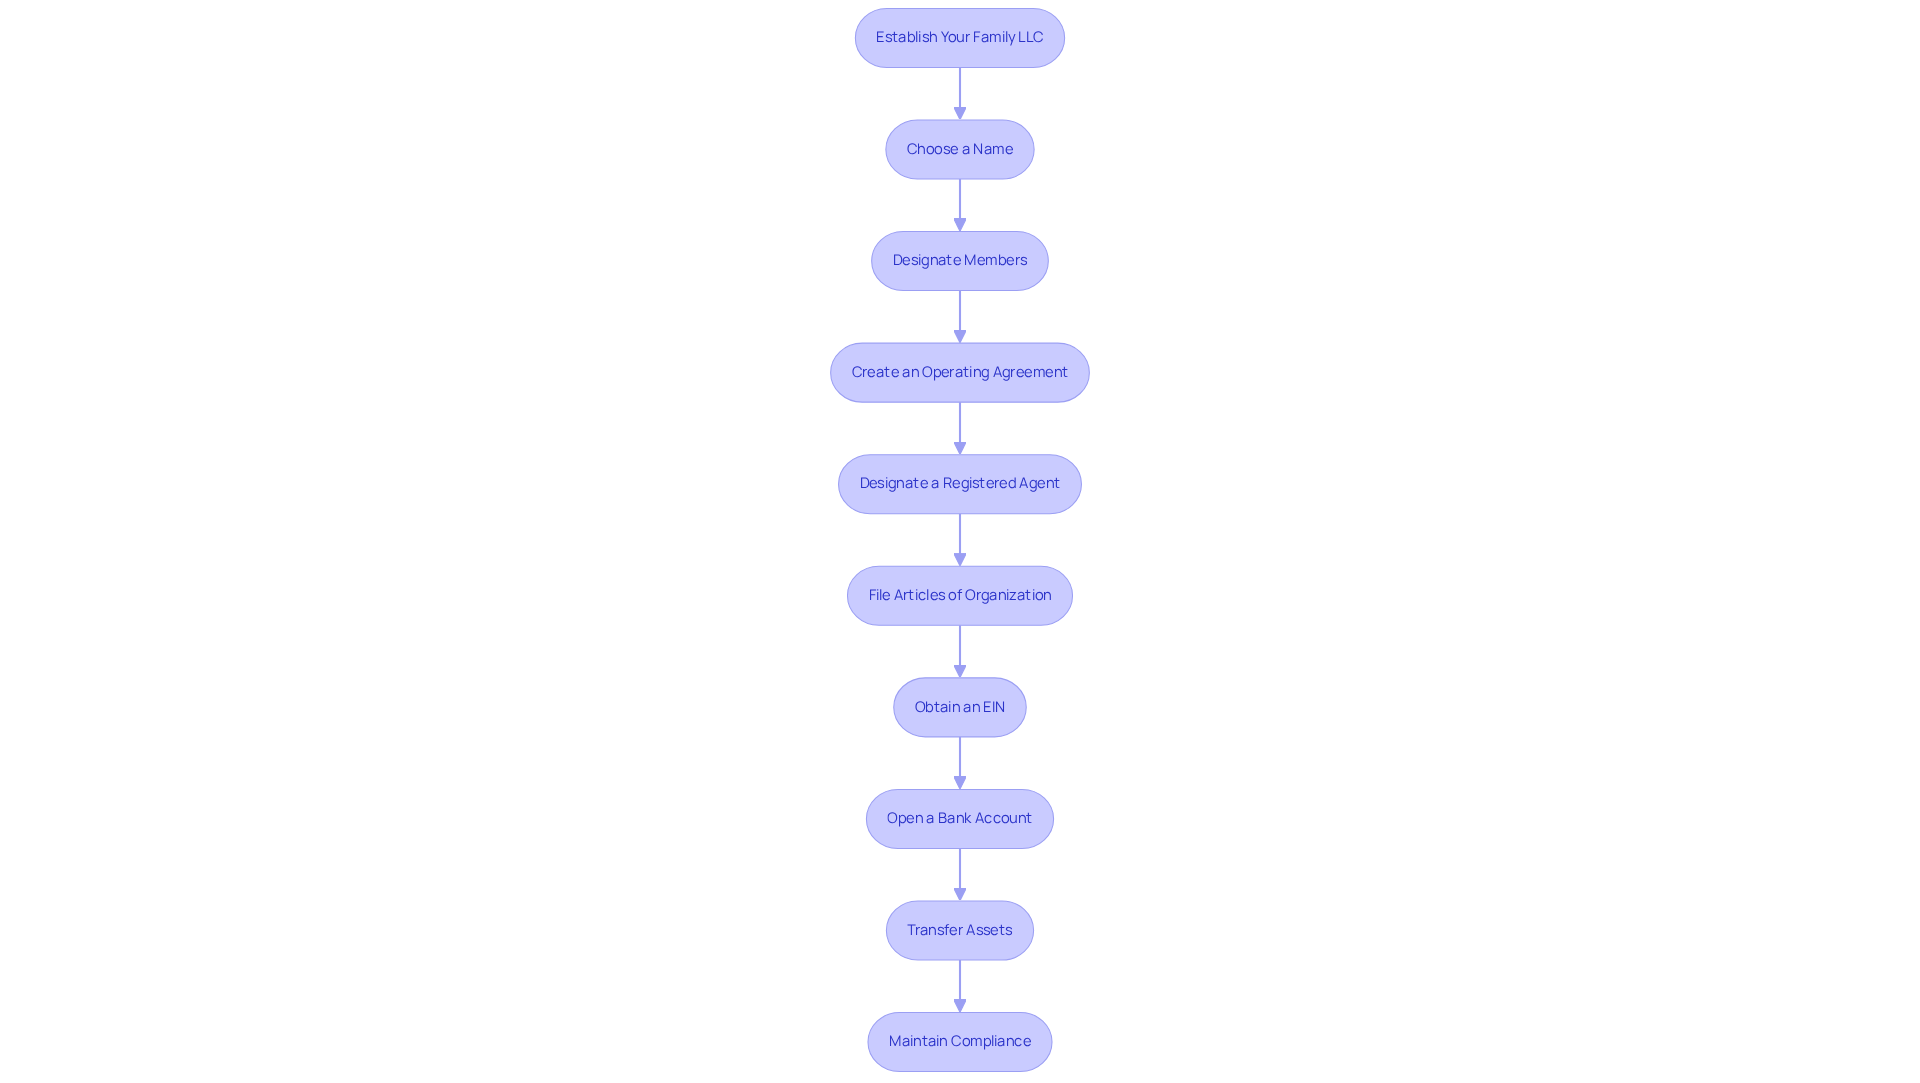
Explore the Benefits of a Family LLC for Young Families
Imagine a future where your family’s wealth is not just protected but nurtured. Creating a family LLC provides a wealth of advantages tailored for young families, ensuring that your hard-earned assets are safeguarded and your children are prepared for financial responsibility.
- Asset Protection: Creating a family LLC can protect your personal assets from liabilities associated with the LLC. This means your family wealth is protected from potential lawsuits or creditors, a crucial consideration in today’s world where automobile accidents can lead to unexpected legal challenges.
- Tax Advantages: One of the significant benefits of creating a family LLC is the tax advantages. They allow you to transfer holdings at discounted values, which can greatly reduce estate and gift taxes. This strategic approach helps families like Emily and Mark retain more wealth for future generations, enhancing their financial situation.
- Control and Responsibility: By creating a family LLC, parents can maintain control over the management of the LLC’s assets while allowing their children to benefit from them. This structure not only upholds family values but also fosters a sense of responsibility among younger members. Bright Advisers helped Emily and Mark create a framework that instilled financial responsibility in their children while enabling them to oversee their investments.
- Wealth Transfer: Creating a family LLC simplifies the process of wealth transfer, allowing for a streamlined passing of wealth to the next generation while bypassing the complexities of probate. This ensures that your heirs can access their assets without unnecessary delays, something Emily and Mark truly valued as they planned for their children’s future.
- Educational Opportunities: Involving your children in the LLC serves as a practical way to teach them about financial management and responsibility. This hands-on experience fosters financial literacy from a young age, preparing them for future challenges. Bright Advisers emphasized the importance of education in their planning process, helping Emily and Mark create opportunities for their children to learn about managing household wealth.
- Cost Considerations: It’s important to understand that the initial setup expenses for an LLC can range from a few thousand dollars to over $10,000, depending on the complexity of the assets involved. Knowing these costs is crucial for families considering this option. Emily and Mark worked with Bright Advisers to manage these expenses efficiently, ensuring their investment in an LLC aligned with their long-term financial goals.
Creating a family LLC offers benefits that extend beyond mere asset protection; it establishes a strong framework for managing wealth, ensuring it is preserved and passed down effectively while instilling essential financial skills in the next generation. Together, we can navigate this journey, ensuring your family’s future is .
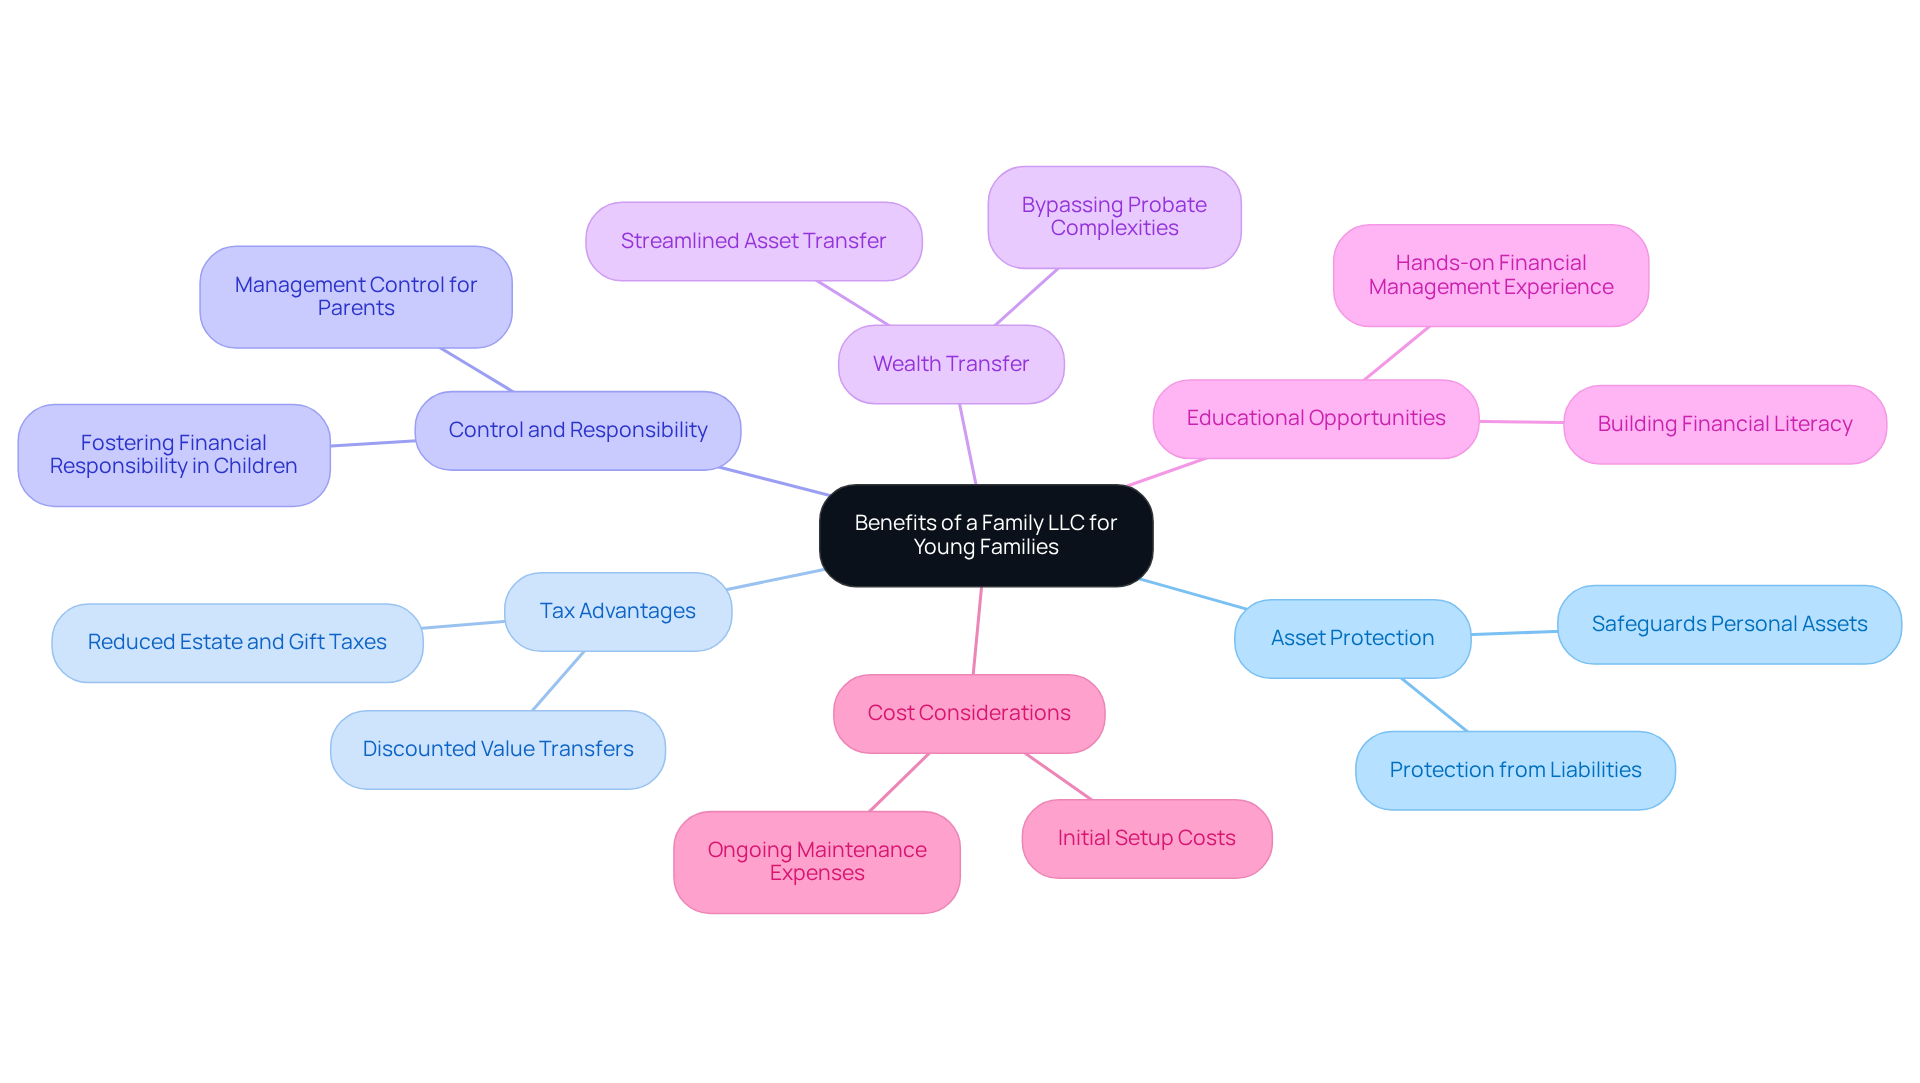
Assess the Downsides and Considerations of a Family LLC
While a can be a wonderful tool for families, it’s important to consider both the advantages and the challenges that come with it.
- Cost of Formation and Maintenance: Setting up a Family LLC might involve legal fees, state filing fees, and ongoing compliance costs. For families like Jay and Emma, who wanted to ease their financial worries, understanding these expenses became a crucial part of their financial planning journey. Imagine if you could navigate these costs with clarity and confidence!
- Complexity: Managing a Household LLC isn’t always straightforward. It requires a grasp of legal and tax implications, which can feel overwhelming. Families may find it beneficial to consult with legal and financial professionals regularly. Emily and Mark, for instance, turned to Bright Advisers for guidance, allowing them to focus on their careers while ensuring their financial future remained secure. It’s comforting to know that help is available when you need it!
- Potential for Disputes Among Relatives: When multiple family members are involved in management, disagreements can arise, especially if roles and responsibilities aren’t clearly defined. Bright Advisers emphasizes the importance of open communication and established roles to prevent conflicts. This was evident in their work with clients like Allison and Brian, who learned to navigate these waters together.
- Tax Implications: Depending on how the LLC is structured and its income, there may be tax consequences that require careful management. Bright Advisers is here to help families optimize their tax situations, ensuring they’re aware of potential liabilities and opportunities for savings. Together, we can make sense of it all!
- Limited Applicability: A Family LLC might not be the best fit for every household, especially those with smaller estates or fewer assets. It’s essential for families to assess their unique needs and circumstances before moving forward. Bright Advisers encourages families to evaluate their situations, just as they did with their clients, to find the best financial strategies that align with their goals. Remember, you’re not alone in this journey; we’re here for you every step of the way!
Conclusion
Creating a family LLC is a meaningful step toward securing your family’s financial future and ensuring a smooth transfer of wealth across generations. This structure not only offers essential asset protection but also provides significant tax advantages, making it a valuable tool for young parents who want to safeguard their hard-earned resources.
Throughout this guide, we’ve explored various aspects of establishing a family LLC. From the step-by-step setup process to the benefits of asset protection and tax savings, we’ve highlighted the importance of educating children about financial responsibility. We also touched on potential challenges, such as costs and family dynamics, to ensure you’re well-informed before making this important decision.
Ultimately, creating a family LLC is more than just a financial strategy; it’s an investment in your family’s legacy and future. By taking the time to understand the intricacies of this structure, you can protect your wealth and foster a culture of financial literacy and responsibility among the next generation. Imagine the peace of mind that comes with knowing you’ve set your family up for success.
Embracing this opportunity can lead to a more secure and prosperous future for all family members. Remember, we’re here for you, and together, we can navigate this journey toward financial stability and growth.
Frequently Asked Questions
What is a Family LLC (FLLC)?
A Family LLC (FLLC) is a legal structure that allows family members to come together to manage and safeguard their shared resources, such as real estate, investments, or businesses.
What is the purpose of creating a Family LLC in estate planning?
The purpose of creating a Family LLC in estate planning is to protect a family’s future by ensuring a smooth transition of wealth across generations while minimizing tax burdens.
How does a Family LLC help in managing assets?
By placing assets into an FLLC, parents can retain control over these holdings while securing their children’s financial well-being and benefiting from valuation discounts that can reduce estate taxes.
What are the tax benefits of using a Family LLC?
A Family LLC can provide valuation discounts that lessen estate taxes when assets are inherited, and it allows families to freeze the growth of business interests, enabling older generations to transfer ownership while utilizing gift exclusions to avoid gift tax.
How does a Family LLC assist with the probate process?
A Family LLC can help avoid the complicated probate process, ensuring that assets transition smoothly to family members when the time comes.
Why is estate planning important for families?
Estate planning is important because it helps prevent financial hardship for loved ones, as statistics show that 31% of people believe poor estate planning can leave families without enough financial support.
How can Bright Advisers assist families with creating a Family LLC?
Bright Advisers provides guidance through the complexities of wealth management, offering personalized financial planning, tax optimization strategies, and innovative investment approaches to help families preserve their wealth and legacy.
List of Sources
- Define Family LLC and Its Purpose in Estate Planning
- Using a family LLC for estate planning (https://thetaxadviser.com/issues/2021/jun/family-llc-estate-planning)
- What is a Family LLC? (https://yourestateally.com/what-is-a-family-llc)
- 50 Estate Planning Statistics and Facts You Need to Know (https://justvanilla.com/blog/estate-planning-statistics-and-facts-you-need-to-know)
- Establish Your Family LLC: Step-by-Step Setup Guide
- How to Create a Family LLC for Estate Planning (https://justvanilla.com/blog/how-to-create-a-family-llc-for-estate-planning)
- How to Form a Family LLC (https://legalzoom.com/articles/how-to-form-a-family-llc)
- 3 Steps to Establish an Investment LLC for Family Success – Bright Advisers (https://brightadvisers.com/3-steps-to-establish-an-investment-llc-for-family-success)
- How Much Does It Cost to Start an LLC? (https://nolo.com/legal-encyclopedia/how-much-does-it-cost-to-form-an-llc.html)
- Family LLC for Estate Planning | ZenBusiness (https://zenbusiness.com/family-llc-estate-planning)
- Explore the Benefits of a Family LLC for Young Families
- The Ultimate Guide to a Family Limited Liability Company (https://commonsllc.com/insights/family-limited-liability-company)
- Own a Valuable Business? Consider a Family LLC | The Khalsa Law Firm, P.C. (https://khalsalaw.com/2024/12/01/own-a-valuable-business-consider-a-family-llc)
- PwC’s 2023 US Family Business Survey (https://pwc.com/us/en/services/audit-assurance/private-company-services/library/family-business-survey.html)
- Asset Protection Planning Facts (https://assetprotectionplanners.com/planning/facts)
- Assess the Downsides and Considerations of a Family LLC
- How to Create a Family LLC for Estate Planning (https://justvanilla.com/blog/how-to-create-a-family-llc-for-estate-planning)
- How to Start an LLC for Estate Planning (https://legalzoom.com/articles/start-an-llc-for-estate-planning)
- The Benefits of Including an LLC as Part of Your Estate Plan (https://elderlawanswers.com/the-benefits-of-including-an-llc-as-part-of-your-estate-plan-18532)
- Family Trust vs LLC: Key Benefits and Drawbacks for Young Families – Bright Advisers (https://brightadvisers.com/family-trust-vs-llc-key-benefits-and-drawbacks-for-young-families)
- LLC cost by state – How much does an LLC cost? 2025 | LLCU® (https://llcuniversity.com/llc-filing-fees-by-state)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About Kevin