

Key Highlights
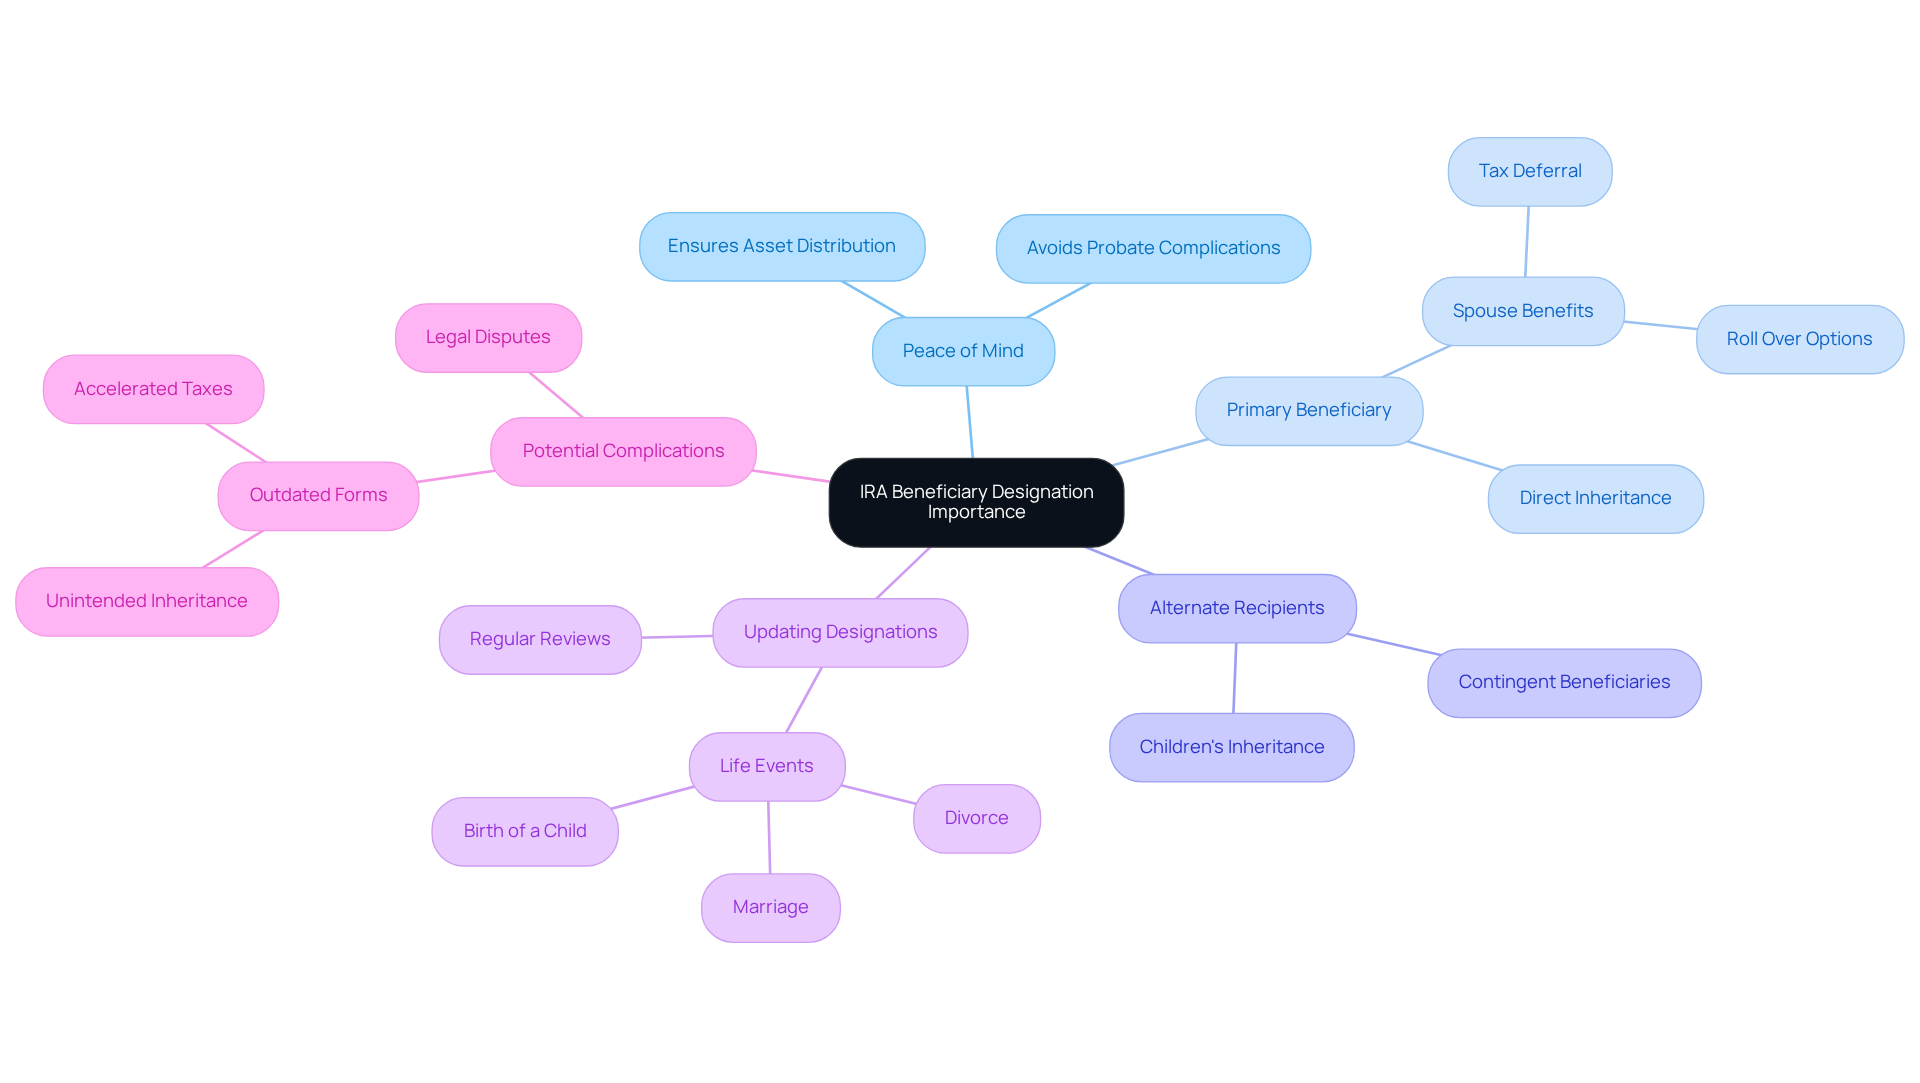
- Designating an IRA primary beneficiary ensures assets are transferred according to your wishes, avoiding probate complications.
- Naming a spouse as the primary beneficiary allows for tax-efficient management of the IRA.
- Updating beneficiary designations is crucial after life events like marriage, divorce, or the birth of a child to prevent unintended consequences.
- Neglecting to designate alternate recipients can lead to conflicts among heirs and increased legal expenses.
- Consider setting up a trust for minor children to manage IRA funds until they reach adulthood.
- Communicating with beneficiaries about their designations can prevent confusion and ensure clarity in asset distribution.
- Regularly reviewing beneficiary designations, at least annually, helps maintain alignment with family dynamics and financial goals.
- Consulting with a financial advisor can provide insights into effective estate planning and necessary updates.
Introduction
Imagine the peace of mind that comes from knowing your family’s financial future is secure, starting with the right choice for your IRA beneficiary. Choosing a primary beneficiary for an Individual Retirement Account (IRA) is a pivotal decision that can significantly impact your family’s financial future. This essential step in estate planning ensures that your assets are distributed according to your wishes, helping to avoid the complications of probate.
Imagine the stress of your loved ones facing unexpected challenges because of outdated beneficiary designations. This oversight can lead to delays in accessing funds and increased tax liabilities, leaving your family in a difficult position during tough times.
Together, we can navigate this journey to secure your legacy and protect your family’s financial well-being.
Understand the Importance of IRA Beneficiary Designation
Imagine the peace of mind that comes from knowing your loved ones are taken care of, even after you’re gone. Choosing an IRA primary beneficiary for your Individual Retirement Account (IRA) is a crucial step in estate planning. This designation ensures that your assets are transferred according to your wishes upon your death, avoiding unnecessary complications. Without a specified recipient, your IRA may be subject to probate, which can delay asset distribution and potentially lead to higher taxes.
Designating an heir facilitates a smoother transition of wealth, especially for families with young children. For instance, if you name your spouse as the primary recipient, they can inherit the IRA without immediate tax consequences, enabling more efficient management of the funds. Furthermore, designating alternate recipients, such as your children, helps ensure that your assets are transferred to them if your main heir is unable to inherit.
Many families overlook the importance of updating their IRA recipients, which can lead to unexpected challenges during difficult times. Outdated forms can result in unintended consequences, such as an ex-spouse inheriting IRA assets or assets defaulting to the estate, triggering probate involvement and accelerated tax payouts. Consistently reviewing and updating designation forms is crucial, especially following significant life events such as marriage, divorce, or the arrival of a child.
Case studies emphasize the potential complications arising from incorrect recipient designations. For example, neglecting to designate contingent recipients can result in conflicts among heirs and avoidable legal expenses. Furthermore, California’s community property regulations render these errors especially harmful, highlighting the necessity for thorough evaluation when selecting recipients.
By taking the time to review your IRA primary beneficiary designations, you’re not just planning for the future; you’re also protecting your family’s legacy and ensuring their financial security.
Follow the Steps to Designate Your Primary Beneficiary
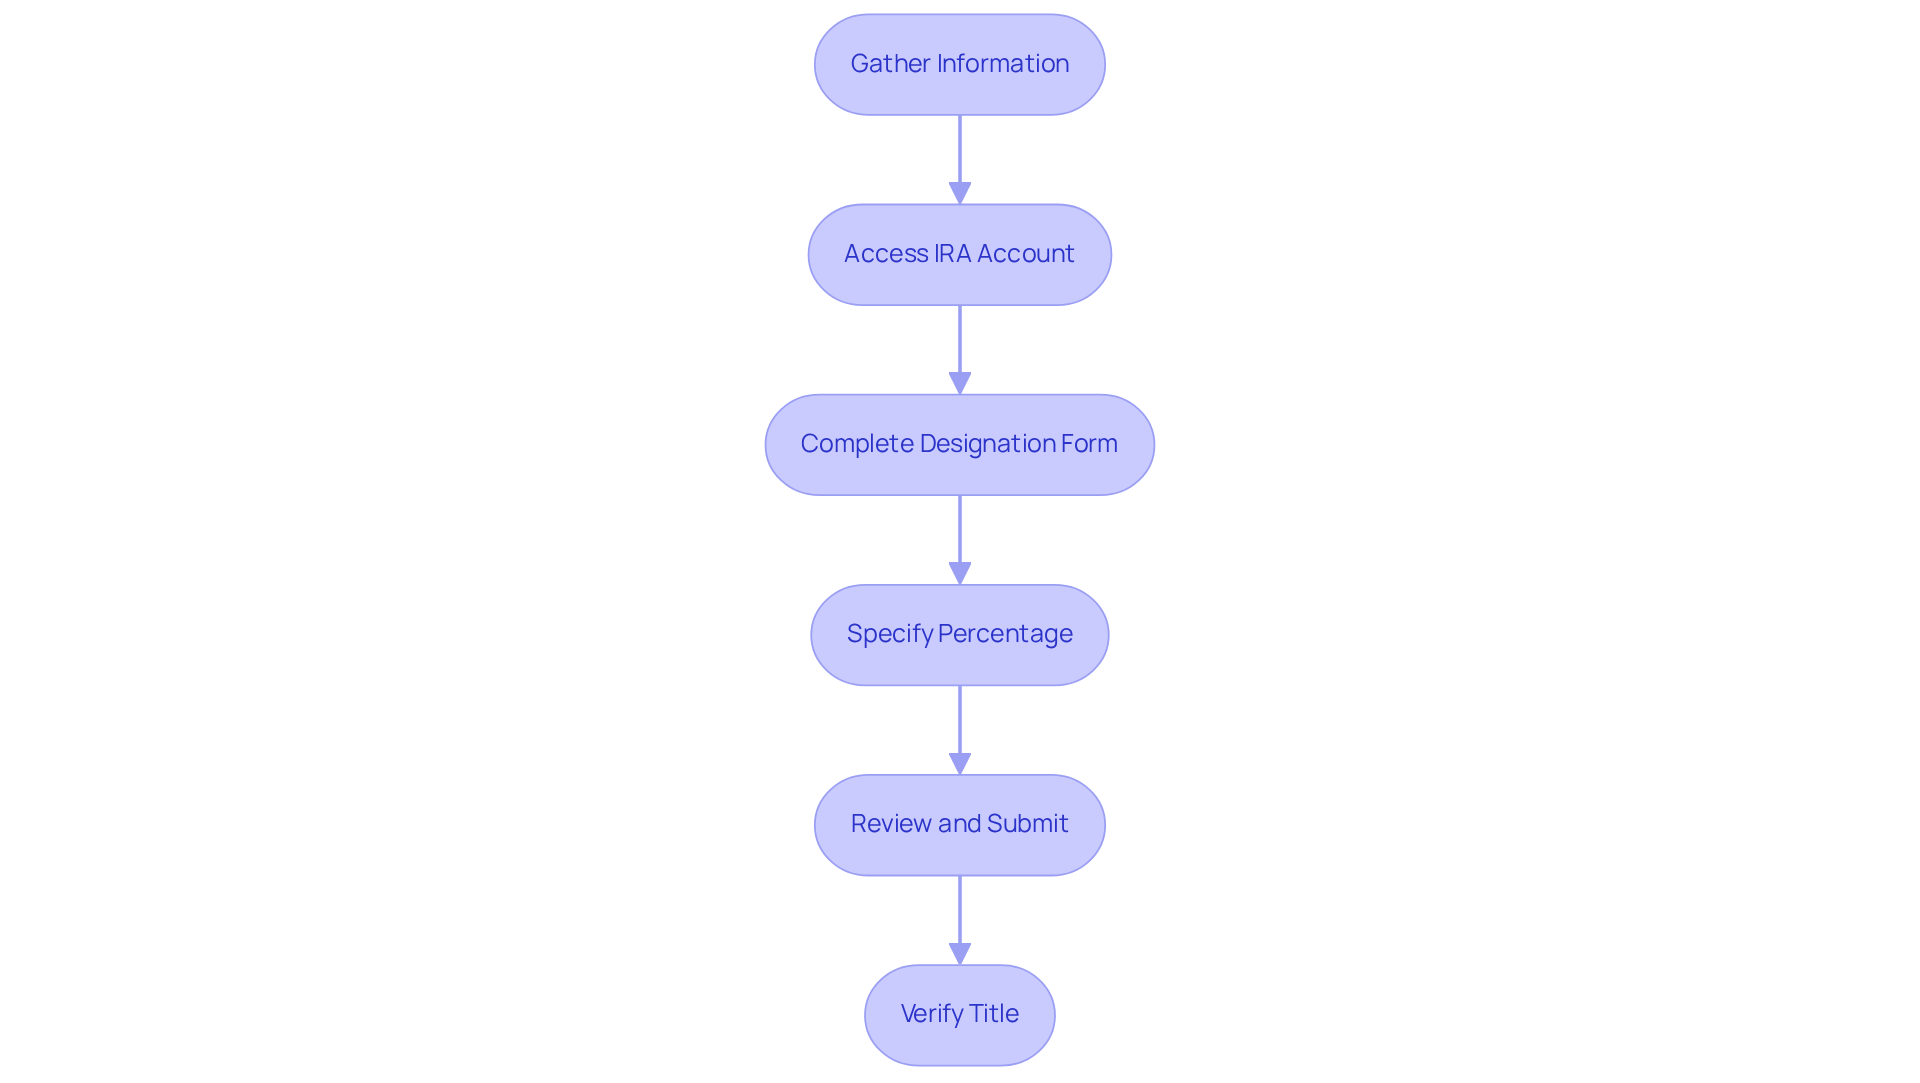
Imagine the peace of mind that comes from knowing your family’s financial future is secure. Designating your primary beneficiary for your IRA involves several straightforward steps:
- Start by gathering the information you’ll need: Collect your IRA account number and the name of the financial institution managing your IRA. This will make the process smoother.
- Access your IRA account: Log into your online account or reach out to your financial institution to get the designation form. Many institutions allow you to complete this process online, making it convenient for you.
- Complete the beneficiary designation form: Fill out the form with the required information. You’ll need to provide the full name, date of birth, and Social Security number of your main recipient. If you wish to name alternate recipients, include their information as well.
- Specify the percentage: If you’re naming multiple recipients, specify the percentage of the IRA each recipient will receive. Just make sure the total equals 100%.
- Review and submit: Double-check all information for accuracy. Submit the form as instructed, either online or via mail, depending on your financial institution’s requirements.
- Verify your title: After submitting, check with your financial institution to ensure that your recipient title has been processed. This step is crucial to ensure that your wishes are documented correctly.
Following these steps helps ensure that your IRA primary beneficiary receives your assets as you desire. This brings peace of mind for you and your family. Consistently examining and revising your recipient designations is crucial, especially after significant life changes. For instance, if a main recipient passes away before you, having alternate recipients designated ensures that your assets are still allocated according to your wishes. Additionally, naming a trust as a beneficiary can help manage the distribution of assets in accordance with your wishes, particularly for minor beneficiaries or specific needs. This proactive approach not only alleviates financial stress but also ensures your household’s future, aligning with the financial planning objectives that many young households, like Jay and Emma, aim to accomplish.
Taking these steps today can safeguard your family’s future, ensuring they are cared for even when you’re not there. Disclaimer: Past performance does not guarantee future results. Securities investments are subject to risk. Bright Advisers, founded by Kevin Luu and Kathleen Chou in 2010, offers tailored investment strategies, including factor investing and tax planning, to help families make wise wealth decisions. All advisory services are provided through Lifeworks Advisors, a registered investment adviser, ensuring transparency and compliance.
Navigate Common Scenarios and Considerations in Beneficiary Designation
Imagine wanting to secure your children’s future but feeling uncertain about how to navigate the complexities of designating an IRA primary beneficiary.
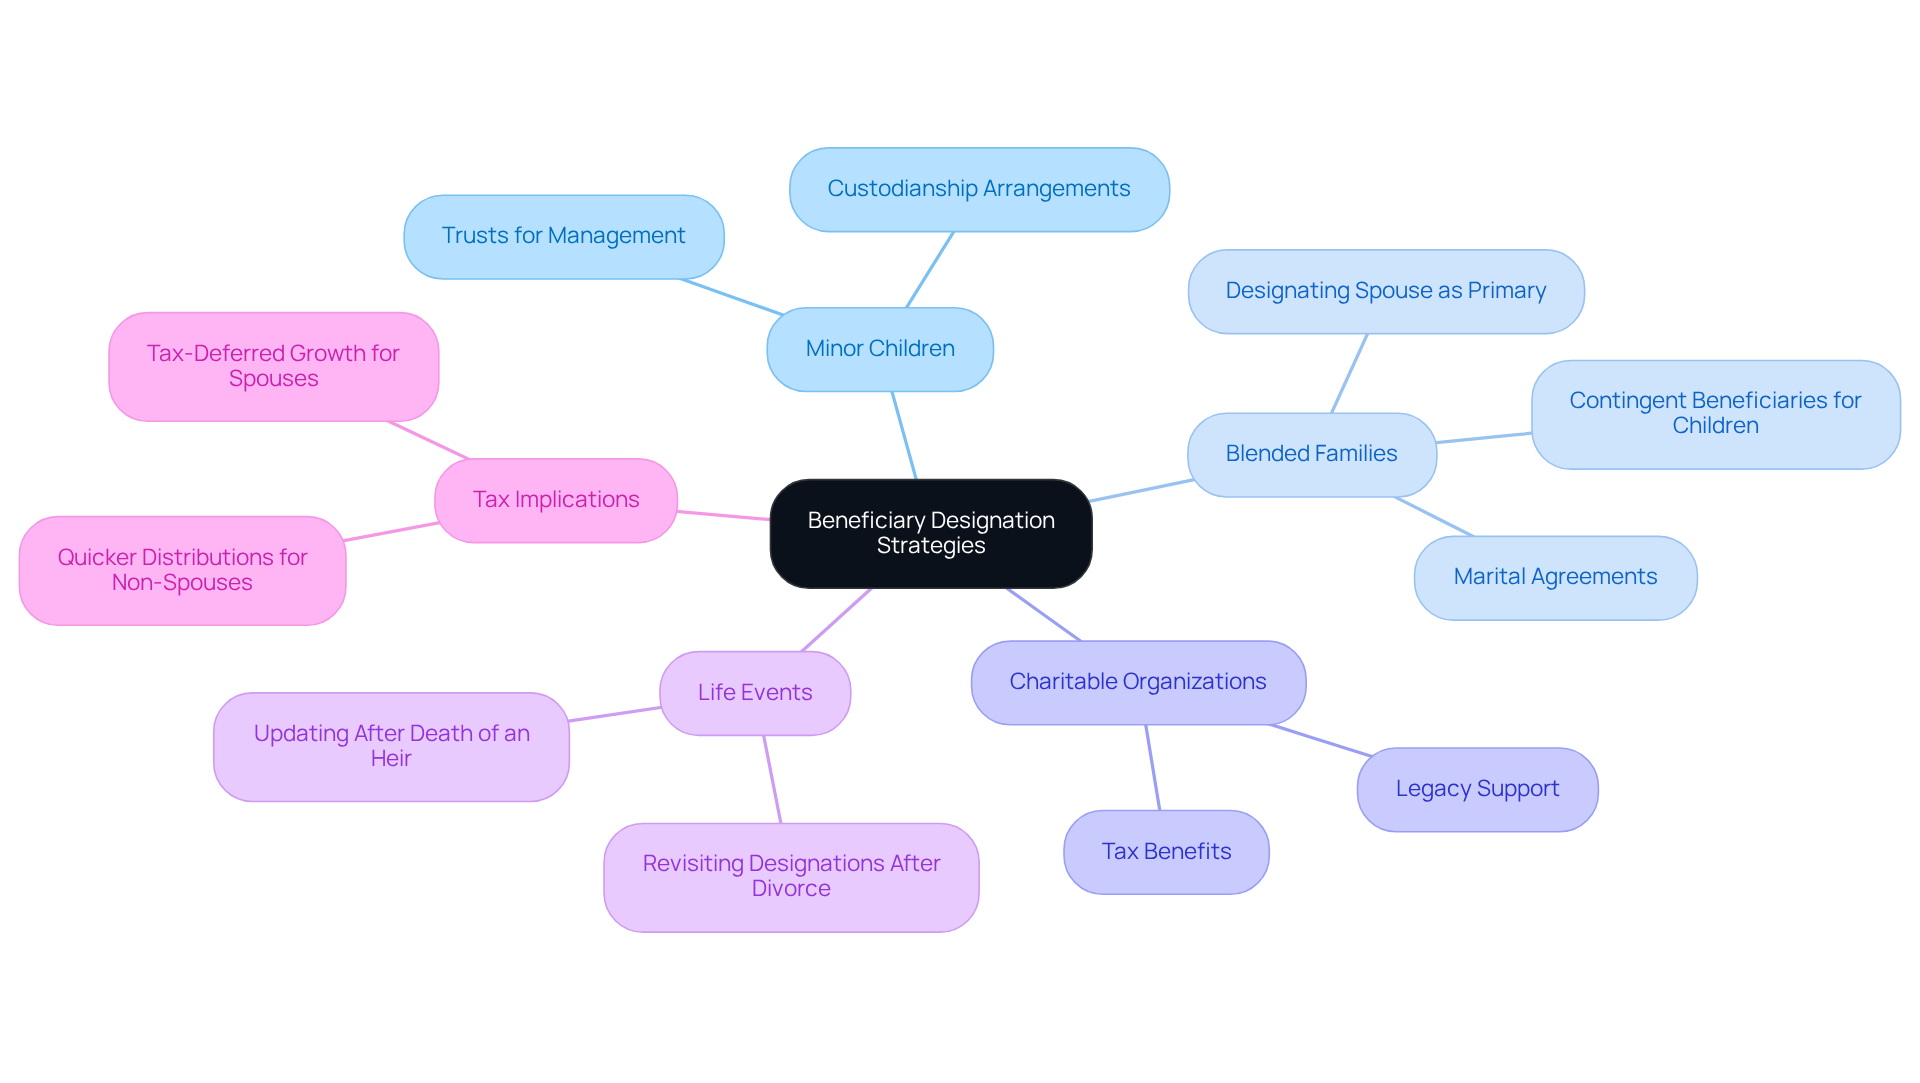
When it comes to naming minor children as beneficiaries, it can be challenging to think about how to secure your children’s future when they are not yet adults. Instead of directly inheriting an IRA, consider setting up a trust or naming a custodian to manage the funds until they reach adulthood. By taking this step, you can rest easy knowing your children will be taken care of when the time comes.
When families blend, it’s so important to talk openly with everyone involved. Designating your spouse as the primary recipient while naming your children from a previous relationship as contingent recipients ensures that all family members are considered in your estate planning. This strategy can help mitigate potential conflicts and ensure equitable treatment of all heirs.
Imagine being able to support a cause close to your heart while also leaving a lasting legacy. If you have a charitable organization in mind, you can designate it as a recipient. This not only allows you to leave a meaningful legacy but can also provide tax benefits, making it a strategic choice for those looking to support causes they care about.
Life occurrences like divorce or the passing of an heir can greatly influence your assignments. It’s essential to revisit your choices after significant life events to make sure they still reflect your family’s needs.
Different recipients may have varying tax consequences. For instance, naming a spouse can allow for tax-deferred growth, while naming a non-spouse may require quicker distributions. Understanding these implications is vital for making informed decisions that align with your financial goals.
By navigating these scenarios carefully, you can ensure that your allocations for the IRA primary beneficiary correspond with your loved ones’ needs and values, ultimately protecting your legacy and reducing potential conflicts.
Review and Update Your Beneficiary Designation Regularly
Have you ever thought about what happens to your IRA assets if your IRA primary beneficiary designations are outdated? To ensure your IRA beneficiary designations remain relevant and effective, adhere to the following guidelines for regular reviews, aligned with Bright Advisers’ mission to help families make wise wealth decisions:
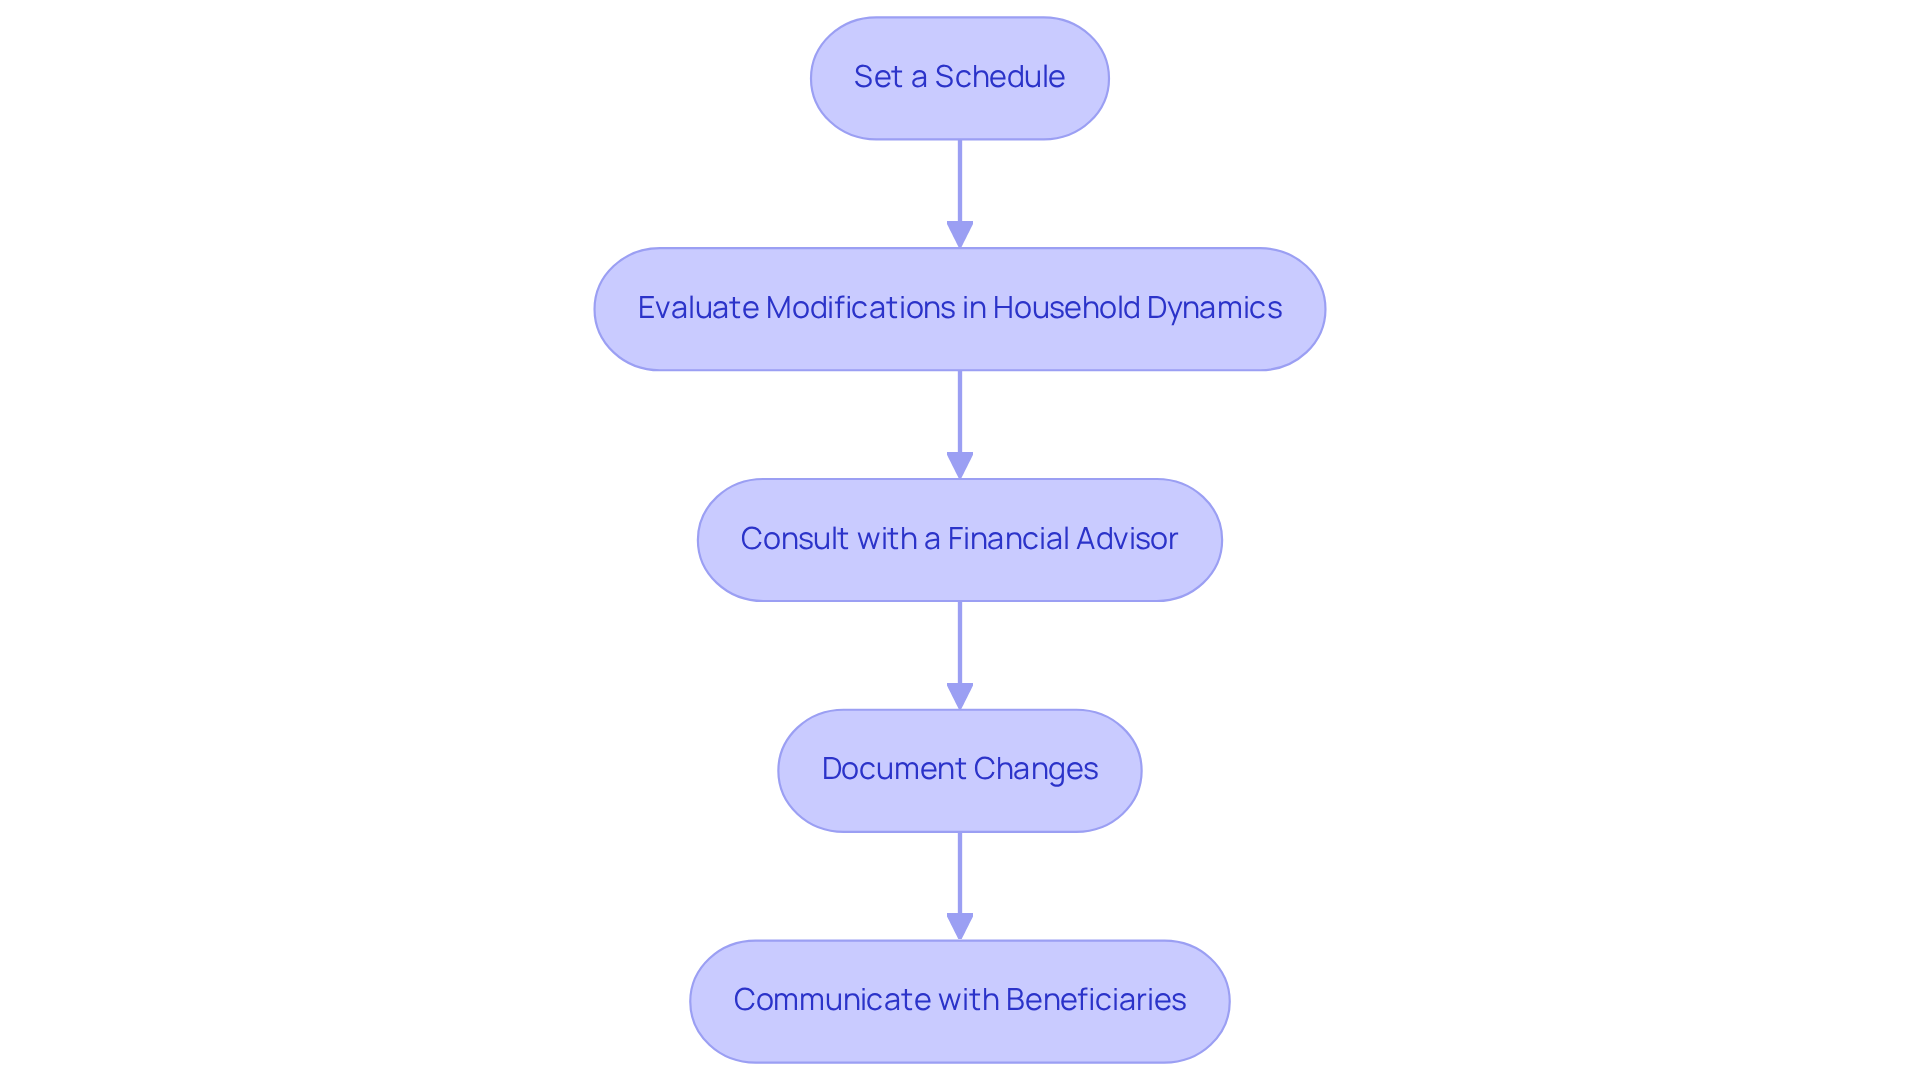
- Set a Schedule: Aim to review your recipient designations at least once a year. Additionally, consider revisiting them after significant life events, such as marriage, divorce, the birth of a child, or the passing of an heir. Imagine the stress and delays your loved ones might face if your IRA primary beneficiary designations are not updated.
- Evaluate Modifications in Household Dynamics: As your household evolves, your recipient assignments may require updates. For example, embracing a new child into your household may encourage you to include them as a recipient, ensuring that your allocations represent your present household arrangement. Neglecting to revise recipient assignments can result in unforeseen outcomes, such as estranged heirs obtaining assets, which may complicate estate planning. This oversight could lead to complications that your family simply doesn’t need during an already challenging time.
- Consult with a Financial Advisor: Engaging with a financial advisor, like those at Bright Advisers, can provide valuable insights into your estate planning. Advisors can assist in clarifying the implications of your titles and suggest necessary updates, ensuring your financial strategies align with your family’s needs. As Jeff Witz, a CFP, recommends, ‘Make the appropriate adjustments to your named recipients when necessary and review these yearly with your adviser to ensure that they stay current and are financially sensible.’
- Document Changes: Whenever you alter your recipient selections, record these modifications carefully. Keeping a record of the date and specifics of the updates is crucial for maintaining clarity in your estate planning.
- Communicate with Beneficiaries: Informing your beneficiaries about their designations is a good practice. This proactive communication can help prevent confusion and ensure that they understand your intentions regarding asset distribution.
By committing to regular reviews and updates, you can maintain control over your IRA assets, ensuring that the IRA primary beneficiary is designated according to your wishes. By taking these steps, you’re not just protecting your assets; you’re safeguarding your family’s future together. We’re here to ensure your financial planning is as clear and supportive as possible.
Conclusion
Imagine the peace of mind that comes from knowing your loved ones are taken care of after you’re gone. Designating a primary beneficiary for your IRA isn’t just a procedural task; it’s a vital step in ensuring that your family is supported when they need it most. This guide has shown how important it is to make thoughtful choices about who you want to support after you’re gone, emphasizing that a well-planned approach can prevent complications and ensure a smooth transition of wealth to your family.
Throughout this article, we’ve explored straightforward steps to designate a primary beneficiary, the significance of regularly reviewing and updating these designations, and the potential pitfalls of neglecting this crucial aspect of estate planning. Navigating the complexities of IRA beneficiary designations can feel overwhelming, especially when considering your family’s future. By understanding the implications of your choices, such as naming contingent beneficiaries and considering tax consequences, you can better navigate these challenges.
When you take the time to choose and review your IRA beneficiaries, you’re investing in your family’s peace of mind. It not only protects your legacy but also provides reassurance, knowing that your loved ones will be supported according to your wishes. Engaging with a fiduciary advisor, like those at Bright Advisers, can further enhance your planning process, ensuring that your financial strategies align with your family’s needs. Prioritize this essential task today to secure a brighter tomorrow for your family, knowing that taking this step means your family can focus on healing and cherishing memories, rather than dealing with financial uncertainties.
Frequently Asked Questions
Why is it important to designate a beneficiary for my IRA?
Designating a beneficiary for your IRA ensures that your assets are transferred according to your wishes upon your death, avoiding complications such as probate, which can delay distribution and increase taxes.
What happens if I do not designate a beneficiary for my IRA?
Without a specified recipient, your IRA may be subject to probate, leading to delays in asset distribution and potentially higher taxes.
How does naming a spouse as the primary beneficiary affect tax consequences?
If you name your spouse as the primary beneficiary, they can inherit the IRA without immediate tax consequences, allowing for more efficient management of the funds.
Why should I consider designating alternate beneficiaries?
Designating alternate beneficiaries, such as your children, ensures that your assets are transferred to them if your primary heir is unable to inherit.
What are the risks of not updating my IRA beneficiary designations?
Failing to update your IRA beneficiary designations can lead to unintended consequences, such as an ex-spouse inheriting assets or assets defaulting to the estate, which can trigger probate and accelerate tax payouts.
When should I review and update my IRA beneficiary designations?
You should consistently review and update your beneficiary designations, especially after significant life events such as marriage, divorce, or the arrival of a child.
What complications can arise from incorrect beneficiary designations?
Incorrect beneficiary designations can lead to conflicts among heirs, avoidable legal expenses, and issues related to California’s community property regulations, making thorough evaluation essential.
How does reviewing my IRA beneficiary designations protect my family’s legacy?
By reviewing your IRA beneficiary designations, you ensure that your family’s financial security is maintained and that your legacy is preserved according to your wishes.
List of Sources
- Understand the Importance of IRA Beneficiary Designation
- How Outdated IRA Beneficiaries Can Derail Your Estate Plan | Botti & Morison Estate Planning Attorneys (https://bottilaw.com/news/how-outdated-ira-beneficiaries-can-derail-your-estate-plan)
- The Importance of Updating IRA Beneficiaries (https://apcifcu.org/blog/the-importance-of-updating-ira-beneficiaries)
- Importance of Retirement Plan Beneficiary Designations for Estate Planning – PK Law (https://pklaw.com/articles/importance-of-retirement-plan-beneficiary-designations-for-estate-planning)
- Follow the Steps to Designate Your Primary Beneficiary
- Naming IRA Beneficiary: What You Need to Know – Equity Trust (https://trustetc.com/blog/whats-possible-when-naming-ira-beneficiary)
- IRAs and Beneficiary Distributions: SECURE Act Changes Distribution Requirements for Some Individuals (https://wolterskluwer.com/en/expert-insights/secure-act-changes-distribution-requirements-for-some-individuals)
- Retirement topics – Beneficiary | Internal Revenue Service (https://irs.gov/retirement-plans/plan-participant-employee/retirement-topics-beneficiary)
- Understanding Your IRA Beneficiary Designations | Capitol Federal® (https://capfed.com/about-capfed/news/ira-beneficiary-designations)
- Navigate Common Scenarios and Considerations in Beneficiary Designation
- Estate Planning for Blended Families: Preserving Generational Wealth (https://wealthgenadvisor.com/estate-planning-for-blended-families-preserving-generational-wealth)
- Navigating Estate Planning for Blended Families (https://financialplanningassociation.org/article/journal/JAN22-navigating-estate-planning-blended-families-OPEN)
- Hidden Pitfalls Of Naming A Minor As An IRA Beneficiary (https://abramslaw.com/media/thought-leadership/hidden-pitfalls-of-naming-a-minor-as-an-ira-beneficiary)
- Planning for the Young Under SECURE | Minor Inherited IRA (https://actecfoundation.org/podcasts/secure-act-young-minor-inherited-ira)
- Estate Planning Questions For Blended Families (https://estateplanning.com/blended-family-estate-planning-questions)
- Review and Update Your Beneficiary Designation Regularly
- How often should beneficiaries be reviewed? | Urology Times (https://urologytimes.com/view/how-often-should-beneficiaries-be-reviewed)
- Beneficiary Designation: How to Choose a Beneficiary (https://merrilledge.com/article/beneficiary-designation)
- Family Wealth Quotes by James E. Hughes (https://goodreads.com/work/quotes/40026765-family-wealth-keeping-it-in-the-family–how-family-members-and-their-ad)
- Are Your Beneficiary Designations Up to Date? – The Goff Financial Group (https://gofffinancial.com/financial-advisor/are-your-beneficiary-designations-up-to-date)
- 85 Family Legacy Quotes: Wisdom to preserve and pass down (https://evaheld.com/blog/family-legacy-quotes-for-you-to-follow)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Estate Planning for high-income W-2 families at Bright Advisers.
Keep reading