

Overview
Navigating your Employee Stock Purchase Plan (ESPP) can feel overwhelming, but we’re here to help you understand it better. By taking a step-by-step approach, you can determine if your ESPP is post-tax. Start by reviewing your plan documentation and confirming that contributions are made with after-tax dollars. It’s also crucial to understand the tax implications of holding periods and plan qualifications.
Imagine if knowing the nature of your ESPP could significantly impact your tax outcomes. Understanding this can help you make informed financial decisions that optimize your benefits, especially regarding capital gains tax rates. Together, we can navigate this journey and ensure that your family’s financial future is secure.
Remember, you’re not alone in this process. We’re here for you, providing the support you need to make the best choices for your family. Understanding your ESPP is a vital step toward achieving your financial goals and ensuring your loved ones are taken care of.
Key Highlights:
- An Employee Stock Purchase Plan (ESPP) allows employees to buy company stock at a discounted rate using after-tax payroll deductions.
- Tax implications vary based on the holding period of shares and whether the ESPP is qualified or non-qualified, affecting potential capital gains tax rates.
- Employees can optimize tax outcomes by understanding qualifying vs. disqualifying dispositions and meeting holding period requirements.
- Average discount rates for ESPPs are competitive, but employees must stay informed about potential tax law changes that could affect benefits.
- Key steps to assess ESPP tax status include reviewing plan documentation, identifying contribution methods, and consulting tax professionals.
- Maintaining accurate records of ESPP transactions is crucial for tax reporting and compliance with IRS regulations.
- 65% of publicly-traded companies with ESPPs report low participation rates among eligible employees, highlighting the need for greater awareness.
Introduction
Navigating the intricacies of Employee Stock Purchase Plans (ESPPs) can feel overwhelming for many employees eager to take advantage of their company’s stock offerings. Imagine being able to acquire shares at a discounted rate—what a wonderful opportunity! However, it’s essential to recognize that these plans come with a complex web of tax implications that can significantly impact your financial journey.
As you consider participating in ESPPs, understanding the nuances of tax treatment becomes crucial. It’s important to grasp the distinction between qualified and non-qualified plans, the significance of holding periods, and how market conditions can affect your outcomes. This article gently delves into the essential factors that influence the tax status of ESPPs.
Together, we can explore valuable insights that empower you to make informed financial decisions aligned with your long-term goals. Remember, you’re not alone in this journey; we’re here to support you every step of the way.
Understand Employee Stock Purchase Plans (ESPPs) and Tax Implications
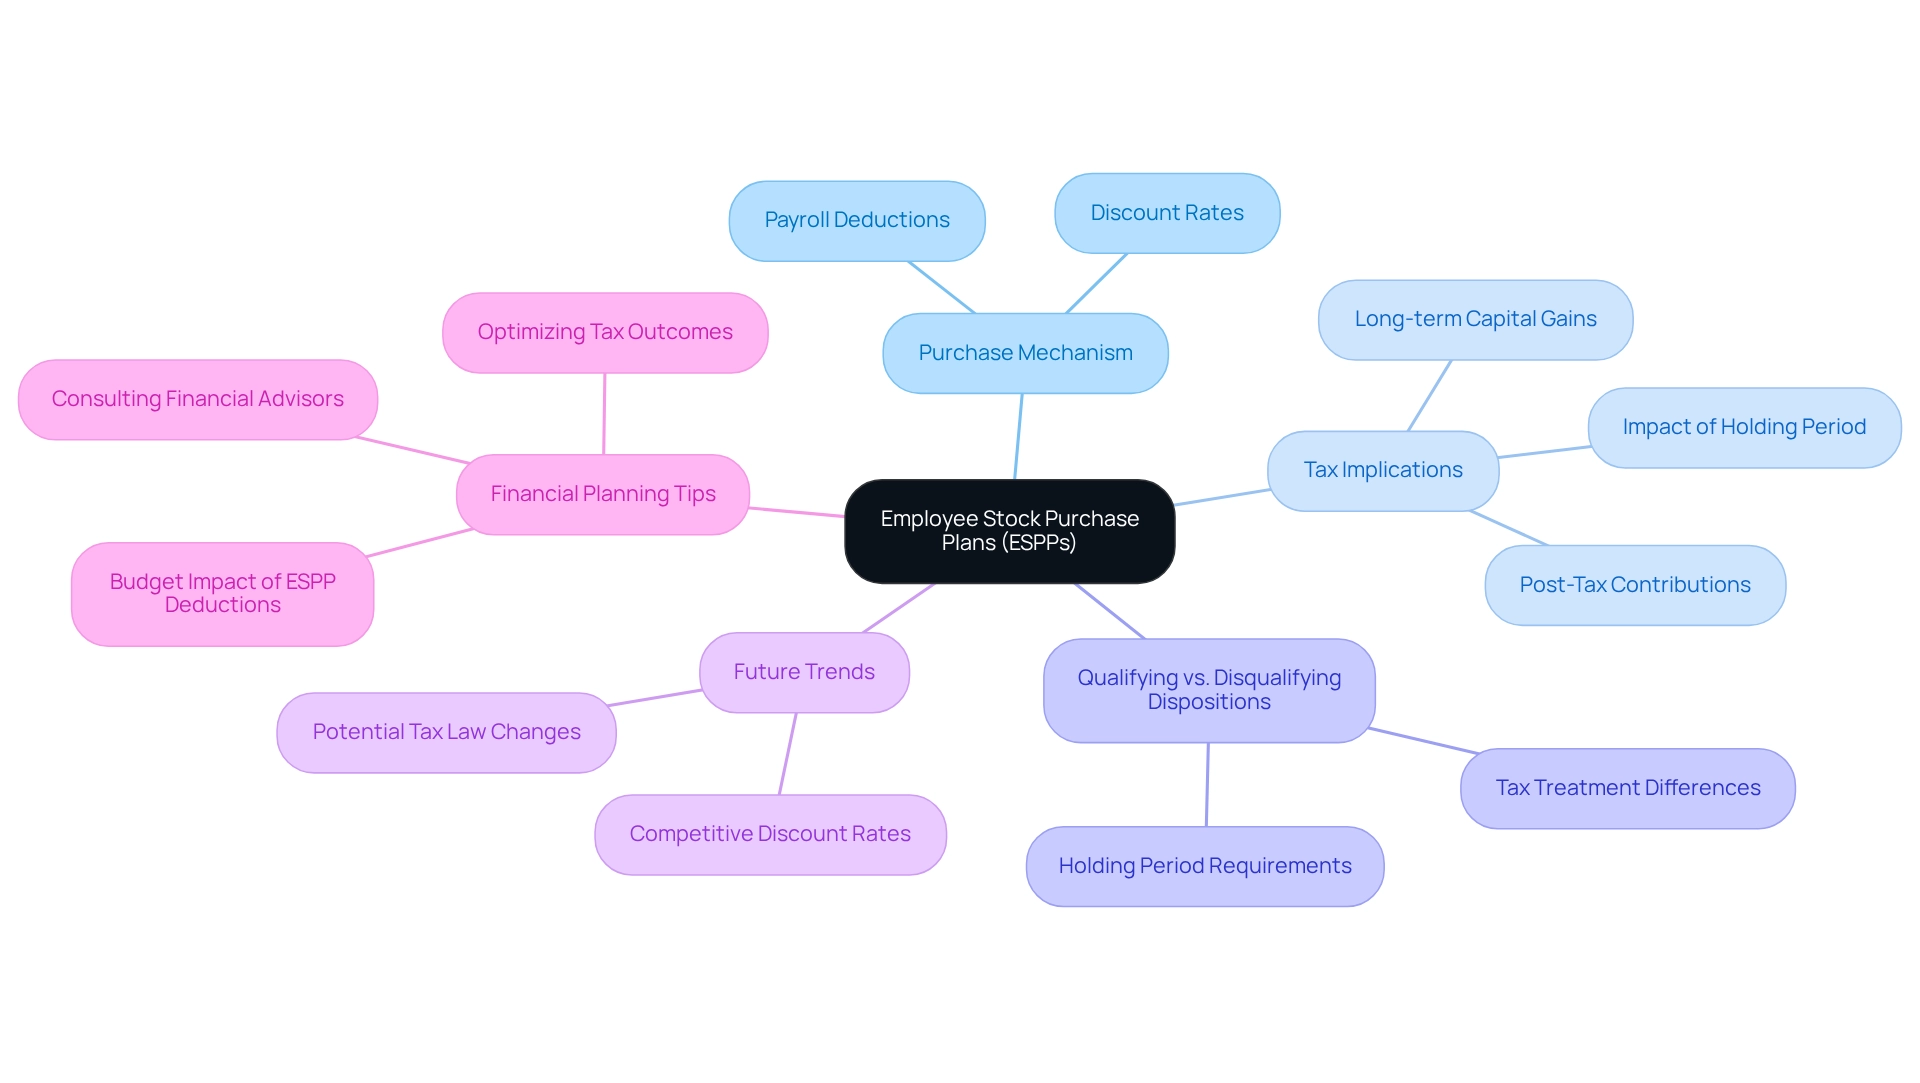
An Employee Stock Purchase Program (ESPP) is a wonderful opportunity for employees to acquire shares of their employer’s stock at a reduced price, often facilitated through payroll deductions. Understanding the tax implications of ESPPs is crucial for effective financial planning, especially since contributions are made with after-tax funds, which means it is ESPP post-tax and taxes are deducted from your paycheck before the contributions are made. When it comes to selling these assets, tax treatment can vary significantly based on how long you hold the shares and whether the ESPP meets IRS requirements. If the plan qualifies, employees may benefit from favorable tax treatment, such as long-term capital gains rates on any appreciation beyond the purchase discount. This can lead to meaningful tax savings, especially for those who hold their shares for the necessary period.
Imagine a scenario where understanding the differences between qualifying and disqualifying dispositions can make a real difference. Employees who meet the holding period requirements can optimize their tax outcomes and investment strategies, highlighting the importance of being aware of the plan’s rules. This is particularly relevant for young families like Jay and Emma, who are eager to alleviate financial stress and make the most of their resources.
As we look ahead to 2025, average discount rates offered in ESPPs remain competitive, reflecting a growing trend among employees who wish to utilize these plans for wealth accumulation. However, it’s essential to stay informed about potential changes in tax laws, as these can impact the overall benefits of participating in an employee stock purchase plan, which is ESPP post-tax. Consulting with a financial advisor, such as those at Bright Advisers, can provide tailored insights into how after-tax contributions and ESPP participation can fit into your broader financial strategy. This personalized planning has helped families like Emily and Mark achieve their financial dreams.
By familiarizing yourself with these aspects, including the specific financial strategies that can help optimize tax outcomes, you can better assess the potential advantages and disadvantages of engaging in an employee stock purchase plan. Together, we can ensure that your financial decisions align with your family’s long-term goals and aspirations. Remember, we’re here for you on this journey.
Identify Criteria for Post-Tax Classification of Your ESPP
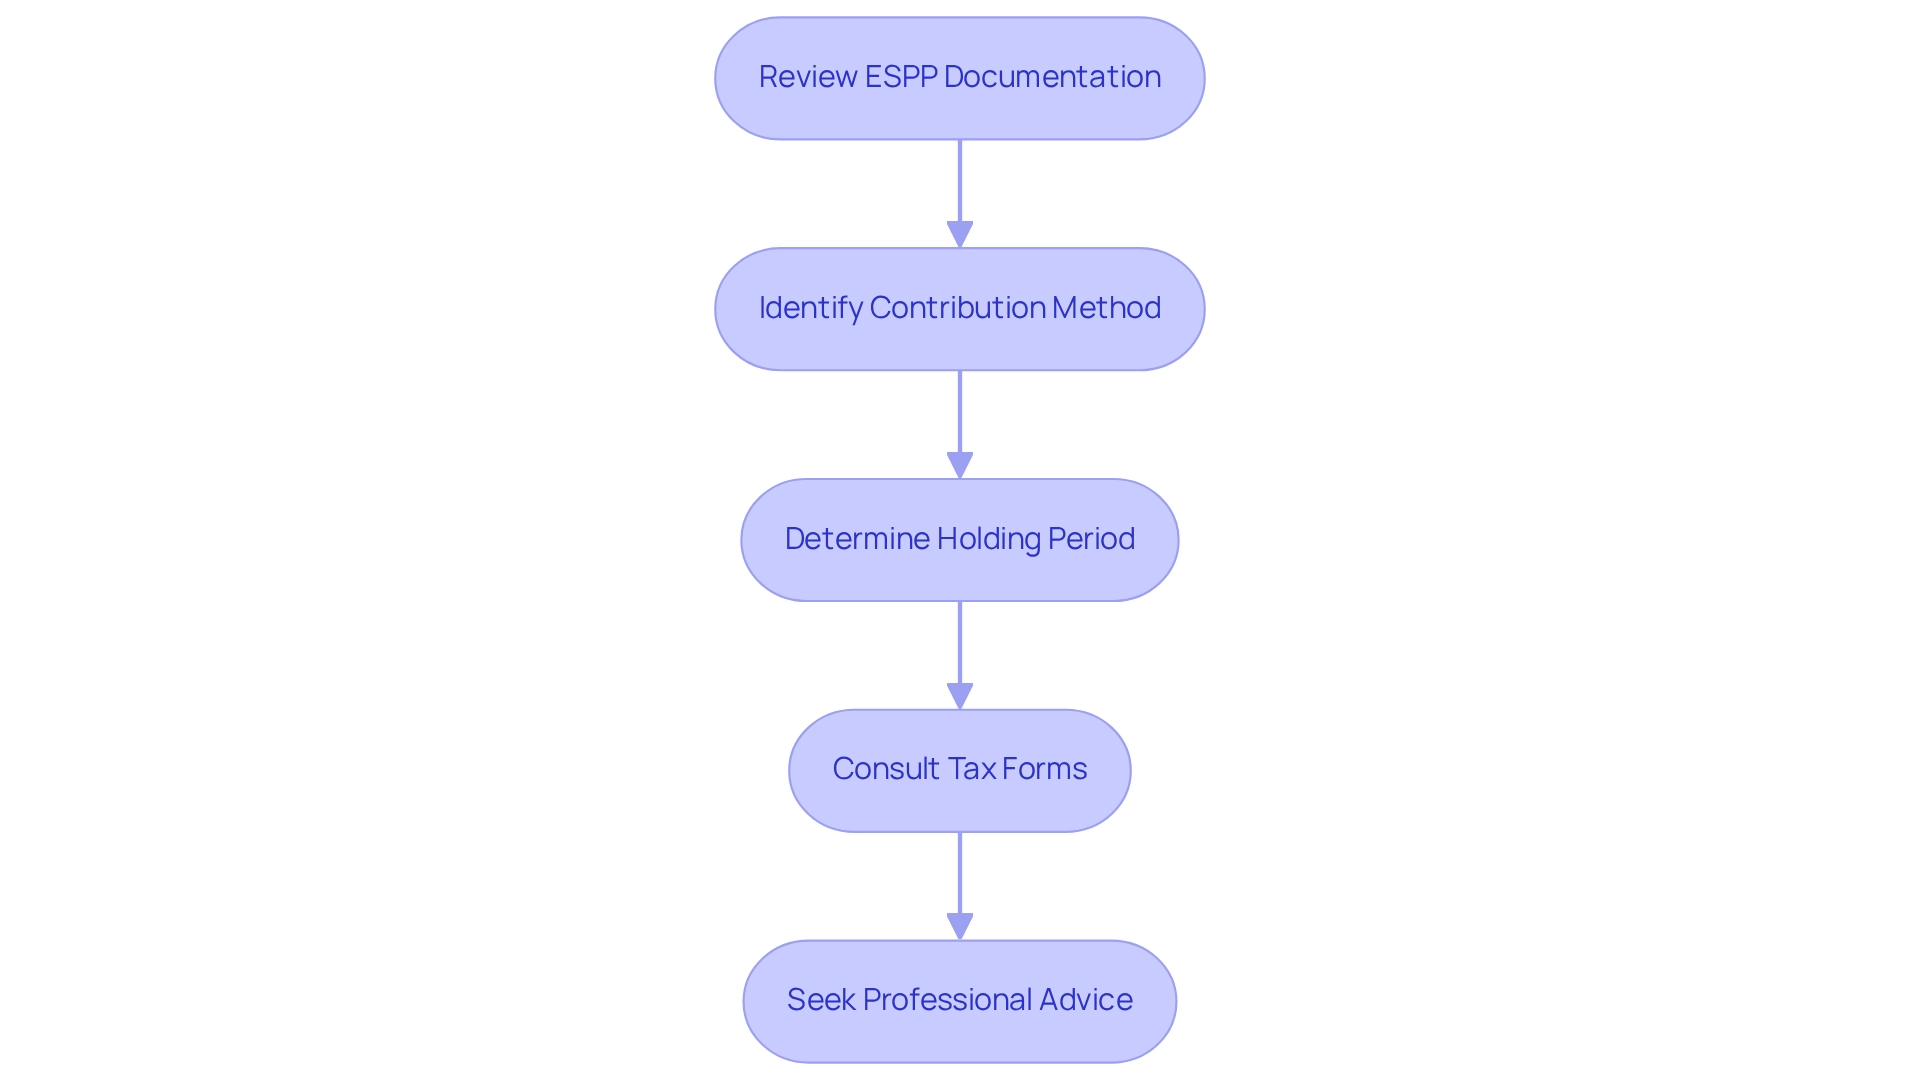
To accurately assess the tax status of your Employee Stock Purchase Plan (ESPP), follow these essential steps:
-
Review Your Employee Stock Purchase Plan Documentation: Begin by thoroughly examining the plan documents provided by your employer. Pay close attention to whether the ESPP is classified as qualified or non-qualified, as this distinction will significantly influence your tax treatment.
-
Identify Contribution Method: Ensure that your contributions, which is espp post tax, are made with after-tax dollars. This trait is essential to ESPPs and directly influences how is espp post tax will affect you when selling the stocks.
-
Determine Holding Period: Evaluate your intended holding duration for the stocks post-purchase. Selling within one year may expose you to short-term capital gains tax, which is typically higher than the long-term capital gains tax relevant to assets held longer. For instance, in a Qualifying Disposition, $1.50 per unit of gain would be taxed as Ordinary Income, while $4.00 per unit would be taxed at favorable long-term capital gains rates.
-
Consult Tax Forms: Upon selling your employee stock purchase plan shares, you will receive important tax forms, such as Form 3922. This form contains crucial information for accurately reporting your income and calculating any capital gains or losses. As George Dimov, President & Managing Owner, mentions, “When you sell your employee stock purchase plan shares, your broker will report the sale on Form 1099-B.”
-
Seek Professional Advice: If you have any uncertainties regarding your findings, consider consulting a tax professional. Their expertise can provide tailored guidance based on your unique financial situation.
Comprehending the tax consequences of your employee stock purchase plan is essential, particularly since many workers lack clarity on these issues. In fact, recent statistics indicate that a significant portion of employees are unaware of how their employee stock purchase plan contributions affect their tax obligations. Furthermore, it’s crucial to recognize IRS limits on employee stock purchase plan contributions, which cap purchases at $25,000 worth of stock value each year under Section 423 plans. By following these steps, you can avoid common mistakes, such as misunderstanding your contribution limits, and ensure compliance with IRS regulations. This proactive approach will empower you to make informed decisions about your financial future.
Evaluate Your ESPP: Steps to Determine Tax Status
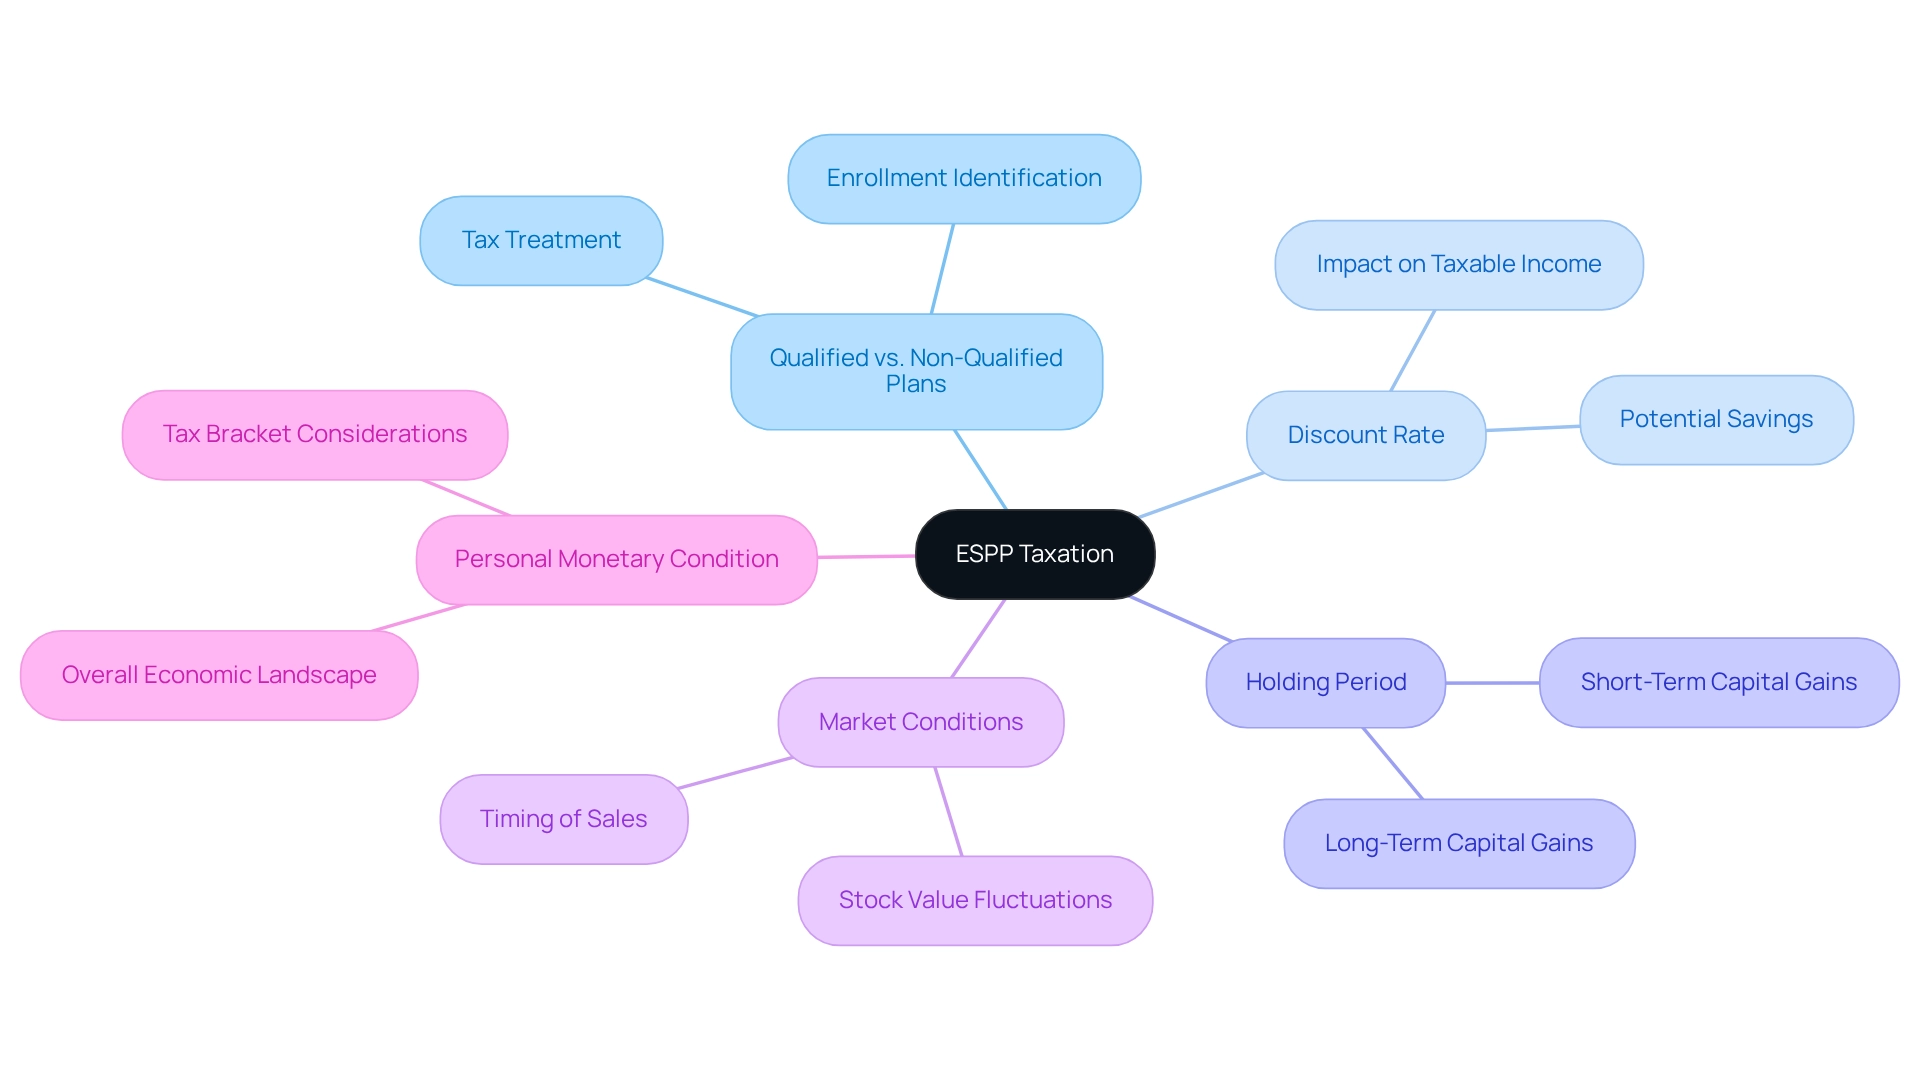
Several critical factors and scenarios influence the taxation of your Employee Stock Purchase Plan (ESPP), particularly what is espp post tax, and understanding them can empower you to make informed decisions for your family’s future.
-
Qualified vs. Non-Qualified Plans: Imagine if you could benefit from lower tax rates on gains. Qualified ESPPs offer this favorable tax treatment, while non-qualified plans do not. Identifying which type you are enrolled in, specifically whether it is espp post tax, is essential for effective tax planning.
-
Discount Rate: Consider the discount at which stocks are acquired. This reduction can significantly influence your taxable income. When you sell these stocks, the discount may be taxed as regular income, impacting your overall tax obligation.
-
Holding Period: Think about how long you plan to retain your stocks before selling them. Holding stocks for more than one year typically qualifies you for long-term capital gains tax rates, which are usually lower than short-term rates.
-
Market Conditions: The stock market can be unpredictable, affecting the value of your shares at the time of sale. By understanding market trends, you can make informed decisions about when to sell, ultimately benefiting your family’s financial health.
-
Personal Monetary Condition: Your overall economic landscape, including other income sources and tax brackets, plays a vital role in how ESPP taxation impacts your obligations. It’s important to consider how your employee stock purchase plan, which is espp post tax, fits into your broader monetary strategy, ensuring you’re making choices that align with your family’s goals.
The case of Allison and Brian, who worked with Bright Advisers, illustrates the importance of strategic tax planning. They enhanced their tax circumstances and secured their children’s future through education funding by understanding the consequences of their financial choices, including their employee stock purchase plan. This emphasizes the importance of being proactive in managing your tax responsibilities and recognizing the economic opportunities that may be overlooked without sufficient planning.
Additionally, it’s noteworthy that 65% of publicly-traded companies offering ESPPs report that less than half of eligible employees actively participate. This underscores the need for awareness and understanding of these plans, particularly regarding how is espp post tax can be a valuable tool for your family’s financial journey.
Maintaining accurate records of your ESPP transactions, such as purchase and sale dates and prices, is essential for tax reporting and preventing double taxation. Good record-keeping practices empower you to manage your tax obligations effectively and ensure compliance. As George Dimov, President & Managing Owner, wisely advises, “Always consider your overall financial picture and don’t hesitate to consult with a tax professional for personalized advice.”
Please remember that the material provided is for informational purposes only and should not be considered as investment or tax advice. Together, we can navigate this journey, ensuring you’re equipped with the knowledge to make the best decisions for your family.
Conclusion
Understanding the intricacies of Employee Stock Purchase Plans (ESPPs) is essential for employees who want to make the most of their company’s stock offerings. Imagine being able to navigate the complex tax implications that come with these plans simply by recognizing the differences between qualified and non-qualified options. Key factors like contribution methods, holding periods, and market conditions can significantly influence the tax treatment of ESPP shares, ultimately impacting your financial outcomes.
It’s important to engage proactively with ESPP documentation, consult tax professionals, and maintain accurate records. These critical steps ensure compliance and help optimize your tax strategies. This awareness empowers you to make informed decisions that align with your financial goals, especially as we see competitive discount rates and growing participation trends in 2025.
In conclusion, participating in an ESPP can be a powerful tool for wealth accumulation. However, it requires a thorough understanding of the associated tax implications and strategic planning. By staying informed and seeking tailored advice, you can navigate your financial journey with confidence, turning potential challenges into opportunities for growth and stability. Remember, we’re here for you—together, we can navigate this journey.
Frequently Asked Questions
What is an Employee Stock Purchase Program (ESPP)?
An ESPP is a program that allows employees to purchase shares of their employer’s stock at a discounted rate, often through payroll deductions.
How are contributions to an ESPP taxed?
Contributions to an ESPP are made with after-tax dollars, meaning taxes are deducted from your paycheck before you contribute.
What are the tax implications when selling stocks acquired through an ESPP?
The tax treatment of selling ESPP stocks can vary based on how long you hold them and whether the plan meets IRS guidelines. Favorable tax treatments, such as long-term capital gains rates, may apply if the plan qualifies.
What is the difference between qualifying and disqualifying dispositions?
Qualifying dispositions occur when stocks are held for a required period and meet IRS criteria, potentially leading to favorable tax treatment. Disqualifying dispositions do not meet these criteria and may result in higher taxes.
What trends are expected for ESPPs in 2025?
By 2025, average discount rates offered in ESPPs are expected to remain competitive, and participation rates are anticipated to increase as more employees look to benefit from these plans for wealth accumulation.
Why is it important to stay informed about changes in tax regulations regarding ESPPs?
Changes in tax regulations can impact the overall benefits of participating in an ESPP, making it essential for employees to stay informed to optimize their financial outcomes.
How can consulting a financial advisor help with ESPP participation?
A financial advisor can provide personalized insights into how after-tax contributions and participation in an ESPP can fit into an individual’s broader financial strategy.
List of Sources
- Understand Employee Stock Purchase Plans (ESPPs) and Tax Implications
- Employee Stock Purchase Plan (ESPP) Taxes: A Guide (https://schwab.com/learn/story/espp-taxes)
- 8 Key Terms to Know About Your Employee Stock Purchase Plan (https://zajacgrp.com/insights/8-key-terms-to-know-about-your-employee-stock-purchase-plan)
- Are Employee Stock Purchase Plans (ESPP) Pre-Tax? (https://smartasset.com/taxes/is-employee-stock-purchase-plan-pre-tax)
- Trends in ESPP Policies and Participation (https://naspp.com/blog/espp-policies-and-participation)
- NASPP | Trends in ESPPs: Five Facts and a Myth (https://naspp.com/blog/five-trends-in-espps)
- Identify Criteria for Post-Tax Classification of Your ESPP
- Understanding Employee Stock Purchase Plans (ESPPs) (https://brightonjones.com/blog/employee-stock-purchase-plans)
- ESPP Tax: Unlock Maximum Savings Today | Dimov Tax (https://dimovtax.com/espp-taxation-guide)
- ESPP Tax Rules: What You Need to Know (https://wealthenhancement.com/s/blog/espp-tax-rules-what-you-need-to-know-MC7NEMNJHGRBD3NPLYMZUQQ23MAQ)
- NASPP | Trends in ESPPs: Five Facts and a Myth (https://naspp.com/blog/five-trends-in-espps)
- Employee stock purchase plan (ESPP): meaning & examples (https://rho.co/blog/employee-stock-purchase-plan)
- Evaluate Your ESPP: Steps to Determine Tax Status
- Employee Stock Purchase Plans 101 | Plancorp (https://plancorp.com/employee-stock-purchase-plans-101)
- ESPP Tax: Unlock Maximum Savings Today | Dimov Tax (https://dimovtax.com/espp-taxation-guide)
- Employee Stock Purchase Plans (https://turbotax.intuit.com/tax-tips/investments-and-taxes/employee-stock-purchase-plans/L8NgMFpFX)
- ESPP Tax Rules: What You Need to Know (https://wealthenhancement.com/s/blog/espp-tax-rules-what-you-need-to-know-MC7NEMNJHGRBD3NPLYMZUQQ23MAQ)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Tax Management for high-income W-2 families at Bright Advisers.
Keep reading