

Overview
Navigating High Deductible Health Plans (HDHPs) can be challenging for families. These plans typically do not include copays for most services until the deductible is met, which means families often find themselves covering all medical expenses out-of-pocket at first. It’s important to understand this payment structure, as it plays a crucial role in budgeting for healthcare expenses.
Imagine if you could plan ahead and feel prepared for these costs. Families need to be aware of their financial responsibilities before insurance coverage begins, which can help alleviate some of the stress that comes with unexpected medical bills.
Together, we can navigate this journey. Understanding your HDHP will empower you to make informed decisions about your family’s healthcare, ensuring that you are ready for whatever comes your way. We’re here for you as you take these important steps toward financial stability and peace of mind.
Key Highlights:
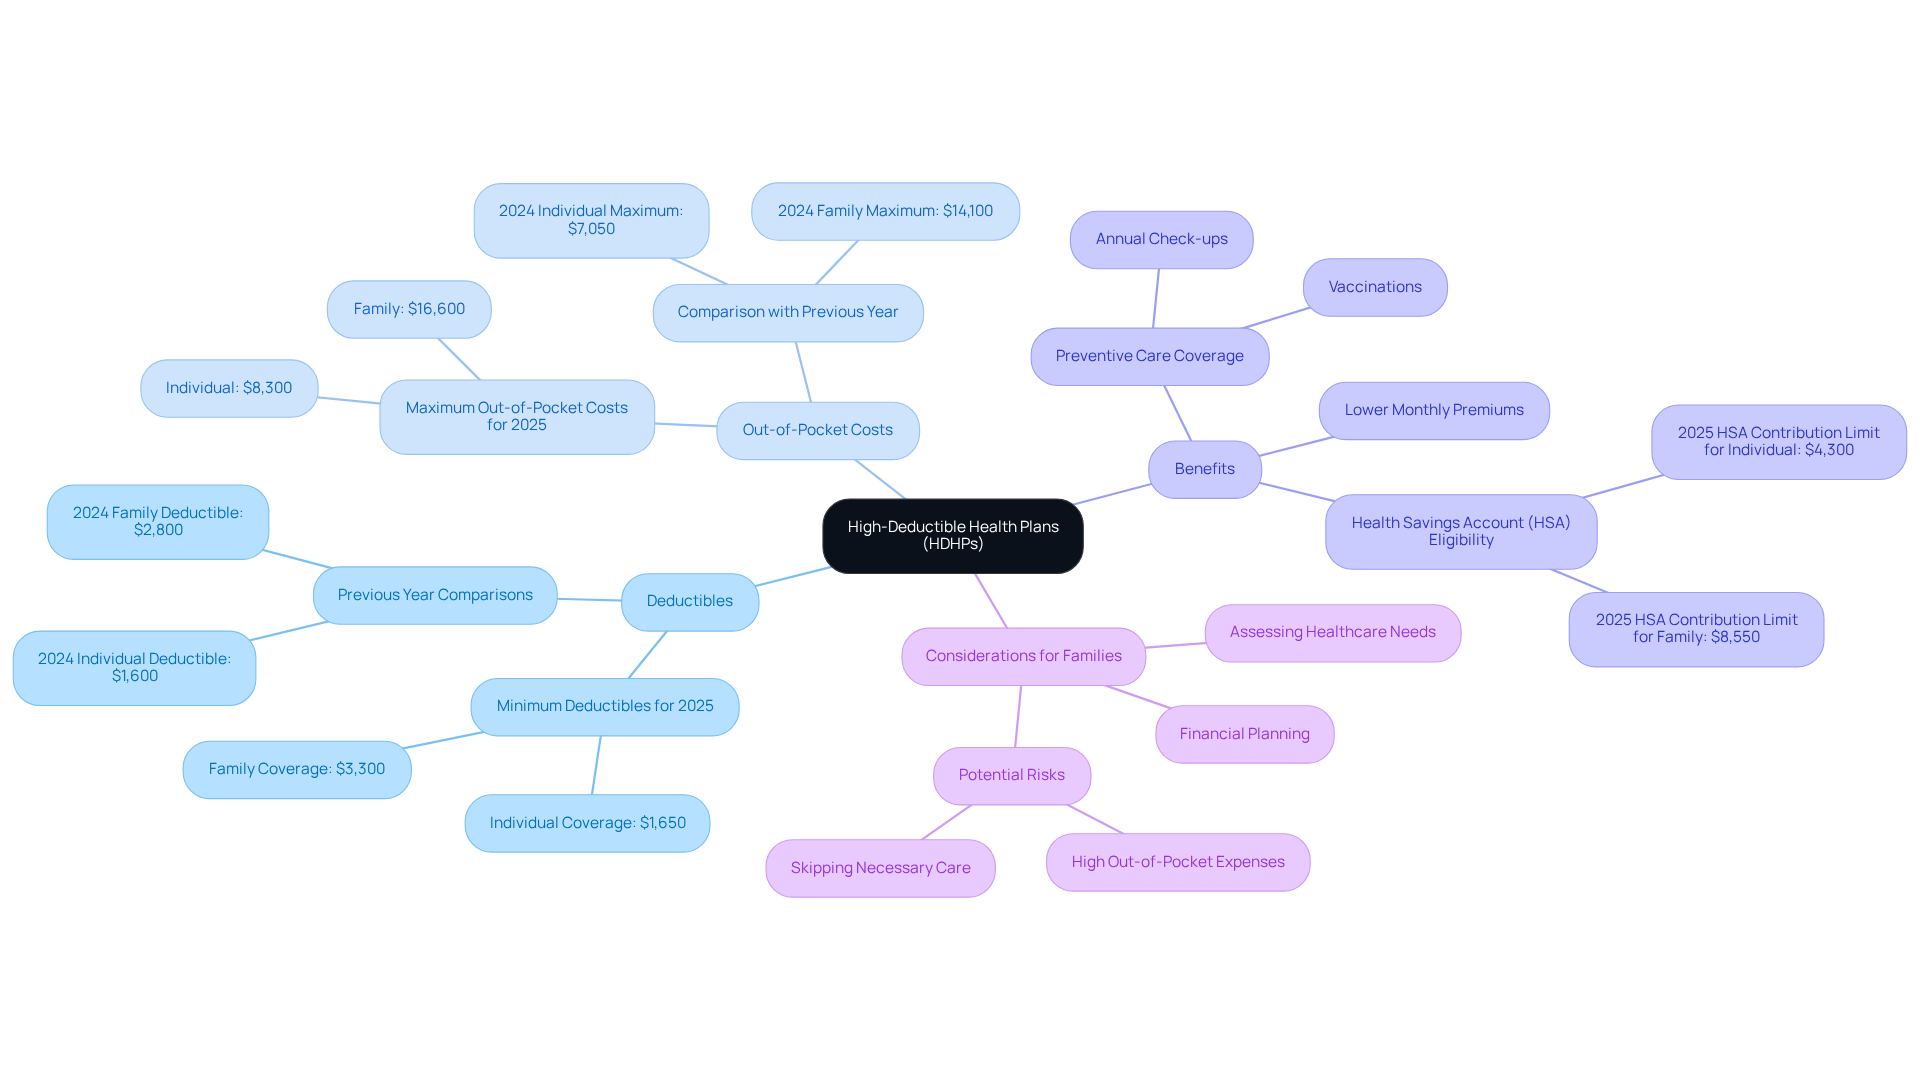
- HDHPs have lower monthly premiums but higher deductibles compared to traditional plans, with a minimum deductible of $1,650 for individuals and $3,300 for families in 2025.
- Families pay all medical expenses out-of-pocket until the deductible is met, which can be beneficial for generally healthy families.
- The total out-of-pocket costs for HDHPs cannot exceed $16,600 for families in 2025, including deductibles, copayments, and coinsurance.
- HDHPs typically do not require copays for most services until the deductible is met, impacting budgeting for healthcare expenses.
- Health Savings Accounts (HSAs) are often available with HDHPs, allowing families to save tax-free for medical expenses, with a contribution limit of $8,550 in 2025.
- About 64% of employers are expected to offer HDHPs linked to HSAs by 2025, reflecting a trend towards affordable healthcare options.
- Families should review their health plan documents for copayment details and understand the terms of coverage to avoid unexpected costs.
- Consulting with insurance representatives can clarify uncertainties regarding copays, deductibles, and out-of-pocket costs, ensuring informed healthcare decisions.
Introduction
High-Deductible Health Plans (HDHPs) can be a thoughtful choice for families striving to balance healthcare costs with their coverage needs. With lower monthly premiums and a structure that places more financial responsibility on individuals, these plans may offer significant savings for those who are generally healthy.
However, the question of whether HDHPs include copays introduces an important layer of complexity for parents to navigate. As families consider the benefits alongside potential out-of-pocket expenses, understanding the nuances of HDHPs becomes vital for making informed healthcare decisions.
Imagine if you could manage your healthcare costs effectively while ensuring your loved ones receive the necessary care. Together, we can explore how to achieve this balance.
Understand High-Deductible Health Plans (HDHPs)
High-Deductible Health Plans (HDHPs) offer a unique option for families, featuring lower monthly premiums and higher deductibles than traditional plans. For 2025, the IRS defines an HDHP as having a minimum deductible of $1,650 for individual coverage and $3,300 for household coverage. Understanding these plans is essential for parents, who often juggle healthcare expenses while ensuring their loved ones’ health needs are met. With HDHPs, individuals typically pay all medical expenses out-of-pocket until they meet their deductible, after which insurance begins to cover a portion of the costs. This structure can be beneficial for families that are generally healthy and do not anticipate regular medical expenses.
Imagine if you could manage your healthcare costs effectively while still focusing on what truly matters—your family’s well-being. In 2025, the total out-of-pocket costs for high-deductible health plans cannot exceed $16,600 for households, including deductibles, copayments, and coinsurance. This cap is a key consideration for families evaluating their financial exposure under an HDHP.
It’s important to understand that managing healthcare expenses with high-deductible health plans, including whether do high deductible plans have copays, requires thoughtful planning. Financial advisors recommend that families assess their healthcare needs and financial situations before committing to an HDHP. For instance, families with healthy children may find that the lower premiums of high-deductible health plans raise the question of whether do high deductible plans have copays that can help mitigate the risks of higher out-of-pocket costs. As Jon Robb, senior vice president of research and technology at Devenir, observes, “The growth of HSA assets projects a strong, upward trajectory for the future, indicating a steady and significant expansion of the HSA market.”
Real-world examples illustrate the benefits of high-deductible health plans for parents. Many families report that the reduced monthly premiums allow them to allocate more resources to other essential expenses, such as education or savings. Additionally, high-deductible health plans often cover preventive care services at no charge, including annual check-ups and vaccinations, helping families maintain their health without incurring extra costs.
Ultimately, understanding how high-deductible health plans work is vital for parents. By evaluating their family’s health needs and financial resources, they can make informed decisions that align with their long-term financial goals while ensuring their loved ones receive the care they need. Together, we can navigate this journey toward a healthier future.
Identify Key Features of HDHPs
Navigating healthcare options can feel overwhelming, especially for young families. High Deductible Health Plans (HDHPs) present some key features that you might find helpful in your financial planning journey.
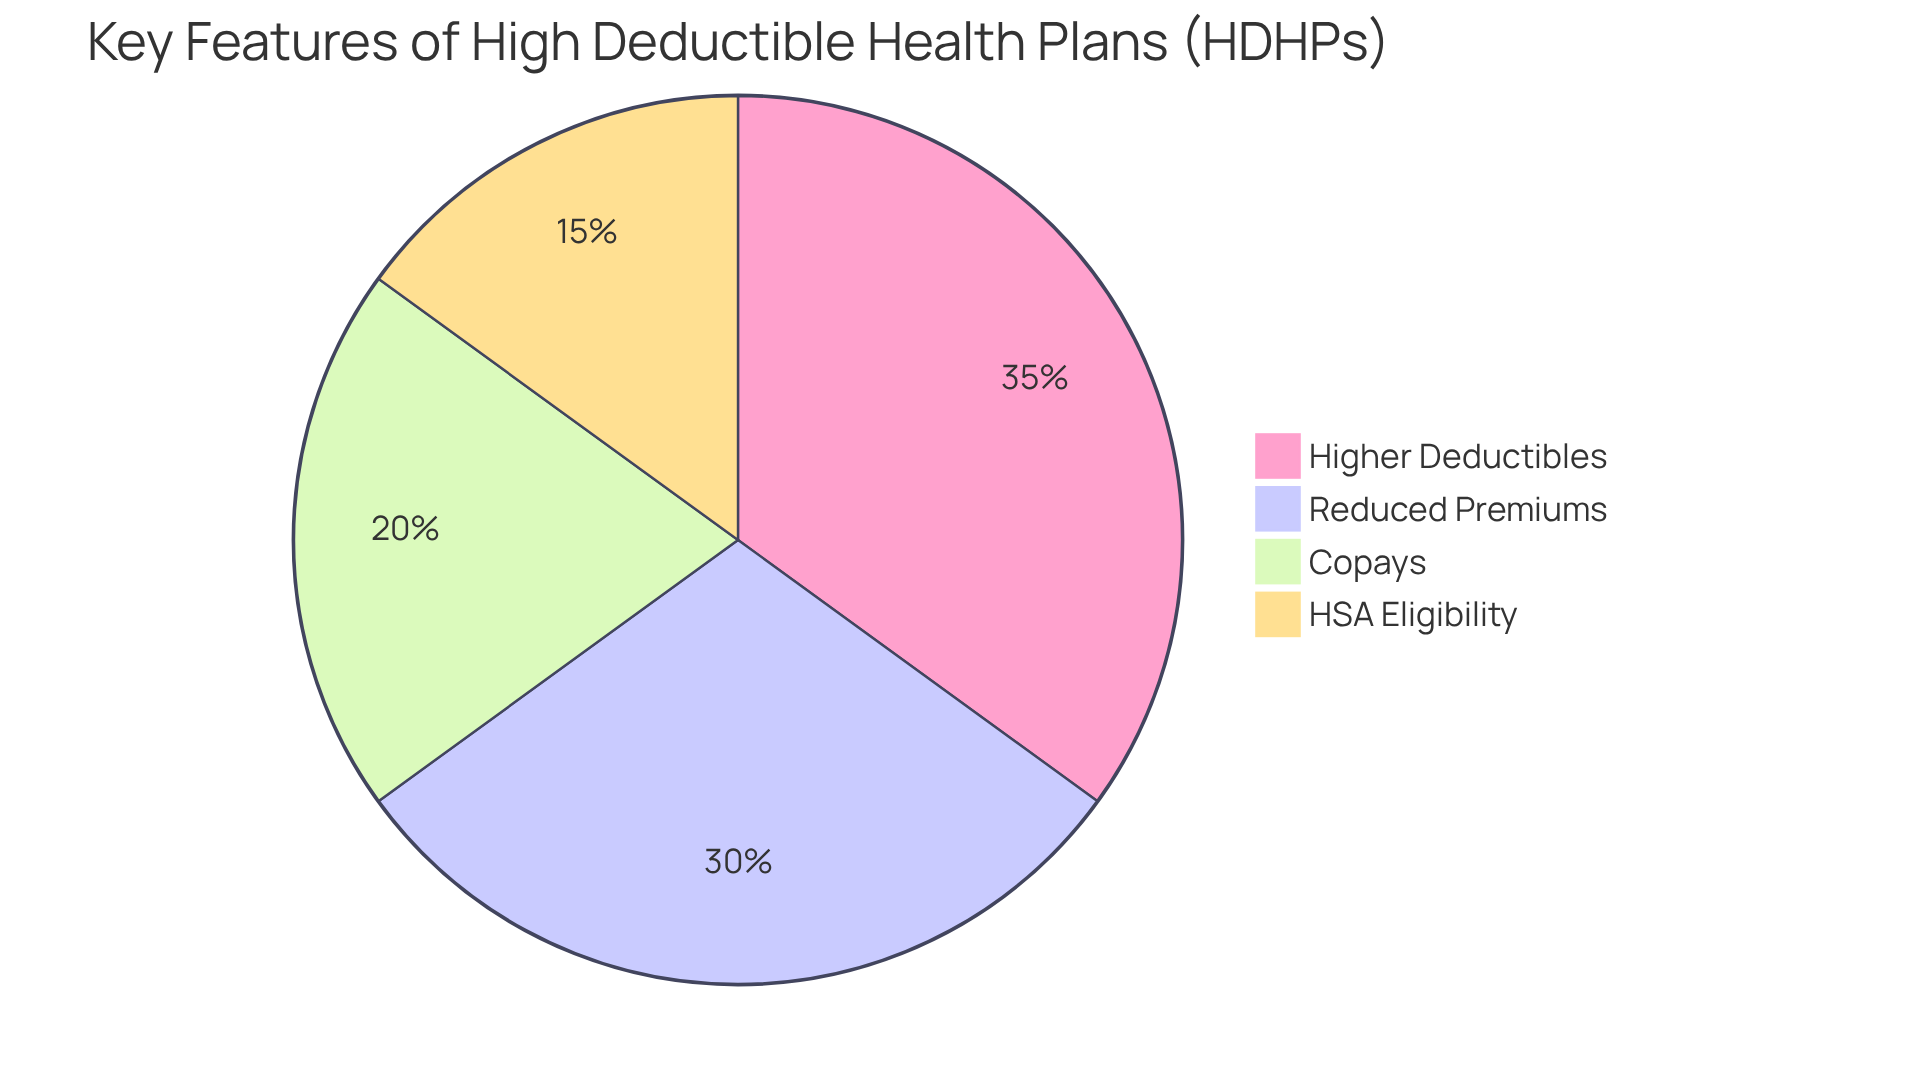
- Higher Deductibles: Families often face higher out-of-pocket expenses before insurance coverage begins. This can lead to significant costs, particularly challenging for those managing chronic conditions or regular healthcare needs. Imagine the stress of unexpected medical bills piling up when you’re already trying to balance family responsibilities.
- Reduced Premiums: One appealing aspect of HDHPs is their lower monthly premiums compared to traditional plans. In 2024, the average household premium increased by 7%, highlighting the financial pressures many families face. Choosing a high-deductible plan can help ease some of that monthly burden, allowing you to allocate funds to other family priorities.
- Copays: To answer the question of whether high deductible plans have copays, it’s important to note that unlike conventional plans, HDHPs typically don’t require copays for most services until you meet your deductible. This means that families will need to cover the full cost of treatments upfront, which can be daunting. It’s important to understand how this might affect your budgeting and healthcare access.
- Health Savings Account (HSA) Eligibility: Many HDHPs allow families to open Health Savings Accounts, providing tax advantages for saving money to cover medical expenses. In 2025, families can contribute up to $8,550 annually to their HSAs, creating a valuable resource for managing healthcare costs over time. This can be a great way to reduce your overall tax obligations while preparing for future medical needs.
Looking ahead, around 64% of employers are expected to offer HDHPs linked to HSAs by 2025, according to the KFF 2024 Employer Health Benefits Survey. This trend reflects a growing interest among families seeking affordable healthcare options. While HDHPs can lead to savings on premiums, it’s crucial to carefully consider your healthcare needs and financial situation. Together, we can navigate this journey and find the right plan for your family.
Review Plan Documents for Copay Details
Navigating your High Deductible Health Plan (HDHP) can feel overwhelming, but we’re here to help you understand do high deductible plans have copays. Let’s take this journey together, step by step.
-
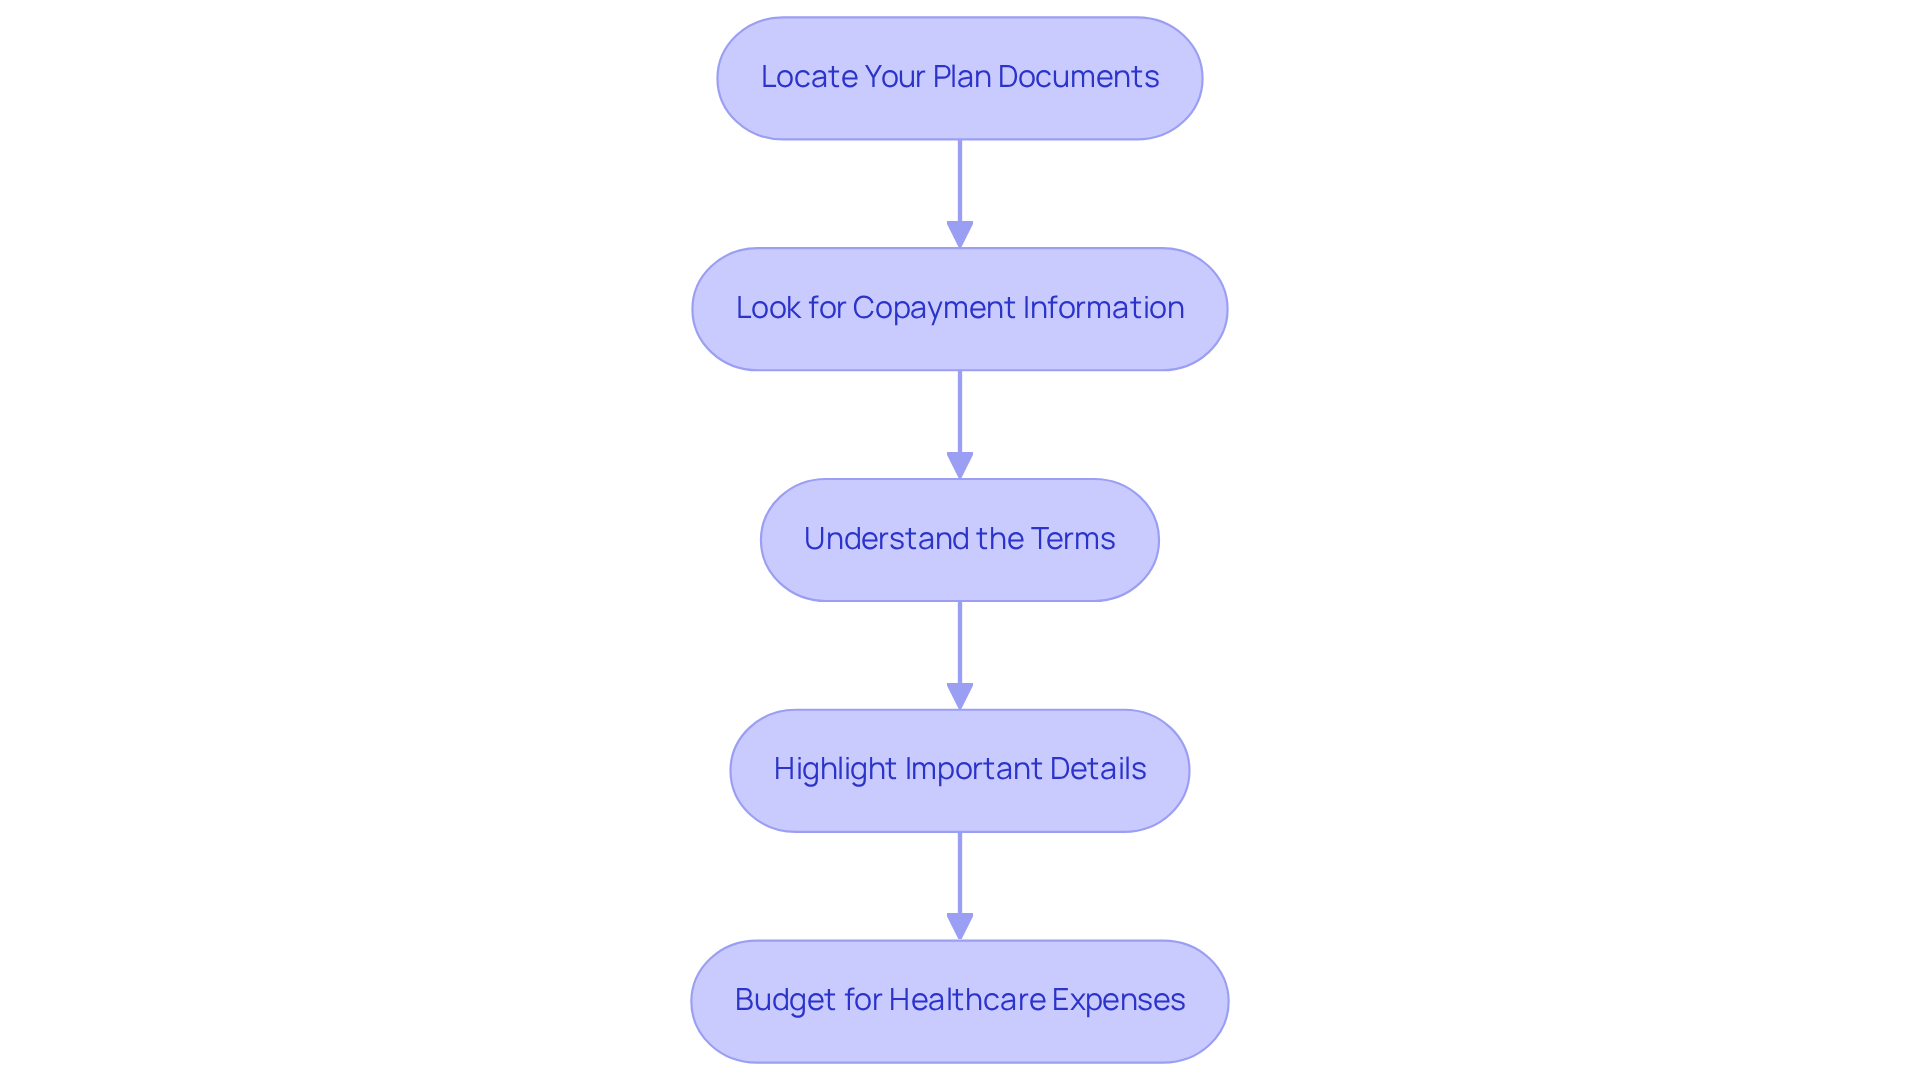
Locate Your Plan Documents: Start by accessing your health insurance plan documents, like the Summary of Benefits and Coverage (SBC) and the Evidence of Coverage (EOC). You can usually find these online through your insurance provider’s website, or you can reach out to customer service for assistance.
-
Look for copayment information: As you review these documents, pay special attention to sections that explain whether do high deductible plans have copays. This is often listed under ‘Cost Sharing’ or ‘Benefits’. Remember, over half of families take the time to review their health plan documents annually, particularly to determine if high deductible plans have copays—this is a crucial step in understanding your coverage.
-
Understand the Terms: It’s important to grasp any notes regarding when you need to start making payments. With HDHPs, you may need to cover the full cost of services until you’ve met your deductible. As insurance specialist Lacie Glover wisely states, “Your decision will be highly personal, a financial choice based on you and your household’s health care needs.” Also, be aware that shared payments might not contribute toward the deductible in some health care plans, which could lead to higher out-of-pocket expenses, especially for families managing chronic conditions.
-
Highlight Important Details: Take note of any services that incur fees and their corresponding amounts. For instance, typical out-of-pocket expenses might range from $20 for a primary care visit to $40 or $50 for a specialist appointment. By doing this, you can budget for healthcare expenses more effectively and avoid unexpected costs. Keep in mind that the out-of-pocket maximum for an HDHP is $4,000—this is a vital detail for understanding your potential maximum expenses. Together, we can navigate this journey and ensure you feel confident in your health care choices.
Consult with Insurance Representatives for Clarity
To clarify any uncertainties regarding your high-deductible health plan (HDHP), consider these supportive steps:
-
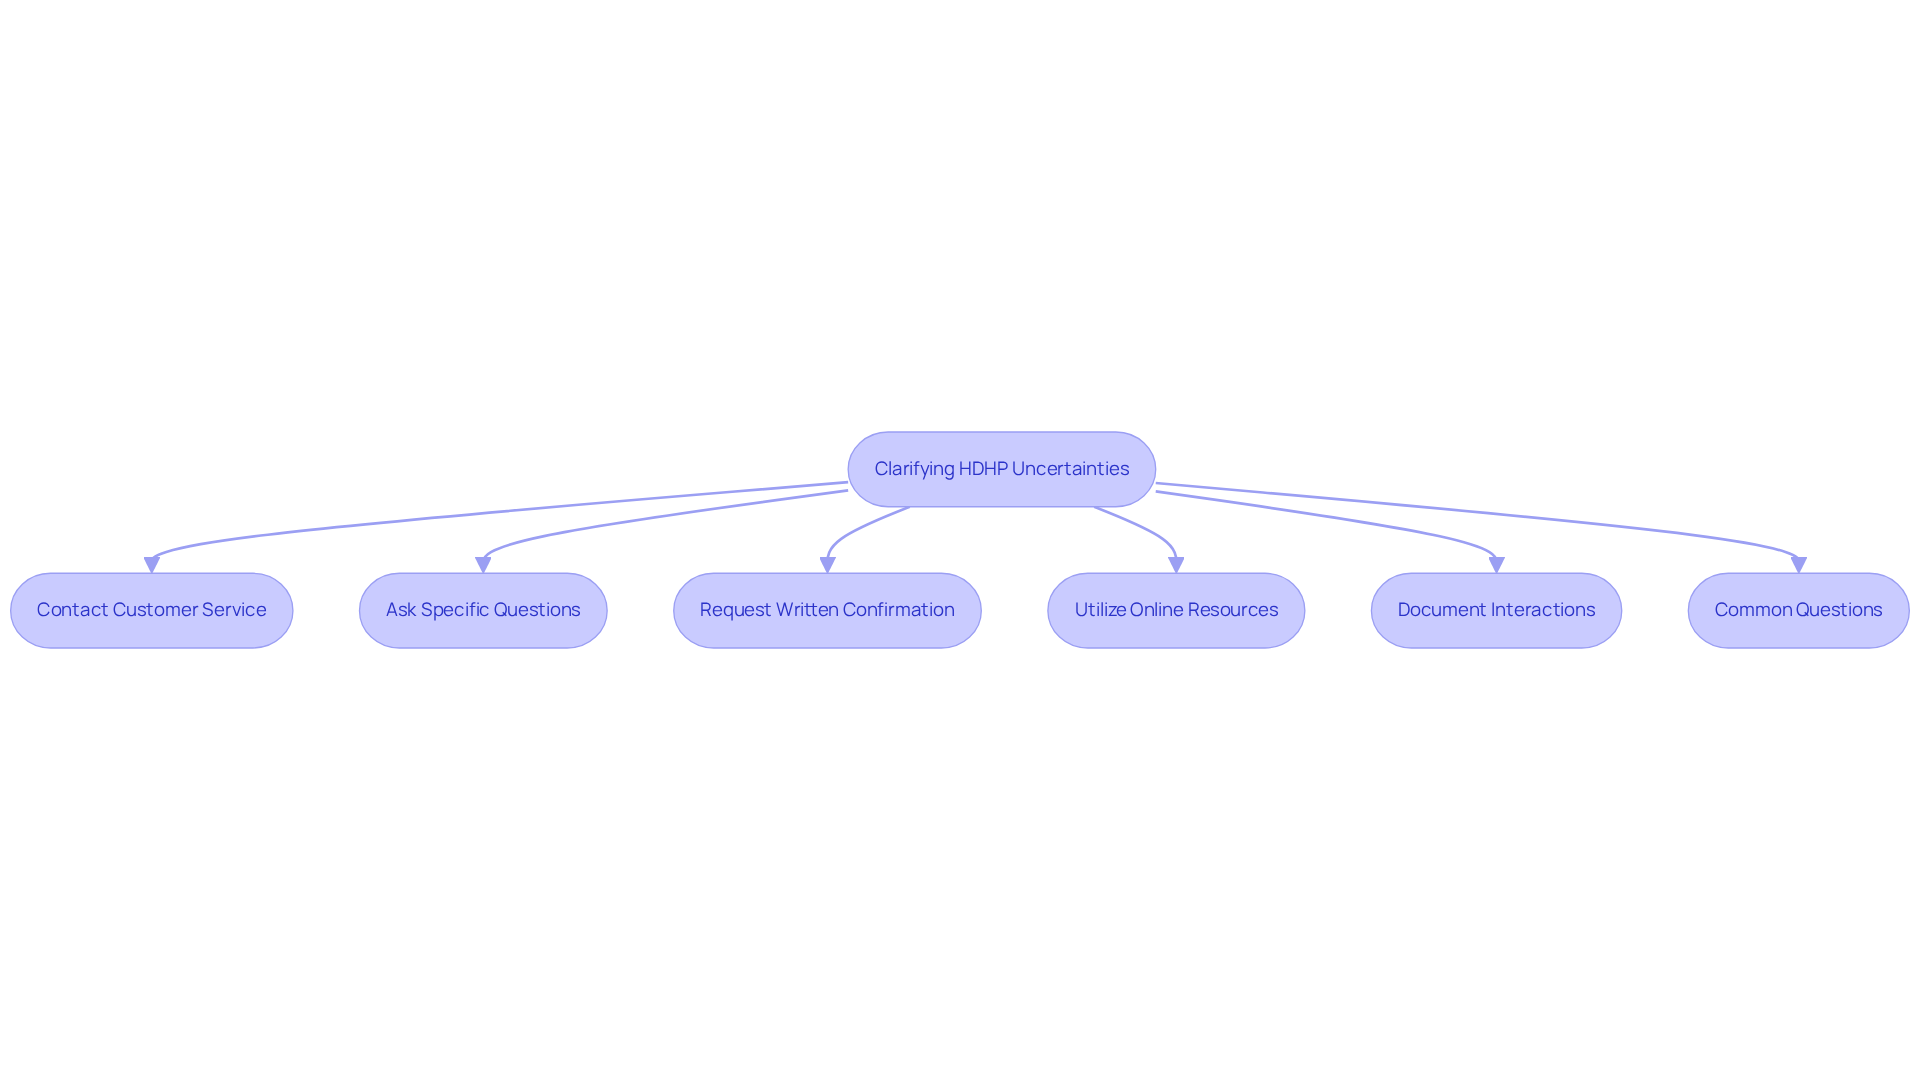
Contact Customer Service: Reach out to your insurance provider’s customer service department. Have your policy number ready and prepare specific questions about copays and deductibles. This initial step can provide peace of mind as you seek clarity.
-
Ask specific questions to determine if high deductible plans have copays, especially regarding preventive care, specialist visits, and prescription medications. Understanding these details can help you anticipate your out-of-pocket expenses. For 2025, the deductible for an individual under an HDHP is at least $1,650, and for households, it is at least $3,300. The maximum out-of-pocket expenses are $8,300 for individuals and $16,600 for families.
-
Request Written Confirmation: If you receive verbal information, ask for written confirmation that outlines the details discussed. This documentation can serve as a valuable reference for future healthcare decisions. Following up in writing after phone conversations can ensure clarity and accountability, making you feel more secure in your understanding.
-
Utilize Online Resources: Many insurance providers offer online chat options or FAQs on their websites. These resources can be helpful for quick clarifications without the need to wait for a representative, allowing you to find answers at your convenience.
-
Common Questions Families Have: Families frequently inquire about the details of out-of-pocket costs for different offerings under HDHPs. Common inquiries include:
- What are the copays for preventive services?
- How do payment contributions for specialist visits function?
- Are there any out-of-pocket costs for prescription medications?
Comprehending how these copays relate to the deductible and what preventive procedures are included before reaching the deductible is crucial for your family’s financial planning.
-
Expert Advice on Communication: When communicating with insurance providers, be confident and clear about your needs. Document all interactions, including dates and names of representatives, to ensure you have a complete record of your inquiries and their responses. As Charlene Rhinehart, CPA, emphasizes, “It’s also important to know the annual HDHP limits to better understand how much you may have to spend out of pocket before your insurance will pay for covered services.”
By following these steps, families can effectively navigate the complexities of HDHPs and make informed decisions about their healthcare coverage. Remember, we’re here for you, and together, we can navigate this journey.
Conclusion
High-Deductible Health Plans (HDHPs) can be a valuable choice for families aiming to manage healthcare costs effectively. By exploring the nuances of these plans, including copays and deductibles, parents can make informed decisions that truly reflect their financial and healthcare needs. With lower premiums and the potential for Health Savings Accounts (HSAs), families can allocate their resources thoughtfully while ensuring access to essential medical care.
Imagine evaluating your family’s unique health needs against the features of HDHPs. It’s crucial to consider factors such as:
- Higher out-of-pocket costs before reaching deductibles
- The absence of copays for most services until the deductible is met
- The benefit of preventive care covered at no charge
Consulting with insurance representatives and thoroughly reviewing plan documents are vital steps in navigating these complexities and understanding the specific terms of coverage.
Ultimately, choosing a high-deductible health plan can significantly influence your family’s financial health and access to care. By taking proactive steps to understand plan details, families can better prepare for potential healthcare expenses and make choices that nurture their long-term well-being. We’re here for you—engaging with resources and seeking clarity from insurance providers can empower families to navigate the healthcare landscape with confidence, ensuring that the health of your loved ones remains a priority while managing costs effectively.
Frequently Asked Questions
What are High-Deductible Health Plans (HDHPs)?
High-Deductible Health Plans (HDHPs) are health insurance options that feature lower monthly premiums and higher deductibles compared to traditional plans. For 2025, an HDHP has a minimum deductible of $1,650 for individual coverage and $3,300 for household coverage.
How do HDHPs work in terms of out-of-pocket expenses?
Individuals with HDHPs typically pay all medical expenses out-of-pocket until they meet their deductible. After reaching the deductible, insurance begins to cover a portion of the costs. The total out-of-pocket costs for HDHPs in 2025 cannot exceed $16,600 for households, including deductibles, copayments, and coinsurance.
Who might benefit from choosing an HDHP?
Families that are generally healthy and do not anticipate regular medical expenses may benefit from HDHPs due to their lower premiums, which can allow for more resource allocation to other essential expenses like education or savings.
Do HDHPs cover preventive care services?
Yes, HDHPs often cover preventive care services at no charge, including annual check-ups and vaccinations, helping families maintain their health without incurring extra costs.
What should families consider before committing to an HDHP?
Families should assess their healthcare needs and financial situations before choosing an HDHP. Financial advisors recommend evaluating whether the lower premiums are worth the potential higher out-of-pocket costs associated with the plan.
What is the significance of Health Savings Accounts (HSAs) in relation to HDHPs?
The growth of Health Savings Account (HSA) assets indicates a strong expansion of the HSA market, which can be beneficial for individuals with HDHPs. HSAs allow users to save money tax-free for medical expenses, helping to manage healthcare costs effectively.
List of Sources
- Understand High-Deductible Health Plans (HDHPs)
- Who Should Consider a High-Deductible Health Plan in 2024? – Bixler Insurance (https://bixlerinsurance.com/who-should-consider-a-high-deductible-health-plan-in-2024)
- Should You Choose a High-Deductible Health Plan? – NerdWallet (https://nerdwallet.com/article/health/high-or-low-deductible-health-insurance-plan)
- Is Your Plan Deductible High Enough? (https://brickergraydon.com/benefits-insights/is-your-plan-deductible-high-enough)
- IRS Announces 2025 HSA, HDHP Limits (https://shrm.org/topics-tools/news/benefits-compensation/irs-announces-2025-hsa–hdhp-limits)
- Is a high-deductible insurance plan right for you? | Blue Cross NC (https://bluecrossnc.com/blog/insurance-basics/open-enrollment/is-high-deductible-insurance-right-for-you)
- Identify Key Features of HDHPs
- High-Deductible Health Insurance Plans (HDHP) (https://thehartford.com/business-insurance/strategy/primary-types-health-insurance/high-deductible)
- High Deductible Health Plans Are Actually Good! (https://hsaforamerica.com/blog/high-deductible-health-plans-are-good-actually)
- IRS Announces 2025 HSA, HDHP Limits (https://shrm.org/topics-tools/news/benefits-compensation/irs-announces-2025-hsa–hdhp-limits)
- Summary of Findings – 10480 | KFF (https://kff.org/report-section/ehbs-2024-summary-of-findings)
- IRS Announces 2025 HSA and EBHRA Contribution Limits, HDHP Minimum Deductibles, and HDHP Out-of-Pocket Maximums (https://tax.thomsonreuters.com/news/irs-announces-2025-hsa-and-ebhra-contribution-limits-hdhp-minimum-deductibles-and-hdhp-out-of-pocket-maximums)
- Review Plan Documents for Copay Details
- Should You Choose a High-Deductible Health Plan? – NerdWallet (https://nerdwallet.com/article/health/high-or-low-deductible-health-insurance-plan)
- What Are Copays In Health Insurance? | My Private Health Insurance (https://myprivatehealthinsurance.com/what-are-copays-in-health-insurance)
- Should You Choose a High Deductible Health Plan or a Co-Pay Plan? | Gravie (https://gravie.com/perspectives/should-you-choose-a-high-deductible-health-plan-or-a-co-pay-plan)
- What is a high-deductible health plan (HDHP)? | healthinsurance.org (https://healthinsurance.org/glossary/high-deductible-health-plan)
- Health insurance deductible vs copay | Decent (https://decent.com/blog/health-insurance-deductible-vs-copay)
- Consult with Insurance Representatives for Clarity
- Communicating with Insurance Companies (https://phassociation.org/patients/insurance-and-treatment-access/communicating-with-insurance-companies)
- IRS Announces 2025 HSA and EBHRA Contribution Limits, HDHP Minimum Deductibles, and HDHP Out-of-Pocket Maximums (https://tax.thomsonreuters.com/news/irs-announces-2025-hsa-and-ebhra-contribution-limits-hdhp-minimum-deductibles-and-hdhp-out-of-pocket-maximums)
- The Pros & Cons of a High Deductible Health Plan (HDHP) (https://bennie.com/blog/pros-and-cons-of-an-hdhp)
- High-Deductible Health Plan (HDHP) Limits for 2025 – GoodRx (https://goodrx.com/insurance/hdhp/high-deductible-health-plan-limits?srsltid=AfmBOooNVv4KQHQ0KkEcndocqePjlK3tNljGYihkzG8ea2RIOsm76R5v)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About Kevin