

Key Highlights:
- Restricted Stock Units (RSUs) are a form of equity compensation that grant employees shares of stock after meeting vesting conditions.
- RSUs do not have a strike price, meaning employees do not need to pay to convert them into shares upon vesting.
- The alignment of RSUs with company performance encourages employees to contribute to the company’s success.
- RSUs are considered taxable income in the year they vest, which can lead to unexpected tax liabilities if not properly managed.
- Families can leverage RSUs for long-term financial planning, including education funding and other goals.
- Understanding the vesting schedule and tax implications of RSUs is crucial for effective financial management.
- Consulting with financial advisors can help employees optimise the benefits of their RSUs and align them with personal financial goals.
- The popularity of RSUs has increased, particularly among small-cap companies, reflecting a growing acceptance of this compensation method.
Introduction
Understanding the complexities of Restricted Stock Units (RSUs) can truly transform how families secure their financial futures. Unlike stock options, which often require an upfront investment, RSUs allow employees to receive shares without a strike price. This makes the journey to ownership much simpler. As employee compensation continues to evolve, parents are faced with the important task of weaving these assets into their broader financial strategies.
Imagine if you could leverage RSUs not just to meet your immediate financial needs, but also to plan for long-term goals like your children’s education or your retirement. It’s essential to understand how these assets can fit into your family’s financial picture.
By embracing RSUs, families can create a more stable financial foundation. This isn’t just about numbers; it’s about ensuring that your loved ones have the opportunities they deserve. We’re here for you, ready to help you navigate this journey together.
Let’s explore how you can make the most of RSUs, turning them into a powerful tool for your family’s future.
Understand Restricted Stock Units (RSUs)
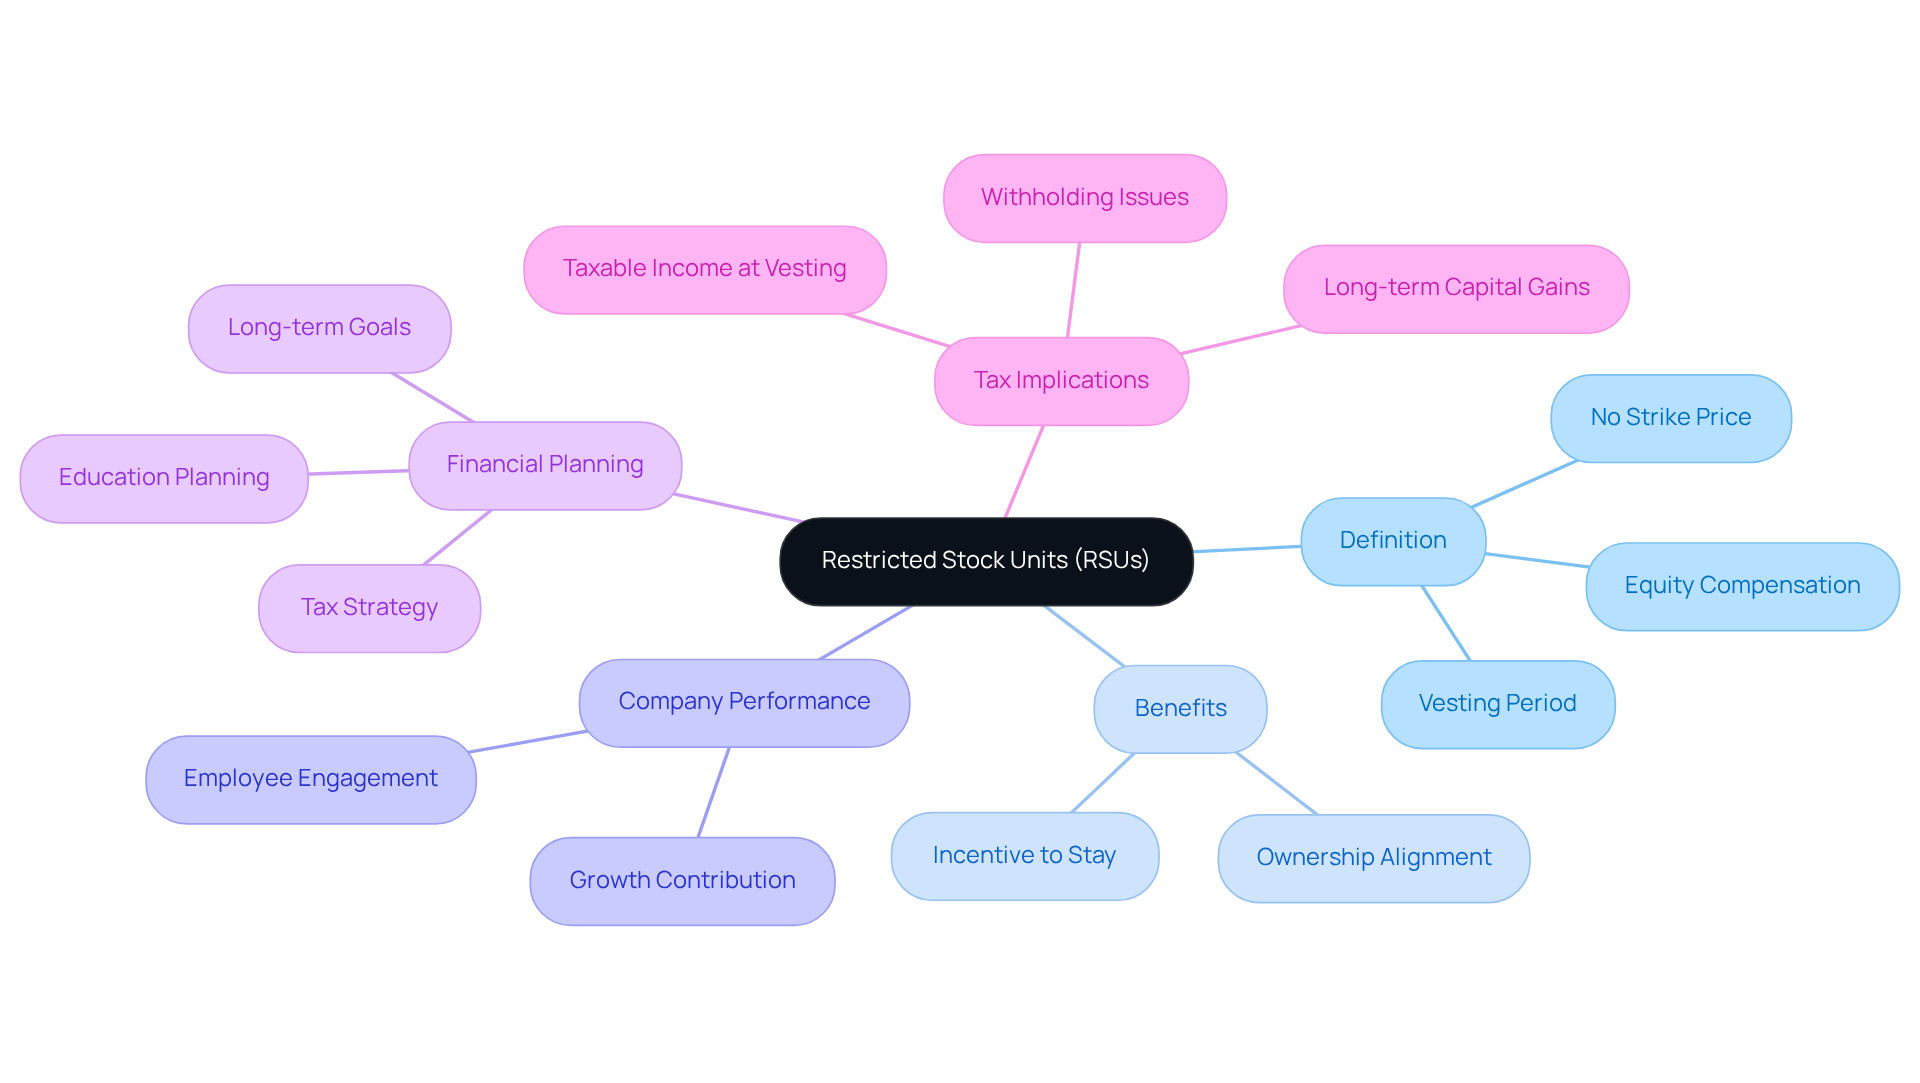
Restricted Stock Units (RSUs) represent a meaningful form of equity compensation that companies offer to their employees. These units grant workers the right to receive shares of the company’s stock once they meet certain conditions, typically after a vesting period. When considering the , one might ask, do RSUs have a strike price? The answer is no, as they don’t require employees to pay a strike price; they automatically convert into shares once vested. This means there’s no need for an initial investment, making RSUs an appealing and straightforward form of compensation.
The connection between RSUs and company performance is truly significant. As employees gain ownership in the company, their [financial interests become closely tied to the organization’s success](https://ir.ptcbio.com/news-releases/news-release-details/ptc-therapeutics-reports-inducement-grants-under-nasdaq-88?mobile=1). This alignment encourages them to contribute positively to the company’s growth, fostering a culture of shared goals. In 2025, many companies, including PTC Therapeutics, are incorporating [RSUs into their compensation packages](https://ir.ptcbio.com/news-releases/news-release-details/ptc-therapeutics-reports-inducement-grants-under-nasdaq-88?mobile=1), reflecting a growing trend in the corporate world.
Imagine how families can leverage RSUs to secure their [financial futures](https://brightadvisers.com/?p=11049). Employees who receive RSUs can plan for their children’s education or other long-term goals by managing their vested shares wisely. [[Bright Advisers emphasizes the importance](https://brightadvisers.com/?p=11578)](https://brightadvisers.com/?p=10183) of [[integrating RSUs into a comprehensive financial strategy](https://brightadvisers.com/master-rsu-vesting-for-young-families-financial-success)](https://brightadvisers.com/is-rsu-good-for-young-families-understanding-financial-benefits), using innovative tools like smart beta and factor investing to enhance investment outcomes and ensure families are prepared for future expenses.
However, it’s crucial for parents to recognize that [[RSUs are considered taxable income](https://brightadvisers.com/master-tax-withholding-on-rsu-strategies-for-young-families)](https://brightadvisers.com/7-essential-rsu-tax-withholding-calculator-tools-for-young-families) in the year they vest. Insufficient tax withholding can lead to unexpected [tax liabilities](https://flsv.com/news/restricted-stock-units-5-essential-tax-and-financial-planning-strategies). Financial experts at Bright Advisers highlight that RSUs not only provide immediate financial benefits but also encourage employees to think about the long-term implications of their investments and personal needs.
[Understanding how RSUs work](https://brightadvisers.com/understanding-restricted-stock-units-definition-for-young-parents) is essential for parents aiming to manage their financial situation effectively. By grasping the mechanics of RSUs and weaving them into a personalized financial plan, families can make informed decisions that align with their financial aspirations, ensuring a stable future for their children.
Together, we can navigate this journey toward financial security, ensuring that your family’s needs are met every step of the way.
Identify Key Features of RSUs Related to Strike Price
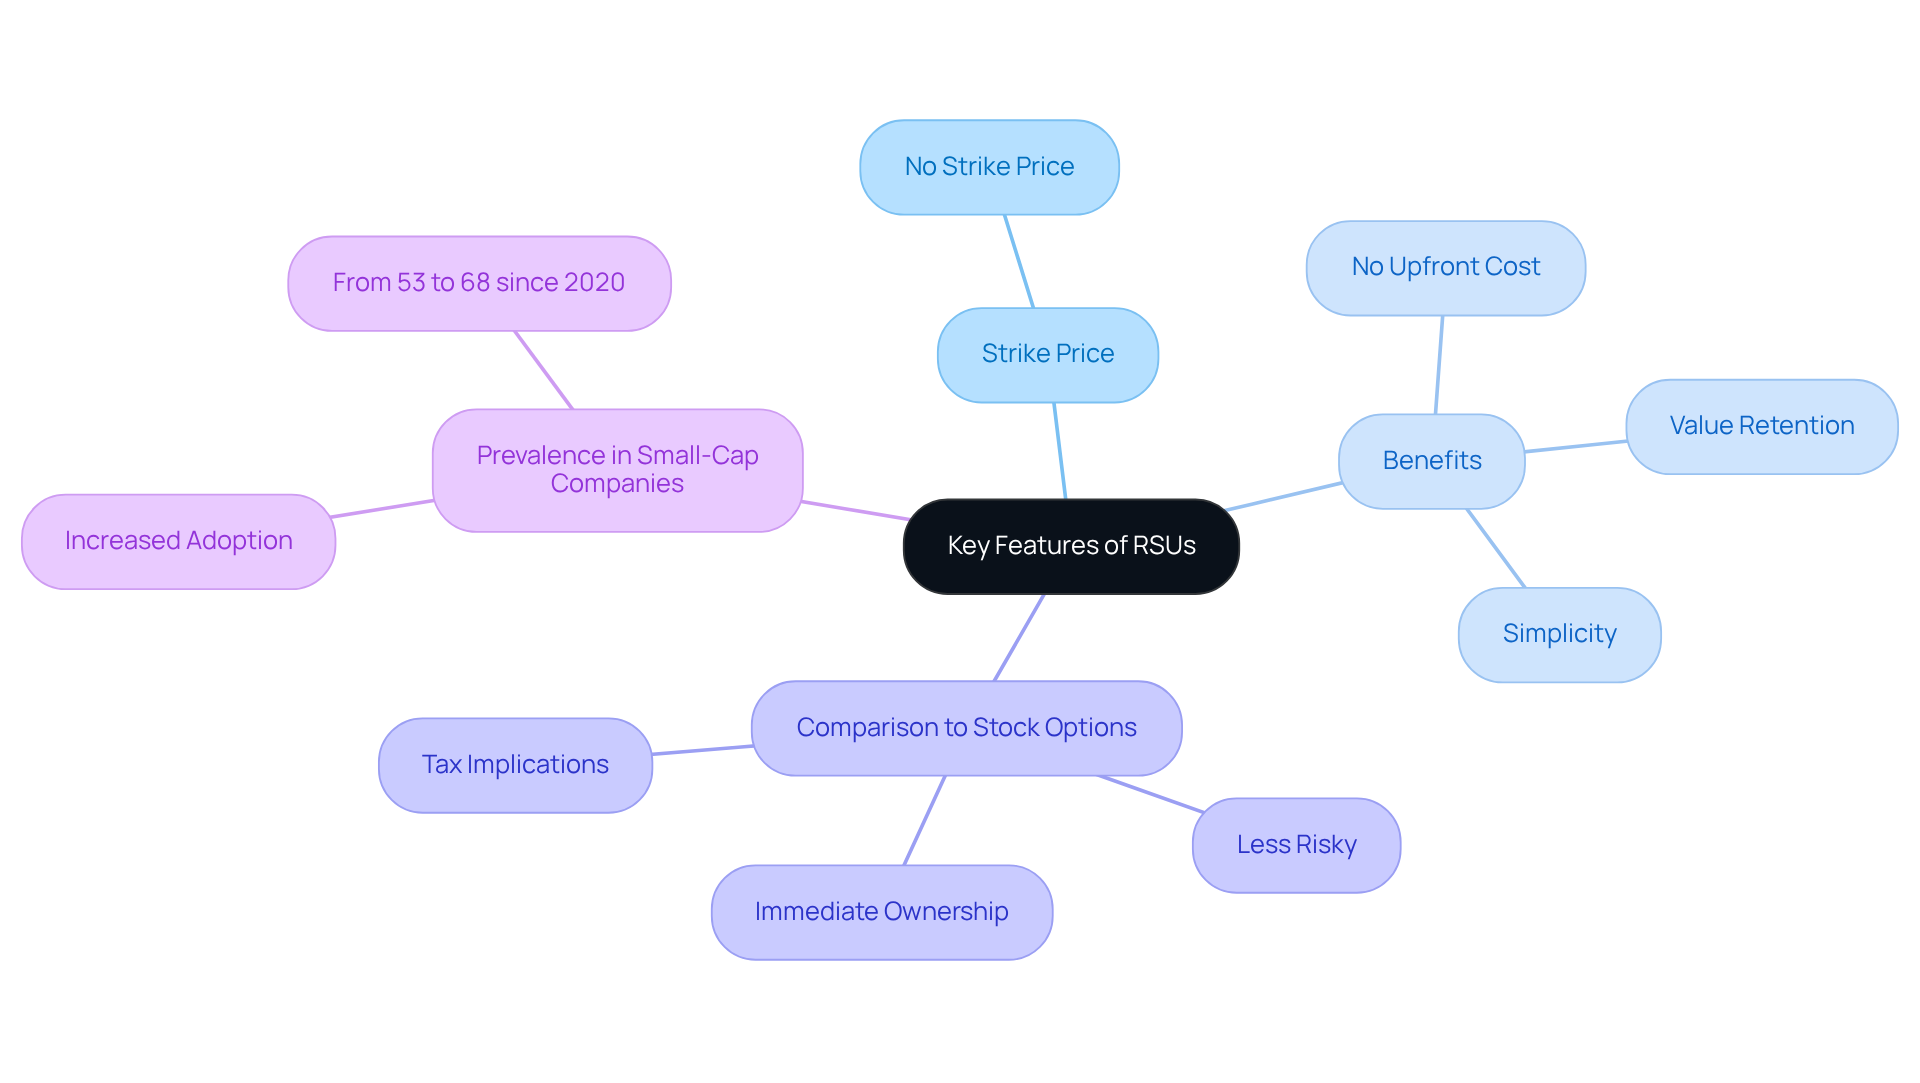
Imagine if you could simplify your family’s financial journey. A defining characteristic of Restricted Stock Units (RSUs) is often questioned: [do RSUs have a strike price](https://carta.com/learn/equity/rsu-vs-stock-options)? The question of do RSUs have a strike price arises when comparing them to stock options, which require you to purchase shares at a predetermined price, while RSUs are awarded outright upon vesting. This means you receive the full value of the shares without any upfront cost, making it easier to decide when to sell or keep your shares.
This feature is especially beneficial for parents, as it reduces the complexity often associated with equity compensation. Plus, RSUs can’t go underwater; they hold their value as long as the company’s stock remains valuable. This stability makes them a compared to stock options. In fact, many workers find RSUs simpler to understand and evaluate, leading to more informed financial choices for their families.
[[Financial consultants](https://brightadvisers.com/?p=11100)](https://brightadvisers.com/10-trusted-sources-for-financial-advice-young-parents-can-rely-on), including those at Bright Advisers, often highlight the stability of RSUs, particularly in unpredictable economic times. This reinforces their appeal as a dependable part of your family’s [financial plan](https://brightadvisers.com/understanding-rsu-vested-but-not-distributed-for-young-parents). Bright Advisers employs innovative strategies like [smart beta and factor investing](https://brightadvisers.com/9-passive-investment-strategies-for-young-families-financial-growth) to help families maximize the value of their RSUs.
As Derek Russell Munchow, Managing Partner and Certified Financial Planner, puts it, “Restricted Stock Units are often viewed as [less risky since they retain value](https://tgcsearch.com/business-insights/rsu-vs-stock-options-navigating-equity-compensation) as long as the company’s stock has any worth, while stock options only possess value if the stock price increases above the grant price.”
Additionally, the [prevalence of RSUs at small-cap companies](https://paygovernance.com/resource/biotech-industry-trends-in-equity-compensation-influence-of-market-volatility-on-equity-program-strategy) has risen from 53% to 68% since 2020, showing a growing acceptance and understanding of this form of equity compensation. Bright Advisers’ innovative in-house technology empowers families to [[navigate these financial tools](https://brightadvisers.com/?p=11070)](https://brightadvisers.com/?p=12338) effectively, ensuring you can secure your future with confidence.
Together, we can navigate this journey and make the most of your financial opportunities.
Review Your RSU Agreement and Plan Documents
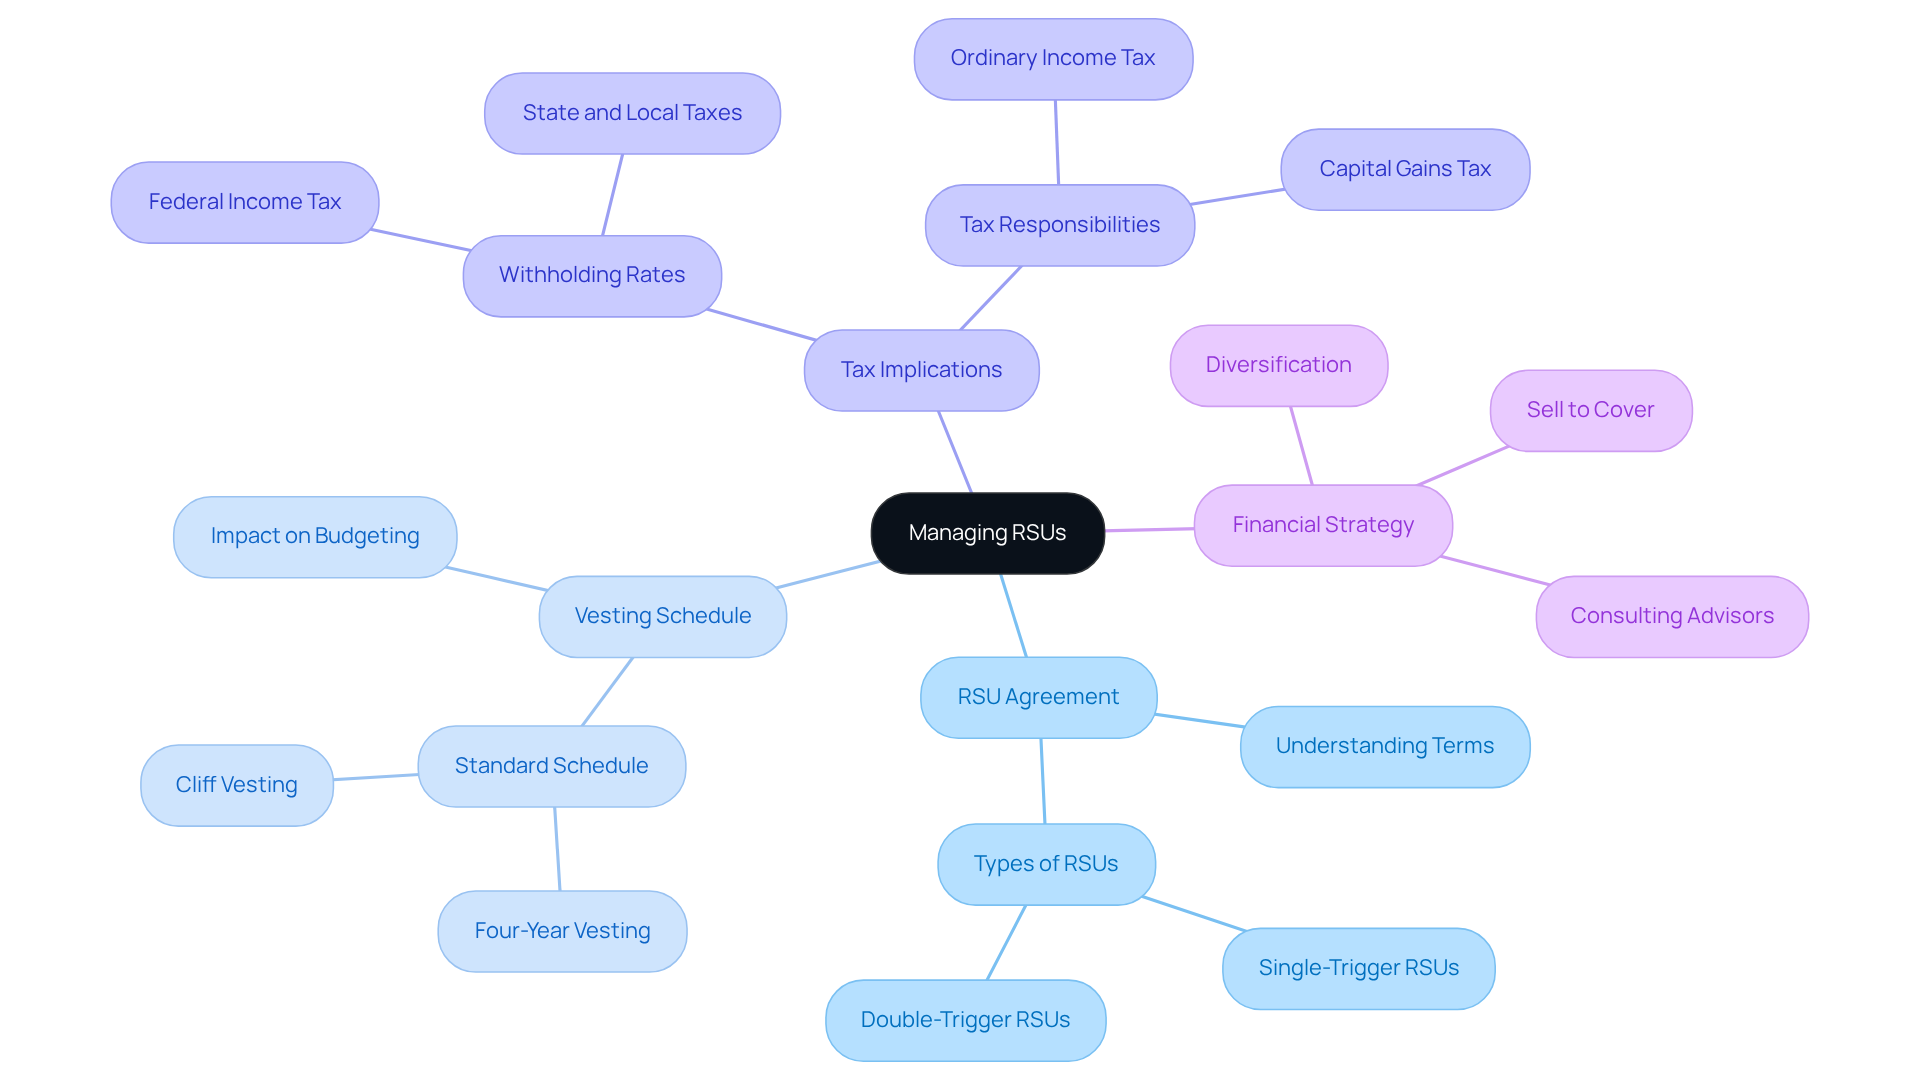
Managing your Restricted Stock Units (RSUs) can feel overwhelming, but you’re not alone in this journey. It’s essential to take a close look at your agreement and any related plan documents. These documents hold vital information, like the vesting schedule, which tells you when you’ll actually own those shares, and any performance criteria you need to meet. Understanding the is especially important as you plan for 2025, as it can significantly impact your budgeting. For instance, if you have a standard four-year vesting schedule, you might receive 25% of your RSUs after the first year. This can greatly influence your tax obligations and overall financial strategy.
Moreover, these documents will clarify the [[[tax implications of your RSUs](https://brightadvisers.com/do-you-pay-taxes-on-rs-us-key-considerations-for-young-parents)](https://brightadvisers.com/essential-tax-planning-strategies-for-young-families-financial-health)](https://brightadvisers.com/do-you-pay-taxes-on-rs-us-key-considerations-for-young-parents), including when you’ll be taxed and how much will be withheld. Employers typically withhold 22% for federal income taxes on the first $1 million in supplemental income, but this might not cover your total tax liability, especially if your effective tax rate is higher. Imagine if 1,000 RSUs vest at $50 each-that’s $50,000 of taxable income, which could lead to [significant tax responsibilities](https://rothschildwealth.com/understanding-rsus-and-isos).
By grasping these elements, you can better prepare for the financial impact of your RSUs and make informed choices about your equity compensation. This proactive approach is crucial for families, especially young parents, who face the complexities of RSU vesting schedules and their tax implications. [At Bright Advisers, we’re here for you](https://brightadvisers.com/?p=11117), offering [tailored wealth management solutions](https://brightadvisers.com/10-benefits-of-fee-only-investment-for-young-families) that ensure your family’s security and educational readiness. Together, we can enhance your strategies as you plan for your family’s future.
Consult Financial Advisors for Expert Guidance
Navigating the complexities of Restricted Stock Units (RSUs) can feel overwhelming, especially when you think about your family’s future. That’s why it’s so important to consult with a [[monetary advisor at Bright Advisers](https://brightadvisers.com/get-started)](https://brightadvisers.com/how-do-taxes-on-rs-us-work-understanding-timing-and-strategies). Our caring team of skilled consultants is here to help you [understand the ins and outs of your RSUs](https://tenetwealthpartners.com/insights/executive-compensation-planning-rsus-vs-stock-options-which-reigns-supreme) and suggest [personalized strategies that fit seamlessly](https://tenetwealthpartners.com/insights/executive-compensation-planning-rsus-vs-stock-options-which-reigns-supreme) into your overall financial plan.
Imagine if you could confidently decide the best time to sell your shares, reduce your [tax liabilities](https://brightadvisers.com/5-legal-ways-young-families-can-reduce-taxable-income), and align your RSUs with your long-term goals – like [funding your children’s education](https://brightadvisers.com/?p=9793) or preparing for a [comfortable retirement](https://brightadvisers.com/?p=12066). With RSUs consistently holding value as long as the company’s stock price is above zero, tailored advice becomes essential. We want to ensure you’re optimizing the benefits of your equity compensation, creating a [[stable financial foundation](https://brightadvisers.com/?p=11336)](https://brightadvisers.com/?p=9882) for your household.
As Kyle Wetters, a financial expert with over 20 years of experience, emphasizes, understanding these elements is vital for effective [[financial planning](https://brightadvisers.com/4-steps-for-planning-your-tax-strategy-as-a-young-family)](https://brightadvisers.com/10-essential-questions-to-ask-a-new-financial-advisor). With a [[projected shortage of advisors by 2034](https://mckinsey.com/industries/financial-services/our-insights/the-looming-advisor-shortage-in-us-wealth-management)](https://mckinsey.com/industries/financial-services/our-insights/the-looming-advisor-shortage-in-us-wealth-management), now is more crucial than ever for young families.
We’re here for you, ready to guide you through this journey. Together, we can [navigate the complexities of financial planning](https://investmentadviser.org/industry-snapshots), ensuring that your family’s future is secure and bright.
Conclusion
Restricted Stock Units (RSUs) can be a wonderful way to support you and your family financially. Unlike stock options, RSUs don’t come with a strike price, meaning you receive shares automatically upon vesting without any upfront cost. This straightforward approach not only boosts your financial security but also aligns your interests with your company’s success, creating a shared journey toward achievement.
Understanding RSUs is crucial, especially when it comes to their tax implications and vesting schedules. It’s wise to consult with financial advisors who can help you weave RSUs into your broader financial strategy. Imagine being well-prepared for future expenses, like your children’s education, with the added support of RSUs. Their growing presence in compensation packages shows just how reliable and appealing they can be for families striving for financial stability.
Navigating the complexities of RSUs might feel overwhelming, but remember, you don’t have to do it alone. By leveraging RSUs effectively, you can secure your family’s financial future and reach your long-term goals. Engaging with financial advisors can provide you with personalized strategies that optimize the benefits of RSUs, ensuring you’re equipped to make informed decisions. Together, we can navigate this journey and thrive financially.
Frequently Asked Questions
What are Restricted Stock Units (RSUs)?
Restricted Stock Units (RSUs) are a form of equity compensation offered by companies to employees, granting them the right to receive shares of the company’s stock after meeting certain conditions, typically following a vesting period.
Do RSUs require a strike price?
No, RSUs do not have a strike price. Employees do not need to pay an initial investment; they automatically convert into shares once they are vested.
How do RSUs relate to company performance?
RSUs align employees’ financial interests with the company’s success, encouraging them to contribute positively to the organization’s growth and fostering a culture of shared goals.
Are RSUs becoming more common in compensation packages?
Yes, many companies, including PTC Therapeutics, are incorporating RSUs into their compensation packages, indicating a growing trend in the corporate world.
How can families leverage RSUs for financial planning?
Families can use RSUs to secure their financial futures by managing their vested shares wisely, which can help in planning for expenses like children’s education and other long-term goals.
Are RSUs considered taxable income?
Yes, RSUs are considered taxable income in the year they vest, and insufficient tax withholding can lead to unexpected tax liabilities.
What should parents consider when managing RSUs?
Parents should understand the mechanics of RSUs and incorporate them into a personalized financial plan to make informed decisions that align with their financial aspirations and ensure a stable future for their children.
List of Sources
- Understand Restricted Stock Units (RSUs)
- Restricted Stock Units (RSUs): What You Need to Know About Taxes, Selling Shares and Long-Term Strategies (https://aspiriant.com/fathom/rsus-taxes-selling-and-more)
- Restricted Stock Units: 5 Essential Tax and Financial Planning Strategies – FLSV | Frankel Loughran Starr & Vallone LLP (https://flsv.com/news/restricted-stock-units-5-essential-tax-and-financial-planning-strategies)
- What Are RSUs & How to Handle Them | SoFi (https://sofi.com/learn/content/what-are-rsus)
- PTC Therapeutics Reports Inducement Grants Under Nasdaq Listing Rule 5635(c)(4) | PTC Therapeutics, Inc. (https://ir.ptcbio.com/news-releases/news-release-details/ptc-therapeutics-reports-inducement-grants-under-nasdaq-88?mobile=1)
- Identify Key Features of RSUs Related to Strike Price
- RSU vs Stock Options: Key Differences & Benefits (https://carta.com/learn/equity/rsu-vs-stock-options)
- RSUs vs Stock Options: Full Guide | Philip Stein (https://pstein.com/blog/rsu-vs-stock-options-detailed-comparison)
- RSU vs. Stock Options: Navigating Equity Compensation (https://tgcsearch.com/business-insights/rsu-vs-stock-options-navigating-equity-compensation)
- Biotech Equity Trends: RSUs Rise Amid Market Shifts (https://paygovernance.com/resource/biotech-industry-trends-in-equity-compensation-influence-of-market-volatility-on-equity-program-strategy)
- Review Your RSU Agreement and Plan Documents
- Restricted Stock Unit (RSU): A Complete Guide to RSUs (https://carta.com/learn/equity/rsu)
- Master RSU Cliff Vesting: A Step-by-Step Guide for Young Families – Bright Advisers (https://brightadvisers.com/master-rsu-cliff-vesting-a-step-by-step-guide-for-young-families)
- Understanding Sell to Cover Meaning: A Step-by-Step Guide for Families – Bright Advisers (https://brightadvisers.com/understanding-sell-to-cover-meaning-a-step-by-step-guide-for-families)
- Understanding Restricted Stock Units and Incentive Stock Options – Rothschild Wealth Partners (https://rothschildwealth.com/understanding-rsus-and-isos)
- Consult Financial Advisors for Expert Guidance
- Executive Compensation Planning: RSUs vs. Stock Options – Which Reigns Supreme? | Tenet Wealth Partners (https://tenetwealthpartners.com/insights/executive-compensation-planning-rsus-vs-stock-options-which-reigns-supreme)
- Industry Statistics (https://investmentadviser.org/industry-snapshots)
- The looming advisor shortage in US wealth management (https://mckinsey.com/industries/financial-services/our-insights/the-looming-advisor-shortage-in-us-wealth-management)
- Cerulli Associates | The Financial Advisor Industry Has a Headcount… (https://cerulli.com/press-releases/the-financial-advisor-industry-has-a-headcount-problem)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Tax Management for high-income W-2 families at Bright Advisers.
Keep reading