

Overview
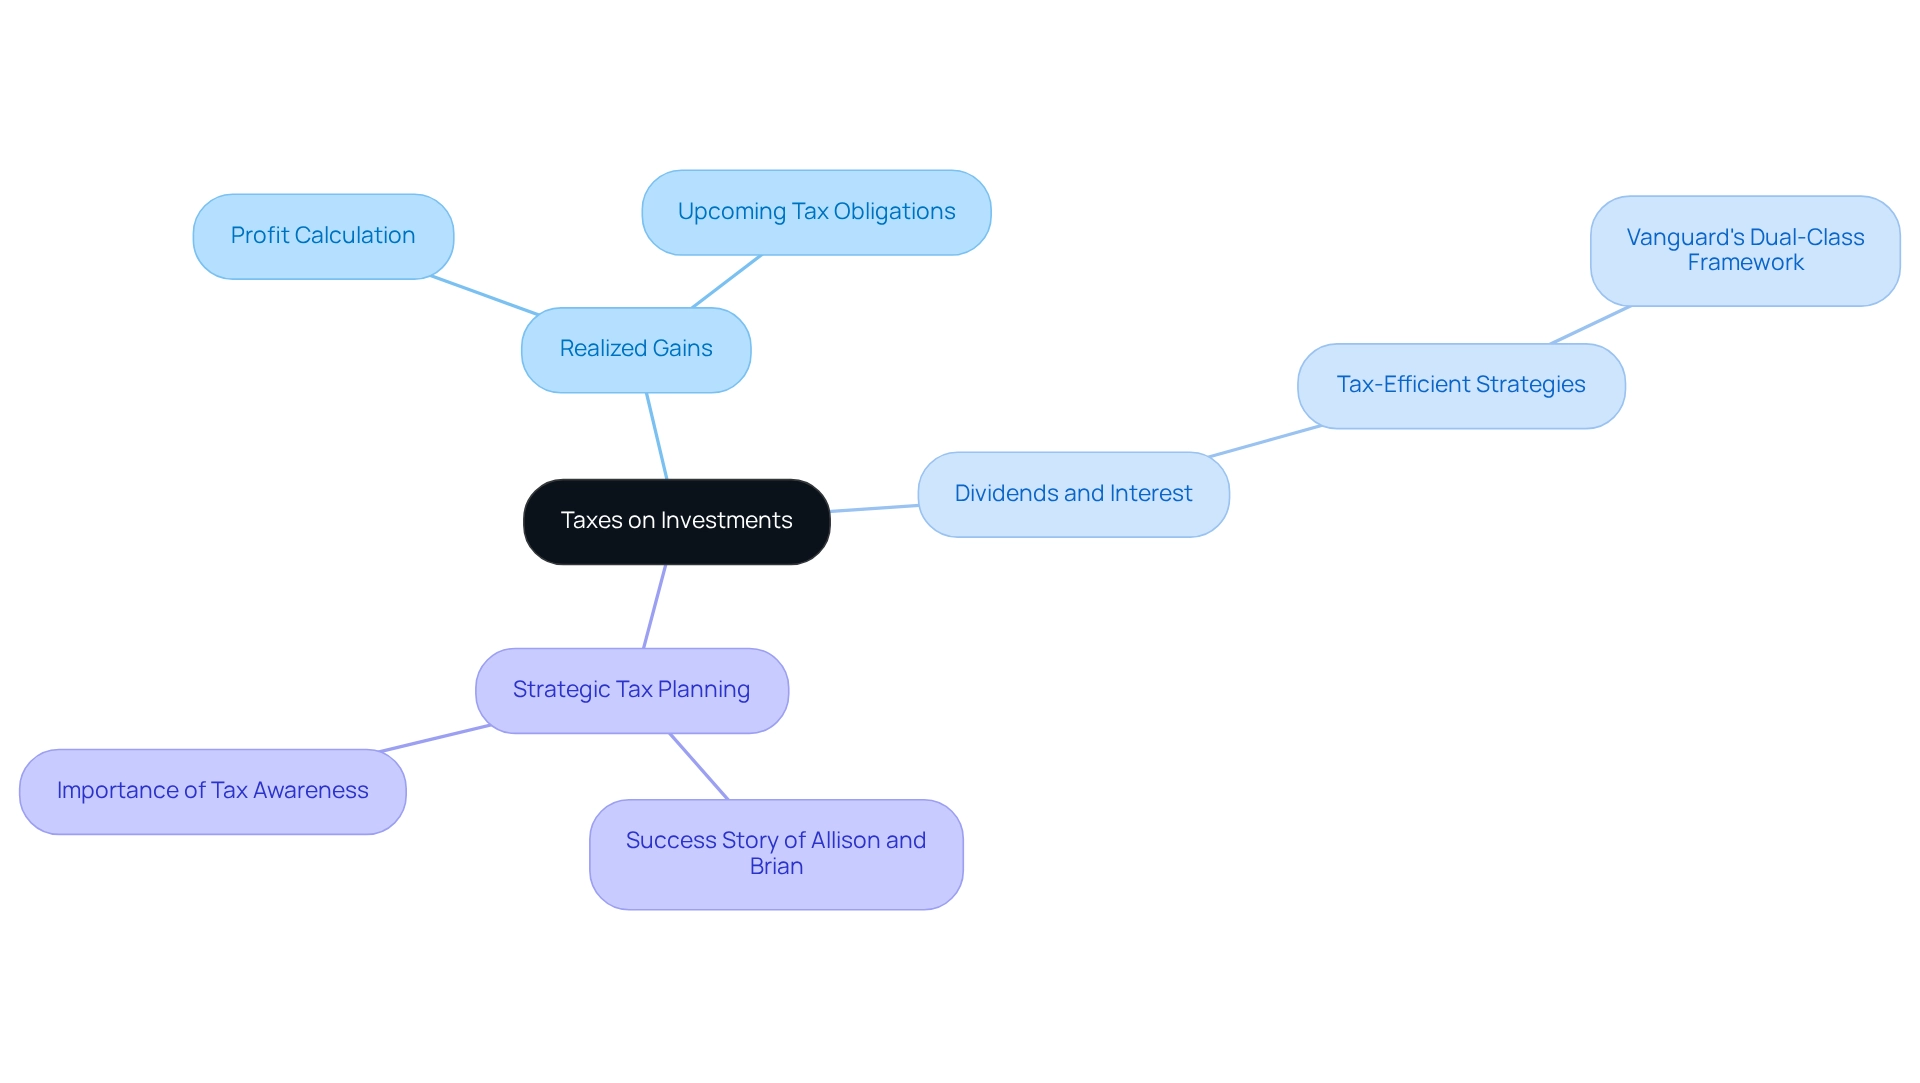
You don’t have to worry about paying taxes on your investments if you choose not to sell them. Taxes are only incurred on realized gains, which happen when an asset is sold for a profit. Imagine feeling relieved knowing that while dividends and interest income are taxed when received, capital gains taxes only apply when you decide to sell your investment. This allows you to defer tax liabilities until you’re ready to realize those gains, giving you more control over your financial journey.
It’s important to understand that this flexibility can be a significant advantage for you as a parent. By managing your investments wisely, you can align your financial goals with your family’s priorities. Together, we can navigate this journey, ensuring that your decisions support your family’s future.
Remember, we’re here for you. If you have any questions or need assistance, don’t hesitate to reach out. With the right guidance, you can make informed decisions that benefit your family for years to come.
Key Highlights:
- Investment taxes focus on capital gains, dividends, and interest income, which are crucial for financial planning.
- Capital gains are classified into short-term and long-term, with favorable tax rates for long-term holdings in 2025, typically capped at 15% for most individuals.
- Dividends are taxed at lower rates than ordinary income if they are qualified, impacting overall tax liability.
- Interest income is taxed as ordinary income, lacking the favorable rates available for capital gains and dividends.
- Realized gains incur tax liabilities upon selling an asset, while dividends and interest are taxed when received, regardless of asset liquidation.
- Strategies to minimize investment taxes include holding investments long-term, utilizing tax-advantaged accounts like IRAs and 401(k)s, and tax-loss harvesting.
- Awareness of potential capital gains distributions from mutual funds or ETFs can help in minimizing tax impacts.
- Resources for managing investment taxes include tax software, calculators, financial advisors, and educational websites, which can enhance informed decision-making.
- Effective tax planning can significantly improve a family’s financial situation, as illustrated by the success story of Allison and Brian.
Introduction
Navigating the intricate world of investment taxes can often feel overwhelming, especially for young families striving to secure their financial future. It’s essential to grasp the fundamentals—understanding capital gains, dividends, and interest income—because each element significantly impacts your tax obligations.
Imagine if you could optimize your investment strategies by recognizing when taxes apply and employing effective minimization techniques. With a wealth of resources at your fingertips, from user-friendly tax software to compassionate financial advisors, you can equip yourself with the knowledge needed to make informed decisions that align with your family’s values.
This article explores the core aspects of investment taxes, illustrating how thoughtful planning can lead to substantial savings and enhance your family’s financial security. We’re here for you, ready to support you on this journey.
Understand Investment Tax Basics
Investment taxes primarily focus on capital profits, dividends, and interest income. Understanding these essential concepts is crucial for navigating your financial landscape:
- Capital Gains: This refers to the profit realized from selling an asset for more than its purchase price. Capital profits are classified into short-term (for assets held one year or less) and long-term (for assets held longer than one year). In 2025, long-term capital profit tax rates are generally favorable, with most individuals paying no more than 15%, according to the IRS. However, for those with higher incomes, such as married couples filing jointly with income exceeding $751,600, the tax rate can rise to 37%.
- Dividends: These are distributions made by corporations to their shareholders, typically derived from profits. In 2025, qualified dividends are taxed at lower rates than ordinary income, making them a more tax-efficient type of income. Understanding the distinction between qualified and non-qualified dividends is crucial, as it affects your overall tax liability.
- Interest Income: This is the income generated from interest-bearing accounts or bonds, which is taxed as ordinary income. Unlike capital profits and dividends, interest income does not enjoy favorable tax rates, making it essential to consider when formulating your financial strategy.
Imagine Allison and Brian, who sought assistance from Bright Advisers to enhance their financial circumstances through efficient tax planning. Grasping these details can significantly influence your financial planning and decision-making regarding assets. Bright Advisers helped them recognize particular tax strategies, such as optimizing their capital gains and utilizing tax-efficient financial tools. By understanding these fundamentals, you can better foresee whether you pay taxes on investments if you don’t sell them yet. This knowledge empowers you to make informed decisions that align with your financial goals, especially as you work to build and secure your family’s financial future. We’re here for you, and together, we can navigate this journey.
Identify When Taxes Apply to Investments
Taxes on assets can feel overwhelming, but understanding them is crucial for your family’s financial health. Let’s explore some key scenarios where taxes might arise:
- Realized Gains: When you sell an asset for a profit, you incur a tax liability. This profit is calculated by subtracting the purchase price (cost basis) from the sale price. As we approach 2025, it’s important to grasp the realized profits tax consequences, as families may face increased obligations based on their financial activities.
- Dividends and Interest Payments: Taxes apply to dividends and interest income as they are received, regardless of whether you sell the underlying investment. This means that even without liquidating assets, it’s vital to consider these income sources when crafting your tax strategy, particularly when asking do you pay taxes on investments if you don’t sell, as investors may owe taxes on capital returns distributed by mutual funds and ETFs. For example, Vanguard’s innovative dual-class framework allows for tax-efficient in-kind redemptions, which can minimize capital distributions, providing significant tax advantages for shareholders. This approach not only benefits current shareholders but also shapes how families can strategize their finances to avoid unnecessary tax burdens.
Additionally, the Joint Committee of Taxation has estimated that repealing Section 852(b)(6) could generate over $200 billion in tax revenue over the next decade. This highlights the importance of understanding tax policies that impact your financial decisions.
By recognizing these triggers, families can better anticipate tax liabilities and plan their financial strategies effectively. Consider the success story of Allison and Brian with Bright Advisers. Their strategic tax planning, which included enhancing capital returns and utilizing tax-efficient investment options, led to an improved financial situation. They secured their children’s future through education funding and gained the ability to retire sooner. This proactive approach brought them peace of mind and allowed for more quality time with their loved ones.
As tax professionals emphasize, being aware of these obligations is essential for effective financial management, especially for families striving to build and maintain wealth. Remember, we’re here for you—together, we can navigate this journey toward a secure financial future.
Implement Strategies to Minimize Investment Taxes
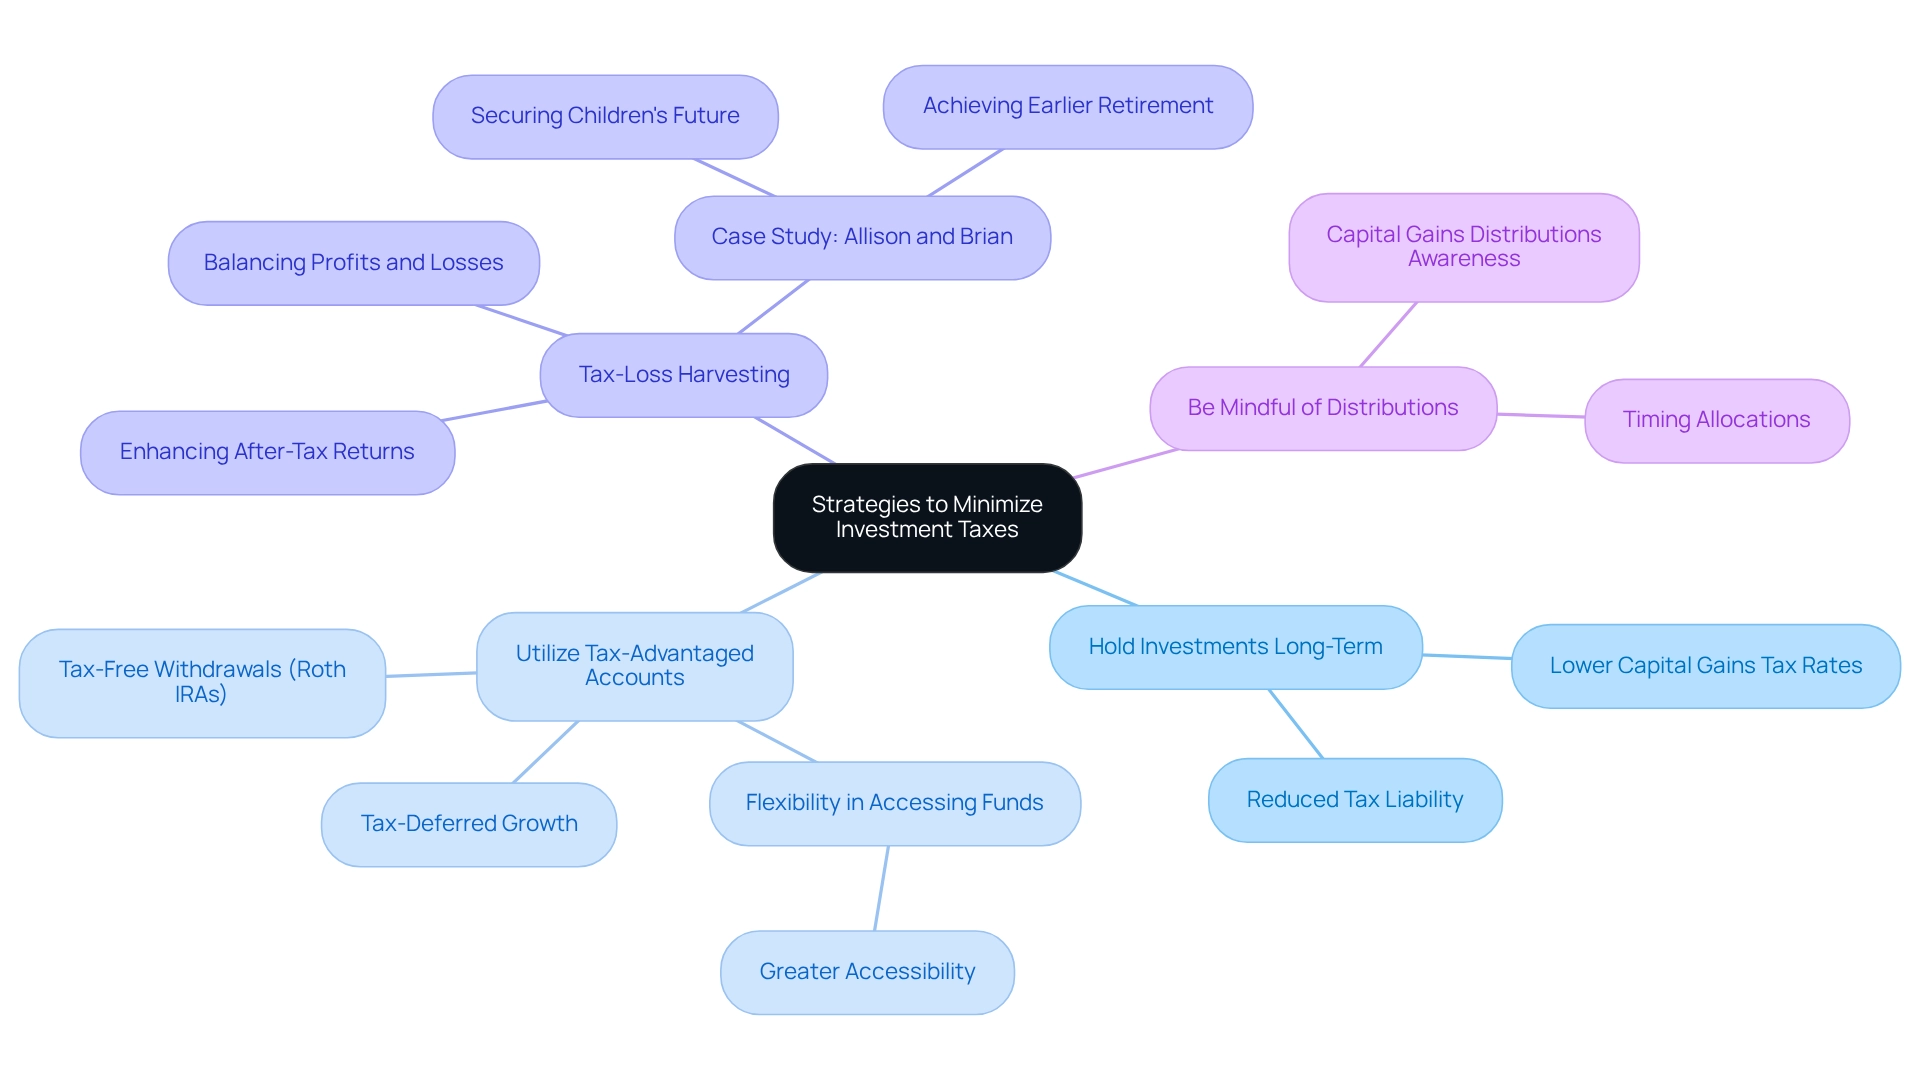
To effectively minimize investment taxes, consider these compassionate strategies designed with your family’s needs in mind:
- Hold Investments Long-Term: Imagine the peace of mind that comes from maintaining your investments for over a year. By doing so, you can take advantage of lower long-term capital gains tax rates, leading to the question of whether you pay taxes on investments if you don’t sell, which significantly reduces your tax liability compared to short-term gains taxed at higher ordinary income rates.
- Utilize Tax-Advantaged Accounts: Think about the benefits of accounts like IRAs and 401(k)s that allow your assets to grow either tax-deferred or tax-free. For instance, Roth IRAs offer tax-exempt withdrawals, making them a wonderful option for families looking to enhance their growth while minimizing expenses. As James Royal, Ph.D., observes, “You’ll enjoy some of the same advantages — such as postponed capital gains taxes — as you would in an IRA, but you’ll have greater flexibility to access your funds, should the need arise.”
- Tax-Loss Harvesting: This strategy involves selling underperforming investments to balance profits from successful ones, effectively reducing your overall tax burden. By strategically realizing losses, you can enhance your after-tax returns. This approach was crucial for families like Allison and Brian, who found that by optimizing their tax situation, including understanding do you pay taxes on investments if you don’t sell, they could secure their children’s future and achieve the opportunity to retire sooner, resulting in substantial savings and enhanced financial security.
- Be Mindful of Distributions: When investing in mutual funds or ETFs, it’s essential to be aware of potential capital gains distributions. Timing your allocations around these distributions can help you minimize tax impacts, ensuring your family’s financial goals remain on track.
Furthermore, it’s important to know that the net earnings tax applies to modified adjusted gross income (MAGI) exceeding $125,000 for those married filing separately, which could influence your understanding of do you pay taxes on investments if you don’t sell in your tax planning approaches. This tax consideration can affect families like Allison and Brian, as they must consider do you pay taxes on investments if you don’t sell when strategizing their financial allocations.
By applying these nurturing strategies, you can achieve significant tax savings and enhanced returns, allowing your family to focus on building a stable financial future. For example, utilizing accounts with financial benefits can assist families in deferring or evading capital gains levies, as highlighted in the success story of Allison and Brian with Bright Advisers. Together, we can navigate this journey towards financial security.
Access Resources for Investment Tax Management
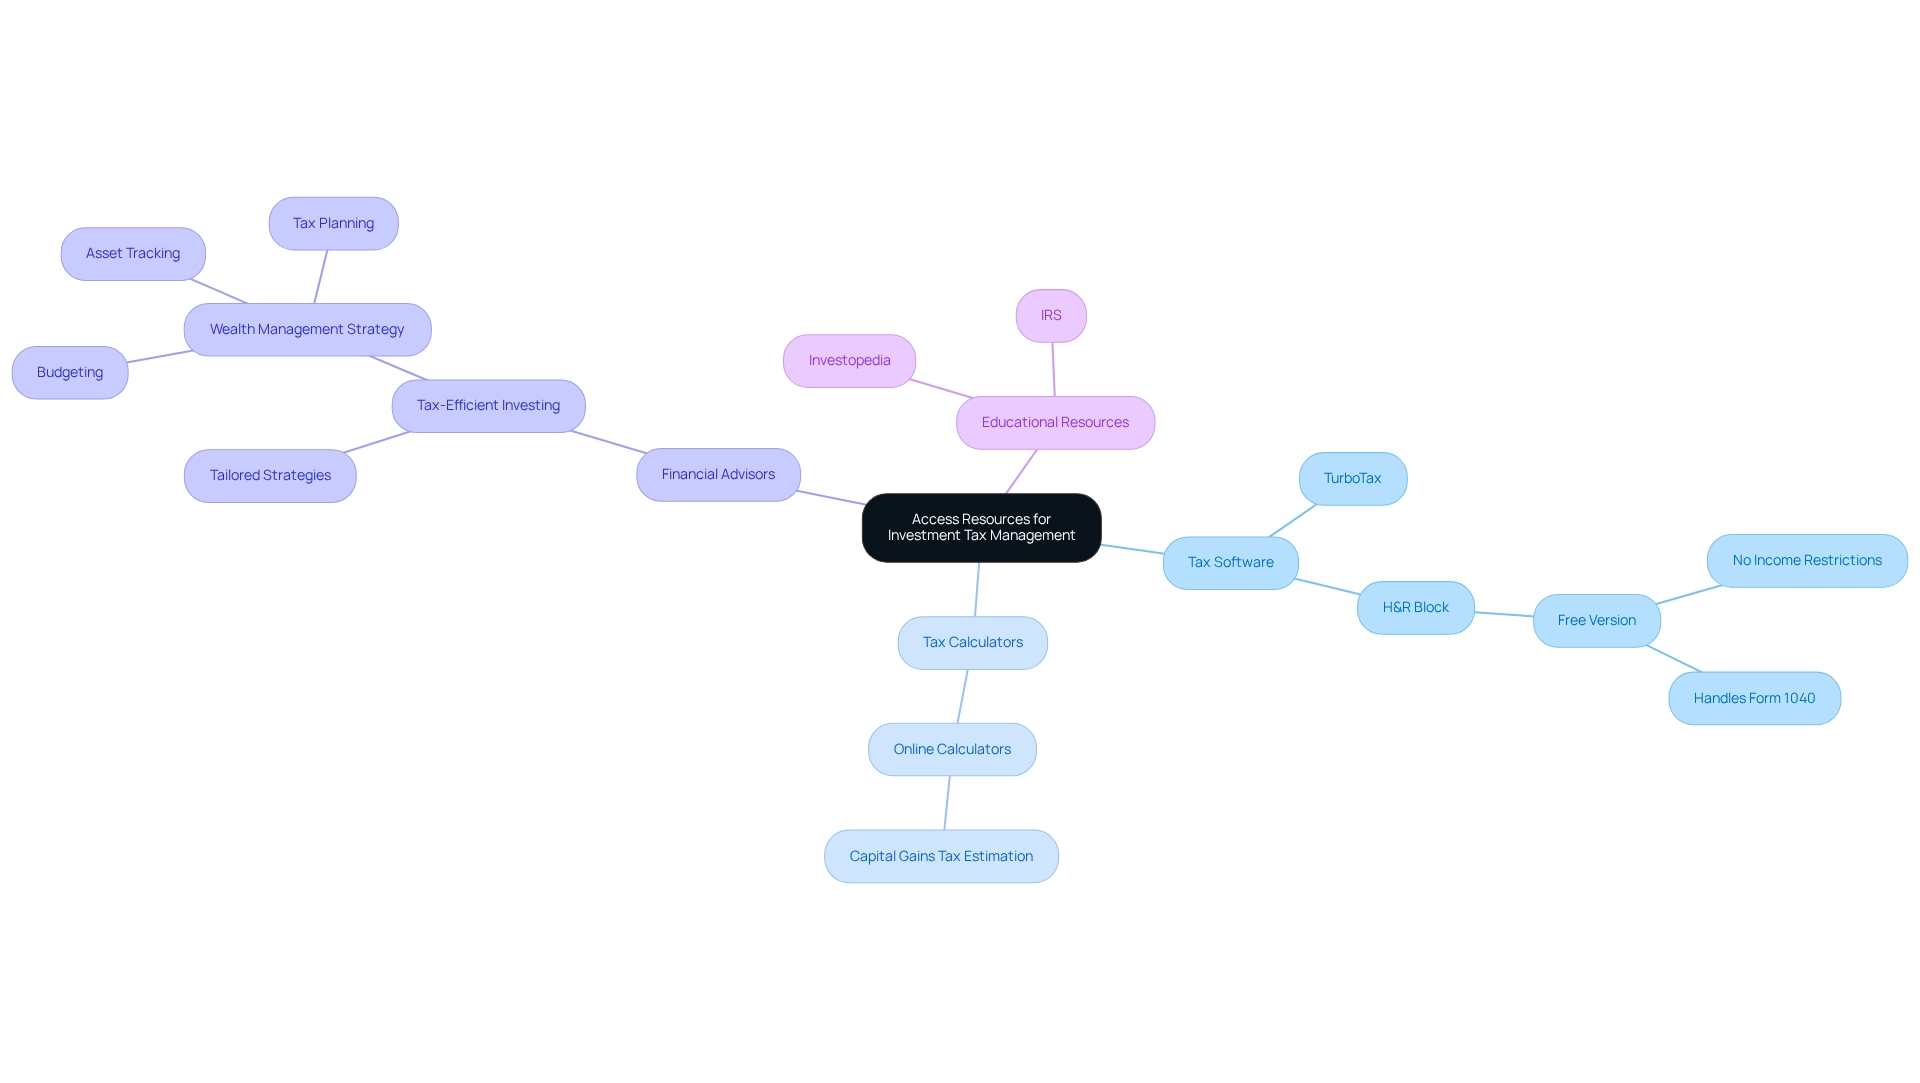
To help you manage your financial obligations with ease, consider exploring these valuable resources:
-
Tax Software: Tools like TurboTax and H&R Block can be your best friends when preparing returns. They ensure you make the most of available deductions and credits. Notably, H&R Block’s free version is accessible for all income levels and can handle Form 1040, making it a great option for many households. Remember, the capital gains tax rate can change based on how long you hold an asset before selling, with long-term gains enjoying lower tax rates.
-
Tax Calculators for Assets: Online calculators are incredibly useful for estimating capital gains taxes and understanding the tax implications of your decisions. In 2025, more people are using these calculators, showing a growing awareness among investors about the importance of tax planning.
-
Financial Advisors: Speaking with a financial advisor who specializes in tax-efficient investing can lead to tailored strategies that fit your family’s unique financial situation. Their knowledge can help you navigate complex tax scenarios and improve your financial approach. Bright Advisers highlights a comprehensive wealth management strategy, blending budgeting, asset tracking, and tax planning to empower families. As Kathy Yakal, a freelancer for PCMag, points out, having access to knowledgeable professionals can significantly enhance your financial decision-making, especially when considering the commitment to low fund fees that increase accessibility for families.
-
Educational Resources: Websites like Investopedia and the IRS offer a wealth of information on tax laws and financial strategies, helping you stay informed and make educated choices.
By engaging with these resources, you can deepen your understanding of tax implications and make informed choices that positively impact your family’s financial future. For example, case studies show that families using tax software like Cash App Taxes found it helpful for basic filing; however, they noticed limitations in support for more complex tax situations, such as missing forms and a lack of expert assistance. This underscores the importance of selecting the right tools and resources to meet your specific needs. Ultimately, effectively utilizing these resources can lead to better investment tax management, including understanding do you pay taxes on investments if you don’t sell, and a more secure financial future for your family. We’re here for you, and together, we can navigate this journey.
Conclusion
Understanding investment taxes is crucial for families looking to secure their financial future. By grasping the fundamentals—capital gains, dividends, and interest income—families can navigate their tax obligations more effectively. Imagine the journey of individuals like Allison and Brian, who discovered the transformative power of informed tax planning. They learned to optimize their capital gains, leverage tax-efficient investment vehicles, and implement strategies like tax-loss harvesting. This ultimately led to improved financial security and a brighter future for their children.
It’s important to recognize when taxes apply to investments. Realized gains, dividends, and the unique tax implications of mutual funds and ETFs necessitate careful planning. Families that proactively manage their tax liabilities can enjoy peace of mind, as demonstrated by the success stories shared throughout this article. By employing strategies such as holding investments long-term and utilizing tax-advantaged accounts, families can significantly reduce their tax burden and enhance their overall investment returns.
Finally, accessing the right resources—such as tax software, financial advisors, and educational platforms—equips families with the tools needed for effective investment tax management. With a wealth of information and support available, families can make informed decisions that align with their financial goals. Together, we can navigate this journey toward financial security. With the right knowledge and strategies, families can build a solid foundation for their future.
Frequently Asked Questions
What are the main types of investment taxes?
Investment taxes primarily focus on capital profits, dividends, and interest income.
What are capital gains and how are they classified?
Capital gains refer to the profit realized from selling an asset for more than its purchase price. They are classified into short-term (for assets held one year or less) and long-term (for assets held longer than one year).
What are the tax rates for long-term capital profits in 2025?
In 2025, long-term capital profit tax rates are generally favorable, with most individuals paying no more than 15%. However, for higher-income individuals, such as married couples filing jointly with income exceeding $751,600, the tax rate can rise to 37%.
What are dividends and how are they taxed?
Dividends are distributions made by corporations to their shareholders, typically derived from profits. In 2025, qualified dividends are taxed at lower rates than ordinary income, making them a more tax-efficient type of income.
What is the difference between qualified and non-qualified dividends?
The distinction between qualified and non-qualified dividends affects your overall tax liability, as qualified dividends are taxed at lower rates.
How is interest income taxed?
Interest income is generated from interest-bearing accounts or bonds and is taxed as ordinary income. Unlike capital profits and dividends, interest income does not benefit from favorable tax rates.
How can understanding investment taxes influence financial planning?
Grasping these details can significantly influence your financial planning and decision-making regarding assets, allowing for optimized capital gains and the use of tax-efficient financial tools.
What role do financial advisers play in tax planning?
Financial advisers, like Bright Advisers, can assist individuals in enhancing their financial circumstances through efficient tax planning by recognizing particular tax strategies.
List of Sources
- Understand Investment Tax Basics
- Dividend Tax Rate for 2024 and 2025 (https://smartasset.com/taxes/dividend-tax-rate)
- 2024 and 2025 Capital Gains Tax Rates and Rules – NerdWallet (https://nerdwallet.com/article/taxes/capital-gains-tax-rates)
- Identify When Taxes Apply to Investments
- Unplugging Heartbeat Trades and Reforming the Taxation of ETFs | The University of Chicago Business Law Review (https://businesslawreview.uchicago.edu/print-archive/unplugging-heartbeat-trades-and-reforming-taxation-etfs)
- (PDF) The Role of Taxes in the Rise of ETFs (https://researchgate.net/publication/368685644_The_Role_of_Taxes_in_the_Rise_of_ETFs)
- Explained: How your mutual fund investments will be taxed in financial year 2025 (https://m.economictimes.com/mf/analysis/explained-how-your-mutual-fund-investments-will-be-taxed-in-financial-year-2025/articleshow/119034030.cms)
- Implement Strategies to Minimize Investment Taxes
- Capital Gains Tax Rates and Potential Changes in 2025 (https://investopedia.com/taxes/capital-gains-tax-101)
- Tax-Efficient Investing: 7 Ways To Minimize Taxes | Bankrate (https://bankrate.com/investing/tax-efficient-investing-guide)
- trajanwealth.com (https://trajanwealth.com/blog/tax-smart-investing-strategies-to-minimize-your-2025-tax-bill)
- myfw.com (https://myfw.com/articles/strategies-to-minimize-capital-gains-taxes-on-your-investments)
- Access Resources for Investment Tax Management
- Best Tax Software of 2025 – NerdWallet (https://nerdwallet.com/p/best/taxes/tax-software)
- 2025 Capital Gains Tax Calculator – Long-Term & Short-Term Gains (https://smartasset.com/investing/capital-gains-tax-calculator)
- pcmag.com (https://pcmag.com/picks/the-best-tax-software)
- TurboTax® Investment Tax Calculators & Tools 2024-2025 (https://turbotax.intuit.com/tax-tools/investment-tax-calculators)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Tax Management for high-income W-2 families at Bright Advisers.
Keep reading