

Overview
Understanding the world of trusts can be overwhelming, especially when it comes to taxes. It’s essential to know that trusts do pay taxes on capital gains, but the way they are taxed varies significantly based on whether the trust is revocable or irrevocable.
Imagine if you had a revocable trust. In this case, the earnings are reported on your tax return, allowing you to avoid entity-level taxation. This can provide a sense of relief, knowing that your financial burden is lightened.
On the other hand, irrevocable trusts operate differently. They incur taxes at the trust level, which can lead to high federal rates. This highlights the importance of understanding the type of trust you have. It’s crucial for effective tax planning and ensuring that your family’s financial future is secure.
Navigating these complexities might feel daunting, but remember, you’re not alone. Together, we can explore your options and find the best path for your family. We’re here for you, ready to support you in making informed decisions that align with your values and goals.
Key Highlights:
- Trusts are legal arrangements where a trustee manages assets for a beneficiary, categorised as revocable or irrevocable.
- Revocable trusts allow grantors to control assets, with earnings reported on their individual tax returns, avoiding entity-level taxation.
- Irrevocable trusts transfer control to trustees, with earnings taxed at the trust level, potentially reaching a federal tax rate of 37%.
- Choosing between trust types involves strategic considerations, impacting tax liabilities and financial planning for families.
- Beneficiaries of trusts may face lower tax rates on distributed capital gains compared to the trust’s tax rates.
- Steps for reporting capital gains in trusts include determining the trust type, calculating gains, filling out tax documents, distributing earnings, and filing returns.
- Resources for managing trust taxes include IRS publications, tax software, financial advisors, and online forums.
Introduction
Navigating the complexities of trust taxation can feel overwhelming, especially when it comes to understanding capital gains. Trusts, whether revocable or irrevocable, carry unique tax responsibilities that can significantly influence your family’s financial planning. As you explore your options, a critical question arises: how do trusts handle taxes on capital gains?
Imagine if you could grasp the intricacies of trust taxation with ease. This article offers a step-by-step guide to help you understand your obligations while identifying strategies that could lead to substantial tax savings. It’s important to understand how families can make informed decisions that align with their financial goals, all while minimizing tax burdens.
Together, we can navigate this journey, ensuring that your family’s values and priorities are at the forefront of your financial decisions.
Understand Trusts and Their Tax Responsibilities
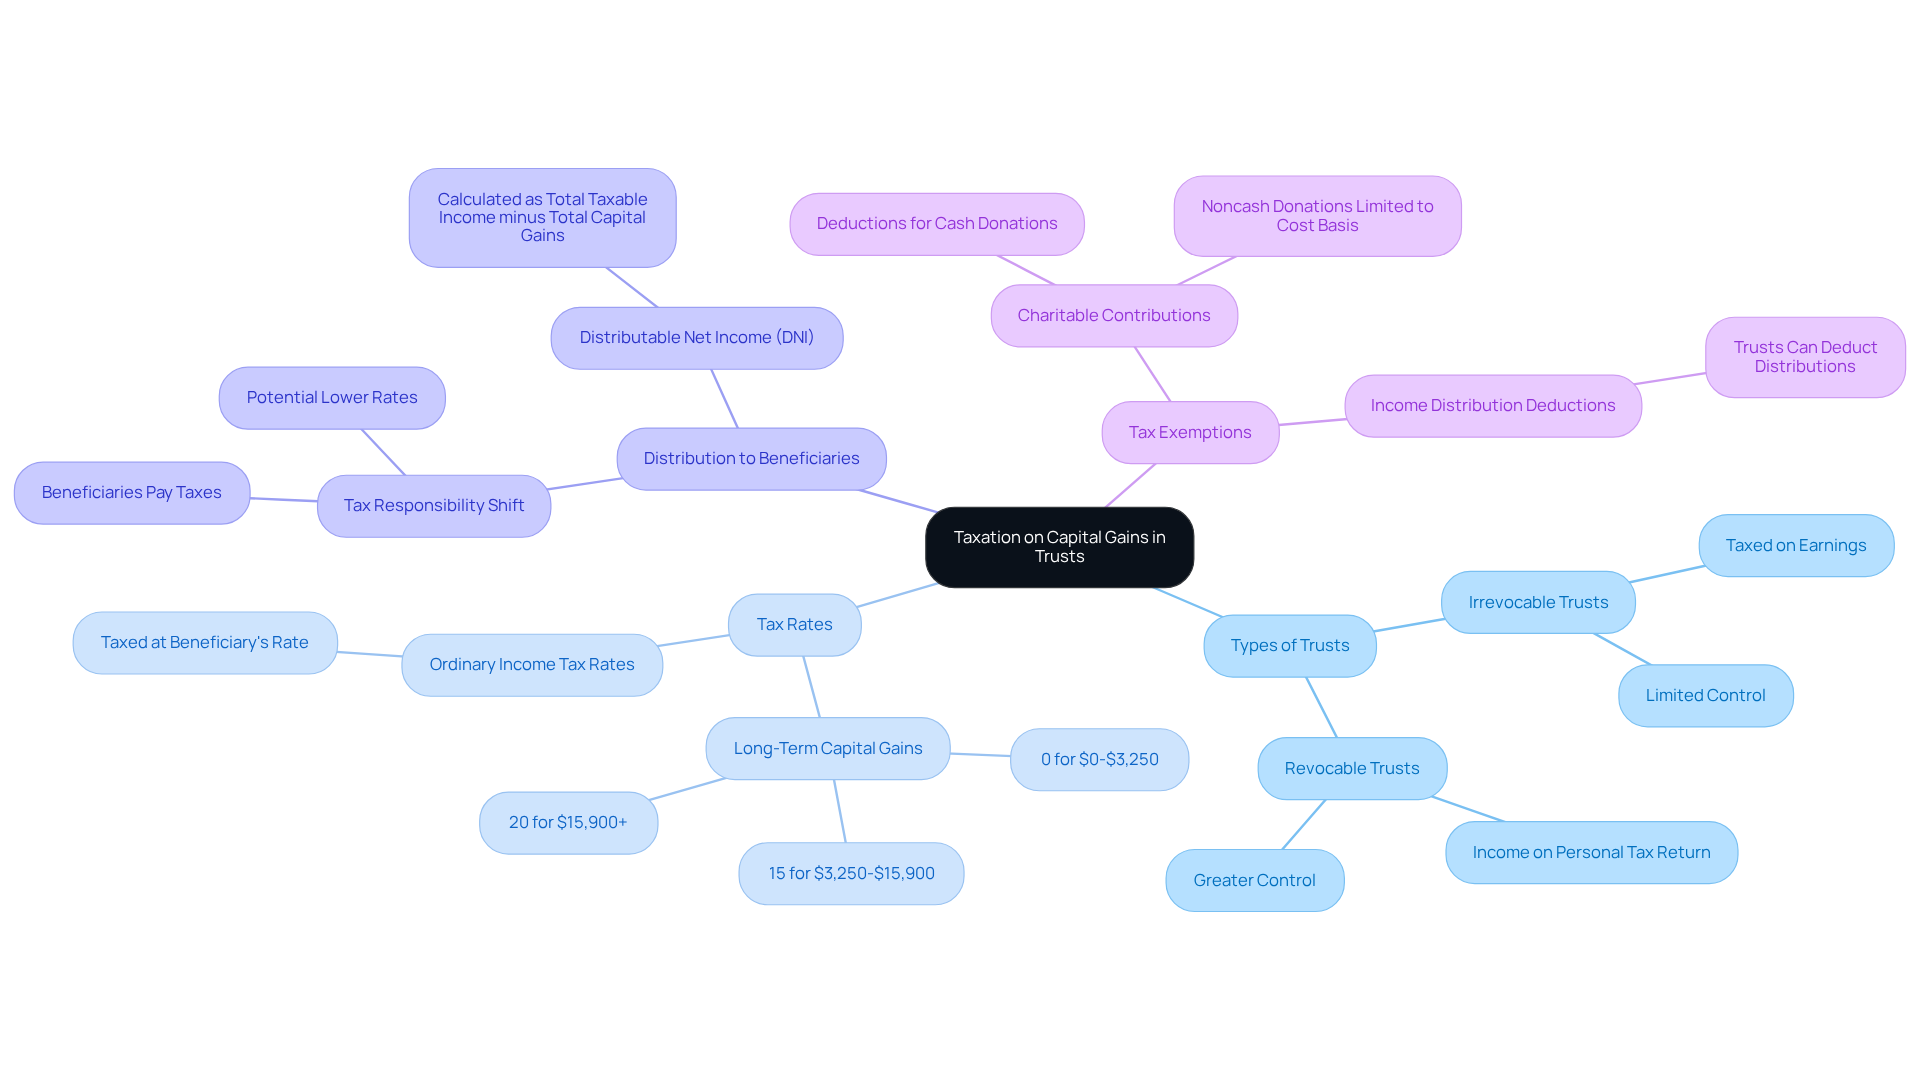
An arrangement is a legal setup where a trustee oversees assets for the benefit of a beneficiary. In the United States, financial arrangements can be categorized as either revocable or irrevocable, each carrying distinct tax responsibilities. As we look toward 2025, the majority of agreements are revocable, allowing the grantor to maintain control over the assets and their distribution. This flexibility means that earnings, including capital profits, are typically reported on the grantor’s individual tax return, leading to the consideration of how does a trust pay taxes on capital gains, thus avoiding taxation at the entity level.
In contrast, irrevocable arrangements relinquish control to the trustee, and any earnings generated, including capital increases, lead to the question of how does a trust pay taxes on capital gains at the arrangement level. For instance, if an irrevocable arrangement realizes capital gains, it prompts the question of how much does a trust pay taxes on capital gains, as it will be subject to federal tax brackets for such entities, which can reach a top rate of 37% after just $15,650 of income. This significant tax burden underscores the importance of understanding how the type of fiduciary arrangement can impact tax liabilities, particularly in addressing the question of how does a trust pay taxes on capital gains.
Tax experts often emphasize strategic considerations when choosing between revocable and irrevocable arrangements. One expert notes, ‘Revocable arrangements offer flexibility and ease of management, while irrevocable arrangements can provide tax benefits and asset protection.’ This distinction is vital for families planning their financial futures, particularly for high-income families like those of Allison and Brian, who may be missing out on substantial tax savings and investment opportunities due to insufficient tax planning.
By partnering with Bright Advisers, families can access tailored strategies to optimize their tax situation and secure their financial future. Ultimately, navigating the complexities of taxation related to fiduciary matters, including questions like does a trust pay taxes on capital gains, requires a solid understanding of these differences. By understanding how does a trust pay taxes on capital gains within each category of fiduciary arrangement, individuals can make informed choices that align with their financial objectives, empowering them to achieve financial security and independence.

Identify Conditions for Taxation on Capital Gains in Trusts
Understanding how capital gains are taxed in estates, particularly regarding whether a trust does pay taxes on capital gains, can feel overwhelming, especially when you’re focused on providing for your family. Typically, these gains are taxed when an entity sells an asset for more than its purchase price, raising the question of how does a trust pay taxes on capital gains. However, several key factors can influence whether or not a trust does pay taxes on capital gains, and it’s important to navigate them thoughtfully.
Imagine if you were faced with a choice between irrevocable and revocable arrangements. The tax treatment varies significantly between these two. Irrevocable arrangements usually incur taxes on their earnings, which raises the question of how does a trust pay taxes on capital gains, while revocable arrangements allow the grantor to declare earnings on their personal tax return. This distinction is crucial for your financial planning.
When an estate allocates capital gains to beneficiaries, it leads to the consideration of whether a trust does a trust pay taxes on capital gains at the beneficiaries’ tax rates instead of the estate’s rates. This means that your loved ones might benefit from lower tax obligations, which raises the question of how does a trust pay taxes on capital gains. Often, beneficiaries fall into broader earnings brackets, which can lead to more advantageous tax treatment. It’s a comforting thought that your planning can ease the financial burden on your family.
Certain arrangements may also qualify for tax exemptions or reduced rates based on their structure or purpose, leading to inquiries about how does a trust pay taxes on capital gains. For instance, if an entity allocates income to beneficiaries, it can subtract these distributions from its taxable income, optimizing the tax burden. This strategic allocation can significantly influence the overall tax obligation for both the entity and its beneficiaries, particularly in understanding how does a trust pay taxes on capital gains.
Let’s consider a scenario: if an entity recognizes $10,000 in capital profits but allocates $5,000 to recipients, those recipients will be liable for taxes on that distributed sum, which leads us to ask, does a trust pay taxes on capital gains? They may face lower rates than the entity would encounter, highlighting the importance of thoughtful distribution.
Navigating these complexities can be daunting, but remember, we’re here for you. Together, we can navigate this journey, ensuring that your family’s financial future remains secure and bright.
Follow Steps for Reporting Capital Gains in Trusts
Navigating the world of fiduciary arrangements can feel overwhelming, particularly regarding the question of how does a trust pay taxes on capital gains. But don’t worry; we’re here to guide you through it step by step, ensuring you feel confident and supported.
-
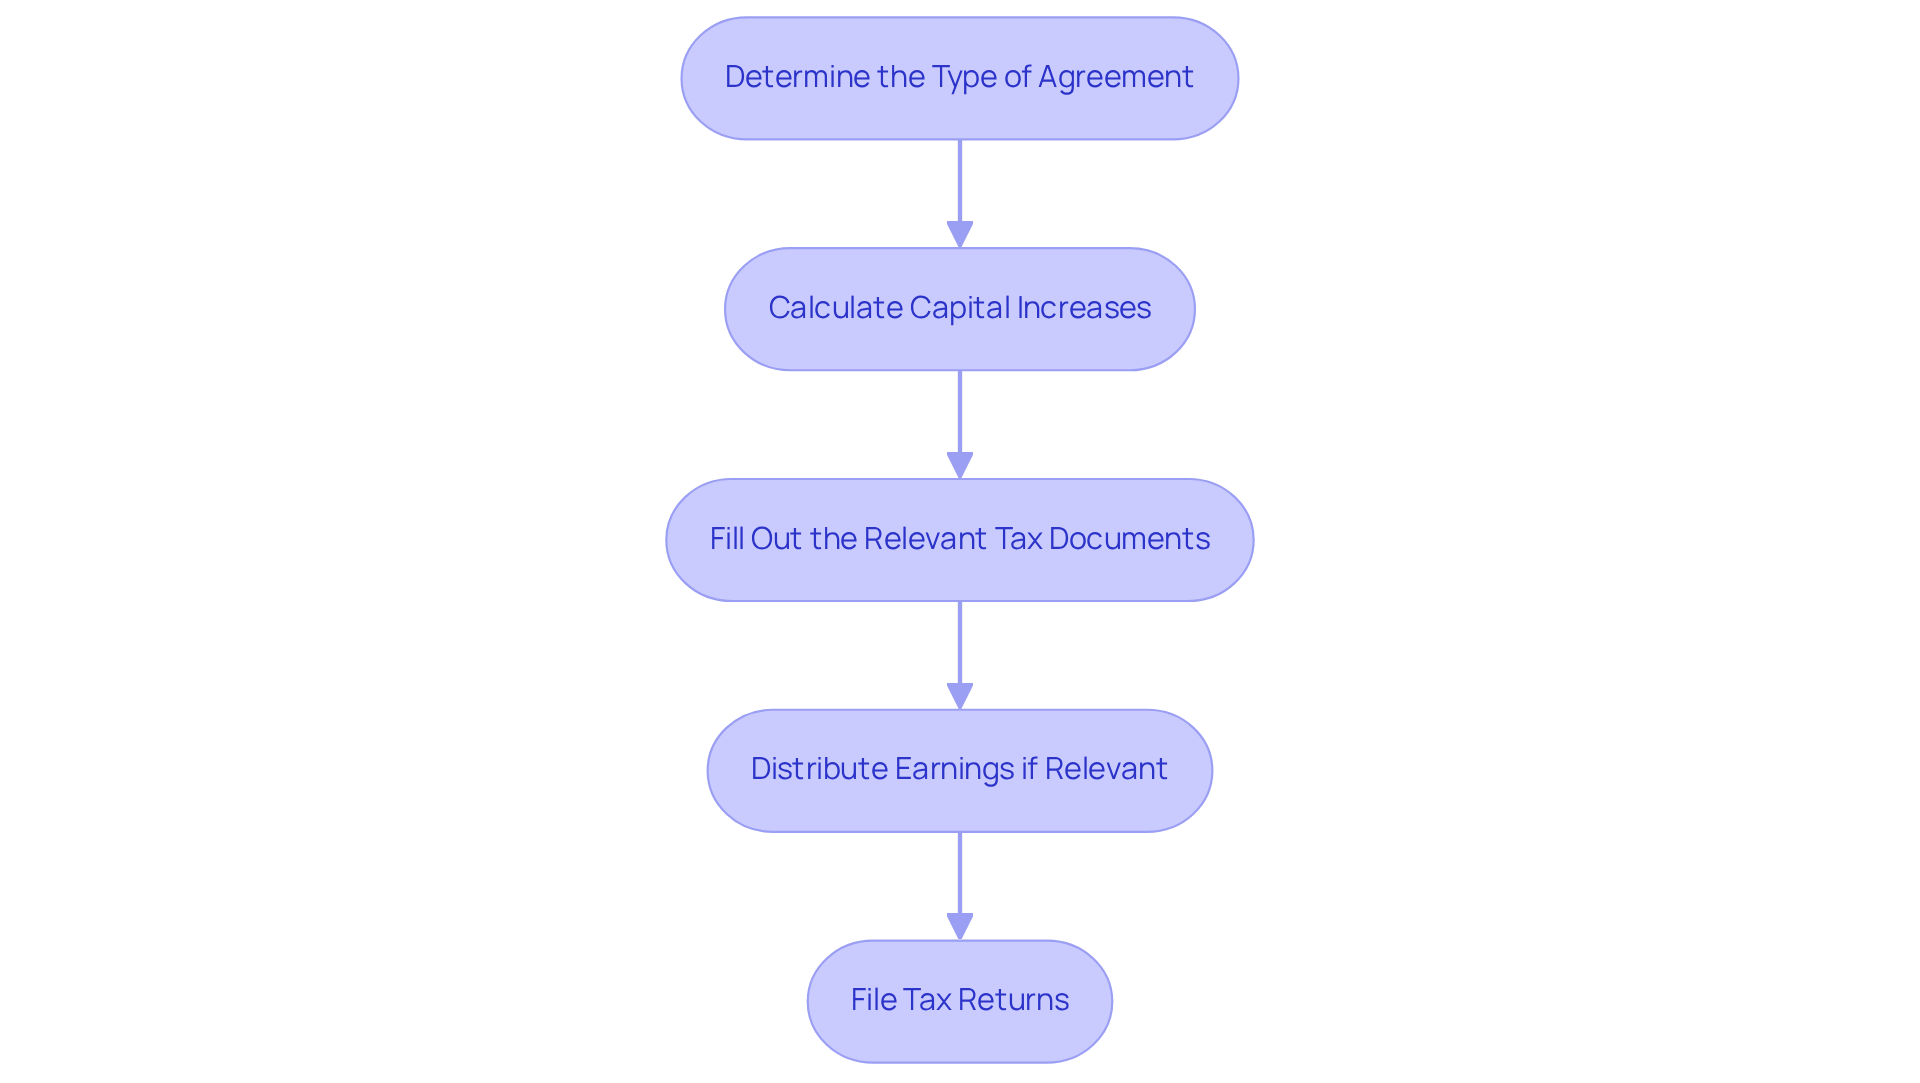
Determine the Type of Agreement: First, it’s essential to understand whether your arrangement is revocable or irrevocable. This distinction is crucial as it influences your reporting obligations.
-
Calculate Capital Increases: Next, take a moment to calculate the capital increase. Simply subtract the asset’s basis—this includes the purchase price and any improvements—from the sale price. This will give you a clear picture of your capital increase.
-
Fill Out the Relevant Tax Documents: When it comes to paperwork, for non-revocable estates, you’ll need to use IRS Form 1041 to report all earnings, including capital profits. If your arrangement is revocable, you’ll report these profits on your individual tax return.
-
Distribute Earnings if Relevant: If your fund assigns capital profits to beneficiaries, remember to provide a Schedule K-1 to each one. This document outlines their portion of the earnings, ensuring transparency and clarity.
-
File Tax Returns: Finally, it’s vital to file all tax forms by the deadline to avoid any penalties. In 2025, keep in mind that entities with gross income of $600 or more must submit Form 1041. This highlights the importance of timely and accurate reporting.
Additionally, be aware that recent changes to IRS Form 1041 may introduce new reporting obligations that could affect how estates report capital gains and whether a trust does a trust pay taxes on capital gains. By following these steps, you can ensure compliance with tax regulations and help preserve your entity’s financial integrity.
Together, we can navigate this journey, ensuring that your family’s financial future remains secure.
Utilize Resources for Trust Tax Management
Managing fiduciary taxes can feel overwhelming, but you’re not alone. There are several resources available to help you navigate this journey:
-
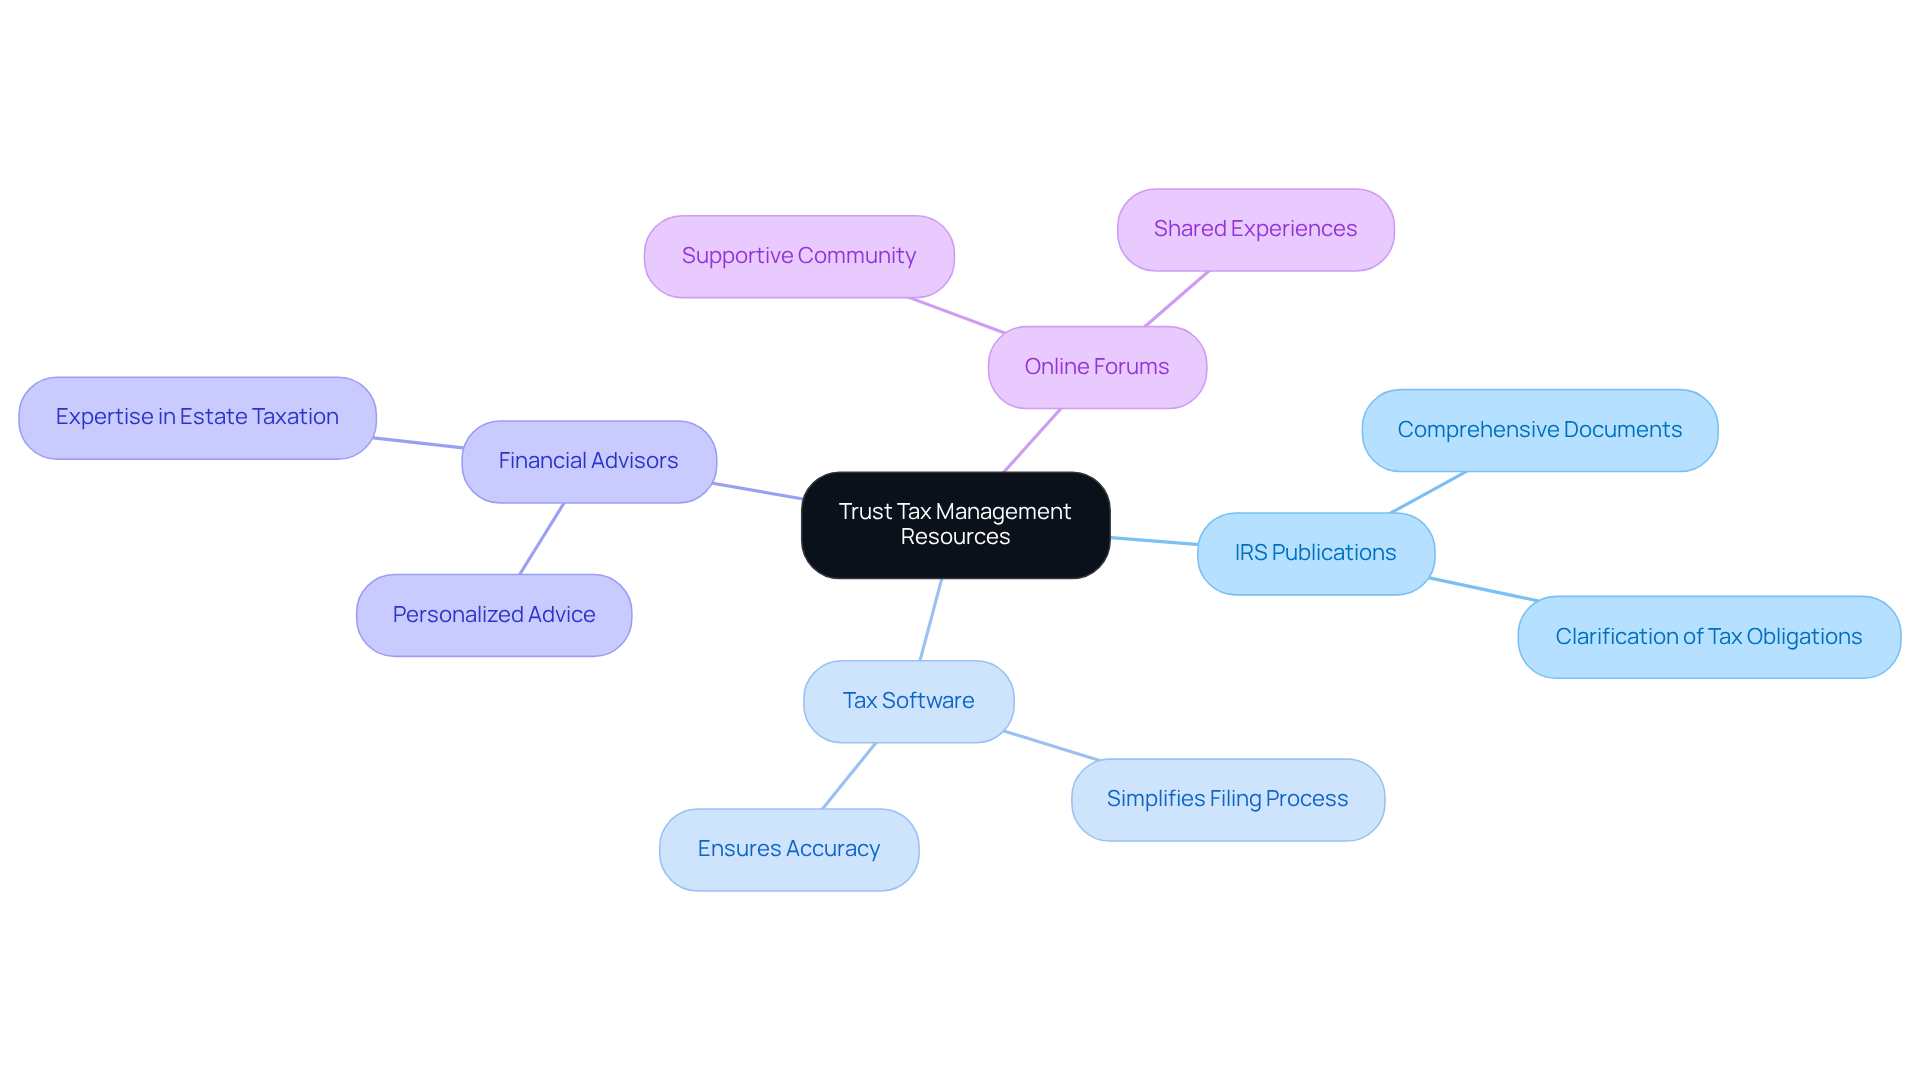
IRS Publications: The IRS provides comprehensive documents on estates, clarifying your tax obligations. In 2025, many taxpayers turned to these publications to better understand their responsibilities. Imagine having clear guidance at your fingertips.
-
Tax Software: Consider using tax preparation software that includes features specifically for fiduciary tax reporting. This can simplify the filing process and ensure accuracy in managing your estate’s tax responsibilities, giving you peace of mind.
-
Financial Advisors: Consulting with a financial consultant or tax expert who specializes in estates can offer you personalized advice. As Peter J Wall observes, having a CPA and a financial planner who understands estate taxation is crucial for structuring your investments efficiently. Think of it as having a trusted partner by your side.
-
Online Forums and Communities: Engaging in online groups focused on estate planning and asset management can provide valuable insights and shared experiences. These platforms can become a supportive community, offering encouragement and information.
By utilizing these resources, you can stay informed and compliant with trust tax regulations, especially regarding how does a trust pay taxes on capital gains. Remember, we’re here for you, ensuring that your financial planning remains on track for your family’s future.
Conclusion
Understanding the tax implications of trusts, especially in relation to capital gains, is vital for effective financial planning. Imagine the peace of mind that comes from knowing how different types of trusts can impact your family’s financial future. The distinction between revocable and irrevocable trusts is crucial in determining tax responsibilities. Revocable trusts allow you, the grantor, to report earnings on your personal tax return, while irrevocable trusts incur taxes at the entity level, which can lead to significant tax liabilities. This fundamental difference highlights the importance of making informed decisions about the type of trust that aligns with your financial goals.
It’s important to understand the conditions under which trusts are taxed on capital gains. Key insights include:
- How gains are allocated to beneficiaries
- The various tax brackets that may apply
Strategic planning can lead to advantageous tax treatment, particularly for beneficiaries who may fall into lower tax brackets. By taking the time to understand reporting requirements and utilizing resources like IRS publications and tax software, you can simplify trust tax management, ensuring compliance and maintaining financial integrity.
Ultimately, navigating the complexities of trust taxation is not just about compliance; it’s about empowering families to secure their financial futures. Together, we can explore the right strategies and resources to optimize your tax situation and provide for your loved ones more effectively. Engaging with financial advisors and utilizing available tools is crucial to ensure that trust management aligns with your long-term financial objectives. Remember, making informed choices today can pave the way for lasting financial security for your family.
Frequently Asked Questions
What is a trust?
A trust is a legal arrangement where a trustee manages assets for the benefit of a beneficiary.
What are the two main types of trusts in the United States?
The two main types of trusts are revocable and irrevocable trusts, each with distinct tax responsibilities.
How do revocable trusts impact tax reporting?
In revocable trusts, the grantor maintains control over the assets, and earnings, including capital gains, are reported on the grantor’s individual tax return, avoiding entity-level taxation.
What happens with taxes in irrevocable trusts?
In irrevocable trusts, control is relinquished to the trustee, and any earnings, including capital gains, are taxed at the trust level, subject to federal tax brackets, which can reach a top rate of 37% after $15,650 of income.
Why is it important to understand the tax implications of different trust types?
Understanding the tax implications is crucial as it can significantly affect tax liabilities, especially for high-income families who may miss out on tax savings and investment opportunities due to poor tax planning.
What are some strategic considerations when choosing between revocable and irrevocable trusts?
Revocable trusts offer flexibility and ease of management, while irrevocable trusts can provide tax benefits and asset protection.
How can families optimize their tax situation related to trusts?
Families can partner with tax experts, such as Bright Advisers, to access tailored strategies that help optimize their tax situation and secure their financial future.
List of Sources
- Understand Trusts and Their Tax Responsibilities
- Federal income tax and trust strategies | Trusts and taxes | Fidelity (https://fidelity.com/viewpoints/wealth-management/insights/trusts-and-taxes)
- SOI Tax Stats – Estate, gift and trust statistics | Internal Revenue Service (https://irs.gov/statistics/soi-tax-stats-estate-gift-and-trust-statistics)
- Trust and Estate Tax Compliance: Strategies to Minimize Liabilities – Wiss (https://wiss.com/trust-and-estate-tax-compliance-strategies-to-minimize-liabilities)
- Yes, Trustees Have Tax Duties. Here’s What to Know (https://ocwillsandtrusts.com/yes-trustees-have-tax-duties-heres-what-to-know)
- Trust Tax Rates and Exemptions for 2025 (https://smartasset.com/taxes/trust-tax-rates)
- Identify Conditions for Taxation on Capital Gains in Trusts
- Federal income tax and trust strategies | Trusts and taxes | Fidelity (https://fidelity.com/viewpoints/wealth-management/insights/trusts-and-taxes)
- Capital Gains Taxes: 2024 & 2025 Rates | City National Bank (https://cnb.com/personal-banking/insights/understanding-capital-gains-tax.html)
- How Trusts Are Taxed: A Guide for 2024 and 2025 (https://legalzoom.com/articles/how-trusts-are-taxed)
- Trust Tax Rates and Exemptions for 2025 (https://smartasset.com/taxes/trust-tax-rates)
- Trust Tax Rates & Deductions in 2025 (https://ardentrust.com/insights/trust-tax-rates-deductions)
- Follow Steps for Reporting Capital Gains in Trusts
- SOI tax stats – Income from estates and trusts statistics | Internal Revenue Service (https://irs.gov/statistics/soi-tax-stats-income-from-estates-and-trusts-statistics)
- About Form 1041, U.S. Income Tax Return for Estates and Trusts | Internal Revenue Service (https://irs.gov/forms-pubs/about-form-1041)
- SOI Tax Stats – Income from trusts and estates study data sources and limitations | Internal Revenue Service (https://irs.gov/statistics/soi-tax-stats-income-from-trusts-and-estates-study-data-sources-and-limitations)
- Instructions for Form 1041 and Schedules A, B, G, J, and K-1 (2024) | Internal Revenue Service (https://irs.gov/instructions/i1041)
- Utilize Resources for Trust Tax Management
- SOI Tax Stats – Estate, gift and trust statistics | Internal Revenue Service (https://irs.gov/statistics/soi-tax-stats-estate-gift-and-trust-statistics)
- Navigating Trust Taxation: A Guide to U.S. Filing Requirements – Austin CPA Firm | Millan + Co. PC | (512) 479-6819 (https://millancpa.com/insights/navigating-trust-taxation-a-guide-to-us-filing-requirements)
- Your Trustee Toolkit: Trust Taxation Basics and Finding the Right CPA (https://truelinkfinancial.com/blog/your-trustee-toolkit-trust-taxation-basics-and-finding-the-right-cpa)
- SOI tax stats – Income from estates and trusts statistics | Internal Revenue Service (https://irs.gov/statistics/soi-tax-stats-income-from-estates-and-trusts-statistics)
- SOI Tax Stats – Income from trusts and estates study data sources and limitations | Internal Revenue Service (https://irs.gov/statistics/soi-tax-stats-income-from-trusts-and-estates-study-data-sources-and-limitations)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Estate Planning for high-income W-2 families at Bright Advisers.
Keep reading