

Key Highlights:
- The Wash Sale Rule prevents claiming a tax deduction for a loss on a security if the same or similar security is bought within 30 days before or after selling it.
- Investors cannot use losses to offset gains in the same tax year if they violate the Wash Sale Rule.
- Understanding the application of the Wash Sale Rule to Roth IRAs is crucial, as transactions in these accounts may not trigger immediate tax penalties.
- Violating the Wash Sale Rule can lead to disallowed losses, raising taxable income and complicating future capital gains calculations.
- Strategies to avoid wash sales include waiting 31 days before repurchasing a sold security and keeping detailed transaction records to prevent accidental violations.
Introduction
Navigating the world of investment regulations can feel overwhelming, especially for families eager to secure their financial futures. Take, for instance, the wash sale rule. This important aspect of tax law is designed to prevent investors from claiming tax deductions on losses while buying back similar securities. But how does this rule fit into the picture for Roth IRAs, which are meant for tax-free growth?
Imagine if you could make the most of your investments without worrying about unexpected tax consequences. Understanding the nuances of the wash sale rule could be the key to maximizing your benefits. As you explore your investment strategies, remember that grasping these concepts can make a significant difference for your family.
We’re here for you, ready to help you navigate this journey. Together, we can ensure that your financial planning aligns with your family’s values and goals.
Define the Wash Sale Rule
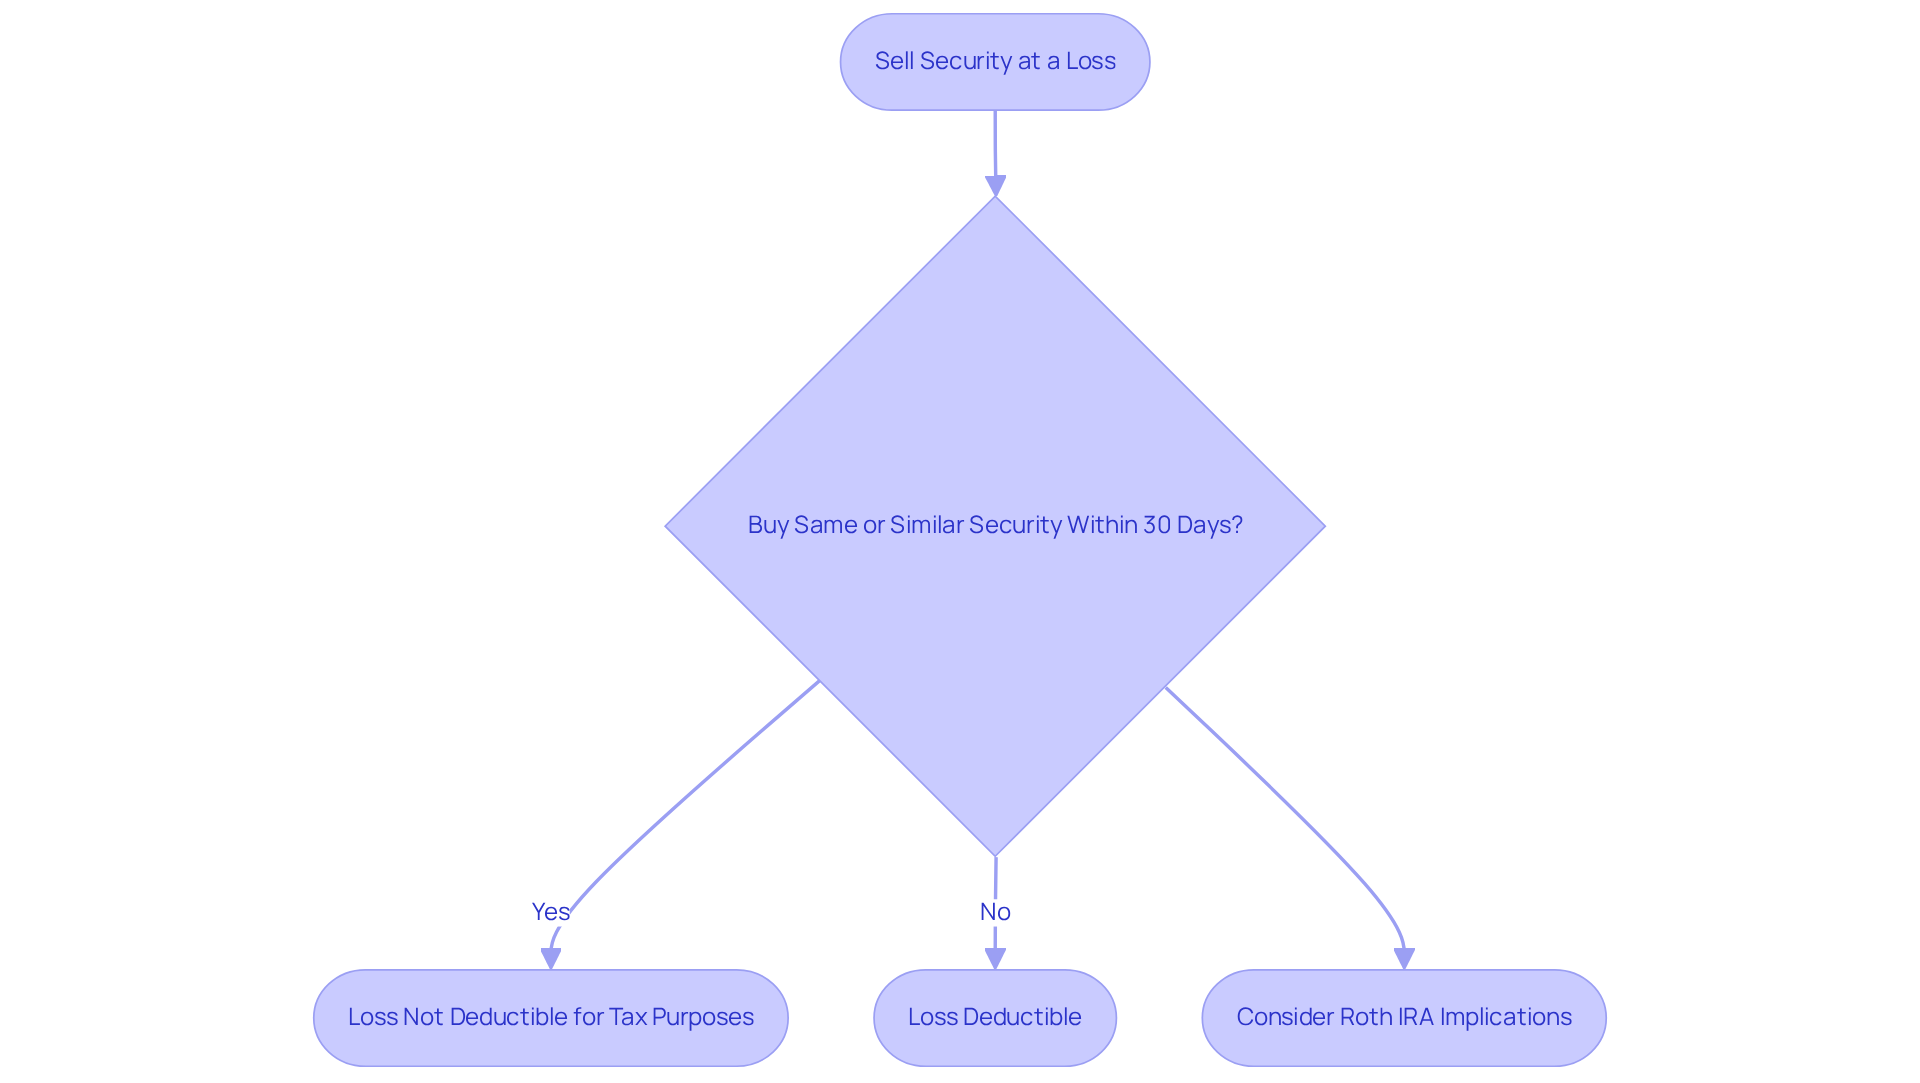
Understanding whether the question of ‘does wash sale rule apply to Roth IRA‘ can feel overwhelming, but it’s essential for your financial journey. This IRS regulation is designed to help you navigate your investments wisely. Simply put, it prevents you from claiming a tax deduction for a loss on a security if you buy the same or a similar security within 30 days before or after selling it.
Imagine selling a stock at a loss, only to buy it back shortly after. While it might seem like a smart move, the . This means you can’t use it to offset gains in the same tax year. It’s a tricky situation that many investors find themselves in, often without realizing the implications.
It’s crucial for countless investors each year to understand whether the rule, specifically does wash sale rule apply to Roth IRA, affects their investments. You might unintentionally trigger a trade that impacts your tax obligations and investment strategies. It’s important to understand how this regulation can influence your financial decisions, especially when you’re trying to make the best choices for your family.
When considering tax-loss harvesting, it’s important to understand whether the question of does wash sale rule apply to Roth IRA affects when you can sell and repurchase securities. This applies to all accounts, including tax-deferred IRAs and taxable brokerage accounts, raising the question of whether the does wash sale rule apply to Roth IRA. Grasping these nuances is vital for effective tax planning and investment management.
Remember, you’re not alone in this journey. We’re here for you, ready to help you navigate these complexities and ensure your financial decisions align with your family’s goals.
Contextualize the Wash Sale Rule in Tax Regulations
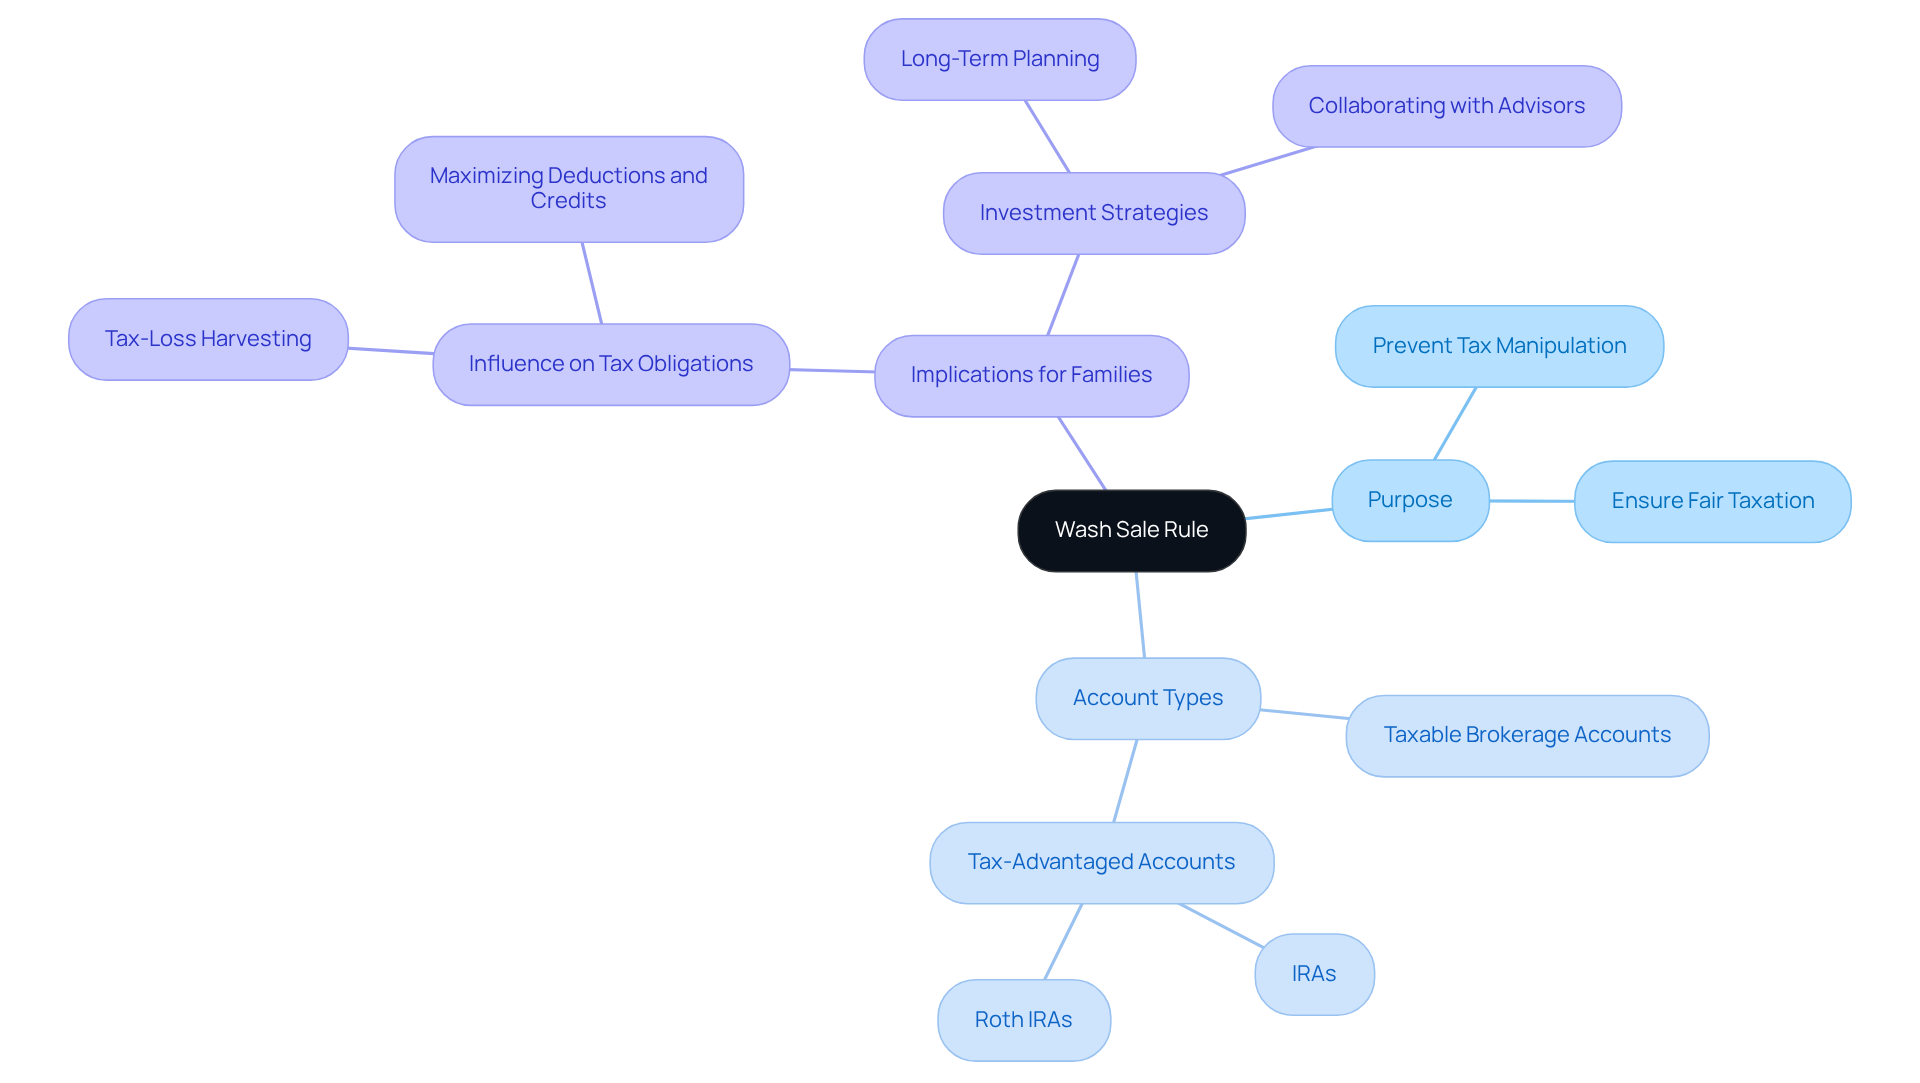
Understanding tax regulations can feel overwhelming, especially for young families trying to secure their financial future. The repurchase rule was created to prevent taxpayers from manipulating their tax obligations through fictitious losses. This regulation is part of a broader effort to ensure fair taxation and discourage strategies that could undermine the integrity of our tax system.
Imagine if you could navigate these complexities with confidence. This rule applies to various account types, including taxable brokerage accounts and tax-advantaged accounts like IRAs, leading to the question of whether the wash sale rule applies to Roth IRAs. However, the implications can differ significantly depending on the context. For families, especially those represented by Bright Advisers’ clients, grasping the nuances of these regulations is crucial.
It’s important to understand how these rules can influence your tax obligations and overall investment strategies. Families looking to optimize their financial situation and secure their children’s future need to be aware of these factors. By working with a financial advisor, you can make informed decisions that align with your family’s goals.
Together, we can navigate this journey toward greater financial security and freedom. We’re here for you, ready to support you in making choices that .
Apply the Wash Sale Rule to Roth IRAs
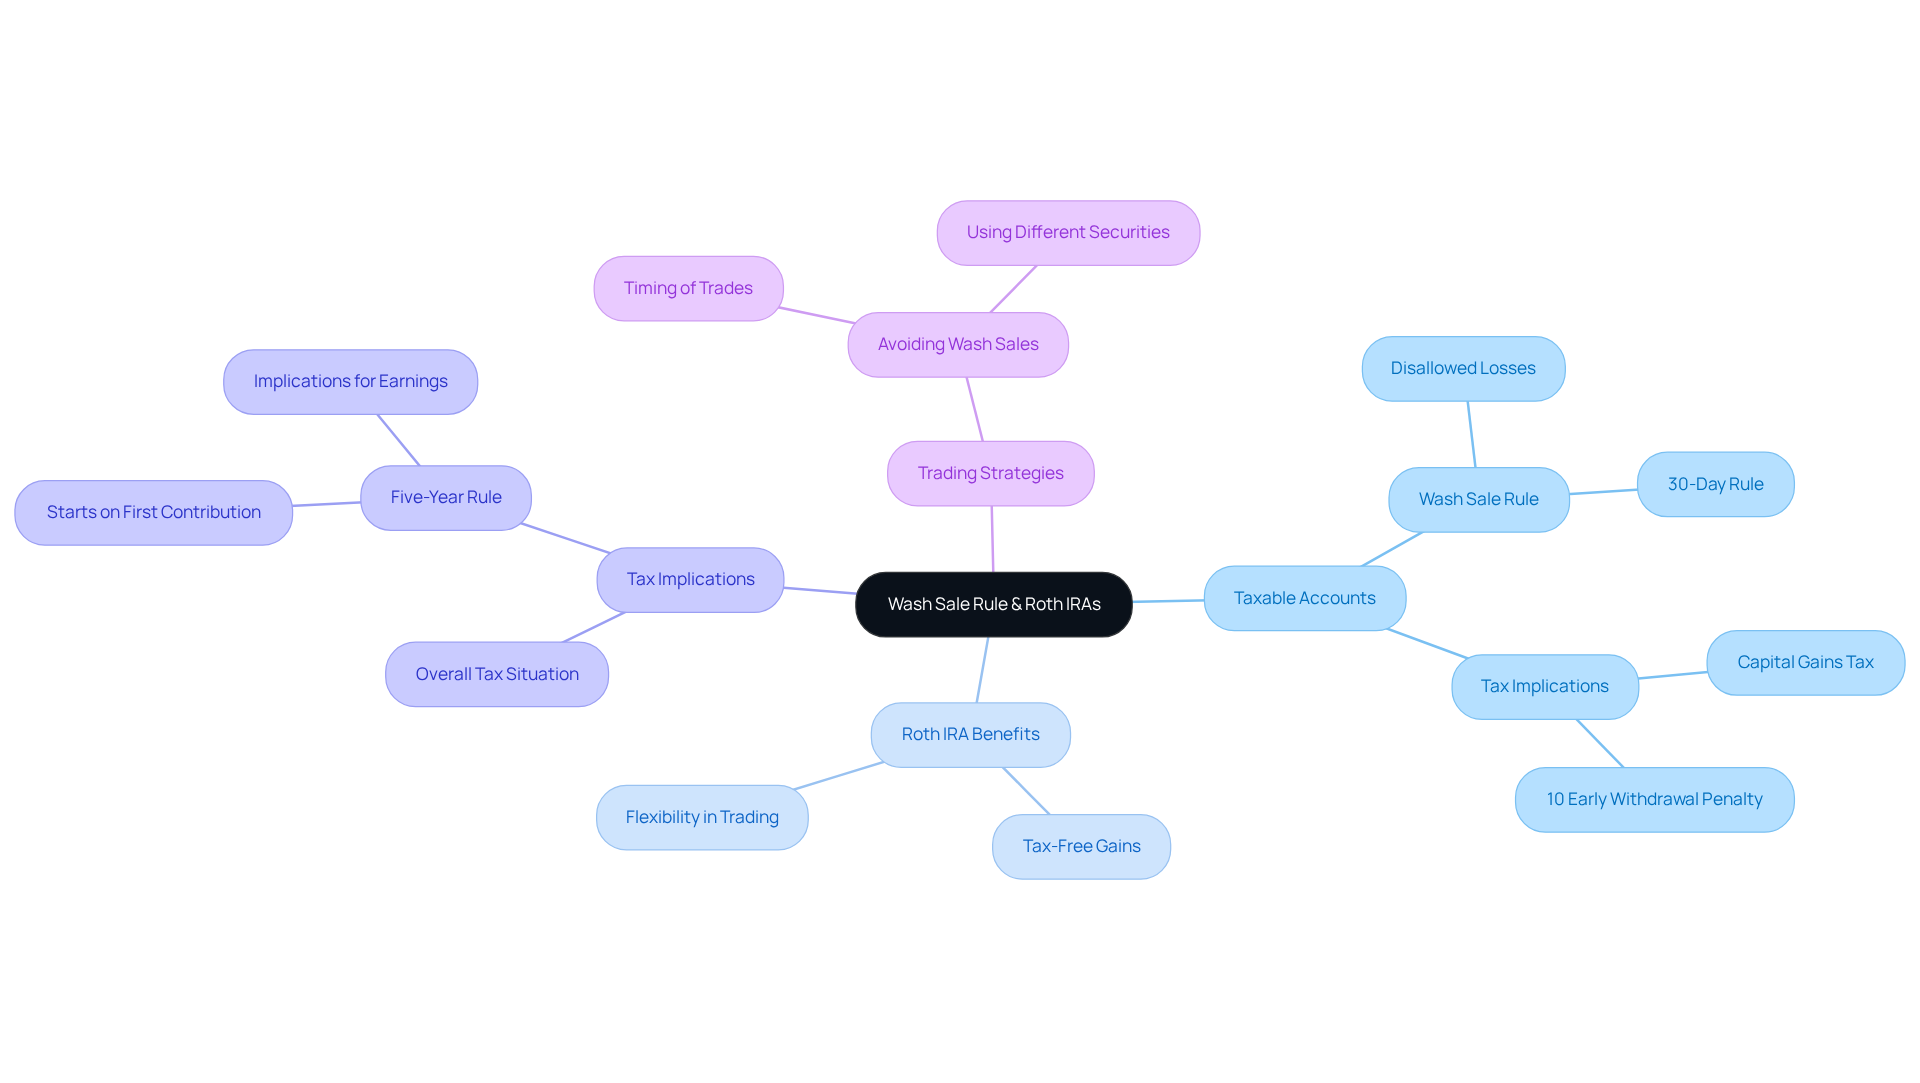
When it comes to planning for your family’s future, understanding the can be a game changer. Unlike taxable accounts, where the wash sale rule complicates things, it is important to understand whether the question of does wash sale rule apply to Roth IRA is relevant, as these accounts offer a more nurturing approach to your investments. In taxable accounts, if you sell a security at a loss and then buy a similar one within 30 days, you can’t claim that loss on your taxes. This can feel frustrating, especially when you’re trying to make the most of your hard-earned money.
But here’s the good news: Roth IRAs allow for tax-free gains when you make qualified withdrawals. This means that if you sell a security at a loss in a taxable account and repurchase it within that 30-day window, the loss is disallowed. However, in a Roth IRA, you can make similar transactions without facing those same tax implications, leading to the question of how the does wash sale rule apply to roth ira. This flexibility helps you keep your investments on track, preserving that valuable tax-advantaged status.
It’s important to remember that while Roth IRA transactions might not trigger immediate tax penalties, the IRS still considers these activities when looking at your overall tax situation. So, being mindful of your trading strategies is key to avoiding any unintended consequences that could affect your family’s financial health.
Additionally, trades executed within IRAs or 401(k) accounts are not subject to the same transaction rules, which further underscores the benefits of choosing a Roth IRA for your family’s investment strategy. As one financial advisor wisely pointed out, “Tax-free money is a very nice place to have some money, especially in retirement and a rising tax environment.” This really highlights the importance of thoughtful planning when it comes to utilizing Roth IRAs effectively.
And don’t forget about the five-year rule for Roth IRA earnings! This rule starts on January 1st of the year you make your first contribution, and it plays a significant role in the long-term implications of your investments.
Together, we can navigate this journey toward financial security for your family, ensuring that you make the most of every opportunity.
Examine Consequences of Violating the Wash Sale Rule
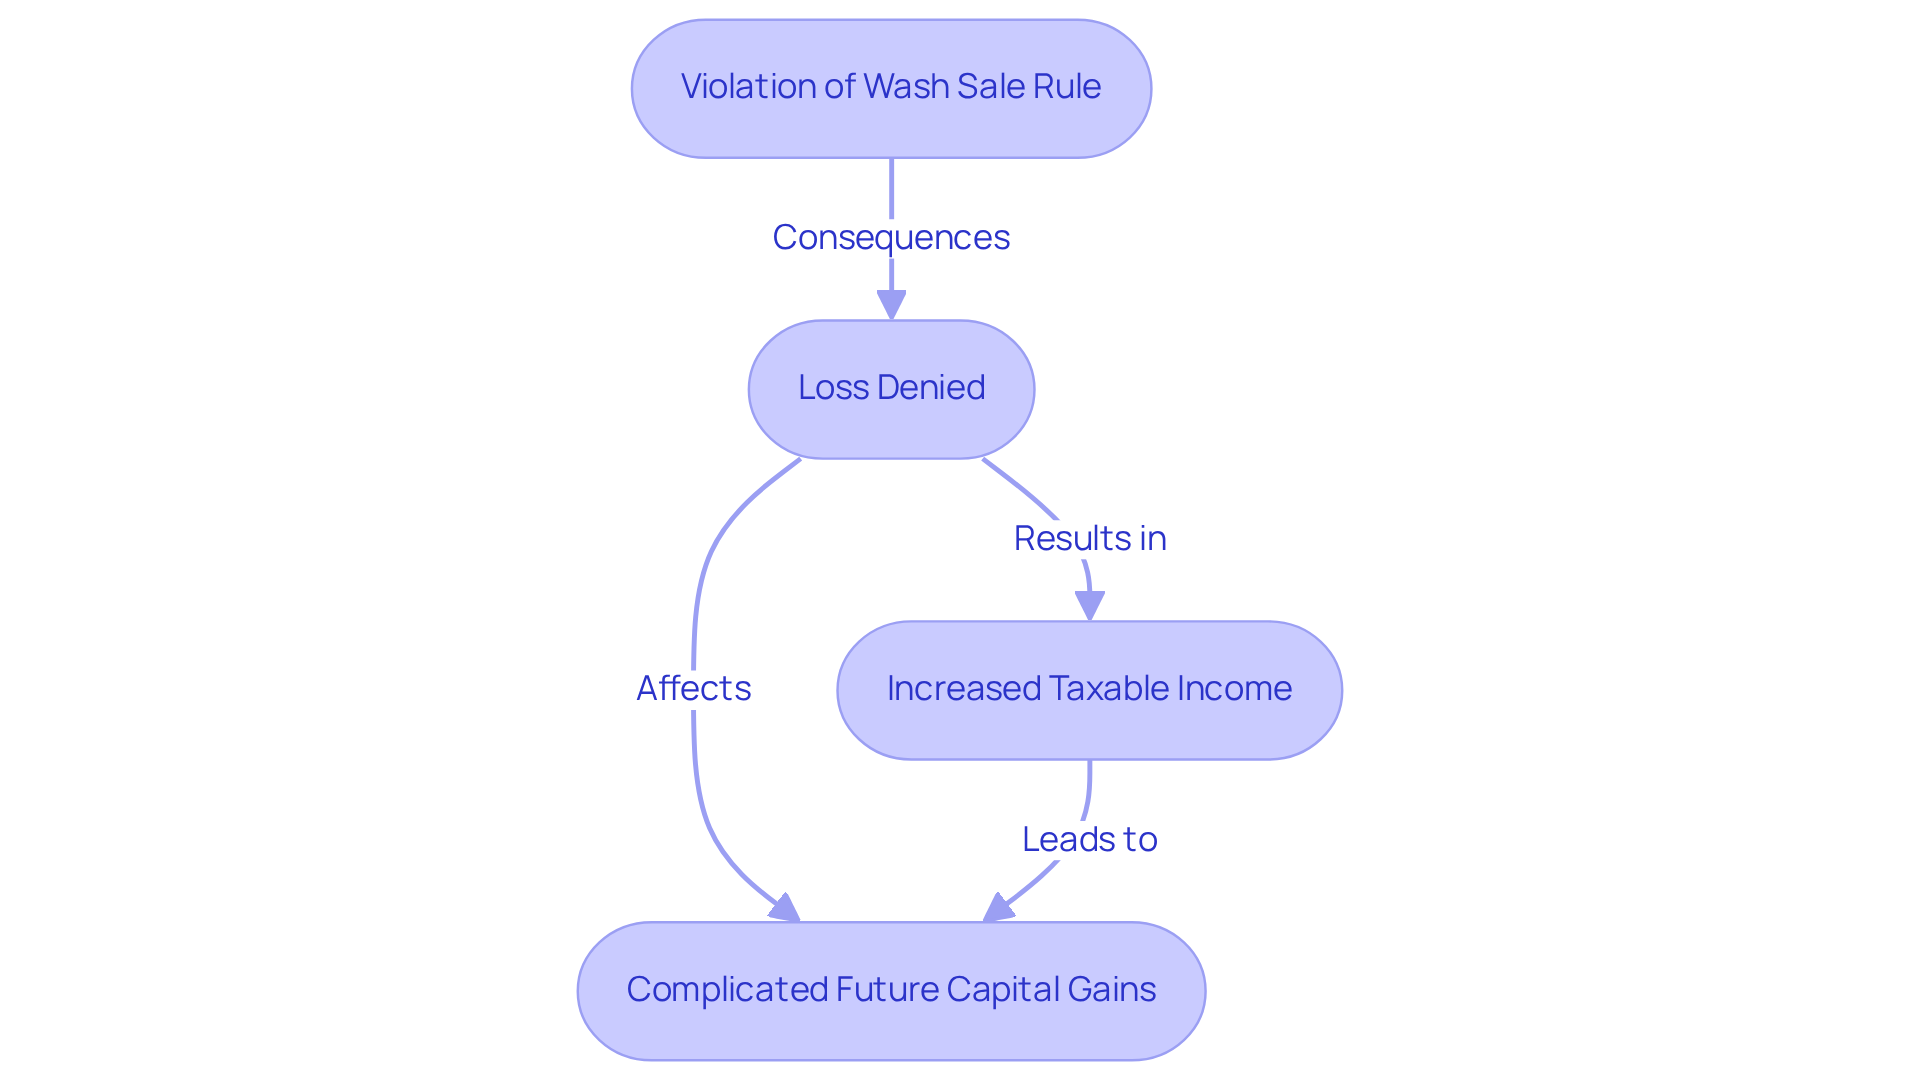
Breaking the trading rule can lead to significant tax implications for families like Allison and Brian, who are striving to improve their financial future through thoughtful tax planning with Bright Advisers. Imagine discovering that the IRS has flagged a transaction. In such cases, the loss from selling a security may be denied, meaning you can’t use that loss to offset any gains for tax purposes. This could unexpectedly raise your taxable income for the year, resulting in a higher tax bill than you anticipated.
It’s important to understand that the disallowed loss gets added to the basis of the repurchased security. This can complicate future capital gains calculations, making it crucial for families managing their investments to be aware of these consequences. By grasping these details, you can avoid unexpected tax liabilities and ensure effective financial planning.
Working with Bright Advisers can . Together, we can implement tailored wealth management strategies that empower you to secure your financial future. We’re here for you, ready to support you on this journey toward financial stability and peace of mind.
Strategies to Avoid Wash Sales
Navigating the world of financial planning can feel overwhelming, especially for young parents. But don’t worry; there are gentle strategies you can use to align your investments with your long-term goals.
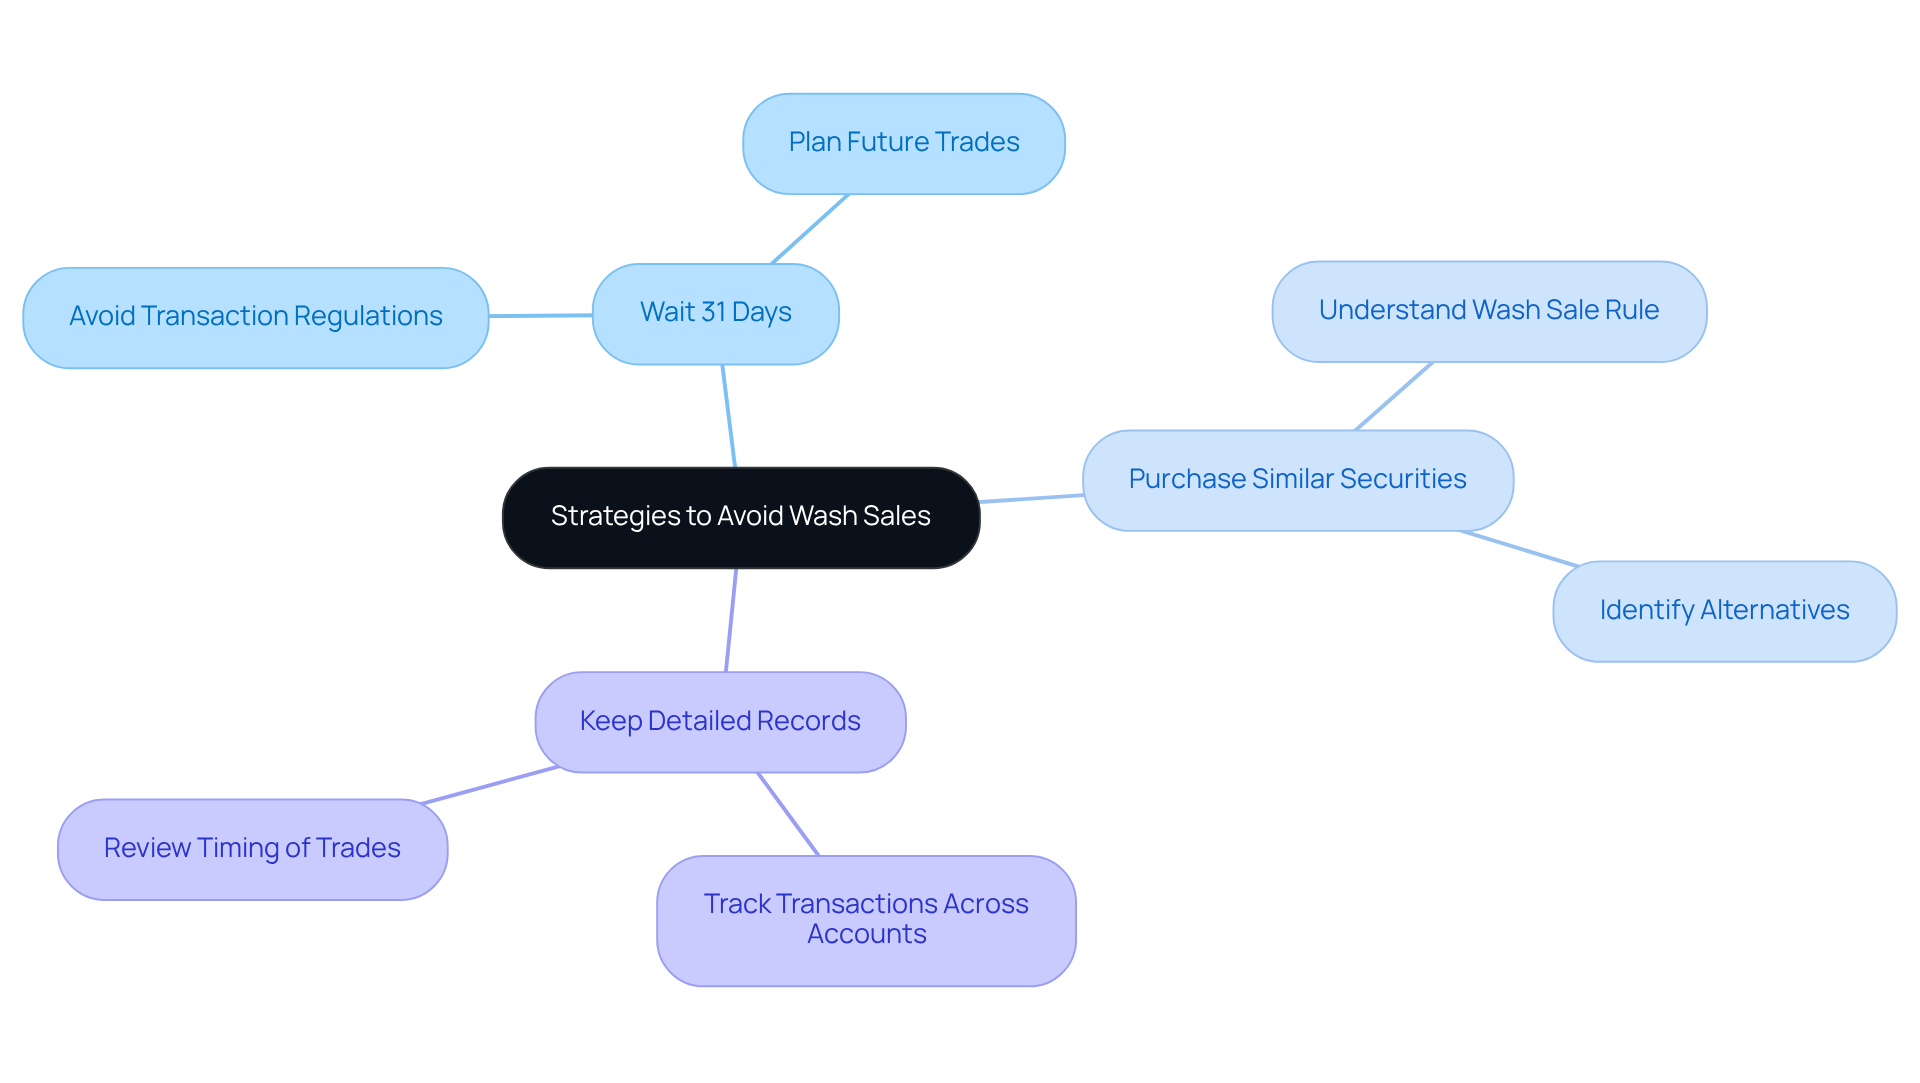
Imagine waiting just a little while – at least 31 days – after selling a security at a loss before you consider buying it back. This simple step can help you avoid activating transaction regulations that might complicate your financial journey. Alternatively, think about purchasing a similar security that isn’t quite the same. This way, you can sidestep the wash sale rule and understand how the wash sale rule applies to Roth IRA to keep your investments on track.
Keeping detailed records of your transactions is another helpful tactic. By being mindful of the timing of your trades across different accounts, you can prevent any accidental missteps. It’s all about creating a disciplined approach to investing that not only supports your financial health but also aligns with your family’s values.
These strategies are not just about tax planning; they encourage a thoughtful way of investing that resonates with your family’s long-term aspirations. Remember, you’re not alone in this journey. Together, we can navigate these waters and ensure a for your loved ones.
Conclusion
Understanding the wash sale rule’s implications on Roth IRAs is crucial for making informed investment choices. This regulation significantly impacts how families manage their portfolios, especially when selling and repurchasing securities. By grasping the nuances of this rule, you can navigate your financial journey with confidence, maximizing your investment potential while staying compliant with tax regulations.
Throughout this article, we’ve shared key insights about the wash sale rule’s definition, its application to different account types, and the unique advantages of Roth IRAs. It’s important to note that trades within Roth IRAs are treated differently than those in taxable accounts, offering you greater flexibility without immediate tax consequences. We also discussed practical strategies to help you avoid triggering the wash sale rule, highlighting the importance of careful planning and diligent record-keeping.
Ultimately, being well-informed about the wash sale rule and its implications empowers families to make strategic financial choices that align with their long-term goals. Imagine having a trusted financial advisor by your side, providing personalized guidance to help you navigate the complexities of tax regulations and investment strategies. Embracing this knowledge not only protects your financial future but also fosters a deeper understanding of how to build and preserve wealth for generations to come.
We’re here for you, ready to support you on this journey. Together, we can ensure that your family’s financial well-being is secure.
Frequently Asked Questions
What is the wash sale rule?
The wash sale rule is an IRS regulation that prevents investors from claiming a tax deduction for a loss on a security if they buy the same or a similar security within 30 days before or after selling it.
Does the wash sale rule apply to Roth IRAs?
Yes, the wash sale rule applies to Roth IRAs as well as other account types, including taxable brokerage accounts and tax-deferred IRAs.
What happens if I sell a stock at a loss and then buy it back shortly after?
If you sell a stock at a loss and then buy it back within the specified 30-day window, the loss will not count for tax purposes, meaning you cannot use it to offset gains in the same tax year.
Why was the wash sale rule created?
The wash sale rule was created to prevent taxpayers from manipulating their tax obligations through fictitious losses and to ensure fair taxation within the tax system.
How can the wash sale rule affect my investment strategies?
Understanding the wash sale rule is crucial for effective tax planning and investment management, as it can influence when you can sell and repurchase securities without affecting your tax obligations.
Who can help me navigate the complexities of the wash sale rule?
Working with a financial advisor can help you make informed decisions regarding the wash sale rule and ensure that your financial choices align with your family’s goals.
List of Sources
- Define the Wash Sale Rule
- What is the wash sale rule & how can it affect your investments? (https://thrivent.com/insights/investing/what-is-the-wash-sale-rule-how-can-it-affect-your-investments)
- Understanding Wash Sale Rules and RSUs: Why Selling Too Soon Could Cost You (https://alisonwealth.com/blog/understanding-wash-sale-rules-and-rsus-why-selling-too-soon-could-cost-you)
- What Is the Wash-Sale Rule? | SoFi (https://sofi.com/learn/content/what-is-a-wash-sale)
- For your year-end tax planning, beware the wash sale rule | J.P. Morgan Private Bank U.S. (https://privatebank.jpmorgan.com/nam/en/insights/wealth-planning/for-your-year-end-tax-planning-beware-the-wash-sale-rule)
- Get a Better Understanding of Wash Sale Rule (https://brickleywealth.com/definitions/wash-sale-rule)
- Contextualize the Wash Sale Rule in Tax Regulations
- 10 Essential Tax Planning Webinar Tips for Young Families – Bright Advisers (https://brightadvisers.com/10-essential-tax-planning-webinar-tips-for-young-families)
- 7 Best Tax Strategies for Young Families to Maximize Savings – Bright Advisers (https://brightadvisers.com/7-best-tax-strategies-for-young-families-to-maximize-savings)
- Apply the Wash Sale Rule to Roth IRAs
- Get a Better Understanding of Wash Sale Rule (https://brickleywealth.com/definitions/wash-sale-rule)
- Wash Sale Rule: Avoiding Violations in Rebalancing (https://mezzi.com/blog/wash-sale-rule-avoiding-violations-in-rebalancing)
- The Tax Implications of Investing — Cornerstone Comprehensive Wealth Management (https://cornerstoneway.com/blog/the-tax-implications-of-investing)
- Tax Planning Opportunities for Funding an IRA (https://thetaxadviser.com/issues/2012/feb/counts-feb2012)
- Wash-Sale Rule: What It Is, How It Works in 2025 – NerdWallet (https://nerdwallet.com/investing/learn/wash-sale)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Retirement & Employee Benefits for high-income W-2 families at Bright Advisers.
Keep reading